Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
Chipotle Mexican Grill needed to do something. In February, the fast-casual restaurant brand reported that traffic to its restaurants fell for the fourth straight quarter to end 2025, and it was projecting flat same-store sales growth for 2026. At that point, the company’s stock had dipped by about 33% over the last year. The brand needed a boost, and it just made a major move to get it. Chipotle named award-winning marketer Fernando Machado as its new chief brand officer. Machado’s last CMO role was with plant-based food company NotCo, which he joined in 2023 after two years as CMO at Activision Blizzard. But he’s best known for his epic run of success—and industry accolades—at Burger King from 2014 to 2020 (the last three years as global CMO for BK parent company Restaurant Brands International). On Chipotle’s latest earnings call on April 29th, CEO Scott Boatwright highlighted Machado as an award-winning, globally-recognized brand leader. “His proven track record of building iconic brands, driving category-defining innovation and leading customer-centric marketing strategies is exactly what we need as we continue to elevate our brand, deepen guest loyalty, highlight the value of our real food, and accelerate our long-term growth,” said Boatwright. At first glance, hiring a proven and celebrated marketer to reverse a sales slide looks like a no-brainer. But there’s also an argument to be made that Machado’s stunt-heavy strengths are a mismatch for Chipotle’s largely earnest brand image. Combining the sensibilities that tried to usurp the Belgian monarchy and promote moldy burgers with a brand that makes sincerely sweet animated short films is definitely a risk that Chipotle is hoping will pay off. Let’s break it down. Pushing boundaries Machado believes the greatest risk a marketer can take is producing “flat” or generic work. He has argued that because people are now so good at ignoring the “sea of sameness” across most advertising and marketing, a brand’s first job is to ensure it isn’t ignored. Rule number one: Don’t be dull. To do that, he views risk-taking as a necessity. For Machado, the biggest barrier to success is not a lack of money, but a company mindset that is afraid of uncertainty. He argues that to achieve significant results, marketers must push boundaries and be willing to fail or face pushback. This approach is clear in past Burger King work that was specifically designed not only to make people laugh but also to attract earned media attention and amplify its reach. The creative tech utility of 2018’s “Whopper Detour” encouraged people to download the Burger King app by using geofencing to target customers within 600 feet of McDonald’s locations and sending them coupons to neighboring BK locations for a 1 cent Whopper. It got more than 1.5 million app downloads in nine days. The visuals of “Moldy Whopper” in 2020 to promote the chain’s removal of preservatives from its menu; using an ad in 2017 to hack Google Home devices; and putting backyard grills of former McDonald’s execs in 2018 print ads all fit this bill perfectly. This work was fun and clever, but often had an underlying sneer—especially when it was aimed at the Golden Arches. Machado’s aesthetic thrived in a challenger-brand dynamic, but it’s tough to picture Chipotle swinging haymakers at, say, Sweetgreen or Panera Bread. Earnest eats Chipotle’s most popular and impactful brand work has leaned heavily into its earnest outlook on the world, and its role in it. Specifically, its creative focus has been on its food supply chain and its work with farmers. It began in 2011, when Chipotle launched a stop-motion short film called “Back to the Start,” featuring a Willie Nelson cover of the Coldplay hit “The Scientist.” After the effort exploded online, the brand used it as its first-ever national TV ad by airing it in its two-minute entirety during the 2012 Grammys. It hit the advertising trifecta of millions of online views, reams of national news coverage, and armloads of ad industry awards. A decade later, to continue washing the taste of its E. coli scandal out of everyone’s mouth, it dropped “A Future Begins,” another animated short, this one set to a Kacey Musgraves cover version of Coldplay’s “Fix You.” Its long-running “Behind the Foil” series highlights real employees and the work they do to bring Chipotle’s food to life. The 2023 ad campaign “Human Nature” juxtaposes Chipotle’s methods with those of its competitors, aiming to show its closer connection to more natural ingredients. The theme here is earnest ambition. Chipotle’s best-known work embraces its healthy food in a way that wants to exist above the kind of hand-to-hand combat advertising that so often characterizes fast-food brand campaigns. Sincerity meets stunt-y On the surface, the approaches of each brand’s most famous works are a mismatch. But looking closer, there is a Venn diagram between Machado and Chipotle that could spell magic. On the earnest side of things, Machado has garnered awards and brand results for 2014’s “Proud Whopper” and the 2015 McWhopper, which published an open letter in The New York Times asking its biggest rival to collab on a burger for Peace One Day. And on the stunt-y side, Chipotle’s long-running Boorito Halloween promotion gives discounts to people who come into its restaurants dressed in costume. Similarly playful, its “Doppelgänger” work paired app users with the same favorite orders with each other. Arguably, Chipotle’s best-known brand work has been when it serves a combo meal of sincere content through creative pop culture ideas. Now the brand needs the potentially perfect pairing of Machado’s natural irreverence with Chipotle’s penchant for speaking honestly and directly to its customers. Machado’s success will be in his ability to layer these flavors in a way that will avoid the dreaded sea of sameness, and gain attention in a way that still reminds people why they fell in love with Chipotle in the first place. View the full article
-
Google I/O is rapidly approaching. Google's big developer conference kicks off May 19 and will be available to stream live for anyone not invited to the keynote in California. While you likely won't get a look at the company's upcoming Pixel products, this presentation will contain a slew of software announcements—though we don't exactly know what Google has up its sleeve. Last year, the company made a number of interesting announcements. We got our first look at Android XR, Google’s platform for smart glasses; AI Mode’s general rollout for Search, following an initial beta period; Gemini Live's official rollout on iPhones; Try it on, a feature that lets you virtually try on clothes; and new AI models across Google's product line. This year will likely feature similar announcements, though the rumors have been pretty thin. That said, we can make some educated guesses here to figure out what Google might be planning: Google will almost assuredly reveal more AI at I/O Google, like most tech companies, is all-in on AI right now. That's not going to change with I/O 2026. In fact, expect to see plenty of new AI announcements, both in features and performance leaps. Keep an eye out for updates to the company's big AI products, like Veo (AI video), Nano Banana (AI images), Lyria (AI music), and Gemma (lightweight open models). Speaking of AI, chances are good that we'll see a new version of Gemini at this year's event. Gemini is Google's flagship AI, including both its chatbot and its AI models. That likely means new models that are faster and more capable than previous iterations. Google has been full speed ahead on Gemini news lately, adding the tech to Google Maps, rolling Nano Banana into the chatbot, and changing how it deals with mental health. I'm fully expecting to see some major Gemini updates at I/O 2026—even if the rumor mill is quiet on specifics. We'll likely see some Android 17 details Google has been beta testing Android 17 since February, though it's definitely a minor update thus far. That doesn't mean Google is skimping on new features: The update includes the ability to remap gaming controllers natively for the first time on Android, as well as the ability to run apps in "bubbles" that you can minimize on the screen until you're ready to use them. Interestingly, the company decided to break out the Android portion of 2025's event into its own keynote, which it called "The Android Show." That freed Google up to spend the main I/O keynote talking about AI. As of yet, there are no plans for another "Android Show" this year, so I expect any Android 17 news to be contained to the main event. Google may announce Android XR news at I/O Google announced Android XR at last year’s I/O event. The pitch focused on a HUD that displays Android elements in your view—including things like messages and Google Maps. That also includes Gemini Live integration, which makes sense. (What good are smart glasses without an assistant that can see what you see?) At the time, Google announced a number of partnerships for its smart glasses platform, including Warby Parker and Gentle Monster. Maybe we’ll learn about some Android XR-powered glasses this year, along with a timeline of when we can buy them. Smart glasses are an emerging market, with more companies and products hitting the scene. But with that growth comes legitimate security concerns. When anyone can buy a pair of glasses with subtle, embedded cameras, how does that square with a public that may not want to be filmed at all times—especially without their knowledge? Some are already fighting back: This app can snitch on people who are wearing smart glasses, in case the frames themselves aren't obvious. We'll have to see how Google handles privacy and security with Android XR—though the company isn't necessarily known for privacy. Aluminum OSGoogle might also take the opportunity to talk about Aluminum OS, the company’s mission to combine Android and ChromeOS. The idea is to design a version of Android for desktop—not simply expand Android to run on larger displays. I'm not sure if Google will share Aluminum OS developments at I/O 2026, but if there was an event for it, it'd be this one. View the full article
-
If you’re considering a bookkeeping career, online classes can provide the foundation you need. There are several free options available that cater to various skill levels, from beginners to those looking to improve their expertise. These courses cover crucial topics like accounting principles and software applications, helping you gain valuable skills. Plus, many offer certificates upon completion, boosting your employability. Let’s explore these top seven free online bookkeeping classes and see how they can benefit your career path. Key Takeaways OpenLearn University’s free “Introduction to Bookkeeping and Accounting” offers 8 hours of beginner-friendly content and a statement of participation upon completion. Coursera’s bookkeeping course, in partnership with Intuit, provides a comprehensive curriculum and a certificate for completing approximately 10 hours of weekly study. Edx’s “Introduction to Bookkeeping” by ACCA spans 30-48 hours, covering key concepts and ideal for beginners seeking a solid foundation. Oxford Home Study Centre’s 20-hour CPD-accredited course focuses on double-entry bookkeeping and awards a certificate upon successful completion. AccountingCoach offers extensive practice quizzes and key concept resources, with subscription plans for deeper content, starting at $49. OpenLearn University OpenLearn University provides a valuable opportunity for anyone interested in exploring the domain of bookkeeping. They offer a free bookkeeping class online titled “Introduction to Bookkeeping and Accounting.” This 8-hour self-paced program is designed for beginners, enabling you to grasp the fundamentals of double-entry bookkeeping. You’ll learn crucial topics, including balance sheets, profit and loss statements, and managerial accounting, which serve as a thorough foundation for aspiring bookkeepers. As a Level 1 course, it’s perfect for those with no prior bookkeeping knowledge or experience. Throughout the course, you can track your progress via quizzes, ensuring you understand the material. Upon completion, you’ll receive a statement of participation or a badge, enhancing your credentials in the field. OpenLearn University, part of The Open University, is committed to providing accessible education, making this course an excellent starting point for your bookkeeping expedition. Coursera Coursera’s bookkeeping course, offered in partnership with Intuit, is structured into four parts, making it accessible for beginners. You’ll spend about 10 hours each week, allowing you to learn at your own pace during covering fundamental topics like the accounting cycle and software usage. The program likewise includes an Applied Learning Project, giving you hands-on experience to reinforce your comprehension and skills. Course Structure Overview If you’re looking to gain foundational bookkeeping skills, the professional certificate series offered through Coursera, in partnership with Intuit, is an excellent choice. This bookkeeping certification online free program comprises four parts designed for beginners, with no prior experience required. You’ll enjoy the flexibility of self-paced learning, dedicating about 10 hours per week, completing the course in roughly two months. The curriculum covers crucial topics such as accounting concepts and the accounting cycle, whereas an Applied Learning Project allows you to apply your skills in real-world scenarios. Part Duration Key Topics 1 2 weeks Accounting Basics 2 2 weeks The Accounting Cycle 3 2 weeks Practical Skills Practical Learning Experience When you enroll in a bookkeeping course on Coursera, you’ll discover a practical learning experience that increases your comprehension of fundamental accounting concepts. Courses like the Bookkeeping Professional Certificate by Intuit offer about 16 hours of on-demand materials customized for beginners. One highlight is the Applied Learning Project, where you can practice real-world scenarios to apply your bookkeeping knowledge effectively. You’ll enjoy flexible scheduling, allowing you to progress at your own pace as you balance other commitments. Completing the accounting 101 online course not just improves your skills but also earns you a certificate, which can boost your resume and showcase your practical abilities to potential employers. The interactive format, featuring video tutorials and assessments, reinforces your learning experience. AccountingCoach AccountingCoach stands out as a valuable resource for anyone looking to deepen their grasp of bookkeeping. The platform offers a variety of self-paced online lessons that cater to learners at all levels, making it easy for you to advance your skills. With over 2,000 practice quizzes and targeted questions, you can identify weak areas and reinforce your comprehension of bookkeeping fundamentals effectively. You’ll find free resources available, including explanations of key concepts, terminology games, and cheat sheets to simplify complex accounting topics. If you’re interested in more in-depth learning, subscription plans like PRO and PRO+ start at $49, providing additional content and features. Many users have praised AccountingCoach for its clarity and ease of comprehension, affirming its value as a resource for aspiring bookkeepers. Plus, you can explore options for accounts receivable certification online free to improve your qualifications. Alison Alison offers a range of free video training courses in accounting and bookkeeping, giving you the flexibility to choose between certificate and diploma options that fit your schedule. With courses accredited by CPD, you’ll gain recognized skills that can improve your career in bookkeeping and finance. Whether you’re looking to master basic techniques or understand crucial financial statements, Alison‘s self-paced learning allows you to progress at your own speed. Free Video Training Courses With a wide range of free video training courses, you can explore various aspects of bookkeeping through Alison’s platform. These bookkeeping training online free courses cover topics from basic accounting principles to advanced financial management techniques. Each course typically lasts between 2 to 15 hours, allowing you to learn at your own pace and fit your studies into your schedule. The interactive content and assessments improve your comprehension and reinforce key concepts. Furthermore, these courses are CPD-accredited, ensuring they meet professional development standards, which can help boost your credentials. Although you can earn a certificate upon completion, a fee may apply for a physical copy. Take advantage of this opportunity to advance your bookkeeping skills today. Certificate and Diploma Options When you’re looking to improve your bookkeeping skills, exploring the certificate and diploma options available through Alison can be a smart move. Alison offers a range of free accounting and bookkeeping courses, with options that take between 2 to 15 hours to complete. Although the free courses include ads, you can pay for an ad-free experience and obtain a certificate or diploma. These certifications can boost your professional credibility, making you more appealing to potential employers. Topics covered include transaction recording, financial statements, and crucial accounting techniques, equipping you with practical skills. Furthermore, you can track your progress and receive a statement of achievement, making your learning expedition more visible in the job market. This is a great step toward a tuition-free online accounting degree. CPD Accreditation Benefits CPD accreditation offers considerable advantages for those pursuing bookkeeping courses on Alison, as it assures both quality and recognition in the professional domain. By completing CPD-accredited courses, you can earn certificates that demonstrate your commitment to professional growth and skill improvement. These courses cover fundamental bookkeeping topics, including transaction recording and financial statements, providing you with crucial skills to advance your career. Furthermore, CPD accreditation signifies that these courses contribute to ongoing learning, keeping you updated with industry standards. Many employers value candidates who’ve pursued recognized professional development opportunities, and completing a financial accounting class online can greatly improve your job prospects. Engaging in CPD-accredited training can set you apart in a competitive job market. Edx Courses edX offers a variety of free online bookkeeping courses designed to cater to different skill levels. One of the standout options is the “Introduction to Bookkeeping” course provided by ACCA, which spans 30-48 hours of self-paced learning. This course covers fundamental topics like double-entry bookkeeping and trial balances, making it perfect for beginners. If you’re looking to deepen your knowledge, the “Intermediate Bookkeeping” course builds on foundational skills, requiring 5-8 hours of study per week over six weeks, ideal for those preparing for ACCA certification exams. You don’t need prior bookkeeping knowledge for the introductory courses, ensuring accessibility. edX courses often include flexible pacing options, allowing you to progress at your own speed, and they feature quizzes and practical exercises to reinforce your comprehension. Although the courses are free, obtaining a certificate may involve additional fees if you pursue ACCA student status. For those seeking QuickBooks online classes near me, these courses are a great starting point. Oxford Home Study Centre If you’re looking to improve your bookkeeping skills without any cost, the Oxford Home Study Centre offers an extensive 20-hour course that covers vital topics like basic terminology and double-entry bookkeeping. This course is CPD-accredited, ensuring it meets recognized professional development standards. You can progress at your own pace, which is perfect for those with varying schedules. The flexibility allows you to fit the accounting training into your life without pressure. Upon completion, you’ll have the opportunity to obtain a CPD-accredited certificate, adding significant value to your professional credentials. With an impressive rating of 4.9 stars based on 53,974 reviews, the course is well-regarded for its quality and effectiveness in teaching bookkeeping fundamentals. It’s an excellent choice for anyone seeking to improve their skills and further their career in accounting. Corporate Finance Institute (CFI) The Corporate Finance Institute (CFI) provides a free Accounting Fundamentals course that’s perfect for anyone looking to build a solid foundation in bookkeeping and finance. This course takes approximately 5 hours to complete and covers vital topics like double-entry bookkeeping, major financial statements, and key accounting terminology. It’s designed for beginners or those wanting to improve their skills. One of the standout features is that you can access accounts receivable online free, allowing you to learn at your own pace. Furthermore, the course includes downloadable Excel practice files, enabling you to apply your knowledge in practical scenarios. This hands-on experience reinforces the concepts taught throughout the program. Upon completing specific courses, you have the chance to earn certificates, which can greatly boost your professional credentials and improve your employability in the finance and accounting fields. CFI’s thorough curriculum sets you on the right path for your career. Frequently Asked Questions What Is the Best Free Bookkeeping Course? The best free bookkeeping course often depends on your specific needs. OpenLearn’s Introduction to Bookkeeping and Accounting offers a solid foundation in just 8 hours. If you’re looking for practicality, consider Coursera’s Bookkeeping for Personal and Business Accounting, which provides a self-paced experience with a certificate. For an extensive overview, the Oxford Home Study Centre’s 20-hour course is thorough and CPD-accredited, making it a strong choice for beginners seeking quality education. How to Get Started as a Bookkeeper With No Experience? To get started as a bookkeeper with no experience, begin by enrolling in free online courses that teach foundational concepts, like double-entry bookkeeping and financial statements. Consider self-paced options on platforms like Coursera or OpenLearn University. You can additionally strengthen your skills with resources from AccountingCoach. Finally, practice with applied projects or quizzes to gain real-world experience, ensuring you’re well-prepared for entry-level bookkeeping roles. What Is the Most Respected Bookkeeping Certification? The most respected bookkeeping certifications are the Certified Bookkeeper (CB) from the American Institute of Professional Bookkeepers (AIPB) and the Certified Public Bookkeeper (CPB) from the National Association of Certified Public Bookkeepers (NACPB). Both require passing exams and demonstrating relevant experience. These certifications cover crucial skills like double-entry bookkeeping and payroll management. Earning one can greatly improve your job prospects, as many employers prefer certified candidates for bookkeeping positions. Are Online Bookkeeping Courses Effective? Online bookkeeping courses are effective for many learners. They offer flexible, self-paced options that fit into your schedule, making it easier to balance studies with other commitments. These courses often include interactive elements like quizzes and practical projects, enhancing your comprehension of key concepts. You’ll gain crucial skills, from double-entry bookkeeping to financial statements, which are applicable in real-world scenarios. Completing a course can likewise boost your job prospects markedly. Conclusion Taking advantage of these free online bookkeeping classes can greatly improve your skills and employability. Each option offers unique resources, catering to various learning styles and levels. By completing these courses, you’ll not just gain valuable knowledge but additionally earn certificates that can strengthen your resume. Whether you choose OpenLearn, Coursera, or any of the others, you’re setting a solid foundation for a successful career in bookkeeping. Start today to advance your career in this crucial field. Image via Google Gemini This article, "7 Best Free Online Bookkeeping Classes to Kickstart Your Career" was first published on Small Business Trends View the full article
-
Smartphone maker increased revenue nearly 17% as iPhone sales rise by a fifthView the full article
-
Earlier this month, Nikkei Asia reported that the ongoing memory crisis was not slowing down anytime soon. RAM supply is currently in extreme demand, as AI companies are scooping up the hardware to power their ever-growing data centers. Unfortunately, there are only so many memory manufacturers in the world, and only so many resources available to actually manufacture those chips. There are really only three key players—SK Hynix, Micron Technology, and Samsung—and while all are ramping up production as much as possible, it doesn't appear to be enough to meet demands for the immediate future. Samsung can't meet memory demand this yearNow, Samsung is officially confirming as much. During a post-earnings call this week, Samsung memory chip business executive Kim Jaejune said, "Our supply falls far short of customer demand...based solely on the demand currently received for 2027, the supply-to-demand gap for 2027 is set to widen even further in 2026." This affirms much of the Nikkei Asia report, namely that Samsung cannot keep up with the current level of demand, and that it expects that reality to continue throughout the next year. It's important to note that these companies are not necessarily trying to boost the production of consumer-grade RAM components; rather, AI companies are looking for high-bandwidth memory (HBM) chips to run their power-hungry processes. But without the HBM supply to meet demand, companies will continue purchasing typical RAM hardware—putting on a strain on the consumer market. Samsung says it expects its HBM revenue to more than triple in 2026 compared to 2025. Even if you don't buy RAM itself, many of the products you do purchase are affected by this memory crisis. If a device runs on some type of computer, it almost assuredly needs RAM to function. As such, products including smartphones, computers, fitness trackers, cars, smart home devices, audio equipment, and more will all feel the squeeze—and may increase in price as a result. You have two choices to weather the memory crisisAs all signs now point to an unavoidable memory crisis, you have two choices you can make as a consumer to weather the storm. The first? If you need a new device, buy one now—and on discount, if you can help it. Based on the reports over the past month, there is little reason to expect tech prices to come down, so don't expect big players to offer their latest devices for less than previous offerings. That doesn't mean you need to pay an inflated price tag, however. Perhaps the best way to shop for new tech is to shop for used tech. Check the refurbished and renewed sections of stores like Apple, Amazon, Best Buy, and Walmart—so long as the device meets certain cosmetic qualifications (and work as they should, of course), you can get something that feels new without paying a 2026 price. You can also take advantage of some companies' education discounts, even if you aren't a student or teacher. Apple will take a good chunk off a new MacBook if you go through its Education Store. If your existing tech still works, however, I'd point you to option number two: hold on tight, and don't let go. If you don't need a new computer, phone, smartwatch, what have you, don't spend your money yet—especially if you can see that device lasting another year or more. There are things you can do to make your aging tech feel new—or, at least, newer than it was before. That includes transforming your existing devices into something different, but just as useful: Rather than buy a new laptop, you could install Linux to speed things up and have more control over your OS; instead of picking up a new phone, you could turn yours into a dumbphone, breaking your addiction while saving money at the same time. We know that the memory manufacturers don't see supply meeting demand until at least 2027; maybe if it does, prices will stabilize, and the time will be right to buy new tech again. View the full article
-
Emma Grede is the powerhouse entrepreneur behind size-inclusive fashion brand Good American and shapewear line Skims—some of the Kardashian family’s most successful business ventures. (Grede co-founded the brands with Khloé and Kim, respectively.) In a recent Bloomberg podcast, Grede shared her staunch take on the pitfalls of remote work. “Working from home is career suicide,” Grede said. “We only talk about the upside of working from home.” Not only does she believe the workplace perk is “career suicide,” but she sees the damage of remote work having wider, lasting societal implications. “Think about what’s happening in the world,” Grede said. “Declining birthrates, declining marriage rates and loneliness epidemic. We think that none of that is linked to the number of people that, like, don’t see people because they are doing Zoom calls from the living room. It’s so crazy to not make that correlation.” “The key to a long and happy life is your close relationships,” she said. It’s a hot take, considering that in the last year or so, return-to-office mandates have caused tension between employees and employers. While companies argue that working from the office boosts collaboration and productivity, some experts say that RTO has to be mandated with purpose and empathy to not drain engagement or break employee trust. Over the last decade, Grede has been at the helm of some of the biggest names in the apparel industry. Good American, launched in 2016, was Grede’s first apparel business venture, she said. The company launched with $1 million in sales on its first day. In 2019, Grede became the founding partner of Kim Kardashian’s apparel and shapewear brand, Skims. Last November, Skims was valued at $5 billion. Her secret weapon to success, especially with Good American, was never doubting her capabilities, and surrounding herself with a team “who knew better and could help me open doors.” Before becoming a multimillionaire founder, though, Grede shared that she’s had plenty of business ventures that didn’t pan out. “There’s a ton of failures,” Grede said. “There’s a ton of things that I’ve done that didn’t work. When I think about my early businesses, I opened offices that didn’t quite work out. I have grown companies and then had to downsize them. And those things are really painful. We only show the glossy side, the amazing things, the great headlines, the stuff we want to put on our Instagram. And the reality is, anyone who is an entrepreneur that’s done multiple things will have failed.” “So much of being an entrepreneur is about figuring it out,” Grede added. “You never have the answers, and I think if you have the answers, you’re probably not moving fast enough.” When it comes to running a team, Grede said her first principle is to be radically honest. She recognizes a challenge in how female leaders are often judged on how empathetic they are—but she doesn’t let that dictate her belief that honesty is the best policy. “I don’t think anybody in my organizations ever wondered what I’m thinking,” she said. It’s safe to assume that no one is unclear about Grede’s office policy, either. View the full article
-
Some from president’s own party have begun to demand accountability in the unpopular conflictView the full article
-
The partnership was designed to support the growth of Redwood's Sequoia platform and give Castlelake purchasing power for fully documented loans. View the full article
-
Deployment of equipment is one of the first examples of major defence co-operation between the two states View the full article
-
It’s no secret that artificial intelligence has penetrated every aspect of the hiring process—even the elements that should necessitate a human touch, like conducting interviews. The vast majority of companies already rely on AI to sift through applications and resumes, but many of them are now also using it for screening calls and initial interviews. The AI interview has grown so ubiquitous, in fact, that a new report from the hiring platform Greenhouse found that nearly two-thirds of job seekers have been interviewed by AI during the hiring process—an increase of 13 percentage points from just six months ago. But that doesn’t mean they are happy about it. In a Greenhouse survey of almost 1,200 job seekers across the U.S., 38% said they had dropped out of a hiring process that involved being interviewed by AI, while another 12% said they would do so if presented with an AI interview. That’s quite notable when workers are faced with a low-hire, low-fire job market, which has kept unemployment low while also making it difficult to find new jobs—especially as companies continue cutting jobs over AI. It’s not that workers are surprised that they might encounter AI during the hiring process. After all, job seekers now regularly use AI to spruce up their resumes and apply to jobs en masse, forcing employers to wade through a glut of applications—some of which hiring managers argue can misrepresent or overstate workers’ qualifications. But workers do expect transparency when AI is part of the hiring process: As the Greenhouse survey reveals, many employers are not transparent about the extent to which AI might be used. Most of the workers surveyed—about 70%—said they were not informed that the hiring process would entail being interviewed and assessed by AI, and about a fifth of them only discovered that was the case when they started the interview. Job seekers were most troubled by companies not disclosing that AI would evaluate them based on pre-recorded video interviews, which led a third of respondents to take themselves out of the running for a job; over a quarter of them dropped out of the hiring process because they took issue with AI monitoring or found that employers were not upfront about the role AI would play. Perhaps most telling is that about 20% of people surveyed walked away from a job because they weren’t sure if they were interacting with a human or AI. As for whether AI might improve on the traditional interview or reduce bias, like some experts have argued: Most people surveyed found that there was little difference. Over a third of respondents said they experienced ageism during interviews with both humans and AI, while more than a quarter felt they encountered bias on the basis of race or ethnicity. When job seekers did AI interviews, only 28% moved on to the next stage of the hiring process; over half of them did not hear back and just 13% were explicitly rejected. Despite their grievances, most workers don’t expect employers to entirely remove AI from the hiring process. While 19% of respondents said they wanted less AI, the vast majority of them simply demanded more transparency—namely, clarity on how AI was being used and the option to conduct an interview with a human. They also wanted more human oversight to ensure that AI was not solely responsible for making decisions about an applicant. In fact, there were some workers, 38% of them, who actually felt more positively about the company after an AI interview. Some research suggests that certain workers might actually prefer AI interviews, in part because they are more consistent and easier to schedule. On the other hand, 34% of people surveyed by Greenhouse said an AI interview left them with a negative impression of the employer, and over half believed that human interviewers would be more fair. In other words: Employers can’t just turn to AI to simplify their hiring process—not without laying the groundwork for prospective hires to trust that process. View the full article
-
Amazon Prime Day 2026 is sure to be the biggest online sale of the year, and it's coming a bit sooner than you may have expected. In a press release yesterday, quickly issued after the sale's timeframe was revealed in Amazon's own first-quarter earnings statement, the company confirmed this year's event will be held in June. This is the first time Amazon has moved its biggest sale of the year earlier since the height of the pandemic in 2021. Amazon doesn't usually announce its sales months beforehand, typically waiting until at most a month out to give shoppers a heads-up on when a shopping event will take place. But after this early news drop, it's likely the other major retailers like Walmart, Target, and Best Buy will also adjust to earlier dates and follow suit, with plenty of time to prepare their own sales. Amazon has yet to announce the exact dates of the sale, but if the 2021 sale is any indication, it will likely be sometime in the week of June 22. In 2025, Prime Day doubled from two days to four for the first time, and it will likely be four days long this year as well. What to expect from Prime Day 2026Amazon says shoppers will be able to find deals on electronics, kitchen, beauty, and apparel, as well as fresh groceries and everyday pantry and household essentials. The company will undoubtedly release more information about the sale "soon," and I'll be sure to update you when we know more. View the full article
-
An opportunity for more Americans to save for their retirement may be on the way. President Donald The President signed an executive order on Thursday aimed at expanding access to retirement plans for workers whose employers don’t provide one. The order, first reported by Semafor, will direct the Treasury Department to launch The PresidentIRA.gov, an online marketplace where workers without employer-provided retirement plans can select a private-sector one. Here’s what to know: How will the plan work? The new site will launch in January 2027, timed to align with the start of Saver’s Match, a federal program enacted in 2022 under President Joe Biden to match retirement contributions, with a maximum match up to $1,000 per individual. To qualify for Saver’s Match, a single filer must earn less than $35,500. Saver’s Match will replace the current Saver’s Credit, a nonrefundable tax credit that reduces tax owed. Workers will be able to filter retirement plans by factors like “cost, minimum contribution, and minimum balance,” Semafor reported. What else happens under the executive order? The Treasury Department and the National Economic Council will draft legislative recommendations to expand The President’s plan, such as automatically enrolling workers and making them eligible for the match. Notably, while the Treasury will vet the plans on The PresidentIRA.gov, it will not partner with any financial institutions. Roughly 60% of Americans report having access to a retirement plan such as a 401(k), a 2025 Gallup survey revealed. However, the percentage drops to just 28% for households earning less than $50,000. The President first addressed a plan to increase retirement savings during his 2026 State of the Union address, noting that half of all working Americans “do not have access to a retirement plan with matching contributions from an employer.” “To remedy this gross disparity, I’m announcing that next year, my administration will give these often-forgotten American workers—great people; the people that built our country—access to the same type of retirement plan offered to every federal worker.” View the full article
-
Donald Jr and Eric have sought to capitalise on sectors backed by father’s presidential administrationView the full article
-
Payroll is more than just paying employees; it’s a critical aspect of your business operations that affects employee morale and legal compliance. It involves calculating gross pay, managing deductions, and ensuring accurate net pay, all during adherence to tax regulations. An effective payroll system streamlines processes and maintains fundamental records for audits. Comprehending its intricacies can greatly impact your business’s success, but what are the specific methods and strategies you can implement to optimize this important function? Key Takeaways Payroll is the process of calculating and distributing employee wages, impacting overall employee satisfaction and retention. Accurate payroll management ensures compliance with tax laws, minimizing legal risks and penalties for your business. Efficient payroll processing involves tracking employee hours, calculating gross pay, and applying necessary deductions for taxes and benefits. Proper recordkeeping is essential for audits and legal requirements, with documentation needed for at least three years. Outsourcing payroll to professional services can streamline operations, reduce errors, and allow businesses to focus on core activities. Understanding Payroll and Its Significance Payroll is a fundamental aspect of running any business, as it involves the systematic process of calculating and distributing employee wages. Comprehending payroll‘s definition is vital; it encompasses gross pay, deductions, and net pay, guaranteeing compliance with tax laws. The payroll process includes employer-paid taxes for Social Security and Medicare, which are essential for legal employment standards and employee benefits. Accurate payroll processing directly impacts employee satisfaction and retention. When employees receive timely payments, it reduces turnover and improves workplace morale. Small businesses often struggle with payroll because of complex compliance requirements. Hence, utilizing payroll solutions or services is crucial to minimize errors and administrative burdens. Furthermore, payroll impacts financial management and involves record-keeping for audits and tax filings, which are significant for maintaining transparency and regulatory adherence. By grasping the significance of payroll, you can guarantee smooth operations in your business. The Payroll Process: Key Steps Explained Comprehending how payroll operates is fundamental for maintaining a smooth business workflow. The payroll process involves several key steps that guarantee your employees are paid accurately and on time. Here’s a breakdown: Gather Employee Information: Collect necessary forms like W-4 and I-9 to guarantee correct tax withholding and compliance with labor laws. Calculate Gross Pay: Determine total earnings based on hourly rates or salaries, including any reimbursements for out-of-pocket expenses. Apply Deductions: Subtract federal and state taxes, Social Security, Medicare, retirement contributions, and any garnishments from gross pay to find net pay. After calculating net pay, distribute payments swiftly via checks or direct deposits to maintain employee satisfaction. Finally, careful recordkeeping of all payroll transactions, including tax filings and compensation details, is vital for compliance and future audits. Types of Payroll Processing Methods In terms of payroll processing methods, you have several options to evaluate. Manual payroll systems might seem straightforward, but they can be time-consuming and prone to errors. On the other hand, automated solutions offer speed and accuracy through software. Furthermore, outsourcing your payroll to third-party services can ease administrative burdens and help you navigate compliance issues more effectively. Manual Payroll Systems Overview For many small businesses, a manual payroll system can seem like a viable option in spite of its drawbacks. This method involves using spreadsheets or physical records to track employee hours and calculate wages. Nevertheless, it requires a significant time investment and a comprehensive grasp of complex calculations. Here are three key considerations: Time Consumption: Processing payroll can take over an hour bi-weekly, which adds to your administrative burden. Risk of Errors: Human error is a constant threat, especially with changing tax laws and reporting requirements. Record-Keeping: Regular updates and careful record-keeping are crucial for compliance and accurate payments. While the upfront costs may be lower, the potential for compliance issues makes manual systems a risky choice. Automated Solutions Benefits Automated payroll solutions offer numerous benefits that can greatly streamline your business’s payroll processing. They considerably cut down processing time, allowing you to complete payroll tasks in minutes instead of hours. These systems reduce the risk of errors in calculations and compliance by automating tax filings and ensuring accurate deductions. Many integrate seamlessly with time management and HR software, improving efficiency. Furthermore, payroll software helps save costs related to errors and compliance issues, contributing to better financial health. Features like employee self-service portals improve transparency and satisfaction. Benefit Description Impact Time Savings Complete payroll in minutes Increased productivity Error Reduction Automate calculations and compliance Improved accuracy Integration Work with HR and time management systems Streamlined processes Cost Efficiency Minimize penalties and errors Better financial health Employee Access Self-service portals for pay stubs and tax docs Improved satisfaction Third-party Service Considerations Choosing the right payroll processing method is essential for any business looking to improve efficiency and reduce administrative burdens. Third-party payroll services can streamline your payroll by managing calculations, payments, and tax filings. Here are three key types of payroll processing methods to reflect on: Automated Payroll Solutions: These software-driven systems minimize errors and save time, allowing for quicker processing than manual systems. Outsourced Payroll Providers: These services offer compliance support, helping guarantee you adhere to federal and state regulations, consequently reducing the risk of penalties. User-friendly Platforms: Many third-party services allow employees to access their payroll information independently, enhancing overall satisfaction and reducing inquiries. Utilizing these services can free up valuable time, letting you focus on core business operations. Compliance and Recordkeeping in Payroll Management Effective compliance and recordkeeping in payroll management are crucial for every business, as they help avoid costly penalties and secure legal standing. You must file payroll taxes on time, covering federal, state, and local obligations, to maintain compliance. Accurate payroll records are essential for audits, with federal law requiring you to keep documentation for at least three years, and potentially longer in some states. Furthermore, you’re obligated to provide employees access to their payroll history, which includes gross pay, deductions, and net pay, guaranteeing transparency and adherence to labor regulations. The IRS also mandates issuing W-2 forms by January 31 each year, detailing wages earned and taxes withheld. Good recordkeeping not only guarantees compliance but also improves payroll efficiency, enabling quick access to necessary information during audits or financial reviews. Benefits of Using Professional Payroll Services Utilizing professional payroll services can greatly boost your time efficiency, allowing you to process payroll in just a few minutes instead of hours. These services furthermore guarantee compliance with tax laws, helping you avoid costly mistakes and penalties. In addition, with improved accuracy in payroll management, you can trust that your employees are compensated correctly and on time, allowing you to focus on growing your business. Time Efficiency Improvement When you decide to outsource payroll to a professional service, you can drastically improve time efficiency for your business. You’ll save valuable hours that can be redirected to more important tasks. Here’s how: Reduce Processing Time: Payroll processing can shrink from over an hour to just three minutes bi-weekly, enhancing overall productivity. Automate Tasks: Automation minimizes manual calculations and paperwork, freeing you from administrative burdens. Integrated Tools: Many services offer features like tax handling and employee self-service, simplifying the payroll process during boosting employee satisfaction. Compliance Assurance Benefits Outsourcing payroll not just saves time but also improves compliance assurance, a key benefit for any business. Professional payroll services guarantee timely and accurate filing of payroll taxes, which reduces the risk of penalties and errors linked to non-compliance with federal and state regulations. By automating complex processes, like filing IRS Form 941, these services help you meet tax obligations as you allow yourself to focus on core operations. Utilizing a payroll service minimizes errors related to employee classification, tax withholding, and deductions, protecting you from costly audits and fines. In addition, payroll providers take responsibility for resolving tax notices and compliance issues, giving you peace of mind as you concentrate on growing your business and reducing administrative burdens. Payroll Accuracy Enhancement Many businesses find that payroll accuracy is crucial to their success, as even small errors can lead to considerable complications. Utilizing professional payroll services can greatly improve your payroll accuracy in several ways: Error Reduction: Automated systems considerably decrease the risk of mistakes, with businesses experiencing up to 80% fewer payroll-related errors. Employee Satisfaction: Timely and accurate payments improve trust and morale among your staff, nurturing a positive work environment. Compliance Assurance: Many providers offer built-in compliance checks, helping you stay updated with the latest tax laws and labor regulations, reducing legal risks. Common Payroll Challenges for Small Businesses Guiding payroll can pose significant challenges for small businesses, particularly as they endeavor to maintain accuracy and compliance. One major hurdle is accurately tracking employee hours; mistakes here can lead to payroll errors and dissatisfaction. Furthermore, keeping up with federal and state payroll tax regulations is essential since non-compliance may result in costly penalties. Many small businesses often lack the resources to maintain detailed payroll records, complicating audits and responses to employee inquiries about pay. Manual calculations of gross pay and deductions can be time-consuming and prone to error, introducing inefficiencies and potential legal issues. As your business grows, you may face increasing intricacies with varying employee classifications, benefits, and tax obligations, making sophisticated payroll solutions necessary. Comprehending these challenges is key to steering payroll effectively and ensuring smooth operations. Frequently Asked Questions What Does Payroll Actually Do? Payroll primarily guarantees that you accurately compensate your employees for their work. It calculates gross pay based on hours or salaries, then deducts necessary taxes and benefits, including retirement and health insurance. You must comply with labor laws and tax regulations, requiring timely filings and accurate records to avoid penalties. Furthermore, payroll systems can automate these tasks, saving time and reducing errors, as well as offering insights into your labor costs for budgeting purposes. How Does Payroll Work for a Small Business? Payroll for a small business involves several key steps. First, you must track employee hours accurately, then calculate their gross pay based on those hours. Next, you’ll withhold necessary taxes and deductions, ensuring compliance with regulations. Obtaining an Employer Identification Number (EIN) is vital, along with preparing forms for direct deposit or checks. Finally, maintain accurate records to support compliance during audits and to manage payroll efficiently, making it a significant business function. Is It Worth Doing Your Own Payroll? Deciding whether to manage your own payroll involves weighing costs against time and compliance risks. Whereas doing it in-house may seem budget-friendly, it often consumes over an hour every two weeks, cutting into your core business activities. Furthermore, intricacies in tax laws can lead to costly errors. Utilizing payroll software can streamline this process, reducing time spent to mere minutes and ensuring compliance, making it a worthwhile investment for efficiency and accuracy. How Much Should Payroll Be for a Business? Payroll should ideally account for 30% to 50% of your business’s total expenses, depending on your industry. For small businesses, average annual costs per employee range from $45,000 to $65,000, including wages, taxes, and benefits. Don’t forget to factor in employer-paid taxes and potential overtime, which can greatly increase costs. Regularly assess your payroll against revenue to maintain a sustainable wage-to-revenue ratio and guarantee profitability in your operations. Conclusion In conclusion, comprehending payroll is vital for your business’s success. It involves calculating wages, managing deductions, and ensuring compliance with tax regulations. By implementing effective payroll processes and considering professional services, you can streamline operations and improve record-keeping. Addressing common payroll challenges is important, especially for small businesses, as it directly affects employee satisfaction and retention. A well-managed payroll system not just supports your workforce but additionally contributes to the overall efficiency of your organization. Image via Google Gemini This article, "What Does “Payroll” Really Mean for Your Business?" was first published on Small Business Trends View the full article
-
Chipotle has been tweaking its recipe to lure diners back, and in the first quarter of the year it appears to be working. The build-your-own burrito chain posted higher sales in its new quarterly earnings report, showing some signs of life after a record rough year. Chipotle reported that sales across established stores perked up by .5%, besting a predicted 1% decline. In the first three months of the year, the chain reported $302.8 million in net income, down from $386.6 million in the first quarter of 2025 – a period prior to its recent struggles. Cost of living stress tied to high prices – and now the war in Iran – continues to steer price-conscious consumers away from restaurant dining. With little relief in sight, Chipotle and its peers are scrambling to develop a secret sauce so enticing that sales bounce back. For Chipotle, that’s meant reintroducing hit menu options like chicken al pastor, getting creative about boosting protein offerings (yes, that means chicken in a cup), and mixing things up with a limited time cilantro lime sauce. Last year, Chipotle found its core customers staying away. The company repeatedly cut its sales forecasts in 2025, leaving investors with a bad taste in their mouth when it came to the once-hot restaurant stock. In the second half of 2025, Chipotle shares plunged to their lowest price since 2023, erasing huge gains from 2024 and the first half of the year. Chipotle builds loyalty with burrito lovers Chipotle CEO Scott Boatwright pointed to economic concerns like “unemployment, increased student loan repayment, and slower real wage growth” that hit its core young diner demographic particularly hard in 2025. “We believe that this trend is not unique to Chipotle,” Boatwright said, noting that the phenomenon is taking a toll on restaurants more broadly. “We tend to skew younger and slightly over-indexed to this group relative to the broader restaurant industry,” Boatwright said. Chipotle is still rebuilding some goodwill with customers suspicious that the burrito hub started skimping on its once-generous portions. The shrinkflation scandal took root on TikTok in 2024, which was particularly a problem given the chain’s young, plugged-in target demographic. To right the ship, the company forged ahead with a plan to expand its brick and mortar footprint in 2026. Chipotle hopes to offset some of the costs associated with new store openings with perkier sales in new markets that don’t yet have an instance of the burrito chain. The company expects to break ground on as many as 370 new locations this year, including new restaurants in Singapore, South Korea, and even Mexico – a risky move for a purveyor of Americanized cuisine with Mexican roots. The chain is also revamping its rewards, redesigning the loyalty program to feel more like a game. Chipotle’s rewards program is key to its success, boasting 21 million active members who drive almost a third of the restaurant’s sales. Most of that happens in the company’s app, which features brand activations like “Freepotle,” which rewards dedicated burrito connoisseurs with perks like free guac. Chipotle’s refreshed loyalty program will offer more personalized rewards and achievements that take individual customer behavior into account, the company explained to Fast Company earlier this month. Chipotle’s Chief Strategy and Technology Officer Curt Garner noted that the company looked beyond restaurants to brand loyalty success stories like Peloton in shaping the new rewards scheme. “We saw what some other brands were doing in places that lead culture and thought, ‘Let’s experiment with things that are similar.’” View the full article
-
Hedge fund Black Diamond claims at least $70mn in damages against audit firmView the full article
-
Accounts payable accounts represent a company’s short-term financial obligations for goods and services acquired on credit, usually due within 30 to 90 days. They appear as current liabilities on the balance sheet, indicating future cash outflows rather than immediate expenses. When you purchase on credit, you debit the relevant asset account and credit accounts payable, showing your obligation to the vendor. Comprehending how these accounts function is crucial for effective financial management and maintaining cash flow. What are the specific benefits of managing accounts payable efficiently? Key Takeaways Accounts payable (AP) represents a company’s financial obligations for goods and services acquired on credit, typically due within 30 to 90 days. AP is classified as a current liability on the balance sheet, indicating future cash outflows rather than immediate expenses. The recording of accounts payable involves double-entry bookkeeping, debiting relevant asset accounts and crediting accounts payable. Efficient management of AP affects cash flow and vendor relationships, emphasizing the importance of timely payments. Key metrics like AP Turnover Ratio and Days Payable Outstanding (DPO) help assess the efficiency of settling liabilities. Definition and Characteristics of Accounts Payable Accounts Payable (AP) represents a vital component of a company’s financial obligations, particularly the amounts owed for goods and services acquired on credit. Typically due within 30 to 90 days, these obligations are classified as current liabilities on the balance sheet, reflecting short-term debts owed to creditors or suppliers. Comprehending accounts payable categories is significant, as they help you manage these credits effectively. It’s noteworthy that although AP is related to expenses, is accounts payable an expense? The answer is no; accounts payable isn’t classified as an expense on the income statement. Instead, it indicates future cash outflows. Furthermore, knowing that payables aren’t considered expenses means you can track cash flow better. Accurate recording and management of AP require a solid grasp of double-entry bookkeeping, ensuring precise financial reporting and enhancing your company’s cash flow stability. Examples of Accounts Payable When managing a business’s finances, recognizing various examples of accounts payable is essential for effective cash flow management. Accounts payable accounts encompass obligations to suppliers for goods and services received on credit. For instance, invoices for raw materials and utility bills reflect these liabilities. You might encounter payments for contractor services, such as repairs or renovations, which fall under accounts payable. In addition, expenses like electricity and water bills, due monthly, are likewise included. Professional service fees for legal or consulting work typically appear as accounts payable accounts and are paid periodically. Moreover, transportation and logistics costs incurred for goods delivery remain as accounts payable until settled. Finally, equipment purchases made on credit, such as office furniture or machinery, contribute to your accounts payable, indicating liabilities on your balance sheet. Comprehending these examples can help you manage your business’s financial obligations more efficiently. Financial Statement Role of Accounts Payable The role of accounts payable in financial statements is crucial for comprehending a company’s short-term financial health. Accounts payable (AP) appears under current liabilities on the balance sheet, reflecting obligations to suppliers for goods and services received on credit. Properly managed AP is critical, as a growing balance could signal cash flow issues. Here are key aspects to reflect upon: AP Turnover Ratio: This ratio measures how efficiently you settle your liabilities by dividing total net credit purchases by the average accounts payable balance. Days Payable Outstanding (DPO): DPO measures the average number of days it takes to pay your accounts payable, offering insights into financial stability. Impact on Liquidity Ratios: Inaccuracies in recording AP can misrepresent financial statements and affect liquidity. Monitoring Metrics: Regularly tracking AP metrics helps maintain effective financial management and operational effectiveness. Recording Accounts Payable Recording accounts payable accurately is essential for maintaining a clear view of a company’s financial obligations. This process involves double-entry bookkeeping, where an increase in liabilities is matched with an equal increase in assets or expenses. When you purchase goods or services on credit, you’ll typically debit the relevant asset account, like inventory, and credit accounts payable to reflect your obligation to the vendor. When you pay the liability, you debit accounts payable to decrease the liability and credit the cash account to show the cash outflow. Regularly reconciling your accounts payable records with vendor statements helps you detect discrepancies and guarantees effective financial management. Here’s a simple table to illustrate these transactions: Transaction Type Debit Account Credit Account Purchase Inventory Accounts Payable Payment Accounts Payable Cash Accounts Payable Management and Comparison With Accounts Receivable Managing accounts payable (AP) effectively is crucial for maintaining a business’s financial health, as it directly impacts cash flow and vendor relationships. During AP represents short-term liabilities to suppliers, accounts receivable (AR) indicates amounts owed to your business by customers. Here are some key differences and management strategies: Timely Payments: Efficient AP management involves processing invoices quickly to maintain good vendor relationships. Cash Flow Impact: AP directly influences cash flow, whereas AR focuses on collecting payments, affecting liquidity differently. Performance Metrics: The AP turnover ratio measures how quickly you settle liabilities, contrasting with AR’s Days Sales Outstanding (DSO). Operational Efficiency: Good AP practices improve cash flow and operational efficiency, whereas poor AR management can lead to cash shortages. Frequently Asked Questions What Is Accounts Payable and How Does It Work? Accounts payable refers to the short-term liabilities your business has to suppliers for goods and services received on credit. When you receive an invoice, you verify it against purchase orders before authorizing payment. Typically due within 30 to 90 days, these obligations appear as current liabilities on your balance sheet. Efficient management of accounts payable can improve your cash flow and strengthen vendor relationships, potentially leading to favorable credit terms and discounts. What Are the Main Functions of Accounts Payable? The main functions of accounts payable include tracking outstanding invoices, ensuring timely vendor payments, and maintaining accurate financial records. You verify vendor invoices against purchase orders to prevent errors before payment processing. Managing cash flow is essential, so you strategically time payments to benefit from discounts or avoid penalties. Regularly reconciling the accounts payable ledger with the general ledger helps identify discrepancies, ensuring an accurate reflection of your liabilities and improving financial health. What Is the Golden Rule of Account Payable? The Golden Rule of Accounts Payable emphasizes paying your suppliers on time. By doing this, you maintain strong relationships with vendors, which can lead to better credit terms and discounts. Timely payments improve your credit rating, vital for future financial support. Managing your cash flow effectively means scheduling payments strategically to avoid late fees and service disruptions, ensuring your operations remain smooth and your reputation as a reliable partner stays intact. How to Explain Accounts Payable in an Interview? When you explain accounts payable in an interview, focus on its role as a current liability representing amounts owed to suppliers. Highlight the importance of timely invoice processing and accurate record-keeping, which guarantees financial health. Mention the need to maintain strong vendor relationships and how effective AP management impacts cash flow. Furthermore, discuss familiarity with accounts payable software, as automation can improve efficiency and reduce errors in financial reporting. Conclusion In conclusion, accounts payable are fundamental for managing a company’s short-term liabilities, reflecting obligations for goods and services purchased on credit. They play a vital role in financial statements and require careful recording and management to guarantee healthy cash flow. By efficiently handling accounts payable, businesses can maintain strong vendor relationships and support overall financial stability. Comprehending this aspect of finance is important for anyone involved in business operations, as it directly impacts a company’s liquidity and operational efficiency. Image via Google Gemini This article, "What Are Accounts Payable Accounts and How Do They Function?" was first published on Small Business Trends View the full article
-
Intel has launched its new Intel Core Series 3 mobile processors, which promise significant improvements in performance and efficiency for small businesses and everyday computing tasks. With advancements in battery life and AI capabilities, these processors aim to meet the rising demands of modern users without breaking the bank. Josh Newman, General Manager and Vice President of Consumer PC at Intel, stated, “At a time when prices are rising and expectations are shifting, Intel Core Series 3 elevates value-oriented computing with exceptional battery life, boosted AI-ready performance, and broad ecosystem choice.” Small business owners looking to upgrade their technology will find the Intel Core Series 3 an appealing option during typically five-year upgrade cycles. Compared to older PCs, these processors deliver notable enhancements: up to 47% better single-thread performance, a 41% increase in multi-thread performance, and up to 2.8 times improved AI performance. Such gains can lead to smoother multitasking and enhanced productivity for teams engaged in everything from administrative tasks to creative projects. The Intel Core Series 3 processors stand out for several reasons: They are Intel’s first hybrid AI-ready processors, enabling support for AI workloads with a robust platform performance of up to 40 TOPS. They feature modern connectivity options, including two integrated Thunderbolt 4 ports and support for Intel® Wi-Fi 7 (R2) and Bluetooth® 6. Designed for all-day battery life, these processors deliver up to 2.1 times faster productivity rates and require up to 64% less power compared to previous generation Intel Core 7 150U processors. Beyond simple computing tasks, the new processors extend their capabilities to various edge computing applications. For small businesses involved in retail or smart technology, the processors can optimize operations across robotics, smart buildings, point-of-sale terminals, and smart metering. This integration offers a cost-effective way to enhance customer experiences and streamline processes without the need for large-scale infrastructure enhancements. However, as with any new technology, small business owners should weigh the practical implications of upgrading to these processors. The benefits are clear, but transitioning to new systems can sometimes involve upfront costs and a learning curve for employees. Particularly for those businesses reliant on specific legacy software or hardware, ensuring compatibility is crucial before making a change. The Intel Core Series 3 processors are set to hit the market via numerous OEM partners, including Dell Technologies, HP, Lenovo, and Samsung, starting from April 16, 2026. This affordable option for companies looking to elevate their computing capabilities comes at a time when efficient, powerful technology is increasingly necessary for maintaining competitiveness. The processors also boast impressive performance metrics against competitors like Nvidia Jetson Orin Nano. They offer up to 1.5 times higher object detection capabilities, nearly double the speed in image classification, and significantly better results for video analytics. This makes them a suitable option for businesses looking to delve deeper into AI-driven applications. As the landscape of everyday computing continues to evolve, small business owners now have access to powerful, cost-effective solutions. With Intel’s latest offerings, the potential for enhanced productivity and innovative applications is vast. Keeping an eye on the rollout of these systems will allow entrepreneurs to determine the best timing for upgrades, ultimately positioning their businesses for future success. For more information on the Intel Core Series 3 processors, see the original press release at Intel Newsroom. Image via Intel This article, "Intel Launches Core Series 3 Processors, Boosting Performance and Value" was first published on Small Business Trends View the full article
-
Home affordability declined on a monthly basis across loan types and racial demographics, but improved from a year ago, the Mortgage Bankers Association said. View the full article
-
A federal judge harshly criticized the settlement of a civil suit between the Department of Justice and a Texas land developer. View the full article
-
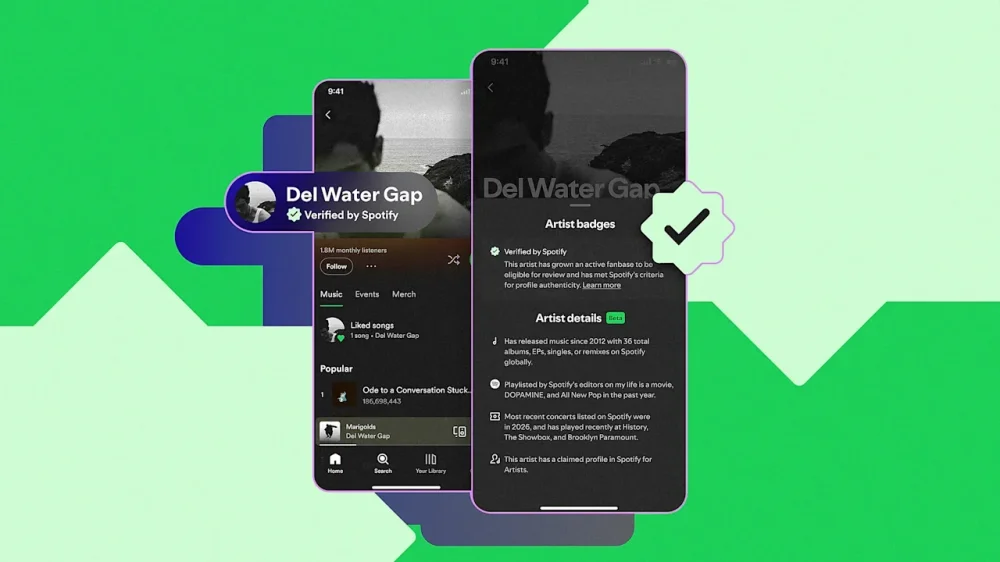
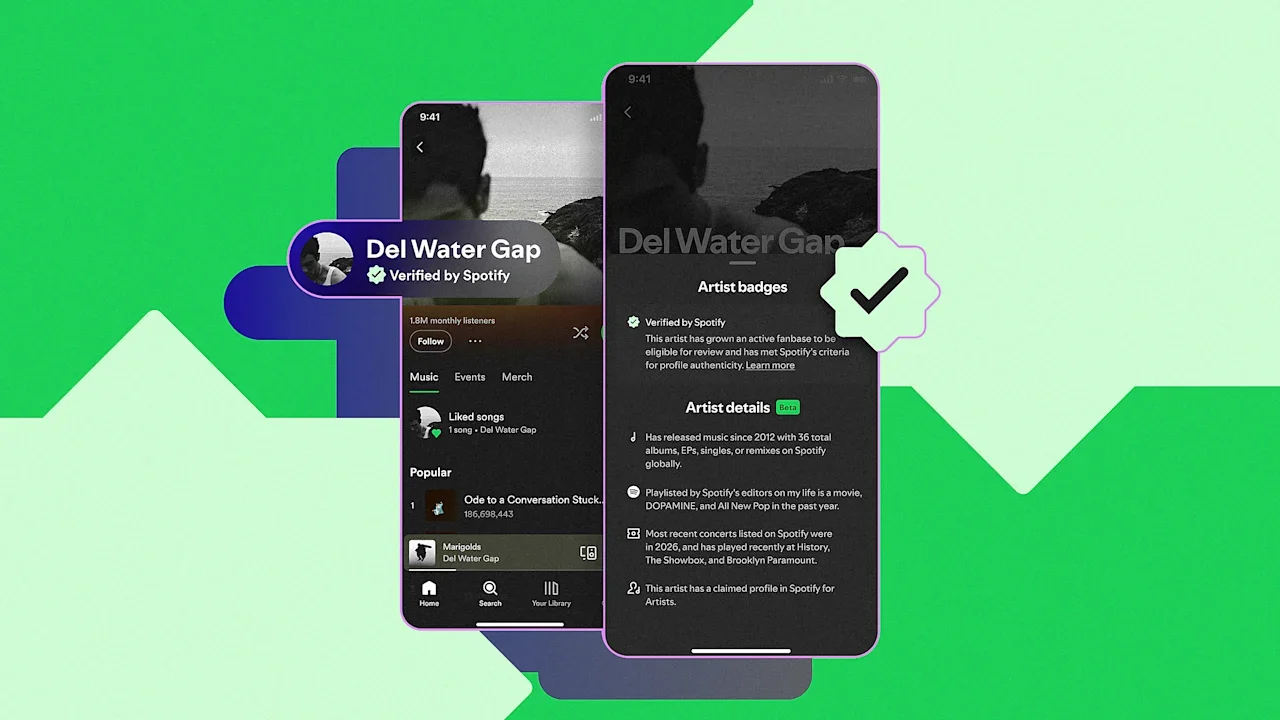
When browsing social media it is sometimes hard to discern reality from AI. Is a video of bunnies jumping on a trampoline at night real-life? Probably not. But while some of us are stuck trying to figure out the authenticity of visual content, Spotify is jumping ahead to help users know if who they are listening to is actually human. The streaming giant’s newest feature, Verified by Spotify, gives artists who have been reviewed by Spotify a mint-green check beside their profile. The company evaluates robust criteria to determine a profile’s authenticity and trust, including data related to listener activity, engagement over time, and an identifiable artist presence in and outside of Spotify. “We’ll pair these standards with human review and judgment to identify real artists behaving in good-faith, not just filtering out bad actors, giving you a more reliable signal of the authentic artistry behind the music,” Spotify said of the announcement. They added, “In today’s music landscape, the concept of artist authenticity is complex and quickly evolving, and we’ll continue to develop our approach over time.” Users will be able to see the badges in the coming weeks, with the company claiming they ensured that “more than 99% of the artists Spotify listeners actively search for will be verified,” at its launch on April 30. The new feature follows a series of added safeguards for listeners as AI scams proliferate in the music industry. Take a recently published song by country singer Blaze Foley on Spotify which turns out was not by the singer—he’s been dead for over two decades—and was instead generated and published using AI. This practice has become increasingly common for scammers who seek to claim royalties from streaming services. In response, Spotify has rolled out a number of safety features for both artists and listeners alike. Artist Profile Protection, for instance, is an opt-in service that enables an extra review step for artists by requiring them to manually authorize a new song populating on their profile. Additional AI protections have also been implemented since last year, with strengthened rules on impersonations, a music spam filter, and efforts towards AI disclosures with industry-wide credits. In addition to the verification badge, Spotify is also introducing a new beta section for artist profiles, similar to nutritional facts on a food package. Regardless of verification status, the artist details section allows listeners to learn more about the artist’s career milestones, release history, and touring activity. Still, while new feature mean to offsett growing concerns around AI and the trust between artists and listeners, safeguards will continue to evolve alongside the emerging technology. “Our goal is to make it easier for you to trust and understand the human artistry behind the music you listen to on Spotify, and develop long-term, meaningful connections with the artists and music you love,” the company said. View the full article