Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
If you’re starting out in video editing, choosing the right app can greatly influence your learning experience. Several options cater particularly to beginners, offering user-friendly interfaces and crucial features. Free apps like DaVinci Resolve and Shotcut provide robust tools without the cost, whereas iMovie simplifies the process for Mac users. On the mobile front, CapCut and KineMaster stand out for their trendy effects. Comprehending your needs will help narrow down the best choice for you, but there’s more to reflect on. Key Takeaways Free apps like DaVinci Resolve and iMovie provide powerful features without cost, making them ideal for beginners. User-friendly options such as CapCut and Filmora offer intuitive interfaces and trendy effects for social media content creation. Multi-layer support in apps like KineMaster allows for more complex editing while maintaining accessibility for new users. Consider device compatibility; iMovie is great for iOS, while CapCut works well on both Android and iOS platforms. Evaluate your editing goals to choose the best app, whether for social media, YouTube, or personal projects. Best Free Video Editing Apps for Beginners When you’re starting your expedition in video editing, choosing the right app can greatly impact your learning experience. Among the best video editing apps for beginners, DaVinci Resolve stands out for its professional-grade features and free access. If you prefer something simpler, Shotcut offers a user-friendly, open-source platform that supports various formats without watermarks. For those interested in visual effects, HitFilm Express provides a robust free version, though it may require more time to master. CapCut is excellent for mobile users, with trendy effects and easy-to-use tools designed for social media content. Finally, iMovie is perfect for Mac users, offering crucial features in a straightforward interface. Each of these options can help you develop your video editing skills effectively. Best Paid Video Editing Apps for Beginners For beginners looking to invest in video editing, several paid apps provide a balance of user-friendly interfaces and strong features. Adobe Premiere Elements is a standout choice, offering guided edits and AI tools along with a one-time payment structure that covers three years of use, making it a cost-effective option as you advance your skills. CyberLink PowerDirector features a sleek interface and is available via subscription at $19.99 monthly or $54.99 annually, including motion tracking and screen recording. Filmora offers budget-friendly subscription options and perpetual licenses, catering to novice editors with professional-level features. Finally, ACDSee Luxea provides a free version with an extensive toolset, whereas Final Cut Pro is ideal for Mac users but may be complex for absolute beginners. Best Video Editing Apps for Ios Users If you’re an iOS user seeking to explore video editing, several apps cater to varying skill levels and needs. iMovie stands out as a free option that’s pre-installed on all iOS devices, offering essential tools like video stabilization and chroma keying, which can help you create polished videos effortlessly. CapCut is another popular free app designed for social media content, featuring trendy effects and auto-captioning for a user-friendly experience. For more advanced editing, KineMaster provides multi-layer support, though its free version includes a watermark. Adobe Premiere Rush allows quick edits with a drag-and-drop interface, whereas LumaFusion offers professional-grade features like multi-track editing and 4K support, available for a one-time purchase. Best Video Editing Apps for Android Users Video editing on Android devices has become increasingly accessible, thanks to a variety of robust apps customized for users at different skill levels. CapCut is a standout choice, offering a free and intuitive interface that includes trendy effects, auto-captioning, and multi-layer editing, making it ideal for quick social media content creation. KineMaster takes things a step further with its professional-level capabilities, enabling multi-layer video editing, real-time previews, and a range of effects, which cater to creators seeking more advanced tools. FilmoraGo provides user-friendly templates, music options, and easy sharing features. InShot allows quick edits with trimming, merging, and music integration, whereas VivaVideo boasts creative tools with drag-and-drop functionality, ensuring engaging videos are just a few taps away. Best Video Editing Apps for Social Media Content In relation to creating engaging social media content, selecting the right video editing app can make all the difference. You’ll want to think about apps like CapCut, which offers trendy effects and auto-captioning, or Clipchamp, known for its customizable templates designed for social media marketing. Grasping the crucial features of these editors will help you produce videos that capture attention and improve your online presence. Top Social Media Editors Creating engaging social media content has never been easier, thanks to a variety of potent video editing apps designed particularly for beginners. CapCut stands out as a free option, offering trendy effects and auto-captioning, making it perfect for quick edits on platforms like TikTok and Instagram. Clipchamp provides an intuitive, browser-based experience with templates customized for social media, enabling you to create appealing content effortlessly. For those who want to mix video and photo editing, InShot allows you to add music, text, and stickers easily. If you’re seeking simplicity, Adobe Premiere Rush offers single-track editing for quick uploads. Finally, KineMaster delivers professional-level tools, suitable for more complex video projects, with multiple layers and effects. Essential Features for Engagement To effectively engage your audience on social media, it’s fundamental to choose video editing apps that offer significant features customized for this purpose. Look for user-friendly interfaces and a variety of templates, as seen in apps like CapCut and Clipchamp, designed particularly for platforms like TikTok and Instagram. Built-in social media integrations allow for seamless sharing, enabling quick uploads. Key tools like auto-captioning and trendy effects make your videos more accessible and visually appealing. Utilizing music libraries and sound effects is imperative, as studies reveal that sound boosts attention. Finally, efficient rendering speeds are significant; apps like CyberLink PowerDirector offer quick exports to meet the fast-paced demands of digital content sharing. Best Video Editing Apps for Quick Edits Here’s a quick comparison of some top apps for quick edits: App Key Features Clipchamp Templates, free, browser-based CapCut Built-in effects, auto-captioning Filmora One-click editing, professional effects iMovie Clean interface, fundamental tools Best Video Editing Apps With Advanced Features If you’re looking to take your video editing skills to the next level, several apps offer advanced features that can improve your projects. Filmora and KineMaster provide strong multi-layer support, letting you add various video and audio tracks for more complex edits. Furthermore, apps like DaVinci Resolve and CyberLink PowerDirector include advanced editing tools such as motion tracking and AI-driven effects, making them suitable for users ready to explore deeper editing techniques. Advanced Editing Tools As you plunge into the domain of video editing, selecting an app with advanced features can greatly boost your projects. Tools like Adobe Premiere Pro and Final Cut Pro offer extensive options, including multi-track editing and advanced color grading, perfect for thorough editing. CyberLink PowerDirector improves your workflow with AI-driven features such as motion tracking and automatic scene detection. DaVinci Resolve is renowned for its robust color correction and visual effects, appealing to both professionals and beginners alike. Filmora allows you to add advanced effects like motion tracking and audio ducking without overwhelming complexity. Furthermore, Kdenlive offers advanced functions like GPU rendering and a customizable interface, making it an excellent choice for experienced users seeking open-source solutions. Multi-layer Support Multi-layer support in video editing apps greatly boosts your ability to create intricate projects, allowing you to work with multiple video and audio tracks simultaneously. This feature is crucial for adding overlays, picture-in-picture effects, and more complex compositions. Apps like KineMaster and Adobe Premiere Rush enable you to combine various media types seamlessly. Here’s a quick comparison of some beginner-friendly apps with multi-layer support: App Name Key Features User Interface KineMaster Multi-track audio, video overlays Intuitive Adobe Premiere Rush Advanced effects, easy sharing User-friendly Filmora Text layers, shifts Simple CapCut Effects library, stickers Accessible With these tools, you can elevate your creative expression as you maintain workflow efficiency. Best Video Editing Apps With Screen Recording Capabilities Regarding video editing apps that also feature screen recording capabilities, several standout options cater to beginners. ACDSee Luxea integrates screen recording with user-friendly editing tools, perfect for tutorials or gameplay videos. CyberLink PowerDirector allows you to capture your desktop or gameplay, making it easy to produce professional-looking videos with voiceovers. Filmora simplifies desktop activity capture, ideal for instructional content or presentations, boasting an intuitive interface. Movavi Video Editor provides a straightforward screen recording option, enabling you to record and edit footage as well as offering various effects and transitions. Finally, OBS Studio is a free, open-source software that delivers high-quality screen recording, making it an excellent choice for those aiming to create tutorials or stream content. Best User-Friendly Video Editing Apps When you’re starting out in video editing, finding user-friendly apps can make a significant difference in your experience and results. CapCut features an intuitive interface and trendy effects, perfect for creating engaging social media content. If you’re an Apple user, iMovie is pre-installed and offers a clean layout with crucial tools, making it easy to learn the basics. KineMaster provides a professional-level experience on mobile, supporting multi-layer editing for high-quality videos. For web-based editing, Clipchamp has numerous templates and straightforward tools that cater to various skill levels. Finally, Adobe Premiere Rush combines user-friendliness with potent features, enabling quick edits and direct uploads to platforms like YouTube, making it ideal for beginners. How to Choose the Right Video Editing App for You How can you determine which video editing app is the best fit for your needs? Start by evaluating your budget; free options like CapCut or iMovie provide excellent features without cost. Next, check device compatibility to guarantee the app runs smoothly on your operating system, whether it’s Windows, Mac, or mobile. Identify your primary editing purpose, like creating social media content or producing complex YouTube videos, to select an app that aligns with those goals. Analyze the app’s learning curve; user-friendly interfaces and accessible tutorials are especially useful for beginners. Finally, consider export capabilities, including resolution limits or watermarks in free versions, to ensure your final output meets your quality standards. Frequently Asked Questions Which Video Editing App Is Best for Beginners? When choosing a video editing app as a beginner, consider user-friendly options that simplify the editing process. Apps like CapCut offer trendy effects and auto-captioning, whereas iMovie provides core tools for Mac users. You might as well explore Adobe Premiere Rush for quick uploads or KineMaster for more editing control. Filmora is another solid option, featuring helpful tutorials to guide you. Assess your needs to determine which app aligns best with your editing goals. What Do Most Youtubers Use to Edit Their Videos? Most YouTubers use various video editing software depending on their needs. Adobe Premiere Pro is favored for its advanced features and compatibility with other Adobe tools. CyberLink PowerDirector is popular for its user-friendly interface and quick rendering. Mac users often choose iMovie for its accessibility and simplicity. DaVinci Resolve gains traction for its potent free version, whereas CapCut is utilized for its trendy effects and mobile editing capabilities, catering to social media content. What Is the Easiest Free Video Editing App? The easiest free video editing app is CapCut. It features a user-friendly interface, making it simple for you to navigate and edit your videos. You’ll find various trendy effects and templates that can improve your content without overwhelming you. Another option is iMovie, which is pre-installed on Macs and offers vital tools. If you prefer browser-based editing, Clipchamp provides intuitive multi-track editing and free templates, ensuring a seamless experience for new users. Which Course Is Best for Video Editing for Beginners? When choosing a video editing course for beginners, consider platforms like Udemy or Coursera. They offer structured lessons on crucial software, including Adobe Premiere Pro and DaVinci Resolve. Look for courses that provide hands-on projects to practice your skills and build a portfolio. Moreover, guarantee the course offers lifetime access to materials and community support for ongoing feedback. Prices vary, so explore options ranging from free to several hundred dollars to find what suits you best. Conclusion In conclusion, choosing the right video editing app involves considering your specific needs, device compatibility, and budget. Free options like DaVinci Resolve and Shotcut provide strong features, whereas iMovie simplifies editing for Mac users. For mobile users, CapCut and KineMaster offer trendy effects. If you’re ready to invest, Adobe Premiere Elements and Filmora are excellent choices. Assess your goals and preferences carefully to find the app that best suits your video editing expedition. Image via Google Gemini This article, "Best Video Editing Apps for Beginners" was first published on Small Business Trends View the full article
-
The latest study from LodeStar found the ratio of average closing cost to home sales price in several states, led by Delaware, well above the national average. View the full article
-
Ask any C-suite leader if AI is a priority in their organization. The answer is yes. The numbers back it up. Menlo Ventures reports that companies spent $37 billion in 2025 on AI. But spending does not guarantee success, and many companies are now coming out of major rollouts with little to show for it. Adoption is low, productivity hasn’t increased, and ROI is still an idea on a slide because organizations handed AI to their IT team like it was new software to install and called it a rollout. Deploying AI is a workforce strategy that demands behavior change and a new operating model. It’s not a technology rollout. It’s a workforce and culture transformation. STOP AUTOMATING BROKEN WAYS OF WORKING The most common mistake we see companies make is simple: they automate the old way of doing business instead of redesigning it. Organizations need to ask different questions. Rather than “How can we do this job faster with AI,” it’s “If we were building this from scratch today, what would humans do, what would AI do, and what should we not do at all?” Start by picking three to five high-impact workflows—not job titles or departments—and rebuild them from scratch. For example, take M&A due diligence. Document review and analysis that used to take weeks can now be done in days. That’s because the workflow itself was redesigned around what AI does best: synthesizing and surfacing insights at scale. ADOPTION NEEDS MORE THAN TRAINING Organizations have a responsibility to upskill their workforce, but upskilling from a central learning department can move slowly, and slow isn’t an option today. While centralized training is important, you also need to find and leverage your champions. Most organizations already have people leaning in—proactively learning, experimenting, and applying AI to their work. The fastest way to accelerate AI adoption isn’t training alone. The best thing you can do is activate your champion network. Connect them and give them agency, time, and tools so they can inspire others to do the same. At West Monroe, we brought together our evangelists, empowered them to test and learn, and charged them with bringing others along. Grassroots energy will get you farther, faster, than any corporate-wide training program. At the same time, leadership must be all in. If leadership isn’t using AI, no one else will believe it matters. Leaders should model the behavior and hold people accountable. A little fun, healthy, and friendly competition plays a role too. We have a corporate-wide leaderboard. We hold AI challenges, award prizes, and give out innovation bonuses to those who are actively learning, participating, and most importantly, innovating for outcomes. Making work fun helps. BUILD A CULTURE OF CONTINUOUS LEARNING It’s our responsibility not only to employ people, but also to keep their skills current so they remain employable whether at our company or elsewhere. There are three clear ways for organizations to do this: 1. Do the hard thing. Be honest about which roles will change and empower those people to learn new skills. Avoiding conversation creates more fear. 2. Real investment and development. For many people, AI proficiency will soon to be a prerequisite for employment. The best thing employers can do is to build a culture of curiosity, learning, innovation, and experimentation. The best thing employees can do is embrace continuous learning and adaptability. Invest in your people. 3. Make it safe to experiment—and fail. Highlight successes, as well as things that didn’t work and what you learned from it. Continual learning is key. CULTURE IS THE REAL AI STRATEGY The organizations that close the gap between AI investment and impact won’t be known for having the best tools; they’ll be known for having the strongest learning and innovation culture. AI is not a technology rollout. It’s a business and workforce transformation, and culture is the competitive advantage. Tanya Moore is the chief people officer at West Monroe. View the full article
-
First TACO, and now NACHO: The acronyms created for a snappy way to denigrate The President’s actions are starting to sound like a menu. By now, Americans might be used to the idea of TACO, or “The President always chickens out.” Financial Times columnist Robert Armstrong coined the term in May 2025 to describe how investors could anticipate market rebounds, even as The President announced (and took back) tariffs. The strategy was to buy into the market after a tariff announcement, with the expectation that The President would call it off soon after. Nearly two months into the war in Iran, some might be wondering if this is a TACO The President situation. The ongoing ceasefire hasn’t done much to alleviate disruptions to the Strait of Hormuz, a key shipping route for about 20% of the world’s oil shipments. The President has given Iran a series of ultimatums to reopen the strait, pushing back before the deadline each time. But with tensions and oil prices rising, the acronym floating around social media is now NACHO—not TACO. The new acronym stands for “Not a chance Hormuz opens,” Bloomberg columnist Javier Blas posted on X, crediting the trader who told him about the term. (On April 29, The President indicated that he was prepared to continue blockading Iranian ports for several months.) While backronyms have been increasingly popular in government lately—take a look at The President suggesting rebranding ICE to NICE—the White House has unsurprisingly not looked favorably on either the terms TACO or NACHO. In a media conference last year, The President called it “nasty” when a reporter asked him about TACO. And, as reported by USA Today, when asked about the new NACHO acronym, White House spokesperson Kush Desai responded, “Are these the same geniuses who thought President The President would never secure voluntary Most-Favored-Nations drug pricing deals or renegotiate broken trade deals?” View the full article
-
Comprehending basic accounting is essential for anyone looking to manage finances effectively. It helps you grasp key concepts like assets and liabilities, which are critical for evaluating a business’s financial health. By familiarizing yourself with fundamental accounting principles, you’ll be better prepared to navigate financial statements and make informed decisions. As you explore the double-entry system and its importance, you’ll find yourself equipped with the tools necessary for sound budgeting and strategic planning. What comes next might surprise you. Key Takeaways Accounting is the systematic recording and summarizing of financial transactions to assess a business’s financial health. Key principles include GAAP, accrual accounting, and the matching principle, ensuring consistent and accurate financial reporting. Financial statements, such as income statements and balance sheets, provide insights into a company’s performance and position. The double-entry accounting system ensures that every transaction affects at least two accounts, maintaining balance and accuracy. Regular financial reporting and analysis help businesses make informed decisions and comply with legal obligations. What Is Accounting? Accounting is the backbone of financial management in any business. So, what’s accounting? At its core, it’s the systematic process of recording, classifying, and summarizing financial transactions to provide useful information for decision-making. To define accounting, it involves evaluating a business’s financial health, ensuring compliance with legal regulations, and providing insights for management. The accounting definition in business includes key components like the preparation of financial statements; these documents—income statements, balance sheets, and statements of cash flows—reflect a company’s performance and position. Fundamental accounting principles, such as the revenue recognition principle and the matching principle, guide how transactions are recorded and reported. Furthermore, the double-entry accounting system is vital, as every transaction affects at least two accounts, helping maintain accurate financial records and ensuring the accounting equation (Assets = Liabilities + Equity) stays balanced. Grasping these basics is fundamental for anyone involved in business management. Basic Accounting Terms Now that you’ve comprehended the basics of accounting, it’s time to explore some fundamental accounting terms that will improve your insight. You’ll encounter key concepts like accounts payable and accounts receivable, which play a vital role in managing a business’s finances. Moreover, familiarizing yourself with important principles such as the accrual basis of accounting and the matching principle will provide you with a clearer picture of how financial transactions are recorded and reported. Essential Accounting Terminology Comprehending crucial accounting terminology is fundamental for anyone looking to navigate the domain of finance effectively. Familiarity with key accounting terms helps you understand the basics of accounting principles and the fundamentals of the accounting process. Here’s a brief overview of important terms: Term Definition Accounts Payable (AP) Money a business owes to suppliers for goods and services, a liability. Accounts Receivable (AR) Money owed to a business by customers, considered an asset. Accrual Basis Accounting Recognizes revenues and expenses when earned, regardless of cash flow. Revenue Recognition Principle Records revenue in the period it is earned, not when cash is received. Assets Resources owned by a business expected to provide future benefits. Understanding these accounting terms will improve your grasp of financial statements and business operations. Key Accounting Principles Grasping key accounting principles is essential for anyone aiming to comprehend the fundamentals of financial reporting. These accounting concepts form the backbone of basic accounting fundamentals. First, the GAAP (Generally Accepted Accounting Principles) guarantees standardized practices, encouraging consistency. The Matching Principle requires you to record expenses in the same period as the related revenues, guaranteeing accurate financial results. Similarly, the Revenue Recognition Principle states that you should recognize revenue when it’s earned, regardless of cash receipt timing. The Cost Principle mandates that you record assets at their purchase cost, providing a basis for valuation. Finally, the Full Disclosure Principle insists on including all relevant information in financial statements, promoting transparency and accountability—key of accounting in building trust with users. Fundamental Accounting Principles Grasping the fundamental accounting principles is essential for anyone looking to navigate the domain of finance and business effectively. These basic accounting concepts provide a framework for comprehension of the concept of accounting and the principles of accounting. For instance, the Revenue Recognition Principle dictates that you recognize revenue when it’s earned, not necessarily when cash is received. The Matching Principle guarantees expenses are recorded in the same period as the related revenues, giving you a clearer picture of profitability. The Full Disclosure Principle requires you to reveal all relevant financial information, promoting transparency. Meanwhile, the Historical Cost Principle states that assets should reflect their original purchase cost, maintaining stability in financial reporting. Finally, the Objectivity Principle emphasizes that your accounting data must be unbiased and verifiable, reinforcing reliability in the fundamentals of the accounting process. Grasping these principles is key to accurate financial management. The Financial Statements Financial statements serve as essential instruments for summarizing a company’s financial performance and position. They primarily include the income statement, balance sheet, and statement of cash flows. The income statement reports revenues earned and expenses incurred over a specific period, providing insight into the net income or loss of the business. It helps you comprehend how well the company is doing financially. Conversely, the balance sheet offers a snapshot of a company’s financial position at a specific point in time. It details assets, liabilities, and shareholders’ equity, following the accounting equation: Assets = Liabilities + Equity. Furthermore, the statement of cash flows outlines cash inflows and outflows from operating, investing, and financing activities, showing how cash is generated and used. Grasping these financial statements is vital for you, as they enable informed decision-making regarding the company’s financial health. Recording and Classifying Transactions Recording and classifying transactions is a fundamental aspect of accounting that helps businesses maintain accurate financial records. When you record transactions, you document the financial activities of your business through journal entries, capturing the date, accounts affected, amounts, and a brief description. Each transaction is then classified based on the type of account it impacts, such as assets, liabilities, or expenses. Using the double-entry accounting system, every transaction must be recorded in at least two accounts, ensuring the accounting equation (Assets = Liabilities + Equity) holds true and that debits equal credits. The chart of accounts plays an important role here, as it organizes all accounts used by your business, making it easier to track and classify transactions effectively. Regularly updating and reviewing these records is vital, as it supports generating reliable financial statements for informed business decision-making. Adjusting Entries Adjusting entries play a crucial role in ensuring that your financial statements accurately reflect your business’s financial position at the end of an accounting period. These entries help match revenues and expenses to the correct period, maintaining financial accuracy. Here’s a breakdown of key adjusting entries you should consider: Type Description Accrued Revenues Income earned but not yet received, impacting your income statement. Prepaid Expenses Payments made for future services, adjusted to reflect the amount used this period. Unearned Revenues Payments received in advance, requiring adjustments to recognize earned revenue later. Preparing Financial Statements When you’re ready to assess your business’s financial performance, preparing financial statements is vital. These statements, which include the income statement and balance sheet, help you understand your company’s financial health. The income statement summarizes your revenues and expenses over a specific period, revealing your net income or loss. This figure indicates your profitability and helps you make informed decisions. On the other hand, the balance sheet provides a snapshot of your assets, liabilities, and shareholders’ equity at a given moment. It illustrates your company’s financial position and stability. Furthermore, you may prepare a statement of cash flows, detailing cash inflows and outflows from various activities. To guarantee accuracy, follow accounting principles like the matching principle, which dictates that revenues and expenses must be recorded in the same reporting period. This disciplined approach allows stakeholders to assess your business effectively. Understanding the Double-Entry System Comprehending the double-entry system is essential for anyone looking to grasp basic accounting principles. This method requires that every transaction impacts at least two accounts, which helps maintain the balance of the accounting equation: Assets = Liabilities + Equity. Core Principles of Double-Entry The double-entry accounting system is vital for maintaining accurate financial records, as it requires you to record every transaction in at least two accounts. This method guarantees the accounting equation—Assets = Liabilities + Equity—remains balanced. Each financial transaction consists of a debit and a credit for equal amounts, which helps prevent errors and improves accuracy. By capturing the dual effects of transactions, double-entry accounting provides an all-encompassing view of your company’s financial health and facilitates the preparation of accurate financial statements. Furthermore, this system promotes accountability and transparency, making it easier for you to track financial transactions and identify discrepancies through the trial balance. Grasping these core principles is fundamental for effective accounting practices. Benefits for Financial Accuracy Building on the core principles of double-entry accounting, the benefits for financial accuracy become evident as you explore how this system operates. This method guarantees that every transaction affects at least two accounts, maintaining balance in the accounting equation (Assets = Liabilities + Equity). Benefit Description Error Prevention Total debits equal total credits, reducing mistakes. Accurate Records Reliable financial statements can be prepared easily. Performance Tracking Allows in-depth analysis of profitability over time. Understanding these accounting basics is essential, as the fundamentals of the accounting process hinge on this system. Implementing double-entry bookkeeping means you can trust your financial data, leading to informed decision-making. Importance of Accounting for Decision-Making Even though many individuals may disregard the importance of accounting, it plays a vital role in decision-making for businesses of all sizes. Grasping the significance of accounting for decision-making can lead to more informed choices. Here are a few key points to reflect on: Accounting provides a systematic framework for tracking financial performance. Regular financial reporting helps identify trends in revenues and expenses. Analyzing financial statements allows for evaluating profitability and overall health. Accurate accounting supports compliance with legal and tax obligations. These fundamentals of the accounting process are important for maneuvering the basics of accounting and finance. With the right data, you can make proactive adjustments to budgeting and strategy, appraise operational efficiency, and guide investment decisions effectively. Frequently Asked Questions How to Learn Accounting Step by Step for Beginners? To learn accounting step by step, start by familiarizing yourself with basic terminology, like assets and liabilities. Next, grasp the accounting equation: Assets = Liabilities + Owner’s Equity. Study the double-entry system, where every transaction impacts at least two accounts. Then, explore financial statements like the income statement and balance sheet. Finally, practice using accounting software to record transactions and generate reports, enhancing your comprehension of accounting principles effectively. What Are the 5 Basic Principles of Accounting? The five basic principles of accounting are the Revenue Recognition Principle, which states you recognize revenue when it’s earned; the Matching Principle, ensuring expenses align with related revenues; the Cost Principle, recording assets at their original purchase cost; the Full Disclosure Principle, requiring all relevant financial information for transparency; and the Objectivity Principle, emphasizing verifiable data to reduce bias. These principles guide accurate financial reporting and improve comprehension of a company’s financial health. How to Explain Accounting in Simple Terms? Accounting is simply the process of tracking a business’s financial activities. It involves recording, classifying, and summarizing transactions to understand financial health. You’ll deal with key terms like assets, liabilities, and equity, which represent what the business owns, owes, and the owner’s investment. The accounting equation—Assets = Liabilities + Equity—ensures balance. Financial statements like the income statement and balance sheet provide crucial insights into profitability and financial status at a specific time. Can I Self Teach Myself Accounting? Yes, you can self-teach accounting effectively. Utilize free online resources like courses and tutorials to comprehend fundamental concepts. Practice with accounting software, such as QuickBooks, to reinforce your skills in recording transactions and generating financial statements. Engaging with textbooks provides structured learning, whereas joining online forums allows you to ask questions and share insights. Regularly applying your knowledge through practical exercises, like creating mock financial statements, improves your grasp of accounting principles. Conclusion In summary, comprehension of basic accounting equips you with vital skills for managing financial transactions effectively. By grasping key concepts like the double-entry system and fundamental terms, you improve your ability to assess a business’s financial health. Familiarity with financial statements and the process of recording transactions is critical for informed decision-making. In the end, mastering these principles not just aids in compliance and strategic planning but likewise cultivates sound financial management practices that can benefit any individual or organization. Image via Google Gemini This article, "Understanding Basic Accounting for Beginners" was first published on Small Business Trends View the full article
-
The benchmark 10-year Treasury yield topped 4.4% on April 29 — its highest level since late March — as investor anxiety mounted. View the full article
-
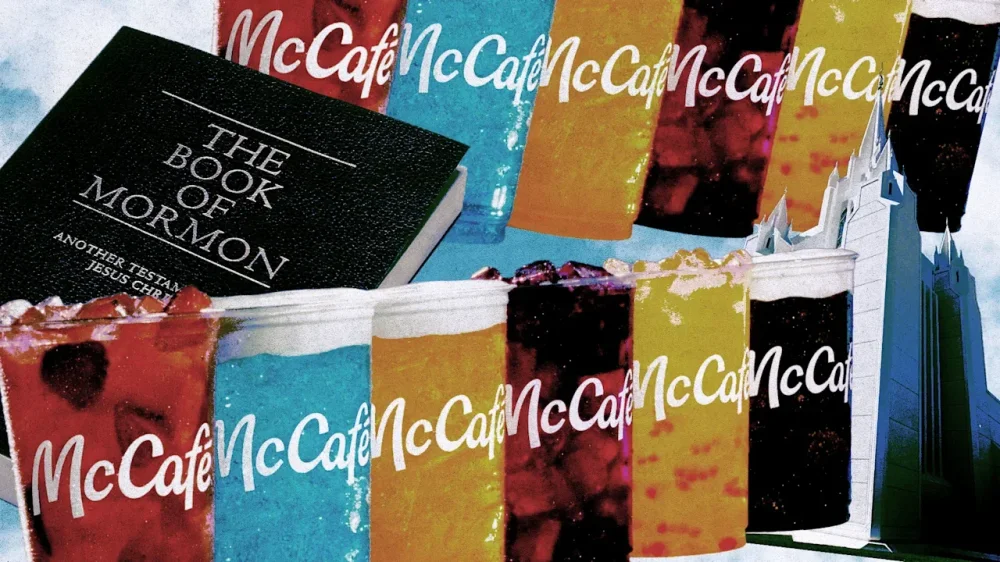
McDonald’s’ latest menu drop is making a Mormon treat mainstream. On Tuesday, April 28, McDonald’s officially announced six new beverages coming to its menu on May 6. That includes three “crafted sodas”—Sprite Berry Blast, Orange Dream, and Dirty Dr Pepper—which combine sodas with flavored syrups and cold foam. The drinks make McDonald’s the latest franchise to embrace the concept of “dirty soda,” or soda with mixed-in flavors and creams. But dirty soda is more than just a viral food trend: It’s a cultural mainstay of Mormon communities, which have embraced the concept since it first rose to prominence in Utah, where 42% of the adult population identifies as Mormon. What makes dirty soda Mormon? Dirty soda isn’t exclusive to Mormons, but they certainly put it on the map. Members of the Church of Jesus Christ of Latter-day Saints aren’t allowed to drink alcohol, tea, or coffee—but caffeine is still on the table, giving soda a massive Mormon market. The term “dirty soda” was trademarked by Utah-based soda shop franchise Swig in 2014, but many other brands have since adopted that language. The treat has had waves of mainstream recognition over the years, but its current degree of popularity can be traced back to another juggernaut of Mormonism in pop culture: The Secret Lives of Mormon Wives. Hulu’s reality show, which follows a group of Mormon influencers called MomTok, premiered in late 2024. The series’ first episode sees the titular Mormon moms patronizing a Swig location and ordering customized 44 oz. sodas, loaded with flavored syrups and creams. “Utah is like land of the Mormon bar, which is all the soda shops that we have,” says cast member Jessi Draper. “There’s one on every corner.” “We don’t drink alcohol or do drugs, and so it’s kind of our vice,” adds fellow MomTok member Demi Engemann. After The Secret Lives of Mormon Wives premiered, Swig experienced a massive boom in publicity. The brand’s CMO Dylan Roeder explained the dirty soda craze to PRWeek at the time, noting that “it’s not exclusive to anyone.” “Everyone wants a refreshing beverage,” Roeder said. “The concept of dirty soda is still foreign and intriguing, and The Secret Lives of Mormon Wives poured gasoline on that. People watch the show and think ‘I need to try this.’” ‘The American Century of Mormonism’ When news of the new McDonald’s beverages hit social media, the internet was quick to point out dirty soda’s Mormon origins. “It’s the American century of Mormonism,” one user declared after seeing McDonald’s’ new drinks. Another user pointed out rising purity culture among Gen Z and the popularity of tradwife content. “Guess it’s a Mormon decade,” they wrote. A third user cited a “Mormon cultural takeover of America,” noting that a new soda shop in their hometown had “a line of cars over a mile long” for weeks after opening. Some users pointed out that McDonald’s is far from the only brand hopping on the dirty soda trend. Dunkin’ Donuts also just announced its take on dirty soda, while fast food chains including Taco Bell and Sonic have also permanently added versions of the drink to their menus. Even movie theater chain AMC offers dirty sodas at select locations under its Cold-Crafted Drinks menu. “What happened in the soda industry that dirty soda is now a hot commodity,” wondered one social media user. “This is a new development.” Meanwhile, The Secret Lives of Mormon Wives’ other main export—its cast of controversial characters—is also dominating pop culture. MomTok ringleader Taylor Frankie Paul was set to be ABC’s next Bachelorette, before the network cancelled the already-filmed season due to a scandal in Paul’s past. Breakout star Whitney Leavitt became a fan favorite on Dancing With the Stars in 2025, before heading to Broadway for a limited run in Chicago. View the full article
-
A recent study by DocuSign in collaboration with Deloitte highlights a significant opportunity for small business owners looking to harness the power of artificial intelligence (AI). The report, titled “Capitalizing on AI: How Automated Agreement Workflows Drive ROI,” reveals that businesses utilizing AI-powered agreement management systems can achieve nearly a 30% higher return on investment (ROI) compared to those relying on traditional methods. This information comes at a critical time when more small business owners are seeking ways to streamline operations and enhance efficiency. The study surveyed over 1,100 senior leaders from various sectors across six countries, unveiling a substantial disparity in the benefits derived from AI adoption. Companies leveraging holistic, end-to-end agreement platforms reported far better outcomes than those using fragmented AI tools. Key findings suggest that companies embracing AI and automated workflows experience notable ROI improvements. Specifically, organizations report average efficiency gains of 36% through time savings and reduced cycle times. This is crucial for small business owners who often juggle multiple responsibilities and can benefit immensely from improved operational efficiency. Furthermore, businesses that implement AI-driven solutions also see a 36% reduction in costs due to better risk management and a 29% decrease in labor costs. Jonathan Jones, a managing director at Deloitte, states, “Value comes from moving the Intelligence & Insights phase to the front of the contract management process.” This perspective is particularly relevant for small business owners, who must make informed decisions quickly to stay competitive. By proactively analyzing agreements, small businesses can unlock new revenue streams and mitigate missed opportunities—a critical aspect in today’s fast-paced market. The implications extend beyond just financial benefits. The report identifies marked enhancements in agreement accuracy, with 72% of organizations noting reductions in clerical errors and improvements in regulatory compliance. As small business owners already face tight margins, minimizing errors can significantly enhance profitability. Small businesses often manage agreements using multiple tools, which leads to inefficiencies. Alarmingly, 65% of surveyed organizations reported using four or more tools for their agreements. This silos data and complicates processes, making seamless collaboration challenging. By integrating AI and aligning agreement management within a singular platform, businesses can foster better collaboration and streamline their workflows. Introducing AI into agreement management also transforms how various teams operate. Legal teams, for instance, reported reclaiming 37% of their time, enabling them to handle more contracts without proportionally increasing workload. Sales teams noted a 43% decrease in contracting-related delays and a potential revenue uplift of about $4.8 million annually from improved efficiency. These statistics underline the importance of adopting AI workflows that benefit multiple sectors within a small business. However, small business owners should also consider potential challenges that come with implementing AI-powered systems. Initial costs, employee training, and the transition from existing processes can create hurdles. Moreover, it’s essential to bear in mind that merely adopting technology isn’t sufficient for long-term success. The report underscores the importance of connecting agreement data across the entire lifecycle. Leaders who make agreement management a central focus of their overall strategy are likely to see the highest returns on investment. Investing in platforms like DocuSign’s Intelligent Agreement Management (IAM) can not only enhance productivity but also drive action based on data-driven insights. As small businesses continue to navigate a competitive landscape, optimizing agreement management through AI appears to be a promising path. Not only does it streamline workflows, but it also holds the potential for significant financial benefits. For those interested in delving deeper into the findings, the full report can be accessed at DocuSign’s website here. By integrating AI successfully, small business owners can position themselves for growth and capitalize on opportunities that may have previously gone unnoticed, setting a foundation for sustained success in the digital age. Image via Google Gemini This article, "AI-Driven Agreement Workflows Boost ROI by Nearly 30%, Says New Study" was first published on Small Business Trends View the full article
-
The technology firm posted annual gains in servicing, origination and closing solutions, although the segment at large posted an operating loss. View the full article
-
Strong earnings and AI spending plans help investors shrug off fallout from Middle East conflictView the full article
-
Want more housing market stories from Lance Lambert’s ResiClub in your inbox? Subscribe to the ResiClub newsletter. During the Pandemic Housing Boom, many publicly traded homebuilders achieved record profit margins as home prices soared and homebuyer demand ran red hot. Once the national housing demand boom fizzled out in the summer of 2022, many large homebuilders compressed their margins in order to do affordability adjustments where and when needed to maintain their sales pace. That includes giant homebuilder PulteGroup, which reported on Thursday that it compressed its Q1 2026 gross margin to 24.4%, compared with 27.5% in Q1 2025 and 24.7% in Q4 2025. While that’s still one of the stronger gross margins in the sector, it’s well below PulteGroup’s Q1 cycle high of a 29.6% gross margin in Q1 2023. The giant homebuilder—ranked No. 229 on the Fortune 500—used that compressed margin in order to deploy bigger sales incentives. In “normal” times, PulteGroup spends around 3.0% to 3.5% of the sales price on incentives. Since the Pandemic Housing Boom fizzled out, the builder has leaned into larger incentives, which have ticked well above its “normal” range. In Q2 2024, PulteGroup posted a sales incentives rate of 6.3%, which would amount to roughly $31,500 in incentives on a $500,000 home sale. In Q1 2025, PulteGroup posted a sales incentives rate of 8.0%, which would amount to roughly $40,000 in incentives on a $500,000 home sale. In Q1 2026, PulteGroup’s sales incentives rate rose to 10.9%, equating to about $54,500 in incentives on a $500,000 home sale. Without the larger incentives, PulteGroup insinuates that its decline in entry-level homebuyers would be even greater. “Our ability to offer low fixed rate mortgages [via forward commitments/buydowns] and other incentives is certainly helping solve the affordability riddle for some, but this comes at a price as incentives in the quarter reach 10.9% of gross sales price,” PulteGroup CEO Ryan Marshall said on the company’s April 23, 2026 earnings call. View the full article
-
Rush by businesses to purchase tech equipment offsets deceleration in consumer spendingView the full article
-
Maneuvering through commercial construction financing rates can be challenging, but comprehending the process is vital for securing the best terms for your project. Start by researching various lenders to compare their interest rates, which typically hover around 1% to 2% above standard mortgage rates. A solid business plan and a good credit score are fundamental for approval. In the following sections, we’ll break down the types of loans, key criteria for approval, and tips to strengthen your position with lenders. Key Takeaways Understand that commercial construction loan rates typically range from 1% to 2% above standard mortgage rates, impacting overall financing costs. Compare offers from multiple lenders to find competitive rates and favorable terms for your construction project. Be aware of variable interest rates, which can start lower but may increase over time, affecting your budget. Maintain a strong credit score of 700 or higher to qualify for better interest rates and loan terms. Engage in thorough planning, including a detailed business proposal, to strengthen your position when negotiating rates with lenders. Understanding Construction Loans Grasping construction loans is essential for anyone looking to finance a commercial building project. These short-term financing options typically last one year or less and are particularly designed to cover costs associated with building or renovating properties. Construction loan rates usually range from 1% to 2% above standard mortgage rates, reflecting the increased risk involved. You’ll likely need to provide a down payment of at least 20% to 25%, which is higher than what you’d find with conventional mortgages. Funds come in phases, or “draws,” tied to particular project milestones, so regular inspections are necessary before additional money is released. To qualify, you must submit detailed project plans, budgets, and specifications, demonstrating your preparedness and reducing perceived risks for lenders. Comprehending these factors will help you navigate the intricacies of construction loan interest rates and guarantee you’re well-equipped for your commercial project. Types of Commercial Construction Loans When exploring commercial construction loans, you’ll encounter several types, each customized to different project needs. Construction-to-permanent loans convert into a traditional mortgage once your project is complete, whereas stand-alone construction loans need refinancing afterward. Other options include renovation loans for upgrades, owner-builder loans for those acting as their own contractors, and specialized green construction loans that support eco-friendly initiatives. Loan Types Overview Several types of commercial construction loans are available, each designed to cater to different financing needs throughout the construction process. Comprehending these options can help you choose the right loan for your project. Here’s a quick overview: Construction-to-Permanent Loans: Combine construction financing and long-term mortgage, simplifying changes. Stand-Alone Construction Loans: Short-term loans for construction only, requiring a separate mortgage afterward. Renovation Construction Loans: Customized for purchasing and remodeling existing properties, suitable for both residential and commercial projects. Owner-Builder Construction Loans: Allow you to be your own contractor but involve higher risks and require project management expertise. Keep an eye on FHA construction loan APR rates today and builders loan rates to make informed decisions about commercial construction financing rates. Key Features Explained Comprehending the different types of commercial construction loans is vital for selecting the right financing option for your project. Construction-to-Permanent Loans combine the construction phase with a long-term mortgage, simplifying your shift to permanent financing. Conversely, Stand-Alone Construction Loans only cover the construction period, requiring a separate mortgage afterward, which adds complexity. If you’re looking to remodel, Renovation Construction Loans offer funds customized for existing properties. For those wanting to manage the project themselves, Owner-Builder Construction Loans allow this but come with higher risks. Finally, Green Construction Loans support eco-friendly projects and often feature favorable construction mortgage rates. Grasping these options helps you find the best construction loans suited for your needs. Key Criteria for Loan Approval Securing loan approval for commercial construction financing involves several key criteria that you need to understand. Focusing on these factors can help you navigate current building loan rates more effectively: Credit Score: Aim for a score of 700 or higher to secure favorable terms. Business Plan: Provide a thorough plan detailing construction specifics, timelines, and budgets. Down Payment: Be prepared to contribute 20% to 25% of the total project cost, as this mitigates lender risk. Loan-to-Value (LTV) Ratio: Keep your LTV ratio low, as lower ratios increase your chances of approval. Additional Considerations for Approval Though meeting the primary criteria for commercial construction loan approval is essential, several additional considerations can further improve your chances of securing financing. First, lenders typically require a minimum credit score of 680; higher scores can lead to better interest rates and terms. A well-documented business plan, complete with detailed construction plans, timelines, and budget, shows your preparedness and boosts project viability. Be ready to provide a down payment of at least 20% to 25% of the total project cost, which is higher than traditional mortgages, to reduce lender risk. Engaging a qualified builder with a proven track record can streamline the approval process and guarantee lenders of successful project execution. Finally, maintaining a healthy debt-to-income (DTI) ratio, ideally below 43%, is critical, as lenders assess this to confirm your ability to manage additional debt responsibly. Construction Timeline Once you’ve addressed the additional considerations for loan approval, comprehending the construction timeline becomes fundamental for successful project execution. Typically, commercial construction projects span 12 to 24 months, influenced by complexity and size. Key phases include: Pre-construction planning Actual construction Post-construction inspections Approvals Delays can occur because of weather, permitting issues, or labor shortages, so it’s critical to anticipate potential setbacks. Regular progress evaluations and adherence to a draw schedule guarantee that funding aligns with completed milestones. This not only helps maintain cash flow but likewise keeps the project on track. Effective project management and clear communication with your contractors are imperative in keeping the timeline intact and avoiding cost overruns. Builder’s Experience and Reputation Builder experience and reputation greatly influence the financing environment for commercial construction projects. Builders with extensive experience often develop established relationships with lenders, leading to more favorable financing rates and terms. A strong reputation improves a builder’s credibility, making lenders more inclined to offer lower interest rates, as they perceive reduced risk. When builders demonstrate a successful track record of completing projects on time and within budget, they’re likely to receive better financing options, including lower loan rates. Lenders typically evaluate a builder’s portfolio and past performance; well-regarded builders can qualify for discounts on interest rates or reduced fees. Furthermore, builders with solid reputations may gain access to exclusive loan products particularly customized to their expertise, further improving financing conditions. Consequently, investing in a builder’s experience and reputation can markedly impact your commercial construction financing outcomes. Interest Rates and Payment Structure When considering commercial construction financing, you’ll notice that variable interest rates can greatly impact your overall costs. During the construction phase, you’ll typically make interest-only payments, allowing you to manage your cash flow more effectively as you defer principal payments until the project is complete. Comprehending these payment structures and their implications can help you make more informed financial decisions throughout your construction process. Variable Interest Rate Impact During the process of maneuvering through the intricacies of commercial construction financing, it’s important to understand how variable interest rates can impact both your payment structure and overall project costs. These rates fluctuate based on market conditions, affecting your monthly payments throughout the loan term. Here are key points to reflect upon: Variable rates often start lower than fixed rates but can increase over time. Payments may change during the construction phase, impacting your budget. Lenders typically tie these rates to benchmarks like the prime rate or LIBOR. Unanticipated rate increases can create financial challenges, so effective cash flow management is essential. Being aware of these factors can help you navigate the intricacies of financing your commercial project more effectively. Interest-Only Payment Period How can comprehending the interest-only payment period of your commercial construction loan benefit your financial planning? During this phase, you’ll make payments solely on the interest accrued, easing your cash flow as the project is underway. Nevertheless, keep in mind that interest rates for these loans are often variable, which means they can fluctuate and may be higher than traditional mortgages because of the risks involved in construction projects. The interest-only period typically lasts until construction is finished, after which the loan converts to a standard mortgage with principal and interest payments. Although this arrangement lowers your immediate financial burden, it doesn’t reduce your principal balance, which must be repaid later. Be cautious of potential rate increases that could raise your overall costs. Loan Disbursement Process Grasping the loan disbursement process is vital for anyone involved in commercial construction. Construction loans are typically disbursed in phases, called “draws,” linked to specific project milestones. This guarantees funds flow as construction progresses. To keep everything on track, lenders conduct regular inspections to verify each phase’s completion before releasing the next draw. Here are key points to take into account during this process: The draw schedule should be detailed in the loan agreement. Plan for potential delays because of unforeseen circumstances, like weather or labor shortages. Effective cash flow management is critical to maintain project momentum. Delays in fund access can lead to increased costs and hinder progress. Risk Management Strategies After grasping the loan disbursement process, it’s important to focus on risk management strategies that can safeguard your commercial construction project. Establishing a contingency fund of 10% to 15% of total project costs helps mitigate unforeseen expenses. Conduct regular risk assessments to identify potential issues early, allowing for proactive management. Implementing robust project management practices, including detailed planning and scheduling, can greatly reduce delays and their financial impacts. Here’s a quick overview of effective risk management strategies: Strategy Benefit Contingency Fund Mitigates unforeseen expenses Regular Risk Assessments Enables timely issue identification Robust Project Management Reduces delays and associated costs Experienced Contractors Guarantees compliance and minimizes mistakes Legal and Regulatory Compliance Comprehension of legal and regulatory compliance is crucial for the success of your commercial construction project, as failing to adhere to local zoning laws and building codes can lead to significant setbacks. You need to understand that each municipality has unique requirements and obtaining the necessary permits is critical. Regular inspections by local authorities are often mandated, impacting your project’s timeline and financing. Furthermore, keep in mind the following: Compliance with safety and building standards is mandatory to avoid fines. Environmental regulations may apply, requiring clearances for projects affecting ecosystems. Non-compliance can jeopardize loan terms and result in financial losses. Consulting legal experts in construction law is imperative for maneuvering these intricacies. Staying informed and compliant will both help you avoid legal repercussions and guarantee your project runs smoothly and efficiently. Tips for Securing the Best Construction Loan When you’re looking to secure the best construction loan, comparing offers from various lenders is essential, as each can present different rates and terms that greatly impact your overall costs. Strengthening your project proposals with detailed plans and budgets not merely improves your credibility but likewise positions you for more favorable loan conditions. Compare Lender Offers Securing the best construction loan involves more than just comparing interest rates; it requires a thorough evaluation of various lender offers. To get the most favorable terms, keep these key factors in mind: Interest rates: Although important, don’t overlook other costs. Associated fees: Look for origination, appraisal, and inspection fees that can add up. Loan-to-Value (LTV) ratio: A lower LTV, ideally 80% or lower, can lead to better rates. Loan structure: Understand if the loan is interest-only during construction or shifts to a fixed-rate mortgage, as this impacts your monthly payments. Strengthen Project Proposals A strong project proposal is essential for securing the best construction loan, and taking specific steps can markedly improve your chances of approval. Start by preparing detailed project plans and specifications, including blueprints and cost estimates, to demonstrate thorough planning and reduce perceived risk to lenders. Highlight your project’s strengths, such as location, market demand, and potential return on investment, to make a compelling case for funding. Gather financial documents like tax returns and bank statements to showcase your income stability and creditworthiness. Maintain open communication with potential lenders to build rapport and trust, which can lead to better loan terms. Finally, consider involving experienced builders or contractors in your proposal to boost credibility and instill confidence in lenders. Building Strong Relationships With Lenders Building strong relationships with lenders is essential for anyone seeking commercial construction financing, as it can lead to more favorable loan terms and conditions. To cultivate these connections, focus on the following key practices: Establish rapport: Get to know your lenders personally, which can improve trust and comprehension. Communicate openly: Keep lines of communication clear to facilitate quick resolutions for any issues that arise during the loan process. Present a solid vision: Share a well-prepared project proposal that clearly outlines your goals and instills confidence in your project. Address concerns proactively: Discuss any potential risks upfront; this shows lenders you’re thorough and responsible. Frequently Asked Questions What Are the 5 Cs of Commercial Lending? The 5 Cs of commercial lending are crucial factors lenders assess when evaluating your creditworthiness. First, character reflects your reputation and credit history. Second, capacity measures your ability to repay the loan through financial analysis. Third, capital indicates your investment in the project, requiring a significant down payment. Fourth, collateral involves assets you pledge as security. Finally, conditions refer to the economic environment and terms of the loan, influencing the lender’s decision. What Are the 4 Cs of Commercial Lending? The 4 Cs of commercial lending are essential for lenders evaluating your creditworthiness. First, Character reflects your reputation and credit history. Next, Capacity assesses your ability to generate cash flow for loan repayment. Then there’s Capital, which represents your personal investment in the project, typically requiring a 20% to 25% down payment. Finally, Collateral is the asset you offer to secure the loan, providing lenders with reassurance against default. What Is a Typical Interest Rate on a Commercial Loan? A typical interest rate on a commercial loan ranges from 4% to 10% as of late 2023. These rates vary based on factors like your creditworthiness and current market conditions. Typically, construction loans carry higher rates than traditional mortgages, often 1% to 2% more. If you have a lower loan-to-value ratio, you might secure better rates. Stay informed about economic trends, as they can greatly impact these rates over time. How Does Commercial Construction Financing Work? Commercial construction financing provides short-term loans that fund construction projects in phases, called “draws,” tied to specific milestones. You’ll need to submit detailed project plans, budgets, and financial documentation, including proof of income and a solid credit score, to qualify. As construction progresses, lenders release funds after inspections confirm completion of each phase. Once the project is finished, you can either refinance into a permanent mortgage or use a construction-to-permanent loan. Conclusion In summary, successfully managing commercial construction financing rates requires thorough research, preparation, and strong relationships with lenders. By comprehending the types of loans available, key criteria for approval, and effective risk management strategies, you can position yourself for ideal financing terms. Always keep your project timeline in mind and remain compliant with legal requirements. With careful planning and a detailed business plan, you can secure the financing needed to bring your construction project to life. Image via Google Gemini This article, "Navigating Commercial Construction Financing Rates: A Step-by-Step Guide" was first published on Small Business Trends View the full article
-
In a previous piece, I argued that large language models are not enterprise architecture. The response was clear: that argument is hard to dismiss. The harder question is what comes next: “if not this, then what?” It’s the right question. Because the problem was never that AI doesn’t work. It clearly does. The problem is that we tried to place it in the wrong layer. We didn’t fail at AI. We failed at where we put it. Over the last two years, companies have invested tens of billions into generative AI. The result is not ambiguity. It’s clarity. A growing body of research, including a widely cited MIT study, shows that around 95% of enterprise generative AI initiatives fail to deliver measurable business impact, despite widespread adoption. This is not because the models don’t work: it’s because they were inserted into organizations as tools, not as systems. We tried to bolt intelligence onto workflows. What we need is systems where intelligence is the workflow. From stateless tools to persistent systems Large language models are, by design, stateless: each interaction starts from scratch unless we artificially reconstruct context. Companies are the opposite. They are stateful systems: they accumulate decisions, track relationships, evolve over time, and depend on continuity. This mismatch is not a minor inconvenience. It is structural. Research on enterprise AI failures consistently points to the same issue: systems fail not because they generate bad outputs, but because they cannot integrate into ongoing processes or maintain context over time. Enterprise AI cannot be session-based. It has to remember. From answers to outcomes We optimized AI to answer questions. But companies need systems that change outcomes. This is where the gap becomes obvious: an LLM can generate a compelling sales strategy, but it cannot track whether it worked, adapt based on results, coordinate execution across teams or improve over time. That’s not a limitation of implementation: it’s a limitation of design. The same MIT research describes a “GenAI Divide”: organizations are stuck in high adoption but low transformation, precisely because current systems don’t close the loop between action and outcome. Answers don’t change companies: systems do. From prompts to constraints Much of today’s AI conversation revolves around prompts. But prompts are just an interface. Companies don’t operate through prompts, they operate through constraints: compliance rules, permissions, risk thresholds and operational boundaries. And this is where most AI systems break. They generate within probabilities. Companies operate within constraints. This is one of the least discussed and most important reasons why enterprise AI initiatives stall. Even broader AI research shows that projects fail when systems are not aligned with real-world constraints, workflows, and decision contexts. Prompts are UX. Constraints are architecture. From copilots to systems of action The dominant metaphor of the last two years has been the “copilot.” It sounds appealing, but it’s also misleading. A copilot suggests. A company needs systems that act. This distinction matters, because suggesting is cheap. Executing is hard. Execution requires: integration with systems of record coordination across processes ownership of outcomes adaptation over time And this is precisely where most current approaches collapse. Not because they are poorly implemented, but because they were never designed for it. The architecture shift no one is talking about What, then, replaces this? Not better prompts, not bigger models, and definitely, not more infrastructure. The next phase of enterprise AI will be defined by something else entirely: Systems that combine persistent state embedded workflows continuous learning from outcomes operation under constraints integration with real environments In other words: systems that don’t just generate language about the world, but operate within it. Research and practice are converging on the same conclusion: success comes not from generic tools, but from systems that adapt, learn, and embed into workflows. Why this shift will feel like a discontinuity We are still early in this transition. Most organizations are investing in the visible layer: models, interfaces, infrastructure. But the real shift is happening one layer deeper. And when it becomes visible, it won’t look like an incremental improvement: it will look like a discontinuity. Because we are not moving from “worse AI” to “better AI.” We are moving from tools that talk to systems that act. The real opportunity This is not the end of enterprise AI: it is the end of a misconception. Language models are not enterprise architecture, they are an interface layer. A powerful one, but insufficient on its own. The companies that understand this first won’t simply deploy AI better. They will build something their competitors won’t recognize until it’s too late. View the full article
-
Earnings hint at growth trajectory despite increases in capital spendingView the full article
-
Welcome to AI Decoded, Fast Company’s weekly newsletter that breaks down the most important news in the world of AI. You can sign up to receive this newsletter every week via email here. Are the biggest AI labs betting on the wrong horse? Big AI companies are betting nearly all of their R&D and capital expenditure on the idea that pre-trained transformer models can deliver AI with human-level general intelligence. This approach relies heavily on backpropagation, the standard algorithm used to train deep neural networks. Ben Goertzel, who coined the term “AGI” with his 2005 book Artificial General Intelligence (co-written with DeepMind founder Shane Legg), is skeptical. “The commercial AI industry is just betting everything on copying GPT [generative pre-trained transformers] in various permutations, which in my view is a waste of resources because all these LLMs are kind of doing about the same thing.” “When something works, everyone wants to double and triple down on what worked,” he says. But this concentration of resources around a single paradigm may be risky. Transformer models require billions of dollars in compute to train, along with enormous ongoing computational resources to operate. So far, major AI labs have continued to see intelligence gains from adding more compute and training data. But as models grow larger, those gains are becoming increasingly expensive, raising the possibility that the returns may eventually no longer justify the cost. And because the financial stakes are so high, labs have little room to invest seriously in fundamentally different approaches. Goertzel argues that scale alone is not enough without the right underlying algorithms. In his view, a major limitation of transformer models is that they cannot continually learn from new experiences and update their internal parameters in real time the way humans do. Instead, they revert to their baseline parameters with each new interaction, without meaningfully learning from prior exchanges. Researchers at Google DeepMind, Microsoft, and Ilya Sutskever’s Safe Superintelligence are exploring alternative neural network architectures that may enable continual learning, Goertzel says. “DeepMind has incredible diversity within their AI team” and possesses a “deep bench” of experience with alternate AI paradigms, he says. The result is an AI landscape in which massive compute resources are largely devoted to refining existing methods rather than pursuing fundamentally different architectures that may be better suited to the kind of human-level generalization required for true AGI. Goertzel remains optimistic that AGI could emerge within the next few years, but he believes it will likely require moving beyond simply scaling current LLMs. Sakana’s new agents combine the intelligence of frontier AI models Last week, Tokyo-based startup Sakana AI announced the beta release of its flagship commercial product, Sakana Fugu. The launch follows a relatively quiet stretch for the company, which was founded in 2023 by Llion Jones, one of the nine inventors of transformer models, alongside former Google DeepMind researcher David Ha. Fugu is a multi-agent orchestration system designed to coordinate multiple frontier foundation models, including those from OpenAI, Google, and Anthropic, into a single collective intelligence engine. Within the system, these models function as agents working together on complex tasks spanning coding, mathematics, and scientific reasoning. AI systems that combine multiple models in a pipeline are nothing new, but assigning tasks to specific models or switching between them has often required manual oversight. Fugu is designed to orchestrate those models autonomously, establishing collaboration topologies and routing subtasks to the model best suited for a given problem. Another key feature is a looping mechanism that operates while the system works through a task. If it becomes stuck or fails to identify a promising path forward, it can recognize that impasse, launch corrective workflows, and iteratively work toward a stronger solution. By combining the strengths of diverse models, Sakana AI says Fugu outperforms comparable systems on industry benchmarks including SWE-Pro, which measures real-world software engineering performance, and GPQA-D, which evaluates graduate-level scientific reasoning. Peter Thiel is backing an AI startup that fact-checks journalists Influential VC Peter Thiel is backing a new startup called Objection AI, whose stated mission is to “restore confidence in the Fourth Estate.” At least, that’s how the company’s CEO framed it to TechCrunch. Objection AI is led by lawyer-turned-entrepreneur Aron D’Souza, who helped spearhead the Thiel-backed lawsuit that ultimately bankrupted Gawker Media. That legal crusade followed a 2007 Gawker article that outed Thiel as gay. While Thiel did not sue Gawker directly at the time, he secretly financed multiple lawsuits against the publisher. If someone believes the media has published damaging or false claims about them, they can pay Objection AI $2,000 to launch an AI-assisted investigation. The company says it deploys a team of AI models to analyze facts gathered by crowdsourced “investigators,” ultimately producing a judgment styled as an official certificate. The ruling carries no legal authority, but it can be widely circulated on social media as a reputational defense tool. D’Souza argues that media organizations can too easily damage reputations, particularly when reporting relies on anonymous sources and later proves inaccurate. (And there is indeed some logic to that critique.) Objection offers clients a mechanism to challenge coverage and initiate a public-facing review process, potentially providing a faster response than a prolonged libel lawsuit. But critics point out that Objection may do more to suppress truth than combat misinformation. By pressuring journalists to reveal sources or discouraging whistleblowers from coming forward, such a system could create a chilling effect on investigative reporting. The real product here probably isn’t objective fact-checking. It’s more likely a database of journalist credibility scores that can be weaponized to discredit reporters, support litigation, intimidate sources, or give powerful figures another avenue to challenge unfavorable reporting. “Your reporter has a 62% credibility rating” could become a potent talking point in a defamation case or PR offensive. Objection AI already lists a number of active investigations on its website, and there is little transparency around whether any could evolve into litigation, potentially backed by wealthy interests operating behind the scenes. On behalf of journalists everywhere, many thanks to Thiel and D’Souza for their tireless efforts to restore public trust in the press. Now do VCs and lawyers. More AI coverage from Fast Company: Celebrities like Taylor Swift are setting the guardrails for the AI age Why Manus has become a crucial prize in the global AI race The hidden logic behind AI CEOs’ job loss warnings PayPal says AI shopping agents are creating an invisible storefront economy Want exclusive reporting and trend analysis on technology, business innovation, future of work, and design? Sign up for Fast Company Premium. View the full article
-
Every year, the Beverage Testing Institute convenes a blind tasting panel to evaluate thousands of American whiskeys, judging each bottle anonymously to determine which truly stand above the rest. Without the influence of brand reputation or marketing hype, the process has become a respected benchmark in the spirits industry. This year’s highest-scoring bottles span the full breadth of American whiskey: classic Kentucky bourbons, bold ryes, high-altitude single malts, Tennessee whiskeys, and even a standout peach-infused spirit. Together, they highlight just how diverse—and competitive—the modern American whiskey landscape has become. BevTest’s top American whiskeys of 2025 include revived heritage labels, carefully aged single-barrel releases, high-proof bottles built for enthusiasts, and inventive flavored expressions that show how far the category has evolved. Whether you’re stocking a bar cart or searching for your next great pour, these four bottles—especially the best bourbon—stood out among the many that impressed the judges most this year, according to Forbes. Best Bourbon: Cream of Kentucky Small Batch Scoring 96 out of 100 and earning a platinum medal, this label was named the best bourbon whiskey of 2025. Cream of Kentucky revives a historic pre-Prohibition brand under the guidance of former Four Roses master distiller Jim Rutledge, who sources and blends select Kentucky bourbons to craft what he describes as a “double-rich” house style. The result is a whiskey that leans into classic Kentucky character. Honeyed orchard fruit and orange blossom lead the aroma, layered with caramel apple, vanilla, and subtle oak. Bottled at 100 proof, the BevTest panel praised the whiskey’s complexity, noting “aromas of caramel, chocolate, rice cookie, spiced poached apricots, and apples, along with flavors of spice cake with crème anglaise, praline with dried fruits, and a hint of white ash.” The judges concluded it is “a sumptuous, finely balanced bourbon with tremendous flavor and length—one that can handle anything you throw at it.” Despite its earning the top bourbon award, Cream of Kentucky retails for $69.99—sometimes as low as $60. Best American single malt: Stranahan’s 10 Year Old Mountain Angel, batch no. 4 Also scoring 96 out of 100 and earning a platinum medal, this label was named the best American single malt whiskey of 2025. Mountain Angel, Stranahan’s ultra-premium American single malt, is aged for a full decade in new charred American oak barrels stored at high altitude in Colorado, where the region’s dramatic temperature swings intensify the aging process. Judges described the nose as inviting and layered, blending warm cream, citrus zest, and caramelized sugar with hints of mountain pine, dried fruit, and spiced oak. On the palate, the whiskey is direct yet well-balanced, revealing silky malt sweetness alongside candied raspberry, orange peel, caramel, toasted barley, and honey. Notes of oak spice, dark chocolate, and a subtle warmth add depth without overpowering the spirit’s core fruit and malt character. The texture is thick, velvety, and mouth-coating, reflecting both the whiskey’s extended aging and the concentration produced by Colorado’s high-altitude climate. The BevTest panel noted aromas of butterscotch, cinnamon, poached pear, and maple, alongside flavors of white pepper, marzipan, and nutmeg, describing the whiskey as “warm, fruity, and nutty with a lightly spiced confectionery note—perfect for sipping by a fireplace.” Best cask-finished bourbon: Kentucky 10 Barrel Strength Hand Selected With a score of 92 out of 100, this Kentucky 10 Year Barrel-Strength Hand-Selected Straight Bourbon is a classic small-batch pick, bottled at full cask proof, usually chosen for its rich flavor and structure. It received a gold medal and was named the best cask-finished straight bourbon whiskey of 2025. On the nose, the whiskey is rich and aromatic, with bold notes of caramel, vanilla, dark brown sugar, and maple syrup layered with ripe stone fruit, apple, baking spices, and well-charred oak. On the palate, it is robust and sweet, revealing caramel corn, toffee, cinnamon, nutmeg, and clove before deepening into darker notes of cocoa, roasted peanuts, tobacco, and leather. With a smooth, oily texture, the whiskey coats the tongue with sweetness and oak tannin. The finish is long and warming with a hunt of barrel char, which makes it a wonderful whiskey for slow sipping or an old fashioned. The BevTest Judging Panel described the whiskey as having “aromas of buttery roasted nuts, chocolate cake with peach sauce, and saffron-spiced fruits. The flavors include chocolate crème brûlée with mint, cola nut, and marzipan. A charming, fruity, spicy bourbon with instant appeal and good versatility.” Best flavored whiskey: Hardhide Chilton County Peach Whiskey Receiving a gold medal and a score of 94 out of 100, Hardhide Chilton County Peach Whiskey was named the best flavored whiskey of 2025. The label is crafted using fresh peaches from Alabama’s Chilton County, which are blended with three-year-old wheat whiskey and light American whiskey at Sugarfield Distillery in Louisiana. From the first sip, the whiskey evokes freshly picked ripe peach, with aromas of honey, caramel, and stone fruit layered over subtle grain and oak, while the smooth palate carries natural peach alongside caramel, brown sugar, toffee, and gentle baking spices without drifting into liqueur-like sweetness. The texture is soft and slightly viscous, reflecting the fruit and sugars integrated into the spirit. The BevTest panel noted aromas of pear flesh, peach, and golden pineapple alongside flavors of nectarine, lychee tea, and butterscotch, describing it as “a bright, balanced, fruity peach whiskey that adds a touch of orchard fruit to cocktails.” —Leila Sheridan This article originally appeared on Fast Company’s sister website, Inc.com. Inc. is the voice of the American entrepreneur. We inspire, inform, and document the most fascinating people in business: the risk-takers, the innovators, and the ultra-driven go-getters that represent the most dynamic force in the American economy. View the full article
-
Information is a commodity. The real challenge is establishing trust in today’s world of content overload and automated answers. How can you tell who, among an array of self-proclaimed experts, really understands a topic? And more importantly, how can you instill that trust in others? It starts at the top. According to the 2026 Edelman Trust Barometer, 75% of respondents said CEOs are obligated to help bridge trust divides, but just 44% do so well. That’s a huge gap that highlights a leadership credibility challenge, playing out externally with customersand inside the workplace. 3 TRUST-BUILDING STRATEGIES These are three core principles I lean on to establish trust. 1. Transparency: Be honest and open to what you don’t know. Authenticity builds connection. Leaders who admit they don’t have all the answers and show vulnerability earn deeper trust. This openness creates a culture of accountability that resonates with both employees and customers. One thing we do at Scribd, Inc. is quarterly employee pulse surveys. As you might imagine, scores across various topics fluctuate. But we share all of them in company meetings, using it as an opportunity to discuss what’s going well and dig into how we can improve. This has led to higher engagement. Transparency means also sharing the bad as well as the good. If someone tells me everything is going great and is perfect, I’m not likely to trust them. There is always something we can do better. It’s the same when you communicate with the employees—share the misses as well as the wins. 2. Communication: Clarity and humanity over bulk. Always clearly articulate your intent, purpose, and vision. Don’t give your teams or your audience an opportunity to second-guess or fill in the blanks of what you don’t say. How you share is equally as important as what you share. We all sound better since we learned to bulk up our messages with AI. It’s personally been a great copyeditor for me, but I don’t want it to take my voice. The best technique I’ve found is reading messages aloud. It sounds simple, but it really helps me catch when I sound authentic or like a robot. The best ways to add weight to your messages are by using personal or firsthand examples that showcase your reasoning and citing your sources, elevating from machine-driven meh opinion towards fact-based messaging. 3. Teamwork Building a strong team is one of the most important leadership skills I’ve learned. When hiring, prioritize good judgment and cultural fit over purely technical skills; judgment is crucial in ambiguous environments like the one we live in. The most effective leaders succeed because of the team around them. I am [formerly!] a finance guy, so I look at things through a specific lens. If I didn’t have creative and technical people around me viewing things from a different perspective, the company might not be doing as well. To operationalize this, try developing an internal committee to ensure those closest to the facts inform your strategy. Teamwork extends outside the workplace. Customers are skeptical. The content you put out is a way to meet them. Reduce the noise and share things that genuinely provide help. Consumers increasingly look to real people, so instead of claiming you’re an expert, bring in actual experts. PIVOT FROM INFORMATION TO UNDERSTANDING Reliable, quality, human source content is increasingly becoming a scarce resource. Real value comes from helping people understand and make sense of that information. This is a challenge I deal with every day. Scribd, Inc. has an abundance of information, hundreds of millions of pieces of content, built over nearly two decades. Just downloading that content has been crucial to our business success in the past. But now, accessing content isn’t the issue; that’s easy. It’s making sense of it all. Like many companies, we’ve pivoted our approach. We’re finding new ways to provide trust and value, which led us to update our mission. Our new North Star is to advance human understanding. The future is not about who has the most information, but who has the credibility to translate the plethora of it into something actionable. The ultimate goal for every leader must be to protect and invest in the one thing AI cannot replicate: genuine human understanding. Tony Grimminck is the CEO of Scribd, Inc. View the full article
-
When considering franchise buy-in prices, it’s vital to understand the varying tiers of investment. Initial franchise fees can range widely, from as low as $10,000 to over $100,000, depending on the brand and model. Established franchises, like Taco Bell or KFC, typically require higher investments. Beyond the initial fees, ongoing expenses, royalty fees, and hidden costs can greatly impact your total investment. Knowing these factors is critical to making an informed decision. What other financial aspects should you consider? Key Takeaways Franchise buy-in prices typically range from under $1,000 for micro-franchises to over $100,000 for major brands like Taco Bell and KFC. Low-cost franchises usually have initial fees under $15,000, while established service franchises cost between $25,000 and $50,000. The average initial investment for franchises, excluding real estate, is approximately $250,000. Additional startup costs may include real estate, renovations, equipment, and hidden expenses like insurance. Ongoing royalty fees range from 1.5% to 10% of gross revenue, impacting overall financial commitment. Understanding Franchise Investment Tiers When you’re considering entering the domain of franchising, comprehending the various investment tiers is crucial, as it helps you identify opportunities that align with your financial capacity and business goals. Franchise buy-in prices can vary greatly, with low-cost franchises often starting under $15,000. Micro-franchises, which may cost less than $1,000, typically involve home-based or mobile businesses with minimal overhead. Service-based franchises range from $1,000 to $5,000, allowing for flexibility and low equipment needs. For mobile and home-based operations, costs typically fall between $5,000 and $25,000, capturing local market demand. Established service franchises, priced between $25,000 and $50,000, offer greater brand recognition and support, making them a compelling choice for aspiring franchisees. Key Factors Influencing Franchise Costs When you’re considering a franchise, it’s crucial to understand the initial investment requirements and ongoing royalty fees that come with it. The initial costs can vary widely based on location and brand recognition, impacting everything from franchise fees to real estate expenses. Furthermore, ongoing royalty fees, typically a percentage of your monthly gross revenue, add to the overall financial commitment of running a franchise. Initial Investment Requirements Initial investment requirements for franchises can vary considerably based on several key factors. If you’re looking to franchise a restaurant, you might find low-cost options starting under $10,000, whereas established brands could demand $250,000 or more. Typically, the franchise fee ranges from $20,000 to $50,000, but some can be as low as $10,000 or as high as $100,000. Don’t forget to factor in supplementary startup costs, which could include real estate, renovations, equipment, and inventory—these can add thousands to your initial investment. Moreover, hidden costs like insurance and technology fees can greatly affect your total financial commitment. Being aware of these factors is vital for making informed decisions when considering franchise opportunities. Ongoing Royalty Fees Ongoing royalty fees represent a fundamental aspect of franchise costs that can greatly affect your overall profitability. These fees typically range from 4% to 8% of your gross revenue, though some franchises charge as little as 1.5% or as much as 10%. It’s important to take into account the following variations: Dream Vacations charges a royalty fee of only 1.5% to 3% on annual commissionable sales. Complete Weddings + Events imposes an 8% royalty rate on annual gross revenue. Motto Mortgage offers a unique structure, charging $0 for the first six months, then $4,500 monthly thereafter. Understanding these fees is significant when evaluating the total cost of ownership and ongoing expenses for your franchise, as they can greatly impact your profitability. Typical Initial Franchise Fees Franchise fees represent a significant upfront investment for anyone looking to enter the domain of franchising. These initial fees can range from $10,000 to over $100,000, depending on the brand and its market position. Many low-cost franchises have initial fees under $15,000, making them accessible to aspiring entrepreneurs. Typically, franchise fees are a one-time payment granting you the right to operate under the franchisor’s brand and business model. Nevertheless, major franchises like Taco Bell and KFC require much higher initial investments, with liquid asset requirements exceeding $750,000 and $1.5 million, respectively. On average, the initial investment for franchises, excluding real estate costs, tends to fall around $250,000, highlighting the financial commitment involved in franchising. Ongoing Expenses and Royalty Fees When considering the financial terrain of franchising, it’s crucial to understand that costs extend far beyond the initial buy-in. Ongoing expenses can greatly impact your profitability. You’ll typically face royalty fees ranging from 4% to 8% of your gross revenue each month, along with marketing fees that add another 2% to 5%. Some franchises, like Motto Mortgage, offer unique structures, waiving royalty fees for the first six months, then charging a flat fee. Here are some key ongoing expenses to keep in mind: Royalty fees that support franchisor services and brand consistency Marketing fees for both local and national advertising efforts Additional costs like insurance and technology fees that aren’t immediately obvious Hidden Costs to Consider When considering the true cost of owning a franchise, you can’t overlook hidden expenses that may not be immediately obvious. Insurance and liability costs, along with technology and software fees, can considerably increase your annual budget, adding thousands of dollars to your operational expenses. It’s essential to factor these costs into your financial planning to guarantee you’re fully prepared for the financial commitment of running a franchise. Insurance and Liability Expenses Steering through the terrain of insurance and liability expenses is fundamental for any franchisee, as these costs can greatly affect your bottom line. You must anticipate various insurance requirements, which often add thousands to your annual expenses. Liability insurance can range from $500 to $3,000 per year, depending on your business type and location. Property insurance, important for protecting your franchise assets, typically costs between $1,000 and $2,500 annually. Workers’ compensation insurance is usually mandatory, averaging around $1,000 to $2,500 per employee per year. These hidden costs can greatly impact your franchise’s profitability and cash flow, so it’s critical to factor them into your overall budget to guarantee financial stability. Technology and Software Fees Insurance and liability expenses are just one part of the financial terrain you’ll navigate as a franchisee. Technology fees can considerably impact your budget, including costs for software subscriptions, point-of-sale systems, and website maintenance. These expenses can add thousands to your annual operating costs. Often, you may be required to invest in specific technology platforms mandated by the franchisor, and these prices can vary widely. Moreover, ongoing support and updates for your technology might incur extra fees that you’ll need to factor in. To avoid surprises, grasping these potential hidden costs is crucial for accurate financial planning. Always review the Franchise Disclosure Document (FDD) carefully, as it typically outlines any technology fees associated with your franchise. Evaluating Total Investment Requirements Evaluating total investment requirements for a franchise involves more than merely the initial buy-in price, as various factors contribute to the overall financial commitment. You’ll need to take into account not just the franchise fee but additional costs that will arise during your expedition. Franchise fees typically range from $10,000 to $100,000, depending on the brand. Expect ongoing operational costs, including marketing fees that can take up 2% to 5% of your gross revenue. Don’t forget expenses for real estate, renovations, and equipment, which can greatly impact your total investment. Understanding all these components guarantees you’re prepared for the financial obligations that come with opening and running a franchise, allowing for better long-term planning. Tips for Financial Preparedness Preparing financially for a franchise opportunity requires a thorough understanding of your resources and potential costs beyond the initial buy-in. Start by evaluating your current financial situation with a personal financial statement that lists your assets and debts. Research the specific franchise’s investment requirements, which can vary considerably. Apply the “3X rule” for budgeting; multiply your available investment by three to estimate total ownership costs, including working capital. Don’t overlook hidden costs like insurance and technology fees that can affect profitability. Finally, consult with a financial advisor or franchise financing firm to create a detailed financial plan, addressing both upfront and ongoing costs, ensuring you’re set for long-term success in your franchise venture. Frequently Asked Questions Why Does It Only Cost $10k to Own a Chick-Fil-A Franchise? It only costs $10,000 to own a Chick-fil-A franchise since the company covers most initial expenses, like real estate and equipment. This low buy-in allows you to focus on operations rather than substantial capital investment. Nevertheless, you need to share a significant portion of your profits with the franchisor, including a 15% royalty fee on sales. In spite of the initial costs, the average annual sales can exceed $4 million, offering a solid return on investment. What Is the 7 Day Rule for Franchise? The 7 Day Rule requires franchisors to provide you with a Franchise Disclosure Document (FDD) at least seven days before you sign any agreements or make payments. This document contains crucial information about the franchise, including fees, obligations, and financial performance. The rule aims to guarantee you have enough time to review and understand the franchise details, promoting transparency and informed decision-making during the reduction of the risk of impulsive purchases. What Are the 4 P’s of Franchising? The 4 P’s of franchising are vital for your franchise strategy. First, there’s Product, which involves what you offer and how it meets customer needs. Next, Price is about setting the right cost for your goods or services, impacting profitability. Place refers to where customers can access your offerings, whether in-store or online. Finally, Promotion includes your marketing efforts to build brand awareness and attract customers, fundamental for driving sales and growth in your franchise. How Much Does Chick-Fil-A Franchise Owner Make? As a Chick-Fil-A franchise owner, you can expect to earn an average annual income between $150,000 and $200,000. Your earnings depend on various factors, including your location and how effectively you manage your restaurant. Since Chick-Fil-A retains ownership of the property, you won’t build equity in the property itself, but the company provides extensive training and support to help you maximize profitability and succeed in the competitive fast-food market. Conclusion In summary, grasping the typical franchise buy-in prices is crucial for anyone considering this investment. You need to evaluate initial fees, ongoing expenses, and potential hidden costs to determine the total investment required. By carefully evaluating these factors and planning your finances, you can make informed decisions that align with your budget and goals. Thorough research and financial preparedness are fundamental steps in the successful maneuvering of the intricacies of franchise ownership and ensuring a profitable venture. Image via Google Gemini This article, "Typical Franchise Buy-In Prices" was first published on Small Business Trends View the full article
-
This week, the gaming community was abuzz with frustration, anger, and confusion over a supposed change in Sony's digital game policy. Reportedly, Sony was rolling out a new system, where digital games would need to connect to the internet once every 30 days in order to function as expected. When some players dug through a digital game's information page, they indeed found a timer, in the form of a "remaining time" deadline, stating how much time they had left before needing to connect to the internet again. If the player missed the deadline, they might lose access to the game, until they connect their PlayStation to the internet again. This is a pretty serious policy shift, and without confirmation from Sony, it sounded to me like a bit of internet speculation. After all, Sony once chided Microsoft for trying to implement the same policy back in 2013 (a policy Microsoft quickly ditched). But soon after, a PlayStation Support account confirmed the change to a customer, stating that the policy affected any digital games purchased after a March 2026 update, and that "The 30-day is a Valid Period and is not a sign of an account restriction or anything like that." Needless to say, gamers were pissed. Sony isn't making you connect to the internet once a monthThe good news, however, is this is not Sony's new policy—despite what one support staff member may have incorrectly asserted. After days of bubbling tensions over the issue, a Sony spokesperson finally made a public statement to GameSpot. It's true Sony is now requiring an internet check on digital games, but there's an important distinction: It only needs to happen once. Here's what the spokesperson said to GameSpot: “Players can continue to access and play their purchased games as usual. A one-time online check is required to confirm the game's license, after which no further check-ins are required." This is a huge difference in policy. Sony isn't threatening to block players who keep their PlayStations disconnected from the internet; rather, you need to confirm the license once, and you're free to play your games as you wish. If you're buying your games digitally, you're connected to the internet, which means this check likely happens at some point in that process anyway. Sony hasn't confirmed why this internet check is now necessary, but it's likely to do with piracy. It was possible to buy a game from the PS Store's website without downloading it to your console, copy the license file, then request a refund for the game. While Sony would remove the game from the customer's account, that user could take the license file to an illegal rip of the game, and, in effect, turn it into a "legit" title. Now, that license file won't activate until the game downloads to the console, and connects to Sony's servers. It's a good reminder to take internet rumors and discussions with a grain of salt, and to wait for official confirmation from a company when it comes to big policy shifts—even if a support page supposedly confirms the change first. PlayStation 5 (1TB) $624.99 at Walmart $499.99 Save 0.00 Shop Now Shop Now $624.99 at Walmart $499.99 Save 0.00 View the full article