Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
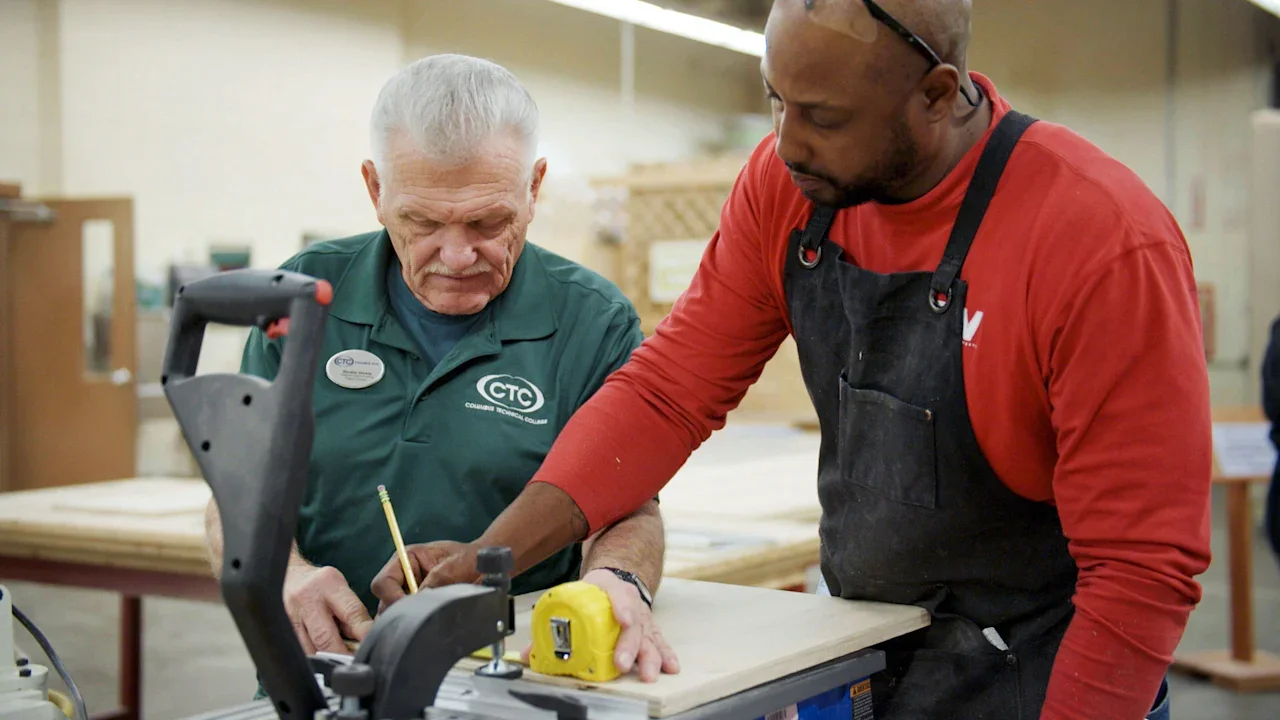
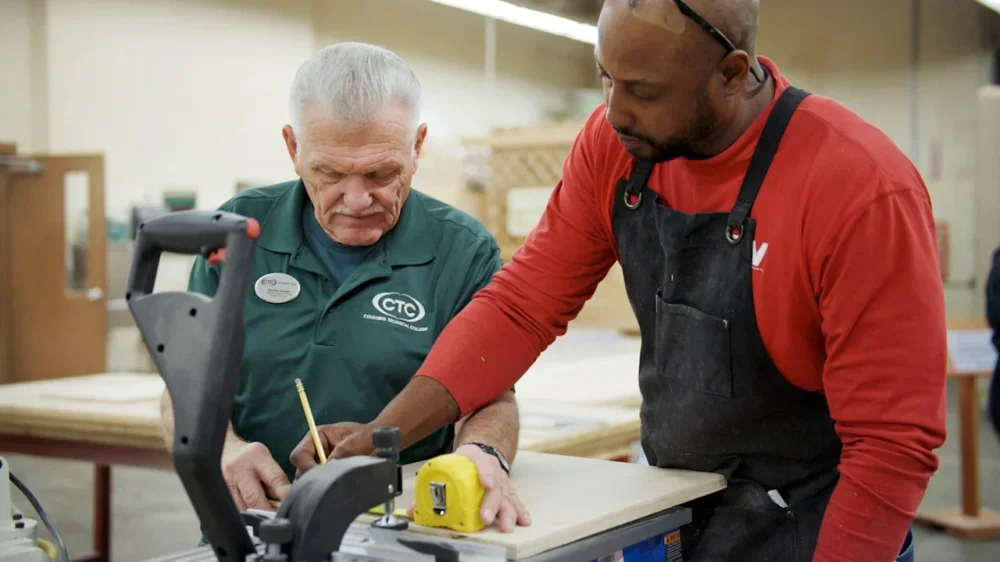
Lowe’s Foundation is making a major investment in future skilled tradesworkers. On Tuesday, the home improvement retailer announced it would commit an additional $200 million to training 250,000 tradespeople by 2035 through its Gable Grants program, bringing its overall commitment to $250 million. The investment comes amid a rising need for skilled tradespeople driven by a surge in AI developments. According to JLL’s 2026 Global Data Center Outlook report, the global data center sector is expanding by about 14% a year. Over the next four years, nearly 100 gigawatts of capacity will be added, which will require a $3 trillion investment. At the same time, we’re seeing a massive wave of retirements in the trades, which is set to continue. One recent report found that by 2030, around 1.4 million blue collar jobs will be open over seven fields. Already, construction companies overwhelmingly reporting that they’re struggling to find enough skilled workers to meet demand. According to a 2025 Associated Builders and Contractors (ABC) report, which analyzed Bureau of Labor Statistics data, the construction industry needs to bring an estimated 499,000 workers this year to meet demand. It’s not the first time Lowe’s has invested in the trades. In 2023, the brand announced a $50 million commitment over five years. At the time, it said it was focused on addressing “one of the most critical worker shortages” in history, explaining that around 546,000 new tradespeople were needed to meet demand that year. Now, the brand is building on the program. “American prosperity is at stake, and we are partnering to solve the workforce gap with a gro,” Marvin Ellison, Lowe’s chairman and CEO and co-champion of the Business Roundtable “Skilled Trades for America” initiative, said in the announcement. Ellison continued, “No single organization can do this alone.” Lowe’s said it would aim to reach 250,000 people over the next decade by expanding partnerships with community colleges and nonprofits and by working with organizations that connect students with employers. Lowe’s is not the only company to invest in training blue collar workers. Earlier this month, Blackrock, the world’s largest asset manager, said it would commit $100 million in training tradesworkers to support a growing infrastructure demand. At the time, Larry Fink, Chairman and CEO of BlackRock, said, “ America needs an estimated $10 trillion in infrastructure investment by 2033 to modernize aging systems and build new energy, digital, and AI infrastructure.” Fink added, “Capital alone is not enough – people are central to building our nation’s future.” View the full article
-
National Wealth Fund gave Gigaclear £240mn guarantee three years ago and is now the biggest shareholder View the full article
-
A new Basel III proposal offers mixed results for warehouse lending, with some risk-weight relief for banks but tougher terms that could crimp credit availability for nonbank mortgage lenders. View the full article
-
If you’re considering securing a commercial loan for rental property, it’s essential to comprehend the various steps involved. First, you need to assess the property’s income potential and prepare a solid business plan that outlines your investment strategy. You’ll additionally want to guarantee your financial profile meets lender requirements, including maintaining a sufficient Debt Service Coverage Ratio. Grasping these elements is just the beginning, as the loan process can be complex and requires careful navigation. Key Takeaways Prepare a solid business plan detailing your investment strategy and projected rental income for the property. Ensure your Debt Service Coverage Ratio (DSCR) is at least 1.25 to demonstrate adequate income for debt payments. Maintain a strong financial profile, including two years of tax returns and proof of reserves for 2 to 6 months of payments. Be ready for a down payment of 20% to 30% of the property’s purchase price, as this is standard for commercial loans. Shop around and compare various lenders for the best interest rates, terms, and fees tailored to commercial real estate financing. Understanding Commercial Real Estate Loans When considering a commercial real estate loan, it’s essential to understand the unique characteristics that set it apart from residential mortgages. Commercial real estate loans are designed to finance income-producing properties like office buildings and warehouses, requiring larger down payments, typically between 20% and 30%. Unlike residential loans, their terms are shorter, often ranging from 5 to 20 years, which may lead to balloon payments at the end. The underwriting process for these loans focuses on the property’s income-generating potential rather than your credit score. This means lenders assess the financial health of the investment and your business plan. Furthermore, interest rates tend to be higher because of perceived risks, and upfront costs can include appraisal and legal fees. Various loan types, such as conventional, SBA, hard money, and bridge loans, cater to different investment strategies and financial situations, providing options to suit your needs. Qualifying for a Commercial Loan When you’re looking to qualify for a commercial loan, lenders will assess your financial health and the income potential of the property. You’ll need to present a solid business plan that outlines your investment strategy and expected earnings, as this plays a vital role in the evaluation process. Comprehending these requirements can help you prepare effectively and improve your chances of securing the financing you need. Financial Health Assessment A thorough financial health assessment is essential for qualifying for a commercial loan, as lenders focus on the property’s income-generating potential rather than individual credit scores. To improve your chances of approval, maintain a strong financial profile, including a solid business plan and proof of reserves, which should cover two to six months of mortgage payments. Typically, the down payment required for investment property ranges from 20-30% of the property’s value. In addition, lenders look for a Debt Service Coverage Ratio (DSCR) of at least 1.25, ensuring you can meet debt obligations. Prepare to provide documentation like two years of tax returns, financial statements, and property appraisals to support your financial situation during the qualification process. Property Income Potential Comprehending the property’s income potential is a key factor in qualifying for a commercial loan. Lenders focus primarily on projected rental income and cash flow, rather than your credit score. They often require a Debt Service Coverage Ratio (DSCR) of at least 1.25, meaning your net operating income should exceed 1.25 times your debt payments. Historical performance and current occupancy rates are likewise evaluated to guarantee consistent income generation. Furthermore, if you’re financing through an LLC or partnership, demonstrating strong financial health can improve your approval chances. A well-prepared business plan outlining the property’s location, market analysis, and projected income can greatly enhance your prospects. Criteria Details DSCR Requirement At least 1.25 Focus for Lenders Projected rental income Historical Performance Evaluate past income consistency Occupancy Rates Assess current tenant occupancy Entity Type LLC or partnership recommended Business Plan Requirements Developing a solid business plan is essential for qualifying for a commercial loan, as it serves as a roadmap that outlines the specifics of your investment. Your business plan requirements should include the property’s location, market analysis, and projected income to demonstrate its viability. Lenders expect detailed financial projections that show anticipated cash flow and expenses over the loan term, helping them assess the property’s income-generating potential. Furthermore, provide a thorough description of the property and its intended use, along with a strategy for acquisition and management. Highlight your experience in real estate or related fields, as this can positively influence loan approval chances. Finally, evidence of past successful investments can further strengthen your business plan, showcasing your capacity to manage the property effectively. Interest Rate and Fees When you’re considering a commercial loan for rental property, you’ll notice that interest rates are typically higher than those for residential loans, often ranging from 3% to 12%. Don’t forget about upfront fees, which can include appraisal, legal, and loan origination costs that add thousands to your total expenses. Market conditions and your financial profile play significant roles in determining both interest rates and fees, so it’s crucial to shop around and compare different lenders’ offers to find the best deal. Higher Interest Rates Comprehending the financial implications of obtaining a commercial loan for rental property is vital, especially since these loans typically come with higher interest rates than residential loans. When you’re investing in property, be prepared for interest rates that can range from 3% to 12%. These rates reflect the increased risk lenders associate with financing an investment property that generates income. Your financial profile and the property’s income potential greatly influence the rates you’ll receive. Moreover, shorter loan terms—often between 5 to 20 years—can lead to balloon payments if not structured properly. In the end, higher interest rates combined with the potential for substantial costs mean you should carefully evaluate your options before committing to a commercial loan. Upfront Fees Explained Comprehending the upfront fees associated with a commercial loan for rental property is essential to your investment strategy. When you pursue financing, expect to incur appraisal fees, legal fees, and loan origination fees, which can greatly increase your overall expenses. Interest rates typically range from 4% to 12%, reflecting the higher risk of commercial properties. Moreover, you’ll need to prepare for a larger down payment on investment property, usually around 20-30%, which directly impacts your initial investment. Be aware that lenders may likewise charge underwriting and processing fees, adding thousands to your costs. Since overall loan expenses can vary widely based on lender and borrower profiles, it’s important to shop around for the best offers. Market Condition Impact Grasping how market conditions affect commercial loans is essential for any rental property investor. Interest rates for investment lending can range from 3% to 12%, depending on perceived risks and current economic stability. These rates are directly influenced by trends set by the Federal Reserve. Furthermore, fees associated with commercial loans, such as appraisal, legal, and origination fees, typically add 1% to 3% to the loan value. Market conditions likewise impact the loan-to-value (LTV) ratio, often capped at 65% to 80%, which can limit your financing options. Be prepared for fluctuating rates and potential balloon payments at the end of your loan term, especially in a tightening credit environment. Comprehending these factors helps you make informed decisions. Down Payment Requirements When considering a commercial loan for rental property, you’ll commonly need to prepare a down payment ranging from 20% to 30% of the property’s purchase price. These down payment requirements for commercial loans reflect the higher risk associated with investment properties. Unlike residential mortgages, you typically won’t find down payment assistance programs for these loans, so having substantial upfront capital is essential. The exact percentage may vary based on the property type, lender policies, and your financial profile. For instance, SBA loans may allow for lower down payments. A strong financial profile can additionally help you negotiate better terms. Factor Impact on Down Payment Property Type Varies from 20% to 30% Lender Policies Different requirements apply Borrower’s Financial Profile May allow for negotiation SBA Loan Availability Potentially lower down payment Types of Commercial Real Estate Loans for Rental Properties Grasping the various types of commercial real estate loans for rental properties is crucial for making informed investment decisions. You have several options to evaluate. Conventional loans require strong credit and typically a 20% down payment, making them suitable for traditional rental properties like single-family homes. If you need quick financing, commercial bridge loans can help with immediate needs, though they usually come with higher interest rates. Conduit loans are another option, ideal for stabilizing income-generating properties, as they offer favorable terms for those with existing cash flow. Finally, hard money loans provide asset-based financing and typically have lower credit requirements, even if they carry higher interest rates. Each type of commercial real estate loan for rental property serves different investment strategies, with terms varying based on the property’s income potential and your financial profile. Comprehending these options can guide you in selecting the right loan for your needs. Assess Your Financial Situation Comprehending your financial situation is a vital step before applying for a commercial loan for rental property. Start by evaluating your credit score; lenders typically require a minimum score between 660 and 680 for approval. Next, review your financial history, including two years of tax returns, to show consistent income and stability. Don’t forget to assess your current debt load, as lenders will check your debt-to-income ratio to gauge your ability to handle new debt. It’s important to verify you have adequate reserves, usually two to six months’ worth of mortgage payments, to demonstrate financial stability. Finally, calculate your net worth by listing your assets and liabilities, providing a thorough view of your financial health. This detailed assessment won’t just help you understand your position but will additionally prepare you for discussions about real estate investment loans with potential lenders. Develop a Solid Business Plan A well-crafted business plan is vital for securing a commercial loan for rental property. Start by conducting a detailed market analysis that identifies your target demographic, local rental trends, and competition. This will demonstrate potential demand for the property, making it more appealing to lenders. Next, include financial projections, such as anticipated rental income, operating expenses, and cash flow analysis, to showcase the property’s income-generating potential. Highlight your strategy for property management, maintenance, and tenant acquisition, emphasizing your thorough approach to maximizing profitability. It’s also important to outline your funding strategy, detailing how much investment home financing you seek, the intended use of funds, and plans to cover cash flow shortfalls. Finally, present a well-defined exit strategy that illustrates your grasp of market dynamics, whether through a long-term hold or potential sale, providing lenders confidence in the investment’s viability. Choose the Right Lender When you’re looking to secure a commercial loan for your rental property, choosing the right lender can make all the difference in your financing experience. Start by researching various lending institutions, such as banks, credit unions, and online lenders, since they may offer different terms and rates for loans for rental property. Evaluate the lender’s specialization in commercial real estate loans, as those with experience can provide better insights and customized terms. Be sure to compare interest rates, fees, and loan structures to find the most favorable option. Consider the lender’s reputation and customer service, as effective communication and support can ease the application process. Moreover, look for lenders that offer pre-approval options to expedite financing and strengthen your position when making offers. Research various lending institutions Evaluate lender specialization Compare interest rates and fees Consider lender reputation and service Submit Your Loan Application Submitting your loan application is a critical step in securing financing for your rental property. To improve your chances of approval for investment house loans, make sure your documents are complete and accurate. This includes providing detailed financial statements, tax returns, and property information to strengthen your request. Most lenders will ask for an extensive business plan that outlines the property’s income potential, market analysis, and your investment strategy, which helps them assess the loan’s viability. Be prepared to make a down payment of 20-30%, as this shows your commitment and minimizes the lender’s risk. Moreover, anticipate upfront costs like appraisal, legal, and loan origination fees, which can increase your overall expenses. Frequently Asked Questions Can You Take Out a Business Loan for a Rental Property? Yes, you can take out a business loan for a rental property. These loans, often classified as commercial real estate loans, focus on the property’s income potential rather than your personal credit score. You’ll typically need a down payment of 20-30% and may face shorter repayment terms of 5 to 20 years. Lenders require a thorough business plan and various financial documents to assess the property’s cash flow and overall viability. How Much Deposit Do I Need for a Commercial Loan? For a commercial loan, you typically need a down payment of 20-30%. Most lenders require at least 25%, but the exact amount can vary based on the property type and your financial profile. A larger down payment can improve your loan terms and bolster your approval chances, as it signifies a stronger financial commitment. Furthermore, lenders often ask for proof of reserves to cover two to six months of payments, ensuring you can manage the loan. What Type of Loan Is Best for Commercial Property? When considering the best type of loan for commercial property, evaluate your investment goals. Conventional loans offer long-term stability with low rates but require a significant down payment. SBA loans are great for owner-occupied spaces, whereas hard money loans provide quick cash for short-term needs, albeit at higher rates. If you own multiple properties, blanket loans can simplify management. Choose the loan that aligns with your financial situation and property plans. How Much Do You Need to Put Down on a Commercial Property Loan? When considering a commercial property loan, you typically need to put down at least 20-30% of the purchase price. This amount varies depending on the lender and your financial profile. Strong borrowers might secure loans with as little as 10% down, especially with SBA loans for owner-occupied properties. Moreover, be aware of potential extra costs like appraisal and legal fees that can impact your total initial investment. Conclusion Securing a commercial loan for rental property involves careful planning and thorough preparation. By comprehending the loan types, evaluating your financial situation, and developing a solid business plan, you can improve your chances of approval. Remember to maintain a strong financial profile and shop around for the best lender options. With the right approach and necessary documentation, you’ll be well-equipped to navigate the lending process and achieve your investment goals. Image via Google Gemini This article, "How to Get a Commercial Loan for Rental Property" was first published on Small Business Trends View the full article
-
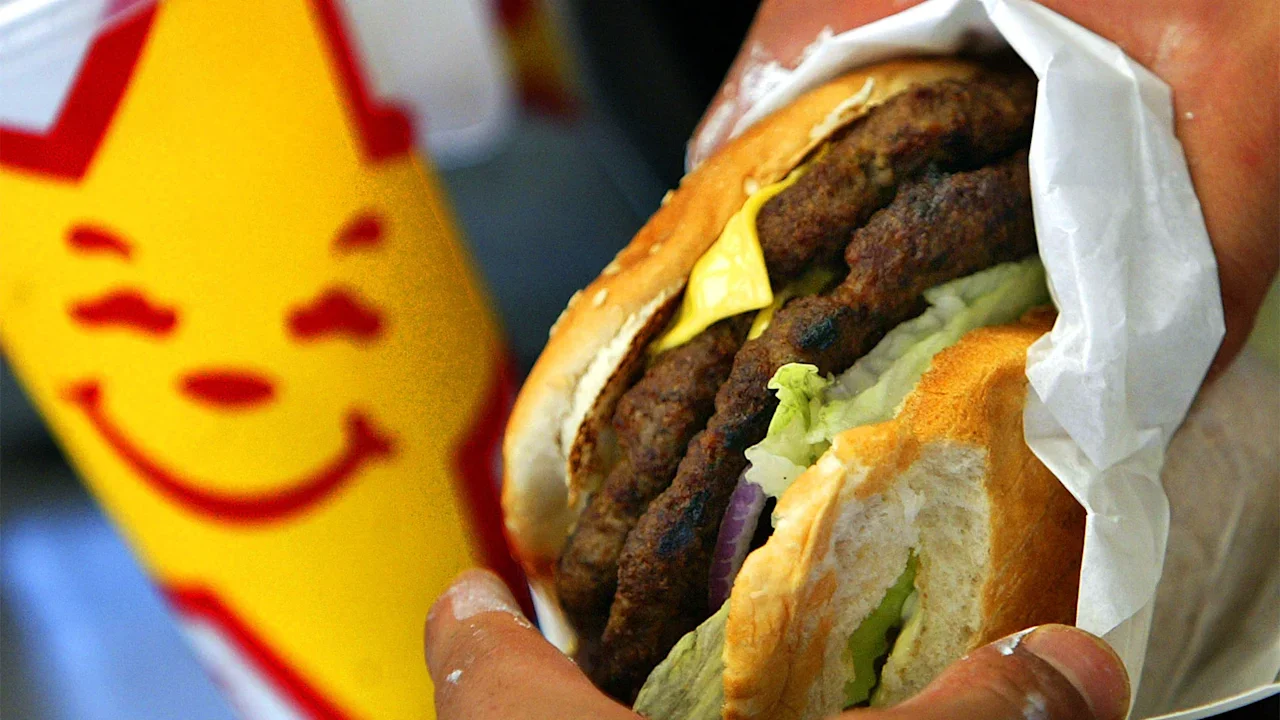
It’s a tough time to own fast-food restaurants. Franchisees for popular chains such as Applebee’s, Subway, and Popeyes Louisiana Kitchen have filed for bankruptcy recently, and another has joined them. Multiple entities associated with Friendly Franchisees Corporation (FFC), owner of 65 Carl’s Jr. locations across California, have filed for Chapter 11 bankruptcy, Restaurant Business first reported. Carl’s Jr. was founded almost 85 years ago and is known for its charbroiled burgers. FFC has yet to state whether any Carl’s Jr. locations will close as a result of the bankruptcies. Its founder, Harshad Dharod, owns the five associated entities that filed for bankruptcy in U.S. District Court for the Central District of California, including Sun Gir, DFG Restaurants, and Second Star Holdings. Fast Company has reached out to FFC and Harshad Dharod for comment and will update this post if we hear back. In each case, the entities have assets and liabilities worth less than $50,000. Will Carl’s Jr. locations close? While franchises aren’t owned by the brand, related bankruptcies could reflect poorly on the chain. Carl’s Jr. seems intent on placing the blame elsewhere. “We are aware that Carl’s Jr. franchisee Harshad Dharod entities and its affiliates, which together independently own and operate certain Carl’s Jr. restaurants in California, have entered into a court-supervised restructuring process under Chapter 11 of the United States bankruptcy code,” a company representative told Fast Company. “This situation is specific to this individual’s financial and business circumstances.” The statement from Carl’s Jr. continued: “This has no impact on the operations of any other Carl’s Jr. locations and we remain committed to delivering quality experiences for our guests, while driving profitable, sustainable growth for our franchisees and the brand.” Carl’s Jr. is owned by Tennessee-based CKE Restaurants Holdings, which also owns Hardee’s. View the full article
-
Millions of Android users are now eligible to claim some cash from Google as part of a $135 million settlement. If you have a qualifying device, you could receive up to $100 once the final approval hearing is completed in June. What is this Android settlement about? This settlement is part of a class-action lawsuit filed earlier this year alleging that Google collected unnecessary data from Android users over cellular networks in the background and without permission—even when Google apps were closed and location sharing disabled. Google denied any wrongdoing but agreed to a $135 million payout along with a commitment to implement additional disclosures shown during Android device setup. Who is eligible for a payment? The settlement provides benefits for anyone in the U.S. with a mobile device running Android OS through a cellular network between Nov. 12, 2017 and the final settlement approval date sometime this year. Note that this does exclude wifi-only devices. Residents of California who are part of the Csupo v. Google LLC also are ineligible for payouts are part of this suit. The exact per-user payment has yet to be determined, as it depends on how many people are eligible for the settlement. Payouts are capped at $100, though the total could be significantly less if the estimated 100 million class members receive equal amounts. How to claim your Android settlement paymentIf you are eligible for payment from this settlement, you should receive a personalized notice by mail or email. The email subject line is "Class Action Notice of Settlement —Taylor v. Google LLC." We've found it in spam, so check that folder if you believe you qualify and haven't received notice. Then, go to the settlement website and enter your notice ID and confirmation code to select a preferred payment method. If you don't go through this process, the settlement administrator will still try to send your funds automatically—however, there's a risk you may not receive them. Since payments will be issued regardless, the only deadline, May 29, is to object or exclude yourself from the settlement class. The final approval hearing is scheduled for June 23. For questions about the settlement or payouts, contact info@federalcellularclassaction.com. View the full article
-
Muse Spark ‘purpose-built’ for social media apps as investors question huge AI investment View the full article
-
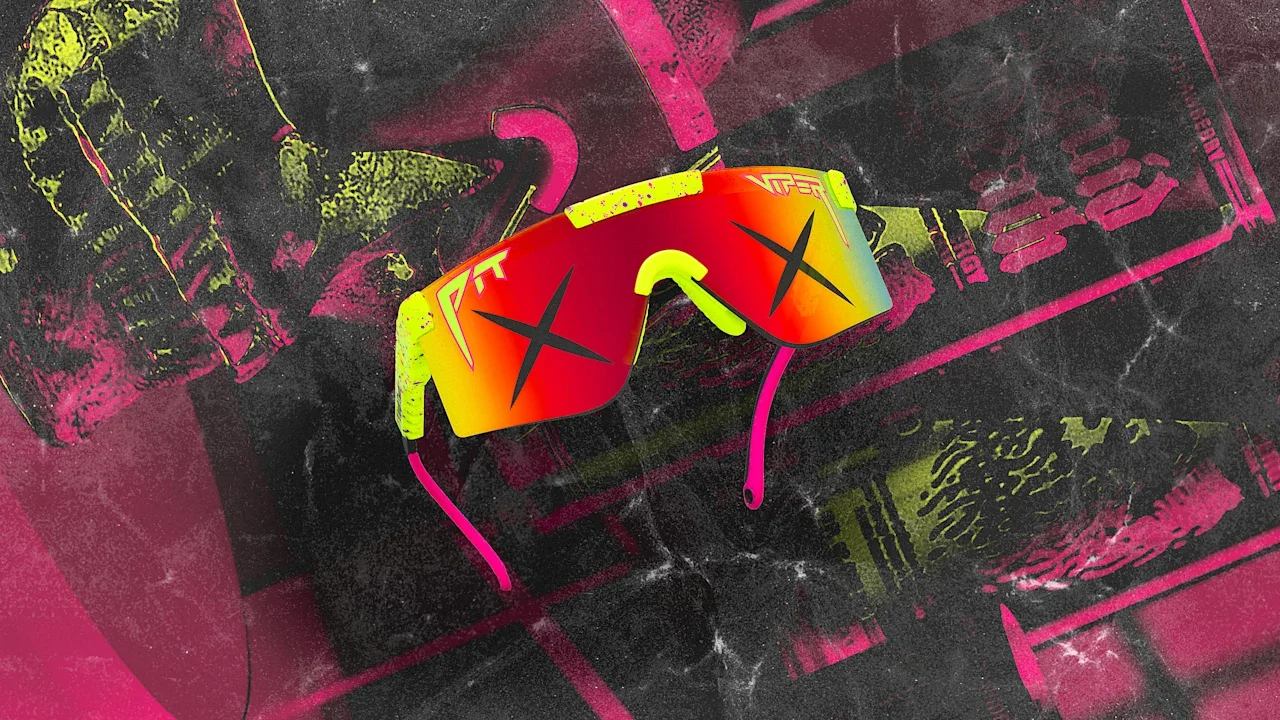
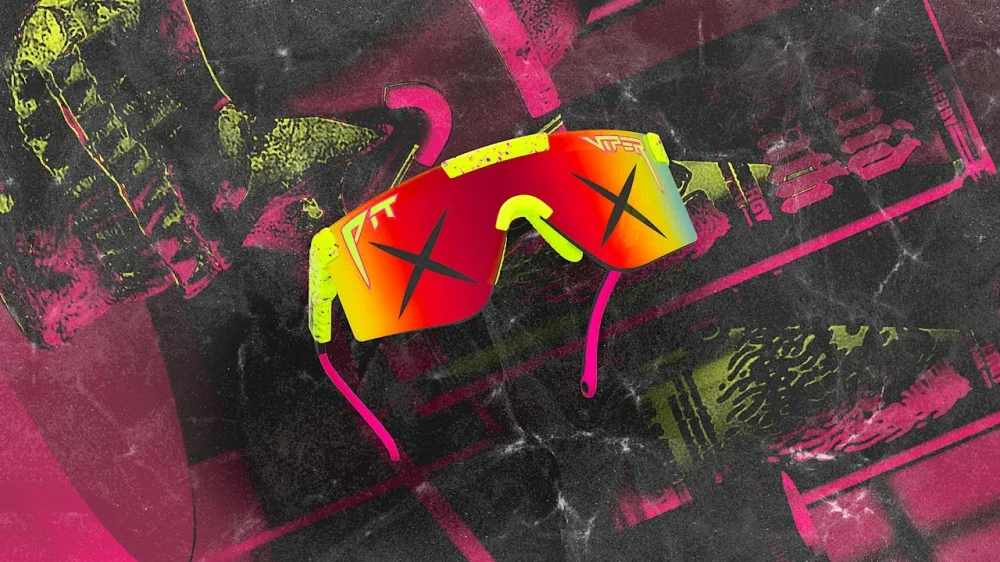
The most famous dead person to ever wear sunglasses just might be Bernie Lomax. Until now. Because the namesake for the 1989 hit comedy Weekend at Bernie’s was a fictional character, but you dear reader, you are very real. Liquid Death just announced its newest collab, this time with sunglasses brand Pit Viper, to make what its calling “Sunglasses for Dead People.” According to Liquid Death, 87% of people who have near-death experiences report seeing a blinding bright light. That’s not an exact science, but the canned water brand isn’t letting that get in the way of a good bit. Available on Pit Viper’s site for $119, the limited-edition shades feature shatterproof, durable lenses with 100% UVA/UVB protection, and every pair comes with what the brand calls a 100% after-lifetime guarantee: if the sunglasses break or fail to protect your eyes from the light that (allegedly) awaits us all, Pit Viper will replace them, no questions asked. The shades, which may or may not make you look like a cool outfielder, are just the latest mortality-themed project from Liquid Death that is pitched as a product for the afterlife. In February, the brand dropped a $495 urn with Spotify that featured an internal Bluetooth speaker in order to play your ashes an “eternal playlist.” Both ridiculous products perfectly embody Liquid Death’s overall brand collaboration strategy, that above all, values comedy you can touch and feel. At the Fast Company Grill at SXSW in March, Liquid Death’s vice-president of creative Andy Pearson told me, “It’s not funny to say, ‘Hey, what if we made something.’ It’s funny to make the thing,” said Pearson. “It’s funny to make adult diapers that are made of pleather so you don’t have to go to the bathroom at a concert, or a Bluetooth-enabled urn so you can play music into your ashes forever. It only becomes truly funny when it actually exists in the world. So we’ve put a lot of stock into making real things.” The brand’s entertainment-driven, social media-focused approach has been credited for its strong appeal among young consumers, amassing more than 14.5 million followers across TikTok and Instagram. In 2024, new funding valued Liquid Death at $1.4 billion, and last year the brand expanded into iced tea and energy drink categories. Deadly collab strategy When I spoke to Liquid Death’s vice-president of marketing Dan Murphy about the Spotify urn, he outlined three key pillars of the brand’s overall collab strategy. First is the Liquid Death Universe Filter. At the core of every collaboration is a simple creative question: “If you take another brand or celebrity into the Liquid Death universe, what is the one right answer?,” said Murphy. Second is mutual business value, where collaborating with other brands offers specific business advantages that working with individual celebrities doesn’t. “We find a lot of brands that are interested in our unique audience value our creativity,” he says. “We do everything in house—film, produce, direct—so we’re seen as a bit of an agency and production company. Partners see that value, and then we’ll find brands that will cover some production hard costs and allow us to extend our marketing budget, bringing what they do best to the table.” And the third pillar is quality and quantity. Going back to what Pearson said about really making the thing is what makes it funny, making something of quality just makes the joke even better. In terms of quantity, limited runs have been successful in driving demand and awareness, with each collab often having between 200 and 500 pieces available. “We want to do enough that people can have them, but also realize some of these very specific things have become more collectible when it’s not a mass product,” said Murphy. “Many things that we do, they sell out in less than a day, and you see them on eBay immediately.” While always amusing, these collabs serve to bring Liquid Death to a broader audience, whether it’s Pit Viper shades, Spotify, or e.l.f. beauty. In exchange for Liquid Death’s creative muscle, collaborating brands typically invest in the production costs and media spend behind it. With Spotify, for example, it custom programmed the Eternal Urn playlist on its platform, tapping into users’ Spotify history and likes. That not only customizes it for each user, but get Liquid Death on Spotify in a way it never could on its own. First we get an urn, now a pair of shades, what could be next for Liquid Death’s deceased demographic? Maybe collab with Ring on a coffin cam, or Scott’s Miracle-Gro on composting yourself, or maybe Hugo Boss “Last Suit You’ll Ever Wear.” The possibilities may never die. View the full article
-
I recently noticed a paradox among a team of developers. With AI, engineers started writing code faster and getting answers in seconds, yet they also reported feeling more exhausted than before. AI hasn’t actually reduced the amount of work that needs to be done. Instead, it has fundamentally changed its nature. We can now run multiple tasks in parallel and perceive this as productivity. Up to a point, it is. But eventually, managing tools and constantly switching between them becomes more draining than performing the original tasks themselves. In some cases, it even slows down the process of finding a solution. I’ve been managing developer teams for over 15 years, and I’ve spent the past year trying to understand why AI tools—designed to make work easier—sometimes have the opposite effect. Here are the causes behind this phenomenon and what we can do about it. WHERE THE FATIGUE COMES FROM WHEN AI IS DOING PART OF THE WORK Take a developer’s workflow as an example. In the past, when faced with a complex problem, developers would search Google, use Stack Overflow (before ChatGPT arrived), and ask colleagues for help. Each step and decision was separated by reflection time. Now, they start using Cursor or GitHub Copilot—AI tools that suggest code in real time. The path to an answer gets shorter. But instead of searching, they’re now engaged in continuous evaluation of AI suggestions: Accept the autocomplete or reject it, rewrite the prompt or regenerate the output. Dozens of micro-decisions with no pauses between them. Each of these carries a cognitive “cost.” Even the smallest choice demands attention and mental effort. The more decisions a person makes daily, the worse the quality of each subsequent one. This happens because of what psychologists call decision fatigue. AI has amplified this problem by dramatically increasing the number of decisions a person must make while completing a single task. Researchers at Boston Consulting Group (BCG) surveyed nearly 1,500 U.S.-based workers. They found that 14% of people who use AI at work, needing a high amount oversight, experience “AI brain fry”—a feeling of mental fog and an inability to focus. And this has consequences: Workers experiencing it are more likely to consider changing jobs and make more mistakes. MORE TOOLS DON’T IMPROVE PRODUCTIVITY I’ve seen it repeatedly: Managers begin implementing AI with the same question: How can we use these tools to help the team get more done? Then they start adding AI services. One or two AI tools genuinely do boost productivity, per BCG, but at three tools, productivity peaks. With the fourth, it drops. Each new tool means new settings, prompts, and workflows. At some point, the team spends more effort managing tools than doing the actual work. The worker stops being the doer and becomes the one checking, comparing, and choosing. Meanwhile, people remain convinced that AI makes them faster. But according to METR data, the opposite was true: Experienced developers using AI tools actually worked more slowly—even while believing their task completion time decreased by nearly a quarter. There’s another paradox here. Even when AI genuinely speeds up work, people don’t use that time to rest. They take on more tasks. This was discovered by researchers at UC Berkeley’s business school, who spent eight months observing employees at an American tech company to understand how AI usage affected their work habits. At first, employees felt energized; their productivity soared. But over time, the workday quietly stretched longer—a prompt during lunch, one last query before leaving the office—while the number of breaks decreased. No one demanded they work more, but that’s exactly what happened. Later, those same workers admitted they were exhausted. The researchers called this “workload creep”—a gradual increase in workload that accumulates unnoticed until fatigue starts affecting decision quality. SHOULD WE ABANDON AI TOOLS? I don’t think abandoning AI is the answer. I’m convinced the problem isn’t the technology but how we use it and our goals. Here are five things that, in my experience, can help implement AI without burning out your team: 1. Start by rethinking your workflows. Before introducing any AI tool into a process, begin with a question: Which tasks require human attention, and which can be automated without sacrificing quality? The approach of “implementing AI in every process” isn’t a strategy—it’s a fast track to breaking what already works. 2. Give managers a leading role in AI adoption. In teams where the manager personally helps people learn AI tools, cognitive fatigue among workers is lower, according to the BCG study. A manager who truly understands how AI works can set a healthy pace for using these tools and prevent the team from drowning in experiments. 3. Establish rules for working with AI. The Berkeley researchers called this “AI practice”—agreements about how the team engages with AI. These might include a short pause before important decisions, sequential execution instead of multitasking, and time for discussion and collective reflection. One of our team leads, for example, encourages juniors to argue with AI more often. 4. Track cognitive load. We regularly conduct team health checks—monitoring productivity, engagement, and stress levels. But I’ve realized that’s no longer enough. In our new reality, cognitive load needs to become a separate metric. You can start with a few questions: How many AI tools is someone using, has AI simplified their work or increased its volume, and how does the employee feel at the end of the day? 5. Explain the reasons behind changes to your team. People can be skeptical of AI because of uncertainty. If a company doesn’t explain why it’s introducing new tools, employees start interpreting it themselves. By contrast, gaining an understanding that the company values balance—rather than simply wanting more output for the same cost—reduces mental fatigue by 28%, per the BCG research. This is exactly the approach I follow with my 100-person software team: transparency. The key question isn’t “how do we use AI” but “why?” Start with the goal of freeing people from routine tasks. Improving decision quality will yield different results than measuring implementation success in tokens or lines of code. Illia Smoliienko is chief software officer of Waites. View the full article
-
When considering investment opportunities, top sales franchises stand out because of their established systems and brand recognition. These franchises often come with proven business models that can lead to a more secure return on investment. As you evaluate your options, it’s important to understand the criteria for selecting the right franchise and the benefits they offer. Let’s explore some of the leading franchises that might align with your investment goals. Key Takeaways Evaluate franchises with strong historical sales data and a solid brand reputation to ensure profitability and support. Consider sectors experiencing growth, like food and beverage, home services, and fitness, for promising investment opportunities. Look for franchises that offer comprehensive training programs and ongoing support to enhance franchisee success. Review the Franchise Disclosure Document (FDD) for financial performance, upfront fees, and potential ROI before investing. Network with existing franchisees to gain insights into operations, challenges, and the level of support provided by the franchisor. Understanding the Franchise Model When you consider investing in a franchise, it’s vital to understand how the franchise model works. This model allows you to operate a business under an established brand, benefiting from proven systems that lead to higher success rates, typically between 80-90%. As a franchise owner, you’ll pay upfront and ongoing fees, which grant you access to fundamental resources, training, and support to guarantee consistency across locations. In the franchise marketplace, opportunities are evaluated based on criteria like sales performance and brand reputation. The International Franchise Association forecasts a 2.5% growth in franchising by 2025, indicating strong market potential. Before signing any contracts, review the Franchise Disclosure Document (FDD) thoroughly, as it outlines critical financial and operational expectations. Criteria for Selecting Top Sales Franchises How do you determine which franchises stand out in sales performance? First, assess the franchise’s historical sales data; higher sales often mean better support and profitability for franchisees. Next, evaluate the brand’s market presence and reputation, as established brands tend to have loyal customers and strong marketing. Thorough training programs and ongoing support are vital; these help franchisees develop important sales skills. Consider the potential for location growth, since franchises with expansion opportunities can boost revenue. Finally, analyze financial viability by studying initial investment costs and potential profit margins to guarantee a favorable return on investment. Consulting Franchise Global broker companies can provide valuable insights into these criteria, streamlining your selection process for the best sales franchises. Benefits of Investing in Sales Franchises Investing in sales franchises offers numerous advantages that can improve your entrepreneurial expedition. One key benefit is the established brand recognition, which nurtures consumer trust and loyalty, ultimately enhancing your sales potential. Many sales franchises provide extensive training programs and ongoing support, ensuring you have the skills necessary to thrive in a competitive market. Furthermore, the franchise model reduces your risk of failure, with an impressive 80-90% success rate compared to independent businesses. Sales franchises likewise feature proven business models that streamline operations, allowing you to generate revenue more efficiently. With a diverse range of industries represented in sales franchises, you can tap into various market demands and cater to different consumer preferences, increasing your chances of success. Top Sales Franchises to Consider Several strong contenders exist in the sales franchise arena, each offering unique opportunities for aspiring business owners. Among these, restaurant franchises for sale often lead the pack, thanks to their established brand recognition and consistent consumer demand. Many of these food and beverage franchises achieve impressive revenue growth through innovative products that cater to changing tastes. Furthermore, service-oriented franchises, particularly in home services and health-related sectors, are gaining popularity because of their crucial nature and the ongoing need for dependable providers. The best franchises likewise offer robust training and support programs, which improve franchisee performance. Effective marketing strategies and a strong focus on customer satisfaction further bolster their competitive edge, making them worth considering for your investment. Financial Performance and ROI Analysis When evaluating the financial performance of top sales franchises, you might wonder how their profitability stacks up against industry standards. Many of these franchises report strong revenue growth and profit margins that exceed the industry average, showcasing their financial viability. To gauge this, financial performance metrics such as historical sales data and profit projections are crucial. Franchise surveys reveal that successful franchises maintain low failure rates, translating to a high return on investment (ROI) for franchisees when managed effectively. Although initial investment costs can vary, top-performing franchises often provide detailed financial performance representations in their Franchise Disclosure Documents (FDDs) to assist potential investors. Thorough support and training programs further improve financial performance, helping franchisees maximize their ROI. Challenges and Risks in Sales Franchising Although the financial performance of top sales franchises may appear robust, potential investors should likewise consider the inherent challenges and risks that come with franchising in this sector. Competition is fierce, as both established brands and new entrants vie for market share, which can dilute profitability. Economic fluctuations can lead to decreased consumer spending, especially in sectors reliant on discretionary purchases like food franchises for sale. High employee turnover can disrupt sales consistency and damage customer relationships. Furthermore, steering through different regulatory environments can impose costs and operational hurdles, impacting overall performance. Finally, inadequate support from franchisors may result in insufficient training and resources, hindering franchisees’ abilities to meet sales targets and grow their businesses effectively. Importance of Brand Recognition Brand recognition plays a crucial role in the success of sales franchises, as it markedly influences consumer behavior and purchasing decisions. Established brands cultivate trust, attracting loyal customers and enhancing franchisee success. Strong marketing strategies further boost visibility and engagement in competitive markets. Here’s a breakdown of the benefits: Benefit Description Consumer Trust Consumers prefer established brands, increasing sales. Marketing Efficiency Recognized brands require less marketing to attract customers. Repeat Business Brand loyalty leads to a stable revenue stream. Market Entry Familiarity helps franchises enter new markets easily. Profitability Higher demand translates to increased profitability. Franchise business brokers understand this importance, helping you choose brands that maximize these advantages. Market Trends Influencing Sales Franchises As the terrain of sales franchises evolves, several market trends are greatly shaping the industry. The food and beverage sector continues to dominate because of strong customer demand and brand recognition. Meanwhile, home services franchises, like plumbing and cleaning, are gaining traction owing to lower startup costs and ongoing consumer needs, eliminating the need for a storefront. The fitness industry is likewise booming, as membership models cultivate brand loyalty amid rising health consciousness. Retail and e-commerce franchises are adapting by merging online and in-store shopping experiences. Finally, the senior care sector is set for significant growth, driven by the aging population, increasing demand for home health and companion services. Keep an eye on franchisors for sale in these thriving sectors. Steps to Getting Started With a Franchise Starting a franchise can be an exciting venture, but it requires careful planning and consideration. Here are crucial steps to get you started: Step Description Select a Franchise Choose one that aligns with your interests and skills for better success. Research Potential Franchises Investigate their history, brand reputation, training, and support systems. Review the FDD Examine the Franchise Disclosure Document for financial performance and fees. Connect with Existing Owners Gain insights from current franchisees about their experiences. Additionally, consider your financial situation and establish a clear budget, accounting for both upfront fees and ongoing costs. If you’re exploring business broker franchises, they can assist you in managing this process effectively. Key Takeaways for Franchise Investors Investing in a franchise can offer substantial financial rewards, but it’s essential to understand key takeaways that can guide your decision-making process. First, look for established franchises for sale, particularly in the food and beverage sector, which often lead in sales because of strong consumer demand. Evaluate the Franchise Disclosure Document (FDD) closely, as it provides critical insights into financial performance and franchisee support. Consider franchises that offer thorough training and ongoing assistance; these factors greatly lower failure rates. Moreover, prioritize franchises with innovative products and services that adapt to changing consumer behaviors, as they show the best growth potential. Frequently Asked Questions What Are the Most Profitable Franchises to Buy? When considering profitable franchises to buy, focus on sectors like food and beverage, which thrive on customer demand and brand loyalty. Home services, such as cleaning and maintenance, offer consistent revenue with lower startup costs. The health and wellness industry, including gyms, is likewise growing swiftly, reflecting a consumer shift in the direction of fitness. Choose franchises with strong support systems and training programs, as they often lead to higher returns on your investment. Which Franchise Has the Highest Sales? When considering which franchise has the highest sales, McDonald’s leads the fast-food industry with over $46 billion in annual global systemwide sales. Following it, 7-Eleven generates around $18 billion, making it a top contender in retail franchises. Dunkin’ likewise shows strong performance with approximately $12 billion, whereas Chipotle reports nearly $7 billion in fast-casual dining. Finally, Subway maintains a significant presence with about $10 billion in sales, in spite of recent challenges. What Franchise Can I Buy for $10,000? If you’re looking to buy a franchise for $10,000 or less, several options are available. Consider Jan-Pro Cleaning Systems, which has low overhead and a proven business model. Another choice is Cruise Planners, a home-based travel agency with minimal operational costs. These franchises often include training and support from franchisors, helping you succeed. Investing in a low-cost franchise can provide a manageable entry point into business with potential for growth. What Are the Most Profitable Franchises in 2025? In 2025, the most profitable franchises will likely include established food and beverage brands, home service franchises, boutique gyms, and senior care services. These sectors have shown consistent demand and profitability. Particularly, health-conscious trends will boost fitness franchises, whereas the aging population will increase the need for senior care. Moreover, franchises embracing eco-friendly practices and technology will attract consumers, offering higher profitability potential in an evolving market terrain. Conclusion Investing in a top sales franchise can be a strategic move for potential business owners. By choosing a franchise with strong brand recognition and a solid business model, you can improve your chances of success. Evaluate the financial performance and market trends of various franchises before making your decision. By following the outlined steps and comprehending the benefits, you can confidently initiate your franchise expedition, maximizing your investment potential in a thriving industry. Image via Google Gemini This article, "10 Top Sales Franchises to Invest" was first published on Small Business Trends View the full article
-
As a business owner, comprehension of your tax obligations is crucial for financial success. Your taxes can vary greatly based on your business structure, whether you’re self-employed, part of a pass-through entity, or running a C corporation. Each type comes with its own tax rates and responsibilities. Furthermore, numerous deductions and credits might help lower your overall tax burden. So, how exactly do these factors impact what you owe? Let’s explore further. Key Takeaways Business owners’ tax rates vary based on their business structure, such as C corporations or pass-through entities. Self-employed individuals pay 15.3% in self-employment payroll taxes on their income. Pass-through entities face federal income tax rates ranging from 10% to 37% based on individual income levels. C corporations are subject to a flat federal tax rate of 21% on their taxable income. Accurate record-keeping of income and expenses is essential to determine tax liability and maximize deductions. Understanding Small Business Taxes Grasping small business taxes can feel overwhelming, especially since they depend on various factors, including your business structure. If you’re self-employed, you’re likely paying self-employed payroll taxes, which include Social Security and Medicare taxes at a combined rate of 15.3%. For pass-through entities like sole proprietorships and S corporations, your income is taxed at individual rates ranging from 10% to 37%. C corporations, conversely, face a flat federal tax rate of 21%. Whether you hire employees or work with 1099 contractors, comprehending how much a business owner pays in taxes is crucial. You might as well qualify for the Qualified Business Income deduction, allowing you to deduct up to 20% of your earned income. Moreover, keeping accurate records of your income and expenses is fundamental for minimizing tax liabilities and ensuring compliance with IRS regulations. Factors Influencing Tax Liability In terms of your tax liability as a business owner, the structure of your business plays an essential role. For instance, C corporations face a flat federal tax rate of 21%, whereas pass-through entities, like sole proprietorships and LLCs, are taxed based on individual income rates that can be much higher. Furthermore, your revenue and the deductions you can claim for ordinary business expenses directly influence how much tax you finally owe. Business Structure Impact The choice of business structure plays a pivotal role in determining your tax liability, impacting how much you eventually owe. C corporations face a flat federal tax rate of 21%, whereas pass-through entities like sole proprietorships and partnerships pay taxes based on your personal income tax rate, which can range from 10% to 37% in 2025. If you opt for an LLC, you enjoy flexibility in taxation, choosing to be taxed as a sole proprietorship, partnership, or corporation. Furthermore, pass-through entities may qualify for the Qualified Business Income deduction, allowing you to deduct up to 20% of your qualified business income. Revenue and Deductions Comprehending how revenue and deductions interact is crucial for managing your tax liability as a business owner. Your taxable income is determined by subtracting allowable business expenses, tax deductions, exemptions, and credits from your total revenue. Corporations face a flat federal tax rate of 21%, whereas pass-through entities like sole proprietorships and LLCs are taxed at individual rates ranging from 10% to 37%. The Qualified Business Income (QBI) deduction allows eligible owners of pass-through entities to deduct up to 20% of qualified income, which can markedly lower taxable income. To maximize your deductions, maintain accurate records of expenses, including office supplies, marketing, travel, and retirement contributions, as these deductions can greatly impact your overall tax liability. Types of Taxes for Small Business Owners Comprehending the various types of taxes you face as a small business owner is crucial for effective financial management. You’ll encounter federal income taxes, which differ based on your business structure; C corporations face a flat 21% rate, whereas pass-through entities like sole proprietorships and LLCs are taxed at individual income tax rates ranging from 10% to 37%. Payroll taxes likewise play a significant role, including FICA taxes totaling 15.3% of eligible gross earnings and federal unemployment taxes of 6% on the first $7,000 paid to each employee. Furthermore, you’ll need to take into account sales and use taxes varying by state; for example, California has a base rate of 7.25%, whereas Texas has 6.25%. If your business is a C corporation, corporate income taxes apply, with rates ranging widely across states. Using deductions for expenses like office supplies and marketing can help lower your taxable income effectively. Federal Income Tax Rates for Small Businesses Comprehending federal income tax rates is crucial for small business owners, as they directly impact your financial obligations. The tax structure can vary depending on how your business is organized. Here’s a breakdown of the key points: C corporations face a flat federal income tax rate of 21% on taxable income. Pass-through entities, like sole proprietorships and partnerships, are taxed based on individual rates between 10% and 37%. Eligible owners can use the Qualified Business Income (QBI) deduction, allowing up to a 20% deduction on business income. For LLCs, tax implications depend on your elected classification, which can affect your overall tax burden. C corporations calculate taxable income as total revenue minus deductions, whereas pass-through entities report income on personal tax returns. Understanding these rates helps you plan your business finances and guarantee compliance with tax laws. State and Local Taxes When running a business, it’s essential to understand that state and local taxes can greatly impact your financial obligations. As of 2025, 44 states impose a corporate income tax, with rates ranging from 2.25% in North Carolina to 11.5% in New Jersey. If you own a pass-through entity like an LLC or partnership, you’ll pay state income tax on your business profits in one of the 42 states that enforce individual income taxes. Furthermore, 45 states and the District of Columbia levy sales tax, which varies widely; for instance, California’s base sales tax rate is 7.25%. Some states offer special business tax rates or incentives, whereas local jurisdictions may impose extra taxes, increasing your overall tax burden. Interestingly, Washington state only taxes capital gains for high-income earners, avoiding a broad-based income tax entirely, which is unique among the states. Tax Deductions and Credits for Small Businesses As a small business owner, grasping tax deductions and credits is vital for managing your finances effectively. You can deduct common expenses like office supplies and travel, which can greatly lower your taxable income. Furthermore, exploring business tax credits can provide direct savings on your tax bill, making it important to stay informed about what’s available to you. Common Tax Deductions Available Maneuvering the tax environment can be challenging for small business owners, but comprehending common tax deductions available to you can greatly ease the burden. Here are some key deductions that may benefit your business: Ordinary and necessary business expenses like office supplies, marketing, and utilities Home office deduction, allowing you to claim a portion of home expenses if used exclusively for business Contributions to retirement plans such as 401(k)s and SEPs, which are tax-deductible Qualified Business Income (QBI) deduction, enabling eligible pass-through entities to deduct up to 20% of qualified business income Section 179 deduction, allowing the full purchase price of qualifying equipment and software in the year it’s placed in service, up to $1,160,000 for 2025. Business Tax Credits Explained Have you ever wondered how tax credits can greatly impact your small business’s bottom line? Unlike tax deductions that only reduce your taxable income, tax credits directly lower the amount of tax you owe, making them especially valuable. For instance, the Work Opportunity Tax Credit can offer up to $9,600 per eligible employee you hire, depending on their demographic. Furthermore, if you provide health insurance, the Small Business Health Care Tax Credit can refund up to 50% of your premiums, provided you cover at least half of your employees’ costs. You can likewise take advantage of credits for energy-efficient improvements, like the Residential Energy Efficient Property Credit, which benefits businesses investing in renewable energy systems. These credits can markedly minimize your tax liability. Tax Payment Schedules and Deadlines Grasping tax payment schedules and deadlines is essential for business owners to avoid penalties and guarantee compliance with federal regulations. Comprehending when payments are due can save you time and money. Here are some key dates to keep in mind: Quarterly estimated tax payments are due on April 15, June 15, September 15, and January 15 for the following year. C corporations must file their tax returns by April 15 for the prior tax year. S corporations and partnerships have a filing deadline of March 15. If a due date falls on a weekend or holiday, the deadline shifts to the next business day. Employers must issue W-2 forms to employees and 1099 forms to independent contractors by January 31. Missing these deadlines can lead to penalties based on the amount underpaid and the duration of the delay, so stay organized and proactive. Frequently Asked Questions How Much Does the Average Business Owner Pay in Taxes? The average business owner pays varying amounts in taxes, largely influenced by their business structure and income level. For pass-through entities, federal tax rates range from 10% to 37%. C corporations face a flat 21% rate. Business owners can lower their taxable income through deductions for expenses and may qualify for a 20% deduction on qualified business income. Moreover, state and local taxes can further affect total tax liabilities greatly. How Much Should Business Owners Put Away for Taxes? You should set aside 25% to 30% of your income for taxes, covering federal, state, and self-employment taxes. If you operate a pass-through entity, keep in mind personal tax rates range from 10% to 37%. For C corporations, allocate 21% for federal taxes, plus any state taxes. In addition, don’t forget to make quarterly estimated payments by specific deadlines to avoid penalties, and consider the Qualified Business Income deduction to reduce your overall tax burden. Do You Pay Tax as a Business Owner? Yes, as a business owner, you pay taxes based on your business structure. If you’re a sole proprietor or part of an LLC, your business income is taxed at your personal tax rate. C corporations, on the other hand, face a flat federal tax rate of 21%. Furthermore, you need to take into account payroll taxes for employees and potential state income taxes, which can vary greatly. Effective tax management strategies can help reduce your overall tax liability. How Much an Hour Is $70,000 a Year After Taxes? To determine your hourly wage from a $70,000 annual salary after taxes, you’ll need to take into account various deductions and tax rates. After federal and state taxes, your net income could range from $50,000 to $60,000. Dividing this by approximately 2,000 working hours a year means you’d take home about $24 to $29 per hour. This estimate varies based on your specific tax situation, including deductions and credits you might qualify for. Conclusion In conclusion, comprehending your tax obligations as a business owner is crucial for effective financial management. Your taxes will vary based on your business structure, income level, and applicable deductions or credits. By staying informed about federal, state, and local tax rates, along with payment schedules, you can better navigate your tax responsibilities. In the end, strategic tax planning can greatly impact your business’s financial health, ensuring you maximize available benefits while reducing liabilities. Image via Google Gemini and ArtSmart This article, "How Much Does a Business Owner Pay in Taxes?" was first published on Small Business Trends View the full article
-
Comprehending the LLC tax deadline is essential for compliance and avoiding penalties. Multi-member LLCs need to file Form 1065 by March 15, 2026, whereas single-member LLCs report income on Schedule C of Form 1040, due April 15, 2026. If you’re considering an extension, Form 7004 can help. Knowing these dates is just the beginning; let’s explore the filing requirements and options available to guarantee you meet all necessary obligations. Key Takeaways Multi-member LLCs must file Form 1065 by March 15, 2026, with an option for extension until September 15, 2026. Single-member LLCs file as sole proprietorships, with a deadline of April 15, 2026, unless extended. Schedule K-1 must be distributed to partners by March 16, 2026, for multi-member LLCs. Use Form 7004 to request an automatic six-month extension for tax filings. Timely filings are crucial to avoid penalties and ensure compliance with tax regulations. Understanding LLC Tax Deadlines Grasping LLC tax deadlines is crucial for ensuring compliance and avoiding penalties. The primary LLC tax filing deadline for multi-member LLCs, which typically file as partnerships, is March 15, 2026. If you miss this date, you can extend your deadline to September 15, 2026, by submitting Form 7004. For single-member LLCs treated as sole proprietorships, the tax return deadline is April 15, 2026, where you’ll file Schedule C with Form 1040. Moreover, if your LLC has partners, you must distribute Schedule K-1 by March 16, 2026, detailing each partner’s share of income, losses, credits, and deductions. Comprehending when LLC tax returns are due and the implications of your LLC’s classification can help you meet these deadlines effectively. Staying organized and informed will prevent costly penalties and keep your business compliant with IRS regulations. Key Deadlines for LLCs in 2026 As you prepare for 2026, it’s essential to stay aware of key filing deadlines for your LLC. Form 1065 is due by March 15, and you’ll need to distribute Schedule K-1 by March 16. If you plan to extend your filing, you can do so with Form 7004, pushing the deadline to September 15. Filing Form 1065 Deadline In regard to filing Form 1065 for your LLC in 2026, it’s essential to be aware of the key deadlines that can impact your tax obligations. The tax deadline for LLCs is March 15, 2026, except you file for an extension. You can obtain an extension by submitting Form 7004, which pushes your deadline to September 15, 2026. If you’re unsure how to file taxes for an LLC with no income, remember you still need to file Form 1065. Furthermore, make sure that Schedule K-1, detailing each partner’s share of income, deductions, and credits, is distributed by March 16, 2026. Filing on time helps avoid penalties and guarantees accurate tax reporting. K-1 Distribution Requirements Comprehending the K-1 distribution requirements is fundamental for LLCs in 2026, especially since each partner relies on this information for their personal tax returns. LLCs must distribute Schedule K-1 to their partners by March 16, 2026, detailing each partner’s share of income, losses, credits, and deductions. It’s important to issue K-1 forms concurrently with the filing of Form 1065, which is due by March 15, 2026, for LLCs and domestic partnerships. If you fail to distribute K-1 forms by the deadline, your LLC may face penalties. These forms provide critical information for partners to accurately report their share of the LLC’s income on their personal tax returns, making complete and accurate K-1 distributions indispensable for smooth tax filing. Extension Filing Options Comprehending your extension filing options is crucial for IRS to confirm compliance with tax deadlines in 2026. If you’re operating a partnership or multi-member LLC, keep in mind that Form 1065 is due on March 15, 2026. You can extend this deadline by filing Form 7004 on or before that date, which grants you an extension until September 15, 2026. Schedule K-1s, nonetheless, must still be distributed to partners by March 16, 2026. For single-member LLCs, filing is due by April 15, 2026, except you request an extension. If your LLC has elected S corporation status, be certain to file Form 1120-S by March 15, 2026, or apply for an extension using Form 7004 for additional time. Filing Requirements for LLCs During the process of maneuvering through the filing requirements for LLCs, it’s essential to understand the different obligations based on the structure of your LLC. For multi-member LLCs and domestic partnerships, you need to file Form 1065 by March 15, 2026, but you can extend this deadline to September 15, 2026, by submitting Form 7004. If you have a single-member LLC, you’ll report your income on Schedule C of Form 1040, which is due by April 15, 2026. When filing Form 1065, you must additionally distribute Schedule K-1 to each partner by March 16, 2026, detailing their share of income, losses, and deductions. If your LLC elects to be taxed as an S corporation, file Form 1120S by March 15, 2026. For C corporations classified as LLCs, Form 1120 is due by April 15, 2026, with an extension option until October 15, 2026. How to File Form 1065 When you’re ready to file Form 1065, it’s essential to understand the filing requirements and important due dates to avoid common mistakes. Remember, this form is due by March 15, 2026, and if you miss it, you can request an extension with Form 7004. Filing Requirements Overview Filing Form 1065 is vital for multi-member LLCs to report their income, deductions, and profits to the IRS. You must submit this form by March 15, 2026. Each partner in your LLC will receive a Schedule K-1, outlining their specific share of the LLC’s income, deductions, and credits, which you need to distribute by March 16, 2026. If you require more time, you can obtain a six-month extension by filing Form 7004 by the original due date. Depending on your preference, you can file Form 1065 electronically or by mail. To guarantee a smooth filing process, it’s important to maintain accurate financial records throughout the year, supporting compliance and reducing errors. Important Due Dates Grasping the important due dates for filing Form 1065 is crucial for multi-member LLCs to remain compliant with IRS regulations. For tax year 2025, your Form 1065 is due by March 15, 2026, except you file for an extension. If you need more time, you can file Form 7004, extending your deadline to September 15, 2026. Remember, you must likewise distribute Schedule K-1 to each partner by March 16, 2026, detailing their share of income, deductions, and credits. If you choose to file electronically, you may receive an extended deadline of March 31, 2026, for submitting Form 1065. Staying organized and aware of these dates will help you avoid penalties and guarantee compliance. Common Filing Mistakes Comprehending common filing mistakes is vital for ensuring that your Form 1065 is submitted correctly and on time. First, accurately report all income and expenses to reflect your partnership’s financial activities for the tax year. Be sure to include your LLC’s federal identification number (EIN) on the form; an incorrect EIN can lead to processing delays or rejection by the IRS. Each partner must receive their Schedule K-1 by March 16, 2026, detailing their share of income, deductions, and credits, which is fundamental for their individual tax filings. If you need an extension, keep in mind that using Form 7004 extends your filing deadline to September 15, 2026, but it doesn’t extend the K-1 distribution deadline. Schedule K-1 and Its Importance In relation to reporting income from a multi-member LLC, comprehending the significance of Schedule K-1 is fundamental. This form must be distributed to partners by March 16, 2026, detailing each partner’s share of income, losses, credits, and deductions. The information on Schedule K-1 is vital for you to accurately report your income on your individual tax return. Multi-member LLCs are required to file Form 1065 by March 15, 2026, which generates the Schedule K-1 for each partner. Schedule K-1 Details Importance Income Helps report taxable income Losses Allows for loss deductions Credits Provides tax credit information Deductions Aids in reducing taxable income If the LLC files for an extension, it must submit Form 7004 by the regular due date, which can delay the issuance of K-1s. Timely distribution is important to avoid complications in tax filings. Options for Tax Extensions When dealing with LLC tax obligations, awareness of your options for tax extensions can provide some relief. You can apply for a tax extension by filing Form 7004, which grants an automatic six-month extension for submitting your tax returns. If your LLC is a multi-member entity classified as a partnership or an S corporation, your new filing deadline will be September 15, 2026. For single-member LLCs treated as disregarded entities, you must file your extension by April 15, 2026, extending your deadline to October 15, 2026. It’s important to emphasize that filing for an extension doesn’t delay your payment deadline; any taxes owed are still due by the original due date. To avoid penalties and guarantee compliance with IRS regulations, make sure to file for an extension before the original deadline. Grasping these options can help you manage your tax responsibilities more effectively. Common Mistakes to Avoid To avoid costly penalties and compliance issues, it is crucial to be aware of common mistakes that LLCs often make during tax season. Here are a few key pitfalls to watch out for: Mistake Consequence Solution Missing Form 1065 deadline Late filing penalties File by March 15, 2026 Not distributing Schedule K-1 Compliance issues and penalties Distribute by March 16, 2026 Missing extension filing Unapproved extension Submit Form 7004 on time Incorrect tax treatment election Misclassification penalties File Form 8832 within 75 days Be sure to classify your LLC accurately to avoid misfiling. Single-member LLCs are treated as disregarded entities, whereas multi-member LLCs are partnerships except an election is made. Keeping these points in mind will help streamline your tax process. Resources for LLC Tax Filing Maneuvering the tax filing process for your LLC can be complex, especially with various forms, deadlines, and regulations to contemplate. To keep things on track, familiarize yourself with the necessary forms. For LLCs and domestic partnerships, you’ll need to file Form 1065 by March 15, 2026, except you request an extension using Form 7004. Remember, Schedule K-1 must be distributed by March 16, 2026, detailing each partner’s financial share. If you’re a single-member LLC, report your income on Schedule C with Form 1040, due by April 15, 2026. Multi-member LLCs can opt to be taxed as an S corporation by filing Form 2553 by March 15, 2026. Don’t forget to stay compliant with both federal and state tax requirements, as deadlines and forms can vary depending on your jurisdiction. Utilize online resources or consult with a tax professional for guidance customized to your specific situation. Frequently Asked Questions What Is the IRS Filing Deadline for an LLC? The IRS filing deadline for an LLC varies based on its structure. For multi-member LLCs, Form 1065 is due on March 15, except you file for an extension. You’ll need to distribute Schedule K-1 to partners by March 16. If you’re a single-member LLC, report income on Schedule C with your Form 1040 by April 15. What Is the Tax Extension Deadline for LLC in 2025? If you’re filing for an LLC in 2025 and need a tax extension, you can file Form 7004 by the regular due date, which is March 17, 2025. This grants you an extension until September 15, 2025. Nonetheless, keep in mind that this extension only applies to filing, not to any tax payments due. You’ll still need to make quarterly estimated tax payments throughout the year to avoid penalties. What Is the New IRS Rule for LLC? The new IRS rules for LLCs focus on how they can choose their tax classification. You’ve got options: LLCs can be treated as corporations, partnerships, or disregarded entities based on your elections and member count. If you want to change classifications, you’ll need to file IRS Form 8832 within 75 days of formation or the fiscal year start. Staying updated on these rules helps you manage your tax obligations effectively. What Do LLCS Need to File Before 2025? Before 2025, LLCs must guarantee they file specific forms based on their classification. Multi-member LLCs need to submit Form 1065 by March 15, 2026, and distribute Schedule K-1 to partners. Single-member LLCs report income on Schedule C with Form 1040, due April 15, 2026. If your LLC elects S corporation status, file Form 1120S by March 15, 2026, or request an extension. Remember to file Form 8832 timely if changing tax classification. Conclusion In conclusion, comprehending the LLC tax deadlines is crucial for compliance and avoiding penalties. Multi-member LLCs need to file Form 1065 by March 15, 2026, whereas single-member LLCs report on Schedule C due April 15, 2026. If you require more time, you can request an extension using Form 7004. By staying informed and organized, you can navigate the tax process effectively and guarantee that your LLC meets all necessary requirements for a smooth filing experience. Image via Google Gemini This article, "What Is the LLC Tax Deadline?" was first published on Small Business Trends View the full article
-
Alberto Safra was charged more than $162,000 on one day alone by US law firm WilmerHaleView the full article
-
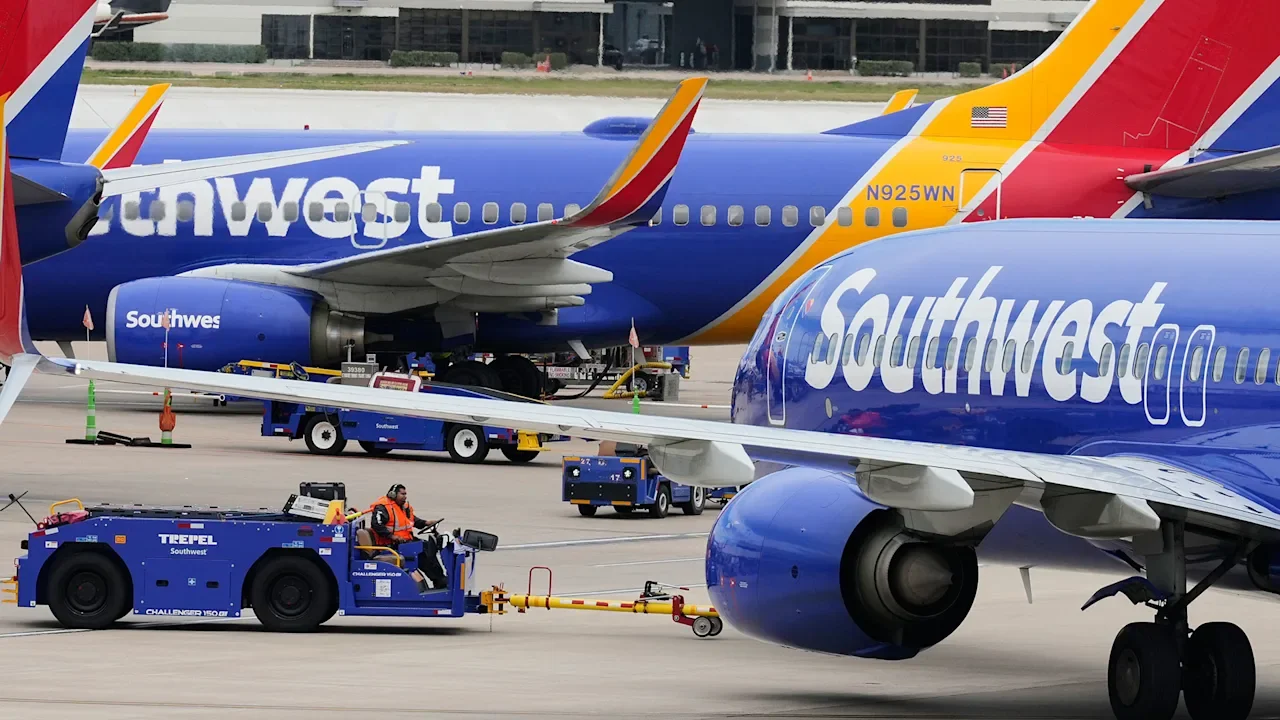
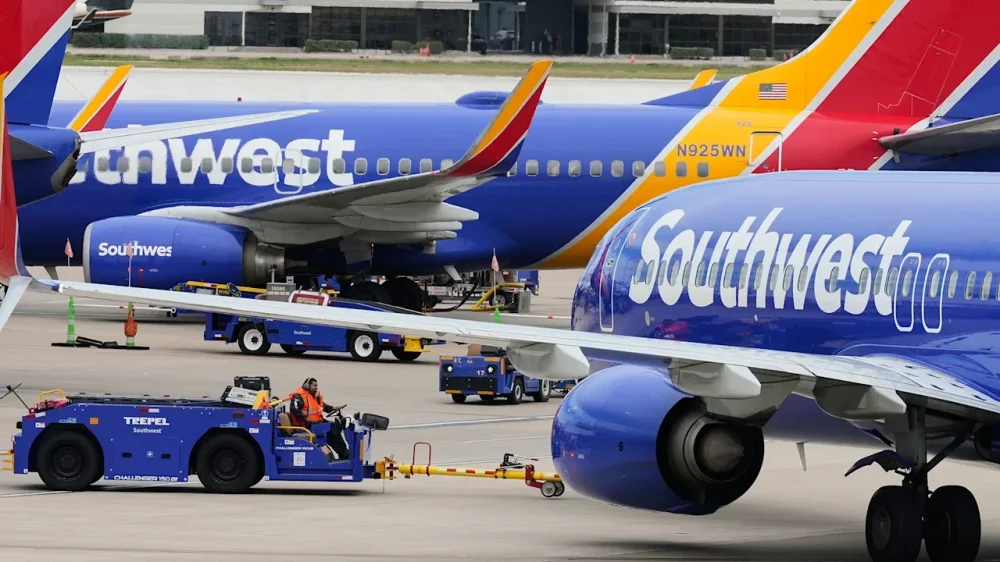
Travelers will soon face restrictions on how many portable chargers they can carry on a flight as airlines continue to try to reduce the risk of another lithium battery fire aboard their jets. Southwest Airlines announced Tuesday that starting April 20 passengers will only be able to carry one charger on their planes, and they won’t be allowed to put it in the overhead bin or in their checked luggage. The airline already requires passengers to keep their chargers in the open while they are using them, so flight attendants can act quickly if they start to overheat. The new Southwest rule goes even further than the limit of two chargers per passenger that the International Civil Aviation Organization recommended last month. But the airline says it isn’t going to aggressively enforce the policy by searching bags and confiscating chargers. Instead, Southwest’s Vice President of Safety and Security Dave Hunt said the airline will stress this to travelers when they book their flights and arrive at the airport while explaining the potential dangers. That alone might be a big help because most people don’t seem to be aware of the risks, said Jeff Marootian, who is CEO of UL Standards & Engagement, which establishes the guidelines for the makers of these chargers and other electronic devices. “A huge part of the concern here is seeing that number of incidents continue to increase, correlating, of course, to the number of devices that people are bringing on planes,” he said. The Federal Aviation Administration said more lithium battery incidents are reported every year and hit 97 in 2025 as everyone carries more re-chargable devices like phones, iPads, laptops and these portable chargers. Marootian said that his organization hears about two incidents every week, and reported a 42% increase in the number of incidents involving portable chargers in 2025. One of the worst happened in January 2025 when a devastating fire aboard an Air Busan plane waiting to take off from an airport in South Korea forced the evacuation of all 176 people aboard before the fire burned through the plane’s roof. Flight attendants have fire-resistant bags and insulated gloves to put overheating devices into to contain any potential blaze. Southwest’s Hunt said the airline’s new rule will “strengthen our ability to contain and mitigate lithium battery incidents, including reducing the risk of battery fires.” To help make the rule workable for passengers, Southwest plans to equip all of its planes with in-seat power by the middle of next year. Aviation safety expert Steve Arroyo, who flew for United Airlines for 37 years, said he thinks Southwest’s new policy is a positive step to reduce the risk. Even though the number of fires is small compared to the roughly 100,000 flights every day around the globe, the potential consequences of a battery fire can be disastrous. “It can turn into something very serious very quickly,” Arroyo said. —Josh Funk, AP Transportation Writer View the full article
-
UAE relief over halt to conflict marred by prospect of regime’s continued threat and stranglehold over Strait of HormuzView the full article
-
Square is changing the lending landscape for small businesses, and the implications are significant. Leveraging advanced machine learning and real-time data, Square has fashioned a cutting-edge approach to small business financing that promises to break down barriers many entrepreneurs face when seeking credit. For over a decade, Square has championed the cause of small businesses, providing them with essential capital that not only fuels their growth but also strengthens local economies. With small businesses being vital to community health, Square’s commitment to expanding access to credit is not just a business strategy; it’s a community investment. Traditionally, financial institutions have relied on static metrics and outdated documentation, often turning away businesses deemed “too risky” or “too small.” In contrast, Square’s innovative underwriting process draws from a comprehensive understanding of a business’s real-time financial activity. Using transaction data, revenue patterns, and other dynamic signals, Square can offer loans that empower rather than hinder. Since 2014, Square has issued over $32 billion in loans, averaging nearly $10,000 per loan, addressing significant gaps in access to capital. Notably, women-owned businesses receive 58% of Square Loans, while minority-owned businesses account for 36%. Additionally, more than half of these loans are directed to areas with low traditional loan approval rates. This commitment to inclusivity not only showcases Square’s progressive approach but also highlights the potential for such a model to create lasting impact. Square’s latest enhancements are designed to reach even more sellers. By refining their underwriting models, the company is now in a position to extend credit offers to over 50% more sellers previously ineligible for Square Loans. This includes newer businesses within their first week of processing, seasonal operations, and service providers with project-based income, reflecting the diverse realities many small businesses encounter. One key benefit of Square’s strategy is the more flexible repayment terms tailored to the unique cash flow cycles of small businesses. Instead of relying on a rigid repayment structure, Square allows sellers to pay back more in busy periods and less when business slows. This flexibility provides immediate relief for businesses facing cash flow hurdles, such as supply needs or utility costs, fostering resilience in challenging times. The early outcomes are already promising: nearly half of the sellers who accessed these new loans had never before received a Square Loan offer. Notably, 66% of offers went to businesses with fewer than $25,000 in annual gross payment volume (GPV), further substantiating Square’s mission to empower small players in the market. However, while these innovations present a wealth of opportunities, small business owners should consider some potential challenges. Applying for funding, even through a streamlined process, still requires thorough preparation and understanding of one’s own financial health. Businesses with volatile revenue streams or those in highly competitive industries may find securing loans challenging, even with the new underwriting model in place. Moreover, as Square expands its lending capabilities, it’s crucial for small business owners to maintain an awareness of their financial practices. Adequate record-keeping and an understanding of how cash flow works can be the difference between securing a loan and missing out. Fostering a good relationship with a financial advisor or engaging with Square’s resources might help navigate these waters effectively. In the evolving landscape of small business lending, Square stands out as a frontrunner in creating meaningful pathways to capital. Their use of technology to assess creditworthiness dynamically offers a lifeline to many who have traditionally struggled to access funding. As small businesses adapt to these changes, the promise of sustained growth and community prosperity becomes more tangible. For more detailed information, you can read the original press release here. Image via Google Gemini This article, "Square Expands Lending Access, Empowering More Small Businesses than Ever" was first published on Small Business Trends View the full article
-
Roughly a third of homeowners with a mortgage rate less than 6% would not give up their rate for any reason, according to a survey of 1,000 mortgage holders. View the full article
-
Idea for pause in fighting originated from Donald The President’s team even as he escalated threats against IranView the full article
-
A Iran ceasefire sparked a $20 oil drop and Treasury rally, narrowing the rate-cut window from 18 to 15 months, but key technical resistance levels and a potentially ugly Friday CPI report could still reshape the outlook, according to the head of correspondent business development at AD Mortgage. View the full article
-
For all the advances in data science, artificial intelligence, and behavioral assessments, one hiring ritual remains stubbornly unchanged: the job interview, where candidates are still subjected to awkward brainteasers about golf balls in airplanes, forced to disclose their “biggest weaknesses” to amateur psychologists, asked whether they would keep working after winning the lottery, or made to present to silent panels who seem less interested in evidence of competence than in observing how gracefully applicants endure a mildly humiliating social experiment. Despite decades of research showing that traditional interviews are only moderately reliable predictors of performance, organizations continue to rely on them heavily. In fact, the typical interview still resembles what it looked like decades ago: a loosely structured conversation in which hiring managers form impressions based on intuition, chemistry, and gut feeling. From a scientific standpoint, this is not ideal. Unstructured interviews are vulnerable to a long list of well-documented biases. Interviewers may favor candidates who resemble themselves (“similarity bias”), appear confident or attractive (“halo effects”), or simply fit the cultural stereotype of what a successful employee looks like (“culture fit”). First impressions loom large, even when they are based on thin evidence. Charisma often outperforms competence. And yet, interviews persist. Why? Because hiring managers, like most humans, remain convinced they can “spot talent” when they see it. In other words, the interview is unlikely to disappear anytime soon. The end game Fortunately for candidates, this irrationality does not mean human behavior is unpredictable. As behavioral economist Dan Ariely famously put it, people are “predictably irrational.” That predictability matters, and you can use it to your advantage. Even if interviews are imperfect, there is a growing body of research on how interviewers evaluate candidates and what signals tend to shape their judgments. Understanding those signals does not mean manipulating the system. It simply means avoiding the common mistakes that cause many candidates to underperform, or ensuring that you come across as well as you can. One of the most overlooked opportunities occurs at the very end of the interview, when the interviewer – at times without a proper underlying plan or deliberate strategy – asks a deceivingly simple question: “Do you have any questions for us?” Many candidates treat this moment as a formality. Some (usually the unprepared ones) say “not really.” Others improvise a question on the spot, which rarely has a significant positive impact. Indeed, both approaches are somewhat risky and could result in decreasing candidates’ ratings even after an overall good performance. Studies on interview dynamics suggest that most employers expect candidates to ask questions, and they interpret this behavior as a signal of preparation, motivation, and interest. When candidates decline to ask anything, interviewers often interpret it as a sign of disengagement or lack of curiosity or preparation. At the same time, asking the wrong question (or too many of them) will likely backfire. The difference between leaving a strong impression and undermining one often comes down to a few subtle signals. Five rules With that, here are five basic rules to inform your interview question strategy: First rule: Avoid questions that make the conversation about you A bad type of questions candidates often ask at the end of interviews are typically self-centered, focused on maximizing personal value at the expense of the organization or employer, and, above all, signal a total lack of social skills (lack of awareness of, or interested in acknowledging, the basic etiquette or rules of interaction governing any professional setting). Examples (from most to least acceptable) may include: “What is your working from home policy?” “What would my vacation time be?” “How soon could I be promoted?” “What are the working hours like?” “How quickly could I get a raise?” “If I get bored after a few months, would the company help me find a more interesting role somewhere else?” “Is it acceptable if I continue applying for other jobs while working here, just to keep my options open?” “How flexible are you if I decide I’m not really a morning person?” “Would it be a problem if I occasionally skipped meetings that seem unnecessary to me?” “How soon before I could start delegating most of my work to other people?” To be sure, these may be legitimate concerns. But raising them too early signals that your primary focus is personal gain rather than contribution. It is also a good illustration of a broader point I made in Don’t Be Yourself, authenticity is often overrated as a career strategy. Saying exactly what you think, when you think it, regardless of what others may think, may feel courageous and honest to you, but in professional settings it can simply reveal poor judgment and be a suicidal career move. Successful people don’t just express themselves; they also know when to edit themselves and how to say things to maximize positive effects and minimize negative effects, which requires quite a bit of strategy. A more effective strategy is to instead ask questions that focus on the organization, the team, or the work itself. This signals interest in the role and demonstrates that you are thinking about the broader context. Second rule: Demonstrate preparation One of the easiest ways to impress an interviewer is to show that you have done your homework. Instead of asking generic questions like … “What does the company do?” “What are your priorities?” “How has the role evolved over the past few years” “What would success look like in the first 12 months?” … try referencing recent public information, which signals engagement. For example: “I saw that the company recently expanded into the European market. How does this role contribute to that strategy?” “I noticed the company has been investing heavily in AI and data capabilities. How is that changing the way this team operates day to day?” “I saw your CEO recently emphasized sustainability as a strategic priority. How does that translate into concrete initiatives for this role or department?” Or: “I read about the recent partnership your firm announced. What challenges does that create for the team?” Questions like these demonstrate that you are informed, engaged, and attentive. Third rule: Use questions to signal the traits employers value Smart candidates use the final questions not just to gather information but to highlight desirable traits indirectly. Consider the following examples. To signal curiosity and learning orientation: “What are the most important things someone in this role needs to learn during the first six months?” To signal teamwork and emotional intelligence: “Which teams or stakeholders does this role interact with most closely?” To signal ambition and drive: “What does success look like in this role after the first year?” To signal self-awareness and self-criticism: “What distinguishes people who really thrive here from those who struggle?” To signal adaptability and resilience: “What challenges tend to surprise people when they first take on this role?” Each of these questions subtly communicates something about the candidate asking it. Fourth rule: Listen carefully to the answer Asking the right question is only half the equation. What happens next matters just as much. Strong candidates treat the answer as an opportunity for dialogue rather than simply nodding politely. For example, if the interviewer describes the challenges of the role, you might respond: “That’s interesting. Could you say a bit more about what has made that particularly difficult for the team so far?” “That’s useful context. From what you’ve seen, what distinguishes the people who end up thriving in this role from those who struggle?” “That’s helpful to know. In my previous role we faced something similar when we expanded our client base, and one thing that helped was…” This approach allows you to reinforce your experience without sounding rehearsed. More importantly, it shows that you are paying attention and treating the occasion as an opportunity for smart dialogue and interaction, making the most of it. Similarly, if the interviewer describes a key success factor, you might respond: “That’s interesting; building cross-team relationships was actually a big part of my last project.” “That resonates with me; in my previous role we found that clear communication across functions made a huge difference in delivering results.” “That’s helpful context; in my last position we faced a similar priority, and one of the things that worked well was…” In short, the goal is not to prolong the interview unnecessarily, but rather to connect your experience to what the interviewer values, and showcase your ability to react, improvise, and share relevant experiences on the fly. Fifth rule: Don’t overdo it Candidates who ask no questions risk appearing uninterested. But candidates who ask too many questions risk appearing unfocused or overly demanding. A good rule of thumb is to ask one or two thoughtful questions. Remember that interviewers are usually busy. Turning the last five minutes of the interview into a 15-minute interrogation is unlikely to win you many points. Curiosity is good; monopolizing the conversation is not, and could make you come across as a self-centered narcissist or someone with zero self-awareness if you fail to get the signals that is timed to shut up. Equally important is the tone. Questions should feel prepared but not scripted. If they sound rehearsed, they may come across as performative. If they are entirely improvised, they may reveal a lack of preparation. The goal is to appear thoughtful, engaged, and authentic, which requires you to pay a great deal of attention to how interviewers evaluate you. The worst possible response? Of course, there is one response that consistently creates a poor impression: “No, I think you’ve covered everything.” This answer suggests either a lack of curiosity or a lack of preparation. Neither interpretation works in your favor. The real purpose of the question? In theory, the opportunity to ask questions at the end of an interview exists to help candidates evaluate whether the role suits them. In practice, it often functions as another evaluation moment. Interviewers are not just listening to what you ask. They are asking themselves what your question reveals about you: your curiosity, your priorities, your preparation, and your interpersonal skills. In that sense, the final question is less about information gathering and more about signaling. The irony is that while the science of hiring has advanced enormously (from predictive analytics to AI-assisted assessments) the human interview remains stubbornly subjective. But once you accept that reality, the strategy becomes clear. You cannot eliminate the biases embedded in interviews. But you can learn to navigate them. And sometimes, the difference between a forgettable interview and a memorable one comes down to something as simple as asking the right question at the very end. View the full article