Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
When defining the roles of franchisors and franchisees, it’s crucial to clarify their distinct responsibilities and the nature of their relationship. The franchisor, as the brand owner, provides the framework and support for success, whereas the franchisee manages day-to-day operations within that framework. Comprehending these roles helps establish a solid partnership. As you explore these aspects further, you’ll uncover critical elements that contribute to a thriving franchising business model. Key Takeaways A franchisor is the brand owner who creates and manages the franchise system, offering support and resources to franchisees. Franchisees purchase rights to operate a business under the franchisor’s brand, managing daily operations independently. The Franchise Disclosure Document (FDD) outlines responsibilities, obligations, and operational guidelines for both franchisor and franchisee. Legal compliance is essential for both parties, ensuring adherence to federal and state franchising laws and regulations. Franchise agreements define the relationship, rights, and responsibilities, making legal support crucial for understanding and navigating these contracts. Understanding the Franchisor Role Comprehending the role of a franchisor is vital for anyone considering entering the franchise business. A franchisor is the original brand owner who develops the business model and operational systems that franchisees replicate. To define franchisor and franchisee clearly, the franchise relationship involves the franchisor providing training, ongoing support, and resources to guarantee franchisee success during maintaining brand integrity. They likewise collect initial franchise fees and ongoing royalties, which are critical for their revenue. Through the Franchise Disclosure Document (FDD), the franchisor discloses its responsibilities and the operational framework of the franchise. This structured approach guarantees compliance with established systems, allowing franchisees to deliver a consistent customer experience across all locations, reinforcing the brand’s reputation and reliability. Key Responsibilities of a Franchisor The foundation of a successful franchise system lies in the key responsibilities of a franchisor, which are essential for guaranteeing consistent brand performance and franchisee success. Here are four primary responsibilities you should know: Develop a Proven Business Model: Create and document a business model in the Franchise Disclosure Document (FDD) to verify brand credibility. Provide Training and Support: Offer thorough training and ongoing support to equip franchisees with the tools and knowledge they need to succeed. Protect the Brand: Maintain and safeguard the registered trademark, which differentiates your franchise from competitors. Establish Operational Systems: Set up business systems that yield reliable results, helping franchisees maintain brand standards and achieve profitability. The Franchisee’s Role Explained Understanding the role of a franchisee is crucial for anyone considering this business model. As a franchisee, you purchase the right to operate a franchise, utilizing the established brand and business model of the franchisor. You’re responsible for managing daily operations independently as you follow the franchisor’s operational guidelines and brand standards. To maintain this relationship, you’ll pay an initial franchise fee and ongoing royalty fees, typically ranging from 4% to 8% of gross sales. The franchisor provides thorough training covering operational procedures and marketing strategies, along with access to proprietary systems. Furthermore, you’ll contribute to national advertising campaigns and manage local marketing efforts within the franchisor’s framework, ensuring your business aligns with the overarching brand. Responsibilities of the Franchisee Even though operating a franchise offers numerous benefits, it also comes with specific responsibilities that franchisees must diligently fulfill. To succeed, you need to focus on the following key areas: Financial Obligations: Pay the initial franchise fee and ongoing royalty fees to maintain your rights to operate under the brand. Operational Management: Manage day-to-day expenses, including employee salaries, rent, and other costs vital for running your business effectively. Brand Standards: Uphold the brand’s reputation by ensuring consistency and quality across all franchise locations. Adherence to Guidelines: Follow the operational systems and guidelines outlined in the franchise operations manual, while contributing to national advertising campaigns and handling local marketing efforts. Meeting these responsibilities is critical for your franchise’s success. The Franchisor-Franchisee Relationship In the franchisor-franchisee relationship, both parties play crucial roles that contribute to mutual success. The franchisor sets the framework with a proven business model and provides fundamental support, whereas the franchisee brings local knowledge and manages daily operations. Comprehending these dynamics can improve collaboration and guarantee the franchise thrives within its market. Symbiotic Partnership Dynamics The franchisor-franchisee relationship thrives on a symbiotic partnership, where each party plays a crucial role in the overall success of the brand. This dynamic relies on four key factors: Brand Recognition: Franchisors provide a recognizable brand, helping franchisees attract customers. Operational Support: Franchisors offer systems and guidelines, enabling franchisees to manage daily operations efficiently. Local Insight: Franchisees contribute valuable knowledge of their local markets, tailoring strategies to meet community needs. Communication: Effective communication between franchisors and franchisees nurtures clarity, preventing confusion and enhancing productivity. Roles and Responsibilities Defined Understanding the roles and responsibilities within the franchisor-franchisee relationship is essential for a successful partnership. The franchisor develops and supports the business model, meanwhile you, as the franchisee, implement it in your local market. This creates a symbiotic relationship that benefits both parties. You’re responsible for daily operational expenses and must adhere to the brand standards established by the franchisor, ensuring consistency and reputation. The franchisor, in turn, provides thorough training and ongoing support, equipping you with the necessary tools and knowledge to thrive. Clear definitions of these roles help mitigate potential legal issues, facilitating smoother operations. Furthermore, the franchisor collects initial fees and ongoing royalties, allowing you to benefit from an established brand and a proven business model. Operational Support Structure Operational support serves as the backbone of the franchisor-franchisee relationship, guaranteeing that both parties can effectively collaborate toward shared business goals. This support not only aids franchisees thrive but also preserves brand integrity. Here’s what you can expect: Training Programs: Extensive training equips you with vital skills for managing your franchise effectively. Ongoing Assistance: Regular evaluations and updates to the operations manual guarantee adherence to brand standards and best practices. Marketing Support: Access to marketing materials and strategic guidance aids in maintaining consistent brand messaging. Clear Communication: Defined roles and open lines of communication prevent misunderstandings and align business objectives. Legal Framework in Franchising When you enter the realm of franchising, comprehending the legal framework is crucial. You’ll need to familiarize yourself with the Franchise Disclosure Document (FDD), which lays out critical information about fees, obligations, and the franchise agreement itself. Compliance with federal and state laws is key, as it safeguards your interests and guarantees a smooth partnership with the franchisor. Franchise Disclosure Document Essentials The Franchise Disclosure Document (FDD) serves as a significant legal instrument in the franchising environment, providing fundamental information to potential franchisees. Comprehending the FDD is essential as it outlines important aspects of the franchise relationship. Here are some key components you should know: Disclosure Items: The FDD contains 23 specific items detailing franchise agreements, fees, and obligations. Timing: You must receive the FDD at least 14 days before signing any agreements or making payments. Updates and Registration: The FDD needs annual updates and registration in states with franchise laws, including specific state modifications. Risks of Non-Compliance: Failing to follow FDD regulations can lead to serious legal repercussions for franchisors, including lawsuits. Compliance With Franchise Laws Maneuvering through compliance with franchise laws is essential for both franchisors and franchisees, as it guarantees a clear comprehension of legal obligations and protections. Franchisors must adhere to federal and state laws, making sure their Franchise Disclosure Document (FDD) includes 23 required items and is provided to prospective franchisees at least 14 days before any agreements are signed or fees are collected. Updating the FDD annually is necessary, along with registering it in states where you plan to offer franchises. Multi-state compliance often requires state-specific addendums and modifications. To navigate these intricacies, seeking legal assistance is imperative, as it helps ascertain that franchise agreements and documentation are properly prepared and compliant with various regulations. Franchise Agreement Requirements A franchise agreement is an important document that establishes the legal framework for the relationship between a franchisor and a franchisee. This binding contract outlines various aspects significant to both parties. Here are some key requirements: Franchise Disclosure Document (FDD): Must be provided at least 14 days before signing, detailing 23 required disclosure items. Scope of Franchise: Clearly defines what the franchise entails, including operational guidelines. Fees and Royalties: Specifies the financial obligations, including initial fees and ongoing royalties. Training and Support: Outlines the training provided by the franchisor and the franchisee’s commitment to maintaining brand standards. Compliance with federal and state laws is crucial, ensuring the FDD is registered where necessary. Advantages of Franchising for Franchisees When you consider franchising, you’ll find several advantages that can make it an attractive option for aspiring business owners. First, you gain immediate access to an established brand name, boosting consumer trust and leading to higher initial sales than starting a new business. By using the franchisor’s proven business model, you reduce your risk of failure, as the concept is already validated in the market. In addition, you’ll receive extensive training and ongoing support, equipping you with necessary skills, even without prior experience. You can also benefit from the franchisor’s purchasing influence, resulting in cost savings on supplies. Finally, you’ll participate in national marketing campaigns funded by the franchisor, enhancing brand visibility and attracting more customers to your location. Disadvantages of Franchising for Franchisors Franchising can come with significant disadvantages for you as a franchisor. You might find that you lose some control over franchise locations since franchisees operate independently, which can lead to inconsistencies in how your brand is represented. Furthermore, the ongoing support demands can be taxing, as you’ll need to allocate resources and time to train and assist franchisees, ensuring they meet your standards. Loss of Control As franchisors expand their networks, they often face a significant challenge: the loss of control over individual franchise locations. Franchisees operate independently, which can lead to inconsistencies in brand representation and service quality. This situation can impact your brand’s overall reputation and success. Here are some key issues you might encounter: Inconsistent customer experiences across locations. Difficulty maintaining uniform standards and practices. Potential disputes over operational guidelines, leading to legal issues. Challenges in managing compliance with franchise agreements. As you scale your system, these factors can leave you vulnerable to breaches and negatively affect your market position, complicating your ability to uphold the brand’s integrity. Ongoing Support Demands The loss of control over franchise locations often leads to significant ongoing support demands for franchisors. You’re obligated to provide ongoing training and assistance to franchisees, which can strain your operational capacity. This continuous demand for support can increase your operational costs, impacting profitability and strategic focus. You’ll need to regularly update training materials and operational systems to keep up with industry changes, requiring ongoing investment. Furthermore, ensuring franchisee compliance with brand standards creates an additional burden, as you must monitor performance and proactively address issues. Standardizing support across diverse franchise locations can be challenging, leading to inconsistencies that may affect your brand reputation and overall franchise performance. Balancing these demands is essential for effective franchisor management. Steps to Franchise Your Business When considering how to franchise your business, it’s vital to first evaluate its readiness for such an expansion. Follow these important steps to get started: Assess scalability, profitability, and operational systems to guarantee your business can be effectively replicated by franchisees. Prepare a compliant Franchise Disclosure Document (FDD) with all required disclosure items, making sure it’s provided to potential franchisees 14 days before any agreements or payments. Create a confidential operations manual that details your brand’s purpose, operational standards, and guidelines for franchisees to uphold consistency and quality. Register your trademarks with the United States Patent and Trademark Office (USPTO) and establish a legal entity to manage franchise operations, protecting your brand as you expand. Importance of Brand Consistency Franchising your business opens up opportunities for growth, but it additionally requires a strong emphasis on brand consistency to guarantee success. A consistent brand image is vital, as it guarantees every franchise location delivers a uniform experience. This uniformity strengthens customer loyalty and recognition across different markets. As a franchisee, you’re obligated to follow the franchisor’s established branding standards, which include logo usage, product offerings, and marketing materials. Adhering to these guidelines protects the overall brand equity. Regular brand audits and training sessions conducted by franchisors help you maintain these standards. Research shows that businesses with strong brand consistency can see a 20% increase in sales, making brand consistency critical for long-term success in franchising. Navigating Real Estate in Franchising Steering through the real estate environment in franchising can be a complex task, especially since choosing the right location is crucial to your franchise’s success. Here are key points to reflect on as you navigate this setting: Site Selection: Work closely with your franchisor’s team to evaluate potential locations based on market analysis. Lease Negotiation: Negotiate and sign leases, ensuring they align with your franchisor’s guidelines for consistency. Local Insights: Balance your local market knowledge with the franchisor’s brand objectives to make informed decisions. Lease Management: Stay compliant with lease terms through regular oversight from your franchisor, including site inspections and assistance during renewals. Following these steps can streamline your real estate decisions and contribute to your franchise’s overall success. Legal Support for Franchisees Maneuvering the legal terrain of franchising can be challenging, so having robust legal support is important for franchisees. Legal assistance helps you navigate franchise agreements, ensuring compliance with federal and state laws that define your rights and obligations. You’ll need guidance in preparing and reviewing the Franchise Disclosure Document (FDD), which is significant to receive 14 days before signing any contracts or making payments. Furthermore, legal support is critical during lease negotiations, as you’ll be responsible for managing lease agreements in spite of franchisor guidelines. Ongoing legal help can likewise be beneficial in resolving disputes with franchisors or landlords, which safeguards your investment and maintains operational continuity. Consider reaching out to specialized firms like LPJ Legal for customized advice. Frequently Asked Questions What Is the Difference Between a Franchisee and a Franchisor? A franchisor owns the brand and business model, granting you, the franchisee, the right to operate under that name. During you pay initial fees and ongoing royalties, the franchisor provides training, support, and brand standards. You manage daily operations and expenses at your location. The relationship is mutually beneficial, with the franchisor relying on your local execution and you benefitting from an established brand and proven business practices to grow your venture. Which Is Correct, Franchiser or Franchisor? The correct term is “franchisor,” which identifies the brand owner granting rights to franchisees. “Franchiser” isn’t recognized in the industry and can cause confusion, especially in legal documents like the Franchise Disclosure Document (FDD). Using “franchisor” emphasizes the role of the entity creating and supporting the franchise system. It’s essential to use accurate terminology to guarantee clarity in agreements and discussions within the franchising environment. What Is the Definition of a Franchisor in the Context of Franchising? A franchisor is the original business owner who establishes a brand and operational system for others to operate under its name. You’ll find that a franchisor provides training, support, and resources to guarantee that franchisees maintain brand integrity. In return, the franchisor collects initial fees and ongoing royalties. Moreover, they develop marketing strategies and guidelines that franchisees must follow, protecting the brand’s reputation and promoting consistency across all locations. Which Document Provides Comprehensive Information About the Franchisor and the Franchise System to Potential Franchisees? The document you’re looking for is the Franchise Disclosure Document (FDD). It provides essential details about the franchisor, the franchise system, and the obligations of both parties involved. You’ll find information on financial performance, fees, and the franchise agreement within its 23 disclosure items. Conclusion In conclusion, comprehending the roles of franchisors and franchisees is vital for a successful partnership. The franchisor provides fundamental support and resources, whereas the franchisee manages daily operations within established guidelines. By recognizing these responsibilities and maintaining brand consistency, both parties can thrive. Moreover, maneuvering legal frameworks and real estate considerations can improve the franchise’s success. A clear comprehension of these elements will empower you to effectively engage in the franchising environment. Image via Google Gemini This article, "How to Define Franchisor and Franchisee in a Comprehensive Guide" was first published on Small Business Trends View the full article
-
Fights over regulation could reshape the US federal system of governmentView the full article
-
Modern accounting systems offer a variety of crucial features that greatly improve financial management. They automate invoicing and transaction entries, which reduces manual errors and saves time. With real-time reporting and customizable dashboards, you can make informed decisions quickly. Furthermore, these systems integrate seamlessly with ERP and CRM applications, enhancing workflow efficiency. As we explore these key features further, you’ll discover how they can transform your approach to financial operations. Key Takeaways Modern accounting systems automate invoicing and payment reminders, significantly reducing manual tasks and errors while saving time for employees. They provide real-time financial insights with customizable reporting options, enabling informed decision-making and trend analysis for better business management. Integration with ERP and CRM systems enhances operational efficiency by centralizing financial data and streamlining workflows across departments. Compliance management features ensure adherence to financial regulations, with automated updates and secure data protection measures such as encryption and multi-factor authentication. Cloud-based benefits improve accessibility for remote teams, facilitating real-time collaboration and automatic upgrades while lowering IT costs. Core Features of Modern Accounting Systems Modern accounting systems are essential tools for businesses looking to improve their financial management. These systems define accounting system processes that guarantee accuracy through methods like double-entry accounting. You’ll find two types of accounting—financial and managerial—each serving different purposes but both benefiting from modern systems. Key features include accounts receivable (AR) and accounts payable (AP) functionalities, which automate invoice processing and payment tracking, augmenting cash flow management. Advanced accounting software often includes optional tools for payroll management, inventory control, and project management, allowing you to tailor the system to your specific needs. Moreover, real-time reporting and analytics provide customizable financial statements and performance metrics, aiding in informed decision-making. Integration with other business applications, like ERP and CRM systems, further improves data sharing and minimizes manual data entry, eventually enhancing overall operational efficiency. These core features make modern accounting systems indispensable for today’s businesses. Automation and Streamlining Financial Processes In today’s fast-paced business environment, automating financial processes is crucial for efficiency. With solutions like automated invoicing, real-time financial insights, and streamlined expense tracking, you can save time and reduce errors in your accounting tasks. Embracing these modern tools not just simplifies your workflows but likewise improves accuracy, allowing you to focus on more strategic initiatives. Automated Invoicing Solutions Automated invoicing solutions transform the billing process by eliminating the need for manual invoicing tasks, which can be both time-consuming and prone to errors. These systems automatically generate and send invoices, considerably reducing the time spent on tedious manual entries. Featuring recurring invoices and automated payment reminders, they help guarantee timely revenue collection and can reduce overdue payments by up to 30%. Integration with accounting software allows for seamless tracking of customer payments, enhancing financial accuracy and cash flow management. Moreover, automated invoicing decreases errors linked to manual data entry, leading to more reliable financial records and fewer disputes with customers. Studies indicate that businesses utilizing these solutions can save an average of 10 hours per month per employee, enabling a focus on strategic initiatives. Real-Time Financial Insights Even though many businesses struggle with outdated financial reporting methods, real-time financial insights provided by advanced accounting systems can greatly improve decision-making processes. These systems automate data collection and analysis, allowing you to swiftly identify trends and performance metrics. You’ll reduce the time spent on manual entry and minimize errors through streamlined invoicing, expense tracking, and bank reconciliation. Continuous access to updated financial data means you can respond timely to opportunities or issues. Advanced reporting features offer customizable dashboards, making it easy to interpret performance at a glance. Integration with other business applications provides an all-encompassing view of business health. Feature Benefit Importance Automated Reporting Saves time on data entry Boosts efficiency Custom Dashboards Quick performance overview Aids in strategic decisions Continuous Updates Immediate access to data Supports timely responses Error Reduction Fewer mistakes in records Improves accuracy Cross-Application Links Holistic view of finances Streamlines workflows Streamlined Expense Tracking Effective expense tracking is essential for any business aiming to maintain financial health and optimize operations. Modern accounting systems automate this process by syncing with your Chase accounts, allowing automatic transaction reconciliation. This reduces manual entry time and minimizes errors. They often include automated invoicing features, enabling you to set up recurring invoices and reminders, which streamlines cash flow management. Advanced tools categorize transactions in real-time, giving you immediate visibility into spending patterns and helping identify cost reduction opportunities. Many systems offer mobile access, allowing you to capture and upload receipts on-the-go, enhancing accuracy in reporting. Real-Time Financial Insights and Reporting In today’s fast-paced business environment, having immediate access to financial data is critical for making informed decisions. Modern accounting systems excel in providing real-time financial insights by integrating data from various business applications. This allows you to instantly access key performance metrics and cash flow status, enhancing agility in your operations. With customizable reporting features, you can generate customized reports like income statements and balance sheets to meet specific analytical needs. Graphical summaries within these reporting tools visually represent financial data, making it easier to identify trends and patterns. Furthermore, advanced analytics capabilities support cost predictions and financial forecasting. Here’s a summary of the key features: Feature Description Real-Time Insights Immediate access to financial data Customizable Reporting Customized reports for specific needs Graphical Summaries Visual representation of financial trends Advanced Analytics Support for cost predictions and forecasting Continuous Monitoring Quick identification of performance issues Cloud-Based Architecture and Benefits As businesses increasingly embrace digital transformation, cloud-based accounting systems have emerged as a crucial solution for managing financial operations. These systems markedly lower IT costs and reduce technology risks by eliminating the need for on-premises hardware and maintenance. With automatic upgrades and easier management, you can improve productivity, allowing your team to focus on core activities instead of IT issues. Cloud architecture provides the flexibility to choose best-in-class solutions, avoiding the limitations of traditional software suites. By centralizing financial information in the cloud, you streamline processes, reduce manual data entry, and boost operational efficiency. Accessing your financial data through cloud platforms enables real-time collaboration and decision-making from any location, improving accessibility for remote teams. Integration With Other Business Applications Even though you may be focused on optimizing your financial operations, integrating modern accounting systems with other Intuit applications can greatly enhance your overall efficiency. These systems seamlessly connect with CRM and ERP platforms, providing a unified view of your financial health. Real-time data exchange allows for accurate and up-to-date financial reporting, markedly reducing manual data entry and the potential for errors. Advanced Features for Enhanced Management In today’s fast-paced business environment, advanced accounting systems offer significant advantages through automation and efficiency. By streamlining tasks like invoicing and payment processing, you can minimize errors and save valuable time. Moreover, real-time financial insights and customizable reporting options enable you to make informed decisions quickly, enhancing your overall management capabilities. Automation and Efficiency Modern accounting systems improve automation and efficiency, fundamentally transforming how Intuit businesses manage their financial processes. By automating transaction entry, invoicing, and payment tracking, these systems considerably increase operational efficiency and cut labor costs associated with manual tasks. Automation in addition reduces data entry errors by up to 80%, ensuring greater accuracy in financial reporting and compliance with accounting standards. Features like automatic bank reconciliations and recurring invoicing can save accountants an average of two hours daily, enhancing productivity. Moreover, integration with SAP systems streamlines workflows and eliminates redundant data entry, improving the return on investment for accounting functions. Automated reporting capabilities provide customizable dashboards, enabling quick decisions and effective trend analysis for better business management. Real-Time Financial Insights Real-time financial insights are vital for businesses aiming to stay agile in today’s fast-paced market. Modern accounting systems provide immediate access to cash flow and performance metrics, enabling swift decision-making. Advanced reporting tools create customizable dashboards that visually represent important data, making it easier to spot trends and anomalies. Integration with other business applications improves data analysis, allowing you to capitalize on new opportunities and adapt to market changes quickly. By centralizing financial data, these systems eliminate silos, providing a single source of truth that supports collaboration and strategic planning across teams. Feature Benefit Instant Data Access Quick decision-making Custom Dashboards Easy identification of trends Centralized Information Improved collaboration Customizable Reporting Options Customizable reporting options are essential features in accounting systems that empower businesses to present financial data in a way that aligns with their unique needs. With these advanced features, you can create role-based dashboards that allow real-time monitoring of key metrics customized for different departments or management levels. Not only can you generate standard reports like income statements and balance sheets, but you have the flexibility to design unique reports focusing on specific financial areas or projects. Moreover, the capability to perform trend analysis through customizable reports helps in identifying performance metrics over time. Many modern accounting systems even support integration with other business applications, ensuring thorough data gathering that improves reporting accuracy and depth of insights. Compliance and Security Measures in Accounting Systems As businesses navigate the intricacies of financial regulations, effective compliance and security measures in accounting systems become vital. Modern systems integrate compliance management features that automate adherence to both regional and international financial regulations. This automation reduces the burden on your organization as it grows. To protect sensitive financial data from unauthorized access and cyber threats, these systems implement robust security measures, including encryption and multi-factor authentication. Regular updates and patches are fundamental for maintaining compliance, ensuring that your software stays aligned with evolving tax laws and accounting standards. Moreover, many platforms offer audit trails that track changes and access to financial data, enhancing transparency and accountability. Compliance reporting features streamline the generation of necessary documents and reports, making it easier for you to meet regulatory requirements efficiently. Implementing these measures not only safeguards your business but furthermore nurtures trust with stakeholders and clients. Frequently Asked Questions What Are the Features of the New Accounting System? The new accounting system includes several crucial features. It automates invoicing and payment processing, making accounts receivable and accounts payable management efficient. You’ll benefit from real-time financial insights through advanced reporting capabilities, which allow you to customize reports easily. The cloud integration provides flexibility and cost savings, letting you access data from anywhere. Furthermore, routine tasks like payroll calculations are automated, reducing errors and manual effort in your financial operations. What Is the Modern System of Accounting? The modern system of accounting leverages cloud technology, providing real-time access to financial data. You’ll notice automation plays a vital role, minimizing manual data entry and simplifying tasks like invoicing and expense tracking. Advanced analytics tools offer insights into financial performance, supporting informed decision-making. Integration with other business applications improves operational efficiency, as well as scalability guarantees that the system meets the needs of both small businesses and larger enterprises as they expand. What Are the 5 Main Components of an Accounting System? The five main components of an accounting system include the general ledger, accounts receivable, accounts payable, chart of accounts, and reporting tools. The general ledger acts as the central hub for financial data, whereas accounts receivable and accounts payable manage incoming and outgoing payments. The chart of accounts categorizes transactions for reporting, and reporting tools generate financial statements and analyses, helping you make informed decisions about your business’s performance. What Are Key Features of Accounting Software? When considering key features of accounting software, you’ll find functionalities like automated invoicing, which streamlines billing processes and improves cash flow. The software likewise supports accounts receivable and accounts payable tracking, allowing efficient management of customer payments and vendor invoices. Furthermore, customizable reporting tools enable you to generate specific financial reports, helping you analyze performance. Integration with other business applications further boosts operational efficiency by providing a complete view of your financial data. Conclusion In summary, modern accounting systems offer crucial features that improve financial management. By automating processes, providing real-time insights, and ensuring secure cloud access, these systems streamline operations. Their ability to integrate with other business applications further enhances efficiency, as advanced features support better decision-making. Prioritizing compliance and security, these systems empower businesses to adapt to evolving financial environments. Adopting such technologies can greatly benefit organizations, making financial management more effective and reliable. Image via Google Gemini This article, "Key Features of Modern Accounting Systems" was first published on Small Business Trends View the full article
-
Mike Kortas will be adding a separate mortgage servicing company and hiring NEXA loan officers to assist with the process and give them customer insights. View the full article
-
Salesforce has unveiled an enhanced version of Slack, a widely recognized communication platform, aiming to help small businesses streamline their operations and enhance collaboration. The updated features come at an opportune moment for small business owners who are navigating challenges ranging from remote work to the need for better team communication. One of the standout improvements is an advanced user interface designed to make navigation more intuitive. This simplification can mean a significant reduction in the time employees spend searching for information, boosting overall productivity. “We’re focused on creating a seamless experience that helps teams focus on what really matters,” said a Salesforce representative, emphasizing the importance of efficiency in the often hectic lives of small business owners. For small businesses, the practical applications of Slack’s new capabilities are plentiful. The integration of a customizable sidebar allows users to access frequently used tools and channels faster, which can enhance focus and minimizes distractions. Additionally, with the introduction of improved search features, team members can find the information they need swiftly, a time-saver for those juggling multiple responsibilities. Collaboration is further enhanced through the platform’s improved channel organization. Teams can categorize conversations and projects, making it easier to locate discussions relevant to various business functions. This organizational strategy can be particularly beneficial for small enterprises where team members often wear multiple hats and may need to switch context quickly. Slack’s revised interface also includes new automation features that help streamline repetitive tasks. Small business owners could automate notifications for project updates or deadlines, improving communication efficiency without adding to their workload. As one small business owner pointed out, “The ability to automate those little reminders means I can focus on growth rather than administration.” Despite these benefits, small business owners should be cautious about potential challenges while adopting the new Slack. Transitioning to any new system takes time, and team members may initially face a learning curve. Training employees to effectively use the updated features will require investment and commitment, which may be a concern for businesses operating on tight budgets. Another consideration is the risk of information overload. With easier access to channels and information, team members might find themselves bombarded with notifications and updates. Establishing guidelines on how to use Slack efficiently is crucial, ensuring that team members are not overwhelmed by messages that could distract them from their core tasks. Interim user feedback on the updated Slack is encouraging, with many early users praising the effort to keep the user experience simple and engaging. “Slack has become the nerve center for our communication. The new changes make everything so much easier to handle,” said another user. Their experience highlights how effective tools can significantly enhance team dynamics and productivity. For small business owners considering a shift to the new Slack, it is essential to evaluate your specific communication needs. Integrating a communication tool that truly fits your team’s workflow can not only improve collaboration but also drive overall business performance. In addition, with the increased focus on remote working arrangements, the upgraded Slack can serve as a virtual hub for teams spread across different locations. By facilitating open communication, small businesses can better foster team cohesion, even when team members are geographically dispersed. In summary, the new Slack offers exciting features tailored to enhance productivity and collaboration for small businesses. While there may be challenges in implementation, the potential benefits for communication and team efficiency could set businesses on a path to growth. As Salesforce continues to innovate, small business owners have an opportunity to leverage such tools to adapt and thrive in an ever-evolving landscape. For more information, you can read the full Salesforce announcement here. Image via Google Gemini This article, "Slack Unveils Major Overhaul to Enhance Team Collaboration" was first published on Small Business Trends View the full article
-
San Francisco's median house price jumped to a record $2.15 million in March, up 18% from a year earlier as wealth generated by artificial intelligence startups flooded the city, according to brokerage Compass Inc. View the full article
-
Market performance tends to dominate the conversation about risks to a retirement plan. But spending shocks can also curb a retirement portfolio’s longevity. In Morningstar’s research, we examined the implications of two major types of spending shocks: unanticipated early retirement and uninsured long-term care expenses at the end of life. The former may necessitate spending over a longer period, often with higher healthcare costs in the pre-Medicare years, while the latter can translate into an effective “balloon payment” toward the end of life. Early retirement Early retirement — before the standard age of 65 — is an increasingly common scenario. While Social Security’s full retirement age is currently between 66 and 67, the average retirement age is 62, according to a study from MassMutual. That’s corroborated by Social Security filing data, which show that roughly 25% of retirees take Social Security when it’s first available at age 62, and 15% file at 63 or 64. Nearly half of the retirees surveyed by MassMutual said they had retired earlier than planned; commonly cited reasons included layoffs, being able to retire sooner than expected, or illness or injury. Early retirement has significant implications for retirement spending, with longer drawdown periods necessitating lower spending to maintain a high likelihood of not running out later on. In our base-case spending simulation, expanding the drawdown period from 30 to 35 years reduces the starting safe withdrawal rate from 3.9% to 3.5%. Stretching the time spending horizon to 40 years takes the starting safe withdrawal rate to 3.2%. Keeping withdrawals low in early retirement may be challenging on a few levels, however. First, individuals aren’t eligible for Medicare coverage until age 65, so bridging healthcare coverage in the intervening years has the potential to increase spending. Insurance coverage for 62- to 65-year-olds from the ACA marketplace averaged between $800 and $1,200 a month in 2025, according to data from Boldin. Meanwhile, Cobra coverage (extending workplace-provided coverage) for people 62 to 65 averaged $700 to $1,500 a month. For a 62-year-old taking a safe withdrawal rate of 3.5% ($35,000) from her $1 million portfolio, healthcare costs would consume roughly a third of those withdrawals. Further complicating matters for young retirees is that many individuals wish to delay Social Security to increase their eventual benefits. At the same time, delaying Social Security can necessitate higher withdrawals in the early part of retirement, thereby imperiling the portfolio’s ability to last over the longer time horizon. Long-term care spending Just as early retirement can cause a spending shock at the front end of retirement, long-term care costs can prompt a spending shock later in life. A 2025 report authored by Spencer Look and Jack VanDerhei of the Morningstar Center for Retirement & Policy Studies found that 43% of baby boomers will incur long-term care costs, with the average cost of that care $242,373. The likelihood of needing care correlates with longevity: While just 24% of men and 27% of women who die at age 75 will require long-term care, 52% of men and 60% of women who die at age 95 will require long-term care. Incurring sizable long-term care costs can have catastrophic effects for a financial plan: The Morningstar study found that when long-term care costs are included in the analysis of the viability of retirement assets, 41% of older-adult households that incur long-term care costs are likely to run out of funds. Older adults can take different approaches to address this risk. They might set aside a separate long-term care “bucket,” separate from their spending portfolios. Others may plan to use home equity. Alternatively, those with very tight finances might create a spending plan to cover their costs during their healthy years, then rely on government resources if they require long-term care after that. The final option for handling the cost of long-term care is to build it into the spending plan, spending less throughout retirement to account for the possibility of a spike later in life. To help model a long-term care shock, we assumed spending in years 29 and 30 to be twice what spending was in year 28. Factoring in that type of shock, the starting safe withdrawal percentage for the person retiring and claiming Social Security at age 67 is 3.5%, versus 3.9% for our base case without that shock. This article was provided to The Associated Press by Morningstar. For more retirement content, go to https://www.morningstar.com/retirement. ChristineBenz is director of personal finance and retirement planning for Morningstar and co-host of The Long View podcast. Related Links What to Do in the Five Years Before You Retire https://www.morningstar.com/retirement/emily-guy-birken-what-do-five-years-before-you-retire What You Need to Know About Annuities https://www.morningstar.com/retirement/what-you-need-know-about-annuities 10 Sources of Emergency Cash, Ranked From Best to Worst https://www.morningstar.com/personal-finance/10-sources-emergency-cash-ranked-best-worst —Christine Benz of Morningstar View the full article
-
Iranians fear The President’s threats against “whole civilization” are part of an onslaught on fabric of nationView the full article
-
I’ve heard it too many times to count, “We’ve never done PR before and are getting ready to announce [insert your major milestone of choice]” Too often, businesses wait until they have big news to begin thinking about strategic communications. They’re about to close a funding round, launch a product, or enter a new market. But here’s the thing: If you’re just starting to think about PR now, you’re already behind. After nearly 20 years leading communications for fintech companies and financial institutions, I can confidently say that the organizations that benefit most from major announcements began building visibility long before the moment arrived. WHY COMPANIES START TOO LATE Teams often assume their news will attract attention. That their announcement will prove their credibility. That the story will tell itself with the build it and they will come mentality. That’s seldom how it works. The mistake is assuming trust can be built on the same timeline as attention. These moments reveal whether credibility already exists. Psychologists call this tendency to underestimate how long it takes to build something meaningful the planning fallacy. In business, it shows up in many ways. One example is believing that trust can be established the moment people start paying attention. Think about your own reaction to news. When a company you’ve never heard of announces a major milestone, you might ask “Who is this?” and quickly return to scrolling. But when a company you’ve seen and heard about shares similar news, your reaction is different. That difference is momentum. 5 SIGNS IT’S TIME TO INVEST IN PR So how do you know when it’s time to invest in PR? Here are five signs. 1. You have something to say. One of the clearest signs a company is ready for PR is having a point of view. You need to have something to say and be able to connect it to what you do. That means being able to explain what’s changing, what’s broken, and why your approach matters now. It requires proof points and substance, not just commentary. This matters even more in the age of AI search and discovery. Research from Muck Rack shows generative AI relies heavily on earned media, making media validation essential for modern brand discovery. Your narrative will take shape with or without you. The question is whether you’re actively taking steps to shape it. 2. You know your story and what makes you different. Companies ready for PR can clearly articulate what makes them different, why it matters, and how it connects to their broader goals. Without that clarity, early communications efforts often feel reactive and fragmented. With it, every media interaction reinforces the same story. In a conversation with me, Shahzeb Khan, head of marketing for the Americas at Amdocs, put it this way: “A fundamental question I ask myself is whether our story is differentiated and not just noise, credible and backed by facts and observations, and whether it advances a meaningful perspective in the market and supports a strategic business priority.” 3. Leadership is aligned and willing to commit. PR cannot succeed as a side project. Crucially, it requires leadership participation. Khan noted that leadership alignment can be the catalyst for thought leadership. But that thought leadership must come from somewhere—from executives willing to offer perspective, speak with media, and contribute to industry conversations. Without that participation, momentum stalls before it starts. And it must be a long-term commitment. PR isn’t a one-time campaign. Once you’re ready for it, it becomes an ongoing part of how the company communicates with the market. 4. Your team can support the attention you create. You also need to ask whether your organization is prepared to support the attention PR creates. Do you have a strong website? Clear messaging? A responsive sales team? Supporting content? And can you move quickly when opportunities appear? Kenon Chen, EVP of strategy and growth at Clear Capital, described to me the moment he knew they were ready: “We had a marketing team ready to support and capitalize on successful PR activities. The right team ready to go after a bigger mission is the perfect time to lean into proactive communications.” 5. Your audience encompasses more than just customers. Eventually, growth depends on influencing decision-makers beyond your customer base—analysts, investors, media, partners, and regulators. “After clearly defining our three-year company strategy, we realized that we needed [to have] greater influence on multiple industry stakeholders beyond potential clients to achieve our goals,” said Chen. MOMENTUM DOESN’T WAIT These five signs don’t all appear at once. When most are true, that’s your moment. The mistake is waiting for perfect conditions that never arrive. Momentum builds through consistency, not perfection. The companies whose stories are heard? They invested in communications before they had big news to share.Grace Keith Rodriguez is the CEO at Caliber Corporate Advisers. View the full article
-
In his news conference Monday, President Donald The President threatened to blow up every bridge and power plant in Iran, action that would be so far-reaching that some experts in military law said it could constitute a war crime. The issue could turn on whether the power plants were legitimate military targets, whether the attacks were proportional compared with what Iran has done and whether civilian casualties were minimized. The President’s threat was so broad it did not seem to account for the harm to civilians, prompting Democrats in Congress, some United Nations officials and scholars in military law to say such strikes would violate international law. The president’s eventual actions often fall short of his all-encompassing rhetoric in the moment, but his warnings about the power plants and bridges were unambiguous both on Sunday and Monday as he set a deadline of Tuesday night for Iran to open the Strait of Hormuz. A spokesman for U.N. Secretary-General Antonio Guterres on Monday warned that attacking such infrastructure is banned under international law. “Even if specific civilian infrastructure were to qualify as a military objective,” Stephane Dujarric said, an attack would still be prohibited if it risks “excessive incidental civilian harm.” Rachel VanLandingham, a Southwestern Law School professor who served as a judge advocate general in the U.S. Air Force, said civilians are likely to die if power is cut to hospitals and water treatment plans. “What The President is saying is, ‘We don’t care about precision, we don’t care about impact on civilians, we’re just going to take out all of Iranian power generating capacity,'” the retired lieutenant colonel said. Shipping in the Strait of Hormuz, a chokepoint in the Persian Gulf through which 20% of the world’s oil normally flows, has been all but halted, sending oil prices soaring and roiling the stock market. The President said Monday that he’s “not at all” concerned about committing war crimes as he continues to threaten destruction. He also warned that every power plant will be “burning, exploding and never to be used again.” “I hope I don’t have to do it,” The President added. When asked for further comment Monday, White House spokeswoman Anna Kelly said “the Iranian people welcome the sound of bombs because it means their oppressors are losing.” “The Iranian regime has committed egregious human rights abuses against its own citizens for 47 years, just murdered tens of thousands of protestors in January, and has indiscriminately targeted civilians across the region in order to cause as much death as possible throughout this conflict,” Kelly wrote in an email. ‘Clearly a threat of unlawful action’ As the conflict has entered its second month, The President has escalated his warnings to bomb Iran’s infrastructure, including Kharg Island, central to Iran’s oil industry, and desalination plans that provide drinking water. In a Truth Social post on March 30, The President warned that the U.S. would obliterate “all of their Electric Generating Plants, Oil Wells and Kharg Island (and possibly all desalinization plants!), which we have purposefully not yet ‘touched.'” On Easter Sunday, The President threatened in an expletive-laden post that Iran will face “Power Plant Day, and Bridge Day, all wrapped up in one,” while adding that “you’ll be living in Hell” unless the strait reopens. “This strikes me as clearly a threat of unlawful action,” said Michael Schmitt, a professor emeritus at the U.S. Naval War College and an international law professor at the University of Reading in Britain. A power facility can be attacked under the laws of armed conflict if it provides electricity to a military base in addition to civilians, Schmitt said. But the strike must not “cause disproportionate harm to the civilian population, and you’ve done everything to minimize that harm.” Harm does not include inconvenience or fear, said Schmitt, who has taught military commanders. But it does mean severe mental suffering, physical injury or illness. Schmitt said military commanders should consider alternatives, such as targeting a substation or transmission lines that feed electricity to a base, before destroying an entire power plant. “If you look at the operation and you’ve got a valid military objective, but it’s going to cause harm to civilians and you go, ‘Whoa, that’s a lot,’ then you should stop,” Schmitt said. “If you hesitate to take the shot, don’t take the shot.” ‘He’s using that leverage’ Republican Sen. Joni Ernst of Iowa said Monday that The President is “absolutely not” threatening a war crime when he said he might bomb civilian infrastructure. The infrastructure is also used by the military, Ernst said, and “it’s an ongoing operation.” “If he needs leverage, he’s using that leverage,” she said while presiding over a brief pro forma session of the Senate. But Democratic Sen. Chris Van Hollen of Maryland, also in the Capitol for the brief session, said it would be a “textbook war crime.” “If you target civilian infrastructure for the purposes the president was talking about, it clearly is a war crime,” Van Hollen said. Dujarric, the U.N. spokesman, said the question of whether attacks on civilian infrastructure would be considered war crimes would have to be decided by a court. However, Katherine Thompson, a senior fellow in defense and foreign policy studies at the Cato Institute, a libertarian think tank, said any accountability would more likely come from Congress. She said thinking otherwise would mean believing that the U.S. would allow its president to be held accountable by foreign entities. “This is the persnickety, inconvenient truth about international law: It only works if sovereign nations are willing to cede their sovereignty to a foreign body for accountability,” she said. But Congress would have to say the president has gone too far. And then both houses would have to take action and with enough support to overcome a presidential veto, a highly unlikely prospect. The President also appears to have broad legal immunity under the Supreme Court’s ruling in the criminal case before his reelection, said VanLandingham. And the president could also grant preemptive pardons to top officials if needed. ‘We’re giving them a gift’ Even if technically justified under the law of war, strikes that bring harm to civilians could backfire for the U.S. long term, VanLandingham said. “There’s a lot of violence that can still be justified as lawful, but lawful can still be awful,” VanLandingham said. “How far did that get us in Iraq? How far did that get us in Afghanistan? How far did that get us in Vietnam?” The President’s rhetoric risks spreading fear among regular Iranians and communicating that the U.S. isn’t worried about their well-being, VanLandingham said. The country’s leaders could use it as propaganda to create and harden opposition, contributing to a longer, tougher war. Associated Press writers Farnoush Amiri and Edith M. Lederer in New York and Mary Clare Jalonick and Seung Min Kim in Washington contributed to this report. —Ben Finley, Lindsay Whitehurst and Gary Fields, Associated Press View the full article
-
Non-bank lenders rapidly reduce holdings of EM debt during shocks such as the Iran war, analysis suggestsView the full article
-
Short positions rise sharply as traders eye economic fallout from Iran warView the full article
-
Whether you’re doomscrolling on LinkedIn or talking to friends, AI-induced job loss anxiety feels inescapable right now. As companies go full throttle on investing in automation tools, the fear that entire roles can be instantly eliminated feels very real. After the surge in economic activity and tech adoption during the pandemic, tech companies issued mass layoffs after over-expanding. That trend continued in the last few months, with tech giants like Amazon and Oracle laying off thousands of employees. But there have been a few silver linings in the mostly pessimistic discourse around AI and the future of work: A recent surprising bright spot in hiring right now for software engineers. Business Insider reported that companies are hiring more software engineers, with software job listings climbing 30% so far this year. According to tech hiring firm TrueUp—whose data tracks more than 260,000 open roles across 9,000 tech startups and public tech firms—more than 67,000 software engineering job openings. After a stretch of hiring freezes and pervasive layoffs, this might feel like renewed momentum for some, especially since the recent jobs report issued on Friday was more optimistic than expected. “Encouraging to see tech hiring gaining momentum again, especially amid ongoing conversations about AI‑driven job displacement,” one insurance professional commented on LinkedIn. “The data reinforces an important point: while AI is reshaping roles, it’s also creating new opportunities that require human expertise, adaptability, and strategic thinking.” In the same vein, an engineer and AI founder wrote: “It’s getting increasingly cheaper to build custom solutions, which means we might end up with much, much more code that needs to be reviewed and maintained.” Others shared less optimism about the statistic. “The data is real[,] but what the headline does not say is that the jobs driving that number are AI-fueled,” a senior recruiter wrote. “The same quarter that produced this hiring surge also saw 52,050 tech job cuts announced, the worst Q1 since 2023, with AI cited as the leading reason for layoffs across industries.” Another LinkedIn user pointed out that job openings do not equate to jobs filled. “Saying ‘AI isn’t killing jobs’ because software engineering openings are up is like saying the housing market is fine because penthouse listings are booming,” one consultant wrote. Coaching company Challenger, Gray & Christmas reported that the tech sector announced 18,720 job cuts in March, and predicted more layoffs to come. Following a bleak few months and the loss of 133,000 jobs in February, the most recent jobs report showed that the U.S. added 178,000 jobs in March, offering a bit of much-needed motivation. AI has completely jolted entry-level roles and internships meant to help young workers kickstart their careers. The unemployment rate for recent college graduates reached 5.6% in December. Even with the increase in job openings for software engineers across the tech sector, young and eager professionals might not feel the reprieve they’re expecting. As companies look to invest in AI, the talent pool—especially among entry-level applicants—has grown considerably, making these available jobs feel more competitive. More job openings don’t necessarily mean job hunting is going to get easier, especially when the bar for skill is getting higher. View the full article
-
I've been using Pixel phones every day for several years at this point, so I thought I'd discovered every secret menu and hidden feature these Google handsets have to offer—but it turns out I was wrong. Make Use Of enlightened me about the diagnostic tool built into Google Pixels, hidden away behind the number pad of the phone app. Its official name is the Pixel Repair Diagnostics App, and according to Google, it's built into every Pixel phone and tablet. It gives you a dashboard for testing just about every part of your phone's setup, from Bluetooth connections to camera sensors. The Pixel Repair Diagnostics App. Credit: Lifehacker To get to the diagnostics tool, open up the Phone app on your Pixel, switch to the Keypad screen, then type *#*#7287#*#*. You'll be asked if you have reliable wifi, so press Confirm, and you'll get into the app proper—with the screen brightness ramped right up. You can choose to work through these diagnostic tests individually, run related tests together via the Check Group options, or test everything via the Start Test button that appears at the top. The three-dot menu up in the top-right corner gives you access to results for tests that have already been run. There's a lot to work through here: The Visual group alone includes tests for Physical Damage, Display Defects, Backglass Defects, and Camera Defects. Each test differs in terms of what you need to do—so for Physical Damage it's simply a case of checking around your phone, whereas for WiFi the phone will itself try and get online and see if the connection is stable. Some diagnostics require more interactionSome of these tests require more interaction than others. For Light Sensor for example, you'll be asked to cover your phone's light sensor with your hand (it's usually up at the top of the screen next to the selfie camera) while a reading is taken. For Gyroscope, you need to move your phone in a figure-of-8 pattern. When it comes to Display under Screen, you get shown a series of images—some solid colors, others with writing on them—so you can carefully examine the screen and look for any inconsistencies or defects. It's then up to you to either choose Pass or Fail. Also under the Screen heading there's Touch Panel, a test that tasks you with performing various taps and swipes—one of the actions you have to do is use three fingers to drag some colored balls down the screen. The aim is to make sure every part of the display remains responsive. You'll need to manually confirm certain tests have been passed. Credit: Lifehacker For Microphone under Audio, your phone will play a little jingle and attempt to record it through all of the mics your phone has, at the same time. Each microphone recording is then played back, and it's up to you to confirm that they all worked. The Front Camera and Rear Camera tests under Camera are particularly useful, because they test each individual camera in turn by capturing photos and videos from them—so if your phone has three cameras around the back that are normally used in unison, you can separate and test them all individually. This is a useful tool to turn to whenever you think something might be broken on your phone—and if there's a problem, it will tell you where the problem lies. You can quit the app like any other, with a swipe up from the bottom of the screen (or by pressing the home button, if you're using button navigation). View the full article
-
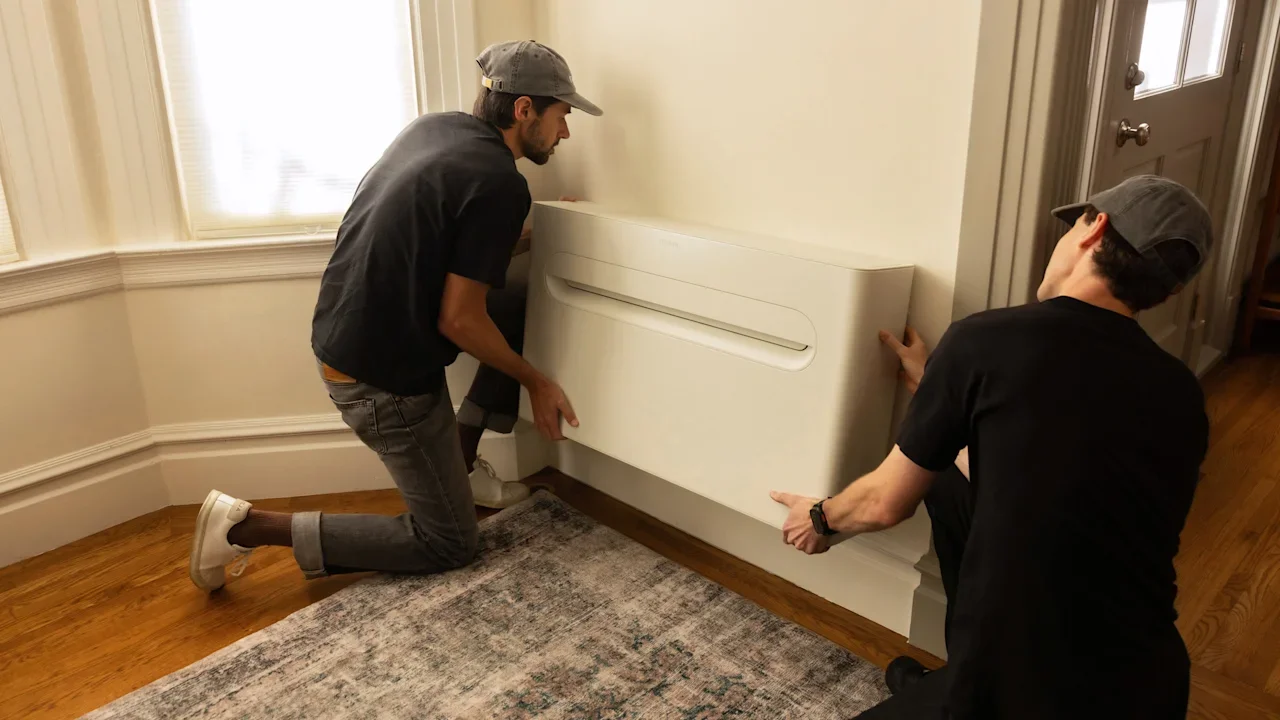
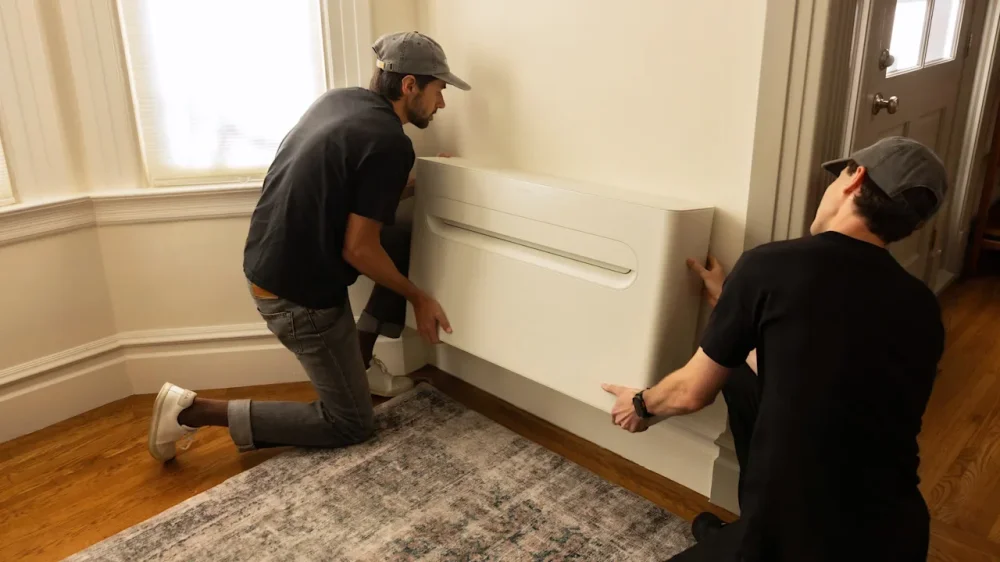
Five years ago, while working at Apple as a product designer, Mary Ann Rau decided to electrify her house and move away from fossil fuels. She installed solar, a battery, an induction range, and owned an EV. But there was still one big challenge: her HVAC system. “When it came to heat pumps, I was shocked when I got a quote for $40,000 to install heat pumps in my own house,” Rau says. Today, Rau launched a startup that’s tackling the problem of making heat pumps more accessible. Merino Energy, which just came out of stealth, makes heat pumps that each take an hour or less to install and come with a fixed price per unit of $3,800, including installation fees. For a whole home, the system could be half the cost of a typical mini split installation. (For someone who wants to add a unit to a single room, it’s an even bigger difference, coming in at a third of the cost.) Mary Ann RauBrad Hall Rau left Apple in 2023 and first worked at Quilt, another startup designing sleek mini-split heat pumps. There, she learned about the complexity of installation, a major driver of cost. “I learned that that was really the true bottleneck when it comes to heat pump adoption,” she says. Mini split heat pumps—units that are installed in walls in rooms throughout a house, and then connected to a condenser outside—can each take eight hours to install. Skilled technicians have to add refrigerant to long lines between the mini splits and the condenser. Labor for the whole process is expensive. New window heat pumps are faster to install, but aren’t compatible with some windows. (Rau’s cofounder, Brad Hall, previously worked at Gradient, one of the companies pioneering window heat pumps, but couldn’t install the product at his own home.) They saw an opportunity to design a different alternative. Merino’s design eliminates outdoor units and the need for complicated connections. Instead, it uses two vents in the wall, one to pull air in and one for exhaust. Each unit takes around an hour to install, shrinking the overall cost. Because refrigerant is added at the factory and not on site, that also reduces labor. Adding refrigerant at the factory also means there’s little risk of it leaking; small leaks can be a major source of emissions. “One leaky mini split can erase the benefits of transitioning around 50 homes off of fossil fuels,” Rau says. The team worked closely with installers to understand what needed to change. Part of the challenge with existing heat pumps wasn’t just the installation time, but the fact that HVAC companies were spending valuable hours visiting homes to give quotes that homeowners ultimately couldn’t afford. By offering flat rate pricing, homeowners can decide beforehand if they want to move forward. The approach means that Merino can give installers better margins while still saving homeowners money. The team also carefully considered the product design. “It’s designed to blend into your home like a modern artifact,” says Rau, who worked on AirPod design at Apple. The heat pump is quiet as it runs, and relatively sleek at 7.8 inches deep, “so it doesn’t take up too much space visually in the room,” she says. It also integrates with smart home tech like Apple HomeKit and Google Home, as well as wearables like the Oura Ring. “There are clinical studies that show that you can improve sleep quality and sleep efficiency by reducing temperature by several degrees when you’re in REM,” Rau says. “So if you choose to integrate your Oura Ring with our product, then you will get the benefit of automatic temperature control based off of your sleep cycle.” The company is launching first in California, where there’s strong demand for heat pumps. Los Angeles recently passed a rule requiring landlords to keep indoor temperatures below 82 degrees as extreme heat becomes more common. Many apartments in L.A. still lack air conditioning, making the new tech a relatively affordable way to add it permanently. Merino also makes a simplified version for low-income housing and recently installed it in a Bay Area apartment building for formerly homeless residents The state also has an aggressive goal to install six million heat pumps by 2030. “At the current pace of installation, it would take until 2045 for California to hit its goals,” Rau says. “With Merino, we think that we can actually do it in four years, and that’s because we’re doing installation eight times faster.” The startup opened preorders on its website today, and expects to ship the first products in late 2026. View the full article
-
A small business loan calculator is a practical tool that helps you estimate your monthly loan payments by inputting key factors like loan amount, interest rate, and loan term. It simplifies the process of comprehending your financial commitments and potential costs associated with borrowing. By using this calculator, you can make informed decisions about financing options. But what specific variables should you consider, and how can they impact your overall loan experience? Key Takeaways A small business loan calculator estimates monthly payments based on loan amount, interest rate, and term duration. It helps users understand total interest paid and overall loan cost over time. Users input desired loan amount, interest rate, and term to generate payment estimates. The calculator can also provide amortization schedules, detailing payment breakdowns throughout the loan’s life. It’s essential to verify estimates with lenders, as results are approximations influenced by input accuracy. What Is a Small Business Loan Calculator? A small business loan calculator is an essential online tool that helps you estimate your monthly payments based on significant factors like the loan amount, term, and interest rate or APR. This calculator allows you to input key financial figures, giving you a detailed estimate of monthly payments, total interest paid, and the overall cost of the loan. Many small business loan calculators additionally generate amortization schedules, breaking down how each payment impacts the principal and interest over time. By utilizing this tool, you can assess your borrowing capacity, typically between 10-30% of your annual revenue, considering your income, expenses, and credit score. How Does a Small Business Loan Calculator Work? How does a small business loan calculator provide valuable insights into your financing options? This online tool allows you to input your desired loan amount, interest rate, and loan term. By doing so, you can estimate monthly payments and the total interest paid over the loan’s life. The commercial loan payment calculator can likewise generate an amortization schedule, showing how each payment is split between principal and interest. You can adjust various factors, like loan amount and repayment term, to see how different scenarios affect your monthly payments. Moreover, it considers your annual revenue and expenses, helping you assess your borrowing capacity. Keep in mind, these results are estimates and should be verified with lenders for accuracy. Benefits of Using a Business Loan Calculator Using a small business loan calculator offers numerous benefits that can greatly aid in your financial planning. This tool helps you estimate monthly payments based on the loan amount, term, and APR, giving you a clear comprehension of your financial commitments. You can explore various loan scenarios by adjusting inputs, providing flexibility in your planning. Benefit Description Cost Insights Calculates total interest paid and total payments, revealing long-term costs. Amortization Schedule Some calculators offer a schedule detailing payment distribution over time. Affordability Evaluation Assists in ensuring your monthly cash flow can comfortably cover estimated payments. Key Variables to Input in the Calculator When using a small business loan calculator, you’ll need to input several key variables to get accurate results. Start with the loan amount, which is the total funds you’re looking to borrow, and then select the interest rate that reflects the cost of borrowing. Finally, specify the loan term duration, as this will determine how long you’ll have to repay the loan and influence your monthly payments. Loan Amount Input Determining the loan amount is a significant step in using a small business loan calculator, as this figure represents the total funds you intend to borrow for your business needs. Inputting the correct loan amount directly influences your estimated monthly payment. Typically, higher loan amounts result in higher payments. Most calculators let you input a range of amounts, helping you evaluate different borrowing scenarios and their financial impact. Here’s a quick overview of how loan amounts can affect your calculations: Loan Amount Estimated Monthly Payment Total Interest Paid $5,000 $100 $300 $10,000 $200 $600 $20,000 $400 $1,200 $30,000 $600 $1,800 $50,000 $1,000 $3,000 Understanding the loan amount is essential for evaluating affordability and comparing various small business loan rates. Interest Rate Selection How do you select the right interest rate for your small business loan? When using a commercial loan calculator, you can input the interest rate as either the APR (Annual Percentage Rate) or a simple interest rate, depending on what’s available. If you’re unsure of the interest rate, you can convert factor rates using specific formulas for a more accurate estimate. Remember, the interest rate you choose will greatly affect your monthly payments; lower rates lead to smaller payments and less total interest paid. Furthermore, be mindful of any fees associated with the loan, as these can impact the true cost and should be included in the APR for a thorough calculation. Adjusting the interest rate in the calculator allows you to evaluate different loan scenarios. Loan Term Duration Selecting the right loan term duration is crucial for managing your small business loan effectively, as it directly influences your monthly payment amount and the total interest paid over the life of the loan. Loan terms typically range from a few months to several years. Longer terms can lower your monthly payments, but they often result in higher total interest costs. By using a commercial loan amortization calculator, you can input different loan term durations to see how they affect both your monthly payments and overall interest. Furthermore, some calculators allow you to select various payment frequencies, which can further impact your repayment structure. Comprehending these factors helps you make informed decisions regarding your financing needs. Understanding Monthly Payments and Total Costs When you’re looking to finance your small business, comprehension of monthly payments and total costs is vital for effective budgeting. A business loan repayment calculator helps you estimate monthly payments by factoring in the loan amount, interest rate, and loan term. Monthly payments typically cover principal, interest, and fees, providing a full picture of your obligations. You can additionally view the total interest paid over the loan term, making it easier to compare options. Loan Amount Interest Rate Monthly Payment $10,000 5% $188 $20,000 7% $402 $30,000 6% $580 $40,000 4% $888 $50,000 5% $1,060 Types of Business Loans You Can Calculate Comprehending the various types of business loans available can greatly ease your financing expedition. One option is an SBA loan, which is partially guaranteed by the Small Business Administration, offering lower interest rates and longer repayment terms for eligible borrowers. If you need larger financing, consider conventional loans, though they often come with higher interest rates and require a solid credit history. Equipment financing is another route, allowing you to purchase equipment with the equipment itself as collateral. Lines of credit provide flexible access to funds, letting you borrow only what you need. Finally, commercial real estate loans are customized for purchasing or renovating properties, usually requiring a larger down payment, making the sba loan calculator a useful tool for evaluating these options. How to Use a Business Loan Calculator Effectively Using a business loan calculator can greatly streamline your financing process, as it allows you to gain insights into your potential loan obligations. To use a business loan calculator SBA effectively, start by inputting the loan amount, term in months, and the annual percentage rate (APR). This will help you estimate your monthly payments and total interest paid over the loan’s duration. Experiment with different loan amounts and terms to find the best balance for your budget. If you’re unsure of the APR, leverage the option to convert factor rates into interest rates for accurate calculations. Finally, review the amortization schedule to see how payments break down over time, and remember to factor in additional fees that may impact your overall loan cost. Alternative Financing Options for Small Businesses Finding the right financing option can be a game-changer for your small business, especially if traditional loans aren’t on the table. Here are some alternative financing options to evaluate: Financing Option Description Pros/Cons Business Grants Free funding but hard to obtain because of strict applications. Pros: No repayment; Cons: Competitive. Personal Business Loans Higher interest rates, suitable for newer businesses. Pros: Accessible; Cons: Costly. Business Credit Cards Revolving capital, potential rewards on purchases. Pros: Flexible; Cons: High interest. Invoice Factoring Sell receivables for immediate cash. Pros: Quick cash; Cons: Fees involved. Invoice Financing Use invoices as collateral for loans. Pros: Fast access; Cons: Debt risk. Utilizing a business loan estimator can help you evaluate these options effectively. Common Mistakes to Avoid When Using the Calculator When you’re calculating potential loan costs, it’s crucial to avoid common pitfalls that can lead to inaccurate results. Using a commercial mortgage loan calculator can be helpful, but mistakes can skew your comprehension. Here are three mistakes to watch for: Entering Inaccurate Amounts or Terms: Make sure the loan amounts and terms you input are correct to avoid misleading estimates. Ignoring Additional Fees: Don’t forget to include origination or documentation fees, as these can greatly affect your total APR. Not Adjusting Interest Rates: Always check if the calculator requires you to input an interest rate or APR; overlooking this can distort your results. Resources for Further Assistance After addressing common mistakes with loan calculators, it’s important to know where to turn for further support as you navigate financing options. The Small Business Administration (SBA) website is a valuable resource for exploring funding programs and counseling customized to your needs. Local chambers of commerce can connect you with lenders and provide information on financing options. Moreover, various grant programs might be available locally, though they can be competitive. Online platforms like Lendio and LendingTree offer tools, including a commercial real estate loan calculator, to help you compare different financing options. Finally, consider working with a business loan broker who can leverage their expertise to find the best financing solutions for your situation. Evaluating Your Loan Options When you’re evaluating your loan options, it’s crucial to compare different loan types to find the best fit for your business needs. Comprehending how payment structures work will help you anticipate your monthly obligations, whereas evaluating total loan costs guarantees you grasp the overall financial impact. Comparing Loan Types Choosing the right type of loan for your small business involves careful consideration of various options, as each type has its unique features and implications. Here are three key types to compare: SBA Loans: Often have lower interest rates because of government backing, making them a cost-effective option. Equipment Financing: Provides 100% funding particularly for necessary equipment, helping you acquire assets without upfront costs. Lines of Credit: Offer flexible access to funds, with interest only on the amount you use, which can be beneficial for managing cash flow. Using a business mortgage calculator can help you evaluate the total cost of each option, including interest and fees, ensuring you make an informed decision that aligns with your financial goals. Understanding Payment Structures Grasping the payment structure of your small business loan is crucial, as it directly impacts your budgeting and cash flow management. A small business loan calculator, like a business property loan calculator, helps you estimate monthly payments based on factors such as loan amount, interest rate, and loan term. Comprehending that monthly payments typically include principal, interest, and any applicable fees gives you an all-encompassing view of your loan’s cost. You can likewise calculate the total interest paid over the loan’s life, which helps clarify the overall expense. Generating an amortization schedule shows how each payment affects both principal and interest over time. Don’t forget to explore early repayment options, as they may save you money on total interest if no prepayment penalties apply. Assessing Total Loan Costs How can you accurately assess the total costs associated with a small business loan? Using a commercial building loan calculator can help you break down your financial obligations effectively. Here’s what you should consider: Loan Amount and Term: Enter the total amount you need and the desired repayment period. Annual Percentage Rate (APR): Input the interest rate to see how it impacts your payments. Additional Fees: Don’t forget to factor in origination and documentation fees, as these affect the true cost of borrowing. Tips for Managing Business Loans Managing business loans effectively is crucial for maintaining your financial health, especially as your business grows and evolves. Regularly review your loan payments and cash flow to guarantee you can cover monthly obligations comfortably. Setting up automatic payments can help you avoid late fees, adding unnecessary costs. Prioritize paying down high-interest loans first to minimize total interest paid over time. If interest rates drop or your credit improves, consider refinancing to lower your monthly payments. Furthermore, maintain open communication with your lender, especially during financial hardships, to explore options for payment adjustments or deferments. Using an SBA loan repayment calculator can help you plan and manage your loan obligations efficiently, making certain you stay on track. Frequently Asked Questions How Much Is a $50,000 Business Loan Monthly? For a $50,000 business loan, your monthly payment depends on the loan term and interest rate. For example, at a 15% interest rate over five years, you’d pay about $1,266.76 monthly. If you choose a longer term, your payments may decrease, but the total interest paid will increase considerably. Moreover, keep in mind any origination fees or other charges, as these can raise your total borrowing costs beyond just the interest. How Does Getting a Small Business Loan Work? Getting a small business loan involves several steps. First, you’ll submit a loan application with required documents like tax returns and financial statements. Lenders evaluate your eligibility based on your credit score, revenue, and debt service coverage ratio. If approved, you receive the loan amount and must repay it regularly, either monthly, weekly, or daily. How Much Can I Realistically Get for a Small Business Loan? To determine how much you can realistically get for a small business loan, consider factors like your annual revenue, credit score, and time in operation. Lenders usually lend 10% to 30% of your revenue. A strong credit score improves your chances of better terms. Furthermore, a debt service coverage ratio of 1.25 or higher is often required for approval. Evaluating these elements will give you a clearer picture of your borrowing potential. What Is the Payment on a $1,000,000 Business Loan? If you take out a $1,000,000 business loan at a 5% APR over 10 years, your monthly payment would be about $10,607. This arrangement leads to a total repayment of roughly $1,276,800, including around $276,800 in interest. Opting for a 15-year term lowers your monthly payment to about $7,908, but increases total interest to approximately $480,000. Remember to factor in any fees or early repayment options affecting your overall costs. Conclusion In conclusion, a small business loan calculator is a valuable tool that helps you grasp your potential loan obligations. By entering key variables like loan amount, interest rate, and term length, you can estimate monthly payments and total costs. This insight allows you to evaluate different financing options and make informed decisions. Remember to input accurate data and consider various scenarios, as this will improve your comprehension of your financial commitments and refine your loan management strategy. Image via Google Gemini This article, "What Is a Small Business Loan Calculator and How Does It Work?" was first published on Small Business Trends View the full article
-
After traveling deeper into space than any other humans, the Artemis II astronauts pointed their moonship toward home Monday night, wrapping up a lunar cruise that revealed views of the far side never beheld by eyes until now. Their flyby of the moon — NASA’s first return since the Apollo era — even included some celestial sightseeing besides yielding rich science. It was a significant step toward landing boot prints near the moon’s south pole in just two years. A total solar eclipse greeted the three Americans and one Canadian as the moon temporarily blocked the sun from their perspective. Mercury, Venus, Mars and Saturn nodded at them from the black void. The landing sites of Apollo 12 and 14 also were visible, poignant reminders of NASA’s first age of exploration more than half a century ago. In an especially riveting retro throwback, Artemis II shattered the distance record set by Apollo 13 in 1970. NASA’s Orion capsule reached a maximum distance of 252,756 miles (406,771 kilometers) from Earth before hanging a U-turn behind the moon, 4,101 miles (6,600 kilometers) farther than Apollo 13. “It is blowing my mind what you can see with the naked eye from the moon right now. It is just unbelievable,” Canadian astronaut Jeremy Hansen radioed. He challenged “this generation and the next to make sure this record is not long-lived.” Artemis II astronauts get an Apollo wake-up message Apollo 13 commander Jim Lovell wished the crew well in a recording made two months before his death last August. Mission Control beamed up his message to commander Reid Wiseman, pilot Victor Glover, Christina Koch and Hansen, before their fly-around began. “Welcome to my old neighborhood,” said Lovell, who also flew on Apollo 8, humanity’s first lunar visit. “It’s a historic day and I know how busy you’ll be, but don’t forget to enjoy the view.” The Artemis II astronauts carried up with them the Apollo 8 silk patch that accompanied Lovell to the moon. “It’s just a real honor to have that on board with us,” Wiseman said. Artemis II is using the same maneuver that Apollo 13 did after its “Houston, we’ve had a problem” oxygen tank explosion wiped out any hope of a moon landing. Known as a free-return lunar trajectory, this no-stopping-to-land route takes advantage of Earth and the moon’s gravity, reducing the need for fuel. It’s a celestial figure-eight that put the astronauts on course for home once they emerged from behind the moon Monday evening. Astronauts lock in on lunar observations Artemis II’s lunar fly-around and intense observation period lasted seven hours, by far the highlight of the nearly 10-day test flight that will end with a splashdown in the Pacific on Friday. Venturing as close as 4,067 miles (6,545 kilometers) to the gray dusty surface, the astronauts zipped through a list of more than two dozen targets, using powerful Nikon cameras as well as their iPhones to zoom in on impact craters and other intriguing lunar features. Before getting started, they requested permission to name two bright, freshly carved craters. They suggested Integrity, the name of their capsule, and Carroll, commander Wiseman’s wife, who died of cancer in 2020. Wiseman wept as Hansen put in the request to Mission Control, and all four astronauts embraced in tears. “Such a majestic view out here,” Wiseman radioed once he regained his composure and started picture-taking. The astronauts called down that they managed to capture the moon and Earth in the same shot, and they provided a running commentary to scientists back in Houston on what they were seeing. At one point, Koch reported an overwhelming sensation of emotion for a second or two while zooming in on the moon. “Something just drew me in suddenly to the lunar landscape and it became real,” she said. The Artemis II astronauts made their closest approach to the moon and reached their maximum distance from Earth while they were out of contact. Their speed at closest approach: 3,139 mph (5,052 kph). The spacecraft accelerated as it appeared from behind the moon and the planned communications blackout and made tracks for Earth. An Earthrise came into view showing Asia, Africa and Oceania as Mission Control called out: “We are Earthbound and ready to bring you home.” Flight controllers in Houston flipped their mission patches over to signify the return leg. President Donald The President phoned the astronauts following the flyby, calling them “modern-day pioneers.” “Today you’ve made history and made all America really proud, incredibly proud,” the president said, adding that more lunar traveling is coming and ultimately “the whole big trip to Mars.” Wiseman and his crew spent years studying lunar geography to prepare for the big event, adding solar eclipses to their repertoire during the past few weeks. By launching last Wednesday, they ensured themselves of a total solar eclipse from their vantage point behind the moon, courtesy of the cosmos. Topping their science target list: Orientale Basin, a sprawling impact basin with three concentric rings, the outermost of which stretches nearly 600 miles (950 kilometers) across. Their moon mentor, NASA geologist Kelsey Young, expects thousands of pictures. Artemis II is NASA’s first astronaut moonshot since Apollo 17 in 1972. It sets the stage for next year’s Artemis III, which will see another Orion crew practice docking with lunar landers in orbit around Earth. The culminating moon landing by two astronauts near the moon’s south pole will follow on Artemis IV in 2028. While Artemis II may be taking Apollo 13’s path, it’s most reminiscent of Apollo 8 and humanity’s first lunar visitors who orbited the moon on Christmas Eve 1968 and read from the Book of Genesis. Glover said flying to the moon during Christianity’s Holy Week brought home for him “the beauty of creation.” Earth is an oasis amid “a whole bunch of nothing, this thing we call the universe” where humanity exists as one, he observed over the weekend. “This is an opportunity for us to remember where we are, who we are, and that we are the same thing and that we’ve got to get through this together,” Glover said, clasping hands with his crewmates. The Associated Press Health and Science Department receives support from the Howard Hughes Medical Institute’s Department of Science Education and the Robert Wood Johnson Foundation. The AP is solely responsible for all content. —Marcia Dunn, AP Aerospace Writer View the full article
-
The workplace has seen its share of technological shifts, but the rise of AI is happening at a much faster pace. What once took years is now unfolding in months, leaving little time for companies or their employees to catch up. A new global study of 2,400 employees and C-suite leaders conducted by Workplace Intelligence and enterprise AI agent platform WRITER finds that 60% of companies plan to lay off employees who won’t adopt AI. Even more striking, 77% of executives say those who resist AI won’t be considered for promotions or leadership roles. AI isn’t just another tool. It’s quickly becoming a baseline expectation for staying relevant at work. This shift is already reshaping how companies evaluate talent. According to the research, 92% of executives say they are actively cultivating a new class of “AI elite” employees, and 87% report that these employees are at least five times more productive than their peers. That productivity gap is creating a two-tier workforce: those who know how to leverage AI to amplify their output, and those who don’t. The implications for career growth are profound. The most valuable employees are no longer just high performers, but those who can combine domain expertise with AI fluency to move faster and scale their impact. Companies aren’t just talking about this shift—they’re enforcing it. At Accenture, senior staff who fail to use AI tools risk missing out on promotions, signaling that AI proficiency is becoming a prerequisite for advancement. Meanwhile, tech giants like Meta are embedding AI usage into daily workflows and performance expectations. Some organizations are also using incentives to accelerate behavior change. KPMG, for instance, has offered financial rewards to employees who develop innovative AI use cases, reinforcing that those who embrace the technology will be recognized. Yet for all the momentum, the reality inside organizations is far more complicated. While 97% of executives say AI has been beneficial, only a minority report seeing significant returns from generative AI (29%) or AI agents (23%). Nearly half of leaders say their AI adoption efforts have been a disappointment so far. This gap between expectation and outcome is fueling pressure at the highest levels. In fact, 38% of CEOs report a high or crippling amount of stress related to AI strategy, and 64% fear they could lose their job if they fail to lead their organizations through the transition. Part of the challenge is that many companies are building the plane while flying it. Despite widespread investment, 39% of executives admit they don’t have a formal strategy in place to drive revenue from AI, and 75% say their existing strategy is more for show than for actual guidance. The result is confusion and fragmentation. More than half of executives say AI adoption is creating internal power struggles, while 78% report tension between IT and other business units. In many organizations, AI usage has become fragmented, with employees experimenting in silos rather than working toward a unified vision. That lack of alignment is also contributing to resistance from employees. The study found that 29% of workers admit to sabotaging their company’s AI strategy, whether by using unauthorized tools, inputting sensitive data into public systems, or refusing to engage. Among Gen Z employees, that number jumps to 44%. For leaders, this behavior represents a real risk. More than three-quarters of executives say employee resistance and misuse of AI poses a serious threat to their organization’s future, especially as 67% report experiencing a data leak or security breach tied to AI usage. Despite these challenges, some organizations are getting it right by treating AI adoption as a business transformation rather than a technology rollout. Marriott International, for example, has focused on aligning AI initiatives with measurable business outcomes, ensuring that investments are tied to growth and operational improvements rather than experimentation alone. The most successful approaches share a few common elements. They empower employees to experiment with AI tools while providing clear guardrails, reducing the risk of security issues. They invest in building AI fluency across the organization so more employees can contribute effectively. They establish governance frameworks for AI systems to ensure innovation doesn’t outpace oversight. And they approach change management as both a top-down and bottom-up effort, recognizing that adoption requires executive alignment and employee buy-in. The message for workers is becoming clear: adapting to AI is no longer a future concern—it’s a present-day requirement. As roles, responsibilities, and performance metrics evolve, employees who fail to integrate AI into their workflows risk falling behind in both productivity and relevance. Those who embrace it, however, have an opportunity to redefine their value and accelerate their careers. For leaders, the stakes are just as high. The organizations that succeed won’t be the ones that simply deploy AI tools, but the ones that rethink how work gets done. That means closing the gap between ambition and execution, turning experimentation into impact, and ensuring that the workforce evolves alongside the technology. Because in the emerging AI economy, the real competitive advantage isn’t just having access to AI, but knowing how to use it. View the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. Bose’s QuietComfort Ultra headphones have been easy to recommend since their late 2023 launch, but the price held them back. That changes with this open-box deal. Right now, the Bose QuietComfort Ultra Headphones in sandstone are down to $242.49 on Woot, compared to about $329 for a new pair on Amazon. Price trackers show earlier dips closer to $279, so this undercuts previous lows. The catch is the “open box” label—these units may have been returned, tested, or repackaged (but they’re cleared to work like new). Shipping is free for Prime members, while others pay $6. The deal is expected to last six days or until stock runs out. Bose QuietComfort Ultra Headphones $242.49 at Woot $429.00 Save $186.51 Get Deal Get Deal $242.49 at Woot $429.00 Save $186.51 Bose has long focused on cutting down low-frequency noise, and these headphones do a good job muting things like traffic, airplane hum, or AC rumble. Mid-range noise gets reduced well, too, though sharper, high-pitched sounds can still come through, notes this PCMag review. That’s normal for ANC, but it’s worth noting if you expect total silence. Compared to older rivals like the Apple AirPods Max and the Sony WH-1000XM5, Bose still holds its ground. Newer models like Sony’s XM6 push ahead, but they also cost more. Outside of ANC, the transparency mode works reliably for letting in voices and street sounds, and the Bose app gives you a clean, easy EQ to tweak audio to your liking. As for its battery life, it's solid but not class-leading. You’ll get around 24 hours on a full charge, or closer to 18 hours with ANC turned on. That’s enough for long flights or a few days of regular use, though some competitors stretch further. Comfort remains a strong point, with a lightweight design that works well for long listening sessions. The main tradeoff here is the open-box condition. If you’re fine with that, this price makes the QuietComfort Ultra far easier to justify. Our Best Editor-Vetted Tech Deals Right Now Apple AirPods Pro 3 Noise Cancelling Heart Rate Wireless Earbuds — $224.00 (List Price $249.00) Apple iPad 11" 128GB A16 WiFi Tablet (Blue, 2025) — $299.99 (List Price $349.00) Samsung Galaxy Tab A11+ 128GB Wi-Fi 11" Tablet (Gray) — $209.99 (List Price $249.99) Apple Watch Series 11 (GPS, 42mm, S/M Black Sport Band) — $329.00 (List Price $399.00) Sony WH-1000XM5 — $248.00 (List Price $399.99) Deals are selected by our commerce team View the full article
-
AI is transforming companies everywhere. While some research has shown that women are falling behind in terms of AI adoption, at the leadership level women are highly involved in guiding AI strategy. According to new research from Chief, a network for senior women leaders, in partnership with The Harris Poll, women leaders are playing a key role in carefully building AI frameworks. The research, which polled 1,768 male, female, and nonbinary leaders, found that, overwhelmingly, women are driving AI strategy with 80% playing active roles in how it’s being implemented into workflows. Nearly a third (31%) said they were involved in AI governance, ethics, and responsible implementation. Another 25% said they design how humans and AI will work together in the organization, and 24% said they create and build AI solutions. Still, while women seem to be ahead of the game in shaping AI strategy, they are prioritizing responsible and intentional adoption over speed. According to the study, 83% of women agreed with the statement: “Being cautious about AI adoption is a sign of good leadership, not resistance to technology.” Still, the vast majority (68%) said that their organization prioritizes “speed over sustainable workforce implementation.” There’s a good reason for proceeding with caution: 62% of women respondents said their organization doesn’t fully understand “what AI can and can’t do.” Three-quarters said they expect critical thinking to decline if implementation doesn’t happen carefully and 81% said “capable managers” will become a thing of the past if companies don’t invest in their human workforce now. Similarly, a staggering 87% said they’ve already witnessed the fallout of companies focusing too heavily on an “AI only” approach that left employees underutilized. Alison Moore, CEO of Chief, said that doesn’t mean women are “slowing down” when it comes to AI’s implementation. They’re simply “making sure the humans keeping pace with it don’t get left behind in the process.” In other words, while some are ready to go all in on AI, women are leaning into their own critical thinking around AI implementation, so that critical thinking doesn’t disappear. This approach offers hope for the future during a time when AI is responsible for 25% of job cuts, except women are still only 29% of the C-suite. View the full article
-
Universal Music Group saw its shares (AMS: UMG) rise more than 11% on Tuesday, following a proposal from billionaire Bill Ackman to buy the music giant through his investment firm Pershing Square Capital Management. Pershing Square currently owns a 10% stake in Amsterdam-listed UMG. Despite today’s bump, the stock is down about 15% year to date. UMG has an extensive music catalogue and is home to major recording artists such as Taylor Swift, Bob Dylan, and Bad Bunny. What would the deal mean for UMG? If approved, the deal would offer shareholders €9.4 billion ($10.9 billion) in cash and 0.77 shares in “new UMG” for each share of UMG they currently own. Overall, this would equal out to €30.40 ($35.11) per share, a 78% premium compared to the closing price on April 2. If all goes well, shares could reach a 92% premium from that date by the end of 2026. Ackman details all of this in a letter to UMG’s board members, on which he sat until last year. The proposal would turn UMG into a Nevada corporation and list it on the New York Stock Exchange (NYSE)—something Ackman has pushed for since UMG’s 2021 IPO in the Netherlands. “While business performance has been strong, UMG’s share price has languished. Since the public listing in September 2021, revenues and Adjusted EBITDA have grown 60% and 70% respectively, while UMG’s share price has declined 23% from its €25.10 closing price on the first day of its Euronext listing.” How has UMG responded? So far, the company has not publicly responded to the deal. Fast Company has reached out to UMG for comment and will update this post if we hear back. In his letter, Ackman details a number of reasons he attributes to UMG shares’ “underperformance,” including postponing a listing on a U.S. stock exchange. He further points to “uncertainty” around Bolloré Group’s 18% stake in UMG, the lack of a “publicly disclosed capital allocation plan,” and “suboptimal” communication and engagement with shareholders. Plus, Ackman would like to see UMG sell its €2.7 billion ($3.1 billion) stake in Spotify. Ackman continued: “Notably, none of the above issues relate to the company’s execution of its music business, and importantly, all of the above issues can be addressed in a merger transaction.” Stipulations for the deal include a new contract and compensation agreement for CEO Lucian Grange, and a shakeup of the board. The latter would include making Michael Ovitz, cofounder of the Creative Artists Agency (CAA), the chair, and adding two additional Pershing Square members. This story is developing… View the full article
-
Something I live by in my role: departmental success means nothing unless the entire company is making progress toward its goals. That thinking changes everything about how I approach my job—from the metrics I care about to the conversations I have with the CEO and leadership team. I’ve moved beyond operating within the confines of a title or a narrowly defined scope. The lines between departments should be artificial, and what truly matters is taking ownership of the company’s success. Historically, the chief marketing officer (CMO) position was often confined to brand management, campaigns, and lead generation. Critical drivers like revenue, customer retention, and renewals were the responsibility of other departments. In my role, I am responsible for aspects of the entire customer journey, from initial awareness to purchase, adoption, expansion, and renewal. This evolution—from thinking in terms of departments to embracing company-wide accountability—is exactly where leadership needs to be. The most effective leaders don’t operate in silos, they take responsibility for outcomes across the entire customer journey and the entire organization. DO YOU THINK LIKE A CEO? The evolving business environment—driven by shifting customer expectations, rapid market changes, and advances in AI—demands leaders who can connect insights across functions and anticipate customer needs. Even if becoming a CEO isn’t your ultimate goal, adopting that mindset will drive you to reach even greater heights. If you aspire to become CEO, the conventional route to that role is evolving. Today, executives who possess deep customer insight, demonstrate strategic vision, and excel at rallying cross-functional teams around a shared purpose are more valuable than ever at the highest levels of leadership. By embodying these qualities, you position yourself much closer to top leadership than you may realize. For instance, the CMO-to-CEO path used to feel like a long shot in most industries. The typical route ran through finance or operations. But consider what is happening right now. Customer expectations shift constantly. AI is reshaping how companies communicate, sell, and serve. Markets evolve faster than annual planning cycles can keep up with. Today, advantage is defined by adaptability. The executives closest to customers, data, and the core narrative are increasingly the ones best equipped to run the company. LEAD BEYOND BOUNDARIES When leaders move beyond departmental boundaries they gain a holistic view of the business. This broader perspective uncovers patterns and opportunities that would otherwise remain hidden. It enables proactive identification of friction points, ensures messaging aligns with customer experiences, and leverages data from every interaction to deliver more relevant solutions. AI makes this even more powerful. Every interaction generates data. Every touchpoint creates insight. With access to the full lifecycle, I can use that data to anticipate what customers need before they ask for it. This approach isn’t about expanding territory or seeking power; it’s about fostering collaboration and aligning the organization around what matters most to customers and the business. It’s about recognizing that customers don’t care where one function ends and another begins—they care about seamless experiences and having their needs met. POSITIVE CHANGE AND COLLABORATION ACROSS TEAMS My current and former CEOs have been instrumental in helping me expand my role and think more broadly about business impact. They helped me realize I needed to stop thinking about staying in my lane and start thinking about how every decision affects company-wide outcomes from revenue to retention and customer lifetime value. That support made all the difference and has prompted me to advocate for a mindset shift that benefits both the organization and its leaders. When I adopted that perspective, I started having different conversations with my peers. I brought different insights into leadership meetings and made different decisions about where to invest time and resources. That shift made me better at my current job. Whether it leads to a CEO role someday is beside the point. READY TO THINK THIS WAY? Look at your goals. Are they department goals or company goals? If there’s a gap, close it—or at least make sure you can articulate clearly how your goals support and align with the company goals. Look at your accountability. Do you own outcomes or activities? Measuring campaigns is excellent; however, you should ensure it’s measured in terms of revenue. Look at your relationships with the rest of the C-suite. Are you seen as a peer, a service provider, a partner, an antagonist, manager, or stranger? The answer matters more than most CMOs realize. If you are seen as a peer and strategic partner by the rest of the C-suite it ensures alignment and credibility. The seat you occupy at the table determines whether the CMO helps set the agenda or simply executes it. I’ve found that thinking like a CEO—regardless of title—changes how I show up. It’s made me more effective and more valuable to my current company. And yes, it’s probably made me a stronger candidate for broader roles if I ever want them. Don’t just get better for the next role. Get better for this one. Melissa Puls is the chief marketing officer and senior vice president of customer success and renewals at Ivanti. View the full article