Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
Salesforce is stepping into a transformative era of sales with the launch of Agentforce Sales, a new model that empowers sales teams by leveraging artificial intelligence to streamline processes. For small business owners, this development could significantly change the way they approach sales, freeing up time to focus on building relationships and closing deals instead of getting bogged down in operational tasks. For years, sales teams have relied solely on human effort to manage everything from lead qualification to meeting preparation. This traditional approach comes with its own set of challenges, often leading to inefficiencies and lost opportunities. Salesforce aims to address these challenges with Agentforce Sales, which introduces a digital workforce designed to work alongside human sellers. The AI agents within this model manage the “operational grind” of selling—tasks like prospecting and lead nurturing—allowing sales teams to center their efforts on what they do best: engaging with customers. This reshaping of roles in the sales process could be a game-changer for small businesses that often have limited resources. Salesforce reports that sales teams utilizing Agentforce Sales can save up to 25 hours per week. This time can then be reinvested into deepening customer relationships and accelerating deal closure. According to Eswar Veluri, CTO of Equinox, “Agentforce can now engage with our prospects 24/7 and respond immediately— with all of the context needed to answer questions clearly, thereby improving our customer experience.” This capability could help small business owners enhance their customer service and improve satisfaction, which are critical drivers of repeat business. Agentforce Sales integrates directly into existing tools like Sales Cloud, Slack, and ChatGPT, putting everything in one accessible platform. The AI agents assist sellers at every step of the sales cycle. For example, the prospecting agent automates research and outreach, saving time by providing a prioritized list of potential leads based on clearly defined criteria. This feature can be particularly valuable for small businesses that struggle with lead generation due to limited manpower. Moreover, the engagement agent can book meetings and nurture leads effectively, allowing sellers to focus solely on the conversations that matter. The automation of meeting preparation further enhances productivity, giving small business owners the research and context they need at their fingertips before they even step into a meeting. Real-world applications of this technology are already yielding positive results. Equipter, for instance, reported a significant decrease in the time its sales reps spent following up with leads. David Beiler, VP of Sales, noted, “Agentforce helped us shorten that window and focus our team on higher-value conversations.” Such feedback highlights Agentforce’s potential to not just make sales processes more efficient but also more impactful. However, small business owners should consider potential challenges with this shift. Implementing an AI-driven model may require an initial investment in training, as sales teams will need to adapt to new workflows. Additionally, there may be concerns about how much control sellers retain when AI agents suggest actions. Having systems in place to ensure that sellers have final approval on AI-generated actions will be essential to maintain their confidence and engagement. Salesforce believes that the future of sales is in leveraging existing enterprise data and transforming it into actionable strategies with the help of AI. Having already worked with many organizations, including Salesforce itself, the results appear promising. “In four months, agents contacted 130,000 leads and created 3,200 opportunities,” said Adam Alfano, President of Sales. “Next year we believe these numbers will be 10x higher.” As small businesses look towards growth, adopting tools like Agentforce Sales could be an effective strategy not only for improving efficiency but also for fostering better customer relationships. The seamless integration into popular platforms like Slack makes it easier for teams to embrace the change without complicating their workflow. For small business owners interested in exploring this new frontier in sales, a virtual event hosted by Salesforce on March 18 will provide live demonstrations and hands-on workshops. Accessing this resource could offer valuable insights into how Agentforce Sales can fit into their operational strategies. With the right implementation strategy and a willingness to adapt, small business owners can harness the power of AI to transform their sales processes, setting the stage for increased productivity and growth. To learn more, visit the original Salesforce announcement here. Image via Google Gemini This article, "Salesforce Unveils Agentforce Sales: AI-Powered Team Reshapes Selling" was first published on Small Business Trends View the full article
-
Venture between carmaker’s Osnabrück plant and Rafael Advanced Defence Systems part of plan to save 2,300 jobsView the full article
-
Ultrahuman finally has a smart ring back on the U.S. market, and it’s the Ring Pro, the new model with the feature-packed charging case. Pre-orders are now open, with early bird prices starting at $349. The regular price will be $479 for the ring plus case. The ring will begin shipping May 15. The company is using a tiered model for early bird pricing, where the price bumps up after a certain number of rings are sold. Here’s the schedule: $349 — first 1,000 orders ($130 off) $389 — next 2,000 orders ($90 off) $429 — next 3,000 orders ($50 off) $449 — until pre-orders close. Ultrahuman’s smart rings have been off the U.S. market since October 2025, due to legal action by Oura. As I detailed here, Oura sued several other smart ring makers over patent infringement and won a judgment by the U.S. International Trade Commission. As a result, most other smart ring companies had to leave the U.S. market or reach a deal with Oura. Ultrahuman found a third option—continuing to develop a ring they already had in the works, betting that the ITC would rule its design is different enough that it does not infringe Oura’s patent. That bet seems to have paid off. U.S. Customs and Border Protection has officially signed off on the new design, allowing it to be sold here. Ultrahuman’s older designs, like the Ring Air I reviewed last year, are still banned. What’s new with the Ultrahuman Ring ProI wrote more about the Ring Pro here. It’s got a faster processor with “on-chip machine learning,” a 15-day battery life, and the ability to hold 250 days of data if you’re unable to sync your ring for extended periods. The physical shape is similar to the Ring Air (no sensor bumps, but there is a flattened area at the bottom of the interior), and it has break points for easier removal of the ring in an emergency. The cleverest feature of the Ring Pro is its charging case, which can store data, flash the firmware, and deliver haptic alerts. It also has a speaker for alarms and for sounding when you use the “find my case” feature. The charger can charge wirelessly. Ultrahuman has since announced that you’ll have the option to buy the ring packaged with the charging case for $479, or with just a “mini charger” (presumably similar to the Ring Air’s charger) for $399. The case will be available separately for $100. View the full article
-
SoftBank-owned tech group secures Meta and OpenAI as first customers of its long-awaited new AI processorView the full article
-
If you’re a minority entrepreneur, accessing the right business loans is vital for your success. Various options cater particularly to your needs, including SBA loans and alternative financing sources. These loans can help you overcome challenges unique to your demographic and empower your business to grow. Comprehending the types available and their particular benefits can make a significant difference. Let’s explore the fundamental loans that can support your entrepreneurial expedition. Key Takeaways SBA 7(A) Loans provide financing up to $5 million, ideal for minority-owned businesses seeking long repayment terms and lower interest rates. SBA Community Advantage Loans target underserved markets with amounts from $50,000 to $250,000, offering flexible repayment options and lower interest rates. The SBA Microloan Program offers microloans up to $50,000, focusing on entrepreneurial training for small business owners in underserved communities. Alternative financing options like Kiva and CDFIs provide accessible loans and crowdfunding opportunities for minority entrepreneurs with flexible requirements. Online lenders ensure fast funding and streamlined applications, making capital accessible to minority businesses with credit challenges or limited documentation. What Is a Minority-Owned Business? A minority-owned business is one that’s at least 51% owned, operated, and controlled by individuals from specific ethnic backgrounds, such as Black, Hispanic, Asian-Pacific, Asian-Indian, Native American, and Alaskan Native groups. In the U.S., these businesses represent over 12 million enterprises, accounting for more than 35% of all businesses. To access certain funding opportunities, minority business owners may need certification, which can improve their eligibility for specific minority business loans. Nevertheless, eligibility for this classification can vary by state, affecting access to various financial programs and resources. It’s essential to recognize that minority business owners often face unique challenges in securing financing. Research indicates they encounter higher loan rejection rates than their white counterparts, which underscores the need for targeted support. Comprehending these aspects can help you navigate the environment of business loans for minority entrepreneurs more effectively. The Importance of Business Loans for Minority Entrepreneurs Securing business loans is vital for minority entrepreneurs, especially given the financial barriers they often face in the marketplace. These funds not only help overcome higher loan rejection rates but also support the growth and sustainability of over 12 million minority-owned businesses in the U.S. Accessing business loans improves financial stability, allowing you to invest in expansion, inventory, and operational needs. Type of Funding Benefits Examples Business Loans Capital for growth SBA 7(a) loans Minority Trucking Grants Targeted support for trucking Funding for equipment Minority Grant Money Non-repayable funds Grants for operational costs Tailored business loans, including minority trucking grants and minority grant money for business, are fundamental for leveling the playing field, enabling you to thrive and compete effectively in the marketplace. SBA 7(A) Loans for Minority-Owned Businesses For minority entrepreneurs seeking financial support, SBA 7(a) loans represent a significant opportunity to secure the necessary capital for business growth. This program offers financing up to $5 million, with long repayment terms ranging from 10 to 25 years. Interest rates are typically lower than those of traditional loans, making it an attractive option. Approximately 32% of SBA 7(a) loans go to minority-owned businesses, underscoring the program’s role in promoting diversity. To qualify, your business must be for-profit, operate in the U.S., and be at least 51% owned by individuals from recognized minority groups, such as Black, Hispanic, or Native American. The application process requires a solid business plan, proof of financial stability, and a credit score of 680 or higher for better approval chances. Furthermore, the SBA 7(a) program provides access to valuable resources and mentorship, further supporting your business development. SBA Community Advantage Loans SBA Community Advantage Loans are a great option for small businesses in underserved markets, offering loan amounts between $50,000 and $250,000. With up to 85% of the loan guaranteed by the SBA, these loans help reduce risk for lenders and improve access to capital for minority entrepreneurs. You’ll find favorable terms, such as lower interest rates and flexible repayment options, making this program a valuable resource for your business needs. Loan Details and Benefits Accessing funding can be a pivotal step for minority entrepreneurs aiming to grow their businesses, and the Community Advantage Loan program offers a viable solution. This SBA-backed initiative provides loans of up to $250,000 particularly for small businesses in underserved markets, addressing the capital gap faced by many minority entrepreneurs. With up to 85% of the loan amount guaranteed by the SBA, lenders experience reduced risk, making financing more accessible for those who might struggle to secure traditional loans. The program focuses on supporting women, minorities, veterans, and other underserved business owners, as repayment terms typically range from 10 to 25 years, allowing for manageable cash flow. Since its inception, thousands of minority-owned businesses have benefited from this financial support. Eligibility and Application Process To qualify for Community Advantage Loans, businesses must meet specific requirements that cater to the needs of minority, women, and veteran entrepreneurs. Your business should be for-profit and located in the U.S. To be eligible, you’ll need a viable business plan and financial projections. You may additionally have to provide documentation proving your minority status. The application process starts with finding an SBA-approved lender participating in the Community Advantage program. After that, you’ll submit your loan application along with the necessary financial documentation. Unlike traditional loans, these loans feature more flexible qualification criteria, making it easier for you to access capital and support the growth of your business in underserved markets. SBA Microloan Program If you’re a minority entrepreneur looking for financial support, the SBA Microloan Program could be an excellent resource for you. This program provides loans up to $50,000, particularly targeting small business owners in underserved communities. These microloans are offered through nonprofit organizations and community-based lenders, making them accessible to those with limited credit history or financial resources. The average loan amount is around $13,000, which can be utilized for startup costs, inventory, or working capital. Repayment terms typically range from six months to six years, offering manageable options as your business grows. Moreover, the SBA Microloan Program goes beyond just financing; it includes entrepreneurial training and technical assistance, helping you develop the skills needed to succeed. Online Business Loans for Minorities As you explore financing options for your business, online business loans can be a valuable resource, especially for minority entrepreneurs. These loans often come with more flexible eligibility requirements than traditional financing, making them accessible to a wider range of applicants. Lenders like OnDeck and Fundation offer loans up to $500,000, with credit score requirements starting as low as 600. Moreover, BlueVine targets minority-owned businesses by providing short-term loans and lines of credit up to $250,000, particularly for those with around $100,000 in annual revenue. The application process is typically streamlined, allowing you to obtain funding quickly—an vital factor for timely business operations. Nonetheless, high demand can lead to limited capital availability. Consequently, it’s important for you to research and compare multiple lenders to find the best fit for your needs, ensuring you secure the necessary funds to support your business growth. Nonprofit Lending Options for Minority Entrepreneurs Even though many minority entrepreneurs face challenges in accessing traditional financing, nonprofit lending options provide a viable alternative that can help bridge the funding gap. Nonprofit lenders focus on supporting low- to moderate-income business owners, offering flexible solutions that traditional Bank of America might not. Here are some options to take into account: Accion: Loans from $300 to $1 million customized for minority entrepreneurs. Kiva: Up to $10,000 in no-interest financing through crowdfunding, leveraging your network. Union Bank’s Business Diversity Lending Program: Loans and lines of credit up to $2.5 million with 25-year repayment terms. Community Development Financial Institutions (CDFIs): Focused on underserved communities, providing flexible lending. Less stringent requirements: Nonprofit loans often have easier qualification criteria compared to traditional banks. These options can empower you to secure the funding necessary to grow your business. Alternative Financing Sources for Minority Businesses When exploring alternative financing sources for minority businesses, you’ll find a range of options customized to your needs. Nonprofit lenders provide flexible loans, whereas LendingClub streamline the application process, making it easier to access funds quickly. Furthermore, angel investors can offer capital in exchange for equity, giving you another avenue to contemplate as you grow your business. Nonprofit Lending Options Nonprofit lending options present a viable pathway for minority entrepreneurs seeking financial support. These organizations understand the unique challenges you face and offer customized solutions to bridge the capital access gap. Here are some key options available to you: Accion: Provides loans from $300 to $1 million for low- to moderate-income minority business owners. Kiva: Offers a crowdfunding model, allowing you to secure up to $10,000 in no-interest financing from your community. Union Bank Business Diversity Lending Program: Targets minority-owned businesses, with loans up to $2.5 million and terms of 25 years. Community Development Financial Institutions (CDFIs): Focus on underserved communities, offering flexible loans and support. Flexible qualifications: Nonprofit loans often have more lenient requirements than traditional banks, enhancing access to funding. Online Lender Advantages As you explore funding options, online lenders offer numerous advantages that make them an attractive choice for minority entrepreneurs. They often have more flexible eligibility requirements compared to traditional banks, making access easier for those with credit challenges or limited documentation. Many online lenders provide fast funding, allowing you to receive capital quickly, often within 24 to 48 hours after approval. Some lenders, like OnDeck and Fundation, particularly focus on minority businesses, offering customized loan products to meet diverse financial needs. Moreover, online platforms feature streamlined applications that require less paperwork, reducing barriers to funding. With competitive interest rates and quicker approvals, online lenders serve as a viable alternative for minority-owned businesses seeking immediate financial support to encourage growth. Angel Investment Opportunities Angel investment presents a unique opportunity for minority entrepreneurs seeking alternative financing sources. These investors provide funding in exchange for equity, allowing you to secure capital without the burden of repayment. Curiously, about 16.1% of minority entrepreneurs successfully obtain angel investment, with lower decline rates compared to traditional loans. To improve your chances of securing this funding, consider the following: Research active minority-focused angel investment groups. Prepare compelling pitches that showcase your business’s growth potential. Engage with networks of angel investors for mentorship opportunities. Understand that these investors value strong business viability. Leverage the financial and strategic support that comes with angel investment. Grants for Minority Business Owners Grants for minority business owners offer a valuable funding source that doesn’t require repayment, which can greatly ease financial pressures. These non-repayable funds are provided by various organizations, including government agencies and nonprofits, particularly designed to support eligible minority-owned businesses. Nonetheless, keep in mind that competition for these grants can be fierce, and availability may be limited. Notable opportunities include the FedEx Small Business Grant Contest, which awards cash annually, and the NASE Growth Grants, offering up to $4,000 for business growth initiatives. The First Nations Development Institute likewise provides targeted grants for Native-owned businesses, concentrating on economic development in indigenous communities. You can explore government grants through Grants.gov, where various funding opportunities await. How to Apply for Minority Business Loans Applying for minority business loans can be a crucial step in securing the funding you need to grow your enterprise. To get started, make sure your business is at least 51% owned by individuals from recognized minority groups. Next, gather important documents: A solid business plan outlining your vision Recent tax returns showcasing your financial history Accurate financial statements detailing your current status Proof of minority status to validate your eligibility Any additional documentation requested by lenders Identify lenders that specialize in minority business loans, like Community Development Financial Institutions (CDFIs) or those offering SBA-backed loans. Prequalifying with lenders helps gauge your eligibility without affecting your credit score. Finally, submit your application early and follow up to provide any extra information requested. This proactive approach can help guarantee a smooth processing experience and increase your chances of securing the loan you need. Frequently Asked Questions Are There Small Business Loans for Minorities? Yes, there are small business loans available particularly for minorities. Options include the SBA 7(a) Loan Program, which offers up to $5 million with favorable terms. Furthermore, Community Development Financial Institutions (CDFIs) and nonprofit lenders provide flexible loan criteria customized for minority entrepreneurs. You can likewise explore SBA Microloans, which give up to $50,000 for startups. Certification as a minority-owned business can further improve your access to funding opportunities and increase your market visibility. What Is the $2750 Small Business Grant? The $2750 small business grant is a financial resource designed to support small businesses with operational costs and growth initiatives. It’s typically offered by state or local government programs and nonprofit organizations. To qualify, you must operate a for-profit business, demonstrate financial need, and outline a clear plan for fund usage. Unlike loans, this grant requires no repayment, making it an attractive option for entrepreneurs seeking to reduce their debt burden. What Is the $10,000 Grant in Washington State? The $10,000 grant in Washington State is designed to support small businesses affected by the COVID-19 pandemic. To qualify, your business must have been operational since February 2020, employ 20 or fewer people, and show a revenue loss of at least 25% owing to the pandemic. You’ll need to complete an online application detailing your financial situation and intended use of funds, as grants are awarded on a first-come, first-served basis. What Is the Easiest Business Loan to Get Approved For? The easiest business loans to get approved for usually come from online lenders, who offer flexible eligibility criteria. If your credit score is around 570, you might still qualify. SBA Microloans are another option, providing up to $50,000 with lenient qualifications. Community Development Financial Institutions (CDFIs) focus on underserved areas, increasing your chances of approval. Finally, alternative lenders like OnDeck or BlueVine offer quick funding with streamlined applications, often approving loans within 24 hours. Conclusion In conclusion, minority entrepreneurs have access to various business loans customized to meet their specific needs. From SBA 7(A) loans to microloans and alternative financing options, these resources can greatly bolster your business’s growth potential. Furthermore, nonprofit lenders and grants provide further financial support. By comprehending and utilizing these options, you can improve your chances of success and navigate the challenges of entrepreneurship effectively. Explore these avenues to empower your business path and achieve your goals. Image via Google Gemini This article, "10 Essential Business Loans for Minority Entrepreneurs" was first published on Small Business Trends View the full article
-
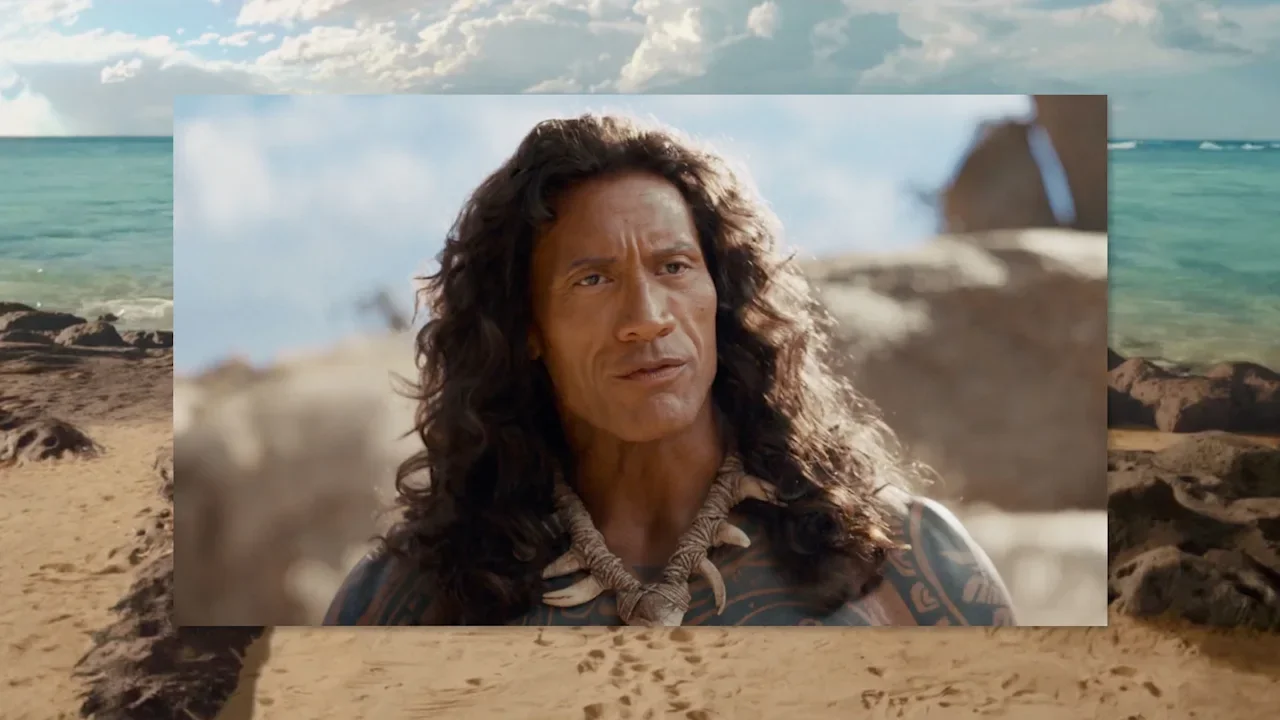
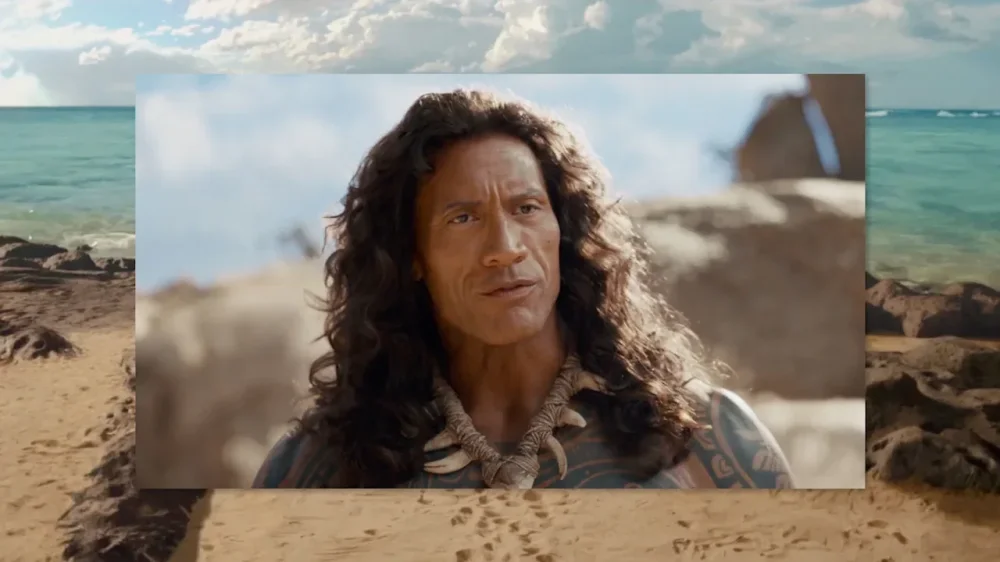
In 2015, Disney discovered a new way to cash in on nostalgia: live-action remakes of its classic animated films. That started with Cinderella, brought back to the big screen 65 years after the original movie premiered. In the decade since, Disney has released 12 more of those remakes, with the gap between the original films’ release dates and the remakes growing shorter and shorter. The next entry is a remake of 2016’s Moana coming to theaters this July, a few months shy of the original’s 10-year anniversary. Disney remakes are designed to recapture the magic of the source material, replicating iconic shots and rehashing beloved lines, scenes, and songs. But that creative philosophy has always raised a simple question: Why watch the remake, when the original animated film still exists? On Monday, March 23, Disney released the first trailer for its new take on Moana, putting that question center-stage like never before—and viewers across social media are dragging the remake to the Realm of Monsters and back. The trailer immediately stands out from the original for its lack of color, falling into the same desaturated camp as the Wicked films and modern Marvel movies. Users on social media placed stills from the trailer side by side with images from the original Moana, making the contrast unmistakable. As one user put it, the remake “literally just sucked up all the color” from Moana’s signature vibrant, tropical setting. literally just sucked up all the color this is awful https://t.co/5T62X8rdH7 pic.twitter.com/PAMcFhPK7p — 💋 Roxxi 💋 (@spicyroxxi) March 23, 2026 why is everything so bland and colorless? why is the lighting so ugly? nobody asked for this, the original moana was perfect. https://t.co/ECQlUYwv21 — ♡ (@glindaupland) March 23, 2026 pic.twitter.com/vl4rhmy5Dj — kevin l. lee (@Klee_FilmReview) March 23, 2026 Moana also stands out from Disney’s other live-action remakes for its casting. Where some of those films have used a buzzy star to provide a new take (at least nominally) on old material, like Emma Watson as Belle in Beauty and the Beast or Halle Bailey as Ariel in The Little Mermaid, the new Moana retreads the exact same casting strategy as the original movie: an unknown actress making her film debut as Disney Princess Moana—then Auli’i Cravalho, now Catherine Laga’aia—and Dwane “the Rock” Johnson as her companion Maui, whose live-action version sports a less-than-stellar wig that’s drawn its own wave of ridicule. Im sorry, these live action Disney remakes need to die. Absolutely embarrassing on all levels. https://t.co/uwT2kOx2s8 pic.twitter.com/KT20XlynSo — The Moonlight Warrior 🌙 (@BlackMajikMan90) March 23, 2026 this looks like some snl sketch im crying https://t.co/rHnUYYPTAS pic.twitter.com/O2heWCHM8B — chia (@julianmiflaco) March 23, 2026 Johnson’s casting marks the first time an actor from an original Disney film is reprising their role in its remake. He may be a big name, but social media users see his rehashed casting as another strike against the film: “Hundreds of millions of dollars wasted so Dwayne Johnson can don a terrible wig and deliver the same lines but with worse timing,” one poster lamented. Recasting the same actor in a principal role only adds to the question at the center of the discourse: What sets this Moana apart from the original, let alone makes it the better viewing option less than 10 years later? Hundreds of millions of dollars wasted so Dwayne Johnson can don a terrible wig and deliver the same lines but with worse timing. New low for the corporate slopmongers. Can't even make it past the two min mark of this trailer, I don't need to see anything from the last 19 seconds https://t.co/81kEzT6Zlc — Schaffrillas (@Schaffrillas) March 23, 2026 At risk of hyperbolizing it’s hard to think of any films as cynically conceived, poorly made, and artistically barren from top to bottom as these godawful Disney “live action” remakes. — youth code orange (@thamosdeaf) March 23, 2026 By far the most insulting one so far. – barely a decade old – there’s no “new story to tell” – can’t use the “remastered” excuse just a flagrant insult to animation, and a cheap money grab https://t.co/B0lUQqNysm — Aidan Pocock (@Dunaidan3019) March 23, 2026 Though that answer may be unclear to critics online, Disney’s box office success speaks for itself. In 2019, the Lion King remake made Disney $1.6 billion worldwide, now sitting as its third-highest-grossing film of all time. 2017’s Beauty and the Beast, 2019’s Aladdin, and 2025’s Lilo & Stitch also crossed that billion-dollar threshold, proving that despite any online outrage, Disney’s remakes are still among its best-selling ventures. That doesn’t mean those movies are necessarily superior to their originals (and any diehard Disney fans would no doubt balk at that very idea), but as long as they’re putting butts in seats, they’re not likely to stop being made any time soon. The new Moana trailer ends with a gag that exemplifies why some stories are best told through animation. Maui, a shapeshifter, gets stuck mid-transformation, with the body of a human and the head of a shark. In the original Moana, the moment was a charming joke that resulted in a cutesy hybrid worthy of being turned into a Funko Pop. In the remake, it’s an off-putting abomination that’s somehow meant to strike the same tone—a descriptor that might just fit the movie itself. They didn’t even use the same type of shark 😭 https://t.co/NJSUvMcFYr — Michael (@TheMG3D) March 23, 2026 View the full article
-
There’s a restaurant in New York City called Rosa Mexicana that positions itself as a fresh take on Mexican cuisine. It’s upscale, well curated, and delicious. However, my favorite part about the dining experience is when you order guacamole, the wait-staff wheels out a little cart, draped in the traditional Mexican cloth, a vibrant sarape, and staked with fresh ingredients—avocados, lime, onion, salt, all the things. And as they arrive at your table, they make the guacamole right there in front of you. It’s quite the show, and it makes the entire dining experience better. What the restaurant has realized is what some of the best organizations know to be true: when the backstage is optimized, not only does it improve the organization’s front stage performance, but it also becomes a part of the show itself. In a healthy organization, the front stage and the backstage are not separated by a physical wall or partition, but rather by the boundaries of the organization’s cultural conventions—its organizational culture. Consider the alternative: quick service restaurants. In most QSRs, the backstage is completely opaque. You order at the front, and your request is signaled to the back before it is handed off in a paper bag. You typically can’t see how the food is made; that’s not a part of the performance. In most cases, you don’t want to see it either, in hopes of maintaining an imagination about its preparation that may not coincide with reality. In most cases, for most QSRs, the backstage of the organization—its culture—is not optimized. They have policies and processes, detailed steps of what to do, but their cultural conventions stop there. But culture is more than what we do; it’s an operating system that is anchored by shared perspectives. Therefore, a culture that operates on rules and regulations only, falls short of its potential. Will Guidara, the Michelin-star restaurateur of Eleven Madison Park fame, believes in the idea of unreasonable hospitality, which is the grounding conviction that powers the behaviors of the organization. It’s an open kitchen because the backstage and the front stage are connected by a commitment to unreasonable hospitality. That’s the boundary that curates the company culture and, therefore, its practices and policies follow suit. That holds for non-Michelin restaurants, also. Take Domino’s, for example. The pizza giant found itself in a slump. Sales were down and public perception of the brand had soured. So, what did the company do? It decided to optimize the backstage of the organization and center everything they did on transparency—inviting people in who had lost trust in the company. They installed webcams so people can see their pizza being prepared. They created a tracker, so you knew exactly where your pizza was in the process and when to expect it at your door—long before food delivery services offered this convenience and years before Uber car service came to market. The result of this cultural optimization completely turned the company around and catapulted their dominance as well as their stock price. This idea of front stage and backstage is not relegated to the food industry only; it applies to organizations more broadly. TED is a good example of this. The non-profit organization, famous for its TED talks, is anchored on the premise of discovering and sharing ideas that drive meaningful change. This belief informs everything the organization does, from the hero event in Vancouver each year to the talks it shares online and the local TEDx events it franchises with people and institutions who share the same belief. Even their partners and sponsors, they, too, are bought into this belief and guarded by this boundary; thus, every touch point of TED feels like…TED. The backstage and the front stage is consistent. After giving three TEDx talks myself, I know this firsthand. Everyone involved is committed to presenting ideas worth sharing. How does your organization fare against this open kitchen idea? What are the ideological boundaries of the organization that connect the front stage and the backstage? If your organization was an open kitchen; how good would the performance be? This line of thinking offers leaders an opportunity for leaders to not only address their cultural challenges but also drive greater business realities. If we want the front stage to flourish, we should consider optimizing the backstage first. To explore this further, we welcomed Laura Beyer, the head of partnerships at TED, onto the FROM THE CULTURE podcast in hopes of further understanding the relationship between the front stage and backstage of an organization. Check out the full episode here. View the full article
-
We may earn a commission from links on this page. If you've taken a look at the back of your computer monitor or TV lately, you may have noticed there's a USB port or two alongside the more familiar HDMI—and that in turn might have left you wondering what exactly a USB port is doing on the back of a big screen. Well, these USB ports have more uses than you might think. Their precise function is going to depend on the make and model of your TV and monitor—and the primary uses tend to differ between the two. However, we can talk generally about how to make use of these ports and some of the options available to you, so you can check on your own specific device to see what's supported. The extra ports can charge your devicesThis is a big one, because it applies to just about every USB port on every TV and monitor: You can plug in small gadgets like phones and charge them up, though charging rates and supported devices may vary, especially on televisions. It saves you having to hunt around for a spare wall outlet, at least. On higher-end monitors with support for USB Power Delivery (USB-PD), you can sometimes charge up larger devices like laptops, while also providing a video connection through the same USB-C cable. It's something to look out for if you're shopping around, as it helps reduce desk clutter and adds convenience—the $620 4K Dell U2725QE is one example of a monitor that will do this for you. With Android smartphones and monitors, you might get the added bonus of support for a desktop environment on the big screen as well as device charging. Both Samsung DeX and the recently launched Pixel Desktop Mode can be used like this, so you might be able to attach a desktop or laptop via HDMI, and a phone via USB-C. Set up a USB hub for cleaner cable maintenanceAs well as device charging, some monitors also add USB hub functionality, especially at the higher end of the market—if you've got several USB-A ports on the back of your monitor, this is likely what they're for. Rather than plugging all your peripherals into your laptop or desktop computer, you can add them to your monitor instead. It's a solution that's often neater and removes the need for a separate USB hub on your desk — with a separate upstream USB cable handling the connection to your computer, if it's not attached via a single data and video cable. You might even see an Ethernet port on some models, giving you a high-speed wired connection to the internet for your laptop. The $260 1080p ViewSonic VG2456 is one such model, and they often offer great value for office use. Connect external storage to display photos and videosThis is a primary one for TVs, including certain Samsung models: You can plug an external USB drive into the back of your television, and access the photos, videos, or audio on it, provided the drive and file formats are supported. You can also do this via the USB ports on monitors, via the USB hub functionality mentioned above. If you've got a large local media library saved somewhere, then this is a simple and quick way of getting those media files up on the big screen (rather than using something like Plex). You're most likely not going to get the most advanced user interface you've ever seen, but it'll work. With the rise of streaming and faster wifi connections, the functionality is now becoming less common, but it's still around—consult your TV documentation for details (Sony's instructions are here). A portable drive such as the $90 WD Elements should be suitable, but be careful to check the requirements listed by your TV manufacturer. Set up a KVM switch for multiple devicesA variation on the USB hub idea is a KVM (Keyboard, Video, Mouse) switch, which can be incredibly useful if you have more than one computer connected up to your monitor (maybe a laptop and a desktop). You can plug your keyboard and mouse into the USB ports on the display, and then use them to control each computer in turn. You can buy these KVM switches separately, but having one built into your monitor cuts down on the number of trailing cables you have to deal with. Once your peripherals are connected, you can typically switch via the monitor's on-screen menu, or through a dedicated hardware button. Perhaps you've had this functionality on your monitor and never realized. A good example of this type of display is the $800 4K Gigabyte M32U aimed at gamers, which does have an integrated button specifically for switching between computers (plus a load of other high-end features, as you would expect at that price). The Gigabyte M32U has an integrated KVM switch. Credit: Gigabyte Those extra ports support a bunch of other devices, tooJust about anything that can be powered by USB can be plugged into one of the spare ports on your TV or monitor (if the power demands and supply match). Maybe you could add a desk fan for keeping you cool through the summer months, or maybe you want to get creative with a smart light setup. For monitors with USB hub functionality, you can think about options like microphones, webcams, and gaming controllers—which can all be easier to plug into a big display rather than a laptop (if your laptop even has any spare USB ports left). It's well worth having a look around the back of your TVs and monitors to see what's available—you might not be using these devices to their full potential. It's also something to look out for the next time you're upgrading. View the full article
-
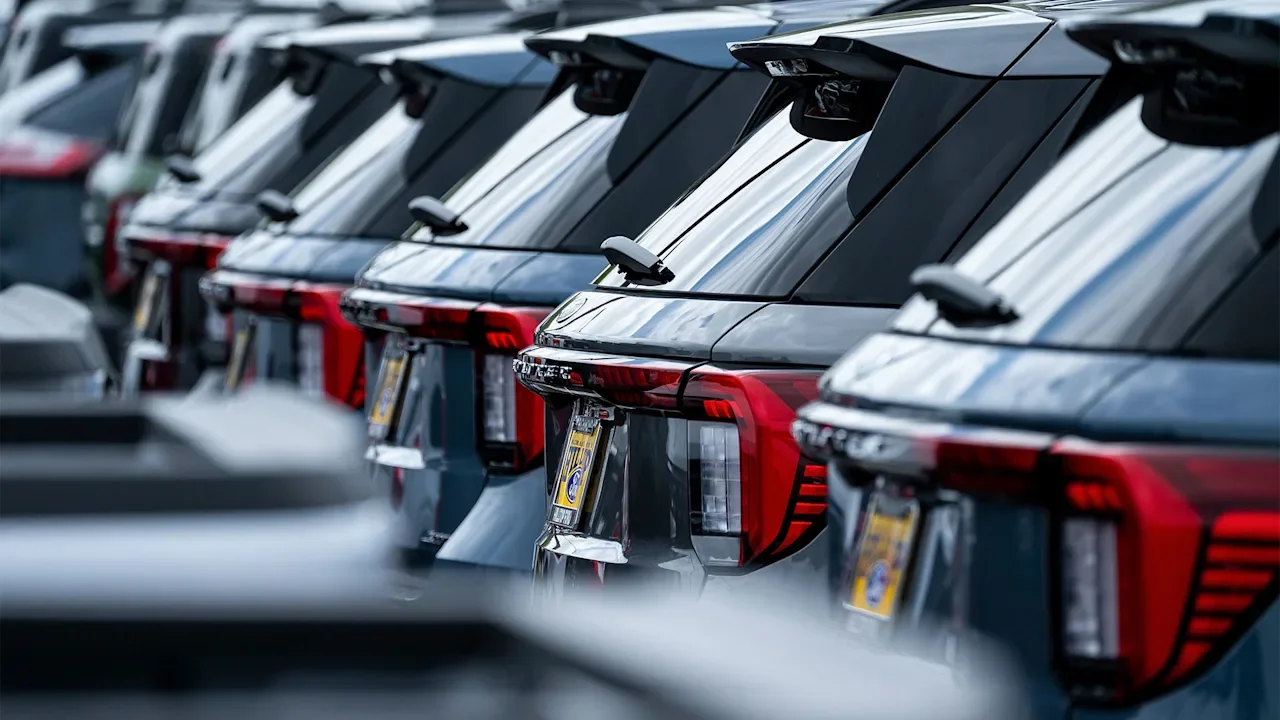
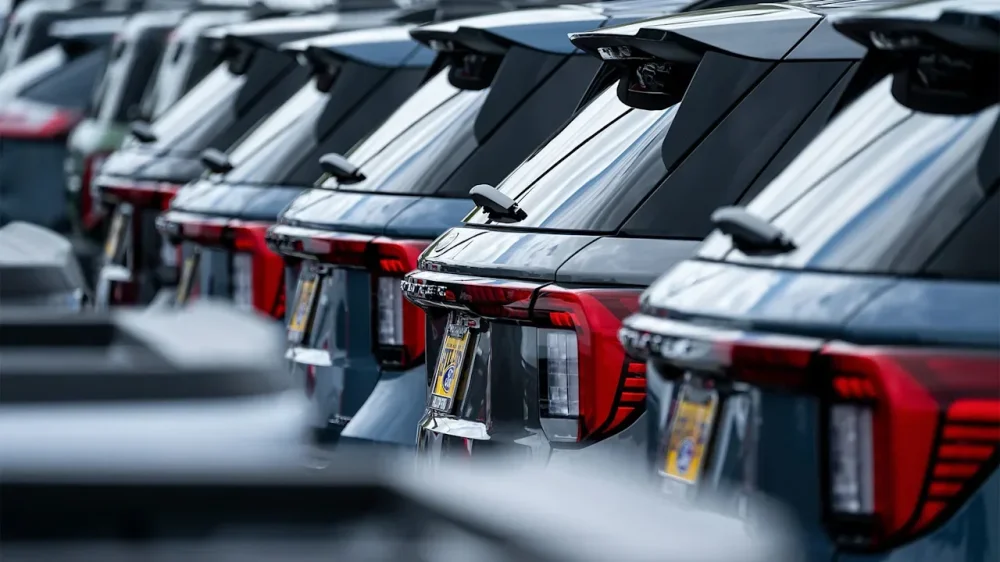
Another day, another Ford Motor Co. recall. This time, the company is recalling 254,640 vehicles due to a potential issue with the rearview camera image. According to the National Highway Traffic Safety Administration (NHTSA), the affected cars all have an Image Processing Module A (IPMA) that might reset unexpectedly. This reset can cause people to lose the rearview camera image and their advanced driver assistance features. The latter includes tools such as blind-spot monitoring, lane-keeping assist, and pre-collision assist. The NHTSA warns that a person might have a greater risk of crashing without these features. Ford has not learned of any related incidents due to this defect. Do you own a Ford? Here’s what you need to know about the recall. What Ford vehicles are included in the latest recall? Starting tomorrow, March 25, you will be able to search specific vehicle identification numbers (VINS) on NHTSA to see if your car is included in the recall. A notification letter should also be mailed to you by next Monday, March 30. In the meantime, the NHTSA has provided a breakdown of affected Ford vehicles and their production dates: 2022-2025 Lincoln Navigator: Produced April 15, 2021 to November 26, 2025 2024-2025 Lincoln Nautilus: Produced September 4, 2022 to August 26, 2025 2025 Ford Explorer: Produced November 29, 2023 to July 16, 2025 2025 Lincoln Aviator: Produced November 29, 2023 to May 21, 2025 How will the Ford recall take place? Ford plans to use an Over-The-Air (OTA) update to fix the IPMA software. However, owners with affected cars can also go to a Ford or Lincoln dealer to get the software update. Both options will incur no cost and dealers should be made aware starting tomorrow, March 25. Ford has a record-breaking number of recalls In 2025 alone, Ford issued 153 recalls for over 12 million vehicles—a record-number of recalls for any car company, Forbes reports. Less than three months into 2026, Ford already has a number of other recalls under its belt. For instance, Ford recalled almost 413,000 Explorer SUVs last month due to a faulty rear suspension component. View the full article
-
The majority of President The President’s tariffs were struck down earlier this year by the Supreme Court, but a number remain in place, with the threat of higher tariffs still to come. While the importers of tariffed goods are the ones who pay the actual tariff costs up front, they generally pass the cost of those tariffs onto you, the consumer, through higher prices. But just how much extra can you expect to pay this year based on the current tariff situation? That depends heavily on several factors, including your income level, your household size, and where you live in the country. The average household will pay around $600 in 2026 due to tariffs The good news is that the amount the average household will pay out during 2026 due to The President’s tariffs is down from their 2025 levels, reports CNBC. In 2025, the average US household incurred about $1,000 in tariff-related expenses, according to an analysis by the nonpartisan Tax Foundation. But in 2026, that number is expected to shrink to about $600 per household on average. That figure is in the same range as what an analysis by Yale University’s Budget Lab found: that in 2026, the average household will pay around $570 in tariff-related costs. However, as CNBC notes, the additional costs a household will bear from tariffs can vary widely depending on several factors. The most significant factor is family size. After all, a household with six family members needs to buy a lot more goods throughout the year than a household with a family of three. These goods encompass everything from food to electronics. But CNBC also notes that another important factor in how much an individual household will pay is where that household is based. Households in high-cost states like California will inevitably pay more in tariff expenses than those in lower-cost states like Alabama. This is because the cost of goods in high-cost states is generally higher than in low-cost states, so the impact of tariff-related cost rises is greater. Wealthier households pay more in tariff costs, but low-income households are more impacted The more tariffed goods a household buys, the more exposure they’ll have to increased prices. And since wealthier households tend to buy more goods, those households will naturally pay more in tariff-related price rises than lower-income households. However, unfortunately, it is lower-income households who will see a greater impact on their overall finances than wealthier ones. That’s because while wealthy households may incur a higher dollar value in tariff costs, lower-income households will incur more of a loss as a percentage of their entire income. For example, as CNBC points out, Yale Budget Lab found that the bottom 10% and top 10% of households by income are expected to incur around $315 and $1,325 in tariff costs, respectively. But $1,325 in tariff costs for a wealthy household amounts to just a 0.3% reduction in after-tax income on average, whereas $315 in tariff costs for low-income households amounts to an after-tax income reduction of 0.8%. In short, while tariffs will affect nearly every American, they will have a greater negative impact on those who live in larger households in high-cost states and are on the lower end of the income spectrum. View the full article
-
Comprehending the Franchise Disclosure Document (FDD) is crucial for making informed investment decisions in franchising. This document outlines critical information about the franchisor, including financial obligations and potential profitability. Key sections, like Item 19, detail financial performance, whereas others reveal costs and support systems. By analyzing these factors, you can better gauge the viability of your investment. Nevertheless, identifying red flags in the FDD can greatly impact your choice. What should you look for next? Key Takeaways Review the FDD thoroughly to understand franchisor history, financial obligations, and franchisee rights before making investment decisions. Analyze Item 19 for Financial Performance Representations to gauge potential profitability and earnings variability of the franchise. Identify and evaluate all initial and ongoing costs outlined in the FDD, including franchise fees and royalties, for effective financial planning. Look for red flags such as high costs, vague operational support, or unclear financial performance that may indicate potential risks. Engage with current franchisees for insights into support effectiveness and satisfaction, ensuring a well-rounded understanding of the franchise opportunity. The Importance of the Franchise Disclosure Document (FDD) When you consider investing in a franchise, grasp of the Franchise Disclosure Document (FDD) is crucial. This legal document must be provided to potential franchisees at least 14 days before any agreements are signed. The FDD comprises 23 key items that cover critical aspects, including franchisor history, financial obligations, and franchisee rights. Item 19 of the FDD directly addresses Financial Performance Representations (FPR), offering insights into profitability and earning potential. Key Sections of the FDD Every Franchisee Should Know When reviewing the FDD, you’ll want to pay close attention to the sections that provide insights into the franchisor’s background and financial performance data. These parts help you assess the brand’s reliability and comprehend potential profitability, which are essential for making informed decisions. Grasping these key areas sets the stage for a successful franchise investment. Franchisor Background Insights Grasping the franchisor’s background is crucial for anyone considering a franchise investment, as it provides insights into the stability and reputation of the business. The Franchise Disclosure Document (FDD) includes critical information about the franchisor’s history, helping you assess their market presence and reliability. You should review the management team’s experience and industry track record, which can indicate their capability to support franchisees effectively. Moreover, the FDD discloses any litigation history from the past ten years, revealing potential risks. Instances of bankruptcy are significant to note, as they highlight the franchisor’s financial health. Comprehending these aspects allows you to gauge the brand’s longevity and adaptability, ultimately aiding in making informed investment decisions. Financial Performance Data Grasping the financial performance data in the Franchise Disclosure Document (FDD) is essential for evaluating a franchise opportunity. This data, found in Item 19, includes Financial Performance Representations (FPR) that reveal the profitability and earning potential of the franchise. You should carefully review both historical financial data and any projections, as discrepancies may indicate variability in earnings potential. The FDD often includes earnings claims from existing franchisees, serving as benchmarks to assess potential profitability. Moreover, pay attention to the disclaimers with the financial data, as they highlight the variability of results based on individual performance. Comprehending this information helps you compare potential returns against the required initial and ongoing costs, guiding your investment decisions effectively. Evaluating Franchise Costs and Financial Commitments When evaluating franchise costs, it’s crucial to take into account both initial fees and ongoing royalty expenses. The Franchise Disclosure Document (FDD) outlines these financial commitments, typically ranging from $10,000 to $50,000 for startup costs, which can greatly impact your budget. Comprehending these obligations will help you make informed decisions about your investment and guarantee your financial plans align with the demands of running a franchise. Initial Franchise Fees Grasping initial franchise fees is fundamental for anyone considering entering the franchise business, as these fees typically range from $10,000 to $50,000 and represent the upfront investment needed to access the franchise system and brand. The Franchise Disclosure Document (FDD) details these costs in Item 6, which includes franchise fees, equipment purchases, and startup expenses. Comprehending this breakdown is critical for effective financial planning, ensuring potential franchisees are aware of all necessary investments before launching their operations. Evaluating initial franchise fees helps you align your financial commitments with your investment goals. Cost Component Estimated Range Purpose Franchise Fee $10,000 – $50,000 Access to brand and system Equipment Purchases Varies by franchise Key for operations Startup Expenses Varies by location Initial operating costs Ongoing Royalty Expenses After grasping the initial franchise fees, the focus shifts to ongoing royalty expenses, which play a crucial role in the financial framework of a franchise. Typically, these expenses range from 4% to 12% of gross sales, depending on the industry and brand. These fees are essential for the franchisor to maintain brand development, marketing, and ongoing support for franchisees. As a potential franchisee, you must evaluate these ongoing costs against your estimated revenues to guarantee the franchise’s financial viability. Franchise agreements often outline how royalties are calculated—whether based on gross sales, net sales, or other metrics—which can considerably impact your overall expenses. Comprehending these implications helps you plan your long-term financial commitments effectively. Identifying Red Flags in the FDD Identifying red flags in the Franchise Disclosure Document (FDD) is crucial for potential franchisees, as it can help you avoid costly mistakes. Look for high initial fees or ongoing costs that exceed industry standards, which may indicate financial strain. Vague language about operational support or franchisee obligations can reveal a lack of commitment from the franchisor. Furthermore, a lack of clarity in financial performance representations may signal unreliable earnings potential. Be cautious of numerous litigation cases or recent bankruptcies, as these indicate operational instability. Finally, unclear or overly restrictive territorial rights can limit your growth opportunities. Red Flag Type Warning Sign Potential Impact High Fees Initial costs exceed industry standards Financial strain Vague Language Unclear support or obligations Franchisor commitment Lack of Transparency Unclear financial performance Unreliable earnings Litigation History Numerous cases or recent bankruptcy Increased operational risk Restrictive Territorial Rights Unclear growth opportunities Unnecessary competition Understanding Franchisee Support and Training Opportunities When you consider investing in a franchise, grasping the support and training opportunities offered by the franchisor is vital to your success. Initial training programs typically cover fundamental operations, brand guidelines, and marketing strategies, preparing you to run your business effectively. Ongoing support often includes access to updated training resources, field representatives, and networking opportunities with other franchisees, which help maintain best practices. The Franchise Disclosure Document (FDD) outlines the specific training obligations of both you and the franchisor, ensuring clarity on available support. Be sure to inquire about ongoing training beyond the initial setup, as this can greatly impact your long-term success. Engaging with current franchisees during the FDD review process can provide valuable insights into the effectiveness of the support provided. Assessing Brand Reputation and Franchisee Satisfaction Evaluating brand reputation and franchisee satisfaction is crucial for anyone considering a franchise investment, as these factors can greatly influence your business’s potential for success. Start by reading online reviews and checking franchisee satisfaction surveys to understand the brand’s market perception. Investigate the franchisor’s track record for longevity and adaptability, which can reveal system stability. Speaking with current and former franchisees about their experiences can provide valuable insights into support and profitability levels. Furthermore, assess the frequency and nature of litigation against the franchisor, as this can indicate possible risks impacting franchisee satisfaction. A strong reputation, coupled with high franchisee satisfaction, often reflects a franchisor’s commitment to ongoing support and brand integrity, critical for long-term success. Frequently Asked Questions What to Look for in an FDD? When reviewing an FDD, focus on key sections. Start with Item 1 to comprehend the franchisor’s background and stability. Look at Item 6 for the initial fees and ongoing costs, as this affects your financial commitment. Item 19 provides insights into profitability, whereas Item 15 outlines your obligations as a franchisee. Finally, assess Item 12 to identify any potential risks associated with the franchise. Each section contributes to a well-rounded comprehension of the opportunity. How to Determine if a Franchise Is Good? To determine if a franchise is good, analyze the Franchise Disclosure Document (FDD) carefully. Focus on Item 19 for financial performance insights, and review Item 3 to check for any litigation history. Evaluate the costs in Items 6 and 8 to guarantee they fit your budget. Speak with current franchisees about their experiences, and consider the brand’s reputation and management team’s strength, as these factors are essential for long-term success. When Should a Potential Franchisee Receive the FDD? You should receive the Franchise Disclosure Document (FDD) at least 14 days before signing any agreements or paying fees. This waiting period allows you to review the document thoroughly, ensuring you understand the franchise’s risks and benefits. The FDD is provided after you submit an application, and franchisors are legally required to deliver it prior to any financial commitments. Be aware that state laws may impose additional disclosure requirements or waiting periods. What Is the Importance of FDD in Franchising? The Franchise Disclosure Document (FDD) is vital for anyone considering a franchise investment. It provides fundamental information about the franchisor’s operations, including fees, obligations, and financial performance. Conclusion In summary, comprehension of the Franchise Disclosure Document (FDD) is crucial for making informed investment decisions in franchising. By carefully analyzing key sections such as financial performance, costs, and support systems, you can gauge the viability of a franchise. Pay attention to any red flags and research brand reputation to guarantee your investment aligns with your financial goals. A thorough evaluation of the FDD will empower you to choose a franchise that meets your expectations and improves your potential for success. Image via Google Gemini and ArtSmart This article, "How to Understand FDD Franchise Meaning for Better Investment Decisions" was first published on Small Business Trends View the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. Think smart lighting is limited to basic bulbs and LED strips? Govee proves otherwise with its unique, space-saving take on floor lamp smart lighting that actually brightens an entire room rather than acting as accent lighting. Available in three different colors, the Govee Floor Lamp 2 does everything from play music to set the mood—and right now, it's at its lowest price ever ahead of Amazon’s Big Spring Sale, dropping 25% to $119.99 (originally $159.99). Govee Floor Lamp 2 $119.99 at Amazon $159.99 Save $40.00 Get Deal Get Deal $119.99 at Amazon $159.99 Save $40.00 At 1,725 lumens, the sleek and minimalist Govee Floor Lamp 2 is one of the brightest smart lighting options around. It supports Matter, making it compatible with Apple HomeKit, Alexa, Google Assistant, and SmartThings. Lighting is highly customizable, with over 80 preset scenes and DIY modes that let you fine-tune colors, effects, and gradients. It uses RGBIC tech, which lets users display multiple colors at once, and it can sync with other Govee lights. It also has Bluetooth speakers in the base that pair with audio, creating a more immersive experience, whether you’re hosting a party or gaming. CNET notes that the lamps are designed so that light faces the wall, making them ideal for corners where you want to “paint” your wall with a glow of the almost infinite colors available for an accent wall effect. There are LEDs in the base as well as the main lights, and they can be controlled independently in the Govee app, where users can unlock most features. You can also control the lights via voice control or the included remote. It’s worth noting that the light only supports 2.4GHz wifi. If you’re looking for a stylish smart light that integrates with any smart-home setup, has a built-in speaker, and brings all the vibes, the Govee Floor Lamp 2 is an easy way to boost your ambiance and jazz up small spaces with customizable lighting, music sync and other features that punch above its price point, especially when it’s at an all-time low in this early Amazon Big Spring Sale deal. Our Best Editor-Vetted Amazon Big Spring Sale Deals Right Now Apple AirPods 4 Active Noise Cancelling Wireless Earbuds — $149.00 (List Price $179.00) Apple iPad 11" 128GB A16 WiFi Tablet (Blue, 2025) — $299.00 (List Price $349.00) Sony WH1000XM6- Best Wireless Noise Canceling Headphones — $398.00 (List Price $459.99) Apple Watch Series 11 (GPS, 42mm, S/M Black Sport Band) — $299.00 (List Price $399.00) Blink Video Doorbell Wireless (Newest Model) + Sync Module Core — $35.99 (List Price $69.99) Ring Indoor Cam Plus 2K Wired Security Camera (White) — $39.99 (List Price $59.99) Fire TV Stick 4K Max Streaming Player With Remote — $34.99 (List Price $59.99) Amazon Kindle Colorsoft 16GB 7" eReader (Black) — $169.99 (List Price $249.99) Deals are selected by our commerce team View the full article
-
As soon as new AI products are released, security researchers and pranksters begin probing them for weaknesses, trying to push systems to violate their own safety precautions and coax them into producing anything from offensive content to instructions for building weapons. After all, AI risks are not just theoretical. In recent months, various AI companies have faced criticism for their software allegedly contributing to mental illness and suicide, nonconsensual fake nude images of real people, and aiding hackers in cybercrime. At the same time, techniques for bypassing safeguards also continue to evolve, with recent methods including everything from malicious prompts disguised with poetry to surreptitiously planting ideas in AI assistant memories via innocuous-looking online tools. But long before new models reach the public, internal security teams are already stress-testing them. At Microsoft, that responsibility largely falls to the company’s AI Red Team, a group that since 2018 has worked with product teams and the broader AI community to pressure-test models and applications before bad actors can. In cybersecurity parlance, a red team focuses on simulating attacks against a system, while a blue team focuses on defending it. Microsoft’s AI Red Team is no exception, exploring a wide range of safety and security concerns—from loss-of-control situations where AI evades human oversight to issues around chemical, biological, and nuclear threats—across an assortment of AI software. “We see a really, really diverse set of tech,” says Tori Westerhoff, principal AI security researcher on the Microsoft AI Red Team. “Part of the kind of magic of the team is that we can see anything from a product feature to a system to a copilot to a frontier model, and we get to see how tech is integrated across all of those, and how AI is growing and evolving.” In one case, says Pete Bryan, principal AI security research lead on the Red Team, members worked with other Microsoft researchers to test whether AI could be manipulated into assisting with cyberattacks, including generating or refining malware. They experimented with framing questions in benign ways, such as describing a student project or security research scenario, then pushing systems to produce increasingly detailed outputs. The effort went beyond simple prompt testing. Researchers evaluated whether the AI could generate code that actually compiled and ran, and whether certain programming languages increased the likelihood of harmful outputs. In the worst case, Bryan says, the systems produced code comparable to what a low- to mid-level hacker might already create, but the team still refined detection systems to better flag such behavior. “In the future, if a more capable model comes along that could add value, we’ve already gotten ahead of this,” Bryan says. Today, the Red Team includes several dozen specialists with backgrounds ranging from software testing to biology. The group also works closely with external experts and peer teams across the AI industry. Bryan and Westerhoff gave a talk at the RSAC conference on March 24, and the team has released open-source tools including an automated testing framework called PyRIT (which stands for Python Risk Identification Tool), along with guidance for evaluating AI systems. The team’s efforts have recently been cited in Microsoft’s own work, including the announcement of an image generation AI model unveiled on March 19, and in third-party releases, like the “system card” explaining the functionality and testing of OpenAI’s GPT-5 model. Microsoft has also recently published AI safety research exploring potential risks around AI fine-tuning and methods for spotting hidden backdoors, or purposely hidden security and safety flaws, in open-weight models. As AI ecosystems expand to include more advanced copilots, autonomous agents, and multimodal systems capable of generating text, images, audio, and video, the Red Team’s mandate has grown more complex. Many of today’s use cases, from automated coding to AI-driven shopping and video generation, would have sounded like science fiction only a few years ago. “For my team, I think that’s part of the fun, that you see so many diverse things,” Westerhoff says. “It’s not just that we’re testing models day in and day out, but we’re actually testing how models go through the entire technological ecosystem.” View the full article
-
Negative online reviews can have a profound impact on your business, affecting everything from sales to reputation. Research shows that potential customers often avoid businesses with low ratings, which can lead to significant revenue losses. Furthermore, these reviews can damage your brand’s trustworthiness and hinder your visibility in search engine results. Comprehending these effects is crucial for steering through today’s digital environment. So, how can you effectively manage and respond to negative feedback? Key Takeaways Negative online reviews can deter up to 80% of potential customers, significantly impacting sales and revenue. A single negative review can decrease purchase intent by 42%, affecting consumer behavior. Ratings below three stars lead to 81% of consumers avoiding the business, damaging brand reputation. Negative reviews harm search engine rankings, reducing online visibility and traffic to the business. Effective engagement with negative feedback can enhance customer trust and improve overall business credibility. Impact on Sales and Revenue When negative online reviews appear, they can profoundly impact a business’s sales and revenue. Research shows that about 80% of potential customers might be deterred by bad reviews. For instance, a furniture store could lose 160 sales out of 200 viewers when faced with negative feedback, translating to an annual revenue loss of around $80,000 if their average sale is $500. Furthermore, a single negative review can decrease purchase intent by 42%, further emphasizing the direct impact of such feedback. It’s important to note that negative reviews often rank higher in search results, diverting traffic away from your website. If your business has a star rating of 3 or lower, expect reduced foot traffic and lower sales. Knowing how to reply to negative feedback is essential, as addressing concerns can mitigate some of these detrimental effects and help restore consumer trust. Damage to Brand Reputation Negative online reviews can lead to serious damage to your brand’s reputation, impacting both trust and visibility. When potential customers see a pattern of poor feedback, they’re likely to avoid your business, which can erode loyalty and trust. Furthermore, these reviews can hurt your online presence, making it harder for new customers to find you and potentially leading to financial losses. Financial Consequences for Businesses The impact of negative online reviews on a business’s financial health can be profound, often translating into significant losses. Studies show that negative reviews can deter up to 80% of potential customers, resulting in substantial financial hits; for example, a furniture store might lose around $80,000 annually because of just a few adverse comments. One negative review can cut purchase intent by 42%, directly affecting sales. Furthermore, businesses with a star rating of 3 or lower face reduced foot traffic and online engagement, impacting revenue generation. In addition, negative reviews can harm search engine rankings, lowering visibility and traffic to your website. If you don’t respond to these reviews, you risk eroding customer trust and may experience long-term financial repercussions. Erosion of Trust Online reviews play a vital role in shaping consumer trust, and a single negative review can have lasting consequences for a brand’s reputation. Studies show that 42% of potential customers are less likely to purchase after reading just one bad review. Businesses with ratings under three stars often lose 81% of prospects, indicating a direct link between star ratings and consumer trust. Moreover, 96% of consumers consult online reviews before making a decision, so a pattern of negative feedback can severely affect your brand’s perception. Responding to reviews can help rebuild trust; 88% of consumers prefer businesses that address negative feedback. In this digital age, maintaining a positive online reputation is vital for sustaining customer confidence and loyalty. Impact on Visibility When consumers come across a business with a series of unfavorable reviews, they often choose to take their patronage elsewhere, greatly impacting the brand’s visibility. Negative reviews can notably deter potential customers, with 80% of viewers avoiding businesses with poor feedback. A single negative review can reduce purchase intent by 42%, whereas businesses with a star rating of 3 or lower face diminished foot traffic. Additionally, negative reviews adversely affect search engine rankings, lowering overall online visibility. To combat this, companies that actively engage with reviews enjoy higher consumer trust, as shown below: Factor Impact on Visibility Percentage Negative Reviews Deters Consumers 80% Reduced Purchase Intent Lowers Sales 42% Star Ratings ≤ 3 Decreased Foot Traffic Notable Search Engine Rankings Reduced Online Visibility Critical Engaging with Reviews Higher Consumer Trust 88% Erosion of Customer Trust When you encounter negative online reviews, your perception of a business’s trustworthiness likely declines. This erosion of customer trust can lead to significant consequences, including damage to reputation and the loss of loyal customers. As you weigh your options, even a single bad review can prompt you to contemplate alternatives, which highlights the critical role that customer feedback plays in shaping trust and influencing purchasing decisions. Trustworthiness Perception Decline Negative online reviews greatly impact the perception of trustworthiness for businesses, often leading to an erosion of customer trust. When you consider how consumers rely on reviews, it’s clear that negative feedback carries weight. Here are some key points: 42% of consumers trust online reviews as much as personal recommendations, making negativity particularly harmful. A single negative review can reduce purchase intent by 42%, showing a direct link to trust erosion. 81% of consumers avoid businesses with ratings below three stars, indicating low ratings can deter potential customers. Unanswered negative reviews create skepticism about a business’s commitment to customer satisfaction, further diminishing trust. Maintaining positive reviews is crucial for credibility and customer loyalty. Reputation Damage Consequences The consequences of reputation damage can be severe, often leading to a significant erosion of customer trust. Negative reviews can deter up to 80% of potential customers, which drastically impacts your sales and revenue. Even a single bad review can cut purchase intent by 42%, clearly showing how quickly consumer trust can wane. If your business has a star rating of 3 or lower, you’ll likely notice reduced foot traffic and sales, as customers perceive you as unreliable. Moreover, 84% of consumers consult online reviews before buying, making a positive reputation crucial. If you don’t address negative feedback, you risk losing customer loyalty, as 88% of consumers prefer businesses that engage with all reviews, regardless of sentiment. Loyalty Erosion Factors Erosion of customer loyalty often stems from the trust issues created by negative online reviews. When potential customers see poor feedback, they hesitate to engage, impacting their loyalty. Here are key factors that contribute to this erosion: High dependence on reviews: 84% of consumers check online reviews before purchasing. Significant impact of negative feedback: A single negative review can decrease purchase intent by 42%. Avoidance of low-rated businesses: 81% of consumers steer clear of companies with fewer than three stars. Unresolved complaints breed skepticism: Unanswered negative reviews can create doubt about a business’s reliability. Influence on Consumer Behavior As consumers increasingly rely on online reviews when making purchasing decisions, their behavior is markedly shaped by the feedback they encounter. A significant 84% of you consult online reviews before buying, underscoring their influence. Just one negative review can decrease your purchase intent by 42%, showcasing how damaging a single piece of negative feedback can be. In fact, 80% of viewers may be deterred by negative reviews, which can lead to substantial revenue losses for businesses. Furthermore, if a business holds fewer than three stars, 81% of you’re likely to steer clear. On the flip side, businesses that actively respond to reviews can boost consumer trust, as you’re 88% more likely to choose them. This engagement is essential in shaping your perception and trust in a brand, demonstrating the significant role online reviews play in your consumer behavior. SEO and Online Visibility Effects Negative online reviews don’t just affect consumer perception; they too greatly impact a business’s search engine optimization (SEO) and online visibility. When a business accumulates negative reviews, it can severely harm its search engine rankings. This pattern leads to decreased visibility in search results, which can result in: A drop in online traffic owing to lower click-through rates on negative reviews. A 42% reduction in purchase intent linked to a single negative review. 81% of consumers avoiding businesses with fewer than three stars. Engagement with feedback, signaling to search engines that the business is responsive, which can improve overall online presence. These factors underline the critical role that online reviews play in shaping a business’s digital footprint. Strategies for Handling Negative Reviews When you encounter negative reviews, it’s vital to approach them strategically, as how you respond can greatly influence your business’s reputation. Responding swiftly shows that you value customer feedback; 88% of consumers prefer businesses that engage with all reviews. Personalize your responses by using the reviewer’s name and addressing their specific concerns; this illustrates attentiveness. If mistakes were made, acknowledge them and offer solutions like refunds or discounts, which can improve customer satisfaction. Additionally, highlighting improvements made in response to past complaints reassures potential customers about your commitment to quality. Implementing a review management system can streamline monitoring and responding to feedback, making the process more efficient. Positive Aspects of Negative Reviews Although it may seem counterintuitive, negative reviews can actually serve as valuable assets for businesses. They offer insights that can lead to improvements in various areas. Here are some positive aspects of negative reviews: Identify Weaknesses: They highlight areas needing improvement, prompting you to enhance products or services. Build Credibility: A balance of positive and negative feedback can make your business appear more trustworthy to potential customers. Transform Loyalty: Addressing complaints effectively can turn dissatisfied customers into loyal advocates who appreciate your commitment to service recovery. Improve Public Perception: Transparent responses to negative feedback can evoke empathy and improve how potential customers view your business. The Role of Customer Service in Reputation Management Customer service plays a crucial role in managing a business’s reputation, especially in the age of online reviews. Timely and effective customer support can mitigate the impact of negative reviews, as 70% of dissatisfied customers are willing to collaborate to resolve their issues before posting publicly. Proactive engagement through customer support systems, like AI chatbots, greatly improves resolution times and helps prevent negative feedback from surfacing. When you acknowledge faults and express empathy in responses to negative reviews, you improve brand perception and rebuild customer trust, leading to potential repeat business. Companies that consistently respond to feedback, both positive and negative, show attentiveness and are 88% more likely to attract new customers. Finally, utilizing review management systems to monitor and address complaints enables you to identify and rectify issues, ultimately enhancing service quality and improving your business’s reputation in the competitive marketplace. Turning Negative Feedback Into Opportunities Negative feedback can serve as a critical tool for businesses looking to improve and evolve. By effectively addressing negative reviews, you can turn complaints into opportunities for growth. Here’s how to leverage that feedback: Identify Improvement Areas: Analyze reviews to pinpoint specific issues in your products or services that need attention. Engage with Customers: Respond publicly to negative feedback, showing your commitment to customer service, which can boost your brand’s reputation. Transform Dissatisfied Customers: Over 70% of customers may change their opinion after a positive response, potentially turning them into loyal advocates. Boost Customer Loyalty: Businesses that actively manage their reviews often see an 88% increase in customer retention by demonstrating responsiveness. Utilizing negative feedback not just refines your practices but also elevates overall customer experience, leading to better retention rates and increased revenue. Frequently Asked Questions How Do Negative Reviews Impact a Business? Negative reviews can markedly impact your business’s success. They deter up to 80% of potential customers, leading to decreased sales and revenue. A single negative review may reduce purchase intent by 42%, causing you to lose valuable opportunities. Moreover, such feedback can harm your search engine ranking, reducing online visibility. Responding to negative reviews is crucial, as businesses that engage with their customers are 88% more likely to attract new clients and build trust. Do Bad Google Reviews Hurt Business? Yes, bad Google reviews can greatly hurt your business. They deter around 80% of potential customers and reduce purchase intent by up to 42%. If your business has a star rating of 3 or lower, you might see decreased foot traffic and online visibility. This decline can directly affect your search engine rankings, harming your overall online presence. Engaging quickly with negative reviews can help regain customer trust and improve your brand’s reputation. Can I Be Sued for Posting a Negative Review? Yes, you can be sued for posting a negative review if it contains false statements. Defamation laws protect businesses from untrue claims that damage their reputation. Although you have the right to express your opinion, it’s essential your review is based on factual information. Exaggerated claims or personal attacks increase the risk of litigation. Always aim for constructive criticism to avoid potential legal consequences that could arise from a misleading review. What Are the Disadvantages of Online Reviews? Online reviews can have significant disadvantages for businesses. They can shape public perception, as potential customers often rely on these opinions before making purchases. A few negative reviews can deter many buyers, impacting sales and foot traffic. Furthermore, negative feedback can harm a business’s online visibility and search rankings. Ignoring these reviews can further damage reputation, as customers prefer businesses that engage with all feedback. This can lead to a cycle of accumulating negative comments. Conclusion In summary, negative online reviews can greatly affect your business, from lowering sales and damaging your reputation to eroding customer trust. They influence consumer behavior and can hurt your SEO rankings, reducing online visibility. Nonetheless, by proactively managing these reviews and using them as opportunities for improvement, you can improve customer service and build a stronger brand. Comprehending these impacts is vital for maintaining credibility and encouraging long-term customer loyalty in an increasingly digital marketplace. Image via Google Gemini and ArtSmart This article, "What Are the Real Impacts of Negative Online Reviews on Business?" was first published on Small Business Trends View the full article
-
Most of the loans, 57.34%, are for cashout purposes and the entire loan pool are first-liens, and are of modest leverage, with an original cumulative loan-to-value (LTV) ratio of 69.74%. View the full article
-
Facebook Marketplace is revolutionizing online selling with the introduction of new Meta AI-powered features aimed at enhancing the experience for both buyers and sellers. As small business owners increasingly seek cost-effective avenues to reach customers, these innovations promise to simplify the selling process and open up new opportunities for engagement on the platform. With over 3.5 million listings posted daily in the U.S. and Canada alone, Facebook Marketplace is already a favored destination for those looking to buy or sell a myriad of products—from home decor to vintage clothing. The recent enhancements are designed to make it even easier to navigate this bustling marketplace, particularly for small business owners who may not have dedicated resources for sales. One of the standout features is the ability to list items more efficiently. Sellers can now upload images of their products, and Meta AI will automatically generate a draft listing that includes key details and pricing suggestions based on similar items in the area. This streamlined process allows vendors to focus on other aspects of their business, making it particularly attractive for those juggling multiple responsibilities. Shipping logistics are also more user-friendly now. Sellers can expand their reach by offering shipping options, thanks to simplified management tools that allow for the generation of prepaid shipping labels in just a few clicks. Keeping track of shipped orders is centralized within a dashboard, eliminating the headaches often associated with delivery logistics. Communication barriers between sellers and buyers are also lowered with the introduction of AI auto replies. When potential buyers inquire about item availability, sellers can enable auto replies that pull information directly from their listings. This feature speeds up interaction and helps to ensure consistent communication, an essential element for customer satisfaction and trust. Building a trustworthy online presence is crucial for small business owners, and Meta AI aims to assist in this area as well. The platform now provides AI-generated profile summaries, displaying an overview of the seller’s Facebook profile. This summary includes how long the seller has been on Facebook, the number of friends they have, and a snapshot of their Marketplace activities. Such transparency could enhance buyer trust, as customers often gravitate toward sellers with established profiles and positive ratings. However, while these tools represent significant advancements, small business owners should also be aware of potential challenges. As with any automation, there’s the possibility of errors in generated content, which means sellers must still take care to review listings before they go live. The reliance on AI for auto replies may also lead to generic responses that lack the personal touch, potentially alienating some buyers who appreciate more direct engagement. Moreover, as sellers leverage these new capabilities, the increased activity on the platform could lead to stiffer competition. Business owners must remain agile, continuously adapting their strategies to distinguish themselves from others employing similar tools. In embracing these innovations, small business owners can capitalize on an expanding customer base while simultaneously reducing the time and effort spent on listing and selling items. The potential for broader market reach combined with enhanced buyer-seller communication makes Facebook Marketplace an increasingly attractive option for small businesses looking to thrive in a competitive digital landscape. As Meta continues to roll out these features, staying informed about updates and best practices will be crucial for small business owners aiming to maximize their presence on this growing platform. For more detailed insights, visit the original press release at Facebook News. Image via Google Gemini This article, "Facebook Marketplace Unleashes AI Tools for Effortless Selling and Buying" was first published on Small Business Trends View the full article
-
I’m so tired. However, the reasons are good: A fun weekend away A growing business Lots of time with family and friends Still, sometimes sleep suffers. I’m well-aware of what the research says that can entail—health risks and effects on productivity and memory. The idea is that sleep is when the brain has a chance to “clean” itself at night. A recent study in Nature Neuroscience takes a more precise look at something many people have experienced: those brief, frustrating moments after a bad night’s sleep when you simply can’t focus. Instead of looking at sleep deprivation over years or even days, the researchers focused on what’s happening inside the brain at the moment attention slips. The scope of the study Researchers at MIT and Boston University recruited 26 healthy adults between the ages of 19 and 40. Each participant went through the same testing protocol twice: once after a full night of sleep and once after staying awake all night under supervision. During both sessions, the researchers tracked what was happening in real time using several methods at once: Functional MRI to monitor blood flow and fluid movement in the brain EEG to measure brain activity Eye tracking to measure pupil size Heart rate and breathing sensors Reaction-time attention tests Because the same people were tested in both conditions, the researchers could compare each person’s performance and physiology when rested versus sleep deprived. What they found It’s well-known that sleep deprivation makes it harder to concentrate. The question behind this study was narrower: What exactly is happening inside the brain when attention slips? The team suspected that the answer might involve processes that normally take place during sleep. When participants were sleep-deprived, their reaction times slowed and they missed more cues during attention tests. The most striking discovery involved what was happening at the exact moments when those mistakes occurred. Normally, during sleep, waves of cerebrospinal fluid move through the brain, helping clear away waste products that build up during the day. In this study, after a night without sleep, similar fluid surges began appearing while participants were still awake, and these events tended to line up with brief attention failures. At the same time, a coordinated set of changes unfolded across the body: Pupils constricted Breathing slowed Heart rate dropped Brain-wave patterns shifted A few seconds later, as attention returned, those signals reversed. “It’s this kind of very sleeplike moment,” study co-author Laura Lewis told the Wall Street Journal. “The person is awake, but at the same time, there’s clearly this brief breakdown of ability to focus on the outside world.” A brain trying to do two jobs at once The study suggested that the brain is juggling competing priorities. During sleep, it performs what amounts to internal housekeeping, including fluid movement linked to clearing metabolic waste. During waking hours, it prioritizes attention and responsiveness. When sleep is cut short, those maintenance processes don’t disappear. Instead, they begin to intrude into waking life in short bursts, and attention drops at the same time. Researchers observed that these lapses were tied to a coordinated shift across the brain and body that looked remarkably similar to the early stages of falling asleep. “This suggests that there’s really some very urgent function of sleep the brain is trying to get to that’s worth this cost,” Lewis told the Journal. The brain appears to be forcing essential maintenance even when we’re trying to stay awake and engaged. Why this matters Most busy adults live with at least some degree of sleep deprivation. It’s easy to assume you can power through a rough night and function close to normal the next day. However, this research suggests the effects may show up in short, subtle interruptions in attention that happen whether you intend them to or not. After just one sleepless night, participants reacted more slowly and missed more signals, alongside measurable physiological changes suggesting the brain was temporarily shifting its focus inward. In situations where attention matters—driving, decision making, managing complex tasks, or even just trying to stay present in a conversation—those brief lapses can carry real consequences. Outside experts see the findings as part of a much larger picture. “Sleep disturbances precede most neurodegenerative diseases by up to decades,” University of Rochester neuroscientist Maiken Nedergaard told the Journal. “We really start to look at sleep as an opportunity to prevent many of the diseases of aging.” The practical lesson The broader takeaway lines up with decades of sleep research. Sleep supports essential processes that can’t simply be postponed. When the brain doesn’t get enough time to perform those functions overnight, it starts making room for them during the day. When that happens, attention becomes less stable. For people balancing work, family, and everything else, the implication is straightforward. Lost sleep doesn’t just leave you feeling tired. It changes how the brain operates moment to moment, sometimes in ways you don’t fully notice until focus slips at exactly the wrong time. Enjoy your life, build your business, spend time with your family and friends. However, don’t sleep on sleep. It’s part of what makes everything else possible. —Bill Murphy Jr. This article originally appeared on Fast Company’s sister website, Inc.com. Inc. is the voice of the American entrepreneur. We inspire, inform, and document the most fascinating people in business: the risk-takers, the innovators, and the ultra-driven go-getters that represent the most dynamic force in the American economy. View the full article
-
Finding additional memory for your PC is already a challenge. Now, connecting to the internet could get tougher, too. The Federal Communications Commission (FCC) released a notice Monday that will prohibit all new consumer-grade routers that were not made in the United States. Routers made in other countries, the alert read, “pose unacceptable risks to the national security of the United States or the safety and security of United States persons.” At least 60% of the routers in U.S. homes are made overseas, with the majority coming from China. Officials fear China could exploit those devices to launch attacks on critical infrastructure or steal sensitive information. “Malicious actors have exploited security gaps in foreign-made routers to attack American households, disrupt networks, enable espionage, and facilitate intellectual property theft,” the FCC wrote. “Foreign made routers were also involved in the Volt, Flax, and Salt Typhoon cyberattacks targeting vital U.S. infrastructure.” The ban applies only to new routers from other countries. The agency is recommending no action for devices already in homes and businesses. Retailers can continue selling existing inventory, and routers previously authorized by the FCC can still be imported, sold, and used. That suggests any suspected risk is not viewed as immediate. The order is likely to face legal challenges. The move is the latest step in the The President Administration’s 2025 National Security Strategy, which states “the United States must never be dependent on any outside power for core components—from raw materials to parts to finished products—necessary to the nation’s defense or economy.” But implementing a ban on a product where even U.S.-based companies rely heavily on overseas manufacturing could create supply headaches. The FCC included a potential loophole by allowing exemptions for companies that obtain “conditional approval” from the Department of Defense or the Department of Homeland Security. (It is worth noting that the FCC’s “Covered List” of routers deemed to pose an unacceptable risk does not restrict the sale or import of routers used by the federal government. Additionally, the FCC said companies could import small batches of unauthorized devices for product development purposes, but could not market or sell those.) If you already own a router on the Covered List, you will not be stuck with an expensive paperweight. A waiver allows those devices to continue receiving software and firmware updates so they remain usable and can defend against hacker attacks. The decision will impact several manufacturers, but perhaps none more than TP-Link. The company was founded in China but has since established its headquarters in Irvine, California. It has faced prior investigations over concerns about ties to China, though no action had been taken before Monday’s announcement. (TP-Link was not specifically mentioned in the FCC announcement, and the company did not immediately respond to a request for comment.) The new rules echo a previous ban on smartphones developed by Chinese companies, which had the biggest impact on Huawei Technologies. Investors are already betting on who benefits. Shares of Netgear rose more than 12% in early trading Tuesday, with Wall Street seemingly expecting the company to receive an exemption and face reduced competition going forward. View the full article
-
Spotify keeps adding new features lately. Last week, the company rolled out "Exclusive Mode" for desktop users to stream in the highest quality possible; last month, Spotify announced "Smart Reorder," which automatically sorts your songs by BPM; and in January, the company's AI-powered "Prompted Playlists" landed in the U.S. after an exclusive stint overseas. It's still not easy to pick a favorite among other services like Apple Music, but Premium subscribers can at least say Spotify is giving them something for their money. Now, the company is rolling out another new feature, one that actually seems like a cool way to learn about your music. On Tuesday, Spotify announced SongDNA, which shows you all the people who worked on a song, as well as all the samples and interpolations that song used. SongDNA lives directly under the lyrics tile in the player window. I already see it on my end, though Spotify does label the feature with a "Beta" tag to note that this feature is still in testing. How Spotify's SongDNA works When SongDNA appears under a song, you'll be able to see the artists who worked on it in one corner. That might include the main artist, but also any of the composers, producers, musicians, or writers who contributed. The SongDNA tile shows the main artist in a bubble, but tap the icon, and you'll see a map of all the people involved. You can tap on any of these names to see how many other artists they've worked with, how many songs they worked on, and what their "top song" is (presumably, what the most popular song they worked on is on Spotify). To the right of the artists' bubble is a sample and interpolations bubble: Here, you'll see all of the clips the artist or artists took from various other songs to incorporate them into their own track. On Kendrick Lamar's "King Kunta," for example, I can see they sampled a drum loop from "Kung Fu" by Curtis Mayfield, and took vocals from James Brown's "The Payback," among others. Spotify will tell you exactly where in each song the sample was taken from, and gives you a play button to listen. You also can scroll down to find songs that have sampled the song in question: "F The Disco" by Cavi samples vocals from "King Kunta" at 1:28, as does "Brain Cells" by Villain Park (at 1:59). Scroll down a bit more, and you'll find any covers of the song available on Spotify. "8-Bit Misfits" has an awesome interpretation of the song that sounds like Kendrick wrote music for the NES. Credit: Spotify I'm an Apple Music guy, truthfully, but I have to say: This rocks (no pun intended). Most of us listen to our music without really knowing much about how it was put together—outside of the headlining artist, anyway. SongDNA makes it easy to learn more about how your favorite songs were made, where they pulled inspiration from, and who actually helped make the hit besides the singer or artist. You could follow up with the lead engineer or producer of your favorite song to see what other projects they worked on, or check out the full songs that were sampled to find new music to listen to. While it's a bummer it's only available for Premium subscribers, it's a great move on Spotify's part. I reached out to Spotify asking whether SongDNA uses AI to retrieve this information, and will update this article if I receive an answer. View the full article
-
Trust hasn’t disappeared from business. It’s been renegotiated. As artificial intelligence moves from novelty to infrastructure, people are changing how they decide who deserves credibility. In Mission North’s 2026 Brand Expectations Index, we surveyed more than 1,500 U.S. adults and knowledge workers to understand what builds trust today, and what quietly undermines it. Some of the results run directly against conventional thinking. Here are five rules for 2026. 1. Visibility alone doesn’t build credibility For years, executive communications equated presence with power: more interviews, more panels, more posts. But only 24% of respondents say frequent CEO visibility increases their trust. That doesn’t mean leaders should disappear. It means audiences can tell the difference between showing up and taking responsibility. What actually moves trust? Protecting customer data. Admitting mistakes. Listening and responding. Visibility without substance now reads as noise. The message is clear: Awareness and credibility are no longer interchangeable. 2. Generational expectations are diverging Where leaders show up matters—and it matters differently depending on who’s watching. Younger generations expect leaders to appear on social media, with 47% of Gen Z and 42% of millennials expecting them to appear on YouTube. Among those groups, trust rises when companies show up on YouTube (38% Gen Z and 37% millennials) and on TikTok or Reels (35% and 21% respectively). Older generations tell a different story. Across the full sample, 56% expect leaders to appear on broadcast TV news—and among knowledge workers, 45% say those appearances increase trust. For many audiences, traditional media still carries legitimacy. But another pattern emerges when you look at trust conversion: Longer-form, explanatory environments consistently generate stronger credibility returns than compressed, reactive formats. Platforms that allow leaders to explain decisions, demonstrate expertise, and show their thinking—whether that’s broadcast interviews, YouTube explainers, podcasts, or substantive LinkedIn posts—convert visibility into trust more effectively than short-form performance. The lesson isn’t that traditional media is irrelevant, or that digital replaces broadcast. Traditional media drives awareness, which is a key element of a strategic communications program. The nuance is that credibility follows depth. The more space leaders have to demonstrate clarity and accountability, the more trust they earn. 3. AI can strengthen trust—or erode it Across generations, one principle holds: Accountability must stay visible. Roughly seven in 10 respondents say their trust would decline if a company used undisclosed AI-generated executive messaging. At the same time, millennials are broadly comfortable with AI integration—60% say they’re fine with AI-generated executive avatars delivering public statements. Among baby boomers, however, that drops to 20%. The divide isn’t about innovation; it’s about accountability. People don’t object to technology; they object to leaders hiding behind it. 4. Silence is sometimes the smarter move Crisis playbooks have long prioritized speed, but our data suggests that instinct deserves a second look. Fifty-seven percent of adults—and 67% of knowledge workers—prefer leaders to say nothing rather than risk being wrong. Nearly seven in 10 would rather companies wait for verified facts than release unconfirmed information. In a media environment that rewards instant reaction, restraint can signal discipline. Accuracy reads as leadership. 5. Substance always wins We also tested whether gender shapes trust in crisis communication by presenting identical statements under the names “John Reed, CEO” and “Jessica Reed, CEO.” Among the general population, subtle perception gaps emerged: John was rated slightly higher on authority (+4 points) and empathy (+5 points). First impressions aren’t neutral. But when respondents evaluated what truly drives credibility—trustworthiness and effectiveness—those gaps nearly disappeared (+1 and +2 points). Among knowledge workers, differences fell within the margin of error. The takeaway? Bias may influence the opening frame, but performance determines the outcome. What leaders need to get right Across the research, a consistent pattern emerges: Accountability beats amplification. Expertise builds more credibility than hierarchy. Transparency is non-negotiable in AI adoption. Tone matters—and varies by audience. Values and clarity stabilize trust under pressure. This isn’t a case for less communication. It’s a case for more disciplined communication. AI can accelerate output, scale messaging, and compress timelines. What it cannot automate is responsibility. The leaders who earn trust this year won’t be the most visible. They’ll be the most accountable. Tyler Perry is co-CEO of Mission North. View the full article