Newsletter
Want to keep up to date with all our latest news and information?
ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
In today’s fast-paced business environment, optimizing your accounts payable processes can greatly influence your bottom line. By following seven fundamental best practices, you can improve accuracy, speed, and overall effectiveness in managing AP operations. Centralizing processes, implementing strong controls, and leveraging automation are just a few strategies that can streamline your workflow. Comprehending these practices is vital for improving efficiency and maintaining positive vendor relationships. Let’s explore each practice in detail to see how they can transform your AP function. Key Takeaways Centralize and standardize AP processes to reduce errors and speed up tasks through unified workflows and clear guidelines. Implement strong internal controls with segregation of duties and multi-level approvals to enhance accuracy and prevent fraud. Adopt automation technologies, including OCR, to significantly cut processing times and improve invoice accuracy. Manage cash flow effectively by categorizing invoices by due dates and establishing clear communication with vendors. Regularly review and analyze AP operations to identify inefficiencies, adapt processes, and foster a culture of continuous improvement. Centralize and Standardize AP Processes When you centralize and standardize your accounts payable (AP) processes, you create a more efficient and controlled environment for managing invoices and payments. By implementing accounts payable automation best practices, you establish a unified system for invoice and payment data, reducing error risks. This centralization directs all inquiries to a single AP function, enhancing control. Standardizing workflows and procedures clarifies invoice approval steps and payment terms, minimizing confusion and streamlining operations. Adopting accounts payable invoice processing best practices helps eliminate redundancies, speeding up tasks and lowering overall costs. Regular reviews of standardized processes can identify bottlenecks, guaranteeing timely invoice reviews and promoting continuous improvement. Establishing clear guidelines for supplier registration within this framework not just minimizes fraud risks but also guarantees accurate supplier data, preventing delays and inefficiencies. These measures collectively contribute to stronger accounts payable internal controls best practices, enhancing the overall effectiveness of your AP operations. Implement Strong Internal Controls Centralizing and standardizing accounts payable processes sets the stage for implementing strong internal controls that further protect your organization from fraud and errors. To achieve this, consider the following accounts payable internal controls: Control Type Description Benefits Segregation of Duties Divide responsibilities among employees. Reduces fraud risk. Approval Workflow Require multiple levels of approval for payments. Improves accuracy and accountability. Regular Audits Conduct internal audits frequently. Identifies vulnerabilities. Automate Invoice Processing for Efficiency Automating invoice processing is a crucial step toward improving efficiency in your accounts payable operations. By implementing AP automation software, you can cut processing time by up to 70%, allowing your team to focus on higher-value tasks. Consider utilizing Optical Character Recognition (OCR) technology to capture invoice data accurately, which reduces manual entry errors and bolsters data integrity. Centralizing invoice processing creates a unified system, improving visibility and simplifying audits and compliance checks. Streamlined workflows for invoice approvals guarantee timely payments, reducing the risk of late fees or missed discounts. Moreover, automated invoice matching against purchase orders minimizes discrepancies, boosting accuracy in your financial records. When choosing accounts payable services, think about the integration capabilities and scalability of the solution. Following these accounts payable best practices won’t just boost efficiency but will also support your overall financial health. Prioritize Invoices to Manage Cash Flow To manage cash flow effectively, you should prioritize invoices based on their due dates and payment terms. By implementing a due date system, you can guarantee timely vendor payments and avoid late fees. Furthermore, utilizing real-time alerts will keep you informed about upcoming deadlines, helping you maintain better control over your cash flow. Implement Due Date System Implementing a due date system can greatly boost your accounts payable process by allowing you to prioritize invoices based on their payment deadlines. This approach helps guarantee timely payments and prevents late fees, which can disrupt your cash flow. Here are some key benefits of a due date system: Categorizes invoices by due dates and payment terms for better management. Utilizes automated workflows for real-time alerts on approaching deadlines. Improves visibility and accountability in the accounts payable process. Regularly reviews due dates to identify potential cash flow issues. Establishes clear prioritization to reduce processing delays and enhance efficiency. Monitor Payment Terms Managing payment terms effectively is a key strategy for maintaining a healthy cash flow in your accounts payable process. Start by implementing a system that prioritizes invoices based on due dates and payment terms. This helps prevent late fees and guarantees steady cash flow. Paying vendors on time not just avoids penalties but strengthens relationships, potentially leading to early payment discounts. Consider using an invoice management system with automated workflows, as this can streamline processing and improve cash flow management. Moreover, regularly review your payment terms and renegotiate with vendors when necessary. This approach can optimize your financial flexibility, allowing you to manage cash outflows more effectively and maintain good vendor relations over time. Utilize Real-Time Alerts Real-time alerts play a crucial role in optimizing cash flow management within accounts payable. By implementing these alerts for invoice due dates, you can proactively manage cash flow, avoiding late fees and maintaining positive vendor relationships. Consider the following benefits: Set automated workflows for timely invoice processing. Prioritize invoices based on due dates for effective fund allocation. Customize alerts for payment terms and early discounts. Identify payment process bottlenecks through regular monitoring. Facilitate timely reviews and approvals to keep cash flow steady. Utilizing real-time alerts guarantees you’re always on top of your financial obligations, improving overall cash flow planning and operational efficiency. This proactive approach not just improves relationships with suppliers but additionally helps you seize cost-saving opportunities. Strengthen Vendor Relationships To strengthen your vendor relationships, focus on timely payment practices and clear communication channels. Paying your suppliers on time not just builds trust but can likewise lead to discounts that benefit your cash flow. Furthermore, establishing regular check-ins and being responsive to their inquiries nurtures a partnership that can improve both negotiation outcomes and overall satisfaction. Timely Payment Practices Timely payment practices are crucial for maintaining strong vendor relationships and ensuring smooth business operations. By prioritizing timely payments, you can prevent late fees and improve your cash flow, allowing you to seize early payment discounts of 1-2%. Here are some best practices to reflect upon: Establish clear payment terms and stick to them to build trust. Communicate regularly about payment statuses to help vendors manage their own cash flow. Use automated payment systems to reduce processing time by up to 70%. Make consistent, timely payments to boost vendor loyalty. Leverage strong relationships for better negotiation opportunities and improved service. Clear Communication Channels Effective communication channels play a significant role in strengthening vendor relationships and ensuring smooth operations. By establishing clear lines of communication, you facilitate timely invoice submissions and improve transparency, which reduces payment errors. Regular updates and open dialogue build trust, often resulting in better payment terms and discounts. Swiftly responding to vendor inquiries and quickly resolving disputes is fundamental for maintaining strong relationships. Utilizing a self-service supplier portal allows vendors to manage their information and track payment statuses, increasing efficiency and satisfaction. Additionally, scheduling regular meetings and feedback sessions with vendors can identify areas for improvement, encouraging collaboration and ensuring ongoing success. Prioritizing these communication practices will in the end boost your accounts payable processes. Regularly Review and Analyze AP Performance Regular reviews and analyses of accounts payable (AP) performance are crucial for identifying inefficiencies that can considerably impact a business’s financial health. By regularly monitoring key metrics, you can improve processing times, potentially reducing invoice handling time by up to 70%. Here are some critical aspects to focus on: Track Days Payable Outstanding (DPO) for cash flow insights. Monitor invoice processing times to identify bottlenecks. Conduct periodic audits to guarantee compliance and detect fraud. Analyze trends in invoice and payment volumes for better vendor negotiations. Engage stakeholders in feedback sessions to adapt processes effectively. These practices not just streamline operations but additionally safeguard your organization’s financial integrity. Foster a Culture of Continuous Improvement Nurturing a culture of continuous improvement in accounts payable is essential for boosting efficiency and streamlining processes. Regularly reviewing and refining your workflows can lead to quicker processing times and reduced errors. Engage your staff in discussions about potential improvements; this encourages ownership and accountability, often resulting in innovative solutions to challenges you face. Implementing feedback loops allows team members to share insights and best practices, helping align your operations with industry standards. Furthermore, conducting regular audits of AP workflows helps identify bottlenecks and inefficiencies, providing opportunities for targeted advancements. Embracing evolving technologies, such as automation and AI, supports a proactive approach to operational excellence. Frequently Asked Questions How Can Technology Enhance Accounts Payable Operations? Technology improves accounts payable operations by automating invoice processing, which reduces manual errors and saves time. By implementing software solutions, you can streamline approvals and improve tracking of payments. Furthermore, using cloud-based platforms allows for real-time access to financial data, facilitating better decision-making. Integrating artificial intelligence can likewise help identify discrepancies and predict cash flow needs. What Key Metrics Should I Track in Accounts Payable? In accounts payable, you should track key metrics like invoice processing time, which measures efficiency, and the payment cycle time, indicating how quickly you settle bills. Furthermore, monitor the percentage of invoices paid on time, as this affects vendor relationships. Another important metric is the cost per invoice, which helps you understand operational expenses. Regularly analyzing these metrics can identify areas for improvement, optimize workflows, and improve overall financial management. How Do I Handle Disputes With Vendors Effectively? To handle disputes with vendors effectively, start by reviewing the contract and purchase order details. Gather all relevant documentation to support your case. Communicate directly with the vendor, addressing the issue calmly and clearly. Listen to their perspective and seek a resolution that works for both parties. If necessary, escalate the matter internally or involve a mediator. Keeping records of all interactions will help guarantee a smoother resolution process and prevent future disputes. What Are the Benefits of Outsourcing Accounts Payable? Outsourcing accounts payable offers several benefits. You can reduce operational costs, as third-party providers often operate more efficiently. It allows your team to focus on core business activities, improving productivity. Furthermore, outsourcing improves accuracy through specialized expertise, minimizing errors in processing invoices. You’ll likewise benefit from advanced technology that vendors utilize, ensuring timely payments and better cash flow management. How Can Staff Training Improve Accounts Payable Processes? Staff training can greatly improve accounts payable processes by ensuring your team understands the latest software and compliance regulations. When employees are well-trained, they make fewer errors, which speeds up invoice processing and improves accuracy. Regular training sessions can likewise keep the team updated on best practices, nurturing consistency. Conclusion Incorporating these seven best practices into your accounts payable operations can greatly improve efficiency and accuracy. By centralizing processes, implementing strong controls, and automating tasks, you’ll streamline workflows and reduce errors. Managing cash flow and nurturing vendor relationships are similarly essential for operational success. Regular reviews and a commitment to continuous improvement will guarantee your team adapts to changes and maintains compliance. Adopting these strategies not just optimizes AP management but likewise contributes to overall organizational effectiveness. Image via Google Gemini This article, "7 Essential Accounts Payable Best Practices for Streamlined Operations" was first published on Small Business Trends View the full article
-
In the movie The Perfect Storm, three large weather events converge, creating a storm bigger than the sum of its parts. As overused as the metaphor might be, it’s a good one for what’s happening to leaders globally right now. This storm involves the widespread integration of mainstream AI tools like ChatGPT, Gemini, and Claude into organizational workflows, and three large, interacting, non-obvious effects of this trend on leaders at all levels. Unchecked, research suggests, artificial intelligence could bring a toxic force to bear on how leaders build and reinforce their cultures. Trend one: Leaders are already overwhelmed and thinking poorly The first trend involves the mental state of leaders themselves, many of whom were overwhelmed before these tools came into play. AI hasn’t pared down our workloads as much as it’s added a layer of new work for all of us, ironically leading people who are the best at using AI to experience some of the strongest “brain fry” in the office. Separate from the issue of being overwhelmed, leaders are working in domains in which they have no experience, that feel completely unpredictable. Before AI tools were widely used, nearly three-quarters of leaders had imposter syndrome. When leaders feel uncertain or out of control, many revert to defensive behaviors, such as being overly controlling or overly goal focused at the expense of considering people. Or, at the far end of things, becoming bullies. The cognitive science take on this is that leaders are experiencing strong threat responses, which reduces their capacity for a skill that’s critical for healthy AI adoption: deep thinking. In particular, metacognition, a specific type of deep thinking, which I have argued is the central skill that differentiates poor from great users of AI tools. Trend two: Leaders are being given the ultimate ‘yes man’ The second trend involves the way mainstream AI agents are designed to be deeply sycophantic. The business model for mainstream AI is the same as for social media: Companies make money by keeping people engaged. To do this, social media worked out how to hack attention. AI tools are trying to hack something much deeper and much more insidious: attachment. A big part of how they do this is by agreeing with you, even when your ideas are potentially harmful to yourself or others. One MIT study showed that delusional spirals are common even in people who are otherwise considered highly logical. From a cognitive perspective, the brain is wired to orient toward things that are innately rewarding, like receiving praise, and orient away from things that create a threat response in any way, like being challenged. Weave challenge into an AI tool, and science suggests a lot of people will just switch to an alternative that makes them feel better. Giving leaders who already aren’t thinking well the perfect “yes-man” in their corner—always on, overly agreeable—is problematic. Their decisions affect an organization’s survival. A leader who incorrectly believes they created a highly valuable new product could put 100,000 people out of work in a quarter if it turns out to be a flop. Trend three: Widely using sycophantic AI for interpersonal issues The third trend may prove to be the most dangerous. It involves what happens when leaders use these tools for interpersonal challenges. It’s widely known that as leaders get more senior, the need for technical skills decreases and the need for human skills increases. Here’s the problem: Leaders are turning to these sycophantic AI agents for very human issues, things like trying to motivate others, deal with poor performers, or resolve interpersonal conflict. An important new study in Science found that using these tools for interpersonal issues made people less prosocial. Are other people frustrating you? Forget about checking in to see what role you might play in that. Your AI will reassure you, “Don’t let them mess with your peace.” A team isn’t performing well? Your AI will confirm that “it can’t have anything to do with you; they must not be a great fit for their role.” You don’t like how your boss spoke to you? Forget about reflecting on your own performance; your AI will suggest “maybe it’s time to explore a role in a place that respects your talents.” You can see how problematic this can quickly become. When today’s mainstream AI tools agree with you, they are innately avoiding making you uncomfortable. This means they won’t challenge you, they won’t help you see other perspectives, and they won’t make you be more reflective. Rather, they do the opposite. They make you more likely to blame others for, well, everything. When leaders are already overwhelmed as outlined above, it becomes all too easy to take this kind of approach. Recently, the executive coach Silvia Christmann shared a harrowing story of two leaders in conflict, both of whom had become unwilling to meet face to face. It turned out that both were using AI to develop comprehensive explanations of how wrong the other person was and why, rapidly escalating their dislike of one another. Instead of “rupture and repair,” which is a normal part of healthy human interactions, it was rupture, exacerbated into more rupture, with an ever deepening cycle of discontent. This was a small issue, likely to now turn into a job-ending situation for at least one of them. “AI chatbots are my new invisible colleagues,” Silvia told me. During a session on leadership effectiveness, Silvia says a client flatly rejected her feedback about their communication style. “Despite evidence that their communication style was stalling team progress, the client remained defensive, claiming that an AI had already affirmed their position,” she said. It’s not too late to avoid the storm When I discuss this coming leadership crisis with organizations, they are concerned that they have already invested heavily in these tools, and their big focus is getting people to use them. This is a worthy focus; however, using mainstream AI tools for interpersonal issues needs to be thought through. Leaders are being given a sounding board that looks like a mirror, likely to make them more toxic, more self-absorbed, and readier to blame everyone but themselves for any challenges. Leaders who are already toxic will likely become more so. But even good leaders may accidentally slip into toxic mode just by following the advice of these supposedly brilliant tools. There are solutions. One of them directly involves training leaders to be more metacognitive. To challenge what they get from an AI tool like a chatbot. A healthy pathway to this lies in learning more about the brain, increasing what my team at the NeuroLeadership Institute calls “neuro intelligence.” Among other things, this involves an understanding of our brains’ tendency to make mistakes, to have biases, to avoid deep thinking. The more tangibly we understand our own brain’s limitations, the better we can partner with these tools in healthy ways. A second solution is more systemic. It involves requiring that leaders use better tools when it comes to addressing human challenges. Tools trained to challenge a leader, to flag poor diagnoses, to consider other people’s perspectives. These are purpose-designed tools for leaders. Lawyers don’t use mainstream AI platforms for critical legal issues; they use specialized AI tools. Perhaps leaders should be using specialized tools for critical leadership issues too. Imagine what can happen as all three trends interact. Leaders having fewer cognitive resources and less capacity to reflect. Add an AI that agrees with the leader’s point of view on everything. Now add in leaders making every social issue another person’s problem, and imagine these three issues amplifying each other. The downstream effects of the storm may not just be more toxic leaders, but more toxic cultures. The good news is there’s probably still time to steer around this one, but relying solely on hope might not be the best idea. The waves, when they come, could be big ones. View the full article
-
G7 finance ministers did not discuss second emergency release to calm energy crisis, says Roland LescureView the full article
-
Largest US bank in discussions over risk transfer as PE firms grapple with prolonged slowdownView the full article
-
As CEO NP Narvekar nears retirement Ivy League fund will have to reckon with expansion into sluggish private holdingsView the full article
-
Putin’s mis-steps have locked it into a relationship with China that is increasingly one-sidedView the full article
-
Markets have yet to register the new fashion among governments for hoarding and huddlingView the full article
-
Western automakers are taking advantage of Chinese overcapacity to export lower-cost vehicles to their home marketsView the full article
-
Threat to code that underpins bitcoin has moved ‘from theoretical to credible’, industry figures warnView the full article
-
Princeton Digital Group’s sale process caps foreign retreat from the country’s sensitive digital infrastructureView the full article
-
Streamlining your small business bookkeeping and payroll is essential for operational efficiency and accurate financial management. By automating payroll and using accounting software, you can reduce errors and guarantee compliance with tax regulations. Organized financial records not solely improve cash flow visibility but likewise support informed decision-making. As you explore these strategies, consider how outsourcing bookkeeping tasks might allow you to focus on your core business activities and boost overall performance. Key Takeaways Implement accounting software like QuickBooks to automate bookkeeping tasks and minimize manual entry errors. Open a dedicated business bank account to separate personal and business finances for better tracking. Utilize payroll software to streamline payroll processes and ensure timely, accurate payments while reducing compliance risks. Maintain organized financial records by categorizing transactions and updating records weekly for a clearer financial overview. Hire a professional bookkeeper to assist with tax preparation and maintain organized records, enhancing compliance and reducing stress. Understanding the Importance of Bookkeeping for Small Businesses Bookkeeping forms the backbone of financial management for small businesses, and comprehending its importance is fundamental for your success. Accurate bookkeeping and payroll practices are critical for recording, organizing, and categorizing financial transactions, which lay the foundation for effective financial reporting. By maintaining reliable small business bookkeeping and payroll, you gain insights into your cash flow, control expenses, and guarantee compliance with tax regulations. Regular bookkeeping allows you to track daily cash movement, which is significant for managing invoices and payroll efficiently. This clarity on your financial position helps measure your business’s profitability and performance. Conversely, poor bookkeeping can lead to disorganized records, complicating financial management and creating unnecessary stress, especially during tax season. As a result, prioritizing timely and consistent bookkeeping practices not only supports your business’s financial health but likewise empowers you to make informed decisions that drive growth and stability. Key Benefits of Streamlined Payroll Processes Streamlined payroll processes can greatly improve efficiency and accuracy in your business operations. By implementing organized systems for deductions and contractor payments, you’ll guarantee timely and precise payments, reducing administrative time and freeing you to focus on growth. Furthermore, automating payroll tasks helps simplify compliance and reporting, minimizing errors and compliance risks as you maintain your records 1099-ready for tax season. Enhanced Efficiency and Accuracy When you implement efficient payroll processes, you can greatly improve both accuracy and productivity within your business. By utilizing advanced payroll software solutions, you can automate tasks that traditionally consume significant administrative time, potentially boosting productivity by up to 30%. These systems minimize errors, reducing payroll discrepancies by as much as 80%. Timely direct deposits improve employee satisfaction and retention, as consistent payments are highly valued. Furthermore, consolidating payroll and accounting functions enhances cash flow visibility, allowing for better financial decision-making and cutting late payment penalties by 50%. Incorporating automated tax calculations within your payroll services further guarantees compliance, potentially saving your business an average of $1,500 annually on tax-related issues, ultimately streamlining your operations. https://www.youtube.com/watch?v=FmdpQzURvDQ Simplified Compliance and Reporting Guaranteeing compliance with tax regulations and labor laws can be an intimidating task for small business owners, but adopting automated payroll systems can greatly simplify this process. By using payroll software programs, you minimize errors through automation, guaranteeing timely payments and reducing compliance risks. These systems maintain accurate records of employee hours, wages, and deductions, making adherence to labor laws easier. Key Benefit Description Minimized Errors Automates calculations to guarantee accuracy in payroll. Real-Time Reporting Integrates with accounting software for up-to-date insights. Professional Assistance Payroll and tax services handle forms like W-2s and 1099s. Regular updates help keep your business compliant with changing regulations, saving you time and resources. Essential Bookkeeping Terms Every Business Owner Should Know As a business owner, comprehension fundamental bookkeeping terms is vital for managing your finances effectively. Key concepts like assets, liabilities, and equity form the foundation of your financial health, whereas terms like accounts receivable help you track money owed to your business. Familiarizing yourself with these definitions will improve your ability to maintain accurate records and make informed decisions. Key Bookkeeping Definitions Grasping key bookkeeping definitions is crucial for any business owner looking to maintain accurate financial records and make informed decisions. The accounting equation, Assets = Liabilities + Equity, helps you keep your financial statements balanced. An accounting ledger serves as the master record of all your financial transactions, providing a structured overview of your activities. Accrual accounting records income and expenses when they’re earned or incurred, giving you a clearer financial picture. Double-entry bookkeeping guarantees every transaction affects at least two accounts, enhancing accuracy and reducing errors. Finally, accounts receivable represents money owed to your business for unpaid invoices, important for managing cash flow and comprehending your financial health, especially when utilizing payroll bookkeeping services for small business payroll and accounting. Essential Financial Terminology Having a solid grasp of key bookkeeping definitions lays the groundwork for comprehending fundamental financial terminology that every business owner should know. Here are four significant terms: Accounting Equation: Assets = Liabilities + Equity; it guarantees balance in financial statements. General Ledger: The master record of all financial transactions, providing a structured overview. Accrual Accounting: Records income and expenses when earned or incurred, offering a clearer financial picture. Accounts Receivable: Money owed to your business from unpaid invoices, critical for cash flow management. Understanding these terms is important for effective accounting and payroll management. Utilizing payroll software for small business can streamline these processes and improve your financial oversight. Steps to Set Up Bookkeeping for Your Small Business Setting up bookkeeping for your small business is crucial for maintaining financial health and ensuring compliance with regulations. Start by opening a dedicated business bank account to separate your personal and business finances. This simplifies tracking and improves record accuracy. Next, choose an accounting method that fits your needs, as it affects how you record income and expenses. Diligently track all financial transactions, including payroll, invoices, and receipts, to maintain accuracy and compliance. Consider using accounting software, like QuickBooks, to automate routine tasks and manage financial data effectively. Implement a chart of accounts to categorize your transactions, ensuring clear expectations for timely recording of purchases and payments. If you need assistance, local bookkeepers can provide valuable support in setting up your system. Finally, don’t forget to integrate payroll software for small business to streamline your payroll processes, further enhancing your financial management. Choosing the Right Accounting Method for Your Business How do you decide which accounting method is right for your business? Choosing between cash basis and accrual basis accounting is essential. Here are some factors to take into account: Complexity of Transactions: If your transactions are straightforward, cash basis might be easier to manage. Business Size: Larger businesses often benefit from accrual basis accounting, providing a clearer financial picture. Regulatory Requirements: Some industries require the accrual method when revenue exceeds $26 million annually. Financial Reporting Needs: Reflect on how each method will affect your financial statements and tax obligations. Using small business software with payroll can simplify these processes. Furthermore, payroll software for accountants can help you align your chosen method with your payroll operations. How to Effectively Track Financial Transactions To effectively track financial transactions, you need to organize your records efficiently, utilize accounting software tools, and implement regular reconciliation practices. Keeping your financial documents well-structured and up-to-date not just simplifies tracking but further improves your ability to analyze cash flow. Furthermore, leveraging software can automate many tasks, whereas routine reconciliations help guarantee accuracy and compliance. Organize Financial Records Efficiently Efficiently organizing financial records is crucial for any small business, as it sets the foundation for accurate tracking of financial transactions. Here’s how you can streamline your process: Collect all financial documents: Gather invoices, receipts, and payroll records to create a thorough view of your business transactions. Implement a chart of accounts: Categorize transactions to guarantee each entry aligns with specific business activities, enhancing financial reporting clarity. Utilize accounting software: Use tools like QuickBooks or payroll software for payroll service providers to automate recording and minimize errors. Regular updates and reconciliation: Update records weekly and reconcile accounts monthly to verify transactions against bank statements, confirming accuracy. Utilize Accounting Software Tools With a solid foundation in organizing financial records, the next step is leveraging accounting software tools to improve your tracking of financial transactions. Utilizing platforms like QuickBooks automates your transaction tracking through bank feeds and invoicing, reducing manual entry errors. You can categorize transactions into a structured chart of accounts for easier access and review. Cloud-based accounting tools provide real-time data accuracy, crucial for maintaining current financial records. Many software platforms also include built-in reporting features, generating important profit and loss statements, balance sheets, and cash flow reports. Moreover, by digitizing and storing receipts within these tools, you augment record-keeping practices, simplifying tax deductions. Consider integrating payroll software for Paychex or online payroll software to streamline your payroll processes further. Implement Regular Reconciliation Practices Regularly implementing reconciliation practices is essential for maintaining the accuracy of your financial records, as it helps you identify discrepancies early on. To effectively track financial transactions, follow these steps: Reconcile your accounts at least monthly to guarantee your records are current. Use accounting software, like QuickBooks, to automate bank feeds and access real-time data. Document every transaction with supporting documents, verifying each debit and credit entry. For payroll management, consider using payroll software USA and payroll tax software to streamline payroll processes during keeping accurate financial records. Consistent reconciliation improves cash flow visibility, empowering you to make informed financial decisions and finally enhancing your business performance. Organizing Business Transactions for Clarity Organizing business transactions is essential for maintaining clarity and structure in your financial records, as it allows you to categorize them into a chart of accounts that includes categories like accounts payable and accounts receivable. By aligning each transaction with specific business activities, you guarantee that your financial statements remain accurate, which helps you understand your overall business performance. Utilizing payroll service software for accountants can greatly streamline this process, allowing you to integrate payroll data seamlessly with your other financial records. Regularly recording transactions in the general ledger creates a master record of all financial activity, facilitating easier access for reporting and decision-making. Moreover, consistent organization of your transactions helps visualize cash flow and manage expenses effectively. Regular reconciliation of these entries with your Chase account activity is essential to maintain the integrity of your financial records and guarantee all entries are accurate and accounted for. Matching and Verifying Financial Transactions Ensuring your financial records are accurate requires matching and verifying financial transactions regularly. This process involves reconciling bank statements with your recorded transactions to confirm accuracy. Here’s how to streamline the process: Gather Supporting Documents: Collect invoices, receipts, and bank statements to support each transaction. Use Payroll Programs: Integrate payroll systems software to manage payroll transactions efficiently. Match Entries: Check that each debit and credit entry corresponds with your supporting documents, identifying discrepancies if they arise. Regular Reconciliation: Perform reconciliations frequently to maintain the integrity of your financial reports. Generating Accurate Financial Statements Generating accurate financial statements is essential for evaluating the overall health of your small business, as these documents serve as a snapshot of your financial status. These statements consist of a balance sheet, income statement, and cash flow statement, providing a thorough view of your business’s finances. To generate them effectively, you need to consistently record transactions in your accounting ledger, ensuring all income and expenses are accurately documented. Utilizing payroll softwares and employee payroll programs can streamline this process by automating data entry and syncing bank transactions. Regularly reviewing these financial statements helps you identify trends, make informed decisions, and plan for future growth based on real financial data. Additionally, compliance with tax regulations is essential; timely and accurate financial statements can prevent costly errors and simplify your tax filing process, ultimately contributing to your business’s long-term success. Common Bookkeeping Mistakes to Avoid Maintaining accurate financial statements is only part of effective bookkeeping; avoiding common mistakes is equally important. Many small business owners overlook key areas that can lead to serious issues. Here are four common bookkeeping mistakes to watch out for: Delaying hiring a bookkeeper until tax season can lead to disorganized records, making it tough to meet deadlines. Failing to communicate effectively about financial reports may create discrepancies that impact decision-making and performance. Choosing the wrong accounting method, like cash vs. accrual, can distort your financial health and lead to misinformed strategies. Neglecting regular updates and reconciliations can complicate financial management and increase the risk of audits or compliance issues. Investing in payroll ADP computer software or employer payroll software can help streamline your processes and minimize these mistakes. Best Practices for Maintaining Up-to-Date Records To keep your business finances organized and compliant, establishing best practices for maintaining up-to-date records is essential. Start by scheduling regular bookkeeping sessions, ideally weekly, to update financial records and reconcile accounts. This guarantees timely and accurate data management. Implement a system for organizing receipts and documentation, categorizing them by type and date. This will help maintain clear records for tax deductions and financial tracking. Utilizing accounting software, like QuickBooks, can automate routine tasks such as transaction recording and expense tracking, reducing errors. Furthermore, generate core financial statements monthly, including profit and loss statements and balance sheets, to keep visibility into your business’s financial health. Always keep a dedicated business bank account and credit card for transactions, simplifying tracking and reducing the risk of mixing personal and business expenses. Consider using the best payroll software for small business or online payroll programs to streamline payroll management. Utilizing QuickBooks for Efficient Bookkeeping and Payroll Efficient bookkeeping and payroll management are crucial for small businesses looking to streamline their financial operations. Utilizing QuickBooks can greatly improve your efficiency with its user-friendly features. Here’s how it can help: Automates Accounting Tasks: QuickBooks handles invoicing and expense tracking, saving you valuable time. Real-Time Updates: The software integrates seamlessly with various apps, ensuring your financial data is always up-to-date. Payroll Features: QuickBooks Payroll, ranked as the #1 payroll provider, offers automated tax calculations and direct deposit scheduling. Affordable Plans: Pricing starts at just $12.50/month, and you can try it free for 30 days. Whether you need simple payroll software or a thorough desktop payroll software solution, QuickBooks provides the tools necessary to improve productivity and organization in your business. With an average user rating of 4.0 on G2, it’s a trusted choice for small business bookkeeping and payroll. The Role of Professional Bookkeeping Services in Your Business During running a small business, you might find that managing your finances can be overwhelming, making it challenging to focus on growth. Engaging professional bookkeeping services can alleviate this burden by providing accurate back-office support, ensuring your financial records are up-to-date. This accuracy is essential for better decision-making and tax compliance. By outsourcing your bookkeeping tasks, you can reclaim valuable time each week to concentrate on core business activities. Certified QuickBooks ProAdvisors can customize solutions like QuickBooks Online migrations, streamlining your workflows. Regular bookkeeping leads to organized financial statements and improved cash flow visibility, allowing you to manage expenses and income more effectively. Additionally, professional bookkeeping services can notably reduce stress related to payroll management and tax filing. By using advanced payroll computer programs, these services improve overall business operations and financial health, enabling you to focus on growth opportunities without getting bogged down by financial details. Frequently Asked Questions What Is the Best Payroll and Accounting Software for Small Business? When choosing the best payroll and accounting software for your small business, consider QuickBooks. It’s highly rated for its user-friendly interface and effective payment tracking. With AI features that automate invoicing and expense categorization, it improves efficiency. QuickBooks offers scalable pricing plans starting at $12.50 per month, ensuring it fits various budgets. Moreover, its strong security measures, including data encryption and automatic backups, protect your financial information effectively. How Much to Charge for Bookkeeping and Payroll Services? When determining how much to charge for bookkeeping and payroll services, consider factors like transaction complexity and business size. Typically, bookkeeping fees range from $300 to $2,500 monthly, whereas payroll services may cost $20 to $200 monthly, plus per-employee fees. Offering fixed monthly rates can help businesses budget effectively. Furthermore, specialized services like tax filing may incur extra charges, so be transparent about your pricing structure to guarantee clarity for your clients. Why Are Bookkeepers Declining? The decline in demand for bookkeepers largely stems from the rise of Intuit and artificial intelligence. Many businesses now rely on cloud-based solutions that streamline bookkeeping tasks, reducing the need for manual input. Furthermore, competition from virtual bookkeeping services offers cost-effective alternatives. As small businesses shift in the direction of financial technology integration, the traditional role of bookkeepers is evolving, emphasizing advisory services over basic bookkeeping functions, which further limits job opportunities. How Much Should You Pay a Bookkeeper per Month? When considering how much to pay a bookkeeper per month, you should expect to spend between $300 and $2,500, depending on your business’s complexity and needs. Basic services usually start around $300, whereas additional tasks like payroll can increase costs. Hourly rates can range from $20 to $100, influenced by the bookkeeper’s experience. Many small businesses find remote services more cost-effective, reducing overhead whilst still receiving quality support for their financial tasks. Conclusion In summary, streamlining bookkeeping and payroll is essential for small businesses aiming for operational efficiency and financial accuracy. By automating processes, utilizing accounting software, and considering professional services, you can reduce errors and guarantee timely compliance with tax regulations. Keeping organized records not just improves cash flow visibility but likewise supports informed decision-making. In the end, prioritizing effective bookkeeping practices allows you to focus on your core business activities, reducing stress and enhancing overall performance. Image via Google Gemini This article, "Streamline Small Business Bookkeeping and Payroll" was first published on Small Business Trends View the full article
-
Streamlining your small business bookkeeping and payroll is essential for operational efficiency and accurate financial management. By automating payroll and using accounting software, you can reduce errors and guarantee compliance with tax regulations. Organized financial records not solely improve cash flow visibility but likewise support informed decision-making. As you explore these strategies, consider how outsourcing bookkeeping tasks might allow you to focus on your core business activities and boost overall performance. Key Takeaways Implement accounting software like QuickBooks to automate bookkeeping tasks and minimize manual entry errors. Open a dedicated business bank account to separate personal and business finances for better tracking. Utilize payroll software to streamline payroll processes and ensure timely, accurate payments while reducing compliance risks. Maintain organized financial records by categorizing transactions and updating records weekly for a clearer financial overview. Hire a professional bookkeeper to assist with tax preparation and maintain organized records, enhancing compliance and reducing stress. Understanding the Importance of Bookkeeping for Small Businesses Bookkeeping forms the backbone of financial management for small businesses, and comprehending its importance is fundamental for your success. Accurate bookkeeping and payroll practices are critical for recording, organizing, and categorizing financial transactions, which lay the foundation for effective financial reporting. By maintaining reliable small business bookkeeping and payroll, you gain insights into your cash flow, control expenses, and guarantee compliance with tax regulations. Regular bookkeeping allows you to track daily cash movement, which is significant for managing invoices and payroll efficiently. This clarity on your financial position helps measure your business’s profitability and performance. Conversely, poor bookkeeping can lead to disorganized records, complicating financial management and creating unnecessary stress, especially during tax season. As a result, prioritizing timely and consistent bookkeeping practices not only supports your business’s financial health but likewise empowers you to make informed decisions that drive growth and stability. Key Benefits of Streamlined Payroll Processes Streamlined payroll processes can greatly improve efficiency and accuracy in your business operations. By implementing organized systems for deductions and contractor payments, you’ll guarantee timely and precise payments, reducing administrative time and freeing you to focus on growth. Furthermore, automating payroll tasks helps simplify compliance and reporting, minimizing errors and compliance risks as you maintain your records 1099-ready for tax season. Enhanced Efficiency and Accuracy When you implement efficient payroll processes, you can greatly improve both accuracy and productivity within your business. By utilizing advanced payroll software solutions, you can automate tasks that traditionally consume significant administrative time, potentially boosting productivity by up to 30%. These systems minimize errors, reducing payroll discrepancies by as much as 80%. Timely direct deposits improve employee satisfaction and retention, as consistent payments are highly valued. Furthermore, consolidating payroll and accounting functions enhances cash flow visibility, allowing for better financial decision-making and cutting late payment penalties by 50%. Incorporating automated tax calculations within your payroll services further guarantees compliance, potentially saving your business an average of $1,500 annually on tax-related issues, ultimately streamlining your operations. https://www.youtube.com/watch?v=FmdpQzURvDQ Simplified Compliance and Reporting Guaranteeing compliance with tax regulations and labor laws can be an intimidating task for small business owners, but adopting automated payroll systems can greatly simplify this process. By using payroll software programs, you minimize errors through automation, guaranteeing timely payments and reducing compliance risks. These systems maintain accurate records of employee hours, wages, and deductions, making adherence to labor laws easier. Key Benefit Description Minimized Errors Automates calculations to guarantee accuracy in payroll. Real-Time Reporting Integrates with accounting software for up-to-date insights. Professional Assistance Payroll and tax services handle forms like W-2s and 1099s. Regular updates help keep your business compliant with changing regulations, saving you time and resources. Essential Bookkeeping Terms Every Business Owner Should Know As a business owner, comprehension fundamental bookkeeping terms is vital for managing your finances effectively. Key concepts like assets, liabilities, and equity form the foundation of your financial health, whereas terms like accounts receivable help you track money owed to your business. Familiarizing yourself with these definitions will improve your ability to maintain accurate records and make informed decisions. Key Bookkeeping Definitions Grasping key bookkeeping definitions is crucial for any business owner looking to maintain accurate financial records and make informed decisions. The accounting equation, Assets = Liabilities + Equity, helps you keep your financial statements balanced. An accounting ledger serves as the master record of all your financial transactions, providing a structured overview of your activities. Accrual accounting records income and expenses when they’re earned or incurred, giving you a clearer financial picture. Double-entry bookkeeping guarantees every transaction affects at least two accounts, enhancing accuracy and reducing errors. Finally, accounts receivable represents money owed to your business for unpaid invoices, important for managing cash flow and comprehending your financial health, especially when utilizing payroll bookkeeping services for small business payroll and accounting. Essential Financial Terminology Having a solid grasp of key bookkeeping definitions lays the groundwork for comprehending fundamental financial terminology that every business owner should know. Here are four significant terms: Accounting Equation: Assets = Liabilities + Equity; it guarantees balance in financial statements. General Ledger: The master record of all financial transactions, providing a structured overview. Accrual Accounting: Records income and expenses when earned or incurred, offering a clearer financial picture. Accounts Receivable: Money owed to your business from unpaid invoices, critical for cash flow management. Understanding these terms is important for effective accounting and payroll management. Utilizing payroll software for small business can streamline these processes and improve your financial oversight. Steps to Set Up Bookkeeping for Your Small Business Setting up bookkeeping for your small business is crucial for maintaining financial health and ensuring compliance with regulations. Start by opening a dedicated business bank account to separate your personal and business finances. This simplifies tracking and improves record accuracy. Next, choose an accounting method that fits your needs, as it affects how you record income and expenses. Diligently track all financial transactions, including payroll, invoices, and receipts, to maintain accuracy and compliance. Consider using accounting software, like QuickBooks, to automate routine tasks and manage financial data effectively. Implement a chart of accounts to categorize your transactions, ensuring clear expectations for timely recording of purchases and payments. If you need assistance, local bookkeepers can provide valuable support in setting up your system. Finally, don’t forget to integrate payroll software for small business to streamline your payroll processes, further enhancing your financial management. Choosing the Right Accounting Method for Your Business How do you decide which accounting method is right for your business? Choosing between cash basis and accrual basis accounting is essential. Here are some factors to take into account: Complexity of Transactions: If your transactions are straightforward, cash basis might be easier to manage. Business Size: Larger businesses often benefit from accrual basis accounting, providing a clearer financial picture. Regulatory Requirements: Some industries require the accrual method when revenue exceeds $26 million annually. Financial Reporting Needs: Reflect on how each method will affect your financial statements and tax obligations. Using small business software with payroll can simplify these processes. Furthermore, payroll software for accountants can help you align your chosen method with your payroll operations. How to Effectively Track Financial Transactions To effectively track financial transactions, you need to organize your records efficiently, utilize accounting software tools, and implement regular reconciliation practices. Keeping your financial documents well-structured and up-to-date not just simplifies tracking but further improves your ability to analyze cash flow. Furthermore, leveraging software can automate many tasks, whereas routine reconciliations help guarantee accuracy and compliance. Organize Financial Records Efficiently Efficiently organizing financial records is crucial for any small business, as it sets the foundation for accurate tracking of financial transactions. Here’s how you can streamline your process: Collect all financial documents: Gather invoices, receipts, and payroll records to create a thorough view of your business transactions. Implement a chart of accounts: Categorize transactions to guarantee each entry aligns with specific business activities, enhancing financial reporting clarity. Utilize accounting software: Use tools like QuickBooks or payroll software for payroll service providers to automate recording and minimize errors. Regular updates and reconciliation: Update records weekly and reconcile accounts monthly to verify transactions against bank statements, confirming accuracy. Utilize Accounting Software Tools With a solid foundation in organizing financial records, the next step is leveraging accounting software tools to improve your tracking of financial transactions. Utilizing platforms like QuickBooks automates your transaction tracking through bank feeds and invoicing, reducing manual entry errors. You can categorize transactions into a structured chart of accounts for easier access and review. Cloud-based accounting tools provide real-time data accuracy, crucial for maintaining current financial records. Many software platforms also include built-in reporting features, generating important profit and loss statements, balance sheets, and cash flow reports. Moreover, by digitizing and storing receipts within these tools, you augment record-keeping practices, simplifying tax deductions. Consider integrating payroll software for Paychex or online payroll software to streamline your payroll processes further. Implement Regular Reconciliation Practices Regularly implementing reconciliation practices is essential for maintaining the accuracy of your financial records, as it helps you identify discrepancies early on. To effectively track financial transactions, follow these steps: Reconcile your accounts at least monthly to guarantee your records are current. Use accounting software, like QuickBooks, to automate bank feeds and access real-time data. Document every transaction with supporting documents, verifying each debit and credit entry. For payroll management, consider using payroll software USA and payroll tax software to streamline payroll processes during keeping accurate financial records. Consistent reconciliation improves cash flow visibility, empowering you to make informed financial decisions and finally enhancing your business performance. Organizing Business Transactions for Clarity Organizing business transactions is essential for maintaining clarity and structure in your financial records, as it allows you to categorize them into a chart of accounts that includes categories like accounts payable and accounts receivable. By aligning each transaction with specific business activities, you guarantee that your financial statements remain accurate, which helps you understand your overall business performance. Utilizing payroll service software for accountants can greatly streamline this process, allowing you to integrate payroll data seamlessly with your other financial records. Regularly recording transactions in the general ledger creates a master record of all financial activity, facilitating easier access for reporting and decision-making. Moreover, consistent organization of your transactions helps visualize cash flow and manage expenses effectively. Regular reconciliation of these entries with your Chase account activity is essential to maintain the integrity of your financial records and guarantee all entries are accurate and accounted for. Matching and Verifying Financial Transactions Ensuring your financial records are accurate requires matching and verifying financial transactions regularly. This process involves reconciling bank statements with your recorded transactions to confirm accuracy. Here’s how to streamline the process: Gather Supporting Documents: Collect invoices, receipts, and bank statements to support each transaction. Use Payroll Programs: Integrate payroll systems software to manage payroll transactions efficiently. Match Entries: Check that each debit and credit entry corresponds with your supporting documents, identifying discrepancies if they arise. Regular Reconciliation: Perform reconciliations frequently to maintain the integrity of your financial reports. Generating Accurate Financial Statements Generating accurate financial statements is essential for evaluating the overall health of your small business, as these documents serve as a snapshot of your financial status. These statements consist of a balance sheet, income statement, and cash flow statement, providing a thorough view of your business’s finances. To generate them effectively, you need to consistently record transactions in your accounting ledger, ensuring all income and expenses are accurately documented. Utilizing payroll softwares and employee payroll programs can streamline this process by automating data entry and syncing bank transactions. Regularly reviewing these financial statements helps you identify trends, make informed decisions, and plan for future growth based on real financial data. Additionally, compliance with tax regulations is essential; timely and accurate financial statements can prevent costly errors and simplify your tax filing process, ultimately contributing to your business’s long-term success. Common Bookkeeping Mistakes to Avoid Maintaining accurate financial statements is only part of effective bookkeeping; avoiding common mistakes is equally important. Many small business owners overlook key areas that can lead to serious issues. Here are four common bookkeeping mistakes to watch out for: Delaying hiring a bookkeeper until tax season can lead to disorganized records, making it tough to meet deadlines. Failing to communicate effectively about financial reports may create discrepancies that impact decision-making and performance. Choosing the wrong accounting method, like cash vs. accrual, can distort your financial health and lead to misinformed strategies. Neglecting regular updates and reconciliations can complicate financial management and increase the risk of audits or compliance issues. Investing in payroll ADP computer software or employer payroll software can help streamline your processes and minimize these mistakes. Best Practices for Maintaining Up-to-Date Records To keep your business finances organized and compliant, establishing best practices for maintaining up-to-date records is essential. Start by scheduling regular bookkeeping sessions, ideally weekly, to update financial records and reconcile accounts. This guarantees timely and accurate data management. Implement a system for organizing receipts and documentation, categorizing them by type and date. This will help maintain clear records for tax deductions and financial tracking. Utilizing accounting software, like QuickBooks, can automate routine tasks such as transaction recording and expense tracking, reducing errors. Furthermore, generate core financial statements monthly, including profit and loss statements and balance sheets, to keep visibility into your business’s financial health. Always keep a dedicated business bank account and credit card for transactions, simplifying tracking and reducing the risk of mixing personal and business expenses. Consider using the best payroll software for small business or online payroll programs to streamline payroll management. Utilizing QuickBooks for Efficient Bookkeeping and Payroll Efficient bookkeeping and payroll management are crucial for small businesses looking to streamline their financial operations. Utilizing QuickBooks can greatly improve your efficiency with its user-friendly features. Here’s how it can help: Automates Accounting Tasks: QuickBooks handles invoicing and expense tracking, saving you valuable time. Real-Time Updates: The software integrates seamlessly with various apps, ensuring your financial data is always up-to-date. Payroll Features: QuickBooks Payroll, ranked as the #1 payroll provider, offers automated tax calculations and direct deposit scheduling. Affordable Plans: Pricing starts at just $12.50/month, and you can try it free for 30 days. Whether you need simple payroll software or a thorough desktop payroll software solution, QuickBooks provides the tools necessary to improve productivity and organization in your business. With an average user rating of 4.0 on G2, it’s a trusted choice for small business bookkeeping and payroll. The Role of Professional Bookkeeping Services in Your Business During running a small business, you might find that managing your finances can be overwhelming, making it challenging to focus on growth. Engaging professional bookkeeping services can alleviate this burden by providing accurate back-office support, ensuring your financial records are up-to-date. This accuracy is essential for better decision-making and tax compliance. By outsourcing your bookkeeping tasks, you can reclaim valuable time each week to concentrate on core business activities. Certified QuickBooks ProAdvisors can customize solutions like QuickBooks Online migrations, streamlining your workflows. Regular bookkeeping leads to organized financial statements and improved cash flow visibility, allowing you to manage expenses and income more effectively. Additionally, professional bookkeeping services can notably reduce stress related to payroll management and tax filing. By using advanced payroll computer programs, these services improve overall business operations and financial health, enabling you to focus on growth opportunities without getting bogged down by financial details. Frequently Asked Questions What Is the Best Payroll and Accounting Software for Small Business? When choosing the best payroll and accounting software for your small business, consider QuickBooks. It’s highly rated for its user-friendly interface and effective payment tracking. With AI features that automate invoicing and expense categorization, it improves efficiency. QuickBooks offers scalable pricing plans starting at $12.50 per month, ensuring it fits various budgets. Moreover, its strong security measures, including data encryption and automatic backups, protect your financial information effectively. How Much to Charge for Bookkeeping and Payroll Services? When determining how much to charge for bookkeeping and payroll services, consider factors like transaction complexity and business size. Typically, bookkeeping fees range from $300 to $2,500 monthly, whereas payroll services may cost $20 to $200 monthly, plus per-employee fees. Offering fixed monthly rates can help businesses budget effectively. Furthermore, specialized services like tax filing may incur extra charges, so be transparent about your pricing structure to guarantee clarity for your clients. Why Are Bookkeepers Declining? The decline in demand for bookkeepers largely stems from the rise of Intuit and artificial intelligence. Many businesses now rely on cloud-based solutions that streamline bookkeeping tasks, reducing the need for manual input. Furthermore, competition from virtual bookkeeping services offers cost-effective alternatives. As small businesses shift in the direction of financial technology integration, the traditional role of bookkeepers is evolving, emphasizing advisory services over basic bookkeeping functions, which further limits job opportunities. How Much Should You Pay a Bookkeeper per Month? When considering how much to pay a bookkeeper per month, you should expect to spend between $300 and $2,500, depending on your business’s complexity and needs. Basic services usually start around $300, whereas additional tasks like payroll can increase costs. Hourly rates can range from $20 to $100, influenced by the bookkeeper’s experience. Many small businesses find remote services more cost-effective, reducing overhead whilst still receiving quality support for their financial tasks. Conclusion In summary, streamlining bookkeeping and payroll is essential for small businesses aiming for operational efficiency and financial accuracy. By automating processes, utilizing accounting software, and considering professional services, you can reduce errors and guarantee timely compliance with tax regulations. Keeping organized records not just improves cash flow visibility but likewise supports informed decision-making. In the end, prioritizing effective bookkeeping practices allows you to focus on your core business activities, reducing stress and enhancing overall performance. Image via Google Gemini This article, "Streamline Small Business Bookkeeping and Payroll" was first published on Small Business Trends View the full article
-
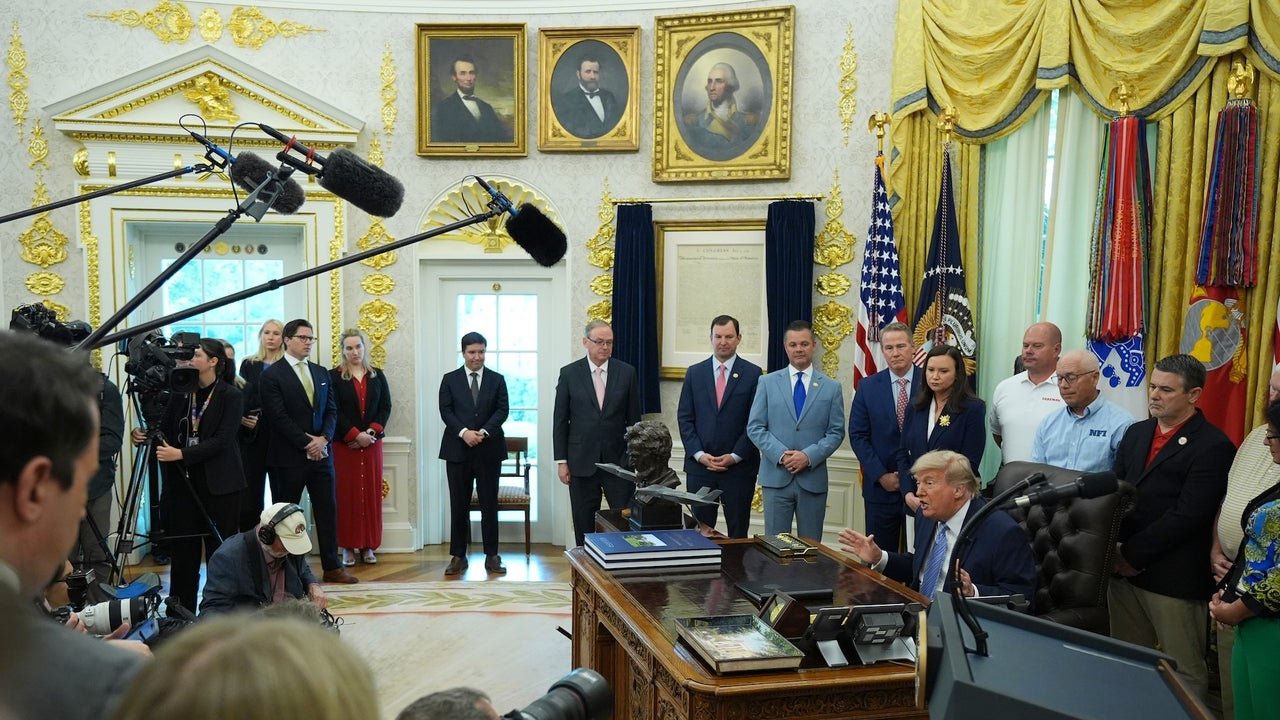
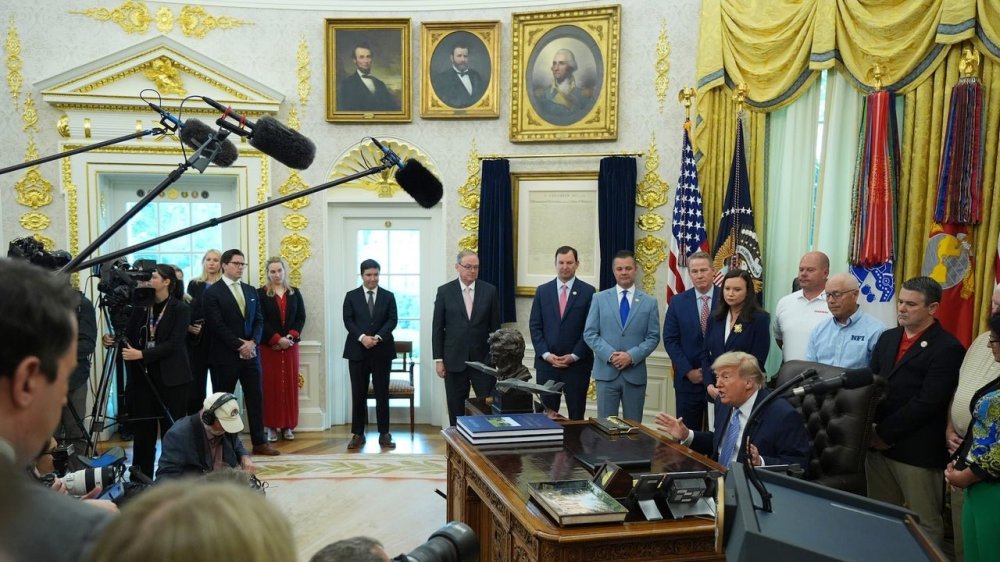
President Donald The President called off plans to sign a new executive order on artificial intelligence hours before an expected White House ceremony Thursday because he said he was worried the measure could dull America’s edge on AI technology. The President said he was postponing the Oval Office event with tech industry executives because he did not like what he saw in the order’s text. “We’re leading China, we’re leading everybody, and I don’t want to do anything that’s going to get in the way of that lead,” The President told reporters. The order would have established a framework for the government to vet the national security risks of the most advanced AI systems before their public release, according to a person familiar with the White House’s deliberations with the tech industry but not authorized to speak about them publicly. The directive was being characterized as a voluntary collaboration with participating U.S.-based tech companies, including Anthropic, OpenAI, and Google, the person said. The push for some kind of government action to review leading AI systems follows growing concern within the banking industry and other institutions about the leaps in AI’s abilities to find cybersecurity vulnerabilities in the world’s software. Treasury Secretary Scott Bessent and outgoing Federal Reserve Chair Jerome Powell convened an urgent meeting with Wall Street CEOs in April, warning them about the cybersecurity risks posed by Anthropic’s AI model, Claude Mythos. The meeting, urgently assembled at the Treasury Department’s headquarters, was intended to ensure that banks were aware of the risks associated with the models, Bessent said at CNBC’s “Invest in America Forum” in Washington in April. “This new Anthropic model is very powerful,” he said. “Some banks are doing a better job in cybersecurity than others, and we want to have the ability to convene them and talk about what is best practices and where they should be heading.” That led some allies of the Republican president to propose better methods for getting those AI tools in the hands of trusted cybersecurity experts. The President’s hopes for AI have run up against voters’ fears of its impact The President had pledged to undo the AI safety regulations set by his predecessor, Democratic President Joe Biden. The President’s administration has viewed the AI sector as an engine to help deliver on his pledges to expand the economy and he has promoted its major players at events at the White House and around the world. Last week, The President had tech CEOs in tow for a summit with China’s Xi Jinping. The President’s ambitions for the sector have collided with the fears of voters over the impact of the technology on American life, jobs and electricity bills. Republicans themselves are divided over whether to embrace the AI industry or side with voters who express skepticism about the technology. Also complicating the government’s interest in working with Anthropic on cybersecurity is the government’s ongoing legal fight with the company. The President in February ordered all U.S. agencies to stop using Anthropic’s chatbot Claude after an unusually public clash between the Pentagon and CEO Dario Amodei. There are competing factions within the administration, said Serena Booth, a computer science professor at Brown University and former AI policy fellow in a Democratic-led Senate committee. “We do see this kind of public fighting,” she said. ”‘We will release an executive order. No, we won’t. We’re going to sign it this afternoon. Oh, the signing is canceled.’ I think this whiplash is because we’re seeing these fractures.’” Some of those divides are balancing what Booth said is a “reasonable idea” to test the most capable AI models before their public release, with a concern that government scrutiny, if it takes too long, could burden AI developers. “It does come at a potential very large cost to innovation and speed of development,” she said. “There is, I think, a real risk here and I do see both sides.” The White House has pushed back against state laws seeking to regulate AI, saying the measures could curb growth. A new executive order that could have been perceived as government screening of commercial AI models would have signaled a significant shift in the administration’s approach. At the same time, similar screening is already happening. The President’s Commerce Department announced earlier this month that it signed agreements with Google, Microsoft, and Elon Musk’s xAI to evaluate their most powerful AI models before their public release, building on previous agreements the Biden administration made with Anthropic and OpenAI. But the announcement later disappeared from the Commerce Department website. White House describes a balance between safety and innovation At a White House press briefing Tuesday, Vice President JD Vance declined to discuss specifics from the order but said the administration wants to promote innovation while also addressing cybersecurity threats and data privacy. “The president wants us to be pro-innovation. He wants us to win the AI race against all other countries in the world,” he said. Vance added, “We also want to make sure that we’re protecting people.” Asked about new models that could pose security risks, Vance said the administration is taking a collaborative approach with tech companies. “It also does have some downsides,” he said, “and we’re trying to balance that safety against innovation.” A former White House tech policy adviser who was a lead author of The President’s AI policy road map said the disagreements likely represent “healthy tension” in an administration that has long been wary of regulating the “frontier AI” companies like Anthropic, OpenAI and Google. “They don’t want to do it because it’s politically risky in a million different ways,” said Dean Ball, now at the Foundation for American Innovation. Ball said he would welcome an executive order that would get those companies working more closely with the government on cybersecurity but “ultimately, I’m fine with them taking time to get this right.” —Collin Binkley and Matt O’Brien, Associated Press Associated Press writer Fatima Hussein contributed to this report. View the full article
-
If you’re leaving meetings feeling destabilized and second-guessing yourself, you’re probably not imagining it. Workplace bullying looks a lot different than it did in middle school. Here’s how to recognize it, respond in the moment, and protect yourself when the bully has power over you. View the full article
-
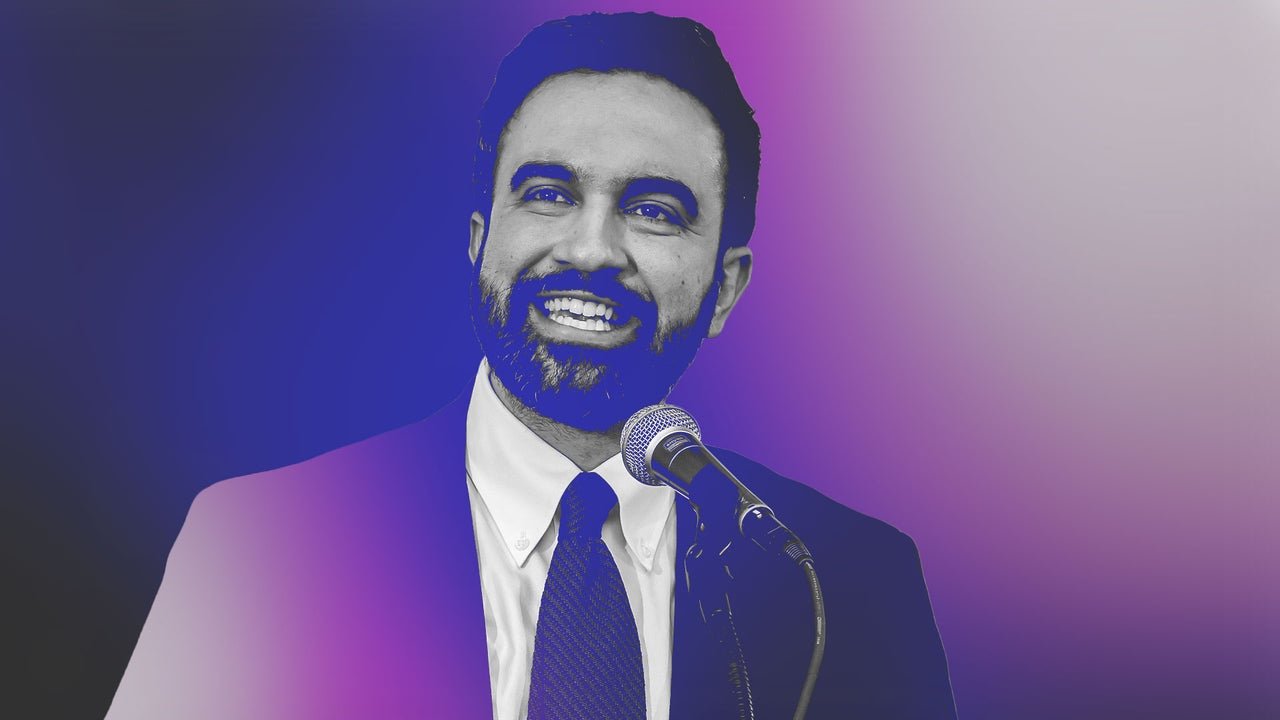
Zohran Mamdani is entering his streamer era. The NYC mayor launched a series on Twitch, titled “Talk with the People,” on May 21. The series has Mamdani answering questions from New Yorkers live on the stream. He announced the series in an Instagram post this morning, featuring a photo of himself and one of a Franklin D. Roosevelt “Fireside Chat.” Mamdani’s campaign was unique in its engaging deployment of social media, and he has continued to create shortform video content since taking office. So it comes as no real surprise that the 34-year-old mayor is utilizing another popular social platform to increase his direct access to constituents. This is the first recurring cross-platform stream hosted by an elected official, but it has its roots in other political eras. Perhaps the most famous example is President Franklin D. Roosevelt’s “Fireside Chats,” which were instituted during the Great Depression and World War II. The idea was that the President was almost sitting in Americans’ living rooms, speaking through their radio as a way to directly address the country—not filtered through the press. But even closer to home for Mayor Mamdani—and the inspiration for the name of his series—is the 1940s radio show of Mayor Fiorello LaGuardia. The former NYC mayor ran his Sunday broadcast “Talk to the People” from January 1942 until the end of his term in December 1945. Now, modern politicians are utilizing these types of shows on platforms like Twitch—which began as a gaming platform, but has recently shifted to include other types of content like politics. IL-D9 Congressional candidate Kat Abughazaleh deployed Twitch during her campaign. She used her social media presence, in part, to mobilize a collective of young voters, many of whom are active on Instagram and Twitch. The use of social media is a growing hallmark of the modern political campaign: Mamdani’s Instagram comment sections were often filled with viewers sharing how much they wished they lived in New York so they could vote for him. In a statement, the mayor described the move as “bringing City Hall directly to the platforms where New Yorkers already spend their time.” Mamdani’s series will broadcast on Twitch, but also be available on YouTube, Instagram, and TikTok. View the full article
-
There’s no doubt that AI has accelerated product marketing. Your copy is getting drafted faster, your personas are cleaner, and your positioning frameworks are getting shipped before your coffee is even cold. But speed has made many teams less disciplined, not more insightful. Too much AI-assisted product marketing sounds polished but lacks grounding in reality. It borrows the language of strategy without doing the strategic work required. You get neat messaging frameworks, confident claims, and copy that sounds familiar in the worst way: “built for modern teams,” “streamline workflows,” “unlock efficiency at scale.” It reads fine. It just doesn’t mean much. That is the risk of speed without discipline. You end up with output that looks finished but was never actually thought through. If you’re tired of seeing the same generic AI outputs dressed up as strategy, it’s time to raise the bar. Here are three ways to make sure your AI brings the evidence that shows you did your homework. DON’T ASSUME AI KNOWS YOUR BUSINESS Developers built large language models to predict language, not to understand your product, your buyer, or your market conditions. So, when marketers ask AI to write positioning without feeding it evidence, the model gives you the most statistically plausible version of product marketing. Not your truth, but the average version of it. Before you prompt, clarify your buyer and product. What are they struggling with? What are they choosing between? What changed that makes your product matter now? If you can’t answer that clearly, the model won’t either. That is why product marketers need to get much more demanding about what goes into these systems. Synthetic audience modeling tools like Mavera are starting to address this gap by grounding AI-assisted decisions in live signals rather than generic training data. FEED IT EVIDENCE, NOT EMPTY PROMPTS If you want AI to help with messaging, give it something worth working from, such as sales call transcripts, win-loss data, product usage patterns, customer objections, competitor movement, and market shifts. The quality of the output depends on the quality of the signal. Otherwise, you’re not using AI to sharpen your thinking; you’re using it to automate guesswork. Quality output needs context. Pull a few real examples before you generate anything. Drop in direct quotes from customers. Summarize what you lost in recent deals. Call out the patterns you’re seeing. Then ask AI to work from that. This is also where a lot of AI-generated marketing falls apart. It makes claims with no proof behind them. Teams collaborate better. Says who? Based on what? Strong product marketing has always required evidence. The best marketers show what changed, who it changed for, and why that matters now. AI should not lower that bar; it should make it easier to clear. GET UNCOMFORTABLY SPECIFIC AI naturally drifts toward broad, safe language unless someone forces it to get concrete. That is still the marketer’s job. Push your prompts further than feels necessary. Who exactly is this for? What are they replacing? What are they skeptical about? What would make them say no? A useful prompt is not, “Write positioning for our product.” It’s a brief with context, constraints, audience tension, and market inputs. If the output still sounds generic, that’s a signal. Go back and tighten the inputs until it can’t be generic. Most teams skip these steps because they slow things down. But this is the work that makes the output worth using. The strongest product marketers are not avoiding AI. They are using it with more rigor. They know it can accelerate drafts, synthesis, and exploration. They also know it can’t replace judgment or decide what matters. It can’t tell the difference between a clean sentence and a true one. If AI is going to sit inside your product marketing workflow, it needs to bring the evidence of its work. If it can’t, it has no business shaping your message. Lisa Larson-Kelley is the founder and CEO of Quantious. View the full article
-
Shares in US cosmetics giant jump 11.5% in post-market trading as investors welcome end of discussionsView the full article
-
If you’re considering starting a business, comprehending what an LLC, or Limited Liability Company, is can be vital. An LLC combines the benefits of a corporation and a partnership, offering personal asset protection during flexible management structures. This guide will walk you through the fundamental steps to form an LLC, from selecting a unique name to filing the necessary paperwork. Each step is important for ensuring your business is set up correctly and legally compliant. Key Takeaways An LLC, or Limited Liability Company, protects members’ personal assets from business liabilities while offering tax benefits. To form an LLC, you must file articles of organization with the appropriate state authorities. Choose a unique name for your LLC that includes “Limited Liability Company,” “LLC,” or “L.L.C.” Appoint a registered agent to receive legal documents on behalf of the LLC and ensure compliance. Drafting an Operating Agreement is recommended to outline management roles and profit distribution among members. What Is an LLC? An LLC, or Limited Liability Company, is a popular business structure that offers a blend of liability protection and tax advantages. The LLC company meaning revolves around its ability to protect its members’ personal assets from business debts and legal actions, ensuring limited liability. This structure is especially appealing in California, where the cost to establish one can vary. So, how much is an LLC in California? You can expect to pay a filing fee along with an annual franchise tax. To officially create your LLC, you’ll need to complete the California LLC filing, which involves submitting articles of organization that outline your business’s name, address, and registered agent. Furthermore, LLCs can be managed flexibly, either by the members themselves or by appointed managers, adapting to your operational preferences while maintaining the significant benefits that come with this business format. Pros and Cons of an LLC When considering an LLC, it’s important to weigh its benefits and drawbacks. You’ll enjoy personal asset protection, which safeguards your belongings from business liabilities, along with a flexible management structure that suits your operational style. Nevertheless, keep in mind the ongoing compliance requirements and costs, which can be more significant than those of simpler business forms. Personal Asset Protection Though many entrepreneurs seek to protect their personal assets, comprehending the nuances of how an LLC provides this protection is vital. An LLC limits your liability for business debts and legal judgments, ensuring that your personal assets, like homes and savings, are typically shielded from creditors. On the other hand, this personal asset protection can be compromised if you fail to maintain separate business records and accounts. Unlike sole proprietorships, LLCs protect your wealth against business-related lawsuits, making them ideal for high-risk industries. Furthermore, although LLCs offer this shield, you’re still personally liable for negligent actions or personal guarantees for loans. When considering the California cost and California tax, weigh these protections against potential risks to make informed decisions. Flexible Management Structure The flexible management structure of an LLC offers significant advantages for business owners, allowing for both member-managed and manager-managed configurations. In a member-managed LLC, all owners participate in daily operations, promoting collaboration and shared responsibility. This setup encourages democratic decision-making, which can be beneficial for small groups. Conversely, a manager-managed LLC is ideal for businesses with passive investors or those preferring professionals to handle operations, streamlining the management process. This adaptability is particularly useful for LLCs in California, where changing business needs arise. Moreover, varying roles and responsibilities can be detailed in the operating agreement, ensuring clarity in governance. Just remember the California LLC annual fee when planning your management structure to maintain compliance. Ongoing Compliance Requirements Grasping ongoing compliance requirements is fundamental for anyone pondering forming an LLC, as failing to meet these obligations can have significant consequences for your business. Here are some key aspects you need to reflect on: You must appoint a registered agent to receive legal documents. Filing annual reports and paying fees, such as the LLC cost for filing in California, is imperative to maintain good standing. Keeping accurate records, like an Operating Agreement, is crucial to clarify ownership and management. Neglecting these requirements can lead to penalties, loss of status, and even compromise your personal liability protection. It’s important to understand that higher maintenance costs may arise compared to simpler structures like sole proprietorships. Stay informed and compliant to protect your LLC. Step 1: Choose a Formation State When you’re choosing a formation state for your LLC, think about where your business will primarily operate, as this can help streamline compliance and cut costs. Each state has its own regulations and tax implications, so researching these factors is vital before making a decision. A solid legal framework in your chosen state can improve your business’s credibility and protect your personal assets effectively. Selecting Business Location Choosing the right formation state for your LLC is crucial—how do you determine which one suits your business best? Start by considering where you’ll primarily conduct business, as this simplifies compliance and legal obligations. Here are three key factors to weigh: State Laws: Some states, like Delaware, Nevada, and Wyoming, offer favorable business laws and lower taxes, making them popular choices. Filing Fees: Each state has different fees; for example, Pennsylvania charges $125 for the Certificate of Organization. Ongoing Compliance: Regulations vary greatly, affecting your annual reporting and tax obligations. If you operate in multiple states, remember you may need to register your LLC in each one, which requires foreign qualification. State Regulations Consideration Selecting the right state for forming your LLC is critical, as it directly impacts your business’s compliance and legal obligations. Typically, it’s best to choose the state where your business will primarily operate. This approach simplifies compliance and reduces legal intricacies. Each state has varying formation fees and annual maintenance costs; for instance, Delaware and Nevada are often favored for their business-friendly regulations and lower expenses. Moreover, consider the legal requirements and protections each state offers, as some may provide better asset protection. Be aware that states treat foreign LLCs differently, requiring registration and compliance with local laws. Researching state-specific regulations, including the need for a registered agent and ongoing reporting requirements, is vital for maintaining good standing for your LLC. Tax Implications Analysis The choice of a formation state for your LLC plays a pivotal role in shaping your business’s tax obligations. Different states have varying tax rates and requirements that can greatly impact your finances. Here are three key factors to take into account: State Income Tax: Some states, like Delaware and Nevada, don’t impose state income tax, which can save you money. Franchise Tax Rates: States impose different franchise taxes; researching these rates can lead to considerable savings. Compliance Costs: Each state has unique compliance requirements that can incur additional fees, so factor these into your decision. Choosing wisely not just eases tax reporting but likewise helps guarantee your LLC remains compliant with local regulations, providing a stable foundation for your business. Step 2: Select a Name for Your LLC What makes a name suitable for your LLC? First, your chosen name must comply with state regulations by including “Limited Liability Company,” “LLC,” or “L.L.C.” as a suffix. This clearly indicates your business structure to customers and partners. In addition, make sure the name is unique and distinguishable from existing businesses in your state to avoid legal conflicts. To confirm availability, conduct a name search using your state’s business entity database. It’s crucial to avoid restricted words like “bank” or “insurance,” as these may require extra approvals or licenses. Moreover, think about your future branding and expansion when selecting a name; it should remain relevant as your business grows or diversifies. A well-chosen name not only reflects your business identity but also sets the tone for your brand’s reputation. Taking these factors into account will help you select an effective, compliant name for your LLC. Step 3: Choose a Registered Agent Once you’ve settled on a suitable name for your LLC, the next step involves choosing a registered agent. This individual or entity will receive legal documents, tax notifications, and official correspondence on behalf of your LLC. Here are three important factors to take into account when selecting your registered agent: Physical Address: They must have a physical street address in your LLC’s state, as P.O. Boxes aren’t acceptable. Availability: The agent needs to be available during standard business hours to guarantee timely receipt of documents, avoiding potential default judgments. Reliability: Since public records will list their name and address, selecting a trustworthy agent is essential for maintaining your LLC’s good standing. You can choose an owner, an employee, or a professional registered agent service, which is often recommended for privacy and compliance expertise. Make this choice wisely, as it impacts your LLC’s legal standing markedly. Step 4: Determine the LLC Management Structure How will you decide on the management structure for your LLC? You have two primary options: member-managed or manager-managed. In a member-managed LLC, all members participate in daily operations and usually have equal rights except specified otherwise. Conversely, a manager-managed LLC allows you to appoint one or more managers—who may or may not be members—to oversee operations, separating ownership from management. It’s essential to indicate your chosen management structure in the articles of organization, as some states require this for formation. Clarity in this structure helps establish operational responsibilities and decision-making authority, reducing potential conflicts among members. Management Structure Description Member-Managed All members participate in daily operations. Manager-Managed Designated managers handle business decisions. Rights Distribution Equal rights except specified otherwise. Separation of Roles Clear distinction between ownership and management. Step 5: Draft Your Operating Agreement Drafting your operating agreement is essential for establishing a solid foundation for your LLC, as this document clearly outlines the management structure, roles, and responsibilities of its members. Although it may not always be legally required, having one is highly recommended to protect your interests and prevent disputes, especially in multi-member LLCs. Your operating agreement should include: Ownership percentages: Clearly define who owns what share of the LLC. Profit distribution: Outline how profits will be shared among members to avoid confusion later. Decision-making authority: Specify who’s the authority to make decisions and the procedures for adding or removing members. This document serves as an internal guide for your LLC, helping to establish operational guidelines and protect your business’s limited liability status. Plus, it improves your LLC’s credibility by demonstrating professionalism to potential investors or partners. Step 6: File Articles of Organization Filing the Articles of Organization is a crucial step in establishing your LLC, as it officially registers your business with the state. This document, also referred to as the Certificate of Formation, is required to create your LLC and must be submitted to the state’s Secretary of State office. It typically includes the LLC’s name, principal address, purpose, and registered agent details. Here’s a quick overview of what to expect: Information Needed Filing Fees Filing Options LLC’s Name $50 – $200 Online or by Mail Principal Address Varies by State Expedites Process Registered Agent Details Approval in 5-7 Days Filing fees vary by state and are due upon submission. Once approved, the Articles of Organization serve as legal proof of your LLC’s existence, which is crucial for obtaining an EIN and opening a business bank account. Step 7: Obtain Necessary Licenses and Permits After successfully filing your Articles of Organization, the next vital step is to obtain the necessary licenses and permits to operate your LLC legally. Depending on your business type and location, you may need various licenses. Here are three key areas to focus on: General Business Licenses: Check if your state or local municipality requires a general business license for your LLC. Industry-Specific Permits: If you’re in industries like food service, healthcare, or construction, additional permits may be important for compliance with safety standards. Zoning Permits: Confirm your business location complies with local zoning laws that dictate what types of businesses can operate in certain areas. It’s vital to verify both state and local regulations to confirm you’ve covered all bases. Resources like the Small Business Administration and local chambers of commerce can provide valuable guidance for your specific needs. Frequently Asked Questions What Is an LLC Explained for Dummies? An LLC, or Limited Liability Company, is a flexible business structure that protects your personal assets from business debts and legal issues. It allows profits and losses to pass through to your personal tax return, avoiding double taxation. To form an LLC, you’ll need to file articles of organization with your state, detailing your LLC’s name and address. You can choose between member-managed or manager-managed structures, enhancing your operational flexibility. How to Start an LLC in 7 Easy Steps? To start an LLC, first choose a unique name that meets state regulations, including the “LLC” suffix. Then, designate a registered agent with a physical address in your state. Next, prepare and file the Articles of Organization with the required details and appropriate filing fee. Create an operating agreement for clarity among members, and finally, obtain an EIN from the IRS and open a dedicated business bank account to manage finances separately. What Is the Biggest Disadvantage of an LLC? The biggest disadvantage of an LLC is often the higher formation and ongoing maintenance costs compared to simpler structures like sole proprietorships. You’ll face compliance requirements, such as appointing a registered agent and filing annual reports, which can be burdensome. Furthermore, ownership transfer can be limited, requiring existing members’ approval. If you don’t maintain the LLC properly, you risk losing limited liability protection, exposing yourself to personal liability for business debts. What Is an LLC and How Does It Work? An LLC, or Limited Liability Company, is a business structure that offers liability protection for its owners, called members. This means your personal assets are shielded from business debts and legal issues. LLCs enjoy pass-through taxation, allowing profits and losses to appear on your personal tax returns. You can manage it yourself or appoint a manager. To form an LLC, you need to file Articles of Organization with your state, including necessary details and fees. Conclusion In summary, forming an LLC offers significant advantages, including personal asset protection and tax benefits. By following the outlined steps—choosing a formation state, selecting a name, appointing a registered agent, determining the management structure, drafting an Operating Agreement, and filing Articles of Organization—you can successfully establish your business. Remember to additionally obtain any necessary licenses and permits to guarantee compliance. Comprehending these elements is vital for setting a strong foundation for your entrepreneurial path. Image via Google Gemini This article, "Understanding LLC Company Meaning – A Step-by-Step Guide" was first published on Small Business Trends View the full article
-
If you’re considering starting a business, comprehending what an LLC, or Limited Liability Company, is can be vital. An LLC combines the benefits of a corporation and a partnership, offering personal asset protection during flexible management structures. This guide will walk you through the fundamental steps to form an LLC, from selecting a unique name to filing the necessary paperwork. Each step is important for ensuring your business is set up correctly and legally compliant. Key Takeaways An LLC, or Limited Liability Company, protects members’ personal assets from business liabilities while offering tax benefits. To form an LLC, you must file articles of organization with the appropriate state authorities. Choose a unique name for your LLC that includes “Limited Liability Company,” “LLC,” or “L.L.C.” Appoint a registered agent to receive legal documents on behalf of the LLC and ensure compliance. Drafting an Operating Agreement is recommended to outline management roles and profit distribution among members. What Is an LLC? An LLC, or Limited Liability Company, is a popular business structure that offers a blend of liability protection and tax advantages. The LLC company meaning revolves around its ability to protect its members’ personal assets from business debts and legal actions, ensuring limited liability. This structure is especially appealing in California, where the cost to establish one can vary. So, how much is an LLC in California? You can expect to pay a filing fee along with an annual franchise tax. To officially create your LLC, you’ll need to complete the California LLC filing, which involves submitting articles of organization that outline your business’s name, address, and registered agent. Furthermore, LLCs can be managed flexibly, either by the members themselves or by appointed managers, adapting to your operational preferences while maintaining the significant benefits that come with this business format. Pros and Cons of an LLC When considering an LLC, it’s important to weigh its benefits and drawbacks. You’ll enjoy personal asset protection, which safeguards your belongings from business liabilities, along with a flexible management structure that suits your operational style. Nevertheless, keep in mind the ongoing compliance requirements and costs, which can be more significant than those of simpler business forms. Personal Asset Protection Though many entrepreneurs seek to protect their personal assets, comprehending the nuances of how an LLC provides this protection is vital. An LLC limits your liability for business debts and legal judgments, ensuring that your personal assets, like homes and savings, are typically shielded from creditors. On the other hand, this personal asset protection can be compromised if you fail to maintain separate business records and accounts. Unlike sole proprietorships, LLCs protect your wealth against business-related lawsuits, making them ideal for high-risk industries. Furthermore, although LLCs offer this shield, you’re still personally liable for negligent actions or personal guarantees for loans. When considering the California cost and California tax, weigh these protections against potential risks to make informed decisions. Flexible Management Structure The flexible management structure of an LLC offers significant advantages for business owners, allowing for both member-managed and manager-managed configurations. In a member-managed LLC, all owners participate in daily operations, promoting collaboration and shared responsibility. This setup encourages democratic decision-making, which can be beneficial for small groups. Conversely, a manager-managed LLC is ideal for businesses with passive investors or those preferring professionals to handle operations, streamlining the management process. This adaptability is particularly useful for LLCs in California, where changing business needs arise. Moreover, varying roles and responsibilities can be detailed in the operating agreement, ensuring clarity in governance. Just remember the California LLC annual fee when planning your management structure to maintain compliance. Ongoing Compliance Requirements Grasping ongoing compliance requirements is fundamental for anyone pondering forming an LLC, as failing to meet these obligations can have significant consequences for your business. Here are some key aspects you need to reflect on: You must appoint a registered agent to receive legal documents. Filing annual reports and paying fees, such as the LLC cost for filing in California, is imperative to maintain good standing. Keeping accurate records, like an Operating Agreement, is crucial to clarify ownership and management. Neglecting these requirements can lead to penalties, loss of status, and even compromise your personal liability protection. It’s important to understand that higher maintenance costs may arise compared to simpler structures like sole proprietorships. Stay informed and compliant to protect your LLC. Step 1: Choose a Formation State When you’re choosing a formation state for your LLC, think about where your business will primarily operate, as this can help streamline compliance and cut costs. Each state has its own regulations and tax implications, so researching these factors is vital before making a decision. A solid legal framework in your chosen state can improve your business’s credibility and protect your personal assets effectively. Selecting Business Location Choosing the right formation state for your LLC is crucial—how do you determine which one suits your business best? Start by considering where you’ll primarily conduct business, as this simplifies compliance and legal obligations. Here are three key factors to weigh: State Laws: Some states, like Delaware, Nevada, and Wyoming, offer favorable business laws and lower taxes, making them popular choices. Filing Fees: Each state has different fees; for example, Pennsylvania charges $125 for the Certificate of Organization. Ongoing Compliance: Regulations vary greatly, affecting your annual reporting and tax obligations. If you operate in multiple states, remember you may need to register your LLC in each one, which requires foreign qualification. State Regulations Consideration Selecting the right state for forming your LLC is critical, as it directly impacts your business’s compliance and legal obligations. Typically, it’s best to choose the state where your business will primarily operate. This approach simplifies compliance and reduces legal intricacies. Each state has varying formation fees and annual maintenance costs; for instance, Delaware and Nevada are often favored for their business-friendly regulations and lower expenses. Moreover, consider the legal requirements and protections each state offers, as some may provide better asset protection. Be aware that states treat foreign LLCs differently, requiring registration and compliance with local laws. Researching state-specific regulations, including the need for a registered agent and ongoing reporting requirements, is vital for maintaining good standing for your LLC. Tax Implications Analysis The choice of a formation state for your LLC plays a pivotal role in shaping your business’s tax obligations. Different states have varying tax rates and requirements that can greatly impact your finances. Here are three key factors to take into account: State Income Tax: Some states, like Delaware and Nevada, don’t impose state income tax, which can save you money. Franchise Tax Rates: States impose different franchise taxes; researching these rates can lead to considerable savings. Compliance Costs: Each state has unique compliance requirements that can incur additional fees, so factor these into your decision. Choosing wisely not just eases tax reporting but likewise helps guarantee your LLC remains compliant with local regulations, providing a stable foundation for your business. Step 2: Select a Name for Your LLC What makes a name suitable for your LLC? First, your chosen name must comply with state regulations by including “Limited Liability Company,” “LLC,” or “L.L.C.” as a suffix. This clearly indicates your business structure to customers and partners. In addition, make sure the name is unique and distinguishable from existing businesses in your state to avoid legal conflicts. To confirm availability, conduct a name search using your state’s business entity database. It’s crucial to avoid restricted words like “bank” or “insurance,” as these may require extra approvals or licenses. Moreover, think about your future branding and expansion when selecting a name; it should remain relevant as your business grows or diversifies. A well-chosen name not only reflects your business identity but also sets the tone for your brand’s reputation. Taking these factors into account will help you select an effective, compliant name for your LLC. Step 3: Choose a Registered Agent Once you’ve settled on a suitable name for your LLC, the next step involves choosing a registered agent. This individual or entity will receive legal documents, tax notifications, and official correspondence on behalf of your LLC. Here are three important factors to take into account when selecting your registered agent: Physical Address: They must have a physical street address in your LLC’s state, as P.O. Boxes aren’t acceptable. Availability: The agent needs to be available during standard business hours to guarantee timely receipt of documents, avoiding potential default judgments. Reliability: Since public records will list their name and address, selecting a trustworthy agent is essential for maintaining your LLC’s good standing. You can choose an owner, an employee, or a professional registered agent service, which is often recommended for privacy and compliance expertise. Make this choice wisely, as it impacts your LLC’s legal standing markedly. Step 4: Determine the LLC Management Structure How will you decide on the management structure for your LLC? You have two primary options: member-managed or manager-managed. In a member-managed LLC, all members participate in daily operations and usually have equal rights except specified otherwise. Conversely, a manager-managed LLC allows you to appoint one or more managers—who may or may not be members—to oversee operations, separating ownership from management. It’s essential to indicate your chosen management structure in the articles of organization, as some states require this for formation. Clarity in this structure helps establish operational responsibilities and decision-making authority, reducing potential conflicts among members. Management Structure Description Member-Managed All members participate in daily operations. Manager-Managed Designated managers handle business decisions. Rights Distribution Equal rights except specified otherwise. Separation of Roles Clear distinction between ownership and management. Step 5: Draft Your Operating Agreement Drafting your operating agreement is essential for establishing a solid foundation for your LLC, as this document clearly outlines the management structure, roles, and responsibilities of its members. Although it may not always be legally required, having one is highly recommended to protect your interests and prevent disputes, especially in multi-member LLCs. Your operating agreement should include: Ownership percentages: Clearly define who owns what share of the LLC. Profit distribution: Outline how profits will be shared among members to avoid confusion later. Decision-making authority: Specify who’s the authority to make decisions and the procedures for adding or removing members. This document serves as an internal guide for your LLC, helping to establish operational guidelines and protect your business’s limited liability status. Plus, it improves your LLC’s credibility by demonstrating professionalism to potential investors or partners. Step 6: File Articles of Organization Filing the Articles of Organization is a crucial step in establishing your LLC, as it officially registers your business with the state. This document, also referred to as the Certificate of Formation, is required to create your LLC and must be submitted to the state’s Secretary of State office. It typically includes the LLC’s name, principal address, purpose, and registered agent details. Here’s a quick overview of what to expect: Information Needed Filing Fees Filing Options LLC’s Name $50 – $200 Online or by Mail Principal Address Varies by State Expedites Process Registered Agent Details Approval in 5-7 Days Filing fees vary by state and are due upon submission. Once approved, the Articles of Organization serve as legal proof of your LLC’s existence, which is crucial for obtaining an EIN and opening a business bank account. Step 7: Obtain Necessary Licenses and Permits After successfully filing your Articles of Organization, the next vital step is to obtain the necessary licenses and permits to operate your LLC legally. Depending on your business type and location, you may need various licenses. Here are three key areas to focus on: General Business Licenses: Check if your state or local municipality requires a general business license for your LLC. Industry-Specific Permits: If you’re in industries like food service, healthcare, or construction, additional permits may be important for compliance with safety standards. Zoning Permits: Confirm your business location complies with local zoning laws that dictate what types of businesses can operate in certain areas. It’s vital to verify both state and local regulations to confirm you’ve covered all bases. Resources like the Small Business Administration and local chambers of commerce can provide valuable guidance for your specific needs. Frequently Asked Questions What Is an LLC Explained for Dummies? An LLC, or Limited Liability Company, is a flexible business structure that protects your personal assets from business debts and legal issues. It allows profits and losses to pass through to your personal tax return, avoiding double taxation. To form an LLC, you’ll need to file articles of organization with your state, detailing your LLC’s name and address. You can choose between member-managed or manager-managed structures, enhancing your operational flexibility. How to Start an LLC in 7 Easy Steps? To start an LLC, first choose a unique name that meets state regulations, including the “LLC” suffix. Then, designate a registered agent with a physical address in your state. Next, prepare and file the Articles of Organization with the required details and appropriate filing fee. Create an operating agreement for clarity among members, and finally, obtain an EIN from the IRS and open a dedicated business bank account to manage finances separately. What Is the Biggest Disadvantage of an LLC? The biggest disadvantage of an LLC is often the higher formation and ongoing maintenance costs compared to simpler structures like sole proprietorships. You’ll face compliance requirements, such as appointing a registered agent and filing annual reports, which can be burdensome. Furthermore, ownership transfer can be limited, requiring existing members’ approval. If you don’t maintain the LLC properly, you risk losing limited liability protection, exposing yourself to personal liability for business debts. What Is an LLC and How Does It Work? An LLC, or Limited Liability Company, is a business structure that offers liability protection for its owners, called members. This means your personal assets are shielded from business debts and legal issues. LLCs enjoy pass-through taxation, allowing profits and losses to appear on your personal tax returns. You can manage it yourself or appoint a manager. To form an LLC, you need to file Articles of Organization with your state, including necessary details and fees. Conclusion In summary, forming an LLC offers significant advantages, including personal asset protection and tax benefits. By following the outlined steps—choosing a formation state, selecting a name, appointing a registered agent, determining the management structure, drafting an Operating Agreement, and filing Articles of Organization—you can successfully establish your business. Remember to additionally obtain any necessary licenses and permits to guarantee compliance. Comprehending these elements is vital for setting a strong foundation for your entrepreneurial path. Image via Google Gemini This article, "Understanding LLC Company Meaning – A Step-by-Step Guide" was first published on Small Business Trends View the full article
-
Elon Musk’s space conglomerate warned in IPO filing that its strategy is ‘highly dependent’ on the massive rocketView the full article
-
Copper Ridge Ventures has joint venture businesses with mortgage loan officers and real estate professionals using the same broker model as NEXA Lending. View the full article
-
VantageScore 4.0 has been incorporated into the existing processes at Rocket for both the retail and mortgage broker-facing origination businesses. View the full article
-
Senators postpone vote on bill because of ‘concern’ over the $1.8bn earmarked for alleged victims of ‘lawfare’View the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. A ton of early Memorial Day sales are going on right now, and if you're an audiophiles, one of the best is happening over on Amazon, where tons of Sonos speakers are seeing huge discounts. Nearly every soundbar, smart speaker, subwoofer, or portable speaker the company makes is on sale right now, some for as much as $200 off. Sonos Era 100 SL - Compact, Microphone-Free Speaker with WiFi, Bluetooth - White $169.00 at Amazon $189.00 Save $20.00 Get Deal Get Deal $169.00 at Amazon $189.00 Save $20.00 Sonos Roam 2 Portable Waterproof Bluetooth Speaker (White) $134.00 at Amazon $179.00 Save $45.00 Get Deal Get Deal $134.00 at Amazon $179.00 Save $45.00 Sonos Sub Mini - White - Compact Wireless Subwoofer $399.00 at Amazon $499.00 Save $100.00 Get Deal Get Deal $399.00 at Amazon $499.00 Save $100.00 Dolby Atmos and Voice Control - 9.1.4 Surround Sound for TV and Music - Black Sonos Arc Ultra Soundbar $899.00 at Amazon $1,099.00 Save $200.00 Get Deal Get Deal $899.00 at Amazon $1,099.00 Save $200.00 Sonos Beam Gen 2 5.0ch Dolby Atmos Smart Soundbar (Black) $369.00 at Amazon $499.00 Save $130.00 Get Deal Get Deal $369.00 at Amazon $499.00 Save $130.00 Sonos Move 2 Wireless Bluetooth Portable Speaker (White) $399.00 at Amazon $499.00 Save $100.00 Get Deal Get Deal $399.00 at Amazon $499.00 Save $100.00 Sonos Era 300 Wireless Speaker - White $379.00 at Amazon $479.00 Save $100.00 Get Deal Get Deal $379.00 at Amazon $479.00 Save $100.00 Wireless Subwoofer - White Sonos Sub 4 $759.00 at Amazon $899.00 Save $140.00 Get Deal Get Deal $759.00 at Amazon $899.00 Save $140.00 Sonos Five The High-Fidelity Speaker $479.00 at Amazon $599.00 Save $120.00 Get Deal Get Deal $479.00 at Amazon $599.00 Save $120.00 Compact Wireless Speaker for Streaming Music. Compatible with Alexa. (White) (Renewed) Sonos Play:1 $159.41 at Amazon Get Deal Get Deal $159.41 at Amazon SEE 7 MORE The Sonos Era 100 SL is an updated version of the Sonos Era 100 smart speaker, which ditches its microphone (and thus its smart speaker capabilities) in favor of a $60 reduction in price. It is currently down to its lowest price ever, $169 (originally $189), according to price-checking tools. The Sonos Era 100 SL came out this February, and other than the microphone, it's the same exact speaker as the Era 100, which received an "excellent" review from PCMag. The speaker works with both Bluetooth and wifi and integrates seamlessly with most major music streaming services. The Roam 2 is Sonos' version of a portable speaker, and it integrates seamlessly into the ecosystem, giving you the freedom to play multi-room media. It has a speakerphone feature, in-app EQ, wireless charging, and water resistance, and it is compatible with the Alexa and Sonos voice assistants, according to PCMag's review. At $134 (originally $179), the Roam 2 is the cheapest Sonos speaker you can buy. The Sonos Sub Mini is a smaller and more affordable version of the Sonos Sub, and it's $399 (originally $499). It's perfect for a small apartment or a room where you want a soundbar and subwoofer combo. You can get Sonos' latest flagship soundbar, the Arc Ultra, for $899 (originally $999) after a $100 discount. The Arc Ultra succeeded the already excellent Arc Soundbar, adding Bluetooth and a more immersive audio experience with deeper bass and clearer dialogue, according to PCMag's "outstanding" review. This is a very long soundbar, measuring 2.95 by 46.38 by 4.35 inches, so make sure you have the space for it. If you don't have the space, the Sonos Beam Gen 2 is much more compact and is going for $369 (originally $499). It has Atmos compatibility, eARC connectivity, NFC connectivity, and a better processor than the Gen 1, according to CNET's review. The Sonos Move 2 is a portable smart speaker offering an impressive 24-hour battery life that makes the imposing design a bit more palatable. You can get one for $399 (originally $499). If you don't care about portability, you can opt for the Sonos Era 300 for $379 (originally $449). It has better bass, plays Dolby Atmos tracks from Apple Music and Amazon Music, and retains most of the other features of the Sonos Move 2. (PCMag gave it an "excellent" review.) The Sub 4 is Sonos' flagship soundwoofer, and it can make your living room rumble when you pair it with a Sonos soundbar to generate theater-worthy sound. You can get it for $759 (originally $899). The Sonos Five has been around for a while. It's a powerful wireless speaker perfect to set up on a bookshelf or kitchen counter, or to use with a turntable. It's $479 (originally $599) right now. Even older than the Sonos Five is the Sonos Play:1,; this is likely why it's being sold as renewed instead of new (you likely won't find this speaker new anywhere in 2026). It's one of Sonos' earliest wireless multi-room speakers, and you can get one for $154.51 (originally $199.99). View the full article
-
Energy costs are increasing, and while it may cost a lot more than before to heat or cool a home, they’re basically peanuts compared to operating a hockey arena. That’s why the National Hockey League is bringing in a building automation heavyweight to help. This week, the NHL announced a new partnership with Honeywell aimed at increasing the efficiency of hockey facilities around the country in an attempt to lower operating costs. The multi-year partnership makes Honeywell—a massive company that provides products and services to many different industries—the “Official Building Automation and Energy Management Partner of the NHL.” The primary issue the partnership seeks to address is a lack of energy efficiency in NHL arenas, practice facilities, and community rinks across the U.S. and Canada, and as such, Honeywell will analyze, address, and then provide AI-enabled automation technologies to lower power consumption and help with climate control. Ice is a difficult thing to manage, particularly in buildings that are also hosting tens of thousands of people for basketball games, concerts, and other events—Honeywell’s tech, hopefully, will help make it easier to control costs related to energy usage. “We keep pumping more technology into our buildings, it’s getting more complex in there, we’re using more energy, and having Honeywell help us be more efficient is hugely important,” David Lehanski, SVP of business development and innovation at the NHL, tells Fast Company. Developing automation plans at NHL arenas The cost increases are no joke, either. Greg Turner, chief solutions officer at Honeywell’s Building Automation unit, says that arenas and hockey rinks are facing 11-17% increases in energy costs, and that makes it “pretty hard to sustain.” But Turner also notes that increasing sustainability measures and lowering costs across a spectrum of different facilities isn’t necessarily something that can be solved by “writing a giant check.” Instead, it requires on-the-ground coordinated efforts and expertise. “This is something that we know how to do, and we’ve been doing it for almost 40 years,” Turner says. “We’ve done this really effectively, and we decided to see how it applies to hockey, and it turns out to be a great partnership.” He notes that the actual process for how Honeywell will help each facility follows a basic protocol: They speak with the facility’s owner or manager, learn the pain points, look at operating costs and energy bills, and develop a sense of an operating model, which Honeywell’s team then uses to develop an energy-savings model. That could include figuring out when parts of the building need to be lit, cooled, or warmed, and making the facility, overall, more flexible, depending on the space’s demand. “You really need to learn how they operate their facility, and then you automate it.” Growing the game Perhaps the most interesting element of the partnership is what it could mean for youth hockey, which is seeing increased participation, despite relatively high entry costs for families compared to other sports. With that, increasing the number of arenas and rinks available to youth hockey teams, and making sure that they’re operating at a reasonable cost level, is important for the growth of the sport—something that is clearly on the NHL’s mind. “We have a unique challenge on the youth side that nobody else has. Every town has a football field, a baseball field, a basketball court—the cost to keep those things running is a fraction of what ours are,” says Lehanksi. “If we want more kids to play hockey, we’ve got to figure this out. It’s a major area of need: helping arenas save more money, so they can put more money back into the arena, creating a better environment.” Again, by helping reduce operating costs at youth sports facilities, the idea is that the cost savings could, in effect, trickle down and help make the game more comfortable, accessible, and potentially, more affordable, over time. It could also lead to the development of a “blueprint” for more efficient facilities, Lehansky says, and more arenas could also lower associated costs for youth hockey players. “The way Honeywell is going to help is by getting more ice surfaces out there,” Lehansky says, “and there aren’t too many companies that you can talk to in that space.” View the full article