Newsletter
Want to keep up to date with all our latest news and information?
ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
Fifteen years ago, tech investor Marc Andreessen published his famous essay, “Why Software Is Eating the World.” He predicted at the time that technology companies were tremendously undervalued, and that low startup costs and almost infinite scalability would lead software-based companies to dominate every industry. You can see what he means. Today, the “Mag 7” stocks dominate the S&P 500 with market capitalizations in the trillions. Even startups like Anthropic and OpenAI are valued at hundreds of billions of dollars. Meanwhile, massive investment in data centers is reshaping industries from construction to energy. But not so fast. While recent advances in machine learning have been exciting, it’s still unclear how much real value is being created. The truth is that we still live our lives largely in the realm of atoms and that isn’t changing. That’s why software is unlikely to ever eat the world, and why many of the most exciting technologies of the future will be rooted in physical space. The economy is not digital In his essay, Andreessen wrote, “Today, the world’s largest bookseller, Amazon, is a software company—its core capability is its amazing software engine for selling virtually everything online, no retail stores necessary.” Well, not really. While software remains a core part of Amazon’s business, today the company is firmly ensconced in the physical world, with not only retail stores but also hundreds of warehouses and a massive fleet of trucks. It’s not just Amazon. Most of our economic lives are rooted in atoms, not bits. A quick examination of your monthly bills will likely show that most of your spending goes to things like housing, transportation, energy, food and, depending on your age, health care. That dwarfs what most people spend on phones, computers, and internet services. In fact, a report by the International Data Center Authority found that the digital economy accounts for a mere 15% of global gross domestic product. That’s a lot of money in nominal terms, but it’s still dwarfed by the other 85%. That’s why Amazon went to the expense and trouble of investing in physical spaces. Even Netflix, another company Andreessen touted, is opening up real-life entertainment centers. As much as we may seem glued to our phones, the physical world is where we live. It’s where we eat, work, meet each other, and have fun. It’s what nature evolved us for, which is why Zoom calls are never quite as satisfying as real-life encounters. Software has a big appetite, but the real world is simply too big and complex to be eaten. Still, there is genuine opportunity in using software to shape the physical world in ways that unlock enormous value. Matter is not digital Materials are something we interact with constantly, often without thinking about them. We want our clothes to be soft and warm, our tools to have high tensile strength so they can do work without breaking. Some things require specific properties, such as the ability to conduct electricity or resist shattering on impact. This has long been the realm of a fairly obscure field called materials science, and, traditionally, it has been something akin to a cottage industry. Scientists would begin with a set of desired properties and then, through a painstaking process of trial and error, often involving the testing of thousands of candidates, eventually find something useful. But in the early 2000s, an MIT professor named Gerd Ceder began developing computational methods to predict new materials. That eventually led to the Materials Project at Lawrence Berkeley National Laboratory. Now, rather than testing thousands of candidates, scientists could eliminate most of them through digital simulations and then test the ones that remain. As more materials data became available, two Stanford graduate students started applying machine learning to materials databases and found that they could dramatically improve development economics. The company they founded, Citrine Informatics, became a pioneer in the space and has attracted large players such as Dassault, Schrödinger, and Microsoft. Still, materials are not digital, so there will always be some loss in information when digital systems are used to model physical reality. However, we are beginning to see the emergence of non-digital architectures, such as quantum computers, that can model the physical world with far greater fidelity. Biology is not digital In 2024, Demis Hassabis and John Jumper won the Nobel Prize for their development of AlphaFold, an AI model that can predict, with incredible accuracy, the structure of proteins. This was a breakthrough of historic proportions because, much like computational approaches in materials science, it allows scientists to identify potential drug candidates hundreds, if not thousands, of times faster than with conventional methods. The potential is mind-blowing. In 2023, Insilico, a Hong Kong-based biotech startup, advanced the first AI-generated drug candidate into human clinical trials. And there are currently dozens of potentially life-changing drugs in the pipeline that were discovered in a mere fraction of the time that it would take using conventional methods. That’s impressive. But like materials, biology is not digital. No matter how ingeniously conceived and constructed, we still need to see how a therapy works on humans in the real world. We need to be sure that proposed cures are safe, nontoxic, and an improvement on existing molecules and methods. That, and not drug discovery, is what makes up the bulk of development costs. A 2024 paper suggested that AI discovery could double the overall success rate from 5% to 10% to 9% to 18%, which is significant. Still, the claims of the tech optimists that “AI will cure cancer” are more than overblown. Anybody who has spent any time in a hospital will tell you that healthcare remains incredibly labor-intensive, requiring capable, caring professionals. And there is an extreme shortage of them in the U.S., which software will do little to solve. We need to focus more on atoms, less on bits Fifty years ago, in 1976, life expectancy in the U.S. was 72 years, versus 78 today. American families typically had one car and one television. Houses were smaller, nutrition was worse, we polluted like hell, and there was no internet. We spent much less time with our screens and more time with each other. Today, it’s easy to see how many things have gotten better, but it’s just as easy to see how others have gotten worse. While in the aggregate, incomes have improved, most of that has gone to top earners, leaving many households feeling worse off. While we have amazingly cool gadgets, costs for basic needs, like housing, healthcare, and education, have soared. The truth is that we’re very good at innovating in the digital space because it’s fast, cheap, and low risk. But the real opportunities are in the messy, physical world. So we’re ending up with lots of incremental digital innovation and not enough transformational change in the real world. In sum, it’s hard to see how we’ve become meaningfully better off over the last 50 years. For all of the Silicon Valley blather, most American families are materially struggling and our mental health is declining. This isn’t because of some exogenous shock, but because of choices we’ve made. We have the technology to improve our lives, but the benefits are not accessible to most. What we have to reckon with is that the world is not digital. We live, eat, travel, and breathe in physical spaces, and no amount of algorithms and data centers will change that. As philosopher Martin Heidegger pointed out long ago, technology is less a creation than it is an uncovering. It brings us possibilities, but it is our responsibility to enframe and direct them in ways that will benefit us. We live in a world of atoms, not bits. Technology matters only if it makes our lives better. View the full article
-
In 1985, Intel was in trouble. Japanese competitors were dominating the memory chip market that Intel had helped invent. Inside the company, leadership debated what to do. During one conversation, Andy Grove, then Intel’s president and COO, asked CEO Gordon Moore a deceptively simple question: “If we were replaced tomorrow, what would a new CEO do?” Moore didn’t hesitate. “He would get us out of the memory business.” The two men looked at each other and realized something uncomfortable. They already knew the answer; they just hadn’t acted on it. Intel exited the market that had defined its identity and doubled down on microprocessors, a decision that reshaped the company and ultimately the technology industry. The lesson wasn’t just about strategy. It was also about the strategic courage to say no. But that only matters if it creates room for something better. Innovation needs judgment Most organizations celebrate experimentation. But after years working with large innovation portfolios, one pattern has become clear to me. The limiting factor isn’t the supply of ideas: it’s the ability to choose between them and identify the right process to take the winning one forward. Every organization accumulates projects that once looked promising but never quite gain momentum. The technology works, but the market is uncertain; or the prototype impresses internally, but scaling would take years. These projects rarely fail outright. Instead, they linger as “zombie projects,” shuffling along year after year, absorbing talent, leadership attention, and budget without ever becoming a real business. Over time, they quietly drain the most valuable resources innovation needs, starting with leadership attention. And because every dollar and person-hour you commit to these ideas is unavailable elsewhere, you must prove that the idea is worth it. The hidden cost of not deciding Large organizations are especially vulnerable to this dynamic. Not because they lack capability, but because scale changes incentives. Ending a project can feel like admitting a mistake. Multiply that behavior across dozens of teams and the result is predictable. Innovation portfolios become crowded. Decision cycles slow down. Resources are spread across too many bets. Unsurprisingly, only a small fraction of corporate innovation pilots ever reach scale, with roughly 95% of new product launches ultimately falling short. The problem is not statistical. It has more to do with not having the structure in place that allows you to filter ideas properly. Why resource allocation matters more than you think in innovation Let me be clear. It’s better to spend thousands evaluating an idea than millions fixing or unwinding it later, so you have to be ruthless about what passes through your filter. Research shows that dedicated transition teams can cut demonstration failure rates by around 50%. We have some well-known corporate examples of resource reallocation. Consider Apple’s turnaround in the late 1990s. When Steve Jobs came back, the company had dozens of overlapping products and a confusing strategy. One of his first moves was to cut the product line down to just a handful of core offerings. That brought focus back, and within a year, the company was profitable again. Stories like this can make failure seem like just part of the process. But the downside is that time and resources go into ideas that probably should’ve been filtered out much earlier. Ultimately, the innovation funnel matters more than the idea pipeline. In strong innovation systems, early-stage ideas face rigorous scrutiny. If the signals aren’t there, the project stops: not because it failed, but because resources are needed elsewhere. As a result, the surviving projects move faster because they aren’t competing with dozens of parallel experiments. Not only that, but leadership attention sharpens and investment becomes more decisive. Disciplined rejection in practice In practice, saying no is less about dramatic leadership moments and more about building the right systems, including defining clear continuation criteria before projects even begin. Teams know what commercial indicators must appear for a project to move forward. Portfolio reviews play a critical role in this. Leaders need to ask, if we were starting today, would we still invest in this? Culturally, organizations must also normalize stopping work. Teams need to understand that ending a project is not career damage. Leaders should actually reward those who identify when an initiative should be shelved, and openly acknowledge shutting down their own initiatives to help create that environment. Finally, companies need to broaden their thinking about pathways to market, especially when the capabilities needed to scale them don’t exist internally. An external partner might be able to move with greater speed and operational clarity, unbound by organizational limitations. The courage to cut Many describe innovation as a creative act. In large organizations, though, it looks much closer to capital allocation. Leaders are constantly deciding where time, money and attention should go. That’s why the ability to say no matters so much. Zombie projects can quietly drain time, talent, and money for years, simply because no one has the courage to kill them. Disciplined rejection is what creates the space real breakthroughs need to cut through the noise. But that can only get you so far. What happens next defines the success of the technology. The strongest organizations make deliberate choices about the future of the ideas that survive, with an honest evaluation of what it takes to see them through commercialization—whether that’s developing them internally or placing them with partners that have the skill and resources needed to scale them. Saying no is the first step. True advantage comes from making sure the right ideas actually go somewhere. View the full article
-
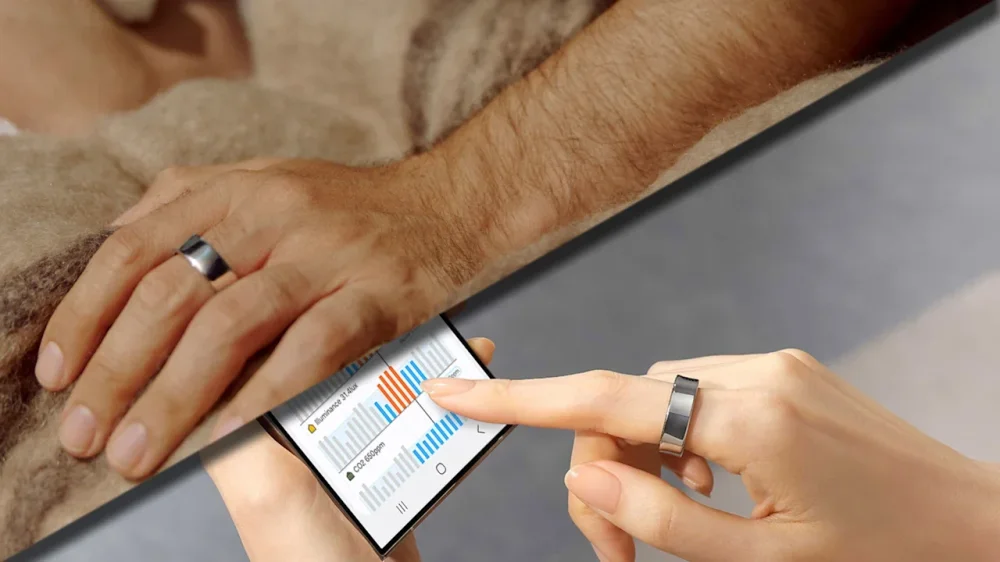
While smartwatches have spent the last decade fighting for our attention with buzzing notifications and glowing screens, a quieter revolution has been moving down to our fingers. Yes, the smart ring market has matured from a niche experimental category into a legitimate hardware battleground where the stakes involve more than just step counts. For anyone looking to track their health without (or while) strapping a small computer to their arm, the landscape is now crowded with options that balance high-end aesthetics with serious sensor arrays. Here are some to check out. Oura Ring 4 ($349 + $6/month) The Oura Ring 4 remains the undisputed heavyweight champion of the category, serving as the benchmark against which every other ring is measured. It starts at $349 and offers what’s arguably the most polished software experience in the business, focusing heavily on recovery and metabolic health through its revamped AI-driven insights. However, there’s a catch that’s become a point of contention for many users: a mandatory $5.99 monthly subscription to see anything beyond basic data. For Oura, the hardware is just the vessel for a recurring revenue model that emphasizes long-term wellness. Samsung Galaxy Ring ($399) Samsung has taken a different path with the Galaxy Ring, positioning it as the ultimate companion for those already living within the Android ecosystem. Priced slightly higher than the Oura at $399, it distinguishes itself by eschewing the subscription model, meaning the price you pay at the register is the end of it. Beyond its scratch-resistant titanium frame and lack of a subscription fee, the Galaxy Ring leans heavily into “Double Pinch” gesture controls that let you dismiss alarms or snap a phone photo with a simple tap of your fingers. The functional catch is Samsung’s walled garden. To get the full suite of features, including the advanced Energy Score—which synthesizes your sleep, activity, and heart rate variability into a single readiness metric—you really need to be paired with a Samsung handset, making it a brilliant piece of hardware that’s tethered to a specific brand of software. Ultrahuman Ring AIR ($349) For the crowd that looks at a heart rate graph and wishes they had more raw data, the Ultrahuman Ring AIR is the specialized tool of choice. Starting at $349 with no recurring fees, Ultrahuman leans into the “quantified self” movement by focusing on circadian rhythm alignment and metabolic tracking. It’s designed to play well with other biohacking tools, like continuous glucose monitors, providing a level of depth regarding how caffeine or late-night meals affect your recovery that other rings tend to gloss over. It’s less a general lifestyle accessory and more a dedicated instrument for those who want to treat their body like a high-performance machine. RingConn Gen 2 Air ($199) The market disruptor in this space is undoubtedly the RingConn Gen 2 Air, which makes a compelling case for being the most practical choice for the average person. With a starting price of $199 and no subscription requirements, it undercuts the major players while offering a battery life that stretches to a full 10 days. Its “squircle” shape isn’t just a design quirk, but an ergonomic choice that prevents the ring from spinning on your finger, ensuring the sensors stay aligned with your skin. While it lacks the brand recognition of Oura or Samsung, as a pure value proposition it manages to pack advanced sleep and heart rate monitoring into a frame that feels significantly lighter than its competitors. Amazfit Helio Ring ($149) Finally, the Amazfit Helio Ring carved out its own niche by targeting athletes who don’t want to choose between a ring and a watch. At $149, it’s the most affordable entry point into the premium ring space and is specifically designed to sync with Amazfit’s existing line of fitness watches. While it can function on its own, it excels when used as a recovery-focused companion piece, filling in the data gaps during the hours when an athlete might take off his or her bulky GPS watch to sleep. It proves that the future of wearables might not be about finding the one device that does everything, but rather about building a subtle network of sensors that disappear into our daily lives. View the full article
-
The government overreacts to popular opinion, which prompts a pendulum swing the other wayView the full article
-
Today’s biggest one-man brands benefit from the impression that no cycle can bring them downView the full article
-
Beijing has yet to step forward to fill the leadership vacuum left by WashingtonView the full article
-
Nobel laureate’s protégés are raising billions and spreading his influence across the AI industryView the full article
-
In the 2028 battle for the White House, the vice-president may face off against secretary of state Marco RubioView the full article
-
Wall Street indices have surged to a string of record highs despite anxiety over economic fallout from Iran warView the full article
-
FT calculates territory under control in Gaza, Lebanon and Syria is about 5% of Israel’s 1949 bordersView the full article
-
If you’re considering starting your own business, grasping the sole proprietorship model is crucial. This structure allows you to be the sole owner and operator, giving you complete control over decisions and profits. Nevertheless, it likewise means you face unlimited personal liability for any debts. To get started, you’ll need to check local licensing requirements and choose a business name. As you navigate this process, there are several key aspects to keep in mind. Key Takeaways A sole proprietorship is an unincorporated business owned by one individual, with no legal distinction between the owner and the business. As a sole proprietor, you have complete control over business decisions and receive all profits, but you also face unlimited personal liability for debts. To start, verify local licensing requirements and select a business name; consider registering a DBA for tax purposes. Obtain necessary licenses and permits, and apply for an Employer Identification Number (EIN) if you plan to hire employees. Report your business income and losses on your personal tax return using Form Schedule C, simplifying your tax obligations. Sole Proprietorship: Definition A sole proprietorship is a straightforward and often preferred business structure for many entrepreneurs. To define sole owner, it refers to an individual who owns and operates the business without any legal distinction between themselves and their enterprise. So, what’s a proprietorship? It’s a type of business that’s unincorporated and non-registered, meaning it doesn’t require formal legal steps to establish. When you start your own business as the only owner, you automatically create a sole proprietorship. As an owner, you’re entitled to all profits, but you’re likewise personally responsible for any debts and liabilities the business incurs. Moreover, it’s important to mention that income from a sole proprietorship is treated as personal income for tax purposes, reported on your individual tax return using Schedule C and Schedule SE. This simplicity makes it an attractive option for numerous new business ventures. Key Characteristics of a Sole Proprietorship When you choose to operate as a sole proprietor, you take full ownership and control of your business, making all key decisions. Nevertheless, this likewise means you bear personal liability for any debts or obligations the business incurs, which can put your personal assets at risk. On the plus side, the tax structure is straightforward, as your business income is reported on your personal tax return, simplifying your financial responsibilities. Ownership and Control In a sole proprietorship, you hold complete ownership and control over your business, as there’s no legal distinction between you and the enterprise itself. This structure allows you to make all decisions and manage daily operations without needing approval from partners or shareholders. You likewise receive all profits generated, which are treated as personal income for tax purposes, simplifying your tax reporting through Schedule C. Establishing a sole proprietorship involves minimal regulatory requirements, letting you start your business quickly and with few formalities. Nonetheless, keep in mind that the business typically ceases to exist upon your death or incapacitation, lacking continuity beyond your life, which can affect long-term planning. Personal Liability Risks Complete ownership and control in a sole proprietorship come with significant personal liability risks that every owner should understand. As a sole proprietor, you’re personally liable for all business debts and obligations, meaning your personal assets, like savings and property, can be at risk if the business faces legal disputes or financial failures. Unlike corporations or LLCs, a sole proprietorship lacks any legal separation between you and your business, leading to unlimited liability. If your business incurs debts, creditors can pursue your personal belongings to settle those debts. This personal liability extends to all actions taken by your business, making you fully responsible for any legal claims or lawsuits, which can deter potential investors who see your personal exposure as a higher risk. Simple Tax Structure Comprehending the simple tax structure of a sole proprietorship is crucial for anyone considering this business model, as it directly impacts your financial responsibilities. A sole proprietorship is taxed as a pass-through entity, meaning you report business income on your personal tax return, using Form Schedule C alongside Form 1040. You’ll need to pay self-employment taxes, covering both employee and employer portions, which can greatly increase your tax liability. Unlike corporations, you avoid corporate taxes, as all profits are taxed only once at your individual level. Furthermore, you can benefit from special deductions, like home office deductions. To maximize tax benefits and guarantee compliance, consulting a tax professional is highly advisable. Difference Between Owner and Sole Proprietor When you think about business ownership, it’s important to recognize that not all owners are the same. A sole proprietor is a specific type of owner who runs a business independently, meaning there’s no legal separation between you and your business. This distinction affects everything from personal liability for debts to tax obligations, so comprehending these differences is essential for anyone considering starting a business. Legal Structure Comparison Grasping the difference between an owner and a sole proprietor is essential for anyone considering starting a business. An owner can be an individual or a legal entity, like a corporation, whereas a sole proprietor particularly refers to an individual operating a sole proprietorship without formal registration. Unlike sole proprietorships, corporations can own multiple businesses and offer limited liability protection, shielding owners from personal debts. Sole proprietors enjoy complete control over business decisions and profits, but they likewise bear personal liability for all business debts. Furthermore, tax implications differ; sole proprietors report business income on personal tax returns, whereas corporate owners face varied tax obligations based on their entity type. Comprehending these distinctions is critical for informed decision-making. Ownership Types Explained Comprehension of the differences in ownership types is crucial for anyone planning to start a business. The term “owner” can apply to individuals or legal entities, whereas “sole proprietor” particularly refers to an individual running a sole proprietorship. A sole proprietorship is an unincorporated business operated by one person, meaning there’s no legal distinction between you and your business. This structure is simpler for those just starting since it limits ownership to a single individual. Nevertheless, as a sole proprietor, you’re personally liable for all debts and obligations of the business, which can endanger your personal assets. Grasping these distinctions helps clarify your legal and financial responsibilities, vital for making informed business decisions. Steps to Start a Sole Proprietorship Beginning a sole proprietorship entails a few uncomplicated steps that can assist you in establishing your business effectively. First, you automatically create a sole proprietorship simply by operating as the sole owner, but it’s vital to verify local licensing requirements. Next, select a business name for tax purposes; this could be your own name or a fictitious name for which you might wish to register a “Doing Business As” (DBA). Additionally, confirm you obtain any necessary licenses, permits, and zoning clearances specific to your industry by consulting local regulations or resources like CalGold. If you plan to hire employees or file certain taxes, apply for an Employer Identification Number (EIN) from the IRS. Finally, keep in mind that all income or losses from your sole proprietorship will be reported on your personal income tax return using Form 540, and you might need to attach Schedule C for business income. Business Licenses and Permits Before plunging into your sole proprietorship, it’s vital to comprehend the various business licenses and permits you might need. These requirements vary considerably based on your industry and location, so checking local regulations is imperative. For instance, if you’re starting a food service, you’ll likely need health permits, whereas professionals like cosmetologists or lawyers may require specific licenses to operate legally. Moreover, some businesses may need zoning clearance to guarantee compliance with local land-use regulations. If you plan to run your business under a name different from your legal name, you’ll additionally need to file a fictitious business name statement, often referred to as a DBA. To simplify the process, consider using resources like CalGold, which offer thorough guidance on the licensing and permitting requirements specific to California businesses. Grasping these elements will help you establish a solid foundation for your sole proprietorship. Operating Under an Assumed Name When you decide to operate under an assumed name, or DBA, you’re choosing a name that reflects your business rather than your personal identity. It’s crucial to register this name with your local or state authorities, which usually involves completing a simple form and paying a fee. Make sure to select a name that stands out and isn’t already in use, as this can help your branding and prevent legal complications. Choosing Your Business Name How can you choose a business name that resonates with your target audience during compliance with legal requirements? Start by contemplating a name that reflects your brand and is marketable. Remember, when you operate under an assumed name, it’s vital to register it with local or state authorities. Additionally, check for existing trademarks to avoid legal issues. Here are some key points to ponder: Confirm the name aligns with your business values. Verify the name isn’t already in use. Think about how the name improves branding. Reflect on public perception and memorability. Be aware of any publication requirements in your state. Choosing the right name can greatly impact your business’s recognition and marketing success. Registering a DBA Registering a DBA (Doing Business As) is a crucial step for any sole proprietor who wants to operate under a name that differs from their legal name, providing an opportunity to improve branding and marketing efforts. To register a DBA, you’ll typically need to complete an application and pay a registration fee at the county or state level. Remember, a DBA doesn’t create a separate legal entity, so you remain personally liable for all business debts. Before registering, check for name availability to prevent conflicts with existing businesses, as many jurisdictions require a name search. Additionally, keep in mind that once registered, a DBA must be renewed periodically, and changes in the business name or ownership may require a new registration. Obtaining an Employer Identification Number (EIN) Obtaining an Employer Identification Number (EIN) is a crucial step for many sole proprietors, especially if you plan to hire employees or need to comply with specific tax requirements. An EIN is a unique nine-digit number assigned by the IRS for tax identification, similar to a Social Security number. You should consider applying for an EIN if you: Have employees. Operate as a partnership. File certain tax returns, like excise taxes. Want to protect personal information when dealing with clients or vendors. Prefer a separate identification for your business activities. You can complete the application online through the IRS website, by mail, or by fax, and it usually takes just a few minutes online. Best of all, there’s no cost associated with obtaining an EIN, making it a valuable resource for your business compliance needs. Advantages of a Sole Proprietorship A sole proprietorship offers a straightforward and cost-effective way to start your own business. This structure is the simplest to establish, requiring minimal paperwork and no formal registration process. You have complete control over all business decisions, allowing you to adapt quickly to changing market conditions. Furthermore, profits are treated as personal income, which simplifies tax reporting through Schedule C, and can result in lower overall tax rates compared to other business structures. There are no ongoing state requirements or formalities, letting you focus more on your operations rather than compliance. In addition, a sole proprietorship provides greater flexibility in managing finances. You can directly reinvest profits back into the business without the intricacies that come with corporate structures. Disadvantages of a Sole Proprietorship Even though the advantages of a sole proprietorship can be appealing, it’s important to contemplate the drawbacks associated with this business structure. Here are some key disadvantages you should consider: Unlimited personal liability: Your personal assets are at risk if your business faces debts or legal issues. Capital challenges: Raising funds can be difficult, as you often rely on your own finances and creditworthiness. Lack of continuity: The business’s existence is tied to you, typically ending upon your death or incapacity. Full responsibility: You bear the weight of both successes and failures, which can lead to stress and financial strain. Attracting investors: Investors and banks often view sole proprietorships as riskier, making it hard to secure funding. Understanding these disadvantages will help you make a more informed decision about whether a sole proprietorship is right for you. Choosing Between a Sole Proprietorship and Other Business Structures When considering how to structure your business, have you thought about the differences between a sole proprietorship and other business forms? A sole proprietorship is the simplest structure, requiring no formal registration, whereas LLCs and corporations involve more paperwork and legal considerations. One key advantage of an LLC is personal liability protection, which safeguards your assets from business debts and legal actions—something sole proprietorships don’t offer. In addition, sole proprietorships are taxed as pass-through entities, meaning your business profits are reported on your personal tax return, avoiding double taxation faced by corporations. Nevertheless, raising capital can be tougher as a sole proprietor, since you rely mainly on your funds and credit. Moreover, a sole proprietorship lacks continuity; it ends with you, unlike LLCs and corporations that can continue independently and facilitate ownership shifts. Comprehending these distinctions can help you choose the best structure for your business needs. Important Considerations for Aspiring Sole Proprietors Comprehending the significant considerations for aspiring sole proprietors is crucial for setting a solid foundation for your business. Here are key points to keep in mind as you commence on this expedition: You’re personally liable for all business debts, putting your assets at risk. Check local requirements for licenses and permits before starting, as they vary by location and industry. All business income is reported on your personal tax return, increasing your taxable income. Raising capital can be challenging, mainly relying on your personal wealth and creditworthiness. Be comfortable with unlimited liability, since sole proprietorships offer no protection against personal asset loss. Being aware of these factors will help you navigate potential pitfalls and better prepare you for the responsibilities of running a sole proprietorship. Make informed decisions to improve your chances of success. Frequently Asked Questions How to Explain Sole Proprietor? A sole proprietor is someone who owns and runs their own business, with no legal distinction between themselves and the business. This structure is simple, requiring minimal setup and regulation. As a sole proprietor, you make all decisions and keep all profits, but you likewise face full personal liability for any debts or legal issues. You report your business income on your personal tax return, benefiting from a straightforward taxation process. Is It Better to Be LLC or Sole Proprietor? Choosing between an LLC and a sole proprietorship depends on your needs. A sole proprietorship offers simplicity and complete control, but it lacks personal liability protection. Conversely, an LLC provides that protection, safeguarding your personal assets from business debts. During both structures benefit from pass-through taxation, LLCs typically require more paperwork. If you plan to raise capital or want longevity for your business, an LLC might be the better option for you. What Is My Business Name if I Am a Sole Proprietor? As a sole proprietor, your business name can either be your legal name or a fictitious name, known as DBA (Doing Business As). If you choose a fictitious name, you’ll need to register it with your local authorities to guarantee it’s legally compliant. It’s important to select a name that reflects your services, is unique, and doesn’t infringe on existing trademarks. This name should likewise align with your tax filings for clarity in reporting. How Do I Establish Myself as a Sole Proprietor? To establish yourself as a sole proprietor, start your business as the sole owner, which doesn’t require formal registration. Check local regulations for necessary licenses and permits specific to your industry. If you plan to operate under a name different from your own, file a DBA. You’ll need an Employer Identification Number (EIN) only if hiring employees. Finally, report your business income and losses on your personal tax return using Form Schedule C. Conclusion In conclusion, a sole proprietorship offers a straightforward way to start your own business with minimal regulatory hurdles. You maintain complete control and enjoy all profits, but you likewise bear unlimited personal liability. To successfully launch your enterprise, make certain you understand local licensing requirements, choose an appropriate business name, and obtain necessary permits. Weigh the advantages and disadvantages carefully to determine if this structure aligns with your goals. With proper planning, you can effectively navigate the path to entrepreneurship. Image via Google Gemini and ArtSmart This article, "How to Explain Sole Proprietor and Start Your Own Business" was first published on Small Business Trends View the full article
-
If you’re considering starting your own business, grasping the sole proprietorship model is crucial. This structure allows you to be the sole owner and operator, giving you complete control over decisions and profits. Nevertheless, it likewise means you face unlimited personal liability for any debts. To get started, you’ll need to check local licensing requirements and choose a business name. As you navigate this process, there are several key aspects to keep in mind. Key Takeaways A sole proprietorship is an unincorporated business owned by one individual, with no legal distinction between the owner and the business. As a sole proprietor, you have complete control over business decisions and receive all profits, but you also face unlimited personal liability for debts. To start, verify local licensing requirements and select a business name; consider registering a DBA for tax purposes. Obtain necessary licenses and permits, and apply for an Employer Identification Number (EIN) if you plan to hire employees. Report your business income and losses on your personal tax return using Form Schedule C, simplifying your tax obligations. Sole Proprietorship: Definition A sole proprietorship is a straightforward and often preferred business structure for many entrepreneurs. To define sole owner, it refers to an individual who owns and operates the business without any legal distinction between themselves and their enterprise. So, what’s a proprietorship? It’s a type of business that’s unincorporated and non-registered, meaning it doesn’t require formal legal steps to establish. When you start your own business as the only owner, you automatically create a sole proprietorship. As an owner, you’re entitled to all profits, but you’re likewise personally responsible for any debts and liabilities the business incurs. Moreover, it’s important to mention that income from a sole proprietorship is treated as personal income for tax purposes, reported on your individual tax return using Schedule C and Schedule SE. This simplicity makes it an attractive option for numerous new business ventures. Key Characteristics of a Sole Proprietorship When you choose to operate as a sole proprietor, you take full ownership and control of your business, making all key decisions. Nevertheless, this likewise means you bear personal liability for any debts or obligations the business incurs, which can put your personal assets at risk. On the plus side, the tax structure is straightforward, as your business income is reported on your personal tax return, simplifying your financial responsibilities. Ownership and Control In a sole proprietorship, you hold complete ownership and control over your business, as there’s no legal distinction between you and the enterprise itself. This structure allows you to make all decisions and manage daily operations without needing approval from partners or shareholders. You likewise receive all profits generated, which are treated as personal income for tax purposes, simplifying your tax reporting through Schedule C. Establishing a sole proprietorship involves minimal regulatory requirements, letting you start your business quickly and with few formalities. Nonetheless, keep in mind that the business typically ceases to exist upon your death or incapacitation, lacking continuity beyond your life, which can affect long-term planning. Personal Liability Risks Complete ownership and control in a sole proprietorship come with significant personal liability risks that every owner should understand. As a sole proprietor, you’re personally liable for all business debts and obligations, meaning your personal assets, like savings and property, can be at risk if the business faces legal disputes or financial failures. Unlike corporations or LLCs, a sole proprietorship lacks any legal separation between you and your business, leading to unlimited liability. If your business incurs debts, creditors can pursue your personal belongings to settle those debts. This personal liability extends to all actions taken by your business, making you fully responsible for any legal claims or lawsuits, which can deter potential investors who see your personal exposure as a higher risk. Simple Tax Structure Comprehending the simple tax structure of a sole proprietorship is crucial for anyone considering this business model, as it directly impacts your financial responsibilities. A sole proprietorship is taxed as a pass-through entity, meaning you report business income on your personal tax return, using Form Schedule C alongside Form 1040. You’ll need to pay self-employment taxes, covering both employee and employer portions, which can greatly increase your tax liability. Unlike corporations, you avoid corporate taxes, as all profits are taxed only once at your individual level. Furthermore, you can benefit from special deductions, like home office deductions. To maximize tax benefits and guarantee compliance, consulting a tax professional is highly advisable. Difference Between Owner and Sole Proprietor When you think about business ownership, it’s important to recognize that not all owners are the same. A sole proprietor is a specific type of owner who runs a business independently, meaning there’s no legal separation between you and your business. This distinction affects everything from personal liability for debts to tax obligations, so comprehending these differences is essential for anyone considering starting a business. Legal Structure Comparison Grasping the difference between an owner and a sole proprietor is essential for anyone considering starting a business. An owner can be an individual or a legal entity, like a corporation, whereas a sole proprietor particularly refers to an individual operating a sole proprietorship without formal registration. Unlike sole proprietorships, corporations can own multiple businesses and offer limited liability protection, shielding owners from personal debts. Sole proprietors enjoy complete control over business decisions and profits, but they likewise bear personal liability for all business debts. Furthermore, tax implications differ; sole proprietors report business income on personal tax returns, whereas corporate owners face varied tax obligations based on their entity type. Comprehending these distinctions is critical for informed decision-making. Ownership Types Explained Comprehension of the differences in ownership types is crucial for anyone planning to start a business. The term “owner” can apply to individuals or legal entities, whereas “sole proprietor” particularly refers to an individual running a sole proprietorship. A sole proprietorship is an unincorporated business operated by one person, meaning there’s no legal distinction between you and your business. This structure is simpler for those just starting since it limits ownership to a single individual. Nevertheless, as a sole proprietor, you’re personally liable for all debts and obligations of the business, which can endanger your personal assets. Grasping these distinctions helps clarify your legal and financial responsibilities, vital for making informed business decisions. Steps to Start a Sole Proprietorship Beginning a sole proprietorship entails a few uncomplicated steps that can assist you in establishing your business effectively. First, you automatically create a sole proprietorship simply by operating as the sole owner, but it’s vital to verify local licensing requirements. Next, select a business name for tax purposes; this could be your own name or a fictitious name for which you might wish to register a “Doing Business As” (DBA). Additionally, confirm you obtain any necessary licenses, permits, and zoning clearances specific to your industry by consulting local regulations or resources like CalGold. If you plan to hire employees or file certain taxes, apply for an Employer Identification Number (EIN) from the IRS. Finally, keep in mind that all income or losses from your sole proprietorship will be reported on your personal income tax return using Form 540, and you might need to attach Schedule C for business income. Business Licenses and Permits Before plunging into your sole proprietorship, it’s vital to comprehend the various business licenses and permits you might need. These requirements vary considerably based on your industry and location, so checking local regulations is imperative. For instance, if you’re starting a food service, you’ll likely need health permits, whereas professionals like cosmetologists or lawyers may require specific licenses to operate legally. Moreover, some businesses may need zoning clearance to guarantee compliance with local land-use regulations. If you plan to run your business under a name different from your legal name, you’ll additionally need to file a fictitious business name statement, often referred to as a DBA. To simplify the process, consider using resources like CalGold, which offer thorough guidance on the licensing and permitting requirements specific to California businesses. Grasping these elements will help you establish a solid foundation for your sole proprietorship. Operating Under an Assumed Name When you decide to operate under an assumed name, or DBA, you’re choosing a name that reflects your business rather than your personal identity. It’s crucial to register this name with your local or state authorities, which usually involves completing a simple form and paying a fee. Make sure to select a name that stands out and isn’t already in use, as this can help your branding and prevent legal complications. Choosing Your Business Name How can you choose a business name that resonates with your target audience during compliance with legal requirements? Start by contemplating a name that reflects your brand and is marketable. Remember, when you operate under an assumed name, it’s vital to register it with local or state authorities. Additionally, check for existing trademarks to avoid legal issues. Here are some key points to ponder: Confirm the name aligns with your business values. Verify the name isn’t already in use. Think about how the name improves branding. Reflect on public perception and memorability. Be aware of any publication requirements in your state. Choosing the right name can greatly impact your business’s recognition and marketing success. Registering a DBA Registering a DBA (Doing Business As) is a crucial step for any sole proprietor who wants to operate under a name that differs from their legal name, providing an opportunity to improve branding and marketing efforts. To register a DBA, you’ll typically need to complete an application and pay a registration fee at the county or state level. Remember, a DBA doesn’t create a separate legal entity, so you remain personally liable for all business debts. Before registering, check for name availability to prevent conflicts with existing businesses, as many jurisdictions require a name search. Additionally, keep in mind that once registered, a DBA must be renewed periodically, and changes in the business name or ownership may require a new registration. Obtaining an Employer Identification Number (EIN) Obtaining an Employer Identification Number (EIN) is a crucial step for many sole proprietors, especially if you plan to hire employees or need to comply with specific tax requirements. An EIN is a unique nine-digit number assigned by the IRS for tax identification, similar to a Social Security number. You should consider applying for an EIN if you: Have employees. Operate as a partnership. File certain tax returns, like excise taxes. Want to protect personal information when dealing with clients or vendors. Prefer a separate identification for your business activities. You can complete the application online through the IRS website, by mail, or by fax, and it usually takes just a few minutes online. Best of all, there’s no cost associated with obtaining an EIN, making it a valuable resource for your business compliance needs. Advantages of a Sole Proprietorship A sole proprietorship offers a straightforward and cost-effective way to start your own business. This structure is the simplest to establish, requiring minimal paperwork and no formal registration process. You have complete control over all business decisions, allowing you to adapt quickly to changing market conditions. Furthermore, profits are treated as personal income, which simplifies tax reporting through Schedule C, and can result in lower overall tax rates compared to other business structures. There are no ongoing state requirements or formalities, letting you focus more on your operations rather than compliance. In addition, a sole proprietorship provides greater flexibility in managing finances. You can directly reinvest profits back into the business without the intricacies that come with corporate structures. Disadvantages of a Sole Proprietorship Even though the advantages of a sole proprietorship can be appealing, it’s important to contemplate the drawbacks associated with this business structure. Here are some key disadvantages you should consider: Unlimited personal liability: Your personal assets are at risk if your business faces debts or legal issues. Capital challenges: Raising funds can be difficult, as you often rely on your own finances and creditworthiness. Lack of continuity: The business’s existence is tied to you, typically ending upon your death or incapacity. Full responsibility: You bear the weight of both successes and failures, which can lead to stress and financial strain. Attracting investors: Investors and banks often view sole proprietorships as riskier, making it hard to secure funding. Understanding these disadvantages will help you make a more informed decision about whether a sole proprietorship is right for you. Choosing Between a Sole Proprietorship and Other Business Structures When considering how to structure your business, have you thought about the differences between a sole proprietorship and other business forms? A sole proprietorship is the simplest structure, requiring no formal registration, whereas LLCs and corporations involve more paperwork and legal considerations. One key advantage of an LLC is personal liability protection, which safeguards your assets from business debts and legal actions—something sole proprietorships don’t offer. In addition, sole proprietorships are taxed as pass-through entities, meaning your business profits are reported on your personal tax return, avoiding double taxation faced by corporations. Nevertheless, raising capital can be tougher as a sole proprietor, since you rely mainly on your funds and credit. Moreover, a sole proprietorship lacks continuity; it ends with you, unlike LLCs and corporations that can continue independently and facilitate ownership shifts. Comprehending these distinctions can help you choose the best structure for your business needs. Important Considerations for Aspiring Sole Proprietors Comprehending the significant considerations for aspiring sole proprietors is crucial for setting a solid foundation for your business. Here are key points to keep in mind as you commence on this expedition: You’re personally liable for all business debts, putting your assets at risk. Check local requirements for licenses and permits before starting, as they vary by location and industry. All business income is reported on your personal tax return, increasing your taxable income. Raising capital can be challenging, mainly relying on your personal wealth and creditworthiness. Be comfortable with unlimited liability, since sole proprietorships offer no protection against personal asset loss. Being aware of these factors will help you navigate potential pitfalls and better prepare you for the responsibilities of running a sole proprietorship. Make informed decisions to improve your chances of success. Frequently Asked Questions How to Explain Sole Proprietor? A sole proprietor is someone who owns and runs their own business, with no legal distinction between themselves and the business. This structure is simple, requiring minimal setup and regulation. As a sole proprietor, you make all decisions and keep all profits, but you likewise face full personal liability for any debts or legal issues. You report your business income on your personal tax return, benefiting from a straightforward taxation process. Is It Better to Be LLC or Sole Proprietor? Choosing between an LLC and a sole proprietorship depends on your needs. A sole proprietorship offers simplicity and complete control, but it lacks personal liability protection. Conversely, an LLC provides that protection, safeguarding your personal assets from business debts. During both structures benefit from pass-through taxation, LLCs typically require more paperwork. If you plan to raise capital or want longevity for your business, an LLC might be the better option for you. What Is My Business Name if I Am a Sole Proprietor? As a sole proprietor, your business name can either be your legal name or a fictitious name, known as DBA (Doing Business As). If you choose a fictitious name, you’ll need to register it with your local authorities to guarantee it’s legally compliant. It’s important to select a name that reflects your services, is unique, and doesn’t infringe on existing trademarks. This name should likewise align with your tax filings for clarity in reporting. How Do I Establish Myself as a Sole Proprietor? To establish yourself as a sole proprietor, start your business as the sole owner, which doesn’t require formal registration. Check local regulations for necessary licenses and permits specific to your industry. If you plan to operate under a name different from your own, file a DBA. You’ll need an Employer Identification Number (EIN) only if hiring employees. Finally, report your business income and losses on your personal tax return using Form Schedule C. Conclusion In conclusion, a sole proprietorship offers a straightforward way to start your own business with minimal regulatory hurdles. You maintain complete control and enjoy all profits, but you likewise bear unlimited personal liability. To successfully launch your enterprise, make certain you understand local licensing requirements, choose an appropriate business name, and obtain necessary permits. Weigh the advantages and disadvantages carefully to determine if this structure aligns with your goals. With proper planning, you can effectively navigate the path to entrepreneurship. Image via Google Gemini and ArtSmart This article, "How to Explain Sole Proprietor and Start Your Own Business" was first published on Small Business Trends View the full article
-
Investment of $5bn by private capital group set to help bring 500MW of data centre capacity online next yearView the full article
-
Talks on Power of Siberia 2 pipeline come just days after Donald The President’s visit to BeijingView the full article
-
US president also suggested they should co-operate with Russian leader against the International Criminal CourtView the full article
-
Bill Winters’ new strategy aims to ‘drive sustainable growth’ at Asia-focused lender View the full article
-
D1 Capital is among the Wall Street firms in line for big rewards if the rocket maker successfully lists next monthView the full article
-
If you’re a Mac user looking for an accounting solution, you’ve got several strong options to evaluate. Each package offers unique features customized to various business needs, from freelancers to small businesses. Xero and QuickBooks Online are popular for their detailed tools, whereas FreshBooks caters particularly to freelancers. Zoho Books stands out in automation, and Wave Accounting provides a free option for startups. Grasping these choices can greatly influence your financial management strategy. Let’s explore these packages further. Key Takeaways Xero offers a robust accounting solution with unlimited users, starting at $25/month, and features a mobile app for Mac users. QuickBooks Online is an industry standard, priced from $38/month, with strong integration capabilities and mobile access for Mac users. FreshBooks is user-friendly for freelancers, starting at $21/month, providing customizable invoices and a mobile app compatible with Mac devices. Zoho Books starts at $20/month, automates financial processes, and includes a 14-day free trial, making it suitable for Mac users. Wave Accounting offers a free plan for unlimited income and expense tracking, accessible via Mac, ideal for startups and small businesses. Why Trust NerdWallet When considering accounting software for your Mac, it’s vital to rely on sources that offer credible assessments, and that’s where NerdWallet shines. With over 250 reviews of small-business products, NerdWallet guarantees you have a thorough selection of the best home accounting software for Mac. Their editorial team brings more than 80 years of combined experience in small business and personal finance, lending substantial credibility to their evaluations. The site covers over 75 categories, providing customized recommendations to fit your unique needs, whether you’re looking for personal accounting software for Mac or accounting packages for Mac. Their objective ratings rubric emphasizes user-friendliness, pricing, and fundamental features, helping you make informed decisions. Plus, strict editorial integrity guidelines assure the accuracy and fairness of the information they present, instilling confidence in the recommendations you receive. Trusting NerdWallet means you’re making well-informed choices for your financial management. Xero Xero stands out as one of the top choices for Mac users seeking robust accounting software, boasting a perfect 5/5 rating. Priced from $25/month, it offers a promotional deal of 90% off for the first six months, making it an attractive option for home accounting software for Mac. Here are some key features of Xero: Unlimited users included in every pricing plan Basic inventory management capabilities Automated bill and receipt capture functionality Intuitive iOS app for managing finances on-the-go While Xero shines in customization with advanced analytics dashboards, it’s important to note that it doesn’t provide live phone support. Furthermore, the entry-level plan limits the number of bills and invoices you can process. QuickBooks Online QuickBooks Online is another standout accounting solution for Mac users, earning a perfect 5/5 rating for its extensive financial management capabilities. With a starting price of $38 per month, it’s affordable, especially with a promotion offering 50% off for the first three months or a free 30-day trial. This software is widely recognized as the industry standard, making it suitable for small businesses with complex financial needs. You’ll appreciate its robust features, which include payroll management, financial reporting, and expense tracking. Plus, it integrates seamlessly with over 750 business applications, enhancing your workflow. If you need support, QuickBooks Online provides reliable live chat and phone assistance from Monday to Saturday. This combination of thorough tools and strong customer service solidifies its position as a top choice for Mac users looking for an effective accounting package customized to their needs. FreshBooks FreshBooks stands out with its user-friendly interface, making it a top choice for freelancers and service providers who want to simplify their accounting tasks. The software’s mobile app features allow you to manage your finances on the go, enhancing flexibility and productivity. With tiered pricing plans starting at $21/month, FreshBooks scales with your business needs as it provides crucial tools like invoicing and time tracking. User-Friendly Interface When you’re looking for accounting software that doesn’t require an accounting degree to use, FreshBooks stands out due to its user-friendly interface customized particularly for freelancers and small business owners. This intuitive platform makes managing your finances straightforward, allowing you to focus on your work rather than getting bogged down in complex accounting tasks. Key features include: A built-in time tracker to efficiently bill clients for hours worked Customizable invoices that reflect your brand, enhancing professionalism Integration with over 100 apps, improving workflow efficiency A 30-day free trial, letting you explore its features without financial commitment With FreshBooks, steering your accounting needs becomes an effortless experience. Mobile App Features For those managing finances during travel, the FreshBooks mobile app is an important tool that streamlines various accounting tasks right from your smartphone. This dedicated app allows you to manage invoices, expenses, and time tracking seamlessly, providing vital flexibility for freelancers and small business owners. Its intuitive interface makes navigation a breeze, so you won’t need extensive training to get started. You can create and send professional invoices directly from the app, with integrated payment processing options to expedite payments. Furthermore, the built-in time tracker lets you log billable hours effortlessly, whether you’re working remotely or on-site with clients. Compatible with both iOS and Android devices, the FreshBooks app improves accessibility across different platforms. Pricing and Plans Comprehending the pricing structure of FreshBooks is crucial for freelancers and small businesses looking to manage their finances efficiently. FreshBooks offers various plans to suit different needs: The basic plan starts at $21 per month. The next tiers are priced at $38 and $65 monthly. New subscribers can enjoy a promotional rate of 60% off for the first three months. A 30-day free trial is available, allowing you to explore its features without commitment. Each plan is designed for a single user, so if your team grows, be aware that additional users will incur extra costs. This structure makes it important to assess your requirements before subscribing to the right plan. Zoho Books Zoho Books stands out as a robust accounting solution customized for Mac users, offering an impressive array of features designed to streamline financial management. With a top rating of 5/5 and a starting price of $20/month, it provides a 14-day free trial for you to explore its capabilities. The software automates financial processes, including recurring billing, expense tracking, and customizable reporting, making it ideal for businesses with regular invoicing needs. Additionally, Zoho Books integrates seamlessly with other Zoho products and supports a variety of third-party applications, enhancing its functionality. You can likewise manage your finances on the go, thanks to its multilingual support and mobile app access for both iOS and Apple Watch devices. Nevertheless, be aware that there are limitations on third-party integrations and a cap of 15 users for its top-tier plan, which may affect larger businesses. Wave Accounting Wave Accounting emerges as an outstanding choice for freelancers and small businesses seeking a cost-effective accounting solution. With its free plan, you can manage unlimited income and expense tracking, making it perfect for those on a budget. The software excels in providing robust financial reporting tools, which allow you to effortlessly generate crucial documents. Here’s what you can expect with Wave Accounting: Create and send invoices, as you track their status. Automate reminders for overdue payments to clients. Benefit from unlimited collaborators on the free plan for seamless teamwork. Enjoy data security through encryption and various payment processor integrations. Key Features in Mac Accounting Software Regarding managing finances on a Mac, grasping the key features of accounting software can greatly improve your experience and efficiency. Most Mac accounting software includes crucial tools like invoicing, expense tracking, and financial reporting, which help streamline your financial management. Many top packages, such as Xero and QuickBooks Online, offer mobile app availability, enabling you to manage your finances on-the-go from your iOS devices. User-friendly interfaces are another important aspect, making it easier for you, even though you’re not an accountant, to navigate and utilize core functionalities effectively. Moreover, cloud accessibility allows you to securely access your financial data from anywhere, ensuring automatic backups and updates. Finally, integration capabilities with other business tools, like payment processors and CRM systems, improve efficiency and streamline your workflows, making your overall financial management process smoother and more productive. Frequently Asked Questions What Is the Best Personal Accounting Software for Mac? When you’re looking for personal accounting software for your Mac, consider options like QuickBooks Online, which offers robust features and a free trial. Xero is great for team collaboration, allowing unlimited users. FreshBooks shines with its user-friendly invoicing, perfect for freelancers. Zoho Books presents an affordable solution for tracking expenses and recurring billing. If you’re on a budget, Wave Accounting provides free income and expense tracking, making it an excellent choice for personal use. Does Mac Have an Accounting Program? Yes, Macs do have several accounting programs available. You can choose from options like QuickBooks Online, Xero, FreshBooks, Zoho Books, and Wave Accounting, all designed to work seamlessly on macOS. Each program offers unique features, such as QuickBooks’ robust capabilities and Xero’s unlimited user access. FreshBooks is user-friendly for freelancers, whereas Wave Accounting provides a free solution for tracking income and expenses, making it suitable for small businesses. Can You Do Bookkeeping on a Mac? Yes, you can definitely do bookkeeping on a Mac. Various accounting software options are customized for macOS, like QuickBooks Online, Xero, and FreshBooks. These platforms offer crucial features such as invoicing and expense tracking, and most provide cloud access, allowing you to manage finances from anywhere. Moreover, many applications offer mobile apps for iOS, enhancing your ability to track finances on the go. Some even provide free plans, making them accessible for freelancers and small businesses. Are Macs Good for Accounting? Yes, Macs are good for accounting because of their compatibility with various accounting software options. These applications often feature user-friendly interfaces, making it easier for you to manage your finances efficiently. Cloud-based solutions provide accessibility from anywhere, which is ideal for freelancers and small businesses. Furthermore, Macs offer strong security measures, including encryption and data backup, ensuring your financial information remains safe. Conclusion In conclusion, finding the right accounting software for Mac can greatly streamline your financial management. Xero and QuickBooks Online excel in features and usability, whereas FreshBooks and Zoho Books cater to freelancers and those needing automation. If budget is a concern, Wave Accounting offers a free option. Each of these packages provides unique benefits, so evaluate your specific needs to choose the one that best fits your business. With the right tool, you can improve productivity and maintain accurate financial records. Image via Google Gemini and ArtSmart This article, "7 Best Accounting Packages for Mac Users" was first published on Small Business Trends View the full article
-
If you’re a Mac user looking for an accounting solution, you’ve got several strong options to evaluate. Each package offers unique features customized to various business needs, from freelancers to small businesses. Xero and QuickBooks Online are popular for their detailed tools, whereas FreshBooks caters particularly to freelancers. Zoho Books stands out in automation, and Wave Accounting provides a free option for startups. Grasping these choices can greatly influence your financial management strategy. Let’s explore these packages further. Key Takeaways Xero offers a robust accounting solution with unlimited users, starting at $25/month, and features a mobile app for Mac users. QuickBooks Online is an industry standard, priced from $38/month, with strong integration capabilities and mobile access for Mac users. FreshBooks is user-friendly for freelancers, starting at $21/month, providing customizable invoices and a mobile app compatible with Mac devices. Zoho Books starts at $20/month, automates financial processes, and includes a 14-day free trial, making it suitable for Mac users. Wave Accounting offers a free plan for unlimited income and expense tracking, accessible via Mac, ideal for startups and small businesses. Why Trust NerdWallet When considering accounting software for your Mac, it’s vital to rely on sources that offer credible assessments, and that’s where NerdWallet shines. With over 250 reviews of small-business products, NerdWallet guarantees you have a thorough selection of the best home accounting software for Mac. Their editorial team brings more than 80 years of combined experience in small business and personal finance, lending substantial credibility to their evaluations. The site covers over 75 categories, providing customized recommendations to fit your unique needs, whether you’re looking for personal accounting software for Mac or accounting packages for Mac. Their objective ratings rubric emphasizes user-friendliness, pricing, and fundamental features, helping you make informed decisions. Plus, strict editorial integrity guidelines assure the accuracy and fairness of the information they present, instilling confidence in the recommendations you receive. Trusting NerdWallet means you’re making well-informed choices for your financial management. Xero Xero stands out as one of the top choices for Mac users seeking robust accounting software, boasting a perfect 5/5 rating. Priced from $25/month, it offers a promotional deal of 90% off for the first six months, making it an attractive option for home accounting software for Mac. Here are some key features of Xero: Unlimited users included in every pricing plan Basic inventory management capabilities Automated bill and receipt capture functionality Intuitive iOS app for managing finances on-the-go While Xero shines in customization with advanced analytics dashboards, it’s important to note that it doesn’t provide live phone support. Furthermore, the entry-level plan limits the number of bills and invoices you can process. QuickBooks Online QuickBooks Online is another standout accounting solution for Mac users, earning a perfect 5/5 rating for its extensive financial management capabilities. With a starting price of $38 per month, it’s affordable, especially with a promotion offering 50% off for the first three months or a free 30-day trial. This software is widely recognized as the industry standard, making it suitable for small businesses with complex financial needs. You’ll appreciate its robust features, which include payroll management, financial reporting, and expense tracking. Plus, it integrates seamlessly with over 750 business applications, enhancing your workflow. If you need support, QuickBooks Online provides reliable live chat and phone assistance from Monday to Saturday. This combination of thorough tools and strong customer service solidifies its position as a top choice for Mac users looking for an effective accounting package customized to their needs. FreshBooks FreshBooks stands out with its user-friendly interface, making it a top choice for freelancers and service providers who want to simplify their accounting tasks. The software’s mobile app features allow you to manage your finances on the go, enhancing flexibility and productivity. With tiered pricing plans starting at $21/month, FreshBooks scales with your business needs as it provides crucial tools like invoicing and time tracking. User-Friendly Interface When you’re looking for accounting software that doesn’t require an accounting degree to use, FreshBooks stands out due to its user-friendly interface customized particularly for freelancers and small business owners. This intuitive platform makes managing your finances straightforward, allowing you to focus on your work rather than getting bogged down in complex accounting tasks. Key features include: A built-in time tracker to efficiently bill clients for hours worked Customizable invoices that reflect your brand, enhancing professionalism Integration with over 100 apps, improving workflow efficiency A 30-day free trial, letting you explore its features without financial commitment With FreshBooks, steering your accounting needs becomes an effortless experience. Mobile App Features For those managing finances during travel, the FreshBooks mobile app is an important tool that streamlines various accounting tasks right from your smartphone. This dedicated app allows you to manage invoices, expenses, and time tracking seamlessly, providing vital flexibility for freelancers and small business owners. Its intuitive interface makes navigation a breeze, so you won’t need extensive training to get started. You can create and send professional invoices directly from the app, with integrated payment processing options to expedite payments. Furthermore, the built-in time tracker lets you log billable hours effortlessly, whether you’re working remotely or on-site with clients. Compatible with both iOS and Android devices, the FreshBooks app improves accessibility across different platforms. Pricing and Plans Comprehending the pricing structure of FreshBooks is crucial for freelancers and small businesses looking to manage their finances efficiently. FreshBooks offers various plans to suit different needs: The basic plan starts at $21 per month. The next tiers are priced at $38 and $65 monthly. New subscribers can enjoy a promotional rate of 60% off for the first three months. A 30-day free trial is available, allowing you to explore its features without commitment. Each plan is designed for a single user, so if your team grows, be aware that additional users will incur extra costs. This structure makes it important to assess your requirements before subscribing to the right plan. Zoho Books Zoho Books stands out as a robust accounting solution customized for Mac users, offering an impressive array of features designed to streamline financial management. With a top rating of 5/5 and a starting price of $20/month, it provides a 14-day free trial for you to explore its capabilities. The software automates financial processes, including recurring billing, expense tracking, and customizable reporting, making it ideal for businesses with regular invoicing needs. Additionally, Zoho Books integrates seamlessly with other Zoho products and supports a variety of third-party applications, enhancing its functionality. You can likewise manage your finances on the go, thanks to its multilingual support and mobile app access for both iOS and Apple Watch devices. Nevertheless, be aware that there are limitations on third-party integrations and a cap of 15 users for its top-tier plan, which may affect larger businesses. Wave Accounting Wave Accounting emerges as an outstanding choice for freelancers and small businesses seeking a cost-effective accounting solution. With its free plan, you can manage unlimited income and expense tracking, making it perfect for those on a budget. The software excels in providing robust financial reporting tools, which allow you to effortlessly generate crucial documents. Here’s what you can expect with Wave Accounting: Create and send invoices, as you track their status. Automate reminders for overdue payments to clients. Benefit from unlimited collaborators on the free plan for seamless teamwork. Enjoy data security through encryption and various payment processor integrations. Key Features in Mac Accounting Software Regarding managing finances on a Mac, grasping the key features of accounting software can greatly improve your experience and efficiency. Most Mac accounting software includes crucial tools like invoicing, expense tracking, and financial reporting, which help streamline your financial management. Many top packages, such as Xero and QuickBooks Online, offer mobile app availability, enabling you to manage your finances on-the-go from your iOS devices. User-friendly interfaces are another important aspect, making it easier for you, even though you’re not an accountant, to navigate and utilize core functionalities effectively. Moreover, cloud accessibility allows you to securely access your financial data from anywhere, ensuring automatic backups and updates. Finally, integration capabilities with other business tools, like payment processors and CRM systems, improve efficiency and streamline your workflows, making your overall financial management process smoother and more productive. Frequently Asked Questions What Is the Best Personal Accounting Software for Mac? When you’re looking for personal accounting software for your Mac, consider options like QuickBooks Online, which offers robust features and a free trial. Xero is great for team collaboration, allowing unlimited users. FreshBooks shines with its user-friendly invoicing, perfect for freelancers. Zoho Books presents an affordable solution for tracking expenses and recurring billing. If you’re on a budget, Wave Accounting provides free income and expense tracking, making it an excellent choice for personal use. Does Mac Have an Accounting Program? Yes, Macs do have several accounting programs available. You can choose from options like QuickBooks Online, Xero, FreshBooks, Zoho Books, and Wave Accounting, all designed to work seamlessly on macOS. Each program offers unique features, such as QuickBooks’ robust capabilities and Xero’s unlimited user access. FreshBooks is user-friendly for freelancers, whereas Wave Accounting provides a free solution for tracking income and expenses, making it suitable for small businesses. Can You Do Bookkeeping on a Mac? Yes, you can definitely do bookkeeping on a Mac. Various accounting software options are customized for macOS, like QuickBooks Online, Xero, and FreshBooks. These platforms offer crucial features such as invoicing and expense tracking, and most provide cloud access, allowing you to manage finances from anywhere. Moreover, many applications offer mobile apps for iOS, enhancing your ability to track finances on the go. Some even provide free plans, making them accessible for freelancers and small businesses. Are Macs Good for Accounting? Yes, Macs are good for accounting because of their compatibility with various accounting software options. These applications often feature user-friendly interfaces, making it easier for you to manage your finances efficiently. Cloud-based solutions provide accessibility from anywhere, which is ideal for freelancers and small businesses. Furthermore, Macs offer strong security measures, including encryption and data backup, ensuring your financial information remains safe. Conclusion In conclusion, finding the right accounting software for Mac can greatly streamline your financial management. Xero and QuickBooks Online excel in features and usability, whereas FreshBooks and Zoho Books cater to freelancers and those needing automation. If budget is a concern, Wave Accounting offers a free option. Each of these packages provides unique benefits, so evaluate your specific needs to choose the one that best fits your business. With the right tool, you can improve productivity and maintain accurate financial records. Image via Google Gemini and ArtSmart This article, "7 Best Accounting Packages for Mac Users" was first published on Small Business Trends View the full article
-
Conglomerate owned by Asia’s richest person had earlier agreed to pay $275mn to settle separate US sanctions violation probeView the full article
-
Proposed deal between NextEra and Dominion would cement control of US ‘data centre alley’ View the full article
-
A decade of light-night history is closing out this week, with Stephen Colbert’s tenure as the host for “The Late Show” coming to an end on Thursday. Filmed in the Ed Sullivan Theater, The Late Show is CBS’s flagship late night talk show, first airing in 1993 with David Letterman hosting. Colbert first joined the show in 2015 following successful stints at The Daily Show and The Colbert Report, with his political monologues during the first The President administration helping grow his popularity, particularly among more liberal viewers. His vocal critique of The President is also seen by many as precipitating the end of his hosting duties. CBS parent company Paramount announced last July that this season, which concludes May 21, would be its final season of The Late Show. CBS has claimed that the cancellation was a financial decision, but many remain skeptical, pointing to possible pressures by the current administration—which Colbert has extensively criticized. The announcement came as the company was still pursuing the merger that created Paramount Skydance, shortly after it reached a $16 million settlement with The President over an interview that aired on 60 Minutes during the 2024 election. “He was dumped because the people selling the network to Skydance said, “Oh no, there’s not going to be any trouble with that guy. We’re going to take care of the show. We’re just going to throw that into the deal. When will the ink on the check dry?” Letterman told The New York Times about the cancellation. “I’m just going to go on record as saying: they’re lying. What’s in store? Ahead of the final week CBS announced the show’s last lineup of guests and programming, including major stars, celebrities, and special segments—although, quite like Colbert and his team’s future, much is still uncertain. Monday’s show will be what the network is dubbing “The Worst of ‘The Late Show With Stephen Colbert,” clarifying the show will not be a clip show and will indeed feature new content. Tuesday’s show will welcome fellow comedian and Colbert’s mentor Jon Stewart, as well as Steven Spielberg, and a joint musical performance from Colbert and David Byrne. Wednesday, the night before the show’s finale, will host a performance from Bruce Springsteen as well as one final segment of “The Colbert Questionert.” Guests for the final episode are yet to be announced, although fellow talk show hosts Jimmy Kimmel and Jimmy Fallon have both announced to air reruns on Thursdays in honor of Colbert. Both hosts, as well as colleagues Seth Meyers and John Oliver joined Colbert last week as a reunion of the Strike Force Five, the name the group assigned to themselves when they joined forces to support and pay their writers during the 2023 WGA strike. During the interview, all comedians agreed to be present during Colbert’s last show. They all also voiced their discontent towards the decision to cancel the show. “I’m waiting for angry Stephen to come out,” Kimmel said during the group interview. “I want to see you go nuts.” While Colbert has been relatively diplomatic during the months-long lead up to the end, he has occasionally shared his feelings about the situation. “You guys started before I did. Each of your shows you’re doing started before this show. And then you’re going to be here after I’m here,” he said during the Strike Force Five reunion. “You’re like the candy shell, I’m like the nougat filling, and then somebody came in and just sucked it out.” View the full article
-
Providence, Rhode Island, headed Zillow's hottest rental markets list, beating out New York and San Francisco, the company announced Monday. View the full article
-
1Password is one of our favorite password managers, especially for users who are new to password management tools. It has a handful of unique features and hidden hacks that keep your data safe and secure while also making it accessible when you need to log into an account, make an online payment, or view a sensitive document. Here's how to get the most out of your 1Password subscription. Enable Travel Mode to hide your more sensitive data at border crossings Travel Mode is one of 1Password's most unique features, and it's especially useful for anyone concerned about keeping their data private when crossing international borders. When Travel Mode is enabled, password vaults are removed from your devices unless you've marked them as "safe," so anyone accessing your phone or computer for inspection won't be able to see anything you've hidden. You can only manage Travel Mode at 1Password.com: after logging in, select your name > Manage Account and turn on Travel Mode. If you need access to some of your data, you can add items to a separate vault and mark that vault as safe under the Vaults section of the sidebar. All other vaults will be removed from desktop and mobile apps and unavailable to view on the web app and browser extension. Use virtual cards to protect your credit card details when paying onlineA virtual credit card is a temporary payment card with a randomly generated number that you can use for online purchases without revealing your real card information, providing an extra layer of protection against fraud. 1Password integrates with Privacy.com, a third-party service that lets you create cards for specific merchants as well as set spending limits and rules for recurring use. 1Password will then suggest your Privacy Card when you check out on that merchant's website. You do need to create a Privacy account—the free tier allows up to 12 cards per month—and have the 1Password browser extension. Set up expiry alerts so you don’t miss renewal deadlines1Password has more than a dozen item types ranging from standard login credentials and credit cards to passports and software licenses—and many of these require renewal or updating at specific intervals. Instead of trying to remember when documents and accounts are set to expire, you can have 1Password remind you automatically (so you'll never have to scramble to renew your passport again). Add a date to the item record, then set an expiry alert ranging from 1 day to 9 months in advance, or choose a custom reminder date. Add authentication codes to shared vaults to avoid texting them back and forth1Password saves your one-time passwords (OTPs) used for multi-factor authentication (MFA) and automatically fills them when you log into a website with your username and password. While MFA is highly recommended, it can be tedious for shared accounts where one person has the rotating authentication codes on their device while someone else is trying to log in from a different location. To avoid having to text codes back and forth, set them up in 1Password and add the item to a shared vault. While any user can share individual vault items, you must have a Families plan to set up shared vaults. Use a temporary vault to share logins with guestsAnother Families feature is guest vaults, which let you share specific items with people outside your family or household on an as-needed basis. For example, you could use guest vaults to share wifi information, smart lock codes, and streaming service logins with visitors or your babysitter. Guests don't need to have their own 1Password accounts, and they won't be able to see any other vaults on your plan. Add guests on the web app under the Invitations tab. Go to Invite by Email, enter their address, and select Guest > Invite. You can remove guests at any time under the People tab. Save your router information to generate a QR code for instant connectionWhen you add your wireless router to 1Password, the app will automatically generate a QR code, allowing anyone to join your network simply by scanning. Tap New Item > Wireless Router and enter the network name and wireless network password (at a minimum—you can complete the other fields if you want to). The QR code will appear at the bottom of the item. You can also hide QR codes by default under Settings > Security > Concealed Fields, which means you'll need to select Reveal before scanning. Add tags and geo-tags to make locating items easier 1Password already makes it relatively easy to find passwords and other items in your vault with sorting options, including those most frequently or recently used, and a Tags field for custom search keywords. You can also add physical locations, and items will appear in a section called Nearby in the mobile app when you're within a certain distance—this quickly pulls up rewards numbers, health insurance information, or travel documents when you're out and about. Open a record, select Edit, tap Add A Location, and paste the map link or coordinates from Apple Maps or Google Maps into the field. On mobile, you can set your "Nearby" radius between 50 feet and 10 miles. Link related vault items together so you don't have to search for what you needAnother useful organization feature in 1Password is the ability to link related items together—when you search for and open one item, everything you've linked to it will show up in that item's details without a separate search. For example, you could link bank accounts and credit cards to the Login item for your financial institution or a secure note or document to any relevant credential or other document. When editing an item, tap Add More > Link to a related item, search for the item, and click Save. Archive old credentials to keep them secure but hidden from viewIf you have logins, documents, notes, or other records that you no longer actively use but don't want to lose, you can archive them in 1Password. This sends them to the Archive folder, removes them from search results, and prevents them from being suggested for autofill. Unlike deleting, however, you can restore them at any time. Open the record you want to archive and tap the three dots > Archive (or drag and drop on desktop). Use 1Password as your "in case of death" folder for your most secure documents1Password is a secure way to store much of your "digital estate." This includes your usernames, passwords, and accounts, obviously, but also sensitive documents and personal files like titles, deeds, wills, certificates, licenses, photos, scans, and information about digital assets. All users get 1GB of storage, and you can upload files via New Item > Document > Add File. (Use the hack about linking related items to keep things organized.) While 1Password doesn't have a legacy access feature to pass your vault onto a trusted contact in case of incapacity or death, you can plan ahead for this to ensure your data isn't locked away permanently. One option is to use the Emergency Kit, which is a written record for accessing your account—put this in secure storage, either physical or digital. Alternatively, you can set up and share recovery codes with a trusted contact. View the full article
-
Accounts payable is a vital aspect of any business’s financial management, representing the money owed for goods and services purchased on credit. It typically has a short-term nature, requiring payment within 30 to 90 days. Comprehending accounts payable is fundamental, as it directly impacts cash flow, supplier relationships, and overall financial health. By managing these obligations effectively, businesses can avoid late fees and fortify vendor partnerships. But what specific strategies can improve your accounts payable process? Key Takeaways Accounts payable represents a company’s obligation to pay for goods and services received on credit, typically due within 30 to 90 days. Efficient management of accounts payable strengthens supplier relationships and ensures timely payments, avoiding late fees and potential disruptions. Accurate recording of accounts payable supports reliable financial reporting and insights into a company’s liquidity and financial health. Automating accounts payable processes reduces errors, improves efficiency, and enhances cash flow management for businesses. Monitoring accounts payable turnover ratio helps assess efficiency in managing liabilities and indicates a company’s short-term liquidity status. Definition of Accounts Payable Accounts payable (AP) is a vital component of a business’s financial management. It represents your company’s obligation to pay for goods and services received on credit, with payments typically due within 30 to 90 days. Recorded as a current liability on the accounts payable balance sheet, AP includes various types of liabilities such as trade payables for regular purchases, accrued expenses for incurred but unpaid costs, and other payables like taxes and interest. Proper management of accounts payable is crucial for maintaining healthy vendor relationships, as timely payments can lead to better credit terms and discounts. Unlike accounts receivable, which indicates money owed to your company, AP serves as a short-term liability reflecting obligations to creditors. Effectively managing your accounts payable improves cash flow by optimizing payment timing and avoiding late fees, eventually contributing to your overall financial health. Types of Accounts Payable Now that we’ve defined accounts payable, it’s important to understand the different types that exist. You’ll encounter trade payables, which come from routine purchases, and accrued expenses that represent costs you’ve incurred but haven’t settled yet. Furthermore, there are other payables like taxes and interest, all of which play a significant role in your financial management. Trade Payables Overview Trade payables represent a crucial component of a company’s financial health, stemming from the routine purchase of goods and services on credit. These payables are a specific type of accounts payable, typically recorded as current liabilities on the balance sheet, due within 30 to 90 days. Efficient management of trade payables is essential for maintaining cash flow and nurturing strong relationships with suppliers, which can lead to improved pricing and terms. Automating trade payables can streamline invoice processing and payment workflows, reducing errors and enhancing efficiency. Nevertheless, an increase in trade payables may indicate a reliance on vendor credit, requiring careful monitoring to prevent potential cash flow issues or financial distress. Accrued Expenses Explained When businesses incur costs for goods or services but haven’t yet made the payment, these obligations become accrued expenses. These liabilities are essential for comprehending your financial position, as they represent costs you’ve already incurred. Common examples of accrued expenses include: Wages payable Interest payable Utilities payable Accrued expenses are recognized in the accounting period they’re incurred, following the accrual basis of accounting. This practice guarantees that expenses align with the revenues they help generate, maintaining accurate financial statements. Other Payables Categories During managing your business’s financial obligations, it’s critical to understand the various categories of payables, particularly other payables, which encompass a range of liabilities beyond trade payables and accrued expenses. Other payables categories include financial obligations like taxes owed and interest payments. These are fundamental for guaranteeing compliance with tax regulations and making timely payments to avoid penalties or legal issues. Effectively managing these payables is important for maintaining your company’s liquidity and financial stability, as they can greatly impact cash flow. Regularly monitoring and reconciling other payables helps guarantee accurate financial reporting, reflecting all outstanding obligations that influence your business’s overall financial position and maintain good relationships with creditors. Importance of Accounts Payable Grasping the importance of accounts payable (AP) is essential for any business aiming to maintain a healthy cash flow and strong supplier relationships. Effective management of AP not only helps you manage your short-term liabilities but likewise optimizes payment timing, ensuring liquidity. Here are some key benefits of accounts payable services: Strengthens supplier relationships by ensuring timely payments, which can lead to better terms and discounts. Enhances financial reporting accuracy, providing insights into your obligations and overall financial health, as reflected in your balance sheet. Reduces processing errors through automation, allowing you to focus on strategic financial management rather than manual tasks. Key Components of Accounts Payable Comprehending accounts payable involves recognizing its key components, which play an important role in managing a business’s financial obligations. The accounts payable process includes vendor invoices, utility bills, employee reimbursements, and accrued expenses, all representing amounts owed for goods and services received. Each component is critical, as they’re classified as current liabilities on the balance sheet, indicating short-term obligations typically due within 30 to 90 days. Purchase orders are essential in this process; they detail the specifics of goods or services ordered, guaranteeing accuracy in invoicing. Efficient management of accounts payable requires timely processing of these invoices, which helps maintain good vendor relationships and optimizes cash flow. Furthermore, accurate record-keeping is important, as it provides insights into your company’s liquidity and overall financial health. Adhering to these accounts payable procedures guarantees your business stays on top of its financial commitments. The Role of Accounts Payable in Financial Statements Accounts payable is categorized as a current liability on your balance sheet, representing your obligation to pay suppliers for goods and services received on credit. This balance not just impacts your cash flow but likewise serves as a key indicator of your company’s short-term liquidity and efficiency in managing working capital. Comprehending how accounts payable influences your financial statements can help you make informed decisions about your business’s financial health. Current Liabilities Overview Though many aspects of a company’s financial health are vital, grasping current liabilities—specifically accounts payable—is important for evaluating its short-term obligations. Accounts payable is classified as a current liability on the balance sheet, representing debts due within one year. Proper management of these liabilities is critical, as it can impact liquidity and working capital calculations. Here are some key points about accounts payable services: A growing accounts payable balance may indicate increased credit purchases. The accounts payable turnover ratio helps assess efficiency in managing liabilities. Accurate reporting prevents late fees and nurtures supplier relationships. Understanding this current liabilities overview allows you to make informed decisions about your company’s financial stability and operational efficiency. Impact on Cash Flow Managing current liabilities like accounts payable is crucial not just for financial health but likewise for cash flow management. Accounts payable (AP) appears as a current liability on your balance sheet and directly affects short-term liquidity. An increase in AP can improve cash flow temporarily by allowing higher credit usage, but excessive growth might indicate financial distress. The AP turnover ratio measures your efficiency in settling obligations, revealing insights into cash flow management. Accounts Payable Impact on Cash Flow Increase Short-term cash flow boost Decrease Potential cash flow strain Timely Payments Avoid late fees, gain discounts Strong Relationships Better payment terms Effective AP management helps maintain supplier relationships, ensuring stable cash flow. Examples of Accounts Payable In the domain of business, grasping the various examples of accounts payable is vital for maintaining financial health. Knowing these examples helps you manage your cash flow effectively and maintain good vendor relationships. Here are some common accounts payable examples you might encounter: Supplier invoices for raw materials Contractor payments for services rendered Monthly utility bills for fundamental services like electricity and water Moreover, accounts payable services include professional fees for legal, consulting, or accounting services. Subscriptions for software or services billed after usage also fall under this category. In addition, charges for employee reimbursements related to business expenses, such as travel or office supplies, can be categorized as accounts payable. Regularly tracking and managing these examples guarantees your business remains financially stable and prepared for future obligations. Recording Accounts Payable Comprehending how to record accounts payable is crucial to managing your business’s financial health. When you receive goods or services on credit, you’ll use double-entry bookkeeping to reflect this transaction accurately. For instance, if you purchase $10,000 worth of office furniture, your accounts payable general journal entry would involve debiting Assets for $10,000 and crediting Accounts Payable for the same amount. This entry increases your liabilities during the process of adding to your assets. When it’s time to pay your suppliers, you decrease accounts payable by debiting it and crediting Cash, showing a reduction in both liability and cash outflow. Accurate recording of accounts payable is vital for reliable financial reporting, ensuring your balance sheet accurately reflects your liabilities. Regularly reconciling your accounts payable records with the general ledger similarly helps identify discrepancies, ensuring your financial records remain precise and up to date. Accounts Payable Management Effective accounts payable management is essential for maintaining a business’s financial stability and supplier relationships. It involves accurately processing, approving, and paying invoices on time, which helps prevent late fees and strengthens partnerships with suppliers. To optimize your accounts payable services, consider these key strategies: Schedule Payments: Strategically timing your payments can improve cash flow and liquidity. Automate Processes: Implementing automation reduces manual errors, streamlines workflows, and improves efficiency in invoice processing. Monitor Performance Metrics: Keeping an eye on the accounts payable turnover ratio offers insights into your company’s efficiency and overall financial health. Regularly reconciling the accounts payable ledger with the general ledger is also essential. This practice helps identify discrepancies swiftly, ensuring accurate financial records and maintaining the integrity of your business’s financial standing. Accounts Payable vs. Accounts Receivable Accounts Payable (AP) and Accounts Receivable (AR) play essential yet opposite roles in your business’s financial health. Whereas AP reflects the money you owe to suppliers for goods and services, AR shows the money owed to you by customers for sales made on credit. Comprehending their differences on financial statements—AP as a liability and AR as an asset—helps you manage cash flow and maintain liquidity effectively. Definitions and Roles Comprehending the distinction between accounts payable (AP) and accounts receivable (AR) is essential for managing a business’s financial health. Accounts payable represents what your business owes to suppliers for goods and services received on credit, typically due within 30 to 90 days. Conversely, accounts receivable indicates money owed to your business by customers for products or services provided. Key differences include: AP is a current liability, whereas AR reflects potential cash inflow. AP management maintains supplier relationships, whereas AR focuses on timely collections. Both are significant for working capital management and optimizing cash flow. Utilizing effective accounts payable services can improve your ability to manage these functions efficiently, ensuring liquidity and supporting overall financial stability. Financial Statement Differences Comprehending the financial statements of a business is crucial, especially when differentiating between accounts payable (AP) and accounts receivable (AR). AP represents short-term liabilities to suppliers for goods and services bought on credit, whereas AR shows the money owed to your business by customers for credit sales. On the balance sheet, AP is a current liability that must typically be settled within 30 to 90 days, whereas AR is a current asset indicating expected cash inflows. The accounts payable turnover ratio measures how quickly you pay suppliers, whereas the accounts receivable turnover ratio assesses how efficiently you collect payments. Grasping these differences is critical, as effective accounts payable services can improve cash flow and overall financial health. Challenges in Accounts Payable Though many businesses endeavor for efficiency in their financial operations, challenges in accounts payable (AP) can greatly hinder that goal. Manual processing often leads to inefficiencies, resulting in delayed payments and increased risk of late fees, which affects cash flow. Human errors during invoice matching and data entry can create payment discrepancies, damaging your relationships with vendors. Furthermore, the lack of automation in accounts payable services raises the risk of fraud, as manual systems are more vulnerable to unauthorized transactions. Here are some common challenges you might face: Inconsistent vendor invoice formats complicate reconciliation. Limited visibility into outstanding payables makes cash flow management harder. Invoice discrepancies lead to increased administrative burdens. Addressing these issues is vital for maintaining accurate financial records and optimizing payment processes, ultimately supporting your business’s financial health. Automation in Accounts Payable To tackle the challenges faced in accounts payable, many businesses are turning to automation as a solution. Automation in accounts payable streamlines invoice processing by cutting down on manual data entry, which helps reduce errors and boosts efficiency in managing payments. By implementing automated systems, you can experience faster approval workflows, enabling your business to take advantage of early payment discounts and improve cash flow management. These solutions often integrate seamlessly with existing ERP systems, offering real-time insights into liabilities and enhancing financial reporting accuracy. Utilizing cloud-based automation tools allows your team to collaborate securely in real-time, making financial data accessible and organized for audits and compliance. Research shows that automation can slash invoice processing costs by up to 80%, freeing up your finance team to focus on more strategic tasks instead of repetitive manual processes, ultimately driving better business outcomes. Frequently Asked Questions What Is Accounts Payable and Why Is It Important? Accounts payable refers to the money your company owes suppliers for goods and services received on credit. It’s crucial for managing cash flow, as timely payments can help you avoid late fees and may even earn you discounts. A growing accounts payable balance could signal increased reliance on vendor credit or cash flow challenges, making effective monitoring fundamental. Properly managing accounts payable likewise strengthens supplier relationships and improves your financial reporting accuracy. What Is the Golden Rule of Account Payable? The golden rule of accounts payable is to make timely payments to vendors, typically within agreed terms of 30 to 90 days. By adhering to this rule, you maintain healthy vendor relationships and avoid late fees. Furthermore, timely payments allow you to manage cash flow effectively, enabling you to take advantage of discounts. It’s vital to guarantee accurate processing and authorization of transactions to prevent fraud and maintain financial integrity. How to Explain Accounts Payable in an Interview? In an interview, explain accounts payable as a company’s obligation to pay for goods and services received on credit, typically due within 30 to 90 days. Highlight its role as a current liability on the balance sheet, emphasizing the importance of timely payments to maintain healthy vendor relationships and optimize cash flow. Discuss how managing accounts payable involves invoice capture, approval, and payment authorization, which all require accurate record-keeping to guarantee compliance with company policies. What Are the Three Basic Functions of Accounts Payable? The three basic functions of accounts payable are invoice processing, payment processing, and vendor management. In invoice processing, you verify and record supplier invoices to guarantee accuracy. During payment processing, you execute payments based on approved invoices, optimizing cash flow. Vendor management involves maintaining relationships with suppliers, addressing payment discrepancies, and promoting ongoing communication. These functions help maintain accurate financial records, support cash flow management, and cultivate positive vendor relationships. Conclusion In conclusion, accounts payable is a vital aspect of business finance, representing the obligations a company has to its suppliers. By managing these obligations effectively, businesses can improve cash flow, maintain strong vendor relationships, and guarantee accurate financial reporting. Comprehending the various components of accounts payable, including its role in financial statements and the benefits of automation, can lead to improved operational efficiency. In the end, effective accounts payable management is fundamental for sustaining financial health and stability within any organization. Image via Google Gemini This article, "What Is Accounts Payable and Its Importance for Businesses?" was first published on Small Business Trends View the full article