Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
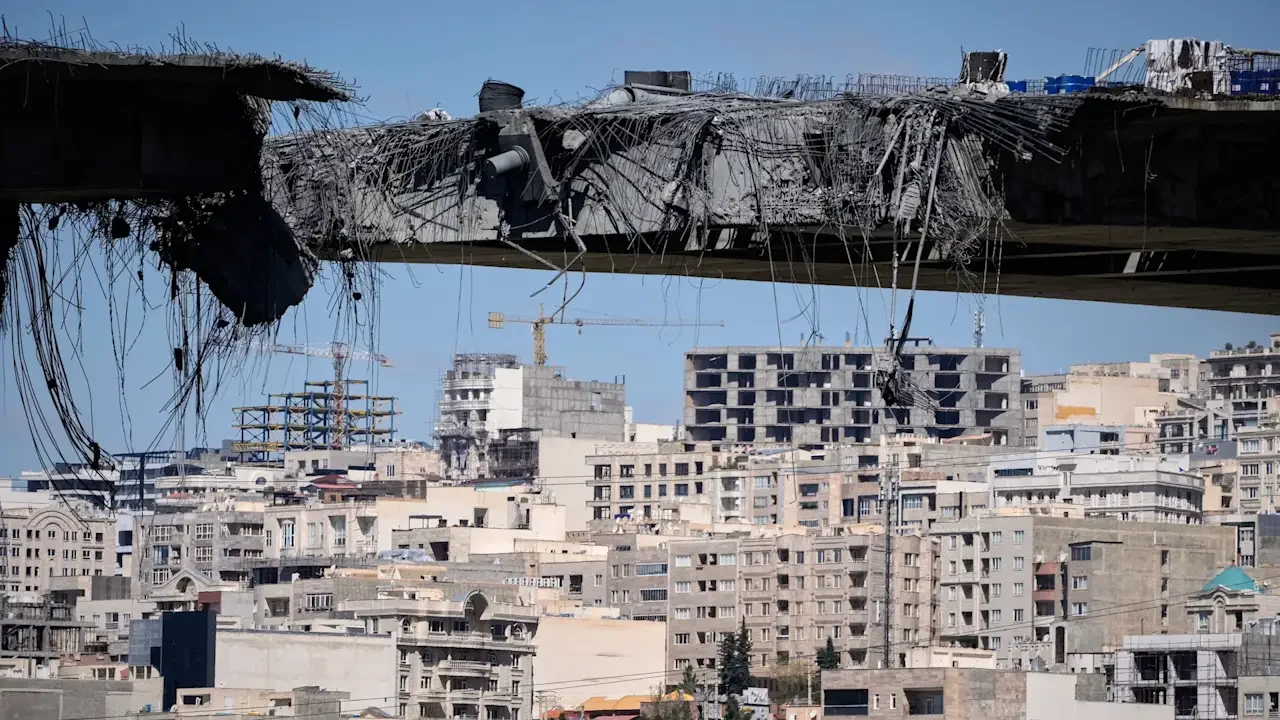
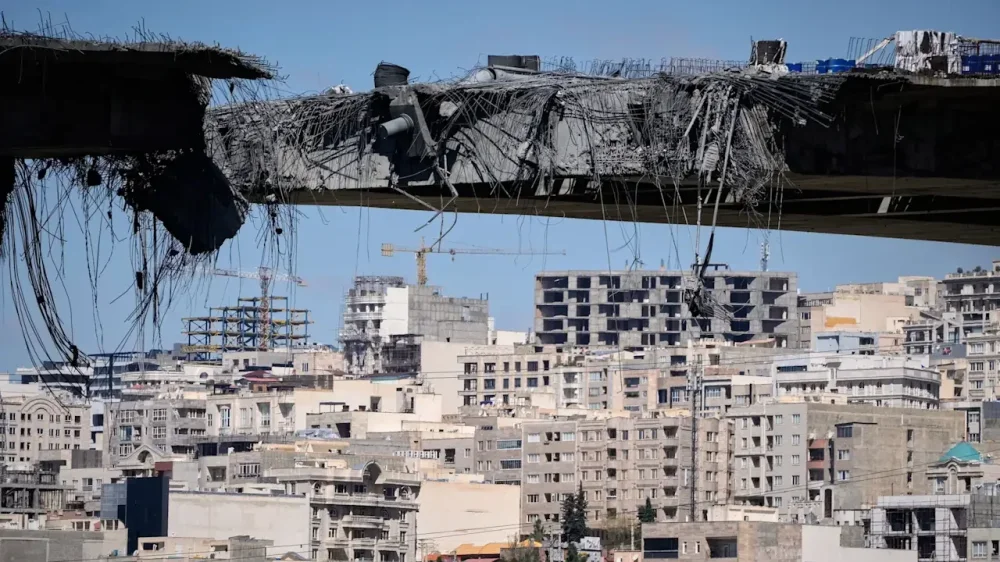
One crew member was rescued Friday after an American aircraft was shot down in Iran, according to one U.S. and one Israeli official, who both spoke on condition of anonymity to describe sensitive ongoing military operations. The rescue occurred as the U.S. military was conducting a search and rescue operation, according to three people familiar who spoke on condition of anonymity to discuss the sensitivity of the situation. Israel is helping the United States with the operation. According to an email from the Pentagon obtained by The Associated Press, the U.S. military said that it received notification of “an aircraft being shot down” in the Middle East. The email did not provide more details. White House press secretary Karoline Leavitt said in a previous statement that President Donald The President had been briefed but did not offer any additional information. It was the first time the U.S. has lost aircraft in Iranian territory and constitutes a dramatic escalation in the war since it began five weeks ago. Iran fired on targets across the Mideast on Friday, as Tehran kept the pressure on Israel and its Gulf Arab neighbors, despite U.S. and Israeli insistence that Iran’s military capabilities have been all but destroyed. Iran’s attacks on Gulf energy infrastructure and its tight grip on the Strait of Hormuz, through which a fifth of the world’s oil and natural gas transits in peacetime, have roiled stock markets, sent oil prices skyrocketing, and threatened to raise the cost of many basic goods, including food. US drones and helicopters spotted over mountainous region Prior to word of the rescue, social media footage showed American drones, aircraft, and helicopters flying over the mountainous region where a TV channel affiliated with Iranian state television had said earlier Friday that at least one pilot bailed out of the fighter jet. An anchor on the channel urged residents to hand over any “enemy pilot” to police and promised a reward. The number of crew on board wasn’t immediately known. The Pentagon and U.S. Central Command didn’t immediately respond to several messages seeking comment. Throughout the war, Iran has made a series of claims about shooting down piloted enemy aircraft that turned out not to be true. Friday was the first time that Iran went on television urging the public to look for a suspected downed pilot. An on-screen crawl earlier urged the public to “shoot them if you see them,” referring to the social media footage circulating of U.S. aircraft in the area. The channel showed metal debris in the back of a pickup truck while making the announcement but provided no other immediate details. Iran targets a desalination plant and a refinery The claim came after Kuwait’s Mina al-Ahmadi oil refinery came under Iranian attack, and the state-run Kuwait Petroleum Corp. said firefighters were working to control several blazes. Kuwait also said an Iranian attack caused “material damage” to a desalination plant. Such plants are responsible for most of the drinking water for Gulf states, and they have become a major target in the war. Sirens also sounded in Bahrain, Saudi Arabia said it had destroyed several Iranian drones, and Israel reported incoming missiles. Authorities in the United Arab Emirates shut down a gas field after a missile interception reportedly rained debris on it and started a fire. Activists reported strikes around Tehran and the central city of Isfahan, but it wasn’t immediately clear what was hit. A day earlier, Iran said the U.S. hit a major bridge, which was still under construction, killing eight people. In Lebanon, where Israel has launched a ground invasion in its fight with the pro-Iranian Hezbollah militant group, an Israeli drone strike on worshippers leaving Friday prayers near Beirut killed two people, according to the state‑run National News Agency More than 1,900 people have been killed in Iran since the war began on Feb. 28 with U.S. and Israeli strikes. In a review released Friday, the Armed Conflict Location and Event Data, a U.S.-based group, said it found that civilian casualties were clustered around strikes on security and state-linked sites “rather than indiscriminate bombardment” of urban areas. More than two dozen people have died in Gulf states and the occupied West Bank, 19 have been reported dead in Israel, and 13 U.S. service members have been killed. More than 1,300 people have been killed and more than 1 million displaced in Lebanon. Ten Israeli soldiers have also died there. Iran is keeping a chokehold on the Strait of Hormuz World leaders have struggled to end Iran’s stranglehold on the strait, which has had far-reaching consequences for the global economy and has proved to be its greatest strategic advantage in the war. The U.N. Security Council was expected to take up the matter on Saturday. The President has vacillated on America’s role in the strait, alternately threatening Iran if it doesn’t open the waterway and telling other nations to “go get your own oil.” On Friday, he said in a post on social media that, “With a little more time, we can easily OPEN THE HORMUZ STRAIT, TAKE THE OIL, & MAKE A FORTUNE.” Spot prices of Brent crude, the international standard, were around $109 Friday, up more than 50% since the start of the war, when Iran began restricting traffic through the strait. Iran’s former top diplomat suggests terms to end the war Former Iranian Foreign Minister Mohammad Javad Zarif — a diplomat with long experience negotiating with the West who remains close to a pragmatic wing of Iran’s leadership — wrote on Friday in Foreign Affairs magazine that the time has come to end what he referred to as a stalemate. The U.S. and Iran have proposed dueling plans, and Zarif’s proposal included elements of both in a sign part of Iran’s leadership might be willing to negotiate. Iran “should offer to place limits on its nuclear program and to reopen the Strait of Hormuz in exchange for an end to all sanctions — a deal Washington wouldn’t take before but might accept now,” he wrote. It’s not clear how much to read into the proposal from Zarif, who has no official position in Iran’s government, but would likely not have published such a piece without at least some authorization from senior leaders. —Jon Gambrell, Sam Mednick, and Konstantin Toropin, Associated Press Associated Press writers Sylvie Corbet, Sarah El Deeb, Tong-hyung Kim, Michelle L. Price, Lisa Mascaro, and Seung Min Kim contributed to this report. View the full article
-
Early this year, rapper and recording executive Gucci Mane was reportedly held at gunpoint and robbed at a music studio in Dallas, Texas. Now, a motive for the crime (and the alleged culprits) have been revealed: A rapper signed to Gucci Mane’s label wanted out of his contract. Rapper Pooh Shiesty, whose real name is Lontrell Williams Jr., has been signed to Gucci Mane’s record label 1017 Records since 2020. According to a criminal affidavit written by FBI agent Brittany Garcia, Williams was unhappy with his record deal and invited Gucci Mane, legal name Radric Davis, to a meeting to discuss the terms of his contract. The not-so-perfect crime According to the affidavit, Williams arrived at the meeting location, a recording studio in Dallas, with eight accomplices, including his father Lontrell Williams Sr. and fellow rapper Rodney Wright Jr., aka Big30. There, he presented Davis with paperwork that would release him from his contract. When Davis refused to sign it, Williams produced “a black AK-style pistol” from his bag and pointed it at Davis, demanding that he sign the release paperwork. Davis did so, while Wright filmed him with a cellphone. Once the paperwork was signed, Williams took Davis’ wedding ring, watch, earrings, and cash. Two of Davis’ associates were reportedly also held at gunpoint and robbed by Williams’ accomplices, with one individual, identified in the affidavit as “M.M.”, being “choked from behind to the point of nearly losing consciousness.” The affidavit claims Wright then blocked the door to the studio lobby, preventing Davis and the other victims from leaving. They were then forced to leave the building through a side entrance and escorted to their vehicle. Williams and the eight other suspects are now facing federal charges in relation to kidnapping and robbery at gunpoint. They face life in prison if convicted. The future for Pooh Shiesty’s contract with Gucci Mane’s label Williams’ scheme to get out of his recording contract apparently didn’t go according to plan, with the victims’ reports, security camera footage, and the fact that he was wearing an ankle monitor during the crime leading to his arrest. But whether or not Williams lands in prison, what will happen to his recording contract? Under contract law, documents signed under duress, including under threat of violence, are generally rendered invalid. That means the paperwork Williams forced Davis to sign likely wouldn’t hold up to legal scrutiny, keeping Williams signed to 1017 Records for the time being. Whether Davis would still want Williams working under his label is another story. Plenty of artists have found success during and after incarceration, with Davis himself having served time in prison from 2014 to 2016 after being charged with possession of a firearm by a convicted felon. Other rappers have seen massive commercial success after facing legal trouble, like A$AP Rocky: Don’t Be Dumb, his first album since being convicted of assault in Sweden and facing trial on potential assault charges in Los Angeles, topped the Billboard 200 chart and saw the largest streaming debut of 2026 so far, with 35.4 million first-day streams on Spotify. In Williams’ case, whether the increased media attention from his kidnapping and robbery charges could drive listeners to stream his music remains to be seen. Given that Williams is still under Davis’ label, any extra earnings will go, in part, to him. As one social media user put it, Williams may have been better off recruiting an entertainment lawyer to help get out of his record deal, but instead, he’s learning the hard way that contract law and threats of violence at gunpoint generally don’t mix. View the full article
-
Amid fluctuating gas prices that have recently surged, Lyft has unveiled a strategically designed 60-day driver relief program aimed at aiding their drivers, many of whom rely heavily on the ride-hailing service for income. Starting March 27 and running through May 26, this initiative highlights Lyft’s understanding of the financial strains that drivers face and underscores their commitment to supporting this critical segment of their workforce. Lyft recognizes that rising gas prices can directly impact drivers’ earnings. Yuko Yamazaki, Lyft’s Vice President and Head of Driver, states, “Drivers are feeling the cost of rising gas prices, which ultimately impacts their earnings. When costs spike, we want drivers to choose Lyft because they feel like the platform works for them, not against them.” This is especially relevant for small business owners who may use rideshare services to complement their business operations. The driver relief program introduces several cash-back rewards designed to provide immediate financial relief. For instance, Elite tier drivers can earn an additional 2% cash back when using the Lyft Direct business debit card at eligible gas stations, while Gold and Platinum tier drivers can gain an extra 1%. Coupled with existing rewards—ranging from 1% to 10% based on driver tier—these offerings present tangible benefits for small business owners or independent drivers incorporating rideshare into their business model. Additionally, drivers can secure 14 cents per gallon through the Upside app, further enhancing their savings potential during this program. The savings can collectively add up significantly, especially for those who drive frequently. Lyft’s existing partnerships, like those with Mastercard® Easy Savings gas stations, provide yet another pathway to bolster this relief, allowing for additional savings on every fill-up through the Lyft Direct app. For small business owners, this presents an opportunity to explore rideshare services as a cost-effective transportation solution for business needs. Whether it’s sending employees to meetings or managing logistics, these cashback rewards can soften the financial load. Furthermore, drivers who participate in Lyft’s Shop points program can redeem points for $5 off their next fill-up, which can help those who use ridesharing as a part of their business operations, especially if they frequently travel for client meetings or deliveries. However, small business owners should be aware of certain challenges associated with this relief program. First, eligibility restrictions may apply; drivers in select states such as California, Washington, Minnesota, and New York City are excluded from certain rewards. Additionally, the efficiency of the program relies on the drivers’ choice to use Lyft, meaning that competition from other rideshare platforms could influence usage rates and, therefore, the benefits received. It’s crucial for small business owners to stay informed about industry changes and emerging trends that can directly impact their operations. Integrating rideshare solutions and keeping abreast of these types of relief initiatives can provide them with a competitive edge in transportation management. As the landscape of ridesharing evolves, Lyft’s proactive measures showcase an understanding of driver experiences, making it clear that even small steps toward assistance can resonate well within the small business community. Business owners interested in these developments can visit Lyft’s original announcement here for a detailed breakdown of the program and all associated benefits. Image via Google Gemini This article, "Lyft Launches 60-Day Relief Program to Support Drivers Amid Rising Gas Prices" was first published on Small Business Trends View the full article
-
We all tend to accept information that is consistent with our prior beliefs, and reject the oppositeView the full article
-
We may earn a commission from links on this page. Sherlock Holmes is only recently in the public domain (at least in full), and hoo boy, are creators going to make the most of it—there are at least three major Doyle-adjacent works streaming in 2026, and I'm probably missing a couple. Not that IP was ever much of a barrier, as evidenced by the hundreds of films, books, porn parodies, etc. released in the near-century since Arthur Conan Doyle's death. Which is all to say that Holmes is pretty resilient as a character, and, while I wouldn't have said that we need a zippy, Guy Ritchie Sherlock prequel—Young Sherlock is unique, and quite a bit of fun. It's stretching the character to nearly his breaking point, for sure, but maintaining at least a reasonable bit of respect for the canon, with a well-cast lead in Hero Fiennes Tiffin alongside Dónal Finn as Moriarty. Here are some other entertainingly stylish period (mostly) dramas for your post-Young Sherlock viewing enjoyment. The Artful Dodger (2023) Artful Dodger serves as a sequel to Oliver Twist, finding Jack Dawkins (Thomas Brodie-Sangster of Queen's Gambit and Wolf Hall) having made a life for himself as a surgeon following a prison escape: Turns out those nimble fingers are good for more than just picking pockets. It's all going great until his old mentor Fagin (David Thewlis) shows up on his doorstep, using their history to nudge Jack back into helping out with criminal endeavors. Thewlis and Brodie-Sangster are well-matched in the surprising and funny series that sees Jack torn between his roguish impulses and his desire to go straight. Stream The Artful Dodger on Hulu. The Artful Dodger (2023) at Hulu Learn More Learn More at Hulu The Irregulars (2021) What sounded like a desperately unnecessary Sherlock Holmes pastiche involving the Baker Street Irregulars (led here by Bad Sisters' Thaddea Graham) layered an unexpected exploration of grief into the dark supernatural mystery at its core. Here, Watson (Royce Pierreson) hires the damaged but resourceful urchins to aid in cases involving occult activity, as well as to help track down an aging, and missing, Sherlock. Holmes angle aside, the show works as a darker, Victorian-era Stranger Things. It was canceled before its time, but comes to a reasonably satisfying conclusion. Stream The Irregulars on Netflix. The Irregulars (2021) at Netflix Learn More Learn More at Netflix Murdoch Mysteries (2008 – ) Kicking off in 1895, the show follows Detective William Murdoch (Yannick Bisson) of the Toronto Constabulary as he and his team solve Upper Canada's most baffling crimes. The chemistry between the leads has powered the show through 19 seasons (and counting), as has the show's whimsical attitude toward historical accuracy, throwing in real-life figures and innovations into a mix that just as readily includes technology that borders on steampunk. A bit cozier, perhaps, than Young Sherlock, but sometimes that's the perfect vibe. Stream Murdoch Mysteries on Tubi. Murdoch Mysteries (2008 – ) at Tubi Learn More Learn More at Tubi A Thousand Blows (2025 – ) A spiritual follow-up to Peaky Blinders from that show's creator, this one goes back a bit further, to the 1880s, during which an all-female crime syndicate is running London's East End. True story! Erin Doherty stars as Mary Carr, leader of the Forty Elephants crew, specializing in shoplifting and confidence schemes. In A Thousand Blows, Mary and her gang come up against Stephen Graham's Henry "Sugar" Goodson (another real-world antihero), running an illicit bare-knuckle boxing organization. Coming between them is Hezekiah Moscow (Malachi Kirby), a recently arrived Jamaican immigrant who introduces us to this gritty world and its competing factions. Stream A Thousand Blows on Hulu. A Thousand Blows (2025 – ) at Hulu Learn More Learn More at Hulu Vienna Blood (2019 – 2024) Vienna Blood creator and writer Steve Thompson was a screenwriter for the Benedict Cumberbatch Sherlock series, as well as for the Young Sherlock series in question, so it perhaps makes perfect sense that this Edwardian-era crime procedural has Holmes in its DNA. Matthew Beard plays Doctor Max Liebermann, a student of Sigmund Freud who's recruited, early on, by police detective Oskar Reinhardt (Jürgen Maurer) to offer up some psychological insight to the investigation of several grisly murders. Liebermann makes brilliant deductions about character traits just as Holmes does with physical evidence, just with a bit more action and serial murder. Stream Vienna Blood on PBS Passport or buy it from Prime Video. Vienna Blood (2019 – 2024) at Prime Video Learn More Learn More at Prime Video Death Comes to Pemberley (2013) This isn't a sexy, action-packed update to Pride and Prejudice, but puts a bit of a spin on the source genre much as Young Sherlock does. Adapted from the novel by P. D. James, one of the 20th century's most accomplished crime novelists, Pemberley finds us several years after the events of the Austen novel. Darcy (Matthew Rhys) and Lizzie (Anna Maxwell Martin) remain contentedly, if not always blissfully, married, and have arranged one of those balls for which Pemberley is famous. On the way there, Lizzie's sister and her husband George Wickham are traveling with Captain Denny. Wickham and Denny have a fight, disappear into the woods, and Denny turns up dead. Lizzie doesn't have time to get bored in her giant house—not when there's a murder to solve. Stream Death Comes to Pemberley on PBS Passport or buy it from Prime Video. Death Comes to Pemberley (2013) at Prime Video Learn More Learn More at Prime Video Perry Mason (2020 – 2022) Speaking of Matthew Rhys, there's this addictive odd duck of a show that takes the Perry Mason of print, film, and television, and places him in a dark and gritty Depression-era prequel. Rhys is fabulous, naturally, as a brilliant but hard-living defense lawyer, going through a divorce while still facing trauma from the Great War. He's hired to investigate the case of a kidnapped and mutilated child, one which ends up having ties to crooked cops, local business leaders, and politicians in 1932 LA. Juliet Rylance co-stars as no-nonsense legal secretary Della Street and Tatiana Maslany as a creepy evangelist. Stream Perry Mason on HBO Max. Perry Mason (2020 – 2022) at HBO Max Learn More Learn More at HBO Max Monsieur Spade (2024) An original drama from Scott Frank (The Queen's Gambit) and Tom Fontana (Homicide, Oz), Monsieur Spade finds Hammett's Sam Spade, of The Maltese Falcon fame, living a quiet life in retirement in the South of France. It's all going well for the rumpled former detective—until six nuns are brutally murdered at a nearby convent, the same convent that's been home to Sam's ward for some time. Naturally, he finds his past has caught up with him, and is forced to surrender his idyllic life in order to help uncover the complex mystery that endangers his (very few) loved ones. Clive Owen is great as the rumpled, emphysemic detective, and the story feels like a fitting sequel to the original novel. Stream Monsieur Spade on Prime Video and AMC+. Monsieur Spade (2024) at Prime Video Learn More Learn More at Prime Video The Gentlemen (2024 – ) Theo James plays army officer and Eddie Horniman (a name mentioned as often as possible), heir to the Horniman estate (there it is again) who, upon the death of his father, is named the Duke of Halstead. He learns that dad was tied to various criminal enterprises, and that his scouse brother is millions of pounds in debt to a drug dealer. What else is the dapper, military-trained Duke to do but learn to navigate the violent underworld while looking cool? Stream The Gentlemen on Netflix. The Gentlemen (2024 – ) at Netflix Learn More Learn More at Netflix Sherlock & Daughter (2025 – ) Even if the setup is removed from anything in the Doyle canon, this CW production offers up, probably, the most lit-accurate Holmes in the form of David Thewlis. He's broody, persnickety, and emotionally distant, which makes for all the more effective a contrast when Amelia Rojas (Blu Hunt) shows up on his doorstep following the death of her mother and a harrowing journey from California. With the real possibility that Sherlock is her father, she teams up with him to investigate an international criminal cartel and, hopefully, to find out what happened to her mother. The clever Amelia quickly takes the place of the missing Watson, though the show doesn't shy away from the challenges an Indigenous American young woman would face in Victorian London. Stream Sherlock & Daughter on HBO Max. Sherlock & Daughter (2025 – ) at HBO Max Learn More Learn More at HBO Max View the full article
-
Microloan investing involves providing small loans to entrepreneurs who may not qualify for traditional financing. Typically ranging from $5,000 to $50,000, these loans enable business growth and development. Borrowers submit online applications, and you can choose whom to invest in based on their credit profiles. Interest rates vary depending on the perceived risk. Comprehending this process is vital, as it not just affects your investment returns but also influences communities in significant ways. What comes next in this process? Key Takeaways Microloan investing involves lending small amounts, typically from $5,000 to $50,000, to support entrepreneurs who cannot access traditional financing. Investors can select borrowers based on credit profiles, with minimum investments as low as $25 for portfolio diversification. Interest rates for microloans can range from 7.99% to 35.99%, depending on borrower creditworthiness, with some platforms offering interest-free options. The application process is less stringent than traditional loans, allowing borrowers with lower credit scores to qualify and access funds quickly. Microloans contribute to economic empowerment by promoting financial inclusion and supporting job creation within communities. Understanding Microloan Investing Microloan investing is an increasingly popular option for individuals looking to support entrepreneurs and small businesses that struggle to secure traditional financing. This form of investing typically involves providing small loans, ranging from $5,000 to $50,000, often facilitated through peer-to-peer lending platforms. As an investor, you can choose specific borrowers based on their credit profiles, with minimum investment requirements sometimes as low as $25. Interest rates on microloans vary considerably, typically from 7.99% for well-rated borrowers to as high as 35.99% for riskier ones, presenting potential returns. Some platforms, like Kiva, allow you to invest in microloans with no interest, while others charge service fees, impacting your overall returns. Although microloan investing offers diversification within your investment portfolio, it’s crucial to understand the risks involved, including borrower defaults and fluctuating interest rates based on individual creditworthiness. How Microloans Function When entrepreneurs seek funding to launch or expand their businesses, they often turn to microloans as a viable solution. Microloans typically range from $5,000 to $50,000, offering an alternative for those who may not qualify for traditional financing. These loans usually have repayment terms of six months to seven years, with interest rates between 8% and 13%, particularly for SBA loans. Nonprofit organizations and community lenders often distribute microloans, providing further support services like business training. The application process is typically less stringent than for traditional loans, allowing borrowers with lower credit scores to qualify. You may need to provide collateral or a personal guarantee. Furthermore, peer lending platforms and p2p lending options have emerged, enabling individuals to invest directly in microloans. The funding process can take anywhere from a few days to several weeks, depending on the lender and required documentation. Benefits of Microloan Investing Microloan investing offers you a chance to diversify your investment portfolio as well as supporting small businesses in underserved areas. By backing these entrepreneurs, you not merely contribute to social impact and empowerment but additionally have the potential for higher returns than traditional investments. Engaging in microloans can improve your financial strategy as you make a meaningful difference in communities that need it most. Diversification of Investment Portfolio Investing in microloans offers a unique opportunity to diversify your investment portfolio, allowing you to engage in small loans that support entrepreneurs in underserved markets. By utilizing a peer to peer loan platform, you can participate in loan investing during minimizing risks. Here are some benefits to evaluate: Risk Mitigation: Spread your capital across various borrowers to reduce the impact of individual loan defaults. Higher Returns: Average interest rates range from 7.99% to 35.99%, often exceeding traditional savings accounts. Tailored Investments: Choose borrowers based on specific criteria, including business type and creditworthiness. Support for Entrepreneurs: Contribute to economic development by funding businesses in need, improving community growth. Engaging with p2p lenders can effectively improve your investment strategy. Social Impact and Empowerment Engaging in microloan investing not merely improves your investment portfolio but furthermore contributes greatly to social impact and empowerment. By supporting small businesses and entrepreneurs, especially women and minorities in underserved communities, you help provide access to capital that traditional lenders often deny. Through peer lending and p2p lending platforms, you enable borrowers to launch or expand their businesses, nurturing job creation and stronger local economies. In addition, many peer to peer loan lenders boost this impact by offering financial education, increasing borrowers’ chances of success. Programs like Grameen have demonstrated that microloans can reduce poverty and raise living standards globally. In the end, your investment not only yields financial returns but also promotes meaningful social change. Potential for Higher Returns Although many traditional investments offer modest returns, the potential for higher yields in microloan investing can be quite appealing. With peer-to-peer (p to p) lending, you can achieve impressive returns, often ranging from 7.99% to 35.99%, based on the borrower’s creditworthiness. Here are some key benefits to contemplate: Diversification: Spread your investments across multiple borrowers to mitigate risk. Higher Average Returns: Microloans often outperform traditional fixed-income investments, enhancing cash flow. Social Impact: Support underserved communities during earning financial returns. Cost-Benefit: Even though service fees exist, the potential returns frequently outweigh these costs for knowledgeable investors. These factors make microloan investing a compelling option for those seeking better financial opportunities. Risks Associated With Microloan Investing When you invest in microloans, you face several risks that could impact your returns. High default rates are common, as many borrowers lack traditional credit histories, making it harder to predict repayment. Furthermore, interest rates vary widely based on creditworthiness, adding another layer of uncertainty to your investment’s potential performance. Default Risk Factors Default risk factors in microloan investing can greatly impact the financial outcomes for investors, especially given the unique challenges associated with this type of lending. Comprehending these risks is essential before you commit your funds. Here are some key factors to take into account: Limited Credit Histories: Many borrowers lack extensive credit backgrounds, making it tough to gauge their reliability. Economic Conditions: Local economic instability can lead to higher default rates, affecting repayment. Lack of Collateral: Microloans often have no collateral, relying solely on the borrower’s business potential. Macroeconomic Factors: Issues like political unrest or natural disasters can further complicate repayment scenarios. Being aware of these factors helps you make informed decisions in microloan investing. Interest Rate Variability Interest rate variability plays a crucial role in microloan investing, impacting both the cost of borrowing for individuals and the potential returns for investors. Rates can range from 5.99% to 35.99%, depending on the borrower’s creditworthiness. Higher rates typically apply to riskier borrowers, potentially leading to greater returns but additionally increasing default risks. Microloan companies often add fees that further inflate borrowing costs, affecting repayment capabilities. Here’s a summary of interest rate factors: Factor Details Interest Rate Range 5.99% – 35.99% Riskier Borrowers Higher interest, higher returns Fees Added Increases overall loan cost Credit Score Limitations Other risk factors matter Default Rate Concerns Poor recovery for lenders The Microlending Process The microlending process plays a crucial role in connecting borrowers, often from developing countries, with lenders through digital peer-to-peer platforms. This framework facilitates small loans typically ranging from $5,000 to $50,000, helping individuals build businesses and improve their lives. Here’s how it works: Digital Assessment: Borrowers undergo a creditworthiness assessment that considers factors like repayment history and homeownership, rather than relying solely on traditional credit scores. Loan Application: Applicants submit their loan requests through an online platform, detailing the purpose and amount needed. Funding: Once approved, lenders can fund these loans, often pooling their resources with other investors to meet the loan amount. Repayment: Borrowers repay the loans over a set period, typically six to seven years, allowing for gradual financial recovery. This structured approach has surged, especially during the COVID-19 pandemic, as many sought financial support amid economic uncertainty. Peer-to-Peer Lending Platforms Peer-to-peer (P2P) lending platforms offer an innovative way for you to invest in microloans by connecting you directly with borrowers, eliminating traditional banking intermediaries. Although these platforms provide opportunities for higher returns and enable you to support small businesses, they likewise carry risks, such as borrower defaults that can lead to financial losses. It’s crucial to weigh the benefits against these potential risks, ensuring you make informed investment decisions. P2P Lending Benefits How can you benefit from peer-to-peer (P2P) lending platforms? By connecting directly with borrowers, you can reveal several advantages that traditional banking may not offer. Here are four key benefits: Higher Returns: Interest rates typically range from 5.99% to 35.99%, allowing your investments to potentially outperform traditional fixed-income options. Low Minimum Investments: Start investing with amounts as low as $25, making it easier to diversify your portfolio. Informed Decisions: Access detailed borrower profiles and credit assessments to evaluate risks and returns effectively. Increased Funding Availability: P2P lending has expanded access to credit, especially in underserved markets, enhancing opportunities for both borrowers and investors. These benefits make P2P lending an attractive option for those looking to invest in microloans. Investment Risks Investing in peer-to-peer lending platforms can offer attractive returns, but it likewise comes with significant risks that you need to understand. One major risk is borrower defaults, which can leave you with little or no recovery, especially if the borrower fails to repay. Interest rates can vary greatly, from 7.99% for strong borrowers to 35.99% for riskier ones, affecting your potential returns. Moreover, service fees from the platforms can diminish your overall profits, so consider these costs carefully. There’s no guarantee of principal repayment, making it crucial to evaluate borrower creditworthiness thoroughly. Finally, you typically lack direct control over borrower selection, which can result in less transparency regarding their financial profiles. Types of Microloans Available Microloans come in various forms, each customized to meet the unique needs of borrowers. Comprehending these types can help you identify which option suits your financial goals best. Here are four common types of microloans: SBA Microloans: Offered by the U.S. Small Business Administration, these loans range from $500 to $50,000, with an average amount around $13,000. Interest rates are typically between 8% and 13%, and repayment terms can extend up to six years. USDA Microloans: Provided through the Farm Service Agency, these loans assist small to mid-sized farms, allowing for a combined limit of $100,000. Peer-to-Peer Loans: Platforms like Kiva offer loans from $1,000 to $15,000, often with zero interest and terms of up to 36 months. Nonprofit Microloans: Organizations like Grameen America focus on specific demographics, offering loans from $500 to $2,500, primarily to women entrepreneurs. Key Players in the Microlending Space The microlending space is populated by a variety of key players, each contributing to the accessibility and growth of small-scale financing. Nonprofit organizations, like Grameen Bank, which pioneered microlending in 1976, play an essential role by providing loans to entrepreneurs in need. Peer-to-peer lending platforms, such as Kiva and Prosper, allow individuals to lend directly to borrowers, helping small businesses that struggle to secure traditional financing. Government agencies, like the Small Business Administration (SBA), offer microloans through approved intermediaries, with average amounts around $13,000 and maximums reaching $50,000. Community Development Financial Institutions (CDFIs) focus on underserved communities, offering flexible loans to support minority and low-income entrepreneurs. Furthermore, notable microlenders like LiftFund and Justine Petersen provide customized microloan products with varying interest rates and repayment terms, addressing the diverse needs of small business owners in different sectors. Evaluating Microloan Investment Opportunities When exploring opportunities in microloan investing, it’s important to understand how the environment operates and what factors influence potential returns. You should consider the following key aspects: Loan Amounts: Microloans usually range from $25 to $50,000, making it crucial to match your investment size with your risk tolerance. Interest Rates: Expect rates between 5.99% and 35.99%, depending on borrower creditworthiness and platform policies; higher rates often reflect greater risk. Borrower Profiles: Review detailed borrower information provided by platforms to assess their creditworthiness, including repayment history and business plans. Social Impact: Many microloans support underrepresented entrepreneurs, which can improve your portfolio during promoting local economic development. Impact of Microloan Investing on Communities Investing in microloans can have a profound impact on underserved communities by providing essential capital that many small businesses desperately need. When you support microloan initiatives, you’re helping to create jobs and stimulate economic development in areas lacking traditional financial services. Research shows borrowers can see income increases of up to 30% within a year, greatly improving their quality of life. Women entrepreneurs, often sidelined by conventional financing, benefit immensely from these investments, especially through programs like Grameen America, which boasts repayment rates exceeding 90%. Additionally, microloan investments bolster community resilience by cultivating local businesses that support entire networks of suppliers and employees. By diversifying funding sources, communities can reduce their reliance on large financial institutions and promote more sustainable economic ecosystems. In the end, your investment in microloans can lead to broader economic empowerment and stability for those who need it most. Alternatives to Microloan Investing As microloan investing is a popular choice for supporting small businesses, several alternatives offer different avenues for individuals looking to make impactful investments. Here are four options you might consider: Peer-to-Peer (P2P) Lending: Platforms like LendingClub and Prosper let you fund personal loans directly to borrowers, often with higher potential returns but increased risk. Crowdfunding: Websites such as Kickstarter and Indiegogo enable you to support innovative projects in exchange for products or equity, focusing on entrepreneurship without traditional loan structures. Community Development Financial Institutions (CDFIs): These organizations provide investment opportunities in underserved areas, promoting economic growth as they offer competitive returns. Real Estate Crowdfunding: This allows you to pool resources for property investments, typically featuring lower minimum investment requirements compared to traditional real estate ventures. Exploring these alternatives can help you diversify your investment portfolio and align it with your financial goals. Steps to Get Started With Microloan Investing Starting your expedition into microloan investing requires careful consideration and research to guarantee it aligns with your financial objectives. Follow these steps to get started effectively: Choose a Microlending Platform: Research platforms like Kiva or Prosper that suit your goals. You can begin investing with as little as $25. Review Borrower Profiles: Assess borrower profiles and loan requests to gauge creditworthiness, focusing on business type and financial history. Diversify Your Investments: Mitigate risks by funding multiple microloans across various borrowers and industries. Understand Fees and Rates: Familiarize yourself with the platform’s fees and interest rates, as they can affect your returns. Monitor Your Investments: Regularly track repayment progress and reinvest recovered funds into new loans. Step Action Select a Platform Research and sign up Assess Borrowers Review profiles and loan requests Diversify Investments Fund multiple loans Frequently Asked Questions Are Micro Loans a Good Investment? Microloans can be a worthwhile investment, offering potential returns that often exceed those of traditional fixed-income options. With interest rates ranging from 7.99% to 35.99%, you can diversify your portfolio during supporting underserved communities. Nevertheless, you should be aware of the risks, like borrower defaults and platform fees, which can affect your returns. Evaluating borrower creditworthiness and comprehending platform policies is vital before committing your funds to microloan investments. What Are the Cons of Micro Loans? Microloans can present several drawbacks. You might face higher interest rates, typically between 8% and 13%, which can strain finances. Loan amounts are often capped at $50,000, potentially insufficient for larger projects. The repayment terms are short, from six months to six years, adding pressure to repay quickly. Furthermore, strict eligibility criteria may lead to disappointment, and the funding process can take longer than expected, delaying urgent needs. How Does a Micro Loan Work? A microloan works by providing small amounts of capital, typically between $5,000 and $50,000, to entrepreneurs and small businesses. You’ll find the application process requires fewer documents than traditional loans, making it accessible. Repayment terms usually range from six months to seven years, with interest rates between 8% and 13%. Microlenders include nonprofits, peer-to-peer platforms, and government programs. These loans can fund working capital, inventory, or equipment purchases. What Is the Interest Rate on a Micro Loan? Interest rates on microloans typically range from 8% to 13% for loans through the Small Business Administration, but they can vary based on the borrower’s creditworthiness. Peer-to-peer lending platforms may have rates as high as 35.99% for riskier borrowers. Nonprofit microlenders often offer competitive rates aimed at supporting underserved communities. Factors like loan amount, repayment term, and the lender’s policies likewise influence the interest rates you might encounter. Conclusion In conclusion, microloan investing serves as a viable option for funding small businesses during promoting economic growth in underserved communities. By comprehending the mechanics, benefits, and risks involved, you can make informed decisions about your investments. The microlending process allows you to evaluate borrowers based on their credit profiles, ensuring that your contributions support meaningful ventures. If you’re interested in making a difference as well as potentially earning returns, exploring microloan investing could be a worthwhile endeavor. Image via Google Gemini This article, "What Is Micro Loan Investing and How Does It Work?" was first published on Small Business Trends View the full article
-
Search under way for two crew members after US F-15E brought downView the full article
-
American healthcare faces a persistent paradox: We have extraordinary medical technology, yet patients often spend years navigating a system that treats symptoms before identifying the underlying cause of disease. This dynamic is especially pronounced for children with neurological conditions such as epilepsy, developmental delay, and intellectual disability. Many families endure years of hospitalizations, emergency room visits, specialist referrals, and inconclusive tests before receiving a definitive diagnosis. Clinicians often refer to this prolonged journey as the “diagnostic odyssey.” It is emotionally draining for families and deeply frustrating for physicians trying to guide care. It is also extraordinarily expensive. When the root cause of a condition remains unclear, care tends to become episodic and reactive. Children cycle through emergency departments, hospital stays, and repeated testing as clinicians attempt to manage symptoms without the benefit of a clear diagnosis. A TOOL THAT ALREADY EXISTS What makes this challenge particularly striking is that healthcare already has a powerful tool to help solve it. Genomic sequencing, including exome and genome sequencing, is that tool. It is like reading the entire instruction manual for a living thing by figuring out the exact order of the chemical letters that make up its DNA. It enables clinicians to analyze thousands of genes simultaneously to potentially identify genetic causes of disease. Over the past decade, these technologies have advanced dramatically. Testing is faster, more accurate, and more widely available than ever before. Clinical guidelines increasingly recommend genomic sequencing as a first-tier test for many children with neurological symptoms. Yet in practice, genomic testing is still often ordered only after years of inconclusive testing and ineffective treatment. In other words, the technology exists—but it is not consistently used early enough in the care journey to realize its full potential. THE HIDDEN COST OF DELAYED DIAGNOSIS Recent real-world evidence illustrates what happens when genomic insights are introduced earlier. In an analysis examining healthcare utilization among children with neurological disorders, our researchers found that overall healthcare costs declined significantly in the year following genomic sequencing. For children with epilepsy, total healthcare costs dropped by as much as 61%, representing nearly $80,000 in average savings per child annually. These savings were not the result of reduced care. Instead, they reflected a shift in how care was delivered. Hospitalizations and emergency room visits declined dramatically, while outpatient visits and medication management increased modestly. In other words, care moved away from expensive acute interventions and toward more targeted, proactive management. This is precisely the kind of shift health systems aim to achieve—delivering the right care earlier, before conditions escalate into costly medical crises. WHY MEDICAID HAS THE MOST TO GAIN The implications of this shift are particularly significant for Medicaid. Children with complex neurological conditions often rely heavily on publicly-funded healthcare programs. When diagnoses are delayed, repeated hospitalizations and emergency care can quickly drive up costs for state Medicaid systems. Earlier access to genomic testing can help change that trajectory. When clinicians understand the genetic drivers of disease sooner, they can guide treatment decisions more effectively, coordinate care more efficiently, and avoid unnecessary interventions. For states balancing limited Medicaid budgets, technologies that both improve outcomes and reduce avoidable spending deserve serious attention. THE REAL BARRIER IS IMPLEMENTATION The challenge today is no longer technological capability. Genomic sequencing is broadly available, and many clinicians who care for children with neurological symptoms—including pediatricians, neurologists, neonatologists, and physicians in intensive care settings—already have the ability to order these tests. Yet adoption remains uneven and underutilized across healthcare settings. A child treated at a large academic medical center may receive genomic testing early in the diagnostic process. Another child with the same symptoms seen in a community setting may wait years before testing is considered. Precision medicine should not depend on geography, referral pathways, or institutional resources. A SMARTER PATH FORWARD If we believe in a healthcare system that is serious about improving outcomes while managing costs, we must focus on ensuring that proven diagnostic tools are available wherever care is delivered. Genomic sequencing offers a rare alignment of incentives in modern healthcare. It can deliver answers faster for families, provide clinicians with more precise information to guide care, and help health systems allocate resources more efficiently. Opportunities like this are uncommon in medicine. When a technology improves care and reduces costs at the same time, the real question is not whether we can use it, but rather why it is not used broadly as standard of care. Linda Genen, MD, MPH is chief medical officer at GeneDx. View the full article
-
One of the major changes unleashed by the pandemic—and the accompanying spread of remote work—was the large migration of employees from major urban areas. With many jobs no longer anchored to city-based offices, people were free to move to almost anywhere else they preferred to live—often at lower costs to boot. But now, new survey data indicates that exodus has reversed course, with grim labor markets and tightening return-to-office (RTO) mandates causing employment-focused workers to head back to metropolises again. That finding was one of many big changes noted in the State of Global Hiring study by payroll and human resources service company Deel. It said that while the introduction and continuation of pandemic-era flexible work arrangements had allowed countless employees to move to places where they could work remotely, the accelerating trend of businesses tightening RTO rules has now drawn many workers back to big U.S. cities. “After a pandemic-era exodus from major cities, remote workers are gradually migrating back,” a Deel statement said about the geographic dispersal of employee that reached its peak in 2022. “In the U.S., workers are now as close to major cities like New York, Los Angeles, Chicago, Houston, and San Francisco as they were in 2021.” What’s driving that return to the nation’s urban centers? Continued evolution of labor markets is one factor, including the kinds of jobs that are now most abundantly available to workers in today’s tight employment environment. For example, Deel recorded a nearly 60 percent surge in the number of U.S. jobs for artificial intelligence model trainers. That means working in the tech sector, which has led the push for reinforced or full-week RTO. Lower but still strong growth rates were observed for other roles crucial to helping businesses pursue fast-developing activities in tech, finance, and other fields. Those more plentiful employment opportunities also tend to be office-based, drawing more candidates back to the cities that host them. “Post-pandemic, there is a slow crawl towards the urban centers that were always where top talent gravitated towards,” before the spread of Covid, said Deel economist Lauren Thomas in the statement. “That talent still lives in major metro areas, closer to big cities than they have in recent years, and they’re a hot commodity for companies.” At the same time, reduced job flexibility is also a likely reason for why workers are returning to big urban areas. Over the past 18 months, many U.S. employers have been increasing their RTO requirements for staff, with companies including Amazon, AT&T, and Home Depot requiring full-week presence. That tightening trend has also caused people to reconsider where they live and return to places where more or better employment opportunities are once again rooted. That marks a big change from earlier post-pandemic worker perspectives that led many people to demand job flexibility as a condition of remaining with an existing employer or joining a new company. Indeed, according to a January survey by MyPerfectResume, only 7 percent of workers “now say they would quit outright over a mandatory RTO policy, compared to 51 [percent] in January 2025.” Another 46 percent of respondents said they expected companies to further tighten their RTO mandates this year, and 44 percent said they believe at least half of U.S. companies will completely eliminate remote work by the start of 2027. Those shifts are making it harder for a growing number of people to continue living and working in the farther-flung places they’d rather be. “This dramatic decline signals a shift away from worker leverage toward a new phase of employer control—what many are calling the ‘Great Compliance,’” the MyPerfectResume report on the survey said. “Economic anxiety is reshaping employee behavior. What was once a deal-breaker is now a calculation rooted in job security, not preference.” —Bruce Crumley This article originally appeared on Fast Company’s sister website, Inc.com. Inc. is the voice of the American entrepreneur. We inspire, inform, and document the most fascinating people in business: the risk-takers, the innovators, and the ultra-driven go-getters that represent the most dynamic force in the American economy. View the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. Working off a single laptop screen gets limiting fast, especially when you’re juggling tabs, documents, and calls. The Mobile Pixels Duex Float 2 Pro is meant to solve that without turning your desk into a full setup, and it’s currently on sale for $279.99 on StackSocial, down from $389.99. This is a 16-inch portable monitor with a 2560x1600 resolution and a 16:10 aspect ratio, so you get more vertical space than a standard display, meaning you scroll less and see more at a glance when working on spreadsheets or editing documents. The 120Hz refresh rate also makes scrolling and general movement feel smoother than most portable monitors, which still tend to sit at 60Hz. Instead of sitting beside your laptop, this extra monitor can sit above it, which feels more natural if you’re used to a dual-monitor desk setup. You can still use it in other ways—as a standalone display with its built-in kickstand or flipped around for presentations. It also works across macOS, Windows, Linux, and even devices like the Nintendo Switch or newer Android phones with DeX support, so it’s flexible depending on how you plan to use it. Setup is simple: A single USB-C cable can handle both power and display, and it supports 65W pass-through charging, so you’re not sacrificing your laptop’s charging port. There’s also a mini-HDMI option if your device doesn’t support full USB-C display output. The screen itself is good for everyday work. It’s bright enough at 350 nits, has an anti-glare coating, and covers 100% of the sRGB color gamut, so colors look accurate. Built-in speakers are there if you need them, but like most portable monitors, they’re more for convenience than quality. The monitor itself weighs about 2.9 pounds, so it’s not the lightest thing to carry, but if you often work from different places and want more screen space without committing to a fixed setup, this is a practical way to stay productive without carrying a full monitor. View the full article
-
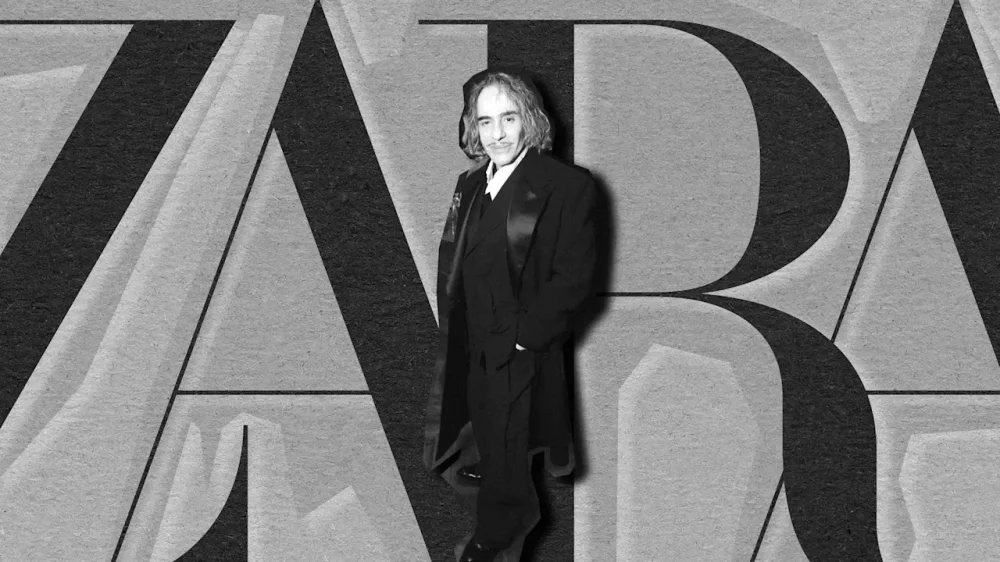
Fashion, it turns out, is a leading indicator. Long before mainstream business commentary catches up to a structural shift in the economy, the runway has usually already staged it. The announcement that John Galliano—arguably the greatest couturier alive—has signed a two-year creative partnership with Zara is one of those moments. It looks like fashion news. It is actually a signal about the future of value creation itself. The most surprising move in fashion in years To understand the shock value, a little context. Galliano’s career has been defined by the haute maison—Givenchy, his own label, Dior, and then a celebrated decade at Maison Margiela, where he orchestrated some of the most critically lauded runway shows of his generation. These institutions were the frame through which his genius was legitimated, distributed, and priced. The assumption was that a designer of his stature would always find his home inside another of fashion’s storied houses. Instead, he is going to Zara. Not as creative director. Not to relaunch a diffusion line. But as a “creative partner” who will deconstruct and “re-author” pieces from Zara’s own vast archive—taking the ephemera of fast fashion and subjecting it to a couture process. The first collection drops in September 2026. The fashion world’s reaction ranged from confusion to awe. But strategists should recognize it immediately: this is what the end of competitive advantage looks like in real time. Seasons are dead. So are categories. For most of its modern history, fashion has operated on a set of assumptions so stable they felt like laws of nature. There were four seasons. There was a clear hierarchy: haute couture at the apex, then ready-to-wear, then high street. There were coherent “looks”—a house had an aesthetic DNA, a consumer had a tribe, and the two found each other through ritual (the show, the magazine, the boutique). All of that is dissolving. Seasons have become continuous flows. TikTok-native consumers don’t cycle through trends on a quarterly basis—they layer them, mix them, reject the premise that a wardrobe needs a coherent sensibility at all. Streetwear bleeds into suiting. Archive Margiela sits alongside H&M finds. The “look” is now personal curation, not institutional affiliation. When taken as a gestalt, across countries and genres, we can see that this is a structural change in how value is created and captured in any industry organized around taste, knowledge, and creative authority. Fashion just got there first. The Carlota Perez lens: We are at a turning point Economic historian Carlota Perez describes how major technological revolutions move through two phases: an installation period of turbulence and speculation, followed by a deployment period in which the new technology’s possibilities are embedded into social and institutional life. First, a period of financialization and destruction of old social arrangements, giving way (hopefully) to a golden age of productivity and a broader distribution of gains. We are, right now, in the painful transition between those two phases and fashion, as a great cultural messenger, is reflecting the dislocations. What makes the current moment distinctive is how traditional advantages in fashion are eroding. For most of industrial history, scale was the primary source of competitive advantage. You built large factories, large distribution networks, large marketing operations—and that scale gave you a moat. The maison was a version of this logic applied to culture: you built a storied institution, a deep archive, a global distribution of prestige, and that infrastructure was the moat. Digital technologies are allowing us to go under, over, and around those moats. The capabilities that once required massive institutional infrastructure—design iteration, content production, trend analysis, personalized marketing—can increasingly be performed by small teams, or even individuals, armed with the right tools. The institutional premium is evaporating. Individual creative IP beats institutional legacy This is the second-order-effects story of Galliano partnering with Zara. What Zara is acquiring is not a house, not a team, not an archive. It is a sensibility—a singular, irreducible creative intelligence that cannot be replicated at scale, cannot be automated, and does not require a Grand Avenue address to be legitimate. We see this pattern everywhere, once you know to look for it. Solo founders building companies with AI leverage that previously required hundreds of employees. Independent consultants outcompeting large firms because their judgment and relationships are the product, not their headcount. Journalists, researchers, designers, and strategists detaching from legacy institutions and finding direct routes to audiences and clients. The unit of value creation is shrinking. What remains scarce—genuinely, durably scarce—is individual creative authority and trusted judgment. Galliano has that. The Zara deal is a stunningly vivid illustration of what happens when that kind of scarcity meets a platform with global reach. For Zara: A masterclass in transient advantage From Zara’s side, this is equally instructive. Under Inditex chair Marta Ortega Pérez, the brand has been on a deliberate campaign to escape the gravitational pull of the “fast fashion” label—a label that increasingly carries reputational, regulatory, and commercial risk. The strategy has involved a series of collaborations: Narciso Rodriguez, Samuel Ross, Stefano Pilati, Ludovic de Saint Sernin. Galliano is the clearest signal yet that Zara is not trying to occupy a lane. It is trying to make lanes irrelevant. This is a textbook execution of what I have called the transient competitive advantage: rather than trying to build and defend a durable position, Zara is stringing together a sequence of shorter-term advantages, each one redefining the competitive landscape before competitors can respond. Each collaboration is an arena entry—it resets the terms of competition before rivals have time to replicate the previous move. What executives should take from this The Galliano-Zara story is exotic enough to feel safely distant from the strategic challenges facing most organizations. It is not. Every industry has its version of the haute maison—institutions that assumed their prestige, their infrastructure, and their accumulated authority would insulate them from disruption. Law firms. Consultancies. Universities. Media organizations. Even hospitals and banks. These institutions are discovering that the individuals who carried their value—the partner with the client relationships, the professor whose ideas drive enrollment, the journalist whose byline drives subscriptions—are increasingly capable of detaching and finding direct routes to the markets they serve. The question for leaders is not whether this dynamic will reach their industry. It already has, or it will soon. The question is whether their organization can become a platform that talented individuals want to work through—rather than an institution that talented individuals feel the need to escape from. Galliano did not go to Zara because Zara is prestigious. He went because Zara offered him something the heritage houses could not: a direct, unmediated route to a global audience, on his own creative terms, without the burden of institutional expectation. That is the positioning smart organizations will have the courage to pursue. View the full article
-
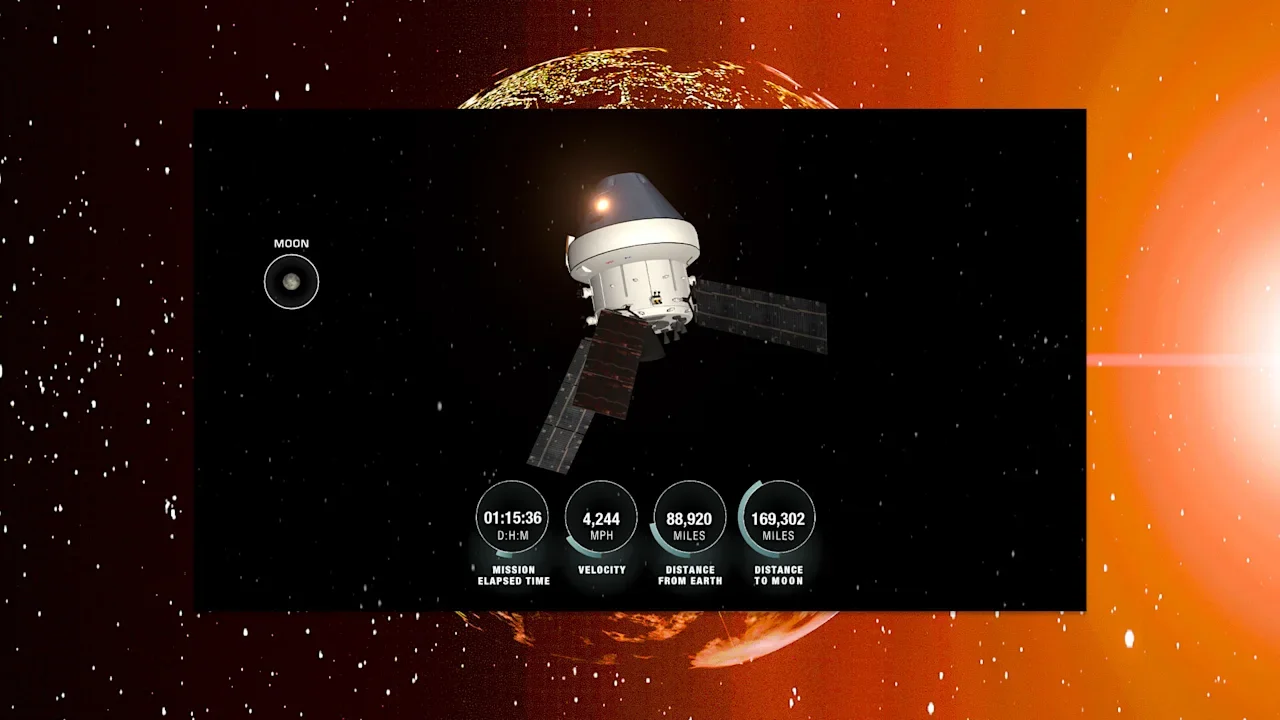
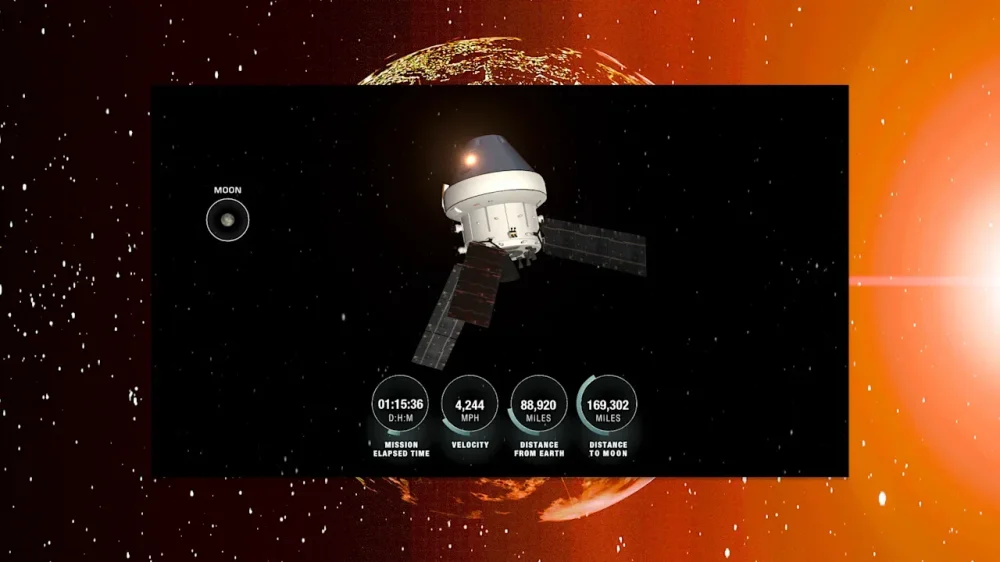
For the first time since 1972, astronauts are on their way into deep space as part of NASA’s Artemis II mission. The mission sees the Orion spacecraft carrying four astronauts to the moon, where they will orbit it, gathering data for future Artemis missions that will see humans touch down on the moon’s surface once again. But unlike in 1972, you don’t have to be a space agency to track the latest lunar mission. NASA has an interactive online tool that lets you see where the Orion spacecraft is and follow it as it performs its maneuvers through space. Here’s what you need to know. This NASA tool lets you track the Artemis II mission NASA has launched a site called the Artemis Real-time Orbit Website, which offers an interactive space map that lets you track the Orion spacecraft in real time. The tool shows three bodies: that of the Earth, the Moon, and the Orion spacecraft, and tracks where they are in relation to each other. It also visualizes the complete path the Orion is scheduled to follow on its 10-day mission. Artemis Real-time Orbit Website You can think of NASA’s Artemis Real-time Orbit Website as Google Maps in space. It offers tools to zoom in and out on any of the three heavenly bodies, and you can click and hold to drag the map’s axis. Another cool feature is “Spacecraft View,” a virtual camera that lets you see an interactive digital reconstruction of the Orion up close. You can also click on any of its four solar array wing (SAW) cameras, which are actually on the spacecraft, to see a digital reconstruction of what those cameras see. (If you want to see the real camera feeds, check out NASA’s Artemis II live mission coverage on YouTube.) How far is Orion from Earth and the Moon? In addition to being able to visibly track the Orion’s trajectory through space, the map also displays real-time data, including how long it has been since the mission commenced (about 1 day and 15 hours, as of the time of this writing), the velocity of the Orion (currently around 4,300 MPH) and its distance from earth and distance to the moon. Given the spacecraft’s speed, those distances change rapidly. As of the time of this writing, Orion’s distance from the Earth is 86,683 miles, and its distance to the Moon is 170,847 miles. But those numbers change by about 1 mile every second. When will Orion reach the Moon? While Orion will not actually land on the moon. It will fly by it. Currently, Orion’s lunar flyby is expected to take place on Monday, April 6, at which point NASA says “the astronauts will take high resolution photographs and provide their own observations of the lunar surface, including areas of the far side of the Moon never seen directly by humans.” After that flyby, the Orion spacecraft will begin making its journey back to Earth, where it is expected to splash down somewhere in the Pacific Ocean off the coast of San Diego, California, on April 10. Until then, you’ll be able to keep tracking the Orion on its journey across the heavens. View the full article
-
When you’re pondering starting a franchise, it’s essential to understand the key costs involved. Initial franchise fees can range from $20,000 to $50,000, allowing you to use the brand’s name and model. Real estate and renovation costs can vary widely, often exceeding $1 million. Ongoing royalty fees and marketing contributions likewise play a significant role in your budget. Knowing these expenses can help you prepare, but there’s much more to reflect upon before you make that commitment. Key Takeaways Initial franchise fees typically range from $20,000 to $50,000, granting rights to the franchise’s name and business model. Real estate acquisition costs can vary from $100,000 to over $1 million, depending on location and property size. Renovation and build-out expenses usually range from $50,000 to over $1 million, influenced by brand standards and local regulations. Ongoing royalty fees generally range from 5% to 9% of gross sales, along with additional advertising contributions of 2% to 5%. Legal, accounting, and insurance fees can range from $2,500 to $5,000, with state filing costs typically between $1,000 to $4,500. Initial Franchise Fees and Their Impact When considering a franchise opportunity, it’s essential to comprehend the impact of initial franchise fees, which typically range from $20,000 to $50,000. These fees grant you the rights to use the franchise’s name and business model, making them a significant part of the cost of franchise. Usually non-negotiable, these fees can vary based on market competition and brand strength. The franchise disclosure document (FDD) provides detailed information about these fees, including any additional costs you might incur. Some franchisors, especially in emerging markets, may offer incentives like deferred fees or discounts to attract franchisees. Grasping these initial fees is imperative for evaluating qsr franchise opportunities and planning your overall startup costs, which can exceed $1 million depending on various factors. Real Estate Acquisition and Renovation Costs When you’re considering starting a franchise, real estate acquisition and renovation costs are essential factors to evaluate. Depending on your location and property size, lease or purchase costs can range from $100,000 to over $1 million, whereas renovations may likewise add significant expenses. It’s important to factor in these costs, along with permits and licenses, to guarantee you’re financially prepared for this major aspect of your franchise expedition. Lease or Purchase Costs Lease or purchase costs are critical factors to contemplate when starting a franchise, as these expenses can greatly influence your initial investment. These costs can vary considerably, often ranging from $100,000 to over $1 million, depending on the franchise brand and geographic location. Your initial real estate expenses typically include down payments, commissions, and security deposits, which can increase your overall startup costs. It’s important to review the Franchise Disclosure Document (FDD) for detailed insights into real estate acquisition costs. This document helps you understand the financial commitments involved. Accurate estimation of these costs is vital for determining the overall feasibility and potential profitability of your franchise operation, ensuring you’re prepared for the financial expedition ahead. Renovation and Build-out Expenses Renovation and build-out expenses are vital considerations that can greatly affect your franchise’s startup budget. Real estate acquisition costs typically range from $100,000 to over $1 million, depending on location and property size. Renovation expenses can likewise vary widely, often falling between $50,000 to over $1 million to meet brand standards and local regulations. Initial costs may include down payments, commissions, and security deposits, all contributing to your overall investment. Budgeting for leasehold improvements is fundamental, as they customize your space for operational needs. Conducting thorough market research helps determine the appropriate real estate costs and renovation needs, greatly influencing your franchise’s financial viability. Expense Type Cost Range Notes Real Estate Acquisition $100,000 – $1 million Varies by location and size Renovation Expenses $50,000 – $1 million Depends on needed changes Initial Costs (Down Payment) Varies Includes commissions, deposits Leasehold Improvements Fundamental Customizes space for operations Location Selection Considerations Selecting the right location for your franchise is crucial, as it not only impacts your initial real estate acquisition costs but also affects your long-term profitability. Real estate acquisition costs can range from $100,000 to over $1 million, depending on market rates and property size. Moreover, you’ll need to factor in renovation costs, which can vary greatly, typically falling between $50,000 and over $1 million, based on necessary modifications to meet franchise standards and local regulations. Initial franchise fees, usually between $20,000 and $50,000, are part of your overall startup costs. Always refer to the Franchise Disclosure Document (FDD) for detailed information on initial purchase funds and ongoing working capital needs, especially regarding real estate and renovation costs. Professional Fees and Insurance Requirements When you’re starting a franchise, comprehending the professional fees and insurance requirements is vital to your budget and compliance. These costs can considerably impact your initial investment, so it’s important to plan accordingly. Here are some key expenses to keep in mind: Legal and accounting fees: $2,500 to $5,000 for compliance and documentation. Franchise Disclosure Document (FDD): $15,000 to $45,000, prepared by an experienced attorney. Insurance coverage: Costs vary for necessary policies like workers’ compensation and property. State filing and registration fees: $1,000 to $4,500, depending on licenses and trademarks. Financial statements: $2,500 to $5,000, prepared by a licensed CPA for FDD inclusion. Understanding these fees helps guarantee your franchise starts on solid ground. Ongoing Operating Costs and Royalties When you start a franchise, comprehending ongoing operating costs and royalty fees is crucial for your financial success. You’ll need to budget for recurring expenses like employee salaries, utilities, and supplies, whilst also accounting for royalty fees that typically range from 4% to 9% of your gross sales. Furthermore, setting aside funds for unexpected costs can help you maintain smooth operations and protect your profitability in the long run. Royalty Fee Structure Many aspiring franchisees may not fully understand the ongoing costs associated with running a franchise, particularly the royalty fee structure. Typically, these fees range from 5% to 9% of your gross sales, paid monthly to the franchisor. This revenue supports indispensable marketing and operational systems that benefit everyone in the franchise. Moreover, you might need to contribute another 2% to 5% for national or regional advertising. Here are some key points to take into account: Regular payments are important for franchise success. Late payments can lead to penalties or termination. Budgeting for royalties is critical for financial health. Monitoring sales guarantees you meet obligations. These fees enable access to brand support and marketing. Recurring Operating Expenses Comprehending recurring operating expenses is essential for anyone considering a franchise, as these costs directly impact your bottom line. Common expenses include employee salaries, utilities, maintenance, and overhead needed for daily operations. You’ll also pay royalty fees, typically 5% to 9% of gross sales, which support the franchisor’s brand and guidance. Furthermore, budget for marketing expenses, usually ranging from 2% to 5% of gross sales, to promote your franchise effectively. Expense Type Percentage of Gross Sales Royalty Fees 5% – 9% Marketing Fees 2% – 5% Employee Salaries Varies Utilities & Overhead Varies Keeping a close eye on these expenses is critical for your franchise’s profitability. Budgeting for Contingencies Budgeting for contingencies is crucial for franchisees, as unexpected expenses can arise at any time. You’ll need to prepare for ongoing costs and guarantee your franchise remains profitable. Here are key areas to reflect upon: Royalty fees: Typically 5% to 9% of gross sales, these fees are a constant expense. Emergency repairs: Setting aside funds for unexpected repairs is indispensable for operational stability. Employee salaries: Regular payroll can notably impact your cash flow. Utilities: Monthly utility bills can add up, so plan accordingly. Marketing contributions: Expect to allocate 2% to 5% of gross sales for brand promotion. Marketing and Advertising Expenses When you start a franchise, grasping marketing and advertising expenses is vital for your success. Typically, franchisees contribute 2% to 5% of gross sales to an advertising fund for brand improvement. Local marketing is equally important and can involve costs for online ads, print materials, and event sponsorships. Budgeting for marketing materials, like banners and promotional items, is critical to attract customers to your franchise. Furthermore, you’ll face extra advertising expenses to comply with franchisor guidelines and maintain brand standards. Expense Type Description National Fund Percentage of sales for brand marketing Local Marketing Online ads, print materials, event sponsorships Required Materials Banners, promotional items for visibility Financing Options for Franchise Startups How can you secure the funding needed to start your franchise? There are several financing options available to help you get started. Consider the following: SBA loans offer favorable terms and partial guarantees, making them accessible. Franchisor partnerships with lenders may provide customized financing programs. Alternative methods like personal savings, crowdfunding, or loans from family can likewise be viable, but make sure you have written agreements. Commercial bank loans typically require a strong credit history and a solid business plan, assessed through the “5 Cs”: Capacity, Capital, Collateral, Conditions, and Credit history. Online marketplaces like Boefly and Biz2Credit can simplify connecting with lenders, streamlining your funding process. Exploring these options can pave your way to successful franchise ownership. Understanding the Franchise Disclosure Document (FDD) The Franchise Disclosure Document (FDD) is a crucial tool for anyone considering investing in a franchise. It’s a legal requirement for franchisors to provide this document at least 14 days before you sign any agreements. The FDD outlines critical information about the franchise system, including Item 7, which details your estimated initial investment, such as franchise fees, real estate costs, and working capital needs. You’ll additionally find an extensive list of associated fees, including ongoing royalty fees, which can range from 4% to 9% of your gross sales. Legal and financial professionals recommend reviewing the FDD thoroughly to understand the franchise relationship, including potential earnings and risks, making it a critical part of your decision-making process. Frequently Asked Questions What Are the 4 P’s of Franchising? The 4 P’s of franchising are crucial for your franchise strategy. First, Product involves the goods or services you offer, focusing on quality and customer satisfaction. Next, Price means setting competitive prices that reflect your value as you ensure profitability. Then, Place highlights the importance of choosing strategic locations to maximize visibility. Finally, Promotion encompasses your marketing efforts, including advertising strategies to build brand awareness and drive sales effectively within your franchise network. Why Is It Only $10,000 to Open a Chick-Fil-A? It costs only $10,000 to open a Chick-fil-A since the company aims to lower the barrier to entry for franchisees. Unlike many franchises that require hefty initial investments, Chick-fil-A covers most startup costs like real estate and equipment, which can exceed $1 million elsewhere. Nevertheless, you’ll pay a 15% royalty on gross sales and must adhere to strict operational guidelines, ensuring brand consistency and success across all locations. What Is the 7 Day Rule for Franchise? The 7 Day Rule mandates that franchisors must provide you with a Franchise Disclosure Document (FDD) at least 14 days before you sign any franchise agreement or make a payment. This rule guarantees you have enough time to review important details, such as franchise fees and ongoing costs, helping you make an informed decision. If franchisors violate this rule, they can face legal consequences, protecting your investment and future business. What Does It Cost to Have a Franchise? Starting a franchise can cost you anywhere from $100,000 to $300,000. This range includes the initial franchise fee, typically between $20,000 and $50,000, plus costs for real estate, equipment, and inventory. You’ll likewise face ongoing expenses, like royalty fees of 5% to 9% of gross sales and marketing fees of 2% to 5%. It’s vital you budget for salaries, utilities, and maintenance to guarantee your franchise’s profitability. Conclusion Starting a franchise involves various significant costs, including initial fees, real estate, and ongoing royalties. To guarantee success, it’s vital to budget for professional fees, insurance, and marketing expenses. Comprehending your financing options and the Franchise Disclosure Document (FDD) is equally important in traversing the intricacies of franchise ownership. By thoroughly researching and planning for these expenses, you can make informed decisions that contribute to the long-term viability of your franchise venture. Image via Google Gemini This article, "Key Costs Involved in Starting a Franchise" was first published on Small Business Trends View the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. Smaller air conditioners struggle to keep up with open layouts, while larger ones can be loud and power-hungry. This LG 23,500 BTU air conditioner strikes the right balance, and it's currently on sale for $599.99 on StackSocial, which is a notable drop for a unit designed to cool spaces up to about 1,400 square feet. That capacity makes it suitable for large living rooms, open studio spaces, or offices where a smaller 8,000- or 12,000-BTU unit would run continuously and struggle to keep up. The design is still recognizably a window air conditioner, but it’s a big one, measuring about 30.7 by 17.7 by 26 inches and weighing 112 pounds, so installation should require two people and a sturdy window frame. Unlike traditional window units, this smart window AC uses LG’s Dual Inverter compressor, which adjusts its speed based on a room's temperature. In everyday use, that means the air conditioner can maintain a steady temperature rather than blasting cold air in short bursts. It delivers 23,500 BTU of cooling power across four cooling and fan speeds, with an Auto Cool setting that automatically adjusts them. You can also change the airflow direction with four-way adjustable vents, so it isn’t limited to the area directly in front of the unit. There’s also a 3-in-1 mode system: standard cooling for hot days, a fan mode to circulate air without running the compressor, and a dry mode that focuses on pulling moisture out of the air during humid weather. Through the LG ThinQ app, you can change settings remotely from your phone, and the system also works with Amazon Alexa and Google Assistant for voice commands—useful if the AC is installed in a hard-to-reach window or you want to turn it on before walking into the room. That said, one practical detail to check before buying is the power requirement—this model runs on a 230-volt outlet, which not every home window setup already has. Our Best Editor-Vetted Tech Deals Right Now Apple AirPods Pro 3 Noise Cancelling Heart Rate Wireless Earbuds — $199.00 (List Price $249.00) Apple iPad 11" 128GB A16 WiFi Tablet (Blue, 2025) — $299.00 (List Price $349.00) Samsung Galaxy Tab A11+ 128GB Wi-Fi 11" Tablet (Gray) — $202.00 (List Price $249.99) Apple Watch Series 11 (GPS, 42mm, S/M Black Sport Band) — $329.00 (List Price $399.00) Sony WH-1000XM5 — $298.00 (List Price $399.99) Deals are selected by our commerce team View the full article
-
In an increasingly interconnected world, America’s small businesses are facing new and complex challenges, particularly from foreign entities like the Chinese Communist Party (CCP). The House Committee on Small Business convened a crucial hearing today titled “Defending Main Street: Combating CCP Threats to America’s Small Businesses” to discuss these pressing issues and explore solutions tailored for small entrepreneurs. At the forefront of the discussion is the undeniable economic impact small businesses have on the U.S. economy. Small firms not only create jobs but also drive innovation, from breakthrough technologies to time-honored family businesses. Chairman Roger Williams emphasized this in his opening statement, stating that “small businesses play a vital role in driving America’s economy and reinforcing our national security.” However, the environment in which these businesses operate is fraught with risk. The CCP has made it a strategic goal to challenge the United States economically, often resorting to aggressive tactics that threaten American innovation. This creates a precarious situation for small business owners who have poured their resources into developing cutting-edge products and services. “Far too often, those innovations are stolen, replicated overseas, and sold at a lower cost,” Williams noted, highlighting the risk of losing market share and profitability. One of the most alarming aspects discussed at the hearing is the issue of foreign investment in American startups. While funding is essential for growth, investments from entities connected to foreign adversaries can expose sensitive technologies to vulnerabilities. The complexities of investment structures can obscure their origins, putting many entrepreneurs at risk without their knowledge. Small business owners must remain vigilant about who they accept capital from, understanding that the implications extend beyond just financial support. Moreover, supply chain reliance on China adds another layer of risk. Over the years, many small businesses have opted to outsource production, drawn by the allure of lower labor costs. Though this may have seemed efficient at the time, it has left American businesses, especially smaller ones, vulnerable to disruptions. “These challenges are not just economic; they are matters of national security,” Williams stated, underlining the heightened importance of reshoring or diversifying supply chains to mitigate risks. For small business owners, navigating these challenges requires a strategic approach. Participation in forums like today’s hearing not only provides insights but also illuminates actionable solutions tailored to small businesses. Recommendations from industry experts and experienced entrepreneurs will help shape policies aimed at equipping small firms with necessary tools for safeguarding their innovations and ensuring secure funding sources. The implications of inaction are significant. Williams cautioned, “If we fail to act, we risk losing not only our competitive edge, but also the ingenuity and entrepreneurial spirit that define our nation.” This stark warning emphasizes the crucial need for policy changes and support mechanisms to empower small entrepreneurs. In light of these complexities, small business owners are encouraged to engage in discussions around national security and economic resilience. Keeping abreast of legislative actions can inform decision-making processes, aiding in preventing potential loss of intellectual property and securing viable funding options. As these conversations continue to evolve, the focus remains clear: protecting American small businesses is vital for strengthening not just the economy, but the greater fabric of national security. To stay informed about the outcomes of today’s discussions and further developments, business owners can access the original hearing details here. The stakes have never been higher, and the roadmap for safeguarding American innovation lies in the hands of both legislators and proactive entrepreneurs. As small business owners plot their course ahead, grappling with these threats will be essential to not just survive, but thrive in today’s dynamic landscape. Image via Google Gemini This article, "House Committee Tackles CCP Threats to Protect Small Businesses" was first published on Small Business Trends View the full article
-
If you want to understand where AI-assisted parenting is headed, skip the research lab and look into a messy living room at 2 a.m. Some of the most revealing use cases are happening in the homes of AI engineers who have just become parents. Few environments are more demanding: high stakes, low sleep, a never-ending stream of split-second decisions with imperfect information. No mom or dad (us included) has patience for a tool that adds friction, noise, or guilt to the daily gauntlet of childcare. It is why parents—especially those who build products—are a valuable and overlooked source of AI product intelligence today. Consider Daanish Masood. When his young son was with him, he was on his own. He didn’t have a partner to share the day-to-day weight of early parenthood. What he did have was deep technical fluency and an urgent need for practical solutions. Daanish built his own AI, trained on child development research and philosophical texts as varied as Rumi and the Tao Te Ching. The result was “Robot,” an agent that could suggest age-appropriate outings, help with meal plans, and generate new chapters in an original epic space odyssey that became a fixture of their shared bedtime routine. The name, Robot, was intentional—a constant reminder that this was not a human being. It was a chance to talk about what it means to be human. Daanish and his son used Robot together, asking questions like how to dress up as a black hole for Halloween, enriching their interactions, not replacing them. When Robot got things wrong, those mistakes became lessons about the limits of technology, and the role of human judgment. In parenting, as in so many parts of life, optimization isn’t about how much AI can do for us, but how it helps us show up. AI TO SUPPORT PARENTS AND KIDS The same dynamic emerges in companies built by founders who experienced parenting struggles firsthand. Soon after Luis Garza became a father, he realized, like most parents, that he was flying blind during the most neurologically critical years of his child’s life. He built Kinedu, an AI-powered app that supports new parents in their role as their child’s first teacher. What began as a founder solving his own parenting challenge has grown into a global platform—raising more than $18 million and reaching 19 million users. Then there’s Carla Small, whose son struggled to read but didn’t receive specialized support until second grade. She built EarlyBird, a game-based assessment tool that uses AI to detect potential reading challenges like dyslexia before children enter school. Developed with cognitive neuroscientist Nadine Gaab, the platform reflects a simple but powerful insight: We start learning the foundations of language in utero. Now families and educators can identify reading challenges that traditional institutions often miss. Increasingly, policy is catching up. Screening legislation has recently changed in many U.S. states. Product followed lived experience, and policy followed. PROXIMATE EXPERTISE Taken together, these stories are strong signals from one especially instructive group: people close enough to both the technology and the problem. The social innovation world calls this “proximate expertise”—the unique perspective that comes from having lived inside the problem you’re trying to solve. Parents are navigating AI’s greatest promise (expanding human potential) alongside its deepest risk (eroding human agency and trust). They’re making those tradeoffs every day, with their favorite small human impacted by the outcome. Parents can bring this uniquely proximate expertise to the lab. They will question guilt-based nudging, resist information overload disguised as innovation, and think hard about unintended consequences—present and future. They can also illuminate what must remain unmistakably human in what they refuse to delegate: comfort, moral judgment, presence, and the relational work of raising a child. The hacks they develop in the middle of the night may be someone else’s product roadmap; their design constraints may be the policy guardrails we’ve been missing. Parenthood is humanity’s oldest operating system. It runs on minimal sleep, continuous improvisation, and an unrelenting real-time feedback loop: cry, adjust, repeat. Innovation under constraint at its best. Parents who also happen to be AI engineers, product designers, and founders can shape how we build, regulate, and deploy intelligent systems that are better for everyone. The best beta testers are putting their kids to bed. Hala Hanna is executive director of MIT Solve. Michael Feigelson is CEO of Van Leer Foundation. View the full article
-
In the world of tax law, truly “free” lunches are rare. Usually, a tax break in one area requires a sacrifice in another. However, if you know where to look, the tax code contains several freebies—legal provisions that allow you to increase wealth, generate income, and gift money without the IRS taking a single penny. Here are five of the most powerful financial freebies available to investors today. 1) The 0% capital gains rate Most investors assume that selling a winning stock always triggers a tax bill. However, for those in the lower income brackets (up to $50,400 for individuals or $100,800 for married couples in 2026), the long-term capital gains tax rate is exactly 0%. The Strategy: If you have a low-income year—perhaps due to early retirement before Social Security or required minimum distributions kick in—you can strategically sell appreciated securities without paying any federal tax. The proceeds can fund living expenses or replace the shares you just sold to capture a free stepped-up basis without having to die first. 2) The ‘Augusta Rule’ (rent your home for free) Named after the homeowners in Georgia who rent out their houses during the Masters golf tournament, Section 280A(g) of the tax code allows you to rent out your primary residence for up to 14 days per year without having to report a single dollar of that income to the IRS. The Strategy: Whether you live near a major sporting event, a film set, or a popular festival, you can pocket the rental income entirely tax-free. There are no income limits on this rule, and you don’t even need to report the income on your Form 1040. For high-income earners in high-tax states like California, this is a significant freebie that bypasses both federal and state taxes. 3) The $1,000 ‘Baby Seed’ money The newly enacted One Big Beautiful Bill Act has introduced a literal cash freebie for the next generation. For every child born between Jan. 1, 2025, and Dec. 31, 2028, the federal government will provide a $1,000 seed deposit into a The President Savings Account. The Strategy: While these accounts have long-term tax flaws, you should never turn down a government grant. Capture the $1,000 as soon as the portal opens in 2026. Let that government money compound, but pivot your own family contributions to a 529 plan for superior tax treatment. 4) The ‘Gap Year’ Roth conversion The most valuable freebie for retirees often occurs in the window between the end of a professional salary and the start of required minimum distributions, or RMDs, and Social Security. During these gap years, your taxable income may drop to its lowest level in decades. The Strategy: Use this low-income window to perform Roth conversions at a 0% or 10% effective tax rate. By filling up these lower tax brackets now, you are effectively prepaying your future tax bill at a massive discount. You eliminate future RMD pressure and ensure that every dollar of future growth in that Roth account is shielded from the IRS forever. It is one of the few times the tax code allows you to move money into a tax-free bucket at little or no cost. In most cases, this is a better deal than recognizing capital gains at 0%. 5) The qualified charitable distribution Is a qualified charitable distribution, or QCD, truly free? If you are charitably inclined and over age 70½, the answer is a resounding yes. Normally, taking money out of a traditional IRA is a taxable event. However, a QCD allows you to send up to $111,000 each year directly to a charity (in 2026). The Strategy: The money goes from your IRA to the charity without ever touching your bank account, meaning it is never counted as taxable income. This is a freebie because a lower adjusted gross income can help you avoid higher Medicare premiums, and it reduces the amount of your Social Security that is subject to tax. You are effectively spending your IRA money on your philanthropic goals while keeping the IRS entirely out of the transaction. Summary for investors The IRS rarely hands out gifts, but these five provisions are as close as it gets. Whether it is capturing $1,000 for a newborn or leveraging your gap years for a low-cost Roth conversion, the key is proactive timing. This article was provided to The Associated Press by Morningstar. For more personal finance content, go to https://www.morningstar.com/personal-finance. Sheryl Rowling, CPA, is an editorial director, financial advisor for Morningstar. Related Links $1,000 The President Accounts: Focus on the Financial Benefits, Not the Branding https://www.morningstar.com/personal-finance/1000-The President-accounts-focus-financial-benefits-not-branding Still Working in Retirement? Watch Out for These Social Security and Medicare Tax Traps https://www.morningstar.com/personal-finance/still-working-retirement-watch-out-these-social-security-medicare-tax-traps How Much Should You Allocate to Safer Assets? https://www.morningstar.com/portfolios/how-much-should-you-allocate-safer-assets —Sheryl Rowling of Morningstar View the full article
-
Mohammad Javad Zarif is first prominent regime figure to put forward detailed suggestions on what Tehran could acceptView the full article
-
Impulse, a sleek induction stove that began shipping to customers last year, advertises itself as “unlike any other induction stove ever made.” But that product is now at the center of a legal fight. Copper, another company making next-generation induction stoves, sued Impulse on Friday in federal court in Delaware for patent infringement. At the center of the dispute is a shared design choice: Both companies build stoves with batteries tucked inside, a feature that boosts performance, eases installation in homes without electrical upgrades, and doubles as energy storage to ease strain on the electric grid. It’s a novel idea, and one that Copper patented first. In a copy of the lawsuit obtained by Fast Company, Copper claims its founders began developing the technology as early as 2019. (The work spun out of R&D lab Otherlab, which received a U.S. Department of Energy grant in 2020 to push the idea further.) The company formally launched in 2022 and secured its first patent that March for “appliance level battery-based energy storage.” Two additional patents followed in 2024 and 2025, detailing versions of an induction stove with an integrated battery. The company has raised around $35 million in venture funding to date, according to PitchBook. Impulse Labs launched in 2022; it’s unclear when the company started work on its design, or how familiar it was with Copper’s work at that time. At launch, Impulse talked about the energy storage benefits of its design. “Effectively, we’re Trojan-horsing a small battery into people’s homes when the appliance goes in,” founder Sam D’Amico, a former Facebook engineer, told Fast Company in late 2022. (Impulse has raised $25 million in venture funding.) The upside for the electric grid is significant. The cost of batteries has dropped dramatically, but grid-scale storage is still slow to build, and it’s more efficient for storage to be located next to the point of use. Home batteries like the Tesla Powerwall are pricey and require permits and electricians to install. If a battery is built into a stove at a factory, installation is as simple as plugging in the appliance. At scale, the stoves can store excess renewable energy and later help the grid during peak demand. Impulse tried to patent the idea of a battery-embedded stove—with four attempts in 2024 and 2025—but the U.S. Patent and Trademark Office rejected the company’s applications, citing Copper’s existing patents. Now Copper’s patent infringement suit is asking for damages “in no event less than a reasonable royalty.” Copper CEO Sam Calisch insists that, despite the lawsuit, he wants to see its battery-integrated design spread across the industry. “Our goal is to eliminate barriers to electrification,” he tells Fast Company, pointing to Copper’s push to bring battery-integrated appliances into more homes by working with large appliance manufacturers that want to license the tech. But, he adds, that push depends on partners respecting its intellectual property. Fast Company has reached out to Impulse for comment and will update the story as we hear back. View the full article
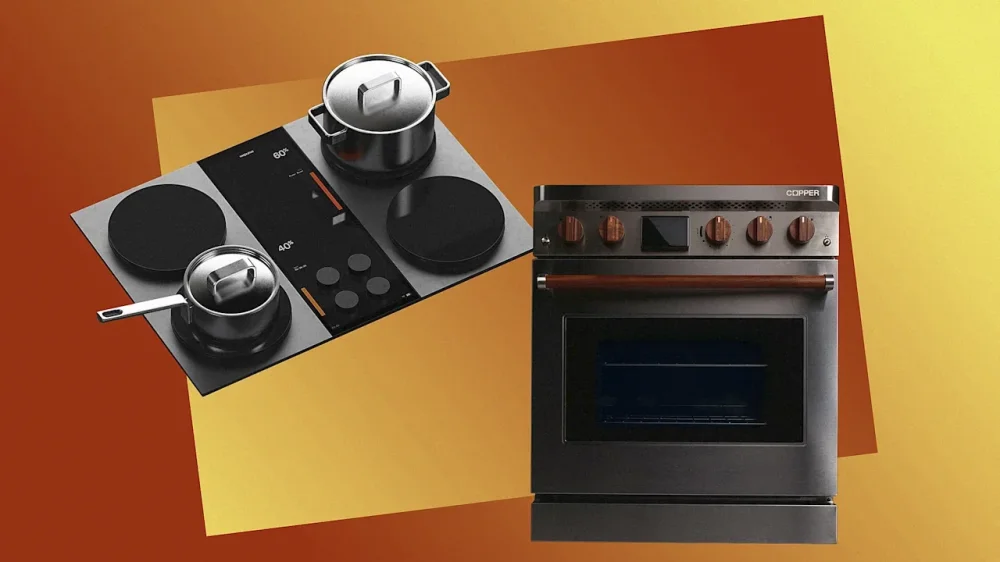
-
Layoffs rose sharply in March, and a quarter of these job losses were due to AI. Job cuts rose about 25% in March reaching 60,620 up from 48,307 cuts the month before. The new data comes from outplacement and executive coaching firm Challenger, Gray & Christmas, who released the report on Thursday. While cuts could be seen across industries, more than 52,000 tech jobs have been cut so far this year with 18,720 happening last month. Reductions took place at major technology companies like Meta, Oracle, Block, and more. However, the report explained that the number was driven up significantly by the workforce reduction at Dell Technologies (DELL), making the total the highest seen since 2023 in the technology sector. “Removing the wave of federal layoffs announced in February and March of last year, job cut announcements in 2026 are closely following the pattern of 2025, said Andy Challenger, chief revenue officer for Challenger, Gray & Christmas in the report. “Last year, it was Government, Retail, and Technology. This year, it’s Technology, Transportation, and Healthcare.” While the new report may fuel worries that AI is taking jobs, the loss in jobs is down about 78% from March 2025, when 275,240 cuts were made. Also, in the last week of March, weekly jobless claims actually approached a two-year low. In a response to the report, Rathin Sinha, a tech founder, CEO and president of America’s Job Exchange, explained the major takeaways in a post on LinkedIn. “Roles are not disappearing wholesale—but they are being redefined,” Sinha wrote. “In a world where AI can do the job, the role of humans is orchestration. Putting the things together—the system thinking. Not project management, but putting things together for a business to deliver on its unique value proposition,” the CEO continued. In the wake of job cuts and companies leaning harder on AI, the report urged employees to focus on upskilling and reskilling. In other words, becoming experts at integrating AI into workflows. It also noted that companies are prioritizing technology, even if it means a loss of jobs. “Companies are shifting budgets toward AI investments at the expense of jobs,” Challenger explained. “The actual replacing of roles can be seen in technology companies, where AI can replace coding functions. Other industries are testing the limits of this new technology, and while it can’t replace jobs completely, it is costing jobs,” he said. Next to the technology sector, transportation had the second-highest number of job losses, with 32,241, up a staggering 703% from the same period in 2025. View the full article
-
After Pam Bondi became U.S. attorney general last year, conservative influencers, online sleuths and others who wanted the government to disclose all it knew about Jeffrey Epstein thought they might have a champion in the Department of Justice. So did Jess Michaels, one of the legions of women who have said they were sexually assaulted by the late financier and convicted sex offender with a roster of powerful friends in business, politics and beyond. “I thought, ‘Well, maybe a woman stepping into this role will finally, finally get the truth,'” Michaels recalled Thursday, after President Donald The President announced Bondi was out of the nation’s top law enforcement job. “She had this opportunity to be a hero and to really do right by survivors of sexual violence and trafficking,” Michaels said, “and she chose not to.” The furor over the “Epstein files,” as the trove of investigative records came to be known, wasn’t the only controversy of Bondi’s tenure. But the arc — first raising expectations for a big reveal, then declaring there was nothing to see, and ultimately a forced, flawed document dump — was a stubbornly problematic storyline that ran through her time as attorney general. Bondi rejected criticism of her handling of the matter, and The President on Thursday praised her as “a Great American Patriot and a loyal friend.” Michaels and other Epstein victims watched it all with shaken trust that Bondi’s departure alone won’t likely rebuild. “This is not about a single person,” accuser Annie Farmer said Thursday. “It is about a government and judicial system that has repeatedly failed Epstein survivors.” Here’s a glance at Bondi’s part in the Epstein saga: February 2025: The binders Freshly confirmed as attorney general for a president who had suggested on the campaign trail that he’d open more government documents on Epstein, Bondi whetted appetites by declaring on Fox News that “you’re going to see some Epstein information released.” And when a host asked about “releasing “the list of Jeffrey Epstein’s clients” — a long-rumored, never-seen sex trafficking roster — she replied that it was “sitting on my desk right now.” A day later, conservative commentators and content creators were brought to the White House to get DOJ binders emblazoned with “The Epstein Files: Phase 1” and “Declassified.” The attempt to showcase transparency soon backfired, once it emerged that the contents largely were already public. Bondi demanded that the FBI give her “the full and complete Epstein files,” and she later said that she’d unearthed a “truckload” of previously withheld material and that “everything is going to come out to the public.” July 2025: The walkback After months of anticipation, the Justice Department said it wouldn’t release any more Epstein material. A court had sealed much of it to protect victims, and “only a fraction” would have come out if Epstein had gone to trial, the agency said in an unsigned memo. It added that authorities hadn’t found evidence that merited new charges or investigations and that “perpetuating unfounded theories about Epstein” wouldn’t help victims get justice. And, it said, there was no “client list.” As for Bondi’s prior comment that it was on her desk, officials said she had meant the overall case file. Conservative influencers, among others, blasted the turnabout and questioned Bondi’s capability. But The President stood by her, scolding a journalist for attempting to ask her a question about Epstein at a White House Cabinet meeting. The President had himself raised questions for some years after Epstein’s 2019 death in jail as the financier faced federal sex trafficking charges. After the Justice Department memo, however, the president suggested there was nothing more to say about Epstein and the country, including his own supporters, should simply move on. November 2025: The legislation Amid a drumbeat of disclosures that begin to exact consequences for some powerful people — particularly Andrew Mountbatten-Windsor, Britain’s former Prince Andrew — Congress passed legislation to force the Justice Department to disclose its investigative files on Epstein. The President signed it into law, casting the quest for Epstein information as a Democratic-led distraction from the Republican agenda. Meanwhile, at his urging, Bondi announced that the U.S. attorney in Manhattan would investigate Epstein’s ties to some of the Republican president’s political foes, including Democratic former President Bill Clinton. None has been accused of misconduct by Epstein’s accusers; nor has The President, another former Epstein friend. Both Clinton and The President have said they knew nothing about Epstein’s misconduct and cut ties with him many years ago. December 2025: The first batch At the statutory deadline for making the Epstein files public, the Justice Department released only some of them. While the records included some material the public hadn’t previously seen, including some candid photos of Clinton, the documents didn’t break major ground and included little about The President. The department said it was continuing to review other Epstein records to make sure that victims were protected. But Democrats cried cover-up, bill sponsor Rep. Thomas Massie, R-Ky., accused the Justice Department of breaking the law by missing the deadline and redacting too much, and some Epstein accusers also questioned the extensive redactions. January 2026: The big release The Justice Department began releasing a huge cache of additional Epstein documents, videos and photos, though others remained under wraps. The records pulled back a curtain on favor-trading and frank communications in a chummy elite that looked past Epstein’s 2008 guilty plea to solicitating prostitution from an underage girl in Florida. Some high-flying Epstein friends resigned or lost jobs in corporate America, academia, big law firms, the British, Slovakian and Norwegian governments and beyond. But the documents disclosed highly personal information about some victims while redacting the names of Epstein correspondents in, for example, emails that appeared to refer to the sexual abuse of underage girls. Gloria Allred, an attorney for numerous Epstein victims, said Thursday that Bondi betrayed them by failing to protect personal information in the files. “She has destroyed the trust in the DOJ that victims had a right to expect, and her termination may be the only type of justice that survivors will receive from the DOJ,” Allred said by email. February 2026: The hearing At a congressional hearing, a combative Bondi tried to quell the Epstein files controversy. She defended how the Justice Department dealt with it, lobbed personal insults at Democrats and lauded The President over, among other things, the performance of the stock market. Bondi said she was deeply sorry for what Epstein victims suffered. But she declined a request from Rep. Pramila Jayapal, D-Wash., to face and apologize to them for the Justice Department’s actions, and Bondi dismissed Massie’s critiques of the release of victims’ personal information. March 2026: The subpoena The House Committee on Oversight and Government Reform subpoenaed Bondi to answer questions on April 14 about the Justice Department’s handling of the Epstein investigation and file release. With five Republicans joining Democrats to support the subpoena, it reflected widespread discontent, including in the GOP base, over Bondi’s management of the matter. The future For now, Deputy Attorney General Todd Blanche will be the acting attorney general. Michaels, who traveled to the Capitol last year to press for the files’ release, wanted Bondi gone. But will Blanche do better? “We can only hope. But given that they worked together, I don’t have great expectations,” she said. The Associated Press generally does not identify people who say they have been sexually assaulted unless they come forward publicly, as Michaels has done. Robert Glassman, an attorney for a woman who testified as “Jane” in the 2021 criminal trial of Epstein confidante Ghislaine Maxwell, noted that agency leaders come and go. “For victims of sexual abuse, what matters is whether the institutions meant to protect them actually do their job,” he said. —Jennifer Peltz, Associated Press View the full article