Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
The livestream of a YouTube content creator talking about investments mysteriously appeared to take over a White House website, raising questions about whether the site was hacked. The livestream appeared for at least eight minutes late Thursday on whitehouse.gov/live, where the White House usually streams live video of the president speaking. It’s unclear if the website was breached or the video was linked accidentally by someone in the government. The White House said in a statement that it was “aware and looking into what happened.” The video that appeared on the government-run website featured some of a more than two-hour livestream from Matt Farley, who posts as @RealMattMoney, as he answered financial questions. Farley said in an email to The Associated Press on Friday that he had no idea what happened. “If I had known my stream was going to go super public like that I would be dressed a bit nicer and had a few more pointed topics! And it likely wouldn’t have been about personal finance,” Farley wrote. President Donald The President‘s administration and campaign have had a series of digital security breaches and challenges over the last year. In May, government officials began investigating after elected officials, business executives, and other prominent figures received text messages and phone calls from someone impersonating Susie Wiles, the Republican president’s chief of staff. Last year, Iran hacked into The President’s campaign. Sensitive internal documents were stolen and distributed, including a dossier on Vice President JD Vance, created before he was selected as The President’s running mate. —Michelle L. Price, Associated Press Associated Press writer Bill Barrow contributed to this report. View the full article
-
In a stark reminder of the ongoing challenges within the small business landscape, a recent indictment has shed light on fraudulent activities related to COVID-19 relief funds. Eleven individuals in Florida are facing serious charges for allegedly misappropriating more than $2 million through fraudulent applications for the Small Business Administration’s (SBA) Economic Injury Disaster Loan (EIDL) and Paycheck Protection Program (PPP). As small business owners continue to navigate their post-pandemic recovery, the implications of these actions continue to ripple through the community. These indictments come from the office of U.S. Attorney Gregory W. Kehoe, revealing a troubling scheme that took place between April 2020 and June 2021. The accused allegedly submitted multiple false EIDL and PPP applications, utilizing doctored financial documentation, including falsified tax forms from the IRS. Such fraudulent claims blatantly undermined the intent of the CARES Act, which was designed to provide crucial financial assistance to legitimate small businesses grappling with pandemic-related challenges. Each of the eleven indicted individuals, if convicted, could face up to 20 years in federal prison for their conspiracy and wire fraud charges. Alongside their potential incarceration, the government has initiated forfeiture proceedings for more than $2.2 million derived from these alleged offenses. An associate named Neil Bryant is also charged in a separate indictment for submitting a fraudulent EIDL application, facing similar penalties. For small business owners, this incident highlights a dual-edged sword. On one hand, the CARES Act and its associated programs offered a lifeline during an unprecedented health crisis, providing essential support to keep businesses afloat. The successful implementation and distribution of these funds helped many navigate through tough economic waters. However, incidents of fraud like the current case serve as a cautionary tale, stirring concern over the integrity of these relief funds and the measures in place to protect them. As the SBA continues to monitor and scrutinize applications more rigorously, legitimate small businesses should understand the heightened examination processes that could lead to delays. Owners must ensure that their applications are accurate and supported by legitimate documentation to avoid drawing unwanted attention from regulators. Experts suggest that the ongoing vigilance by federal agencies should also serve as a blueprint for small business owners to take proactive steps in safeguarding their own enterprises. Understanding the criteria and documentation required for relief programs is critical. Additionally, companies must rely on trustworthy advisors who can guide them through the complexities of federal programs. While some small business owners may find themselves daunted by regulatory scrutiny, understanding the rationale behind it can ease concerns. The increased emphasis on fraud prevention is aimed at ensuring that funds are directed to those who genuinely need them to recover and thrive in the aftermath of the pandemic. “The rising prevalence of fraudulent activity during this critical period should alert businesses to remain vigilant and informed,” noted a representative from the SBA Office of Inspector General. “It is our responsibility to ensure that aid reaches the intended recipients and that those attempting to misappropriate funds are held accountable.” As the narrative unfolds, it is essential for small business owners to stay informed about any changes in federal assistance programs. Keeping abreast of the latest news and leveraging trustworthy resources will help navigate the ongoing complexities of post-pandemic recovery. The recent indictments underscore the importance of transparency and accountability in federal funding. Small businesses need to advocate for themselves by ensuring their application practices adhere strictly to SBA guidelines. Proactive measures in documentation and compliance will not only help avoid fraud allegations but foster a more robust business environment for all. For more information about COVID-19 related fraud and how to report incidents, you can visit the Justice Department’s National Center for Disaster Fraud hotline at www.justice.gov/disaster-fraud/ncdf-disaster-complaint-form. Small business owners looking to stay informed on related investigative cases and updates can also sign up for SBA OIG email alerts for the latest news on fraud oversight efforts. This can help ensure that your business remains compliant and protected in these ever-evolving circumstances. Stay alert, stay compliant, and navigate the future of your small business with confidence. For further details, visit the original press release from the SBA. Image via Google Gemini This article, "Eleven Charged with Fraudulently Securing $2.3M in COVID Relief Funds" was first published on Small Business Trends View the full article
-
The government took stakes in a number of private companies during 2025, and is likely to continue making equity investments while Donald The President remains in office. Whether or not this is a wise long-term strategy is an ongoing debate with strong opinions on both sides. The practice represents a new industrial policy that’s meant to tie the executive branch of government closer to companies it considers essential to national security and economic prowess. The The President Administration hopes it’s a more robust approach than subsidy grants to rebuilding critical supply chains domestically, reducing reliance on China, and ensuring key industries remain under U.S. control. But it also puts the government in the venture capital business — which may not be a good fit for politicians and bureaucrats. “The government now perceives itself as a source of capital and the markets perceive them as a source of capital–it’s not going to stop,” said former (acting) White House Chief of Staff Mick Mulvaney on a recent episode of The Informed Board, a podcast from Skadden Arps. And it may not be easy for a private company to say no. “[A]ny business that either sells a lot of stuff to the federal government or gets a lot of subsidies from the federal government is going to be a target,” he added. “I think it’s extraordinarily dangerous and the reason I think it’s not going to go away is that regardless of the outcome, I think this is where the Republican Party is,” Mulvaney said, adding: “and it’s where the Democrat Party has wanted to be for a long time.” The U.S. government has taken equity shares in private companies before, but only in times of war or economic crisis, and never as a normal feature of industrial policy as the The President administration views it. The government took a minority stake in Chrysler in the early 1980s when the company faced bankruptcy. During the 2008 financial crisis the government took equity stakes in AIG, General Motors, Citigroup, Bank of America, and others. During the COVID pandemic the Treasury received equity warrants in airlines including Delta, United, American in exchange for payroll support. Commerce Secretary Howard Lutnick has suggested that the administration is considering expanding the practice of buying equity to include defense contractors. The U.S. and Intel The government’s biggest equity investment is the troubled chip maker Intel. The The President administration said in August it would take a 9.9% stake, using $8.9 billion of CHIPs and Science Act grant money that had already been earmarked for the company. Intel’s finance chief David Zinsner said the government’s investment was meant to incentivize Intel to keep majority control over its contract chip-fabrication business. The bigger picture is that the U.S. economy, including the defense industry, is increasingly reliant on the powerful chips used to train and run AI models, and the vast majority of those are made in Taiwan by TSMC. The U.S. could benefit greatly if Intel could fabricate equally advanced chips in the U.S. Taiwan is a potential geopolitical flash point because it’s a mere 85 miles away from China, and while the island has its own government, the Chinese government denies its sovereignty and claims it as its own. Other bets In July the Defense Department paid $400 million for a 15% stake in the rare earth minerals company MP Materials (MP), making the Pentagon the company’s largest shareholder. The deal includes a $150 million loan to help MP build a heavy rare earth separation plant in California. The government received a “golden share” in Nippon Steel in exchange for approving the Japanese company’s proposed merger of Pittsburgh-based U.S. Steel Corporation. The golden share doesn’t represent equity in Nippon, but it does give the U.S. veto power in certain kinds of business decisions, as well as a right to appoint a board member. In October the Department of Energy loaned the Canadian mining company Lithium Americas Corp. (LAC) and its Thacker Pass lithium mine project $2.26 billion in exchange for a 5% stake in both LAC and the mining venture. In October the Department of Defense paid $35.6 million for a 10% stake in the Canadian company Trilogy Metals, which is developing the Ambler Access Road infrastructure project in Alaska to access metals like copper, cobalt, and zinc. In November the Commerce Department said it intended to use $50 million in CHIPs Act money to buy a significant stake in the private rare-earth magnet producer Vulcan Elements. The Pentagon also intends to loan Vulcan another $620 million to help it build a large facility for neodymium iron boron magnets. Risky business There is a real purpose behind the stakes. The government isn’t putting tax dollars into golf courses or TV networks (not yet, anyway). The investments are targeted at weak spots in the supply chains that the government and its suppliers need to support U.S. economic interests and national security. That was the core idea behind the CHIPs Act, too. Equity investments let the government have something to show for it after they dispense grants to private sector companies. And the equity ownership often affords the government some direct influence over the operations and plans of the company. Prominent progressives have championed this sort of thing. In 2022 Bernie Sanders and Elizabeth Warren proposed that CHIPS Act beneficiaries give Uncle Sam an equity stake for that reason, but the measure failed. Sanders and Warren also wanted to attach prohibitions against CHIPs grant recipients from using the funds to buy back stock, offshore U.S. jobs, or to discourage unionization. Under The President, 2.0, the government is making bets on private-sector companies using tax money without the consent of Congress or the voters. What could go wrong? If the company falls on hard times, the government’s equity could shrivel, the tax dollars that bought it vanish. In a broader sense, Republicans, especially small-government conservatives, have historically been hesitant to back private companies, out of fear of appearing as if the government is “picking winners” in the marketplace. The Chamber of Commerce warned that the government buying into private companies could “turn innovative manufacturers into state-owned enterprises” and harm U.S. competitiveness. Still, the government’s investment has been met with criticism. The Cato Institute’s Scott Lincicome writes in a Washington Post op-ed that government equity stakes represent “a dangerous turn in American industrial policy,” adding that it abandons decades of market-oriented principles and risks politicizing Intel’s decision-making. “With the U.S. government as its largest shareholder, Intel will face constant pressure to align corporate decisions with the goals of whatever political party is in power,” he cautions. All of these companies saw their stock prices rise, in some cases dramatically, after their government investments were announced. And most of the companies are still doing well. Intel stock has gained about 53% (calculated from the pre-announcement opening price to closing price on December 18). MP Materials shares have risen 8%. Trilogy Metals is up 113%. Lithium Americas is down 35%. View the full article
-
The furore over football World Cup prices is the most glaring example of tensions fuelled by a post-pandemic boom in demand for experiencesView the full article
-
We may earn a commission from links on this page. While I’m a frequent reviewer of laptops and other computer-y type things, the gadgets that I care about the most are the ones I actually use on a regular basis in my day-to-day life. This year, I got big into showing off important memories with a digital picture frame, and into nostalgic handheld gaming with my first Anbernic device. But out of all the upgrades I’ve made to my life this year, the Ninja Creami was my easy favorite. What is the Ninja Creami?The Ninja Creami is different from a more traditional ice cream maker, which sits on your counter and constantly churns and freezes your liquid ice cream mixture until it's ready. Instead, you prep and freeze your liquid ice cream mix overnight, and then process it (in just a few minutes) when you want it. That does mean you'll need to get your ice cream going at least 24-hours in advance, but if you keep a few pints ready in your freezer at any given moment, I actually think it's more convenient than the alternative, and makes for great spontaneous snacking. Plus, you can get a bit more creative with your ingredients than with a traditional ice cream maker, since your mixture doesn't need to thicken while being churned. In short, it's a great machine for making custom desserts whenever you get the urge. Read on here for more on how exactly this all works, but for now, let's get into just how much of a difference it's made in my life this year. I got it as a gift, but it's quickly become indispensable in my kitchen. Pint of processed Ninja Creami ice cream. Credit: Michelle Ehrhardt Why the Ninja Creami is my tech upgrade of the yearWith the explanation out of the way, there are a few specific use cases that really made the Ninja Creami shine for me this year. In no particular order, here’s why it’s my favorite gadget I got in 2025. It’s easy to useI’ve already talked about how using the Ninja Creami generally takes less time than making ice cream with a more traditional ice cream maker, assuming you remember to keep your freezer stocked with Creami pints that you’ve frozen for at least 24 hours ahead of time. But let’s walk through the actual process of making ice cream with the Creami, just to really drive it home. Get urge for ice cream Pull pre-frozen Ninja Creami pint out of freezer Place pint into slots on Ninja Creami pitcher, install blade into pitcher lid, and place lid on top of pitcher Press button for your preferred ice cream program and wait two to five minutes. And that’s it. It’s a good sight faster than going out for ice cream, not to mention cheaper. And the Creami can even do mix-ins like your own live-in Coldstone—just dig a hole in the center of your ice cream after processing, add your mix-ins, and snack on the ice cream you dug out while waiting for the mix-in program to incorporate your goodies into your ice cream. As for cleanup, the pints, lid, and blade are dishwasher safe, so fuggedaboutit. It’s customizableMaybe the biggest reason to get any home ice cream maker is the ability to make your own ice cream flavors, and the Ninja Creami is no different. While I’ve made the standard vanilla and chocolate, I’ve also experimented with more offbeat flavors in my Ninja Creami. Good examples are Milk Tea flavored ice cream and Chocolate Dulce de Leche ice cream (stay tuned). You can’t find those at Baskin-Robbins! It’s healthy(er)The thing that actually made me get a Ninja Creami is protein ice cream, or ice cream where protein powder is the chief contributor to your flavor. This is harder to make in a more traditional ice cream maker, but because of how the Ninja Creami mixes its ice cream together, it’s dead simple to make with it. It’s actually 90% of what I use the Creami for. This allows me to satisfy my sweet tooth while generally keeping calorie counts lower than a full fat ice cream would. You can still make that in the Ninja Creami, but I’ve had satisfying results with just 2% milk, protein power, and my secret ingredient—sugar free Jell-O. The Jell-O comes with xantham gum that acts as a binder, and when mixed with the milk and protein powder, gives you a nearly indistinguishable texture from full fat ice cream after processing. You can actually buy xantham gum on its own, but Jell-O is a bit easier to find, and can add some additional flavor. Granted, I’ll usually add in some mix-ins and whipped cream, which does counteract the healthiness a little bit, but it’s still not uncommon to get a pint that’s under 400 calories. And a full pint usually serves both me and my husband, and makes a great compliment to a smaller dinner, which means it can help with portion control, too. It saves milkI’m not always great at using up milk ahead of its expiration date, but I hate the idea of dumping it down the drain. The Ninja Creami makes for easy recipes to freeze milk that’s about to go bad, as each recipe calls for about 2 cups of the stuff. Granted, I like to use 1 cup of cow milk and 1 cup of almond milk, since almond milk provides some flavor and an extra smooth texture, but you can totally get away with just one or the other. Overall, the Ninja Creami has made me much less wasteful with my milk, even as I’m using it more often. Boozy milkshakes!Finally, the Ninja Creami can make easy milkshakes. Yes, I know it’s not that hard to make milkshakes in a blender, but I hate washing my whole blender just for that. With the Ninja Creami, you just dump your ice cream into your pint, or process some custom ice cream and mix it around a bit, then dig a hole in the center of it and add some milk and alcohol. Run it through the milkshake program, and the resulting texture will be perfect pretty much every time, with none of the guesswork of using a blender. My husband and I like to do this before watching a movie, and it’s an easy way to save money on the $15+ boozy milkshakes at our local Alamo Drafthouse. Plus, there are also programs for making other desserts like sorbets, so while I mostly like to use the Creami for ice cream, there are a lot of other ways to get creative with this thing. My favorite Ninja Creami recipe Credit: Michelle Ehrhardt I've got my iPhone Notes app filled with dozens of recipes at this point, but to give you a brief idea of just want I do with my Ninja Creami, let's walk through my favorite. You're not going to find this at Baskin-Robbins, but once you've tried Dulce Chocolate, you won't be able to go back. Dulce ChocolateMy husband’s a big fan of Häagen-Dazs’ Dulce de Leche ice cream, and using a special kind of Dulce de Leche protein powder that only one company seems to make, we’ve been able to make a pretty convincing but much healthier dupe of it (for that, use vanilla Jell-O instead of what I’m about to suggest). However, we’ve discovered that Dulce de Leche also goes very well with chocolate, and that’s a mixture you’re unlikely to find unless you make it yourself. This is the recipe that really sold me on the Ninja Creami, and once you try it, I think you'll understand. 1 cup 2% milk Roughly 1 cup sweetened almond milk (leave enough room for your powders) 1 scoop Black Magic Dulce de Leche Protein powder 1 tbsp sugar free chocolate fudge Jell-O powder Use the Lite Ice Cream setting to process. After processing, optionally add mix-ins of your choice. My favorite for Dulce Chocolate ice cream are Kit-Kats and Reese’s Thins. Both are best slightly pre-crushed before being added to your ice cream. Which Ninja Creami should you get? Ninja Creami Dulce de Leche milkshake with caramel sauce. Credit: Michelle Ehrhardt If I’ve convinced you to get one of your own, you’ve got a few options. The one I own is the standard Ninja Creami, and it normally costs $200 and does everything I need. Pints are two cups and there are fewer program presets than on other models, but it's what I'd recommend to most people. But if you want a few more programs and larger pints, you could also go for the Ninja Creami Deluxe, which normally costs $250. Here, you'll be able to make three-cup pints, and you can also process just part of your pint at a time, making for easier leftovers. Finally, if you like soft serve ice cream, there's the Ninja Creami Swirl. This normally costs $350, and is a lot like the standard Ninja Creami, but also comes with a dispenser for swirling out your ice cream into a cone or bowl like you're at an ice cream shop. It's also got a few extra programs that make it easier to make ice cream with a soft serve consistency, but with the right knowhow, you can also do that with every Creami model. View the full article
-
To tax tips or not? That is a question that will confront lawmakers in states across the U.S. as they convene for work next year. President Donald The President’s administration is urging states to follow its lead by enacting a slew of new tax breaks for individuals and businesses, including deductions for tips and overtime wages, automobile loans, and business equipment. In some states, the new federal tax breaks will automatically apply to state income taxes unless legislatures opt out. But in many other states, where tax laws are written differently, the new tax breaks won’t appear on state tax forms unless legislatures opt in. In states that don’t conform to the federal tax changes, workers who receive tips or overtime — for example — will pay no federal tax on those earnings but could still owe state taxes on them. States that embrace all of The President’s tax cuts could provide hundreds of millions of dollars of annual savings to certain residents and businesses. But that could financially strain states, which are being hit with higher costs because of new Medicaid and SNAP food aid requirements that also are included in the big bill The President signed. Most states begin their annual legislative sessions in January. To retroactively change tax breaks for 2025, lawmakers would need to act quickly so tax forms could be updated before people begin filing them. States also could apply the changes to their 2026 taxes, a decision requiring less haste. So far, only a few states have taken votes on whether to adopt the tax breaks. “States in general are approaching this skeptically,” said Carl Davis, research director at the nonprofit Institute on Taxation and Economic Policy. The President’s treasury presses states to ‘immediately conform’ A bill The President signed on July 4 contains about $4.5 trillion of federal tax cuts over 10 years. It creates temporary tax deductions for tips, overtime, and loan interest on new vehicles assembled in the U.S. It boosts a tax deduction for older adults. And it temporarily raises cap on state and local tax deductions from $10,000 to $40,000, among other things. The law also provides numerous tax breaks to businesses, including the ability to immediately write off 100% of the cost of equipment and research. Forty-one states levy individual income taxes on wages and salaries. Forty-four states charge corporate income taxes. Treasury Secretary Scott Bessent this month called on those states “to immediately conform” to the federal tax cuts and accused some Democratic-led states that haven’t done so of engaging in “political obstructionism.” Though Bessent didn’t mention it, many Republican-led states also have not decided whether to implement the tax deductions. “By denying their residents access to these important tax cuts, these governors and legislators are forcing hardworking Americans to shoulder higher state tax burdens, robbing them of the relief they deserve and exacerbating the financial squeeze on low- and middle-income households,” Bessent said. But some tax analysts contend there’s more for states to consider. The tax break on tips, for example, could apply to nearly 70 occupation fields under a proposed rule from the Internal Revenue Service. But that would still exclude numerous low-wage workers, said Jared Walczak, vice president of state projects at the nonprofit Tax Foundation. “Lawmakers need to consider whether these are worth the cost,” Walczak said. Only a few states offer tax breaks for tips and overtime Because of the way state tax laws are written, the federal tax breaks for tips and overtime wages would have carried over to just seven states — Colorado, Idaho, Iowa, Montana, North Dakota, Oregon, and South Carolina. But Colorado opted out of the state tax break for overtime shortly before the federal law was enacted. Michigan this fall became first — and, so far, only — state to opt into the tax breaks for tips and overtime wages, effective in 2026. The overtime tax exemption is projected to cost the state nearly $113 million and the tips tax break about $45 million during its current budget year, according to the state treasury department. Michigan lawmakers offset that by decoupling from five federal corporate tax changes the state’s treasury estimated would have reduced Michigan tax revenues by $540 million this budget year. Republican state Rep. Ann Bollin, chair of the Michigan House Appropriations Committee, said the state could not afford to embrace all the tax cuts while still investing in better roads, public safety, and education. “The best path forward is to have more money in people’s pockets and have less regulation — and this kind of moved in that direction,” she said. Arizona could be among the next states to act. Democratic Gov. Katie Hobbs has called upon lawmakers to adopt the tax breaks for tips, overtime, seniors, and vehicle loans, and follow the federal government by also increasing the state’s standard deduction for individual income taxpayers. Republican state House leaders said they stand ready to pass the tax cuts when their session begins Jan. 12. Several states have rejected corporate tax breaks In addition to Michigan, lawmakers in Delaware, Illinois, Pennsylvania, and Rhode Island have passed measures to block some or all of the corporate tax cuts from taking effect in their states. A new Illinois law decoupling from a portion of the corporate tax changes could save the state nearly $250 million, said Democratic state Sen. Elgie Sims, chair of the Senate Appropriations Committee. He said that could help ensure continued funding for schools, health care and vital services. Illinois Gov. JB Pritzker, an outspoken Democratic opponent of The President, also cited budget concerns for rejecting the corporate tax cut provision. He said states already stand to lose money because of other provisions in The President’s big bill, such as a requirement to cover more of the costs of running the Supplemental Nutrition Assistance Program. “The decoupling is an effort to try to hold back the onslaught from the federal government to make sure that we can support programs like the one we’re announcing today,” Pritzker told reporters at a December event publicizing a grant to address homelessness in central Illinois. —David A. Lieb, Associated Press Associated Press writer John O’Connor contributed to this report. View the full article
-
Britain had only been planning to deploy the plan in lockstep with Australia, Canada and the EUView the full article
-
Existing-home sales in the US barely rose in November, as a recent moderation in price growth and mortgage rates motivated buyers at the margin. View the full article
-
The UK capital is subject to more than its fair share of misinformationView the full article
-
A marketing campaign calendar template is an important tool for organizing your marketing efforts effectively. It helps you outline fundamental details like campaign names, target audiences, and timelines. By providing a clear visual representation of your marketing activities, this template promotes team collaboration and accountability. Comprehending its structure can greatly improve your marketing strategy, but the real question lies in how to create and manage one effectively. What steps should you take to guarantee its success? Key Takeaways A marketing campaign calendar template organizes marketing activities, providing a structured outline for campaigns, timelines, and responsibilities. It includes essential fields like campaign name, target audience, start and end dates, and channels for execution. The template enhances collaboration by assigning ownership and distributing tasks among team members. It improves planning efficiency, ensuring deadlines are met and aligning strategies with business objectives. Regular updates and reviews of the calendar facilitate real-time adjustments and accountability in campaign execution. Understanding a Marketing Campaign Calendar Template A marketing campaign calendar template is an invaluable tool for organizing your marketing efforts. It provides a structured outline of all planned activities, including campaign names, target audiences, start and end dates, and channels used. By utilizing a marketing calendar template, you can visualize your marketing schedule, ensuring you stay aligned with deadlines and deliverables. This template acts as a roadmap, allowing for real-time updates and adjustments to fit changing strategies or market trends. Integrating various channels within a marketing campaign calendar template helps maintain consistent messaging across platforms as well as aligning with important cultural and industry events. Importance of a Marketing Campaign Calendar In managing marketing efforts, having a well-structured campaign calendar is vital for ensuring that all activities are organized and aligned with your business objectives. A marketing campaign calendar helps you: Visualize timelines and deadlines for various campaigns across different channels. Improve collaboration and communication among team members, reducing miscommunication. Align marketing efforts with your business goals, ensuring every campaign contributes to your strategy. Track progress and performance regularly, allowing for adjustments based on real-time insights. Incorporate key internal and external dates, maximizing engagement opportunities and ensuring timely execution. Key Components of an Effective Marketing Campaign Calendar When creating an effective marketing campaign calendar, you’ll want to include vital elements like campaign names, owners, and target audiences to guarantee everyone’s on the same page. It’s furthermore important to align these components with your overall strategy, linking key dates and milestones to your marketing goals. Essential Calendar Elements To create an effective marketing campaign calendar, it’s vital to include key components that encourage clarity and accountability. Here are fundamental elements you should incorporate: Campaign Name: Clearly identify each campaign for easy reference. Owner: Designate a responsible individual for accountability. Target Audience: Specify who the campaign is aimed at to tailor your message. Channels: List the marketing platforms you’ll use, providing a thorough view of execution. Key Dates: Include start and end dates, milestones, and deadlines to track progress and maintain focus. Regularly updating your calendar is necessary to reflect any changes in strategy or team responsibilities. Additionally, consider adding metrics to evaluate campaign effectiveness, which will inform future marketing strategies. Strategic Alignment Importance Strategic alignment is crucial for an effective marketing campaign calendar, as it guarantees that all planned activities directly support your business objectives. By ensuring that every campaign contributes to overarching goals and measurable outcomes, you improve your overall marketing effectiveness. Your calendar should include key fields like campaign name, target audience, channels, start and end dates, and milestones, providing clarity for all team members involved. Regular updates keep the calendar accurate, allowing for real-time adjustments to evolving priorities and market dynamics. In addition, integrating significant internal and external dates, such as product launches and cultural events, increases relevance and engagement. A well-structured calendar likewise promotes effective collaboration among stakeholders, ensuring coordinated efforts and consistent brand messaging throughout your campaigns. Steps to Create a Marketing Campaign Calendar Creating a marketing campaign calendar starts with clearly defining your marketing goals and objectives, which guarantees that all activities align with your overall vision. Follow these steps to create an effective calendar: Identify key dates like product launches, holidays, and industry events that impact your campaigns. Set deadlines for each task to maintain organization and accountability. Brainstorm marketing activities that fit your goals, specifying the channels for execution (e.g., social media, email). Assign ownership for each task to team members, ensuring clarity on responsibilities. Regularly review and update the calendar to reflect changes in strategy, timelines, and tasks, encouraging collaboration. Types of Marketing Campaign Calendars After establishing the steps to create a marketing campaign calendar, it’s important to understand the different types of calendars available to boost your planning and execution. You can choose from various options, such as editorial calendars for content planning, social media calendars for tracking posts, and integrated marketing calendars that coordinate multiple channels. An advertising calendar focuses on scheduling your advertising efforts, whereas a digital marketing calendar details online activities like SEO and email campaigns. Each type typically includes crucial elements like campaign names, target audiences, channels, start and end dates, and key milestones. Best Practices for Managing a Marketing Campaign Calendar To effectively manage your marketing campaign calendar, it’s essential to assign clear ownership for each task and campaign, which improves accountability among team members. Regularly updating the calendar guarantees it reflects any changes in strategy, making it a reliable resource for all stakeholders. Clear Ownership Assignment Clear ownership assignment is crucial for the success of any marketing campaign calendar, as it directly impacts accountability and execution efficiency. When team members know their responsibilities, it leads to increased efficiency and reduces confusion. Here are some best practices for establishing clear ownership: Assign specific tasks to individuals, ensuring accountability. Define roles to minimize overlaps and improve collaboration. Regularly review assignments during team meetings for open communication. Use project management tools to track ownership and deadlines. Document ownership details, including names and contact information, in the calendar template. Regular Updates Schedule Implementing a regular updates schedule is fundamental for maintaining an effective marketing campaign calendar. Aim to update your calendar weekly or bi-weekly to reflect any changes in project timelines, task statuses, and new initiatives. Monthly review meetings with key team members are essential, as they allow you to assess planned activities’ effectiveness and adjust strategies based on performance metrics and market trends. Utilize project management tools for real-time updates and notifications, ensuring all team members stay informed. Assign a dedicated calendar owner to maintain accuracy and completeness, which boosts accountability. Finally, incorporate a feedback mechanism for team members to suggest updates or improvements, cultivating collaboration and ensuring the calendar evolves with your team’s needs. Tools and Software for Marketing Campaign Calendars When managing marketing campaigns, using specialized tools and software can greatly boost your efficiency and organization. These solutions help you streamline collaboration and keep everything on track. Here are some key features you can expect: Real-time updates: Stay informed about changes instantly. Customizable views: Tailor your calendar to fit your needs. Task assignments: Delegate responsibilities easily among team members. Integration capabilities: Sync with platforms like Google Calendar for seamless event management. Filtering options: Focus on specific campaigns or marketing activities for improved visibility. Examples of Marketing Campaign Calendar Templates Marketing campaign calendar templates come in various formats, each designed to meet specific needs and improve your campaign planning. For instance, digital marketing calendars focus on online initiatives, clearly laying out tasks and timelines for your digital efforts. Editorial calendars help you plan content publication, detailing articles, blog posts, and other materials, ensuring consistency across your messaging. Furthermore, social media calendars allow you to schedule posts on different platforms, tracking engagement and performance. These templates typically include crucial fields like campaign names, target audiences, and key milestones. Frequently Asked Questions What Is a Marketing Campaign Calendar? A marketing campaign calendar is a strategic tool that helps you organize and plan your marketing activities. It outlines your campaigns, promotions, and launches, usually by month or quarter. This calendar integrates various marketing channels and aligns your team’s efforts, ensuring consistency in messaging. Key elements include campaign names, target audiences, start and end dates, and milestones. Regular updates are crucial for maintaining accuracy and adapting to changing market trends. What Does a Good Marketing Calendar Look Like? A good marketing calendar includes clear campaign names, assigned owners, target audiences, and channels. You’ll find start and end dates, along with key milestones that keep everyone aligned. It visually organizes your activities, helping you coordinate across platforms for consistent messaging. Regular updates are crucial to reflect any strategy changes. Furthermore, incorporating significant dates like holidays and product launches allows you to seize timely engagement opportunities with your audience effectively. What Is a Marketing Content Calendar? A marketing content calendar is a strategic tool that helps you plan and manage your content creation and distribution. It outlines important elements like publication dates, topics, formats, and team responsibilities, ensuring your messaging is consistent and timely. By visualizing your content schedule, you can identify gaps and optimize your distribution across various channels. Regular updates keep your calendar adaptable to trends and changing audience preferences, aligning your content strategy with overall marketing goals. How to Develop a Marketing Campaign Template? To develop a marketing campaign template, start by defining your campaign’s goals and target audience. Next, outline crucial elements like channels, timelines, and milestones. Incorporate key dates, such as product launches or events, to align your activities. Assign responsibilities to team members to guarantee accountability, and regularly update the template to reflect changes in strategy or deliverables. Using software tools can improve collaboration and provide real-time updates for efficient execution. Conclusion In conclusion, a marketing campaign calendar template is a crucial tool for organizing and managing marketing efforts. By outlining campaign details and timelines, it promotes collaboration and accountability among team members. Comprehending its key components and best practices can greatly improve your marketing strategy. Utilizing the right tools and software can streamline the process, ensuring you stay on track and adapt to any changes. In the end, implementing a well-structured calendar can lead to more effective and aligned marketing initiatives. Image via Google Gemini This article, "What Is a Marketing Campaign Calendar Template?" was first published on Small Business Trends View the full article
-
Ford is recalling more than 270,000 electric and hybrid vehicles in the U.S. because of a parking function problem that could lead to them rolling away. The Detroit automaker said that the recall includes certain 2022-2026 F-150 Lightning BEV, 2024-2026 Mustang Mach-E, and 2025-2026 Maverick vehicles. At issue is the integrated park module, which may fail to lock into the park position when the driver shifts into park. Ford said that it will implement a park module software update for free. Vehicle owners may contact Ford customer service at 1-866-436-7332 for additional information. View the full article
-
Visa and Mastercard have agreed to pay $167.5 million to settle a long-running class action lawsuit. The suit, which was first filed back in Oct. 2011, accused the two major credit card companies of conspiring to keep ATM fees artificially high. The proposed settlement, filed on Thursday in Washington, if approved, it will mean an end to “almost fourteen years of vigorously contested litigation.” The lawsuit alleged that both companies “participated in an unlawful conspiracy” involving Visa and Mastercard blocking independent ATM operators from offering lower prices. If approved, the settlement will have Visa and Mastercard pay millions to ATM users who say they were charged an unreimbursed access fee to withdraw cash from independent, non-bank ATMs. Per a Guardian report, Visa is set to pay 53% of the settlement, $88.8 million, while Mastercard will contribute 47%, or $78.7 million. In the settlement, attorneys for the plaintiffs called the settlement “an excellent result in light of the risks of continued prosecution.” Attorneys for the defendants did not immediately reply to a Fast Company request for comment. Last year, Visa and Mastercard also agreed to pay $197.5 million to ATM users who claimed they were overcharged at bank-operated ATMs. At the time, the plaintiffs’ attorneys said the settlement will “deliver immediate and assured relief.” That settlement followed a 2021 settlement with major banks, such as JP Morgan Chase, Bank of America, and Wells Fargo, agreeing to pay $66 million to settle similar claims. Still, the lawsuits against the two major credit card companies are not over, as a third lawsuit, launched by independent ATM owners and operators, is pending against the companies. “The rules prevent ATM operators from passing on the savings to cardholders when their ATM transactions are handled by an ATM network other than Visa or Mastercard,” Jonathan Rubin, an attorney for the plaintiffs said in 2023 when announcing that suit will continue to move forward. At the time, the attorney added that it will ask the court to eliminate rules which all but eliminate competition. Despite Thursday’s settlement, the companies have denied any wrongdoing. View the full article
-
Whether you want them to or not, appliances are getting smarter. It’s increasingly challenging to find even basic models without some kind of “smart” feature or embedded artificial intelligence. If you don't believe me, just try to find a “dumb” television at your local Best Buy. You will be disappointed. While it's true that many of the “smart” features offered by these nifty new appliances are quite useful. The ability to pre-heat your oven or adjust your thermostat by pressing a button on your phone is great, and getting alerts when the fridge door is left open or when you forget to move your laundry from the washer to the dryer is undeniably a boon. But sometimes, the convenience these features offer is an illusion, as many supposedly smart features in modern appliances aren’t very smart at all—and they can actively make your life harder instead of easier. If you’re shopping for a new appliance, considering avoiding these not-so-smart features. Dryer with moisture sensors that leave your clothes dampModern clothes dryers offer a lot of great capabilities. Some can even talk to your washer, pre-setting themselves for the laundry coming its way, and many can remind you to collect your laundry, sparing you wrinkled clothes, and to clean out the lint filter. But modern dryers often come with moisture sensors that shut off the dryer when it detects that your clothes are dry. In theory, sensor drying saves you money and time over a fixed time dry. But the sensors in these dryers are notorious for being inaccurate shutting the dryer down when your clothes are still a bit damp. And you still have to make a guess as to how much drying you need and set the sensor to the proper level. At best, this can mean running another drying cycle. At worst, your clothes will sit there getting mildewy until you remember to check the machine. Dishwashers with "eco modes" that leave dishes dirtyNew dishwashers often come with efficient or “eco” modes that use less water and less energy to clean your dishes. That’s a great idea—in theory. But these modes achieve those efficiencies the only way they can: By running at lower temperatures and literally using less water in their cleaning cycles. This can often leave your dishes visibly dirty after running a load, forcing you to cancel out the benefit by running them a second time. Worse, these modes don’t get hot enough to kill dangerous bacteria like E. coli, so even if your dishes come out looking clean, they may not be sanitary. Smart fridges that misidentify your groceriesSmart fridges are often at the top of people’s complaints list for two main reasons: One, they are often abandoned by their manufacturers soon after they arrive on the market, with updates and support vanishing in as quickly as two years. That transforms your pricey smart fridge into a pricey dumb fridge. More frustratingly, smart fridges that supposedly use artificial intelligence to identify your groceries as you place them inside (in order to help you track your shopping needs and expiration dates) often get things wrong. For example, this woman complained that her smart fridge often mistook her husband’s head for an avocado, among other problems, which rendered the feature worse than useless. Sensor-cooking microwaves that don't cookWhile the modern microwave remains the steadfastly boxy, unsexy beast it’s always been, there have been attempts to make it smarter—and sometimes these attempts backfire on you. Some microwaves offer “sensor cooking,” the ability to sense the weight and moisture level of the food in order to adjust cooking time and power levels to cook your food perfectly. Except when it senses incorrectly and leaves you with a half-cooked mess, or if you’re trying to cook something that simply doesn't work well with sensor cooking, like dry foods that don’t produce enough steam for the sensor to detect. Smart kitchen scales that are just making guessesA smart kitchen scale might seem like a nifty idea; you weigh your food and use an app to get nutritional information, like the amount of calories in what you’re about to eat. That’s fine, but it really just adds an unnecessary step to your cooking routine, because most “smart” scales are just regular, standard kitchen scales and an app that Googles on your behalf. You’ll get the same general experience—and likely better accuracy—by weighing something and using your phone to search for nutritional information yourself. Smart garage doors that are less secureSmart garage doors are a great example of a piece of technology that isn’t improved much by being smart. And the core technology that makes the garage door smart—a WiFi connection to a cloud server—can also make it worse than useless. Aside from the fact that any disruption in the door’s connection can cause it to remain locked in the open position, leaving your home vulnerable, there’s also the fact that the manufacturer can make changes any time they like that could potentially alter the way your door functions or brick it entirely. View the full article
-
Sales of previously occupied U.S. homes rose in November from the previous month, but slowed compared to a year earlier for the first time since May despite average long-term mortgage rates holding near their low point for the year. Existing home sales rose 0.5% in last month from October to a seasonally adjusted annual rate of 4.13 million units, the National Association of Realtors said Friday. Sales fell 1% compared with November last year. The latest sales figure came in slightly below the 4.14 million pace economists were expecting, according to FactSet. Through the first 11 months of this year, home sales are down 0.5% compared to the same period last year. “It’s possible that 2025, unless December (sales) figures really improve, we may be technically slightly down from one year ago,” said Lawrence Yun, NAR’s chief economist. One factor limiting home sales is weaker demand for condominiums. Sales of condos are down 6% so far this year, Yun noted. Despite sluggish sales, home prices continued to climb last month. The national median sales price increased 1.2% in November from a year earlier to $409,200, an all-time high for any November on data going back to 1999. Home prices have risen on an annual basis for 29 months in a row, even as the housing market has been mired in a slump that began in 2022 when mortgage rates began climbing from historic lows. Sales of previously occupied U.S. homes sank last year to their lowest level in nearly 30 years. Sales have been stuck at around a 4-million annual pace now going back to 2023. That’s well short of the 5.2-million annual pace that’s historically been the norm. Home sales got a boost this fall as the average rate on a 30-year mortgage declined at the end of October to 6.17%, the lowest level in more than a year. Even so, affordability remains a challenge for many aspiring homeowners, especially first-time buyers who don’t have equity from an existing home to put toward a new home purchase. Uncertainty over the economy and job market are also keeping many would-be buyers on the sidelines. A shortage of homes for sale, especially in the more affordable end of the market, continues to weigh especially on first-time homebuyers. They accounted for 30% of homes sales last month. Historically, they made up 40% of home sales. An annual survey of homebuyers by NAR showed first-time buyers accounted for an all-time low 21% of home purchases between July 2024 and June 2025, while the average age of such homebuyers rose to a record-high of 40. Homes purchased last month likely went under contract in September and October, when the average rate on a 30-year mortgage ranged from 6.5% to 6.17%, according to Freddie Mac. Mortgage rates have mostly remained close to their October low in recent weeks. Home shoppers who can afford to buy at current mortgage rates benefited from a wider selection of properties on the market last month than a year ago, although the number of homes for sale in November declined from the previous month. There were 1.43 million unsold homes at the end of last month, down 5.9% from October and up 7.5% from November last year, NAR said. The latest inventory snapshot remains well below the roughly 2 million homes for sale that was typical before the COVID-19 pandemic. November’s month-end inventory translates to a 4.2-month supply at the current sales pace. Traditionally, a 5- to 6-month supply is considered a balanced market between buyers and sellers. Yun is forecasting that existing U.S. home sales will jump 14% next year. That’s more optimistic than several other housing economist forecasts, which range from a 1.7% to 9% increase. Economists generally forecast that the average rate on a 30-year mortgage will remain slightly above 6% next year. —Alex Veiga, AP business writer View the full article
-
More than 80% of mortgage brokers expect business to grow in 2026, mainly through the strengthening of referral networks and the expansion of non-QM offerings. View the full article
-
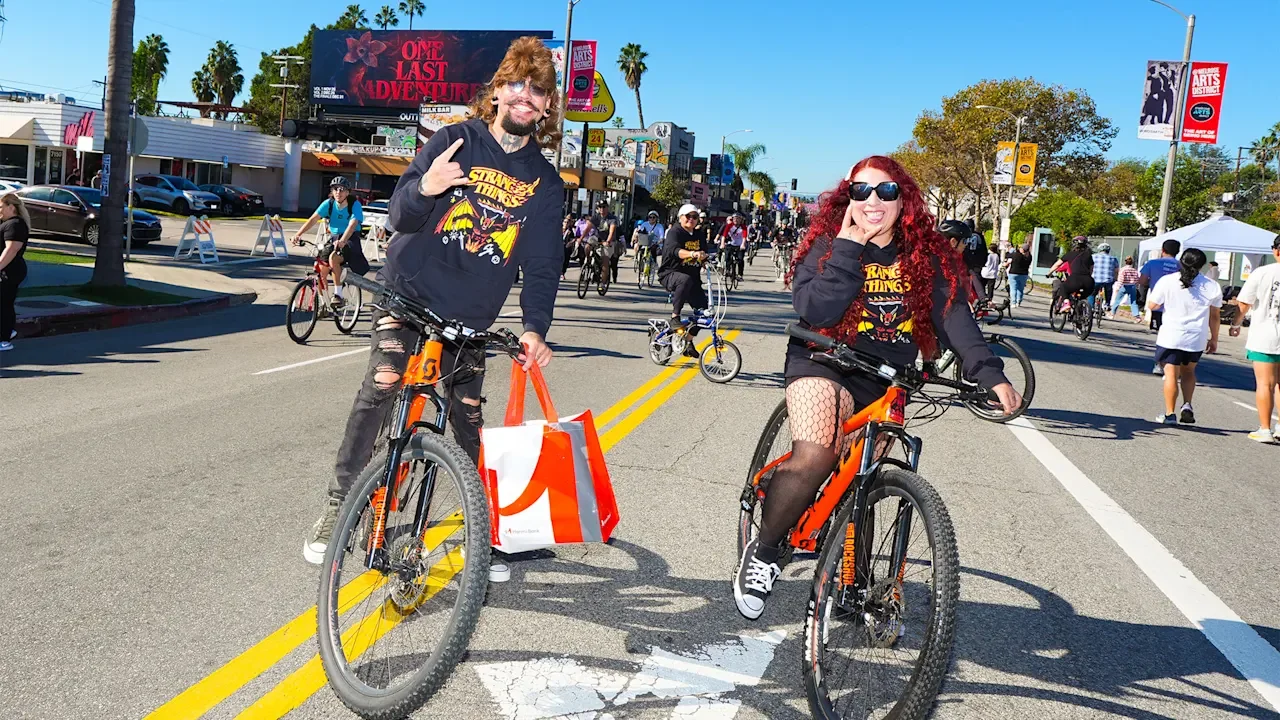
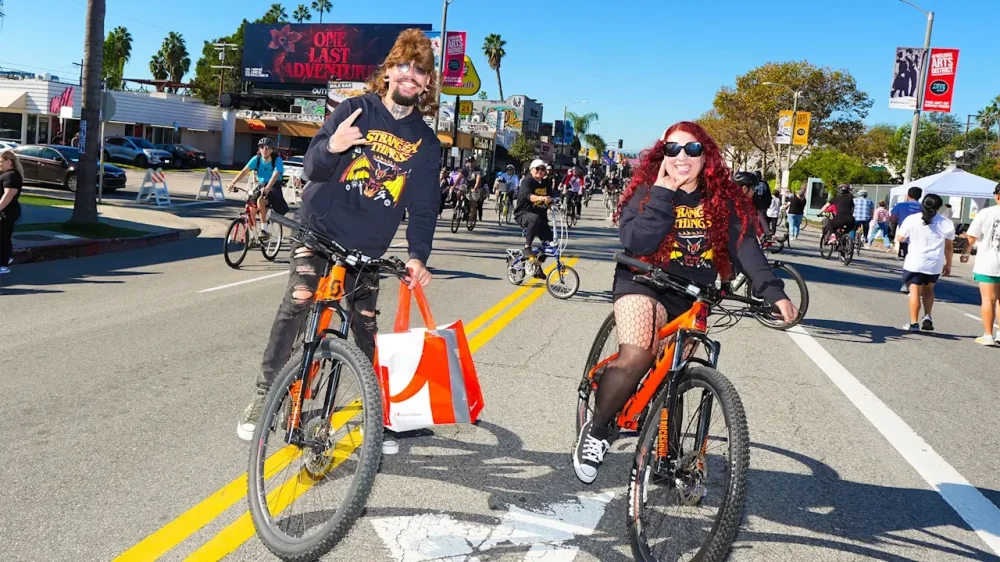
It’s been nearly a decade since Netflix introduced fans to the fictional town of Hawkins, Ind., the Upside Down, Demogorgons, and the Stranger Things universe. Since 2016, the sci-fi series has become a massive hit for Netflix making it one of the streaming service’s most-watched shows with the fourth season alone amassing over 140.7 million views globally, according to the company. The series has earned 12 Primetime Emmy Awards over the course of the last several years, has pushed its young cast into superstardom, and has become a global phenomenon inspiring several live events and pop-up stores in various cities. And its fifth and final season, which is premiering in three parts, is no exception when it comes to the scale. While the streaming giant and showrunners Matt and Ross Duffer have other spin-offs planned, the fandom was always at the top of their mind when planning the marketing for the show to give the original series a proper send-off. “Stranger Things is the first franchise for Netflix overall so we do different things year round to reach all the fans and we’ve done that for years and it just keeps building,” Marian Lee, chief marketing officer of Netflix, tells Fast Company. “The fact that we started our live experiences with Stranger Things and have continued to evolve them in different ways is exciting.” To really build that excitement for fans heading into the final season, Netflix launched a massive global marketing campaign that includes a mix of real life, immersive experiences as well as social media components. And by the beginning of next month, Netflix will have launched several fan events across 32 cities across 23 countries from Tokyo to London and Berlin to Los Angeles. Turning ‘Stranger Things’ into real-world experiences Netflix hosted a “One Last Ride” cycling event with CicLAvia with over 50,000 attendees; a transit station in Buenos Aires was turned into an Upside Down-portal at a transit station; a holographic featuring elements from the series was projected over the Sydney Harbour in Sydney; an old airport hangar in Berlin was transformed into the Stranger Things universe where visitors had the opportunity to enjoy a bike ride through pivotal moments from the show; and just last month in New York City, a Stranger Things-themed float was debuted at the Macy’s Thanksgiving Day parade to its three million attendees. Other events are planned in London, Bangkok, Milan, Las Vegas, and Madrid later this month. In Las Vegas, fans will be treated to “One Last Adventure: Las Vegas,” a drone show that will feature 5,000 choreographed drones and pyrotechnics highlighting moments from the show complete with a musical mashup. Meanwhile, fans will be able to watch the final episode in theaters across the United States and Canada. Earlier this month, Netflix House, the new live entertainment venue that launched in Philadelphia and Dallas this month, features Stranger Things elements at both locations. The Dallas location features an immersive Stranger Things: Escape the Dark experience with a brand new storyline, while the Philadelphia location features a Stranger Things: Catalyst game developed in collaboration with Sandbox VR. On top of that, visitors can enjoy food inspired by the show in the Netflix Bites food court at the Las Vegas location debuting next year. But even before Netflix began heavily leaning into the experiences during the second half of the year, they also opened its Stranger Things: The First Shadow show on Broadway and West End earlier this year. According to the entertainment giant, demand across Broadway and the West End saw an almost instant sustained increase in sales, with sales at their highest levels since the initial launch of both productions. The Upside Down takes over social media Lee said when her team was planning the marketing for the final season, it was important to start early with a social campaign that focused on rewatching previous seasons to get ready for the new one. Ahead of the final season, Netflix rolled out a pre-launch rewatch campaign, which has generated 5.7 billion earned global social impressions. “It’s a brilliant way for the team to really think about how to re-engage fans and to get them ready for this next season,” Lee said. “A lot of our strategy really leaned into those core moments.” A video featuring the four boys played by Finn Wolfhard, Noah Schnapp, Caleb McLaughlin, and Gaten Matarazzo, recreating a scene from the second season earned over 215 million impressions globally. According to Netflix, total earned social impressions for the fifth season has reached 11.5 billion and that’s without the last two volumes of the episodes released yet. Since then, Netflix has also released many behind-the-scenes moments and audition tapes of the cast across its social channels, which all have millions of followers. Powered by brands… and ‘80s nostalgia Lee said another essential part of the campaign was its various partnerships with brands — and for this season, Netflix partnered with many companies across various lifestyle and retail categories like Spotify, Meta, Target, Walmart, Nike, Gap, and several food and beverage brands like Eggo, Doritos, Kellogg’s, Chips Ahoy, and Gatorade all infused with nostalgic elements inspired by the show’s 1980s setting. Netflix launched a collaboration with military quarantine snack Peanut Butter Boppers earlier this month for a limited time, several other items and snacks inspired by the series with including a special collection with Target that included over 150 exclusive products like Demogorgon popcorn bucket, Demogorgon Bundle Box by Jazwares and exclusive Gatorade x Stranger Things apparel and accessories. Along with the partnerships with brands like Doritos and Discover, Netflix collaborated closely with each respective brand on a custom partnership that included commercials. Lee said her and her team set the bar really high when it came to working with its brand partners this season. “This fandom is so rich and unique and it just happens to also dovetail really nicely with brands and retailers who are seeing the nostalgia for that 80s’ aesthetic come back so it came together in a really serendipitous way for us to lean in,” Lee said. Ultimately, Lee said all the work her and her team really ties back to the fanbase the series has accumulated over the last five seasons. “It is hard to even articulate the impact on culture that the Duffer Brothers has had,” Lee said. “To watch them tell their story of dreams they had of bringing this show to life and we’re lucky to be the home for that.” View the full article
-
A federal judge’s four-year prison sentence for an Iowa meatpacking plant worker underscores that pandemic-era relief fraud remains an active enforcement priority—and a cautionary tale for small business owners who relied on Paycheck Protection Program funds to survive COVID-19 disruptions. According to a release from the Small Business Administration (SBA) Office of Inspector General, Yovany Ciero, 48, of Mason City, Iowa, was sentenced on December 3, 2025, to 48 months in federal prison for his role in a multi-million-dollar scheme to defraud the SBA through fraudulent Paycheck Protection Program (PPP) loans. Ciero was convicted by a jury earlier this year on multiple counts, including wire fraud, money laundering, and conspiracy, after prosecutors showed he helped orchestrate and profit from false loan applications during the pandemic. The case, detailed in an SBA investigative summary, highlights how PPP funds—intended to help legitimate small businesses keep workers on payroll—were instead siphoned off through organized fraud. Evidence presented at trial showed that Ciero, a former sergeant in the Cuban military, was working at an Algona, Iowa meatpacking plant when the COVID-19 pandemic began. Beginning in July 2020, he and more than 100 other immigrants from Cuba obtained fraudulent PPP loans by falsely claiming they were self-employed individuals with approximately $100,000 in gross income in 2019. In reality, they were wage employees at meatpacking plants or other businesses. Prosecutors described Ciero as one of six “bundlers” in the scheme. His role involved recruiting participants, collecting their personal identifying information, and passing that information to others who submitted the fraudulent loan applications to participating lenders. Investigators determined that more than $4 million in fraudulent PPP applications were submitted, resulting in losses of over $2.4 million to the federal government. Once loan funds were disbursed—typically about $20,000 per applicant—Ciero also acted as a “funnel” in a money laundering conspiracy. He collected fees charged by the organizers, usually $3,000 per fraudulent loan. The government also showed that Ciero personally obtained two fraudulent PPP loans, one for himself and one for his paramour, and used much of that money to purchase a semi-truck. After receiving the PPP funds, he also obtained a Federal Housing Administration loan to buy a home in Mason City. The district court judge found that Ciero obstructed justice by testifying falsely at trial, a factor that contributed to the length of his sentence. United States District Court Judge Leonard T. Strand ordered Ciero to pay $212,293 in restitution to the SBA and to serve two years of supervised release following his prison term. There is no parole in the federal system. For small business owners, the case serves as a reminder that PPP compliance did not end when the program stopped accepting applications. Federal agencies continue to audit loans, pursue criminal cases, and seek restitution years after funds were distributed. Businesses that legitimately received PPP loans should ensure their documentation—including payroll records, tax filings, and forgiveness applications—remains complete and accessible. The case also illustrates how fraud schemes can involve individuals who were not business owners at all, but who falsely claimed self-employment status. For legitimate sole proprietors and independent contractors, this distinction matters. The government’s aggressive pursuit of false claims can increase scrutiny across the board, making accurate reporting and careful recordkeeping even more important for compliant businesses. Ciero is the fifth former Iowa meatpacking plant worker sentenced in this particular scheme. Other defendants received prison terms ranging from five to 11 months and were ordered to pay restitution amounts between roughly $60,000 and $138,000, according to court records. Prosecutors said the investigation involved multiple agencies, including the SBA Office of Inspector General, the Federal Deposit Insurance Corporation Office of Inspector General, Homeland Security Investigations, the FBI, and local law enforcement. As enforcement actions continue, small business owners may want to revisit how they applied for pandemic relief, how funds were used, and whether forgiveness filings accurately reflected their operations. While the vast majority of PPP recipients followed the rules, cases like this demonstrate that the government is still sorting out pandemic-era abuses—and that the consequences for fraud can be severe and long-lasting. Image via Google Gemini This article, "Cuban Military Veteran Sentenced in $2.4M PPP Loan Fraud Scheme" was first published on Small Business Trends View the full article
-
As you get stronger, you become able to lift heavier and heavier weights. That's the idea at the heart of an often-misunderstood fitness concept: progressive overload. Unfortuantely, there are a lot of myths and misunderstandings about this principle, so here's how to use it to plan your own workouts or judge whether a program you're following will keep you on track. What is progressive overload? Progressive overload is the increase, over time, in the amount of work or stress you ask your body to handle. The term is used two different ways: as a principle of how the human body works, and as a description of how a workout program changes over time. If you want to know how to "do progressive overload," you're thinking of the second one—how to design a workout program. The simplest way to implement this is to just do a little more each time you're in the gym. More weight, or more reps, or making the workout harder in some other way. You can still take some easier "deload" workouts (or weeks) from time to time, but over the long term you want to see a trend of the workouts getting harder. They won't necessarily feel harder, because you'll be getting stronger. It's more like the workouts are keeping up with you. In other words, progressive overload is a bit of a chicken-and-egg situation. As you get stronger, your workouts need to get harder to keep up. But in a sense you are also becoming stronger because you're challenging yourself with harder workouts. What does progressive overload look like in real life?If you’re bummed out by the idea of working harder and harder forever, don’t panic. You’ll work harder in absolute terms—by lifting heavier weights, let’s say—but the challenge stays about the same in relative terms. Your workouts will fall into an effort level you might call “hard, but doable,” and you’ll notice progress because your numbers are going up. (A similar approach applies to endurance sports. As cyclist Greg Lemond reportedly said: “It never gets any easier, you just go faster.”) When I started lifting weights many years ago, 65 pounds was a decently challenging bench press for me. I remember being proud of myself for being able to squeeze out a rep or two at 85 pounds. Now, if I’m going to do a bench workout, I don’t even bother loading those amounts onto the bar. My warmup sets start at 95 pounds, and a heavy single might be around 135. That 135 feels just as hard as 85 used to, but it’s undeniably more weight. How did I make that progress? Well, I kept lifting the weights that felt heavy for me. Over time, the same weights that used to be challenging started to feel easy, and I needed to add more and more weight to the bar to get something that actually felt heavy. (I have a guide here to figuring out whether you’re lifting “heavy.”) Most of the time, I either followed a program that told me how many pounds to lift, increasing that amount slowly over time, or one that told me what effort level to lift at (a concept called RPE), which allowed me to choose an appropriate weight each day. Following a program will usually net you better progress than just winging it, but as long as you’re using the overload principle and the progression principle, you will get stronger. Workout routines that use progressive overloadHere are some examples of workout routines that use progressive overload: Double progression. Let's say you're aiming for three sets of eight to 12 reps of dumbbell shoulder press. You choose a weight that you can handle for 3 sets of 8 reps. The next time you do shoulder press, try to add at least one rep. If you can't, that's fine—just do your three sets of eight. One day maybe you'll get 10 reps on the first set, then only eight on the next two. Another time maybe you get 12, 10, and eight. After a few weeks you manage three full sets of 12. That means it's time to increase the weight! The next time you do the exercise, you'll use a heavier set of dumbbells and start again at three sets of eight. It's called "double" progression because first you increase the reps, and then you increase the weight. Linear progression. This is a common progression for barbell exercises for beginners. You do the same number of reps every time (say, five sets of five reps) but add a small amount of weight every workout. Often the program will have instructions for what to do if you can't complete the five sets of five reps at the new weight. These workouts aren't usually realistic for experienced lifters, since you can't keep increasing the weight forever, but they're great for people who are learning an exercise for the first time or returning to the gym after a break. Set progression. This may be used along with double progression, or may be its own thing. You start with just a few sets of an exercise per workout, say two or three, and then add a set each week. Once you're doing, say, five sets, you'll start over with heavier weight. If you're using it with double progression, you'll increase sets, and then reps, and then weight. Density progression. This is commonly used in timed sets, like Crossfit WODs ("workout of the day") or for accessory lifts. Set a timer for several minutes and do as many reps as possible in the given time, resting as needed. The next time you do the workout, try to do more reps in the same amount of time. Once you can do the lifts with little to no rest, you'll either add weight or find another way to make the exercises harder (for example, doing dips instead of pushups). As you can see, weight isn't the only variable that progresses. You can increase reps, or sets, or increase the amount of work you do in a given time by decreasing rest. You can increase the difficulty by choosing a harder exercise (like progressing from dips to pushups). As long as things get harder over time, you're doing progressive overload. How to use progressive overload even if you can't add more weightAdding weight is part of most progressive overload schemes, but you don’t have to add weight to the bar literally every time you lift. There’s a wide range of weights and rep ranges that can be effective for building strength and muscle. For example, if I did a bench workout today, I might do sets of 10 at 100 pounds, or sets of five at 120, or some heavy singles at 140, or any combination of these. If I’m really tired or stressed, I might decide to do the sets of 10 at just 90 pounds. If I’m feeling great, I might be able to do them at 105. This is what I mean by a wide range: All of these are hard enough work to spur my muscles to adapt and get stronger. (There are reasons you might choose one of these workouts over the others, but we don’t need to get into those details at the moment.) What wouldn’t be progressive overload? Well, if I did sets of 10 with just the bar, that wouldn’t help me get stronger. If I had a mini barbell set, and it maxed out at 85 pounds, my strength would stagnate once I got to the point where 85 pounds isn’t a challenging weight anymore. Even as your strength improves, you don’t have to do more every single workout, as long as you’re getting stronger in the long term, and your workouts are still in the range that is challenging to you. So let’s say you’re doing bicep curls with a 10-pound dumbbell. You can do eight or 10 reps with it. Perfect. But the only way to add weight, at your gym, might be to pick up a 15-pound dumbbell. If that weight is too heavy for you, that’s okay. Keep working with the 10-pounder, and in time you’ll be ready for the 15. You can progress on more than one metricWhile you’re probably itching to lift heavier weights, weight on the bar is not the only way to progress. Sometimes you can’t add weight because of equipment issues, or just because your strength is improving slowly. (Even if your beginner gains were meteoric, everybody’s progress slows down at some point.) But if you’re smart, you probably don’t want to only get better at one specific thing. A lot of beginners start off doing squat, bench, and deadlift in sets of five reps, and trying to add weight each workout. But you’ll be a more well-rounded lifter if you also know how to lift heavy singles and sets of 10 or 15. Depending on your goals you might consider front squats in addition to back squats, and reverse hypers or kettlebell swings in addition to deadlifts. There are ways to improve at all of these things, and it’s normal for a lifter to be simultaneously increasing their reps in accessory lifts, increasing their weight on the bar for heavy singles, and increasing the amount of time they spend on conditioning workouts. How to spot workouts that don't use progressive overloadNot every workout or routine will have progressive overload built in. For example, if you have a favorite workout that you do every day, but you never make it any harder (say, it's always three sets of ten pushups), you won't make progress over time. That's OK if you enjoy the workout for another reason, like if you're just trying to get the mental health benefits of a little exercise boost in the morning. But if you want to get better at pushups, you need to find a way to do more of them over time, or make them harder in some way (like elevating your feet, or doing them with a backpack on). Workouts with progressive overload tend to be personalized to you. If the workout tells you exactly what to do, down to the exact weight of dumbbell to pick up, it's not giving you room to choose the weight that matches your current strength level. The 12-3-30 treadmill workout, for example, is the same for everyone every time. If it's one-size-fits-all, there's no way to progress. That said, some workouts have a sneaky progression built in. If you jog for 30 minutes each day, chances are you'll get a little faster over time even if you don't realize it, and then you're doing more work within the same amount of time. Or if you do "three sets of 10" of an exercise, but each day you pick up whatever dumbbells feel appropriate for that level, you'll probably end up using heavier ones over time. Just make sure you don't get stuck doing the exact same thing month in and month out. The limits of progressive overloadOne last thing, now that we’ve discussed what progressive overload looks like. It’s important to remember that progression happens in the long term. Some competitive lifters might not test their one-rep max outside of competition, which means they’ll only find out once or twice a year how much their deadlift has gone up. That doesn’t mean they haven’t progressed in the meantime. If they’re doing an effective program, consistently challenging themselves, they’re still working. Plateaus are a fact of life when you’re a lifter. Sometimes it takes a while to get stronger. Sometimes you need to work on your technique to be able to express your newfound strength. Sometimes factors like stress or weight loss or changes in your training can make you weaker in the short term, but if you keep training in a way that challenges you, you’ll set new PRs soon enough. View the full article
-
Planned £100mn overhaul of train station will seek to end ‘holding pen’ experience for passengers View the full article
-
The seven states that rely on the Colorado River to supply farms and cities across the U.S. West appear no closer to reaching a consensus on a long-term plan for sharing the dwindling resource. The river’s future was the center of discussions this week at the annual Colorado River Water Users Association conference in Las Vegas, where water leaders from California, Nevada, Arizona, Colorado, New Mexico, Utah, and Wyoming gathered alongside federal and tribal officials. It comes after the states blew past a November deadline for a new plan to deal with drought and water shortages after 2026, when current guidelines expire. The U.S. Bureau of Reclamation has set a new deadline of Feb. 14. Nevada’s lead negotiator said it is unlikely the states will reach an agreement that quickly. “As we sit here mid-December with a looming February deadline, I don’t see any clear path to a long-term deal, but I do see a path to the possibility of a shorter-term deal to keep us out of court,” John Entsminger of the Southern Nevada Water Authority told The Associated Press. An essential resource More than 40 million people across seven states, Mexico, and Native American tribes depend on the water from the river. Farmers in California and Arizona use it to grow the nation’s winter vegetables such as broccoli, cabbage, and carrots. It provides water and electricity to millions of homes and businesses across the basin. But longstanding drought, chronic overuse, and increasing temperatures have forced a reckoning on the river’s future. Existing water conservation agreements that determine who must use less in times of shortage expire in 2026. After two years of negotiating, states still haven’t reached a deal for what comes next. The federal government continues to refrain from coming up with its own solution — preferring the seven basin states reach consensus themselves. If they don’t, a federally imposed plan could leave parties unhappy and result in costly, lengthy litigation. Not only is this water fight between the upper and lower basins, individual municipalities, tribal nations and water agencies have their own stakes in this battle. California, which has the largest share of Colorado River water, has over 200 water agencies alone, each with their own customers. “It’s a rabbit hole you can dive down in, and it is incredibly complex,” said Noah Garrison, a water researcher at the University of California, Los Angeles. No deal emerges During a Thursday panel of state negotiators, none appeared willing to bend on their demands. Each highlighted what their state has done to conserve water, from turf-removal projects to canal lining in order to reduce seepage, and they explained why their state can’t take on more. Instead, they said, others should bear the burden. Entsminger, of Nevada, said he could see a short-term deal lasting five years that sets new rules around water releases and storage at Lakes Powell and Mead — two key reservoirs. Lower Basin states pitched a reduction of 1.5 million acre-feet per year to cover a structural deficit that occurs when water evaporates or is absorbed into the ground as it flows downstream. An acre-foot is enough water to supply two to three households a year. But they want to see a similar contribution from the Upper Basin. The Upper Basin states, however, don’t think they should have to make additional cuts because they already don’t use their full share of the water and are legally obligated to send a certain amount of water downstream. “Our water users feel that pain,” said Estevan López, New Mexico’s representative for the Upper Colorado River Commission. Upper Basin states want less water released from Lake Powell to Lake Mead. But Tom Buschatzke, director of the Arizona Department of Water Resources, said he hasn’t seen anything on the table from the Upper Basin that would compel him to ask Arizona lawmakers to approve those demands. Within the coming weeks, the Bureau of Reclamation will release a range of possible proposals, but it will not identify a specific set of operating guidelines the federal government would prefer. Scott Cameron, the bureau’s acting commissioner, implored the states to find compromise. “Cooperation is better than litigation,” he said during the conference. “The only certainty around litigation in the Colorado River basin is a bunch of water lawyers are going to be able to put their children and grandchildren through graduate school. There are much better ways to spend several hundred million dollars.” —Jessica Hill, Associated Press View the full article
-
When starting a business, securing the right funding is vital for your success. There are several types of startup loans available, each designed to meet different needs. From small microloans to larger SBA loans, knowing your options can help you make informed decisions. Comprehending how to access these funds is fundamental, especially if you face challenges along the way. Let’s explore the key loan options available for startups and how you can navigate this financial environment effectively. Key Takeaways SBA Microloans provide up to $50,000, ideal for new businesses needing smaller amounts, with an average loan of $16,208. SBA 7(a) loans can be hard to secure for startups under two years, but offer larger funding options when approved. Online loans cater to startups with less than one year of operation, offering quicker access to necessary funds. Equipment financing allows startups to acquire essential tools without needing additional collateral, making it a practical option. Merchant Cash Advances (MCAs) offer quick funding based on future sales, though they typically come with higher costs. What Is a Startup Business Loan? A startup business loan is a financial tool designed to help new companies access the funds they need to cover various expenses, such as working capital, inventory, and fixed assets. Unlike traditional loans, these loans often have less stringent requirements, making them more accessible for entrepreneurs. The loan amounts typically range from $1,000 to over $1.5 million, with annual percentage rates starting as low as 4.66%, depending on the lender and loan type. You can qualify for various options, including SBA Microloans up to $50,000 or online loans that may require only a few months of operational history. Many lenders look for a minimum credit score ranging from 570 to 680, so improving your score can boost your chances of approval. If you’re wondering how to get a grant to start a business, keep in mind that startup business loans serve as a viable funding option for new ventures. Types of Startup Business Loans Numerous types of startup business loans exist, each customized to meet the unique needs of new entrepreneurs. For instance, SBA Microloans provide up to $50,000, perfect for small businesses, with an average loan amount of $16,208. If you’re considering a more substantial option, SBA 7(a) loans can be challenging to secure, especially for those with less than two years in operation. Online loans are accessible for startups with one year or less, offering quicker approval than traditional banks. Equipment financing helps you acquire necessary tools without extra collateral, whereas invoice financing allows you to sell unpaid invoices for immediate cash. Moreover, Merchant Cash Advances (MCAs) base funding on future sales, making them easier to qualify for, though they tend to be expensive. Don’t forget to explore startup business grants as well; knowing how to get grant money to start a business can greatly aid your business launch. Best Startup Business Loan Options When starting a new business, finding the right funding option can greatly impact your success. Several excellent startup business loan options can help you manage your business finances effectively. Fora Financial offers loans up to $1.5 million with a minimum credit score of 570 and just six months in business, making it accessible for new ventures. If you need quick cash, OnDeck provides short-term loans from $5,000 to $250,000, requiring a credit score of 625 and offering same-day funding. For flexible borrowing, Headway Capital‘s line of credit up to $100,000 is a great choice, with a credit score requirement of 625. Fundbox specializes in lines of credit based on invoices, allowing quick access up to $250,000 for those with a score of 600. Finally, National Funding focuses on equipment financing, helping you acquire necessary tools without additional collateral. These options can be essential as you explore how to start a business and attract investors for a business. How to Get a Startup Business Loan Securing a startup business loan requires careful planning and a clear comprehension of your financial needs. Start by realistically evaluating how much capital you need for marketing, inventory, and operations. Next, confirm your eligibility by reviewing lender requirements, which often necessitate a minimum of six months in business and specific revenue thresholds. Research multiple lenders to prequalify, comparing their rates, terms, and repayment schedules to find the best fit for your business. Compile vital documentation, such as business licenses, bank statements, and financial projections, to strengthen your loan application. Moreover, explore grants for new business owners, as they can provide critical funding—ask yourself, how can you get a grant to start a business? Finally, understand the steps to set up a company, ensuring everything is in order before applying for your loan. By following these guidelines, you can increase your chances of securing the financing you need. What to Do If Denied a Startup Business Loan Facing a denial for a startup business loan can be disheartening, but it’s important to view it as an opportunity for growth and improvement. Start by inquiring with the lender about the specific reasons for the denial; comprehending their concerns can help you address them before reapplying. Strengthen your business plan by incorporating projected financial statements and clearer market analysis, which can improve future applications. Consider exploring alternative financing options, such as microloans or crowdfunding, which often have more flexible requirements. You might likewise look into grants for young business owners from government agencies or private foundations, as these funds don’t need to be repaid, though competition can be tough. Finally, evaluate borrowing from friends and family, ensuring you communicate loan terms clearly to avoid misconceptions and maintain valuable relationships. Each step can help you move closer to securing the funding you need for your small business to start. Alternatives to Startup Business Loans If you’re exploring funding options for your startup, consider alternatives to traditional business loans that might better suit your needs. Startup business grants are a great option, as they come from federal and private organizations, often targeting specific industries, and they don’t require repayment. Business credit cards can provide quick access to cash for daily operations, allowing you to manage short-term expenses as you build credit for future financing. If business loans aren’t available, personal loans can help cover startup costs, even though they may carry higher interest rates. Crowdfunding platforms are another avenue, enabling you to raise capital from many individuals online; a compelling pitch is key to attracting contributions. Furthermore, friends and family can offer funding through personal loans or gifts, usually with fewer formalities. Nevertheless, it’s essential to communicate terms clearly to avoid misunderstandings. Explore these alternatives to find the best fit for your startup’s needs. Tips for Comparing Startup Business Loans When you’re ready to compare startup business loans, how do you know which option is best for you? Start by evaluating the types of loans available, such as SBA microloans, online loans, and equipment financing. Next, check the interest rates and Annual Percentage Rates (APRs), which can differ notably among lenders. Loan Type Interest Rates Minimum Credit Score Requirements SBA Microloans 4.66% – 9% 650 Online Loans 7% – 30% 500 – 700 Equipment Financing 5% – 15% 600 Additionally, review the minimum credit score requirements, as higher scores typically lead to better terms. Analyze repayment terms, which can range from short (12-24 months) to more flexible options, and don’t forget to take into account customer service and online reviews to guarantee a smooth borrowing experience. Frequently Asked Questions Can You Get a Loan of $50,000 for a Startup Business? Yes, you can get a loan of $50,000 for a startup business. Options include SBA Microloans, which offer up to $50,000, and online lenders with fewer restrictions, often requiring a minimum credit score of around 600. To improve your chances of approval, prepare a solid business plan and relevant financial documents. Moreover, consider alternative financing methods like equipment financing or lines of credit customized to specific business needs. Can a New LLC Get a Small Business Loan? Yes, a new LLC can get a small business loan, but it often faces stricter requirements. You’ll need a solid business plan and a personal credit score typically between 570 and 680. Many lenders require your LLC to be operational for at least six months, though some online lenders consider three months. Furthermore, building relationships with lenders and providing thorough financial documentation can improve your chances of securing funding successfully. Can You Get a Loan for a Start-Up Business? Yes, you can get a loan for a start-up business. Various options exist, including SBA microloans and online loans, which often have less strict requirements. Nevertheless, lenders typically expect a solid business plan, proof of revenue, and a decent credit score, usually between 500 and 680. Keep in mind that although alternative financing like merchant cash advances offers quick cash, they often come with higher costs. Always evaluate the terms carefully before proceeding. Can I Use My EIN to Get a Loan? Yes, you can use your Employer Identification Number (EIN) to apply for a loan. Lenders often require an EIN to verify your business’s legitimacy and financial history. Having an EIN helps separate your personal and business finances, which can improve your chances of approval. Nevertheless, keep in mind that lenders additionally consider other factors, such as your credit score and business plan, when evaluating your loan application. Conclusion Securing the right funding is essential for your startup’s success. By comprehending the various types of loans available, such as SBA Microloans and Merchant Cash Advances, you can make informed decisions that align with your business needs. If you encounter challenges in obtaining a loan, exploring alternative funding options can likewise be beneficial. Always compare different loan offerings to guarantee you choose the best fit for your financial situation and growth objectives, helping you lay a solid foundation for your enterprise. Image via Google Gemini This article, "7 Essential Business Loans for Startup Companies" was first published on Small Business Trends View the full article