Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. Black Friday sales officially start Friday, November 28, and run through Cyber Monday, December 1, and Lifehacker is sharing the best sales based on product reviews, comparisons, and price-tracking tools before it's over. Follow our live blog to stay up-to-date on the best sales we find. Browse our editors’ picks for a curated list of our favorite sales on laptops, fitness tech, appliances, and more. Subscribe to our shopping newsletter, Add to Cart, for the best sales sent to your inbox. Sales are accurate at the time of publication, but prices and inventory are always subject to change. The Nespresso Vertuo Pop+ offers café-style coffee without leaving your kitchen or putting on pants, and it's currently on sale for $74.99 on StackSocial. It’s small enough to fit on even the most crowded countertops (about the size of a toaster), but still delivers that signature Vertuo crema with the push of a button. It's a refurbished model with a Grade A rating, meaning the machine comes in a near-mint condition with only minimal wear, and could be a solid pick for anyone who wants fast, customizable coffee without splurging on a brand-new machine. The coffeemaker heats up in just 30 seconds, so you can go from half-asleep to sipping something warm without much of a wait. Brewing is handled with a single button, and the Vertuo barcode system automatically adjusts for cup size and strength. Whether you're after a 1.35-ounce espresso or a 12-ounce coffee, it reads the pod and takes care of the rest. There's also a Coffee Creations Mode that activates with a quick double-tap, brewing a more concentrated shot that holds up better over ice, which is useful if you’re into iced coffee or milk drinks. It even has Bluetooth and wifi support, which won’t affect your coffee’s flavor but does help with maintenance alerts through the app, especially if you’re the type to ignore descaling until it's too late. That said, the Pop+ only works with Vertuo capsules, and none come in the box, so your first cup requires a separate purchase. These capsules also cost more than Nespresso’s Original line, though you get over 40 blends and seasonal editions to choose from. The machine also shuts off after two minutes to save energy, which is efficient but can feel a bit annoying if you step away between brews. Still, it's a compact, dependable, and easy-to-use coffeemaker, and the refurb rating removes most of the usual uncertainty that comes with secondhand appliances. If you want quick, varied cup sizes with little cleanup and don’t mind sticking to the Vertuo capsule system, this deal makes the Pop+ an easy machine to consider. How long do Black Friday deals really last?Black Friday sales officially begin Friday, November 28, 2025, and run throughout “Cyber Week,” the five-day period that runs from Thanksgiving through Cyber Monday, December 1, 2025. But Black Friday and Cyber Monday dates have expanded as retailers compete for customers. You can get the same Black Friday sales early, and we expect sales to wind down by December 3, 2025. What stores have the best sales on Black Friday?Nowadays, both large retailers and small businesses compete for Black Friday shoppers, so you can expect practically every store to run sales through Monday, December 1, 2025. The “best” sales depend on your needs, but in general, the biggest discounts tend to come from larger retailers who can afford lower prices: think places like Amazon, Walmart, Target, Best Buy, and Home Depot. You can find all the best sales from major retailers on our live blog. Are Black Friday deals worth it?In short, yes, Black Friday still offers discounts that can be rare throughout the rest of the year. If there’s something you want to buy, or you’re shopping for gifts, it’s a good time to look for discounts on what you need, especially tech sales, home improvement supplies, and fitness tech. Of course, if you need to save money, the best way to save is to not buy anything. Our Best Editor-Vetted Early Black Friday Deals Right Now Apple AirPods Pro 3 Noise Cancelling Heart Rate Wireless Earbuds — $219.99 (List Price $249.00) Apple iPad 11" 128GB A16 WiFi Tablet (Blue, 2025) — $279.00 (List Price $349.00) Amazon Fire HD 10 (2023) — $69.99 (List Price $139.99) Sony WH-1000XM5 — $248.00 (List Price $399.99) Blink Outdoor 4 1080p Wireless Security Camera (5-Pack) — $159.99 (List Price $399.99) Amazon Fire TV Stick 4K Plus — $24.99 (List Price $49.99) NEW Bose Quiet Comfort Ultra Wireless Noise Cancelling Headphones — $298.00 (List Price $429.00) Shark AI Ultra Matrix Clean Mapping Voice Control Robot Vacuum with XL Self-Empty Base — $249.99 (List Price $599.00) Apple Watch Series 11 (GPS, 42mm, S/M Black Sport Band) — $349.00 (List Price $399.00) Western Digital 14TB Elements Desktop External Hard Drive — $169.99 (List Price $279.99) Deals are selected by our commerce team View the full article
-
In a move set to transform operations for midsize businesses, Workday has unveiled significant updates to its Workday GO platform, designed to streamline HR and financial management. This comprehensive, all-in-one solution is targeted at the 90% of global companies identified as midsize, addressing their unique challenges and empowering them with advanced technology often reserved for larger enterprises. Midsize businesses are critical players in the economy, generating approximately 70% of global employment and contributing significantly to GDP. Yet, many of these organizations grapple with outdated systems and inefficiencies, which hinder their ability to compete effectively. Workday GO seeks to bridge this gap by offering industry-leading HR, payroll, and AI capabilities under one roof, making it easier for these businesses to manage their operations. “Midsize organizations are often forced to choose between powerful technology and practical simplicity,” explained Max Wessel, Workday’s Senior Vice President of Growth. “Workday GO changes that equation. We’ve combined the power of enterprise-grade HR, payroll, and AI with one predictable price, one trusted partner ecosystem, and one of the simplest deployment experiences in the market—so every growing business can scale confidently.” The introduction of Workday GO Global Payroll stands out as one of the most critical features for small business owners looking to expand internationally. Payroll complexities can escalate when businesses enter new markets, facing varying compliance rules and regulations. Workday GO Global Payroll offers a seamless, integrated system designed to pay employees worldwide easily. Job van der Voort, CEO of Remote, noted, “Workday GO Global Payroll removes one of the biggest barriers to global growth: disconnected systems for hiring and paying international teams.” Another layer of support is provided through the new Workday GO Partner Network, which consists of global payroll, benefits, and deployment partners. This ecosystem allows businesses to upscale operations while minimizing the typical complexities associated with international expansion. With partners like Benefit Harbor and OneSource Virtual, companies can more easily navigate the intricacies of global hiring and compliance. Workday’s innovations don’t stop at payroll. They have introduced the Deployment Agent to facilitate quicker, easier setups for the Workday GO platform. This AI-powered assistant minimizes complexity and lowers implementation time by up to 25%, enabling businesses to achieve operational efficiency sooner. Denise Trentin, Manager of Global HR Projects at Master Builders Solutions, shared her positive experience: “With Workday GO, we went from kick-off to go-live in just 42 working days—a clear sign of strong teamwork and focus to deliver in time, scope, and budget.” Midsize organizations can also benefit from embedded Workday agents from day one, which are designed to automate processes, reduce manual work, and allow teams to focus on strategic growth. The ability to access enterprise-grade AI capabilities equips small businesses to operate more efficiently, driving growth with fewer resources. While these advancements present an opportunity for small businesses to leverage cutting-edge technology, they also pose considerations. Transitioning to a new system can require upfront investment and training resources. Small business owners should weigh the potential benefits against these costs. Upgrading systems could lead to operational disruptions if not executed carefully, creating challenges during the transition period. The next iteration of Workday GO, featuring the Deployment Agent, Workday GO Global Payroll, and the integration of partner solutions, is set to launch in February 2026 across markets including the U.S., U.K., Canada, Germany, Ireland, and France, with plans for further expansion. For small business owners, implementing systems like Workday GO can foster growth, enhance operational efficiency, and facilitate international expansion without the headache of complicated processes. At a time when adaptability is paramount, these solutions may prove invaluable in navigating the evolving business landscape. Eventual pricing structures, user experiences, and integration approaches will be critical for small businesses as they consider Workday GO. More details on this solution are available in the original press release at Workday Newsroom. As companies strive for future success and efficient scalability, platforms like Workday GO could provide the strategic edge needed to compete effectively in an increasingly complex global market. Image via Google Gemini This article, "Workday Launches GO to Simplify Global Payroll for Midsize Businesses" was first published on Small Business Trends View the full article
-
Expansion plan for London’s hub airport will require moving the M25 motorway View the full article
-
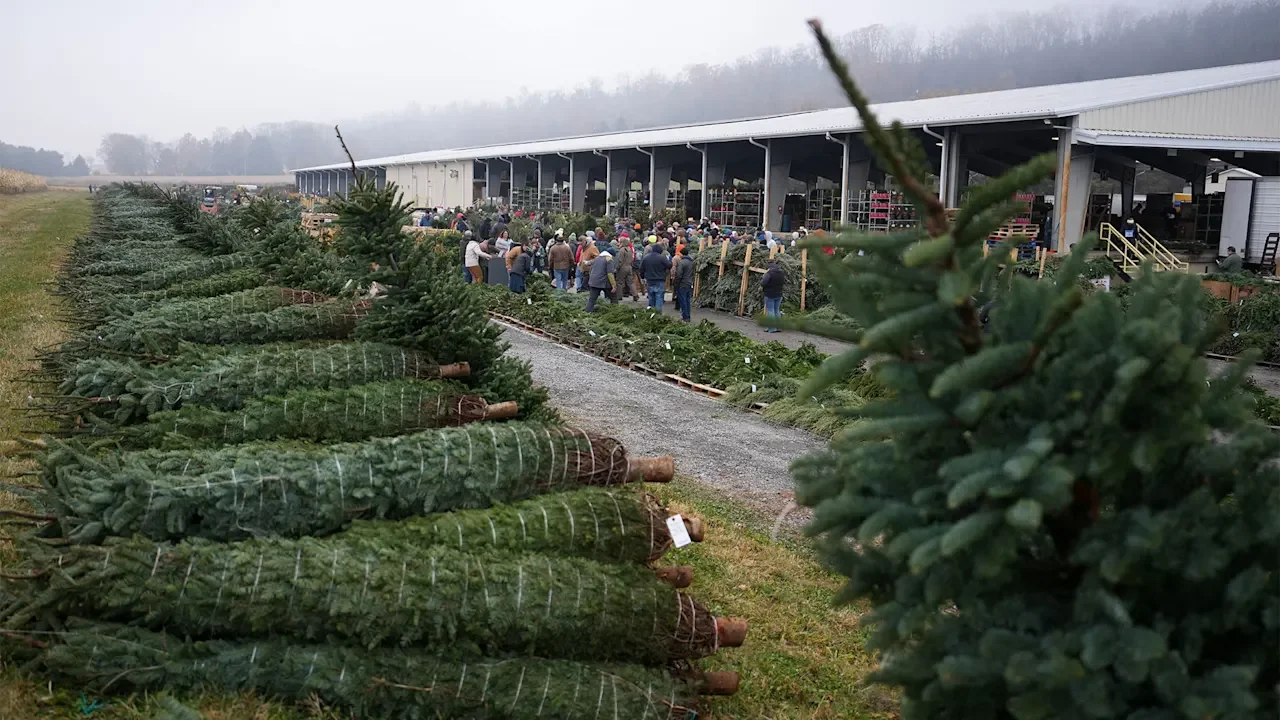
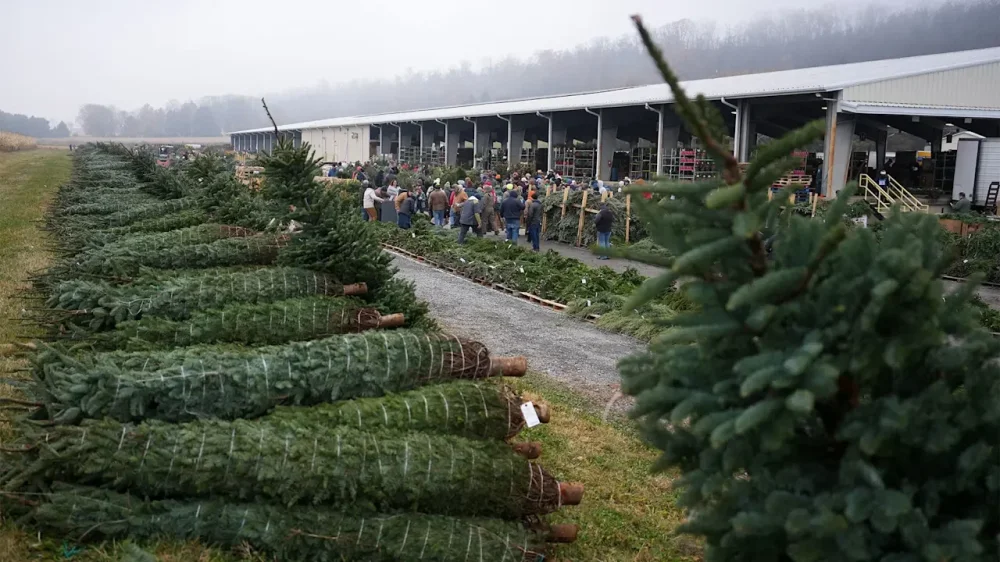
Christmas went on the auction block this week in Pennsylvania farm country, and there was no shortage of bidders. About 50,000 Christmas trees and enough wreaths, crafts and other seasonal items to fill an airplane hangar were bought and sold by lots and on consignment at the annual two-day event put on at the Buffalo Valley Produce Auction in Mifflinburg. Buyers from across the Northeast and mid-Atlantic were there to supply garden stores, corner lots and other retail outlets for the coming rush of customers eager to bring home a tree — most commonly a Fraser fir — or to deck the halls with miles of greenery. Bundled-up buyers were out in chilly temperatures to hear auctioneers hawk boxes of ornaments, bunches of winterberry, cotton branches, icicle lights, grave blankets, red bows and tree stands. It was nearly everything you would need for Christmas except the food and the presents. Americans’ Christmas tree buying habits have been evolving for many years. These days homes are less likely than in years past to have a tree at all, and those that do have trees are more likely to opt for an artificial tree over the natural type, said Marsha Gray with the Howell, Michigan-based Real Christmas Tree Board, a national trade group of Christmas tree farmers. Cory Stephens was back for a second year at the auction after his customers raved about the holiday decor he purchased there last year for A.A. Co. Farm, Lawn & Garden, his store a three-hour drive away in Pasadena, Maryland. He spent nearly $5,000 on Thursday. “It’s incredible, it’s changed our whole world,” Stephens said. “If you know what you’re looking for, it’s very hard to beat the quality.” Ryan Marshall spent about $8,000 on various decorations for resale at Ward’s Berry Farm in Sharon, Massachusetts. Among his purchases were three skids of wreaths at $29 per wreath — and he expected to double his money. “The quality’s good, and it’s a place that you can pick it out yourself,” he said. Gray said her group’s research shows the main reason people pick a real tree over an artificial tree “is the scent. They want the fresh scent of a real Christmas tree in their home.” Having children in the house also tends to correlate with picking a farm-grown tree, she said. An August survey by the Real Christmas Tree Board found that 84% of growers did not expect wholesale prices to increase this season. Buffalo Valley auction manager Neil Courtney said farm-grown tree prices seem to have stabilized, and he sees hope that the trend toward artificial trees can be reversed. “Long story short — we’ll be back on top of the game shortly,” Courtney said. “The live tree puts the real Christmas in your house.” A survey by a trade group, the National Christmas Tree Association, found that more than 21 million farm-grown Christmas trees were sold in 2023, with median price of $75. About a quarter of them were purchased at a “choose-and-cut” farm, one in five from a chain store, and most of the rest from nurseries, retail lots, nonprofit sales and online. —Mark Scolforo, Associated Press View the full article
-
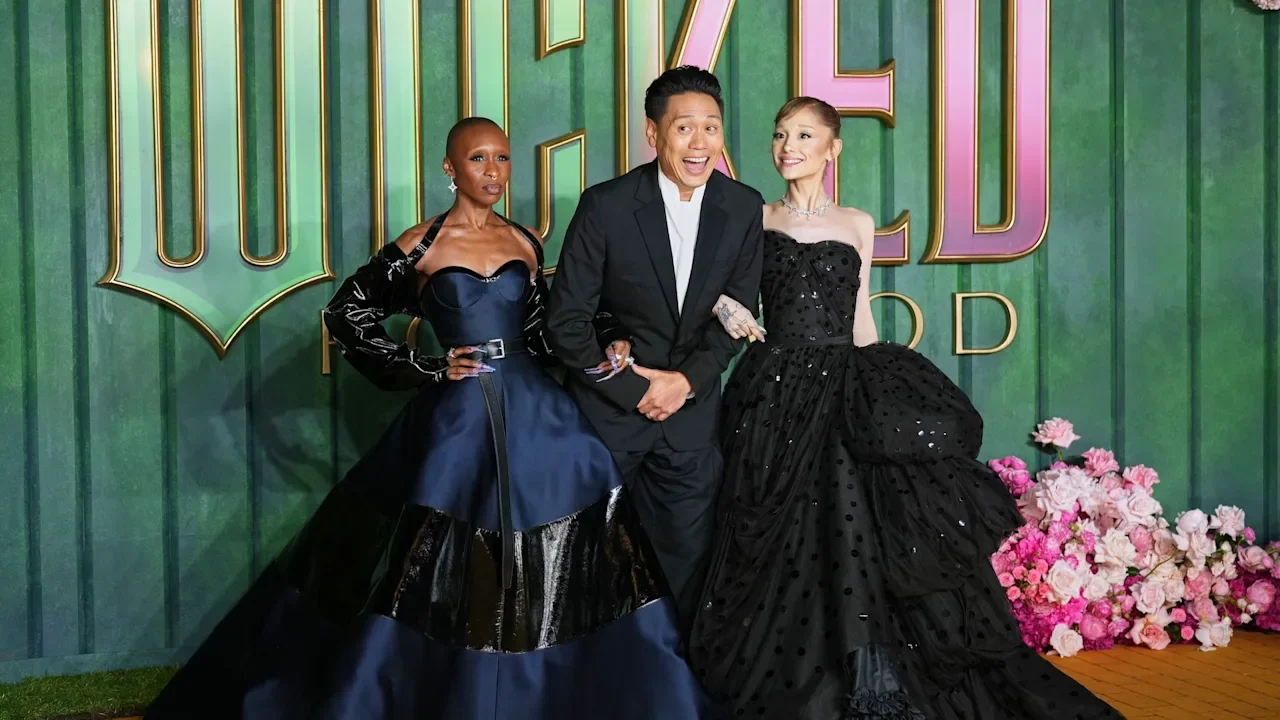
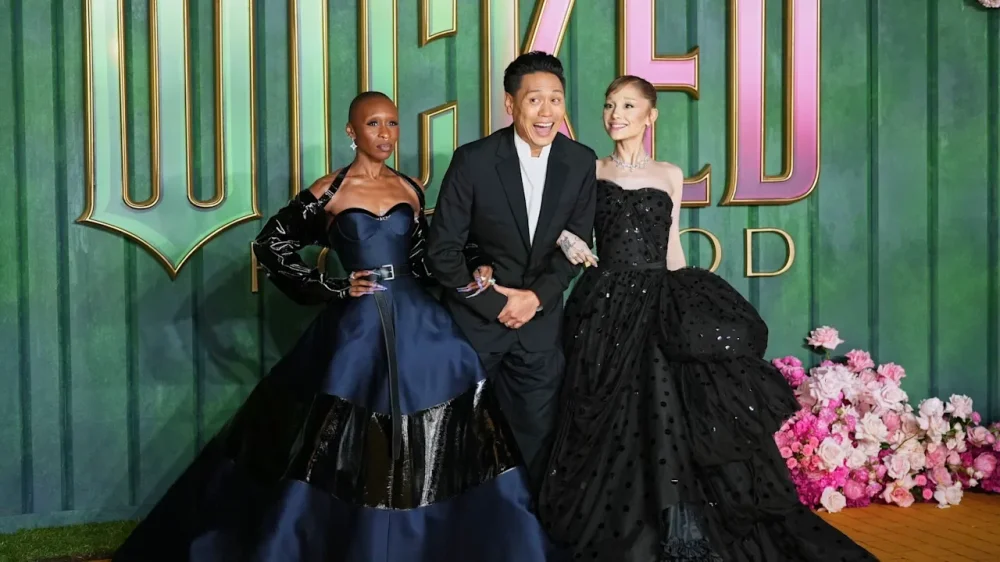
Universal Pictures’ two-part Wicked gamble continues to defy gravity at the box office. Just a year after part one brought droves of audiences to movie theaters around the country, even more people bought opening weekend tickets to see the epic conclusion, Wicked: For Good. According to studio estimates on Sunday, Wicked: For Good earned $150 million from North American theaters in its first days in theaters and $226 million globally. Not only is it the biggest opening ever for a Broadway musical adaptation, unseating the record set by the first film’s $112 million launch, it’s also the second biggest debut of the year behind A Minecraft Movie’s $162 million. “The results are just fantastic,” said Jim Orr, who heads domestic distribution for Universal. “Some films can deliver a false positive when tickets go on sale early but these results speak for themselves.” Universal began rolling out Wicked: For Good in theaters earlier this week, with previews on Monday ($6.1 million from 1,050 theaters) and Wednesday ($6.5 million from 2,300 theaters). By Friday, it was playing in 4,115 North American locations and had raked in $68.6 million. IMAX showings accounted for $15.5 million, or 11%, of its domestic haul—a November record for the company. IMAX CEO Rich Gelfond said in a statement that the strong market share shows, “our momentum carries into demos and genres beyond our traditional core, including families.” As with the first film, women powered the opening weekend, making up around 71% of ticket buyers according to PostTrak exit polls. Critics were somewhat mixed on the final chapter, but audiences weren’t: An overwhelming 83% of audiences said it was one they would “definitely recommend” to friends. As far as foot traffic is concerned, the box office tracker EntTelligence estimates that about two million more people came out for Wicked: For Good‘s first weekend than for Wicked‘s.” Jon M. Chu directed both Wicked films, starring Cynthia Erivo and Ariana Grande. The first film made over $758.7 million worldwide and received 10 Oscar nominations (winning two, for costume and production design). The question is how high Wicked: For Good can soar. Combined, the two films cost around $300 million to produce, not including marketing and promotion costs. “The first film paved the way,” Orr said. “It’s really become a cultural event I think audiences are going to be flocking to theaters for quite some time to come.” Two other films also opened in wide release this weekend, but further down on the charts behind a buffet of holdovers. Searchlight Pictures opened its Brendan Fraser film Rental Family in 1,925 theaters, where it earned $3.3 million. The Finnish action film Sisu: Road to Revenge, a Sony release, also played in 2,222 theaters. It earned an estimated $2.6 million. Second place went to Now You See Me: Now You Don’t with $9.1 million in its second weekend, followed by Predator: Badlands with $6.3 million in weekend three. The Running Man followed in fourth place with $5.8 million, down 65% from its debut last weekend. Although this weekend the box office was more of a winner takes all scenario, Wicked: For Good’s success is vitally important for the exhibition industry as a whole as it enters the final weeks of the year. “It sets up a very strong final homestretch of the year,” said Paul Dergarabedian, Comscore’s head of marketplace trends. After the slow fall season, the Thanksgiving blockbusters could not arrive soon enough. Early next week, Zootopia 2 enters the mix and is also expected to drive big crowds to the cineplex over the holiday break. Thanksgiving is often one of the biggest moviegoing frames of the year, Dergarabedian said, and both Wicked 2 and Zootopia 2 will benefit. Last year Wicked, Moana 2, and Gladiator II helped power a record five-day frame. The running domestic box office is currently hovering around $7.5 billion, according to Comscore. Before the pandemic, the annual box office would regularly hit $11 billion, but the post-pandemic goal has lessened to $9 billion. The big question now is whether titles like Wicked: For Good, Zootopia 2, and Avatar: Fire and Ash can push the industry over that threshold. Top 10 movies by domestic box office With final domestic figures being released Monday, this list factors in the estimated ticket sales for Friday through Sunday at U.S. and Canadian theaters, according to Comscore: 1. Wicked: For Good, $150 million. 2. Now You See Me: Now You Don’t, $9.1 million. 3. Predator: Badlands, $6.3 million. 4. The Running Man, $5.8 million. 5. Rental Family, $3.3 million. 6. Sisu: Road to Revenge, $2.6 million. 7. Regretting You, $1.5 million. 8. Nuremberg, $1.2 million. 9. Black Phone 2, $1 million. 10. Sarah’s Oil, $711,542. —Lindsey Bahr, AP film writer View the full article
-
Last week, tech headlines were abuzz with a concerning claim: According to some on social media platforms, and even some news outlets, Google had secretly opted Gmail users into sharing their emails with Gemini. The goal? To train Google's AI. While this controversy set off quite a lot of noise, it appears much of the conversation kicked off with this inflammatory post on X, complete with select words in all caps: This Tweet is currently unavailable. It might be loading or has been removed. According to the poster, the only remedy for the situation is to disable a setting you've probably never heard of: "smart features." The claims suggest "smart features" was switched on in two locations on your account: One that controls Gmail, Chat, and Meet, and another that enables it in the larger Google Workspace suite—assuming you have a Workspace account. The "smoking gun" is a small part of Google's privacy policy which says that the company does not use your Workspace data to train its AI models, without permission. Taken at face value, the assertion is that Google opted you into these settings, thus taking your "permission" to start using your data for this AI training. As of this morning, the post has nearly 150,000 likes on X, but the claims spread far and wide across the internet. Even Malwarebytes ran a story explaining the situation, and urging users to disable these settings to keep their messages out of Google's AI training. As it turns out, however, Google doesn't actually appear to be doing this. What are "smart features?" I reached out to Google on Friday to see if the company had any comment concerning these claims. In response, I received the following from a Google spokesperson: "These reports are misleading—we have not changed anyone’s settings, Gmail Smart Features have existed for many years, and we do not use your Gmail content for training our Gemini AI model. Lastly, we are always transparent and clear if we make changes to our terms of service and policies." Indeed, "smart features" has existed for years. In fact, Lifehacker first covered the setting back in 2020, nearly three years before Google first launched Bard (now Gemini). To the claimants' credit, smart features does use your data to improve Google features, but not to train AI models en masse. Instead, smart features uses your data to customize your specific Google experience. In Gmail, that might mean learning how you write, to generate more relevant smart replies; in Search, that might mean suggesting keywords based on previous searches; in Maps, that might mean showing restaurant reservations; in Wallet, that might mean recommending tickets for shows based on your interests. Smart features also powers core Google features, like spam filters and categorization. That's not to say that you should necessarily be down for smart features: If you personally don't care for Google collecting your data to customize your personal experience, you can absolutely turn these features off. But it's important to understand what you're choosing to turn on or off: Just because someone claims that these features are doing something doesn't make it true. Turn off smart features if you want, but just know that it has no impact on how Google handles your private messages, or how it trains its AI models for everyone. Plus, it may impact how apps like Gmail function: You may not be able to sort your emails into categories, or stop certain spam from getting into your inbox. How to disable "smart features"If you do want to turn off smart features, it's easy to do. You'll find the settings in the Gmail web app: Click the settings gear, then choose "See all settings." Here, scroll down, and disable the toggle next to "Smart features." You'll need to agree to "Turn off and reload" Gmail in order to see the changes take effect. If you have a Workspace account, you have another settings page to manage. Click "Manage Workspace smart features settings," then disable the toggles next to "Smart features in Google Workspace" and "Smart features in other Google products." Finally, choose "Save." Just remember: These settings control a number of smart features across your Google products. As such, you might notice certain features missing going forward. To revert your changes, return to these settings pages at any time and flip the toggles back on. Google isn't in the clearThe dust has settled since controversy's peak last week. Malwarebytes issued a correct to its original article, sharing the same spokesperson statement I received. The site says that Google's vague rewrite of the smart features setting contributed to this confusion, but that it does appear the setting doesn't scrape users' private messages to train Gemini. However, that's not to say Google is entirely in the clear here. While this specific claim might not be true, a lawsuit claims the company improperly gave Gemini private user data from Gmail, Chat, and Meet without the permission of those users. Google as a whole doesn't have the best reputation when it comes to respecting users' privacy too, so it's not surprising that these claims took off the way they did. Malwarebytes also makes the point that while Google says these settings are all opt-in, many users don't actually remember opting in themselves, further fueling confusion around smart features. To be candid, I definitely don't remember enabling smart features on either my personal or work Gmail accounts, though it's entirely possible I did. All I know is these settings are on now, and while I'm considering disabling them, I also don't know if I'd be willing to get rid of all smart features. View the full article
-
Gaza Humanitarian Foundation was heavily criticised over killings of Palestinians desperate for foodView the full article
-
Michael Prescott tells MPs there was ‘no ideology at play’ in document that led to exit of director-general View the full article
-
Hard money loans for small businesses are a type of short-term financing secured by collateral, usually real estate or other valuable assets. These loans can provide quick access to funds, often within one to two business days, which can be vital for urgent financial needs. Nevertheless, they come with high interest rates, ranging from 8% to 45%. Comprehending their characteristics and implications is fundamental before deciding if this option fits your business needs. Key Takeaways Hard money loans provide quick funding for small businesses, using collateral such as property or assets to secure the loan. Approval processes are fast, with funds typically available within one to two business days, regardless of the borrower’s credit score. Interest rates on hard money loans range from 8% to 45%, reflecting the lender’s risk and the short repayment periods of up to two years. Loan amounts usually vary between $50,000 to $2 million, based on the collateral’s value and requiring down payments ranging from 10% to 30%. While accessible, hard money loans carry risks due to high interest and short terms, making careful financial planning essential for borrowers. Understanding Hard Money Loans When you’re exploring financing options for your small business, grasping hard money loans is essential, especially if you need quick access to funds. Hard money loans for small businesses are secured loans, relying on your company’s property or assets as collateral. Unlike traditional loans, private hard money loans focus more on the collateral value than your credit score, making them accessible even for startups or those with poor credit histories. The approval process is faster, allowing you to get quick hard money loans within one to two business days. Nonetheless, keep in mind that these loans often come with high interest rates, ranging from 8% to 45%, and short repayment terms, typically capped at two years or less. Characteristics of Hard Money Loans Hard money loans are structured around collateral, meaning your business assets secure the loan rather than relying on your credit history. You’ll notice that these loans often come with high interest rates, sometimes ranging from 8% to 45%, reflecting the lender’s assessment of risk. Furthermore, repayment terms are typically brief, typically lasting from a few months to two years, which requires you to generate cash flow quickly to meet your obligations. Collateral-Based Financing Structure Securing a hard money loan involves leveraging your company’s property or assets as collateral, which shifts the focus from your credit history to the value of the asset itself. This collateral-based financing structure allows you to access hard money loans for real estate ascertaining lenders assess the collateral’s worth rather than your financial history. Typically, the loan-to-value (LTV) ratio ranges from 50% to 75%, meaning you can borrow a significant portion of your asset’s appraised value. While some no money down hard money lenders exist, most require a down payment of 10% to 30%. For first-time investors, comprehending these requirements is essential to maneuvering the lending environment effectively and securing the funds needed for your business endeavors. High Interest Rates Interest rates on hard money loans can be considerably higher than those offered by traditional lenders, often ranging from 8% to 45%. These high interest rates reflect the increased risk lenders assume, especially when lending to borrowers with poor credit or limited financial histories. While some lenders may provide fast hard money loans with no down payment, the total cost can escalate quickly because of these steep rates. Most hard money loans feature fixed interest rates, but adjustable rates can likewise be part of the deal, leading to unpredictable costs over time. As a result, it’s essential to fully understand how high interest rates will impact your overall financial obligations before committing to a hard money loan. Short Repayment Terms When considering a hard money loan, it is vital to understand that these loans typically come with short repayment terms, often lasting just a few months up to two years. This urgency means you need to prepare for quick repayment, making them suitable for immediate funding needs. It’s important to have a clear exit strategy, whether refinancing or selling the property, to avoid defaulting on the loan. The higher interest rates associated with hard money home loans can increase your repayment burden within that limited timeframe. Keep in mind that approval relies heavily on the collateral’s value, so you must be confident in your ability to meet these short-term obligations. Feature Description Importance Term Length Few months to 2 years Quick funding needs Exit Strategy Requirement Necessary to avoid default Important for financial planning Collateral Value Focus Over cash flow or credit history Guarantees loan approval Higher Interest Rates Amplifies repayment costs Increases overall costs Urgency in Repayment Financial pressure on borrowers Demands immediate attention How Hard Money Loans Work Hard money loans operate primarily on the value of the collateral, often real estate, rather than the borrower’s creditworthiness. To get a hard money loan, you’ll typically approach hard money real estate lenders who assess the property’s value to determine your loan amount. Loan-to-value (LTV) ratios usually range from 50% to 75%, allowing you to borrow a portion of the collateral’s worth. The approval process is faster than traditional loans, often taking just a few days because of fewer documentation requirements. Nevertheless, expect higher interest rates, ranging from 8% to 45%, reflecting the risk associated with these loans. Pros of Hard Money Loans One of the main advantages of hard money loans is the quick access to funds, which can be crucial for small businesses in need of immediate capital. Approval often occurs within 24 hours, and you could receive your funds in just one to two business days. These loans are particularly beneficial for those with poor credit since they focus on the value of your collateral rather than your credit score. Hard money lenders typically offer loan-to-value ratios ranging from 50% to 75%, enabling you to leverage your assets for financing. Furthermore, the streamlined application process requires minimal documentation, making it easier for you to secure necessary capital. You can use hard money loans for working capital, debt refinancing, or urgent business acquisitions. Cons of Hard Money Loans When considering hard money loans, you should be aware of the high interest rates that can range from 8% to 45%, making them considerably more expensive than traditional financing options. Furthermore, the short repayment terms, often spanning just a few months to a couple of years, can pressure your business to quickly generate cash flow. These factors can create a challenging financial environment, making it crucial to carefully evaluate whether this type of loan aligns with your business needs. High Interest Rates Many borrowers may find themselves drawn to hard money loans owing to their quick approval processes and flexible terms, but the high interest rates present a significant drawback. These rates can range from 8% to a staggering 45%, far exceeding traditional loans that start around 6.25%. Here are some key points to reflect on: Higher rates reflect the increased risk lenders take on, as they focus on collateral value rather than creditworthiness. The financial burden can escalate quickly as a result of high rates and potential additional fees. Short repayment terms intensify financial pressure on borrowers. Defaulting on a hard money loan can lead to losing the collateralized property, making careful evaluation crucial. Short Repayment Terms Short repayment terms are a notable drawback of hard money loans, often ranging from just a few months to two years. This urgency can pressure you to quickly generate cash flow, resulting in higher monthly payments that may strain your business’s finances. As the repayment period shortens, the risk of default increases, forcing you to either repay the loan in full or refinance before the term ends. Many hard money loans require a large lump-sum payment at the end, which can be challenging to manage for small businesses. Furthermore, the brief duration makes these loans less suitable for long-term financing needs, often trapping you in a cycle of seeking new loans to cover existing debt obligations. Comparing Hard Money Loans and Traditional Loans Though both hard money loans and traditional loans serve as financing options for small businesses, they differ markedly regarding structure and terms. Here’s a comparison to help you understand the key differences: Interest Rates: Hard money loans typically have higher rates, ranging from 8% to 45%, whereas traditional loans start around 6.25%. Repayment Terms: Hard money loans have shorter repayment periods, often from six months to two years, in contrast to traditional loans which can last 20-25 years. Loan-to-Value Ratios: Hard money loans usually cap at 65-75% LTV, whereas traditional loans may reach up to 90%. Approval Criteria: Hard money lenders focus on collateral value, whereas traditional loans require a credit score of 670 or higher for approval. Eligibility Criteria for Hard Money Loans When considering hard money loans, you’ll need to focus on the collateral you can provide, as these loans primarily hinge on the value of your assets, like real estate or equipment. Lenders typically assess the loan-to-value (LTV) ratio, which usually falls between 50% and 75%, determining how much you can borrow based on the collateral’s worth. Furthermore, preparing financial documentation is crucial, as lenders may require proof of your assets and a down payment that often ranges from 10% to 30%, depending on their evaluation of your situation. Collateral Requirements Collateral requirements play a crucial role in securing hard money loans for small businesses, as these loans are primarily backed by valuable assets. Lenders focus on the collateral’s value rather than your creditworthiness, making it easier for those with poor credit histories to qualify. Here are key factors to reflect upon: Type of Collateral: Real estate is the most common, but other valuable assets may likewise qualify. Loan-to-Value (LTV) Ratio: Expect LTV ratios between 50% and 75%, meaning you’ll receive a fraction of the collateral’s appraised value. Down Payment: Higher down payment requirements, usually between 10% and 30%, are common. Asset Condition: Confirm your collateral is in good condition and has a clear title to avoid complications. Financial Documentation Needed Securing a hard money loan often requires specific financial documentation that demonstrates the value of your collateral and your business’s viability. Unlike traditional loans, the paperwork is usually minimal, focusing on crucial documents. You’ll need proof of ownership for the collateral property, property valuation reports, and a detailed business plan outlining how you plan to use the funds. Although credit scores aren’t a primary concern, some lenders might request a credit report to evaluate your overall financial stability. Furthermore, providing financial statements or tax returns can showcase your business revenue and cash flow, strengthening your application. Since documentation requirements can vary by lender, it’s wise to check with them about what specific information they’ll need. Application Process for Hard Money Loans The application process for hard money loans is designed to be straightforward and efficient, making it an appealing option for small business owners in need of quick funding. Here’s what you typically need to do: Gather Property Information: Provide details about the property you’ll use as collateral, including its appraised value and condition. Prepare a Business Plan: Many lenders require a detailed business plan outlining how you’ll use the funds and guarantee repayment. Submit Minimal Documentation: Focus primarily on the collateral’s value rather than your credit history or business performance. Apply to Multiple Lenders: Submit applications to various lenders to compare terms, interest rates, and repayment schedules, helping you secure the best deal. Expect approval within 24 to 72 hours, allowing quick access to funds. Typical Loan Terms and Conditions When you’re considering hard money loans for your small business, it’s essential to understand the typical loan terms and conditions. You’ll usually face interest rates ranging from 8% to 45%, with repayment periods that can last from a few months up to two years. Furthermore, be prepared for loan amounts to be capped at a percentage of your collateral’s value, often limiting your access to a portion of what you might need. Loan Amount Limits Hard money loans for small businesses typically range from $50,000 to $2 million, allowing borrowers to access substantial funding based on the value of their collateral. The loan amount you can secure often depends on several factors: Collateral Value: The more valuable your collateral, the higher the loan amount you might receive. Loan-to-Value (LTV) Ratio: This usually caps at 50% to 75%, meaning you can obtain a loan based on that percentage of your collateral’s appraised value. Repayment Terms: These typically range from six months to three years, with options for lump-sum payments or interest-only payments. Down Payment Requirements: Expect to provide a down payment of 10% to 30% or more, based on your credit profile and lender’s terms. Interest Rate Ranges Interest rates for hard money loans can vary considerably, typically ranging from 8% to 45%, based on factors such as the lender’s assessment of risk and the specifics of your financial situation. The perceived risk is influenced by your creditworthiness, the collateral value, and market conditions. You should also take into account that most hard money loans require down payments of 10% to 30% or more, depending on your financial profile and the collateral’s strength. Furthermore, loan-to-value (LTV) ratios usually cap at around 50% to 75%, limiting how much you can borrow against the property. Be aware of extra fees, such as origination and processing costs, which can further increase your overall borrowing expenses. Repayment Period Duration Though many small businesses seek quick access to funds, the repayment period for hard money loans reflects this urgency, typically ranging from just a few months to two years. Most lenders expect repayment within 6 to 24 months, making these loans suitable for short-term financing rather than long-term capital needs. Here are some key points to take into account: Interest Rates: They usually range from 8% to 15%, affecting overall borrowing costs. Down Payments: Typically, you’ll need to pay 10% to 30% or more upfront. Loan-to-Value (LTV) Ratios: These typically cap at 50% to 75%, determining your maximum loan amount. Flexibility: Short terms allow for quicker access to capital but require prompt repayment. When to Consider Hard Money Loans When you find yourself in need of quick access to capital, hard money loans can be a viable option for your small business. Consider these loans if you have time-sensitive opportunities, like purchasing real estate or making urgent renovations. They’re particularly useful for startups or businesses with poor credit histories that struggle to secure traditional financing. If you have valuable collateral, you can leverage it for immediate funding. Furthermore, hard money loans are ideal when facing cash flow issues, as you might receive approval within 24 hours and funding in just one to two business days. Nevertheless, before committing, make sure you have a clear repayment strategy in place, given the high interest rates and short repayment terms associated with these loans. Alternatives to Hard Money Loans Are you exploring funding options beyond hard money loans for your small business? There are several alternatives that might suit your needs better. Consider the following options: Traditional Bank: These usually offer lower interest rates and longer repayment terms, but require good credit and a solid business history. Invoice Factoring: This lets you sell unpaid invoices to a third party at a discount, providing immediate cash flow without collateral. Equipment Financing: Customized for purchasing specific assets, this allows you to borrow against the equipment’s value, often resulting in better terms. Business Lines of Credit: These offer flexible funding, letting you draw funds as needed and pay interest only on the amount used, potentially lowering costs. Tips for Using Hard Money Loans Effectively Using hard money loans effectively requires a strategic approach to confirm that your business can meet its financial obligations without compromising its stability. Here are some tips to contemplate: Tip Description Clear Repayment Strategy Assess cash flow projections to guarantee timely payments and avoid default. Strategic Use Utilize loans for urgent needs or growth opportunities to maximize impact. Negotiate Terms Discuss interest rates and repayment schedules for manageable obligations. Maintain Transparency Keep your lender informed about business performance and challenges. Monitor Performance Regularly check your business metrics to adjust strategies and avoid overleveraging. Risks Associated With Hard Money Loans Though hard money loans can provide quick access to capital for small businesses, they likewise carry significant risks that you must consider. Here are some key risks associated with these loans: High Interest Rates: Expect rates between 8% and 45%, which can drastically increase your total borrowing costs. Short Repayment Terms: With terms often between six months and two years, you may feel pressured to generate cash flow swiftly to avoid default. Collateral Dependency: If you fail to repay, you risk losing the asset used as collateral, jeopardizing your business’s financial stability. Lender Fees: Hard money lenders often impose significant fees, like origination and processing fees, which can further strain your resources and impact your bottom line. Final Thoughts on Hard Money Loans for Small Businesses Maneuvering the terrain of financing options can be challenging for small business owners, especially when time is of the essence. Hard Money Loans can be a viable option, particularly for those facing credit challenges. Nevertheless, the high interest rates and short repayment terms can impose significant financial pressure. Aspect Details Interest Rates 8% to 45% Loan-to-Value Ratio Caps at 75% Approval Speed Funds typically within days While these loans offer quick access to funds, they come with risks, including potential asset loss. Consequently, it’s essential to assess your business’s ability to manage repayments and guarantee thorough planning before proceeding with a hard money loan. Frequently Asked Questions What Is a Hard Money Loan for a Small Business? A hard money loan for a small business is a secured loan where your property serves as collateral. These loans offer quick access to funds, often from private lenders, focusing more on the value of your collateral than your credit history. You can typically receive 50% to 75% of your collateral’s appraised value. Nevertheless, be aware of the high interest rates and short repayment terms, as failure to repay could lead to foreclosure on your assets. How Does a Hard Money Loan Work? A hard money loan works by using real estate or assets as collateral. Lenders assess the property’s value rather than your creditworthiness, allowing for faster approval, often within days. You can expect loan amounts based on a percentage of the collateral’s appraised value, typically between 50% and 75%. Although interest rates can be higher, ranging from 8% to 15%, the short repayment terms, usually six months to two years, require prompt planning for repayment. Do I Need an LLC to Get a Hard Money Loan? You don’t need an LLC to get a hard money loan, but having one can boost your chances. Many lenders prefer borrowers who operate as LLCs since it offers liability protection and improves credibility. An LLC helps separate your personal and business finances, which can fortify your application. Although sole proprietors can qualify for these loans, forming an LLC provides legal protections and may offer more flexibility regarding collateral options. Do You Need a Down Payment for a Hard Money Loan? Yes, you typically need a down payment for a hard money loan. This down payment usually ranges from 10% to 30% of the property’s value, depending on your financial profile and the lender’s terms. If your credit isn’t strong, you might face a higher requirement. A larger down payment reduces the lender’s risk and demonstrates your commitment, impacting your likelihood of loan approval considerably. Failing to meet this requirement could result in denial. Conclusion To summarize, hard money loans can provide quick access to capital for small businesses, especially when traditional financing isn’t an option. Nevertheless, with interest rates ranging from 8% to 45%, they require careful evaluation and a solid repayment strategy. If you’re considering this route, weigh the pros and cons, explore alternatives, and make certain you have a clear plan for managing the financial implications. Doing so can help you maximize the benefits during minimizing potential risks. Image via Google Gemini This article, "What Are Hard Money Loans for Small Businesses?" was first published on Small Business Trends View the full article
-
Social media posts point to a 40% to 100% price hike this year, the latest in a series of hikes started in 2023, when for some lenders prices rose 400%. View the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. Black Friday sales officially start Friday, November 28, and run through Cyber Monday, December 1, and Lifehacker is sharing the best sales based on product reviews, comparisons, and price-tracking tools before it's over. Follow our live blog to stay up-to-date on the best sales we find. Browse our editors’ picks for a curated list of our favorite sales on laptops, fitness tech, appliances, and more. Subscribe to our shopping newsletter, Add to Cart, for the best sales sent to your inbox. Sales are accurate at the time of publication, but prices and inventory are always subject to change. The Google Nest Thermostat E has been around for a few years, but this “Grade A” refurbished model—on sale for $71.99 on StackSocial, over 50% off—is offering it a second life. Grade A here means it has undergone full testing to confirm that the sensors, wifi radios, and battery behave as they should, and it arrives in near-mint condition, with little to no visible wear. It’s the kind of refurb deal where you don’t feel like you downgraded anything, especially since its frosted 320×320 LCD has always leaned towards a more modern aesthetic. The tradeoff is readability: You reportedly need to stand closer than you would with the sharper display on the pricier Nest Learning Thermostat. The Thermostat E learns your patterns after a few days and automatically adjusts temperatures, while Home/Away Assist does its job without fuss. You leave the house, and it slips into Eco Temperatures; you come back, comfort returns before you notice. The Nest app keeps everything clear and simple. You can tweak temperatures from your phone, check Energy History to see when your AC spiked last week, or read HVAC alerts when the system starts behaving oddly. Voice control with Alexa or Google Assistant slots right into that routine. And the power draw stays low (under 1 kWh per month), which helps the energy-saving features feel honest, not performative. Still, there are limits. Compatibility covers roughly 85% of 24-volt HVAC systems; however, anyone with older wiring or more complicated setups might need a C-wire or a call to a technician. The E model also supports fewer components than the flagship Learning Thermostat, and it doesn’t include remote sensors, so room-to-room temperature swings won’t be fully solved without buying extras. Still, the core package remains steady, offering reliable temperature and humidity sensing, an ENERGY STAR certification, and a simple installation. Factor in the refurb discount and this “excellent” PCMag review, and it becomes a great option to consider. How long do Black Friday deals really last?Black Friday sales officially begin Friday, November 28, 2025, and run throughout “Cyber Week,” the five-day period that runs from Thanksgiving through Cyber Monday, December 1, 2025. But Black Friday and Cyber Monday dates have expanded as retailers compete for customers. You can get the same Black Friday sales early, and we expect sales to wind down by December 3, 2025. What stores have the best sales on Black Friday?Nowadays, both large retailers and small businesses compete for Black Friday shoppers, so you can expect practically every store to run sales through Monday, December 1, 2025. The “best” sales depend on your needs, but in general, the biggest discounts tend to come from larger retailers who can afford lower prices: think places like Amazon, Walmart, Target, Best Buy, and Home Depot. You can find all the best sales from major retailers on our live blog. Are Black Friday deals worth it?In short, yes, Black Friday still offers discounts that can be rare throughout the rest of the year. If there’s something you want to buy, or you’re shopping for gifts, it’s a good time to look for discounts on what you need, especially tech sales, home improvement supplies, and fitness tech. Of course, if you need to save money, the best way to save is to not buy anything. Are Cyber Monday deals better than Black Friday?Black Friday used to be bigger for major retailers and more expensive tech and appliances, while Cyber Monday was for cheaper tech and gave smaller businesses a chance to compete online. Nowadays, though, distinction is almost meaningless. Every major retailer will offer sales on both days, and the smart move is to know what you want, use price trackers or refer to guides like our live blog that use price trackers for you, and don’t stress over finding the perfect timing. Our Best Editor-Vetted Early Black Friday Deals Right Now Apple AirPods Pro 3 Noise Cancelling Heart Rate Wireless Earbuds — $219.99 (List Price $249.00) Apple iPad 11" 128GB A16 WiFi Tablet (Blue, 2025) — $279.00 (List Price $349.00) Amazon Fire HD 10 (2023) — $69.99 (List Price $139.99) Sony WH-1000XM5 — $248.00 (List Price $399.99) Blink Outdoor 4 1080p Wireless Security Camera (5-Pack) — $159.99 (List Price $399.99) Amazon Fire TV Stick 4K Plus — $24.99 (List Price $49.99) NEW Bose Quiet Comfort Ultra Wireless Noise Cancelling Headphones — $298.00 (List Price $429.00) Shark AI Ultra Matrix Clean Mapping Voice Control Robot Vacuum with XL Self-Empty Base — $249.99 (List Price $599.00) Apple Watch Series 11 (GPS, 42mm, S/M Black Sport Band) — $349.00 (List Price $399.00) Western Digital 14TB Elements Desktop External Hard Drive — $169.99 (List Price $279.99) Deals are selected by our commerce team View the full article
-
Crypto tycoon pardoned by Donald The President faces US court complaint from families of victims of October 7 attackView the full article
-
Peter Kyle signals more help for start-ups and companies aiming to ‘scale up’View the full article
-
Move comes as UK government attempts to funnel more cash into London-listed stocksView the full article
-
When you’re considering investing in a franchise, a thorough review of the franchise agreement is essential. This document outlines your rights, responsibilities, and financial commitments. Failing to comprehend its terms can lead to unexpected challenges down the line. Key areas to focus on include fees, territory rights, and termination clauses. Engaging a franchise attorney can clarify complex language and identify potential risks. Grasping these components can greatly impact your long-term success. What should you look for next? Key Takeaways Understand all financial obligations, including initial franchise fees, ongoing royalties, and additional advertising fees outlined in the Franchise Disclosure Document (FDD). Review territory rights to ensure exclusive operational areas and prevent competition that could impact revenue potential. Analyze renewal conditions, including timelines and performance expectations, to secure ongoing rights and operational continuity. Examine default and termination clauses carefully to grasp the implications of non-compliance and the processes for termination. Consult a franchise attorney for expert guidance on legal jargon, potential risks, and strategies to protect your investment. Explanation of Franchise Agreements A franchise agreement is more than just a contract; it’s an extensive document that defines the relationship between the franchisor and franchisee. This legally binding agreement outlines important aspects like franchise fees, royalty payments, and territory rights. It furthermore details intellectual property usage and conditions for termination and renewal. Performance expectations are clearly stated, ensuring compliance with the franchisor’s operational guidelines. To fully understand your commitments, a franchise agreement review is significant. You might consider hiring a franchise agreement lawyer to help navigate complex clauses and identify potential red flags. In addition, the Franchise Disclosure Document (FDD) offers critical insights into financial obligations and initial investments, further assisting in your franchise contract review to make informed decisions. Importance of Reviewing a Franchise Agreement Reviewing a franchise agreement is crucial for anyone considering entering a franchise business, as it lays the groundwork for your future success. A thorough review helps you identify critical provisions, like financial obligations and territory rights, which greatly impact your business. Overlooking key clauses can lead to severe consequences, including unexpected termination risks. Engaging a franchise contract lawyer guarantees you uncover potential red flags and understand the legal implications of complex terms. A careful attorney review of the franchise agreement safeguards you against excessive financial liabilities. In the end, a detailed review equips you with the necessary knowledge to make informed decisions and compare different franchise opportunities effectively, setting you on the path to success in your franchise experience. Term of the Agreement and Renewal Conditions When you enter into a franchise agreement, it’s essential to grasp the term of the agreement and the conditions for renewal, as these elements greatly affect your long-term business strategy. Typically, the term can last between 5 to 20 years, depending on the franchise system. Renewal conditions often hinge on your performance and adherence to operational guidelines. You’ll need to express your intent to renew within a specified timeframe before the agreement expires, and many agreements include automatic renewal clauses except you provide notice of non-renewal, which could require several months’ notice. Comprehending these factors is critical for ensuring you can recoup your investments and maintain continuity in your business operations. Franchise Fees and Other Payments When reviewing a franchise agreement, it’s essential to understand the various fees involved, starting with the initial franchise fee, which grants you the right to operate under the brand. You’ll likewise encounter ongoing royalty payments, typically a percentage of your gross sales, plus additional financial obligations like advertising fees that support collective marketing efforts. Each of these fees should be clearly outlined in the agreement, ensuring you can effectively plan your budget and financial commitments. Initial Franchise Fees Initial franchise fees are a vital component of the overall investment required to start a franchise, and these fees can vary considerably across different franchise systems. Typically, you’ll pay these upfront payments to the franchisor for the rights to operate under their brand, with amounts ranging from a few thousand to several hundred thousand dollars. To understand your financial commitment, carefully review the Franchise Disclosure Document (FDD) Item 7, which details the estimated initial investment, including these fees, real estate costs, equipment, and opening expenses. It’s crucial to verify the fee structure aligns with industry standards and your financial capabilities, as discrepancies could lead to unexpected costs that might impact your franchise’s success in the long run. Ongoing Royalty Payments Ongoing royalty payments represent a essential financial obligation for franchisees, typically calculated as a percentage of gross sales. These payments are important for supporting the franchisor’s brand and operational assistance. You’ll want to examine the Franchise Disclosure Document (FDD) closely, especially Item 6 for initial fees and Item 7 for ongoing royalties. Royalty fees can vary greatly, usually ranging from 4% to 8% of your gross sales. Here’s a quick overview of these payments: Franchise Type Royalty Fee Range Fast Food 4% – 6% Retail 5% – 7% Services 6% – 8% Hospitality 4% – 7% Fitness 5% – 8% Carefully reviewing these clauses can help you avoid unexpected costs that may affect your profitability. Additional Financial Obligations Comprehending the financial obligations tied to a franchise is vital for your long-term success, especially since these costs can greatly impact your profitability. Franchise fees typically start with an initial payment for brand rights, ranging from $10,000 to over $100,000. Then, you’ll face ongoing royalty fees, usually 4% to 8% of your gross sales, necessary for brand support. Furthermore, expect advertising fees around 1% to 5% of gross sales, funding collective marketing efforts. It’s important to understand the potential for fee increases or other financial commitments throughout your franchise agreement, as these can affect your bottom line. Make sure your franchise agreement clearly outlines all financial obligations and penalties for late payments to avoid unexpected financial strain. Territory Rights and Limitations Comprehending territory rights is vital for you as a franchisee, as these provisions define your exclusive area of operation and protect you from competition within the same brand. Clear territorial definitions can greatly impact your revenue potential, and disputes often arise when franchisors allow new franchisees to open in overlapping regions. When reviewing your franchise agreement, it’s important to benchmark territory clauses against industry standards to guarantee they align with your business goals and provide adequate market opportunities. Geographic Exclusivity Importance When you enter into a franchise agreement, the importance of geographic exclusivity can’t be overstated, as it establishes your territory rights and limitations. These rights protect you from competition within your designated area, allowing you to build and grow your business without facing direct rivals from the same franchise. Clearly defined territory rights can greatly improve your chances of success. They prevent potential financial losses because of ambiguous territorial clauses. A thorough review guarantees your rights are accurately detailed, avoiding future disputes. AI tools can help identify any inconsistencies or unfair restrictions in your territory rights. Understanding these factors is vital for safeguarding your investment and securing a profitable franchise experience. Territorial Disputes Impact The impact of territorial disputes in franchise agreements can greatly affect your business’s success. Territorial rights define the exclusive area where you can operate, preventing competition from other franchisees of the same brand. Nevertheless, disputes often arise when franchisors grant multiple franchises too close together, leading to market saturation and reduced sales for you. It’s vital to have clear definitions of territorial boundaries in your agreement to protect against encroachment. Furthermore, be mindful of renewal conditions that may alter your rights; failure to meet performance metrics could jeopardize your exclusivity. Benchmarking Territory Clauses Benchmarking territory clauses in franchise agreements is vital for guaranteeing that your operational rights are both fair and secure. Clear territorial definitions protect you from competition within specified boundaries, reducing potential disputes and financial losses. You should carefully review the conditions under which these rights may be modified or revoked to maintain long-term operational security. Consider the following key aspects when benchmarking: Assess potential overlaps with neighboring franchises to avoid conflicts. Understand limitations on expansion or transfer within your defined territory. Compare your territory rights against industry standards to identify inconsistencies and guarantee fairness. Default and Termination Clauses Comprehending default and termination clauses in a franchise agreement is vital for any franchisee, as these provisions dictate the circumstances under which the franchisor can deem you in breach of the contract. Default clauses outline specific conditions, such as failing to meet sales targets, non-compliance with operational standards, or not paying royalties on time. Termination clauses explain the process for ending the franchise relationship, often including a grace period for you to correct any defaults before termination takes effect. It’s important to understand that termination can lead to loss of brand rights, financial penalties, and restrictions on your ability to operate in the same market afterward. Thoroughly evaluating these clauses helps you grasp the risks tied to non-compliance or performance issues. Role of a Franchise Attorney Comprehending the intricacies of a franchise agreement is only part of the equation for franchisees; having the right legal support can make a significant difference. A franchise attorney brings specialized knowledge that helps you identify potential risks and avoid costly mistakes. They can negotiate key provisions that protect your interests, guaranteeing you’re not left in a vulnerable position. They conduct thorough reviews of Franchise Disclosure Documents (FDDs) to confirm consistency with the agreement. Their ability to interpret complex legal jargon clarifies implications, allowing for informed decision-making. They provide valuable strategies for mitigating disputes, enhancing your ability to navigate challenges effectively. Engaging a franchise attorney is vital for safeguarding your investment and assuring compliance with operational standards. Frequently Asked Questions What Are the Common Misconceptions About Franchise Agreements? Many people believe franchise agreements are simple and standard, but they’re often complex and vary greatly between brands. Another misconception is that signing an agreement guarantees success; in reality, it requires ongoing effort and compliance. Some think they can easily negotiate terms, but franchisors typically have strict policies. Finally, many assume they fully understand the agreement after a quick glance, yet, careful review is essential to avoid potential pitfalls and misunderstandings. How Can I Negotiate Better Terms in My Franchise Agreement? To negotiate better terms in your franchise agreement, start by researching industry standards and comparing agreements. Identify clauses that seem unfavorable or unclear, and prepare your rationale for why they should change. Approach the franchisor with a collaborative mindset, expressing your desire for mutual benefit. Be open to compromise during critical issues. Finally, consider consulting a legal expert to guarantee you understand all implications before finalizing any agreements. What Impact Do Franchise Agreements Have on Local Competition? Franchise agreements can greatly shape local competition by establishing brand standards, pricing strategies, and market territories. When you enter a franchise, you often agree to operate within specific boundaries, limiting your ability to compete freely with other businesses. These agreements may likewise create barriers for new entrants, as they often require compliance with established brand rules, thereby affecting pricing and service offerings in the local market. As a result, this can influence customer choices and overall market dynamics. Are There Standard Industry Practices Regarding Franchise Agreements? Yes, there are standard industry practices regarding franchise agreements. Typically, these agreements outline the rights and obligations of both franchisees and franchisors, covering fees, territorial rights, and operational guidelines. Most agreements likewise include a duration clause, renewal terms, and conditions for termination. Franchisors often require franchisees to adhere to brand standards and operational procedures, ensuring consistency across locations. Comprehending these practices can help you navigate franchise opportunities more effectively and avoid potential pitfalls. How Often Should I Review My Franchise Agreement After Signing? You should review your franchise agreement at least annually after signing. Regular checks help you stay updated on terms and conditions that may change, including fees and operational guidelines. Furthermore, consider reviewing it whenever there are significant business changes, such as expansions or new regulations. This practice guarantees that you’re compliant and aware of your rights and obligations, helping you avoid potential disputes and make informed decisions for your franchise’s future. Conclusion In summary, conducting a thorough franchise agreement review is essential for your success as a franchisee. By examining key components like fees, territory rights, and termination clauses, you can identify potential risks and guarantee the agreement aligns with your business goals. Engaging a franchise attorney can provide invaluable insights and clarify complex terms. Taking these steps will empower you to make informed decisions, finally safeguarding your investment and enhancing your chances for long-term success in the franchise industry. Image via Google Gemini This article, "Conducting a Thorough Franchise Agreement Review" was first published on Small Business Trends View the full article
-
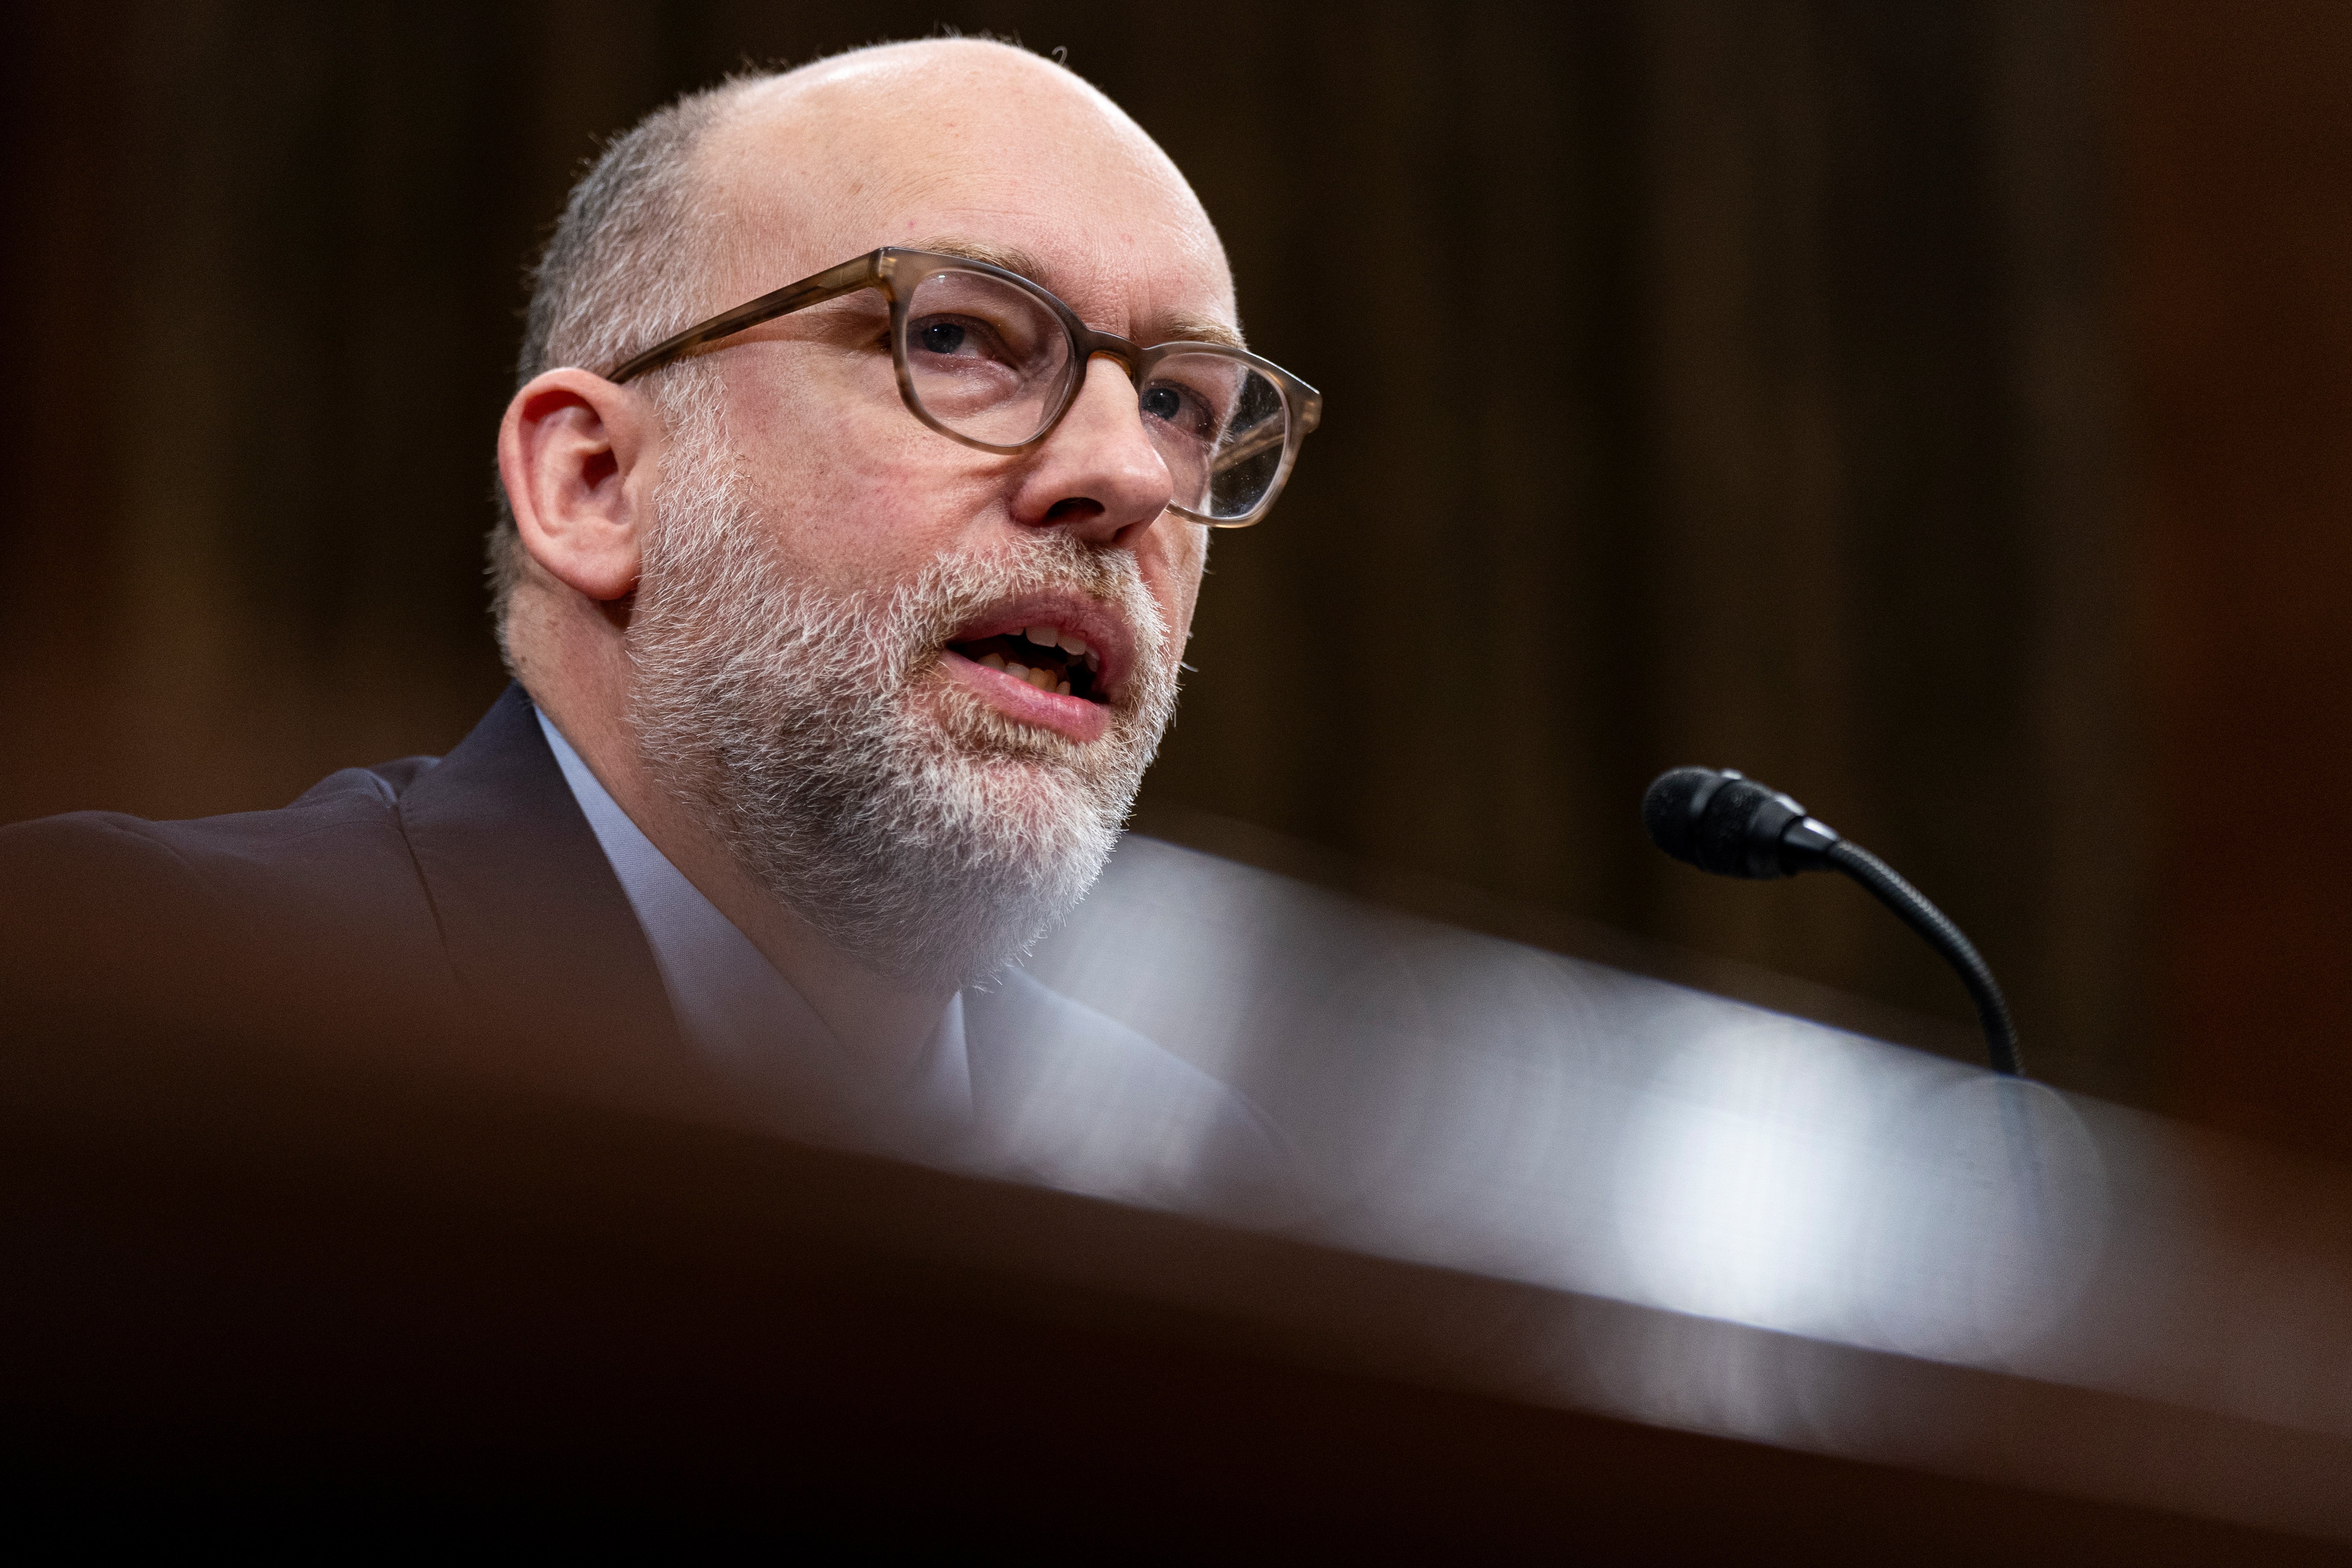
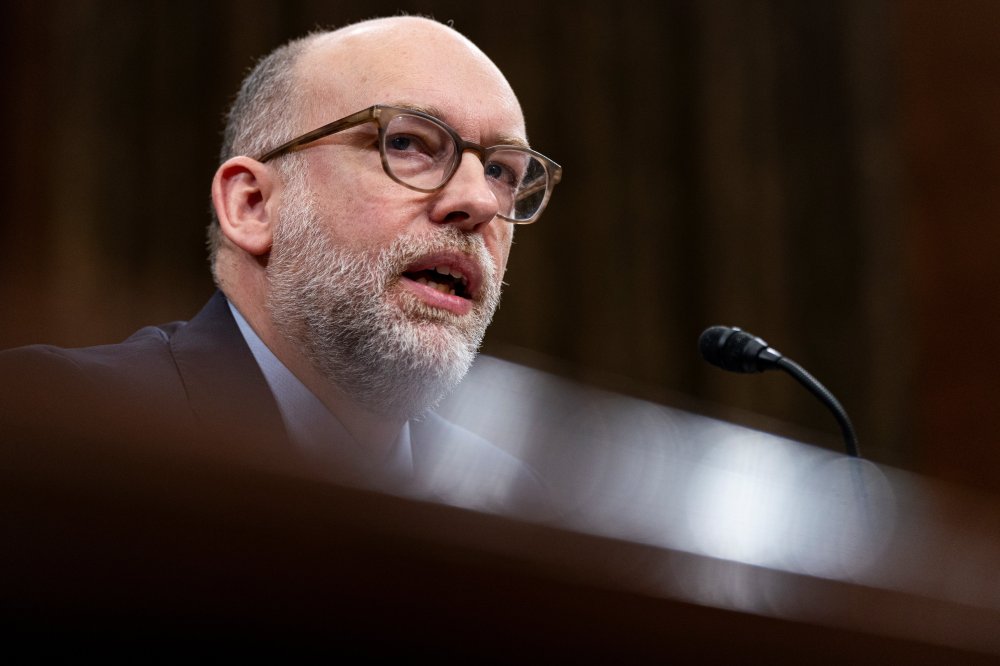
The Natural Treasury Employees Union has asked a district court to clarify whether Russell Vought, the acting director of the Consumer Financial Protection Bureau, has complied with a preliminary injunction. View the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. Black Friday sales officially start Friday, November 28, and run through Cyber Monday, December 1, and Lifehacker is sharing the best sales based on product reviews, comparisons, and price-tracking tools before it's over. Follow our live blog to stay up-to-date on the best sales we find. Browse our editors’ picks for a curated list of our favorite sales on laptops, fitness tech, appliances, and more. Subscribe to our shopping newsletter, Add to Cart, for the best sales sent to your inbox. Sales are accurate at the time of publication, but prices and inventory are always subject to change. Sony’s WH-1000XM6 headphones are now available in New Open Box condition on sale for $349.99 at StackSocial, which is a tempting offer if you’ve been eyeing the best premium headphones of 2025 (according to our writer, Daniel Oropeza). “Open Box” here means these units come from excess store inventory or returns that were inspected, verified to be new, and repackaged. You might see some wear on the box, but the headphones themselves are unused and come backed by a one-year warranty. For a product that normally goes for $449, that $100 cut is worth a look, especially if you’re upgrading from an older model or switching from Bose or Apple. The WH-1000XM6 improves on Sony’s already-dominant line in small but meaningful ways. The return of the foldable design makes them easier to stash in a bag, and the new QN3 processor, which is seven times faster than the last generation, powers 12 microphones that listen, filter, and fine-tune sound in real time. That translates to adaptive noise cancellation that silences traffic, chatter, and plane engines with near-surgical precision. You can still hear high-pitched clinks or sudden noises, but most distractions disappear once music starts. It’s also the first Sony model that lets you charge while listening, a fix users have wanted for years. Battery life stays strong at around 30 hours with ANC on, and a three-minute charge nets three hours of playback, ideal for last-minute commutes or flights. Sound quality holds Sony’s usual polish: crisp vocals, steady bass, and a clean balance that only improves once you tweak EQ settings in the app. Spatial Audio and Adaptive Sound Control add immersion, though they still rely on compatible apps and can be finicky to set up. The AI-powered call clarity works well, and the return of a 3.5 mm jack will please audiophiles who still prefer wired listening. At its core, this is Sony refining, not reinventing, a flagship. The XM6 doesn’t drastically outpace the XM5, but it’s a clear step up from the XM4, faster, smarter, and more portable. For those new to Sony’s ANC line, this Open Box deal offers top-tier performance at a gentler price, minus the factory-sealed box. How long do Black Friday deals really last?Black Friday sales officially begin Friday, November 28, 2025, and run throughout “Cyber Week,” the five-day period that runs from Thanksgiving through Cyber Monday, December 1, 2025. But Black Friday and Cyber Monday dates have expanded as retailers compete for customers. You can get the same Black Friday sales early, and we expect sales to wind down by December 3, 2025. What stores have the best sales on Black Friday?Nowadays, both large retailers and small businesses compete for Black Friday shoppers, so you can expect practically every store to run sales through Monday, December 1, 2025. The “best” sales depend on your needs, but in general, the biggest discounts tend to come from larger retailers who can afford lower prices: think places like Amazon, Walmart, Target, Best Buy, and Home Depot. You can find all the best sales from major retailers on our live blog. Are Black Friday deals worth it?In short, yes, Black Friday still offers discounts that can be rare throughout the rest of the year. If there’s something you want to buy, or you’re shopping for gifts, it’s a good time to look for discounts on what you need, especially tech sales, home improvement supplies, and fitness tech. Of course, if you need to save money, the best way to save is to not buy anything. Are Cyber Monday deals better than Black Friday?Black Friday used to be bigger for major retailers and more expensive tech and appliances, while Cyber Monday was for cheaper tech and gave smaller businesses a chance to compete online. Nowadays, though, distinction is almost meaningless. Every major retailer will offer sales on both days, and the smart move is to know what you want, use price trackers or refer to guides like our live blog that use price trackers for you, and don’t stress over finding the perfect timing. Our Best Editor-Vetted Early Black Friday Deals Right Now Apple AirPods Pro 3 Noise Cancelling Heart Rate Wireless Earbuds — $219.99 (List Price $249.00) Apple iPad 11" 128GB A16 WiFi Tablet (Blue, 2025) — $279.00 (List Price $349.00) Amazon Fire HD 10 (2023) — $69.99 (List Price $139.99) Sony WH-1000XM5 — $248.00 (List Price $399.99) Blink Outdoor 4 1080p Wireless Security Camera (5-Pack) — $159.99 (List Price $399.99) Amazon Fire TV Stick 4K Plus — $24.99 (List Price $49.99) NEW Bose Quiet Comfort Ultra Wireless Noise Cancelling Headphones — $298.00 (List Price $429.00) Shark AI Ultra Matrix Clean Mapping Voice Control Robot Vacuum with XL Self-Empty Base — $249.99 (List Price $599.00) Apple Watch Series 11 (GPS, 42mm, S/M Black Sport Band) — $349.00 (List Price $399.00) Western Digital 14TB Elements Desktop External Hard Drive — $169.99 (List Price $279.99) Deals are selected by our commerce team View the full article
-
Novo Nordisk’s closely-watched Alzheimer’s trials of an older oral version of its semaglutide drug failed to help slow the progression of the brain-wasting disease, the firm said on Monday, a blow to the obesity drug giant that sent its shares sliding. The trials, which Novo had previously called a “lottery ticket” to underline its highly uncertain outcome, were testing whether the medicine could slow cognitive decline in patients. The setback scuppers hopes for Novo that Alzheimer’s could open a major new market for GLP-1 medicines such as semaglutide, as it faces rising competition to its blockbuster drugs in its core treatment areas of obesity and diabetes. Erik Berg-Johnsen, portfolio manager at Novo shareholder Storebrand Asset Management, told Reuters that the trial failure was likely “a nail in the coffin” for using its products against Alzheimer’s. “The fact that the study was discontinued after two years, despite a planned third year extension, suggests that semaglutide offers virtually no benefit in slowing Alzheimer’s progression.” Novo’s trial was being closely watched as an indication about whether GLP-1 drugs – used by millions for diabetes and weight loss – might slow disease progress. The drug tested was Rybelsus, a pill approved only for type 2 diabetes. Like Novo’s blockbusters Ozempic and Wegovy, it contains semaglutide. ‘LOTTERY TICKET’ LOSES OUT The company’s Executive Vice President for Product and Portfolio Strategy, Ludovic Helfgott, had described the Alzheimer’s trials as a “lottery ticket” in September, referring to its uncertain prospects yet huge potential. Alzheimer’s disease and other dementias affect more than 55 million people globally. There is no cure. “While semaglutide did not demonstrate efficacy in slowing the progression of Alzheimer’s disease, the extensive body of evidence supporting semaglutide continues to provide benefits for individuals with type 2 diabetes, obesity, and related comorbidities,” Chief Scientific Officer Martin Holst Lange said in a statement. The results from the two trials of early-stage patients, called EVOKE and EVOKE+, are another setback for the Danish drugmaker and new CEO Mike Doustdar, which had seen booming success, driven by Ozempic and Wegovy, before slowing sales growth and a tumbling share price prompted a CEO change and mass layoffs. The setback reinforces analyst scepticism about Novo’s Alzheimer’s ambitions, with UBS having estimated just a 10% probability of success. Henrik Hallengreen Laustsen, Jyske Bank analyst, said however that a 10% share price fall on Monday looked like an “overreaction”. Sydbank analyst Soren Lontoft Hansen said that the failure was not a surprise for Novo, which has had a tough year with slowing sales of its key weight-loss drugs, management overhaul and rising competition from U.S. peer Eli Lilly . “The share’s reaction is probably more due to the bad sentiment around the Novo Nordisk shares and the negative news flow over the past year – perhaps there was hope for a little tailwind from this study.” PARTICIPANTS AGED 55 TO 85 Shares of Biogen jumped about 5% premarket following news of Novo’s Alzheimer’s trial failure. Biogen and partner Eisai’s Leqembi and rival Eli Lilly’s Kisunla are the only approved treatments for Alzheimer’s in the United States. Both drugs require infusions or injections and can cause significant side effects. “There was some fear that Ozempic might reduce the opportunity for Leqembi and other Alzheimer’s drugs by preventing progression of disease. So these data lift a potential competitive overhang,” said Cantor analyst Eric Schmidt. The Rybelsus trials, covering a combined 3,808 patients, were the first large trials for patients with early stage Alzheimer’s. The trials used a ratings system to assess clinical changes in areas such as memory and how patients were able to care for themselves over a two-year period. The studies aimed for a 20% slowing of cognitive decline, trial details show. Wall Street analysts viewed the trials as high-risk, high-reward, and had said the data would determine if Novo’s Alzheimer’s programme could become a future growth driver. —Stine Jacobsen, Maggie Fick and Jacob Gronholt-Pedersen, Reuters View the full article
-
As the digital landscape continues to evolve, small business owners must adapt to new communication methods while ensuring compliance with regulatory demands. Google’s recent announcement of RCS message archival presents a timely solution, addressing a pressing need in today’s business environment. This innovative feature is designed for fully managed Google Pixel devices and aims to simplify compliance with data retention regulations, making it a potentially game-changing tool for small enterprises. The surge in remote work and hybrid arrangements has led to a rapid shift towards modern, encrypted communication platforms. While these advancements enhance security, they pose new challenges for IT and compliance teams. Small businesses, in particular, must navigate legal complexities related to eDiscovery and federal data requests like the Freedom of Information Act (FOIA). Google’s RCS message archival feature supports businesses in capturing necessary records to stay compliant. This new capability fundamentally improves how small businesses can archive text communications. Historically, archiving relied on carrier-level logging, which does not accommodate modern, encrypted messaging methods. The RCS archiving solution integrates directly with Google Messages, ensuring IT departments receive comprehensive records of message interactions. This feature captures not only the sending and receiving of messages but also tracks edits and deletions, allowing for a more thorough documentation process. For small businesses, this tailored approach yields substantial benefits. By enabling third-party archival applications to work seamlessly with Google Messages, organizations can maintain compliance more effectively. The archiving occurs directly on the device, preserving end-to-end encryption during transmission—a reassuring aspect for businesses dealing with sensitive customer information. Furthermore, the system captures SMS and MMS messages, offering a unified solution for diverse messaging formats. Existing IT infrastructure can integrate smoothly with this new RCS message archival capability. IT administrators can easily configure and implement the feature based on the specific needs of their organization, determining which devices will use the archival capability and selecting the most suitable archival application. This flexibility allows businesses to customize their deployment strategy, minimizing disruptions while ensuring adherence to compliance mandates. “IT administrators can enable RCS Archival through a simple configuration,” notes Google. This level of ease is crucial for small business owners who often juggle multiple responsibilities and may lack extensive IT resources. RCS also enhances user experience with features such as read receipts and typing indicators, further improving communication efficiency within teams. To date, vendors like Celltrust, Smarsh, and 3rd Eye have developed integrations with Google Messages, with plans for more archival applications anticipated in 2026. This growing ecosystem provides small business owners with multiple options to select an archival solution that aligns with their existing compliance framework. While the benefits of adopting the RCS message archival system are clear, there are challenges to consider. Small business owners should evaluate the costs associated with implementing these third-party archival solutions, particularly for those with limited budgets. Additionally, business owners need to ensure that their entire team is adequately trained to use the feature, so it doesn’t hinder productivity. Overall, Google’s RCS message archival capability stands to empower small businesses by streamlining compliance processes while enhancing communication security. As remote work becomes more entrenched, tools that maintain regulatory adherence while promoting secure messaging will be invaluable. In a rapidly evolving digital world, small business owners must make informed decisions to align their communication strategies with compliance needs. To learn more about this feature and its integration with Android Enterprise, visit the original announcement here. Image via Google Gemini This article, "Google Pixel Launches RCS Message Archival for Enhanced Compliance" was first published on Small Business Trends View the full article
-
Nasdaq buoyed by investor hopes for Fed rate cut in December View the full article
-
The most politically sensitive elements are left for The President and Zelenskyy to discussView the full article