Newsletter
Want to keep up to date with all our latest news and information?
ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
Google Workspace is getting a slew of AI-related updates, including a brand new app called Google Pics, which can generate and edit images for you. Many of these updates will be available to those who use Gmail, Google Docs, Google Drive, and other Google Workspace apps, the company announced during the Google I/O 2026 keynote. This includes conversational features that will allow you to control Gmail, Docs, and Keep; a new AI inbox that aims to help you stay on top of your email; and a personal AI agent called Gemini Spark that can integrate with Google Workspace apps to get things done for you. Here are all the major Google Workspace updates unveiled during Google I/O 2026. These features are rolling out for Google AI subscribers and paying Google Workspace users. This means that you won't be able to try much if you're on the free tier of Google services. Create and edit images with AI in Google PicsGoogle Pics is a new app built with the company's latest Nano Banana AI image generation model, and allows you to create and edit photos using AI. Google claims this tool makes useful image editing tools more accessible, highlighting examples such as modifying and translating text, as well as transforming specific elements in an image (e.g., changing a sweater's color or turning a dog into a cat). You can also generate an image with a text prompt, but the real highlight seems to be granular editing. Like every other AI-related image generation tool, Google Pics also raises ethical questions about the nature of an image. It's not hard to imagine how tools like these could be misused to manipulate and deceive. One can only hope that Google has guardrails in place to clearly identify images edited with Google Pics, and to prevent misuse. This app is available to "Trusted Testers" today, and will be rolling out globally to Google AI Pro and Ultra subscribers (and in preview to Google Workspace business users) this summer. Enhanced conversational capabilities in Gmail, Docs, and KeepGoogle is adding new voice features to Gmail, Google Docs, and Google Keep. The email service is getting a feature called Gmail Live, which will search your inbox to answer your questions. For instance, you could ask something like, "What's going on at my kid's school this week?" The service will then search your inbox and find all the emails from your child's school. The idea is to ask questions with natural language, which is what makes it "conversational." The next new feature is Docs Live, which acts as your partner and co-writer, according to Google. You can talk to Docs Live, and it will help you brainstorm ideas, organize your thoughts, and structure your document. Google says the feature can even pull information from Gmail, Google Drive, Google Chat, and the web with your permission. You can think of Docs Live as an outlining tool that can gather a bunch of information quickly, making the writing process quicker for those who struggle to get started with a blank document. For Google Keep users, the new conversational features can turn your "brain dump" into organized notes and lists. You can say everything you want noted down, and the AI assistant will do the sorting and organizing for you. Like Google Pics, all of these conversational features will be rolling out to Google AI Pro and Ultra subscribers (and in preview to Google Workspace business users) this summer. New features in Gmail's AI InboxGmail's AI Inbox, which offers AI-powered summaries, suggestions, and proofreading, is getting a few new tricks too. During I/O 2026, Google announced that AI Inbox will get personalized draft replies, instant file access, and streamlined task management. AI Inbox will be able to generate a contextual draft for you when it detects that an email requires an urgent response, the company claims. With instant file access, AI Inbox can find and display a link to a document from Google Docs, Sheets, or Slides when you need it, which could make it easier to find the right document in email threads. The feature also lets you mark all emails in a certain topic as read. These features will be available to Google AI Plus and Pro subscribers in the U.S. starting today. A new personal AI agent: Gemini SparkThe final Workspace-related update today is a new AI agent called Gemini Spark. The company says Spark transforms Gemini from an assistant that answers your questions to one that gets things done with your permission. Once you enable this feature, Google says Gemini Spark can perform tasks such as sending emails on your behalf, and adding events to your calendar. The company adds that it will always ask your permission before performing these actions. Gemini Spark will be rolling out to Google Workspace business users in the coming week, and it'll be available through the Gemini app. View the full article
-
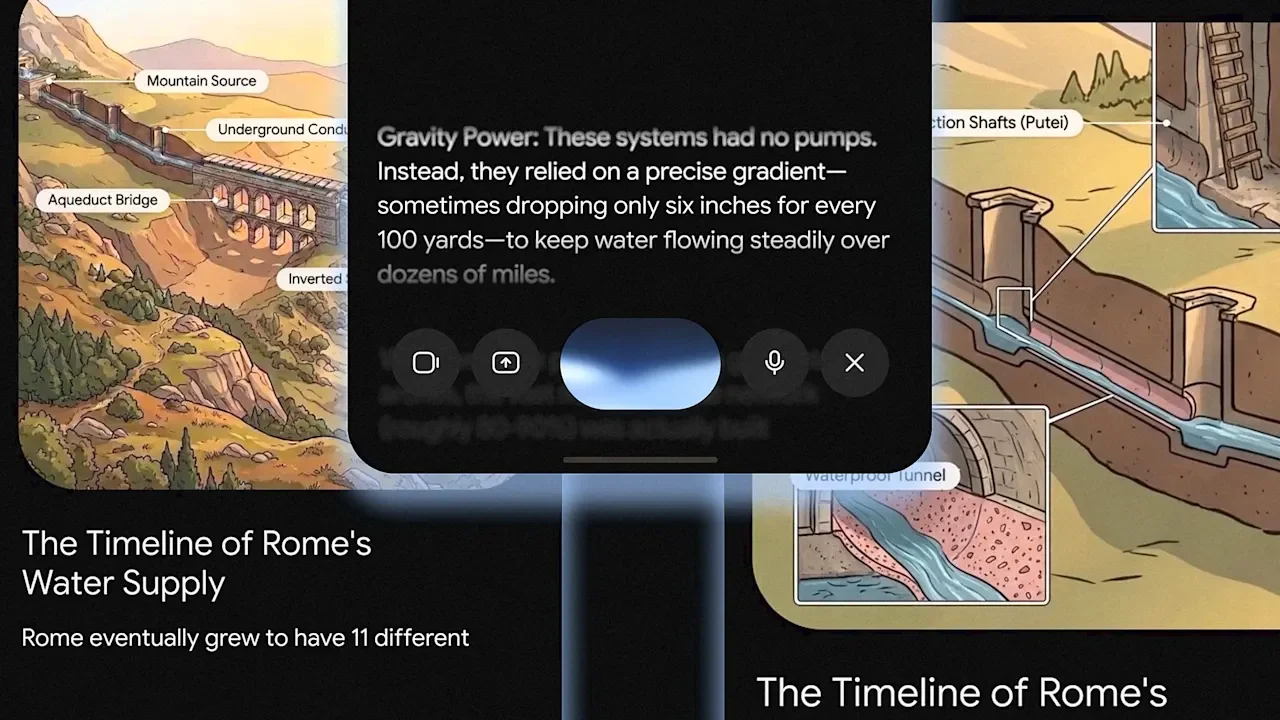
Google's Gemini app is getting an overhaul, in terms of both design and function. At Google I/O 2026, the company announced Gemini is getting upgraded models that will lean more into agentic AI capabilities, which allow the assistant to send emails, add calendar events, and perform other actions on your behalf. (Google does emphasize that all agentic capabilities are designed to be used under your supervision, which hopefully allays fears of the agent going rogue and, I don't know, draining your bank accounts.) Here's is everything Google announced about Gemini's app upgrades during this year's event. Gemini has a new lookGoogle says it has revamped the design language for the Gemini app. The company calls it Neural Expressive, and it includes new animations, colors, typography, and refreshed haptic feedback. Another change: The Gemini Live conversational experience is now integrated into the Gemini app. This means you can easily switch from typing your questions to using your voice to talk to the AI. There are also changes to the voice chat mode, allowing you to tap and talk to Gemini at your own pace. This prevents unwanted interruptions and doesn't force you to keep speaking at a certain speed if you need more time to frame your thoughts, according to Google. You'll soon also have an option to ask Gemini to speak in regional dialects, which can offer a more personalized experience to some people. I think the best part of Neural Expressive design is Google's focus on making interacting with Gemini look like something more than a wall of text. The company claims Gemini will now show responses with images, interactive timelines, narrated videos, and dynamic graphics, instead of just huge blocks of text. This new design language is rolling out today and will be available on the web, Android, and iOS. Turn Gemini into a personal AI agent with SparkGemini Spark marks Google's big play on agentic AI services. It transforms Gemini from a simple word generator into an assistant that can take actions for you. This feature works even if you've switched off your laptop or phone, and it can continue to work independently based on your requirements. Some examples Google shared during I/O 2026 include the ability to set recurring tasks or triggers, such as scanning your credit card bills to flag new or hidden subscription fees, go through your meeting notes to create a "polished" document in Google Docs with a summary of its findings, and drafting a companion email to kickstart a project. Google says you'll also be able to teach Gemini Spark to pick up on deadlines for school projects and share them with your spouse, which could allow you to keep a tab on your child's schoolwork without actively monitoring their inbox every day. It's worth noting that Google's repeatedly emphasized the fact that Spark works on your commands. You'll have to choose which apps it can connect to, and it'll only take high-stakes actions with your explicit consent, whether that's spending money or sending an email. Gemini Spark is rolling out to Google AI Ultra subscribers in the U.S. next week, but it will be available to "Trusted Testers" this week. Google also said that Gemini Spark will is coming to the Gemini app for macOS later this summer, allowing you to automate workflows involving local files on your computer. Daily Brief creates a personalized morning digest for youGemini is getting a new morning digest feature called Daily Brief, which works only if you opt in to receive it. The service accesses your Gmail inbox and your calendar to give you an overview of what's ahead in your day. Google says this feature will prioritize your tasks based on your goals, and suggest the next steps you should take to tackle upcoming tasks. You'll have the ability to tune the AI service's feedback by giving it a quick thumbs up or down in the app. The Daily Brief feature is rolling out in the U.S. starting today, and it'll be available to Google AI Plus, Pro, and Ultra subscribers. Turn ideas into cinematic videos with OmniIn a move to fill the void left by OpenAI's shuttering of Sora, Google is launching Gemini Omni, which allows you to combine text, images, and video inputs to generate videos. The company claims Omni makes it easy to edit videos using conversational inputs, such as swapping out backgrounds or applying cinematic zoom effects. You'll be able to upload footage from your camera roll and use Omni to apply built-in templates to create videos quickly without needing editing software expertise. There's also an option to create a custom AI avatar that looks and sounds just like you, and drop this avatar in your videos. This feature does suggest a few ethical concerns, since it sounds like it would make it easy for a person with malicious intent to generate deepfakes. While it's nice to see that video editing is becoming more accessible, generating videos with real people's faces is in a grey area, and I hope that Google has strong guardrails in place to safeguard against abuse. Gemini Omni is rolling out starting today to Google AI Plus, Pro, and Ultra subscribers across the globe. View the full article
-
There are a flurry of AI-related announcements coming out of Google I/O 2026 today, but perhaps the most impressive is a new multimodal model called Gemini Omni. While it's launching as a video generator to begin with, it'll eventually be able to incorporate images and audio too, on both the input and output side. The idea is you can remix different audio, images, and video into a completely new clip, via a custom prompt. Right now, you can only generate videos from text prompts and images within Gemini, so you're getting the added ability to combine audio clips and existing videos too when generating something new—multiple sources for input, and then an output that Google promises is better than ever in terms of realism and accuracy. While image and audio generation is on the way, the ability to create videos is coming first, with a model called Gemini Omni Flash. The example Google gives is picking a few styles from images in your phone's gallery, and then applying them to an existing video: So if you wanted to, you could make a video of you in the real world look like a Pixar animation. Omni lets you combine videos, images, and audio into new clips. Credit: Google You can also edit your videos through "conversation," says Google. That conversation aspect will be familiar to anyone who already uses Gemini to make videos: You just explain what it is you want to see, and Omni takes care of it. You can use follow-up prompts to change something specific about the video, like an object or color, or to create your very own reshoots of the scene where the action changes. You can also change the angle or the environment of a video—transporting yourself from a bedroom to a beach scene, perhaps. Google says you can take multiple turns to refine your videos, while still being able to get back to the original clip. Gemini's world knowledgeGoogle says Gemini Omni uses "an intuitive understanding of physics" together with "Gemini's knowledge of history, science, and cultural context" to make videos as realistic and as consistent as possible—though I'll have to try this out for myself to see if this all works as well as Google says it will. Omni now comes with a better understanding of forces like gravity, kinetic energy, and fluid dynamics, so there should be less AI weirdness on show. As well as building scenes, Google says, Gemini Omni reasons about what should happen next. AI videos can often collapse because they're trying to follow patterns from the vast number of videos in their training data, rather than follow the laws of physics. If a person disappears off-camera, they won't necessarily still be there when the camera pans back. Google claims Gemini Omni will show fewer issues like this. You'll need to be signed up for a Google AI subscription to use Omni. Credit: Google To protect against deepfakes, Google is putting some limits on video creation. For now, you'll only be able to use your own voice and a digital avatar based on you to generate outputs. In addition, all videos will carry Google's invisible SynthID watermark that indicates the content is AI-generated. Gemini Omni Flash is rolling out now in the Gemini app and Google Flow, for Google AI Plus, Pro, and Ultra subscribers. It's also going to be available for free in YouTube Shorts and the YouTube Create app later this week. At the time of writing, there's no word on usage limits. At the moment, those on a Google AI Plus plan ($7.99 a month) can generate two videos a day using the Veo 3.1 Lite model. It remains to be seen how generous Google is with Gemini Omni generations—it looks like they take up a fair amount of AI processing power. View the full article
-
Among the many AI-powered features announced today at Google I/O 2026 is a new "intelligent shopping cart" designed to help you find items faster and make purchasing more seamless. Universal Cart is an agentic hub that works across Google, so you can add products from multiple merchants while using Search, Gemini, YouTube, and Gmail to a single shopping cart. How Google's new Universal Cart worksOnce you add an item to your Universal Cart, Gemini will search for deals, show pricing history, and alert you to price drops and restocks. It can suggest other products relevant to your purchase, identify potential problems (such as items that are incompatible), and provide alternatives. For example, if you're buying parts to build a PC, Universal Cart may warn you if one component isn't compatible with another. Universal Cart integrates with Google Wallet, so it will also consider loyalty points, merchant offers, and rewards programs to look for additional savings. Finally, you can complete your purchase from your cart with Google Pay or transfer saved items to the retailer's website. These checkout features will be integrated for merchants like Nike, Sephora, Target, Ulta, Walmart, Wayfair, and Shopify merchants. Universal Cart builds on existing AI shopping features from Google, like price tracking and agentic checkout, powered by the Universal Commerce Protocol (UCP). Google says the feature runs on its Gemini models, so Universal Cart should continue to improve as the company upgrades its AI over time. When is Universal Cart coming out? Universal Cart is rolling out to Search and the Gemini app this summer (in the U.S.) and will eventually integrate with YouTube and Gmail. Google is also expanding agentic checkout features to users in Canada, Australia, and the U.K. as well as to YouTube in the U.S. and services like hotel booking and food delivery. View the full article
-
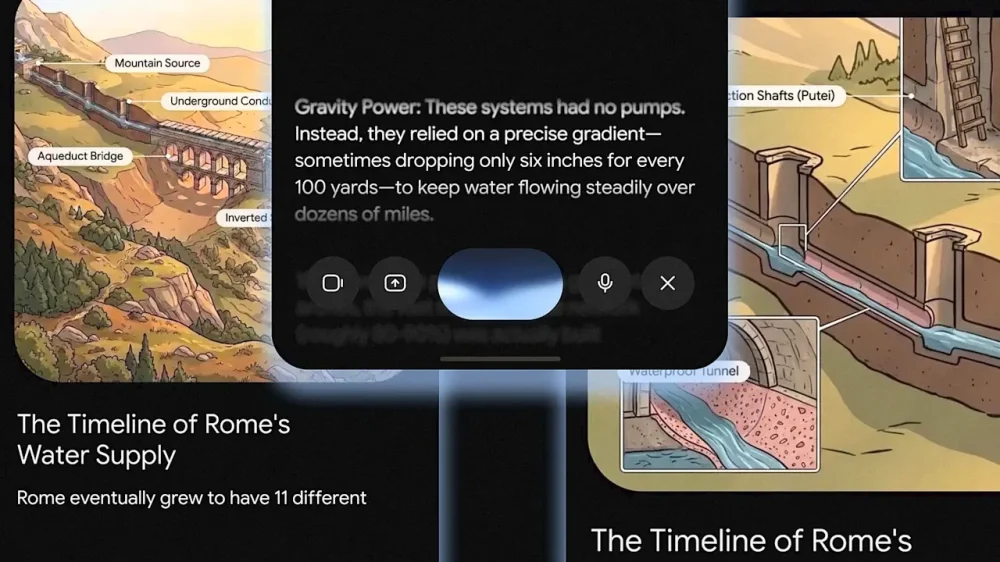
The chat log era of artificial intelligence is coming to an end. Google has just released a new version of its AI assistant, Gemini, that radically rethinks the prompt-and-response interface that has been a mainstay of the first few years of widely available generative AI. Instead of users typing in questions or prompts and getting back detailed written answers—”the giant wall of text,” as Gemini’s UI/UX lead Jenny Blackburn puts it—Gemini will now respond with a wider variety of content, from rich visuals to interactive elements to magazine-like graphic layouts. Depending on the prompt or query, Gemini will organically respond with the most appropriate level of detail in the display format that makes the most contextual sense. “It stops feeling like you’re scrolling through this endless chat log and more like the interface is organically adapting around the information that’s being generated,” says Blackburn. Announced at Google’s annual developer conference, Google I/O, the redesign of Gemini is a major shakeup of the user interface of mass market AI. With an estimated 900 million monthly users, Gemini is one of the main ways most people interact with AI firsthand. Until now, those interactions have been limited by the parameters of the chat format, a sometimes clunky conversation that can require asking and re-asking a question to get an AI to return a useful nugget of non-hallucinated information. The new Gemini app and desktop experience was designed around adaptability, with more intuitive controls and features, more ways of injecting information or collateral detail into a prompt, and more nimble responses. “We think that as this technology becomes more capable, the interface should actually get simpler,” Blackburn says. “Instead of you as a user having to learn and adapt to the software, which has been how software has been forever, we really see a future where the software adapts to the user and takes into account their specific needs.” Blackburn and her team drew on a depth of user data and feedback to guide their interventions. One prominent request from users was to be able to toggle more easily between input modes, switching from typing a query to speaking to uploading documents or reference images. “Multimodality matters a lot,” says Blackburn. “We see, particularly on phones, people use their camera a lot to give context to Gemini. They also really like to switch between voice and typing. And they were telling us you need to make this easier.” The redesigned Gemini streamlines the typing interface by displaying only the text box and the keyboard during written prompting, and has a separate menu with a simple grid of icons to choose other forms of input. Blackburn says the redesign of Gemini was a chance to reframe the AI experience, offering not just a superficial gloss but a more thoughtful design scaffold undergirding the entire process of prompting and receiving a response. She and her team developed a visual concept for the new Gemini that references the atomic-level movement of energy, and simple interconnected units that work together as a system. “This is a subtle nod to what’s happening behind the glass. And it’s intended to capture the fluid momentum of the model as it’s processing data,” she says. They named the resulting design language Neural Expressive. “We wanted to create the feeling of seeing neurons fire,” she says. This shows up in various ways, from the procedurally created animated background on the main query screen to the motion in the menu when the system is listening to a query or processing information. The design language also governs how Gemini’s responses get displayed in that text-wall-busting visual layout, giving information a hierarchy and organizing it in ways that make processing large amounts of information easier. For a typical query, a simple, overarching answer is displayed at the top of the page, with additional information presented in digestible layouts like chunks of text broken up by embedded images or videos, and offset bullet points summarizing key takeaways. “Every single change we made was really engineered to make it more scannable, reduce the fatigue of reading, and really make it easy and effortless to deep-dive into the content,” Blackburn says. On the imagery side, some of what Gemini will display to users will be real images, like photos of actual products in response to a shopping query. Other times, like when a diagram would do a better job than text in explaining a scientific concept, the images will be created on the fly using Google’s Nano Banana AI image generator. Blackburn says this added functionality within Gemini works without bloating the system, or taking extra time to field a query. “The way I thought about that was this can’t be slower. If people have to wait, that’s a really hard trade-off,” she says. “We did a lot of rigorous testing to make sure that these responses are not slower because they have these new attributes in them.” The Gemini redesign is so dramatically different from the typical AI interface that it may set a new standard. At the least, it will make Gemini a less rigid AI tool for its many users. “It’s not just a cosmetic refresh. It really is sort of like a deep reimagining of the experience,” Blackburn says. “As responses become a lot more tailored to what the user needs, that’s going to change how they use the product.” View the full article
-
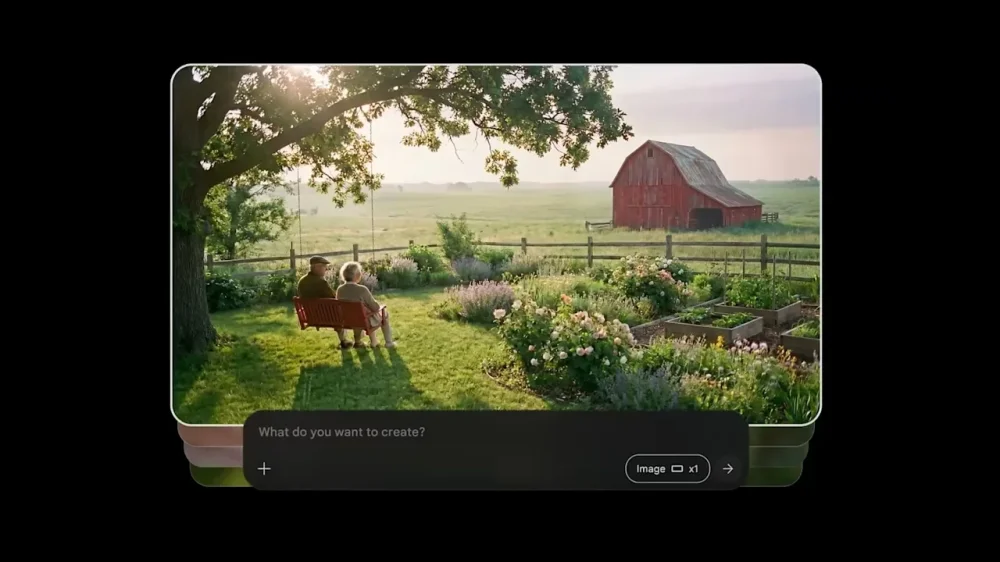
When Google’s Nano Banana image-generation tool first appeared in the wild in summer 2025, it quickly captured the internet’s attention for its ability to edit existing photos. The company also boasts one of the industry’s leading video models and has gained significant traction in AI media generation. Just this week, Google announced that users have generated more than 50 billion images with Nano Banana to date. However, like the rest of the industry, a lot of it is still fly-by use. People ask Google’s Gemini app to generate an image or short video clip and then move on. “These tools started as something you put a prompt into and then get an output out of, like a coin-operated [machine],” says Google Labs VP Elias Roman. Now Google wants to use its media-generation chops to build products that artists, filmmakers, and other professionals turn to over and over again, throughout the entire creative process. “We’re really building a new Google product line that’s entirely dedicated to creativity,” Roman says. Turning Google’s Flow tool into a media solution At the heart of these efforts is Flow, an online video-generation tool built by Google Labs that the company unveiled at its 2025 developer conference. Previously, Flow could generate images and 8-second video clips from text prompts. At this week’s Google I/O, the company unveiled an update to Flow aimed at going beyond generating individual assets. Users can now chat with an AI agent to brainstorm and storyboard projects, develop scenes and character art, and ultimately generate videos. For video generation, Flow uses Google’s new Gemini Omni model, which brings Nano Banana-style editing capabilities to the medium. Throughout these projects, Flow aims not only to keep characters consistent but also to maintain other stylistic guidelines. One example: Flow can preserve the same camera lens look across every shot, without users having to specify it in every prompt. “Flow is evolving from this prompt-in, content-out tool to an agent that’s a copilot at every step of the creative process,” Roman says. To support that vision, Roman says Google is allowing users to customize the platform itself, letting “creators basically vibe-code any tool or workflow they want.” Chatting with the platform’s AI agent, creatives can build tools that add video filters, compare two generated versions of a clip to spot differences, and more. “Once you make a tool, it’s shareable and even remixable by anyone else on the platform if you choose to make it public,” Roman says. Turning Flow into more than a toy for filmmakers At this point, Flow remains a Google Labs project. Turning it into a full-fledged product capable of competing with creative industry leaders like Adobe won’t be easy. But a shift in how the company positions Flow suggests Google is serious about trying. When Flow debuted last year, Google partnered with Donald Glover to promote the tool, giving it the feel of a playground for Hollywood insiders eager to experiment with AI. “We had an overly limited view of that,” Roman admits. “A year ago, we really thought it was for filmmakers.” But once the company released Flow, it saw marketers, architects, and even kindergarten teachers using it, many of whom likely don’t consider themselves the target audience for traditional creative suites aimed at media professionals. Given the right tools, though, they may become creators in their own right. “What we didn’t appreciate,” Roman says, “was that with truly AI-native tools, you’re able to serve an incredibly wide audience.” View the full article
-
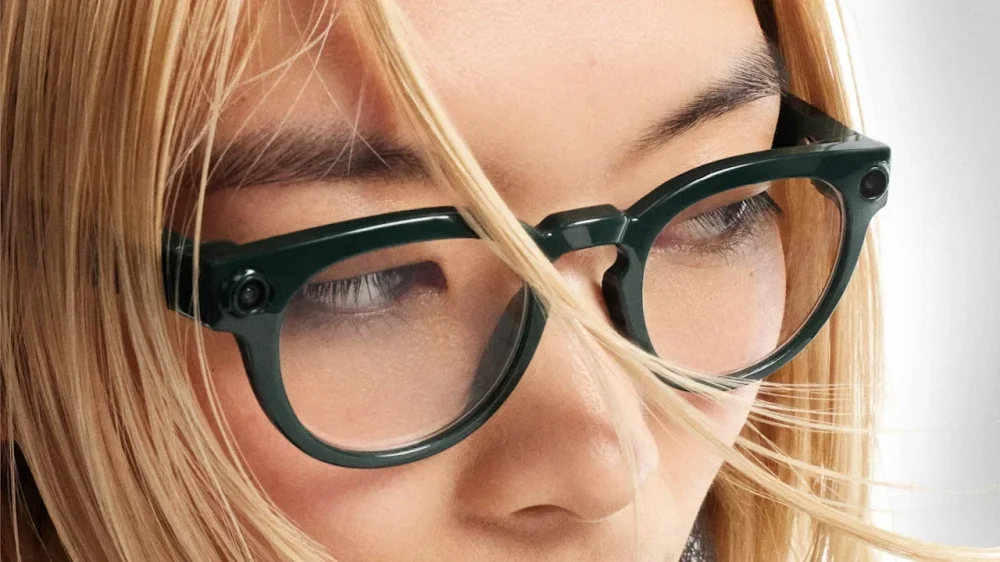
Meta and Ray-Ban are finally getting some serious competition. Warby Parker is launching its first-ever smart glasses, developed with Google and Samsung. Announced Tuesday at Google I/O, it could change the wearables market. Its new Intelligent Eyewear frames have speakers, cameras, and access to AI inside a light, flexible, dark green nylon frame that will be available as sunglasses and regular glasses. The glasses are powered by Google Gemini, the company’s AI assistant; and Android XR, Google’s unified operating system for ‘XR’ (extended reality) headsets and glasses. Warby Parker declined to share pricing, however Meta Ray-bans currently run from $390 to almost $500 (some models are on sale). The glasses represent Warby Parker’s entry into wearable tech, which is a category experiencing serious growth. Smart glasses could reach revenues of $4.2 billion by 2028, according to Bank of America, up from less than $500 million in 2024. For its part, Google has been looking to break into the category for years. It first launched Google Glass back in 2013. More recently, it launched its first Android XR headset last fall, which Gizmodo called “the future of wearables,” and tech blog CNET described as “Like Apple Vision Pro for half the price.“ Now it’s bringing XR mainstream with a glasses form factor designed by Warby Parker and honed for everyday use. “XR is going to be the next frontier for Gemini, and for AI,” Shahram Izadi, Google’s VP and GM for Android XR, told CNET nearly a year ago. Now we know how they plan to take a big piece of it from Meta, which has dominated the category since the launch of its smart Ray-Bans in 2023. Beyond simple diversity of choice, Gilboa thinks smart glasses could broadly change the way wearers interact with their smartphones by allowing them to take calls, send texts and emails, or check their calendars all without taking their phones out of their pockets. He says some people in the Warby Parker office have used prototypes of the glasses for live instructions on how to make a balloon animal. He’s used them for help in installing a car seat. Gilboa says his smartphone screen time dropped by more than half after wearing a pair of the company’s first smart glasses. “I got an alert from my phone that my screen time was down 60% the other day, which was pretty shocking,” he tells Fast Company. The technology isn’t without its detractors, however, because of wider backlash to AI and privacy concerns around facial recognition and what the glasses can secretly record. “If you look at most technology that’s been introduced over the last 20-plus years, it’s designed to take your attention away from the real-world surroundings and onto a screen,” he says. “I think that this is a fundamentally new category of products.” Warby Parker worked hand-in-glove with Google and Samsung to design the glasses, which are the result of thousands of tiny decisions, like shaving fractions of millimeters off frames and what shape to make the battery, he says. The semi-translucent finish of the interior temple subtly shows where the technology is integrated into the glasses. The frames were designed to be light enough for all-day wear. “We joke that glasses are the original wearable technology going back hundreds of years,” Gilboa says. “They serve a form and function and provide a really compelling utility in helping enable a wearer to see. The whole idea behind Intelligent Eyewear is to have all the best parts of glasses—enable enhanced vision, comfort—while enabling the wearer to express themselves, while also adding additional technology.” The debut style will be a classic, rounded silhouette that the company says will launch this fall. “We think our initial collection will be very well received,” he says. View the full article
-
If you run a small business, effective bookkeeping is vital for your financial health. Utilizing the right templates can simplify your processes and improve your management capabilities. From tracking cash flow with a Cash Book Template to managing vendor payments through an Accounts Payable Template, these tools provide structure and clarity. You’ll additionally find invoicing and expense monitoring templates fundamental for day-to-day operations. Curious about how these templates can particularly benefit your business? Key Takeaways Utilize a Cash Book Template for efficient tracking of both debit and credit transactions, ensuring accurate financial management. Implement a Billing Invoice Template to simplify invoicing processes and maintain organized records for better transaction oversight. Use an Accounts Receivable Template to track customer payments and outstanding invoices, enhancing financial oversight and cash flow management. Adopt an Inventory Tracking Template to monitor inventory levels and costs, providing clear insights into stock management. Leverage a Balance Sheet Template to gain a comprehensive view of your business’s financial position, aiding in financial assessment and decision-making. Cash Book Template The Cash Book Template is an important tool for small business owners looking to manage their finances efficiently. This double-column format allows you to record and track both debit and credit transactions, ensuring thorough documentation of cash movements. You’ll find key entries like the date, description, and amount for each transaction, which helps maintain accuracy. The template automatically calculates subtotals and your total cash balance, giving you an up-to-date overview of your financial status. You can easily download the Cash Book Template in Microsoft Excel, making it accessible for customization and regular use. By incorporating this template into your bookkeeping practices, you improve your cash management efficiency. It serves as a foundational tool for managing cash flow, allowing you to create sample cash flow projections in Excel. Furthermore, using an Excel template cash flow forecast can aid in making informed financial decisions, finally supporting your business’s growth and sustainability. Balance Sheet Template When you create a balance sheet template, you’ll gain a clear view of your business’s financial position, showcasing key components like assets, liabilities, and equity. Comprehending the importance of financial ratios is essential, as they provide insights into your company’s financial health and performance. Furthermore, the customization options allow you to tailor the template to your specific needs, ensuring that it accurately reflects your unique financial situation. Key Components Explained Grasping the key components of a Balance Sheet Template is crucial for gaining insights into a business’s financial health. This template provides a thorough snapshot of your assets, liabilities, and equity at a specific point in time. You can easily edit line items for current and long-term assets and liabilities based on your business needs. Here’s a quick overview of the components: Component Description Example Assets Resources owned by the business Cash, Inventory Liabilities Obligations owed to others Loans, Accounts Payable Equity Owner’s claim after liabilities Retained Earnings Balance Sheet Templates make financial assessments straightforward and are available for download in Microsoft Excel and Smartsheet. Importance of Financial Ratios Grasping the importance of financial ratios derived from your Balance Sheet Template is essential for effective business management. These ratios, such as the current ratio, help you assess liquidity, solvency, and profitability. A current ratio above 1 indicates financial stability, allowing you to cover short-term obligations. The debt-to-equity ratio reveals your financial leverage, with lower ratios preferred for reduced risk. Furthermore, the working capital ratio shows your short-term financial health; positive working capital suggests you can meet liabilities. Customization Options Available Comprehending your financial ratios is just the beginning of managing your business’s financial health; the customization options available in the Balance Sheet Template can greatly improve your reporting capabilities. This template allows you to tailor your financial reports to suit your specific needs, providing a clearer picture of your financial standing. Edit line items for current and long-term assets and liabilities. Include specific financial ratios, like working capital and debt-to-equity, for deeper analysis. Download the balance sheet template in Microsoft Excel or Smartsheet for flexibility. For those looking for a personal financial statement template excel free download, this balance sheet template is an invaluable tool that guarantees your financial data remains relevant and insightful. Business Expense Template A Business Expense Template is an essential tool for small business owners, allowing you to efficiently track your various expenses. This straightforward spreadsheet helps you record payment dates, methods, descriptions, and amounts, providing a running subtotal of your costs. It’s particularly beneficial for self-employed individuals since it can include home office expenses for tax deductions. You can easily customize this template to fit your specific needs by adding or deleting columns and rows. You can download the business expense report template in Excel, making it user-friendly and accessible. Here’s a quick example of what your template might look like: Date Description Amount 2023-01-01 Office Supplies $150.00 2023-01-10 Internet Bill $60.00 2023-01-15 Utilities $120.00 2023-01-20 Marketing Expenses $200.00 2023-01-25 Travel Expenses $300.00 Using this template can as well help you create a personal cash flow statement template, ensuring you maintain healthy finances. Billing Invoice Template An effective Billing Invoice Template can greatly simplify your invoicing process, making it easier to manage your business transactions. This customizable tool allows you to enter crucial details, such as the invoice number, date, customer ID, and payment terms, streamlining the entire process. It’s especially beneficial for maintaining organized records, particularly during tax season. Key features of the billing invoice template include: An itemized list of payments due, enhancing clarity for customers. An adjustable tax percentage field for accurate sales tax calculations. Availability in both Microsoft Excel and Smartsheet formats for versatile use. Invoice Tracking Template An Invoice Tracking Template is crucial for managing your invoicing process efficiently. It allows you to monitor every invoice you’ve issued, track payments, and keep a clear overview of outstanding amounts. Streamlined Invoice Management When managing invoices, having a reliable system in place can greatly improve your efficiency and accuracy. The Invoice Tracking Template serves as a simple spreadsheet solution, allowing you to effectively manage your accounts receivable. With this template, you can: Track invoice ID numbers, dates, and customer names easily. Enter payment dates upon receiving remittances for clear visibility. Monitor your total invoiced amounts, similar to a monthly statement sample or a loan statement template. Payment Tracking Efficiency Efficient payment tracking is crucial for maintaining a healthy cash flow in any small business, and the Invoice Tracking Template offers a streamlined approach to achieve this. This template allows you to organize invoices by ID number, date, customer name, description, and amount, ensuring accurate record-keeping of outstanding payments. You can likewise enter payment dates upon receipt, giving you a clear view of which invoices are paid and which remain pending. Invoice ID Amount Due 001 $500 002 $300 003 $450 004 $700 Statement of Account Template A Statement of Account Template serves as an important tool for businesses, offering a detailed overview of financial interactions with customers. This template consolidates fundamental account information into one accessible document, helping you manage customer relationships effectively. It includes a summary of previous balances, credits, current charges, and due dates. You’ll find an itemized list of charges and credits, detailing invoice numbers and transaction descriptions. By using a statement format in Excel, you can customize the template to meet your specific branding needs. Downloading a sample of statement of account in Excel enables you to improve financial organization and accuracy. With this template, you’ll clearly outline outstanding balances, prompting timely payments and reducing overdue accounts. Implementing this tool will streamline your bookkeeping processes, ensuring you maintain clear communication with your customers about their account statuses. Inventory Tracking Template Managing your inventory effectively is crucial for any business, as it directly impacts your bottom line. An inventory tracking template allows you to monitor the value of your current inventory and the cost of goods sold. By listing physical items with details like item number, name, description, type, and location, you can gain a clear overview of your stock. This template likewise records inventory purchases, including dates, vendors, and prices, enabling you to track inventory flow accurately. Accounts Receivable Template The Accounts Receivable Template is crucial for tracking customer payments efficiently, allowing you to keep a clear record of outstanding invoices. With its aging report feature, overdue payments automatically populate, enabling you to prioritize which invoices require immediate action. Tracking Customer Payments Efficiently To effectively track customer payments, utilizing an Accounts Receivable Template simplifies the process and boosts your financial oversight. This template allows you to monitor outstanding invoices effortlessly, ensuring that you maintain accurate records. By inputting crucial data like invoice terms, amounts, and payments received, you can generate a clear overview of total amounts due from customers. Consider these benefits: Reduces time spent on manual tracking Automatically populates an aging tab for overdue accounts Facilitates better cash flow management and financial planning You can use an excel sheet sample or a tax spreadsheet for small business to customize your template. Implementing this tool improves your collection processes, leading to enhanced financial efficiency. Aging Report Automation Benefits Even though many small businesses struggle with tracking overdue invoices, automating the aging report process through an Accounts Receivable Template offers a practical solution. This automation highlights overdue accounts quickly, allowing you to prioritize collection efforts effectively. By reducing manual errors and saving time, it improves your cash management, eventually benefiting your profit and loss account in Excel. Here’s a quick overview of the aging report automation benefits: Benefit Description Time-Saving Reduces manual data entry and tracking errors. Improved Cash Flow Insights Identifies overdue invoices and payment timelines. Better Decision-Making Facilitates financial planning and customer management. Utilizing this template streamlines your bookkeeping process, ensuring you’re always on top of your accounts receivable. Accounts Payable Template An effective Accounts Payable Template is essential for small businesses aiming to manage their financial obligations efficiently. This template helps you track money owed to vendors by listing important information such as balances due, payments made, supplier names, invoice numbers, and amounts. Key features include: Automatic calculations: It subtracts payments to show a running balance, simplifying your financial management. Prominent totals: The total amount owed to all vendors is displayed at the top, providing easy access to significant information. Customization options: Downloadable in Microsoft Excel and Smartsheet, it allows you to tailor it to fit your specific business needs. Using this accounts payable template not just maintains accurate records but additionally helps avoid late payments and streamlines vendor management. In the end, it contributes to a more organized annual financial report template, making your overall bookkeeping process more efficient. Simple Cash Flow Template A Simple Cash Flow Template is a crucial tool for small businesses that want to maintain a clear comprehension of their financial health. This template enables you to effectively track the movement of money in and out of your business, providing a clear overview of cash availability over time. You can list cash receipts, payments, operating expenses, and additional costs, making it easier to analyze your financial performance. Frequently Asked Questions What Software Can I Use to Create These Templates? You can use various software to create templates for bookkeeping tasks. Popular options include Microsoft Excel and Google Sheets, which offer flexibility and ease of use. If you prefer dedicated bookkeeping solutions, consider QuickBooks or FreshBooks, which come with built-in templates designed for small businesses. Furthermore, accounting software like Xero provides customizable options. Each tool has features that can help streamline your bookkeeping process, so choose one that fits your specific needs. Are These Templates Customizable for Specific Business Needs? Yes, these templates are customizable to fit your specific business needs. You can adjust various elements, such as categories, descriptions, and formats, ensuring they align with your financial processes. Many software options allow you to edit templates easily, providing flexibility in how you manage your data. This customization helps you create reports that reflect your unique operations, making it easier to track performance and stay organized throughout the financial year. How Often Should I Update My Bookkeeping Records? You should update your bookkeeping records regularly to maintain accurate financial information. Ideally, you’ll want to do this at least once a month, but if your business transactions are frequent, consider updating weekly. This practice helps you track cash flow, manage expenses, and prepare for taxes efficiently. Consistent updates likewise guarantee you can quickly generate reports, identify trends, and make informed decisions to support your business growth and sustainability. Can I Use These Templates for Non-Profit Organizations? Yes, you can use these templates for non-profit organizations. They’re designed to help track income, expenses, and donations, which are essential for non-profits. You’ll find that many features, such as budget tracking and financial reporting, apply to both small businesses and non-profits. Just adapt the categories to suit your specific needs. Make certain you follow applicable regulations and guidelines for non-profit financial management to maintain compliance and transparency. Are There Any Costs Associated With These Templates? Yes, there can be costs associated with these templates. Some templates may be free, whereas others might require a one-time purchase or a subscription fee. If you’re using software that offers templates, there could be additional costs for premium features or updates. It’s important to review the terms and conditions before downloading or purchasing to understand any potential fees. Always consider your budget when evaluating these options for your business. Conclusion By utilizing these 10 crucial bookkeeping templates, you can streamline your financial management and guarantee your small business operates efficiently. Each template serves a specific purpose, from tracking cash flow to managing expenses and invoicing. Implementing these tools will help you maintain clarity in your financial records and make informed decisions. Investing time in these templates now will pay off in improved organization and financial stability as your business grows. Start enhancing your bookkeeping practices today. Image via Google Gemini This article, "10 Essential Small Business Bookkeeping Templates You Need Today" was first published on Small Business Trends View the full article
-
If you run a small business, effective bookkeeping is vital for your financial health. Utilizing the right templates can simplify your processes and improve your management capabilities. From tracking cash flow with a Cash Book Template to managing vendor payments through an Accounts Payable Template, these tools provide structure and clarity. You’ll additionally find invoicing and expense monitoring templates fundamental for day-to-day operations. Curious about how these templates can particularly benefit your business? Key Takeaways Utilize a Cash Book Template for efficient tracking of both debit and credit transactions, ensuring accurate financial management. Implement a Billing Invoice Template to simplify invoicing processes and maintain organized records for better transaction oversight. Use an Accounts Receivable Template to track customer payments and outstanding invoices, enhancing financial oversight and cash flow management. Adopt an Inventory Tracking Template to monitor inventory levels and costs, providing clear insights into stock management. Leverage a Balance Sheet Template to gain a comprehensive view of your business’s financial position, aiding in financial assessment and decision-making. Cash Book Template The Cash Book Template is an important tool for small business owners looking to manage their finances efficiently. This double-column format allows you to record and track both debit and credit transactions, ensuring thorough documentation of cash movements. You’ll find key entries like the date, description, and amount for each transaction, which helps maintain accuracy. The template automatically calculates subtotals and your total cash balance, giving you an up-to-date overview of your financial status. You can easily download the Cash Book Template in Microsoft Excel, making it accessible for customization and regular use. By incorporating this template into your bookkeeping practices, you improve your cash management efficiency. It serves as a foundational tool for managing cash flow, allowing you to create sample cash flow projections in Excel. Furthermore, using an Excel template cash flow forecast can aid in making informed financial decisions, finally supporting your business’s growth and sustainability. Balance Sheet Template When you create a balance sheet template, you’ll gain a clear view of your business’s financial position, showcasing key components like assets, liabilities, and equity. Comprehending the importance of financial ratios is essential, as they provide insights into your company’s financial health and performance. Furthermore, the customization options allow you to tailor the template to your specific needs, ensuring that it accurately reflects your unique financial situation. Key Components Explained Grasping the key components of a Balance Sheet Template is crucial for gaining insights into a business’s financial health. This template provides a thorough snapshot of your assets, liabilities, and equity at a specific point in time. You can easily edit line items for current and long-term assets and liabilities based on your business needs. Here’s a quick overview of the components: Component Description Example Assets Resources owned by the business Cash, Inventory Liabilities Obligations owed to others Loans, Accounts Payable Equity Owner’s claim after liabilities Retained Earnings Balance Sheet Templates make financial assessments straightforward and are available for download in Microsoft Excel and Smartsheet. Importance of Financial Ratios Grasping the importance of financial ratios derived from your Balance Sheet Template is essential for effective business management. These ratios, such as the current ratio, help you assess liquidity, solvency, and profitability. A current ratio above 1 indicates financial stability, allowing you to cover short-term obligations. The debt-to-equity ratio reveals your financial leverage, with lower ratios preferred for reduced risk. Furthermore, the working capital ratio shows your short-term financial health; positive working capital suggests you can meet liabilities. Customization Options Available Comprehending your financial ratios is just the beginning of managing your business’s financial health; the customization options available in the Balance Sheet Template can greatly improve your reporting capabilities. This template allows you to tailor your financial reports to suit your specific needs, providing a clearer picture of your financial standing. Edit line items for current and long-term assets and liabilities. Include specific financial ratios, like working capital and debt-to-equity, for deeper analysis. Download the balance sheet template in Microsoft Excel or Smartsheet for flexibility. For those looking for a personal financial statement template excel free download, this balance sheet template is an invaluable tool that guarantees your financial data remains relevant and insightful. Business Expense Template A Business Expense Template is an essential tool for small business owners, allowing you to efficiently track your various expenses. This straightforward spreadsheet helps you record payment dates, methods, descriptions, and amounts, providing a running subtotal of your costs. It’s particularly beneficial for self-employed individuals since it can include home office expenses for tax deductions. You can easily customize this template to fit your specific needs by adding or deleting columns and rows. You can download the business expense report template in Excel, making it user-friendly and accessible. Here’s a quick example of what your template might look like: Date Description Amount 2023-01-01 Office Supplies $150.00 2023-01-10 Internet Bill $60.00 2023-01-15 Utilities $120.00 2023-01-20 Marketing Expenses $200.00 2023-01-25 Travel Expenses $300.00 Using this template can as well help you create a personal cash flow statement template, ensuring you maintain healthy finances. Billing Invoice Template An effective Billing Invoice Template can greatly simplify your invoicing process, making it easier to manage your business transactions. This customizable tool allows you to enter crucial details, such as the invoice number, date, customer ID, and payment terms, streamlining the entire process. It’s especially beneficial for maintaining organized records, particularly during tax season. Key features of the billing invoice template include: An itemized list of payments due, enhancing clarity for customers. An adjustable tax percentage field for accurate sales tax calculations. Availability in both Microsoft Excel and Smartsheet formats for versatile use. Invoice Tracking Template An Invoice Tracking Template is crucial for managing your invoicing process efficiently. It allows you to monitor every invoice you’ve issued, track payments, and keep a clear overview of outstanding amounts. Streamlined Invoice Management When managing invoices, having a reliable system in place can greatly improve your efficiency and accuracy. The Invoice Tracking Template serves as a simple spreadsheet solution, allowing you to effectively manage your accounts receivable. With this template, you can: Track invoice ID numbers, dates, and customer names easily. Enter payment dates upon receiving remittances for clear visibility. Monitor your total invoiced amounts, similar to a monthly statement sample or a loan statement template. Payment Tracking Efficiency Efficient payment tracking is crucial for maintaining a healthy cash flow in any small business, and the Invoice Tracking Template offers a streamlined approach to achieve this. This template allows you to organize invoices by ID number, date, customer name, description, and amount, ensuring accurate record-keeping of outstanding payments. You can likewise enter payment dates upon receipt, giving you a clear view of which invoices are paid and which remain pending. Invoice ID Amount Due 001 $500 002 $300 003 $450 004 $700 Statement of Account Template A Statement of Account Template serves as an important tool for businesses, offering a detailed overview of financial interactions with customers. This template consolidates fundamental account information into one accessible document, helping you manage customer relationships effectively. It includes a summary of previous balances, credits, current charges, and due dates. You’ll find an itemized list of charges and credits, detailing invoice numbers and transaction descriptions. By using a statement format in Excel, you can customize the template to meet your specific branding needs. Downloading a sample of statement of account in Excel enables you to improve financial organization and accuracy. With this template, you’ll clearly outline outstanding balances, prompting timely payments and reducing overdue accounts. Implementing this tool will streamline your bookkeeping processes, ensuring you maintain clear communication with your customers about their account statuses. Inventory Tracking Template Managing your inventory effectively is crucial for any business, as it directly impacts your bottom line. An inventory tracking template allows you to monitor the value of your current inventory and the cost of goods sold. By listing physical items with details like item number, name, description, type, and location, you can gain a clear overview of your stock. This template likewise records inventory purchases, including dates, vendors, and prices, enabling you to track inventory flow accurately. Accounts Receivable Template The Accounts Receivable Template is crucial for tracking customer payments efficiently, allowing you to keep a clear record of outstanding invoices. With its aging report feature, overdue payments automatically populate, enabling you to prioritize which invoices require immediate action. Tracking Customer Payments Efficiently To effectively track customer payments, utilizing an Accounts Receivable Template simplifies the process and boosts your financial oversight. This template allows you to monitor outstanding invoices effortlessly, ensuring that you maintain accurate records. By inputting crucial data like invoice terms, amounts, and payments received, you can generate a clear overview of total amounts due from customers. Consider these benefits: Reduces time spent on manual tracking Automatically populates an aging tab for overdue accounts Facilitates better cash flow management and financial planning You can use an excel sheet sample or a tax spreadsheet for small business to customize your template. Implementing this tool improves your collection processes, leading to enhanced financial efficiency. Aging Report Automation Benefits Even though many small businesses struggle with tracking overdue invoices, automating the aging report process through an Accounts Receivable Template offers a practical solution. This automation highlights overdue accounts quickly, allowing you to prioritize collection efforts effectively. By reducing manual errors and saving time, it improves your cash management, eventually benefiting your profit and loss account in Excel. Here’s a quick overview of the aging report automation benefits: Benefit Description Time-Saving Reduces manual data entry and tracking errors. Improved Cash Flow Insights Identifies overdue invoices and payment timelines. Better Decision-Making Facilitates financial planning and customer management. Utilizing this template streamlines your bookkeeping process, ensuring you’re always on top of your accounts receivable. Accounts Payable Template An effective Accounts Payable Template is essential for small businesses aiming to manage their financial obligations efficiently. This template helps you track money owed to vendors by listing important information such as balances due, payments made, supplier names, invoice numbers, and amounts. Key features include: Automatic calculations: It subtracts payments to show a running balance, simplifying your financial management. Prominent totals: The total amount owed to all vendors is displayed at the top, providing easy access to significant information. Customization options: Downloadable in Microsoft Excel and Smartsheet, it allows you to tailor it to fit your specific business needs. Using this accounts payable template not just maintains accurate records but additionally helps avoid late payments and streamlines vendor management. In the end, it contributes to a more organized annual financial report template, making your overall bookkeeping process more efficient. Simple Cash Flow Template A Simple Cash Flow Template is a crucial tool for small businesses that want to maintain a clear comprehension of their financial health. This template enables you to effectively track the movement of money in and out of your business, providing a clear overview of cash availability over time. You can list cash receipts, payments, operating expenses, and additional costs, making it easier to analyze your financial performance. Frequently Asked Questions What Software Can I Use to Create These Templates? You can use various software to create templates for bookkeeping tasks. Popular options include Microsoft Excel and Google Sheets, which offer flexibility and ease of use. If you prefer dedicated bookkeeping solutions, consider QuickBooks or FreshBooks, which come with built-in templates designed for small businesses. Furthermore, accounting software like Xero provides customizable options. Each tool has features that can help streamline your bookkeeping process, so choose one that fits your specific needs. Are These Templates Customizable for Specific Business Needs? Yes, these templates are customizable to fit your specific business needs. You can adjust various elements, such as categories, descriptions, and formats, ensuring they align with your financial processes. Many software options allow you to edit templates easily, providing flexibility in how you manage your data. This customization helps you create reports that reflect your unique operations, making it easier to track performance and stay organized throughout the financial year. How Often Should I Update My Bookkeeping Records? You should update your bookkeeping records regularly to maintain accurate financial information. Ideally, you’ll want to do this at least once a month, but if your business transactions are frequent, consider updating weekly. This practice helps you track cash flow, manage expenses, and prepare for taxes efficiently. Consistent updates likewise guarantee you can quickly generate reports, identify trends, and make informed decisions to support your business growth and sustainability. Can I Use These Templates for Non-Profit Organizations? Yes, you can use these templates for non-profit organizations. They’re designed to help track income, expenses, and donations, which are essential for non-profits. You’ll find that many features, such as budget tracking and financial reporting, apply to both small businesses and non-profits. Just adapt the categories to suit your specific needs. Make certain you follow applicable regulations and guidelines for non-profit financial management to maintain compliance and transparency. Are There Any Costs Associated With These Templates? Yes, there can be costs associated with these templates. Some templates may be free, whereas others might require a one-time purchase or a subscription fee. If you’re using software that offers templates, there could be additional costs for premium features or updates. It’s important to review the terms and conditions before downloading or purchasing to understand any potential fees. Always consider your budget when evaluating these options for your business. Conclusion By utilizing these 10 crucial bookkeeping templates, you can streamline your financial management and guarantee your small business operates efficiently. Each template serves a specific purpose, from tracking cash flow to managing expenses and invoicing. Implementing these tools will help you maintain clarity in your financial records and make informed decisions. Investing time in these templates now will pay off in improved organization and financial stability as your business grows. Start enhancing your bookkeeping practices today. Image via Google Gemini This article, "10 Essential Small Business Bookkeeping Templates You Need Today" was first published on Small Business Trends View the full article
-
When we talk about infrastructure for a local economy, most people picture roads, sewer pipes, broadband, or parks. But there is an invisible type of infrastructure that shapes where capital flows and which businesses are considered investable. These are the narratives shape how a city talks about itself and its people. Strong narratives rooted in abundance help attract institutional capital, spur innovation, and foster partnership and collaboration. When you treat narrative as an investable priority, you can reshape a city’s physical landscape. Seeking a quick return on investment, some fabricate narratives and relabel entire communities within cities without residents’ assent. In Denver, an intentional branding campaign shifted the name of a historically Black neighborhood (“Five Points”) to River North (or “RiNo”) with the hope that it would spur a local arts community. It worked—and brought in economic development, restaurants, and higher-income residents. But the campaign also helped the neighborhood become the second-most gentrified place in the country. Like it or not, these fabricated narratives and relabeling are effective. If done with intention and focused on inclusive growth, they can transform a place for the better. Our current national economic policy narrative seems to center on unpredictability and chaos. Yet the disruption of systems and expectations does allow us to create a new national narrative that acknowledges all people and every community have the capacity and potential to thrive economically. NARRATIVE AS ECONOMIC INFRASTRUCTURE Creating a narrative infrastructure goes beyond city slogans or branding campaigns. Narratives about talent, ingenuity, and industriousness become local and regional history and the stuff of lore, legends, and pride, like Pittsburgh as “Steel Town USA.” Or the “Keep Austin Weird” slogan, which branded Austin, Texas, as a creatively rich and innovative place, helping it become the tech hub it is today. When we align investment capital with the perceptions that flow from our narratives, the stories that undergird them become reality. We found three narrative components that show up in cities that do this well: 1. Shared language: These cities have a unified way of describing value, risk, and inclusion. Establishing shared language was a central tenet of our collective impact work through The Integration Initiative. When economic development officials, lenders, philanthropy, and community partners all use the same language to talk about entrepreneurs, creditworthiness, or wealth-building, it becomes much easier to identify opportunities in the same places and move resources in the same direction. 2. Shared decision rules: Cities that have repeatable methods for translating community stories into policy, programs, and investment design are creating a successful narrative infrastructure. These criteria, guardrails, and questions are standard in RFPs, loan committees, and city council deliberations—for example, asking how a project advances shared ownership or incorporates known resident priorities. Many communities work together to create standardized approaches connected to shared goals, such as Nashville, which developed a streamlined process and checklist for responding to local government RFP to support the growth of local suppliers. 3. Shared performance signals: When cities monitor what type of businesses receive funding, which neighborhoods see new investment, and how quickly new capital is deployed, they can understand how their stories influence impact. Creating a shared measurement framework and partnering with a third-party evaluator can ensure the integrity of the performance data and that the storytelling remains robust. WHEN STORIES MOVE CAPITAL In the Twin Cities, systemic exclusion left Black and Indigenous communities with limited wealth-building opportunities, even as new investment dollars flowed into the region. We partnered with Youthprise to launch cooperative entrepreneurship cohorts that placed young founders of color at the center of the city’s economic story. Young entrepreneurs had an opportunity to explore co-ownership models. By shifting the focus from individual enterprises to cooperative enterprises, the city cultivated ecosystems that were not only profitable but also equitable. Co-ownership models, including worker cooperatives, community land trusts, and shared-equity enterprises, offer a tangible way to build a locally rooted economy where ownership, decision-making, and prosperity are held in common by those who live and work there. Even though these small businesses were young and first-time entrepreneurs, they were not seen as risky investments. Instead, they were seen as critical to the fabric of the community and, therefore, to building a resilient economy. By embedding narrative infrastructure into economic development strategies, the Minneapolis-Saint Paul region is beginning to shift public will, policy appetite, and investor perception in tandem with concrete support for cooperative, community enterprises. Since the original partnership, approximately $2.5 million in private funding has been secured for a multi-use development anchored by youth cooperative housing. FROM STORY TO POLICY TO CAPITAL We assume stories are our reflections on what has come before, but we can also tell ourselves future stories and speak new opportunities into being. Cities that anchor narrative language in assumptions about entrepreneurs, sectors, or neighborhoods will never grow beyond limiting constraints. In an era of disruption and widening inequality, cities that intentionally build narrative infrastructure won’t just tell better stories; they will build more inclusive, resilient local economies that prove those stories true. Joe Scantlebury is president and CEO of Living Cities. View the full article
-
The U.S. Small Business Administration (SBA) has unveiled an exciting initiative that aims to honor American entrepreneurship while providing substantial financial rewards for participating small businesses. The newly launched Patriot Pitch Competition boasts a total cash prize pool of $1 million, thanks to a generous contribution from Clover Network, Inc. This competition is open to small businesses demonstrating the innovative spirit that has been a cornerstone of American free enterprise for 250 years. SBA Administrator Kelly Loeffler underscored the profound impact small businesses have had on the American economy. “From the family farm to the factory floor, small businesses have punched above their weight for the last 250 years to power America’s economy,” said Loeffler. She highlighted the contest as a celebration of entrepreneurship’s legacy and potential, adding that it aims to spotlight small businesses as vital catalysts for job creation and economic growth. This nationwide competition is tailored for businesses that have utilized qualifying SBA capital products, making it a strategic opportunity for those who have already engaged with SBA resources. With categories for evaluation that focus on strengthening American competitiveness, demonstrating innovation, creating economic opportunities, and showing execution readiness, the competition promises to attract a diverse array of small enterprises. The competition will unfold in four stages, culminating in a live finals event in Washington, D.C., scheduled for September. Finalists will have the chance to pitch their business concepts before a panel of distinguished judges, vying for a share of the $1 million prize pool. Not only does this provide a platform for participants to showcase their innovations, but it also offers national visibility. In addition to the pitches, the finals event will feature notable speakers from various sectors, offering attendees valuable insights. A supplier matchmaking expo will connect small businesses with potential partners, opening doors to contracting opportunities. Networking with investors and industry leaders adds another layer of potential value for participants. Small business owners interested in participating must submit their applications by June 10. This presents an opportunity not just for funding, but for exposure to industry trends and connections that could fuel growth. The SBA encourages all eligible small businesses to take action and leverage this unique platform. However, potential challenges exist for small businesses considering participation. The competitive nature of the event may be intimidating for some, especially those without extensive experience in pitching. Additionally, significant preparation may be necessary to meet the judging criteria, which demand a clear demonstration of innovation and impact. For many entrepreneurs, time is a valuable commodity, and the commitment to prepare a compelling pitch can be daunting. Small businesses should weigh the potential benefits of cash prizes and exposure against the resources they have available for preparation. Ultimately, the Patriot Pitch Competition epitomizes the ongoing commitment to fostering entrepreneurship in America. By providing much-needed financial incentives and resources, the SBA aims to galvanize small businesses into taking bold steps toward innovation and growth. For more details on eligibility, competition stages, and event programming, please visit SBA’s Patriot Pitch page. As the Patriot Pitch Competition gears up, small business owners have a unique opportunity to engage with a national audience, showcase their potential, and perhaps walk away with a significant financial boost that can help elevate their business to new heights. Image via Google Gemini This article, "SBA Launches $1 Million Patriot Pitch Competition for Innovating Small Businesses" was first published on Small Business Trends View the full article
-
The U.S. Small Business Administration (SBA) has unveiled an exciting initiative that aims to honor American entrepreneurship while providing substantial financial rewards for participating small businesses. The newly launched Patriot Pitch Competition boasts a total cash prize pool of $1 million, thanks to a generous contribution from Clover Network, Inc. This competition is open to small businesses demonstrating the innovative spirit that has been a cornerstone of American free enterprise for 250 years. SBA Administrator Kelly Loeffler underscored the profound impact small businesses have had on the American economy. “From the family farm to the factory floor, small businesses have punched above their weight for the last 250 years to power America’s economy,” said Loeffler. She highlighted the contest as a celebration of entrepreneurship’s legacy and potential, adding that it aims to spotlight small businesses as vital catalysts for job creation and economic growth. This nationwide competition is tailored for businesses that have utilized qualifying SBA capital products, making it a strategic opportunity for those who have already engaged with SBA resources. With categories for evaluation that focus on strengthening American competitiveness, demonstrating innovation, creating economic opportunities, and showing execution readiness, the competition promises to attract a diverse array of small enterprises. The competition will unfold in four stages, culminating in a live finals event in Washington, D.C., scheduled for September. Finalists will have the chance to pitch their business concepts before a panel of distinguished judges, vying for a share of the $1 million prize pool. Not only does this provide a platform for participants to showcase their innovations, but it also offers national visibility. In addition to the pitches, the finals event will feature notable speakers from various sectors, offering attendees valuable insights. A supplier matchmaking expo will connect small businesses with potential partners, opening doors to contracting opportunities. Networking with investors and industry leaders adds another layer of potential value for participants. Small business owners interested in participating must submit their applications by June 10. This presents an opportunity not just for funding, but for exposure to industry trends and connections that could fuel growth. The SBA encourages all eligible small businesses to take action and leverage this unique platform. However, potential challenges exist for small businesses considering participation. The competitive nature of the event may be intimidating for some, especially those without extensive experience in pitching. Additionally, significant preparation may be necessary to meet the judging criteria, which demand a clear demonstration of innovation and impact. For many entrepreneurs, time is a valuable commodity, and the commitment to prepare a compelling pitch can be daunting. Small businesses should weigh the potential benefits of cash prizes and exposure against the resources they have available for preparation. Ultimately, the Patriot Pitch Competition epitomizes the ongoing commitment to fostering entrepreneurship in America. By providing much-needed financial incentives and resources, the SBA aims to galvanize small businesses into taking bold steps toward innovation and growth. For more details on eligibility, competition stages, and event programming, please visit SBA’s Patriot Pitch page. As the Patriot Pitch Competition gears up, small business owners have a unique opportunity to engage with a national audience, showcase their potential, and perhaps walk away with a significant financial boost that can help elevate their business to new heights. Image via Google Gemini This article, "SBA Launches $1 Million Patriot Pitch Competition for Innovating Small Businesses" was first published on Small Business Trends View the full article
-
One small glimmer of hope for anyone hoping to buy a home soon: You might not need as much cash as you would have in years past. Down payments hit their lowest level in five years in the first three months of 2026, according to a new report from Realtor.com. The amount of cash buyers need to put down to buy a home has dropped consistently over the last year, reaching a new low that’s 19% less than this time in 2025. Dwindling down payments are a sign of a new phase in the U.S. housing market. In the heady housing scramble that kicked off with pandemic-era rate cuts, sky-high down payments became table stakes for making a strong offer. After a sharp uptick from 2020 to 2022, down payments continued to climb through the end of 2024, when they peaked at an average of $32,700 or 15% of a home’s selling price. In early 2019, the average down payment was $12,500, which represented 10.7% of the average home price. By early last year, that percentage jumped up to 14% or $28,900—a huge increase considering that this number represents the cash in hand that you’d need to buy a house. This year, a buyer would need to put down 12.8% or $23,400, according to the new homebuying report. The downward trend means that competition for homes is easing a bit as inventory opens up and prices soften. “Down payments are falling as the housing market slowly tilts toward buyers,” Hannah Jones, a senior economic research analyst at Realtor.com, said in the report. “High prices and borrowing costs continue to test affordability, and while conditions are improving, some of the buyers reentering the market are doing so via government-backed programs that have lower down-payment requirements.” Jones says that while the market is improving by some measures, many households may still find the path to owning a home challenging. Parts of the country where home prices are cooling off show the biggest dip in the average down payment. The South and the West showed the biggest declines, with the Midwest staying steady and the Northeast still showing a spike in the amount of cash people need to put down to compete for a home. Signs of a shift There are a few signs in the housing market that things are finally getting a little easier for buyers. The average home buyer’s credit score started trending down last year, a sign that people previously priced out of the market are finding their way back in—and many of them had a little help. To get their foot in the door, more buyers are tapping government programs like Federal Housing Administration (FHA) and Veterans Affairs (VA) loans designed to ease the financial burden of buying a home. Over the last five quarters, FHA’s portion of purchase mortgages has remained above 24%, its longest stretch at such high levels in 10 years. VA loans accounted for 11.7% of mortgages in the first quarter of 2026, also a 10-year high. Both government-backed loans allow lower earners to make smaller down payments, easing the cash crunch that can prove to be insurmountable for many people trying to buy a home. “Government-backed programs are serving as a critical pressure valve, keeping the door to homeownership open for buyers who might otherwise be shut out entirely,” Jones said. “But the growing reliance on FHA and VA financing also reflects how much the conventional path to homeownership has narrowed for buyers without significant cash reserves.” Across the country, many homebuying markets are tipping back in favor of buyers. Last month, two-thirds of the biggest housing markets moved into more balanced or buyer-friendly territory. Only a quarter of the top metros in the U.S. qualified as seller’s markets, with a large ratio of home buyers competing for the same housing inventory. While that picture is still uneven from region to region, it’s just one more sign that things may start easing for potential homebuyers waiting in the wings. View the full article
-
Far-right finance minister Bezalel Smotrich says move would be a ‘declaration of war’View the full article
-
Managing your EIDL payment effectively is vital to maintaining your business’s financial health. You’ll start by creating an account on the MySBA Loan Portal, which allows you to monitor your loan details and payment schedule. Comprehending key dates and payment options, like ACH or PayPal, can simplify the process. Setting up reminders can help guarantee you never miss a due date. To navigate this efficiently, let’s examine the fundamental steps for a seamless payment experience. Key Takeaways Log in to the MySBA Loan Portal to view loan details and monitor your balance regularly. Set up reminders for payment due dates to ensure timely payments and avoid penalties. Choose your preferred payment method, such as ACH, PayPal, or debit card, for convenience. Prepare mailed payments with your SBA loan number included in the memo field for proper processing. Communicate with your lender for assistance or to discuss repayment options if facing financial difficulties. Understanding Your EIDL Loan When you receive an Economic Injury Disaster Loan (EIDL), it’s vital to fully understand its terms and conditions to manage your repayment effectively. EIDL loans carry an interest rate of less than 4% and can be repaid over a maximum of 30 years. Unlike EIDL Advances, these loans require repayment from all Obligors, including Borrowers and Guarantors. You’ll start making EIDL payments 30 months after the loan origination date, with interest continuing to accrue during the deferment period. To keep track of your expenses, an SBA loan lookup can help you maintain accurate records. Documentation of how funds were spent is important, so save all itemized receipts as required by the SBA to guarantee compliance and facilitate repayment. Key Dates for EIDL Payments When managing your EIDL payments, it’s essential to know the key dates that will affect your loan repayment. Payments will start 30 months after your loan origination date, so it’s important to mark that on your calendar. With the deferment period extended, you should likewise keep track of interest accruing during this time, as it impacts your total loan balance. Important Payment Deadlines Comprehending the key payment deadlines for your Economic Injury Disaster Loan (EIDL) is vital to maintaining financial stability. Payments begin 30 months after the loan origination date, following a deferment period. To avoid late fees and guarantee timely payments, stay aware of deadlines, as interest accrues during deferment. You can check your loan balance and obligations through the MySBA Loan Portal or the SBA’s Capital Access Financial System. Deadline Type Description Action Required Loan Origination Date Start of deferment Note the 30-month countdown First Payment Due 30 months post-origination Prepare for payment Payment Frequency Monthly payments thereafter Set reminders Regularly monitor your loan status for effective financial management. Deferment Period Extension The extension of the deferment period for Economic Injury Disaster Loans (EIDL) offers borrowers additional relief before repayments begin, now set to start 30 months after the loan origination date. This extension provides you with extra time to prepare your finances. Nevertheless, it’s important to bear in mind that interest continues to accrue during this period, potentially increasing your total repayment amount. You can make early payments without any pre-payment penalties, which can help reduce the overall interest costs. Staying informed about your loan terms and payment schedules is crucial to avoid surprises when the deferment period ends. Accessing the MySBA Loan Portal To access the MySBA Loan Portal, you’ll need to create an account using the same login credentials from the previous Capital Access Financial System (CAFS). Once you’re logged in, maneuvering your loan information is straightforward, enabling you to review details and make payments online. This portal not merely streamlines your payment process but will additionally add features like recurring payments in the future for added convenience. Creating Your Account Accessing the MySBA Loan Portal is a straightforward process, especially for those who’ve previously used the Capital Access Financial System (CAFS). To create your account, you’ll need to use the same login credentials from CAFS, as the system changed on March 23, 2023. If you’re not already enrolled, you can set up an account by providing your name, date of birth, and SBA loan number. You can find your SBA loan number in the RAPID portal or your original loan documents, which are crucial for this process. Once logged in, you’ll be able to view your loan details, make payments, and access statements directly from the portal, streamlining your loan management experience. Navigating Loan Information Once you’ve successfully created your MySBA Loan Portal account, managing your loan information becomes a streamlined process. You can access the portal using the same login credentials you previously used for the Capital Access Financial System (CAFS) as of March 23, 2023. Within the portal, you’ll find detailed loan information, including account statements. Even though the option to set up recurring payments is anticipated to be added in the future, you can currently make payments through various methods, including PAY.gov and online banking. Remember, for payments to advance the due date, they must be processed within 25 days of the due date. For any questions or documentation requests, contact the COVID-EIDL Contact Center via email, ensuring you include your company name and loan number in the subject line. Making Payments Online Making online payments for your EIDL loan is a straightforward process when you utilize the MySBA Loan Portal. First, log in using the same credentials you used for the Capital Access Financial System (CAFS) as of March 23, 2023. Once you’re in, you can view your loan details, make payments, and access your statements directly. Remember, payments must be completed within 25 days of the due date to advance the payment date, and bulk payments aren’t supported. You’ll find a recurring payments feature may be added in the future for easier management. Keep in mind that interest continues to accrue during hardship accommodations, which allow for reduced payments for six months. Stay informed to manage your obligations effectively. Checking Your EIDL Loan Balance How can you effectively manage your EIDL loan obligations? Start by checking your EIDL loan balance regularly. To do this, visit the SBA’s Capital Access Financial System (CAFS) website. If you haven’t created an account yet, you’ll need to sign up using your name, date of birth, and SBA loan number, which you can find in the RAPID portal or your original loan documents. If you’re struggling to locate it, don’t hesitate to contact the Disaster Loan Servicing Centers for help. Monitoring your loan balance is essential, especially since interest continues to accrue during the deferment period. This way, you can stay informed about your repayment obligations and guarantee effective financial planning moving forward. How to Pay Your EIDL Loan Online Paying your EIDL loan online is a straightforward process that can help you stay on top of your financial responsibilities. To get started, sign in or create an account at pay.gov, then locate the SBA 1201 Borrower Payment form. Enter your SBA loan number and the payment amount on the form. Choose a payment method such as ACH, PayPal, or debit card, as credit card payments aren’t accepted. You can set up one-time or recurring payments based on your preferred frequency. Remember to make your payment within 25 days of the due date to advance the payment date and avoid late fees. Keep in mind that interest continues to accrue during the deferment period, which lasts up to 30 months. Steps to Create a Pay.gov Account Creating a Pay.gov account is crucial for managing your EIDL payments effectively. To get started, head to the Pay.gov website and select “Create an Account,” where you’ll need to provide your name, date of birth, and your SBA loan number. Once you’ve entered this information and followed the prompts, you’ll gain access to various payment options for your loan. Account Creation Process To start the account creation process on Pay.gov, visit the website and select the “Sign Up” option. You’ll be prompted to enter personal information, including your name, date of birth, and email address. Make sure you have your SBA loan number handy, as it’s needed during registration. After you’ve filled out the required information, take a moment to carefully review the terms and conditions before submitting your account application. Once your account is successfully created, you can log in to manage your EIDL loan payments online. Pay.gov offers various payment methods, including ACH transfers, PayPal, or debit cards, making it easy and convenient to stay on top of your loan obligations. Required Information Details When you’re ready to create your Pay.gov account, start by visiting the website and selecting the “Create an Account” option. You’ll need to provide personal information, including your name, date of birth, and your SBA loan number, which you can find in your RAPID portal or original loan documents. After entering this required information, you’ll set up a secure username and password for your account. Once your account is created, it enables you to make your EIDL loan payments online, with options like ACH or debit card. Remember to keep your login credentials secure, as you’ll need them to access your account and manage future payments efficiently. Accessing Payment Options Accessing payment options for your EIDL loan becomes straightforward once you create a Pay.gov account. To start, visit the Pay.gov website and select the “Sign Up” option. You’ll need to provide personal information, including your name, date of birth, and SBA loan number. If you can’t find your loan number, check the RAPID portal, your original loan documents, or contact Disaster Loan Servicing Centers. After setting up your account, you can access the SBA 1201 Borrower Payment form to make payments via ACH, PayPal, or debit card. Remember to keep your login credentials secure and check your account regularly for updates. Step Action Notes 1. Visit Pay.gov Go to the website Look for “Sign Up” 2. Provide Info Enter your details Include SBA loan number 3. Make Payments Access SBA 1201 form Use ACH, PayPal, or debit Completing the SBA 1201 Borrower Payment Form Completing the SBA 1201 Borrower Payment form is a crucial step in managing your Economic Injury Disaster Loan (EIDL) payments. To guarantee a smooth process, follow these steps: Sign in or create an account at pay.gov, the SBA’s preferred platform. Input your SBA loan number and payment amount accurately to avoid delays. Choose a payment method—options include ACH, PayPal, or debit card, as credit cards aren’t accepted. Decide whether to set up a one-time or recurring payment based on your financial needs. After you fill out the form, review all details carefully before submitting. This guarantees your payment processes correctly and on time, helping you stay on track with your EIDL obligations. Making Payments by Mail Making payments by mail for your Economic Injury Disaster Loan (EIDL) requires careful attention to detail to guarantee your payment is processed correctly. Start by preparing a check or money order made out to “U.S. Small Business Administration.” Don’t forget to include your 10-digit SBA loan number in the memo field to guarantee proper allocation. Mail your payment to the designated SBA address in Portland, OR, as specified in your loan documentation. It’s crucial to send payments well in advance of the due date to account for possible postal delays and avoid late fees. Retain a copy of your payment and any tracking information. Regularly check your loan balance through the SBA’s Capital Access Financial System to confirm receipt and application. Using Bank Bill Pay Services Using bank bill pay services can streamline your EIDL loan payment process, offering a convenient alternative to mailing checks. To get started, follow these steps: Add the SBA as a payee in your bank’s online banking platform, using your loan number as the account number. Follow your bank’s specific procedures for processing payments to avoid any delays or issues. Make sure the payment includes the correct loan number in the memo field, ensuring proper application to your EIDL account. Keep a record of your payment confirmation from the bank to maintain accurate financial records. Setting Up Payment Reminders To guarantee you never miss a payment on your EIDL loan, setting up payment reminders is essential. Start by adding calendar reminders for your loan payment due dates, which begin 30 months after loan origination. You can likewise utilize the online payment system at pay.gov to schedule one-time or recurring payments, making it easier to manage your cash flow. Be sure to regularly check your EIDL loan balance through the SBA’s Capital Access Financial System or the MySBA Loan Portal to stay updated on your outstanding amount and upcoming obligations. Mark your calendar for the end of the deferment period and consider setting reminders at least a week in advance to prepare for any necessary adjustments to your finances. Keeping Track of Loan Documentation Keeping track of your loan documentation is crucial for maintaining compliance with SBA requirements and guaranteeing smooth management of your EIDL loan. Here are key items to monitor closely: Itemized Receipts and Contracts: Keep detailed records of all expenses related to the EIDL loan, as the SBA may request these for verification. Loan Agreement Details: Document the terms, interest rates, and repayment schedules for easy reference and effective financial planning. Tax Documentation Alignment: Confirm your loan usage records align with your tax documents to support compliance. Business Changes: Document any changes in business structure or ownership and notify the SBA without delay to maintain compliance with reporting requirements. Regularly reviewing these documents prepares you for potential audits and keeps your financial management on track. Understanding Payment Allocation Grasping how your EIDL loan payments are distributed is essential for effective financial management and compliance with SBA requirements. Each payment consists of both principal and interest, so comprehending this breakdown helps you track your loan progress. During the deferment period, interest accrues, potentially increasing your total loan balance even without payments. Once payments start, closely monitor how much of each payment reduces the principal versus covering interest. Properly allocating payments not just decreases your outstanding balance but additionally minimizes overall interest paid over the loan’s life. Keeping transparent records of these allocations is critical, ensuring compliance with SBA guidelines and aiding in your personal financial planning, which ultimately supports your business’s growth and sustainability. Seeking Assistance for EIDL Management As you manage your EIDL loan payments, it’s important to know that personalized support is available to help you navigate your repayment obligations. Utilizing these resources can greatly ease your experience, allowing you to focus on your business. Here are some options to evaluate: SBA Support Teams: Reach out to dedicated teams for guidance on loan terms and conditions. MySBA Loan Portal: Use this platform to make payments and access important loan details easily. Financial Counseling: Seek assistance in managing your business finances effectively. Eligibility Clarification: Engage with support services to understand funding eligibility and streamline repayments. Frequently Asked Questions How Do I Make a Payment on My EIDL Loan? To make a payment on your EIDL loan, you can use the SBA’s online payment method through pay.gov. Create an account and complete the SBA 1201 Borrower Payment form. On the other hand, you can pay via bank bill pay by adding the SBA as a payee, using your loan number. If you prefer mailing, send a check to “U.S. Small Business Administration,” noting your loan number in the memo. What Is the 20% Rule for SBA? The 20% Rule for SBA loans requires any owner with 20% or more ownership to provide a personal guaranty for loans exceeding $200,000. This rule guarantees that significant stakeholders have a personal stake in repaying the loan. If you own a substantial portion of your business, comprehending this rule is essential, as failure to comply can lead to loan denial or complications during the approval process, impacting your overall financial strategy. Is There a Penalty for Early Payoff of EIDL Loan? No, there’s no penalty for early payoff of your EIDL loan. You can pay off your loan in full at any time without incurring extra fees. This can help you save on overall interest since it continues to accrue during deferment. Though your monthly payment amount won’t change, paying early will shorten your loan term, allowing you to achieve financial relief sooner. Adjust your repayment strategy as your financial situation permits for ideal savings. Will Eidl Ever Be Forgiven? EIDL loans won’t be forgiven, as they aren’t designed for that purpose. Unlike grants, these loans require repayment regardless of your business’s financial status. All borrowers, guarantors, and obligors must fulfill this obligation, and there’s no option for loan forgiveness or modification of repayment terms. For loans exceeding $25,000, collateral is additionally necessary, further emphasizing the importance of repaying the full amount as outlined in the loan agreement. Conclusion By actively managing your EIDL payments, you can guarantee timely repayment and avoid potential penalties. Utilize the MySBA Loan Portal to monitor your loan details, set up reminders for payment due dates, and choose a convenient payment method. Automating your payments can streamline the process, as staying organized with your loan documentation will help you keep track of important information. If you encounter any issues, don’t hesitate to reach out to the COVID-EIDL Contact Center for support. Image via Google Gemini This article, "Manage Your EIDL Payment – A Step-by-Step Guide" was first published on Small Business Trends View the full article
-
Managing your EIDL payment effectively is vital to maintaining your business’s financial health. You’ll start by creating an account on the MySBA Loan Portal, which allows you to monitor your loan details and payment schedule. Comprehending key dates and payment options, like ACH or PayPal, can simplify the process. Setting up reminders can help guarantee you never miss a due date. To navigate this efficiently, let’s examine the fundamental steps for a seamless payment experience. Key Takeaways Log in to the MySBA Loan Portal to view loan details and monitor your balance regularly. Set up reminders for payment due dates to ensure timely payments and avoid penalties. Choose your preferred payment method, such as ACH, PayPal, or debit card, for convenience. Prepare mailed payments with your SBA loan number included in the memo field for proper processing. Communicate with your lender for assistance or to discuss repayment options if facing financial difficulties. Understanding Your EIDL Loan When you receive an Economic Injury Disaster Loan (EIDL), it’s vital to fully understand its terms and conditions to manage your repayment effectively. EIDL loans carry an interest rate of less than 4% and can be repaid over a maximum of 30 years. Unlike EIDL Advances, these loans require repayment from all Obligors, including Borrowers and Guarantors. You’ll start making EIDL payments 30 months after the loan origination date, with interest continuing to accrue during the deferment period. To keep track of your expenses, an SBA loan lookup can help you maintain accurate records. Documentation of how funds were spent is important, so save all itemized receipts as required by the SBA to guarantee compliance and facilitate repayment. Key Dates for EIDL Payments When managing your EIDL payments, it’s essential to know the key dates that will affect your loan repayment. Payments will start 30 months after your loan origination date, so it’s important to mark that on your calendar. With the deferment period extended, you should likewise keep track of interest accruing during this time, as it impacts your total loan balance. Important Payment Deadlines Comprehending the key payment deadlines for your Economic Injury Disaster Loan (EIDL) is vital to maintaining financial stability. Payments begin 30 months after the loan origination date, following a deferment period. To avoid late fees and guarantee timely payments, stay aware of deadlines, as interest accrues during deferment. You can check your loan balance and obligations through the MySBA Loan Portal or the SBA’s Capital Access Financial System. Deadline Type Description Action Required Loan Origination Date Start of deferment Note the 30-month countdown First Payment Due 30 months post-origination Prepare for payment Payment Frequency Monthly payments thereafter Set reminders Regularly monitor your loan status for effective financial management. Deferment Period Extension The extension of the deferment period for Economic Injury Disaster Loans (EIDL) offers borrowers additional relief before repayments begin, now set to start 30 months after the loan origination date. This extension provides you with extra time to prepare your finances. Nevertheless, it’s important to bear in mind that interest continues to accrue during this period, potentially increasing your total repayment amount. You can make early payments without any pre-payment penalties, which can help reduce the overall interest costs. Staying informed about your loan terms and payment schedules is crucial to avoid surprises when the deferment period ends. Accessing the MySBA Loan Portal To access the MySBA Loan Portal, you’ll need to create an account using the same login credentials from the previous Capital Access Financial System (CAFS). Once you’re logged in, maneuvering your loan information is straightforward, enabling you to review details and make payments online. This portal not merely streamlines your payment process but will additionally add features like recurring payments in the future for added convenience. Creating Your Account Accessing the MySBA Loan Portal is a straightforward process, especially for those who’ve previously used the Capital Access Financial System (CAFS). To create your account, you’ll need to use the same login credentials from CAFS, as the system changed on March 23, 2023. If you’re not already enrolled, you can set up an account by providing your name, date of birth, and SBA loan number. You can find your SBA loan number in the RAPID portal or your original loan documents, which are crucial for this process. Once logged in, you’ll be able to view your loan details, make payments, and access statements directly from the portal, streamlining your loan management experience. Navigating Loan Information Once you’ve successfully created your MySBA Loan Portal account, managing your loan information becomes a streamlined process. You can access the portal using the same login credentials you previously used for the Capital Access Financial System (CAFS) as of March 23, 2023. Within the portal, you’ll find detailed loan information, including account statements. Even though the option to set up recurring payments is anticipated to be added in the future, you can currently make payments through various methods, including PAY.gov and online banking. Remember, for payments to advance the due date, they must be processed within 25 days of the due date. For any questions or documentation requests, contact the COVID-EIDL Contact Center via email, ensuring you include your company name and loan number in the subject line. Making Payments Online Making online payments for your EIDL loan is a straightforward process when you utilize the MySBA Loan Portal. First, log in using the same credentials you used for the Capital Access Financial System (CAFS) as of March 23, 2023. Once you’re in, you can view your loan details, make payments, and access your statements directly. Remember, payments must be completed within 25 days of the due date to advance the payment date, and bulk payments aren’t supported. You’ll find a recurring payments feature may be added in the future for easier management. Keep in mind that interest continues to accrue during hardship accommodations, which allow for reduced payments for six months. Stay informed to manage your obligations effectively. Checking Your EIDL Loan Balance How can you effectively manage your EIDL loan obligations? Start by checking your EIDL loan balance regularly. To do this, visit the SBA’s Capital Access Financial System (CAFS) website. If you haven’t created an account yet, you’ll need to sign up using your name, date of birth, and SBA loan number, which you can find in the RAPID portal or your original loan documents. If you’re struggling to locate it, don’t hesitate to contact the Disaster Loan Servicing Centers for help. Monitoring your loan balance is essential, especially since interest continues to accrue during the deferment period. This way, you can stay informed about your repayment obligations and guarantee effective financial planning moving forward. How to Pay Your EIDL Loan Online Paying your EIDL loan online is a straightforward process that can help you stay on top of your financial responsibilities. To get started, sign in or create an account at pay.gov, then locate the SBA 1201 Borrower Payment form. Enter your SBA loan number and the payment amount on the form. Choose a payment method such as ACH, PayPal, or debit card, as credit card payments aren’t accepted. You can set up one-time or recurring payments based on your preferred frequency. Remember to make your payment within 25 days of the due date to advance the payment date and avoid late fees. Keep in mind that interest continues to accrue during the deferment period, which lasts up to 30 months. Steps to Create a Pay.gov Account Creating a Pay.gov account is crucial for managing your EIDL payments effectively. To get started, head to the Pay.gov website and select “Create an Account,” where you’ll need to provide your name, date of birth, and your SBA loan number. Once you’ve entered this information and followed the prompts, you’ll gain access to various payment options for your loan. Account Creation Process To start the account creation process on Pay.gov, visit the website and select the “Sign Up” option. You’ll be prompted to enter personal information, including your name, date of birth, and email address. Make sure you have your SBA loan number handy, as it’s needed during registration. After you’ve filled out the required information, take a moment to carefully review the terms and conditions before submitting your account application. Once your account is successfully created, you can log in to manage your EIDL loan payments online. Pay.gov offers various payment methods, including ACH transfers, PayPal, or debit cards, making it easy and convenient to stay on top of your loan obligations. Required Information Details When you’re ready to create your Pay.gov account, start by visiting the website and selecting the “Create an Account” option. You’ll need to provide personal information, including your name, date of birth, and your SBA loan number, which you can find in your RAPID portal or original loan documents. After entering this required information, you’ll set up a secure username and password for your account. Once your account is created, it enables you to make your EIDL loan payments online, with options like ACH or debit card. Remember to keep your login credentials secure, as you’ll need them to access your account and manage future payments efficiently. Accessing Payment Options Accessing payment options for your EIDL loan becomes straightforward once you create a Pay.gov account. To start, visit the Pay.gov website and select the “Sign Up” option. You’ll need to provide personal information, including your name, date of birth, and SBA loan number. If you can’t find your loan number, check the RAPID portal, your original loan documents, or contact Disaster Loan Servicing Centers. After setting up your account, you can access the SBA 1201 Borrower Payment form to make payments via ACH, PayPal, or debit card. Remember to keep your login credentials secure and check your account regularly for updates. Step Action Notes 1. Visit Pay.gov Go to the website Look for “Sign Up” 2. Provide Info Enter your details Include SBA loan number 3. Make Payments Access SBA 1201 form Use ACH, PayPal, or debit Completing the SBA 1201 Borrower Payment Form Completing the SBA 1201 Borrower Payment form is a crucial step in managing your Economic Injury Disaster Loan (EIDL) payments. To guarantee a smooth process, follow these steps: Sign in or create an account at pay.gov, the SBA’s preferred platform. Input your SBA loan number and payment amount accurately to avoid delays. Choose a payment method—options include ACH, PayPal, or debit card, as credit cards aren’t accepted. Decide whether to set up a one-time or recurring payment based on your financial needs. After you fill out the form, review all details carefully before submitting. This guarantees your payment processes correctly and on time, helping you stay on track with your EIDL obligations. Making Payments by Mail Making payments by mail for your Economic Injury Disaster Loan (EIDL) requires careful attention to detail to guarantee your payment is processed correctly. Start by preparing a check or money order made out to “U.S. Small Business Administration.” Don’t forget to include your 10-digit SBA loan number in the memo field to guarantee proper allocation. Mail your payment to the designated SBA address in Portland, OR, as specified in your loan documentation. It’s crucial to send payments well in advance of the due date to account for possible postal delays and avoid late fees. Retain a copy of your payment and any tracking information. Regularly check your loan balance through the SBA’s Capital Access Financial System to confirm receipt and application. Using Bank Bill Pay Services Using bank bill pay services can streamline your EIDL loan payment process, offering a convenient alternative to mailing checks. To get started, follow these steps: Add the SBA as a payee in your bank’s online banking platform, using your loan number as the account number. Follow your bank’s specific procedures for processing payments to avoid any delays or issues. Make sure the payment includes the correct loan number in the memo field, ensuring proper application to your EIDL account. Keep a record of your payment confirmation from the bank to maintain accurate financial records. Setting Up Payment Reminders To guarantee you never miss a payment on your EIDL loan, setting up payment reminders is essential. Start by adding calendar reminders for your loan payment due dates, which begin 30 months after loan origination. You can likewise utilize the online payment system at pay.gov to schedule one-time or recurring payments, making it easier to manage your cash flow. Be sure to regularly check your EIDL loan balance through the SBA’s Capital Access Financial System or the MySBA Loan Portal to stay updated on your outstanding amount and upcoming obligations. Mark your calendar for the end of the deferment period and consider setting reminders at least a week in advance to prepare for any necessary adjustments to your finances. Keeping Track of Loan Documentation Keeping track of your loan documentation is crucial for maintaining compliance with SBA requirements and guaranteeing smooth management of your EIDL loan. Here are key items to monitor closely: Itemized Receipts and Contracts: Keep detailed records of all expenses related to the EIDL loan, as the SBA may request these for verification. Loan Agreement Details: Document the terms, interest rates, and repayment schedules for easy reference and effective financial planning. Tax Documentation Alignment: Confirm your loan usage records align with your tax documents to support compliance. Business Changes: Document any changes in business structure or ownership and notify the SBA without delay to maintain compliance with reporting requirements. Regularly reviewing these documents prepares you for potential audits and keeps your financial management on track. Understanding Payment Allocation Grasping how your EIDL loan payments are distributed is essential for effective financial management and compliance with SBA requirements. Each payment consists of both principal and interest, so comprehending this breakdown helps you track your loan progress. During the deferment period, interest accrues, potentially increasing your total loan balance even without payments. Once payments start, closely monitor how much of each payment reduces the principal versus covering interest. Properly allocating payments not just decreases your outstanding balance but additionally minimizes overall interest paid over the loan’s life. Keeping transparent records of these allocations is critical, ensuring compliance with SBA guidelines and aiding in your personal financial planning, which ultimately supports your business’s growth and sustainability. Seeking Assistance for EIDL Management As you manage your EIDL loan payments, it’s important to know that personalized support is available to help you navigate your repayment obligations. Utilizing these resources can greatly ease your experience, allowing you to focus on your business. Here are some options to evaluate: SBA Support Teams: Reach out to dedicated teams for guidance on loan terms and conditions. MySBA Loan Portal: Use this platform to make payments and access important loan details easily. Financial Counseling: Seek assistance in managing your business finances effectively. Eligibility Clarification: Engage with support services to understand funding eligibility and streamline repayments. Frequently Asked Questions How Do I Make a Payment on My EIDL Loan? To make a payment on your EIDL loan, you can use the SBA’s online payment method through pay.gov. Create an account and complete the SBA 1201 Borrower Payment form. On the other hand, you can pay via bank bill pay by adding the SBA as a payee, using your loan number. If you prefer mailing, send a check to “U.S. Small Business Administration,” noting your loan number in the memo. What Is the 20% Rule for SBA? The 20% Rule for SBA loans requires any owner with 20% or more ownership to provide a personal guaranty for loans exceeding $200,000. This rule guarantees that significant stakeholders have a personal stake in repaying the loan. If you own a substantial portion of your business, comprehending this rule is essential, as failure to comply can lead to loan denial or complications during the approval process, impacting your overall financial strategy. Is There a Penalty for Early Payoff of EIDL Loan? No, there’s no penalty for early payoff of your EIDL loan. You can pay off your loan in full at any time without incurring extra fees. This can help you save on overall interest since it continues to accrue during deferment. Though your monthly payment amount won’t change, paying early will shorten your loan term, allowing you to achieve financial relief sooner. Adjust your repayment strategy as your financial situation permits for ideal savings. Will Eidl Ever Be Forgiven? EIDL loans won’t be forgiven, as they aren’t designed for that purpose. Unlike grants, these loans require repayment regardless of your business’s financial status. All borrowers, guarantors, and obligors must fulfill this obligation, and there’s no option for loan forgiveness or modification of repayment terms. For loans exceeding $25,000, collateral is additionally necessary, further emphasizing the importance of repaying the full amount as outlined in the loan agreement. Conclusion By actively managing your EIDL payments, you can guarantee timely repayment and avoid potential penalties. Utilize the MySBA Loan Portal to monitor your loan details, set up reminders for payment due dates, and choose a convenient payment method. Automating your payments can streamline the process, as staying organized with your loan documentation will help you keep track of important information. If you encounter any issues, don’t hesitate to reach out to the COVID-EIDL Contact Center for support. Image via Google Gemini This article, "Manage Your EIDL Payment – A Step-by-Step Guide" was first published on Small Business Trends View the full article
-
We may earn a commission from links on this page. Dan Levy's follow-up to Schitt's Creek teams him with I Love LA creator Rachel Sennott for a comedy that, in the best tradition of crime shows, starts small and gets absolutely ridonculous. Laurie Metcalf stars as mom and matriarch Linda alongside Dan Levy's closeted gay minister Nicky and Taylor Ortega's chaos-magnet Morgan. Linda demands that the two of them get a piece of jewelry for their dying grandmother's last birthday, leading to a tiny bit of theft that finds them in debt to the mob. Not content to put the family through the wringer just once, Netflix has renewed it for a second season. In the meantime, enjoy these other crime comedies that try and mostly fail to keep things in the family. Good Girls (2018 – 2021) Beth, Ruby and Annie (Christina Hendricks, Retta, and Mae Whitman, respectively) are three moms in suburban Michigan, and they are all having serious money troubles. They're not exactly criminal masterminds, so they concoct a scheme to rob the local grocery store to solve them—a store that just happens to be serve as a front for a money-laundering operation. They make off with $500,000—but the gang leader whose money they unknowingly stole wants it back. Oh, and the store manager spotted one of their distinctive tattoos and is threatening blackmail. It's definitely not a sitcom, but it's a solid comedy-drama with a talented cast of characters who keep finding themselves in deeper and deeper trouble over the course of four seasons. Stream Good Girls on Netflix. Good Girls (2018 – 2021) at Netflix Learn More Learn More at Netflix Deli Boys (2025 – ) Pakistani-American journalist and producer Abdullah Saeed has long been celebrated for his investigative reporting and his Vice documentaries, many of them dealing with the impacts of cannabis laws. That experience lends a unique verisimilitude to this comedy series following two brothers—hardworking Mir (Asif Ali) and hard partying Raj (Saagar Shaikh)—who, after the death of their wealthy father, learn that the bulk of their family's money comes not from the public-facing chain of delis, but from the illegal drug operation running behind the scenes. It's fast-paced and frequently very fun, and plays with the notion that the only way to make it in modern America is to live some kind of double life. Stream Deli Boys on Hulu. Deli Boys (2025 – ) at Hulu Learn More Learn More at Hulu Search Party (2016 – 2022) Alia Shawkat stars here as Dory Sief, an aimless millennial who decides, after seeing a missing-person poster for a college acquaintance, that she's going to make it her purpose to track down Chantal (Clare McNulty) with the extremely begrudging support of her friends. The show shifts focus from season to season, but it's really in the second that the similarities to Big Mistakes become most clear: While initially a darkly comic take on a Nancy Drew-style mystery, the show later finds the gang desperate to cover up a mostly unintentional murder. It's a funny, smart, and impressively weird oddity of a show. Stream Search Party on Netflix. Search Party at Netflix Learn More Learn More at Netflix How to Get to Heaven From Belfast (2026 – ) How to Get to Heaven comes from Irish playwright and Derry Girls creator Lisa McGee, though that earlier and justifiably beloved show will only moderately prepare you for the latest. Three high school friends from Belfast reunite after learning that their fourth bestie has died unexpectedly—except that maybe she didn't, a mixed blessing given that they all have life-ruining secrets that they were hoping to bury. Now they're off to investigate the mystery of the maybe-murder, and find themselves in way over their heads and in a complex web of lies, secrets, and old vendettas. The tone is all over the place in a way that somehow works, and the show has a beating heart beneath the absolute chaos. Stream How to Get to Heaven From Belfast on Netflix. How to Get to Heaven From Belfast (2026 – ) at Netflix Learn More Learn More at Netflix Vincenzo (2021) Vincenzo reads like a typical crime drama with just a bit of a twist: Song Joong-ki plays Park Joo-hyung AKA Vincenzo Cassano, Korean by birth but later adopted by an Italian family; as an adult he becomes a lawyer and Mafia consigliere. When the head of the Cassano Family dies, the Don's biological son looks to clean house, forcing Vincenzo to flee to Korea to claim a large cache of money he'd stashed. This is when it gets weirder and more interesting: The money's hidden under a commercial building full of weird and quirky tenants, and circumstances soon put Vincenzo at odds with the pharmaceutical conglomerate that has its eyes on the complex. What started as an unconventional mob story becomes a story about a guy using his mafia skills (the show doesn't shy away from violence) to battle capitalism on behalf of some charmingly goofy new friends. Stream Vincenzo on Netflix. Vincenzo (2021) at Netflix Learn More Learn More at Netflix Barry (2018 – 2023) Bill Hader won a couple of Emmys for his performance as Barry Berkman, a depressed and anxious hitman who discovers a love of acting that leads him to look for a life beyond killing people, even though he's rather good at it, and keeps getting drawn back in. Barry's mentor and father figure in his quest to rebuild his life on the stage is the wildly eccentric Gene Cousineau (Henry Winkler, who also won an Emmy here), who's entirely supportive of Barry—until he learns of his protégé's double life. Stream Barry on HBO Max. Barry (2018 – 2023) at HBO Max Learn More Learn More at HBO Max Bad Sisters (2022 – 2024) A pitch-dark and pitch-perfect comedy, the Irish import Bad Sisters picked up several well-deserved Emmy nominations in its first year. Writer and co-creator Sharon Horgan leads the cast as Eva Garvey, oldest of five sisters, including Grace (Anne-Marie Duff), who's married to John Paul, an abusive and isolating husband. When the dude winds up dead under rather suspicious circumstances, down-on-his-luck insurance investigator Tom (Brian Gleeson) starts poking his nose into things. We know the sisters definitely wanted John Paul dead, but did they actually do the deed? Tom's family business will go under if he has to pay out on the life insurance policy, so he's very motivated to pin the (potential) crime on at least one of the women. Stream Bad Sisters on Apple TV. Bad Sisters (2022 – 2024) at Apple TV Learn More Learn More at Apple TV The Gentlemen (2024 – ) This is very much a Guy Ritchie show inspired by a Guy Ritchie film—which ought to tell you all you need to know about the vibe (polished, snarky, and ultra-violent). Theo James plays army officer and Eddie Horniman (I believe I mentioned Guy Ritchie?), heir to the Horniman estate (there it is again) who, upon the death of his father, is named the Duke of Halstead. He learns that dad was tied to various criminal enterprises, and that his scouse brother is millions of pounds in debt to a drug dealer. What else is the dapper, military-trained Duke to do but learn to navigate the violent underworld while looking cool? Stream The Gentlemen on Netflix. The Gentlemen (2024 – ) at Netflix Learn More Learn More at Netflix The Sticky (2024) Though it's tempting to find questionable taste in setting a caper show in Quebec and then having it involve maple syrup, The Sticky is loosely based on The Great Canadian Maple Syrup Heist—a real thing that happened in 2012. Margo Martindale (Justified) plays Ruth Landry, a maple syrup farmer struggling since her husband's incapacitation and running up against a greedy businessman trying to buy her land out from under her. She meets dopey security guard Remy Bouchard (Guillaume Cyr), who's been stealing a barrel or two at a time from the warehouse where he works, and then mobster Mike Byrne (Chris Diamontopoulos) who, she realizes, could provide the muscle needed for a heist. In the best tradition of something like Fargo, the foolproof plan to steal a bunch of syrup gets well out of hand, very quickly. The show ends on a bit of a cliffhanger, but there's still a relatively complete story in its single season. Stream The Sticky on Prime Video. The Sticky (2024) at Prime Video Learn More Learn More at Prime Video The Brothers Sun (2024) A fun action-comedy and member of the Netflix one-season-and-done club, The Brothers Sun stars Oscar-winner Michelle Yeoh as Eileen Sun, the exiled matriarch of a family of Taiwanese gangsters. She'd come to Los Angeles years before, taking a son, Bruce (Sam Song Li), who grew up knowing little of his origins and has few ambitions beyond becoming great at improv comedy. An assassination attempt sends his older brother to L.A., drawing Eileen and Bruce back into the criminal fold, with rival factions coming at them from every side. Stream The Brothers Sun on Netflix. The Brothers Sun (2024) at Netflix Learn More Learn More at Netflix View the full article
-
US president warns Tehran has ‘two or three days’ to reach a deal and reopen the Strait of HormuzView the full article
-
A few times each year, the tech community lights up with new theories and renewed speculation about what Apple might announce next. Those of us who scour the internet for the latest leaks and whispered rumors might try to guess what colors the next iPhone might come in, or what new features could ship with the next version of iOS, then watch Apple's keynote presentations live to see if we were right. If that sounds like you, listen up: This year, your guesses could win you a brand new Apple Watch. Throughout 2026, Lifehacker is running a guessing game contest based on Apple's new announcements and releases. Here's how it works: The contest will unfold across three rounds. We're currently in Round 1, which will continue through June 2. As you can see from the questions above, this round is focused on the scuttlebutt around Apple's software (iOS, iPadOS, macOS, watchOS, visionOS, etc.). Round 2, which will run from July 7 through July 21, concerns Apple's devices (iPhones, iPads, Macs, Apple Watches, Vision Pro, etc.). Round 3, which will span Aug. 18 through Sept. 1, centers on Apple's fall event. During each round, you'll answer five questions about what Apple might announce or reveal during its major keynote events. Each question you answer with a correct prediction earns you one entry into the grand-prize drawing, to be held at the conclusion of all three rounds. If you win the drawing, you'll walk away with the latest version of the Apple Watch. To be eligible, an entrant must be at least 18 years old, and a resident of the 50 U.S. states or Washington, D.C. Lifehacker isn't throwing this event alone: The other CNET Group sites (CNET, Mashable, PCMag, ZDNET) are also hosting their own questions. That means there will be 75 possible questions to answer across all CNET Group sites and all three rounds. You're free to submit answers to any and all of the questionnaires on these sites during each round, but please note that each entrant is only eligible to win one prize. Each of the five websites will announce the winner of its contest shortly after Apple's fall event. Once you've answered, you'll receive a copy of your responses at the email address you provide, so you can keep track of your predictions—and make sure to come back in July for Round 2 of Lifehacker's Big Guessing Game: Apple Edition. NO PURCHASE NECESSARY to enter or win the "CNET Group Big Guessing Game" Giveaway. Open to legal U.S. residents in the 50 U.S. & D.C., 18+ yrs of age. Other restrictions apply. Begins May 19, 2026 at 12:01 p.m. ET and ends Sept. 1, 2026 at 11:59 p.m. ET. Void where prohibited. Subject to Official Rules. Sponsor: Ziff Davis, LLC. Apple is not a sponsor of, affiliated with, or endorser of this sweepstakes. Apple Watch is a trademark of Apple Inc. View the full article
-
Boards everywhere are saying “we need AI agents.” That pressure moves down the organization fast. Teams build a pilot and achieve good results in a sandbox. Then they try to put it in production and everything slows down. Usually, the model performed fine. What was missing was what surrounded it—monitoring, ownership, a plan for when things go wrong. I’ve been shipping software in regulated industries for 20 years. In those industries, when something hallucinates, planes don’t fly or money doesn’t move. So you learn to care about the process more than the tools, and realize that the model is the easy part. You can swap one for another in an afternoon. What you can’t swap is the workflow underneath it, and the domain knowledge baked into how an agent actually makes decisions. THE WORKFLOW IS THE PRODUCT In production, you don’t release anything without a rollback plan. You collect metrics from day one because if you forget, you can’t answer questions later. Every layer needs to be traceable. None of it changes just because the code is being written by an agent instead of a person. An agent in a regulated environment needs control on its decision logic, defined inputs and outputs, monitoring, and a way back to a safe state when something breaks. But the harder part is what comes before any of that—domain knowledge. The reason companies keep working with the same engineering teams for years is that those teams know which systems interact, which areas are fragile, and where a small change cascades. That accumulated understanding of a client’s business, processes, and technical landscape is what allows you to build agents that hold up in production. Without it, you may be automating processes you don’t fully understand. MIT’s 2025 research shows that 95% of enterprise AI pilots produce no measurable business impact, and the problem is consistently how organizations adopt, integrate, and govern AI. ONBOARD AGENTS THE WAY YOU ONBOARD ENGINEERS You don’t expect a new developer to do a proper feature or fix in the main branch on day one. There’s a ramp-up period and supervision. You start them on smaller tasks, review their work closely, and gradually increase the scope as they prove they can deliver reliably. Agents need the same treatment. That means giving them a clear “definition of done,” evaluating their output against known benchmarks, having someone review the results until trust is earned, and building an escalation path for when the agent hits something it can’t handle. The discipline we’ve spent decades building around human onboarding applies directly here, as well—we just haven’t been applying it. Stack Overflow’s 2025 Developer Survey, with more than 49,000 respondents, found that 45% of developers say debugging AI-generated code is more time-consuming than expected. The output looks right. Then you look closer and it isn’t. A function passes its tests but handles an edge case in a way no experienced engineer would accept. That’s where the human job is moving—not writing code, but catching what the machine got almost right. And doing that well requires people who know what “right” looks like in a given domain. REVIEW THE BLUEPRINT, NOT THE BRICKS An agent can produce a thousand lines of code in seconds. If your senior engineers are reviewing all of that after the fact, they become a permanent bottleneck. A better approach would be to do a shift left and review the spec before the agent starts. A small misalignment early on compounds quickly. By the end, you’re looking at an output that barely resembles what was intended. The teams understanding that have moved their senior people into something closer to an architect-supervisor role. They spend most of their time sharpening the brief, not inspecting finished work. That takes people who’ve shipped things in production, who know what breaks at scale, and who understand the domain well enough to write specs an agent can follow without drifting. The models will keep getting better on their own. The workflows, the guardrails, the knowledge of what actually matters in a specific industry, all come from years of doing the work. Denis Danov is CTO at Dreamix. View the full article
-
Finding the right accountant for your new business is a critical step in the direction of financial stability. You need to assess your specific accounting needs, such as tax obligations and payroll requirements. It’s essential to understand the different types of accountants available and how their expertise aligns with your industry. As you explore your options, consider the qualifications, communication styles, and whether they can grow with your business. Knowing what to look for can make all the difference as you navigate this important decision. Key Takeaways Assess your accounting needs to determine if you require ongoing support or seasonal assistance based on your business’s complexity and financial situation. Seek accountants with relevant industry experience to ensure they understand unique regulations and challenges specific to your business sector. Verify qualifications and credentials, such as CPA or CMA, while checking references and client testimonials for reliability and effectiveness. Evaluate communication styles and personal compatibility to ensure a comfortable working relationship for discussing sensitive financial matters. Discuss scalability of services to ensure your accountant can support your business as it grows and adapts to changing financial complexities. Assess Your Accounting Needs When you start a new business, it’s crucial to assess your accounting needs, as this will significantly influence your decision on which accountant to hire. First, evaluate whether you require ongoing accounting support or just seasonal assistance; this distinction will guide your choice. Next, identify specific services you need, like tax preparation, payroll management, or budgeting, to guarantee the accountant can meet your unique requirements. Consider the complexity of your financial situation; intricate needs may necessitate hiring a CPA or a specialized accountant. If your business operates in a sector with unique financial regulations, seek industry-specific expertise. Furthermore, assess your financial literacy and comfort with managing finances, as this will help you decide how much support you may need. Finally, prepare a list of questions to ask an accountant, as this will assist you in how to choose an accountant best suited for your new business. Understand the Different Types of Accountants When you’re selecting an accountant, it’s essential to understand the different types available and their key responsibilities. Certified Public Accountants (CPAs) offer a broad range of services, whereas Enrolled Agents (EAs) focus on tax representation. Furthermore, knowing whether you need a Bookkeeper for daily transactions or a Tax Attorney for complex issues can greatly impact your business’s financial management. Types of Accounting Professionals Steering through the domain of accounting can feel overwhelming, especially for new business owners who need to understand the various types of accounting professionals available. Certified Public Accountants (CPAs) are licensed experts, equipped to handle complex tasks and provide strategic advice. Enrolled Agents (EAs) focus on tax preparation and can represent you before the IRS. If you face legal tax issues, a Tax Attorney specializes in tax law and can navigate disputes with the IRS. Management Accountants (CMAs) work within your organization, focusing on budgeting and financial analysis. To find the right fit, consider the specific financial needs of your business and prepare questions to ask a CPA, ensuring you select the professional best suited to help you succeed. Key Responsibilities of Accountants Grasping the key responsibilities of accountants is crucial for any new business owner. Certified Public Accountants (CPAs) offer services like tax preparation, financial planning, and business consulting, making them indispensable for ongoing financial management. If you face complex tax situations, Enrolled Agents (EAs) are licensed by the IRS to represent you during audits and appeals. For legal matters, Tax Attorneys focus on tax law disputes and provide necessary legal advice. Management Accountants, or Certified Management Accountants (CMAs), specialize in financial analysis, guiding your business decisions based on financial data. Finally, Bookkeepers manage daily transactions like invoicing and payroll, ensuring accurate record-keeping that supports accountants in handling more complex tasks. Comprehending these roles helps you choose the right professional for your needs. Look for Relevant Industry Experience How important is it for your accountant to have industry-focused experience? It’s vital. When you inquire about their experience, focus on how well they understand your industry’s unique challenges and regulations. An accountant with a proven track record in your sector can provide valuable insights into tax breaks and financial strategies customized particularly for your business type. Moreover, make certain they’ve worked with businesses of similar size and complexity to grasp your financial needs and operational nuances. Familiarity with industry-oriented accounting software is likewise fundamental, as these tools can streamline your operations. Finally, prioritize accountants who demonstrate success in managing financial situations similar to those your business may face. This capability can greatly support your growth and help you navigate any challenges that arise. Having an accountant with relevant experience can make a considerable difference in your business’s financial health. Seek Referrals From Trusted Sources When starting a new business, seeking referrals from trusted sources can greatly improve your search for the right accountant. Friends, family, and colleagues can lead you to reliable accountants who understand your specific business needs. Often, word-of-mouth recommendations reveal insights into an accountant’s professionalism, reliability, and effectiveness, which can save you valuable time. Personal connections may share firsthand experiences, offering feedback on strengths and weaknesses in handling financial matters, giving you a clearer idea of what to expect. Moreover, engaging with adjacent businesses in your industry can yield referrals from those who’ve faced similar challenges and can recommend accountants familiar with your sector’s specific requirements. Finally, combining these personal referrals with online platforms and customer reviews will provide a well-rounded perspective, ensuring you choose the best fit for your new business. This approach can greatly improve your confidence in your final decision. Evaluate Qualifications and Certifications Finding the right accountant involves more than just personal recommendations; evaluating their qualifications and certifications is equally important. Start by looking for accountants with credentials like Certified Public Accountant (CPA) or Certified Management Accountant (CMA), as these indicate a high level of expertise and commitment to ongoing education. Verify their qualifications align with your business’s specific needs, since different industries often require specialized knowledge in areas such as tax regulations. Next, assess their experience and examine their previous work history with businesses similar to yours. This will help you determine if they’ve successfully navigated challenges relevant to your sector. Furthermore, inquire about their proficiency with accounting software and tools that pertain to your operations, as modern technology is key for efficient financial management. Finally, check for any extra certifications or training that could improve their qualifications, such as expertise in specific tax laws or financial planning strategies beneficial to your business. Consider the Accountant’s Fee Structure Understanding the accountant’s fee structure is vital for effectively managing your business budget, especially since fees can vary widely based on the services provided. Typically, hourly rates range from $100 to $500, depending on the accountant’s experience and location. Some accountants charge a flat fee for specific tasks, like tax preparation, which can offer cost predictability, whereas others may bill hourly, leading to fluctuating expenses based on service complexity. It’s important to inquire about any additional costs that might arise, especially during peak times like tax season, to avoid surprises. Comparing quotes from multiple accountants can help you find the best value; nonetheless, keep in mind that the lowest price doesn’t always mean the best service. Look for a thorough fee structure that outlines all potential costs, including retainer fees for ongoing services, to guarantee alignment with your business’s financial capabilities and needs. Check References and Client Testimonials When you’re selecting an accountant, checking references and client testimonials is essential for verifying their expertise. Look for feedback from clients in similar industries to guarantee their experience aligns with your needs, and ask about their responsiveness and communication style. Moreover, independent review platforms can provide unbiased insights into the accountant’s reliability and effectiveness in addressing specific challenges, helping you make a well-informed decision. Importance of Verification Verification plays a crucial role in selecting the right accountant for your new business, as it helps guarantee you’re making an informed decision. Checking references from previous clients offers insights into an accountant’s reliability and effectiveness. Client testimonials can reveal strengths and weaknesses, providing a clearer picture of service quality. Engaging with former clients allows you to assess how the accountant navigated challenges and contributed to financial success. Furthermore, verifying credentials and licenses through official channels guarantees the accountant is qualified. Conducting independent research on reviews can uncover unbiased opinions, enhancing your assessment of their capabilities. Aspect Importance References Insight into reliability and professionalism Client Testimonials Highlights strengths and weaknesses Credential Verification Confirms qualifications are valid Independent Research Uncovers unbiased opinions Diverse Client Experiences Diverse client experiences are essential for grasping the effectiveness of an accountant, as they can reveal how well the accountant meets varied business needs. By checking references and client testimonials, you can gain valuable insights into their reliability and professionalism. Consider the following points: Speak with former clients to perceive their experience with businesses like yours. Look for testimonials that highlight both strengths and weaknesses. Gather feedback from multiple sources to avoid bias. Evaluate how the accountant handles industry-specific challenges. This approach guarantees you develop a thorough grasp of the accountant’s communication style and overall effectiveness in supporting your business. In the end, diverse client experiences will guide you in making a well-informed decision. Independent Reference Checks Independent reference checks are a vital step in selecting the right accountant for your business. By reaching out to former or current clients, you can gather unbiased insights about an accountant’s performance and reliability, rather than relying merely on firm-provided references. When you contact references, ask specific questions about their experiences, focusing on the accountant’s responsiveness, industry expertise, and ability to meet deadlines. Multiple client assessments can highlight consistent strengths and weaknesses, aiding your decision-making process. Furthermore, verify testimonials for credibility by ensuring they originate from legitimate businesses or individuals who’ve directly worked with the accountant. Thorough reference checks not just help you find a qualified accountant but also establish a foundation of trust and transparency for your future working relationship. Ensure Proficiency With Accounting Software When selecting an accountant for your new business, it’s vital to guarantee they’re proficient with accounting software that fits your needs. An accountant skilled in the right tools can streamline your financial management and improve efficiency. Here are some key points to keep in mind: Confirm their proficiency with popular platforms like QuickBooks, used by over 3.4 million businesses. Make sure they can seamlessly integrate with your existing accounting systems to avoid complications. Ask about their experience with cloud-based tools, which allow for real-time financial monitoring and collaboration. Inquire if they stay updated on new accounting technologies, as 70% of small businesses believe technology improves financial management. Evaluating an accountant’s adaptability to various software platforms is important since 80% of accountants report that the right technology boosts their efficiency and accuracy. Investing time in this area will pay off in the long run. Assess Communication Style and Personal Compatibility When you’re choosing an accountant for your new business, evaluating their communication style and personal compatibility is key. Pay close attention during initial meetings to see how well they listen and address your concerns, as this can reveal their approachability. Furthermore, consider their availability for ongoing consultations and how they explain complex financial concepts, ensuring you’re comfortable discussing sensitive issues as your relationship develops. Evaluate Initial Meetings How can you determine if an accountant is the right fit for your new business during initial meetings? Start by evaluating their communication style; they should explain complex financial concepts in a way that makes sense to you. Next, assess personal compatibility; you need to feel comfortable discussing sensitive financial matters. Pay attention to their responsiveness and availability, as this indicates the level of support you can expect. Consider these key points: Inquire about their approach to client relationships. Observe if they prioritize comprehension of your unique business needs. Verify they’re approachable and willing to provide ongoing advice. Gauge their enthusiasm for building a long-term partnership. These factors will help you make an informed decision. Determine Availability for Consultations Finding the right accountant goes beyond evaluating their skills; it also involves comprehending their availability for consultations and communication style. First, assess their availability to guarantee they can meet your business needs and provide timely support. During initial meetings, pay attention to how they communicate; their style should align with your preferences for effective collaboration. Responsiveness to inquiries is vital; an accountant who quickly addresses questions demonstrates commitment to client service. Furthermore, discuss your preferred communication methods—whether it’s email, phone calls, or in-person meetings—to make certain they can accommodate your style and frequency. Finally, personal compatibility matters; choose an accountant you feel comfortable with, as this promotes a trusting and productive working relationship. Assess Long-term Relationship Dynamics What should you consider when evaluating long-term relationship dynamics with an accountant? Start by evaluating personal compatibility, as this nurtures open communication and collaboration crucial for your business growth. During initial meetings, assess their communication style and confirm it aligns with your preferences. Consider the following factors: Approachability and availability for consultations, which impacts timely insights. Trust and transparency, fundamental for maneuvering complex financial scenarios. Comprehension of your business goals and challenges, indicating their commitment to your success. Responsiveness in discussions, which affects ongoing advice quality. These elements will help you determine if the accountant is a good fit for a lasting partnership that supports your business’s evolving needs. Plan for Future Growth and Changes in Your Business As your business evolves, planning for future growth and changes becomes crucial, especially in relation to selecting an accountant. You need an accountant who can scale their services as your business grows, ensuring they can handle increased complexity in financial management. Discuss your long-term goals with potential accountants to gauge their comprehension of how to support your financial strategies. Consider the following aspects when evaluating accountants: Key Aspect Considerations Experience with Scaling Familiarity with businesses adapting to sizes Approach to Change Guidance on mergers and acquisitions Financial Planning Proactive strategies for future needs Long-term Goals Alignment with your business objectives Frequently Asked Questions How Can I Determine if an Accountant Is Trustworthy? To determine if an accountant is trustworthy, start by checking their credentials, such as certifications and licenses. Look for reviews or testimonials from previous clients, as these can provide insight into their reliability. It’s prudent to interview the accountant directly; ask about their experience and approach to client service. Furthermore, verify they follow ethical guidelines and maintain transparency regarding fees and services to establish a solid foundation of trust. What Red Flags Should I Watch for During Interviews? During interviews, watch for red flags like unclear communication, reluctance to provide references, or lack of relevant experience. If an accountant seems overly focused on fees rather than your needs, that’s a concern. Be cautious if they avoid discussing their qualifications or if you sense disorganization in their approach. Trust your instincts; if something feels off, it probably is. Clear, transparent dialogue is essential for a successful working relationship. How Often Should I Meet With My Accountant? You should meet with your accountant at least once a quarter to review your financial health, discuss tax strategies, and address any concerns. Monthly meetings can be beneficial, especially during busy seasons or if your business is growing swiftly. These regular check-ins guarantee you stay on track with your financial goals, allow for timely adjustments, and help you make informed decisions based on accurate data. Consistent communication nurtures a strong partnership. Can an Accountant Help With Tax Planning Strategies? Yes, an accountant can definitely help with tax planning strategies. They analyze your financial situation, identify potential deductions, and recommend tax-efficient practices customized to your business. By staying updated on tax laws, they guarantee you comply as they reduce your tax liability. Furthermore, they can project future tax obligations, guiding you in making informed financial decisions. Collaborating with an accountant improves your ability to navigate complex tax regulations effectively and optimize your overall tax strategy. What Happens if I Don’t Like My Accountant After Hiring? If you don’t like your accountant after hiring, it’s important to address the issue without delay. You can communicate your concerns directly and see if adjustments can be made. If that doesn’t work, you have the option to terminate the relationship. Make sure you review your contract for any termination clauses, and consider finding a replacement who better fits your needs. Maintaining a good working relationship is crucial for effective financial management. Conclusion Finding the right accountant for your new business is a critical step toward achieving financial stability. By evaluating your specific needs, seeking referrals, and reviewing qualifications, you can identify a professional who aligns with your goals. Comprehending their expertise, communication style, and ability to adapt as your business grows will guarantee a successful partnership. Taking the time to make an informed choice now can save you time and resources in the future, in the end contributing to your business’s success. Image via Google Gemini and ArtSmart This article, "10 Essential Tips for Finding the Right Accountant for Your New Business" was first published on Small Business Trends View the full article
-
Finding the right accountant for your new business is a critical step in the direction of financial stability. You need to assess your specific accounting needs, such as tax obligations and payroll requirements. It’s essential to understand the different types of accountants available and how their expertise aligns with your industry. As you explore your options, consider the qualifications, communication styles, and whether they can grow with your business. Knowing what to look for can make all the difference as you navigate this important decision. Key Takeaways Assess your accounting needs to determine if you require ongoing support or seasonal assistance based on your business’s complexity and financial situation. Seek accountants with relevant industry experience to ensure they understand unique regulations and challenges specific to your business sector. Verify qualifications and credentials, such as CPA or CMA, while checking references and client testimonials for reliability and effectiveness. Evaluate communication styles and personal compatibility to ensure a comfortable working relationship for discussing sensitive financial matters. Discuss scalability of services to ensure your accountant can support your business as it grows and adapts to changing financial complexities. Assess Your Accounting Needs When you start a new business, it’s crucial to assess your accounting needs, as this will significantly influence your decision on which accountant to hire. First, evaluate whether you require ongoing accounting support or just seasonal assistance; this distinction will guide your choice. Next, identify specific services you need, like tax preparation, payroll management, or budgeting, to guarantee the accountant can meet your unique requirements. Consider the complexity of your financial situation; intricate needs may necessitate hiring a CPA or a specialized accountant. If your business operates in a sector with unique financial regulations, seek industry-specific expertise. Furthermore, assess your financial literacy and comfort with managing finances, as this will help you decide how much support you may need. Finally, prepare a list of questions to ask an accountant, as this will assist you in how to choose an accountant best suited for your new business. Understand the Different Types of Accountants When you’re selecting an accountant, it’s essential to understand the different types available and their key responsibilities. Certified Public Accountants (CPAs) offer a broad range of services, whereas Enrolled Agents (EAs) focus on tax representation. Furthermore, knowing whether you need a Bookkeeper for daily transactions or a Tax Attorney for complex issues can greatly impact your business’s financial management. Types of Accounting Professionals Steering through the domain of accounting can feel overwhelming, especially for new business owners who need to understand the various types of accounting professionals available. Certified Public Accountants (CPAs) are licensed experts, equipped to handle complex tasks and provide strategic advice. Enrolled Agents (EAs) focus on tax preparation and can represent you before the IRS. If you face legal tax issues, a Tax Attorney specializes in tax law and can navigate disputes with the IRS. Management Accountants (CMAs) work within your organization, focusing on budgeting and financial analysis. To find the right fit, consider the specific financial needs of your business and prepare questions to ask a CPA, ensuring you select the professional best suited to help you succeed. Key Responsibilities of Accountants Grasping the key responsibilities of accountants is crucial for any new business owner. Certified Public Accountants (CPAs) offer services like tax preparation, financial planning, and business consulting, making them indispensable for ongoing financial management. If you face complex tax situations, Enrolled Agents (EAs) are licensed by the IRS to represent you during audits and appeals. For legal matters, Tax Attorneys focus on tax law disputes and provide necessary legal advice. Management Accountants, or Certified Management Accountants (CMAs), specialize in financial analysis, guiding your business decisions based on financial data. Finally, Bookkeepers manage daily transactions like invoicing and payroll, ensuring accurate record-keeping that supports accountants in handling more complex tasks. Comprehending these roles helps you choose the right professional for your needs. Look for Relevant Industry Experience How important is it for your accountant to have industry-focused experience? It’s vital. When you inquire about their experience, focus on how well they understand your industry’s unique challenges and regulations. An accountant with a proven track record in your sector can provide valuable insights into tax breaks and financial strategies customized particularly for your business type. Moreover, make certain they’ve worked with businesses of similar size and complexity to grasp your financial needs and operational nuances. Familiarity with industry-oriented accounting software is likewise fundamental, as these tools can streamline your operations. Finally, prioritize accountants who demonstrate success in managing financial situations similar to those your business may face. This capability can greatly support your growth and help you navigate any challenges that arise. Having an accountant with relevant experience can make a considerable difference in your business’s financial health. Seek Referrals From Trusted Sources When starting a new business, seeking referrals from trusted sources can greatly improve your search for the right accountant. Friends, family, and colleagues can lead you to reliable accountants who understand your specific business needs. Often, word-of-mouth recommendations reveal insights into an accountant’s professionalism, reliability, and effectiveness, which can save you valuable time. Personal connections may share firsthand experiences, offering feedback on strengths and weaknesses in handling financial matters, giving you a clearer idea of what to expect. Moreover, engaging with adjacent businesses in your industry can yield referrals from those who’ve faced similar challenges and can recommend accountants familiar with your sector’s specific requirements. Finally, combining these personal referrals with online platforms and customer reviews will provide a well-rounded perspective, ensuring you choose the best fit for your new business. This approach can greatly improve your confidence in your final decision. Evaluate Qualifications and Certifications Finding the right accountant involves more than just personal recommendations; evaluating their qualifications and certifications is equally important. Start by looking for accountants with credentials like Certified Public Accountant (CPA) or Certified Management Accountant (CMA), as these indicate a high level of expertise and commitment to ongoing education. Verify their qualifications align with your business’s specific needs, since different industries often require specialized knowledge in areas such as tax regulations. Next, assess their experience and examine their previous work history with businesses similar to yours. This will help you determine if they’ve successfully navigated challenges relevant to your sector. Furthermore, inquire about their proficiency with accounting software and tools that pertain to your operations, as modern technology is key for efficient financial management. Finally, check for any extra certifications or training that could improve their qualifications, such as expertise in specific tax laws or financial planning strategies beneficial to your business. Consider the Accountant’s Fee Structure Understanding the accountant’s fee structure is vital for effectively managing your business budget, especially since fees can vary widely based on the services provided. Typically, hourly rates range from $100 to $500, depending on the accountant’s experience and location. Some accountants charge a flat fee for specific tasks, like tax preparation, which can offer cost predictability, whereas others may bill hourly, leading to fluctuating expenses based on service complexity. It’s important to inquire about any additional costs that might arise, especially during peak times like tax season, to avoid surprises. Comparing quotes from multiple accountants can help you find the best value; nonetheless, keep in mind that the lowest price doesn’t always mean the best service. Look for a thorough fee structure that outlines all potential costs, including retainer fees for ongoing services, to guarantee alignment with your business’s financial capabilities and needs. Check References and Client Testimonials When you’re selecting an accountant, checking references and client testimonials is essential for verifying their expertise. Look for feedback from clients in similar industries to guarantee their experience aligns with your needs, and ask about their responsiveness and communication style. Moreover, independent review platforms can provide unbiased insights into the accountant’s reliability and effectiveness in addressing specific challenges, helping you make a well-informed decision. Importance of Verification Verification plays a crucial role in selecting the right accountant for your new business, as it helps guarantee you’re making an informed decision. Checking references from previous clients offers insights into an accountant’s reliability and effectiveness. Client testimonials can reveal strengths and weaknesses, providing a clearer picture of service quality. Engaging with former clients allows you to assess how the accountant navigated challenges and contributed to financial success. Furthermore, verifying credentials and licenses through official channels guarantees the accountant is qualified. Conducting independent research on reviews can uncover unbiased opinions, enhancing your assessment of their capabilities. Aspect Importance References Insight into reliability and professionalism Client Testimonials Highlights strengths and weaknesses Credential Verification Confirms qualifications are valid Independent Research Uncovers unbiased opinions Diverse Client Experiences Diverse client experiences are essential for grasping the effectiveness of an accountant, as they can reveal how well the accountant meets varied business needs. By checking references and client testimonials, you can gain valuable insights into their reliability and professionalism. Consider the following points: Speak with former clients to perceive their experience with businesses like yours. Look for testimonials that highlight both strengths and weaknesses. Gather feedback from multiple sources to avoid bias. Evaluate how the accountant handles industry-specific challenges. This approach guarantees you develop a thorough grasp of the accountant’s communication style and overall effectiveness in supporting your business. In the end, diverse client experiences will guide you in making a well-informed decision. Independent Reference Checks Independent reference checks are a vital step in selecting the right accountant for your business. By reaching out to former or current clients, you can gather unbiased insights about an accountant’s performance and reliability, rather than relying merely on firm-provided references. When you contact references, ask specific questions about their experiences, focusing on the accountant’s responsiveness, industry expertise, and ability to meet deadlines. Multiple client assessments can highlight consistent strengths and weaknesses, aiding your decision-making process. Furthermore, verify testimonials for credibility by ensuring they originate from legitimate businesses or individuals who’ve directly worked with the accountant. Thorough reference checks not just help you find a qualified accountant but also establish a foundation of trust and transparency for your future working relationship. Ensure Proficiency With Accounting Software When selecting an accountant for your new business, it’s vital to guarantee they’re proficient with accounting software that fits your needs. An accountant skilled in the right tools can streamline your financial management and improve efficiency. Here are some key points to keep in mind: Confirm their proficiency with popular platforms like QuickBooks, used by over 3.4 million businesses. Make sure they can seamlessly integrate with your existing accounting systems to avoid complications. Ask about their experience with cloud-based tools, which allow for real-time financial monitoring and collaboration. Inquire if they stay updated on new accounting technologies, as 70% of small businesses believe technology improves financial management. Evaluating an accountant’s adaptability to various software platforms is important since 80% of accountants report that the right technology boosts their efficiency and accuracy. Investing time in this area will pay off in the long run. Assess Communication Style and Personal Compatibility When you’re choosing an accountant for your new business, evaluating their communication style and personal compatibility is key. Pay close attention during initial meetings to see how well they listen and address your concerns, as this can reveal their approachability. Furthermore, consider their availability for ongoing consultations and how they explain complex financial concepts, ensuring you’re comfortable discussing sensitive issues as your relationship develops. Evaluate Initial Meetings How can you determine if an accountant is the right fit for your new business during initial meetings? Start by evaluating their communication style; they should explain complex financial concepts in a way that makes sense to you. Next, assess personal compatibility; you need to feel comfortable discussing sensitive financial matters. Pay attention to their responsiveness and availability, as this indicates the level of support you can expect. Consider these key points: Inquire about their approach to client relationships. Observe if they prioritize comprehension of your unique business needs. Verify they’re approachable and willing to provide ongoing advice. Gauge their enthusiasm for building a long-term partnership. These factors will help you make an informed decision. Determine Availability for Consultations Finding the right accountant goes beyond evaluating their skills; it also involves comprehending their availability for consultations and communication style. First, assess their availability to guarantee they can meet your business needs and provide timely support. During initial meetings, pay attention to how they communicate; their style should align with your preferences for effective collaboration. Responsiveness to inquiries is vital; an accountant who quickly addresses questions demonstrates commitment to client service. Furthermore, discuss your preferred communication methods—whether it’s email, phone calls, or in-person meetings—to make certain they can accommodate your style and frequency. Finally, personal compatibility matters; choose an accountant you feel comfortable with, as this promotes a trusting and productive working relationship. Assess Long-term Relationship Dynamics What should you consider when evaluating long-term relationship dynamics with an accountant? Start by evaluating personal compatibility, as this nurtures open communication and collaboration crucial for your business growth. During initial meetings, assess their communication style and confirm it aligns with your preferences. Consider the following factors: Approachability and availability for consultations, which impacts timely insights. Trust and transparency, fundamental for maneuvering complex financial scenarios. Comprehension of your business goals and challenges, indicating their commitment to your success. Responsiveness in discussions, which affects ongoing advice quality. These elements will help you determine if the accountant is a good fit for a lasting partnership that supports your business’s evolving needs. Plan for Future Growth and Changes in Your Business As your business evolves, planning for future growth and changes becomes crucial, especially in relation to selecting an accountant. You need an accountant who can scale their services as your business grows, ensuring they can handle increased complexity in financial management. Discuss your long-term goals with potential accountants to gauge their comprehension of how to support your financial strategies. Consider the following aspects when evaluating accountants: Key Aspect Considerations Experience with Scaling Familiarity with businesses adapting to sizes Approach to Change Guidance on mergers and acquisitions Financial Planning Proactive strategies for future needs Long-term Goals Alignment with your business objectives Frequently Asked Questions How Can I Determine if an Accountant Is Trustworthy? To determine if an accountant is trustworthy, start by checking their credentials, such as certifications and licenses. Look for reviews or testimonials from previous clients, as these can provide insight into their reliability. It’s prudent to interview the accountant directly; ask about their experience and approach to client service. Furthermore, verify they follow ethical guidelines and maintain transparency regarding fees and services to establish a solid foundation of trust. What Red Flags Should I Watch for During Interviews? During interviews, watch for red flags like unclear communication, reluctance to provide references, or lack of relevant experience. If an accountant seems overly focused on fees rather than your needs, that’s a concern. Be cautious if they avoid discussing their qualifications or if you sense disorganization in their approach. Trust your instincts; if something feels off, it probably is. Clear, transparent dialogue is essential for a successful working relationship. How Often Should I Meet With My Accountant? You should meet with your accountant at least once a quarter to review your financial health, discuss tax strategies, and address any concerns. Monthly meetings can be beneficial, especially during busy seasons or if your business is growing swiftly. These regular check-ins guarantee you stay on track with your financial goals, allow for timely adjustments, and help you make informed decisions based on accurate data. Consistent communication nurtures a strong partnership. Can an Accountant Help With Tax Planning Strategies? Yes, an accountant can definitely help with tax planning strategies. They analyze your financial situation, identify potential deductions, and recommend tax-efficient practices customized to your business. By staying updated on tax laws, they guarantee you comply as they reduce your tax liability. Furthermore, they can project future tax obligations, guiding you in making informed financial decisions. Collaborating with an accountant improves your ability to navigate complex tax regulations effectively and optimize your overall tax strategy. What Happens if I Don’t Like My Accountant After Hiring? If you don’t like your accountant after hiring, it’s important to address the issue without delay. You can communicate your concerns directly and see if adjustments can be made. If that doesn’t work, you have the option to terminate the relationship. Make sure you review your contract for any termination clauses, and consider finding a replacement who better fits your needs. Maintaining a good working relationship is crucial for effective financial management. Conclusion Finding the right accountant for your new business is a critical step toward achieving financial stability. By evaluating your specific needs, seeking referrals, and reviewing qualifications, you can identify a professional who aligns with your goals. Comprehending their expertise, communication style, and ability to adapt as your business grows will guarantee a successful partnership. Taking the time to make an informed choice now can save you time and resources in the future, in the end contributing to your business’s success. Image via Google Gemini and ArtSmart This article, "10 Essential Tips for Finding the Right Accountant for Your New Business" was first published on Small Business Trends View the full article
-
A Sample Chart of Accounts serves as a fundamental framework for organizing an organization’s financial information. It categorizes accounts into assets, liabilities, equity, revenue, and expenses, each with a unique identifier for tracking. This structured approach not just aids in compliance and transparency but additionally simplifies bookkeeping. Comprehending how to effectively implement this chart can greatly impact your financial management practices. Let’s explore the different categories and best practices for using a Sample Chart of Accounts effectively. Key Takeaways A Sample Chart of Accounts organizes financial information into categories like assets, liabilities, equity, revenue, and expenses for easy tracking. It serves as a foundational tool for financial management, ensuring transparency and compliance, especially for nonprofits. Accounts are assigned unique identifiers, typically using a coding system for efficient organization and retrieval. The chart of accounts aids in preparing financial statements, streamlining bookkeeping processes, and supporting strategic planning. Complexity varies by organization size, with smaller entities using around 100 accounts and larger ones potentially requiring thousands. Definition of a Sample Chart of Accounts A sample chart of accounts serves as a foundational tool for organizing a business’s financial information. It provides a structured template that categorizes financial accounts into assets, liabilities, equity, revenue, and expenses. Each account is assigned a unique identifier, allowing for easy identification and tracking. For example, in accounting for nonprofit membership organizations, a chart of accounts nonprofit example might include specific accounts for membership dues and grants. Typically, a well-designed sample chart of accounts includes detailed descriptions of each account, enhancing clarity in financial transactions. The complexity of these charts can vary, with smaller organizations using around 100 accounts, whereas larger entities may require thousands, customized to their specific financial reporting needs. Purpose and Importance Clarity in financial management hinges on a well-structured sample chart of accounts, which plays a crucial role in a business’s financial organization. For instance, when accounting for nonprofit membership and association organizations, a nonprofit accounting chart of accounts helps categorize funds effectively, ensuring transparency and compliance with regulations. This structured framework allows you to track financial activities systematically, enhancing your ability to prepare critical financial statements like balance sheets and income statements. Furthermore, using a chart of accounts for service businesses streamlines bookkeeping processes, reduces errors, and adapts easily to your specific needs. In the end, a sample chart of accounts provides the clarity and consistency necessary for accurate financial reporting and informed decision-making in any organization. Structure of a Sample Chart of Accounts When structuring a sample chart of accounts, it’s essential to organize it into two primary sections: Balance Sheet Accounts and Income Statement Accounts. Each account is assigned a unique identifier, typically using a coding system where the first digit denotes the account type. For instance, ‘1’ indicates Assets, whereas ‘2’ indicates Liabilities. You might have current assets like cash and accounts receivable, alongside current liabilities such as accounts payable. Here’s a simple qbo chart of accounts template: Account Type Example Accounts Assets Cash, Accounts Receivable Liabilities Accounts Payable Equity Retained Earnings Revenue Sales Revenue Expenses Salaries, Rent This structure allows for future growth and clarity in financial tracking. Categories of Accounts Now, let’s explore the different categories of accounts that make up a sample chart of accounts. You’ll find that asset accounts, like cash and inventory, represent resources owned by your business, whereas liability accounts, such as loans payable, indicate what you owe. Finally, equity accounts reflect the owner’s stake in the business, encompassing items like retained earnings and common stock, providing a clear picture of your financial position. Asset Accounts Overview Asset accounts play a crucial role in representing the resources owned by a company that hold future economic value. These accounts include cash, accounts receivable, inventory, and property and equipment. You’ll find that asset accounts are divided into current and non-current categories. Current assets are those expected to be converted into cash or used up within one year, like cash on hand and accounts receivable. Conversely, non-current assets, or long-term assets, encompass property, plant, and equipment, which provide benefits over several accounting periods. Typically, asset accounts start with the number ‘1’ in the chart of accounts, making them easy to identify. The balance sheet displays these accounts at cost or lower, ensuring compliance with accounting standards. Liability Accounts Explained Liability accounts reflect the financial obligations a company has to external parties, representing amounts owed that can greatly impact its overall financial health. These accounts are typically categorized into current and long-term liabilities based on their due dates. Current liabilities, due within one year, include accounts payable, accrued expenses, and short-term loans, reflecting immediate financial obligations. Long-term liabilities, such as notes payable and bonds payable, extend beyond one year and are often used to finance significant investments. Each liability account usually contains “payable” in its name, indicating amounts owed, and is recorded with a credit balance. Accurately tracking these accounts is essential for maintaining financial health and ensuring compliance with reporting standards, as they directly affect cash flow and solvency ratios. Equity Accounts Breakdown Comprehending equity accounts is vital for grasping a company’s financial structure since they represent the ownership interest of shareholders after all liabilities have been settled. Common equity accounts include common stock, which represents ownership shares, and preferred stock, which offers dividends before common stockholders. Additional paid-in capital reflects funds received beyond the par value of shares. Retained earnings showcase cumulative net income minus any dividends declared, indicating profits reinvested in the business. Treasury stock, a contra equity account, represents shares the company has repurchased, thereby reducing total equity on the balance sheet. Comprehending these categories is significant, as they provide insight into a company’s financial health and capital structure, often detailed in the statement of stockholders’ equity. Asset Accounts Asset accounts are essential for comprehending the resources your company owns, which contribute to its financial stability and future growth. You’ll commonly encounter types like cash, accounts receivable, and inventory, all of which play a significant role in evaluating liquidity and overall health. Types of Asset Accounts In the domain of accounting, comprehension of the various types of asset accounts is essential for managing a business’s financial health. Asset accounts represent resources owned by your business that possess future economic value. They’re measurable in monetary terms, including cash, accounts receivable, and inventory. You’ll encounter two main categories: current and non-current assets. Current asset accounts, like cash, accounts receivable, inventory, and prepaid expenses, are expected to be converted to cash or used up within one year. Non-current assets, often termed long-term assets, encompass property, equipment, and investments that will provide value over more than one year. Each asset account gets a unique identifier in your chart of accounts for efficient tracking and reporting on the balance sheet. Importance of Asset Tracking Effective management of your asset accounts is crucial for maintaining a healthy financial position within your business. Asset accounts, including cash, accounts receivable, inventory, and fixed assets like property and equipment, represent resources that provide future economic benefits. Tracking these assets accurately is vital for managing liquidity and making informed investment decisions, which ultimately improves cash flow management. In addition, proper asset tracking guarantees compliance with accounting standards, impacting financial ratios that influence investor and lender perceptions of your company’s stability. Regular reconciliation of these accounts helps identify discrepancies, maintaining the integrity of your financial records. This practice not only facilitates strategic planning but additionally supports informed decision-making regarding your business’s future growth and sustainability. Liability Accounts Liability accounts serve as a crucial component of a company’s financial structure, representing the obligations owed to external parties. These accounts are typically categorized into current and long-term liabilities. It’s important to monitor them regularly to maintain financial health. Here’s a breakdown of common liability accounts: Accounts Payable – Money owed to suppliers for goods and services. Short-Term Loans – Loans that must be repaid within one year. Accrued Expenses – Expenses incurred but not yet paid, like wages or utilities. Long-Term Liabilities – Obligations extending beyond one year, such as mortgages and bonds payable. Each liability account usually has a unique account number starting with ‘2’, making identification straightforward and effective for financial management. Equity Accounts Equity accounts are essential as they represent your ownership interest in a company, encompassing types like common stock, preferred stock, and retained earnings. Common stock gives you voting rights and a claim on assets, whereas preferred stock offers fixed dividends and priority during liquidation. Retained earnings, in contrast, reflect the profits your company keeps for reinvestment after paying out dividends, highlighting its growth strategy. Common Equity Account Types When you’re looking at common equity account types, you’ll find they play a crucial role in representing ownership and financial health within a corporation. Here are some key account types you should know: Common Stock: This represents ownership in the corporation and often carries voting rights for shareholders. Retained Earnings: This account accumulates net income retained in the business after dividends are declared, reflecting the company’s reinvestment strategy. Additional Paid-In Capital: This shows the amount received from shareholders above the stock’s par value, indicating confidence in the company’s growth. Treasury Stock: This accounts for shares repurchased by the company, reducing total equity and signaling a commitment to shareholder value. Understanding these types is crucial for evaluating a company’s financial status. Importance of Equity Accounts Grasping the significance of equity accounts is vital for anyone analyzing a company’s financial standing. Equity accounts represent the ownership interest in a business, including common stock, preferred stock, and retained earnings. They reflect the company’s net worth after liabilities are deducted from assets. For example, retained earnings show cumulative net income retained for reinvestment, signaling growth potential. Common stock accounts indicate the total value of issued shares, providing insights into capital structure and investor confidence. Preferred stock accounts attract investment by offering preferential treatment in dividends and asset distribution. Revenue Accounts Revenue accounts play a crucial role in a business’s financial reporting, as they categorize and track various sources of income, such as sales revenue, service revenue, and interest revenue. These accounts help you maintain clear records of your income streams, facilitating better financial analysis. Here are some common types of revenue accounts you might include: Sales Revenue: Income generated from selling goods. Service Revenue: Earnings from providing services to customers. Interest Revenue: Income earned from interest on investments or loans. Other Income: Revenue from sources like rental income or asset sales. Each revenue account is assigned a unique identifier, often starting with the digit ‘4’, ensuring accurate tracking and reporting aligned with your business activities. Regularly review these accounts to keep them relevant. Expense Accounts Expense accounts are vital for tracking the costs your business incurs during its operations, as they categorize various types of expenses that directly impact your financial performance. Common expense accounts include cost of goods sold, salaries and wages, rent, utilities, and marketing expenses. These accounts are fundamental for reflecting the ongoing costs you face within a specific reporting period. Each expense account typically has a unique number within the chart of accounts, often starting with a 5XXX series, which helps organize them distinctly from asset and revenue accounts. Operating expenses are debited to their respective accounts and routinely carry a normal debit balance. Furthermore, non-operating expenses, like interest or losses from asset sales, are likewise tracked but relate to peripheral activities outside your core operations. Best Practices for Implementing a Sample Chart of Accounts Implementing a sample chart of accounts requires careful planning and organization to accurately reflect your business’s financial activities. Here are some best practices to follow: Ensure consistency in account naming, numbering, and categorization to improve clarity and comprehension of financial data. Anticipate future needs by leaving gaps in account numbers, making it easier to add new accounts as your business grows. Regularly review and update the chart to maintain relevance and accuracy, consolidating outdated or redundant accounts when necessary. Conduct training sessions for staff on using the chart of accounts, ensuring effective implementation and adherence to accounting practices. Common Challenges in Using a Chart of Accounts Even though a well-structured chart of accounts can greatly boost your financial management, several common challenges can arise that may hinder its effectiveness. Challenge Impact Overcomplication Slows down data entry and analysis Lack of standardization Creates reconciliation and reporting gaps Duplicate categories Leads to inconsistencies in financial comparisons Misalignment with reports Causes compliance issues with accounting standards Failure to update Results in outdated practices Navigating these challenges requires you to regularly review your chart of accounts. By simplifying its structure, adopting standardized naming conventions, and ensuring it aligns with your financial reports, you can improve its utility and maintain accurate financial insights as your business evolves. Examples of Sample Charts of Accounts When you’re setting up a chart of accounts, comprehension the structure and categories involved is crucial for effective financial management. A sample chart typically includes: Assets: Accounts starting with ‘1’, such as 1000 for cash and 1100 for accounts receivable. Liabilities: Accounts beginning with ‘2’, like 2000 for accounts payable and 2100 for accrued expenses. Revenue: Often starting with ‘4’, for example, 4000 for sales revenue. Expenses: These accounts begin with ‘5’, such as 5000 for cost of goods sold, and can include sub-accounts like 5100 for advertising and 5200 for electricity. Each account type has a unique numerical identifier, facilitating easy reference and efficient financial tracking customized to your business needs. Frequently Asked Questions What Is a Chart of Accounts With an Example? A chart of accounts (CoA) is a structured listing of all financial accounts a business uses, categorized for easy reference. For example, you might see asset accounts like Cash (101), Accounts Receivable (102), and liabilities like Accounts Payable (201). Revenue accounts could include Sales Revenue (401), whereas expenses might feature Rent Expense (501). Each account has a unique identifier, simplifying tracking and enhancing financial reporting, which aids in decision-making. What Are the 5 Main Types in the Chart of Accounts? The five main types in a chart of accounts are Assets, Liabilities, Equity, Revenue, and Expenses. Asset accounts include items like cash and inventory, representing resources you own. Liabilities cover your obligations, such as accounts payable. Equity reflects your ownership interest, including retained earnings. Revenue accounts track your income from sales, whereas Expense accounts capture costs associated with generating that income. Each type is essential for accurate financial reporting and analysis. What Should Be in My Chart of Accounts? Your chart of accounts should include key categories like Assets, Liabilities, Equity, Revenue, and Expenses. Under Assets, list accounts like cash and accounts receivable. For Liabilities, include accounts payable and notes payable. Revenue should cover sales and service income, whereas Expenses may include salaries, rent, and utilities. Each account needs a unique identifier for easy tracking. Regularly review and update your chart to guarantee it meets your business needs and accounting standards. How to Write a Chart of Accounts? To write a chart of accounts, start by defining your major categories: assets, liabilities, equity, revenue, and expenses. Assign unique account numbers, using a consistent coding system; for instance, use ‘1’ for assets. List accounts in the order they’ll appear in financial statements, ensuring each has clear descriptions. Leave gaps in numbering for future additions, and regularly review the chart for accuracy to align with accounting standards like GAAP or IFRS. Conclusion In summary, a sample chart of accounts is crucial for effective financial management, offering a clear structure for organizing financial data. By categorizing accounts into assets, liabilities, equity, revenue, and expenses, it aids in compliance and transparency. Implementing best practices can help overcome common challenges, ensuring accurate financial reporting. Overall, utilizing a well-structured chart of accounts enables informed decision-making, streamlining bookkeeping processes and enhancing the financial health of any organization. Image via Google Gemini This article, "What Is a Sample Chart of Accounts?" was first published on Small Business Trends View the full article
-
A Sample Chart of Accounts serves as a fundamental framework for organizing an organization’s financial information. It categorizes accounts into assets, liabilities, equity, revenue, and expenses, each with a unique identifier for tracking. This structured approach not just aids in compliance and transparency but additionally simplifies bookkeeping. Comprehending how to effectively implement this chart can greatly impact your financial management practices. Let’s explore the different categories and best practices for using a Sample Chart of Accounts effectively. Key Takeaways A Sample Chart of Accounts organizes financial information into categories like assets, liabilities, equity, revenue, and expenses for easy tracking. It serves as a foundational tool for financial management, ensuring transparency and compliance, especially for nonprofits. Accounts are assigned unique identifiers, typically using a coding system for efficient organization and retrieval. The chart of accounts aids in preparing financial statements, streamlining bookkeeping processes, and supporting strategic planning. Complexity varies by organization size, with smaller entities using around 100 accounts and larger ones potentially requiring thousands. Definition of a Sample Chart of Accounts A sample chart of accounts serves as a foundational tool for organizing a business’s financial information. It provides a structured template that categorizes financial accounts into assets, liabilities, equity, revenue, and expenses. Each account is assigned a unique identifier, allowing for easy identification and tracking. For example, in accounting for nonprofit membership organizations, a chart of accounts nonprofit example might include specific accounts for membership dues and grants. Typically, a well-designed sample chart of accounts includes detailed descriptions of each account, enhancing clarity in financial transactions. The complexity of these charts can vary, with smaller organizations using around 100 accounts, whereas larger entities may require thousands, customized to their specific financial reporting needs. Purpose and Importance Clarity in financial management hinges on a well-structured sample chart of accounts, which plays a crucial role in a business’s financial organization. For instance, when accounting for nonprofit membership and association organizations, a nonprofit accounting chart of accounts helps categorize funds effectively, ensuring transparency and compliance with regulations. This structured framework allows you to track financial activities systematically, enhancing your ability to prepare critical financial statements like balance sheets and income statements. Furthermore, using a chart of accounts for service businesses streamlines bookkeeping processes, reduces errors, and adapts easily to your specific needs. In the end, a sample chart of accounts provides the clarity and consistency necessary for accurate financial reporting and informed decision-making in any organization. Structure of a Sample Chart of Accounts When structuring a sample chart of accounts, it’s essential to organize it into two primary sections: Balance Sheet Accounts and Income Statement Accounts. Each account is assigned a unique identifier, typically using a coding system where the first digit denotes the account type. For instance, ‘1’ indicates Assets, whereas ‘2’ indicates Liabilities. You might have current assets like cash and accounts receivable, alongside current liabilities such as accounts payable. Here’s a simple qbo chart of accounts template: Account Type Example Accounts Assets Cash, Accounts Receivable Liabilities Accounts Payable Equity Retained Earnings Revenue Sales Revenue Expenses Salaries, Rent This structure allows for future growth and clarity in financial tracking. Categories of Accounts Now, let’s explore the different categories of accounts that make up a sample chart of accounts. You’ll find that asset accounts, like cash and inventory, represent resources owned by your business, whereas liability accounts, such as loans payable, indicate what you owe. Finally, equity accounts reflect the owner’s stake in the business, encompassing items like retained earnings and common stock, providing a clear picture of your financial position. Asset Accounts Overview Asset accounts play a crucial role in representing the resources owned by a company that hold future economic value. These accounts include cash, accounts receivable, inventory, and property and equipment. You’ll find that asset accounts are divided into current and non-current categories. Current assets are those expected to be converted into cash or used up within one year, like cash on hand and accounts receivable. Conversely, non-current assets, or long-term assets, encompass property, plant, and equipment, which provide benefits over several accounting periods. Typically, asset accounts start with the number ‘1’ in the chart of accounts, making them easy to identify. The balance sheet displays these accounts at cost or lower, ensuring compliance with accounting standards. Liability Accounts Explained Liability accounts reflect the financial obligations a company has to external parties, representing amounts owed that can greatly impact its overall financial health. These accounts are typically categorized into current and long-term liabilities based on their due dates. Current liabilities, due within one year, include accounts payable, accrued expenses, and short-term loans, reflecting immediate financial obligations. Long-term liabilities, such as notes payable and bonds payable, extend beyond one year and are often used to finance significant investments. Each liability account usually contains “payable” in its name, indicating amounts owed, and is recorded with a credit balance. Accurately tracking these accounts is essential for maintaining financial health and ensuring compliance with reporting standards, as they directly affect cash flow and solvency ratios. Equity Accounts Breakdown Comprehending equity accounts is vital for grasping a company’s financial structure since they represent the ownership interest of shareholders after all liabilities have been settled. Common equity accounts include common stock, which represents ownership shares, and preferred stock, which offers dividends before common stockholders. Additional paid-in capital reflects funds received beyond the par value of shares. Retained earnings showcase cumulative net income minus any dividends declared, indicating profits reinvested in the business. Treasury stock, a contra equity account, represents shares the company has repurchased, thereby reducing total equity on the balance sheet. Comprehending these categories is significant, as they provide insight into a company’s financial health and capital structure, often detailed in the statement of stockholders’ equity. Asset Accounts Asset accounts are essential for comprehending the resources your company owns, which contribute to its financial stability and future growth. You’ll commonly encounter types like cash, accounts receivable, and inventory, all of which play a significant role in evaluating liquidity and overall health. Types of Asset Accounts In the domain of accounting, comprehension of the various types of asset accounts is essential for managing a business’s financial health. Asset accounts represent resources owned by your business that possess future economic value. They’re measurable in monetary terms, including cash, accounts receivable, and inventory. You’ll encounter two main categories: current and non-current assets. Current asset accounts, like cash, accounts receivable, inventory, and prepaid expenses, are expected to be converted to cash or used up within one year. Non-current assets, often termed long-term assets, encompass property, equipment, and investments that will provide value over more than one year. Each asset account gets a unique identifier in your chart of accounts for efficient tracking and reporting on the balance sheet. Importance of Asset Tracking Effective management of your asset accounts is crucial for maintaining a healthy financial position within your business. Asset accounts, including cash, accounts receivable, inventory, and fixed assets like property and equipment, represent resources that provide future economic benefits. Tracking these assets accurately is vital for managing liquidity and making informed investment decisions, which ultimately improves cash flow management. In addition, proper asset tracking guarantees compliance with accounting standards, impacting financial ratios that influence investor and lender perceptions of your company’s stability. Regular reconciliation of these accounts helps identify discrepancies, maintaining the integrity of your financial records. This practice not only facilitates strategic planning but additionally supports informed decision-making regarding your business’s future growth and sustainability. Liability Accounts Liability accounts serve as a crucial component of a company’s financial structure, representing the obligations owed to external parties. These accounts are typically categorized into current and long-term liabilities. It’s important to monitor them regularly to maintain financial health. Here’s a breakdown of common liability accounts: Accounts Payable – Money owed to suppliers for goods and services. Short-Term Loans – Loans that must be repaid within one year. Accrued Expenses – Expenses incurred but not yet paid, like wages or utilities. Long-Term Liabilities – Obligations extending beyond one year, such as mortgages and bonds payable. Each liability account usually has a unique account number starting with ‘2’, making identification straightforward and effective for financial management. Equity Accounts Equity accounts are essential as they represent your ownership interest in a company, encompassing types like common stock, preferred stock, and retained earnings. Common stock gives you voting rights and a claim on assets, whereas preferred stock offers fixed dividends and priority during liquidation. Retained earnings, in contrast, reflect the profits your company keeps for reinvestment after paying out dividends, highlighting its growth strategy. Common Equity Account Types When you’re looking at common equity account types, you’ll find they play a crucial role in representing ownership and financial health within a corporation. Here are some key account types you should know: Common Stock: This represents ownership in the corporation and often carries voting rights for shareholders. Retained Earnings: This account accumulates net income retained in the business after dividends are declared, reflecting the company’s reinvestment strategy. Additional Paid-In Capital: This shows the amount received from shareholders above the stock’s par value, indicating confidence in the company’s growth. Treasury Stock: This accounts for shares repurchased by the company, reducing total equity and signaling a commitment to shareholder value. Understanding these types is crucial for evaluating a company’s financial status. Importance of Equity Accounts Grasping the significance of equity accounts is vital for anyone analyzing a company’s financial standing. Equity accounts represent the ownership interest in a business, including common stock, preferred stock, and retained earnings. They reflect the company’s net worth after liabilities are deducted from assets. For example, retained earnings show cumulative net income retained for reinvestment, signaling growth potential. Common stock accounts indicate the total value of issued shares, providing insights into capital structure and investor confidence. Preferred stock accounts attract investment by offering preferential treatment in dividends and asset distribution. Revenue Accounts Revenue accounts play a crucial role in a business’s financial reporting, as they categorize and track various sources of income, such as sales revenue, service revenue, and interest revenue. These accounts help you maintain clear records of your income streams, facilitating better financial analysis. Here are some common types of revenue accounts you might include: Sales Revenue: Income generated from selling goods. Service Revenue: Earnings from providing services to customers. Interest Revenue: Income earned from interest on investments or loans. Other Income: Revenue from sources like rental income or asset sales. Each revenue account is assigned a unique identifier, often starting with the digit ‘4’, ensuring accurate tracking and reporting aligned with your business activities. Regularly review these accounts to keep them relevant. Expense Accounts Expense accounts are vital for tracking the costs your business incurs during its operations, as they categorize various types of expenses that directly impact your financial performance. Common expense accounts include cost of goods sold, salaries and wages, rent, utilities, and marketing expenses. These accounts are fundamental for reflecting the ongoing costs you face within a specific reporting period. Each expense account typically has a unique number within the chart of accounts, often starting with a 5XXX series, which helps organize them distinctly from asset and revenue accounts. Operating expenses are debited to their respective accounts and routinely carry a normal debit balance. Furthermore, non-operating expenses, like interest or losses from asset sales, are likewise tracked but relate to peripheral activities outside your core operations. Best Practices for Implementing a Sample Chart of Accounts Implementing a sample chart of accounts requires careful planning and organization to accurately reflect your business’s financial activities. Here are some best practices to follow: Ensure consistency in account naming, numbering, and categorization to improve clarity and comprehension of financial data. Anticipate future needs by leaving gaps in account numbers, making it easier to add new accounts as your business grows. Regularly review and update the chart to maintain relevance and accuracy, consolidating outdated or redundant accounts when necessary. Conduct training sessions for staff on using the chart of accounts, ensuring effective implementation and adherence to accounting practices. Common Challenges in Using a Chart of Accounts Even though a well-structured chart of accounts can greatly boost your financial management, several common challenges can arise that may hinder its effectiveness. Challenge Impact Overcomplication Slows down data entry and analysis Lack of standardization Creates reconciliation and reporting gaps Duplicate categories Leads to inconsistencies in financial comparisons Misalignment with reports Causes compliance issues with accounting standards Failure to update Results in outdated practices Navigating these challenges requires you to regularly review your chart of accounts. By simplifying its structure, adopting standardized naming conventions, and ensuring it aligns with your financial reports, you can improve its utility and maintain accurate financial insights as your business evolves. Examples of Sample Charts of Accounts When you’re setting up a chart of accounts, comprehension the structure and categories involved is crucial for effective financial management. A sample chart typically includes: Assets: Accounts starting with ‘1’, such as 1000 for cash and 1100 for accounts receivable. Liabilities: Accounts beginning with ‘2’, like 2000 for accounts payable and 2100 for accrued expenses. Revenue: Often starting with ‘4’, for example, 4000 for sales revenue. Expenses: These accounts begin with ‘5’, such as 5000 for cost of goods sold, and can include sub-accounts like 5100 for advertising and 5200 for electricity. Each account type has a unique numerical identifier, facilitating easy reference and efficient financial tracking customized to your business needs. Frequently Asked Questions What Is a Chart of Accounts With an Example? A chart of accounts (CoA) is a structured listing of all financial accounts a business uses, categorized for easy reference. For example, you might see asset accounts like Cash (101), Accounts Receivable (102), and liabilities like Accounts Payable (201). Revenue accounts could include Sales Revenue (401), whereas expenses might feature Rent Expense (501). Each account has a unique identifier, simplifying tracking and enhancing financial reporting, which aids in decision-making. What Are the 5 Main Types in the Chart of Accounts? The five main types in a chart of accounts are Assets, Liabilities, Equity, Revenue, and Expenses. Asset accounts include items like cash and inventory, representing resources you own. Liabilities cover your obligations, such as accounts payable. Equity reflects your ownership interest, including retained earnings. Revenue accounts track your income from sales, whereas Expense accounts capture costs associated with generating that income. Each type is essential for accurate financial reporting and analysis. What Should Be in My Chart of Accounts? Your chart of accounts should include key categories like Assets, Liabilities, Equity, Revenue, and Expenses. Under Assets, list accounts like cash and accounts receivable. For Liabilities, include accounts payable and notes payable. Revenue should cover sales and service income, whereas Expenses may include salaries, rent, and utilities. Each account needs a unique identifier for easy tracking. Regularly review and update your chart to guarantee it meets your business needs and accounting standards. How to Write a Chart of Accounts? To write a chart of accounts, start by defining your major categories: assets, liabilities, equity, revenue, and expenses. Assign unique account numbers, using a consistent coding system; for instance, use ‘1’ for assets. List accounts in the order they’ll appear in financial statements, ensuring each has clear descriptions. Leave gaps in numbering for future additions, and regularly review the chart for accuracy to align with accounting standards like GAAP or IFRS. Conclusion In summary, a sample chart of accounts is crucial for effective financial management, offering a clear structure for organizing financial data. By categorizing accounts into assets, liabilities, equity, revenue, and expenses, it aids in compliance and transparency. Implementing best practices can help overcome common challenges, ensuring accurate financial reporting. Overall, utilizing a well-structured chart of accounts enables informed decision-making, streamlining bookkeeping processes and enhancing the financial health of any organization. Image via Google Gemini This article, "What Is a Sample Chart of Accounts?" was first published on Small Business Trends View the full article
-
Trains are set to resume rolling on the Long Island Rail Road on Tuesday after a deal was reached to end a strike that had shut down the busiest commuter rail system in the country. But commuters in the eastern suburbs of New York City still had to muddle through another tough morning rush hour, as trains weren’t set to be running in time for the commute into work after the agreement was reached late Monday. Limited train service was set to resume around noon, with full service expected to be back in time for the evening rush. The LIRR still urged riders to work from home again Tuesday if possible. Shuttle buses were being offered from a handful of locations on Long Island to subway stations in New York City. Five labor unions representing about half the train system’s workforce went on strike at 12:01 a.m. Saturday, halting service for roughly 250,000 commuters who use the rail system that connects New York City to its eastern suburbs every weekday. Hallie Kessler was among the weary Long Island commuters who welcomed the strike’s end. With the trains out of service, the 24-year old speech therapist commuted three hours home from her job at a public school in the New York City borough of Queens on Monday. “Obviously I wish trains would be running when peak hours start so I could avoid the long morning commute, but happy to not deal with it in the afternoon when I’m leaving work,” Kessler said. “Curious what the deal says about future fares, which has been a big concern, but we’ll see.” New York Gov. Kathy Hochul and railroad officials have said they’re not at liberty to disclose details of the new contract terms until they’re voted on and approved by union members. But the Democrat, who is up for reelection, stressed the deal won’t increase fares or taxes and will give unionized workers the fair wages they deserve. The first impacts of the walkout were felt over the weekend, as baseball fans had to find other ways to get to Citi Field in Queens to see the New York Mets take on their crosstown rivals the New York Yankees. Hochul said the deal ensures basketball fans won’t meet the same fate as they travel to watch the New York Knicks continue their playoff run on Tuesday night at Madison Square Garden, which is located directly above the LIRR’s Penn Station hub in Manhattan. The unions — which represent locomotive engineers, machinists, signalmen and others — and the Metropolitan Transportation Authority had been negotiating a new contract since 2023, but talks had stalled over salaries and healthcare. The unions have said raises were needed to help workers keep up with inflation and the rising cost of living in the New York City area. The MTA had said the union’s initial demands would lead to fare increases and set a difficult precedent for negotiations with other transit unions. The strike was the first walkout for the LIRR since a two-day strike in 1994. —Philip Marcelo, Associated Press View the full article