Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
If you’re starting out in video editing, choosing the right software can make all the difference. Various programs, like CyberLink PowerDirector and Filmora, provide user-friendly interfaces that simplify the editing process. Options such as ACDSee Luxea and Clipchamp cater to different needs and skill levels, ensuring accessibility for all beginners. Comprehending these tools can help you create engaging content with ease. Explore the standout features of each option to find the best fit for your projects. Key Takeaways User-Friendly Interface: Software like Filmora and WeVideo offer intuitive drag-and-drop functionality, making it easy for beginners to navigate and edit videos. Built-in Templates and Effects: Platforms such as Adobe Premiere Elements and Clipchamp provide pre-made templates and effects, simplifying the content creation process for new users. Accessibility Across Devices: Many editors, including CyberLink PowerDirector and WeVideo, are compatible with various devices, allowing edits from anywhere with an internet connection. Free Versions Available: ACDSee Luxea and Movavi Video Editor offer free trials or basic versions, enabling beginners to start editing without upfront costs. Comprehensive Learning Resources: Software like Movavi provides tutorials and guides, helping newcomers learn the ropes of video editing efficiently. CyberLink PowerDirector CyberLink PowerDirector is a robust video editing software that caters to both beginners and experienced editors. In many editing software reviews, it stands out as one of the easiest to use video editors available. With a sleek, user-friendly interface, you can navigate its features with ease. Available for a monthly subscription of $19.99 or an annual plan for $54.99, it’s a cheap film editing software option considering the extensive tools it offers. You’ll find AI effects, motion tracking, and screen recording capabilities, perfect for creating professional-quality videos. Even though it has a slight learning curve, its cross-device compatibility across Windows, Mac, iOS, and Android allows for flexible editing, making it an excellent choice for anyone looking to improve their video projects. ACDSee Luxea ACDSee Luxea is a great option for beginners, especially since it offers a free version packed with crucial features, allowing you to start video editing without spending a dime. You can easily capture screen recordings, perfect for creating tutorials or gaming videos. Nonetheless, keep in mind that the free version limits video exports to 1080p, so if you need higher resolutions, you might consider upgrading to the Pro version. Free Version Features If you’re looking for a solid entry point into video editing, ACDSee Luxea‘s free version offers an impressive array of features. With a fully featured toolset, you can explore various editing capabilities without any initial cost. The free version supports video exports capped at 1080p resolution, which is suitable for standard viewing but limits high-definition output. Furthermore, you can use the built-in screen recording feature, making it versatile for creating tutorials or presentations. On the other hand, keep in mind that exported videos will include watermarks, which might be a drawback if you’re aiming for professional-quality content. Finally, ACDSee Luxea is compatible exclusively with Windows, so Mac users will need to ponder other software options for their video editing needs. Screen Recording Capability For those venturing into video editing, the built-in screen recording capabilities of ACDSee Luxea provide a valuable tool for improving your projects. This feature allows you to capture your screen activities seamlessly during editing, making it ideal for tutorials and presentations. You can select specific regions of your screen or opt for full-screen capture, giving you flexibility in your content creation. The software supports various resolutions, including full HD, ensuring high-quality outputs. Moreover, ACDSee Luxea enables real-time editing of your recorded footage, allowing for immediate improvements and adjustments. Its user-friendly interface makes it accessible for beginners looking to create instructional videos or share gaming content, providing a straightforward approach to screen recording. Adobe Premiere Elements Adobe Premiere Elements is a popular choice among beginners looking to plunge into video editing, offering a user-friendly experience at a competitive price. With a one-time purchase, you can utilize the software for three years, making it a cost-effective option compared to other Adobe products. Here are some key features that make it appealing: Free trial available for new users. Compatible across multiple platforms. Built-in templates for various content types. Smooth progression to advanced tools like Premiere Pro. Suitable for novices and hobbyists. While it lays a solid foundation for beginners, some may find its complexity slightly challenging compared to simpler alternatives. Additionally, it lacks certain advanced features available in Premiere Pro. Clipchamp Clipchamp stands out as a user-friendly video editing tool, perfect for beginners and social media marketers alike. With its intuitive drag-and-drop interface and a variety of pre-designed templates, you can quickly create engaging content for platforms like YouTube and Instagram. Whereas it offers solid basic editing capabilities, keep in mind that it may not meet the needs of those looking for advanced features or high-resolution support. User-Friendly Interface When you’re looking for a video editing tool that’s easy to navigate, Clipchamp stands out with its user-friendly browser-based interface. You don’t need to install any software, making it accessible from any device. The drag-and-drop functionality simplifies importing video clips, images, and audio files into your projects, so you can start editing right away. Key features include: Intuitive layout that improves navigation Built-in tools for adding text, changes, and effects Streamlined editing process for beginners Direct upload to popular social media platforms A variety of templates particularly for social media content With these features, Clipchamp makes video editing straightforward, allowing you to create engaging videos without any hassle. Social Media Templates Creating engaging social media content is made simpler with the variety of customizable video templates available through Clipchamp. You can easily create videos for platforms like Instagram, TikTok, and Facebook. The drag-and-drop interface lets you add your media to templates and modify text, images, and audio quickly, giving each project a personal touch. Clipchamp likewise provides built-in stock footage, images, and music, so you won’t need to search for extra resources. When you’re ready to share, exporting your project in different aspect ratios guarantees your videos look great on any channel. Furthermore, features like AI-powered speech-to-text auto-captioning and voice-overs make it easier to produce professional-quality content, even as a beginner. Filmora Filmora is a robust video editing software customized for beginners who want to explore the domain of video creation without overwhelming intricacies. Its user-friendly design simplifies navigation, making editing tasks manageable. Here are some key features you’ll appreciate: Intuitive interface with no hidden menus, ensuring easy access to tools. A wide selection of effects, shifts, and filters for creative improvement. Support for 4K video editing and various aspect ratios, accommodating diverse projects. “Easy Mode” allows simple drag-and-drop editing, perfect for novices. One-time payment option for a lifetime license, starting at $68.98, making it budget-friendly. With Filmora, you’ll find it easier to bring your video ideas to life without unnecessary complications. Apple Imovie Apple iMovie stands out as a popular choice among beginner video editors, especially for those who use Apple devices. This free software comes pre-installed on all Apple products, making it easily accessible for Mac users. With a user-friendly interface, you can quickly learn fundamental editing techniques such as cutting, trimming, and adding transitions. iMovie likewise includes advanced tools like green-screen effects and picture-in-picture options, enabling you to explore more creative projects. Furthermore, it supports 4K video editing, which means you can create high-quality videos perfect for professional presentations or social media. The seamless integration with other Apple applications, like iTunes and GarageBand, allows you to incorporate music and soundtracks effortlessly into your videos. WeVideo WeVideo is a cloud-based editing platform that simplifies video creation for beginners through its user-friendly interface. With its drag-and-drop functionality, you can easily customize templates and add over 50 transitions and animated effects to improve your projects. Furthermore, features like screen capture and green screen removal make it versatile for various content needs, catering to both casual creators and more serious producers. Cloud-Based Editing Platform In today’s digital environment, using a cloud-based video editing platform like WeVideo can greatly boost your video production process. This tool enables you to create and edit videos directly in your web browser without installing software. Here are some key features that elevate your editing experience: Customizable video templates for quick starts Over 50 shifts and animated effects for engaging visuals Screen recording capabilities to capture content easily Green screen removal for professional-looking edits Flexible subscription tiers to fit various budgets With WeVideo, you can collaborate on projects and access your work from any internet-connected device. This makes it an ideal choice for beginners looking to create educational or interactive videos. User-Friendly Interface Features A user-friendly interface is crucial for beginners traversing the domain of video editing, and WeVideo stands out in this area. Its drag-and-drop interface simplifies the process of arranging video clips, images, and audio, eliminating the need for technical skills. You can choose from customizable video templates, allowing you to produce professional-looking videos by just filling in your content. With access to over 1 million stock assets in the built-in media library, enhancing your videos with quality visuals and music is effortless. The intuitive editing tools, including changes, text overlays, and effects, are straightforward for first-time users. Plus, WeVideo’s cloud-based platform enables seamless collaboration and editing from any device, making your video projects convenient and accessible. OpenShot When you’re looking for a video editing software that’s both potent and accessible, OpenShot stands out as an excellent choice. This free, open-source software is compatible with Windows, Mac, and Linux, making it widely available. Its user-friendly interface features drag-and-drop functionality, simplifying the editing process for beginners. Here are some key features of OpenShot: Supports various video, audio, and image formats. Offers unlimited tracks for complex projects. Includes 3D animations and video effects. Regular updates improve functionality without extra costs. Intuitive design helps you learn quickly. OpenShot equips you with professional-quality tools as your skills grow, allowing you to create impressive videos with ease. Movavi Video Editor Movavi Video Editor presents an intuitive platform for newcomers venturing into video editing. Its user-friendly interface features simple drag-and-drop functionality, making it accessible for beginners without prior editing experience. You can effortlessly work with various video formats and resolutions, ensuring compatibility with different media types. Movavi enriches your editing experience with a library of filters, changes, and built-in music, allowing for creative improvements without needing external resources. Furthermore, it offers a one-time payment option for a lifetime license, making it budget-friendly. To support your learning, the software includes helpful tutorials and guides, ensuring a smooth shift as you explore its capabilities. With Movavi, you’ll find a strong yet straightforward tool for your video editing needs. Nero Video For those just starting out in video editing, Nero Video offers an affordable and user-friendly option priced at $49.99. This software is crafted with beginners in mind, featuring a simple interface and crucial editing tools to help you create engaging videos. Here are some key highlights of Nero Video: Supports basic editing tasks like cutting and trimming Offers various transitions to improve your video flow Includes effects to add flair without overwhelming complexity Provides a budget-friendly basic version for $39.95 Guarantees a straightforward learning curve for new users With Nero Video, you can easily navigate the realm of video editing, making it a solid choice for those looking to start their video creation expedition. Frequently Asked Questions What Do Most Youtubers Use to Edit Their Videos? Most YouTubers use a variety of video editing software depending on their needs and skill levels. Popular choices include Wondershare Filmora and CyberLink Director for their user-friendly interfaces, whereas Adobe Premiere Pro caters to advanced users seeking professional features. Apple users often prefer iMovie for its seamless integration with macOS. Furthermore, entry-level editors like Clipchamp are favored for social media, and many creators start with free options like HitFilm Express or Movavi Video Editor. What Is the Easiest Program to Make a Video? When you’re looking to make a video easily, consider programs like Apple iMovie or Filmora. iMovie offers a straightforward interface with drag-and-drop features, perfect for beginners. Filmora, in contrast, includes an “Easy Mode” for quick edits. If you prefer browser-based options, try Clipchamp, which provides templates and a user-friendly experience. Each of these programs simplifies video creation, allowing you to focus on your content rather than complex software. Which Video Editing Software Should I Learn? When deciding which video editing software to learn, consider your goals and experience level. If you want user-friendly options, CyberLink PowerDirector and Wondershare Filmora are excellent choices for beginners. For Mac users, Apple iMovie offers vital tools at no cost. If you’re planning to advance your skills, Adobe Premiere Elements serves as a solid foundation. Finally, Clipchamp is great for quick edits customized for social media, making it easy to start creating engaging content. Is Capcut the Easiest Video Editing Software? CapCut is often considered one of the easiest video editing software options available. Its user-friendly drag-and-drop interface lets you edit videos quickly, without needing extensive experience. You’ll find a variety of templates and effects, making it easier to create polished content. Furthermore, CapCut’s built-in tools for text, music, and changes streamline the editing process. It’s compatible with multiple devices, providing flexibility for your editing needs, whether you’re on mobile or desktop. Conclusion In conclusion, choosing the right video editor can greatly improve your editing experience as a beginner. Options like CyberLink PowerDirector and Filmora provide user-friendly interfaces, whereas ACDSee Luxea and Clipchamp offer accessible features for quick edits. OpenShot and Movavi cater to diverse formats, ensuring versatility. With tools like Adobe Premiere Elements and Nero Video, you’ll find crucial functions for professional-looking results. Exploring these options will help you find the perfect fit for your video editing needs. Image via Google Gemini This article, "10 Easiest Video Editors to Use for Beginners" was first published on Small Business Trends View the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. The AirPods Max finally got their anticipated upgrade—and no, I'm not talking about the 2024 refresh when they added a USB-C and called it a "new" version. These are the AirPods Max 2, with improvements that warrant putting that "2" after the name. Now, the new AirPods Max 2 are getting their first decent discount, currently $509.99 (originally $549.99), their lowest price yet after their recent release, according to price-tracking tools. Yes, they're still expensive, but these are Apple's latest flagship headphones and the best Bluetooth headphones an Apple user can buy. Wireless Over-Ear Headphones, Active Noise Cancellation, Adaptive Audio, Personalized Spatial Audio, Live Translation, Bluetooth Headphones for iPhone – Midnight Apple AirPods Max 2 $509.99 at Amazon $549.00 Save $39.01 Get Deal Get Deal $509.99 at Amazon $549.00 Save $39.01 Wireless Over-Ear Headphones, Active Noise Cancellation, Adaptive Audio, Personalized Spatial Audio, Live Translation, Bluetooth Headphones for iPhone – Blue Apple AirPods Max 2 $509.00 at Amazon $549.00 Save $40.00 Get Deal Get Deal $509.00 at Amazon $549.00 Save $40.00 Wireless Over-Ear Headphones, Active Noise Cancellation, Adaptive Audio, Personalized Spatial Audio, Live Translation, Bluetooth Headphones for iPhone – Orange Apple AirPods Max 2 $509.99 at Amazon $549.00 Save $39.01 Get Deal Get Deal $509.99 at Amazon $549.00 Save $39.01 Wireless Over-Ear Headphones, Active Noise Cancellation, Adaptive Audio, Personalized Spatial Audio, Live Translation, Bluetooth Headphones for iPhone – Purple Apple AirPods Max 2 $509.99 at Amazon $549.00 Save $39.01 Get Deal Get Deal $509.99 at Amazon $549.00 Save $39.01 Wireless Over-Ear Headphones, Active Noise Cancellation, Adaptive Audio, Personalized Spatial Audio, Live Translation, Bluetooth Headphones for iPhone – Starlight Apple AirPods Max 2 $509.99 at Amazon $549.00 Save $39.01 Get Deal Get Deal $509.99 at Amazon $549.00 Save $39.01 SEE 2 MORE The biggest upgrades on the AirPods Max 2 are the new "dynamic range" amplifier and Apple's H2 chip (no longer the H1). But there are many other upgrades that are also worth noting. The amplifier makes the audio cleaner and bass thumpier with virtually no distortion, as well as better instrument separation, which makes spatial audio a better experience for music or movies. The H2 chip improves many features, notably Apple's Voice Isolation feature, which uses the headphone's microphone to isolate your voice in noisy environments. Transparency mode, spatial audio, and ANC are all improved as well. One of the most exciting features is the addition of Live Translation, which is exactly as it sounds—you can hear real-time translation of what someone is saying in another language right through your headphones. You can also control your iPhone camera with buttons on the AirPods. The ANC is now adaptive, meaning it will increase/decrease the level depending on the ambient noise around you. There are many more features you can read in detail on CNET's review. If you're looking for the best and latest headphones you can seamlessly use with your iPhone or Apple products, get the AirPods Max 2. They don't go on sale very often. Our Best Editor-Vetted Tech Deals Right Now Apple AirPods Pro 3 Noise Cancelling Heart Rate Wireless Earbuds — $199.99 (List Price $249.00) Apple Watch Series 11 [GPS 46mm] Smartwatch with Jet Black Aluminum Case with Black Sport Band - M/L. Sleep Score, Fitness Tracker, Health Monitoring, Always-On Display, Water Resistant — $329.00 (List Price $429.00) Fitbit Versa 4 Fitness Smartwatch (Black) — $149.95 (List Price $199.95) Apple iPad 11" A16 128GB Wi-Fi Tablet (Silver, 2025) — $299.99 (List Price $349.00) Anker Nano 45W 10,000mAh Compact Power Bank With Retractable Cable — $59.99 (List Price $59.99) Deals are selected by our commerce team View the full article
-
Crypto-related stocks surged on Monday after news of a deal on a key stablecoin provision in the CLARITY Act, a U.S. crypto bill which has been stalled in Congress for months. The bill establishes a regulatory framework for digital commodities—”defined by the bill as digital assets that rely upon a blockchain for their value”—and would enable the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission to regulate cryptocurrencies. The Senate is planning a crypto markup later this month. Shares in Circle Internet Group (CRCL) rose over 18% in afternoon trading on Monday at the time of this writing, while Coinbase Global (COIN) surged 7%. Coinbase is a distributor in Circle’s USDC stablecoin. After months of negotiation between bank and cryptocurrency lobbies, Senators Thom Tillis (R-N.C.) and Angela Alsobrooks (D-Md.) finalized a bipartisan compromise on Friday to restrict stablecoin yield and rewards, in a bill that directs regulators to propose a new series of stablecoin regulations. The news was first reported by Punchbowl News. At issue is whether or not stablecoin issuers can offer yield-bearing products and other rewards, which could incentivize consumers away from depositing money in traditional banks, according to Reuters. Coinbase and other crypto companies have argued they need to offer some type of rewards to remain competitive. The updated, finalized language restricts crypto companies from paying out yields on stablecoin deposits, leaving that to traditional banks, but does allow rewards tied to trading, transactions, or staking, per CNBC. “In the end, the banks were able to get more restrictions on rewards, but we protected what matters, the ability for Americans to earn rewards, based on real usage of crypto platforms and networks,” Coinbase chief policy officer Faryar Shirzad posted on X; while Coinbase CEO Brian Armstrong added, “Mark it up.” President Donald The President has prioritized crypto reform during his second term in office. Critics have questioned his aggressive promotion of crypto-friendly reforms and initiatives, and whether the president and his family have a conflict of interest due to their personal stake in crypto investments. View the full article
-
If your console of choice is PlayStation and you tend to buy your video games digitally, I have good news and bad news. The good news is you might be entitled to some money thanks to a proposed lawsuit settlement from Sony. The bad news is, it's probably not going to amount to all that much. In a press release on Wednesday, the Saveri Law Firm announced a class action settlement for a case filed against Sony. The case, which is currently pending in the U.S. District Court for the Northern District of California, centers on Sony's PlayStation Store: The plaintiffs in the case claim that Sony acted as a monopoly in the sale of its digital games, which drove prices for gamers higher than they should have been on the PlayStation Store. At the core of the argument is Sony's game voucher program, which, prior to 2019, allowed gamers to buy digital game copies from retail stores. The case argues that stores could sell games cheaper than Sony's digital store, but once the company stopped supporting game vouchers, gamers only had the option to pay the higher online prices. Sony, for its part, has denied any wrongdoing in this case, and the court has not found Sony guilty of the allegations. While Sony is not admitting guilt, it does seem ready to settle. As such, the court has "preliminarily approved" the $7,850,000 settlement. If this settlement is approved during a subsequent hearing, that's the amount Sony will pay to settle the suit for all impacted customers. If you've ever bought a digital game on the PlayStation Store, you could be eligible for a (small) slice of those millions. How can I check if I'm eligible for the PlayStation Store settlement?There are a few qualifications that may exclude some customers, but if you're a Sony gamer, I'd bet there's a good chance you'd qualify. According to the suit, anyone who bought at least one digtal game through the PlayStation Store between April 1, 2019 and Dec. 31, 2023 may be entitled. That game needed to have previously had a voucher available in stores, and that voucher must have sold at least 200 copies before April 2019. Finally, the game's price needs to have increased by at least $0.50 after April 2019 compared to the price while the voucher was available. You can see the full list of applicable games here. If that's confusing, here's the saving grace: If you do qualify, you don't actually need to do anything. The suit says that if you don't act to exclude yourself before July 2, 2026, you will be considered part of the Settlement Class. You can exclude yourself from the settlement if you want, but you must do so before July 2. You'll lose out on the payment, but you'll retain your right to sue Sony if you choose. You can also formally object to the settlement, which grants you the right to speak in person at the Fariness Hearing. How much you'll get from the PlayStation Store settlementWe don't know exactly how many people will make up the settlement class, so it's tough to say precisely what the payments will be. But since there are likely many gamers who bought the digital games in the list during those select dates, the pool is probably quite large—especially considering you don't have to do anything (or even know about the lawsuit) to get a payout. Push Square's Sammy Barker has an estimate based on all available data thus far, and it's not too impressive: You're likely to get around $1 to $3 per purchase. If you bought a ton of digital games on your PS4 or PS5, you might be wind up with a decent payout, but if you only bought a handful, don't expect your cut to amount to much. View the full article
-
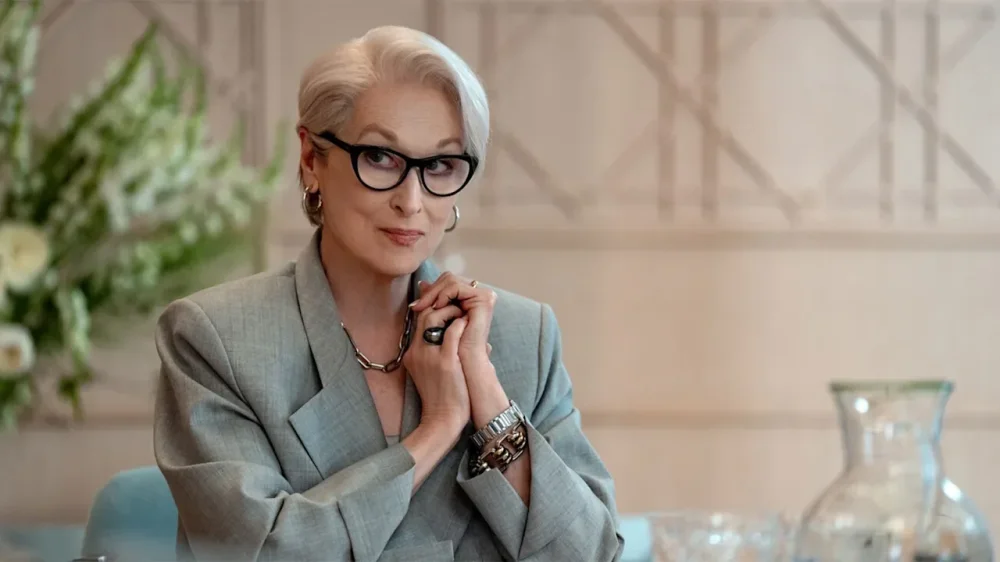
Forget AI replacing human artists—The Devil Wears Prada 2 just proved that human artists can replace AI. The new movie, a long-awaited sequel to 2006’s The Devil Wears Prada, sees the return of star Meryl Streep as iconic fashion editor Miranda Priestly. It begins with Priestly in a PR crisis, sparking a slew of online hate. That includes memes like an image of Priestly dressed as a fast food worker captioned, “Would you like lies with that?” The image is only briefly on screen, and at first glance, many moviegoers assumed it was AI-generated. After all, on the internet of 2026, it most likely would be—an internet troll likely isn’t going out of their way to craft the image by hand. But after The Devil Wears Prada 2 hit theaters on May 1, digital artist Alexis Franklin took to social media to set the record straight: She’s the one who created the artwork, not AI, at the request of director David Frankel. On Instagram, Franklin posted the artwork along with a timelapse of her digital painting process. “Absolutely no disrespect to Queen Meryl, but this is something I would’ve painted in my free time, so when they asked me to do this it was nothing but fun,” she wrote in the caption. Franklin also shared her art on X, writing that her Instagram post had been “flooded with comments of relief that this gag in The Devil Wears Prada 2 was created by an actual human (me), so I figured I’d also post it here because I think these companies should get their flowers when they hire an artist.” ‘People do crave real art’: Social media celebrates human artists The story behind Franklin’s artwork quickly went viral, with her X post amassing 3.7 million views. Many users praised the Devil Wears Prada 2 team for staying true to the pro-artistry message of their film and hiring a human artist, even when using an AI-generated image would have made sense for the plot. “This is genuinely one of the coolest things I’ve seen a movie do,” reads one viral response. “Would’ve been so easy to AI generate something for the movie but they held themselves to a higher standard which I really really respect.” “People do crave real art and not AI slop and this is a proof,” wrote another user. A third user said they hope other films will follow in The Devil Wears Prada 2’s footsteps when it comes to telling stories about AI. “There’s a reason that it always disappoints me to no end when people assume that the only way to portray AI in a movie is by actually using AI,” they wrote. “Clearly alternatives always exist.” An accidental statement against AI Though social media largely assumed Franklin’s art was intentionally replicating AI’s signature art style, she’s since clarified that any similarities to AI were totally coincidental. In a series of follow-up posts on X, Franklin emphasized that she “was not told to mimic AI” and the aspects of her drawing people assumed were nods to AI, including the blurred lettering and font inconsistencies in the background, were just meant to be impressionistic. “I was just hired to create a cheap meme and the context of the movie has everyone, understandably, thinking I was emulating AI,” Franklin wrote. In an email to NBC News, Franklin said she understands where people’s suspicions come from, but that assuming human-made art is AI can have real, negative consequences for artists. “This mass hypervigilance prevails because people don’t want to be fooled, leading them to see signs on the walls that aren’t really there or that have very simple, reasonable explanations,” she wrote. “And it’s hard to know what the solution is.” “AI is so prevalent now, it feels like people have forgotten how it got that good—it studied us,” Franklin added. “The techniques it uses are ours!” View the full article
-
You don't necessarily need an app to see where an aircraft is at any given time—if you type the airline and flight number into Google, it'll show you the arrival and departure information and where it is en route based on data pulled from Flightview (which also has a standalone app). However, there are a handful of native and third-party flight trackers, both paid and free, that provide live updates and other alerts so you have the most current information when you travel, often faster than the airlines themselves. Here are five of my favorite recommendations. Flighty costs money but can be more accurate than your airline's own appFlighty is an iOS app with robust flight tracking features like real-time delays and cancellations and live updates shown on your lockscreen (as a Live Activity) for flights in progress, whether yours or someone else's. It's one of our favorite travel apps because it often has more current information than other sources, including airlines themselves. It also shows your plane's status starting 25 hours in advance. Most of these features require a paid subscription, which you can do by week ($5) if you don't travel often, or annually ($60) if you do. FlightAware is a flexible, free alternativeIf you don't want to pay for flight tracking and don't mind ads, you can get all the data you need with FlightAware. The free app allows you to search and track any flight in real time and set up custom alerts for departures, arrivals, cancellations, and more. You can see live progress to the destination and check for delays using the "Where's My Plane?" feature—plus, there's a global flight map, airport weather data, and other features for aviation nerds. FlightAware doesn't have a Live Activities integration, but it is an excellent no-cost tracker. FlightRadar24 integrates with iOS and AndroidFlightRadar24 is similar to FlightAware in terms of the information available, including historical data, real-time flight status, and arrivals and departures at any airport around the world. It, too, has far more detail than the casual flyer needs, but the basic features are free, including tracking with Live Activities (iOS) and Live Notifications (Android). Apple Messages offers built-in tracking for iOS usersMessages on iOS has a built-in flight tracking feature with real-time information about departures, arrivals, gate changes, and baggage claim numbers—and, if the flight is en route, a live map. To use it, you simply need to have texted yourself or someone else the flight number via iMessage (not SMS), meaning you can use Messages to track any flight. The flight info does have to be in one of a few specific formats, the simplest being airline + flight number (Delta 426, for example). Within the message, tap the underlined flight text to pull up the tracking info within Messages. This is a solid, if basic, free option for iOS, lacking both live updates and push notifications. Google Wallet shows flight status on the lock screen on AndroidIf you're an Android user, you can now see your own flight's live status on your always-on display and lockscreen. Google recently introduced Live Updates to Google Wallet—all you have to do is add your boarding pass, and tracking will pop up soon after your flight takes off. The icon shows flight duration, estimated arrival time, and progress to a destination. Obviously, this feature doesn't allow you to view other flights besides the one you're currently on, so it's not as useful for tracking flights more broadly. View the full article
-
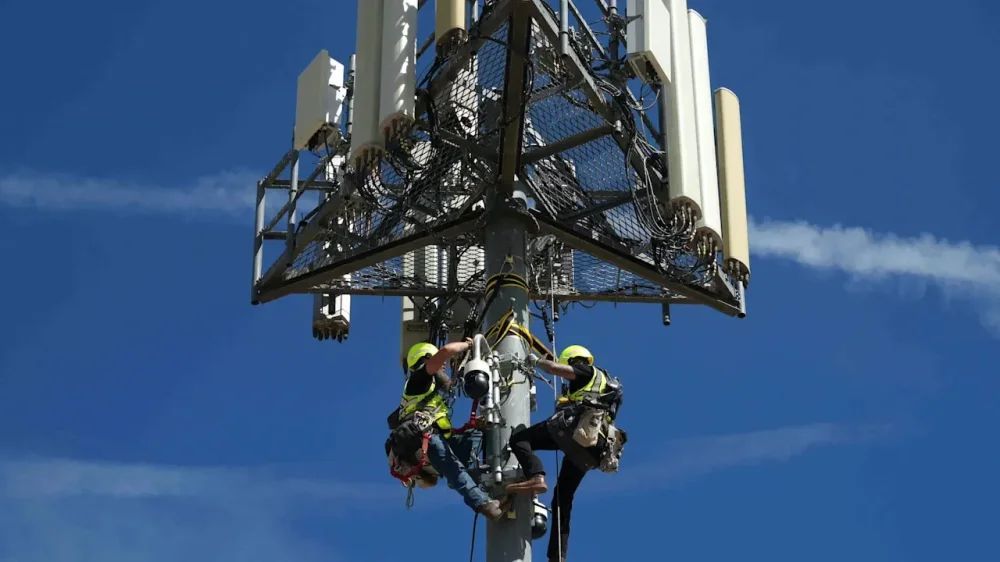
On a March afternoon, artificial intelligence detected something resembling smoke on a camera feed from Arizona’s Coconino National Forest. Human analysts verified it wasn’t a cloud or dust, then alerted the state’s forest service and largest electric utility. One of dozens of AI cameras installed for the utility Arizona Public Service had spotted early signs of what came to be known as the Diamond Fire. Firefighters raced to the scene and contained the blaze before it grew past 7 acres (2.8 hectares). As record-breaking heat and an abysmal snowpack raise concerns about severe wildfires, states across the fire-prone West are adding AI to their wildfire detection toolbox, banking on the technology to help save lives and property. Arizona Public Service has nearly 40 active AI smoke-detection cameras and plans to have 71 by summer’s end, and the state’s fire agency has deployed seven of its own. Another utility, Xcel Energy in Colorado, has installed 126 and aims to have cameras in seven of the eight states it serves by year’s end. “Earlier detection means we can launch aircraft and personnel to it and keep those fires as small as we can,” said John Truett, fire management officer for the Arizona Department of Forestry and Fire Management. Where there are fewer eyes, AI looks for fires ALERTCalifornia is a network of some 1,240 AI-enabled cameras across the Golden State that work similar to the system in Arizona. Human intervention keeps the risk of false positives low and trains the technology to become more accurate, said Neal Driscoll, geology and geophysics professor at the University of California, San Diego, and founder of ALERTCalifornia. “The AI that’s being run on the cameras is actually beating 911 calls,” he said. In Arizona, California, and beyond, the technology is mostly used in high-risk areas that are sparsely populated, rural or remote, where a blaze might not be quickly spotted by human eyes. “It’s just the ones where we won’t get a 911 call for a long time, it is extremely helpful to have that AI always monitoring that camera,” said Brent Pascua, battalion chief for the California Department of Forestry and Fire Protection, or Cal Fire. “In many cases, we’ve started a response before 911 was even called, and in a few cases, we’ve actually started a response, went there, put the fire out, and never received a 911 call.” A technology driven by worsening blazes Pano AI, whose technology combines high-definition camera feeds, satellite data, and AI monitoring, has seen a growing interest in its cameras since launching in 2020. They’ve been deployed in Australia, Canada and 17 U.S. states, including Oregon, Washington and Texas. Its customers include forestry operations, government agencies and utilities, including Arizona Public Service. Last year, its technology detected 725 wildfires in the U.S., the company said. “In many of these situations, we hear from stakeholders that the visual intelligence, the time, really, really gives them a head start and some of these could have taken off into hundreds if not thousands of acres,” said Arvind Satyam, the company’s co-founder and chief commercial officer. Cindy Kobold, an Arizona Public Service meteorologist, said the technology notifies them about 45 minutes faster on average than the first 911 call. Satyam said development of the technology was driven by the lack of hardened solutions to combat worsening wildfires. Climate change — caused by burning oil, gas, and coal — is warming the planet and fueling dry conditions that supercharge infernos, making them burn hotter, faster, and more frequently. The technology helps firefighters to safely and effectively respond while protecting communities and infrastructure, he said. Challenges and limitations One of the biggest obstacles to implementation is the price tag; Pano AI, for instance, charges around $50,000 annually per camera. The cost also includes fire risk analysis and 24/7 intelligence center. False alarms present a challenge, which can be costly in terms of time and attention, said Patrick Roberts, a senior researcher with the nonprofit research group RAND who recently finished a project on accelerating innovation in wildfire management. And when the AI accurately detects a fire, it doesn’t tell stakeholders the best course of action. “Do you send help right away? Do you monitor? Should you worry about it? Where do you send help? Do you think about evacuation? All this still requires people and decision support systems,” said Roberts. In highly populated areas, people tend to spot and call in fires pretty quickly, and the tech is not so useful when extreme weather events, such as hurricane-force winds, intensify and rapidly shift the flames, as happened in Los Angeles last year. Pascua says the technology complements Cal Fire’s work. “As the fire moves and shifts around, that’s where the human factor comes in and decides which tactics are best in fighting the fire. AI can only do so much,” he said. “It just provides that real time information where we can make better decisions on the fire ground.” AI firefighting assistance is not limited to detection AI can also be employed to identify the best places to thin vegetation and burn cool fires, and even to monitor air quality for signs of smoke, just like your home’s carbon monoxide sensor, said Roberts, but “1,000 times more sensitive.” At George Mason University in Virginia, professor Chaowei “Phil” Yang is working with researchers from California State University of Los Angeles, the city of LA and NASA Jet Propulsion Laboratory to create a system that forecasts where a fire will burn and which communities will be hardest hit by smoke pollution. The idea is to give agencies real-time maps so they can make quick, life-saving decisions about evacuations, school and road closures, and send out early air quality warnings. Yang said they hope the technology will be operational in three years. “AI in wildfires, it’s no longer just speculative. It’s really being used,” said Roberts, and it’s use will only continue to grow. “The future is AI everywhere,” he said, “and the lines will blur between AI wildfire detection and just wildfire detection as the lines will blur in other areas of our life.” ___ The Associated Press receives support from the Walton Family Foundation for coverage of water and environmental policy. The AP is solely responsible for all content. For all of AP’s environmental coverage, visit https://apnews.com/hub/climate-and-environment —Dorany Pineda and Brittany Peterson, Associated Press View the full article
-
Comprehending the definition of a Limited Liability Company, or LLC, is essential for anyone pondering starting a business. An LLC offers personal liability protection for its members, meaning your personal assets are typically safe from business debts. It additionally allows profits to pass through to your personal tax return, avoiding double taxation. Nevertheless, there are benefits and drawbacks to evaluate. To make an informed decision, it’s important to explore how an LLC compares to other business structures. Key Takeaways An LLC, or Limited Liability Company, combines features of corporations and partnerships for operational flexibility and liability protection. Owners, known as members, enjoy personal liability protection against business debts, safeguarding their personal assets. LLCs benefit from pass-through taxation, meaning profits are taxed only on members’ personal tax returns, avoiding double taxation. Management can be either member-managed or manager-managed, offering flexibility in operational structure. Establishing an LLC requires filing Articles of Organization and creating an Operating Agreement to define roles and profit distribution. What Is a Limited Liability Company (LLC)? A Limited Liability Company (LLC) is a unique business structure that merges features of both corporations and partnerships, providing a blend of operational flexibility and personal liability protection for its owners, who are referred to as members. So, what’s meant by LLC? It’s a hybrid entity that allows profits to pass through to members’ personal tax returns, effectively avoiding the double taxation that corporations often face. An LLC can be owned by individuals, corporations, or even foreign entities, with no cap on the number of members involved. You have the option to manage an LLC either through its members or by appointed managers, offering significant operational flexibility. To form an LLC, you must file articles of organization with your state and might need to obtain an Employer Identification Number (EIN) for tax purposes. This structure effectively balances liability protection with operational ease. Benefits of an LLC Numerous advantages make forming a Limited Liability Company (LLC) an appealing choice for many entrepreneurs and small business owners. First and foremost, LLCs provide personal liability protection, ensuring your personal assets aren’t at risk for any business debts or legal obligations. You as well benefit from a flexible management structure, allowing for either member-managed or manager-managed operations, depending on your preferences. In addition, LLCs enjoy pass-through taxation, meaning profits are taxed only at the individual level, which helps you avoid the double taxation often faced by corporations. With fewer formalities and reporting requirements than corporations, maintaining your LLC is simpler, making it a practical option for busy entrepreneurs. Moreover, LLCs offer customizable profit distribution arrangements, enabling you to allocate earnings flexibly among members. If you’re interested, you can start your LLC in Texas by completing the LLC in Texas application online, making the process even more convenient. Drawbacks of an LLC Though Limited Liability Companies (LLCs) offer various benefits, there are also notable drawbacks that potential owners should reflect upon. One major issue is that LLCs may dissolve upon a member’s death or bankruptcy, complicating business continuity compared to corporations, which can exist indefinitely. Furthermore, you might face self-employment taxes on your earnings, increasing your tax burden relative to corporate structures. Without a well-defined operating agreement, roles can become unclear, leading to potential disputes among members. In addition, LLCs often have state-specific regulations and compliance requirements, including annual fees and reports, which add to the ongoing costs of maintaining your business. Finally, transferring membership typically requires approval from existing members, making ownership changes less flexible than in a corporation. When weighing the ltd vs llc choice, it’s crucial to reflect upon these drawbacks to make an informed decision. How to Start an LLC Starting an LLC involves several significant steps that lay the foundation for your business. First, choose a unique name that meets your state’s regulations and includes “LLC” or “Limited Liability Company.” Next, file the Articles of Organization with your state’s Secretary of State, including crucial details like your LLC’s name, address, and registered agent. After that, draft an Operating Agreement to clarify member roles and profit distribution. Don’t forget to obtain an Employer Identification Number (EIN) from the IRS for tax purposes and to open a business bank account. Finally, guarantee compliance with state regulations by acquiring any necessary licenses or permits and maintaining ongoing obligations. Here’s a quick overview of the steps: Step Description Choose a Business Name Verify it complies with state naming rules. File Articles of Organization Submit necessary documents to your state. Create an Operating Agreement Outline management and profit distribution. Obtain an EIN Required for taxes and banking. Guarantee Compliance Acquire licenses and maintain obligations. LLC vs. Corporation: Key Differences When comparing LLCs and corporations, grasping their key differences is vital for making informed business decisions. Here are some fundamental distinctions to reflect on: Ownership Structure: LLCs have members, whereas corporations have shareholders, affecting management and profit distribution. Management Flexibility: LLCs allow for member-managed or manager-managed options, whereas corporations require a board of directors and a structured hierarchy. Taxation: LLCs typically benefit from pass-through taxation, meaning profits are taxed only at the individual level, whereas corporations may face double taxation on profits. Ownership Transfer: LLCs offer more flexible ownership transfer governed by the operating agreement, whereas corporations have stricter regulations for transferring shares. Both LLCs and corporations provide limited liability protection, but corporations usually have more established legal precedents supporting this. Recognizing these differences can help you choose the right structure for your business. Frequently Asked Questions What Is an LLC Explained for Dummies? An LLC, or Limited Liability Company, combines benefits from corporations and partnerships. It protects your personal assets from business debts, meaning you’re not personally liable for losses. You can choose how it’s taxed, often avoiding double taxation. Forming an LLC involves selecting a unique name, filing Articles of Organization, and possibly creating an operating agreement. They’re flexible and require fewer formalities, making them ideal for small businesses and entrepreneurs. What Is a Simple Definition of LLC? An LLC, or Limited Liability Company, is a flexible business structure that combines personal liability protection with tax benefits. As a member, you enjoy limited liability, meaning your personal assets are typically safe from business debts. LLCs can be formed by one or more individuals or entities, and profits pass through to your personal tax return, avoiding double taxation. To establish an LLC, you file articles of organization and designate a registered agent for legal matters. What Is the Biggest Disadvantage of an LLC? The biggest disadvantage of an LLC is often the self-employment tax liability. If you actively participate in the business, your profits are subject to this tax, which can be significant. Moreover, LLCs can incur higher startup and maintenance costs compared to other business structures. Limited ownership transferability complicates succession planning, and raising capital may prove challenging since investors frequently prefer more established entities like corporations. Proper maintenance is vital to protect personal assets from business liabilities. What Are Three Things That LLCS Are Not Required to Do? LLCs aren’t required to hold annual meetings, which simplifies their management. You likewise don’t need to maintain extensive corporate records, unlike corporations. Furthermore, LLCs don’t have to file separate federal tax returns; profits are typically reported on your personal tax return, allowing for pass-through taxation. Although it’s advisable to have an operating agreement for clarity, it’s not mandatory, providing you with flexibility in managing your business structure. Conclusion In conclusion, a Limited Liability Company (LLC) offers a blend of liability protection and tax advantages, making it an attractive option for many business owners. As it provides benefits like flexible management and pass-through taxation, it is crucial to evaluate potential drawbacks, such as varying regulations and self-employment taxes. Starting an LLC involves specific steps, and grasping the differences between an LLC and a corporation can further guide your decision. With the right information, you can make an informed choice for your business structure. Image via Google Gemini This article, "Understanding the Company LLC Definition: A Simple Guide" was first published on Small Business Trends View the full article
-
You might remember ZenBooths—Amazon’s contribution to corporate well-being. These were booths installed in the middle of warehouses, equipped with a fan, a potted plant, and a monitor playing meditation videos. The company called them mindful practice rooms. Employees called them despair chambers. The internet called them coffins for workers—workers who, incidentally, didn’t even have time to use the bathroom because of crushing productivity demands. ZenBooths are, I think, a fitting metaphor for modern corporate wellness. According to Gallup, employee engagement dropped to 20% in 2025—the lowest it’s been since the COVID-19 lockdowns. Companies are pouring money into all kinds of initiatives, convinced they’re building attractive workplaces, while their employees quietly disengage. Why is this happening, and what can we do about it? Here are a few observations from my own experience. STRESS AS A SYMPTOM OF POOR MANAGEMENT University of Oxford researchers analyzed data from more than 46,000 employees, comparing those who used corporate wellness programs with those who didn’t. None of the practices produced any meaningful improvement in employee well-being. Wellness programs rest on a simple assumption: if someone is stressed, give them a tool to relax. The problem is that this approach treats symptoms while ignoring the conditions that cause the stress in the first place. Those conditions—surprise—tend to be unrealistic workloads, micromanagement, a lack of feedback, and messages landing in inboxes after hours. Employees feel all of this through their daily interactions with their manager: how tasks get assigned, how they measure performance, and whether working hours are respected. In a separate study, Gallup found that employees who view their team’s management practices as ineffective are roughly 60% more likely to report high levels of stress. If your team has is less proactive and burning out faster, the problem almost certainly isn’t a shortage of wellness programs. Moments like these are a signal for managers to take a hard look at their own decisions first. A SUPPORTIVE MANAGER IS THE KEY TO TEAM WELL-BEING I manage a team of 90 people. Until 2022, we worked out of an office in the Ukrainian city of Kherson and were firm believers in in-person collaboration. Our health check surveys consistently show the sense of connection we built over 10 years of working side by side motived people most. Russia’s full-scale invasion of Ukraine forced us to scatter across different cities and countries, and we moved to fully remote working. I had to introduce new online formats to keep people engaged: regular one-to-ones with team leads, short team syncs focused on priorities and blockers, and open Q&A sessions where the team could ask about decisions and changes in the way we work. We can’t hold in-person events right now, but we’ve still managed to preserve a healthy atmosphere despite the distance and the limited opportunities for team building. Here are the five approaches I’ve found most effective. 1. Cover the basics. A reasonable workload, a flexible schedule, and fair pay aren’t perks—they’re the foundation. If a person can’t take sick leave without it costing them, no wellness tool will relieve the pressure. In our case, the most basic need after the war began was physical safety. I understood that no one could be productive while they or their loved ones were under bombardment. So, until every member of the team had settled somewhere safe, I redistributed work, flexed our processes, and personally helped people with relocation. Our clients didn’t notice. 2. Be a coach, not a controller. Delegate the task and the right to choose how it gets done. That kind of autonomy makes people feel they’re shaping the outcome, not just following instructions—and that has a direct impact on engagement. A couple of years back, I had a complex technical problem on my hands. My first instinct was to pick the solution myself, but I handed it to my development team instead. They chose their own approach and delivered a stunning result. 3. Lead by example. If you send emails at midnight and never take vacation or sick days, your team reads that as the norm. Talking about work-life balance is worthless when the manager’s actions say the opposite. When leaders model healthy habits, it defines the culture for everyone else. 4. Be interested in people, not just tasks. We run check-in meetings where team members can share how they’re doing in general, and watercooler meetings where we talk about anything except work. It helps a manager stay in touch with the team and catch things before they become problems. Even in first interviews, I personally ask candidates more questions about their lives than about their work. 5. Don’t be afraid to hear the truth about yourself. Most managers never get honest feedback on their work—not because everything is perfect, but because there’s no real channel for it. People won’t air their concerns in all-hands meetings. That’s why I hold regular one-to-ones and actively seek input from the team. Whatever doesn’t come up in those conversations, we surface through anonymous surveys and team health checks. Companies that take employee well-being seriously start with an honest question: Are our managers creating an environment where people want to work? The best wellness program is a working environment you don’t constantly need to recover from. Illia Smoliienko is the chief software officer at Waites. View the full article
-
In a stark reminder of the vigilance required in managing federal relief programs, Marcus Eichelberger, a former pastor from Jacksonville, Florida, faces serious legal consequences for alleged wire fraud tied to the Paycheck Protection Program (PPP). The case highlights ongoing challenges for small business owners navigating relief programs designed to support them amid financial uncertainty. Eichelberger was indicted on four counts of wire fraud, which carries a potential sentence of up to 20 years in federal prison for each count. The indictment alleges that between March 2021 and February 2022, he and an associate submitted false applications for PPP loans. They purportedly claimed the funds would be used to maintain payroll and operational expenses for an unqualified business. Instead, the funds were allegedly diverted for personal use. U.S. Attorney Gregory W. Kehoe commented on the case, emphasizing the government’s commitment to safeguarding taxpayer-funded programs. “The U.S. Attorney’s Office is committed to prosecuting those who use fraud and deception to exploit our nation’s federal benefits programs,” he said. Such statements reinforce the growing scrutiny on loan applications, especially in the wake of widespread fraud in relief programs during the pandemic. The alleged activities surrounding Eichelberger’s case serve as a crucial alert for small business owners. The PPP was designed to offer financial relief during the COVID-19 pandemic, but the influx of funds also opened avenues for fraudulent claims. For entrepreneurs, this means that they must be particularly diligent in documenting and using funds according to the requirements set by the SBA. Moreover, the case is part of a larger investigative effort spearheaded by the Department of Justice’s National Fraud Enforcement Division, which aims to combat misuse of taxpayer dollars. “This case demonstrates the VA OIG’s unwavering commitment to detecting and preventing fraud,” remarked Special Agent in Charge David Spilker of the VA Office of Inspector General’s Southeast Field Office. This pronouncement not only underlines the seriousness of the allegations but also highlights the collaborative approach government agencies are taking to address fraud. While the PPP provided financial lifelines to many businesses, small business owners must consider the implications of this surveillance. Compliance with federal guidelines is paramount; failing to do so can lead to severe penalties, including prosecution. Misunderstanding the eligibility criteria or misusing the funds can result in not just repayment demands but significant criminal charges. Further complicating matters for small businesses, the landscape of federal aid continues to evolve. With new rounds of funding being introduced, being informed about the rules is essential. Keeping abreast of updates from the SBA and other relevant agencies can provide clarity, though navigating the details remains an ongoing challenge. Additionally, courts have reaffirmed the presumption of innocence until proven guilty, which is vital in cases like that of Eichelberger. Nevertheless, this underscores the fact that the burden of proof lies with individuals seeking federal funds. Detailed documentation and transparency are non-negotiable. For small business owners looking to secure funds through federal programs, diligence is key. It is not just essential to fill out the application properly; careful attention must be paid to how those funds are spent. Failure to comply could open a floodgate of issues, potentially endangering the very existence of a business that relies on such financial assistance. As the Department of Justice continues its crackdown on fraud, the consequences will likely resonate beyond those accused. Small business owners must remain aware of their responsibilities, the evolving regulatory environment, and the importance of ethical practices in securing federal funding. For more information on this case and ongoing fraud prevention efforts, you can visit the original U.S. Department of Justice press release here. Additionally, updates on SBA guidelines and related news can be found by signing up for the SBA OIG email updates here. Image via Google Gemini This article, "Former Jacksonville Pastor Indicted for Fraud in PPP Loan Scheme" was first published on Small Business Trends View the full article
-
The music industry has seen disruption before. Vinyl gave way to cassettes, CDs to Napster, downloads to streaming. Each shift rewired how the music industry distributes and monetizes songs but did not change what music fundamentally is or the fact that humans have always created it. Artificial intelligence doesn’t just change how music moves. It challenges who owns it and who gets paid for it. The real threat of AI isn’t that it can make songs. It’s that it reveals how fragile the music industry is. For years, artists have operated inside a system where millions of streams translate into fractions of a cent, algorithms dictate visibility, and ownership is often diluted long before a song reaches an audience. The conversation around AI is not a battle between humans and machines over creativity. It’s a structural shift that puts the entire artist economy at risk, and how we respond will determine if AI expands opportunities or quietly erodes them. AUTOMATION, ACCOUNTABILITY AND CONTROL At its best, AI is a powerful equalizer. For emerging artists without teams or budgets, it reduces the friction of getting started. What once required a label infrastructure can now be assembled independently. Tools can generate press materials, build websites, create visuals, and help develop production ideas. That matters because access, not talent, has been the primary barrier to entry into music for decades. Used responsibly, AI doesn’t replace creativity. It gives artists more time to focus on what’s needed to build their careers: songwriting, live performances, and audience connection. But that’s only one side of the equation. The biggest threat AI poses to music isn’t that it can create songs. It’s that it can do so without clear ownership, consent, or compensation. We’re entering a moment where automation is outpacing accountability, and creators lose when that happens. The real issue is control: who owns the inputs, who profits from the outputs, and who gets displaced in between. If streaming platforms can’t distinguish between human and machine-generated content, what happens to already fragile royalty systems? Who owns the output if an AI model is trained on decades of recorded music and artist catalogs without permission? Who gets paid when a fully AI-generated track goes viral? AI-generated content can also inflate streams, manipulate metrics, and create the appearance of traction without any tangible audience connection. Growing the illusion of popularity is not real success, and that distortion has real consequences for who gets signed, booked, and funded in a business already driven by data. If AI platforms won’t distinguish between human and machine-generated content, the value of human labor in music doesn’t just decline; it becomes optional. AI CANNOT CARRY AN AMP While much of the conversation focuses on creation, the music economy runs on people: sound engineers, lighting designers, tour managers, road crews, venue operators, and staff. These roles don’t just support music; they are the infrastructure. Music has never just been about the product. It’s about the experience. Experts predict the global live music market will surge to a $60+ billion industry in the coming decade, as digital content and experiences become infinitely more abundant, making physical experiences and real-world connections much more valuable. AI can generate a song in seconds, but it can’t replicate the electricity of a live performance. It can’t replicate the deep connections between an artist and their fans, or the ecosystem of workers who make that moment happen. It can’t develop a fan base over years of touring or create the shared, unpredictable, and imperfect moments that turn listeners into communities. And it definitely can’t load a truck at 2 a.m., tune a guitar, or run a festival. If anything, AI makes those human elements even more important. TEST WHAT WE VALUE The rise of AI in music is forcing deeper questions around what we value in art. If the answer is efficiency, AI will win. But that’s the whole point and beauty of art; it’s not about efficiency; it’s about connection, storytelling, and shared experiences. The market is giving us signals. Even as AI-generated music becomes more polished, audiences are doubling down on live experiences from stadium tours to intimate listening rooms. That’s not because we can’t access music digitally; it’s because we’re searching for something digital can’t provide. For all the noise around AI, the most important decisions about the future of music won’t happen in code. They’ll happen in venues, local scenes, and in the infrastructure that supports artists long before and after their music is released. The question isn’t whether AI belongs in music because it already does. The question is whether we’re willing to invest in the human systems that make music matter in the first place. Because if we’re not, AI won’t need to replace artists. It will simply outcompete an ecosystem we allowed to weaken on its own. GOVERNANCE AND BUILDING AN ARTIST-CENTERED AI FUTURE We are allowing AI to build a new layer of infrastructure—one that can replicate, remix, and redistribute creative work at scale without clearly defining the rules of participation. The goal isn’t to resist AI. The goal is to shape how it integrates into the music ecosystem. AI should expand what’s possible for artists, not dilute what makes them valuable. That starts with a few clear priorities: Establish real guardrails around authorship and consent. Artists should have control over how their work is used to train AI systems. Invest in workforce development, not just technology. The future of music jobs depends on reskilling, not replacement. Prioritize tools that empower creators—not platforms that extract from them. Re-center success around audience connection, not algorithmic performance. The industry’s current response to AI has been reactive through lawsuits, policy debates, and platform guardrails that are already struggling to keep up. If platforms, labels, and policymakers don’t step in with clearer frameworks around consent, compensation, and attribution, we won’t get an AI-powered creative boom. We’ll just race to the bottom. Matt Mandrella is the music officer for the City of Huntsville. View the full article
-
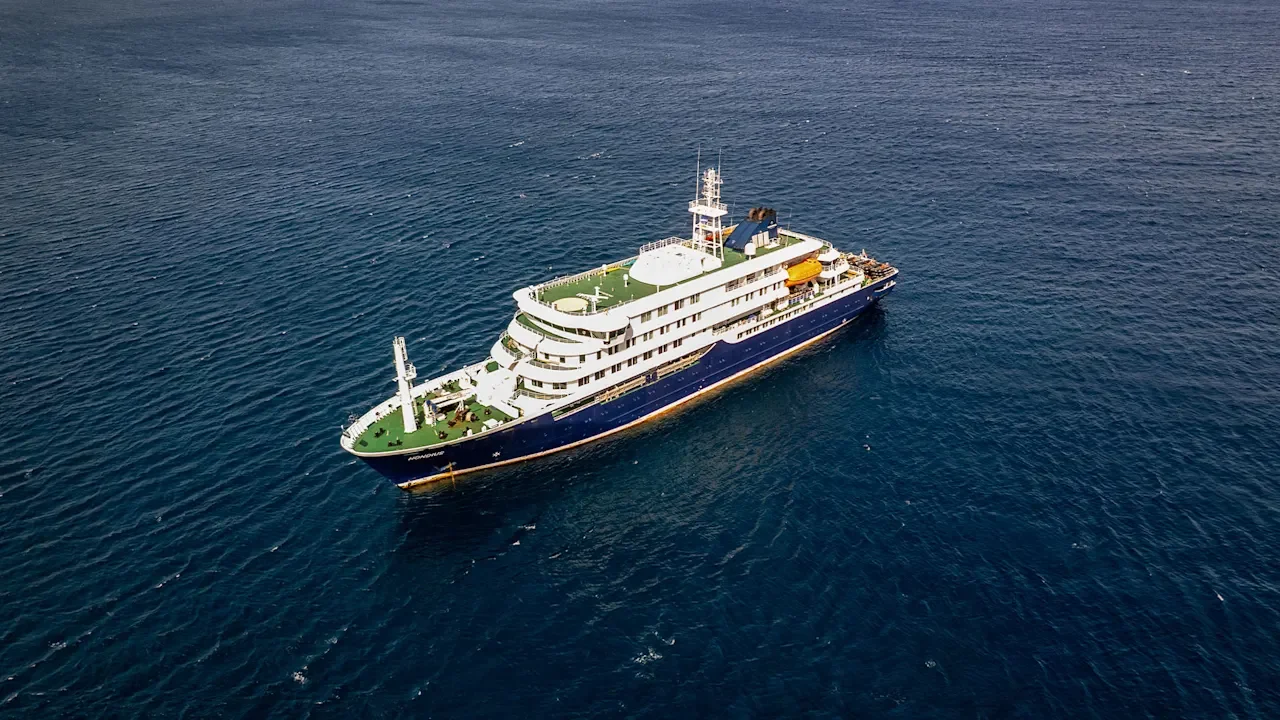
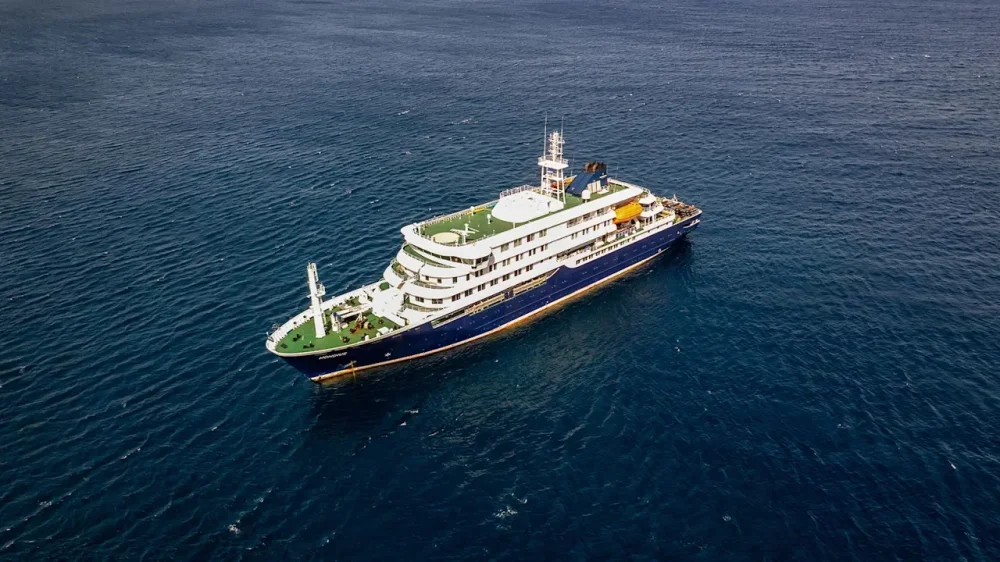
A luxury cruise ship is currently being held off the coast of West Africa after a suspected outbreak of hantavirus—a rare infectious disease typically carried by rodents—killed three passengers and infected three others. The World Health Organization (WHO) shared the news of the suspected outbreak in a post to X. According to the organization, one case of hantavirus on the ship, MV Hondius, had been confirmed through laboratory testing, and there are five additional suspected cases. Of those six affected individuals, three have died and one is currently in intensive care in South Africa. According to an official update from Dutch company Oceanwide Expeditions, the operator of the ship, two crew members are still on board the ship with acute respiratory symptoms, both of whom require immediate care. As of Monday morning, medics were working to evacuate them. Meanwhile, 149 passengers remain stuck on the ship as local medical teams and authorities work to determine how to proceed. “Strict precautionary measures are in process on board, including isolation measures, hygiene protocols and medical monitoring,” Oceanwide’s statement reads. “All passengers have been informed and are being supported.” Foster Mohale, a spokesman for the National Department of Health in South Africa, told The New York Times that “There is no need for the public to panic, because only two patients from the cruise ship have been within our borders.” As the situation develops, here’s what to know about the hantavirus: What is hantavirus? Hantaviruses are a family of viruses that can cause serious illness and, in some cases, death. According to the Centers for Disease Control and Prevention (CDC), hantavirus infection can lead to two main syndromes: hantavirus pulmonary syndrome (HPS), which is typically found in the Western hemisphere hemorrhagic fever with renal syndrome (HFRS), which is typically found in Europe and Asia As of the end of 2023, the CDC reported 890 total confirmed cases of hantavirus disease in the U.S. since surveillance began in 1993. How does it spread? All hantaviruses spread primarily through contact with rodents. Typically, the Mayo Clinic notes, infection is caused by “inhaling hantaviruses that have become airborne from rodent urine, droppings, or saliva.” Hantaviruses can also spread through contact with infected people, though the WHO says these cases are extremely rare. What are the symptoms? While HPS and HFRS are both diseases caused by hantavirus strains, their symptoms and impacts are different. HPS is a disease that affects the lungs. Symptoms typically start to show between one and eight weeks after contact with an infected rodent and, in early stages, include markers like fatigue, fever, and muscle aches. As the disease progresses, late-stage symptoms look like coughing and shortness of breath. Per the CDC, 38% of people who develop respiratory symptoms die from the disease. Unlike HPS, HFRS primarily impacts the kidneys. Symptoms usually develop between one to two weeks after contact with an infected rodent, and include intense headaches, back and abdominal pain, fever, blurred vision, and nausea. Later symptoms include low blood pressure, internal bleeding, and acute kidney failure. The severity of the disease depends on which strain of hantavirus infected the patient, as some (Hantaan and Dobrava, for example) lead to more severe illness, while others (Seoul, Saaremaa, and Puumala) are typically less harmful. How to prevent hantavirus from spreading Given that hantavirus is primarily carried and spread by rodents, both the CDC and the Mayo Clinic say that eliminating contact with rodents is the best way to avoid infection. That means sealing holes or gaps in your home or garage, cleaning up any easy-to-access food, setting traps, and taking precautions (like a mask, gloves, and disinfectant) while cleaning up any rodent droppings. In regard to the MV Hondius outbreak, Hans Kluge, the WHO’s regional director for Europe, told Reuters, “The risk to the wider public remains low,” adding that there’s no need for panic or travel restrictions. View the full article
-
Text exchange revealed in court filings came after world’s richest man tried to start last-minute settlement talksView the full article
-
The top bullet point in Two Harbors' rejection notice is the Mizuho credit facility does not constitute committed financing for UWM to pay for the deal. View the full article
-
Term financing is a structured funding option that gives businesses a lump sum of capital to invest in growth or significant projects. You’ll repay this amount over a set period, often through fixed or variable payments that include interest. This type of financing can be advantageous for long-term financial planning, but it’s crucial to understand its various types and features. What should you consider before applying for this form of financing? Key Takeaways Term financing provides a lump sum of cash that is repaid over a set period through regular payments, often requiring collateral. It includes various loan types: short-term, medium-term, long-term, and specialized loans like balloon or step-up repayment loans. The approval process assesses creditworthiness, requiring strong financial statements and an evaluation of collateral. Repayment structures are fixed, with payments typically made monthly or quarterly, depending on the loan duration. Term financing is suitable for significant investments, predictable revenue streams, and consolidating high-interest debts. What Is Term Financing? Term financing is an essential funding option that provides businesses with a lump sum of cash, which they repay over a set period through regular payments. This financing can be categorized into different types, such as term loan A versus term loan B, depending on the structure and terms. Term loans typically require collateral, which may include business assets or personal guarantees, and the approval process is rigorous to evaluate creditworthiness. The duration of term financing varies; short-term loans last less than a year, whereas intermediate-term loans span one to three years, and long-term loans can extend from three to 25 years. Interest rates can be fixed or variable, and costs are reflected in the annual percentage rate (APR), including any fees. Businesses often use term financing for significant investments in fixed assets, like equipment purchases and operational expansions, making it a critical option for growth. Key Features of Term Financing When considering financing options, comprehension of the key features of term financing can greatly improve your decision-making process. Term financing offers distinct characteristics that can help you manage your business’s financial needs effectively: Provides a lump sum of capital upfront, which you repay over a set period, usually with fixed or variable interest rates. Features structured repayment schedules, typically with monthly or quarterly payments that include both principal and interest. Offers a range of loan durations: short-term (less than a year), intermediate-term (one to three years), and long-term (three to 25 years). Often requires collateral, like business or personal assets, which can lower interest rates and reduce lender risk. Understanding these key features allows you to make informed choices and better plan your finances, ensuring that your business remains on a stable path throughout the loan period. Types of Term Financing Several types of term financing are available, each designed to meet specific business needs and timelines. Comprehending these options can help you make informed decisions for your business. Type of Loan Duration Purpose Short-Term Loans A few months to 2 years Immediate needs like inventory purchases Medium-Term Loans 2 to 5 years Equipment purchases or modest expansions Long-Term Loans Over 5 years (up to 25) Significant investments such as real estate Balloon Loans Varies Smaller payments with a large final payment Step-Up Repayment Loans Varies Lower initial payments that increase over time Short-Term Financing Explained Short-term financing is a valuable option for businesses needing quick access to capital to address immediate financial challenges. Typically lasting less than one year, this type of financing is perfect for situations like: Seasonal inventory purchases Urgent operational expenses Managing cash flow fluctuations Covering unexpected costs While short-term loans provide rapid approval with less documentation, they often come with higher monthly payments and steeper interest rates. This makes them more suitable for businesses that can rely on consistent near-term revenue, ensuring that repayments won’t strain cash flow. Nevertheless, it’s vital to manage these loans carefully, as accumulating high-interest costs can pose risks if not handled properly. Overall, short-term financing can deliver quick relief, but comprehending its implications is key for maintaining financial health. Intermediate-Term Financing Explained Intermediate-term financing serves as a practical solution for businesses seeking to fund specific projects or acquisitions over a period of one to three years. This type of financing is commonly used for purchasing equipment or modest expansions. Repayment typically occurs through manageable monthly payments based on your business’s cash flow, making it easier to budget. Interest rates for intermediate-term loans are typically lower than those for short-term loans, providing a cost-effective financing option. Nevertheless, many lenders require collateral, which might include business assets or personal guarantees to reduce risk. The structured repayment schedule aids in effective cash flow management throughout the loan duration. Here’s a quick overview of intermediate-term financing: Feature Description Loan Duration 1 to 3 years Repayment Frequency Monthly payments Interest Rates Typically lower than short-term loans Collateral Requirements Business assets or personal guarantees Typical Uses Equipment purchase, modest expansions Long-Term Financing Explained Long-term financing is a crucial option for businesses aiming to invest considerably in their future without the immediate pressure of repayment. Typically, these loans have repayment periods ranging from three to 25 years, allowing for significant investments in fixed assets. Here are some key points to reflect on: Loans often require collateral, such as business assets or personal guarantees, to secure the lender’s investment. Interest rates can be fixed or variable, providing predictability in monthly payments. Maximum loan terms vary; real estate loans may extend up to 25 years, whereas other types may be shorter, around 10 years. Long-term financing is ideal for substantial expenditures like purchasing commercial real estate, equipping facilities, or funding major business expansions. Benefits of Term Financing Term financing offers numerous advantages that can greatly benefit businesses looking to invest in their growth. It provides access to substantial capital, enabling you to make significant investments in equipment, real estate, or expansion projects that mightn’t be feasible with smaller funding options. With predictable repayment schedules, term financing aids your budgeting and cash flow management, allowing you to plan for fixed monthly or quarterly payments. Typically, it offers lower interest rates compared to other financing methods, such as credit cards, which can help reduce your overall borrowing costs. By securing larger amounts of capital through term financing, you can facilitate growth initiatives, like entering new markets or upgrading technology, enhancing your competitiveness. Finally, successfully repaying term loans can positively impact your credit score, creating opportunities for future financing at more favorable terms. Drawbacks of Term Financing When considering term financing, you should be aware of several drawbacks that could impact your business. First, the need for collateral means you might risk valuable assets if you can’t make payments. Furthermore, rigid repayment structures and qualification challenges can add stress to your financial planning, especially during tough economic times. Collateral Risks Involved Collateral risks are a significant concern for businesses evaluating term financing, as they often require assets or personal guarantees to secure the loan. If you default, the lender can seize these assets, which might jeopardize your operations. Here are some key risks to bear in mind: You could lose vital business assets or even personal property. Your access to financing may be limited if you lack sufficient collateral. Defaulting on a loan could lead to severe personal financial repercussions. Strained cash flow from rigid repayment terms can increase the risk of default during tough times. Understanding these risks is important before committing to term financing to guarantee that you’re making informed decisions for your business’s future. Rigid Repayment Structures Despite having a structured repayment plan may seem beneficial, the rigidity of these schedules in term financing can pose significant challenges for your business. Fixed repayment schedules require consistent monthly or quarterly payments, which might strain your cash flow during slower periods. This lack of flexibility makes it tough to adjust payments based on fluctuating revenues or unexpected expenses. If you encounter financial difficulties, the obligation to make regular payments can increase stress and lead to default risks. Furthermore, prepayment penalties could limit your ability to adjust your repayment strategy. Strict repayment terms can likewise hinder your chances of securing additional financing, as lenders may view existing debt as a risk factor. Challenge Impact on Business Fixed Repayment Schedules Strained cash flow Lack of Flexibility Difficulty adjusting payments Default Risks Increased financial stress Qualification Challenges for Borrowers Securing term financing often involves maneuvering through a complex terrain of qualification challenges that can be overwhelming for many borrowers. You may encounter several hurdles, including: Stringent qualification requirements, demanding a strong credit history and solid financial statements. Collateral demands, which could put your business assets or personal guarantees at risk if you default. Difficulties for startups and newer businesses, often struggling because of a lack of established creditworthiness. Lengthy approval processes that can deter you, especially if you need quick access to capital. These challenges can make obtaining term financing an intimidating experience, as you navigate strict criteria and potential risks that may affect your financial stability. How Term Financing Works When you pursue term financing, the process begins with an application and approval phase, where lenders assess your financial health and creditworthiness. Once approved, you’ll receive a lump sum that you’ll repay through a structured schedule of fixed or variable payments over a set period, which can range from a few months to several years. Moreover, comprehending interest rates and any associated fees will help you grasp the total cost of your loan, ensuring you’re fully aware of your financial obligations. Application and Approval Process To obtain term financing, you’ll need to navigate a structured application and approval process designed to assess your creditworthiness and the financial health of your business. Typically, you’ll need to gather and submit: Financial statements Business plans Personal guarantees Tax returns and cash flow projections The lender reviews your application, focusing on these documents to determine your business’s viability. If approved, they’ll present you with terms that outline the loan amount, interest rate, repayment schedule, and any associated fees. Once you accept these terms, the lender disburses the agreed lump sum into your bank account, allowing you to utilize the funds for your planned business activities. This process is essential for ensuring both parties understand their commitments. Repayment Structure Explained Comprehending the repayment structure of term financing is crucial for managing your business’s financial obligations effectively. Typically, you’ll face fixed monthly or quarterly payments that include both principal and interest over a set period. The repayment schedule is established at the loan’s inception, varying by loan type—short-term loans usually require payments in less than a year, whereas long-term loans can extend up to 25 years. Here’s a quick overview of common repayment structures: Loan Term Payment Frequency Duration Short-term Monthly Medium-term Quarterly 1-5 years Long-term Monthly 5-25 years Flexible option Varies Depends on agreement Understanding this structure helps you plan your cash flow effectively. Interest Rates Overview Interest rates play a pivotal role in how term financing works, impacting the overall cost of borrowing. When you consider a term loan, you’ll typically encounter fixed or variable interest rates, which depend on your creditworthiness and market conditions at the time of your loan agreement. Here are some key points to remember: Interest rates for term loans are typically lower than those for credit cards. Monthly or quarterly payments include both principal and interest, with interest decreasing over time. Prepayment penalties may apply if you pay off the loan early, particularly for longer maturities. The Annual Percentage Rate (APR) provides a thorough view of the loan’s overall cost, combining interest and additional fees. Understanding these factors helps you make informed borrowing decisions. When to Consider Term Financing When should you evaluate term financing for your business? If you need significant capital for long-term investments, like purchasing equipment or broadening operations, term financing may be a good fit. It allows predictable repayment over time. Furthermore, if your business has a stable revenue stream, you can support consistent monthly or quarterly payments without straining cash flow. Term financing is also helpful for consolidating high-interest debts into a single payment, potentially lowering interest rates. In addition, if you have a solid business plan and strong financial statements, term loans can provide access to larger sums of capital. Finally, businesses financing real estate purchases or major renovations should contemplate long-term term loans, which can extend repayment periods up to 25 years. When to Evaluate Term Financing Benefits Significant long-term investments Predictable repayment Stable revenue stream Support for consistent payments Debt consolidation Lower overall interest rates Real estate financing Extended repayment terms Tips for Applying for Term Financing When applying for term financing, it’s vital to prepare fundamental financial documentation, like tax returns and bank statements, to showcase your business’s creditworthiness. Furthermore, consider applying with multiple lenders so you can compare interest rates, terms, and fees, which may lead to better financing options. Prepare Financial Documentation Applying for term financing requires careful preparation of financial documentation that showcases your business’s financial health and stability. To improve your chances of approval, gather the following crucial documents: Recent tax returns, profit and loss statements, and balance sheets to demonstrate financial health. A detailed business plan outlining how you’ll use the loan, projected cash flow, and anticipated growth. Personal financial documentation, including tax returns and credit history, as many lenders require personal guarantees. Existing loan documentation to illustrate current debt obligations, helping lenders assess overall financial stability and repayment capacity. Compare Multiple Lenders Securing the right term financing requires a careful evaluation of various lenders to identify the best fit for your business. Gather quotes from at least three lenders to compare interest rates, repayment terms, and fees. Remember, it’s not just about the interest rate; consider the total loan cost, including origination fees and any prepayment penalties. Each lender has different qualification requirements, which can affect your approval chances based on your financial health. Review the fine print in loan agreements for covenants that may impact your operations. Fortifying your application with financial documents like tax returns and cash flow statements can greatly improve your credibility. Lender Interest Rate Fees Repayment Terms Lender A 5.5% $500 5 years Lender B 6.0% $300 7 years Lender C 5.8% $400 6 years Frequently Asked Questions What Is Term Financing? Term financing is a borrowing method where you receive a lump sum from a lender, which you repay over a set period. This type of financing is ideal for large purchases, like equipment or real estate. The repayment includes both principal and interest, making it easier for you to plan your finances. Typically, you’ll need to provide collateral and undergo a credit assessment to secure the loan, which helps mitigate lender risk. Is a Term Loan Good or Bad? A term loan can be both good and bad, depending on your business’s financial situation. It offers predictable monthly payments and often lower interest rates, which can be appealing for long-term investments. Nevertheless, it may require collateral, risking your assets if you fail to repay. Furthermore, the fixed repayment schedule can strain cash flow during slow periods, making it less suitable for short-term needs. Assess your stability and purpose before deciding. What Is Better, a Term Loan or a Line of Credit? Choosing between a term loan and a line of credit depends on your needs. If you’re making a large, one-time investment, a term loan may be better because of its lower interest rates and structured repayment schedule. On the other hand, if you need flexible access to funds for ongoing expenses or cash flow management, a line of credit provides that adaptability. Assess your financial goals and choose the option that aligns best with your situation. Can Term Loans Be Paid off Early? Yes, you can often pay off term loans early, but it depends on your specific loan agreement. Many loans allow for early repayment without penalties, which can help reduce overall interest costs. Nonetheless, some long-term loans may impose prepayment fees if paid off too soon, especially those with maturities of 15 years or more. Always review your loan terms carefully to understand any potential fees or restrictions regarding early payoff options. Conclusion In conclusion, term financing is a structured funding option that provides businesses with the capital needed for significant investments. By comprehending its key features, types, and potential drawbacks, you can make informed decisions about whether it’s right for your financial needs. When applying, guarantee you present a strong financial profile and a clear repayment plan. Finally, term financing can support your business growth when used strategically and responsibly. Image via Google Gemini and ArtSmart This article, "What Is Term Financing and How Does It Work?" was first published on Small Business Trends View the full article
-
If you're a long-time Samsung Galaxy user, your messaging app of choice might be Samsung Messages. Despite the company removing the app as a default several years ago, many still rely on it—though not for long. Samsung is shuttering the app in July, marking the end of an era for the Galaxy ecosystem. The app won't be completely useless after this date, as Samsung says that you'll still be able to contact both emergency services and emergency contacts. But aside from these limited scenarios, Samsung Messages will essentially be defunct. As such, all Samsung Messages users need to plan for how they want to continue messaging on their Galaxy. While Samsung hasn't told us which day the app will shut down, we do know it will happen sometime in July. That gives Samsung Messages users just over two months to find other arrangements—including how to move existing texts from Samsung Messages over to a new home. Samsung recommends moving to Google MessagesIn the company's original announcement, Samsung strongly suggested that Samsung Messages users move to Google Messages instead. The company even took the opportunity to tout the advantages of Google Messages over Samsung Messages, including RCS support, AI features, cross-device functionality, and enhanced security features. It is a bit odd to see Samsung pushing a different company's product like this, but it makes sense: For one, Google develops Android, but Samsung has already distanced itself from its messaging app. If it had to plug one app, it might as well be Google's default. Perhaps the biggest perk of choosing Google Messages, however, is that your existing Samsung Messages chats come along with the move. If you care about preserving your message history, this might be the simplest path forward—though it means going all-in on yet another Google product. If you tend to avoid Google apps and services, you have other options, but they might not be as convenient—especially if you're looking to move your messages. How to move from Samsung Messages to Google MessagesAccording to Samsung, the move is relatively straightforward. First, make sure you have Google Messages installed on your Galaxy. When you open it, the app will ask you to make it your default messaging app. To do so, hit "Set default SMS app," choose "Google Messages," then tap "Set as default." Now that the app is your default choice, your Galaxy should automatically begin moving texts from Samsung Messages to Google Messages. Samsung warns that this process can take some time, especially if you have a long message history saved on your device, so don't be alarmed if your messages don't transfer all at once. Google Messages alternatives exist, but may not be as convenientGoogle Messages is far from the only messaging app on Android. You can find any number of simple or feature-filled options on the Play Store, including, of course, Signal, Telegram, and WhatsApp. For basic SMS messaging, however, a few names frequently pop up: Textra, Chomp SMS, and Handcent SMS. These apps should offer a similar basic messaging experience to Samsung Messages, without having to jump to another Google app. Setting any of these as your default messaging app is as simple as the steps for Google Messages above. However, it's not clear if doing so will transfer your message history in the same way. While Google Messages supports an easy transfer, you might not have the same experience setting Textra or Handcent as your default app. As such, you may need to look into third-party backup and transfer services if you want your message history to move apps for certain. By far, SMS Backup & Restore is the app I see most recommended amongst Android users here. While Phone Arena's Aman Kumar found it helped when transferring messages on his Android device, the focus was on a scenario where Google Messages didn't migrate the messages on its own. It should be possible to back up your Samsung Messages with this app and import them to another messaging app, but it isn't as obvious as it should be. View the full article
-
The longer the Strait of Hormuz blockade continues, the more likely a crisis-like adjustment in rich economies becomesView the full article
-
Oil jumps to $114 as tensions flare up in Middle EastView the full article
-
In December 2025, the biggest battery maker in the world, CATL, started what it calls the world’s first large-scale deployment of robots in its Luoyang, China factory. Last week, the State Grid Corporation of China began its $1 billion 2026 plan to deploy a humanoid army to maintain its grid autonomously. And just a few days ago, at the other side of the East China Sea, Japan Airlines announced the beginning of a test program of humanoids to carry luggage at airports. While we listen to Elon Musk tell us how magical and civilization-changing Tesla’s Optimus robots are, Asian countries are light-years ahead of us, deploying humanoids to do their bidding in real-life scenarios. There are two main reasons humanoids are happening much faster in Asia than in the U.S. or Europe. One of the reasons is purely economic: China is always looking at cost optimization. For years, industrial robotics has been a main driver in the country’s quest to reduce manufacturing prices and times. China’s dark factories, where fully automated robots churn out devices with the lights off because they don’t need them, are famous. “China is by far the world’s largest robotics market in 2024. It represents 54% of global deployments. The latest figures show that 295,000 industrial robots have been installed in the country, the highest annual total on record,” says the International Federation of Robotics in its World Robotics 2025 Report. So humanoids—bipeds or wheeled—are the logical next step. This is especially true as AI models begin to understand the world, and companies realize that a huge market awaits for general and specialized tasks that only human-like robots can properly do. The other reason is demographic: Japan’s population is quickly getting older, while in China, fewer people want to do hard and dangerous work like maintaining power grids. Japan became the world’s first “super-aged” society back in 2006, and as of 2026, over 30% of its population is aged 65 or older. The country’s total population is currently shrinking by nearly one million people per year. The sheer lack of young, able-bodied workers makes manual labor roles in logistics and aviation impossible to fill, forcing the country into reliance on machines. In China, the issue is slightly different, but equally pressing. While China has a massive population, its traditional blue-collar workforce is aging out. An estimated 300 million migrant workers—the people who physically built the country’s modern infrastructure and power grids over the last four decades—are now approaching retirement age. Younger generations are simply not stepping in to replace them in highly dangerous roles, like maintaining live 10,000-volt power lines. Facing a critical workforce shortage in the trades, China has chosen to deploy robotic electricians that operate 50% faster than human crews with a 98% success rate. Business and political drive At the same time, China and Japan have the means and the willpower to make this happen. The former controls the majority of the global supply chain to make humanoids—and robots of any kind—in huge quantities. Meanwhile, the U.S. can’t even produce magnets—a key component to robotics—without reliance on its rival. Japan, with its aging population in mind, has been working on robotics for years and now is making the jump from small deployments in hospital facilities to large-scale industrial deployment of humanoids. The country’s move into aviation logistics is born of sheer demographic desperation. According to The Guardian, the country will require more than 6.5 million foreign workers by 2040 just to hit its economic growth targets, but it faces intense political pressure to limit immigration. The solution is mechanical. Starting this May, a 130-centimeter-tall humanoid manufactured by the Chinese company Unitree will begin hauling passenger luggage and cargo on the tarmac of Haneda airport, a massive hub that handles over 60 million passengers annually. These units can operate continuously for two to three hours. Tomohiro Uchida, President of GMO AI and Robotics—which is collaborating on the pilot alongside JAL Ground Service—says that while airports look highly automated, “their back-end operations still rely heavily on human labor and face serious labor shortages.” While Japan is testing the waters to plug a gaping demographic hole, China is diving headfirst into mass industrialization. The State Grid Corporation of China has allocated 6.8 billion yuan (roughly $1 billion) to purchase approximately 8,500 robots this year alone. While that order includes 5,000 quadruped robot dogs to examine power lines in mountainous terrain, they are actively introducing humanoid and dual-arm models to execute dangerous maintenance duties on the ultra-high-voltage grid. Across all Chinese utility companies, spending on AI robotics is projected to exceed 10 billion yuan in 2026. The growth of embodied AI is about to explode in the Asian country—with total output in China reaching 2.1 million units by 2030—says Zheshang Securities. It’s only the beginning of the future, as the financial firm describes: “We believe 2026 will be the year humanoid robots achieve mass production. The future has arrived.” A robotic army marches towards automation That future is already clocking in at CATL’s Zhongzhou facility. Operating via a Vision-Language-Action AI model, robotics company Spirit AI’s Xiaomo humanoids visually identify shifted plug positions and instantaneously correct their grip to connect high-voltage battery components with a 99% success rate. Not only is this a dangerous task for human operators—who obviously don’t want to get electrocuted—but, because they don’t take breaks, a single humanoid handles a daily workload three times larger than a human employee. CATL is not alone in this industrial shift. A massive ecosystem of highly funded, specialized manufacturers is fueling these deployments. Unitree Robotics—the Hangzhou-based firm supplying Japan Airlines—recently completed its Series C funding, pushing its valuation past $1.6 billion. The company recorded over 5,500 shipments in 2025 and recently filed for a $610 million IPO on the Shanghai Stock Exchange to aggressively scale manufacturing. AgiBot is another purely-robotic play in China. Founded in 2023, the Shanghai-based company shipped over 5,100 humanoid robots in 2025 alone, securing the number one spot globally in both humanoid shipment volume and market share. By early April 2026, AgiBot officially rolled its 10,000th unit off the production line, cementing its position as the undisputed global leader in commercial humanoid manufacturing. For context, American counterparts like Figure AI, Agility Robotics, and Tesla shipped a fraction of the Chinese humanoid industry numbers. Same with Ubtech Robotics, which has introduced its Walker S2 industrial humanoid. It features an autonomous battery swapping system that allows it to operate continuously. Ubtech reported a staggering 2,200 percent surge in full-size humanoid robot revenue in 2025, successfully hitting its target of delivering 500 units by year’s end, and actively placing hundreds on the factory floors of BYD, Geely, and Foxconn. Ubtech has amassed cumulative orders exceeding 1.4 billion yuan and is currently scaling its manufacturing capacity with a target of 10,000 units annually. But the humanoid push doesn’t stop at these specialized robotic startups. Other tech and car brands are quickly pivoting to embodied AI as well. Xpeng just broke ground in the first quarter of 2026 on a 1.2 million-square-foot production facility in Guangzhou that will build its viral Iron humanoid robots by year’s end. Xiaomi is embracing robotics, too. Its CEO Lei Jun recently announced that the company’s humanoids have successfully completed autonomous trial operations on their EV assembly lines, maintaining a 90% success rate when installing self-tapping nuts on car floors within a 76-second window. Xiaomi plans to deploy these machines in large numbers across its production facilities by 2030. Supply chain and more China is clearly ahead and that’s because, in addition to having the political and economic will, they have the manufacturing power to make it happen. The same reason why American giants like Tesla will struggle to compete with this robotic army that Beijing is pushing full steam ahead: China fully dominates the supply chain. The center of which is in Shenzhen, a hyper-concentrated manufacturing hub that acts as the world’s primary robotics forge. By the end of 2025, Shenzhen manufactured nearly 8 million service robots—a broad category that includes logistics bots, cleaners, and the foundation for more complex humanoids. This staggering volume accounted for 43% of China’s total national output, pushing the city’s robotics industry value past $35.4 billion. Yang Qian, the chief operating officer of X Square Robot, says that this local supply chain advantage means “custom parts can be delivered in days, compared with months overseas.” He adds that iteration costs in Shenzhen are “only a tenth of those abroad.” American manufacturers are currently choking on their lack of a domestic supply chain. It’s not only that the Chinese have more experience and manufacturing power. You only have to focus on one of many critical bottlenecks: rare-earth magnets. A single Tesla Optimus humanoid requires up to eight pounds of Neodymium-Iron-Boron magnets to power its 40-plus servo motors. When Beijing halted exports of these materials on April 4, 2025—after The President started his tariff war against China—Optimus production hit a brick wall. Anonymous sources within the Optimus supply chain confirmed to AInvest that Tesla capped its inventory at roughly 1,000 units, stating that with the procurement freeze, Musk’s goal of producing 5,000 units this year is “now largely unattainable.” In a recent podcast recorded at Nvidia’s GTC event in San Jose, CEO Jensen Huang warned that the U.S. robotics industry will be forced to rely on China. “I think China is formidable,” Huang said. “The reason for that is because their microelectronics, motors, rare earth and magnets—which are foundational to robotics—are the world’s best. So in a lot of ways, our robotics industry relies deeply on their ecosystem and their supply chain.” Huang added that, while the U.S. practically invented robotics, then the country got “tired and exhausted” waiting for the necessary AI “brain” technology to emerge, allowing China to seize the manufacturing advantage. The problem is that, while the U.S. government is frantically trying to prop up a domestic magnet supply chain through companies like MP Materials, China is also advancing in the AI models that humanoid robots use, matching and even surpassing its American counterparts. If Washington and Silicon Valley don’t spend more money in becoming independent from China as fast as possible, America will be stuck watching Elon Musk’s home videos while China actually builds the robotic workforce of the future to solve real problems, today. View the full article
-
Willie Simon stood outside the Memphis motel where Rev. Martin Luther King, Jr. was assassinated in 1968, now a museum dedicated to the Civil Rights Movement. Days after the U.S. Supreme Court gutted a key provision of the Voting Rights Act, Simon feared what the decision would mean not just for Black Americans like himself but an entire country where the political guardrails seem to be coming apart. Simon, who leads the Shelby County Democratic Party in Tennessee, said the court’s conservative majority set a precedent that if you’re “not in the in-crowd group, they can just erase us.” By weakening a requirement that states draw congressional districts in a way that gives minorities an opportunity to control their own fate, the court escalated the nationwide redistricting war that has seen Democrats and Republicans casting aside decades of tradition in hopes of gaining an edge over the competition. New sessions are scheduled to begin this week in two Republican-controlled states to eliminate U.S. House districts represented by Democrats, and there’s more on the horizon. It’s the latest example of how the American democratic experiment has been pushed to the breaking point in the decade since Donald The President rose to power. Extreme rhetoric has become commonplace. There’s been a spike in political violence and a rash of assassinations. Five years after the Jan. 6 attack on the U.S. Capitol, The President’s allies are trying to harness the same falsehoods about voter fraud to reshape elections. The rules and norms that once helped smooth over an unruly country’s vast differences have given way to a race for power at all costs. “I’ve never subscribed to the idea we’re in a civil war, but the gerrymandering wars and the recent decision from the Supreme Court do not make the United States more united,” said Matt Dallek, a political scientist at George Washington University. “It speeds up the hyperpartisan force and atmosphere that people feel on both sides.” ‘No more rule of law’ The President ignited the conflict over redistricting last year by urging Republicans to redraw congressional maps to reduce the likelihood that his party loses the U.S. House in the November midterm elections. It was an unusual step, since redistricting normally only takes place after the once-a-decade census to accommodate population shifts. But in 2019 the Supreme Court ruled federal courts cannot prevent partisan gerrymandering, and The President saw a chance to push the limits. Once Republican-led states like Texas started shifting district lines, Democratic-led states like California countered. The fight was heading for a draw until the Supreme Court’s conservative majority issued its long-awaited decision in Louisiana v. Callais. The court weakened the last remaining national impediment to gerrymandering — the Voting Rights Act’s requirement that, in places where white people and outnumbered racial minorities vote differently, districts be drawn to give those minorities a chance to elect representatives they prefer. The ruling opened a new set of political floodgates. Republicans in Tennessee plan to erase the only Democratic congressional district, which is majority Black and centered in Memphis, by splitting it up among more conservative suburban and rural white communities. More than a dozen other majority-minority districts, mainly in the South, could face the same fate. Louisiana moved to postpone its congressional primaries, set for May 16, to have a chance to redraw two majority-Black Democratic seats it was required to maintain before the recent ruling. Alabama is trying to get the Supreme Court to let it redraw its two majority-Black seats. “We should demand that State Legislatures do what the Supreme Court says must be done,” The President wrote on social media on Sunday. “That is more important than administrative convenience.” He said Republicans could gain 20 seats through redistricting. Democrats have threatened to retaliate by splitting up conservative bastions in states like New York and Illinois, which would reallocate Republican voters to more liberal, urban districts. With fewer limits — either legal or self-imposed — people expect the issue to become a perpetual race to squeeze every possible advantage out of legislative maps. “It’s hard to know where it ends,” said Rick Hasen, a law professor at UCLA. Partisans gleefully shared color-coded maps of California with all 54 House seats drawn for Democrats, or southern states with only a couple of blue districts. Most agreed that eventually it will be very hard for Democrats to get elected to the House in any Republican-run state, even if there are large swaths of blue-leaning terrain, and vice versa for Republicans in Democratic-run states. That seems un-American, said Jonathan Cervas, a political scientist at Carnegie Mellon who’s redrawn maps on behalf of judges reviewing redistricting litigation. The country’s system, he said, “was founded on this idea that it’s majority rule with minority rights.” “There is no more rule of law in redistricting,” Cervas said. “There have to be some constraints, somewhere. Otherwise we don’t really have elections.” Politicians’ best tool to game elections The arcane art of drawing legislative lines is the most powerful tool that politicians have for gaming elections. They can make districts an almost guaranteed win for their side by drawing lines that scoop up a majority of their voters and just enough of the opposition’s supporters to ensure the other party cannot win that seat or the one next door, either. Lawmakers have used the trick since the country’s founding. Democratic gerrymanders helped the party hold onto the House through the Reagan revolution. After the 2010 midterms, Republican majorities in state legislatures allowed the GOP to draw districts to lock up control of the House even during President Barack Obama’s reelection two years later. However, that didn’t prevent the “blue wave” in 2018, during The President’s first term, when Democrats retook the House. It was a reminder that even the most partisan gerrymanders may stifle shifts in public opinion but eventually crack as political tides turn. “When you try to get every last ounce of blood from the stone you can end up shooting yourself in the foot,” said Michael Li of the liberal Brennan Center for Justice in New York. Political coalitions also change, and voters that a party thinks will be reliable can switch sides. That’s what’s happened in the The President era, as Democrats have expanded their support among wealthier and suburban voters and Republicans among Blacks and Latinos. Although Republicans won’t be able to exploit the full force of the Supreme Court ruling until after the November midterms, it will be challenging for Democrats to find enough seats to counter those gains. Sean Trende, a political analyst who has drawn maps for Republicans, agreed that the court decision is likely to lead to partisan gerrymandering run amok. He said it’s been hard to find neutral arbiters to rein in politicians who draw lines to benefit themselves. The coming storm, Trende said, will be more of a symptom of polarization than its root cause. “All our institutions are broken. We don’t speak a common political language,” Trende said. “This is what you get.” —Nicholas Riccardi, Associated Press View the full article
-
World Liberty Financial accusation against Justin Sun comes after he sues firm over alleged fraudView the full article
-
When considering the average tax rate for corporations, it’s crucial to acknowledge that the current rate stands at 21 percent, a significant drop from the historical average of nearly 32 percent. This decline reflects various fiscal policy changes over the years, impacting large firms differently, as their effective tax rate hovers around 16 percent. Comprehending these nuances, along with the role of pass-through entities, can illuminate broader implications for corporate taxation and business strategies. What might these trends suggest for future reforms? Key Takeaways The current U.S. corporate tax rate is 21 percent on net income. The historical average corporate tax rate from 1909 to 2025 is approximately 31.99 percent. In 2022, the average effective tax rate for firms over $100 million was 16.0 percent. U.S. corporate tax revenues account for about 1.3 percent of GDP, lower than many OECD countries. Pass-through entities report around 70% of business income, impacting overall corporate tax revenues. Overview of Corporate Tax Rates Corporate tax rates play a crucial role in shaping the financial environment for businesses in the United States. Currently, the corporate tax rate in the United States stands at 21 percent, which applies to a corporation’s net income. Historically, the average tax rate for corporations from 1909 to 2025 is around 31.99 percent, with significant fluctuations over the decades. For instance, the highest recorded corporate tax rate was 52.80 percent in 1968, whereas the lowest was just 1.00 percent in 1910. In 2022, corporations with net incomes exceeding $100 million reported an average effective tax rate of 16.0 percent. Compared to other wealthy countries, the U.S. corporate tax revenues accounted for approximately 1.3 percent of GDP, indicating a lower tax burden overall. Historical Trends in Corporate Tax Rates Although many factors influence corporate tax rates, an extensive look at historical trends reveals a significant evolution in the U.S. tax environment over the last century. The average corporate tax rate in the U.S. has been approximately 31.99 percent since 1909, with notable fluctuations. In 1968, the highest recorded rate reached 52.80 percent, whereas the lowest was just 1.00 percent in 1910. Since the late 1960s, federal corporate tax rates have typically declined, currently sitting at 21 percent. This downward trend reflects broader fiscal policy changes and aligns with data from the tax rates by president chart. Comprehending these historical trends can help you grasp the shifting terrain of corporate tax by nation and its implications on business behavior. Comparison of U.S. Corporate Tax Rates With Other Countries When you compare U.S. corporate tax rates to those in other wealthy OECD countries, you’ll find some notable differences. Whereas the U.S. has a federal statutory tax rate of 21 percent, many OECD countries have average rates around 13 percent, which can greatly affect overall business costs. Moreover, comprehending the impact of state and local taxes, in addition to the distinction between effective and statutory rates, is essential for grasping the full picture of corporate taxation in the U.S. U.S. vs. OECD Rates In comparing U.S. corporate tax rates with those of other OECD countries, it’s important to recognize that the U.S. federal statutory rate stands at 21 percent, which aligns closely with the average rates of 13 wealthy OECD nations. Nevertheless, the effective tax rate for U.S. firms earning over $100 million is around 16.0 percent, illustrating a disparity between statutory and actual tax burdens. Here’s a quick comparison of statutory rates: Country Statutory Tax Rate United States 21% Germany 30% France 26.5% Japan 30.62% Despite the U.S. rate being competitive, corporate tax revenues account for only 1.3 percent of GDP, lower than many peers. State and Local Taxes Grasping the impact of state and local taxes on the overall corporate tax burden is vital for businesses operating in the United States. During the federal statutory corporate tax rate is set at 21 percent, adding state and local taxes can greatly increase the total tax burden. The average top state rate stands around 6.5 percent, pushing the effective tax rate higher for many corporations. In comparison, countries like Ireland attract multinational corporations with a much lower corporate tax rate of 12.5 percent. As a result, U.S. corporate tax revenues, which were only 1.3 percent of GDP in 2022, reflect a decline relative to similarly wealthy countries, emphasizing the importance of considering state and local taxes in overall tax strategy. Effective vs. Statutory Rates Even though the statutory corporate tax rate in the U.S. is set at 21%, comprehending the effective tax rate reveals a more nuanced picture. For large firms, the average effective tax rate was 16% in 2022, showing significant differences because of deductions and credits. In comparison, countries like Ireland and Hungary have lower rates at 12.5% and 9%, respectively. Meanwhile, the average effective rate across OECD countries was about 23.5% in 2021. This data highlights that U.S. corporate taxes are relatively low among developed nations. Country Statutory Rate U.S. 21% Ireland 12.5% Hungary 9% OECD Avg. 23.5% Large U.S. Firms 16% Impact of Pass-Through Entities on Corporate Tax Revenues As the popularity of pass-through entities, like S corporations and partnerships, grows, the scope of corporate tax revenues is undergoing significant changes. Today, about 70% of business income in the U.S. is reported by these entities, which means more income is taxed at individual rates instead of the corporate tax rate. This shift has led to a substantial reduction in overall corporate tax revenues, as pass-through entities completely avoid the corporate income tax. For instance, in 2022, firms earning over $100 million had an average effective tax rate of just 16.0%, well below the statutory corporate tax rate of 21%. This trend highlights the increasing influence of pass-through entities on the framework of corporate taxation, warranting careful consideration. State and Local Corporate Tax Rates Corporate tax rates at the state and local levels play a significant role in shaping business environments across the United States. The average top state corporate income tax rate is 6.5%, with New Jersey at 11.5% and North Carolina at a low 2.25%. States like South Dakota and Wyoming attract businesses by not levying any corporate income tax. Here’s a summary of some notable state corporate tax rates: State Corporate Tax Rate New Jersey 11.5% Nebraska 5.2% Louisiana 5.5% North Carolina 2.25% South Dakota No Tax Twelve states, including Arizona and Arkansas, as well maintain rates at or below 5%, impacting profitability for businesses. Policy Options for Reforming Corporate Taxation To effectively address the challenges faced by the current corporate tax system, lawmakers are considering a range of policy options aimed at reforming corporate taxation. One approach involves broadening the tax base and eliminating certain tax expenditures that disproportionately benefit a few corporations. Adjusting the corporate tax rate could improve fairness and efficiency, ensuring that all companies contribute a fair share to federal revenues. Lawmakers are additionally examining the implementation of a minimum tax on large corporations, targeting those with substantial profits that currently pay low taxes. Implications of Corporate Tax Rates on Business Decisions Comprehending how corporate tax rates affect your business decisions is essential for effective financial management. With the current federal rate at 21 percent and an average effective rate of 16.0 percent for large firms, you might need to implement tax liability management strategies to optimize profitability. Furthermore, fluctuations in these rates can influence your choices regarding investment, growth opportunities, and whether to reinvest profits or distribute dividends. Tax Liability Management Strategies As the federal corporate tax rate in the U.S. stands at 21%, businesses must navigate a complex environment of tax liability management strategies to optimize their financial performance. In order to minimize liabilities, corporations often employ tax planning techniques, utilizing deductions and credits that can lead to effective rates as low as 16.0% for firms earning over $100 million in 2022. Furthermore, with the rise of pass-through entities, companies need to evaluate their business structures carefully to achieve better tax outcomes. Changes in tax legislation, such as the Corporate Alternative Minimum Tax (CAMT) at 15%, further require businesses to adapt their strategies. Investment and Growth Decisions The implications of corporate tax rates on investment and growth decisions are significant, as they directly influence how businesses allocate their resources. With the federal corporate tax rate currently at 21 percent, companies often find themselves with higher after-tax profits compared to the historical average of 31.99 percent. This lower rate may encourage reinvestment in expansion or research and development. Furthermore, firms earning over $100 million faced an effective tax rate of about 16.0 percent in 2022, which can drive mergers and acquisitions as businesses aim to optimize tax liabilities. In addition, the rise of pass-through entities has shifted more income to individual tax rates, prompting companies to reconsider their strategic planning to improve overall profitability and growth potential. Frequently Asked Questions What Is the Average Corporate Tax Rate? The average corporate tax rate in the U.S. is currently 21 percent, effective until at least December 2025. Nevertheless, large corporations often pay a lower effective rate, around 16 percent, as a result of various deductions and credits in the tax code. Historically, rates have fluctuated markedly, peaking at 52.80 percent in 1968. Today, corporate tax revenues account for about 1.3 percent of GDP, reflecting a long-term decline in tax contributions relative to the economy. Why Is the Corporate Tax Rate 21%? The corporate tax rate is 21% primarily because of the Tax Cuts and Jobs Act enacted in December 2017. This law aimed to boost U.S. business competitiveness globally by lowering the previous rate of 35%. The 21% rate aligns more closely with those of other developed nations, making it easier for U.S. corporations to operate effectively in the international market. Moreover, various deductions and credits can influence the effective tax rate for companies. Why Is My Blended Tax Rate 37%? Your blended tax rate is 37% since it combines the corporate tax rate of 21% with other taxes you may owe, such as personal income taxes and state or local taxes. If your business is structured as a pass-through entity, your profits get taxed at individual rates, potentially reaching the highest personal tax rate of 37%. Furthermore, if applicable, the Corporate Alternative Minimum Tax adds a minimum tax burden of 15% on adjusted income. Are C Corps Taxed at 21%? Yes, C Corporations are typically taxed at a federal statutory rate of 21% on their net income. This rate was established by the Tax Cuts and Jobs Act in 2017 and is effective until at least December 2025. On the other hand, large corporations with net incomes exceeding $100 million may experience an effective tax rate of about 16% because of deductions and credits. Furthermore, certain corporations might face a Corporate Alternative Minimum Tax starting in 2023. Conclusion In conclusion, grasping corporate tax rates is vital for businesses and policymakers alike. The current U.S. statutory rate of 21 percent contrasts with an effective rate of 16 percent for large firms, reflecting complex tax strategies and the impact of pass-through entities. Historical trends show significant declines in tax rates over the last century. As debates on reform continue, the implications of these rates on business decisions and revenue generation remain critical for economic planning and growth. Image via Google Gemini This article, "Average Tax Rate for Corporations?" was first published on Small Business Trends View the full article