Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
Every few months, we find ourselves circling back to the same question. What skills will matter next? Every time, the answers feel urgent, confident, and somehow incomplete. A new technology dominates the conversation. Or there’s a new ‘essential’ capability. Organizations rush to respond, often without much confidence that the target will stay still long enough to hit. The reality is that the future of work is no longer unfolding in neat stages. It’s arriving in overlapping waves. Technological change, geopolitical instability, climate pressure, demographic shifts, and changing expectations about work are all happening at once. In this kind of environment, predicting specific jobs or technical skills five or ten years out is increasingly unrealistic. But that doesn’t mean leaders are flying blind. If we stop asking “what jobs are coming?” and instead ask “what helps people stay effective when things keep changing?”, a clearer and more useful picture emerges. Across industries and regions, what holds up is not a single skill set, but a handful of human capabilities that remain relevant, even as the context around them keeps shifting. Thinking clearly when the pressure is on One of the most valuable skills is the ability to think clearly under pressure. As automation accelerates and information becomes faster and cheaper, judgment becomes more important, not less. The World Economic Forum’s Future of Jobs research shows that analytical and creative thinking remain the most in‑demand core skills globally, even as technology adoption increases. The organizations that navigate uncertainty well are not the ones with the most data. It’s those with people who can interpret it, challenge assumptions, and make sound decisions when there isn’t an obvious answer. This kind of thinking is practical rather than theoretical. It shows up in people who can cut through noise, identify what matters, and explain complex issues in plain language. It also shows up in leaders who resist the pull of constant urgency and take just enough time to make the right decisions. Creativity beyond automation This kind of thinking is linked to creativity. And we’re not necessarily talking about the artistic sense here, but also the ability to see alternatives. When a specific approach no longer works, someone needs to imagine a different way forward. According to a McKinsey report, capabilities that allow people to add value beyond what automated systems can do—like higher‑order cognitive and judgment skills—are becoming more critical as AI scales across industries. Learning faster than the change around you Learning agility is another capability that stands out. The shelf life of knowledge is shrinking. What you mastered five years ago might still be relevant, but it won’t be enough. According to the World Economic Forum, employers expect roughly 40 to 45 per cent of workers’ core skills to change within a five‑year window. The OECD also emphasizes that resilience in both economies and organisations depends on the ability to continuously build and apply new skills. The workplace of the future will reward willingness and ability to keep learning. Curious people adapt faster. People who are comfortable being beginners cope better with change. Organisations that normalize learning as part of everyday work—rather than as a separate activity—move more easily with the market. Using AI with confidence and judgment This becomes particularly important as AI becomes embedded in more roles. Globally, there is strong demand from employees to build confidence in using AI tools. Linkedin’s 2024 Workplace Learning Report found that four in five people want to learn how to use AI in their job. But the real differentiator is not tool use alone. It is knowing when to rely on technology, when to question it, and when human judgment should override what the system produces. As technology takes on more routine and analytical tasks, the human side of work becomes more visible, not less. Skills like listening, collaboration, influence, and building trust grow in importance. In global organisations, this plays out across cultures, time zones, and lived experiences. The ability to work effectively with people who see the world differently is no longer a leadership nice‑to‑have. It is operationally essential. What this means for leaders Where does this leave leaders? It’s impossible to predict the future, so the most responsible strategy is investing in capabilities that travel well. Skills that help people think well, learn quickly, work constructively with others, and use technology with confidence and care are far more durable than any narrow technical credential. We may not know exactly what the world of work will look like in ten years’ time. But we do know this: complexity is not going away. And the organizations that thrive will be those that equip their people to stay effective even when the world of work keeps changing. View the full article
-
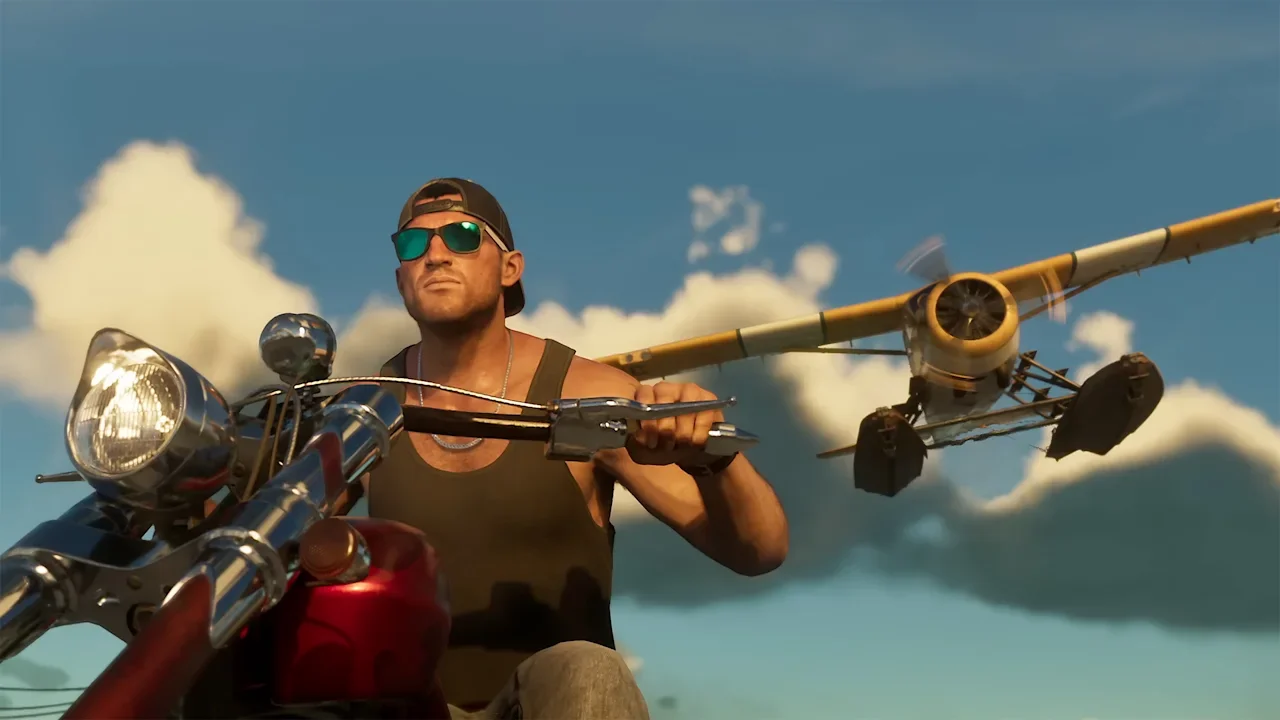
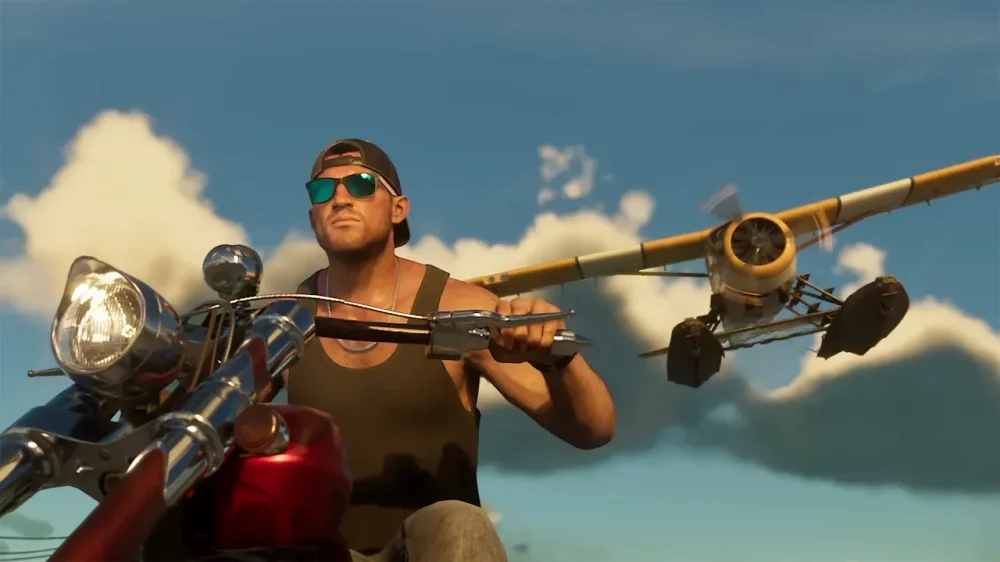
Consolidation is all the rage in the video game world these days. In the past year, Ubisoft created a new gaming subsidiary with Chinese tech giant Tencent, while Electronic Arts announced a $55 billion deal led by Saudi Arabia’s Public Investment Fund that will take the company private. An industry that, just a decade ago, included more than a dozen publicly traded game makers now has only a handful left. Take-Two Interactive Software has managed to remain independent while rivals, including Activision-Blizzard and EA, have been absorbed. And as it continues digesting its 2022 acquisition of Zynga, CEO Strauss Zelnick says the company is already eyeing its next acquisition target. However, he says, that could still be a couple of years away. “I think for the next couple of years, our story will be one of organic growth, but then if we do things right, we’d be in a position to [do] something inorganic as well,” he tells Fast Company. “But would we be interested in growing? Of course.” As expected, Zelnick declined to name specific targets, but acknowledged the company already has some in mind. “We have our eye on a couple opportunities, but . . . they may not be around at that time,” he says. “And there are no guarantees. But I think there still would be some opportunity, no matter what.” What he did concede is that whenever Take-Two next opens its checkbook, it will likely be focused on app shopping. Mobile gaming now accounts for half of the company’s revenue. “There are a couple—I’m not going to name names—but there are a couple in the mobile space we’re very impressed with. Less so on the console side,” he says. Organic growth Part of the reason for any acquisition delay may simply be that Take-Two will be fully occupied over the next year or two with the launch of Grand Theft Auto VI. The latest installment in one of entertainment’s most lucrative franchises is scheduled for release on Nov. 19. At the recent iicon conference, an invitation-only summit for video game industry leaders, Zelnick said marketing for the game would begin “soon,” suggesting further delays are unlikely. Expectations are ludicrously high. Its predecessor, released in 2013, has sold more than 225 million copies and generated nearly $10 billion in revenue for Take-Two. It was still the industry’s 11th best-selling game in March, according to Circana, an astonishing feat for a title more than a decade old. Most games are fortunate to remain on sales charts for a few months. Few last beyond a year. New challenges Of course, there is always the possibility that someone could attempt to buy Take-Two itself. Zelnick acknowledges that, but downplays the likelihood, pointing to the company’s dramatic growth since he took over 18 years ago. “We’ve always been at risk of someone wanting to own us because we’re public and not controlled,” he says. “We’re here for the shareholders. The best protection in terms of remaining independent is doing a great job. When we bought the company, the stock was $11. Today it’s $213. And if we continue to create value in the company, there would be no reason for someone to take it over and it would be hard for them to take it over.” Part of the challenge in sustaining those financials, even with GTA VI looming, is adapting to shifting player habits. Mobile continues to expand, while console gaming no longer dominates the way it once did. And amid speculation that GTA VI could carry a significantly higher price tag than most major releases, Take-Two will need to stay especially attuned to player behavior. “The truth is, for the console side of our business, it’s very clear that business is opening up,” Zelnick says. “PC is becoming a more and more important format for what were previously console releases, with a little PC on the side. And now it’s become like PC is becoming the main course. That’s not lost on us at all.” Despite that shift, there are still no plans to launch GTA VI on PC simultaneously with its console debut. It will eventually arrive on the platform, but there is still no timeline, nor much explanation for the staggered release. “All of our major titles ultimately make it to PC,” says Zelnick. “In the case of Grand Theft Auto VI, we’re obviously only launching on two consoles, so … there are clearly business reasons to do that.” View the full article
-
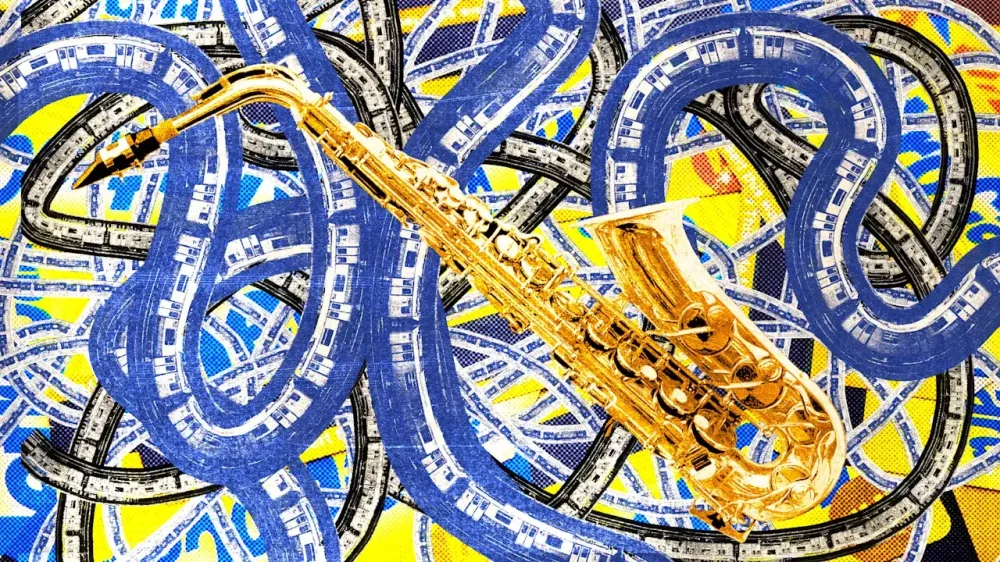
New York City is notoriously loud. Cabs honking everywhere, thousands of people flocking to the streets at all hours, and cars blasting music for all to hear. But while some of us hear only noise, others hear music. Joshua Wolk is one of those people. The designer is the creative mind behind Train Jazz, which turns the rhythm of NYC’s subway into an interactive musical website. Train Jazz started when Wolk came across New York City’s open repository of transit data. He first created a soundless live map of the city’s transit. “It felt unfinished. I soon realized that music was that missing piece,” he tells Fast Company. Train Jazz Wolk ended up assigning an instrument to every train line across the various boroughs. On the website, users see a simplified map of the Metropolitan Transportation Authority (MTA) subway lines, showing the active trains running in real time. Every note is played based on where a train is along its route, coming together as a sonic tapestry of the city’s movement. When playing around with the website, users can hover over a panel displaying the symbols for each line. The number of trains running for that specific line then appear, alongside more information regarding the line’s history and the instrument it’s been assigned. A sound for every train line The specific sounds and instrument associated with each line are influenced by Wolk’s research on each line. For instance, at the time of publishing, the F line had 51 trains running in the city. “The F is famously unreliable—its sound wobbles like a player who can’t hold a pitch.” Or take the Z train, which plays soft maracas only during rush hour, when the train runs. The Z’s sound has half the strength of its other brown line counterpart, the J, which routinely runs throughout the entire day. “The harmony moves through a slow chorus. A note is placed precisely where the train happens to be along its route. Rush hour fills the band with held tones; at 3 a.m. the silences grow longer,” the site reads. “Whatever is playing now has not played before and will not play again.” The map is updated every 15 seconds, with the website fetching every train’s coordinates from MTA’s API, Wolk explains. The project also reacts to location, with trains near the user growing louder than the rest. “You are listening to a portrait of where you stand, played by the city you are standing in,” the site adds. Though the sounds can be discordant depending on which trains are running, it’s free-form and beautiful in the way that only jazz is. “My rule was that Train Jazz wasn’t complete until it was something I could listen to for three hours straight,” he says. “That required putting a lot of care into how the notes float through the chord progressions.” Ultimately, Wolk wants to take his virtual project to the real world. “The internet is cool, but my dream is to give Train Jazz a physical home in New York: A wall, a bus stop, maybe even the MTA,” he says. View the full article
-
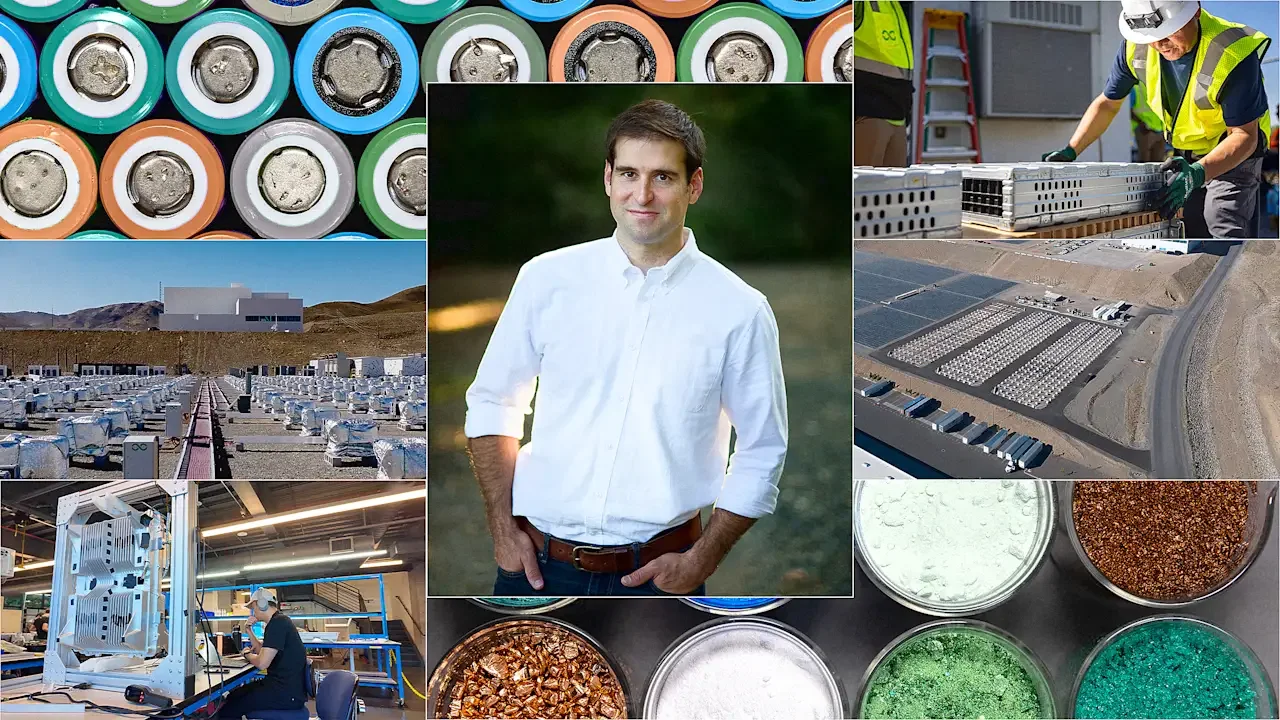
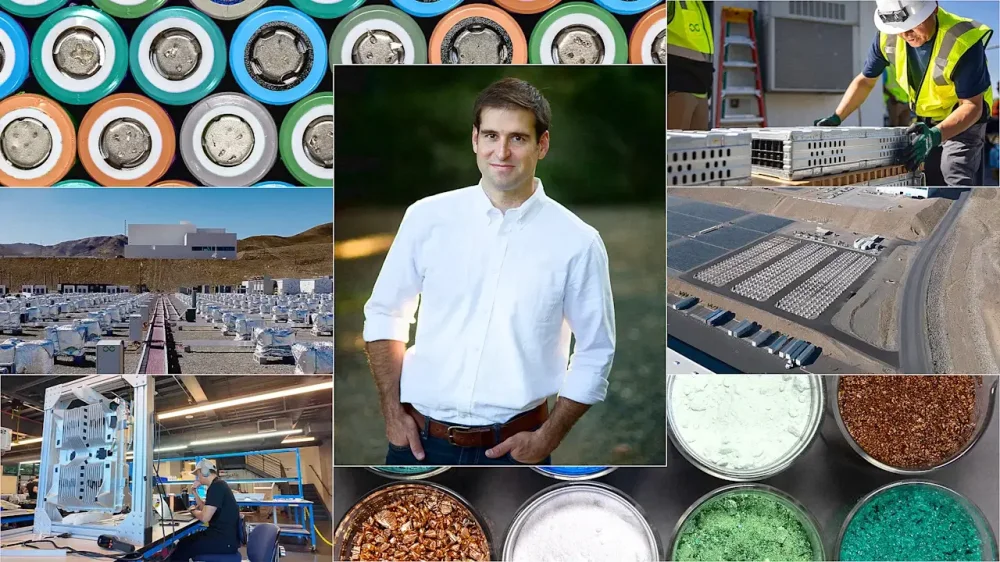
In the rolling hills near Reno, Nevada, in a field filled with solar panels, something unexpected is nestled into the landscape: a data center that isn’t blowing up its neighbors’ electric bills. In fact, the modular data center, built by Crusoe, essentially doesn’t rely on the electric grid at all. It runs on solar power and an unlikely source: hundreds of second-life EV batteries. At a time when data centers are driving up electricity demand—and facing intense political pushback over potential impacts on energy bills and the environment—the batteries offer a flexible way to add power without leaning harder on the grid. The astonishing setup is the handiwork of $6 billion startup Redwood Materials and its founder and CEO, JB Straubel, who’d seen a new opportunity in the flood of used EV batteries. His new vision for the electric grid was sparked by the sheer volume of electric vehicle batteries that still hold significant financial and functional value. This made a new and more lucrative business case feasible: Instead of manufacturing new batteries—an expensive process dependent on global supply chains—the team could use the energy left in secondhand EV batteries to make cheap, quickly deployed, cost-effective energy storage at a large enough scale that they could be used by electric utilities or in microgrids like the one in Nevada. “I have kind of an aversion to waste, personally. It pains the engineer in me to watch that happen, even though we certainly could recycle these packs, and we do every day,” Straubel continues. “That was the impetus for thinking that there must be a better way. There’s got to be some way we can take advantage of that and be one of the first to really scale it up.” The insight—presciently—came just as the energy storage market was poised to boom. In the U.S., a record 18.9 gigawatts of energy storage capacity were added last year, enough instantaneous power for roughly 15 million to 20 million homes. California recently set a record when 43% of the total power in the state was being supplied by batteries. And between now and early 2027, the U.S. Energy Information Administration expects battery storage to surge again by more than 50%, driven both by the need to store renewable energy and by surging demand for electricity due to the massive build-out of new data centers. As some data centers plan to rely on new gas plants that could collectively emit more pollution than some countries, Redwood’s low-cost batteries make renewable energy more viable. For data center developers, they offer a way to avoid long waits with utility companies—and to comply with the White House’s demand to bring their own power to new projects. For utilities, they’re a lower-cost method to store renewable energy. At factories, they can store grid power when it’s cheapest for later use. Redwood, flush with the batteries Straubel saw were coming, is on pace to deploy hundreds of megawatt hours of its systems, equivalent to the capacity of some power plants; next year, it aims to deploy gigawatt hours of storage. In a moment defined by grid bottlenecks and soaring demand, Redwood is rethinking how energy infrastructure can be built—and reused. For Straubel, the former CTO at Tesla, it’s just the latest unconventional bet in a career built on them. And it might just save the electric grid before it’s too late. Early adoption finds success Redwood’s strategy reflects Straubel’s history of pursuing ideas in energy and transportation that initially seemed early, but later became essential. As a student at Stanford University in the 1990s, where he designed his own major in energy systems engineering, he started building electric cars. Before his work at Tesla, he spent the early 2000s pitching investors on the idea of an electric sports car that used lithium-ion batteries to increase range. Most investors passed. Elon Musk, though, recognized the potential and brought Straubel into the company soon after he led the Series A investment in 2004. (A settlement from a lawsuit about Tesla’s early days allows five people, including Musk and Straubel, to call themselves “cofounders.”) As Tesla grew, Straubel was the internal champion for building the Supercharger network and the company’s own battery factories, not just the cars themselves. He later saw the opportunity to build energy storage for renewables using lithium-ion batteries, another idea that faced skepticism from the energy industry but soon became widely accepted. Cal Lankton, Redwood’s chief commercial officer, worked on charging infrastructure and energy sales at Tesla. At first, he says, utilities argued that grid-scale batteries wouldn’t work and that they wouldn’t use the technology. But over time, as solar and wind power created more need for energy storage, and the cost of batteries came down, they began deploying more. The technology proved itself on the grid and has now been widely adopted. In 2017, after Tesla reached the milestone of mass-producing the Model 3, Straubel began work on Redwood on the side, and officially left the automaker in 2019 to begin launching Redwood. (He was elected to Tesla’s board in 2023.) As with his electric car pitches, investors were initially skeptical about his new project. “[They were] maybe a little bit confused, in a way, like, ‘You’re starting a garbage company? Shouldn’t you be focused on one of these more obvious and trendy and sexy topics?’” Straubel says. Most investors thought the idea was too early: EVs were still in the early stages of acceptance, and most other automakers hadn’t yet scaled up production. So there was still a relatively small supply of batteries to recycle, and a relatively small demand for new materials to make more. But Straubel, after years immersed in battery technology at Tesla, had identified two major challenges. The critical materials used to make batteries were likely to become much harder to source in the future. And as the EV market expanded, there would eventually be a growing pile of battery waste. Recycling EV batteries could solve both problems, offering a new domestic supply of critical materials while keeping batteries out of landfills. He saw that there weren’t good solutions for recycling at the time; automakers didn’t have the bandwidth to focus on it. For the future he wanted to exist, he realized that he’d need to build it himself. Breakthrough Energy Ventures, the Bill Gates-backed VC fund, became one of the first investors, with $40 million in funding in 2020. Its team had already been thinking about future shortages of critical materials. A decade later, that scarcity has “played out the way we imagined,” says Carmichael Roberts, chief investment officer at the fund. The investors also saw that the company had the right leadership to take on the work. “Who would know more about where the future of battery materials was going than JB did at that moment?” Roberts says. Straubel also had the right qualities to be an entrepreneur. He was shrewd, with “that ability to assess a circumstance and then to be creative and capitalize,” Roberts says. “He wants to work on things that are unsolved, and when solved, are transformational. You can see it in him—he gravitates toward that. He’s a tremendous leader; his leadership style is literally by example. He’s the kind of person you would follow into the fire. He’s not a big ‘rah rah’ kind of guy. He’s still motivational and just [because of] his purpose, his intent and his depth.” Controlling the battery recycling market Nine years later, the company—now having raised $2.25 billion from investors ranging from Goldman Sachs to Nvidia’s NVentures—says that it is the largest recycler of lithium-ion batteries in the U.S. Some other startups in the young market have struggled, such as Li-Cycle, which filed for bankruptcy in 2025 as it dealt with higher-than-expected costs for building its recycling hub and slower-than-expected demand for materials for EVs, along with falling prices for battery materials that make recycling less profitable. Ascend Elements, another competitor, lost a Department of Energy grant shortly after The President took office and filed for bankruptcy last month. Some legacy players remain, like Cirba Solutions, a 35-year-old company that was the first to recycle lithium-ion batteries. But Redwood has taken over the market, and says that it now controls roughly 90% of lithium-ion battery recycling in the U.S. At a facility in Nevada and a new factory in South Carolina, Redwood produces as much lithium and cobalt from recycled batteries as the country’s largest mines extract from the ground. Most battery materials are still produced outside the U.S., but Redwood’s aim—to create a domestic supply of critical materials through “urban mining”—is beginning to take shape. The company receives EV batteries through agreements with automakers—from Tesla and Rivian to Ford and General Motors—some of whom also make batteries for energy storage. At its recycling plant, Redwood also takes in a wide variety of other lithium-ion batteries of all sizes—from laptops and other electronics, even electric toothbrushes. (In San Francisco, the company recently started testing new bins to make it easier to collect old batteries directly from consumers.) In 2024, Redwood generated $200 million in revenue (the company declined to share more recent numbers). Though EV sales have slowed—meaning demand for EV battery materials is still growing, but not as quickly as projected—the company’s move to grid storage has protected its bottom line as the broader battery market continues to strengthen. Grid storage has emerged as a much larger source of demand for battery materials, making overall demand even more robust—and reinforcing Straubel’s realization that putting batteries to work on the grid could be even more lucrative than simply recycling their material Other companies had piloted similar ideas, but Straubel realized that it could make the concept economically feasible by creating a system that could manage hundreds or thousands of EV batteries of any type, from any manufacturer, in the same shipping container. After weatherizing the batteries and placing them in a simple layout on a field next to the tech that controls them, the system can perform like other large-scale batteries at half the cost. At first, the innovation might not seem obvious. After a battery is too depleted to be used in a car, you might assume that it needs to be recycled. “When we first started this, there was a little more skepticism, [with people] saying, ‘Okay, aren’t there enough new batteries? Why would you want to do this?’” Straubel says. Though the approach is unconventional, the tech is already proven. “Effectively, it’s a field of cars plugged into a centralized control system,” Lankton says. “Just take the vehicle away, the part with the wheels, and that’s what you have.” While some news stories called the energy storage business a pivot when it was announced in 2025, both parts of the business are connected. When EV batteries used for energy storage are depleted, Redwood will recycle the materials at that point. “It actually helps our recycling business, because we have more visibility and more predictability of the flow of material into material recovery and remanufacturing materials,” Straubel says. In the meantime, those same batteries are already being deployed with customers, storing energy on the grid and proving their value in real-world use. Fast power for the data center surge Like other data center developers, Colorado-based Crusoe has a major energy challenge. To build a new data center, it usually has to get in line with a utility to get approval to connect to the grid—a process that takes years because of bureaucracy and backlogs, and that doesn’t guarantee the company will be able to access power in the end. That’s why Crusoe became the first to partner on Redwood’s new battery solution: It offered a new, affordable option to build off-grid power for data centers, which meant the company didn’t need to wait for approval from the utility. In 2025, Crusoe and Redwood pioneered the first solar- and EV-battery-powered data center at Redwood’s headquarters in Nevada, using Crusoe’s own modular design for small shipping-container-size units with the data center infrastructure. “The constraint of going 100% renewable off-grid has always been the cost of the batteries,” says Crusoe cofounder Cully Cavness. By cutting the cost of battery storage roughly in half, Redwood has made 24/7 renewable power “economic and scalable,” he adds. (Cavness and Straubel met, somewhat improbably, on LinkedIn. Straubel, who has an insatiable appetite for new technology, reached out early in Crusoe’s existence to learn about the startup, and the companies saw the chance to work together years later.) With the traditional process, “the timelines just continue to widen,” Cavness says. “You’re five-plus years, and not even with certainty that at the end of that timeline you’ll have availability of power or approval to connect. By contrast, here we have very high certainty of the ability to do the thing we want to do.” It also avoids the supply chain disruptions that can slow the manufacture (or raise the price) of newly made batteries. Closing the Strait of Hormuz, for example, has already affected battery material manufacturing. “In this case, it’s a stream of batteries that already exists that are coming back out of use on the roads,” Cavness says. Because most EV batteries still have life in them and don’t immediately need to be recycled, Redwood currently has nearly 3 gigawatt-hours of batteries in inventory that are ready to deploy. As with other grid-scale batteries, the system can be used with any power source. Some data centers plan to use them with gas turbines or connect to the grid. Because power demand from a data center can quickly spike and fall, and turbines or the grid can struggle to adapt, batteries can help buffer those swings. But solar has advantages, “and not even just from a sustainability point of view,” Straubel says. “Solar is the cheapest and fastest energy that you can deploy today. The data shows that in every way you look at it. The one challenge, of course, is how you make it stable and how you buffer through the variability. That’s what our systems are deploying into.” And while data centers and their power needs occupy much of the news, utilities are also eager for Redwood’s help. At the company’s Nevada campus, Lankton and Straubel take turns playing the part of tour guide, showing customers how the system powers the modular data center 24/7. The usual questions are not whether it will work, but about things like whether there will be a supply of batteries over time. That’s not a concern, Straubel says. “It’s so much bigger even than our current ability to process,” he notes. “That almost keeps me up at night, because I’m, like, geez, we have to scale by 10 times just to be able to do what’s in the market now even if [EV] sales stayed flat for the next 10 years.” Rivian, the EV manufacturer, recently announced that it’s working with Redwood to install the system—using Rivian’s own used batteries—in a field next to the automaker’s factory in Illinois. By using the batteries to store energy from the grid when it’s cheapest, along with excess power from Rivian’s own on-site wind turbine and solar panels, the company can save significantly on electric bills. The system does take space; Rivian will install it near its wind turbine, on land that it wouldn’t otherwise use. “It’s a perfect application in a factory setting where we have the land available,” says Andrew Peterman, director of advanced energy solutions at Rivian. “An engineer’s engineer” At Redwood, as the technology begins to roll out more widely, the team continues to look for new ways to expand it. That includes Straubel, who still finds time to dive into hands-on engineering work. It’s similar to how he worked at Tesla, says Mateo Jaramillo, now CEO of Form Energy, who worked with Straubel in Tesla’s energy division. (Form Energy now makes “iron-air” batteries that can store energy for long periods, and that will be used in projects such as a new Google data center in Minnesota.) Straubel’s ideas grow out of his intense curiosity and the way he thinks. “He spends his time immersed in details, and he’s an engineer’s engineer,” Jaramillo says. “And so in many ways, the visionary aspects of what he does are a natural output of who he is.” At Tesla, that leadership style was notably different from Elon Musk’s. “JB is very much in the weeds on the front lines of any technical project, and on a sustained basis as well,” Jaramillo continues. “Elon, of course, was famous for literally jetting in and jetting out. That’s not JB’s approach. He’s consistently pushing the technical details and through the complexities of a project.” In a 2022 Time article, Jaramillo shared the story of Musk learning about a battery project years after it had been underway; Musk wanted it to stop, but Straubel kept it going without the CEO’s permission. “There were enough gaps in the organization that we could go get that done,” Jaramillo says. “And it speaks to the fact that JB and I were there every day pushing that project.” In his own work at Form Energy now, Jaramillo says he has drawn from what he learned watching JB hold a team to high standards, set aggressive goals, and dive into the details to make sure the results came out right. “All those things I saw JB do day in and day out,” he says. Now, Redwood is racing to meet the demand from data centers, utilities, and other customers for energy storage. By 2030, the company estimates that it’s feasible for end-of-life batteries to supply more than half of the energy storage market. Redwood is not without its own challenges. The company, which currently employs around 1,000 people, had two recent rounds of layoffs, which Straubel has pinned on expanding too fast. But in a note to employees in April, when 135 employees were laid off, Straubel wrote that the company had “successfully adapted to changes in the market that have bankrupted many of our competitors,” and that the materials part of the business was “well on its way to profitability.” The work “is very much a team sport now,” Straubel says. But he’s still closely involved in hands-on engineering work—Redwood employees describe him as still trading notes on design and implementation and building new prototypes on his own—and that’s continuing to push new innovation forward in a way that should let him again see the next energy pivot before the rest of the industry. “I love the engineering work, personally,” he says. “I derive a lot of fun from that. So A, it’s fun. And B, I do think it’s actually really useful to stay close to things and be able to kind of see where technology is going—and have an intuition on how these projects work.” View the full article
-
Small business accounting involves systematically tracking and analyzing financial transactions to maintain a company’s financial health. It covers vital activities like managing sales, expenses, and payroll, which are fundamental for compliance with tax regulations. Comprehending how to generate key financial statements can aid your decision-making and strategic planning. As you consider the implications of effective accounting practices, you’ll find that they not merely guarantee compliance but likewise provide a competitive edge in the marketplace. Key Takeaways Small business accounting involves tracking and analyzing financial transactions to assess a company’s fiscal health and profitability. It includes managing purchases, sales, expenses, payroll, and ensuring compliance with tax regulations. Key financial statements generated include income statements, balance sheets, and cash flow statements for performance evaluation. Accurate financial records provide insights for informed decision-making and enhance transparency for stakeholders. Utilizing accounting software can streamline processes, reduce errors, and support efficient financial management. Definition of Small Business Accounting Small business accounting is the process of carefully tracking, recording, and analyzing financial transactions that reflect a company’s fiscal health. Comprehending accounting is fundamental for small business owners, as it encompasses managing purchases, sales, expenses, payroll, and other financial activities necessary for evaluating profitability. In small business accounting 101, you’ll learn how to translate numerical data into financial statements that communicate your business’s performance to stakeholders and regulators. This basic accounting knowledge is significant for compliance with tax regulations and for documenting assets and liabilities. A robust accounting system allows you to monitor growth and identify areas for improvement, ensuring accurate reporting for tax obligations. By excelling in these principles, you can make informed decisions that positively impact your business. Investing time in small business accounting paves the way for financial clarity, helping you navigate your company’s financial environment with confidence. Importance of Small Business Accounting Though many entrepreneurs focus on product development and customer acquisition, grasping the importance of accounting in small businesses is equally crucial for long-term success. Small business accounting helps you track and analyze financial transactions, determining your profitability and overall financial health. By mastering accounting basics for beginners, you can maintain compliance with regulatory requirements, ensuring timely tax filings and minimizing penalties. Accurate financial records provide insights into business performance, enabling you to make informed decisions about expenses, pricing, and investments. Monitoring cash flow is another critical aspect; effective accounting practices support your operations and future growth planning. With around 33.2 million small businesses in the U.S., having strong accounting knowledge can give you a competitive edge. Key Components of Small Business Accounting In small business accounting, tracking financial transactions is crucial for comprehending your company’s performance. You’ll generate key profitability analysis statements, like income statements and balance sheets, to assess how well your business is doing financially. Financial Transaction Tracking Effective financial transaction tracking is a cornerstone of successful small business accounting, as it involves recording every purchase, sale, expense, and payroll entry with great care. Mastering these accounting basics for students is crucial, whether you’re taking an accounting 101 class or managing your own business. Accurate tracking guarantees compliance with tax regulations, aids in documenting assets and liabilities, and supports audits or financial reviews. Many businesses use accounting software for efficiency and to minimize manual errors. Below is a simple overview of tracking methods: Method Advantages Disadvantages Accounting Software Efficiency Cost Spreadsheets Accessibility Error-prone Traditional Ledgers Simplicity Time-consuming Regular transaction tracking is important for preparing tax returns and monitoring growth. Profitability Analysis Statements How can comprehension profitability analysis statements improve your small business’s financial strategy? These vital reports, like income statements, summarize your revenues and expenses, helping you determine net profit or loss over a specific period. Key components include gross profit, calculated by subtracting the cost of goods sold from total revenue, which offers insights into production efficiency. Moreover, operating profit, or earnings before interest and taxes (EBIT), reveals the profitability of your core operations, important for evaluating performance. The net profit margin, found by dividing net profit by total revenue, indicates the percentage of revenue that remains as profit after all expenses. Regularly generating these statements enables you to identify trends, make informed decisions, and communicate effectively with stakeholders. Tracking Financial Transactions Tracking financial transactions is a fundamental aspect of small business accounting that can’t be overlooked. You need to keep records of sales, purchases, expenses, and payroll to maintain accurate financial documentation. This organization is vital for complying with IRS requirements, which demand receipts and financial statements. By accurately tracking these transactions, you can monitor cash flow, assess profitability, and pinpoint areas needing improvement. Regularly reconciling financial records with bank statements is important for identifying discrepancies and ensuring accuracy. This process allows you to spot errors before they escalate into larger issues. Although manual tracking is possible, using accounting software can greatly streamline your efforts, automating data entry and providing real-time insights into your financial health. Benefits of Accounting Software While managing a small business can be overwhelming, utilizing accounting software offers significant benefits that simplify financial management. First, it automates financial tasks, reducing manual errors and saving you time, so you can focus on core operations. Generating financial reports becomes straightforward, allowing you to create income statements, balance sheets, and cash flow statements quickly and efficiently. Many accounting software options, like QuickBooks Online, come with integrated payroll features, ensuring accurate tax withholdings and employee payment management. Furthermore, using accounting software streamlines tax processes, helping you comply with IRS documentation requirements, which ultimately results in more accurate and timely tax filings. Moreover, it improves your financial decision-making by providing real-time insights and analytics, enabling you to track expenses, revenue, and cash flow effectively. Establishing a Bookkeeping System Establishing a bookkeeping system is vital for any small business aiming for financial clarity and stability. You’ll need to choose between single-entry and double-entry accounting methods, as each has its advantages for tracking transactions. Decide whether cash-basis or accrual-basis accounting fits your needs, since this choice affects when you recognize revenues and expenses, influencing your financial reports and tax obligations. Consider using accounting software like QuickBooks or FreshBooks to simplify your bookkeeping tasks, automate data entry, and provide integrated reporting tools. Regularly reconciling your bank statements with recorded transactions is important for maintaining accuracy and spotting discrepancies. Finally, categorize your income and expenses by creating a chart of accounts that organizes financial data into assets, liabilities, revenue, and expenses. This organization will facilitate better financial analysis and support informed decision-making for your business. Understanding Financial Reports Comprehending financial reports is vital for your business success, as they provide insights into your financial health. Key statements like the income statement, balance sheet, and cash flow statement summarize important data about revenues, expenses, and cash movements. Importance of Financial Reports Financial reports play a crucial role in the success of small businesses, as they provide insights into profitability, financial position, and liquidity through key documents like income statements, balance sheets, and cash flow statements. Regularly reviewing these reports helps you identify trends, make informed decisions, and adjust strategies for better financial performance. Accurate financial reporting guarantees compliance with regulations and transparency for stakeholders, including investors and creditors. Furthermore, financial reports track key performance indicators (KPIs) that highlight areas for improvement and guide resource allocation. Timely generation of these reports is essential for effective cash flow management and preparing accurate tax filings, avoiding penalties, and guaranteeing compliance. Financial Report Type Purpose Income Statement Assess profitability Balance Sheet Evaluate financial position Cash Flow Statement Analyze liquidity KPI Tracking Identify areas for improvement Compliance Ensure adherence to regulations Key Financial Statements Explained During the process of exploring the domain of small business finance, you’ll encounter three key financial statements that serve as vital tools for evaluating your business’s health. The balance sheet provides a snapshot of your assets, liabilities, and equity at a specific time, allowing you to assess financial stability. Next, the income statement, or profit and loss statement, summarizes your revenues, expenses, and net income over a period, helping you evaluate profitability. Finally, the cash flow statement tracks the inflow and outflow of cash categorized into operating, investing, and financing activities, fundamental for comprehending liquidity. Regularly reviewing these statements enables you to identify trends, make informed decisions, and maintain compliance with financial reporting regulations. Frequency of Report Generation Generating financial reports regularly is crucial for small businesses aiming to stay on top of their performance. You should prioritize generating reports at different intervals to maintain a clear financial picture. Consider the following frequency recommendations: Monthly Reports: Track cash flow and operational efficiency to make timely adjustments. Quarterly Reports: Prepare income statements and balance sheets to assess profitability and financial position over time. Annual Reports: Summarize your financial activities, including the cash flow statement, for tax preparation and compliance. Tax Preparation and Compliance During managing your small business’s finances, comprehension of tax preparation and compliance is fundamental for minimizing your tax liability and avoiding penalties. Accurate bookkeeping helps you track all financial transactions, guaranteeing you report income and expenses correctly as you identify deductible expenses. This can considerably reduce your tax liability. To file your tax returns accurately and comply with IRS regulations, you’ll need significant documents like profit and loss statements and balance sheets. Understanding your tax obligations—federal, state, and local—is essential. Utilizing accounting software can automate tax calculations and guarantee timely filings. Furthermore, keeping organized records of receipts, invoices, and financial statements is crucial, as the IRS requires documentation to substantiate deductions and credits. Finally, engaging a certified accountant can guide you through complex tax laws, help maximize allowable deductions, and guarantee compliance with evolving regulations, making your tax preparation process more manageable and efficient. Resources for Small Business Accounting Support How can small business owners find the right resources to manage their accounting needs effectively? There are several valuable options available to help you gain the necessary skills and support. Coursera: Platforms like Coursera offer a variety of accounting courses that can help you improve your financial management skills and grasp fundamental accounting principles. Moreover, consider subscribing to the Oregon SBDC newsletter for updates on resources, tips, and relevant news. Utilizing accounting software like QuickBooks can as well streamline your processes, integrating payroll, invoicing, and expense tracking into one platform. Frequently Asked Questions What Is a Small Business Accounting? Small business accounting involves tracking and managing your financial transactions, such as sales and expenses. It helps you understand your business’s financial health by providing insights into profits and losses. You can use various methods, like accounting software or spreadsheets, to maintain accurate records. This process is vital for tax compliance, preparing financial statements, and making informed decisions about resource allocation. In the end, effective accounting supports your business’s growth and sustainability. What Type of Accounting Do Small Businesses Use? Small businesses typically use cash basis or accrual basis accounting. With cash basis, you recognize revenues and expenses only when cash changes hands, making it simpler for businesses with revenues under $5 million. https://www.youtube.com/watch?v=DpbXWP8fLbc Conversely, accrual basis records transactions when they’re earned or incurred, providing a clearer financial picture. Many small businesses likewise rely on accounting software like QuickBooks, which supports both methods, helping you manage finances effectively according to your needs. How Much Would an Accountant Cost for a Small Business? Hiring an accountant for your small business can cost between $150 and $400 per hour, depending on their expertise and the complexity of services you need. Annually, you might pay between $1,000 and $5,000 for basic services like bookkeeping and tax preparation. Some accountants offer fixed monthly fees ranging from $200 to $1,000. If you’re looking to save, consider part-time bookkeepers or accounting software, which can lower your expenses considerably. Can You Do Your Own Small Business Accounting? Yes, you can manage your own small business accounting, especially if your finances are straightforward. By using accounting software like QuickBooks, you can automate tasks such as invoicing and expense tracking. Nonetheless, it’s crucial to stay organized and understand basic accounting principles. This approach can save you money, but it likewise requires a commitment to regularly record transactions and prepare financial reports. As your business grows, consider hiring a professional for complex needs. Conclusion In summary, small business accounting is essential for managing your company’s financial health. By tracking transactions and generating key reports, you gain insights that inform important decisions. Establishing a solid bookkeeping system and utilizing accounting software can streamline your processes, making compliance with tax regulations easier. Comprehending financial reports helps you assess performance and plan strategically. For ongoing support, various resources are available to assist you in mastering small business accounting and enhancing your competitive edge. Image via Google Gemini This article, "What Is Small Business Accounting?" was first published on Small Business Trends View the full article
-
Leaders call on their other partners to maintain global trade flows with similar agreementsView the full article
-
Threat follows Donald The President’s announcement that America would ‘guide’ stranded ships through waterwayView the full article
-
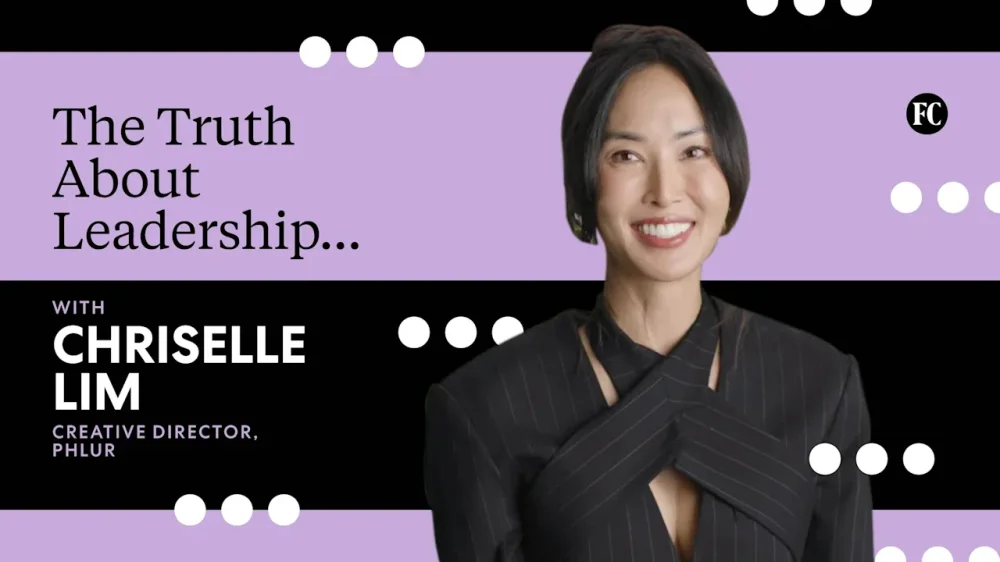
Chriselle Lim didn’t come from a perfume background, but she didn’t let that stop her. She realized there is always room for new brands that bring a different perspective. View the full article
-
CEO of Black Girls Code, Cristina Mancini shares her perspective on leaders treating DEI as a brand strategy rather than a true commitment. View the full article
-
Bozoma Saint John shares her approach to leadership, emphasizing curiosity as a driving force behind growth, confidence, and long-term success View the full article
-
Creating a financial report for your small business is essential for comprehending its financial health. It involves compiling key statements like the income statement, balance sheet, and cash flow statement. These documents highlight your profitability, liquidity, and cash management. By gathering accurate financial data and utilizing accounting software, you can streamline the reporting process. Nevertheless, many small business owners overlook common mistakes in preparation. Let’s explore how to avoid these pitfalls and guarantee your financial reports reflect your business’s true performance. Key Takeaways Gather all relevant financial data to create the income statement, balance sheet, and cash flow statement for a comprehensive financial report. Organize accounts into assets, liabilities, revenues, and expenses to establish a clear financial structure for effective reporting. Utilize accounting software to streamline data entry, minimize errors, and ensure consistency in financial reporting. Regularly review and adjust preliminary financial statements against actual records to maintain accuracy and transparency. Include comparative data and trends in your financial report to enhance analysis and support strategic planning. Importance of Financial Statements for Small Businesses Financial statements are important tools for small businesses, acting as a roadmap to navigate the intricacies of financial management. They help you monitor profitability and assess your financial health, enabling informed decision-making and strategic planning. By using a financial statement template, you can easily create documents like income statements and balance sheets that provide insights into your cash flow. This oversight allows you to make timely corrections, safeguarding your financial stability. Furthermore, accurate financial reporting is critical for identifying areas ripe for improvement and growth, necessary for long-term sustainability. When seeking loans or attracting investors, these statements offer transparency and demonstrate your financial capacity. Additionally, effective financial reporting practices can improve your business resilience by revealing key performance metrics. For instance, financial projections for a business plan example can illustrate potential growth, guiding your strategic decisions and resource management. Key Financial Statements Overview Grasping the key financial statements is crucial for effectively managing your small business. The balance sheet offers a snapshot of your assets, liabilities, and shareholders’ equity at a specific moment, illustrating the equation: Assets = Liabilities + Shareholders’ Equity. Comprehending this will help you assess your financial position. The income statement summarizes your revenues, costs, and expenses over a designated period, guiding you in determining net profit or loss from core operations. Finally, the cash flow statement tracks cash inflows and outflows across operating, investing, and financing activities, revealing your business’s liquidity and short-term viability. Together, these statements interconnect to provide an all-encompassing view of your financial health, aiding in strategic planning. For those looking to create a financial report for small business, utilizing a financial projections template for business plan can streamline this process and improve your grasp of financial outcomes. Income Statement: Understanding Profitability When analyzing a business’s performance, the income statement serves as an important tool that reveals its profitability over a specified time frame. This statement summarizes revenues and expenses, helping you understand key metrics like gross profit and net income. By reviewing the income statement regularly—perhaps monthly or quarterly—you can spot trends and make informed decisions. Component Description Calculation Total Revenue Income from sales and services N/A Cost of Goods Sold (COGS) Direct costs associated with production N/A Gross Profit Revenue minus COGS Total Revenue – COGS Using proper income statement forms is crucial for a clear presentation. You might as well refer to a financial forecast business plan sample to project future profitability effectively. This focused approach empowers stakeholders to assess the earning capacity of your business. Balance Sheet: Assessing Financial Health A balance sheet acts as a vital financial statement that provides a clear snapshot of your business’s financial health at a specific moment. It details your assets, liabilities, and shareholders’ equity, following the key equation: Assets = Liabilities + Shareholders’ Equity. This equation guarantees that everything your business owns is funded either by borrowing or owners’ investments. Assets are divided into current and non-current categories, whereas liabilities are similarly classified, allowing you to assess liquidity and long-term stability. Regularly analyzing your balance sheet can reveal metrics like the current ratio, which indicates your ability to pay short-term obligations. A balanced balance sheet signifies sound financial management, reflecting your capacity to maintain sufficient assets to cover liabilities. This information is significant for your annual report for LLC, helping you demonstrate financial health to stakeholders and guide future business decisions. Cash Flow Statement: Monitoring Cash Flow Comprehending your cash flow is vital for your business’s success. By analyzing cash flow trends, you can identify patterns that highlight when you’re generating revenue and when expenses arise, helping you make informed decisions. Effectively managing your cash flow not just guarantees you meet your financial obligations but likewise positions your business for growth. Importance of Cash Flow Monitoring cash flow is fundamental for any small business, as it allows you to keep track of the money coming in and going out. The cash flow statement is a key tool in this process, categorizing cash flows into operating, investing, and financing activities. By reviewing this statement regularly, you can identify potential cash shortages or surpluses, enabling you to manage your finances proactively. Positive cash flow indicates you’re generating more cash than you’re spending, which is critical for your business’s long-term sustainability and growth. Additionally, comprehending the timing of cash flows helps you navigate seasonal fluctuations and unexpected expenses, contributing to the overall financial health reflected in the annual report of a company. Analyzing Cash Flow Trends Analyzing cash flow trends is vital for gaining insights into your business’s financial health, especially since these trends can reveal patterns that inform future decision-making. The cash flow statement categorizes cash transactions into operating, investing, and financing activities, offering a thorough view of cash movement. Positive cash flow from operating activities is fundamental, as it shows your core operations generate sufficient cash for growth. By examining cash flow trends, you can identify seasonal fluctuations and timing mismatches between cash inflows and outflows, enhancing financial planning. Regular monitoring helps uncover potential liquidity issues, allowing you to address cash shortages proactively. Moreover, cash flow forecasts can improve cash management, guiding spending and investment decisions, especially during annual report filing. Managing Cash Flow Effectively Effective cash flow management is vital for any small business, as it directly impacts your ability to operate and grow. The cash flow statement categorizes cash activities into operating, investing, and financing sections, providing a clear view of cash inflows and outflows. Monitoring cash flow from operating activities is important; it indicates the cash generated from your core business operations. Positive cash flow shows you’re generating more cash than spending, which maintains liquidity and meets obligations. Regular updates to your cash flow forecast, including new sales data and payment schedules, can help anticipate cash shortages or surpluses. Analyzing patterns in your cash flow can reveal timing mismatches, informing strategies to optimize cash management, as seen in the annual report of corporation. Steps to Prepare Financial Statements When preparing financial statements for your small business, the first step involves gathering all essential financial data from various sources and organizing it into clear categories, such as expenses, revenue, assets, and liabilities. This organization helps you create a thorough overview of your business’s financial position. After gathering the data, follow these steps: Prepare preliminary financial statements, including your income statement, balance sheet, and cash flow statement. Review and adjust these preliminary reports against existing records for accuracy. Finalize the financial statements, ensuring they meet necessary standards for stakeholders, investors, and lenders. Regularly update these statements to reflect your business plan financial forecast and track your projected financial statements over time. Organizing Your Accounts Organizing your accounts is crucial for gaining a clear picture of your business’s financial health. By categorizing financial data into distinct sections like assets, liabilities, revenues, and expenses, you create a structured overview that helps in effective management. Streamlining data entry through standardized methods or accounting software not just saves time but furthermore improves the accuracy of your financial records. Categorizing Financial Data Categorizing financial data is crucial for small businesses aiming to maintain clear and accurate records. By organizing accounts into key groups, you can improve financial reporting and analysis. Here are some categories to reflect upon: Assets: Divide into current and non-current to reflect short-term and long-term resources on your blank balance sheet. Liabilities: Similarly, categorize into current and long-term obligations to understand your financial commitments. Revenues: Track total income from sales and services, making necessary adjustments for discounts to reflect true earnings. SG&A Expenses: Monitor Selling, General, and Administrative costs separately to identify potential savings. Using standardized financial statement forms and a consistent chart of accounts will greatly aid in comparing financial performance and ensuring compliance. Streamlining Data Entry Streamlining data entry is essential for small businesses seeking efficiency and accuracy in their financial reporting. Start by organizing your accounts, categorizing financial data into clear sections like revenue, expenses, assets, and liabilities. This structure simplifies how to create a financial report. Use accounting software such as FreshBooks or QuickBooks to automate data collection, minimizing manual entry errors. Implement a standardized chart of accounts for consistency across periods, making it easier to analyze data. Regularly reconcile your accounts to guarantee accuracy, reflecting your business’s true financial condition. Establish a routine for updating financial information, which helps make informed decisions. You can likewise utilize a printable free financial statement template to further streamline your reporting process. Preparing Preliminary Financial Statements When preparing preliminary financial statements, it’s important to first gather all relevant financial data from various sources. Organizing this data into categories helps create a clearer picture of your business’s financial health. You’ll typically focus on: Revenue and sales figures Expenses incurred over the period Assets owned by the business Liabilities that need to be settled The primary preliminary financial statements include the income statement, balance sheet, and cash flow statement. Each provides unique insights critical for your business annual report and annual reporting process. Consistency in applying accounting principles is fundamental; this guarantees your reports are reliable and comparable over time. Once drafted, you’ll need to review these preliminary reports against your financial records, making necessary adjustments before finalizing them for stakeholders, investors, and lenders. This diligence not merely improves accuracy but additionally builds trust in your financial reporting. Reviewing and Adjusting Financial Reports Reviewing and adjusting your financial reports is essential for maintaining accuracy and transparency in your business. By comparing preliminary statements with actual records, you can identify discrepancies and make necessary adjustments, such as reconciling accounts or correcting misclassifications. Regularly checking your income statements, balance sheets, and cash flow statements not just helps you spot red flags but likewise guarantees that stakeholders have a clear view of your financial health. Importance of Adjustments Adjustments to financial reports play a vital role in ensuring that your business’s financial data is both accurate and reliable. Regularly reviewing and adjusting these reports is critical for informed decision-making and maintaining stakeholder trust. Here are some key benefits of making these adjustments: Identify discrepancies and areas for improvement. Improve operational efficiency and financial performance. Detect errors early through reconciliations, minimizing risks in your small business annual report. Uncover trends and patterns for strategic planning and forecasting. These adjustments based on real-time data not only increase the relevance of your financial reports but also enable better responsiveness to market changes and operational challenges. In the end, this diligence supports your business annual filing and long-term success. Common Adjustment Practices To maintain accurate financial reporting, it’s crucial to regularly assess and adjust your preliminary financial statements against recorded transactions. Start by reconciling discrepancies between your financial records and Bank of America statements to guarantee all transactions are properly recorded. Analyzing variances in your budget versus actual reports helps identify trends that may require adjustments in your financial forecasts or operational strategies. Implementing automated processes through accounting software can improve the efficiency and accuracy of this review. Conduct periodic audits to verify the reliability of your financial statements, making necessary adjustments to reflect your true financial condition. Finalizing and Reporting Financial Statements Finalizing financial statements is an essential step in guaranteeing that your small business’s financial reports are accurate and compliant with accounting standards. This process involves reviewing and adjusting preliminary reports against your accounting records, allowing you to identify discrepancies. Before presenting to stakeholders, make certain to: Perform reconciliations to confirm accuracy Format the income statement, balance sheet, and cash flow statement clearly Regularly audit your financial statements for reliability Cultivate transparency to build trust with stakeholders Stakeholders, including shareholders and creditors, depend on finalized financial statements to assess your business’s financial health. They use this information for decisions regarding investments and lending. Using Accounting Software for Efficient Reporting Using accounting software can greatly improve the efficiency of your financial reporting processes, especially for small business owners who may not have extensive accounting backgrounds. This software automates data collection and organization, considerably cutting down the time you spend on reporting and minimizing errors in calculations. Tools like FreshBooks provide built-in reporting features that allow you to generate financial statements quickly, making it easy for anyone to navigate. Many platforms likewise offer standardized templates for income statements, balance sheets, and cash flow statements, ensuring consistency in your yearly business report. Furthermore, utilizing cloud-based accounting software gives you real-time access to financial data, supporting timely insights for decision-making. Automated reconciliation features further boost financial accuracy by matching transactions against bank statements. For a solid start, consider a business plan template free download to help structure your financial goals alongside efficient reporting practices. Common Mistakes in Financial Statement Preparation When preparing financial statements, many small business owners unknowingly make common mistakes that can compromise the accuracy and reliability of their reports. To guarantee your financial statements reflect your business’s true condition, avoid these pitfalls: Excluding comparative data hinders performance analysis and makes it hard to spot trends over time. Miscategorizing expenses and revenues leads to discrepancies that misrepresent your financial health. Not regularly reviewing and adjusting preliminary financial statements against actual records can result in misleading reports for stakeholders. Ignoring consistency in applying accounting standards reduces trust in your financial reports. Tips for Maintaining Accurate Financial Records Accurate financial records are the backbone of any successful small business, providing essential insights into your financial health and guiding decision-making. To maintain these records effectively, start by establishing a consistent schedule for recording transactions. Whether you choose daily, weekly, or monthly updates, regularity guarantees accuracy. Consider utilizing accounting software; it automates data entry and categorization, minimizing human error and saving you time. Next, keep your business and personal finances separate by using dedicated business accounts. This separation helps maintain clear records and simplifies tracking. Regularly reconcile your financial records with bank statements to identify any discrepancies quickly. Finally, implement a standardized chart of accounts for consistency across periods and departments. For further assistance, you can explore free business planning templates or a business plan template download to improve your financial management skills. Taking these steps will help you build a solid foundation for your business’s financial success. Frequently Asked Questions How to Do Financial Reporting for a Small Business? To handle financial reporting, you start by gathering relevant data like revenues and expenses. Next, prepare key statements, such as the income statement and balance sheet, to depict your financial position. Regularly review these reports against your records, making necessary adjustments for accuracy. Employ accounting software to automate data collection, which streamlines the process and minimizes errors. Finally, finalize the reports for stakeholders, ensuring they accurately reflect your business’s financial health. Is a CPA Worth It for a Small Business? Yes, hiring a CPA is often worth it for a small business. They can identify tax deductions you might miss, saving you significant amounts each year. CPAs guarantee your financial reporting complies with regulations, reducing the risk of costly audits or fines. They additionally provide strategic financial planning, which can improve your cash flow and decision-making. Although there’s an upfront cost, the long-term benefits usually outweigh these expenses, leading to better profitability and growth. What Are the Basic Financial Statements for a Small Business? The basic financial statements for a small business include the balance sheet, income statement, and cash flow statement. The balance sheet provides a snapshot of your company’s financial position, detailing assets, liabilities, and equity. The income statement summarizes your revenues and expenses, helping assess profitability. Finally, the cash flow statement tracks cash inflows and outflows, essential for managing liquidity. Together, these statements offer an extensive view of your business’s financial health. What Are the 5 Steps of Financial Reporting? The five steps of financial reporting include compiling relevant financial data into organized categories, preparing preliminary financial statements like the income statement and balance sheet, reviewing and adjusting these statements for accuracy, finalizing the reports to guarantee they meet regulatory standards, and regularly updating the reports for ongoing relevance. Each of these steps guarantees that financial information is clear, accurate, and useful for decision-making by stakeholders in any business setting. Conclusion In summary, creating a financial report for your small business is crucial for comprehending its financial position. By compiling key statements like the income statement, balance sheet, and cash flow statement, you can gain insights into profitability, liquidity, and cash management. Utilizing accounting software can simplify this process, ensuring accuracy and efficiency. Avoid common mistakes by maintaining careful records and regularly reconciling your accounts. With these practices, you’re better equipped to make informed decisions for your business’s future. Image via Google Gemini This article, "Creating a Financial Report for Small Business" was first published on Small Business Trends View the full article
-
Capping methane emissions would alleviate energy and climate crisisView the full article
-
Most founders believe their job is to stay deeply involved as their company grows. But that instinct often becomes the very thing that holds the business back. As companies scale, what once made them successful—founder-led decision-making, strong creative direction, tight control—can start to create bottlenecks. Teams can’t become truly autonomous, leadership layers struggle to emerge and the organization remains tied to the founder’s perspective instead of evolving beyond it. I saw this firsthand after a decade of building Kurppa Hosk with business partner Thomas Kurppa. Nothing was broken; we had become a globally renowned creative agency. But growth was becoming constrained in quieter ways. As CEO, in charge of the business side of the agency, my leadership style—direct, hands-on, and rooted in constant dialogue and discussion—made it hard to scale the company. This growth coincided with the birth of Eidra, a broader consultancy collective that Kurppa Hosk co-founded. Suddenly, the agency was part of a 30-company, 1,400-people partnership that spanned 14 offices, with expertise in strategy, creativity, innovation, and tech. I jumped on the chance to channel my strengths into something new. The realisation was simple, but difficult to act on: the business didn’t need more of me. It needed a different me. Letting go of the CEO position became a deliberate decision to give the company room to grow and to focus on its future. This move is not easy; 58% of founders have difficulty letting go of control. But if you’re wondering whether it’s time to step aside, here are five tips for navigating this transition with confidence. 1. Recognise the need for change Stepping back as a founder is often equated with failure. It’s easy to think of high-profile examples like Groupon’s founder Andrew Mason or WeWork’s Adam Neumann, where founders were forced out after their leadership became detrimental to the business. But you don’t need a public meltdown to consider stepping aside. A responsible leader recognises when their style no longer serves the company’s growth. For me, it was the realisation that our agency needed a focus on operational rigour to make the most of future opportunities. And my direct and involved approach would not have delivered this. So always ask yourself: Are decisions slowing down? Is the team overly reliant on you? Are you unintentionally muting other voices or hindering the growth and development of your talent? Asking these questions proactively enables your company to evolve. 2. Don’t just look for competence, look for cultural match A crucial part of a successful transition is building a leadership team you genuinely trust. This is about more than competence on paper. Trust also has to be about cultural alignment. A new leader must understand and respect your company’s DNA while bringing their own perspective to the table. We were built on a strong internal culture that was a key part of our agency’s identity and success – it needed to be preserved and respected during the leadership transition. So, if you’re looking for someone to take the reins, consider it as a search for a ‘steward’ of the existing culture, rather than someone to overhaul it. Look for an alignment of values and vision, not just competence and operational excellence. Finding just that right person is of course hard. At Eidra, we spend a lot of time on succession planning to identify the next generation of leaders that have both the right abilities, values and cultural fit to then train them. Having an increasingly large pool of talent to source from these days, is of course beneficial. Once new leaders are in place, you then give them the platform and autonomy to succeed. Your job is to support, not overshadow. 3. Empower successors to succeed Empowerment is the most crucial part here. It’s about giving people the autonomy, mastery and meaning they need to thrive. As a founder, it’s tempting to micromanage. But if you’re constantly involved, you’re not empowering your team, you’re undermining them. Instead, focus on creating an environment where people feel trusted to make decisions, take risks and grow. For example, at Kurppa Hosk and among the wider Eidra leadership team, we embrace what we call “fruitful friction”. It’s the idea that diverse perspectives and healthy debate fuel innovation, as long as everyone agrees on the company’s overarching vision. Disagreement is fine, but it needs the framework of a shared direction. Your role as a leader is to set the direction and enable people to create the path there together. 4. Redefine your role for the future Moving out of the way, however, doesn’t always mean moving on completely. Often, it’s about evolving your role to support your company’s next phase more effectively. For me, this meant shifting from day-to-day operations at Kurppa Hosk to become Co-CEO of Eidra. I focused on scaling what I was good at – creative leadership and vision – while leaving the operational details to others. That next role can be about adding value in a way that supports the company’s growth. Maybe it’s mentoring the next generation of leaders. Maybe it’s focusing on strategy or exploring new ventures. Whatever it is, make sure it plays to your strengths. And surround yourself with people who complement those. 5. Take care of yourself Let’s be honest: a decision like this can feel like a personal crisis. For founders, the business is often an extension of their identity. Letting go is a professional challenge, but it’s also an emotional one. During my transition, I leaned heavily on a coach to help me navigate the shift. I also made a point to prioritise my well-being: spending time with family, exercising, and getting enough sleep. It sounds basic, but when you’re in the middle of a major change, self-care is often the first thing to go. Remember that stepping toward something new is positive. Focus on what excites you about the next chapter, whether it’s a new role, a new venture, or simply the chance to reclaim a life outside of the business. It isn’t easy – especially as a founder. It requires humility, self-awareness and a willingness to relinquish control. But if done right, it’s not just good for the business and the next generation of talent, it’s good for you. View the full article
-
If you’re still copy-pasting the same formatting requests or resorting to “write this like a professional” prompts every single time you open ChatGPT, you’re working too hard. There’s an essential feature buried in the Settings menu called Custom Instructions. In short, it lets you set permanent preferences so you don’t repeat prompts. Think of it as a set of persistent filters. Instead of reminding ChatGPT that you hate long-winded intros or that you need everything delivered in a clean table, you tell it once and it remembers forever. Setting it up is a breeze: Click your profile name or icon in the bottom-left corner and choose Personalization. You’ll notice a form field about halfway down. That’s where you’ll input your custom instructions. Once that’s done, every new conversation starts with those rules already baked in. It’s the ultimate way to kill the repetitive busywork of “prompt engineering” before you even start typing. Here are some custom instructions to try out. The key is to experiment and find what works for you. With a little creativity, you can turn ChatGPT into an indispensable productivity tool. Summarizer We all get bogged down in long emails, reports, and articles. This instruction will automatically summarize any text you feed into ChatGPT. Instead of spending 15 minutes reading a dry report, you can get a summary in seconds. It’s a total game changer for staying on top of information without getting overwhelmed. Custom Instruction: “Whenever I paste text, provide a concise summary highlighting the key points, main arguments, and actionable takeaways. Keep it brief and easy to scan.” Action item extractor Ever spend an hour in a meeting, only to realize later that you don’t actually know what you’re supposed to do? Yeah . . . me . . . um, neither. I never multitask during meetings. No more guessing games. This instruction creates a to-do list for you, so you can just focus on getting things done. Custom Instruction: “When I paste meeting notes or transcripts, extract all action items, assignees, and deadlines into a clear bulleted list. Also, identify any open questions or follow-up tasks.” Email drafter Drafting emails, especially routine ones, can be a major time-suck. This instruction will draft emails for you, saving you precious minutes and mental energy so you can spend your time on more important things. Custom Instruction: “When I provide a topic or bullet points, draft a professional and concise email. Adjust the tone based on the recipient (e.g., formal for a client, casual for a colleague). Include a clear subject line and call to action.” Brainstorming buddy Stuck on a problem or need some fresh ideas? Sometimes you just need a nudge. This instruction gives you a burst of creativity when you need it most, whether you’re brainstorming marketing campaigns or trying to find a solution to a technical problem. Custom Instruction: “When I share a project or problem, act as a creative brainstormer. Generate at least five innovative and diverse solutions, ideas, or approaches. Don’t be afraid to think outside the box.” View the full article
-
Millions of seats cut as Middle East crisis throws global travel into disarrayView the full article
-
Security around Russia’s president has tightened after Ukraine’s audacious drone attacksView the full article
-
Unbowed by the Iran war and other shocks, individual investors are buying their way to new heights of influenceView the full article
-
With fewer than 300 lawyers, Wachtell racked up bumper profits and exercised outsize influence. Now its model is being challenged as never beforeView the full article
-
EU must adapt to geopolitical reality shaped by US and China, says Belgium’s Pierre WunschView the full article
-
Brokers report growing interest from ‘almost every sector’ as companies reassess security risksView the full article
-
With the Strait of Hormuz choked off, Riyadh focuses on Red Sea infrastructure View the full article
-
Experts say Tehran is likely to eventually seek retaliation against senior figures over the US-Israeli war View the full article
-
An LLC, or Limited Liability Company, is a versatile business structure that offers both liability protection and tax benefits. To form an LLC, you need to file Articles of Organization with your state, and it can have one or more members. The operational structure can be customized to your needs, either being member-managed or manager-managed. Comprehending how LLCs function can help you decide if this structure is right for your business goals. What specific aspects are you curious about? Key Takeaways LLCs provide a legal structure that combines personal liability protection with tax advantages for business owners. Formation requires filing Articles of Organization with the state and creating an Operating Agreement is advisable. LLCs can be managed by all members or by designated managers, offering flexibility in operations. Income is typically passed through to members, avoiding double taxation and allowing for deductions on personal income. LLCs can have unlimited members, making them suitable for diverse ownership structures and various business types. What Is an LLC? A Limited Liability Company, or LLC, is a popular business structure that offers a unique blend of benefits for entrepreneurs. So, what’s an LLC and how does it work? It combines the liability protection of a corporation with the tax advantages and flexibility of a partnership or sole proprietorship. In an LLC, owners are called members and enjoy limited personal liability for business debts, which means their personal assets are typically safe from business claims. You can form an LLC by filing Articles of Organization with your state, detailing the LLC’s name, address, and registered agent. When considering single member vs multi member LLC, keep in mind that single-member LLCs default to sole proprietorships, whereas multi-member LLCs are treated as partnerships, allowing profits to pass through to your personal tax returns. This structure additionally provides greater operational flexibility since there are no strict requirements for annual meetings or minutes. LLC Formation To form an LLC, you’ll need to start by filing the Articles of Organization with your state’s Secretary of State, along with the necessary fee. It’s additionally wise to create an Operating Agreement that outlines the roles and responsibilities of each member, although it’s not always required by law. Finally, obtaining an Employer Identification Number (EIN) is essential for tax purposes and may be needed to open a business bank account. Filing Articles of Organization When you’re ready to set up your LLC, the first step is filing the Articles of Organization, also known as the Certificate of Formation, with the appropriate state agency, usually the Secretary of State. This document requires specific details about your business, including the LLC’s name, the registered agent‘s name and address, the business purpose, and the management structure, especially important for a multi-member LLC. Keep in mind that filing fees vary by state, ranging from as low as $1 to as high as $500. Some states may additionally necessitate additional documentation or licenses to guarantee compliance with local laws. Once approved, your LLC is recognized as a separate legal entity, allowing it to conduct business and enter contracts. Creating an Operating Agreement Creating an Operating Agreement is vital for any LLC, as it establishes a clear framework for how the business will operate. This important document outlines the management structure, roles, responsibilities, and operational procedures, ensuring clarity among members. Typically, it includes details on member contributions, profit and loss allocation, voting rights, and procedures for adding or removing members. Although it may not be legally required in all states, having an Operating Agreement can help prevent disputes and provide a structured approach to business operations. Tailoring the document to your LLC’s specific needs is critical, reflecting the agreement of all members involved. A well-drafted Operating Agreement additionally reinforces the limited liability protection, emphasizing that the LLC is a separate legal entity from its owners. Obtaining an EIN Obtaining an Employer Identification Number (EIN) is a crucial step in the formation of your LLC, as it serves as your business’s unique identifier for tax purposes. Although single-member LLCs without employees aren’t legally required to get one, it’s highly recommended to keep your personal and business finances separate. You can apply for an EIN for free online through the IRS website, and it typically takes just a few minutes. Here are four key reasons to obtain an EIN: Required for filing federal taxes. Necessary for hiring employees. Used to open a business bank account. Needed for applying for business licenses and permits. Keep your EIN secure, as it accesses sensitive business information. LLC Structure and Operation Limited Liability Companies (LLCs) offer a flexible ownership structure that can include individuals, corporations, or even other LLCs as members. You can choose between a member-managed LLC, where all members participate in management, or a manager-managed LLC, where designated managers handle daily operations. The LLC owns property and assets, which protects your personal assets from business liabilities and debts. Additionally, LLCs don’t have to hold annual meetings or maintain meeting minutes, simplifying their operational requirements. Major decisions are usually made by the members, whereas everyday tasks may be delegated to managers in a manager-managed structure. Type of Management Description Member-Managed All members participate in management. Manager-Managed Designated managers run daily operations. Ownership Flexibility Members can be individuals or entities. Asset Protection Personal assets are shielded from liabilities. Simplified Operations No annual meetings or minutes required. LLCS and Taxes In relation to taxes, LLCs offer significant advantages over other business structures, especially due to their classification as pass-through entities. This means profits and losses are reported on your personal tax return, eliminating double taxation. Here are some key points to reflect on: Single-member LLCs are treated as sole proprietorships for tax purposes, simplifying your tax filings. Multi-member LLCs are typically classified as partnerships except you choose to be taxed as a corporation. You can elect S Corporation or C Corporation status by filing appropriate forms with the IRS, potentially providing tax benefits. Members must pay self-employment taxes on their earnings, impacting your overall tax liability. Additionally, the default taxation method allows you to deduct business expenses from your personal income, which can reduce your taxable income and optimize your tax situation. Comprehending these aspects can help you make informed decisions about your LLC. Benefits of an LLC Choosing an LLC for your business comes with several notable benefits that make it an appealing option for many entrepreneurs. Here are some key advantages to evaluate: Benefit Description Impact Limited Liability Protection Protects personal assets from business debts and legal claims. Reduces personal risk Pass-Through Taxation Profits are reported on personal tax returns, avoiding double taxation. Simplifies tax reporting Flexible Management Structure Offers member-managed or manager-managed options customized to your needs. Adapts to business dynamics With no requirement for annual meetings or extensive record-keeping, LLCs provide a simpler operational structure compared to corporations. Furthermore, they can have an unlimited number of members, promoting diverse ownership structures, including individuals and other businesses. These benefits contribute to the LLC’s growing popularity among small business owners. Drawbacks of an LLC Even though the benefits of forming an LLC are considerable, it’s equally important to contemplate the potential drawbacks that could impact your business. Here are some key considerations: Dissolution Risk: An LLC may dissolve upon a member’s death or bankruptcy, limiting the business’s longevity compared to corporations that can exist indefinitely. Self-Employment Taxes: Members often face self-employment taxes on their share of profits, which can greatly affect your finances. Unclear Roles: Without a well-defined operating agreement, unclear roles and responsibilities may lead to disputes, complicating operations. Capital Contributions: Failing to make the required capital contributions can result in penalties, creating complications in the LLC’s financial structure. These drawbacks can pose challenges for your business, so weigh them carefully before deciding to form an LLC. Types of LLCs When considering the types of LLCs, you’ll find options that cater to different ownership structures. A Single-Member LLC is a great choice if you’re the sole owner, offering personal liability protection whilst simplifying your tax situation. Conversely, a Multi-Member LLC allows two or more owners to share responsibilities and profits, providing similar benefits whilst functioning like a partnership for tax purposes. Single-Member LLCs A single-member LLC, which is owned by just one individual or entity, provides a unique blend of benefits that many entrepreneurs find appealing. Here are some key advantages: Limited Liability Protection: Your personal assets are safeguarded from business debts and liabilities. Tax Simplicity: It’s treated as a sole proprietorship for tax purposes, so profits and losses are reported on your personal income tax return, avoiding double taxation. Flexible Management: You can make all business decisions without needing a formal management structure or operating agreement. Reduced Formalities: Unlike corporations, single-member LLCs don’t require annual meetings or extensive record-keeping, making them easier to maintain. These features make single-member LLCs an attractive option for solo entrepreneurs. Multi-Member LLCs Multi-member LLCs, which involve two or more owners known as members, offer a collaborative approach to business management and decision-making. This structure allows for shared responsibilities, making it easier to manage the business together. By default, multi-member LLCs are taxed as partnerships, meaning profits and losses pass through to your personal tax returns, helping you avoid double taxation. Members can include individuals, corporations, or other LLCs, providing flexibility in ownership. To guarantee smooth operations, an Operating Agreement is vital; it outlines each member’s roles, responsibilities, profit distribution, and decision-making processes. Furthermore, you can elect to be taxed as an S or C corporation if that’s more beneficial for your financial situation, providing further options for tax management. Common Uses of LLCS Limited liability companies (LLCs) serve various purposes that cater to the needs of different business owners. Here are some common uses of LLCs: Liability Protection for Small Businesses: By forming an LLC, you can limit personal liability for business debts, safeguarding your assets from lawsuits. Professional Groups: Doctors, attorneys, and accountants often create LLCs to enjoy liability protection while benefiting from management and tax flexibility. Real Estate Investments: If you’re a real estate investor, holding property in an LLC allows you to manage multiple properties under one entity, reducing risk associated with each property. Family Businesses: Many family-owned businesses register as LLCs to simplify succession planning and change management, in addition to protecting family members from personal liability. These uses demonstrate how LLCs can be versatile tools for various types of businesses, helping to address specific needs and concerns. Frequently Asked Questions How Do LLC Owners Make Money? LLC owners make money primarily through profit distributions, which align with their ownership percentages or as specified in the operating agreement. These profits are reported as personal income, benefiting from pass-through taxation, thereby avoiding double taxation. Furthermore, members can earn guaranteed payments for their services, providing consistent income. Owners may likewise choose to reinvest profits into the business for growth, enhancing future earning potential and, in some cases, elect S corporation taxation for tax savings. What Is the Disadvantage of an LLC? One disadvantage of an LLC is that it may dissolve if a member dies or goes bankrupt, which can disrupt business continuity. Moreover, members face self-employment taxes on profits if they choose pass-through taxation, potentially raising their tax burden. Without a solid operating agreement, roles can become unclear, leading to disputes. Finally, LLCs aren’t ideal for those planning to go public, as they’ve limitations on stock issuance and fundraising opportunities. How Does an LLC Work for Dummies? An LLC, or Limited Liability Company, combines the flexibility of a partnership with the protection of a corporation. When you form an LLC, you file Articles of Organization with your state. This structure shields your personal assets from business debts. Profits and losses pass through to your personal tax return, avoiding double taxation. You’ll additionally enjoy fewer formalities compared to corporations, making management simpler for small business owners like you. What Is the Purpose of Having an LLC? The purpose of having an LLC is primarily to provide you with limited liability protection. This means your personal assets are typically safeguarded from business debts and liabilities. Furthermore, an LLC allows for flexible management structures and benefits from pass-through taxation, simplifying your tax obligations. With the ability to include multiple members, an LLC serves as a versatile option for various business ventures, making it a popular choice among entrepreneurs. Conclusion In conclusion, an LLC offers a flexible business structure that combines liability protection with tax benefits. By forming an LLC, you can safeguard your personal assets as you enjoy pass-through taxation and operational adaptability. Although there are advantages, it’s crucial to evaluate potential drawbacks and the specific type of LLC that best suits your needs. Comprehending how LLCs work can help you make informed decisions for your business, ensuring you choose the right path for your entrepreneurial goals. Image via Google Gemini This article, "How Do LLCs Work?" was first published on Small Business Trends View the full article