Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
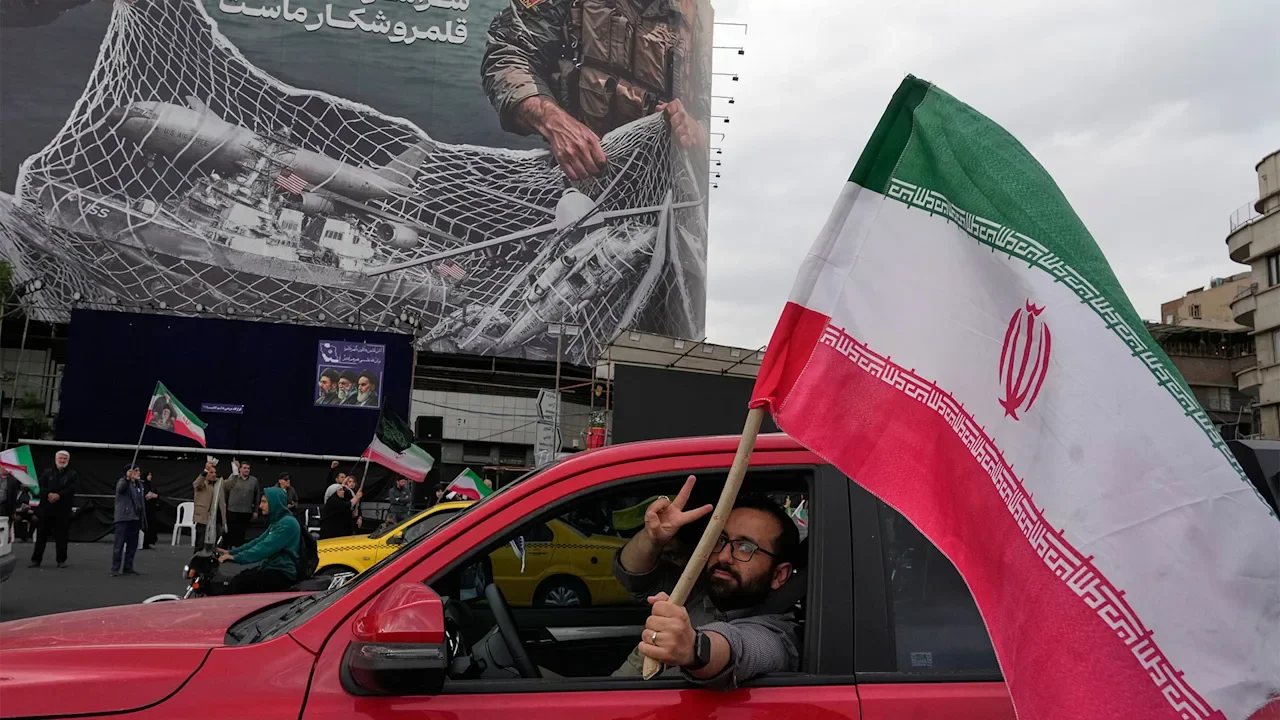
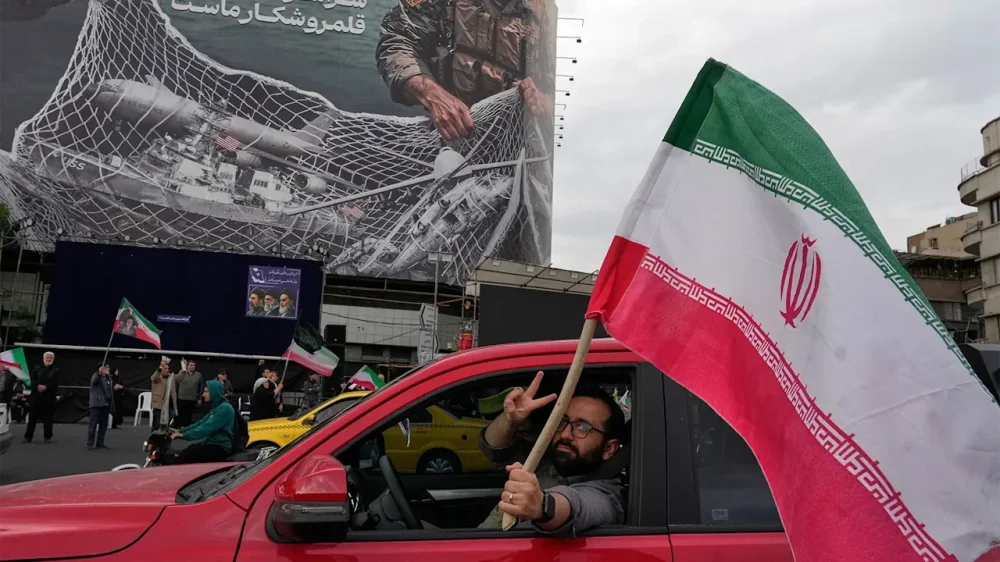
The standoff between the United States and Iran deepened Tuesday as the U.S. declared it had blockaded Iran’s ports, Tehran threatened to strike targets across the region, and Pakistan said it was racing to bring the sides together for more talks. Though last week’s ceasefire appeared to hold, the showdown over the Strait of Hormuz risked reigniting hostilities and deepening the region-wide war’s economic fallout. Talks aimed at permanently ending the conflict — which began Feb. 28 with U.S. and Israeli strikes on Iran — failed to produce an agreement last weekend, though Pakistan has proposed hosting a second round in the coming days. Two Pakistani officials, who spoke on condition of anonymity because they weren’t authorized to discuss the matter with the media, said that the first talks were part of an ongoing diplomatic process rather than a one-off effort. Two U.S. officials, who spoke on the condition of anonymity to discuss sensitive diplomatic negotiations, said on Monday that discussions were still underway about a new round of talks. They said that the venue, timing and composition of the delegations hadn’t been decided, but that talks could happen Thursday. The war, now in its seventh week, has jolted markets and rattled the global economy as a great deal of shipping has been cut off and airstrikes have torn through military and civilian infrastructure across the region. The fighting has killed at least 3,000 people in Iran, more than 2,000 in Lebanon, 23 in Israel and more than a dozen in Gulf Arab states. Thirteen U.S. service members have also been killed. Tanker reported rounding the corner The blockade is intended to pressure Iran, which has exported millions of barrels of oil, mostly to Asia, since the war began. Much of it has likely been carried by so-called dark transits that evade sanctions and oversight, providing cash flow that’s been vital to keeping Iran running. Both the nature of enforcement and the extent to which ships will comply remained unclear during its first full day in effect on Tuesday. Tankers approaching the strait on Monday turned around shortly after it took effect, though one turned around and transited the waterway early Tuesday. The tanker Rich Starry had been waiting off the coast of the United Arab Emirates, according to shipping data firm Lloyd’s List, which cited data from the energy cargo-tracking firm Vortexa. It wasn’t immediately clear whether the Rich Starry had earlier docked in Iran. Yet it is listed by the U.S. Treasury’s Office of Foreign Assets Control as linked to Iranian shipping. Lloyd’s List, citing ship registry and tracking data, reported that it’s owned by a Chinese shipping company and ultimately bound for China. U.S. Central Command didn’t immediately respond to questions about the vessel after it cleared the 21-mile-wide (nearly 34-kilometer) waterway. A day earlier, it said that the blockade applied to vessels going to and from Iranian ports. Since the start of the war, Iran has curtailed maritime traffic, with most commercial vessels avoiding the waterway. Iran’s effective closure of the strait, through which a fifth of global oil transits in peacetime, has sent oil prices skyrocketing, pushing up the cost of gasoline, food and other basic goods far beyond the Middle East. U.S. President Donald The President on Monday said that Iran’s control of the strait amounted to blackmail and extortion as the U.S. blockade took effect. He said in a social media post that Iran’s navy had been “completely obliterated,” but still had “fast attack ships.” He warned that “if any of these ships come anywhere close to our BLOCKADE, they will be immediately ELIMINATED.” Iran threatened to retaliate against Persian Gulf ports if attacked. “If you fight, we will fight,” Iran’s parliamentary speaker, Mohammad Bagher Qalibaf, said in a statement addressed to The President. French President Emmanuel Macron and British prime Minister Keir Starmer will co-chair a conference Friday for nations willing to deploy warships to escort oil tankers and container ships through the Strait of Hormuz. The deployment will happen “when security conditions allow,” Macron’s office said Tuesday. Israel and Lebanon scheduled for talks Meanwhile, direct talks between Israel and Lebanon were set to begin in Washington on Tuesday, the first such negotiations in decades. Israel has pressed ahead with its air and ground campaign since last week’s ceasefire in Iran, insisting that it doesn’t apply to fighting in Lebanon. It has, however, halted strikes in the country’s capital since April 8, after a deadly bombardment that hit several crowded commercial and residential areas in central Beirut. It sparked an international outcry and threats by Iran that it would end the ceasefire. After more than a year of near-daily strikes in southern Lebanon, Israel escalated its offensive in the early days of the war following Hezbollah launching rockets into Israel. The fighting has carved a path of destruction from agricultural towns near the border to Beirut, killing more than 2,000 people and displacing in excess of 1 million others, according to Lebanese authorities. The talks are expected to be preliminary, focused on setting parameters rather than resolving core issues. Lebanese officials have pushed for a ceasefire, while Israel has framed the negotiations around Hezbollah’s disarmament and a potential peace deal, without publicly committing to halting hostilities or withdrawing its forces. Israel wants Lebanon’s government to assume responsibility for disarming Hezbollah, much like was envisaged in a November 2024 ceasefire. But the militant group has survived efforts to curb its strength for decades and said on Monday that it won’t abide by any agreements that may result from the talks. Aamer Madhani, Matthew Lee and Farnoush Amiri contributed to this report. —Munir Ahmed and Sam Metz, Associated Press View the full article
-
Meg O’Neill plans to return BP to structure before its complicated 2020 reorganisationView the full article
-
Demand drops 3.4% in March due to soaring prices, supply shortages and collapse of Middle East air travelView the full article
-
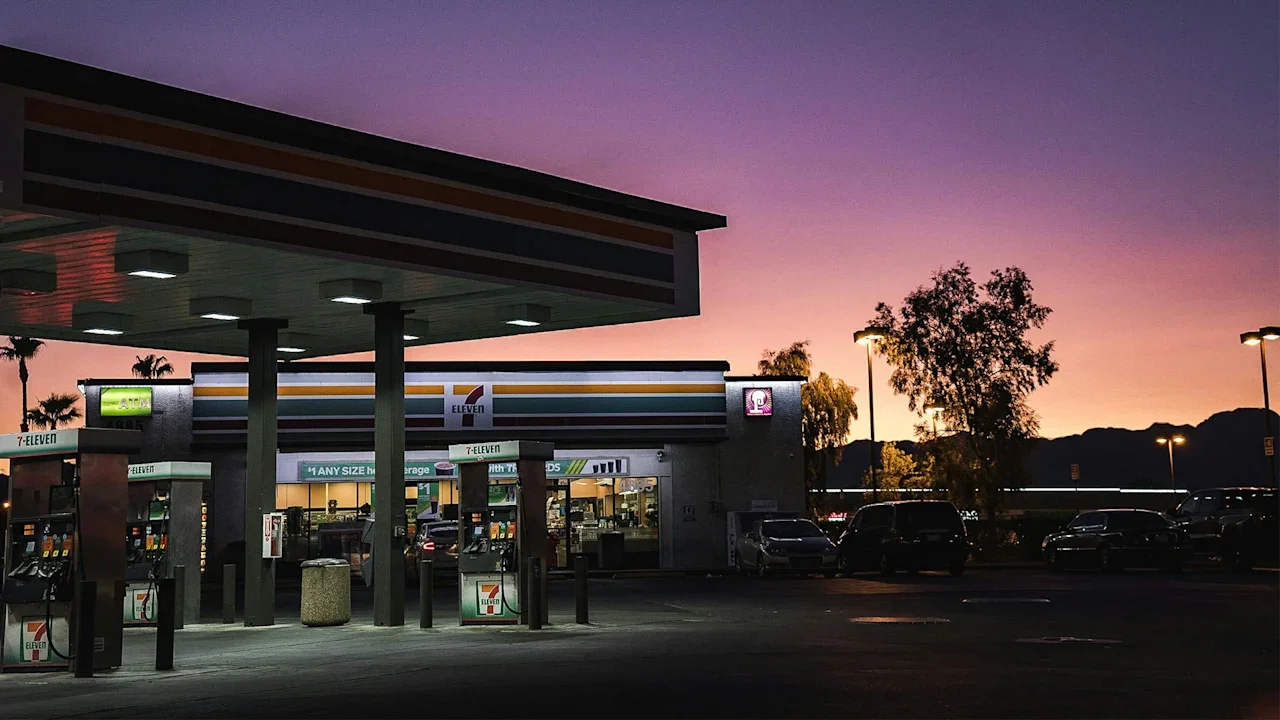
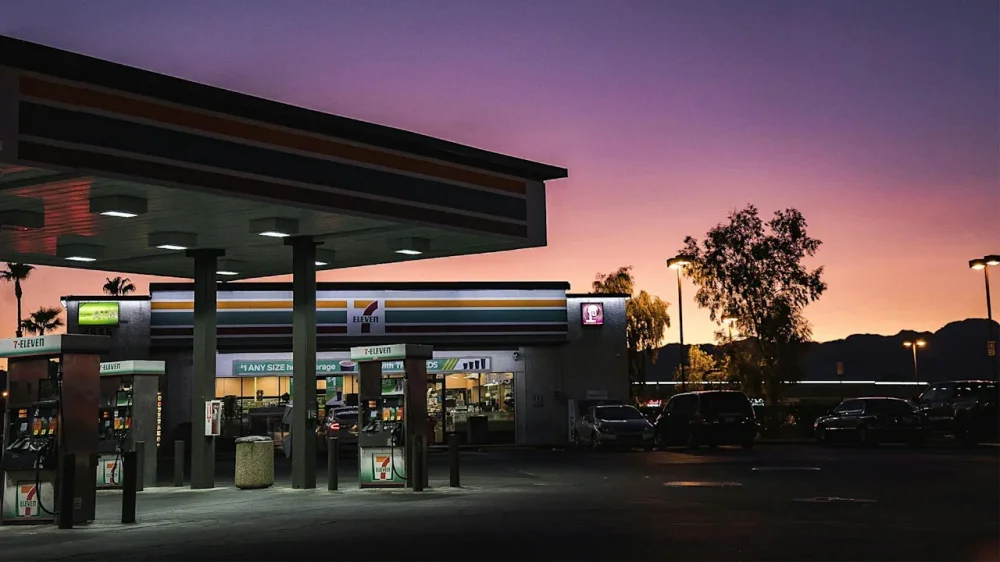
Seven & i Holdings, the Japan-based owner of 7-Eleven, has announced that it plans to close hundreds of stores in North America over the next year. The store closures are an attempt to reduce costs and increase profitability for the chain of convenience stores ahead of a U.S. initial public offering for its North American unit, which was recently delayed. Here’s what you need to know. 645 store closures in North America Tucked away in Seven & i Holdings’ brief summary for its fiscal year 2025 last week was news that the company plans to close more than 1,000 locations in its fiscal year 2026, which runs from March 1, 2026, to February 28, 2027. According ot the document, Seven & i Holdings plans to shutter 645 locations in North America. During the same period, 205 new 7-Eleven locations are set to open, meaning a net loss of 440 of the beloved convenience stores is expected. For context, 645 closures represent about a 5% reduction in the company’s current footprint of 12,272 North American locations. However, it should be noted that Seven & i Holdings says some of the closing locations won’t be shuttered entirely. Many 7-Eleven locations in North America sell both gas at the pump and food inside the convenience store. Locations that don’t have an operating convenience store and only sell gas are known as wholesale fuel stores. Seven & i Holdings says that the “645 store closures in the full-year FY2026 forecast include the conversion to wholesale fuel stores.” This means some locations will close their convenience store segment, but continue to operate as gas stations. However, the locations that undergo a transition to wholesale fuel stores only will no longer count as part of the chain’s total footprint, hence a wholesale fuel stores conversion counts as a closure. Which 7-Eleven locations are closing? It’s unknown which of the company’s 12,272 North American locations are closing. Fast Company has reached out to Seven & i Holdings for comment. However, the 645 North American locations aren’t the only 7-Eleven locations that Seven & i Holdings is shuttering over the next year. The company says it will close additional stores internationally, including: 350 in Japan 18 in Australia 30 in Beijing, China 25 in Tianjin, China 10 in Chengdu, China How has 7-Eleven’s delayed IPO impacted closures? While Seven & i Holdings is a publicly traded company in Japan, the 7-Eleven owner has long intended to list its North American operations separately on a U.S. stock exchange. This initial public offering for 7-Eleven was expected to take place this year, but has now been delayed until at least 2027. As the Financial Times reported last week, Seven & i Holdings has announced that the U.S. IPO would be delayed until the company’s 2027 financial year “at the earliest.” That financial year runs from March 1, 2027, until the end of February 2028. The delayed IPO is being driven by the company’s desire to turn around profits at its North American locations ahead of the listing. The company’s North American locations have been hit by declining sales as cash-strapped consumers cut back on spending. The ongoing U.S. war with Iran is also not helping the company’s bottom line, as it is raising fuel prices, thereby eating into profits. Companies also tend to cut costs wherever they can before an IPO to help present a better bottom line to potential investors. So the upcoming IPO is also likely having an impact on Seven & i Holdings’ decision to close hundreds of North American locations. When will 7-Eleven close its stores? That is unknown. But it is unlikely that the 645 stores marked for closure will all close at once. Instead, locations will likely close individually throughout Seven & i Holdings’s 2026 fiscal year. That fiscal year runs until February 28, 2027, so expect the 645 North American locations to be closed by that date. View the full article
-
UK carmaker tests limits of the market with its personalised vehicles for the super-richView the full article
-
Saying “my back hurts” is a bit like saying “my car is making a noise.” It may be serious, or it may be nothing, and only a professional will know for sure. But if you have back pain, especially in your lower back, you’re not alone: By some estimates, 75% of us will have an achy lower back at some point in our lives, often without any obvious cause. I cannot diagnose your back pain over the internet. That said, I can tell you about common reasons for back pain, and provide general strategies that can help you feel less achy. Back pain doesn’t always mean you’re injuredWe tend to assume that pain is a sign that some part of our body is damaged and needs fixing. But that’s not always true. When it comes to back pain, around 90% of the time there is no detectable injury. That doesn’t mean that the pain is imaginary—there can be physical causes that don’t show up on x-rays or MRIs, and other factors also contribute to us feeling a sensation of pain. Doctors and scientists used to think of pain as a simple signal sent from damaged body parts to the brain. It’s now considered more accurate to say that pain is a perception created in the brain in response to a variety of things we experience. Tissue damage can be one of them, but our experience of pain is also shaped by our expectations, our fears, and other things going on in our brain and body. You might feel pain more acutely if you’re stressed or worried about it. This increases your stress, and things snowball from there. Or maybe you’ve been to the doctor about something that was worrying you, only to find out that the issue is actually very minor, and you’ll be fine. It’s not unusual to experience less pain from that point onward, even though nothing has physically changed. Obviously, there are back problems that are physical and fixable, so it’s definitely worth getting checked out to rule out serious issues. But if you just have an achy back sometimes and your doctor says nothing is seriously wrong, what can you do? A strong back tends to be a healthier backExercise tends to help people with low back pain feel better, according to a 2021 meta-analysis of trials that included everything from strength training to Zumba. If you’re dealing with pain on a daily basis, the first step doesn’t have to be finding the “best” exercises to deal with it. Instead, focus your efforts on finding something you can do without experiencing pain, or at least without increasing your pain. A physical therapist can help guide you through this process, especially one who specializes in sports medicine or who has experience working with active people. (Some physical therapists prescribe exercises that are too easy to be effective, especially to older adults; this is a recognized problem in the industry.) There is still disagreement on exactly what kind of exercise is best to prevent or treat back pain. Some PTs focus on core work, believing that it’s crucial for your deep core muscles, such as the transverse abdominis, to be strong to protect your back. Using this approach, you may find yourself doing a lot of dead bugs and bird dogs, and get a lot of practice drawing your belly button in toward your spine. Another school of thought holds that core muscles are only a small part of the picture, and that strengthening your back muscles themselves should be the focus of training. This approach is more likely to favor work with free weights, like deadlifts, dumbbell rows, and lunges. Done correctly, these moves also work your core; you need to brace your core to stabilize your spine for a deadlift or squat, and that’s as legitimate a type of core work as anything you do on a yoga mat. Sore muscles are okay, actuallyIt’s normal to be concerned about protecting your back. After all, if you’ve heard a million times not to “lift with your back,” you might worry that any soreness after lifting or bending means you injured something. But there are muscles in your back, and they can get fatigued or sore when you use them a lot—just like the muscles in your arms or legs. You wouldn’t be surprised or worried if you had sore thighs after a heavy squat day or after running a race. The muscles in your lower back can feel sore after your deadlift day at the gym, or even after a long day of standing and walking more than you’re used to. Sometimes people confuse this normal soreness with injury, and worry that those deadlifts did something terrible to their back. But before you panic, consider treating your back the same way you would any other sore muscle: Use gentle heat, walk around a bit, and consider foam rolling or massage. The pain from sore muscles tends to feel a bit better with activity, and will usually fade within a few days. Stretches and exercises that are good for people with back painWhat exercises can you do to potentially prevent back pain and possibly manage back pain you already have? Again, it’s best to check with a professional to be sure of what makes the most sense for you, but here are some strengthening and stretching exercises that are often recommended: Core exercisesBird dogs Dead bugs Planks Side planks Back-strengthening exercises (with barbells, dumbbells, or kettlebells)Deadlifts or Romanian deadlifts Rack pulls or block pulls Bent-over rows Split squats or your favorite regular squat Reverse hypers StretchesCat/cow Jefferson curls Figure 4 stretch Spinal twist Lying hamstring stretch View the full article
-
CoreWeave is having a very eventful week, and its stock price reflects it. Shares of the AI cloud-computing firm (Nasdaq: CRWV) are up more than 37% in five days following deals with Meta Platforms and Anthropic. On Thursday, April 9, CoreWeave announced a six-year agreement with social media giant Meta, parent company of Facebook and Instagram. CoreWeave will supply AI cloud capacity to Meta through December 2032. “The dedicated capacity will be deployed across multiple locations and will include some of the initial deployments of the Nvidia Vera Rubin platform,” CoreWeave stated in a release. “This distributed approach is designed to optimize performance, resilience, and scalability for Meta’s AI operations.” The agreement is worth about $21 billion for CoreWeave. Then, on Friday, April 10, the company announced another deal, this time with Anthropic. The multi-year agreement will see CoreWeave support Anthropic’s development and deployment of the latter’s Claude AI models. The plan is to bring compute online by the end of the year. “CoreWeave joins Anthropic’s growing ecosystem of infrastructure partners helping to scale the adoption of Anthropic’s AI models across developers, startups, and enterprises worldwide,” the company stated in another release. “With the addition of Anthropic, nine of the leading ten AI model providers now leverage CoreWeave’s platform, reflecting the growing demand for infrastructure that can support AI at scale.” Analyst goes from hold to buy In response to these developments, Macquarie analyst Paul Golding upgraded CoreWeave’s position from Hold to Buy. Golding further increased its target price from $90 to $125 per share. Currently, it’s at about $115 per share. As of early Tuesday, CoreWeave shares are up another 4.53% in premarket trading. The stock has increased 39% year to date. Although it has been volatile along with many tech stocks in 2026, CoreWeave has far outperformed the broader Nasdaq Composite, which has declined 0.22% over the same period. View the full article
-
“I would like to introduce our Principal Auctioneer for the Broad Arrow sale today, Lydia Fenet at the Amelia.” As I walk up the steps to the podium to take my place next to the auction reader, I look out at a packed room of over a thousand people sitting and standing around the room. 10, 9, 8. Adrenaline floods my body. Deep breath in. Deep breath out. 7, 6, 5. Shoulders back. Chin up. Eyes forward. I listen as the reader finishes the last minute sale announcement and gives a brief description of the first car we will be selling. 4, 3. As he is finishing the description I open the binder that holds all the auction information in front of me, glancing at the reserve price which is the amount agreed upon by the seller and the company to make sure the number is fully in my head. 2, 1. Lydia, Lot Number One. I lift my head, smile, and bring the gavel down three times. For the next five hours, I’ll stand onstage representing Broad Arrow as the first woman to serve as Principal Auctioneer for a major car company. For some, seeing a woman preside over a car auction, where men have traditionally held the gavel, still feels surprising, maybe even a little uncomfortable. But after more than twenty years refining my craft, I have complete confidence in my ability to command a room. Over a career as a charity auctioneer that has helped raise more than $1 billion for nonprofits around the world, I’ve developed techniques that allow me to perform at the same level, regardless of the size of the stage or the prominence of the audience. The beauty of those techniques is that they work anywhere. No matter the pressure or the people in front of you, the same strategies that hold a room at auction work just as well in the boardroom. Find Your Strike Method In my first book, The Most Powerful Woman in the Room Is You, I introduced what I call The Strike Method. The three cracks of the gavel against the podium serve two purposes. They steady my nerves and focus the surge of adrenaline that comes with stepping into a high pressure moment. That rush is universal. It can unsettle even seasoned speakers, and it can overwhelm someone who hasn’t spent a lot of time onstage. The Strike Method narrows my focus to a single, controllable action. When the gavel hits the podium, everything else fades. It allows me to step onto any stage and command attention with intention. Everyone needs a version of The Strike Method. It might be a mantra. It might be a small object that reminds you of your strength. Some people tap the underside of their desk before a meeting and whisper, “Here we go,” before they begin a Zoom call. A friend of mine carries a small red pebble in her pocket when she walks into a presentation. The ritual matters because it centers you. Once you use it, have your opening lines ready so you move forward with complete control. Equally important is what happens next. If you are a nervous public speaker, make sure you have lined up your next sentence so that no matter what happens you are already locked in. The minute you start speaking onstage the adrenaline dissipates so the further into your speech you can go, the easier it will be. Mindset Over Everything Ask someone why they fear public speaking and they will describe the physical sensations. Shaking hands, a dry mouth, the feeling of standing at the top of a roller coaster. Even the most seasoned performers feel the same sensations. The difference is how they interpret them. Instead of labeling those feelings as fear, see them as energy. Your body is preparing you to rise to the moment. Think of that energy as fuel and channel it toward the outcome you want to create in the room. Your Audience Wants You to Succeed One of the fastest ways to derail a presentation is to obsess over how you are being perceived. Remember this: your audience wants you to succeed. No one wants to sit through a bad presentation. Think of the audience as your supporters. They are hoping you will deliver something worth their time. When you focus on serving them rather than judging yourself, your confidence grows. Give them your full presence and they will respond in kind. View the full article
-
Twenty-six years ago a Lebanese militant leader stood in Bint Jbeil to hail a landmark Israeli retreat. Now the IDF is set to take the townView the full article
-
The call comes on a Tuesday morning. Taiwan Strait tensions have escalated overnight. Markets are already moving. Your CFO is on one line, your General Counsel on another. By the time you’ve hung up, your head of communications is in the doorway. Most CEOs have planned and prepared for this moment. In my work running a global communications firm, I’ve been part of the war-gaming sessions. But I’d contend that most leaders aren’t ready for it. Not because they haven’t been paying attention to geopolitics—they have. But because their teams have been assessing the Taiwan risk through a single lens: geoeconomic exposure. The financial model has been stress-tested. The team has contingencies for supply chain disruption, semiconductor access, and revenue at risk in Asia-Pacific. What hasn’t been stress-tested is everything else. For most companies today, a crisis in the Taiwan Strait won’t arrive purely as a geoeconomic event. It will cut across the four modern risk domains—political, economic, cultural, and technological. Companies that have only prepared for one will be managing the other three in real time. The four modern risk domains Political Risk Your company’s existing posture in China becomes a liability overnight. Your joint venture in Shenzhen, the market access statement you made two years ago, and the politically-connected hire you made in Beijing are all read through a new lens by lawmakers in Washington and Brussels. Economic Risk The first casualties aren’t on the balance sheet—they’re in the narrative. A Substack reporter with 200,000 subscribers publishes a thread mapping your China revenue exposure—incomplete and partially wrong, but specific enough to travel. Within 24 hours, AI-driven research tools have ingested it, flagged your ticker, and surfaced it in portfolio managers’ morning briefings. By the time your team is returning calls, two analysts have downgraded their outlook. Cultural Risk Within hours, an internal petition circulates among your workers: “Don’t use this as cover to shift production to cheaper markets and call it patriotism.” It gets screenshotted. It lands on X. A mid-level manager’s LinkedIn post about “what this company really stands for” gets ten thousand shares before your team has even seen it. The fault lines already forming around AI displacement, economic anxiety, and corporate trust crack open wider. Technological Risk The geopolitical tension brings data security and reputation into collision. You are hit with a sophisticated ransomware attack that paralyzes key systems. Within hours “OSINT” social feeds, Taiwanese state media, and others are attributing the attack to China. You aren’t sure where the attack has come from, but narrative is outstripping assessment. On Reddit threads, you’re accused of concealing China’s involvement. The Single-Lens Problem Most companies are not ignoring risk. But they’re assessing it through a single domain, while the threat is multidimensional. Consider this: A major financial institution announces it will eliminate a significant share of its analyst workforce due to AI-driven efficiencies. It’s a technology and efficiency-driven decision. Share price volatility hits the markets as soon as it becomes public. The political and regulatory environment—already sensitized to AI’s workforce implications—sharpens its focus. Employees take to social media, followed by customers. Or this: A global manufacturer, caught between U.S. and Chinese trade policy on a critical issue, announces it will reduce reliance on Chinese manufacturing for U.S.-bound goods. It warns investors—then finds itself targeted by an AI-generated content campaign mocking U.S. trade policy. Chinese influencers encourage American customers to buy direct, bypassing the manufacturer entirely. All of this spreads before the company can frame a coherent response. These are not hypotheticals. They’re real events that occurred at major multinational corporations within the past year. Navigating The New Era The modern risk environment demands a different approach—one that treats political, economic, cultural, and technological exposure as interconnected by default. Every domain of risk in the modern era is ultimately experienced as narrative—by investors, regulators, employees, and customers. The mandate for modern corporate affairs teams is to bring upstream intelligence on how decisions will land before they’re made, which demands a new conversation inside the C-suite. What’s needed is a genuine, integrated assessment—political, economic, cultural, and technological exposure mapped together—before the Tuesday morning call comes. The companies that build this discipline won’t just manage risk better. They’ll be faster to act, and more credible and better positioned when they do. When a single geopolitical trigger can cascade across all four domains in 24 hours, the capacity to navigate across all of them isn’t defensive. It’s the foundation for value creation. View the full article
-
Shake-up spurred on by rise of AI and threat of major upheaval across the industryView the full article
-
Have you noticed the junk-food aisle at your local grocery store is looking a little, well, funky lately? Blame the youngest generations of shoppers. While the preferences of Gen Z and Gen Alpha consumers are likely leading to healthier choices for all of us, they’re also reshaping the snacking industry. Some changes include snacks that are available in smaller sizes and have cleaner ingredients, according to data from Nielsen IQ, as reported by the National Association of Convenience Stores (NACS), an industry trade group. One of the most consequential changes is that shoppers are seeking out healthier snacks. Among parents of Gen Alpha kids who are buying snacks for the household, Nielsen IQ (NIQ) research has found that 35% are prioritizing natural ingredients and 34% said they’re looking for high-protein options. Meanwhile, about one-in-four shoppers actively avoid buying ultra-processed snacks and a comparable share look for snacks that don’t have artificial ingredients. That means shoppers are carefully scrutinizing ingredients and looking for products that bear organic claims or gluten-free certifications. And young shoppers don’t necessarily take brands at their word—compared with older shoppers, they’re far more likely to use third-party mobile scanning apps to evaluate foods and closely compare products, according to NIQ figures. “The baseline for Gen Alpha is a better product. It’s a cleaner product. It’s a more transparent product,” Chris Costagli, vice president of thought leadership at NIQ and the lead for food and non-alcoholic beverage insights, told NACS. BETTER-FOR-YOU SNACKS The evolution of snacking preferences can also be explained by health trends, John Baumgartner, an analyst at Mizuho, wrote in a note to clients last week. That’s seen a rising demand for more functional snacks, including snack bars, meat snacks, and fruit snacks, as Barron’s recently reported. Protein-packed snacks are the top snack trend for 2026, according to Innova Market Insights, while snacks that deliver gut health benefits are also gaining in popularity. The U.S. market for “better for you” snacks, which raked in nearly $13 million in 2024, is expected to grow at a compound annual growth rate of 7.4% to reach $19.8 million by 2030, according to projections by Grand View Horizon. SMALLER SIZING But cash-strapped younger shoppers may also be contributing to the frustrating trend of shrinkflation—in which package sizes get smaller but the price doesn’t budge (or even, potentially, increases). Because Gen Z shoppers prioritize lower unit prices versus bulk savings, that makes smaller pack sizes more appealing, according to Costagli. Shrinkflation is such a popular topic of discussion that there’s a subreddit devoted to it that attracts more than 88,000 people weekly. It’s also on the radar of the Bureau of Labor Statistics, as examples of shrinkflation are treated as a price increase when calculating inflation numbers, according to a Federal Reserve report. While the latest consumer price index report showed that inflation rose at the fastest annual clip since April 2024, Americans aren’t likely to give up snacking—something that about three-quarters of consumers do daily, according to Innova Market Insights surveys. Instead, we may have to be satisfied with the smaller packaging we’re finding at stores. Companies have already started churning out a wider range of shrunken snack sizes—a trend that’s likely to continue, as The Wall Street Journal reported in July. “Consumers are going into small pack sizes to optimize their absolute budget,” Luca Zaramella, the chief financial officer for Mondelez International, told the publication at the time. “The $3, $4 as opposed to the $6, $7, particularly in snacks, are becoming a clear center of gravity.” View the full article
-
Hello and welcome to Modern CEO! I’m Stephanie Mehta, CEO and chief content officer of Mansueto Ventures. Each week this newsletter explores inclusive approaches to leadership drawn from conversations with executives and entrepreneurs, and from the pages of Inc. and Fast Company. If you received this newsletter from a friend, you can sign up to get it yourself every Monday morning. “If you elegantly avoid the subject of money,” says Emma Grede, “money will somehow elegantly avoid you.” Grede is most certainly not avoiding the subject of money, ambition, or other topics some women may consider taboo. In her new book, Start With Yourself: A New Vision for Work and Life, the Skims and Good American cofounder aims to dismantle “Old Thoughts” and biases, including the way women talk—or don’t talk—about wealth. She notes that there are many reasons for the reticence: many women are acculturated to believe that talking about money is impolite, or worse, selfish. “I think sometimes that there is this misconception that if somebody is really focused on the money that they have nothing else that they care about,” she says. “And that’s just not the case.” Indeed, she says, women should embrace the idea of being well compensated for doing work that they find personally rewarding. “What I want to do is to connect this idea that you can do deeply meaningful and impactful work and still be paid for it,” she says. Grede’s perspective reminds me of a piece I wrote about in 2020, encouraging affluent women to earmark some of the money they donate to charity for backing female-founded startups. Women “give a tremendous amount of money, and they have things they believe in,” investor and entrepreneur Kay Koplovitz told me at the time. “But they can also invest in missions and values they hold dear.” Growing to give back Little seems to have changed since then. Research from HSBC finds that affluent women prioritize saving for retirement over investing at every stage of life. Women in their 20s say planning for children is their top financial priority; caring for aging parents is the No. 1 financial goal for women in their 40s. The data support one of Grede’s observations: “I see far too often women thinking about everybody else in their lives before they think about themselves— and before they think about their ability to grow that money to make more money,” she says. And Grede believes that making money—at a company or attaining personal wealth—supports philanthropic and purpose-driven efforts rather than detracting from them. “I’ve always had companies that have done really great important work and been able to give back once they’re profitable,” she says. “We have to put money at the center of the conversation. We have to start with money in the same way that we have to start with ourselves.” With women set to control 40% of global wealth by 2030, according to HSBC, Grede’s message feels especially urgent. Your AI questions answered Next month, Modern CEO subscribers will have an opportunity to hear join me in conversation with Matt Fitzpatrick, CEO of Invisible Technologies, discussing the most urgent AI issues of the day. Register here and submit your burning questions to stephaniemehta@mansueto.com, and we’ll try to tackle as many as possible in the live session on May 18 at 1 p.m. ET/10 a.m. PT. Read more: Emma Grede’s world Skims was No. 1,168 on the 2024 Inc. 5000 ranking. Is it ready for an IPO? Female founders on what helped them level up Emma Grede says remote work is sabotaging careers View the full article
-
When I launched TaskRabbit in 2008, I thought entrepreneurship was about persistence. The narrative in Silicon Valley was simple. If you believe in an idea strongly enough and push hard enough, success eventually follows. Years later, after building TaskRabbit into one of the companies that helped define the early gig economy, I started hosting a podcast called “Breaking Precedent.” I wanted to talk with founders, investors, and innovators who had changed the rules in their industries. What I expected to hear were stories about grit and determination. What I actually heard were stories about something else entirely. Again and again, the most pivotal moments in their journeys were not about staying the course. They were about changing it. After dozens of conversations, a clear pattern emerged. The leaders who ultimately break precedent are not the ones who stubbornly defend their original plan. They are the ones who recognize when reality has changed and have the courage to pivot. The pivot is not a failure. In many cases, the pivot is the point. Climbing the Wrong Mountain I learned this lesson firsthand while building TaskRabbit. In the early days, our platform looked a lot like eBay. Customers posted a task and workers, whom we called Taskers, bid on the job. The model made perfect sense in 2008. Online marketplaces were built around auctions, and we assumed the same system would work for everyday services. For a while, it did. The platform grew quickly, and we built a vibrant community of users and workers. But by 2012 something fundamental had changed. Smartphones had transformed consumer expectations. People no longer wanted to post a request and wait hours for responses. They wanted help immediately. The more we studied our data, the clearer it became that our marketplace model was slowing the experience down rather than enabling it. Recognizing the problem was one thing. Acting on it was another. By that point we had millions of users, tens of thousands of Taskers, and years of engineering invested in the bidding system. Walking away from that infrastructure felt almost unthinkable. Eventually, we had to admit the truth. The company was not failing. We were simply climbing the wrong mountain. So we rebuilt the platform as a mobile-first, on-demand service where tasks could be booked instantly. Rather than risk the entire company, we first tested the new model quietly in London. The results were immediate. Usage doubled. Customer retention improved dramatically. Revenue followed. That pivot ultimately helped TaskRabbit become profitable and, years later, led to our acquisition by IKEA. At the time, the decision felt terrifying. Looking back, it was the moment the company finally started working the way it was meant to. The Data That Forces a Pivot Once you start listening for these moments, you begin to hear them everywhere. On my podcast, I recently spoke with venture capitalist Ann Miura-Ko about the early days of Lyft. Before Lyft existed, the founders were building a long-distance ridesharing platform called Zimride. It helped people carpool between cities and seemed like a promising idea. Then, a data scientist analyzed their most engaged users. The results were brutal. Their best customers used the platform twice a year. Each ride generated roughly thirty dollars in revenue. In marketplace economics, that combination is extremely difficult to scale. A business built on low transaction values and infrequent usage rarely creates momentum. Instead of ignoring the data, the founders confronted it directly. They held a hackathon and began experimenting with a completely different idea: on-demand rides within a city. That experiment eventually became Lyft. What stands out about the story is that the pivot was not driven by inspiration or creativity. It was driven by honesty about what the numbers were saying. Pivoting the Path, Not the Dream The pivot does not only appear in startup stories. One of the most memorable conversations on Breaking Precedent came from Dr. Eiman Jahangir. For most of his life, Eiman had one dream. He wanted to go to space. He pursued the traditional path. He built an impressive medical career and applied to NASA’s astronaut program multiple times. He even made it to the final rounds. Each time he came close, but each time he was ultimately rejected. Most people would have taken that as the end of the road. Eiman saw it differently. Instead of abandoning the dream, he changed the path. As commercial spaceflight expanded, he explored alternative routes into the industry and eventually entered a decentralized organization’s lottery for a seat on a rocket. Against extraordinary odds, he won. Last year, he became the 705th human in history to travel to space. His story captures something entrepreneurs understand deeply. Sometimes the vision is right. The path simply is not. The Leadership Pivot What I have come to appreciate through these podcast conversations is that pivoting is not simply a tactical move. It is a leadership decision. Pivoting requires founders and leaders to admit that the original plan might be wrong. It requires prioritizing evidence over ego and recognizing that the mission matters more than the strategy used to pursue it. Great entrepreneurs do not pivot because they lack conviction. They pivot because their conviction is focused on the outcome rather than the plan. The mission remains constant. The path evolves. The Pattern Behind Breaking Precedent Across every story I have heard on Breaking Precedent, one pattern stands out. The leaders who ultimately reshape industries tend to pivot earlier than everyone else. They listen closely to signals others ignore. They treat discomfort as useful information. Most importantly, they understand that persistence and adaptability are not opposites. When I think back to the moment we realized TaskRabbit was climbing the wrong mountain, I remember how much it felt like failure. Today I see it as something else entirely. It was the moment we stopped protecting the past and started building the future. Breaking precedent rarely happens through one dramatic leap. More often, it happens when someone dares to change direction while everyone else is still insisting the original path is the only one. Because the pivot is not the detour. The pivot is the moment the vision finally becomes possible. View the full article
-
After a series of setbacks, the vice-president is no longer The President’s obvious successorView the full article
-
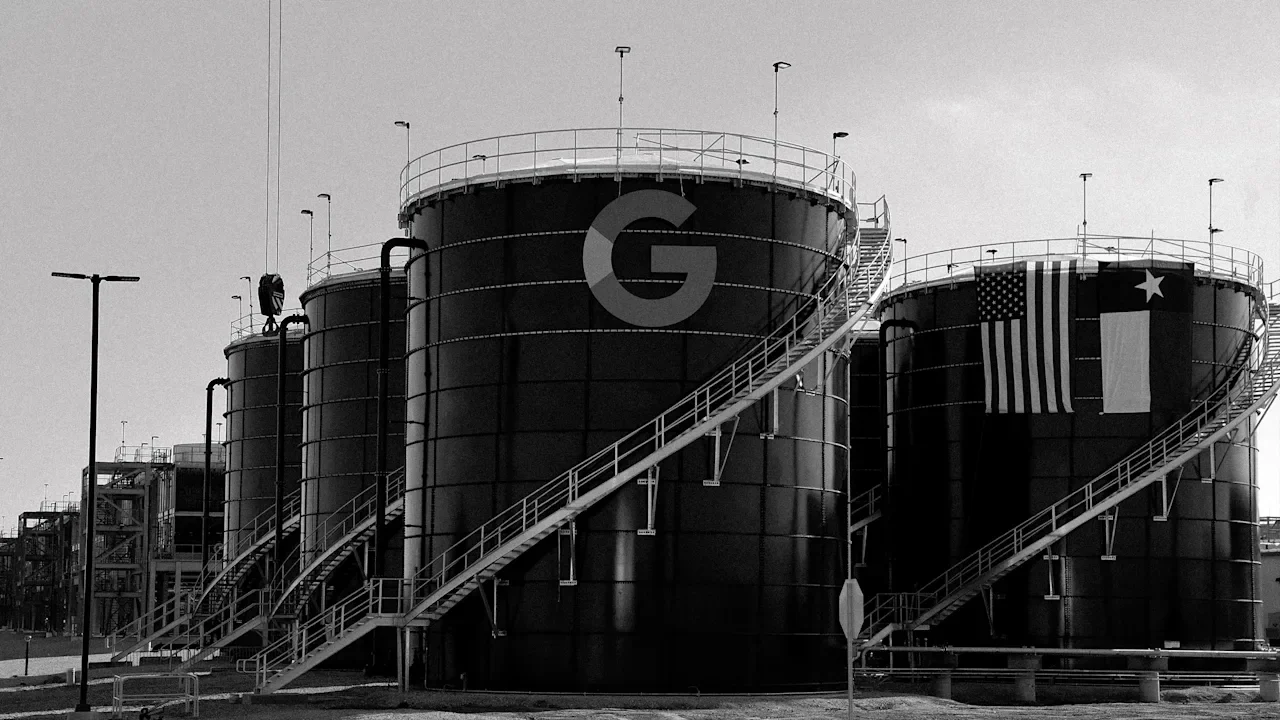
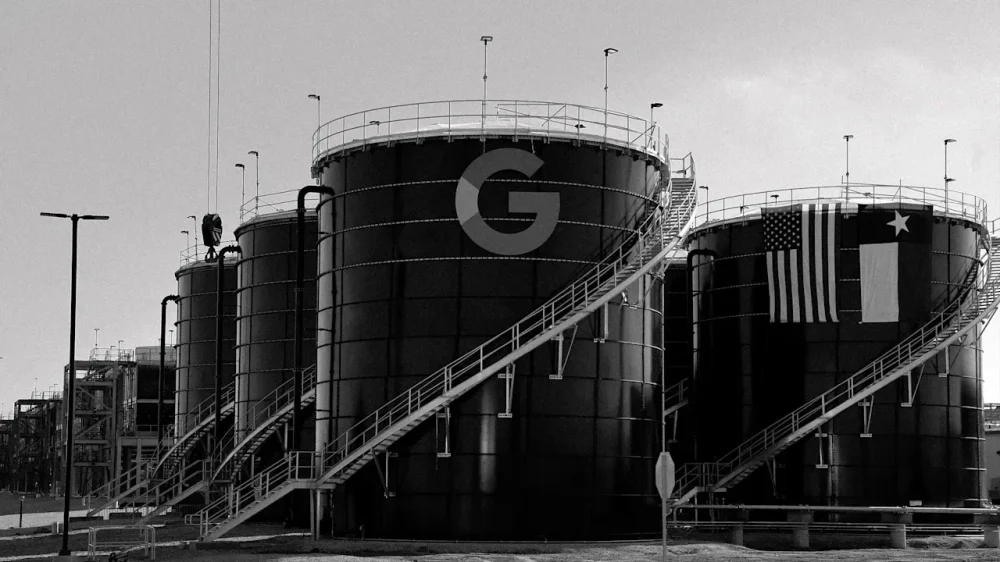
Google’s sustainability webpage once specifically mentioned the company’s goal to reach net-zero emissions by 2030, and included a subpage titled “operating sustainably.” But that pledge has disappeared from the main page, which now highlights the company’s commitment to artificial intelligence. The subpage was renamed “our operations.” Google maintains that it is still aiming for a 2030 goal, though executives have acknowledged that the growth of AI makes it challenging. Still, the change to the sustainability page is an example of how tech companies are being a bit quieter about their climate goals as they expand their use of AI. The explosive growth of data centers to support the AI surge is “calling into question” whether the major tech companies—Google, Meta, Microsoft, Apple, and Amazon—can meet their pledges to reduce emissions, according to a 2025 corporate responsibility report from the NewClimate Institute. Already, companies are reporting emissions increases in their annual sustainability reports. Along with complicating their climate goals, the AI push seems to be changing how Big Tech talks about, and even considers, the climate. These companies are “just in a rush to build out as much as they can, and to stay ahead of the competition with new trends with AI,” says Thomas Day, one of the report’s authors, who analyses such commitments for the NewClimate Institute. “Climate appears to be the last thing that they’re thinking about.” Emissions targets have ‘lost their meaning’ When that NewClimate report came out in June 2025, it warned that tech companies’ emissions targets “appear to have lost their meaning and relevance.” It did note that some companies, like Microsoft and Google, had “promising” strategies for how to power data centers with renewable electricity. But already, that outlook is out of date. “Those [companies] that we identified before as having more constructive or ambitious positions have gone relatively quiet,” Day says, “while those pushing for more problematic approaches really doubled down.” Microsoft’s emissions could surge 44% due to just one West Virginia data center that will run entirely on natural gas, according to Stand.earth research. Google also recently announced it will use natural gas to power a massive Texas data center, which could emit, according to one calculation, as much as 4.5 million tons of carbon dioxide a year—more than the entire city of San Francisco. In 2023, Amazon’s operational carbon emissions grew 182% compared to three years prior, according to a 2025 United Nations report, due to higher energy demands to power data centers. Amazon continues to announce new data center investments. Big Tech says AI will help climate goals The five major tech companies all have net zero or carbon neutral commitments by either 2030 or 2040. These companies maintain that they’re committed to those goals and working on sustainability. A Microsoft spokesperson said the company is still committed to being carbon negative, water positive, and zero waste by 2030, and that it continues to expand its clean energy portfolio. A Meta spokesperson said “We’re working towards our goal to achieve net zero emissions across our value chain in 2030.” But online, its language has changed: Meta’s sustainability page previously said the company “commit[s] to reaching net zero emissions” by 2030. Now, the page says “we have set a goal to achieve net zero emissions” by then. And as Big Tech talks about sustainability, it often does so in conjunction with AI. “We remain committed to our ambitious moonshot of reaching net-zero emissions across our operations and value chain,” a Google spokesperson said without specifying a timeline. “Reaching this moonshot will be non-linear and has become increasingly complex. We’re working to build efficiency into every layer of our infrastructure, catalyzing new energy sources like nuclear, geothermal and battery storage, and using AI itself to accelerate climate solutions. ” “Rather than viewing AI as a barrier to sustainability, we see it as an opportunity to pioneer solutions at scale,” an Amazon spokesperson said. “We’re harnessing the power of AI to help us find science-based solutions at a rapid pace while remaining committed to our goal of net-zero carbon by 2040.” The spokesperson added that Amazon is “diversifying its carbon-free energy portfolio, including our first investments in nuclear energy.” A 2025 Microsoft blog noted that its sustainability goals were a “moonshot,” and “nearly five years later, we have had to acknowledge that the moon has gotten further away.” Then it said that the same thing making those goals less attainable now will bring them closer in the future: AI. Apple did not respond to a request for comment. Claims that AI will solve climate change often lack scientific evidence, according to a 2026 report by multiple climate groups. Tech companies also tend to lump together “traditional AI” with the more environmentally harmful generative AI when making such statements, that report said. The actions that tech companies are taking to develop data centers and expand AI are “simply not in line” with their climate pledges,” Day says. “The priority seems to be, put up as many data centers as you can, wherever you can, and make sure there’s enough immediate power to run it,” he says. “And that’s, in almost all cases, going to be gas.” The AI data center boom is directly linked to an increase in natural gas development. The U.S. now has the most gas-fired power capacity in development (including projects that have been announced as well as those in preconstruction and/or construction), according to Global Energy Monitor—with more than a third of that capacity slated to directly power data centers. Regulatory changes could alter climate targets It’s not that tech companies are abandoning their climate pledges, Day notes. But in some cases, they’ve omitted prhases, or changed how they talk about climate. “It feels a bit more like they just put their head in the sand, and no one is really putting pressure on them to clarify their climate pledges,” he says. “The regulatory environment at the moment is not exactly conducive to holding them accountable.” The system of accounting for corporate emissions is currently being revised, and those changes may force companies to reassess their climate goals. The Greenhouse Gas Protocol, which provides emissions accounting and reporting standards for corporations, currently gives companies two ways to count Scope 2 emissions, which are the indirect emissions from a company’s purchase of electricity, steam, heat, or cooling: the location-based method or the market-based method. Location-based refers to the emissions associated with the grid where that energy is consumed. The market-based method means companies can “artificially reduce the emissions they report,” Day says, by buying renewable energy certificates. Take a data center in Ireland, for example. At night in the winter, renewables can’t do much to power that data center—but the company that owns it could buy a certificate from solar panels in the summer based in Spain to claim that that data centers’ emissions are zero. Several companies only report market-based emissions, Day says, and they purchase enough of those certificates to report zero emissions. This is why it can be difficult to glean how well tech companies are doing to reduce emissions based on their own reports. In its most recent sustainability report, for example, Google said it reduced its data center emissions by 12%, but that was calculated through the market-based method. But the standards are considering changes that would mean companies can only claim renewable energy certificates from places in the same location, and concerning electricity generated at the same time. “That will make it far more difficult to make these kind of misleading claims,” Day says. “But it’ll also change the targets that companies set, because many of them have just set 100% renewable energy targets, knowing that they can just buy these certificates for peanuts when they have very little impact in reality.” (The Amazon spokesperson said that it wants to ensure its climate effort is “pointed towards decarbonizing the overall electricity system, and that goes far beyond the power that we consume and where we consume it.”) Kicking the climate can down the road This potential change to emissions accounting may be one reason why tech companies are quieter about their climate goals. If that rule goes through and they have to revise their pledges, they may not want to be loud about their current goals. Day questions if counting emissions is even the right framework for tech companies in the AI age, though. Through AI, Big Tech companies are becoming more like financial institutions or marketing companies. They may not have large emissions footprints themselves, but what does matter is who they sell their products to—if they are financing fossil fuel expansion, or doing advertising work for oil companies, for example. Similarly, if an AI tool is being used to ramp up fossil fuel production, or even to improve algorithms that drive up environmentally harmful overconsumption, that’s an impact that goes beyond direct emissions. When it comes to Big Tech, we need to ask “What can climate leadership look like for these types of companies?” Day says. “I think it really requires them to be a bit more selective about how they use AI, and I don’t see it as a very good political environment right now for that discussion,” he notes. Tech companies may be kicking the climate can down the road, figuring that they’ll work it out after the manic rush of the AI buildout cools off. But the planet may not have that time. “It’s quite a frustrating moment for all this to be happening the way it is, because we didn’t get as far as we needed to as a society on all of these objectives over the last 10 years,” Day says. “What we did achieve in the last 10 years was to get a lot of companies talking about climate change, and get them setting targets,” he adds. Opinions about how impactful that was differ, but mentioning climate change seemed to become a norm in business discussions. What needed to happen around 2024, however, was for those pledges to turn more into “high-quality action.” By that time, though, the AI boom was beginning, and companies got on board. “There was the narrative two years ago when this all started to say, ‘Hey, don’t worry so much about our emissions. Look the look how much of a force for good we are, or we can be,'” Day says. But now, “I rather get the sense at the moment that tech just doesn’t talk about climate.” View the full article
-
Washington’s demand that Tehran halt uranium enrichment has been a barrier to progress on talksView the full article
-
Financial institutions that are members could gain access to expedited funding through a Fed partnership and advances secured by a broader range of collateral. View the full article
-
Adjustable rate mortgages accounted for 12% of total home loan volume in March, reaching its highest share of the market since October 2022. View the full article
-
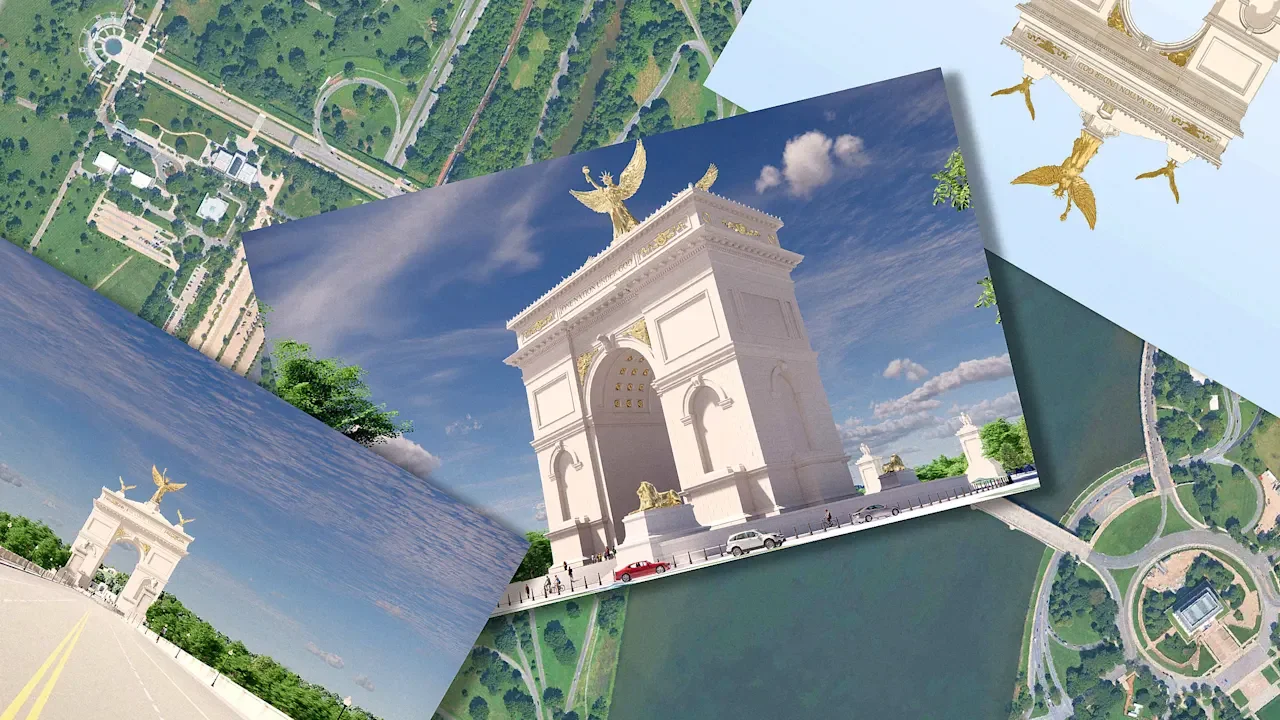
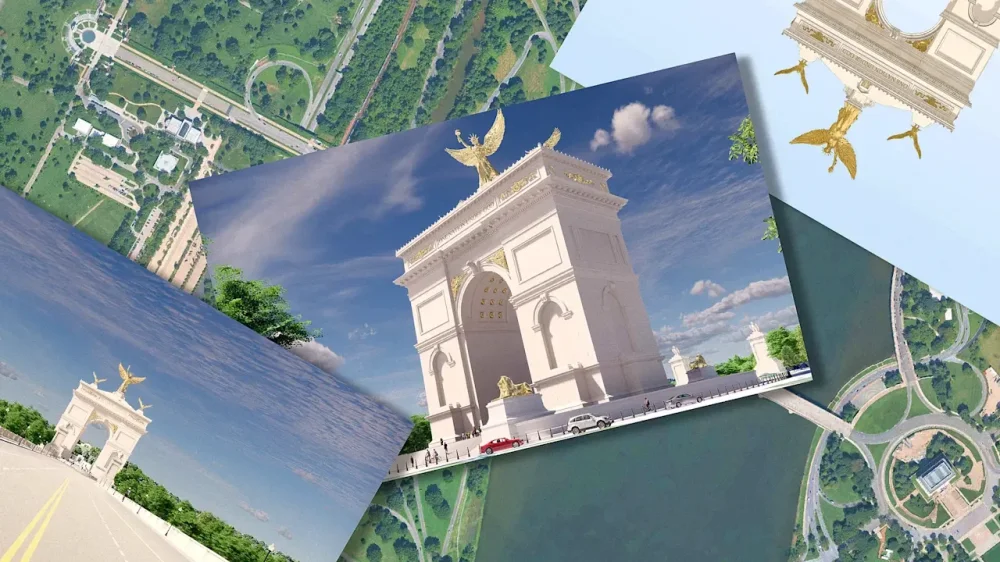
For months, President Donald The President has shown off various prototypes of an arch monument he wants to build in Washington, D.C., and finally he’s landed on a concept: an extra-tall “Triumphal Arch” that he hopes will soon rise just outside Arlington National Cemetery overlooking the National Mall. Nearly a quarter of the arch’s 250-foot height is thanks to a gilded statue on top. The The President administration submitted renderings for the massive arch to the president’s handpicked Commission of Fine Arts on April 17. The renderings by Harrison Design, an architecture, interiors, and landscapes firm, show an arch and park that would stand in a roundabout between the cemetery and the Lincoln Memorial. The design carries some of the hallmarks of The President’s second-term federal buildings initiative with its oversize, gold-accented classical architecture, which would look right at home at Mar-a-Lago. Harrison Design did not respond to a request for comment. The height of the arch is a hat tip to the semiquincentennial anniversary of the nation’s founding, which will be celebrated in July. But like a skyscraper that adds a spire or antenna for a few extra feet, it gets there with some help from its ornamentation: a 60-foot winged Lady Liberty-like gold statue flanked by gold bald eagles. The rendering also shows gilded lions at the base and the phrases “ONE NATION UNDER GOD” and “LIBERTY AND JUSTICE FOR ALL” inscribed on either side. The President wrote in an April 10 post on his social network that the structure would be “the GREATEST and MOST BEAUTIFUL Triumphal Arch, anywhere in the World. This will be a wonderful addition to the Washington, D.C. area for all Americans to enjoy for many decades to come!” Though he said the arch would be completed by Independence Day, construction hasn’t started. The President’s planned arch would tower above the 99-foot-tall Lincoln Memorial on the other side of the Potomac River. Architecture critic Catesby Leigh, who supports the idea of an arch monument in D.C. like those found in other Western capital cities like Paris, nevertheless told PBS that The President’s proposal is “way out of scale” and “way too big.” Sue Mobley, director of research at the nonprofit public art studio Monument Lab, calls it “banal.” “I believe it is traditional to have some sort of victory prior to erecting a triumphal arch,” Mobley tells Fast Company. “That said, one of the more exhausting traditions of authoritarians is to perform victory out of a loss, and to imagine that the aesthetic will overwrite the actual.” As with The President’s push to build a massive White House ballroom and add his name to any number of prominent structures (from the Kennedy Center to New York’s Penn Station), his proposal to build an arch has also drawn fierce scrutiny and lawsuits. Demonstrators marched on the site of the proposed arch during last month’s No Kings protest, and a group of Vietnam War veterans accused The President of not getting the proper congressional approvals to build the arch in a suit filed in February by the watchdog group Public Citizen. In their court filing, attorneys for the veterans said the arch, which would be roughly as tall as an 18- to 25-story office building, would obstruct “a line of sight” between Arlington National Cemetery and the Lincoln Memorial “that was designed to represent the unification of the Nation following the Civil War and that has existed for nearly a century.” The filing further states that the plaintiffs believe the structure would “dishonor their military and foreign service and the legacy of their comrades and other veterans buried at Arlington National Cemetery, and would degrade their personal experience when visiting Arlington Cemetery.” The President announced his plans for an arch last year, but if pushback to the project is anything like pushback to his ballroom, there could still be hurdles. A federal judge halted construction of the ballroom earlier this month. View the full article
-
AI is already transforming how organizations operate, compete, and create value, and adoption is accelerating across industries. Businesses that are experimenting with AI and learning how to move from initial ideas to deployment are building the infrastructure to deliver value both now and in the future. Those that are waiting—for the technology to mature, for conditions to stabilize, for someone else to figure it out first—risk finding that a competitor has upended their market before they’ve even begun adapting to this new era. Given the current chaos in global markets and geopolitics, the temptation to avoid change and pursue a defensive strategy is strong. But it must be resisted. Organizations that gain ground now will be difficult to catch. Those that fall behind may find that they’ve missed their chance for good. A strong innovation pipeline is more important today than ever before. The Four Pillars Innovation efforts fail for predictable reasons that rarely have anything to do with the quality of available ideas or technology. Instead, these efforts fail because the conditions needed to sustain them aren’t in place. Those conditions rest on four pillars. Leadership mindset. The biggest barrier to innovation isn’t budget or technological capability—it’s the mindset of the leadership team. Leaders tend to look for stability and certainty when making decisions. Yet instability and change are the default conditions of the AI age, and senior executives need to adapt to this new reality. Organizational design. This is the pillar that gets overlooked most often, and it’s the one that most frequently determines whether innovation programs succeed or fail. If a transformational approach to innovation is to take root, then reporting lines must value experimentation over immediate returns and incentive structures must not punish risk-taking. Decision rights must also be unambiguous across the organization. Capital allocation. Innovating through uncertainty doesn’t necessarily mean spending more, but it does mean spending deliberately—starting from strategic priorities and then holding every dollar accountable through a stage-gated approach to funding that rewards progress and kills inertia. The innovation pipeline. Most organizations have a portfolio problem, not an idea problem. They either bet everything on one transformative initiative or they scatter resources across dozens of underfunded experiments. What they need instead is a balanced portfolio of bets with explicit mechanisms for deciding what moves forward. These four foundations are the basis for every phase of the 90-day plan that follows. The 90-Day Plan Days 1-30: Diagnose The goal of this phase is clarity. You can’t build what you can’t see, and most organizations have never taken a systematic look at where they stand when it comes to their capacity for innovation. 1. Start with purpose, not technology. The most common mistake in AI adoption is asking What can AI do? instead of What problems are preventing us from achieving our strategic goals, and could AI help solve any of them? Begin by reaffirming your organizational purpose, mapping your strategic priorities, and then working backward to identify bottlenecks and points of friction. At this point, you can start thinking about how AI might solve these problems. The output of this step is a ranked list of opportunities grounded in what your organization is trying to achieve. This step follows the Outline phase of the OPEN framework for AI innovation. 2. Diagnose your organization’s relationship to change. Culture is the primary barrier to AI transformation, so before you invest in tools, assess the environment those tools will be deployed into. Determine whether your organization treats AI as a legitimate business tool or a sign of questionable practice, and whether your frontline teams have ideas for AI applications that nobody has thought to ask them about. This diagnostic will tell you whether your culture will support what you’re about to build. If the answers you get are uncomfortable, solving these cultural issues must be a priority. 3. Audit your current innovation activity and spend. Inventory every experiment, pilot, and stalled initiative, then map every innovation dollar being spent. Flag anything that’s being funded out of inertia rather than strategy—the endlessly “almost ready” pilot or the expensive software subscription that nobody uses. This audit gives you two things: a clear picture of what you’re doing and spending right now, and the raw material for the capital allocation decisions that come later. For a detailed example of a thorough baseline assessment, see our practical playbook for AI innovation pipelines. 4. Map your decision rights. This is where organizational design enters the picture. You need clear answers to five questions: Who approves a new experiment? Who decides when a project advances to the next stage? Who can reallocate budget between initiatives? Who has the authority to kill a failing project? And who can request resources across functions? If the answers are ambiguous—and in most organizations they will be—then every innovation project you launch is structurally vulnerable. An accurate decision rights matrix is the structural precondition for everything that follows. Days 31-50: Organize The ground is mapped. Now it’s time to build the machinery that will sustain innovation over the long term. This phase is about putting the human and organizational infrastructure in place so when experiments begin, they have the support they need to succeed. 1. Establish ownership and structure. Someone needs to own the innovation pipeline, with explicit authority to allocate resources, kill underperforming projects, and escalate blockers. The best approach is to create a central point of accountability that sets standards and can take a unified view of the portfolio paired with leads embedded in each function or business unit who own execution in their area. 2. Realign incentives. If managers’ performance is measured exclusively on quarterly delivery and cost efficiency, they will never protect innovation spend. Changing behavior means changing incentives. Tie a part of the leadership evaluation to innovation pipeline health. Measure active experiments running, the speed at which failing projects are identified and killed, stage-gate throughput, and willingness to support experimentation. The organizational culture you diagnosed in Phase 1 won’t change because you’ve drawn a new org chart. It will change because you’ve changed what the organization values. 3. Establish a recurring innovation rhythm. Set up a weekly session: 30 minutes, with nonnegotiable attendance from senior leadership. That forces forward-looking thinking into the calendar. When uncertainty dominates, every meeting becomes reactive. This weekly session is a counterweight to that tendency, a protected space for reviewing emerging opportunities that builds the habit of treating innovation as an ongoing discipline. Days 51-70: Prepare The infrastructure is in place. Now build your portfolio of AI initiatives and get your first cohort of projects ready to launch. 1. Structure your opportunities as a portfolio. Take the ranked list of opportunities from the Diagnose phase and score them against five criteria: strategic alignment, feasibility, cost, risk, and potential value. The core principle is straightforward: Treat your AI initiatives as an interconnected investment portfolio, not a to-do list. You want a deliberate mix across time horizons—quick wins that can demonstrate value within weeks alongside medium-term projects that require deeper integration and longer-term bets that could reshape the business. For the detailed stage-gate portfolio methodology, see this framework for managing AI innovation. 2. Determine and allocate capital on a purpose-driven basis. Start from your strategic priorities and work forward. Ask what level of investment your innovation portfolio actually requires to deliver against your goals. That number may be more than is currently budgeted. If so, confront that gap honestly. The question isn’t How do we spread what we have across these projects? It’s What do we need to invest to remain competitive, and how do we fund that? Once the total budget is determined, allocate it across the portfolio with clear stage gates. No project gets its next tranche of funding without hitting defined milestones. 3. Design your first cohort of experiments. Select the three to five highest-scoring quick wins from the portfolio and design each one for launch. Every experiment needs an owner, a budget, a timeline, a success metric, and a defined milestone at which it will be evaluated. Structure each experiment as a learning journey—you’re testing not just whether the technology works but whether people adopt it and what organizational capabilities it requires. Days 71-90: Ignite The machinery is built. The portfolio is structured. Now light the fuse and lock in the governance processes that will enable the system to sustain itself. 1. Launch your first experiments. Get your first cohort of bounded, measurable AI experiments into motion. Early visible results are the single most powerful antidote to organizational paralysis—they demonstrate that innovation is possible, that AI can deliver tangible value, and that the system you’ve built actually works. Pay attention to what breaks. That information is as valuable as the experiment results themselves. 2. Establish mechanisms for long-term operation. As you launch your first experiments, establish the governance structures that will sustain the pipeline beyond the initial 90-day push. First, innovation pipeline health becomes a standing agenda item in senior leadership meetings—not an annual innovation day or a quarterly update buried in a strategy deck. Second, stage-gate discipline is fully embedded: Every innovation investment requires a gate review at each stage—no exceptions. Third, design and schedule the quarterly portfolio review process that will become the engine for continuous improvement. 3. Stress-test your organizational design. Take stock of what the first 70 days have taught you about your own structure. Are the decision rights working in practice, or are decisions still getting stuck? Is the ownership model delivering both coherence and relevance, or has it become a bottleneck? Are the incentive changes having the intended effect on behavior? Is the culture beginning to shift, or are the old defaults reasserting themselves? This isn’t a onetime fix. It’s a system that needs continuous tuning. But by day 90, the system should exist and be operating, even if imperfectly. 4. Begin the second cycle. In your quarterly review, ask: What worked? What didn’t? What scales? What gets killed? What have we learned about our organization’s capacity to support AI innovation? Feed the answers back into the pipeline. Replenish the portfolio with fresh opportunities. Assess whether the balance across time horizons is right. The 90 days were the ignition. This first review is the beginning of the ongoing engine. Conclusion This plan won’t transform your organization in 90 days. But it will jump-start its journey toward AI transformation. At the end of the period, you’ll have a functioning innovation pipeline and a portfolio of AI initiatives, your first experiments will be in motion, and the governance machinery to sustain continuous innovation will be in place. The 90-day plan is just the key to the ignition. After that, the road is all yours. View the full article
-
Chinese president says Spain and China are ‘morally upright’ nations that should strengthen their co-operationView the full article
-
First-quarter results come amid growing concerns around the links between traditional lenders and the private credit boomView the full article
-
Missing the late tax return deadline can lead to significant financial repercussions that you might not fully anticipate. Penalties for late filing, such as the failure-to-file penalty, can accumulate quickly, whereas interest on unpaid taxes compounds daily. This situation not solely complicates your financial standing but can additionally attract IRS scrutiny. Comprehending these consequences is essential, especially if you want to maintain your financial health and stability moving forward. What steps can you take now? Key Takeaways Late filing incurs penalties starting at 5% of unpaid taxes each month, capping at 25%. Interest on unpaid taxes begins accruing at an annual rate of 8% immediately after the due date. Missing deadlines can lead to severe consequences, including property liens and wage garnishment. Long-term financial stress may arise due to compounding penalties and unresolved tax issues. Increased IRS scrutiny may occur, leading to audits and potential legal actions for repeated late filings. Understanding the Importance of Timely Tax Filing When you recognize the importance of timely tax filing, you not only stay compliant with the law but similarly avoid unnecessary financial penalties. Missing the late tax return deadline can lead to severe consequences, especially for S corporations. If you file your Form 1065 late, you’ll face a penalty for filing 1065 late, which is 5% of unpaid taxes for each month overdue, capping at 25%. Moreover, unpaid taxes accrue a late payment penalty of 0.5% monthly, increasing your overall liability. Interest on unpaid taxes compounds daily at an 8% rate, starting the day after the deadline. Timely filing also guarantees you’re eligible for any potential refunds within three years, preventing those funds from being turned over to the U.S. Treasury. In addition, timely compliance reduces the likelihood of audits and scrutiny, particularly important for business owners. Penalties for Late Filing When you file your tax return late, you face significant penalties that can add up quickly. The failure-to-file penalty starts at 5% of your unpaid taxes for each month you’re late, reaching a maximum of 25%. Furthermore, interest on any unpaid taxes begins accruing immediately, compounding daily, which can further complicate your financial situation. Failure-to-File Penalties Missing the tax return deadline can lead to significant financial repercussions, especially in the form of failure-to-file penalties. The IRS imposes a penalty of 5% of unpaid taxes for each month your return is late, capping at 25%. If you file more than 60 days late, the minimum penalty jumps to either $525 or 100% of the unpaid tax, whichever is lower. Remember, the penalty clock starts ticking on the original due date, usually April 15. Filing an extension doesn’t shield you from these penalties if you still submit your return late. For instance, if you owe $1,000 and file 10 days late without an extension, you’ll incur a $50 penalty, adding to your financial burden. Consequences of Late Filing Failing to file your tax return by the deadline can lead to significant penalties that accumulate quickly. Here’s what you need to know about the consequences of late filing: The failure-to-file penalty is 5% of your unpaid taxes for each month your return is late, maxing out at 25%. If you file your tax return more than 60 days late, you’ll face a minimum penalty of either $525 or 100% of your unpaid tax, whichever is lower. Remember, filing an extension doesn’t eliminate these penalties; they still apply if you submit your return after the extended deadline. Both failure-to-file and failure-to-pay penalties can accumulate simultaneously, potentially leading to substantial costs over time. Stay informed to avoid these financial burdens. Interest Accumulation Effects The financial repercussions of late tax filing extend beyond penalties; interest on unpaid taxes can exacerbate your overall liability greatly. Starting just one day after the due date, interest begins accruing at an approximate annual rate of 8%, compounding daily until you fully pay your tax bill. Alongside this, late filing penalties of 5% per month can accumulate, capping at 25%, which further inflates your total debt. If you file more than 60 days late, you’ll face a minimum penalty of either $525 or 100% of your unpaid tax, adding to your financial burden. This combination of penalties and interest can notably increase what you owe, making timely payment essential to limit additional costs. Failure-to-File Penalty Explained When you don’t file your tax return by the deadline, you may incur a failure-to-file penalty, which can greatly increase your tax burden. This penalty is a serious matter, and here’s how it works: 5% Penalty: You’ll face a 5% penalty on your unpaid taxes for each month your return is late, capping at a maximum of 25% of the total unpaid tax. 60-Day Rule: If you file more than 60 days late, the minimum penalty jumps to the lesser of $525 or 100% of the unpaid tax owed. Concurrent Penalties: If both the failure-to-file and failure-to-pay penalties apply, the late-filing penalty reduces to 4.5% for those months. Consequences of Late Payment When you miss a tax payment, penalties start piling up quickly. You’ll face a late payment penalty of 0.5% of your unpaid taxes each month, capped at 25%, as interest on that amount compounds daily at a rate of 8%. As the balance remains unsettled, your overall liability increases considerably because of these added costs. Late Payment Penalties Accrue Missing the tax payment deadline can lead to significant financial repercussions, especially with late payment penalties stacking up. If you don’t pay your taxes by the April 15, 2026 deadline, you’ll incur penalties that can quickly escalate. Here are the key points to take into account: A penalty of 0.5% of the unpaid tax amount accrues each month, maxing out at 25%. If you face both late payment and late filing penalties in the same month, the late filing penalty drops to 4.5%. Unpaid taxes can lead to severe consequences, including property liens and wage garnishment by the IRS. Understanding these penalties can help you avoid costly mistakes and manage your tax obligations effectively. Interest Compounds Daily Interest on unpaid taxes begins to accrue just one day after the due date, compounding daily until you fully settle your tax bill. Currently, the interest rate stands at 8%, but this can change quarterly, potentially increasing your financial burden. It’s important to note that interest applies to any unpaid taxes, regardless of whether you’ve filed a return or requested an extension. Even though you think you’re covered by an extension, the clock is still ticking on that interest from the original due date. Over time, accumulated interest can considerably inflate your overall tax liability, underscoring the necessity of timely payments. Staying current with your tax obligations can prevent costly surprises down the road. Interest Accumulation on Unpaid Taxes Regardless of whether you’ve filed your tax return late, you’ll still face consequences if you don’t pay your unpaid taxes without hesitation. Interest on unpaid taxes starts accruing the day after the due date and compounds daily, increasing your overall liability. Here are three key points to take into account: Interest Rate: Currently, the interest rate on unpaid taxes is 8% annually, but this rate can change each quarter, potentially increasing your costs even more. Compounding Effect: The longer you wait to pay, the more significant the impact of interest becomes on your total debt, making timely payment crucial. Universal Application: Interest applies to any unpaid taxes, regardless of whether you filed your return on time or not, emphasizing the importance of addressing outstanding balances quickly. Impact of Delayed Refunds When you miss the tax return deadline, you might face delays in receiving your refund, which can disrupt your financial planning. Even though there are no penalties for late filings if you expect a refund, the IRS can still withhold your money if you have unresolved tax obligations. This situation may lead to added financial strain, as you could be counting on those funds for expenses or savings. Financial Planning Delays Missing the tax return deadline can greatly disrupt your financial planning, especially if you’re expecting a refund. Delays in processing your refund can hinder your ability to meet immediate financial needs, complicating your budgeting. Here are three significant impacts: Bill Payments: Without your refund, paying bills on time may become challenging, leading to late fees or penalties. Emergency Expenses: You might find it difficult to cover unexpected expenses, such as medical emergencies or car repairs, without the anticipated funds. Planned Purchases: Missing out on your refund can derail plans for significant purchases, like home improvements or vacations. Ultimately, the longer you wait to file, the more uncertainty surrounds your financial outlook, potentially complicating future tax situations. Withholding Potential Refunds Failing to file your tax return on time can have serious implications for potential refunds you might be owed. If you miss the deadline, you risk forfeiting any refunds after three years, as unclaimed amounts go to the US Treasury. Delayed filings can lead to longer processing times, affecting your cash flow and financial plans. Furthermore, the IRS may withhold refunds if you have outstanding obligations, resulting in reduced or even no refunds. Here’s a quick overview: Issue Impact Forfeiting refunds After three years, refunds are lost Delays in processing refunds Affects cash flow and planning Outstanding obligations May reduce or eliminate refunds Take action to avoid these pitfalls and secure your rightful refund. Long-Term Financial Ramifications Although you might think that missing the tax return deadline merely results in immediate penalties, the long-term financial ramifications can be greatly more severe. Here are three key consequences you should consider: Compounding Penalties and Interest: Over time, the IRS can add penalties and interest, which currently stands at 8% annually, considerably increasing your total debt. Higher Tax Liability: If you fail to file your return, the IRS may file a substitute return for you that doesn’t include deductions or credits, potentially leading to a larger tax bill. Credit Score Damage: Unresolved tax issues can severely impact your credit score, making it harder to secure loans or mortgages in the future. These long-term financial stresses mightn’t merely hinder your financial stability but could likewise affect your employment opportunities, especially in finance-related fields, because of unresolved tax matters. Increased Scrutiny From the IRS When taxpayers neglect to file their returns by the deadline, they often find themselves facing increased scrutiny from the IRS. This scrutiny intensifies for those with a history of late filings or unpaid taxes. The IRS may flag your account for audit, raising red flags about your compliance and financial behavior. If you’ve repeatedly missed deadlines, expect an intensified review process, which includes additional inquiries and requests for documentation. Business owners are particularly at risk, as failing to file taxes on time can lead the IRS to suspect underreporting of income or tax evasion. This increased scrutiny can result in more extensive investigations, which may uncover further discrepancies. As a result, you could face additional penalties and interest on any unpaid taxes, which accumulate over time. It’s crucial to be aware of these consequences to avoid escalating issues with the IRS. Options for Penalty Relief If you’ve missed the tax return deadline, it’s important to know that the IRS provides several options for penalty relief that could help ease your financial burden. Here are three primary avenues you might explore: First-Time Penalty Abatement (FTA): If you haven’t had penalties in the past three years, are current on your returns, and have paid or arranged to pay your taxes, you may qualify for this relief. Reasonable Cause: You can request relief based on unique circumstances, such as illness or natural disasters. This requires a written explanation and is at the IRS’s discretion. Appealing Penalties: If you believe you have reasonable cause or meet FTA criteria, submit Form 843 to appeal the penalties assessed against you. Additionally, filing a late return as soon as possible can help reduce penalties and interest. Whereas installment agreements may prevent further penalties for unpaid taxes if you stick to the plan. Steps to Take After Missing the Deadline Missing the tax return deadline can feel overwhelming, but taking prompt action can greatly mitigate the consequences. Start by filing your tax return as soon as possible to minimize penalties; remember, late filing penalties accrue at 5% of unpaid taxes each month, capping at 25%. Paying as much of the owed taxes as you can in addition helps, as late payment penalties begin at 0.5% monthly, with the same 25% cap. If you have a clean tax record for the past three years, consider requesting a First-Time Penalty Abatement (FTA) to eliminate some penalties. If you’re unsure of your next steps or how to handle potential penalties, seeking help from a tax professional can provide valuable guidance. Finally, if you can’t pay the full amount owed, explore IRS payment plans to manage your tax liability effectively and avoid further complications. How to Avoid Future Missed Deadlines To avoid future missed tax deadlines, it’s vital to establish a proactive approach to your tax obligations. Here are three effective strategies to keep you on track: Mark Key Deadlines: Add important dates, like April 15, to your calendar. This will remind you when to file and pay your taxes, helping you avoid last-minute rushes. Automate Payments and Reminders: Set up automatic payments for your taxes and create reminders for filing dates. This way, you won’t have to worry about forgetting significant deadlines. Consider Professional Help: Work with a tax professional throughout the year. They can provide ongoing guidance and support, ensuring you’re well-prepared for your tax obligations. Importance of Financial Organization Financial organization plays a crucial role in ensuring you meet your tax obligations efficiently. Keeping your financial records organized throughout the year can streamline tax preparation, making it easier to file on time. Use a calendar to mark key tax deadlines, including filing and payment dates; this simple step can greatly reduce the risk of late submissions. To further improve compliance, automate reminders for tax obligations and due dates, which helps minimize penalties. Regularly reviewing your financial documents allows you to identify discrepancies early, reducing delays during tax season. If you work with a tax professional year-round, they can provide valuable guidance on maintaining financial organization and developing timely filing strategies. Seeking Professional Assistance When tax deadlines slip by, seeking professional assistance becomes a practical option for managing the potential consequences. Tax professionals can help you navigate the intricacies of late filing penalties, which can quickly add up to 25%. Here are three key benefits of consulting a tax expert: IRS: They can guide you on eligibility for First-Time Penalty Abatement (FTA), potentially relieving penalties if you haven’t had any in the past three years. Understanding Rights: A tax advisor can clarify your rights and options, especially if you’re facing IRS collection actions for unpaid taxes. Filing and Payment Plans: Professionals can assist in filing late returns to mitigate further penalties and help set up payment plans with the IRS, easing your tax liabilities. Frequently Asked Questions Will You Get in Trouble if You Miss the Tax Deadline? Yes, you can get in trouble if you miss the tax deadline. If you owe taxes, the IRS may impose penalties, including a late filing penalty of 5% of the unpaid amount each month, up to 25%. Furthermore, a failure-to-pay penalty of 0.5% may apply monthly. Interest on unpaid taxes begins accruing immediately after the deadline. Not filing can likewise lead to serious collection actions, like audits or wage garnishments. How Much Does the IRS Penalize for Late Taxes? The IRS penalizes late taxes primarily through a filing penalty of 5% of unpaid taxes for each month overdue, maxing out at 25%. If you’re over 60 days late, the minimum penalty is $525 or 100% of the unpaid tax, whichever’s less. Moreover, late payment penalties accrue at 0.5% per month, likewise capping at 25%. Interest on unpaid taxes starts accruing the day after the due date, compounding daily, increasing what you owe. Can I Submit a Tax Return After the Deadline? Yes, you can submit a tax return after the deadline. Although it’s possible to file late, you may face penalties if you owe taxes. If you’re expecting a refund, there’s no penalty for late filing, but you must file within three years to claim it. To minimize penalties, it’s best to file and pay any owed taxes as soon as possible. Interest will accumulate on unpaid taxes starting the day after the due date. What Is the $600 Rule in the IRS? The $600 rule from the IRS requires you to issue a Form 1099-MISC or 1099-NEC for each independent contractor or unincorporated entity you pay $600 or more in a calendar year. This includes payments for services, rents, and prizes, but typically excludes corporations. If you make multiple payments to one recipient totaling $600, you must still issue a 1099. Conclusion Missing the late tax return deadline can lead to significant financial repercussions, including penalties and interest on unpaid taxes. To mitigate these consequences, it’s essential to take immediate action by filing your return and addressing any owed taxes. Going forward, adopting strong financial organization practices and seeking professional assistance can help you avoid future issues. Staying informed about tax obligations guarantees you maintain compliance and protect your financial stability, ultimately securing your credit and reducing stress related to tax matters. Image via Google Gemini and ArtSmart This article, "Consequences of Missing the Late Tax Return Deadline" was first published on Small Business Trends View the full article