Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
US forces will be ready to descend from helicopters on to oil tankersView the full article
-
Lending for new single-family homes jumped 11% from a year ago and 26% from February, the Mortgage Bankers Association said. View the full article
-
If you’re just a few words into this story, but already feeling the urge to click or swipe or begin some other activity altogether, I won’t take it personally. Attention spans among humans have reduced dramatically in the past several years. Several school districts around the country are trying to reclaim that by instituting bans on cell phones in classrooms—and some of those programs are bearing fruit. Two years after phones were banned in an unnamed large urban Florida school district, test scores were up significantly, in part because students were better able to focus on the work in front of them. And a recent survey of Ohio public schools found 68% of principals saying students can now stay on one task for more than 20 minutes without seeking a quick digital break. It’s one thing to ban phones in schools, though. Putting limitations on them in the real world isn’t practical. And that means attention spans in adults continue to lag. Squirrel! Researcher Gloria Mark, who studies human attention at the University of California, Irvine, found in 2004 that the average person focused their attention on a single screen for about two and half minutes. By 2016, that length of time had dropped to 47 seconds, a reduction of roughly 69%. In other words, we’re all chasing shiny objects these days. And it’s a trend that’s not likely to reverse itself. It could, in fact, get even worse. We are, after all, under assault from distractions. The lure of dopamine-feeding social media threads calls to us constantly. Email, Slack and Discord ping right as we get into a groove. TV news and shows, as well as films, feature quickly changing shots, further sapping our ability to focus. AI, meanwhile, is impacting our ability to think critically. It’s even worse at work. Microsoft, in its 2025 Work Trend Index, found that the average office worker was interrupted every two minutes. Employees receive 92 emails per day, on average (and that doesn’t factor in your personal email), along with an average 153 Teams messages per work day. Throw in meetings and your circadian rhythm, which regulates your natural peak focus times, and we’re all in trouble. We’re not doomed, though, says Mark. In her book Attention Span: A Groundbreaking Way to Restore Balance, Happiness and Productivity, she reframes myths around attention, pointing out that just as you couldn’t keep up a physical activity indefinitely, it’s impossible for your brain to focus all the time. And some of that mental wandering isn’t bad. “It turns out that mindless activities like playing simple games doesn’t just make us temporarily happy,” she writes. “When used strategically, those activities can also help us replenish our overspent mental resources, and enable fresh ideas to surface.” But if you’re concerned you’re on a path to being the human equivalent of Dug, the easily distracted golden retriever from Pixar’s Up, there are tools to retrain your brain, despite the daily assaults you face on your focal abilities. The benefits of books First, you’ll also want to put some physical distance between you and your phone. If you can’t grab it, you’ll be less likely to doomscroll and distract your brain. The best method, though, is to read more. Neuroscientist Maryanne Wolf argues that the physical process of reading changes our brain. It matters what and where you read, though. Most reading on screens is “skimming to inform”—looking for key words that give you a loose idea of what’s being said. That’s not likely to help. You’ll need to slow down and actually read what was written—and that’s easier with a physical book. “When we skim, we literally, physiologically, don’t have time to think. Or feel,” she writes. “The difference between skimming and reading with all our intelligence is the difference between fully activated reading brains and their short-circuited, screen-dulled versions.” Reading a printed publication is a slower process that requires more attention. Our brains associate screens with distraction, which triggers our brain to skim. We think we read “faster” on screens, but the truth is, we’re just reading less, even if we don’t realize it. In July 2020, less than half of Americans read one book over a 12-month period, according to a Survey of Public Participation in the Arts. And a 2025 study by the University of Florida found the number of people who partook of pleasure reading was down 40% over two decades. “This is not just a small dip—it’s a sustained, steady decline of about 3% per year,” said Jill Sonke, director of research initiatives at the University of Florida’s Center for Arts in Medicine in a statement. “It’s significant, and it’s deeply concerning.” View the full article
-
Small manufacturers across the United States are set to receive a significant boost as the U.S. Small Business Administration (SBA) unveils an enhanced International Trade Loan (ITL) Program. Starting May 1, the program will offer a 90% federal loan guarantee, enabling small producers to expand operations, invest in modern equipment, and create jobs. This initiative is part of the The President Administration’s broader effort to restore America’s industrial dominance. SBA Administrator Loeffler emphasized the urgency of bolstering American manufacturing, highlighting that “Industrial dominance is essential to our national security and strength.” She noted that small businesses comprise 98% of all manufacturers in the U.S., underscoring the critical role they play in driving economic growth and job creation. As small business owners often face challenges in securing affordable financing, this enhanced guarantee presents a vital opportunity to address capital needs. Under the newly expanded ITL program, eligible manufacturers can not only unlock long-term financing but also gain additional flexibility thanks to the increased SBA guarantee. This change aims to inspire confidence among lenders, encouraging them to invest in domestic manufacturing. It opens doors for small businesses to access funds for a range of purposes, including upgrading equipment, modernizing facilities to meet both customer and national security demands, and enhancing inventory resilience. The loan specifics are designed to incentivize various improvements within the manufacturing sector. Small businesses can use the funds to replace outdated machinery, diversify supply chains to reduce dependence on foreign suppliers, and even expand their operations through strategic acquisitions. This alignment with the Administration’s commitment to reshoring American industry is expected to enhance competitiveness and long-term sustainability for small manufacturers. The SBA’s recent initiatives, including the Made in America Manufacturing Initiative, aim to provide a comprehensive support framework. In addition to the ITL enhancement, the SBA has taken steps such as waiving loan fees for small manufacturers and launching the Make Onshoring Great Again Portal, a tool connecting businesses with over a million domestic suppliers. Real-world implications of these initiatives are already becoming evident. Weekly wages in the manufacturing sector surged by 5.1% in February, marking a tangible response to the policies designed to support small businesses and boost employment in this sector. As these changes unfold, small business owners are poised to benefit from increased financial support in a landscape that continues to change. However, potential challenges remain. While the program provides a much-needed avenue for financing, small manufacturers must also consider the complexities of navigating the application process and aligning their business needs with the program’s requirements. Additionally, while the enhanced lending terms can foster growth, it’s essential for owners to strategically assess how debt financing will impact their overall financial health. For small business owners interested in learning more about the updated International Trade Loan program, the SBA encourages them to reach out to their national team of Finance Managers. These specialists can provide tailored assistance, helping businesses understand how the ITL can be integrated with other available SBA financing options, streamlining access to working capital solutions. As the manufacturing sector anticipates this substantial shift in funding availability, the coming months will be pivotal for small businesses looking to expand and modernize. This initiative not only promises immediate financial relief but also serves as a long-term strategy to rejuvenate domestic industries and safeguard the future of American manufacturing. For further details about the initiative, small business owners can visit the SBA’s official announcement at SBA.gov. Image via Google Gemini This article, "SBA Expands Loan Program to Boost U.S. Small Manufacturers’ Growth" was first published on Small Business Trends View the full article
-
While wars always come with an added cost to taxpayers, a public policy expert is saying the The President administration’s military efforts in Iran, which include attacking infrastructure and a blockade of the Strait of Hormuz, could drag on and come with tremendous costs to the American people—and long term, the projections are alarming. That’s according to Linda Bilmes, a senior lecturer in Public Policy and public finance expert at Harvard’s Kennedy School. She says that the war is already costing about $2 billion a day, but that’s only “the tip of the iceberg.” In a recent interview, Bilmes said that while the Pentagon said the war cost around $11.3 billion in the first few days of the war alone, that’s an “underestimate,” and the true cost is much higher. “According to my calculations, those first few days cost at least $16 billion,” Bilmes explained. “We are spending down munitions at an extraordinarily fast pace—to put it in perspective, we fired more Patriot missiles in the first four days of the Iran war than we have given to Ukraine over the past four years,” she said. The researcher asserted that short-term costs are adding up quickly, as “we are losing high-cost assets,” but it’s the long-term costs that are most troubling. For starters, Bilmes said it’s important not to overlook the cost of human life, which is already being lost. Thousands of Iranians, including at least 1,700 civilians, have already lost their lives to the war. Hundreds of U.S. soldiers have been injured with at least 13 dead. Financially speaking, the cost of medical and disability care for veterans will be substantial. So will be the increase in the defense budget, which Bilmes explained could become permanent. “The president is proposing roughly a 50% increase in the defense budget,” Bilmes explained. “If enacted in full, that would push defense spending to levels about 20% higher than the peak reached during World War II. This raises the baseline. Even if Congress does not agree to approve the full increase, it is highly likely that at least $100 billion per year will be added to the base defense budget that would not have been approved in the absence of this war.” Bilmes says those costs add up to at least $100 billion per year. “I am certain we will reach $1 trillion for the Iran war,” Bilmes explained. While the projections are no doubt troubling, Americans are already paying for the war. Gas prices recently saw the largest jump in about 60 years, which means that air travel costs are also up. And on Tuesday, the International Monetary Fund (IMF) warned that if the conflict continues to escalate, we could face a global recession. As the costs of the war are adding up quickly, Bilmes is urging that the financial impacts, which so far have been underestimated, will spread far and wide. “There are many dangers, but they are not all military threats,” Bilmes says. View the full article
-
JPMorgan Chase, Citigroup and Wells Fargo reported more than $25bn of profits for the first quarterView the full article
-
Money market funds are mutual funds that invest in short-term debt instruments with high credit quality, including US Treasury bills and short-term unsecured corporate-backed notes (aka commercial paper). Money market funds aim to sustain a net asset value of $1.00 per share while offering higher yields than bank savings accounts. What are the advantages and risks of using a money market fund? Money market funds are popular with both individual savers and corporations, who often use them as a tool for managing the cash on their balance sheets. They are available through any major brokerage platform and often offer features such as check writing, making them easy to use for larger expenses such as tax payments and major purchases. Shareholders in money market funds can easily transfer assets to or from a bank account or a longer-term investment vehicle. Taxable money market funds account for the bulk of money market fund assets. They invest in taxable securities such as Treasury bills, other short-term government obligations, and other high-quality, floating-rate debt such as commercial paper. Their holdings typically have pristine credit quality. All three types of holdings have very short maturities (with bonds coming due in weeks or months). As a result, they take on little to no interest rate risk. Because maturities are so short, portfolio yields quickly respond to changes in prevailing interest rates as bills mature and get replaced. Money market funds are also safe because they generally don’t lose value. (There have been exceptions.)This safety comes at a price: they’ve had among the lowest returns compared with other types of assets. Because cash has no potential for capital appreciation, returns on money market funds are driven by yield. Over the past 40 years or so, income returns for money market funds have ranged from a high of 13.4% in 1981 to a low of 0.01% in 2013 and 2014. Past problems with money market funds In contrast to bank accounts, which are insured by the Federal Deposit Insurance Corporation for up to $250,000 per depositor, per bank, money market funds don’t come with a guarantee. And on occasion, money market funds have “broken the buck” by dropping below a $1.00 per share net asset value. In 1978, First Multifund for Daily Income took losses on some of its longer-maturity holdings as interest rates spiked and eventually liquidated at $0.94 per share. A similar problem arose in 1994, when Community Bankers U.S. Government Money Market Fund liquidated at $0.96 per share after suffering losses on interest rate derivatives as the Federal Reserve raised rates. The biggest problems came around the global financial crisis. In 2007, several funds were exposed to defaults on commercial paper linked to subprime mortgages, but their sponsors stepped in to prevent their NAVs from dropping. In 2008, the Reserve Primary fund dropped to $0.97 per share thanks to Lehman Brothers’ default on commercial paper. And in 2020, several prime (institutional) money market funds suffered a liquidity crunch but maintained their $1.00 per share net asset values when the Fed created an emergency lending program to cover losses. Recent reforms In July 2023, the Securities and Exchange Commission adopted reforms meant to reduce the risk of future money market woes. Among other things, the SEC tightened liquidity requirements for money market funds’ portfolio holdings, eliminated automatic redemption “gates” tied to certain liquidity thresholds, imposed a mandatory liquidity fee for certain funds, and set new rules for disclosure and stress-testing. Here are some of the most popular money market funds widely available to individual investors: Fidelity Government Cash Reserves Fidelity Series Government Money Mkt Gabelli US Treasury MMkt I Schwab Treasury Oblig Money Inv Schwab US Treasury Money Investor T. Rowe Price Government Money T. Rowe Price US Treasury Money UBS Government Money Market Invt P Vanguard Federal Money Market Investor Vanguard Treasury Money Market Investor How much of my portfolio should be in a money market fund? If you use a money market fund for cash management, the size of that position largely depends on your life stage. If you’re many years away from retirement, you don’t need to allocate much to cash, assuming you already have an emergency fund. Closer to retirement age, financial advisors typically recommend keeping at least one to two years’ worth of expenses in cash or other low-risk assets so you don’t have to sell stocks or bonds when the market is down. This article was provided to The Associated Press by Morningstar. For more personal finance content, go to https://www.morningstar.com/personal-finance. Amy C. Arnott, CFA, is a portfolio strategist for Morningstar and co-host of The Long View podcast. Related Links Portfolio Basics: How to Build an Investment Portfolio https://www.morningstar.com/portfolios/portfolio-basics-how-build-an-investment-portfolio How to Handle Market Volatility at Every Life Stage https://www.morningstar.com/portfolios/how-handle-market-volatility-every-life-stage How to Use Short-Term Bonds in Your Portfolio https://www.morningstar.com/portfolios/how-use-short-term-bonds-portfolio —Amy C. Arnott of Morningstar View the full article
-
In relation to real estate lending, several key factors come into play. You’ll need to assess the borrower’s creditworthiness, which involves looking at credit scores and income ratios. Property valuation is essential, as it impacts loan terms through the loan-to-value ratio. Furthermore, market conditions can influence property demand and investment potential. Comprehending these elements is crucial for making informed lending decisions, but there’s more to take into account as you navigate this intricate environment. Key Takeaways Creditworthiness, determined by credit scores and payment history, significantly impacts loan approval and interest rates in real estate lending. Property valuation influences loan amounts and terms, with accurate assessments determining the loan-to-value (LTV) ratio and lender risk. Market conditions, including economic trends and rental demand, affect property values and investment potential, guiding lenders’ decisions. Financing options, such as fixed-rate mortgages and bridge loans, vary in terms of interest rates, repayment schedules, and suitability for different projects. Due diligence, including inspections and environmental assessments, is crucial for minimizing risk and ensuring informed lending decisions. Understanding Creditworthiness When you’re looking to secure a mortgage, comprehending your creditworthiness is crucial. Your creditworthiness is mainly assessed through your credit score, which reflects your credit history and payment reliability. Higher credit scores usually lead to better mortgage terms, including lower interest rates, so maintaining good credit health is imperative. To strengthen your creditworthiness, pay your bills on time, keep credit card balances low, and avoid opening new credit accounts before applying for a mortgage. Mortgage lenders likewise closely examine your debt-to-income (DTI) ratio. A lower DTI indicates that a smaller portion of your income goes toward debt payments, showing you can handle mortgage repayments. A solid credit history not just boosts your chances of loan approval but also affects the terms and conditions lenders offer during the mortgage process. Grasping these factors will empower you to make informed decisions as you prepare for your mortgage application. The Importance of Property Valuation Property valuation plays a pivotal role in real estate lending, as it establishes the market value of a property, which directly influences the loan amount lenders are willing to approve. Mortgage lenders rely on local appraisers to assess property valuation, considering factors like property condition, location, and recent comparable sales. Accurate property valuation is crucial for determining the loan-to-value (LTV) ratio, a key metric that helps lenders gauge the risk associated with a mortgage. A higher property valuation can lead to more favorable loan terms, such as lower interest rates and reduced required down payments. By conducting thorough property valuations, including inspections and assessments, lenders can mitigate risks in real estate transactions, ensuring both their interests and those of the borrower are protected. In the end, comprehending the importance of property valuation is fundamental for anyone involved in the real estate lending process, as it lays the groundwork for successful financing. Evaluating Market Conditions Evaluating market conditions is important for making informed decisions in real estate lending, as it helps identify trends that can greatly impact property values and investment potential. You’ll want to assess general economic conditions in your region, including job growth and population trends that drive demand for real estate. Comprehending key demand drivers for various property types, like office spaces and apartments, is fundamental for gauging the market’s health. Additionally, consider the presence of large employers and industry health, as they markedly affect real estate attractiveness. Micro market conditions, encompassing supply-and-demand factors for specific submarkets and current rent trends, are critical for determining a project’s competitiveness. Pay attention to absorption rates, which reveal how quickly properties are leased, indicating local market strength. This knowledge can inform how to get a mortgage and help you meet mortgage requirements when you apply for a mortgage loan, eventually leading to successful home loan approval. Assessing Cash Flow Potential When you assess cash flow potential, it’s crucial to analyze income projections and manage expenses effectively. Start by calculating the net operating income (NOI) to get a clear picture of profitability. Then consider how occupancy rates and rental trends can impact your income. Income Projections Analysis Income projections analysis is essential for comprehending the cash flow potential of a real estate investment. This process involves evaluating factors like rental income, occupancy rates, and market trends to determine financial viability. A thorough cash flow analysis calculates net operating income (NOI) by subtracting operating expenses from gross rental income, providing valuable insight into profitability. Lenders often look for a debt service coverage ratio (DSCR) of at least 1.25, meaning the property’s income should exceed its debt obligations by 25%. Market research plays an important role, as local job growth, population trends, and rental property demand greatly influence future cash flow potential. Moreover, sensitivity analysis helps assess varying assumptions’ effects on projected income, revealing financial risks. Expense Management Strategies Effective expense management strategies are vital for maximizing cash flow potential in real estate investments. To guarantee profitability, you should conduct detailed cash flow analyses, comparing rental income against operating expenses and mortgage payments. Calculate the capitalization rate by dividing net operating income by property value, which helps you assess potential returns. Keep an eye on variable expenses like maintenance and utilities, anticipating these costs in your budget. Implementing cost-saving measures, such as energy-efficient upgrades, can further improve cash flow and property value. Moreover, maintaining a healthy debt service coverage ratio (DSCR) of at least 1.25 guarantees rental income covers debt obligations, providing a cushion against unexpected expenses. This is significant when working with Quicken Loans or mortgage lending companies for home financing or how to get a mortgage loan. Analyzing Borrower Financial History Comprehending a borrower’s financial history is essential for lenders as they assess the risk of extending a mortgage loan. By analyzing this history, lenders gain insights into your reliability as a borrower. Here are key factors they focus on: Credit score: A numerical representation of your creditworthiness. Payment history: Track record of on-time and late payments. Outstanding debts: Total amount of current debts you owe. Debt-to-income ratio (DTI): Percentage of your income spent on debt payments. Credit account length: Duration of your credit history. These elements contribute considerably to mortgage loan approval decisions. A higher credit score and lower DTI typically lead to better terms. To improve your chances, maintain good credit practices, avoid new credit accounts before applying, and guarantee timely payments. Your financial history is a vital aspect of securing a favorable mortgage. The Role of Credit Score in Lending As you navigate the mortgage lending terrain, grasping the pivotal role of your credit score can greatly affect your borrowing experience. A credit score, ranging from 300 to 850, serves as a numerical representation of your creditworthiness, influencing mortgage lenders‘ decisions during the mortgage loan approval process. Typically, scores above 700 are considered good, whereas scores below 620 might complicate your loan application. A higher credit score can lead to more favorable mortgage terms, such as lower interest rates, which reduces your overall borrowing costs. Furthermore, borrowers with strong credit scores may qualify for benefits like reduced mortgage insurance premiums or improved loan-to-value ratios. To improve your credit score, practice timely bill payments, maintain low credit card balances, and avoid opening new credit accounts right before you apply for a mortgage. Your credit score is a key player in accessing the best lending options available. Debt-to-Income Ratio Considerations Grasping your credit score is just one aspect of the mortgage lending process; another significant factor to contemplate is your debt-to-income ratio (DTI). This ratio reflects the percentage of your gross monthly income that goes toward debt payments. Mortgage lenders typically prefer a DTI of 36% or lower. A lower DTI not only enhances your chances of mortgage approval but may additionally yield better loan terms. To calculate your DTI, consider: All monthly debt payments (mortgage, credit cards, loans) Your gross monthly income Front-end DTI (housing costs only) Back-end DTI (total debt) Strategies to improve DTI (increase income, reduce debt) When you apply for a home loan, grasping your DTI will help you present a stronger home loan application. Knowing how to apply for a home loan effectively means keeping your debt manageable and your income robust. Collateral: The Property Itself When you secure a real estate loan, the property itself acts as collateral, meaning it safeguards the lender’s investment. To determine the property’s value, lenders usually hire an appraiser who evaluates factors like its condition, location, and recent sales in the area. Comprehending the loan-to-value ratio is additionally vital, as a larger down payment can lower this ratio, in the end reducing the lender’s risk and potentially influencing your mortgage terms. Property Appraisal Process The property appraisal process plays a vital role in real estate lending, as it determines the market value of a property, which serves as collateral for a loan. A local appraiser evaluates various factors to establish this value, including: The property’s size and layout Its age and overall condition Amenities such as pools or garages The neighborhood’s economic environment Recent comparable sales in the area A thorough home inspection is often recommended to uncover any potential issues that could affect the property’s value. In the end, the appraisal results in an appraised value that helps lenders assess the loan-to-value ratio, significant for evaluating collateral risk. Comprehending this process can help you navigate your lending expedition effectively. Loan-to-Value Ratio Comprehending the loan-to-value (LTV) ratio is vital for anyone traversing the real estate lending environment. This ratio is calculated by dividing the loan amount by the property’s appraised value, expressed as a percentage. Mortgage lenders often prefer an LTV ratio of 80% or less, which means you should aim for at least a 20% down payment. A lower LTV typically indicates less risk, leading to better loan terms. Nevertheless, if your LTV ratio exceeds 90%, you may need private mortgage insurance (PMI) to protect lenders from defaults. LTV Ratio Implications ≤ 80% Better terms, lower interest 81%-90% Standard terms, possible PMI > 90% Higher risk, mandatory PMI Types of Financing Options Available Steering through the terrain of real estate financing requires a grasp of the various options available to developers and investors. Comprehending these financing types can greatly impact your project’s success. Here’s a breakdown of common financing options: Fixed-rate mortgages: Provide consistent monthly payments, ideal for long-term budgeting. Adjustable-rate mortgages (ARMs): Offer lower initial rates that fluctuate based on market conditions, potentially increasing costs later. Hard money loans: Quick access to cash backed by collateral, typically at higher interest rates, suitable for urgent needs. Mezzanine financing: A hybrid of debt and equity, this option allows for larger investments during the maintenance of ownership control. Bridge loans: Short-term financing solutions designed to cover gaps until more permanent financing is secured. Selecting the right option can influence your financial strategy, so weigh the pros and cons carefully before committing. Common Commercial Real Estate Loans When considering common commercial real estate loans, you’ll encounter various options customized to your investment needs. Fixed-rate mortgages provide stability, furthermore adjustable-rate mortgages offer potential cost savings but come with risks. Moreover, short-term solutions like bridge and construction loans can help you navigate specific financing challenges during property transactions or development projects. Loan Types Overview A variety of loan types are available for those looking to finance commercial real estate, each designed to meet different needs and circumstances. Here’s a brief overview of common options: Fixed-rate mortgages: These offer stable interest rates and predictable payments, ideal for long-term financing. Adjustable-rate mortgages (ARMs): These feature fluctuating rates, which can lead to lower initial payments but may increase costs later. Bridge loans: Short-term financing that helps you purchase or renovate properties during the wait for long-term options. Construction loans: Particularly for funding development or renovation projects, disbursed periodically based on milestones. Other considerations: Always evaluate interest rates, repayment schedules, covenants, and fees to confirm the right fit for your investment strategy. Key Loan Considerations Comprehending key loan considerations is crucial for making informed decisions in commercial real estate financing. Fixed-rate mortgages provide stability with consistent interest rates and predictable payments, making them ideal for long-term investments. Conversely, adjustable-rate mortgages (ARMs) can offer lower initial payments, but remember, these rates fluctuate, potentially increasing your costs over time. If you need short-term financing, bridge loans are a viable option, typically lasting between 6 months to 3 years, allowing you to secure properties or fund renovations until permanent financing is arranged. For development projects, construction loans are purpose-built, releasing funds in stages based on progress, which helps manage cash flow effectively. Always evaluate interest rates, fees, and repayment terms to choose the right loan for your strategy. Factors Influencing Loan Terms Comprehending the factors that influence loan terms is essential for anyone looking to secure financing in real estate. Several key elements come into play: Credit score: A higher score often leads to lower interest rates and better repayment conditions. Debt-to-income ratio: Lenders prefer a lower DTI, indicating your ability to repay the loan. Down payment: A larger down payment reduces the loan-to-value ratio, which can result in better loan terms. Market conditions: Job growth and supply-demand dynamics in the property submarket can affect perceived risk and loan terms. Loan product: The type of loan, whether it’s a fixed-rate or adjustable-rate mortgage, can influence your overall borrowing costs and payment stability. Understanding these factors can help you make informed decisions when securing your financing. Evaluate your credit, DTI, and down payment options carefully to improve your loan terms. The Due Diligence Process in Lending Securing financing for real estate involves not just understanding loan terms, but moreover steering through the due diligence process in lending. This process entails a thorough assessment of a property’s physical condition, legal status, and market value, ensuring it meets lending criteria as you minimize risk for yourself as the lender. Key components include conducting property inspections, reviewing title reports, and performing environmental assessments to uncover potential issues. In addition, you’ll need to analyze financial aspects such as cash flow projections, operating expenses, and current market conditions to evaluate the property’s income-generating potential effectively. Engaging professional appraisers and inspectors is essential, as they provide unbiased evaluations and detailed reports regarding the property’s condition and market value. A detailed due diligence process eventually aids in risk mitigation, influencing loan terms and your approval decisions considerably. Frequently Asked Questions What Are the 5 C’s of Lending? The 5 C’s of lending are essential for comprehending how lenders evaluate borrowers. They include Character, which assesses your credit history; Capacity, measuring your ability to repay based on income and debt; Capital, reflecting your financial investment in the loan; Collateral, the asset securing the loan, and Conditions, the economic environment and loan terms. Together, these factors help lenders gauge the risk of lending to you and your overall creditworthiness. What Are the 5 P’s of Real Estate? The 5 P’s of real estate are crucial for evaluating any property transaction. They include People, who are the buyers, sellers, and agents involved; Property, which refers to the asset’s characteristics and location; Price, the agreed amount influenced by market factors; Purpose, the intended use of the property, whether for investment or personal reasons; and Process, the steps taken in executing the deal. Comprehending these components helps you navigate real estate effectively. What Are the 4 C’s of Lending? The 4 C’s of lending are fundamental for evaluating a borrower’s creditworthiness. First, Credit refers to your credit score and history, which can affect loan terms. Next, Capacity assesses your ability to repay the loan, analyzing income and debt-to-income ratio. Collateral involves the asset securing the loan, requiring an appraisal to determine value. Finally, Conditions encompass the market environment and specific loan terms that influence the lending decision. Comprehending these can improve your chances of approval. What Are the 4 P’s of Lending? The 4 P’s of lending include Credit, Capacity, Collateral, and Capital. Credit assesses your creditworthiness through scores and history, whereas Capacity evaluates your ability to repay based on income and debt ratios. Collateral refers to the property securing the loan, ensuring its value supports the amount borrowed. Finally, Capital reflects your financial strength and down payment, indicating your investment in the property, which can improve your credibility with lenders during the approval process. Conclusion In summary, comprehending the key factors in real estate lending is crucial for both lenders and borrowers. By evaluating creditworthiness, property valuation, and market conditions, you can make informed decisions. Analyzing cash flow potential and reviewing financial history aids in selecting the right financing options. Additionally, recognizing the due diligence process guarantees that all parties are aware of the risks and opportunities involved. This thorough approach ultimately leads to more successful lending outcomes and sustainable investments in real estate. Image via Google Gemini and ArtSmart This article, "Key Factors in Real Estate Lending" was first published on Small Business Trends View the full article
-
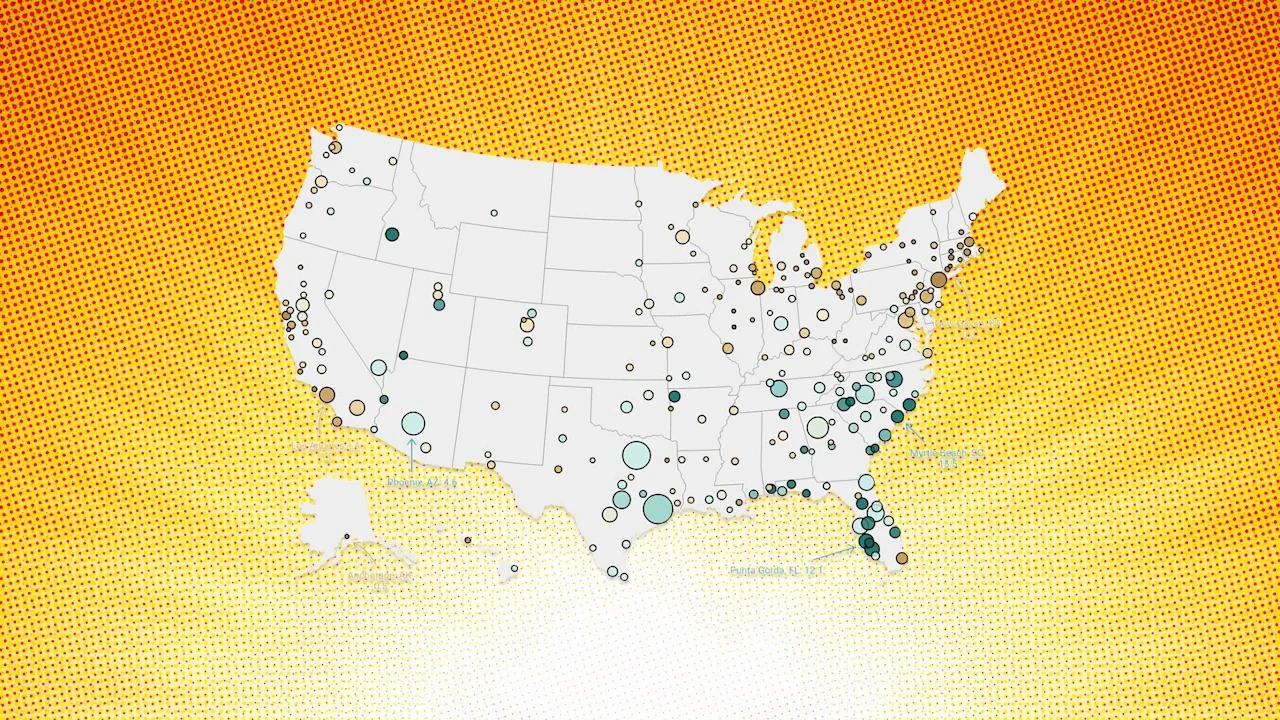
Want more housing market stories from Lance Lambert’s ResiClub in your inbox? Subscribe to the ResiClub newsletter. While many growth markets in Texas and Florida have seen some of the biggest power shifts toward homebuyers since the Pandemic Housing Boom fizzled out, Beazer Homes CEO Allan Merrill acknowledged at ResiDay 2025 last November that Beazer Homes—America’s 23rd-largest homebuilder—doesn’t plan to chase the relatively tighter housing markets in the Northeast and Midwest. Instead, he said the builder plans to stay focused on growth markets in Texas, Georgia, North Carolina, and Florida, which—despite experiencing a greater post–Pandemic Housing Boom cyclical cooling—he expects will be long-term new-home demand winners driven by population growth. Merrill pointed out that if homebuilders make investment decisions purely based on which housing markets are performing best in the short-term, then by the time those investments are made and the pipeline is ready to deliver homes in 2 to 4 years, local housing market conditions may have already shifted. Here’s what Beazer Homes CEO Allan Merrill said at ResiDay 2025 on Friday, November 7, 2025 in New York City: “You’ve pointed it out—your data doesn’t lie. Texas and Florida have been really tough [in 2025], and they were tough because inventory built. I think there was a lot of enthusiasm for the spring selling season that led to a lot of starts last fall and into the early part of the calendar year, [but] the demand didn’t materialize. So you start to see a lot of homes finished. And that puts pressure on buyers. It puts pressure on builders. It puts pressure on prices. And we saw all of that, particularly in Texas and Florida.” “I think long-term. Where’s the job growth, where’s the wage growth? I think that there are some supply and demand dynamics right now that are favorable in those places [in the Northeast and Midwest]. But when we’re buying land, we’re 2 to 4 years out from delivering homes. I want to bet on where job growth, population growth and wage growth is.” “I love our footprint. We’ve made decisions about why we are where we are, and we can grow our business substantially right where we are. There are places like Raleigh, like Nashville, that are in the Sun Belt and still have profound growth opportunities. Our home market of Atlanta is going to continue to be a big market. So there are plenty of places for us to grow within our footprint, without casting a longing glance to another city.” “They [many Midwest and Northeast communities] are also very challenging markets from an entitlement perspective. So even if builders wanted to rush in, it’d be a minute before there was any real impact.” The reason ResiClub resurfaced the commentary made by Beazer Homes CEO Allan Merrill at ResiDay 2025 is that it’s a reminder that when it comes to predicting where the most homes will be built over the next 5 to 10 years, it’s critical to examine population growth. Indeed, ResiClub’s analysis finds a strong positive statistical relationship between population growth and single-family permitting across major U.S. metro area housing markets (R² ≈ 0.68), suggesting that high homebuilding activity largely concentrates in growth markets. No region dominates homebuilding like the South, which is home to 39.0% of the nation’s population but generates 59.2% of all single-family permits. It makes sense given that the South is the epicenter of population growth. Back on January 15, I had a call with outgoing KB Home CEO Jeffrey Mezger and incoming KB Home CEO Robert McGibney. During that call, I asked them the same question I asked Beazer Homes CEO Allan Merrill last fall: Given that many housing markets in the Northeast and Midwest remain tighter than core homebuilding markets in the Southeast and Southwest, would they consider expanding their presence into some of those tighter Midwest and Northeast markets? Here’s what Mezger told ResiClub on January 15, 2026—weeks before the builder publicly announced he would transition to executive chairman, effective March 1, 2026: “We position our company strategically, where we have a presence in the strongest growth opportunity cities. When I say growth, it’s population [growth], but also economic growth, job growth, pro business, good climates, where people want to live, desirable cities, and so they come and they go, and we keep the presence. Even if it’s a softer market [today], there’s still opportunity: Literally five miles apart in one city, you can have a totally different market dynamic. And in every one of our communities, even in red divisions right now, we are encouraging them to grow and make investment. In fact, here in the first quarter, we’re going to, as we conveyed on earnings call, we’re going to have the highest community count coming out of the first quarter. Of the first quarter we’ve had in the last six or seven years across the system. So our focus is to continue to grow market share in all of our markets. And while Denver is softer, as Rob [McGibney] mentioned, we have a presence, and we know what its potential is. And you navigate and optimize it, and then you take it on a run when the market conditions support it. So we wouldn’t opportunistically jump somewhere, because it’s good at this point in time when it could be not so good a year from now. We’d rather be consistent and really push the opportunities where we’re at.” Of course, while many large homebuilders have made the decision to anchor down in growth markets and resist the urge to chase currently tighter Midwestern and Northeast pockets like Buffalo and Youngstown, that doesn’t mean they will maintain high spec levels in Sun Belt markets that are passing through home price corrections. Indeed, over the past 12 to 18 months, many large homebuilders have temporarily reduced their volumes in the weakest housing markets. “We’ve seen [housing] starts come down year-over-year in many [weaker] markets . . . especially spec starts,” Mezger told ResiClub in January. “It’s good to see that there’s not a lot more inventory being injected into some of the softer markets, and I think that’s going to help places like Florida stabilize.” KB Home says the pullback is helping limit further inventory pressure in markets like Florida, Phoenix, and Denver where “prices just ran up too much relative to incomes [during the Pandemic Housing Boom].” The big picture Ultimately, the split between softer Sun Belt markets and tighter Midwest and Northeast metros reflects current housing-market dynamics. But for giant homebuilders, market presence hinges more on long-term housing base growth fundamentals—population growth, income gains, and job creation—than just the current level of months of supply. That’s why many giant publics are slowing starts to a degree in softer pockets of Texas and Florida rather than pulling out entirely: the long-run demographic tailwinds in many Southern markets remain strong. As for the Midwest, when giant homebuilder push in, they aren’t simply chasing the tightest markets right now. Instead, when they do expand there, it’s through selective moves—into metros like Indianapolis, Cincinnati, and Columbus. They’re looking for places with durable, multi-year growth prospects. Homebuilding is a 2- to 6-year pipeline business. By the time a new community delivers, today’s conditions may have shifted. Long-term outlooks matter. View the full article
-
The long-running rumor that Mark Zuckerberg is secretly a robot is starting to feel a lot less like a joke. According to a report by the Financial Times, Meta is building out a “photorealistic, AI-powered 3D” version of its CEO that employees can interact with and get direct feedback from. Sources told the publication that the bot will be trained on his image, mannerisms, tone, speaking style and public statements to give employees a fully authentic Zuck experience. Zuckerberg himself is directly involved with training the AI avatar “so that employees might feel more connected to the founder through interactions with it,” according to the Financial Times. He also started spending five to 10 hours per week coding AI projects and joining in on technical reviews. (Meta has not yet responded to Fast Company’s request for comment.) In the ongoing AI race among other tech giants like OpenAI and Google, Meta has embraced the technology to the fullest. It’s not the company’s first rodeo with AI doppelgangers: In October 2023, Meta announced partnerships with celebrities—like Kendall Jenner, Snoop Dogg and Paris Hilton—to create chatbot versions of themselves. (They later discontinued the initiative after it received backlash.) In 2024, Meta introduced “AI Studio” to all creators, allowing them to generate custom AI chatbots. Earlier this year, however, the company banned teens from accessing the personal chatbots over safety concerns. Meta has also pushed its staff to use AI tools in their workflows, even encouraging employees to design their own AI agents to streamline and automate tasks. This has sparked fears of layoffs among staffers, according to Financial Times. Last month, Reuters reported that Meta was planning layoffs that could impact 20% of the company to offset the cost of AI. The internet responded to the news of an AI-generated Zuckerberg in typical internet fashion. “Robozuck would 100% be more personable than Meatzuck,” one Redditor commented. “If a CEO can be replaced by AI then none of them should be worth billions,” another Reddit user said. “The closest we’ve come to a human Mark Zuckerberg,” a third joked. Earlier this year, the Wall Street Journal reported that Zuckerberg was creating an AI agent of himself to help him complete daily tasks—though that was a separate endeavor from Meta’s project to clone him. Sources told the Financial Times that if this experiment goes well, creators might be able to create clones of their own. Maybe we’ll all get to see the day where our photorealistic AI clones do the work we don’t want to. View the full article
-
We may earn a commission from links on this page. When Squid Game hit Netflix in 2021, the world felt the impact. Emerging from a pandemic, people were broke, bored, and ready to break bad, and the show’s sharp satire of capitalism hit just right. The premise—people in various levels of life-destroying debt sign up to play a series of deadly children’s games in exchange for the chance at a life-changing amount of cash (kept on display in a giant piggy bank, in one of the show’s many brilliant visual touches)—straddled the line between sadly plausible and nightmarishly bizarre, but anyone could sympathize with the desperate protagonist, Seong Gi-hoon (Lee Jung-jae). The show has finished its third and final season, and we’ve already offered up the best series you can watch to keep those bleak vibes going. But if you need more bleak in your life, you have other options. Here are the books, movies, video games, and podcasts you can turn to when you’re done watching (and re-watching) Squid Game. The best books like Squid GameUnder the bright primary colors and friendly shapes, Squid Game is a story about money, desperation, and mob mentality. Lucky for you, plenty of books offer those same themes along with similarly gripping tension. The Plotters, by Un-Su Kim $15.19 at Amazon Shop Now Shop Now $15.19 at Amazon Hit, by Delilah S. Dawson $12.99 at Amazon Shop Now Shop Now $12.99 at Amazon Docile, by K.M. Szpara $17.49 at Amazon $22.99 Save $5.50 Shop Now Shop Now $17.49 at Amazon $22.99 Save $5.50 The Running Man, by Richard Bachman (Stephen King) $9.99 at Amazon $11.99 Save $2.00 Shop Now Shop Now $9.99 at Amazon $11.99 Save $2.00 The Family Experiment, by John Marrs $18.99 at Amazon Shop Now Shop Now $18.99 at Amazon SEE 2 MORE The Plotters, by Un-Su KimLike Squid Game, The Plotters is set in contemporary South Korea, and like the show, the novel tells the story of a flawed man who comes to realize he’s been playing a rigged game. Reseng is an assassin who has unquestioningly followed orders his whole life, killing people according to orders handed down by the mysterious “plotters.” When a colleague is killed for disobeying an order, however, Reseng’s faith is shaken, and he begins investigating just who, exactly, is issuing those orders. What he finds won’t surprise Squid Game fans one bit. Hit, by Delilah S. DawsonIf the interrogation of an unfair economic system is what resonated with you while watching Squid Game, then Hit is for you: When Valor National Bank buys the national debt, it also gains the right to kill the people who owe it money—which is just about everyone. People like Patsy are given a choice: Pay their debt (impossible), be killed right there and then (undesirable), or work as a bounty hunter killing other debtors. It’s violent, messy, and filled with trenchant commentary on the broken system we live in. Docile, by K.M. SzparaThe way debt warps and dehumanizes us is a major theme in Squid Game, which makes Szpara’s novel the perfect choice. In the near future, debt has legally become inheritable, trapping whole families in a cycle of financial servitude that is owned by a small handful of the ultra-wealthy. People can choose to become literal slaves for a period of time in order to work of some or all off their debt—but their temporary “owners” can do whatever they want to them during their servitude, so most opt to numb themselves with a drug called Dociline that keeps them calm and insulated from their suffering. Fans of Squid Game will recognize the sweaty desperation on display here. The Running Man, by Richard Bachman (Stephen King)King’s 1982 novel was definitely before its time, and has a setup similar to Squid Game. In the far-future of 2025 (!), Ben Richards is struggling to pay his bills and buy medicine for his sick daughter in an America devastated by economic ruin. Desperate, he signs up to be a contestant with the government-run reality game called The Running Man, where he’ll be hunted by trained assassins. If he can survive for 30 days, he gets $1 billion—with bonuses for killing hunters. The Family Experiment, by John MarrsMarrs’ novel (part of his Dark Future series) hits those Squid Game vibes in a different key. As the world’s population soars and the economy worsens, most people can no longer afford to have children. A company offers a grim, Black Mirror-esque solution: You can ‘grow’ a virtual child and interact with them in the metaverse. To promote the technology, they launch a reality show where ten couples raise a virtual child from birth to the age of 18 in just nine months—and then must compete for a chance to keep their virtual child, or risk it for the chance at a real child. The best movies like Squid GameFor all its bright colors and menacingly silly design, Squid Game offers up a suffocatingly dark, dystopian vision of the world. If you want more of that, here are some feature-length movies that will hit that dark, sweet spot. Cube (1997) In the midst of all the violent strategies and desperate gambits on Squid Game, you get the sense that it’s also a kind of experiment to see just how far (and low) people will go to survive and get paid. In Cube, five people find themselves trapped in a series of square rooms connected by hatches in each wall, floor, and ceiling—many of which are booby-trapped in horrifying ways. As the group works its way through the rooms, there’s a similar vibe as their creativity and willingness to sacrifice each other comes into play. Stream Cube on Plex or rent it from Prime Video. Cube (1997) $3.99 at Prime Video Learn More Learn More $3.99 at Prime Video The Platform (2019) Squid Game is a trenchant social commentary, examining the morality of modern society and the impact of inequality. That makes The Platform the perfect movie pairing. In this film, a man named Goreng agrees to spend six months in the “Vertical Self-Management Center,” where pairs of prisoners live on different levels. Once a day, a platform laden with a rich feast descends from above and stops for two minutes—prisoners can only eat during that time. The people placed on top can eat what they like, while the people on the lower levels are lucky to get anything. Goreng eventually goes on an odyssey to discover the secrets of who’s behind this cruel system. Stream The Platform on Netflix. The Platform (2019) at Netflix Learn More Learn More at Netflix The Belko Experiment (2016) One of the great pleasures of Squid Game is watching well-rounded characters fight for their lives using every skill and advantage they have. In The Belko Experiment, a standard group of office drones suddenly find themselves trapped in a fortified building and inform the employees that they must kill two people within 30 minutes, or several of them will be killed at random. The bloody chaos that ensues will be music to the ears of any Squid Game fan. Rent The Belko Experiment on Prime Video. The Belko Experiment (2016) $3.99 at Prime Video Learn More Learn More $3.99 at Prime Video Escape Room (2019) One of the great thrills of each episode of Squid Game was finding out what bizarro version of a children’s game was going to be repurposed into a crowd-thinning slaughter. Escape Room offers a similar vibe: Characters forced to survive deadly escape rooms using their brains and physical skills means a whole new mystery challenge every time they make it to the next room. Rent Escape Room on Prime Video. Escape Room (2019) $3.99 at Prime Video Learn More Learn More $3.99 at Prime Video Cheap Thrills (2007) Want more desperate people willing to do much more than they ever imagined in exchange for getting out of soul-crushing financial difficulty? Of course you do, so you’ll love this black comedy. Two down-on-their-luck friends meet a seemingly friendly man and his wife at a bar. When the man offers them a few bucks to take on innocuous challenges and innocent pranks, they both eagerly lean into the contest—but as the offered sums get larger, the cruelty and danger of the required tasks grow as well. Stream Cheap Thrills on The Roku Channel or rent it from Prime Video. Cheap Thrills (2007) $4.99 at Prime Video Get Deal Get Deal $4.99 at Prime Video The best video games like Squid GameSquid Game is modeled in some ways on video games—platforms, dream logic, gore aplenty, etc. So it makes sense that the best way to extend your Squid experience would be to get into a game that has similar mechanics and vibes. Luckily, you’ve got a lot of choices. Squid Game: Unleashed If you’re yearning for more of the Squid Game universe, it makes sense to go directly to the source and play the official game version. You can play almost all of the classic Squid Game games, like Red Light, Green Light (although some have been tweaked to make them more playable on a console or phone), and it’s all done up in the show’s iconic color scheme and visual style. If you’re looking for a direct extension of the show, this is the bet. Platforms: Android, iOS Squid Game: Unleashed at Apple App Store Learn More Learn More at Apple App Store Fortnite Fortnite remains an incredibly popular battle royale and survival game, and if you’re seeking the chaotic violence of Squid Game’s early rounds, this is the way. Plus, you can literally download Squid Game skins, play Squid Game-themed versions, and build Squid-themed islands in the game, combining these two fictional universes into one demented sandbox. Platforms: PlayStation, Xbox, Nintendo Switch, Android, iOS Fortnite at Epic Games Learn More Learn More at Epic Games Fall Guys Looking to replicate the mechanics of some of Squid Game’s more epic challenges? Play Fall Guys, a fast-paced, super fun obstacle/racing game with obstacles, delightfully cartoonish graphics, and the opportunity to knock opponents off the course. It doesn’t have the grim violence of the show, but that means you can have all the fun without worrying that you’re pushing your cosmic karma into the red. Platforms: PlayStation, Nintendo Switch, Xbox, Android, iOS Fall Guys at Epic Games Learn More Learn More at Epic Games Danganronpa If you want more of the bleak whimsy that Squid Game serves up, check out Danganronpa, a series of interactive visual novels. In the first installment, you play as a high school student trapped in their school by a robotic teddy bear. Your only hope to escape is to murder another student—and get away with it—in a battle royale-esque competition. It combines mystery-solving with other first-person gameplay elements to offer up an immersive experience fans of the show will enjoy. Platforms: PlayStation, Nintendo Switch, Xbox, Steam Danganronpa Trilogy $64.99 at Amazon Shop Now Shop Now $64.99 at Amazon We Happy Few Did you love the atmosphere of paranoia and dread experienced by anyone in the Squid Game universe who tried to cling to their moral and ethical principles in the games? Then We Happy Few is for you. Set in a world where most of the population is tripping on powerful hallucinogens that allow them to commit all kinds of terrible violence while wearing creepy, smiling masks, you play as a “downer” who’s trying to escape the city’s chaos without drawing attention to yourself. Combined with a wonderfully bent visual style, this game is ideal for Squid fans. Platforms: PlayStation, Xbox, Steam We Happy Few $59.99 at Steam Shop Now Shop Now $59.99 at Steam The best podcasts like Squid GameWhether you want a deep dive into the show’s lore or production, or a similarly creepy narrative experience, these are the podcasts you should check out. Squid Game: The Official Podcast Credit: Podcast logo Might as well go to the source: The official Squid Game podcast is hosted by Phil Yu, and offers up insider info on the show’s universe, game mechanics, themes, and production. If you’re curious about all the real-life moving parts that come together to make something with this much cultural impact, put this in your ears. Player 456 Credit: Podcast logo If you want discussion about and analysis of Squid Game from a more fan-focused perspective, check out Jack and Colin’s obsessive podcast. They dissect the show’s themes and recap episodes with a sharp eye for detail and a fan’s genuine love of the show. Rabbits Credit: Podcast logo If you want a narrative podcast that hits the same dopamine generator as Squid Game, Rabbits is the creepy story you need. When a young woman’s friend goes missing and the police aren’t motivated to find her, she begins her own investigation, and begins to suspect her friend has been playing a kind of “alternate-reality” game that is much older and much deadlier than she realizes. It’s got the dread, world-building, and game mechanics fans of the show will appreciate. Limetown Credit: Podcast logo This classic narrative podcast is centered on the mysterious disappearance of hundreds of residents of a research facility. Like Squid Game, the story starts off rooted in a realistic universe, then slowly reveals a much weirder, and much more ominous reality hiding behind the superficial world. There’s sci-fi technology, immersive world-building, and a terrific mystery to be solved. Project Nova Credit: Podcast logo In Project Nova, four people wake up to discover they’re trapped in a mysterious experiment in a high-tech facility. An artificial intelligence gives them tasks to perform—and the consequences of not doing as they’re told or performing these tasks incorrectly can range from painful to deadly. It’s got the high-stakes, high-style buzz of the show coupled with an engaging mystery. View the full article
-
Earnings for first quarter underline asset manager’s push into investment products that generate higher feesView the full article
-
Cash-strapped Stormont executive appeals to prime minister for aid package for hard-pressed regionView the full article
-
We may earn a commission from links on this page. A juicy prestige mystery series with Nicole Kidman in the lead? Honestly, who ever heard of such a thing? As a crime procedural, it's a bit more Special Ops: Lioness than Nine Perfect Strangers, but the era of Kidman domination demands variety, so now we get this series based on the long-running (29 books and counting) Kay Scarpetta series from Patricia Cornwell that follows the eponymous forensic pathologist. She's joined by Jamie Lee Curtis as her sister, Dorothy, and Bobby Cannavale as a forensic operations specialist, which is a job that I definitely know what it is. Stream Scarpetta on Prime Video before examining these other juicy crime dramas. Ballard (2025 – ) Based on another popular novel series, this one by Michael Connelly (the show itself a spin-off of the spin-off of the Prime Bosch series), Ballard stars Maggie Q as the title's Detective Renée Ballard, head of an LAPD cold-case unit. Ballard takes over an understaffed, volunteer-heavy LAPD cold-case unit, solving (sometimes) decades-old crimes while uncovering, over the course of the first season, a web of corruption within the police department (if you can imagine). Stream Ballard on Prime Video. Ballard (2025 – ) at Prime Video Learn More Learn More at Prime Video The Åre Murders (2025) Scandinavian cop drama (or Nordic noir, if you prefer) is its own sub-genre, so ubiquitous that the Disney+ show Agatha All Along did an episode parodying the form. Certainly The Åre Murders (adapted from the novels of Viveca Sten) makes the case that Swedes know from murder. Plain-spoken, troubled (as in: under suspension) detective Hanna Ahlander (Carla Sehn) leaves Stockholm to spend some time unwinding at her sister's place in remote Åre. A case involving a missing girl finds her back on the job, and up against local police officer Daniel Lindskog, whom she's reluctant to trust. Looking for a bleakly beautiful landscape and ambiguous morality? Åre might be the place for you. Stream The Åre Murders on Netflix. The Åre Murders (2025) at Netflix Learn More Learn More at Netflix When No One Sees Us (2025 – ) A distinctive police thriller imported from Spain, When No One Sees Us stars Mariela Garriga (Mission Impossible: Dead Reckoning) as a Cuban-American special agent of the U.S. Army, and Maribel Verdú (Pan’s Labyrinth) as a Spanish Civil Guard sergeant struggling with a complex home life. Both are investigating an apparent death by violent suicide on an air base during Holy Week. It's another complex mystery, but the performances and the emphasis on character over plot make it a standout. Stream When No One Sees Us on HBO Max. When No One Sees Us (2025 – ) at HBO Max Learn More Learn More at HBO Max Get Millie Black (2024) Booker-winning novelist Marlon James created and co-wrote this wildly acclaimed miniseries, touching on bias, discrimination, and colonialism in the context of an impressively cracking missing-person drama. Having been encouraged to leave Scotland Yard following the death of a missing child she'd been searching for, Detective Millie-Jean Black (Tamara Lawrance) opts to return home to Jamaica and join the police force there. She reunites with her sibling, Hibiscus (Chyna McQueen, who received a BAFTA nomination for this, her first screen role), before being drawn into the case of a Black teenager who seems to have been groomed by a rich white family before disappearing—a case that forces her to work with a condescending colleague sent over from London. It was constructed as a miniseries, but there's talk of a revival somewhere down the line. Stream Get Millie Black on HBO Max. Get Millie Black (2024) at HBO Max Learn More Learn More at HBO Max The Chestnut Man (2021 – ) Head on over to sunny Copenhagen, where Naia Thulin (Danica Curcic) is assigned to investigate the murder and dismemberment of a young woman in a playground, the best clue being a small figurine made of chestnuts nearby. When a politicians daughter goes missing, that wee chestnut man is enough to tie the case back to the murder of an entire family on a farm nearly four decades ago. It's been a while, but the series is returning soon under the title The Chestnut Man: Hide and Seek. Stream The Chestnut Man on Netflix. The Chestnut Man (2021 – ) at Netflix Learn More Learn More at Netflix Prime Suspect (1991 – 2006) A lady Detective Chief Inspector? What will they think of next? Prime Suspect isn't entirely about sexism in the workplace, but it was born in an era when a female officer in the London's Metropolitan Police would have been a rarity in the extreme. DCI Jane Tennison's personal and professional struggles are inseparable from her work as a homicide investigator, but she's very, very good at her job, and Helen Mirren's absolutely iconic performance in the role has become a template followed, at least in parts, by many a cop show since. Stream Prime Suspect on Peacock, Prime Video, and Tubi. Prime Suspect (1991 – 2006) at Peacock Learn More Learn More at Peacock Deadloch (2023 – ) Not a tonal match, in that it's a comedy, but plays in a similar sandbox even as it takes crime drama tropes and flips them on their heads. It's also an excellent mystery/crime procedural that simultaneously works as a very funny send-up of the genre—in this case we're talking about the dour, dangerous world of shows like Broadchurch and its many imitators. The Australian import stars Kate Box stars as Dulcie Collins, the fastidious senior sergeant of the police force in the title's fictional town, who, when a body turns up dead on the beach, is joined by Madeleine Sami's Eddie Redcliffe—a crude, loud, and over-the-top obnoxious detective brought in to help solve the case. The web of secrets and mysteries in the tiny Tasmanian town makes everything appropriately addictive, with the added bonus of being, frequently, a hoot. Stream Deadloch on Prime Video. Deadloch (2023 – ) at Prime Video Learn More Learn More at Prime Video Mare of Easttown (2021) Kate Winslet picked up an Emmy for her performance as thoroughly troubled Mare Sheehan, a local hero in her days as a high school basketball champ whose adult reputation is rapidly losing its luster. As a police detective, she's been unable to solve the case of a missing girl even as she's confronted with a recently murdered teenage mother—you probably won't be surprised to find that the cases are linked. Word on the street is that a second season might be in the works. Stream Mare of Easttown on HBO Max. Mare of Easttown (2021) at HBO Max Learn More Learn More at HBO Max Bones (2005 – 2017) A bit lighter in tone than Scarpetta, this network procedural gave us an impressive 12 seasons of forensic crime-solving involving cases both hot and cold. Emily Deschanel is Temperance Brennan, the "Bones" of the title, a forensic anthropologist and crime fiction author who's recruited by earthy FBI Special Agent Booth (David Boreanaz) to help him solve cases that require an expertise in the examination of human remains (which, luckily enough, turns out to be just about every case). Stream Bones on Peacock, Prime Video, and Hulu. Bones (2005 – 2017) at Peacock Learn More Learn More at Peacock Crossing Jordan (2001 – 2007) Following her mother's murder, Massachusetts forensic pathologist Dr. Jordan Cavanaugh (Jill Hennessy) becomes obsessed with solving violent crimes in a show that blends intense crime procedural motifs with quirky characters and relationships; the show's got a unique tone that shouldn't work but does, mostly. The stacked supporting cast includes Miguel Ferrer, Mahershala Ali, Kathryn Hahn, Lorraine Toussaint, and Jerry O'Connell. Stream Crossing Jordan on Peacock and Prime Video. Crossing Jordan (2001 – 2007) at Peacock Learn More Learn More at Peacock View the full article
-
Today, April 14, is World Quantum Day. The day marks the beginning of an annual event in which scientists and educators around the globe work to raise awareness of the underlying science behind technologies that could radically transform our world in the years ahead. Here’s what you need to know. What is World Quantum Day 2026? World Quantum Day is an annual awareness day organized by quantum scientists worldwide. According to the day’s official website, the initiative is “decentralized and bottom-up,” meaning there is no single organization promoting World Quantum Day. Instead, individual scientists work in tandem to promote the event. Those scientists, in turn, invite other scientists, artists, technologists, educators, entrepreneurs, and those from myriad other fields to host their own activities for the day, including talks, exhibitions, and interviews. At the heart of World Quantum Day is the goal of promoting public awareness of quantum science and the technologies that rely on it. 2026’s World Quantum Day is the fifth annual one. The first World Quantum Day took place on April 14, 2022, and has been held every April 14th since then. According to WorldQuantumDay.org, the 2025 event saw more than 530 events take place in more than 318 cities in over 83 countries. Why is World Quantum Day on April 14? World Quantum Day is held on April 14 each year, but that day wasn’t chosen at random. The April 14th date is a nod to Planck’s constant, a principle first theorized by the physicist Max Planck in 1900. According to the National Institute of Standards and Technology (NIST), the “constant is a number that defines the amount of energy” held in each quanta, which are packets of energy exchanged between constructs in the quantum world. The constant underpins quantum physics and plays a central role in technologies such as GPS, computer chips, touchscreens, and many others we rely on every day. When put in a decimal format, April 14 equals “4.14,” which is “the rounded first digits of Planck’s constant,” according to WorldQuantumDay.org. That constant equals 4.1356677×10⁻¹⁵. Why should I care about World Quantum Day? Quantum physics underlies most of the technologies you rely on today. And now scientists are harnessing humankind’s understanding of quantum physics to develop the next generation of computer systems that have the potential to radically transform everything from medicine to communications to artificial intelligence. These computers are known as quantum computers, and they operate on the principles of quantum physics rather than classical physics, as today’s computers do. Currently, every computer you have ever used (unless you are a quantum scientist) has operated on the principles of classical physics. These computers operate on binary bits, where each bit can only be 1 or a 0. But a quantum computer runs on qubits. Unlike a regular bit, thanks to the principles of quantum physics, a qubit can be a 1 or a 0—or anything in between, at the same time. This means they can perform calculations exponentially faster than the bits powering classical computers. Theoretically, what would take today’s fastest supercomputer millions of years to process could be solved by tomorrow’s quantum computer in just a few hours. While this has tremendous potential for the fields of medical research, communications, and materials science, quantum computers also pose serious security risks to today’s classical encryption systems, which underpin everything from messaging security to Bitcoin. All this means that it is more important than ever for the general public to understand what quantum physics is, the technological advancements it already offers, and the upcoming technologies it will enable that will further transform our world. View the full article
-
US president turns against Italian premier despite her being one of his few remaining allies in EuropeView the full article
-
Representatives of the two meeting in Washington to discuss conflict and its links to the Iran warView the full article
-
Data highlights concerns about lack of jobs growth among British-born populationView the full article
-
Grasping the key components of franchises is fundamental for anyone considering this business model. Franchises thrive on brand consistency, operational effectiveness, and a solid partnership between franchisors and franchisees. Each element, from training systems to marketing support, plays a vital role in ensuring success. As you explore how these components work together, you’ll discover the intricate balance needed for franchising to flourish in today’s competitive market. What aspects should you focus on to maximize your franchise potential? Key Takeaways A strong brand name fosters customer trust and loyalty, crucial for franchise success. Unique business models set franchises apart from competitors and attract customers. Well-structured training systems ensure consistent quality and effective replication of the business model across locations. Rigorous planning and execution are essential for scalability and maintaining brand integrity over time. A partnership model encourages collaboration between franchisors and franchisees, enhancing operational success. Key Ingredients of a Successful Franchise When you consider the key ingredients of a successful franchise, it’s important to recognize that several factors contribute to its effectiveness and appeal. A strong brand name instills customer trust, whereas a unique business model sets you apart from competitors. Before investing, ask questions to assess these elements, like “What’s the brand’s reputation?” or “How does this franchise differ from others?” A well-structured training system guarantees consistent quality across all locations, making it easier for franchisees to succeed. Furthermore, the partnership model nurtures collaboration between franchisors and franchisees, sharing both risks and rewards. To understand how do franchises work, rigorous planning and execution are crucial for scalability and replicability, which are fundamental for long-term success. What Can Be Franchised? Franchising offers a flexible growth strategy that can be applied across various industries, provided the business meets vital criteria. Any business with a strong brand, unique business model, compelling value proposition, effective training system, and partnership model can be franchised. This model allows you to replicate unique products, services, or offerings across multiple sectors, showcasing its versatility. Successful franchises demand rigorous planning, development, and execution to guarantee brand integrity and consistency across all units. Dentons’ expertise spans various sectors like retail, restaurants, and education, highlighting how franchising isn’t limited to one industry. Whether you’re in food service or education, if you meet the fundamental franchise criteria, your business could thrive through franchising as a method for expansion and market penetration. The Dentons Seven-Step Plan to Launching a Franchise Business Launching a franchise business involves a systematic approach, and the Dentons Seven-Step Plan provides a structured framework to guide you through this process. Step Description Purpose Risk-Benefit Analysis Evaluate if franchising aligns with your brand goals Confirm strategic alignment Financial Models Develop models to validate profitability Determine pricing structures Franchise Operating Model Modify practices for replication by franchisees Standardize operations Following these steps guarantees you establish a solid foundation. You’ll create extensive documentation, including manuals for franchisees, which is essential for maintaining consistency. Moreover, implementing robust training and audit programs will help uphold brand standards across all locations, assuring a uniform customer experience. Franchise Rights and Operations Comprehending franchise rights and operations is fundamental for anyone considering entering the franchise business. Franchise rights grant you the ability to operate under a recognized brand name and trademark, which can greatly boost your visibility. Territorial rights define the specific geographic areas where you can operate, preventing overlap with other franchisees. Your operations will be guided by FranConnect Standard Operating Procedures (SOPs) and detailed operational manuals, ensuring consistency across all locations. It’s critical to comply with local laws and health standards to maintain brand integrity. Finally, your franchise agreement will outline the terms of your rights and operations, detailing initial fees, ongoing royalties, and conditions for termination or transfer of ownership, which are crucial for a successful franchise expedition. Marketing and Advertising Support After comprehending franchise rights and operations, it’s important to recognize the role of marketing and advertising support in the success of your franchise. Franchisors typically provide national advertising campaigns that improve brand visibility, benefiting all franchise units. You’ll furthermore receive guidance on effective local marketing initiatives customized to your area, which can greatly enhance customer engagement. Moreover, access to professionally designed promotional materials helps maintain a consistent brand image during cost savings. Franchise agreements usually require a percentage of your revenue to be contributed to an advertising fund, supporting both national and local marketing efforts. Approved advertising channels and promotional activities are outlined by franchisors, ensuring all marketing aligns with the brand’s standards and messaging. Financial Obligations and Reporting Comprehending the financial obligations tied to franchising is crucial for your long-term success as a franchisee. These obligations can notably impact your investment and operational decisions. Here’s what you need to know: An initial franchise fee varies widely, potentially costing from a few thousand to millions, especially for recognized brands. Ongoing royalty fees typically range from 4.6% to 12.5% of your sales, ensuring revenue for the franchisor. You’ll likely contribute to an advertising fund for national marketing campaigns. Equipment and supply costs can add to your initial and ongoing expenses. Regular financial reporting to the franchisor is mandatory, promoting transparency and compliance. Understanding these components helps you navigate your franchise expedition effectively. Contract Duration, Termination, and Transferability When you enter into a franchise agreement, comprehending the contract’s duration, termination clauses, and transferability conditions is essential for your operational strategy. Franchise agreements usually last between 5 to 30 years, giving you a defined timeframe to operate under the franchisor’s brand. Renewal terms are often specified, outlining how you can extend your agreement once it expires. Termination clauses indicate the conditions under which either party can end the agreement, including breaches or failure to meet standards. After termination, you must fulfill obligations like returning proprietary materials and adhering to trademark guidelines. Finally, transferability conditions may require you to seek franchisor approval for ownership transfer, possibly involving fees for administrative processes. Quality Standards and Dispute Resolution Maintaining quality standards is crucial for the success of any franchise, as it directly impacts customer satisfaction and brand reputation. To achieve this, franchisors implement several key practices: Approved supplier lists guarantee consistency in product quality. Detailed service protocols guide customer interactions, enhancing satisfaction. Pre-approval of advertising materials maintains brand image across locations. Mediation and arbitration clauses provide structured dispute resolution. Confidentiality provisions protect sensitive information during conflicts. These elements work together to create a cohesive franchise experience. Support and Resources for Franchisees When you become a franchisee, you’ll rely on extensive training programs that cover everything from operations to customer service, ensuring you meet brand standards. Ongoing operational support and marketing assistance are likewise essential, helping you tackle challenges as you promote your business effectively. This robust support system not just improves your performance but additionally strengthens your relationship with the franchisor, setting the stage for long-term success. Comprehensive Training Programs Thorough training programs are vital for franchisees aiming to succeed in their business ventures. These programs cover fundamental areas to guarantee you can replicate the business model effectively: Operations management Customer service techniques Financial management skills Brand standards and compliance Market adaptation strategies Ongoing Operational Support Ongoing operational support is crucial for franchisees, as it provides the resources and guidance needed to navigate the challenges of running a successful business. This support includes thorough training programs that cover key areas like operations, customer service, and financial management, ensuring you meet brand standards. Furthermore, continuous assistance from franchisors helps you tackle challenges and seize local market opportunities. Regular business reviews assess your performance, nurturing a strong relationship with your franchisor, which is imperative for long-term success. You’ll likewise gain access to valuable resources, such as marketing materials and advertising strategies, empowering you to effectively promote your business. This collaboration helps maintain brand consistency and drives overall franchise growth, benefiting everyone involved. Marketing Assistance Strategies Effective marketing assistance strategies play an essential role in the success of franchisees, as they provide fundamental resources and guidance for promoting the brand. These strategies not just improve visibility but additionally guarantee that franchisees can connect with their local markets effectively. National advertising campaigns boost brand recognition across all locations. Customized local marketing initiatives resonate with the community. Professionals design marketing materials, maintaining brand consistency. Franchisees contribute to an advertising fund for wider marketing efforts. Digital platforms like social media and email marketing engage target audiences. Technology’s Role in Franchise Operations As technology continues to evolve, its role in franchise operations becomes increasingly critical for success. Integrating technology improves communication efficiency and streamlines processes across multiple locations. Advanced analytics tools enable you to make data-driven decisions, boosting operational efficiency and brand consistency. Point-of-sale systems and inventory management software allow you to track sales and stock levels in real-time, facilitating timely adjustments. Digital marketing platforms optimize local advertising efforts, helping you effectively reach your target audience. Furthermore, technology empowers franchises to adapt to market changes, enabling quick responses to consumer trends and encouraging ongoing innovation. Technology Tool Benefits Advanced Analytics Data-driven decision-making Point-of-Sale Systems Real-time sales tracking Digital Marketing Optimized local advertising Building a Robust Support System Building a robust support system is vital for franchise success, as it empowers franchisees to thrive within the established brand framework. A well-structured support system encompasses various fundamental elements that guarantee franchisees can operate efficiently and maintain brand integrity. Extensive training programs equip franchisees with necessary knowledge. Ongoing support includes marketing assistance and operational guidance. Clearly defined standard operating procedures (SOPs) promote consistency across units. A strong partnership model improves communication and collaboration. Technology integrates efficient tools and analytics for quick adaptation. Frequently Asked Questions What Are the Three Main Components of a Franchise Strategy? The three main components of a franchise strategy are brand identity, operational consistency, and franchisee support. Brand identity creates a recognizable name and trademark that draws customers and potential franchisees. Operational consistency guarantees that all locations deliver the same quality and service through standardized procedures. Finally, franchisee support involves training programs and resources that help franchisees maintain brand standards and address challenges, nurturing a successful partnership between franchisors and franchisees. What Are the 4 P’s of Franchising? The 4 P’s of franchising are essential for your franchise’s success. They include Product, which focuses on the unique goods or services you offer; Price, which involves setting prices that reflect value during ensuring profitability; Place, highlighting the importance of choosing ideal locations for customer access; and Promotion, which encompasses marketing efforts to effectively communicate your brand message. What Is a Key Feature of a Franchise? A key feature of a franchise is the franchise agreement, which allows you to operate under the franchisor’s established brand name. This agreement typically lasts between 5 to 30 years and outlines your rights and responsibilities. You’ll benefit from a recognizable brand, making it easier to attract customers. Furthermore, you’ll receive ongoing support, including training and marketing assistance, ensuring you maintain the brand’s standards and operational procedures for consistent performance across all units. What Are the Four Elements of Franchising? The four key elements of franchising are a strong brand identity, a proven business model, a thorough franchise agreement, and ongoing support from the franchisor. A strong brand identity helps attract customers and guarantees consistency across units. The proven business model allows franchisees to replicate success effectively. The franchise agreement defines the rights and responsibilities of both parties. Finally, ongoing support, including training and marketing, is crucial for franchisee success and brand maintenance. Conclusion In summary, comprehending the key components of franchises is essential for success. A strong brand name, a unique business model, and effective training systems create consistency and operational efficiency. Furthermore, nurturing a collaborative partnership between franchisors and franchisees improves growth potential. By prioritizing rigorous planning, marketing support, and quality standards, franchises can maintain brand integrity and scalability across multiple locations. Emphasizing these elements will contribute to the overall success and reliability of the franchise system. Image via Google Gemini This article, "What Do Key Components of Franchises Work?" was first published on Small Business Trends View the full article
-
We may earn a commission from links on this page. Prices are going up on many different goods and services, and technology is no exception. Global events over the past year, from the implementation of tariffs to interruptions in oil shipments, are pushing companies to raise the cost of smartphones, tablets, and more for consumers. At this point, it's refreshing when a company doesn't raise prices—like when Apple dropped a brand-new MacBook for just $599. It's not just new products seeing price hikes. As reported by Phone Arena, Samsung just increased the prices on a number of its devices, including some smartphones, and a lot of tablets. That includes the following phones, which seen their prices change as noted: Galaxy Z Flip 7: from $1,219.99 to $1,299.99 (512GB) Galaxy S25 FE: from $709.99 to $749.99 (256GB) Galaxy S25 Edge: from $1,219.99 to $1,299.99 (512GB) You'll notice that the company's latest flagship smartphones, the S26, S26 Plus, and S26 Ultra, are absent from this list, which is a silver lining of sorts. Of course, those devices are relatively new, and already exist within the company's priciest tier—though you can find deals and discounts already if you are willing to wait. Samsung Galaxy S26 (256GB) $799.99 at Amazon $899.99 Save $100.00 Get Deal Get Deal $799.99 at Amazon $899.99 Save $100.00 Samsung's tablets have been hit much harder than the smartphones. Samsung is raising prices on seven different models of tablets—eight if you differentiate between the wifi and 5G version of the Galaxy Tab A11 Plus. In addition, the company is raising prices on each storage variant. The Galaxy Tab S11, for example, gets a price hike no matter whether you opt for the 128GB, 256GB, or 512GB model. Here are the increases so far: Galaxy Tab S11: from $799.99 to $899.99 (128GB) Galaxy Tab S11: from $859.99 to $999.99 (256GB) Galaxy Tab S11: from $979.99 to $1,199.99 (512GB) Galaxy Tab S11 Ultra: from $1,199.99 to $1,299.99 (256GB) Galaxy Tab S11 Ultra: from $1,319.99 to $1,499.99 (512GB) Galaxy Tab S11 Ultra: from $1,619.99 to $1,899.99 (1TB) Galaxy Tab S10 FE: from $499.99 to $549.99 (128GB) Galaxy Tab S10 FE: from $569.99 to $669.99 (256GB) Galaxy Tab S10 FE Plus: from $649.99 to $699.99 (128GB) Galaxy Tab S10 FE Plus: from $749.99 to $819.99 (256GB) Galaxy Tab S10 Lite: from $349.99 to $399.99 (128GB) Galaxy Tab S10 Lite: from $419.99 to $489.99 (256GB) Galaxy Tab S10 Plus: from $999.99 to $1,099.99 (256GB) Galaxy Tab S10 Plus: from $1,119.99 to $1,299.99 (512GB) Galaxy Tab A11 Plus: from $249.99 to $299.99 (128GB) Galaxy Tab A11 Plus: from $309.99 to $379.99 (256GB) Galaxy Tab A11 Plus 5G: from $279.99 to $329.99 Now, just because these are the new MSRPs for these devices, doesn't mean you'll necessarily pay full price. As with the Galaxy S26 line, you may find phones like the Z Flip 7 on discount from retailers like Amazon, so shop around before making a purchase. That said, these price increases may have a ripple effect across markets: Even stores offering discounts could raise prices to accommodate the new MSRPs. Rarely does a company raising prices mean that things stay the same. Even more rarely does it mean prices will go lower. View the full article
-
AI is everywhere—in emails, slide decks, and calendars. But just because it’s omnipresent in workplaces doesn’t mean employees are embracing the tech. In fact, they could be doing just the opposite. A new report by generative AI company Writer and research firm Workplace Intelligence reveals that 29% of workers surveyed across the U.S., U.K., and Europe admit to sabotaging their company’s AI strategy. The survey included 2,400 workers: 1,200 C-suite execs and 1,200 employees, ranging from individual contributors to managers/team leads. The report details many forms of resistance. In some cases, employees said they have ignored guidelines, opted out of AI training, or flat-out refused to use AI tools. In more extreme situations, some admit to having fed sensitive company information to public, unapproved AI tools and even to tampering with performance metrics to make the tech seem less effective. Among Gen Z workers surveyed, 44% admitted to having sabotaged their company’s AI rollout in some way. The report says there is “a strong undercurrent of resistance among younger workers,” which makes sense, considering young professionals have had to pivot and adapt to a tumultuous job market with limited entry-level positions. Because of this, Gen Z has had to AI-proof their careers, taking on side hustles or part-time work and even switching college majors due to AI. According to the report, the reasons for pushback range from fear of job loss to dissatisfaction with their company’s AI tools or strategies to frustration from feeling that the tech has diminished their value and creativity. Real-world stats prove those fears and frustrations are not without merit. In March, AI accounted for 25% of job cuts across the U.S. Additionally, a new report from Goldman Sachs shows that workers who are hit by AI-fueled job loss also take longer to find a new job. The Writer-Workplace Intelligence survey reveals a significant disconnect between how employees and executives view the importance of AI literacy at work. While 24% of employees said they fear being laid off if they don’t become expert AI users, a majority (60%) of C-suite executives confirmed that they plan to lay off employees who can’t—or won’t—use AI. View the full article
-
In a rapidly evolving technological landscape, Google’s latest offering, Gemma 4, is making waves that small business owners should pay attention to. These new AI models promise to enhance efficiency and performance while remaining accessible across various devices. With their multimodal capabilities and innovative features, Gemma 4 might just be the tool that businesses need to streamline operations and foster growth. The Gemma 4 models, specifically designed to operate efficiently on a range of hardware, can run smoothly on everything from billions of Android devices to high-end developer workstations. This flexibility is critical for small businesses, which often face budget constraints and limited access to cutting-edge technology. One of the standout features of Gemma 4 is its advanced reasoning capability. This allows the model to execute multi-step planning and handle complex tasks, significantly enhancing operations in areas like customer service, data analysis, and financial forecasting. For instance, a small retailer could utilize this feature to improve inventory management by predicting sales trends, thus avoiding stock shortages or excess inventory. In addition to reasoning, Gemma 4 supports “agentic workflows” that enable the creation of autonomous agents. These agents can interact with various tools and APIs, automating many routine tasks that small business owners often juggle. As such, a restaurant might implement an autonomous agent to manage online bookings, sending confirmations and reminders, freeing up staff to focus on customer service. The models also support high-quality code generation, which can turn personal workstations into local AI code assistants. This functionality can be invaluable for small tech startups or businesses developing applications, as it allows developers to retrieve or generate code swiftly, thereby speeding up project timelines. Another practical application is the processing of visual and audio content. The new models excel at tasks such as optical character recognition (OCR) and chart understanding, which can simplify data extraction from documents and presentations, a valuable capability for reporting and analytics tasks. Furthermore, the native audio input feature for speech recognition opens doors for businesses engaged in customer interactions, enhancing voice-based applications or automating transcriptions. For small businesses operating in a global market, Gemma 4’s capability to process over 140 languages is a game-changer. This feature not only allows for the development of high-performance applications tailored to diverse customer bases but also positions small businesses as competitive players internationally. However, potential challenges accompany these innovations. Small business owners must consider the technical demands of implementing such advanced AI models. Understanding how to fine-tune models for specific use cases may require a learning curve. While Google provides resources to support this process, business owners must allocate time and possibly finances towards training their teams. Moreover, the release of Gemma 4 under an open-source Apache 2.0 license is a boon for many small businesses, providing them with flexibility and digital sovereignty. They gain control over their data and infrastructure, freeing them from restrictive frameworks. However, this autonomy comes with the responsibility to maintain systems and integrations effectively. Google’s focus on making these models versatile for different hardware is crucial. The 26B and 31B models are optimized to run on consumer GPUs, making them attainable for small businesses equipped with standard development setups. Additionally, the newer E2B and E4B models are engineered specifically for mobile and IoT devices, driving down RAM and battery consumption while ensuring near-zero latency. As many small businesses strive to find their footing in 2023, the introduction of Google’s Gemma 4 presents a compelling opportunity. It possesses the potential to transform operations, boost productivity, and ultimately drive business growth. Small business owners looking to leverage AI should think critically about how Gemma 4 can align with their unique needs. Whether optimizing workflows or enhancing customer engagement, the possibilities are considerable. Given that these models focus on practicality and integration rather than just raw performance, small businesses have much to gain by considering this advanced technology as part of their operational toolkit. To explore more about Google’s innovative Gemma 4 models and their potential applications, visit the original press release at Google Blog. Image via Google Gemini This article, "Google Unveils Gemma 4: Advanced AI Models for Every Device and Use Case" was first published on Small Business Trends View the full article