Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
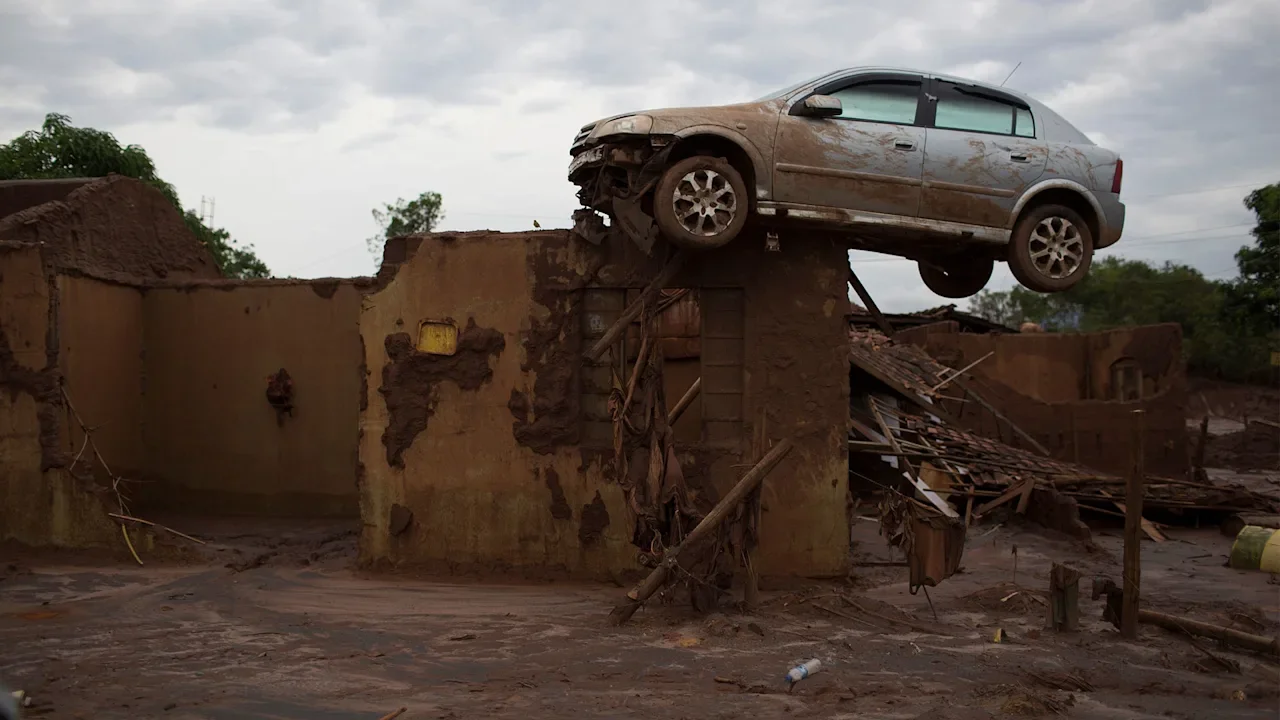
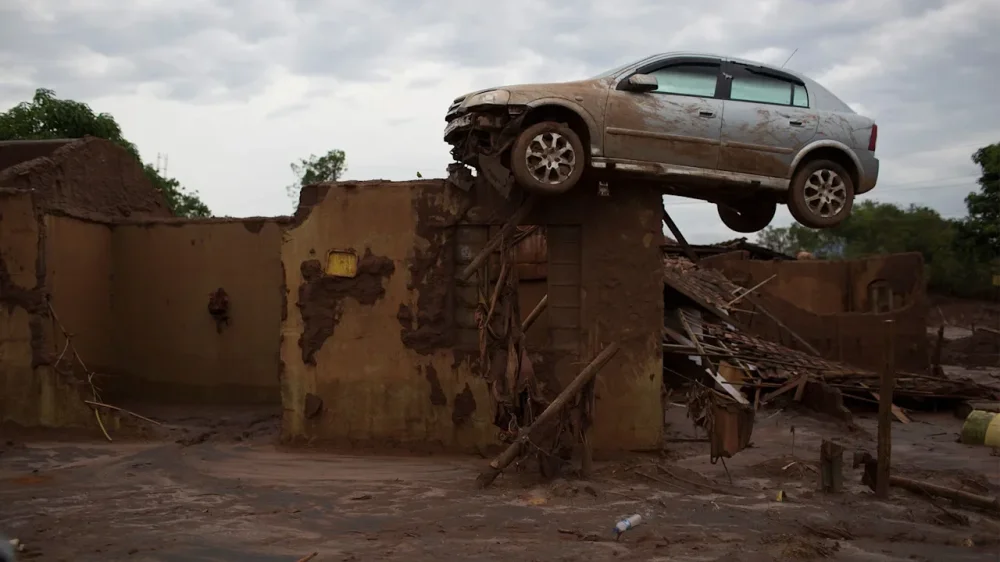
A London judge ruled Friday that global mining company BHP Group is liable in Brazil’s worst environmental disaster when a dam collapse a decade ago unleashed tons of toxic waste into a major river, killing 19 people and devastating villages downstream. High Court Justice Finola O’Farrell said that Australia-based BHP was responsible, despite not owning the dam at the time, finding its negligence, carelessness or lack of skill led to the collapse. Anglo-Australian BHP owns 50% of Samarco, the Brazilian company that operates the iron ore mine where the tailings dam ruptured on Nov. 5, 2015. Sludge from the burst dam destroyed the once-bustling village of Bento Rodrigues in Minas Gerais state and badly damaged other towns. Enough mine waste to fill 13,000 Olympic-size swimming pools poured into the Doce River in southeastern Brazil, damaging 600 kilometers (370 miles) of the waterway and killing 14 tons of freshwater fish, according to a study by the University of Ulster in the U.K. The river, which the Krenak Indigenous people revere as a deity, has yet to recover. A decade later, legal disputes have prolonged reconstruction and reparations and the river is still contaminated with heavy metals. Even as Brazil tries to define itself as a global environmental leader while hosting the U.N. COP30 climate summit, advocacy groups say the dam collapse is a reminder of industry-friendly policies that have ecological protection. Victims of the disaster called the ruling a historic victory in seeking justice. “We had to cross the Atlantic Ocean and go to England to finally see a mining company held to account,” said Mônica dos Santos of the Commission for Those Affected by the Fundão Dam. Gelvana Rodrigues, whose 7-year-old son, Thiago, was killed in a mudslide, celebrated the step forward and said she wouldn’t rest until those responsible are punished. “The judge’s decision shows what we have been saying for the last 10 years: it was not an accident, and BHP must take responsibility for its actions,” Rodrigues said. The judge agreed with lawyers representing 600,000 Brazilians and 31 communities in the class-action case who argued that BHP was heavily involved in the Samarco operation and could have prevented the disaster, but instead encouraged raising the dam to allow more production. “The risk of collapse of the dam was foreseeable,” O’Farrell wrote in the 222-page decision. “It is inconceivable that a decision would have been taken to continue raising the height of the dam in those circumstances and the collapse could have been averted.” BHP said that it plans to appeal. The claimants are seeking 36 billion pounds ($47 billion) in compensation, though the ruling only addressed liability. A second phase of the trial will determine damages. The case was filed in Britain because one of BHP’s two main legal entities was based in London at the time. The trial began in October 2024, just days before the federal government in the South American country reached a multibillion-dollar settlement with the mining companies. Under the agreement, Samarco — which is also half owned by Brazilian mining giant Vale — agreed to pay 132 billion reais ($23 billion) over 20 years. The payments were meant to compensate for human, environmental and infrastructure damage. BHP had said the U.K. legal action was unnecessary, because it duplicated matters covered by legal proceedings in Brazil. The judge ruled that those who were compensated in the settlement in Brazil could still bring claims, though they might be limited by any waivers they signed. Brandon Craig, BHP’s president of Minerals Americas, said that nearly half of the claimants could be eliminated from the group because of settlement agreements they signed in Brazil. BHP shares fell more than 2% on the London market after the ruling and the company said that it would update its financial provisions. —Brian Melley, Associated Press View the full article
-
When considering opening a franchise, it’s vital to comprehend the financial commitments involved. Initial investments typically range from $100,000 to $300,000, depending on factors like brand and location. You’ll encounter franchise fees, which can vary from $10,000 to $50,000, along with ongoing royalty fees that often take 3% to 6% of your gross sales. Grasping these costs is fundamental, but there are other factors at play that could influence your startup expenses. Key Takeaways The initial investment for a franchise typically ranges from $100,000 to $300,000 depending on the brand and location. Franchise fees generally vary between $10,000 and $50,000 based on market competitiveness and brand reputation. Common startup expenses include real estate, equipment, office supplies, and leasehold improvements. Ongoing fees, such as royalty fees, usually range from 3% to 6% of monthly gross sales. The Franchise Disclosure Document (FDD) provides detailed breakdowns of initial and ongoing costs, crucial for financial planning. General Franchise Opening Costs When you’re considering opening a franchise, it’s vital to understand that the initial investment typically ranges from $100,000 to $300,000, depending on the brand and the specific industry requirements. One significant component of this cost is the franchise fees for restaurants, which can vary widely based on market competitiveness and brand reputation. Furthermore, you’ll need to account for common startup expenses like office supplies, equipment, and leasehold improvements. If you’re looking into fast food franchise cost, keep in mind that real estate expenses, permits, and working capital for operational expenses are also fundamental. To get a clearer picture of how much it costs to open a franchise, refer to the Franchise Disclosure Document (FDD), which outlines all these investment details. Typical Parts of a Business Plan A detailed business plan is crucial for anyone looking to open a franchise, as it serves as a roadmap for your venture. Start with an executive summary outlining your business concept, objectives, and unique value proposition. Next, include a company description detailing the franchise’s history, structure, and operational model. Don’t forget to conduct a thorough market analysis, covering target demographics, market needs, and competition. This helps you understand franchise cost comparisons and restaurant franchise prices. The management structure section should define your leadership team and their experience. Finally, provide financial projections, detailing your revenue, expenses, and profitability forecasts, often referencing the Franchise Disclosure Document (FDD) for accuracy. This foundation will guide you on how do you buy a franchise restaurant successfully. Initial Investment Breakdown When you’re considering opening a franchise, comprehending the initial investment is essential. You’ll encounter various costs, including the franchise fee, which grants you the right to operate under the brand, and startup expenses like real estate and equipment. Furthermore, it’s important to factor in ongoing financial obligations that can impact your long-term profitability. Franchise Fee Overview Franchise fees represent a significant initial investment for anyone looking to enter the franchise world, as they typically range from $10,000 to $50,000. These fees grant you the right to operate under the franchisor’s brand and are just the starting point. For instance, if you’re considering how to open a fast food franchise, comprehending the Jack in the Box franchise cost or jack’s franchise cost can help you gauge the overall financial commitment. Although the franchise fee is important, keep in mind that the total initial investment often falls between $100,000 and $300,000, depending on factors like location and specific franchise requirements. Consulting the Franchise Disclosure Document (FDD) is fundamental for grasping all associated costs, including ongoing royalty fees that can impact your finances. Startup Cost Components Starting a franchise involves several key components that contribute to your initial investment. Typically, this investment ranges from $100,000 to $300,000, depending on the brand and location. Common startup costs include franchise fees, which grant you the right to operate under the franchisor’s brand, real estate expenses, equipment purchases, office supplies, and leasehold improvements. Franchise fees can vary considerably and are usually non-negotiable. The Franchise Disclosure Document (FDD) is crucial for reviewing detailed investment costs, including initial purchase funds and working capital needs. Furthermore, you should account for professional services related to permits, insurance requirements, and working capital to cover operating costs for several months as you launch your franchise successfully. Ongoing Financial Obligations Comprehending the ongoing financial obligations of a franchise is vital for maintaining its success beyond the initial investment phase. After the startup costs, you’ll need to evaluate ongoing expenses like royalty fees, which typically range from 4% to 8% of your sales. These fees grant you the right to use the franchisor’s brand and support services. Moreover, you’ll face costs for marketing contributions, which help promote the brand. It’s important to maintain adequate working capital to cover operational expenses and personal living costs during the early months. The Franchise Disclosure Document (FDD) will provide detailed insights into both initial and ongoing financial commitments, ensuring you’re well-prepared for the expedition ahead. Common Franchise Fees When considering the costs associated with opening a franchise, it’s essential to understand the various fees involved. The initial franchise fee, often reflecting the brand’s reputation, typically ranges from $10,000 to $50,000 or more, and these fees are usually non-negotiable. Furthermore, many franchisors require contributions to marketing, which can be a percentage of sales or a fixed amount, aimed at supporting national or regional advertising efforts. As some franchisors may offer incentives like deferred fees or discounts to attract franchisees, these options vary widely. It’s important to review all fee structures in the franchise disclosure document to guarantee you’re fully aware of the financial commitments before making your investment decision. Ongoing Royalty Fees Ongoing royalty fees are a vital aspect of franchise ownership that can greatly impact your bottom line. Typically, these fees range from 3% to 6% of your monthly gross sales, but some franchises, like Complete Weddings + Events, charge up to 8% of annual gross revenue. Others, such as Motto Mortgage, require a flat fee of $4,500 per month after the first year. Dream Vacations offers a variable rate from 1.5% to 3% of annual commissionable sales, showcasing significant differences among franchises. Help-U-Sell Real Estate mandates a 6% fee on gross commissions, whereas United Country Real Estate charges between $1,200 and $2,400 monthly, depending on performance. Comprehending these fees is essential for evaluating your franchise’s profitability. Financing Options for Franchise Startups How can you effectively finance your franchise startup? Comprehending your options is vital to guarantee you secure the necessary funds. Here are three viable financing methods: Small Business Administration (SBA) Loans: Although the SBA doesn’t lend money directly, it guarantees loans, making it easier for you to access funds through banks. Franchisor Financing: Many franchisors offer financing assistance or partner with lenders, which can simplify your funding process. Alternative Financing: Consider personal savings, crowdfunding, or loans from family and friends, assuring you have written agreements to protect all parties involved. Additionally, online marketplaces like Boefly and Biz2Credit can connect you with lenders, whereas FranFund can help streamline your funding efforts. Each option has its benefits, so explore what suits you best. Understanding the Franchise Disclosure Document (FDD) What do you need to know about the Franchise Disclosure Document (FDD) before investing in a franchise? The FDD is vital, as it outlines fundamental information about the franchise, including initial investment costs, ongoing fees, and working capital requirements. Particularly, Item 7 details the specific funds needed to start and run the franchise, helping you estimate your total investment. Here’s a summary of key FDD components: FDD Component Description Importance Initial Costs Upfront investment needed Determines your financial entry Ongoing Fees Royalty and other fees Affects long-term profitability Financial Stability Franchisor’s financial history Assesses investment viability Litigation History Past legal issues Identifies potential risks Franchise Obligations Responsibilities of both parties Clarifies your commitments Factors Influencing Franchise Startup Costs When choosing a franchise, the brand you select and its market presence can greatly impact your startup costs. Factors like location, local demand, and competition play essential roles in determining how much you’ll need to invest. Comprehending these elements will help you make informed decisions and better prepare for the financial commitment ahead. Franchise Brand Selection Selecting the right franchise brand can greatly impact your startup costs and overall success. When evaluating potential franchises, consider these key factors: Initial Investment: Costs can range from under $15,000 for low-cost franchises to millions for established brands like Taco Bell or KFC. Franchise Disclosure Document (FDD): This vital document outlines financial obligations, including franchise fees and ongoing royalty fees, ensuring you understand your investment commitments. Franchisee Support: Evaluate the training and marketing assistance offered by the franchisor, as this can markedly affect your overall startup costs and operational expenses. Location and Market Factors Choosing the right franchise brand is just the beginning; your location and the surrounding market factors play a significant role in determining your startup costs. The demographics and market demand in your chosen area directly influence your potential customer base and sales projections. Real estate costs, including lease rates and property availability, can greatly impact your initial investment. Conducting a competitive analysis in the target market allows you to identify gaps and opportunities that could guide your decisions. The Franchise Disclosure Document (FDD) outlines financial obligations that may vary based on local economic conditions. Furthermore, local regulations and necessary permits can add to your overall startup costs, making thorough research vital before launching your franchise. Frequently Asked Questions Why Does It Only Cost $10k to Own a Chick-Fil-A Franchise? Chick-fil-A‘s low $10,000 franchise fee stems from the company’s unique business model. They cover most startup costs like real estate and equipment, allowing you to focus on running the business. Nonetheless, this opportunity isn’t passive; you’ll need to be hands-on, dedicating significant time and effort to meet operational standards. The competitive selection process seeks franchisees with strong entrepreneurial spirits and community commitment, ensuring the brand’s legacy is upheld. Can I Buy a Franchise With No Money? Buying a franchise with no money is challenging, but not impossible. Some low-cost franchises, like Dream Vacations, require minimal initial investments. You can explore financing options such as SBA loans or franchisor programs, which may offer payment plans or deferred fees. Furthermore, consider using personal savings, crowdfunding, or loans from family and friends, ensuring you document agreements. A solid business plan and good credit score are crucial for securing these financing options. What Is the Cheapest Franchise to Own? If you’re looking for the cheapest franchise to own, Dream Vacations is a strong contender, with a start-up cost of about $9,800. Image One follows closely, offering janitorial services for around $15,000. Other affordable options include Complete Weddings + Events and Showhomes Home Staging, both requiring $10,000. TSS Photography additionally stands out, needing $10,500. Each of these franchises provides a low entry point, making entrepreneurship more accessible for you. What Is the 7 Day Rule for Franchise? The 7 Day Rule for franchises requires you to receive the Franchise Disclosure Document (FDD) at least 14 days before signing any franchise agreement or making payments. This rule gives you the time to review essential information about fees, obligations, and financial performance. It’s designed to help you conduct thorough due diligence and seek advice before committing to a franchise investment, ensuring you make informed decisions in line with FTC regulations. Conclusion In conclusion, opening a franchise involves various costs, including initial investments, franchise fees, and ongoing royalty payments. Comprehending these financial obligations is essential for making informed decisions. By carefully reviewing the Franchise Disclosure Document and considering financing options, you can better prepare for the challenges ahead. In the end, thorough research and planning will help you navigate the intricacies of franchise ownership, ensuring you’re equipped to succeed in your venture during the management of your finances effectively. Image via Google Gemini This article, "How Much Does It Cost to Open a Franchise?" was first published on Small Business Trends View the full article
-
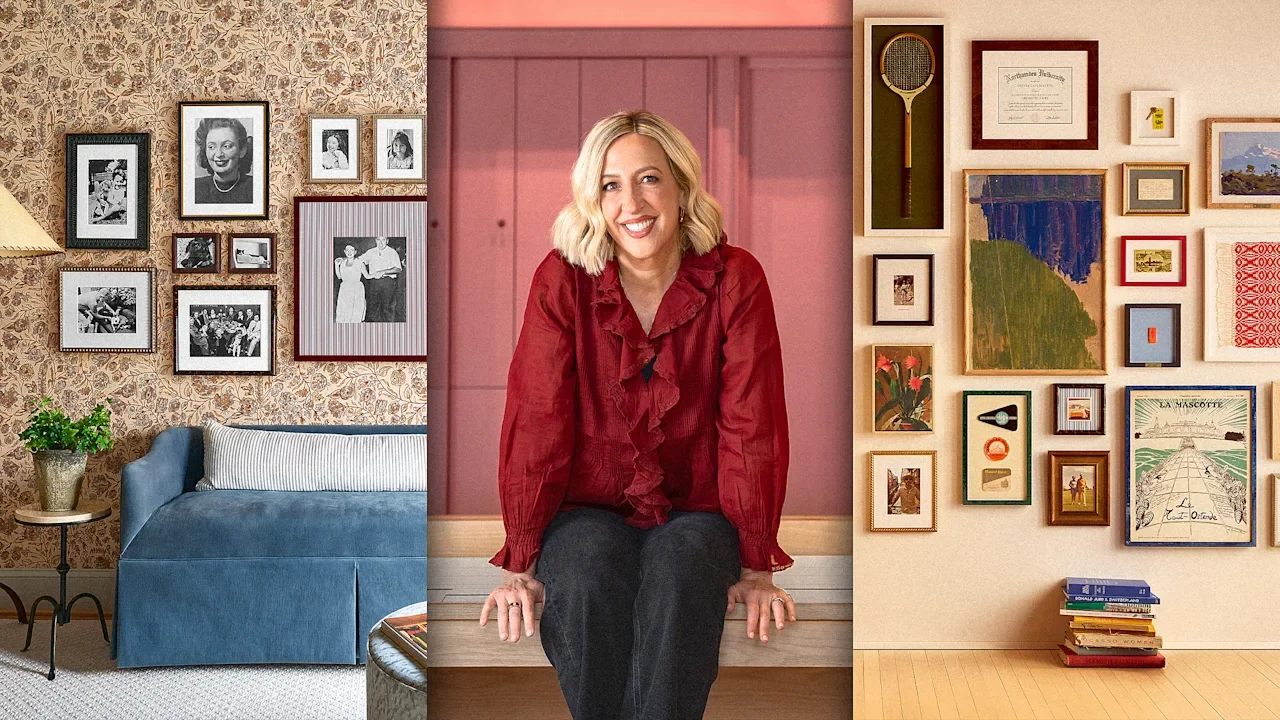
In the late 2010s, at the height of the direct-to-consumer boom, Framebridge founder Susan Tynan was green with envy. Many other venture-backed startups from the era—like Casper, Away, and Glossier—were growing much faster than her custom framing business. While these other buzzy brands focused on acquiring customers and growing revenue, Tynan was using her $81 million in venture funding to tackle more arduous operational issues, like building factories and hiring hundreds of craftspeople to make frames by hand. Eleven years into the business, Tynan’s slow, steady approach to growth is paying off. Framebridge now has 750 employees, 500 of whom work at the company’s four factories in Kentucky, Virginia, and Nevada. Meanwhile, its brick-and-mortar footprint is growing rapidly, with 10 new stores opening last year (it now operates 40 physical stores) and more planned. Tynan says that by investing in Framebridge’s infrastructure early on, she built a moat around the business that has allowed it to ward off competitors. And now the company is in a position to scale rapidly, actively looking to expand its network of brick-and-mortar locations, possibly into the hundreds. Meanwhile, many DTC startups that Tynan once envied are fending off challengers that have created similar products, from mattresses-in-a-box to design-forward luggage. “Framebridge was a hard business to build, but that’s why it’s impossible to replicate,” says Tynan. “We’re now reaping the benefits.” The DTC Boom and Bust Today you’ll find a custom framing shop in most towns: By one estimate, there are more than 15,000 in the United States. But custom framing is notoriously expensive and takes a long time, which turns off many consumers who are happy to settle for a cheaper prefabricated frame they can buy from Michaels or Amazon. As Tynan studied the framing business model, she found the industry laden with inefficiencies. Most frame shops are owned by a single person. Since the store can’t afford to keep hundreds of mats and frame options in stock, it will order the components only once the customer has made their selection. Buying in such small quantities is expensive; it’s also time-consuming to send out for these pieces and construct the frame in-store. Tynan, who started her career as a tech executive, decided to launch Framebridge because she believed she could make framing cheaper, faster, and more convenient. Like many other VC-backed DTC startups, Framebridge was meant to disrupt a dusty industry. But Tynan’s business model was far more complex than those of peer brands of the 2010s. Startups like Casper and Away, which redesigned common consumer products, worked with overseas factories to make them, then sold the products online. Framebridge, by comparison, needed to build out a complex logistical operation to create custom frames at scale. This would involve setting up factories in the States and hiring artisans to build custom frames. In 2020, Graham Holdings Co. (GHC) acquired Framebridge for an undisclosed amount, giving Framebridge’s investors a payout. The sale meant that Framebridge had a deep-pocketed holding company that would allow Tynan to keep investing in factories and other infrastructure at a time when many other DTC operations were seeking out ever-larger sums of VC capital or exploring an IPO. Taryn Jones Laeben, who served as the chief commercial officer of Casper until 2018 before founding the VC firm IRL Ventures, believes Framebridge owes its success largely to one unique factor. “What makes Framebridge special is its supply chain,” she says. “Businesses that survived the DTC era are the ones that are truly differentiated. But investing in factories is complex because it is capital intensive and prevents you from being nimble. For Framebridge, it has clearly paid off.” While GHC, which generated $4.7 billion last year, does not break out revenue for individual companies, its annual report noted that “Framebridge posted real growth in 2024.” That said, the report described Framebridge as an “investment stage business” that is not profitable yet. The upshot is that it’s much harder to copy Framebridge’s business. Over the past five years, many DTC brands have struggled to acquire new customers, partly because a wave of competitors have popped up. Away is now competing with Monos, July, and Antler. The beauty and mattress industries have hundreds of direct-to-consumer players. To gain market share under these conditions, brands must continue pumping money into marketing and advertising. But no other companies have yet been able to replicate what Framebridge is doing. The Moat In 2014, the Framebridge website went live. It allowed customers to send in art or upload digital photographs to be framed and delivered back to them. It seemed like a simple service. But Tynan had spent the previous two years—and $3 million in seed funding—to build out a factory in Richmond, Virginia. She hired a team of expert framers as well as some people from other creative professions who enjoy the work of framing. “I found someone who sold mantles on Etsy,” she recalls. “He loves using his hands.” Framebridge orders large volumes of framing materials, which allows the company to charge less per frame than the average neighborhood framer. Small frames start at $50; larger pieces, like an 18-by-24-inch frame, cost $155. (This is roughly half of what my local frame shop in Boston charges.) Framebridge’s concept resonated with customers, especially digital-native millennials who were already ordering everything from mattresses to house plants on the internet. Within three years of launch, the company had generated $58 million in revenue. Laeben, the VC investor, says Tynan was smart about how her startup used its $81 million in VC capital. While many brands of the era were investing in customer acquisition, Framebridge was focused on infrastructure that would give it longevity. “They spent their money on durable, defensible strategies as opposed to acquiring customers on social media who might not even purchase from the company again,” she says. “Looking back, customer acquisition was basically like lighting money on fire.” Many investors would not have been satisfied with Framebridge’s pace of growth, Laeben points out. “DTC is a very broad category. There are many sectors where it makes sense to grow slowly and profitably, but this means being aligned with your investors on what your goals are,” she explains. As Framebridge grew, Tynan recognized the many benefits of having physical stores. While it’s possible to visualize frames on the company’s website, some customers simply want to see what the materials look like in person. More crucially, there are people who want to do business at a physical location where they can bring their expensive art and irreplaceable, precious keepsakes in person, rather than sending them through the mail, where they could be damaged or lost. So in 2019 Framebridge opened its first two stores in the Washington, D.C., area, and quickly began opening others in major cities such as New York and Boston. Tynan also decided to buy a fleet of trucks to transport people’s items from the stores to the factory in Virginia. This is another complex, expensive part of the business—but one that Tynan believes strengthen’s her company’s “moat,” making it even less likely that a competitor will spring up. “If [customers] were going to send in their baby blanket or an antique family photograph, they needed to know it wouldn’t get lost,” Tynan says. “It was important to customers that their things remained in our chain of custody throughout the whole process.” The Framebridge store footprint is much smaller than a traditional frame shop, since no actual framing happens on-site. The stores sometimes serve simply as a way to introduce people to the brand. Framebridge often hosts in-store events, offering free portrait sessions or photos with Santa during the holidays. While some DTC brands saw retail stores primarily as a marketing engine, Tynan thought it was crucial that Framebridge learn how to run these stores profitably. “This wasn’t a pop-up strategy,” she says. “As a startup, you want to test a lot of things, but if you test them halfway, you don’t know if they’re actually going to work. So we put our best foot forward with these stores.” The Future of Framing Today, Framebridge still doesn’t have a major competitor that does what it can do. Instead, its biggest source of competition is the traditional, neighborhood frame shop. But Tynan says her goal isn’t to put these places out of business. She points out that Framebridge has a particularly modern, millennial-oriented aesthetic that isn’t necessarily for everyone. And store associates are trained to point customers to other framing shops nearby if Framebridge doesn’t have what they’re looking for. “We have a curated assortment of frames,” Tynan says. “We have a point of view.” Still, she believes there’s a lot of room to grow. Given how expensive custom framing has been in the past, few consumers create bespoke frames for their art. Most just buy premade frames. By offering less-expensive options and offering customers the ability to make selections online, Tynan hopes that Framebridge will appeal to people who might never have thought to custom frame their keepsakes or art before. “In many ways,” she says, “we’re only just starting to scale.” View the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. While I've been thinking about the sale prices we might see on Black Friday, Garmin just went and dropped the prices on several of their watches. The Forerunner 265 and 965 are at their lowest prices ever, both $150 off. Several other watches are on surprisingly good sales as well. Garmin Forerunner 265 Running Smartwatch $299.99 at Amazon $449.99 Save $150.00 Get Deal Get Deal $299.99 at Amazon $449.99 Save $150.00 Garmin Forerunner 265S Running Smartwatch, Colorful AMOLED Display, Training Metrics and Recovery Insights, Light Pink and Powder Gray $299.99 at Amazon $449.99 Save $150.00 Get Deal Get Deal $299.99 at Amazon $449.99 Save $150.00 Garmin Forerunner® 965 Running Smartwatch, Colorful AMOLED Display, Training Metrics and Recovery Insights, Amp Yellow and Black $449.99 at Amazon $599.99 Save $150.00 Get Deal Get Deal $449.99 at Amazon $599.99 Save $150.00 SEE 0 MORE The Garmin Forerunner 265 is one of my favorite running watches, and you can read my review of it here. It's got an AMOLED screen, all kinds of advanced training metrics, dual-band GPS, and can connect to a bike power meter, to name a few of the features that set it apart from other watches. I own one myself and highly recommend it. Its original price was $449.99, but it's sometimes been on sale for $50 or $100 off. It was $100 off for last year's Black Friday, and has made occasional dips back down to that price since the Forerunner 570 came out this year. (The 570 is basically a 265 plus voice features, and it's not on sale this year—yet?) Both sizes are now on sale: the 46-millimeter 265 and the smaller version, the 42-millimeter 265S (S for "smaller"). Both are the same price at $299.99. The Forerunner 965 has the same features as the 265, plus a few extras—the biggest of which is maps. Normally $599.99, the 965 is on sale for $449.99. Amazon has these marked as a "limited time deal," but Garmin has them in their "holiday gift guide," suggesting this might be the Black Friday price showing up early. Also on sale: Garmin Forerunner 165: $199.99 ($50 off) and 165 Music: $249.99 ($50 off) Garmin Vivoactive 6: $249.99 ($50 off). See my review of the Garmin Vivoactive 6. Our Best Editor-Vetted Tech Deals Right Now Apple AirPods 4 Wireless Earbuds — $84.99 (List Price $129.00) Apple iPad 11" 128GB A16 WiFi Tablet (Blue, 2025) — $324.99 (List Price $349.00) Shark AV2501AE AI XL Hepa- Safe Self-Emptying Base Robot Vacuum — $294.99 (List Price $649.99) Apple Watch Series 10 — $279.00 (List Price $429.00) Amazon Fire HD 10 (2023) — $69.99 (List Price $139.99) Sony WH-1000XM5 — $297.98 (List Price $399.99) Blink Outdoor 4 1080p Wireless Security Camera (5-Pack) — $159.99 (List Price $399.99) Ring Floodlight Cam Wired Plus 1080p Security Camera (White) — $99.99 (List Price $179.99) Amazon Fire TV Stick 4K Plus — $24.99 (List Price $49.99) NEW Bose Quiet Comfort Ultra Wireless Noise Cancelling Headphones — $299.00 (List Price $429.00) Deals are selected by our commerce team View the full article
-
At the recent Web Summit 2025, Visa revealed exciting developments aimed at empowering digital creators—a group increasingly recognized as vital small businesses. With their new 2025 Creator Report and plans for a collaboration with Karat Financial, Visa aims to provide modern tools and resources to help creators grow both locally and globally. Small business owners should pay close attention, as Visa’s initiatives highlight a critical shift in the marketplace: creators are not merely influencers; they are entrepreneurs vying for a strong foothold in the economy. Visa’s study, conducted in partnership with Morning Consult, surveyed over 1,000 TikTok creators from regions including the U.S., Brazil, Australia, the U.K., and the U.A.E. The findings reveal not just the challenges these creators face but also their growing resilience. According to Jonathan Kolozsvary, Global Head of Small Business for Visa Commercial Solutions, “Creators are among the most dynamic small business segments in the world.” Key highlights from the report demonstrate a robust momentum among creators: Optimism: A striking 88% of the creators surveyed expect their revenue to increase within the next year, suggesting a strong confidence in their economic prospects. Funding Challenges: While creators often rely on personal funds, community support, and innovative financing models like crowdfunding, there remains a pressing need for tailored financial products designed specifically for their unique scenarios. Global Reach: More than half (52%) of the creators surveyed receive payments from outside their home countries. This underscores the need for modern payment solutions capable of handling cross-border transactions efficiently. Support Networks: A remarkable 94% of creators report encouragement from friends and family, enhancing the perception of content creation as a serious long-term career choice. The report emphasizes that many creators are actively enhancing their business skills, particularly in areas like financial management and contract negotiation. Small business owners can relate to this journey, as both groups often navigate similar hurdles in building their enterprises. Visa’s exploration of a new creator agentic pilot program with Karat Financial will focus on easing common administrative burdens faced by creators. Karat, a financial technology leader in the creator community, specializes in credit services and banking solutions tailored to these entrepreneurs. The proposed pilot program promises to include several practical tools that could benefit small business owners: Smarter Payments: Automation that simplifies the processes of sending, receiving, and tracking payments, making it easier for small businesses to manage cash flows. Automated Reminders: Features that follow up on late invoices—essential for maintaining cash flow and ensuring timely payments, which are often a struggle for small businesses. Trusted Database: A centralized system where users can store and verify their buyer and supplier details, potentially reducing the risk of fraud. However, while these developments are promising, small business owners should also remain cautious. Transitioning to new financial tools and systems might require training or adjustments in current business practices. Understanding how these tools integrate with existing operations is crucial to maximizing their benefits. Visa reiterates its commitment to supporting the creator community, which has only solidified its acknowledgment of creators as valuable small businesses. The initiatives outlined not only aim to drive growth and innovation but also address the unique challenges that creators face in today’s digital landscape. For those interested in diving deeper into the findings and implications of Visa’s 2025 Creator Report, the full report can be accessed here. In an evolving economy, the integration of creative entrepreneurship with traditional small business frameworks may redefine how these entities operate and grow, turning them into pivotal contributors to economic resilience and expansion. Image via Google Gemini This article, "Visa’s 2025 Creator Report Reveals Optimism and New Support Initiatives" was first published on Small Business Trends View the full article
-
The long roar of speculation about the Budget has already damaged market confidenceView the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. A small upgrade can make an old TV feel new again, and the Amazon Fire TV Stick HD is the kind of plug-and-play streaming device that does exactly that. It’s down to $17.99 right now (from $34.99), which price-tracking sites confirm is its lowest recorded price. Amazon Fire TV Stick HD (1080p) $17.99 at Amazon $34.99 Save $17.00 Get Deal Get Deal $17.99 at Amazon $34.99 Save $17.00 PCMag calls it “the best 1080p media hub” for folks sticking to Full HD, and that lines up with how simple it is to set up. The stick slides straight into an HDMI port, and Amazon also includes a short extender in case your TV’s ports are too tight. It runs in 1080p and supports HDR10, so shows and movies mastered for HDR look a bit richer, even on older screens. I wouldn’t expect a dramatic jump in picture quality, but scenes with a lot of contrast—the kind with bright signage or dark backgrounds—look more defined. It also supports Dolby Atmos, which helps when you pair it with a soundbar that can handle it. Using it day to day feels familiar if you’ve used any recent Fire TV interface. You get all the usual streaming services—Prime Video, Netflix, Hulu, Disney+, YouTube, Apple TV+, even Crunchyroll and Twitch. The Alexa button on the remote works like it does on other Fire devices: press, talk, let it find what you want. The remote itself feels simple enough to use, and the built-in volume rocker is helpful if your TV remote is long gone. It relies on a quad-core 1.7GHz processor, 1GB RAM, and 8GB of storage. That’s enough for the basics, but you’ll feel its limits from time to time. The interface can get choppy, especially when you jump across tabs quickly or open a large library. Reviews also point out that the stick still uses wifi 5 instead of wifi 6, which matters if your home has a lot of devices fighting for bandwidth. This is strictly a 1080p device, so if you have a 4K TV (or plan to get one), the Fire TV Stick 4K is just $7 more and offers smoother performance, better wifi, and Dolby Vision. It also doesn’t support AirPlay or Google Cast, so sending videos from an iPhone or Android phone isn’t as seamless. Still, for someone with an older TV who wants the modern streaming apps in one place, the current $18 price makes it feel like a low-risk upgrade. Our Best Editor-Vetted Tech Deals Right Now Apple AirPods 4 Wireless Earbuds — $84.99 (List Price $129.00) Apple iPad 11" 128GB A16 WiFi Tablet (Blue, 2025) — $324.99 (List Price $349.00) Shark AV2501AE AI XL Hepa- Safe Self-Emptying Base Robot Vacuum — $294.99 (List Price $649.99) Apple Watch Series 10 — $279.00 (List Price $429.00) Amazon Fire HD 10 (2023) — $69.99 (List Price $139.99) Sony WH-1000XM5 — $297.98 (List Price $399.99) Blink Outdoor 4 1080p Wireless Security Camera (5-Pack) — $159.99 (List Price $399.99) Ring Floodlight Cam Wired Plus 1080p Security Camera (White) — $99.99 (List Price $179.99) Amazon Fire TV Stick 4K Plus — $24.99 (List Price $49.99) NEW Bose Quiet Comfort Ultra Wireless Noise Cancelling Headphones — $299.00 (List Price $429.00) Deals are selected by our commerce team View the full article
-
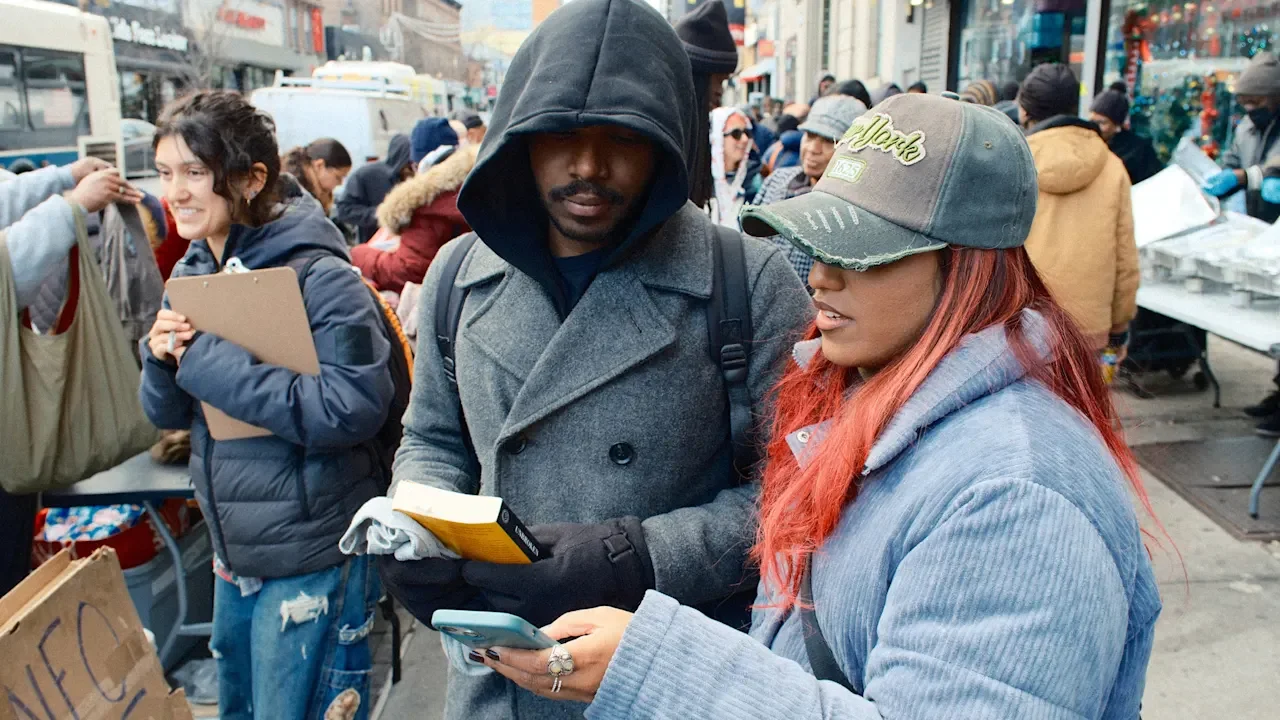
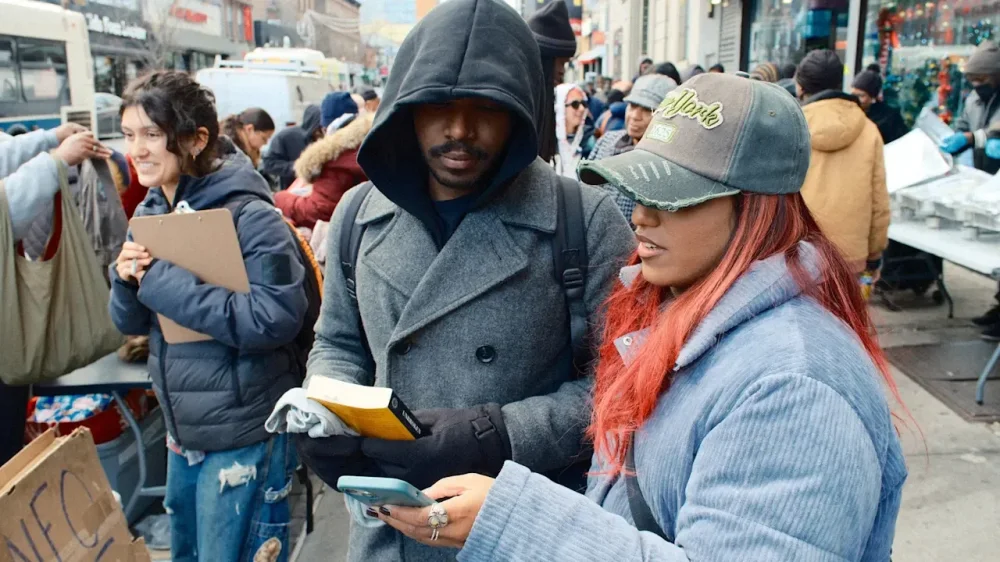
As a community organizer in New York City, Sharifa Khan spends a lot of time visiting food distribution hubs, community gardens, and local shelters. While speaking with community members, she often encounters the same issue: people want to get involved in volunteering, but they’re not sure where to start. So, Khan decided to make a tool to address that—and it couldn’t have come at a more important moment. Dora.nyc, short for Directory of Resources & Aid, is a new website dedicated to compiling New York City’s mutual aid offerings into one easy-to-understand resource. It’s designed both for those seeking aid—like food, housing, and immigration services—as well as those looking for places to offer help. The website was created through a collaboration between Khan, who runs an organization called Hope Altars; Cornell PhD student Johan Michalove, who builds digital mutual aid tools through a project called Mutua; and the NYC Resource Library, which compiles lists of local mutual aid resources. dora.nyc The website comes as the government shutdown has led to a pause in the SNAP food aid program, which provides food stamps to about one in eight Americans. This month, millions of low-income Americans have been left without the full benefits that usually help them afford basic necessities. Now that the shutdown has ended, SNAP funding is set to resume, although it’s still unclear how quickly recipients will receive their benefits. Dora.nyc offers New Yorkers a clearer picture of where aid is available—and, Khan and Michalove say, it’s a concept that they think other urban areas could replicate. AsiyahBryce Lacy How to use dora.nyc The dora.nyc page’s UI, designed by Michalove, is organized under two main categories: space and time. On the top of the site is a map of NYC’s five boroughs with markers for resources across the city. “Resources,” in this case, are defined as any kind of aid with a permanent presence in the area. These markers are color-coded by category, like distribution hub, shelter, housing, elder care, community fridge, and more. Users can navigate the map by region and click on any of the markers to learn more about the associated resource. The bottom half of the map is a calendar, organized Monday through Friday, that lists food distribution events by place and time. This part of the website includes recurring food distribution events, but can also feature one-off pop-ups or services that take place on an irregular schedule. dora.nyc Like the map, the calendar section is color-coded by region, and users can filter it by their local borough. Michalove also added an AI-powered search feature that lets users enter queries in plain language, like, “Where is there food near me” or “Where can I find a shelter in Brooklyn,” to easily find resources that match their needs. Anyone who would like to add a new resource or food distribution time to the website can do so via a set of forms in the top right of the site, which are individually vetted by Khan. “When you’re already stressed about needing access to food, and there’s the added stress of figuring out where to go, this can alleviate that one factor,” Khan says. “That is actually something someone mentioned to me directly. They said, ‘When I was struggling to find distro sites, I wish this tool existed.’” Dora.nyc’s premise may seem simple, but the website’s genius is its ability to condense information that’s historically been shared more disparately. Bryce Lacy Why dora.nyc’s premise makes so much sense Khan and Michalove have been working on dora.nyc since the summer, but sped up their development process when they heard the news of the SNAP shutdown. The idea initially came when Khan realized that information about food distribution and other mutual aid events was primarily being shared through social media posts or WhatsApp group chats—spaces that some community members, especially older folks, might not have access to. “I think a lot of times, we assume that everyone has the autonomy to put those pieces together,” Khan says. “That really does neglect a ton of factors that people are facing on a personal basis, like socioeconomic factors that are impacting their capability to go out there and find places to volunteer, for example.” Khan and Michalove pooled both her experience in community organizing and an existing list of resources from NYC Resource Library to build dora.nyc’s foundational database. Eventually, Khan says, she hopes to use dora.nyc to help different shelters across the city share resources among themselves—like, for example, if one food distribution site ends up with extra food items, those might more easily be sent to another site in need. Bryce Lacy So far, Khan has already heard from one site that a visitor found them through the dora.nyc map. She’s also helped several older community members, who may not have access to social media sites like Instagram, to add dora.nyc to their bookmarked websites. “I’ve shown aunties, specifically my Caribbean aunties, how to use it, and you can see the delight on their faces,” Khan says. Michalove and Khan agree that the model could be replicated in other cities, if local community organizers can establish an adequate vetting process for proposed sites. “When you make the goodwill visible, it gives people a direction toward how they can organize and help, because they see, ‘Oh, there are so many community fridges, maybe I could add one to my neighborhood or do a distro where I’m located.’ It gives people more of a focus toward how they can contribute.” View the full article
-
The President’s trade representative Jamieson Greer says tariffs will be reduced to 15%, ending months-long dispute with BernView the full article
-
There’s a new sheriff in Bentonville. Today, Walmart announced that John Furner will become the company’s new CEO and president, effective February 1 next year, succeeding longtime boss Doug McMillon, who is retiring. McMillon has been at the helm of the retail giant since 2014. Prior to becoming CEO, he led Walmart’s international division for four years, after leading Sam’s Club, a Walmart subsidiary, between 2005 and 2009. “Serving as Walmart’s CEO has been a great honor and I’m thankful to our Board and the Walton family for the opportunity,” McMillon said in a statement Friday. Why is McMillon retiring? “This is the right time to retire because the company’s in such great shape, and John is more than ready to lead this company through another set of transformations,” McMillon said in a separate video message, filmed alongside Furner. Walmart’s team also tells Fast Company that previous CEO transitions have followed a similar pattern. Specifically, they were announced in November and followed a sequence: a successor was named, the transitions started at the end of the year, and the outgoing CEO remained on the board for a period of time in an advisory capacity. McMillon said he believes the company will be in good hands when Furner takes the reins. “I’ve worked with John for more than 20 years. His love for our associates and this company runs deep,” McMillon said. “He’s uniquely capable of leading the company through this next AI-driven transformation. He’s a merchant, an operator, an innovator, and a builder. I know that our future is bright with his leadership.” A tenure marked by growth and technological change Walmart has made notable strides under McMillon’s tenure, including investments in the company’s workforce by increasing wages and expanding employee programs, and more recently, embracing AI by partnering with OpenAI to allow new ways for customers to shop and interact with the brand. It also went under a small but ambitious rebrand this year, the first in decades. Furner is currently the president and CEO of Walmart U.S., a role he’s held since 2019, and is responsible for 1.5 million employees and roughly 4,600 stores. He started at Walmart as an hourly associate in 1993, working his way up the corporate ladder. “As we enter a new retail era fueled by innovation and AI, our purpose and our people will continue to guide us,” Furner said in a statement. Walmart’s stock fell around 3% during premarket trading on Friday after the news was released. Year-to-date, shares are up around 14%, and they’re up 104% over the past five years. Walmart will is expected to release its latest earnings numbers on November 20. View the full article
-
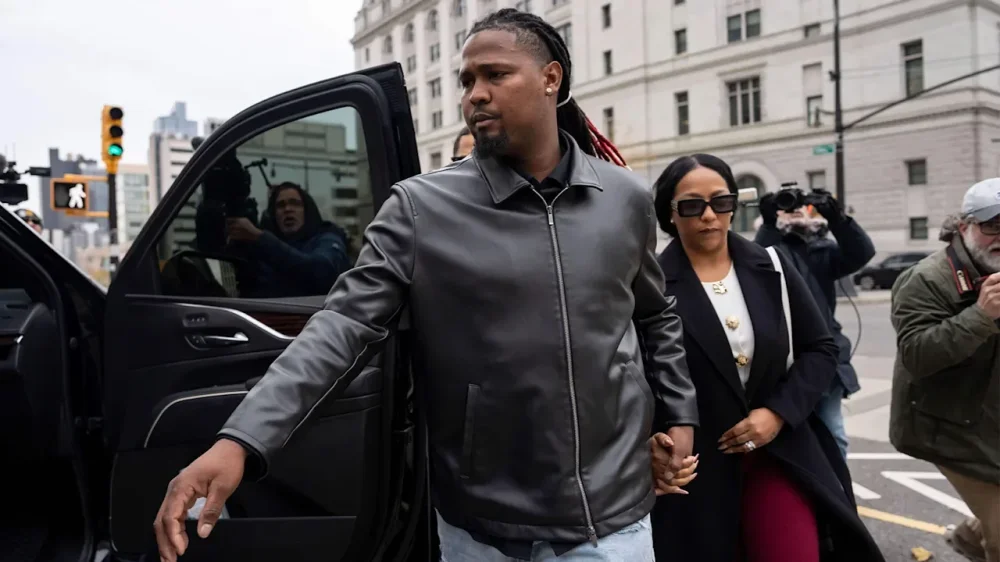
Baseball and bets go hand-in-hand in the Dominican Republic, where professional athletes, musicians and even legislators go public with their wagers. But for every legal bet in the Caribbean country, officials say there are countless more illegal ones. It’s a widespread, multimillion-dollar industry that has come under scrutiny following U.S. federal indictments of Cleveland Guardians pitchers Emmanuel Clase and Luis Ortiz. They are accused of taking bribes from unnamed sports bettors in the Dominican Republic to throw certain pitches and help those bettors win at least $460,000, according to an indictment unsealed Sunday in New York. Ortiz and Clase have both pleaded not guilty. The accusations have dismayed and embarrassed many in the players’ native country. “The case of Emmanuel Clase and Luis Ortiz tarnishes the image of Dominican baseball players,” said José de los Santos, a fan of Dominican and Major League Baseball. “Actions of that nature put Dominican and Latino players in the spotlight.” The DR has 3,500 registered betting shops, and those are just the legal ones Sports betting shops are widespread in the Dominican Republic, a country of more than 11 million people where baseball is king. According to data from the Dominican Association of Sports Betting Shops, there are about 3,500 registered businesses, and countless more illegal ones. Quico Tabar, head of the country’s national lottery who was tasked by the president to regulate gambling, recently stated in a public letter that officials have been working for years to regulate betting shops but that “circumstances beyond our control” have not allowed that to happen. He did not elaborate. For Raymond Jiménez, a self-described frequent sports gambler, it’s all the same. He said he chooses the biggest and closest businesses that allow big wagers, regardless of whether they’re legal or not. “I don’t know of any illegal betting shops,” he said. Jiménez said most bets in the Dominican Republic focus on sports including MLB, NBA and NFL games. “I’ve been gambling since 1998, when I was underage,” Jiménez said. “I used to jump the school fence to go into a betting shop at 14 years old. I’ve heard everything, from athletes who sell themselves to gamblers to others who bet against them.” Gambling persists amid corruption Legislators in the Dominican Republic are debating a bill that would create a new entity to regulate and oversee gambling and establish penalties for non-compliance. Meanwhile, chatter about the Clase and Ortiz cases continues to dominate the news and social media, as does the case of Oscar Chalas, the Dominican Republic’s former director of casinos and gambling. He reached a plea deal with prosecutors in late October and admitted responsibility in collecting money from illegal betting shops to allow them to keep operating. Chalas told a judge that each illegal shop paid up to $100 a month, but that he didn’t remember the total amount collected because there were “so many” of them. He also claimed that a former treasury minister knew and approved of the scheme, according to local media reports. The pace of legal and illegal gambling is only expected to surge as local teams and fans prepare for the Dominican Republic’s Professional Baseball League final early next year. One of the country’s most famous public bets involving the local league took place earlier this year. Hall of Famer and former Red Sox star David Ortiz offered fans a 1 million peso ($16,000) wager on social media in favor of the team that went on to win the championship — he ended up with 15 million pesos ($240,000) on the line. That included a 2 million peso ($32,000) bet with Dominican urban singer Bulin 47, but Ortiz forgave him after winning: “You’re good to those who are poor,” he wrote. AP MLB: https://apnews.com/hub/MLB —Martín Adames, Associated Press View the full article
-
Excelling in fundamental sales negotiation skills is critical for your success in a competitive market. Comprehending how to listen actively and leverage data can greatly improve your communication with buyers. By focusing on key performance indicators, you can refine your tactics and measure your outcomes effectively. Preparing for negotiations and anticipating objections likewise play important roles. These strategies not only assist in closing deals but likewise nurture lasting relationships. What other skills could boost your negotiation game? Key Takeaways Master active listening to understand client needs and build rapport for lasting relationships. Utilize data-driven negotiation techniques to tailor strategies and enhance credibility. Analyze historical sales data to identify buyer behavior patterns and refine tactics. Establish clear negotiation goals and prepare alternative offers to encourage collaboration. Leverage key performance indicators (KPIs) to measure success and focus discussions effectively. Understanding Sales Negotiation Sales negotiation is a fundamental process where buyers and sellers engage in discussions to reach a mutually beneficial agreement. Comprehending sales negotiation involves recognizing that it’s not merely about closing deals but in addition addressing the emotional and financial concerns of the buyer. You’ll need strong negotiation skills for salespeople, including clear communication to prevent misunderstandings and align expectations. Effective negotiation cultivates trust and rapport, indispensable for long-term relationships. Additionally, mastering advanced negotiation for institutional sales can improve your ability to navigate complex interactions. It’s critical to engage in back-and-forth dialogue, addressing concerns and compromises, as this collaborative approach leads to satisfactory outcomes for both parties involved. Importance of Negotiation in Sales Negotiation plays a pivotal role in the sales process, as it helps create agreements that are beneficial to both parties involved. By mastering effective sales negotiation skills, you can cultivate trust and improve long-term relationships with buyers. This process allows you to align your offerings with the buyer’s strategic objectives, clearly communicating the value of your solution. Successful negotiations lead to higher average deal sizes and improved customer satisfaction during reducing discounting, ultimately preserving your profit margins. Furthermore, a well-executed negotiation process boosts your brand reputation by preventing misunderstandings and frustrations. Companies that prioritize negotiation training for their sales teams often see better revenue forecasting and higher closure rates, making negotiation a crucial aspect of successful sales strategies. Essential Sales Negotiation Skills To master fundamental sales negotiation skills, you need to focus on two key areas: preparation and active listening. Preparation involves thoroughly researching your product, comprehending customer needs, and being aware of market dynamics so you can tailor your approach effectively. Meanwhile, active listening techniques allow you to pick up on underlying concerns and objections, enabling you to respond appropriately and cultivate a more productive dialogue. Preparation and Research Preparation and research are foundational elements in achieving successful outcomes in negotiations. By thoroughly comprehending the buyer’s business model and industry pressures, you can identify their needs and expectations, which improves your negotiation strategy. Analyzing past purchasing behavior and any existing relationships with competitors can provide valuable insights that inform your approach. Before negotiations, set clear goals and define acceptable alternatives to maintain focus. Gathering data on market trends and pricing fortifies your position, allowing you to anchor discussions with informed benchmarks. Furthermore, preparing for potential objections by mapping out responses helps you address concerns confidently and maintain momentum. This groundwork guarantees you enter negotiations well-equipped, facilitating a more effective and productive dialogue. Active Listening Techniques Entering negotiations well-prepared sets the stage for productive conversations, but the effectiveness of those discussions greatly depends on your ability to listen actively. Active listening involves fully concentrating on the speaker, which nurtures trust and rapport. Techniques like paraphrasing and summarizing clarify points and show you value their input. Active Listening Techniques Benefits Paraphrasing Clarifies comprehension Summarizing Reinforces key points Non-verbal cues Shows engagement Open-ended questions Uncovers deeper insights Effective Sales Negotiation Strategies When you’re preparing for a sales negotiation, thorough research is key to comprehending both your product and the buyer’s needs. Active listening techniques can greatly improve your ability to address concerns and objections, ensuring that you fully grasp the buyer’s perspective. Preparation and Research Thorough research lays the groundwork for effective sales negotiations, as it equips you with crucial insights into the buyer’s business model, industry challenges, and specific needs. This preparation enables you to formulate alternative offers and set clear negotiation goals, improving your leverage during discussions. By anticipating objections and preparing responses that emphasize long-term value, you can close deals without excessive discounting. Furthermore, utilizing data from your research helps communicate the economic and operational impact of your offerings, aligning discussions with the buyer’s strategic goals. Mapping out potential negotiation scenarios guarantees you can adapt your strategies dynamically. Key Elements Benefits Strategies Buyer Insights Customized conversations Research thoroughly Alternative Offers Boosted negotiation leverage Prepare multiple scenarios Anticipating Objections Improved closing likelihood Highlight long-term value Data Utilization Aligned discussions Communicate impacts clearly Dynamic Strategies Adaptability in negotiations Map potential outcomes Active Listening Techniques Active listening is a critical skill during sales negotiations, as it allows you to fully engage with the other party and uncover their underlying needs and concerns. To improve your active listening, try paraphrasing the speaker’s words and employing mirroring techniques; this builds rapport and encourages open dialogue. Incorporate empathetic responses to validate your counterpart’s feelings, which can help reduce tension and promote collaboration. Asking clarifying questions not only shows your engagement but also guarantees you grasp their position deeply, leading to customized solutions. Regularly practicing skills like summarizing key points and acknowledging emotions can greatly improve your negotiation outcomes, helping you build long-term relationships with clients and achieving mutually beneficial agreements. Preparation Is Crucial Preparation is essential for successful sales negotiations, as it allows you to understand the buyer’s business model and tailor your value proposition effectively. A well-prepared sales team is more likely to close deals, as thorough preparation builds confidence and reduces reliance on emotional decision-making. Here are some key aspects of effective preparation: Conduct extensive research on industry pressures and competitor offerings to anticipate objections. Set clear negotiation goals to maintain focus and direction during discussions. Prepare alternative offers in advance to adapt to changing dynamics and encourage collaboration. Active Listening In the context of successful sales negotiations, listening attentively can greatly impact the outcome of discussions. Active listening involves fully concentrating, comprehending, and responding to what the other party says. This skill helps uncover deeper needs and concerns, cultivating trust and rapport between negotiators. Research shows that effective active listening can increase the likelihood of closing deals by up to 60%. Techniques like paraphrasing and asking clarifying questions improve comprehension and demonstrate genuine engagement. Furthermore, paying attention to both verbal and non-verbal cues allows you to pick up on emotions and motivations, which can be vital for addressing objections. Regular practice of active listening not just enhances communication but also leads to longer-lasting business relationships and higher customer satisfaction. Data-Driven Negotiation Data-driven negotiation leverages analytics and insights to improve the effectiveness of negotiation strategies, greatly increasing the likelihood of favorable outcomes. By utilizing data, you can tailor your approach to better align with client needs, enhancing both your position and the perceived value of your offer. Consider these key points: Historical sales data helps you identify patterns in buyer behavior, allowing for strategic adjustments. Implementing key performance indicators (KPIs) can refine your negotiation tactics and reduce unnecessary discounting practices. Presenting evidence of past performance and ROI boosts buyer confidence, making them more willing to agree to premium pricing. Incorporating data into your negotiations not merely strengthens your arguments but also supports your credibility, leading to a higher success rate in closing deals. Frequently Asked Questions What Are the 7 Elements of Negotiation? The seven elements of negotiation are interests, options, alternatives, legitimacy, communication, relationship, and commitment. Interests refer to each party’s underlying needs. Options are potential solutions that satisfy these interests. Alternatives, or BATNA, provide fallback plans if negotiations fail. Legitimacy focuses on fair standards, whereas communication emphasizes clarity and active listening. The relationship involves maintaining rapport between parties, and commitment guarantees all parties agree on the terms reached during negotiations. What Are the 7 Steps of Negotiation? The seven steps of negotiation include preparation, where you gather information and set your goals; establishing rapport to build trust; defining the agenda to clarify discussion points; exchanging information to understand both parties’ needs; bargaining to reach a mutually beneficial agreement; closing the deal with clear terms; and implementing and following up on the agreement to guarantee all commitments are met. Each step is vital for achieving a successful negotiation outcome. What Are the 5 C’s of Negotiation? The 5 C’s of negotiation are Communication, Collaboration, Compromise, Creativity, and Confidence. Effective communication involves clear dialogue and active listening, which promotes comprehension. Collaboration encourages working together to achieve common goals. Compromise requires making concessions to reach agreements. Creativity allows for innovative solutions that address both parties’ needs. Finally, confidence helps you approach negotiations assertively, influencing outcomes positively. Mastering these elements can greatly improve your negotiation effectiveness and relationship-building skills. What Is the 70/30 Rule in Negotiation? The 70/30 rule in negotiation suggests you should spend 70% of your time listening and comprehending the other party’s needs, whereas only 30% should be spent presenting your position. This approach encourages better communication, allowing you to uncover hidden objections and align your proposals with the other party’s priorities. Conclusion Acquiring the seven crucial sales negotiation skills is fundamental for your success in today’s market. By focusing on active listening, utilizing data-driven techniques, and preparing thoroughly, you can improve your negotiation outcomes. Comprehending KPIs and leveraging historical sales data will allow you to present compelling proposals that justify your pricing. In the end, these skills not just help you close deals more effectively but additionally cultivate long-term relationships with clients, ensuring ongoing success in your sales career. Image via Google Gemini This article, "Master 7 Essential Sales Negotiation Skills for Success" was first published on Small Business Trends View the full article
-
MacOS is great in all kinds of ways, but it's far from the most customizable operating system out there. Sure, it's not locked down to the extent iOS and iPadOS are, but compared to Linux and even Windows, macOS really doesn't let you change the look and feel very much. But that isn't to say there's no room to tweak the operating system to make it the way you like—if you know where to look. Here are a few third-party tools that let you make macOS your own. Use a custom cursorIt's pretty easy to change how the mouse pointer looks on Windows and Linux—you just need to dig around in the settings. On macOS, you can only change the size of the pointer. Unless, that is, you install the free and open source Mousecape. This application lets you create a cursor, then use it in place of the default system ones. You can also install cursors made by others. There's no centralized collection of cursors for this, unfortunately, but I found a fun hand on Github, some Wii cursors, and a decent collection on DeviantArt. You could also try your hand at creating your own set. Note that Tahoe users will have to download an updated fork in order to use Mousecape—the main build doesn't work at the moment. You'll need to install a pre-release download as of this writing. Use any website as your wallpaper Credit: Justin Pot Some great wallpapers, including dynamic ones, are included with macOS. There's also the option to use your own photos. But what macOS doesn't offer are custom, animated wallpapers. Enter Plash. This free application lets you turn any website into a macOS wallpaper, which opens up all kinds of interactive possibilities. A few sites included let you look out a random stranger's window, see real-time weather data, or take in some animated pixel art, but you can use any website you can think of. It's a lot of fun to play around with. Clean up the menu bar Credit: Justin Pot The macOS menu bar is a bit of a mess. Windows makes it relatively easy to hide icons by dragging them to a secondary area. Apple hasn't offered anything like this until Tahoe, which added a way to disable any icon in the settings. The problem: it's all or nothing. Hide an icon in the settings and there's no quick way to access it other than going back into the settings and turning it back on. For that, you'll need a third party app. I personally recommend Ice, which is the best free app for cleaning up your menu bar. My coworker Pranay recommends Barbee, another great option. Both make it easy to hide menu bar icons in a secondary bar accessible by hitting an icon, similar to how it works on Windows. Every Mac user should install some sort of tool like this. Change your folder icons Credit: Justin Pot This one isn't unofficial, exactly, but it's so buried it might as well be. You can change the icon for any folder, document, or even application by right-clicking it, clicking "Get Info", then dragging an image to the icon in the window that opens. Weird, right? But it works, meaning you can customize folders to look however you want. I talked about this in an article with more details. This gets really fun if you install Fancy Folders, a free application seen in the image above which allows you to create folder icons in the color of your choice, complete with either the text or icon of your choice. It's a lot of fun to play with, and can be very useful for visually keeping things organized. View the full article
-
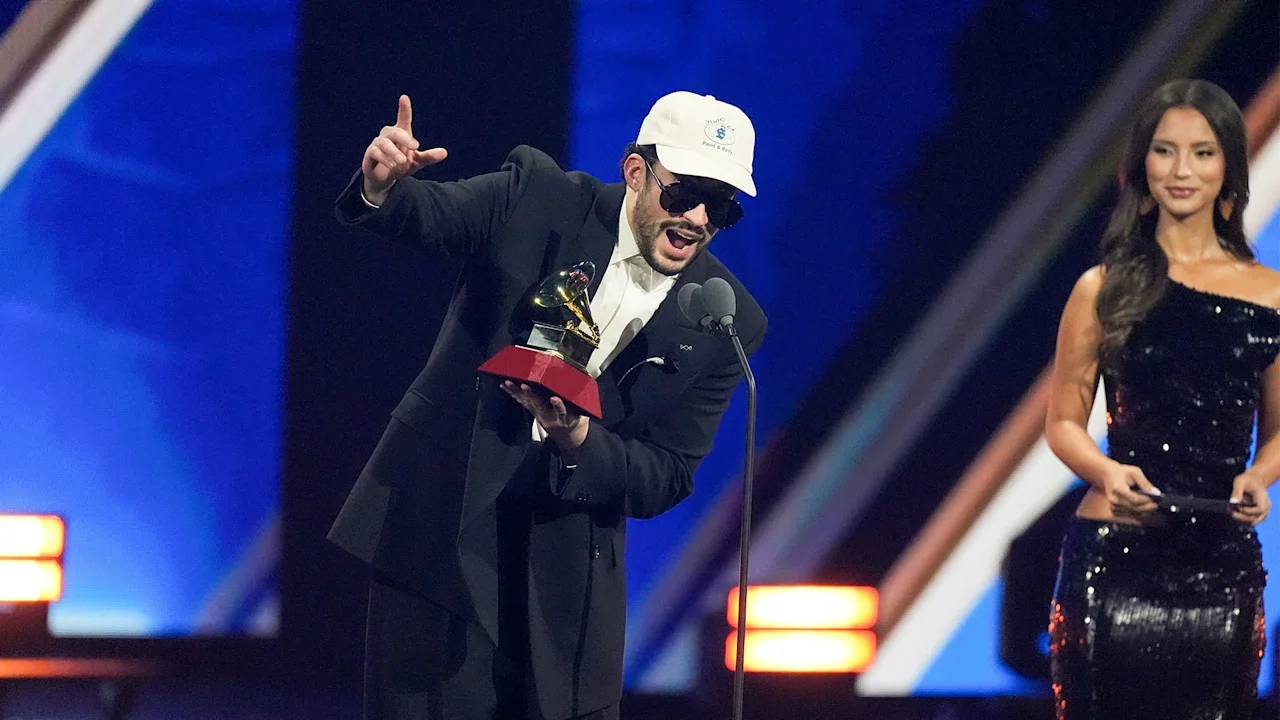
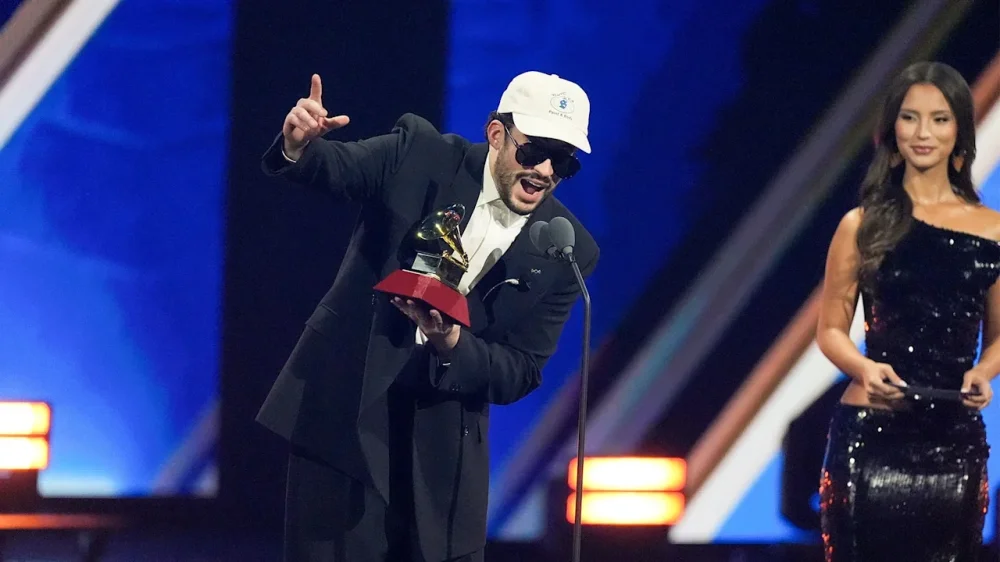
It should come as a shock to no one: The 2026 Latin Grammy Awards were all about Bad Bunny. The Puerto Rican superstar won album of the year for his landmark release “Debí Tirar Más Fotos.” After thanking his family and all those who worked on the album, he ended his speech with “Puerto Rico, I love you, thank you.” Those are powerful words honoring a record that doubles as a love letter for his island. The artist born Benito Antonio Martínez Ocasio was destined to dominate from the jump. He also won the first award of the night, for música urbana album. Halfway through the show, the singer found himself back on stage accepting the música urbana song trophy for “DTmF.” “I never practice my speeches,” he said in Spanish. And then he showed up for a third time: to perform “Weltita” with Chuwi. He wasn’t the only one with reason to celebrate: Song of the year went to Karol G, Andrés Jael Correa Ríos and Édgar Barrera for “Si Antes Te Hubiera Conocido.” And Alejandro Sanz took home record of the year for “¿Y Ahora Qué?” Live from Sin City, the 26th annual Latin Grammys were both energetic and eclectic. Take Raphael, the 2025 Person of the Year, who launched into an emotive rendition of “Qué Sabe Nadie” and “Mi Gran Noche,” inviting the crowd to sing along. That was after Santana kicked things off — specifically, Maluma singing Santana’s 1970 hit “Oye Como Va” with the guitar legend himself. It was just the beginning of a memorable medley, talents of today celebrating Santana — Christian Nodal joining in for “Corazón Espinoza” and Grupo Frontera for their 2025 collaboration with the virtuosic musician, “Me Retiro.” Performances hit hard and fast: Aitana brought her dreamy electro-pop, Sanz delivered a medley of “El Vino De Tu Boca” and “Las Guapas,” Rauw Alejandro channeled Puerto Rico in Vegas with “Khé?,” the bachata “Silencio,” “Falsedad” and “Carita Linda.” Then: Danny Lux, Kakalo and Ivan Cornejo brought contemporary Mexicana sounds. Pepe Aguilar followed, with his life-affirming mariachi — “El Cihualteco” into “El Fuereño.” Elena Rose slowed things down with “Me Lo Merezco.” Karol G and the legendary Mexican singer Marco Antonio Solís dueted the romantic ballad “Coleccionando Heridas.” Two of the biggest groups in regional Mexican music – Grupo Frontera and Fuerza Regida – launched into their joint hit, “Me Jalo,” before the latter took over for “Marlboro Rojo.” That’s a cut from their record-breaking 2025 album “111xpantia.” Carín León’s lovely raspy vocal tone carried throughout “Ahí Estabas Tú”; then he was joined by Kacey Musgraves for “Lost in Translation.” Not long after, León took home the trophy in competitive contemporary Mexican album category for “Palabra De To’s (Seca).” Morat brought the pop-rock with “Faltas Tú” and Ca7riel and Paco Amoroso brought a kind of outsider, artistic spirit. Joaquina delivered a full-bodied “Quise Quererte.” Any aspiring artists watching would be wise to take a page out of the Brazilian singer Liniker’s book; “Negona Dos Olhos Terríveis” was one of the night’s most joyful. The same, of course, should be said about norteño band Los Tigres del Norte. The coveted best new artist trophy was handed out to Paloma Morphy. Traditional tropical album went to Gloria Estefan for “Raíces.” Not long afterward, she hit the stage for “La Vecina” and “Chirriqui Chirri,” joined by Nathy Peluso for the latter. Then ranchero/mariachi album went to Christian Nodal for “¿Quién + Como Yo?” Most of the evening’s awards were handed out during a pre-televised Premiere Ceremony. That included: Bad Bunny’s “Voy A Llevarte Pa Pr” winning for reggaeton performance. Argentinian duo Ca7riel and Paco Amoroso cleaned house then, too: taking home their first Latin Grammys for short and long form music video, alternative song, as well as alternative music album for “Papota,” and pop song for “El dia del amigo.” That’s five wins, making them the most awarded act at the 2025 show. The three-hour award show aired live from Las Vegas’ MGM Grand Garden Arena. It was hosted by the dynamic duo of Maluma and actor, producer and musician Roselyn Sánchez. This story has been updated to correct that Maluma helped open the Latin Grammys, not Miguel. —Maria Sherman, AP Music Writer View the full article
-
The stock market survived the longest government shutdown in U.S. history with minimal impact. But it tumbled on Thursday, November 13, amid a sell-off of tech stocks as worries about overinflated values and interest rate cuts grew. Take the S&P 500, which shrank 1.66% to 6,739.49, or the Dow Jones Industrial average, which went down by 1.65% to 47,457.22—both at their lowest in over a month. It was only the day before that the Dow had surpassed 48,000, reaching a new record high. The Nasdaq composite met a similar fate, dropping 2.29% to its month low of 22,870.36. Many tech stocks felt the effect. Shares of electric vehicle maker Tesla (Nasdaq:TSLA) dropped 6.64% on Thursday, followed by another 4.78% at one point during after-hours and premarket trading on Friday. Palantir Technologies (Nasdaq:PLTR), which has been repeatedly pointed to as an example of overinflated value, saw its shares fall 6.53% Thursday and an additional 4.30% in after-hours and premarket trading. As of yesterday’s closing bell, Palantir was still trading 127.61% up in 2025. Nvidia Corporation, which just became the first company to hit a $5 trillion valuation in late October, also saw its shares (Nasdaq:NVDA) fall. Shares of the AI chip designer closed down 3.58% and, like its fellow tech companies, saw that drop continue through after-hours and premarket trading with a decline of 3.33%. Nvidia’s stock had already fallen Tuesday, following the news that Softbank sold its 32 million Nvidia shares—worth $5.8 billion—in October. These drops occurred alongside a decreasing likelihood that the Federal Reserve will cut interest rates when it meets on December 9 and 10. According to CME FedWatch, the likelihood for a rate cut reached over 98% a month ago, but sank to 62.9% on Wednesday and 50.1% on Thursday. View the full article
-
Head of US division will take over from February after current boss retiresView the full article
-
As an aspiring entrepreneur, you need to grasp fundamental small business advice that can steer your venture toward success. Staying organized is vital; it involves managing financial records and utilizing project management tools effectively. Furthermore, you must learn to be flexible, adapting to market changes and customer feedback. These foundational steps pave the way for automating tasks and prioritizing customer service, yet there’s more to explore that can enhance your business even further. Key Takeaways Stay organized by maintaining accurate financial records and using project management tools to enhance productivity and collaboration. Be flexible in adapting to market changes and actively listen to customer feedback to improve services and offerings. Automate processes like CRM, accounting, and payroll to save time, reduce errors, and enhance efficiency. Prioritize exceptional customer service to boost retention rates and increase profitability through satisfied customers’ referrals. Build personal connections and a professional network to create collaboration opportunities and foster loyalty among customers. Stay Organized Staying organized is fundamental for any entrepreneur looking to run a successful business. Accurate records of your finances are essential; by recording transactions weekly, you can spot financial trends and issues early on. Using project management software like Trello or Notion can streamline your task assignment and deadline management, boosting productivity. Planning your social media campaigns and email marketing in advance with automation tools saves time and guarantees consistent customer engagement. Centralizing documentation on a shared platform makes access easier for your team, enhancing collaboration. Furthermore, creating a daily to-do list and prioritizing high-priority tasks greatly improves efficiency, making sure you address critical responsibilities swiftly. For more insights, consider consulting a business advisor for small businesses or visiting local business centers for customized small business advice. Learn to Be Flexible Organizational skills lay the groundwork for running a successful business, but the ability to adapt is equally important. Being flexible in response to changing market conditions can markedly reduce your risk of obsolescence, keeping your business relevant and competitive. Listening to customer feedback is vital; 70% of customers prefer brands that do so, which can help you adjust your business model or pricing strategy. Furthermore, consider updating your website design to improve user experience, potentially boosting conversion rates by 200%. A business advisor can guide you through these changes, and exploring a local business center near you may offer more resources. Automate as Many Things as Possible In today’s fast-paced business environment, automating various tasks can considerably streamline your operations and improve efficiency. By implementing tools like CRM systems, accounting software, and payroll solutions, you can save time, reduce errors, and enhance customer engagement. Furthermore, setting up automated emails and chatbots can help you maintain customer satisfaction as you free up your resources for more strategic activities. Streamline Operations With Technology Streamlining operations with technology is essential for any entrepreneur looking to improve efficiency and reduce costs. By adopting various tools, you can automate repetitive tasks and focus on growth. Here are some effective strategies: Implement CRM tools to automate follow-ups with leads, enhancing conversion rates and saving time. Utilize QuickBooks for streamlined bookkeeping, reducing manual data entry as well as providing real-time financial insights. Set up automated email campaigns to recover up to 15% of abandoned shopping carts, boosting potential revenue effortlessly. Integrate ADP to automate payment processes and tax calculations, minimizing errors and ensuring compliance. Enhance Efficiency Through Automation Finding ways to improve efficiency can considerably impact your business’s bottom line. Implementing automation tools, like CRM systems, can handle customer follow-ups automatically, allowing you to focus on strategic growth. Utilizing accounting software can reduce manual data entry errors by up to 90%, streamlining bookkeeping processes and saving valuable time. Automated email campaigns targeting abandoned shopping carts can recover about 10-15% of lost sales, greatly boosting your revenue. Additionally, chatbots can provide instant customer support outside business hours, enhancing customer satisfaction as well as reducing your staff’s workload. Finally, payroll software can expedite payroll processing by over 50%, ensuring timely payments and compliance with tax regulations, thereby enhancing your overall operational efficiency. Embrace automation to maximize productivity and drive success. Focus on Customer Service Though many aspects of running a small business demand attention, focusing on customer service can greatly impact your bottom line. Prioritizing exceptional customer service can boost your retention rates by up to 25%, enhancing profitability. Here are four key strategies to implement: Listen to Feedback: Actively seek and respond to customer feedback, which can increase satisfaction and loyalty by 10-15%. Timely Communication: Respond without delay to inquiries, improving your ratings by up to 30%. Create Positive Experiences: Guarantee every interaction is positive; satisfied customers recommend your business to an average of 3 to 4 people. Adopt a Customer-Centric Approach: Companies prioritizing customer service see profits 60% higher than those that don’t. Investing in customer service pays off remarkably. Understand Financial Management Financial management is a cornerstone of any successful small business. Maintaining a positive cash flow is vital, as 82% of small businesses fail because of cash flow mismanagement. To navigate financial uncertainties, establish a thorough budget that includes all expenses, revenue projections, and contingency plans. Regularly reviewing financial statements, such as income statements and balance sheets, provides insights into your business performance and informs strategic decision-making. Utilizing accounting software can streamline your financial management, reducing manual errors and ensuring accurate tracking of income and expenses. Furthermore, consulting with financial professionals can improve your comprehension of tax obligations and help identify potential deductions, ultimately impacting your overall business profitability positively. Prioritize these practices to strengthen your financial foundation. Develop a Marketing Strategy When you develop a marketing strategy, it’s essential to blend both digital and traditional channels to maximize your reach and engagement. Allocate at least 70% of your budget to digital marketing for ideal results. Here are some effective tactics to reflect on: Utilize social media: Engaging actively can boost your lead generation by an average of 126%. Implement targeted advertising: Using platforms like Google Ads can yield a return on investment of up to 400% when customized to specific audiences. Collaborate with influencers: This can expand your reach by 11 times, connecting you authentically with potential customers. Regularly review performance data: Companies that analyze their data are five times more likely to make faster, more effective decisions. Network and Build Relationships To grow your business effectively, you should prioritize networking and relationship-building. Attend networking events to meet potential partners and investors, as you leverage online platforms to expand your reach and connect with a broader audience. Don’t forget to follow up diligently with your contacts; maintaining these relationships can lead to valuable referrals and opportunities that traditional marketing might miss. Attend Networking Events Networking events are essential for entrepreneurs looking to expand their business opportunities and build meaningful relationships. By attending these gatherings, you can connect with a diverse group of professionals who may help your business grow. Here’s how to maximize your networking experience: Meet potential investors who may be interested in funding your projects. Form partnerships with other entrepreneurs, leading to valuable collaborations. Gain insights into market trends by engaging with industry experts at conferences. Follow up with contacts you make, as 70% of people will refer a business after a personal connection. Leverage Online Platforms In the current digital era, leveraging online platforms is crucial for entrepreneurs aiming to expand their professional networks and build valuable relationships. Start by utilizing platforms like LinkedIn to connect with industry professionals, which can lead to potential partnerships and collaborations that improve your business visibility. Joining relevant online forums and groups allows you to share insights and ask questions, nurturing relationships with peers and opening doors to networking opportunities. Participate in virtual networking events and webinars to broaden your professional circle and gain insights from industry leaders. Furthermore, engage with customers and fellow entrepreneurs on social media to create a community, leading to referrals. Follow Up Diligently After meeting new contacts at networking events, following up diligently is essential for building lasting relationships. This process demonstrates your genuine interest and commitment to maintaining connections. Here are some effective follow-up strategies: Send personalized messages that reference specific topics discussed, increasing response rates by up to 30%. Be persistent; studies show that 80% of sales require five follow-ups after the initial meeting. Engage on social media platforms, like LinkedIn, to facilitate ongoing communication and share updates. Schedule regular follow-ups to keep your business top-of-mind, enhancing referral opportunities and collaboration. Frequently Asked Questions What Is the Best Advice for Entrepreneurs? The best advice for you as an entrepreneur is to maintain a clear vision and mission that directs your decisions. Build a strong network, as connections often lead to opportunities. Prioritize financial management, ensuring you budget accurately to avoid cash flow issues. Engage in continuous learning through education and mentorship, adapting to market changes. Ultimately, focus on exceptional customer service, since satisfied customers are likely to pay more for a better experience. Is $10,000 Enough to Start a Small Business? Yes, $10,000 can be enough to start a small business, particularly in service-based industries with lower overhead. You’ll need to budget carefully, focusing on vital expenses like legal fees, marketing, and initial equipment. Consider a lean startup model, working from home and utilizing cost-effective tools. Nevertheless, keep in mind that around 30% of small businesses fail within two years, so thorough market research and a solid business plan are key for success. How to Succeed in Business 9 Tips for Small Business Growth? To succeed in business, focus on building strong customer relationships by delivering exceptional service and seeking feedback. Develop a thorough marketing strategy that blends digital and traditional methods, adjusting based on performance data. Embrace technology to streamline operations and gather insights. Set clear, SMART goals to guide your growth. Finally, network effectively by attending industry events, as many successful businesses credit networking for their achievements. These steps can greatly improve your business’s growth potential. What Skills Do Entrepreneurs Need to Successfully Manage a Small Business? To successfully manage a small business, you need strong financial management skills to monitor cash flow effectively. Communication skills help you build relationships with customers and employees, whereas problem-solving abilities allow you to tackle challenges creatively. Marketing skills are crucial for promoting your products, and time management skills enable you to balance various responsibilities efficiently. Acquiring these skills will improve your ability to navigate the intricacies of running a small business. Conclusion In summary, mastering these seven crucial small business advice tips can greatly enhance your chances of success. By staying organized, being flexible, automating tasks, prioritizing customer service, comprehending financial management, developing a marketing strategy, and networking effectively, you create a strong foundation for your business. Each of these strategies contributes to a more resilient operation, nurturing growth and customer loyalty. Implementing these practices will help you navigate challenges and seize opportunities in the competitive entrepreneurial environment. Image via Google Gemini This article, "7 Essential Small Business Advice Tips for Entrepreneurs" was first published on Small Business Trends View the full article
-
We may earn a commission from links on this page. Scheduling your day is an important part of being productive. You can (and should) prioritize your to-dos by timeliness and time box your way to a jam-packed, detailed schedule, but there’s more to time management than that. You should also consider dividing up not only your day, but your week overall, to maximize productivity. The trick here is to theme your workdays. Instead of jumping from task to task on any given day, try grouping all the similar ones together and parking them on a specific day, when your schedule allows. By putting similar tasks together on the same day, you’ll stay in that “zone” longer, focusing only on what needs to be done in it. If all the things you have to do have something in common, you’ll stay focused on the central theme of the day’s work as you move from task to task. How to divvy up themed days for productivityFirst, start by thinking about why you want to do what you're doing. I don't mean you need to get all philosophical, but adding a "why" to your to-do list is valuable. You don't just want to clean your house because you have to, but because you want a safe, comfortable space or because your mom is coming to say for a week and you want her to feel cozy (and not harp on you about any lingering dust). You don't just want to finish your big project at work because it was assigned to you, but because you want to grow in your career, stay employed, or get a promotion. If thinking this way is a stretch for you, try setting SMART goals around your tasks. SMART goals are specific, measurable, actionable, relevant, and time-bound (in accordance with the acronym) and they help you stay focused on why you're doing what you're doing, as well as how you're going to do it. Set these intentions so you feel like you have something to work toward. That's where the daily themes come in. If you complete similar tasks over the course of one day, you are striving for an intention—meeting whatever goal you’ve set for that day’s theme—and staying focused on it from task to task. Say you have a big project at work. Here's how your first three days could look: Consider getting all administrative-type work done on Mondays. Designate Mondays for responding to emails, sending out new ones, taking calls, or scheduling meetings. Make sure you use this day to request any resources, details, or answers you need from others involved in the project, so you have everything you need for the following days. Creative activities, like brainstorming or designing, could be handled Tuesday, while Wednesday could be for research. You could also theme your days by project, according to Leonard Alexandru, an engineering director at Deloitte who has written about the value of themed days. Instead of dedicating time every day to multiple projects, consider assigning each project its own specific day of the week for work, so a project that requires a big focus on management should take up a whole day while one that requires you to focus on marketing, communications, sales, or whatever else should be on another. Why this works (and what to keep in mind)I do this around my apartment: One day is for cleaning my bedroom, the other is for the living room, and another is for the kitchen. It is that simple—and broadly applicable beyond your job. Hell, if you do strength training, you probably already do arm day, back day, leg day, etc. You wouldn't do a lat pulldown on leg day because it wouldn't make sense to exhaust your whole body, nor divert your focus from your glutes and quads. The reason it works is the same reason divvying up gym days works. When you are focused entirely on one thing, you do better at it, which makes you more productive at it. When you throw everything into the metaphorical blender, you lose that focus. Plus, the stress of figuring out what to do at a given time is gone, leaving you open to just get to work. You can "eat the frog" (that is, tackle your biggest task first) or work off a system like 1-3-5, which calls on you to take care of one major task, three medium-sized ones, and five smaller ones. With a themed grouping, you don't have to decide what those are; you just go. Try setting each day’s theme as an all-day event on whatever calendar software you use, so you’ll have a reminder at the top of the page about what to focus on each day. Just knowing your Thursdays are for client meetings, for instance, relieves you of the anxiety of deciding what to prioritize that day or when to schedule those meetings. It eliminates decision fatigue and keeps you on-task without you having to think too hard about what activity should go in what slot during your busy week. Obviously, a necessary or urgent meeting could crop up on a day that isn't Thursday. It's fine to take it, of course, but try to keep the general framework of the themed days whenever you can. View the full article
-
Emotional intelligence matters, and not just on a personal level. Research shows developing greater emotional intelligence can lead to higher performance and pay, as well as better professional and personal relationships. The better you can understand and manage your emotions, and the emotions of people around you, the greater your chances of success. So how emotionally intelligent are you? You could take an emotional intelligence test. Or you could just see how you answer the following questions. “Do I ask for advice instead of feedback?” Say you’re okay with getting feedback, even when it’s critical. (Plenty of people who claim they do, really don’t.) You may even enjoy getting critical feedback. But that doesn’t mean other people like to give you the feedback you need. Research shows when feedback is requested rather than volunteered, it tends to be too vague. Too fluffy. Too, “I don’t want to hurt your feelings so I’ll just be nice,” to be of any real value. But when you ask for advice? Harvard Business School researchers found that compared to asking for feedback, asking for advice resulted in respondents providing 34 percent more areas of improvement, and 56 percent more ways to improve. In short, emotionally intelligent people realize that asking another person to provide feedback (saying, “How did I do?”) puts them on the spot. On the other hand, asking another person for advice (saying, “What can (or should) I do?”) is flattering. Asking someone for advice implicitly shows you respect their knowledge, skills, experience, etc. Do that, and two great things happen: you get the input you need, and they feel valued, trusted, and happy to offer guidance they know will help you. Win-win. “Do I appreciate (even if I don’t like) negative feedback?” But what if you’re given feedback you didn’t request? That’s the farthest thing from fun. No one likes to be told what they can do better. Research shows most people rarely appreciate feedback when it’s negative. And when they do receive constructive criticism, they rarely use it to improve their performance. (In fact, studies show that within days we tend to totally forget the negative feedback we receive.) Emotionally intelligent people keep their feelings in check and embrace — or at least put aside — the discomfort to find ways to improve. A study published in Journal of Experimental Psychology: Learning found that we’re far more likely to recall evaluative feedback (feedback about something we’ve already completed) than directive feedback (feedback on how we could improve on a future task.) That’s why emotionally intelligent people embrace — again, even if they don’t enjoy — critical feedback. They focus on what it says about the task, not about themselves. Instead of avoiding feedback that threatens how you currently perceive yourself, use it to improve how you will someday perceive yourself. Smarter, more skilled, more talented, more inclusive… more of whatever you someday hope to be. “Do I often praise other people?” Do you feel you don’t receive enough recognition and praise? Science says you’re not alone. Two out of three employees surveyed feel they don’t receive enough praise, and nearly three-fourths say they receive some form of positive feedback less than once a week. Clearly that doesn’t feel great. Emotionally intelligent people recognize that what they want — or need — is what they can give to people they know. A kind word. A sincere thank-you. Plenty of people you know — employees, vendors, customers, friends, family, etc. — deserve a kind word. A sincere thank-you. But you should also recognize people you don’t know. A store clerk. A delivery person. A customer service rep. Because praise that is unexpected, like the gift that is given “just because,” is often even more powerful. “Do I willingly admit my mistakes?” As Daniel Coyle writes in his book The Culture Code, Navy SEAL Dave Cooper feels the most important words a leader can say are, “I screwed that up.” While that might sound odd, since conventional wisdom says leaders should project unshakable confidence, and admitting weakness risks creating more weakness, emotionally intelligent people realize strong cultures can only be built when people feel safe enough to tell one another the truth. Which starts with leaders who admit they aren’t perfect. The result is a vulnerability loop: one person allows themself to be vulnerable and admits a mistake or a shortcoming, which allows another person to do the same. In time, that leads to more open exchanges that build trust and drive performance. And helps people focus on how they can get better, together. “Do I often skip past the small talk?” Say you’re at a conference and just met someone new. Do you whip out the small talk? Science says you shouldn’t. A series of studies published in Journal of Personality and Social Psychologyfound that the more awkward and uncomfortable a conversation with another person sounded, the more they tended to bond with the other person, and the more they liked the other person. Participants felt less awkward, more connected, and a lot happier after those conversations than they expected to feel. Emotionally intelligent people realize that the deeper the conversation, especially with someone they don’t know, the more likely they both are to enjoy it. Keep in mind “deep” doesn’t have to be too deep. When researchers asked people to come up with what they considered to be “deeper” questions, the most common were pretty straightforward: What do you love doing? What do you regret most? Where do you see yourself in five years? As the researchers write, “Our research suggests that the person next to you would probably be happier talking about their passions and purpose than the weather or ‘What’s up?’” And so do you. View the full article
-
Investors in Bitcoin are waking up to another bad morning for the world’s preeminent cryptocurrency. As of the time of this writing, the price of one token is down 6.55% in the last 24 hours to just above $95,000 per coin. It’s a low that Bitcoin has not seen since May. Today’s selloff continues a monthlong trend in which Bitcoin has now lost about 20% of its value. But what’s driving this most recent selloffs? Two culprits are most likely at play. Uncertainty of Fed rate cuts Next month, the Federal Reserve is expected to announce a decision on whether it will change interest rates. The Fed has three options: increase rates, hold rates at current levels, or cut (decrease) rates. Until recently, Wall Street was pretty bullish about the likelihood that the Fed would cut rates in December. When the Fed cuts rates, it’s generally seen as beneficial because rate cuts boost liquidity in markets. Increased liquidity generally prompts investors to allocate more to risk assets. Risk assets include assets like cryptocurrencies and highly volatile stocks (such as AI-adjacent stocks lately). So a Fed rate cut in December would boost liquidity, likely driving investors toward risk assets, including cryptocurrencies such as Bitcoin, which would likely rise in price. But now, as NBC News notes, in recent days, traders think there is only around a 50% chance that the Fed will cut rates in December. At the beginning of November, the majority of traders thought there was a 90% chance the Fed would do so. This uncertainty over whether the Fed will cut rates in December is likely one of the biggest factors behind Bitcoin’s fall today. Selloff of tech and crypto stocks Bitcoin is generally seen as a risk asset since its price is highly volatile compared to more traditionally stable assets like bonds. But Bitcoin isn’t the only risk asset. Many tech stocks are seen as risk assets—particularly ones operating in the AI space—because their prices can swing so widely as of late. And as of the past day, those risky tech assets have been plummeting. Yesterday alone, the prices of some major tech and AI-adjacent stocks dropped significantly due to both uncertainty about Fed rate cuts and growing fears of an AI bubble. Those drops yesterday included: Palantir Technologies Inc. (Nasdaq: PLTR): down 6.53% Intel Corporation (Nasdaq: INTC): down 5.23% Nvidia Corporation (Nasdaq: NVDA): down 3.58% Tesla, Inc. (Nasdaq: TSLA): down 6.64% Amazon.com, Inc. (Nasdaq: AMZN): down 2.71% Alphabet Inc. (Nasdaq: GOOG): down 2.89% Meanwhile, those traditional tech stocks weren’t the only ones getting hit hard yesterday. As noted by CoinCentral, crypto stocks in the mining and trading space also had a pretty bad day, including: Bitfarms Ltd. (Nasdaq: BITF): down 17.98% Bitdeer Technologies Group (Nasdaq: BTDR): down 20.3% Coinbase Global, Inc. (Nasdaq: COIN): down 6.86% Gemini Space Station, Inc. (Nasdaq: GEMI): down 9.78% Bullish (NYSE: BLSH): down 9.85% When investors see risk asset stocks declining sharply—particularly ones operating in the crypto space—it may drive an outflow of investment in cryptocurrencies themselves as they seek safer and more stable investment assets to park their money in. Bitcoin has had a chaotic 2025 Being an investor in Bitcoin has certainly had its highs and lows this year. The token began trading just above $94,000 per coin just after the new year. It got a crypto-friendly The President administration boost around the time of President The President’s inauguration later that month. But after trading above six figures for the first few months of the year, Bitcoin took a hit, along with most of the stock market, thanks to President The President’s Liberation Day tariffs, which injected more uncertainty into investors’ minds than they had experienced in a long time. By April, Bitcoin had fallen to just above $76,000. However, the crypto recovered nicely since then, steadily rising until it hit an all-time high of over $126,000 in October. But since then, Bitcoin has steadily declined. And after its recent fall, Bitcoin is now up only about 2.8% for the year. View the full article
-
We may earn a commission from links on this page. The Pomodoro technique is a superstar in the world of productivity methods because its premise—that you should work hard for 25 minutes, then reward yourself with a few minutes off—is effective and appealing. But that doesn’t mean it works perfectly for everyone. Like any other method, it’s adaptable and, once you get the hang of it, should be customized to meet your unique needs. And if you find that Pomodoro's 25-minute work sessions with five-minute cooldowns aren’t cutting it for you, there's a similar but more flexible alternative: flowtime. What is the flowtime technique?The flowtime technique is a spin on Pomodoro, and as such, relies on the same principles: You work for a while, then get a break. The difference is that you determine how long the work and rest time last. Sometimes referred to as “flowmodoro,” this method is also all about keeping you in the zone on a task, luring you into deep work by using the goal of taking a break to keep you going. The break is crucial, so no matter how long you work, you do have to take one. Not only is that the motivator to keep you focused, but your productivity will take a massive hit if you work too long. Flowtime—or any technique designed to help you accomplish deep work—is useless if you end up producing dreck. The key here is the uninterrupted work you do while you’re gunning for that break. Like Pomodoro, you’re supposed to stay focused intently on a single task for the duration of your grind time, rather than do a little work, check your phone, type a little more, check your email, etc. Don't multitask, either, since it will actually make you less efficient. The only way flowtime is truly different from Pomodoro that you decide how long you work for, instead of relying on the "25 on, five off" framework. With Pomodoro, you are stricter, typically using a timer to keep you working and from checking your phone. You may not think you need the timer with the flowtime technique, but you should use one that has a stopwatch function to track how long you actually end up working and keep it on hand for days when you need the extra structure of the timer itself. In fact, once you finish a few days of flowtime and figure out your own working habits with the stopwatch, you'll need the timer so you can set it in personalized increments. This where I recommend using an app to help you manage things. My favorite is FocusPomo, which blocks your distracting apps for you whenever you're in a focus session. These sessions are customizable, so they don't have to be 25 minutes, and once you use it for a while, you get useful data on how long you work and when you may have gotten distracted. How to set up your personal flowtimeThe downside to using flowtime over Pomodoro is the same as the upside: You’re in charge of how long you work. While the Pomodoro technique is straightforward and outlines exactly how long you get to work and play, setting up your personal flowtime requires a little bit more effort and thought. You’ll need about a week to figure it out before you fully put it into action. During this exploratory setup period, here’s what you do: Track when you start working on a specific task with no distractions. You can use time-tracking software, but in this case a spreadsheet might be better because you also… Write down when you start feeling restless, distracted, or disinterested. Check your stopwatch to see exactly how long you were working, then take a break. Jot down when you feel energized enough to get back to the task and restart your stopwatch. Repeat until the task is done, then mark down when you finished, and how you feel overall. In a spreadsheet, dedicate one sheet to each task that needs to get done. Your columns can be labeled however makes sense to you, but something like the below—including a date, start and break times, and an ultimate conclusion time—is helpful. After using the spreadsheet for a while, you’ll get a sense of how long you can usually stand working on something before you need a break and how long those breaks typically need to be for you to feel rejuvenated enough to get back at it. Credit: Lindsey Ellefson Once you have a sense of your own work abilities and preferences, you can put them into action. If you can usually focus on cleaning for 15 minutes, start setting your timer for 15 minutes every time you clean, then give yourself a break that works for you, whether it’s five or 10 minutes. Commit to getting back to the task. From personal experience, this part matters a lot. I can think of plenty of times when I did not commit to getting back to it, but I notice I feel significantly less motivated when that happens. Focus on those feelings of self-satisfaction, and use them to motivate you to get back at it. You can challenge yourself to add more time to your work sessions gradually, but that’s optional. If your specific method is working for you, great. If you want to get better at focusing for long periods of time, start by adding one minute every time you do a task, inching it from, say, 15 to 16 to 17 minutes every time. It’s helpful to go back to the spreadsheet if you plan to do this, so you can see if you’re starting to tap out too early and readjust your flowtime. Bear in mind that you need to run through that experimental period for every single kind of task. If you're working on an application for grad school and feel extremely motivated, the time might fly by, and you may discover you can work for an hour with no problem. If your house is a mess and you struggle to find cleaning motivation, you may not be able to do more than 15 or 20 minutes of that at a time. It wouldn't make sense to block out an hour for cleaning just because it's something else you can do for an hour—you're only setting yourself up to fail. Unfortunately, this means the preparation period for flowtime adoption is lengthy, but it is worth it. This isn’t an easy way out if Pomodoro doesn’t work for you. Rather, it’s a challenge to find a time combination that does work for you. Something is always better than nothing, so find the flowtime that fits your needs and tap into the power of uninterrupted work with the promise of breaks, even if it looks a little different from the norm. Don't get discouraged if you don't feel like you're working in long enough chunks at first; productivity falls off when you don't give yourself enough breaks, so look at this as a way of making sure that doesn't happen. View the full article