Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
The mortgage company, even though it is owned by a bank, has been profitable for the last two years, when considering its originations operations, as it does. View the full article
-
Apple brought RCS (Rich Communication Services) messaging to the iPhone with iOS 18 last year, giving green-bubble users access to more features and functions. But what exactly is possible with RCS on the iPhone, and what is still exclusive to iMessage users? Are Android RCS users now fully integrated into chats in the iOS Messages app or not? I'll lay out exactly what you can do in RCS chats between iPhones and Android phones, and explain which features are still missing—and when you might be able to get them. If you've got contacts on other mobile platforms, this should help you understand more about what the experience is like from their end. To use RCS, you must have a carrier that supports it (most now do). On an iPhone, open Settings, then choose Apps > Messages > RCS Messaging to enable it. In Google Messages on Android, tap your profile picture (top right), then choose Messages settings and RCS chats to turn on the feature. RCS on iOS and Android: what you can do Ever since iOS 18, RCS messaging has officially been supported in the iOS Messages app—specifically, via the RCS Universal Profile 2.4. This brings green bubble Android users closer to parity with iMessage users, though some features only work in one direction, and some features only work in one-to-one conversations and not group chats. One notable upgrade is support for high-resolution photos and videos, which should work seamlessly across all your RCS-enabled conversations, with no more issues around compression or transfer. Web links look better as well, because you'll get a proper preview shown on both Android and iOS, and you can share current locations too (though only as a static pin, not a live and updating one). Web links now look much better between iOS and Android. Credit: Lifehacker Typing indicators and read receipts are supported in both directions, assuming you've got them enabled on your devices. However, they don't work in group chats—RCS users on Android can now join group chats, but the experience can be buggy based on reports, and you lose the typing indicators and the read receipts. Emoji reactions are now supported, up to a point—but based on my testing, these only work from iPhone to Android. If you try and send an emoji reaction in the other direction, iPhone users will just get a separate text showing the emoji (it won't appear as a bubble on top of the original message). RCS on iOS and Android: what you can't do (yet)If you look at everything you can do in iMessage (with other iMessage users) and Google Messages (with other Android RCS users), you'll realize there's a long way to go when it comes to cross-platform support. For example, at the moment you can't unsend messages, or reply inline in a thread, either from Android to iPhone or iPhone to Android. You can edit messages, but only if you're an Android user messaging an iPhone user—and with the caveat that the iPhone user gets two texts (the original message and the edited message, which rather defeats the point). The ability to edit messages on an iPhone simply doesn't appear in an RCS conversation. Message editing is something that doesn't quite work yet. Credit: Lifehacker Another missing feature is end-to-end encryption for your chats and files shared in them. Apple has promised that support for this in RCS conversations is on the way, though it hasn't shown up yet—not even in iOS 26. This should give you pause when it comes to sharing sensitive information in these chats. Full end-to-end encryption is part of the RCS Universal Profile 3.0, which Google is testing in beta and which Apple has yet to adopt. Once this next update finally makes its way to iPhones and Android devices, interoperability will be leveled up again—it should, in theory, bring with it full support for message editing, emoji reactions, and inline replies. Until then, it's something of a half-baked implementation, especially for group chats. View the full article
-
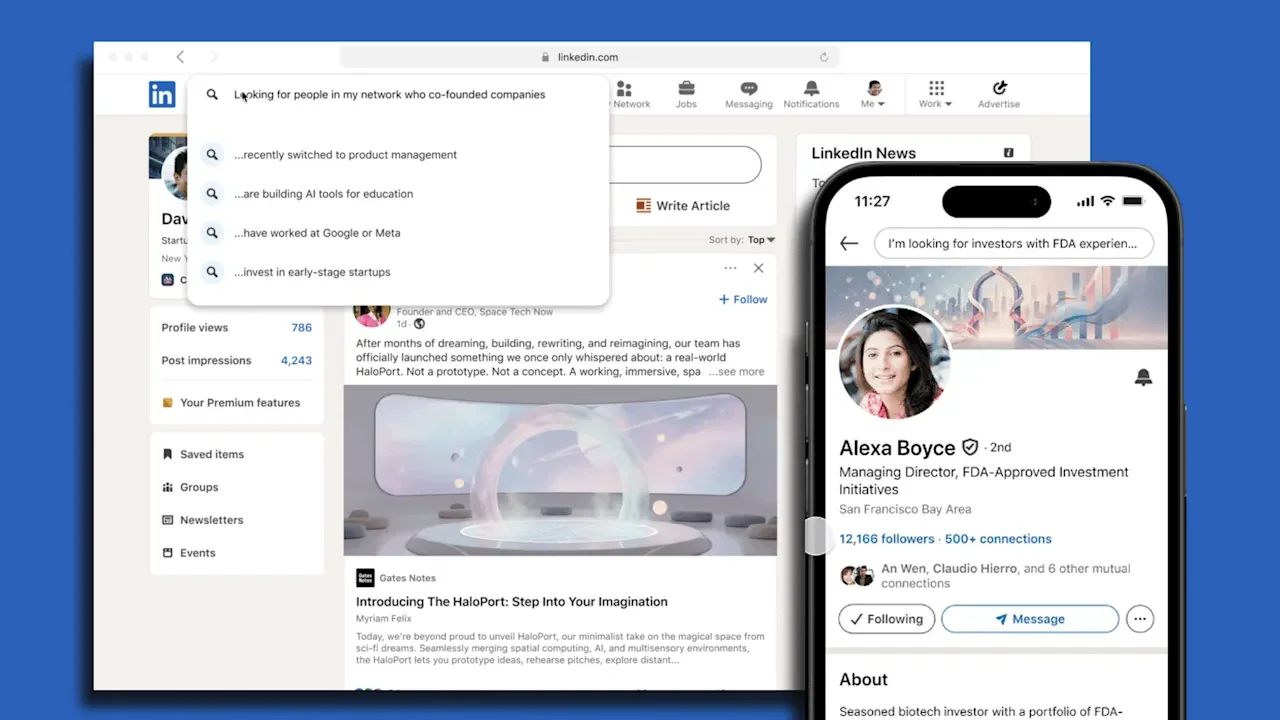
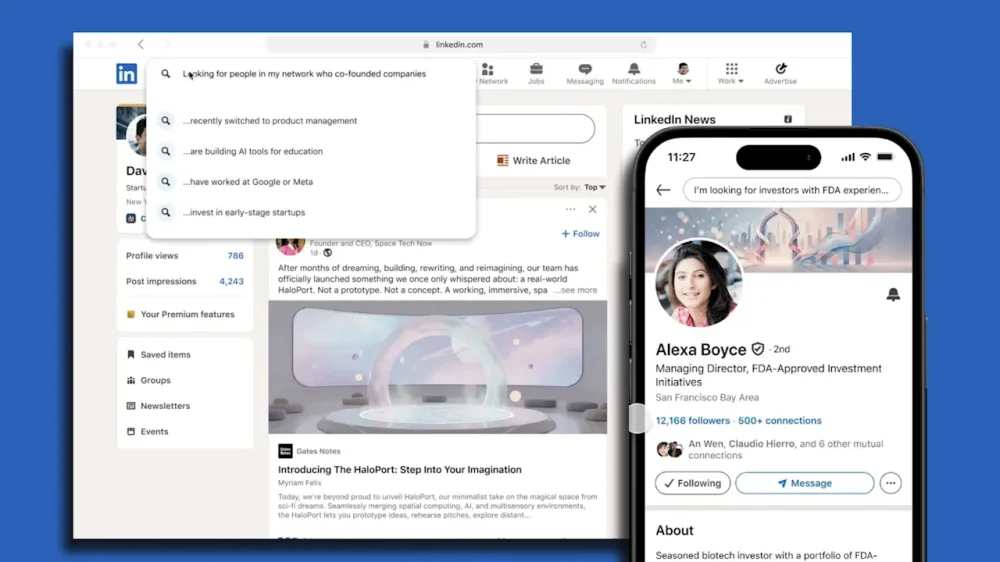
Last June, LinkedIn CEO Ryan Roslansky took on a second job. Microsoft, the social network for business professionals’ owner since 2016, expanded his responsibilities to include Microsoft 365—the suite still better known by its former name, Microsoft Office—and its Copilot AI assistant. The role charges him with making AI useful in a productivity context, a goal that’s still very much a work in progress. But Roslansky also remains in charge of LinkedIn, a place whose entire reason for being springs from the network effect of its billion-plus members. Their unique connections, learnings, and willingness to help other people can’t be fed into an LLM and reprocessed into the kind of generic advice a chatbot can spout. In a world of increasingly commodified information, Roslansky argues that LinkedIn’s essential humanity is more essential than ever. “Trusted, contextual, expert-driven knowledge—the type of stuff that comes from having a lived experience or doing a specific job or having a deep insight or knowing people that have actually done the job—in my view, that’s becoming much more valuable, not less,” he says. “I think the question moving forward from professionals isn’t just going to be something like, ‘What’s the answer?’, but ‘Who can I trust to guide me?’ And that’s where we come in.” Still, once you venture beyond your core LinkedIn contacts, it’s never been all that easy to tap into the power of your network. “We’ve always had, what I’ll call decent, keyword-based lexical people search that allows you to type someone’s name if you know them,” says Roslansky. “We did a decent job at name-plus-company.” But even if you were seeking a particular kind of advice or favor that a friend of a friend (or a friend of a friend of a friend) might have been happy to dispense, there was no guarantee you’d be able to track them down with keywords and filters. Now LinkedIn is taking a major step to address that. A new feature called AI-powered people search uses generative AI to break past the limitations of conventional search. It understands requests such as “investors with FDA experience for a biotech startup,” “Northwestern alumni who work in entertainment marketing,” “teachers turned industrial designers,” and “who can help me raise money for a nonprofit?” The results it returns include relevant profiles regardless of the exact words you used to phrase the search. AI-powered people search is rolling out first to members who pay for LinkedIn Premium accounts, but the company says it will eventually be available to all users. It follows the AI-powered job search feature introduced earlier this year, which Rolansky notes can understand open-ended asks such as “‘I want to help bring humanity to Mars” or ‘I want to work on AI products with my finance skills.” Using technology that’s very 2025, these features deliver on the promise of the nearly 23-year-old site’s original vision that—as an early tagline put it—relationships matter. Members who have managed to rack up hundreds of connections over the years might find new value in visiting the site more regularly and diving deeper. “The company was founded on the idea that if we were able to build a valuable community, that any professional can become more productive and successful through other people in their network,” says Roslansky. “When you can leverage AI to reason over that network of people, it opens up a whole new world.” As for how LinkedIn’s ongoing evolution fits into Roslansky’s new role at Microsoft, he points out several advantages to his twin responsibilities. For one, the ability to sit in on meetings with people like Microsoft CEO Satya Nadella, CTO Kevin Scott, and Microsoft AI CEO Mustafa Suleyman give him “a view into where the bleeding edge of where AI and technology are going.“ But expanding his purview is also about aspects of LinkedIn’s mission that remain unfulfilled even nine years after the two companies became one. “Recruiters, we make productive and successful,” Roslansky explains. “Salespeople. Marketers. But general professionals are still something that we are decent at, not what we’ve thrived on. It turns out the greatest set of tools in the world to make professionals more productive is the suite of office tools that I have the amazing honor to be working on right now.” Until now, LinkedIn has felt like a most distant relative of Microsoftian stalwarts such as Word, Excel, and PowerPoint. As AI provides opportunities to rethink all these products—with well over a century of combined history behind them— Roslansky says he’s thinking about them holistically. That alone is a new approach. And its upshot could shape the future of some of the world’s most-used business tools. View the full article
-
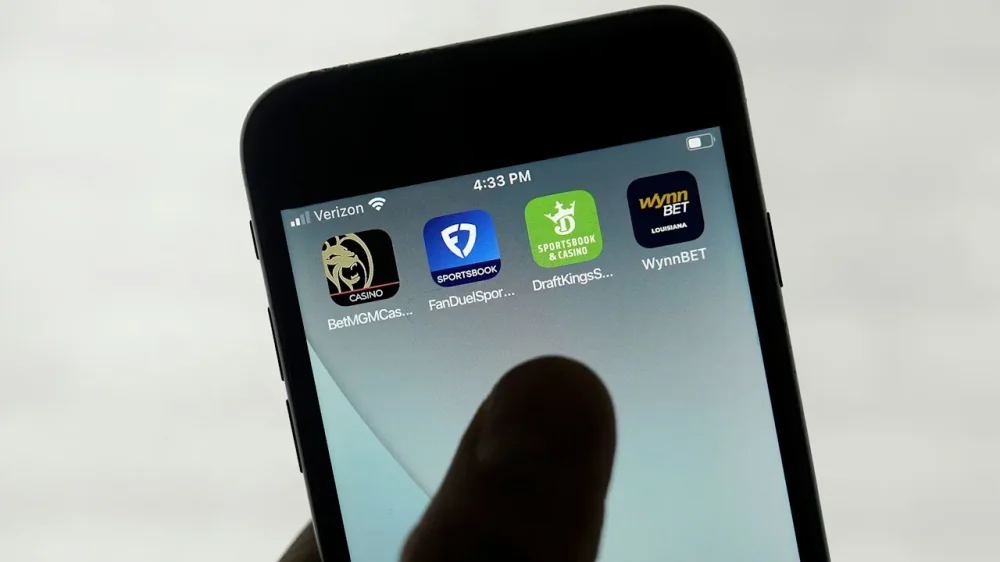
Online betting is more accessible than ever, with 14% of U.S. adults saying they bet on professional or college sports online either frequently or occasionally, according to a February poll by The Associated Press-NORC Center for Public Affairs Research. It’s also in the news, with a growing list of sports betting scandals making headlines. Public health advocates and personal finance advisers say it’s important to know the risks if you’re going to gamble online. “Gambling and ‘responsibly’ seem to be oxymoronic, because if you’re gambling it’s all about risk,” said Caleb Silver, editor in chief of personal finance site Investopedia. “But people still do it. Online gambling and sports betting are only becoming more popular.” Since the Supreme Court struck down a ban on sports betting in 2018, 38 states and Washington, D.C., have legalized gambling, according to the American Gaming Association. For those new to online gambling, it can be helpful to set limits in advance on how much you’re willing to lose and how much time you’re willing to spend. Many of the platforms and apps that offer gambling, such as FanDuel and DraftKings, include optional safeguards to limit time or losses. Other apps can block access to the platforms for set amounts of time. Here’s what to know: Online gambling can be riskier than gambling in person The potential losses of digital betting can occur more quickly than in a physical casino, according to Heather Eshleman, director of operations at the Maryland Center for Excellence on Problem Gambling, since people can bet so much so easily and quickly on the internet or apps, with less friction. The new prevalence of prediction markets, such as PredictIt and Kalshi, has also created new opportunities to place wagers online on everything from election outcomes to celebrity news to the weather. How to tell if you have a problem with online gambling According to public health advocates, the biggest warning sign of a problem is if you’re devoting time to online betting that’s taking away from other things in your life — especially your relationships with friends, family, and work. If you’re spending money on gambling that could instead go towards unmet basic needs, that’s also a warning sign. “We encourage people to only use money they would use for fun and entertainment, not money that should be used to pay the mortgage or the rent or to pay for food,” said Eshleman. Silver echoed this. “You have to know before you do it how much you can afford to lose,” he said. “What is your ‘tap out point?’ Those rules have to be firmly established.” Ways to limit online gambling Most sports betting platforms offer “responsible gambling tools,” according to Eshleman. “You can set limits on time, money, deposits, wins, and losses,” she said. “The goal is to set those limits before you start, because if you don’t set them in advance, they’re not really going to work for you. Once you’re into the excitement of it, you’re not going to stop and use those tools.” Eshleman recommends apps such as GambBan and BetBlocker, which limit access to gambling sites externally. She also directs those who suspect they may have a problem to use the 1-800-GAMBLER hotline or contact Gamblers Anonymous. Know the risks and downsides Silver, the head of Investopedia, said he started adding definitions of online betting and gambling terms to the personal finance site when he saw an increasingly “closer connection between sports betting, day trading, options trading, and cryptocurrency trading.” He encourages those who are interested in digital betting to make sure they know what they’re getting into. “Before anyone even gets an online (gambling) account, they should be required to know the fundamental terms and rules about the way sports betting works,” he said. “What’s the ‘money line’ or ‘parlay?’ How do odds work? What is the maximum I could lose on this bet?” The other thing to do is to “play with no expectation of a return,” he said. “The likelihood is that you will lose. So, if you’re willing to lose, how much are you willing to lose?” Cory Fox, senior vice president of public policy and sustainability at FanDuel, who handles the site’s responsible gambling initiatives, compares using the safeguards to wearing a seatbelt when driving in a car and said FanDuel is committed to setting standards for being a responsible operator in the online gambling space. Lori Kalani, chief responsible gaming officer at DraftKings, said the site is committed to the same goal and compared using the limit-setting tools to taking Ubers instead of driving on a night when you know you’ll be drinking. Fox added that responsible gambling tools are important to help allow FanDuel to maintain its social license. He said that it’s in the interest of the site to make sure its users can be on the site and play for a long time to come. Make sure it’s not a coping mechanism “If you’re taking care of your mental health, you’re less likely to have a problem with gambling,” Eshleman said. Rather than turning to the thrill of placing online bets, Eshleman encourages people to find positive ways to cope with stress — listening to music, taking walks, getting more sleep and exercise, and spending more time socializing. Social gambling is safer than hidden, private gambling, she said. “If you’re doing it alone, that’s a red flag that it’s not an activity that’s healthy for you,” said Eshleman. “It all ties in to our basic wellness. I think if people focus on wellness, it will prevent a lot of gambling.” The Associated Press receives support from the Charles Schwab Foundation for educational and explanatory reporting to improve financial literacy. The independent foundation is separate from Charles Schwab and Co. Inc. The AP is solely responsible for its journalism. —Cora Lewis, Associated Press View the full article
-
Asset manager famous for bet against US housing market says stock valuations are unhinged from fundamentalsView the full article
-
New documents reveal fresh details about the sex offender’s powerful networkView the full article
-
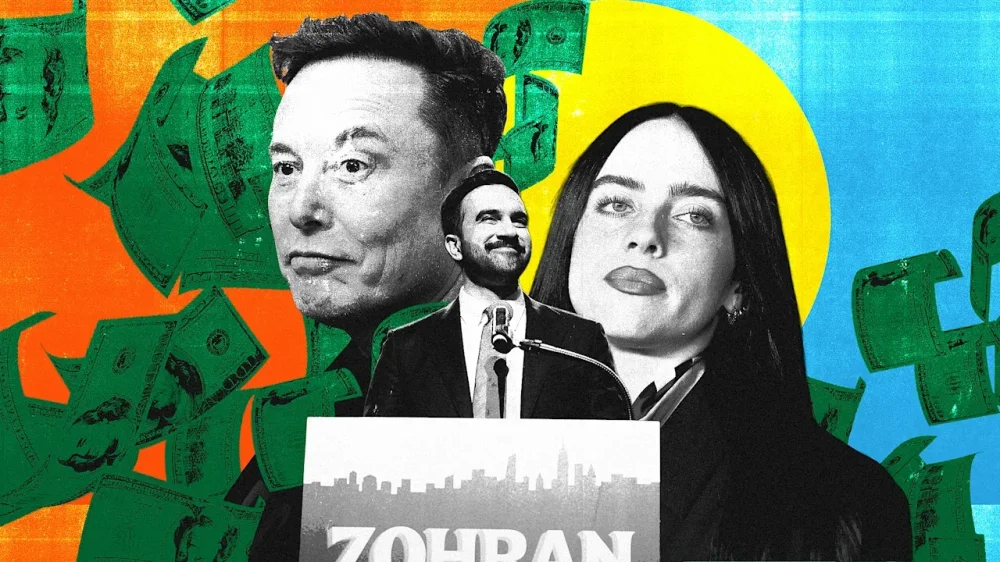
Americans have long ogled the rich, but the country’s widening wealth gap—and the billionaires fueling it—have been facing growing scrutiny. The news that Elon Musk is on track to be the world’s first trillionaire came the same week that a judge ordered the The President administration to fully fund food stamps, as 42 million Americans were left without the benefits they need to buy food. (The The President administration appealed that ruling.) New York City Mayor-elect Zohran Mamdani, a Democratic Socialist, made national headlines throughout his campaign for highlighting the affordability crisis in the city. Mamdani received support from figures like former labor secretary Robert Reich and Senator Bernie Sanders of Vermont, who have frequently criticized billionaires. Even singer Billie Eilish called out the ultra wealthy recently. “If you’re a billionaire, why are you a billionaire?” she said while announcing an $11.5 million donation (about 23% of her net worth), before urging billionaires to give away their money. A new Harris Poll shared exclusively with Fast Company highlights how everyday Americans are paying more attention to this inequality—and how they oscillate between admiring and admonishing the wealthy. An economic system that works best for the rich In the Americans & Billionaires survey, now in its third year, only 28% of respondents said that the current U.S. economic system works well for most people. Instead, 35% said it prioritizes the ultra-wealthy, and 36% said it offers opportunity—but not equally. Nearly three-quarters of Americans say wealth inequality is a serious national issue. Americans are also directly blaming billionaires for the financial struggles they face. Sixty-seven percent said billionaires are “creating more of an unfair society,” an eight-point increase from the 2024 survey. That sentiment was also higher among Gen Z and millennials, 72% of whom agreed with the statement compared to 62% of Gen X and baby boomers. Fifty-five percent of Americans said that billionaires “make it harder to achieve my American dream;” for Gen Z and millennials, the share was 65%. And they’re also generally over seeing extreme wealth on display: 74% of respondents say that billionaires are over-celebrated in U.S. culture. ‘The era of the untouchable billionaire is over’ When calling out inequality, people often point to the ways billionaires could help the rest of the world. Mamdani ran in part on taxing the wealthy in order to pay for free childcare and buses; others have noted how taxing the rich could fund universal healthcare, end world hunger, and address climate change. Americans broadly believe that the more wealth someone has, the more responsibility they have to the world, the Harris Poll found. Seventy-two percent of Americans agreed that billionaires have an “ethical responsibility” to address the world’s humanitarian crises—up 4 points from the year prior—and 69% said billionaires have a responsibility to better society, and should give back. Across all age groups, Harris Poll saw an increase in the percent of Americans who want a limit on wealth accumulation, compared to 2024. “The era of the untouchable billionaire is over,” Libby Rodney, chief strategy officer and futurist at The Harris Poll, says in a statement. “Americans want wealth to work harder, for society, not just for shareholders.” Still, they don’t seem to have much hope that billionaires will do so; 76% of respondents agreed with the statement that billionaires “are more concerned about protecting themselves than helping others.” One area billionaires are wading into, though, is politics. Billionaires like Bill Ackman spent millions opposing Mamdani’s race for mayor, and Musk notoriously enmeshed himself in the federal government this year. Americans are growing wary of that trend: 7 in 10 wish billionaires played a smaller role in U.S. politics. Americans want wealth for security These sentiments toward the rich don’t completely preclude people from wanting to join their ranks. Even though 76% of Americans admit that billionaires benefit from a broken system, six in ten still said that they want to become a billionaire one day. But it’s also clear that Americans aspire to wealth because it seems like one of the only ways to survive our continuous, mounting economic shocks. Two-thirds of Gen Z and millennials said that they aspire for extreme wealth not for success, but for security in an increasingly unstable economy. Overall, 52% of Americans agreed with the statement that “If I was a billionaire, then all my problems would be solved.” “Gen Z doesn’t want to be billionaires for bragging rights, they want safety in an uncertain economy,” Rodney says. “They’re rewriting the rules of ambition, turning wealth into a survival strategy, not a status symbol.” View the full article
-
If you’re exploring franchising opportunities, you’ll find several companies that stand out in the market. From The UPS Store‘s reliable courier services to Chick-fil-A‘s exceptional customer service, each brand offers unique advantages. Other notable options include Papa John’s and McDonald’s, which emphasize quality and innovation. As you consider your investment, it’s essential to weigh these factors carefully. Next, let’s look at the other franchises that could be a great fit for your business ambitions. Key Takeaways The UPS Store: Offers extensive support and a strong community presence, with startup costs ranging from $240,959 to $508,472. Chick-fil-A: Known for strong brand loyalty and operational support, requiring an investment of $582,000 to $2.25 million. Papa John’s: Features a competitive pizza market presence, with opening costs between $130,120 and $844,420 and dedicated training support. McDonald’s: Recognized for brand excellence and innovation, requiring a minimum cash requirement of $100,000 for franchisees. Taco Bell: Combines menu innovation and brand loyalty, with initial investments ranging from $575,600 to $3,370,000 and franchise fees between $25,000 and $45,000. The UPS Store If you’re considering a franchise opportunity, The UPS Store stands out as a leading option in the courier and local delivery services market. With nearly 5,000 locations across the U.S., it’s projected to grow at a CAGR of over 5% by 2023. As one of the best franchises to own in 2025, it offers startup costs ranging from $240,959 to $508,472 for traditional locations. The UPS Store provides extensive support, including help with location selection, permits, and equipment, along with web-based training programs. This franchise emphasizes a strong community presence, catering to both individual and business clients. If you’re seeking companies you can franchise or work from home franchise opportunities, The UPS Store proves to be a reliable choice. Chick-fil-A Chick-fil-A represents an appealing franchise opportunity for entrepreneurs interested in the fast-food industry. With a highly selective application process that can take 1-2 years, commitment is crucial. The franchise fee is $10,000, but total investments range from approximately $582,000 to $2.25 million, making it a significant financial commitment. Although you must pay royalty fees of 15% plus 50% of pretax profits, this supports marketing and operational initiatives. Chick-fil-A boasts over 2,000 locations and is known for its strong brand loyalty and customer service. The company provides extensive operational support, including training and resources, ensuring franchisees have the tools needed for success. This opportunity stands out among best part-time franchises and new franchise concepts, even as a potential work-from-home franchise option. Papa John’s When considering Papa John’s for your franchise investment, you’ll find a brand with a robust growth potential and a solid support system. Their extensive training programs equip franchisees with the necessary skills to succeed in a competitive market, whereas the company’s established presence with over 5,000 locations worldwide adds to its appeal. With ongoing opportunities for new franchisees, now might be a great time to explore what Papa John’s has to offer. Franchise Growth Potential With over 5,000 locations worldwide, Papa John’s showcases remarkable franchise growth potential, particularly in the competitive pizza delivery market. As one of the top 3 businesses with the most franchises in the world, it has a proven track record since the 1980s. The estimated opening cost for a franchise ranges from $130,120 to $844,420, making it accessible to various investors. With a one-time franchise fee of $25,000 and a 5% royalty fee on monthly net sales, you can benefit from a structured financial model. The brand’s commitment to quality and customer satisfaction fuels ongoing demand, positioning Papa John’s as one of the best home based franchises for those seeking stability and growth in the food industry. Support and Training Programs Beyond its impressive growth potential, Papa John’s stands out for its robust support and training programs designed for franchisees. As a new franchisee, you’ll benefit from extensive training that includes both classroom instruction and hands-on experience, ensuring you grasp the operational aspects effectively. You’ll also receive ongoing assistance from a dedicated support team, who’ll help you navigate marketing strategies and operational challenges. Collaboration is emphasized, allowing you to connect with other franchise owners and share valuable insights. In addition, you’ll have access to proprietary technology that streamlines operations and improves customer service. Regular updates and training sessions keep you informed about new menu items, promotions, and industry trends, helping you stay competitive in the constantly changing market. McDonald’s When you think about franchising, McDonald’s stands out because of its incredible brand recognition and innovative menu offerings. With over 40,000 locations globally, the brand attracts customers with its consistent quality and diverse food choices. As a franchisee, you’ll benefit from this strong brand presence during your access to a wide range of menu items that keep customers coming back. Brand Recognition Power As one of the most recognizable brands globally, McDonald’s has built its reputation through decades of consistent marketing and operational excellence. Since the 1950s, it’s led the fast-food industry, operating over 40,000 locations worldwide. The brand’s strong recognition stems from a global advertising strategy that emphasizes consistency and encourages customer loyalty, making it one of the most trusted names in fast food. McDonald’s consistently ranks among the top franchises owing to its robust sales performance and effective customer retention strategies. The franchise provides extensive training and support, enabling franchisees to uphold the brand’s high standards. With a minimum cash requirement of $100,000, McDonald’s appeals to a diverse range of investors, solidifying its status as a lucrative franchise opportunity. Innovative Menu Offerings McDonald’s consistently aims to keep its menu fresh and appealing by introducing innovative offerings that cater to diverse tastes and trends. The company regularly launches seasonal items and limited-time products, like the McRib and specialty coffee drinks, sparking customer interest. To improve local engagement, McDonald’s adapts its menu to regional preferences, featuring items such as the McAloo Tikki in India and the Teriyaki Burger in Japan. Acknowledging the shift in direction of healthier eating, McDonald’s has expanded its offerings to include salads, fruit, and oatmeal. Furthermore, the introduction of plant-based options, like the McPlant burger, showcases its commitment to sustainability. Through platforms like “Create Your Taste,” customers can customize their meals, further boosting satisfaction and engagement. 7-Eleven Eleven stands out as a swiftly growing franchise in the home services sector, particularly known for its plumbing and related services. Recognized among the Top 100 franchises, Eleven offers extensive support to franchisees, including thorough training programs and marketing assistance. This support is essential for ensuring your operational success. The business model has demonstrated strong sales performance, making it attractive for potential franchisees like you. With significant location growth potential, there’s robust market demand for its services in both urban and suburban areas. As a franchisee, you’ll benefit from being part of an established brand with a solid reputation, enhancing consumer trust and loyalty, which are critical elements for long-term success in the competitive home services market. Taco Bell Taco Bell ranks among the leading franchises in the fast-food sector, offering a unique menu that combines Mexican-inspired dishes with American tastes. As a subsidiary of Yum! Brands, it requires an initial investment ranging from $575,600 to $3,370,000, with a franchise fee between $25,000 and $45,000. The franchise has a royalty fee of 5.5% and an advertising royalty fee of 4.25%. To qualify, you’ll need a minimum net worth of $1.5 million and at least $750,000 in cash. Recognized as the best franchise in 2023 by Entrepreneur, Taco Bell has over 7,500 locations across the U.S. Its focus on menu innovation helps attract customers and maintain brand loyalty during offering extensive training and resources to support franchisee success. Firehouse Subs Firehouse Subs consistently ranks as a popular choice among franchise opportunities, particularly in the fast-casual dining segment. With over 1,200 locations across the U.S., this brand is notable for its commitment to supporting first responders through various community initiatives. If you’re considering franchising with Firehouse Subs, the initial franchise fee is $20,000, with total investments averaging around $412,731. You’ll also pay a royalty fee of 6% on sales, plus an advertising expenditure of 3% to 5%. Firehouse Subs emphasizes quality and excellent customer service, featuring a menu of hearty subs and a unique dining experience. Furthermore, through the Firehouse Subs Public Safety Foundation, franchisees contribute to local fire and police departments, enhancing community engagement. Frequently Asked Questions What Are the Best Businesses to Franchise? When considering the best businesses to franchise, look for established brands with strong market demand. Options like Mr. Rooter in home services, Chick-fil-A in fast food, and Dunkin’ in coffee are popular choices. Each franchise varies in investment requirements. For example, Chick-fil-A needs a lower franchise fee but a higher total investment, whereas Dunkin’ offers a substantial return on investment. Researching these opportunities can help you make an informed decision about franchise ownership. What Is the 7 Day Rule for Franchise? The 7 Day Rule for franchises requires that you receive the Franchise Disclosure Document (FDD) at least seven days before signing any agreements or making payments. This rule, enforced by the Federal Trade Commission (FTC), allows you time to review vital information about the franchise, such as financial performance and obligations. Compliance is crucial, as failure to adhere to this rule can lead to legal consequences for franchisors, including rescission of agreements. Which Company Is Best for Franchises? Choosing the best franchise depends on your goals, budget, and interests. For strong support, consider Mr. Rooter in home services. If you’re looking for a recognized brand, McDonald’s offers extensive reach but requires significant investment. Chick-fil-A is profitable but has a selective process. Dunkin’ provides a solid option in the coffee market, whereas Orangetheory Fitness caters to the growing fitness trend. Evaluate each based on your financial capacity and market preferences. What Is the #1 Franchise in the US? The #1 franchise in the U.S. is McDonald’s, known for its extensive global presence and brand loyalty. With over 40,000 locations, it has maintained a leading position since the 1950s. If you’re considering investing, the initial cost ranges from $1.4 million to $2.5 million, including a $45,000 franchise fee. Furthermore, you’ll pay a 4% royalty fee on gross sales, alongside an advertising royalty fee. This model emphasizes operational consistency and customer service. Conclusion In summary, franchising offers diverse opportunities with top companies like The UPS Store, Chick-fil-A, Papa John’s, McDonald’s, 7-Eleven, Taco Bell, and Firehouse Subs. Each franchise presents unique advantages, such as brand recognition and extensive support systems. By carefully evaluating your investment options and aligning your goals with a suitable franchise, you can establish a successful business. Whether you prefer fast food or courier services, these franchises can provide a solid foundation for your entrepreneurial expedition. Image via Google Gemini This article, "Top 7 Companies You Can Franchise" was first published on Small Business Trends View the full article
-
Some of my best ideas come to me when I’m exercising. At least I think they’re some of my best ideas; by the time I actually get a chance to write them down, I’ve often forgotten them. While you could argue that something I was unable to remember for an hour or so can’t be that great, still: we’ve all had things we wanted to remember, but couldn’t. So what can you do if you need to remember something important? Most memory-improvement techniques—like mnemonics, chunking, and building memory palaces—involve a fair amount of effort. But these simple strategies to improve your short-term memory and recall require almost no effort—and very little time. 1. Say it out loud We’ve all been around people who repeat things they’re learning out loud. Or just mouth the words. They look a little odd: smart people just file knowledge away. They don’t have to talk to themselves. Actually, smart people do talk to themselves. A study published Learning, Memory, and Cognition found that saying words out loud—or just mouthing them—makes them more distinctive by separating them from all the other words you’re thinking. In short, saying words out loud makes them different. Which makes them more memorable. So go ahead. When you need to remember something, say it aloud. Or mouth it to yourself. Your cerebral cortex will thank you for it. 2. Predict whether you will actually remember Sounds odd, I know. But a study published in the Canadian Journal of Experimental Psychology shows the simple act of asking yourself whether you will remember something significantly improves the odds that you will remember, in some cases by as much as 50%. That’s especially true for remembering things you want to do. Psychologists call them prospective memories: remembering to perform a planned action, or recall a planned intention, at some point in the future. Like remembering to praise an employee, email a customer, or implement a schedule change. Why this works is somewhat unclear. Maybe the act of predicting is a little like testing yourself; research shows that quizzing yourself is an extremely effective way to speed up the learning process. What is clear is that the act helps your hippocampus better form and index those episodic memories for later access. So if you want to remember to do something in the future, take a second and predict whether you will remember. Science says that act alone makes it more likely you will. 3. Rehearse for 40 seconds Memory consolidation is the process of transforming temporary memories into more stable, long-lasting memories. Even though the process of memory consolidation can be sped up, still: Storing a memory in a lasting way takes time. One way to increase the odds is to rehearse whatever you want to remember for 40 seconds. A study published in The Journal of Neuroscience found that a brief period of rehearsal—like replaying an event in your mind, going over what someone said in a meeting, or mentally mapping out a series of steps—makes it significantly more likely that you will remember what you rehearsed. As the researchers write, that “brief period of rehearsal has a huge effect on our ability to remember complex, lifelike events over periods of one to two weeks. We have also linked this rehearsal effect to processing in a particular part of the brain: the posterior cingulate.” Which should be long enough for you to actually do something with whatever you hope to remember. 4. Close your eyes for 2 minutes A study published in Nature Reviews Psychology found that “. . . even two minutes of rest with your eyes closed can improve memory, perhaps to the same degree as a full night of sleep.” Psychologists call it “offline waking rest.” In its purest form, offline waking rest can be closing your eyes and zoning out for a couple of minutes. But offline waking rest can also be daydreaming. Mind-wandering. Meditating. Basically turning your mind off for a minute or two. While mentally disconnecting doesn’t sound productive, when it comes to remembering more, it is: without those intermittent periods of lack of focus, memory consolidation doesn’t occur nearly as efficiently. So go ahead and zone out for a couple minutes. As the researchers write, “Moments of unoccupied rest should be recognized as a critical contributor to human waking cognitive functions rather than a waste of time.” Can’t beat that. View the full article
-
If you've booked a hotel through a platform like Booking.com or Expedia, beware any communication that directs you to confirm your payment details to hold your reservation. Threat actors are targeting the hospitality industry with a phishing campaign designed to steal from travelers. As outlined by security firm Sekoia.io and reported by The Hacker News, the scheme is referred to as "I Paid Twice" because hotel customers are eventually conned into handing over their banking information. Scammers contact guests via WhatsApp or email about their booking, saying that they need to verify their payment or risk cancellation. The link goes to a fake landing page that looks like Booking.com or Expedia, where victims are prompted to provide card information. This isn't the first scam to target Booking.com: Scammers have previously spoofed the site to spread malware directly to users via both fake CAPTCHAs and homograph attacks, which exploit similar characters in the URL to redirect to a malicious website. How the Booking.com ClickFix scam works This multi-step campaign actually begins when hackers target hotels themselves with ClickFix attacks, a type of social engineering attack designed to trick users into downloading malware via fake error messages or CAPTCHA forms. (I've covered a handful of ClickFix schemes, such as those spread via AI-generated instructional videos on TikTok and expired invite links on Discord.) The scam runs as follows: Hotel managers receive emails from compromised accounts with phishing links that redirect to a supposed reCAPTCHA page. This is the ClickFix component, as targets are instructed to complete the challenge to "ensure the security of your connection." A couple of redirects lead to the user copy and execute a PowerShell command that downloads a Remote Access Trojan (like PureRAT) to their device. Once the malware has been delivered, it allows threat actors remote access, including control of the mouse and keyboard, data exfiltration, command execution, file uploads and downloads, keylogging, and webcam and microphone capture. Hackers are then able to steal admin credentials to gain access to booking platforms and send the aforementioned phishing emails to hotel guests—or they can sell the information to other cybercriminals. Don't fall for the hotel booking scamYou can't control whether a hotel manager unwittingly hands over access to your booking information. But you can avoid further compromising your personal and financial data by staying vigilant to any unexpected communication about your reservation. A reputable hotel probably won't contact you via a booking platform (nor will the platform itself) to demand payment for holding a reservation you've already confirmed. This sense of urgency is meant to trick you into acting quickly, so if you're not sure what's going on, call the hotel directly using the number on their official website (not from the email or WhatsApp message). Don't click any links, and don't enter any information unless you have confirmed that you are on a legitimate booking platform or hotel website. View the full article
-
Like Gordon Brown’s ‘prudence for a purpose’, this chancellor should prioritise tax reform for transformationView the full article
-
As 2026 takes shape, the most successful leaders will adopt new tools with responsibility and vision while keeping the human side of shopping alive. These 10 tech trends in retail tech and AI are evolving, transforming how brands design, distribute, and deliver experiences. These are not distant forecasts, but happening in real time across retailers, marketplaces, and consumer ecosystems. 1. Predictive intent engines Reactive personalization is being replaced by predictive intent engines. Instead of waiting for a customer to browse, AI anticipates the customer’s next wants based on contextual data like weather, life events, and even local cultural moments. For example, as outdoor searches tick upward in specific regions, retailers surface camping gear. The upside is deeper relevance. As with every trend, there are risks. Here, if the timing is too perfect, the relevance can feel intrusive to the customer. 2. Retail copilots for associates When I talk to retail teams, many describe how AI copilots are becoming the new work partner for associates. In practice, staff use smart glasses and mobile assistants to feed real-time product data, customer history, or upsell suggestions. Frontline employees transform from reactive clerks to proactive advisors. The challenge is keeping interactions authentic. Customers want genuine conversations, not AI scripts delivered through a human face. 3. Algorithmic supply webs The supply chain is no longer a straight line but a web of constantly reconfiguring nodes. Retailers tell me their systems now simulate thousands of scenarios daily—rerouting orders, shifting suppliers, or adjusting transportation paths on the fly. I see this trend especially in grocery and fashion, where volatility is high. Supply webs provide resilience, but also create a transparency challenge. Shoppers and regulators will want to know how these algorithmic choices affect workers and sustainability. 4. Immersive brand layers Immersive storytelling is moving from pilot projects to mainstream adoption. Augmented reality is layered into packaging, storefronts, and mobile apps. One apparel brand I follow lets customers scan a tag to see the product’s journey from fiber to fashion show. Another uses AR mirrors to project outfit combinations in the store. The brand layers transform shopping into a multimedia experience. The challenge is keeping it purposeful rather than gimmicky. 5. Microfactories near the customer More retailers are experimenting with localized, AI-driven microfactories. These factories can 3D-print fashion accessories, produce limited-run beauty items, or assemble electronics close to demand centers. I recently saw a footwear brand offering near-instant customization at an urban hub, with shoes ready within days. The opportunity is speed and personalization. The challenge is cost. Microfactories remain expensive compared to global mass production. 6. Real-time sustainability scores Retailers are making sustainability metrics visible at the shelf or checkout. Shoppers now see carbon impact scores, packaging grades, or ethical sourcing flags. AI crunches supplier and logistics data to make this possible. One grocer is piloting real-time sustainability dashboards in an app, so shoppers can compare two items not just by price but by footprint. The opportunity is radical transparency. The challenge is to ensure credible numbers and avoid greenwashing in a new format. 7. Autonomous merchandising systems Conversations with merchandising leaders reveal how manual planning cycles are being replaced by AI-driven systems making thousands of small decisions daily. Platforms decide which colors to stock by neighborhood, which SKUs to pull from digital shelves, or how to rotate assortments dynamically. The benefit is responsiveness. The risk involves blind spots: Without human oversight, algorithms can miss cultural nuances or local contexts. 8. Neural commerce platforms Commerce is dissolving into everyday life through connected devices. Smart fridges reorder staples. Cars let drivers voice-order coffee and have it waiting at the next stop. Voice assistants anticipate weekly needs without prompting. Retail is becoming neural, with systems firing across networks without friction. The opportunity is effortless convenience. The challenge is maintaining customer agency—retailers must ensure that shoppers feel in control of purchases instead of letting automation decide entirely. 9. Data collaboratives across competitors Retailers are starting to collaborate on data despite fierce competition. Shared, anonymized pools of information strengthen forecasting, reduce waste, and help optimize logistics. For example, several mid-sized fashion brands are joining forces to track demand signals and cut excess inventory. The opportunity is collective intelligence. The challenge is trust—deciding what to share and how to govern these collaboratives fairly. 10. Leadership as technology stewardship The last trend isn’t a tool but a leadership evolution. Executives are now judged by how they steward technology responsibly. I observe boards asking harder questions: How are algorithms monitored for bias? How is customer privacy respected? How is staff retrained for AI collaboration? There’s an opportunity to build brands trusted as responsible innovators. The challenge is balancing the speed of adoption with careful stewardship in a space where technology is evolving faster than regulation. The future: 2026 and beyond When I put these trends together, the picture is clear: Retail in 2026 is not just using technology, it is becoming technology. Predictive engines anticipate demand, copilots empower staff, immersive layers engage customers, and neural commerce embeds shopping into everyday life. But the deeper story is about responsibility. Customers demand transparency, regulators demand accountability, and employees demand clarity about their role in AI-shaped workplaces. The retailers who win will not be the ones with the flashiest tech but the ones who use it thoughtfully, balancing automation with humanity. A new playbook is emerging that will anticipate needs, empower people, embed transparency, and lead with stewardship. Those who follow it will not just adapt to the future of retail; they will shape it. Charisma Glassman is the group vice president and global head of retail applied advisory at Genpact. View the full article
-
Yields were higher by as much as three basis points, led by tenors more sensitive to changes in Fed policy. View the full article
-
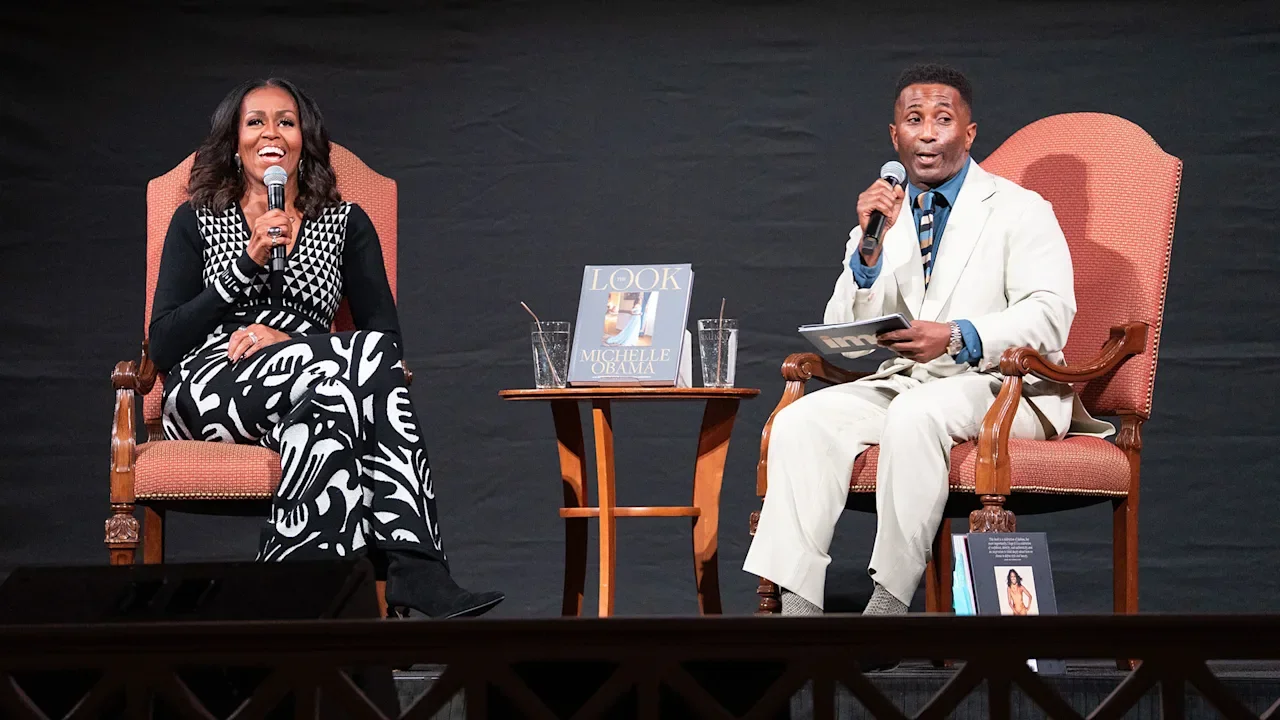
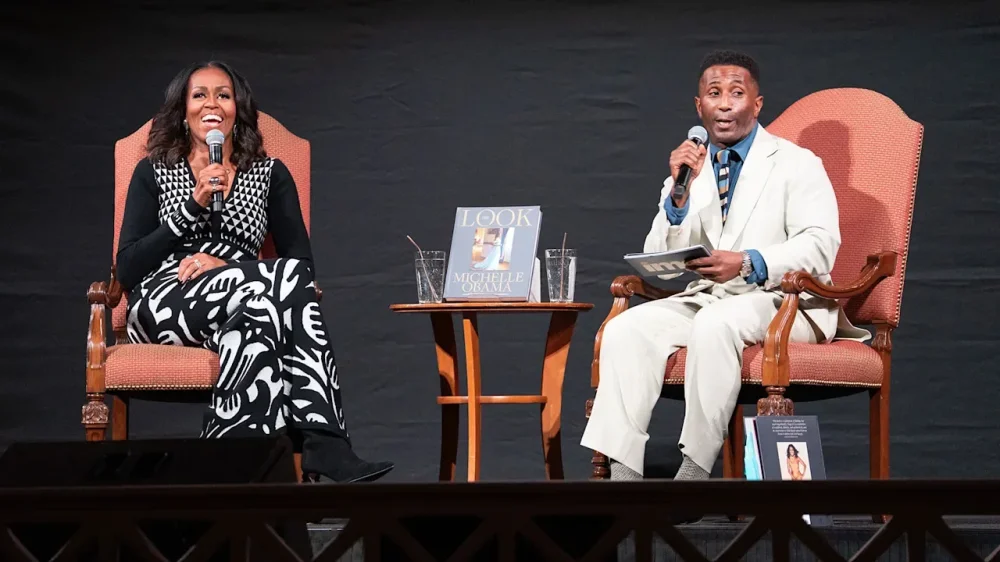
On any day during her eight years as First Lady of the United States, Michelle Obama said she could go from giving a speech to meeting with a counterpart from another country to digging in her vegetable garden with groups of schoolchildren. And her clothes had to be ready for that. There was too much else to do, including raising daughters Sasha and Malia, and she said she didn’t have time to obsess over what she was wearing. “I was concerned about, ‘Can I hug somebody in it? Will it get dirty?'” she said Wednesday night during a moderated conversation about her style choices dating back to growing up on the South Side of Chicago to when she found herself in the national spotlight as the first Black woman to serve in the role. “I was the kind of First Lady that there was no telling what I would do.” Obama would become one of the most-watched women in the world, for what she said and did, but also for what she wore. She chronicled her fashion, hair and makeup journey in her newest book, “The Look,” written with her longtime stylist Meredith Koop and published earlier this month. As First Lady, she was well-known for her athleticism and caught a football from an NFL player, played soccer with David Beckham, broke a Guinness World Record for jumping jacks and did pushups with Archbishop Desmond Tutu of South Africa. She wanted her clothes to be welcoming as well as versatile. “The thing about clothes that I find is that they can welcome people in or they can keep people away, and if you’re so put together and so precious and things are so crisp and the pin is so big, you know, it can just tell people, ‘Don’t touch me,'” she said. She said she wouldn’t wear white to events with rope lines in case someone wanted a hug. “I’m not going to push somebody away when they need something from me, and I’m not going to let the clothes get in the way of that,” Obama said. Here’s what she said about a few of her notable fashion choices: Her gown for Obama’s first inauguration The white, one-shoulder chiffon gown was designed by Jason Wu, then an unknown 26-year-old who was born in Taiwan. But when she stepped out at the inaugural ball wearing the gown, the moment changed Wu’s life. And that was by design, she said. “We were beginning to realize everything we did sent a message,” Obama said, speaking of herself and her husband, former President Barack Obama. “So that’s what we were trying to do with the choices we made, to change lives.” She would continue to help launch the careers of other up-and-coming designers by wearing their creations. Chain mail state dinner gown Obama wore the rose gold gown by Versace for the Obama administration’s final state dinner, for Italian Prime Minister Matteo Renzi in October 2016. “So that was a kind of a, ‘I don’t care’ dress,” she said of the shimmery, one-armed gown. “I put that on. I was like, ‘This is sexy.’ It’s the last one,” she said, meaning their final state dinner. “All of my choices, ultimately, are what is beautiful — and what looks beautiful on.” Pantsuit worn to Joe Biden’s inauguration “I was really in practical mode,” Obama said, explaining why she chose the maroon ensemble by Sergio Hudson with a flowing, floor-length coat that she wore unbuttoned, exposing the belt around her waist with a big, round gold-toned buckle. Her boots had a low heel. “The sitting president was trying to convince us that Jan. 6 was just a peaceful protest,” she said. The inauguration ceremony at the Capitol was held two weeks after the Jan. 6, 2021, riot there by supporters of President Donald The President who had sought to overturn Biden’s victory. She said she had been thinking about the possibility of having to run if something else had happened that day. “I wanted to be able to move. I wanted to be ready,” she said. But she and her team “had no idea” the outfit “was going to break the internet,” she said. White House East Wing Obama also spoke about the East Wing, the traditional base of operations for first ladies that The President last month tore down to make room for a ballroom he’s long desired. Obama described the East Wing as a joyful place that she remembers as full of apples, children, puppies and laughter, in contrast to the West Wing, which dealt with “horrible things.” It was where she worked on various initiatives that ranged from combating childhood obesity to rallying the country around military families to encouraging developing countries to let girls go to school. She said she and her husband never thought of the White House as “our house.” They saw themselves more as caretakers, and there was work to do in the mansion. “But every president has the right to do what they want in that house, so that’s why we’ve got to be clear on who we let in,” Obama said. —Darlene Superville, Associated Press View the full article
-
Small business owners might feel a twinge of unease as the NFIB Small Business Optimism Index shows a slight decline for October, moving down 0.6 points to 98.2. While this figure remains above the long-term average of 98, it highlights the challenges that businesses face, particularly in navigating labor shortages and fluctuating sales. This ongoing uncertainty necessitates a closer examination of the current landscape. Bill Dunkelberg, NFIB’s Chief Economist, commented on the findings, stating, “Optimism among small businesses declined slightly in October as owners report lower sales and reduced profits.” His insights reveal a significant concern for owners: Despite a desire to hire, finding qualified applicants remains a notable hurdle. The October report also revealed a notable decrease in the Uncertainty Index, which fell 12 points to 88, marking its lowest point this year. This shift hints at a more predictable business environment but underscores the pressing issues that many small business owners still grapple with. Key findings from the report deliver valuable insights into small business operations: Job Openings: A steady 32% of owners reported unfilled job openings for the second consecutive month. Before this, similar levels hadn’t been seen since December 2020. Labor Quality Concerns: An alarmingly high 27% of small business owners cited labor quality as their top concern, a significant increase from previous months, which emphasizes a challenging hiring environment. Sales Trends: A net negative 13% of owners reported higher nominal sales over the past three months, demonstrating a downturn in sales performance. Profit Trends: Reports of positive profit trends fell markedly, contributing to a net negative 25%—the most considerable decline in this category and a vital factor in the drop of the Optimism Index. Price Adjustments: In response to changing market conditions, the percentages of owners planning to increase prices have declined slightly, though inflationary pressures remain evident in the market. Small business owners can leverage the insights from this report to adapt their strategies. For instance, addressing labor quality could involve targeted recruitment or training programs. Additionally, understanding current sales trends will be crucial for adjusting inventory and operational planning. Setting realistic price adjustments despite inflation can also help maintain competitiveness without alienating customers. However, the current atmosphere presents challenges that owners must consider. The difficulty in attracting qualified applicants not only stifles growth but also places increased burdens on existing staff. Small businesses often operate on tight margins, meaning any dips in sales or profits can significantly impact their long-term viability. Moreover, navigating the balance between price increases and customer retention will require careful strategizing. With 60% of business owners indicating that supply chain disruptions affect operations, maintaining clear communication with suppliers and customers will be critical. To foster a deeper understanding of these dynamics, the NFIB has launched a new podcast titled “Small Business by the Numbers,” featuring discussions around economic conditions impacting small businesses. Co-hosts Holly Wade and Peter Hansen delve into data and stories relevant to the small business economy, providing a platform for owners to explore solutions and strategies collaboratively. While the dip in the NFIB Small Business Optimism Index may raise concerns, it also serves as a reminder of the resilience and adaptability that characterize small business owners. The insights from the October report offer actionable data that owners can utilize to navigate challenges while seizing opportunities for growth amidst uncertainty. For further information and to explore the full findings, you can visit the original report here. Image via Google Gemini This article, "Small Business Optimism Dips as Labor Quality Tops Concerns" was first published on Small Business Trends View the full article
-
Hedge fund’s Innsworth arm claims property site overcharges estate agents in £1bn caseView the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. The 65-inch Hisense U65QF TV is now selling for $547.99, marked down from $847.99, and price trackers confirm this is its lowest recorded price. 65" Hisense U6 Series 4K Mini-LED QLED Smart TV (2025 Model) $547.99 at Amazon $847.99 Save $300.00 Get Deal Get Deal $547.99 at Amazon $847.99 Save $300.00 It’s a solid drop for a TV that is also PCMag’s Editors’ Choice pick, praised in an "outstanding" review as “a bright, beautiful TV at a budget-friendly price.” That summary fits. The TV’s mini-LED backlight is the first thing that stands out. It gets bright (crossing the 1,000-nit mark), which you feel immediately when you watch something mastered for Dolby Vision or HDR10. Scenes with high contrast, like night shots filled with neon signs, look sharp and bold, though you’ll notice some light bloom in those high-contrast edges. Still, for a 65-inch model at this price, the picture feels more vibrant than last year’s Hisense U6N, which already had a solid reputation. If you’re looking for something bigger, the 75-inch and 85-inch versions are also priced under $1,000 at the moment. The U65QF handles motion in a way that makes day-to-day viewing feel easy, whether you’re watching a late-night movie or catching a weekend match. The 144Hz refresh rate keeps fast scenes clean, so car chases, quick pans, and rapid game replays don’t break into blur. That same responsiveness carries into gaming. AMD FreeSync Premium Pro keeps the picture stable when frame rates dip, and the input lag—4.6ms at 1080p/120 and 13.1ms at 4K/60—helps the TV respond as soon as you do. The panel’s brightness also plays a big role. Highlights stay strong without washing out shadows, and the screen holds its color well even when you’re off to the side, giving it better viewing angles than you’d expect from a budget TV. Hisense does shift direction on the software side, moving from Google TV to Amazon’s Fire TV, and that change shapes the experience noticeably. Fire TV is familiar, smooth, and supports every major streaming app, but the interface leans heavily on ads. The platform still covers the basics well, offering AirPlay for Apple devices, though the lack of Google Cast means Android users lose an easy streaming option they may be used to. Alexa remains part of the setup and handles voice commands without trouble, but the absence of hands-free microphones means you’ll still rely on the remote’s mic button each time. It’s a workable setup, just not as flexible as before. Our Best Editor-Vetted Tech Deals Right Now Apple AirPods 4 Wireless Earbuds — $84.99 (List Price $129.00) Apple iPad 11" 128GB A16 WiFi Tablet (Blue, 2025) — $319.35 (List Price $349.00) Shark AV2501AE AI XL Hepa- Safe Self-Emptying Base Robot Vacuum — $294.99 (List Price $649.99) Apple Watch Series 10 — $309.99 (List Price $429.00) Google Pixel 9 128GB Unlocked 6.9" OLED Smartphone (Obsidian) — $544.98 (List Price $799.00) Amazon Fire HD 10 (2023) — $69.99 (List Price $139.99) Sony WH-1000XM5 — $328.00 (List Price $399.99) Blink Outdoor 4 1080p Wireless Security Camera (5-Pack) — $159.99 (List Price $399.99) Ring Floodlight Cam Wired Plus 1080p Security Camera (White) — $99.99 (List Price $179.99) Amazon Fire TV Stick 4K Plus — $24.99 (List Price $49.99) Deals are selected by our commerce team View the full article
-
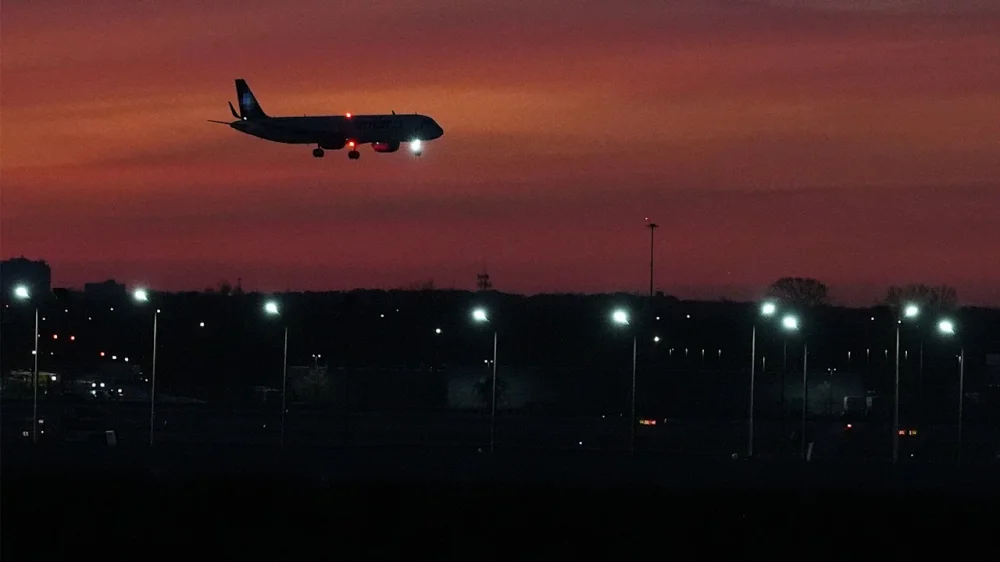
Flight reductions at 40 major U.S. airports will remain at 6% instead of rising to 10% by the end of the week because more air traffic controllers are coming to work, officials said Wednesday. The announcement was made as Congress took steps to end the longest government shutdown in history. Not long after, President Donald The President signed a government funding bill to end the closure. The flight cuts were implemented last week as more air traffic controllers were calling out of work, citing stress and the need to take on second jobs — leaving more control towers and facilities short-staffed. Air traffic controllers missed two paychecks during the impasse. The Department of Transportation said the flight reduction decision was made on recommendations from the Federal Aviation Administration’s safety team, after a “rapid decline” in controller callouts. The 6% limit will stay in place while officials assess whether the air traffic system can safely return to normal operations, Transportation Secretary Sean Duffy said, although he did not provide a timeline Wednesday. “If the FAA safety team determines the trend lines are moving in the right direction, we’ll put forward a path to resume normal operations,” Duffy said in a statement. Duffy and FAA Administrator Bryan Bedford said Wednesday that safety remains their top priority and that all decisions will be guided by data. Delta struck an optimistic note about how much longer flight reductions would continue, saying in a statement the airline looked forward to bringing its “operation back to full capacity over the next few days.” Since the restrictions took effect last Friday, more than 10,100 flights have been canceled, according to the flight tracking site FlightAware. The FAA originally planned to ramp up flight cuts from 4% to 10% at the 40 airports. The FAA said that worrisome safety data showed flight reductions were needed to ease pressure on the aviation system and help manage worsening staffing shortages at its air traffic control facilities as flight disruptions began to pile up. Duffy has declined to share the specific safety data that prompted the flight cuts. But at a news conference Tuesday at Chicago’s O’Hare International Airport, he cited reports of planes getting too close in the air, more runway incursions and pilot concerns about controllers’ responses. The FAA’s list of 40 airports spans more than two dozen states and includes large hubs such as New York, Atlanta, Los Angeles and Chicago. The order requires all commercial airlines to make cuts at those airports. Airlines for America, the trade group of U.S. airlines, posted on social media that it was grateful for the funding bill. It said reopening the government would allow U.S. airlines to restore operations ahead of the Thanksgiving holiday which is in about two weeks. How long it will take for the aviation system to stabilize is unclear. The flight restrictions upended airline operations in just a matter of days. Many planes were rerouted and aren’t where they’re supposed to be. Airlines for America said earlier Wednesday that there would be residual effects for days. Eric Chaffee, a Case Western Reserve professor who studies risk management, says airlines face complex hurdles, including rebuilding flight schedules that were planned months in advance. Airline and hotel trade groups had earlier Wednesday urged the House to act quickly to end the shutdown, warning of potential holiday travel chaos. Flight cuts disrupted other flights and crews, leading to more cancelations than the FAA required at first. The impact was worsened by unexpected controller shortages over the weekend and severe weather. The CEO of the U.S. Travel Association said essential federal workers like air traffic controllers and Transportation Security Administration workers must be paid if “Congress ever goes down this foolish path again” and there is a shutdown. “America cannot afford another self-inflicted crisis that threatens the systems millions rely on every day,” Geoff Freeman said in a statement. Associated Press writer Audrey McAvoy contributed to this report. —Rio Yamat, AP Airlines and Travel Writer View the full article
-
These attempts to remove legit items from credit files are made with the aim of at least temporarily boosting the credit score in order to get a loan. View the full article
-
Creating a winning sales strategy is crucial for aligning your sales efforts with your business goals. It starts with defining clear, measurable objectives and identifying your target customers through effective segmentation. By selecting the right selling channels and building a streamlined sales process, you’ll guarantee a steady flow of leads. Monitoring your pipeline health and adjusting your approach based on data-driven insights will keep you agile. But what specific steps can you take to implement this strategy effectively? Key Takeaways Set SMART sales goals that align with business objectives and adjust them based on performance and market changes. Identify and segment target customers to tailor strategies to specific industries and buyer personas. Implement effective outreach and follow-up strategies, leveraging data analytics to optimize lead engagement. Regularly monitor sales pipeline health through KPIs and CRM tools for timely performance assessments. Foster a culture of continuous improvement by adapting strategies based on data-driven insights and market trends. What Is a Sales Strategy? A sales strategy is fundamentally a roadmap that guides your business toward achieving its revenue goals. It’s a detailed plan outlining how you’ll identify target customers and the ideal selling channels to reach them. To develop a sales strategy, you must analyze your market and understand customer behavior, which will help you tailor your approach. This structured method guarantees your sales team aligns their efforts with your overall business goals. In addition, a successful strategy requires continual adaptation to market changes and regular evaluation of performance data to spot trends. By doing this, you improve efficiency, navigate resource limitations, and maintain consistent messaging. In the end, a well-defined sales strategy is vital for building lasting customer relationships and maximizing sales opportunities. Importance of Having a Sales Strategy Clarity in sales strategy is vital for any business aiming to succeed in a competitive market. A well-defined sales strategy serves as a roadmap, aligning your sales team toward common goals and ensuring everyone understands their roles in achieving revenue targets. It helps you identify potential risks and sales trends during deal progression, allowing you to address issues proactively and seize opportunities. By creating clear guidelines for the sales process, a structured strategy boosts efficiency, enabling your team to focus on high-impact activities and prioritize leads effectively. Companies with a solid sales strategy can better navigate resource constraints and high-pressure situations, in the end improving overall sales performance. Regularly reviewing and adapting your strategy is fundamental for maintaining competitiveness and optimizing revenue generation. Steps to Build a Winning Sales Strategy Building a winning sales strategy involves several key steps that can greatly improve your sales performance. First, define clear sales goals using the SMART criteria—make them specific, measurable, achievable, relevant, and time-bound. Next, conduct thorough market research to identify your target audience, creating detailed buyer personas that highlight their pain points and preferences. Establish a structured sales process with defined steps to guide prospects from initial contact to closing the deal, ensuring consistency across your sales team. Implement a CRM system to track customer interactions and monitor sales performance, analyzing key performance indicators (KPIs) for continuous improvement. Finally, regularly review and adjust your sales strategy based on performance data and market changes to maintain adaptability and optimize results. Define Your Sales Goals To effectively define your sales goals, start by setting clear revenue targets that align with your company’s overall objectives. Analyze your product focus and past sales data to guarantee your goals are realistic and achievable, as this will guide your efforts more effectively. Set Revenue Targets Setting revenue targets is crucial for directing your sales efforts and measuring success. Start by analyzing past sales data to establish clear targets that align with your overall business objectives and current market conditions. Use the SMART criteria—Specific, Measurable, Achievable, Relevant, and Time-bound—to create well-defined sales goals that guide your team. To determine the number of deals needed to meet your revenue goals, divide the target revenue by the average deal size, which helps set actionable benchmarks. Engage cross-departmental stakeholders in the goal-setting process to guarantee alignment and support. Finally, regularly review and adjust your revenue targets based on performance data and market shifts to stay agile and responsive in a changing business environment. Analyze Product Focus Analyzing your product focus is essential for defining effective sales goals that drive growth. Start by setting specific revenue targets that align with your overall business objectives, like aiming for a 30% year-over-year growth rate. Next, evaluate your product portfolio to determine which offerings to prioritize based on market demand and profitability. Understand average deal sizes and conversion rates to calculate the number of deals needed to meet those revenue targets realistically. Furthermore, identify your target customers, ensuring your sales efforts focus on those most likely to convert. Finally, establish the best selling channels, whether direct sales or partnerships, to maximize your reach and optimize your sales strategies based on customer preferences. Determine Your Target Customers How do you effectively determine your target customers? Start by segmenting them based on size; differentiate between large corporations and small businesses to tailor your sales approaches. Conduct thorough market research to grasp regional needs and preferences, especially if you’re eyeing global expansion. This alignment helps guarantee your offerings meet specific demands. Focus on particular industries, such as manufacturing or healthcare, where you can build expertise and provide specialized solutions. Utilize customer segmentation to refine your sales strategies, making certain your messaging resonates with each identified group. Finally, analyze purchasing behaviors and pain points to create detailed buyer personas, which will personalize your sales approach and address the unique needs of your target customers effectively. Select Your Selling Channels Which selling channels will best connect you with your target customers? Start by researching your competitors and comprehending customer buying preferences. This will help you identify the most effective channels for your products or services. For complex offerings, consider direct sales to provide personalized engagement, ensuring your sales team is trained in industry-specific language. A multi-channel approach is often beneficial; combining online, offline, and social media platforms can effectively reach diverse customer segments. Utilize data analytics to gauge each channel’s performance, enabling you to make informed decisions on resource allocation. Finally, regularly evaluate your channels based on customer feedback and market trends to stay competitive and relevant in a constantly changing environment. Build an Efficient Sales Process Building an efficient sales process is critical for guiding your sales team from the initial contact with potential customers to successfully closing deals. Start by establishing a clear sales process with defined steps, ensuring consistency across your team. Identify key milestones for each stage, such as lead qualification, needs assessment, proposal presentation, and closing, to effectively track progress. Tailor the process to fit different customer types and their preferred selling channels, which improves engagement and increases conversion likelihood. Don’t forget to include post-sales activities like follow-up communication and customer satisfaction checks to nurture ongoing relationships. Finally, regularly review and refine your sales process based on performance data and feedback, adapting to market changes and evolving customer needs. Fill Your Sales Pipeline With Leads Filling your sales pipeline with leads is vital for meeting revenue goals and driving business growth. To achieve this, start by calculating the number of prospects needed based on your revenue goals and average deal size. Then, utilize a mix of strategies to generate leads, such as: Attending industry conferences and networking events Implementing targeted outreach and follow-up strategies Leveraging data analytics to identify high-quality lead sources Monitoring lead generation activities to adjust your strategies effectively Monitor and Adjust Your Sales Strategy To effectively monitor and adjust your sales strategy, it’s crucial to regularly assess the health of your sales pipeline. Analyze key performance indicators (KPIs) like conversion rates and lead response times to pinpoint areas needing improvement. Utilizing CRM systems allows you to track sales performance metrics in real-time, enabling you to make quick adjustments based on data-driven insights. Conduct monthly or quarterly reviews to identify trends in customer behavior, which can help you proactively adjust your strategy to align with market shifts. Be ready to pivot your approach depending on market conditions, and gather continuous feedback from your sales team and customers to refine your sales processes, ensuring they remain effective and relevant to your target audience’s needs. Frequently Asked Questions What Are the 7 Steps of a Sales Strategy? To create an effective sales strategy, you’ll want to follow these seven steps: first, define your sales goals using the SMART framework. Next, analyze your target audience to build detailed buyer personas. Then, establish a clear sales process with defined steps. Implement lead generation strategies to fill your pipeline, and regularly review your performance metrics. Finally, adjust your strategy based on market changes, ensuring continuous improvement within your team. What Is the 3-3-3 Rule in Sales? The 3-3-3 Rule in sales is a systematic approach aimed at maximizing your chances of converting prospects. It suggests you make three calls, send three follow-up emails, and engage in three social media interactions with each lead. This method promotes consistent engagement across different channels, ensuring you reach potential customers effectively. What Are the 4 P’s of Sales Strategy? The 4 P’s of sales strategy are Product, Price, Place, and Promotion. You need to guarantee your product meets customer needs, reflecting market demand. Setting the right price involves balancing competitiveness and profitability based on perceived value. Place focuses on distribution channels that improve accessibility for your target audience. Finally, Promotion encompasses the marketing tactics that generate awareness and interest, driving sales through effective communication and messaging strategies. How Do You Develop a Sales Strategy? To develop a sales strategy, start by setting clear sales goals using the SMART framework—specific, measurable, achievable, relevant, and time-bound. Conduct market research to identify your target audience and understand their needs. Create an ideal customer profile to focus your efforts on high-value prospects. Establish a structured sales process with defined steps, and regularly analyze key performance indicators to adapt your strategy based on insights and market changes, ensuring continuous improvement. Conclusion In summary, developing a winning sales strategy requires a structured approach that aligns your sales efforts with business objectives. By setting SMART goals, identifying your target customers, and selecting appropriate selling channels, you can create an effective sales process. Continuously monitor your pipeline and adjust your strategy based on data-driven insights to guarantee ongoing success. Following these steps will improve your ability to adapt to market changes and ultimately drive revenue growth for your business. Image via Google Gemini This article, "Develop a Winning Sales Strategy: A Step-by-Step Guide" was first published on Small Business Trends View the full article
-
I'm a former Android-Mac hybrid user. Laugh all you want—we exist. I enjoy having a polished operating system on my computer and an endlessly hackable operating system on my phone, and the combination of Mac and Android gave me all of that. I only stopped using Android alongside my Mac a couple years ago, mostly because an iPhone SE was cheaper than most mid-range Android options at the time. When I think about switching back, though, I realize how much I'll miss the integrations. Using a Mac and an iPhone gives you access to all kinds of tricks. Among the ones I use the most are the shared notifications, the syncing clipboard, and the easy ways to sync files. There's also the ability to control your iPhone from your Mac. Android users can't do any of this on a Mac. That's where AirSync comes in. The open source application, built by Sri Lanka based developer Sameera Sandakelum, integrates Android devices with macOS in all kinds of ways. Android notifications show up on your Mac. You can sync your clipboard. It's also easy to send files from Android to the Downloads folder on your Mac, or vice versa. And with a little bit of setup, you can even take control of your Android device from the comfort of your Mac. Credit: Justin Pot Getting started is straightforward. You need to download the app for Android and macOS and install them. You will be prompted on both devices to enable certain permissions, after which you can connect your devices to each other by scanning a QR code. (It's worth noting that you can only connect devices that are on the same wifi network.) After that, you should start seeing Android notifications on your Mac—they'll show up in the native Mac notifications, or you can review existing ones in the app itself. You can even trigger buttons, allowing you to do things like respond to text messages from the notifications on your Mac. Items copied on your clipboard on one device will sync to the other. And you will see controls for the media currently playing on your Mac on the lock screen of your Android device. It has lot of nice touches, and you can go a bit further by paying for AirSync+, which costs either $2.49/month or $50 one time. This paid version of the application lets you take control of your Android device, similar to iPhone Mirroring. I tried this feature out and enjoyed it, though you can set this up yourself using Scrcpy for free. Credit: Justin Pot Other features in the paid version include controlling your Android's music from your Mac, opening websites open on one device from another, and custom app icons. Even without these paid features, though, Airsync makes it a little bit easier to be a Mac/Android person. Not missing notifications, easier file sharing, and clipboard syncing are all big quality of life improvements, so check this app out if you're tired of macOS and Android not playing nicely together. View the full article
-
Forty-three days later, the U.S. government shutdown has come to an end. While it wreaked havoc on government services, flights, and paychecks for federal workers, stock market appears to have come through it unscathed. In fact, by some measures, it improved. The Dow Jones Industrial Average reached 46,441.10 on the first day of the shutdown. Since October 1, it has grown over 4%, reaching over 48,000 for the first time on Wednesday, November 12. While the record number came as the shutdown’s end became a sure thing, the Dow had continued to rise throughout the period. The S&P 500 also followed a mostly upward trajectory throughout the shutdown. It opened at 6,664.92 on October 1 and closed at 6,850.92 on Wednesday. The tech-heavy Nasdaq Composite also grew about 4% during the shutdown period, even despite concerns of an AI bubble that had dinged shares of major tech companies like Nvidia and Palantir earlier this month. How do government shutdowns typically impact stock markets? Historically, shutdowns have not had a significant effect on the markets. “Government shutdowns tend to be high profile though low-impact market events,” Truist, a financial company, reported ahead ahead of the most recent shutdown. “In the previous 20 shutdowns, there has been almost no change, on average, for the S&P 500, while it has been in positive territory 50% of the time during the shutdown period.” As the shutdown began, Bloomberg shared data demonstrating the S&P 500’s seemingly unrelated growth and decline during shutdowns. It further reported on the impact of what some experts see as a 16-year-long bull run in U.S. markets. Both Bloomberg and, more recently, MarketWatch point to historically elevated stocks that have created what many see as inflated valuations for quite a few companies, including many in the tech industry. View the full article