Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
Conservatives accuse Prime Minister Sir Keir Starmer of misleading parliamentView the full article
-
Since opening in Silicon Valley in 2019, NTT Research has operated as a long-horizon science lab, a dedicated arm of Japan’s telecommunications giant NTT Group, which invests more than $3 billion annually in global R&D. Now in its seventh year, the lab was built as a research subsidiary insulated from quarterly pressure and product roadmaps. Unlike startups or typical corporate innovation teams, NTT Research is a wholly owned entity focused on seeding advances in computing, security, and healthcare that can later fold into NTT’s global infrastructure and enterprise services. Many of these efforts take five to fifteen years to approach commercialization, a timeline now under strain as AI compresses development cycles and markets reward speed. The question has sharpened: what is the value of discovery if it never leaves the lab? NTT Research is trying to answer that with what it calls “NTT Research 2.0,” a dual-engine model that maintains long-horizon science while pushing discoveries toward market. President and CEO Kazu Gomi frames the shift as inevitable. At its center is Scale Academy, a new incubator designed to spin out companies from lab breakthroughs. Its first test case, SaltGrain, is a zero-trust data security platform built on attribute-based encryption, a concept first proposed in 2004 that has largely remained theoretical. The effort reflects a broader challenge: turning deep research into viable companies without losing the rigor that produced it in the first place. In a conversation with Fast Company, Gomi discusses how to operationalize advanced science, what sets Scale Academy apart from traditional incubators, and how to judge when emerging technologies are ready for the real world. This conversation has been edited for length and clarity. NTT Research has long operated on a 5–15 year horizon for breakthroughs. With NTT Research 2.0, you’re introducing a more market-driven, startup-like approach. How do you decide when a technology is ready to move from the lab to commercialization—and how do you balance avoiding premature launches with not letting viable ideas sit too long? This shift didn’t happen overnight—we have actually been building this business incubation capability behind the scenes for over a year. What you are now seeing with Research 2.0 is the formalization of something that was already taking shape internally. At a practical level, the key realization was that after seven years of fundamental research, we now have several technologies that are approaching, or in some cases already at, a point where there is clear commercial potential. And it would be a shame to let those opportunities sit idle. So operationally, we have introduced a new layer—a business incubation function—that selectively picks up technologies that show near-term product viability. The idea is not to change how research is done, but to create a parallel path that can take these technologies to market in a more structured way. In terms of avoiding risks such as pushing immature technologies too early or letting mature ones sit too long, the way I think about it is not through rigid stage gates, but through separation of roles and clarity of intent. The research team continues to focus on fundamental discovery without pressure from product timelines. Meanwhile, the incubation team evaluates technologies through a completely different lens: market readiness, customer relevance, and business viability. The decision of when something is ‘ready’ is less about a fixed checklist and more about whether we can see a credible path to real-world deployment and value creation. The most important structural choice we made was not to convert researchers into business operators. Instead, we built Scale Academy as a completely separate team, bringing in people from outside who think in terms of markets, customers, and revenue. That separation ensures we don’t compromise the integrity of either side. The research team is not rushed, and the incubation team is not constrained by academic thinking. Many big-tech companies have incubators or venture arms. What makes Scale Academy structurally different? Is it truly operating with startup-like independence in incentives and governance, or is it still shaped by being inside a large enterprise? And how do you define success: venture creation, revenue, or building a repeatable commercialization engine? Where we differentiate is the starting point. Scale Academy is not sourcing ideas from product teams or incremental innovation—it is directly connected to a very strong basic research foundation. That means the technologies we are working with are often fundamentally new, sometimes even ahead of market demand, which gives us a different kind of leverage. In terms of governance and constraints, yes, we do have the advantage of NTT as a large parent providing funding and stability. But at the same time, we are very conscious that no company can succeed in isolation today. So one of the core principles we are building into Scale Academy is ecosystem participation. When we spin out companies, we don’t intend to own everything—we want to bring in other partners, investors, and players who are relevant to that market. Being part of a broader ecosystem is critical to scaling these upcoming technologies. As for success metrics, it’s still evolving, but I don’t want to reduce it to just the number of startups launched. That would be too simplistic. What matters more is whether we can create a repeatable, effective process—identifying the right technologies, applying the right business thinking, and building ventures that can become self-sustaining as quickly as possible. Of course, revenue and profitability will be important at the individual company level, but success for me is whether this becomes a sustainable engine that consistently translates deep research into real businesses. Research thrives on patience and uncertainty, while startups demand speed and market validation. How do you reconcile those two fundamentally different operating models without compromising either? And what cultural or organizational shifts were required within NTT Research to support both discovery and deployment? This is probably the most challenging aspect of Research 2.0. Trying to merge those directly would create conflict, so the key is clear separation with controlled collaboration. The incubation team needs technical depth and continued support from the researchers. But this interaction has to be carefully managed. Too much overlap risks distracting the research team; too little collaboration risks weakening the product. Culturally, I do see a shift happening, particularly in motivation. Many researchers have expressed a desire to see their work used in the real world. With Scale Academy, we can now offer that pathway. It becomes an additional incentive, not replacing the academic mission, but complementing it. We can say, ‘You’ve created something valuable, do you want to explore how it might be used?’. But if we don’t manage the boundaries and interactions properly, we could fail on both fronts—neither achieving strong research nor successful commercialization. So this is something we are actively watching and adjusting as we go. Attribute-based encryption (ABE) has existed for years, but never really broke into mainstream enterprise deployment. Why is it viable now? What changed in terms of performance, scalability, or real-world readiness? And does SaltGrain truly redefine zero-trust by embedding policy into the data itself, or is it an evolution of existing approaches shaped by the demands of AI? Technologies like ABE often require a long maturation period. Over the past decade, ABE has become significantly more stable and practical from a technical standpoint. So the technology itself is now ready. However, the more important factor is the market timing. What has changed dramatically in the last one to two years is the rise of AI, especially agentic AI. We are entering a world where more and more AI agents are being deployed across enterprises, and these agents require access to large volumes of data to function effectively. That creates a fundamental tension. On one hand, organizations need to provide as much data as possible to train these agents. On the other hand, much of that data contains sensitive information—personal data, financial details, internal records—that cannot simply be exposed. So companies are stuck in a dilemma: either risk leaking sensitive data or restrict access and limit the effectiveness of AI. This is where SaltGrain comes in. We are combining ABE with additional capabilities to address this specific problem. For example, we are developing classification engines that can automatically scan documents, identify sensitive information, and categorize it into different levels of sensitivity. Once that is done, ABE allows us to selectively mask or encrypt those parts of the data while leaving the rest accessible. Another key shift is that we are no longer designing this system primarily for human users. Increasingly, the ‘viewer’ of the data is an AI agent. So we are fine-tuning the system with that assumption in mind. Different agents can be given different levels of access based on policy, all enforced at the data level. The core idea of embedding policy into the data itself aligns strongly with zero-trust principles. But what makes it new is the context, applying it to AI-driven environments where the scale, speed, and nature of access are fundamentally different. Right now, I don’t see many practical solutions in the market addressing this problem. We’re entering a world where AI agents, not just humans, access and act on enterprise data, creating new security risks. How does your data-centric model address that reality, and can policies embedded at the data level scale across complex, real-world workflows? And how should enterprises think about post-quantum readiness today—urgent priority or longer-term transition? Recent security incidents, like large-scale data breaches where entire document repositories are exposed, show why data-centric security is important. In traditional models, once data is stolen, it is essentially compromised. But with ABE, the protection stays with the data itself. Even if a file is copied or leaked, the access control policies remain embedded, so sensitive information is still protected. For us, zero-trust data security means not relying on perimeter defenses alone and securing the data wherever it goes. In terms of scaling this to AI-driven environments, I think we are still in the early stages. We can point to scenarios where this approach would have significantly reduced the impact of past breaches, but we are still building real-world use cases to quantify that impact more precisely. At the same time, if enterprises can trust that their sensitive data will remain protected, even when shared with agentic AI systems, they will be much more willing to use that data for training and operations. That’s a critical enabler for AI adoption and innovation. The first release of SaltGrain is not post-quantum ready, and that is intentional. Today’s systems are still largely based on pre-quantum cryptography, so we want to deliver value immediately rather than wait. However, in parallel, our research team has already developed post-quantum versions of ABE. The challenge has been performance. Early implementations were too computationally heavy to be practical. Through collaboration between the research team and the incubation team, we spent two years refining those algorithms, adjusting assumptions, and optimizing them to reduce computational requirements while maintaining security. Now we have a version that is much more practical. So our roadmap is to deploy the current solution, demonstrate value, and then transition to post-quantum readiness over the next couple of years. We want to show the market that we not only understand where things are going, but that we have a concrete path to get there. Research is an increasingly crowded space with hyperscalers, startups, and governments all investing heavily in AI, quantum, and next-gen infrastructure. Where does NTT truly differentiate? Is it the depth of research, system-level integration, or long-term capital? And if Scale Academy succeeds, does it redefine the role of a corporate research lab in the AI era, or is this still an experiment in balancing deep science with commercialization? I see this as a management challenge. Until now, NTT Research has been completely focused on fundamental research, with a clear mandate of producing strong scientific work and publishing impactful papers. That has been successful and has built a very strong foundation. What changes with Research 2.0 is that we are adding another dimension. We are not replacing the research mission, but we are expanding it. Our strength lies in the depth of our research, combined with our ability to now connect that to real-world applications. Many companies participate in the Silicon Valley ecosystem, but not all of them come in with the same level of deep, fundamental innovation. I am particularly interested in leveraging this model across the broader NTT organization. Many technologies are being developed in our labs globally, including in Tokyo. Not all of them will be suitable for commercialization, but some of them could be very strong candidates. If Scale Academy proves successful, we can bring those ‘crown jewels’ into this process and take them to global markets more effectively. At this stage, this is still an experiment, but it is a very intentional one. We are not trying to prove that deep science and commercialization are easy to combine—they are not. But we believe that with the right structure, it is possible to create a system where both can thrive. And from what I see internally, there is strong support for this direction. There is a sense of excitement, but also eagerness to see how it develops. View the full article
-
If you’re considering franchising as a business model, it’s important to comprehend the step-by-step process for success. First, you’ll need to assess your business’s viability and unique value. Next, exploring different franchise types can help you find the right fit. Evaluating financial resources and grasping the Franchise Disclosure Document (FDD) are essential steps. With the right strategy for training and support, you can set your franchise up for growth. But what are the key components of a successful franchise strategy? Key Takeaways Assess your business model for profitability and scalability to attract potential franchisees effectively. Research various franchise types to align with your entrepreneurial goals and investment capacity. Carefully analyze the Franchise Disclosure Document (FDD) to understand obligations and financial commitments. Seek professional advice to identify risks, financing options, and evaluate total investment needs. Develop a structured training program and operations manual to maintain brand consistency across franchise locations. Assessing Your Readiness for Franchising Before plunging into franchising, you need to assess your readiness thoroughly. Start by evaluating your business model’s profitability to demonstrate viability to potential franchisees. Unique value propositions will help your brand stand out in the market, which is essential for attracting franchisees who seek long-term success. Consider the scalability of your operations; effective franchise growth relies on being able to replicate your business model across multiple locations. Established brand recognition can greatly improve your appeal, as franchise organizations often seek partnership with well-known brands. Finally, confirm your financial planning and resources are adequate to support franchisee needs, providing necessary training and ongoing support, much like international franchise companies do to maintain consistency and success across their networks. Researching Different Franchise Types When researching different franchise types, it’s essential to understand the distinctions between business-format franchises, product distribution franchises, and home-based franchises. Business-format franchises offer a complete system for operation, whereas product distribution franchises allow you to sell products under the franchisor’s trademark without extensive support. Home-based franchises typically require a lower investment and are often service-oriented, which can be a great fit for those looking for flexibility and lower overhead costs. Business Format Franchises Business format franchises stand out as the most prevalent franchise type, primarily owing to the extensive framework for operating a business. They provide you with a complete system that includes marketing, operations, and training support. By choosing a recognizable brand, you can benefit from established customer trust and brand loyalty. Typically, you’ll pay an initial franchise fee ranging from $10,000 to over $100,000, alongside ongoing royalty fees of 4% to 12% of monthly revenue. Adhering to strict operational guidelines guarantees brand consistency across all locations. Here’s a quick comparison: Feature Description Example Brand Recognition Established customer trust McDonald’s Initial Fee $10,000 – $100,000 Starbucks Royalty Fees 4% – 12% of monthly revenue Dunkin’ Donuts Product Distribution Franchises Though business format franchises offer a structured approach to running a business, product distribution franchises present a distinct model that might appeal to those looking for flexibility. In this type, you sell the franchisor’s products while using their trademarks, often without needing a brick-and-mortar store. This allows for lower initial investments, as your focus is primarily on inventory and distribution rather than extensive operational costs. Franchisors provide valuable support, including brand recognition, marketing assistance, and established supply chains, which can improve your sales potential and lower risks. Common examples include beverage companies like Coca-Cola, where you operate as a local distributor. Furthermore, you benefit from economies of scale through the franchisor’s supplier relationships, helping with pricing and inventory management. Home-Based Franchises Have you considered the advantages of home-based franchises? These businesses typically require a low initial investment, usually between $10,000 and $50,000, making them accessible for many aspiring entrepreneurs. Operating without a physical storefront allows you to work from home during providing crucial services like cleaning, tutoring, or consulting. Many home-based franchises as well offer thorough training and ongoing support, ensuring you have the skills needed to thrive. The demand for these franchises has surged, especially post-pandemic, as people increasingly seek convenience and flexibility. Furthermore, with lower overhead costs, you can enjoy higher profit margins compared to traditional brick-and-mortar franchises. Exploring home-based options could be a strategic move for your entrepreneurial expedition. Evaluating Financial Resources and Costs When evaluating your financial resources and costs for franchising, it’s essential to assess the initial investment you’ll need, which can vary considerably based on the franchise brand. You’ll additionally want to explore financing options, such as traditional loans or partnerships, to guarantee you have the necessary funds. Finally, consider the long-term profit potential, factoring in ongoing fees and expenses, to gauge the overall viability of your franchise investment. Initial Investment Assessment Evaluating your initial investment for franchising is vital, as it directly influences your potential for success. The initial investment can range from $10,000 to over $100,000, depending on the franchise brand and industry. Well-known franchises typically require higher fees, which often cover the rights to operate under their brand, along with valuable training and marketing support. Furthermore, ongoing royalty fees usually fall between 4% and 12% of your monthly revenue, affecting your profitability. It’s important to verify you have liquid capital amounting to 25% to 30% of any requested loan to qualify for financing options. Conducting a thorough financial assessment, including an analysis of total investment versus potential returns, will help you make informed decisions about franchise ownership. Financing Options Exploration How can you guarantee your financing options align with your franchise goals? Start by grasping the initial franchise fees, which can range from $10,000 to over $100,000, depending on the brand. You’ll additionally face ongoing royalty fees, typically between 4% and 12% of monthly revenue, plus around 2% for marketing. Ascertain you have liquid capital amounting to 25% to 30% of any loan you seek, as this shows lenders your financial stability. Your financing options include traditional bank loans, SBA-backed loans, or leveraging personal assets like real estate. Finally, comprehending all associated costs, including operational expenses after you launch, is essential for effective financial planning and guaranteeing the profitability of your franchise investment. Long-Term Profit Analysis Understanding your long-term profit potential is crucial for making informed franchise investment decisions. To effectively evaluate your financial resources and costs, consider these key factors: Conduct a thorough cost analysis, including initial franchise fees, ongoing royalties, and marketing fees, which typically range from 4% to over 12% of your monthly revenue. Confirm that your liquid capital makes up 25% to 30% of any financing requested, as lenders usually require this for franchise investments. Evaluate the average unit volumes and cost structures to assess the potential return on investment (ROI) before committing, as total investment costs can vary from $20,000 to over $100,000 based on the franchise brand and industry. This analysis will guide your financial decisions moving forward. Analyzing the Franchise Disclosure Document (FDD) When you’re considering a franchise opportunity, the Franchise Disclosure Document (FDD) serves as your significant roadmap. This legal requirement consists of 23 disclosure items that include important details about fees, obligations, and the franchise agreement terms. You must receive the FDD at least 14 days before signing any agreements or making payments, giving you time to review it thoroughly. Pay close attention to the franchisor’s business experience, litigation history, and financial performance representations. The FDD likewise lists current franchisees, providing insights into credibility. Moreover, state regulations may necessitate extra addendums in the FDD, so comprehending these nuances is critical. Assess the financial obligations, including initial fees and ongoing royalties, to evaluate the investment’s profitability potential. Seeking Legal and Financial Advice Before plunging into a franchise opportunity, it’s essential to seek legal and financial advice, as this can greatly impact your decision-making process. Engaging experts can help you navigate complex franchise agreements and guarantee compliance with regulations. Here are three key steps to follow: Consult a licensed franchise attorney to review Franchise Disclosure Documents (FDD) and identify obligations, risks, and compliance issues. Work with a financial advisor to evaluate the total investment needed, including initial fees, ongoing royalties, and funding options. Understand financing terms thoroughly to secure favorable loan conditions, avoiding potential pitfalls. Conducting due diligence with professionals helps you assess the viability and profitability of the franchise before making a commitment. Contacting Franchisors and Initiating Discussions Engaging with franchisors is a crucial step in exploring your franchise options, as it allows you to gather fundamental information about their business model and support systems. Start by researching potential franchisors online and reviewing their Franchise Disclosure Documents (FDD). Prepare a list of questions regarding franchise operations, support, and expectations. Reach out through their official contact methods to express your interest and request further information. Here’s a quick overview of actions you can take: Action Purpose Research FDDs Understand the business model Prepare questions Facilitate meaningful discussions Follow up after contact Show commitment and seek clarifications Attending Discovery Days for Insights Attending Discovery Days offers a unique opportunity to gain firsthand insights into the franchise you’re considering. These events allow you to explore the franchisor’s headquarters and meet the team, providing a deeper comprehension of their culture and operations. Here’s what you can expect: Engage in Q&A sessions: Clarify any concerns about training, support, and daily operations, ensuring you have all the information you need. Attend detailed presentations: Learn about the franchise’s business model, financial performance, and growth potential, which can help guide your decision-making. Network with existing franchisees: Gain insights from those already operating the franchise, offering a realistic perspective on their experiences. Making Informed Commitments Making an informed commitment to a franchise requires careful consideration and due diligence, as the decisions you make can greatly impact your future success. First, thoroughly review the Franchise Disclosure Document (FDD), which outlines crucial details like fees, obligations, and the franchisor’s background. This document must be provided at least 14 days before you sign any agreements or make payments. Assess financial requirements, as initial franchise fees can vary considerably, and ongoing royalties affect long-term profitability. Research existing franchisee experiences to gauge market presence and brand reputation. It’s wise to engage a franchise attorney for legal guidance, ensuring compliance with regulations. Finally, confirm you have adequate financial resources to manage both initial investments and ongoing operational expenses. Developing a Franchise Success Strategy To achieve success in franchising, it’s vital to develop a well-structured strategy that aligns with both your goals and the franchise brand’s standards. Start by focusing on these key areas: Franchise Disclosure Document (FDD): Confirm your FDD complies with federal and state laws, detailing important disclosures to inform potential franchisees about costs and obligations. Operations Manual: Create a thorough operations manual that standardizes procedures, helping franchisees maintain brand consistency across locations. Training and Support: Implement a structured training program to equip franchisees with necessary skills and knowledge, guaranteeing they adhere to brand standards. Frequently Asked Questions What Is the 7 Day Rule for Franchise? The 7 Day Rule for franchises mandates that franchisors provide a Franchise Disclosure Document (FDD) to potential franchisees at least 14 days before any agreement is signed or payment is made. This rule guarantees you have sufficient time to review important information about the franchise opportunity. If franchisors fail to comply with this requirement, they risk legal consequences, including lawsuits, impacting their credibility and brand integrity in the marketplace. What Are the 4 P’s of Franchising? The 4 P’s of franchising are Product, Price, Place, and Promotion. Product refers to the goods or services you offer, ensuring they meet customer expectations and brand standards. Price involves setting fees and royalties that franchisees must pay, which can vary greatly. Place focuses on selecting ideal locations, requiring market research to find areas with demand. Finally, Promotion includes marketing strategies that help build brand awareness and engage customers effectively. How to Franchise Step by Step? To franchise step by step, start by evaluating your business’s readiness, ensuring you have a replicable model and a unique value proposition. Next, prepare a compliant Franchise Disclosure Document (FDD) with all necessary disclosures. Create a detailed operations manual for franchisees, and develop a franchise sales strategy targeting potential franchisees. Finally, engage legal experts to draft the franchise agreement, ensuring compliance with regulations to protect both your interests and your franchisees’. Why Is It Only $10,000 to Open a Chick-Fil-A? Chick-fil-A‘s initial franchise fee is only $10,000 since the company retains ownership of the restaurant property and equipment. This arrangement greatly reduces the financial burden on you as a franchisee. Nevertheless, you must have a net worth of at least $1 million and liquid assets of $250,000 to guarantee you can sustain operations. Furthermore, Chick-fil-A charges royalties around 15% of sales, which supports a sustainable business model whilst keeping entry costs low. Conclusion In summary, succeeding in franchising requires a strategic approach that encompasses thorough preparation, diligent research, and informed decision-making. By evaluating your readiness, exploring various franchise types, and comprehending financial commitments, you position yourself for success. Furthermore, analyzing the FDD and seeking expert advice can help you navigate potential challenges. In the end, developing a robust franchise success strategy guarantees consistency and support, allowing your franchise to thrive across multiple locations as you meet your business goals effectively. Image via Google Gemini This article, "A Step-by-Step Guide to Success in Franchising Franchising" was first published on Small Business Trends View the full article
-
I have a bit of an issue with short-form content. It's so easy to lose hours scrolling through Instagram Reels at night that I deleted the app, and I only use the Instagram website on my laptop (a categorically worse Instagram experience). The problem is, I just moved my addiction to YouTube Shorts. Because you're greeted with a grid of Shorts as soon as you launch the YouTube app, it's too easy to just keep scrolling through Shorts for hours. It looks like I'm not the only one with this problem: Back in October, YouTube added an option to limit your Shorts watch time. Then, in January, it rolled out an option to disable Shorts in YouTube search. But while these changes are helpful, they're far from perfect: The lowest you could go with the timer was 15 minutes, so you could still watch Shorts when you launched the app—even if only for a quarter of an hour. Now, YouTube is taking things one step further, adding a new “0 minutes” option to its Shorts time management feature. It's not exactly what I would have wanted—a toggle to disable Shorts altogether—but this is a start, especially since it removes Shorts from your main feed. The only issue here is that this is not a strict block. You will still see a Shorts tab, and if you tap on a Short from a profile, you'll see an option to ignore the limit for the day. If you choose this, you're right back to where you started. How to "block" Shorts from the YouTube app on iPhone and AndroidTo enable this feature, open the YouTube app, go to your Profile tab, tap the Settings icon from the top toolbar, and choose the Time Management option. Here, enable the Shorts feed limit feature, then pick the new 0 minutes option. YouTube is rolling out this feature slowly across the globe, so it might take a while for you to see it. According to The Verge, who spoke to YouTube spokesperson Makenzie Spiller, the option is live now for parents and is currently being rolled out to all users. If you're a parent managing a kid's account, you should see the option to limit Shorts to zero minutes right now. The rest of us might have to wait a bit longer for it. If you're curious what a Shorts-free feed looks like, take a look at the video below. If you mostly watch YouTube on your laptop, there's no need to wait. You can block Shorts using the UnTrap extension for YouTube. It has over 300 options for customizing the YouTube interface, but my favorite feature is its ability to reliably delete the Shorts section from the YouTube home screen. View the full article
-
Company tax brackets are crucial for comprehending how businesses determine their tax obligations. For C corporations, the federal tax rate is a flat 21%, which simplifies calculations compared to individual tax brackets. Nevertheless, state tax rates vary, impacting the overall tax burden. Knowing how these brackets work can help you navigate corporate tax planning effectively. But what about the implications of alternative minimum tax and strategies for minimizing liabilities? Key Takeaways C corporations face a flat federal tax rate of 21% on all taxable income, with no graduated tax brackets. State corporate tax rates vary, averaging around 6.2%, leading to a combined rate of approximately 26%. C corporations experience double taxation on profits: first at the corporate level and again on dividends distributed to shareholders. The Corporate Alternative Minimum Tax (CAMT) ensures large corporations pay a minimum tax of 15% on financial statement income exceeding $1 billion. Pass-through entities, like partnerships and S corporations, avoid double taxation by having profits taxed only at individual income tax rates. Understanding Company Tax Brackets Grasping company tax brackets is vital for navigating the corporate tax environment effectively. For C corporations, comprehending c corporation tax brackets is straightforward since they’re taxed at a flat federal rate of 21%. This rate was reduced from 35% by the Tax Cuts and Jobs Act in 2017, simplifying tax calculations for many businesses. Unlike other business structures, such as pass-through entities, C corporations don’t face graduated tax rates; all taxable income is subject to that same 21% rate. It’s also significant to note that state taxes vary, with 44 states and D.C. imposing additional rates, which can lead to an average combined rate of around 26%. In addition, the Corporate Alternative Minimum Tax, effective after 2022, adds a 15% minimum tax for certain corporations with significant income, affecting overall tax liability. Grasping these company tax brackets is vital for effective financial planning and compliance. The Flat Corporate Income Tax Rate The flat corporate income tax rate in the U.S. stands at 21%, a significant drop from the previous 35% because of the Tax Cuts and Jobs Act of 2017. This rate applies equally to the profits of C corporations, which are taxed separately from their owners, simplifying tax calculations by eliminating graduated brackets. Comprehending how this flat rate affects corporate taxation—including the implications of double taxation and comparisons with pass-through entities—is crucial for grasping the broader framework of company tax brackets. Corporate Tax Rate Overview During the process of maneuvering through the intricacies of corporate taxation, it’s essential to understand that the corporate income tax rate for C corporations in the U.S. is set at a flat 21%. This rate, reduced from the previous 35% by the Tax Cuts and Jobs Act in 2017, applies uniformly to profits calculated as total receipts minus allowable deductions like wages and depreciation. Unlike individual tax rates, which vary based on income levels, the corporate tax rate maintains consistency for all corporate profits. Furthermore, state-level taxes can raise the average combined corporate tax rate to around 26%. This flat structure makes it easier for corporations to predict their tax obligations, contributing considerably to federal revenue. Double Taxation Effects Comprehending double taxation is crucial for grasping the implications of the flat corporate income tax rate. Under this system, C corporations face a 21% corporate tax on profits. When these profits are distributed as dividends to shareholders, they incur an additional tax, which can reach as high as 40.8%. This dual taxation leads to an effective tax burden on the same income, making it a significant factor in corporate decision-making. Tax Stage Tax Rate Corporate Level 21% Individual Dividends Up to 40.8% Overall Tax Burden Varies by income Total Federal Receipts 8.7% (2022) Status of Revenue Third largest Understanding these dynamics helps clarify the challenges corporations face. Comparison With Pass-Through Entities When comparing C corporations to pass-through entities, it’s essential to recognize the fundamental differences in how their income is taxed. C corporations face a flat federal corporate income tax rate of 21%, established by the Tax Cuts and Jobs Act in 2017. This uniform rate applies regardless of income levels, unlike pass-through entities, which are taxed at individual owners’ personal income tax rates ranging from 10% to 37%. Additionally, C corporations experience double taxation, as profits are taxed at the corporate level and again at the individual level when dividends are distributed. Conversely, pass-through entities avoid this entity-level tax, resulting in a significant portion of business income being taxed under individual tax frameworks. Corporate Alternative Minimum Tax (CAMT) The Corporate Alternative Minimum Tax (CAMT) introduces a 15% minimum tax on adjusted financial statement income for corporations with average annual income exceeding $1 billion, starting in tax years after 2022. This tax aims to prevent large IBM from using deductions and credits to avoid paying their fair share, promoting more equitable contributions to the tax system. Comprehending CAMT’s implications is vital for corporations, as it impacts their tax liabilities as well as influences their overall financial strategies. Purpose of CAMT Ensuring fairness in the corporate tax system is a primary goal of the Corporate Alternative Minimum Tax (CAMT). This tax imposes a 15% minimum on adjusted financial statement income for corporations with average annual AFSI exceeding $1 billion, starting after 2022. CAMT targets larger corporations, especially foreign-parented multinationals, requiring them to pay a minimum tax regardless of deductions and credits that could lower their tax bills. By establishing a minimum tax credit that can carry forward indefinitely, CAMT provides relief when liabilities exceed standard corporate tax amounts. In the end, CAMT aims to prevent tax avoidance strategies that undermine the corporate tax base, ensuring that profitable corporations contribute fairly to the tax system, thereby promoting equity in taxation. Impacts on Corporations With the introduction of the Corporate Alternative Minimum Tax (CAMT), large corporations must now navigate a new terrain of tax obligations that considerably impacts their financial strategies. Here are key considerations for corporations: Minimum Tax Rate: CAMT imposes a 15% tax on adjusted financial statement income for those with average annual income exceeding $1 billion. Compliance Requirements: Corporations must carefully track their financial statement income to guarantee they meet the new requirements and avoid penalties. Tax Credit Benefits: If CAMT exceeds regular tax liabilities, corporations can generate a minimum tax credit that can be carried forward indefinitely, providing potential future tax relief. These changes aim to guarantee that highly profitable corporations contribute a fair share of taxes, addressing long-standing concerns about tax avoidance and base erosion. Base Erosion and Anti-Abuse Tax (BEAT) Base Erosion and Anti-Abuse Tax (BEAT) represents a significant measure aimed at large multinational corporations engaged in profit shifting through base-eroding payments to foreign affiliates. This tax particularly targets corporations with average annual gross receipts of at least $500 million over a three-year period. BEAT imposes an additional tax liability on deductible base-eroding payments, ensuring these companies contribute fairly to the U.S. tax base. The BEAT tax rate is currently set at 10% for tax years beginning after 2022, with an increase to 12.5% for tax years starting after 2025. Affected corporations must calculate their regular tax liability and compare it to their BEAT liability, paying the higher amount. In the end, BEAT is designed to supplement the corporate income tax system, ensuring that large corporations pay a minimum level of tax on their income earned in the U.S., in spite of deductions for payments to foreign entities. Taxation for C Corporations Taxation for C corporations involves a structured approach to corporate income that greatly impacts how businesses operate in the U.S. C corporations face a flat federal corporate income tax rate of 21%, following a reduction from 35% as a result of the Tax Cuts and Jobs Act in 2017. Here’s what you need to know: Double Taxation: C corporations pay taxes on profits at the corporate level, and shareholders pay individual income taxes on dividends. State Taxes: In addition to federal taxes, C corporations are subject to varying state corporate income taxes, creating an average combined rate of about 26%. Filing Requirements: Corporations must file Form 1120 to report their income, gains, losses, deductions, and credits for the tax year. Understanding these aspects is essential for managing your corporation’s tax obligations effectively. Taxation for Pass-Through Entities When you operate a pass-through entity, such as a sole proprietorship, partnership, LLC, or S corporation, you’ll notice a distinct difference in how your business is taxed compared to C corporations. Pass-through entities don’t pay corporate income tax; instead, profits are passed through to you as the owner and taxed at individual income tax rates, which range from 10% to 37%. You’ll report this business income on your personal tax return using forms like Schedule C for sole proprietorships or Form 1065 for partnerships. Unlike C corporations, which face double taxation on profits and dividends, pass-through businesses avoid this by having profits taxed only once at the individual level. Furthermore, the Qualified Business Income (QBI) deduction allows eligible pass-through entities to deduct up to 20% of their qualified business income, potentially lowering your overall tax liability. This structure has led to a shift in the direction of pass-through entities as a more tax-efficient option. Federal vs. State Corporate Tax Rates Comprehending the differences between federal and state corporate tax rates is vital for businesses operating in the U.S. The federal corporate tax rate is a flat 21%, established by the Tax Cuts and Jobs Act (TCJA) of 2017. Conversely, state corporate tax rates vary considerably, impacting your overall tax burden. Here are some key points to take into account: Variability: 44 states and D.C. impose corporate taxes, averaging around 6.2%. Rates can be as low as 0% in Florida and as high as 13.3% in California. Incentives: Some states offer specific tax incentives or lower rates for certain types of businesses, which can reduce your tax liability. Effective Rate: When combined, federal and state rates can lead to an effective tax rate of approximately 26% for C corporations, depending on your state. Understanding these differences is fundamental for strategic financial planning. Calculating Corporate Taxes Calculating corporate taxes involves comprehension of how your taxable profits are determined and the various factors that influence your overall tax liability. In the U.S., corporate income tax is imposed at a flat federal rate of 21% on taxable profits, which you calculate by subtracting allowable deductions—like wages and depreciation—from your total receipts. If you’re a C corporation, you’ll need to file Form 1120 to report your income, expenses, and tax liability. Furthermore, states impose their own corporate income taxes, ranging from 0% to 9.80%, which can increase your total tax burden, especially if you operate in multiple jurisdictions. When factoring in state taxes, the average combined corporate tax rate can reach approximately 26%. Accurate recordkeeping is crucial for capturing all allowable deductions, as this directly impacts your taxable income and, in the end, the taxes you owe. Strategies for Minimizing Corporate Tax Liability Minimizing corporate tax liability requires a strategic approach to leverage available deductions and credits effectively. By implementing well-planned strategies, you can greatly reduce your tax burden. Here are three key strategies to contemplate: 1. Maximize Deductions: Take full advantage of allowable deductions such as wages, interest, and depreciation. These directly reduce your taxable income, adhering to Internal Revenue Code guidelines. 2. Utilize Tax Credits****: Explore tax credits, including those for increasing research activities. Unlike deductions, these credits directly offset taxes owed, providing a more substantial reduction in your overall tax liability. 3. Engage in Tax Planning****: Contemplate strategies like the Qualified Business Income (QBI) deduction for eligible pass-through entities, which can reduce qualifying business income by up to 20%. Frequently Asked Questions How Do Corporate Tax Brackets Work? Corporate tax brackets determine how much tax a corporation pays on its profits. In the U.S., C corporations face a flat federal rate of 21%, regardless of income level. This means all taxable profits are taxed uniformly. Moreover, state taxes can apply, varying widely across states. The shift to a territorial tax system means you’ll mainly pay taxes on domestic profits, impacting your overall tax obligations considerably. Comprehending this can help you plan effectively. How Do You Explain How Tax Brackets Work? Tax brackets work by dividing income into segments that are taxed at different rates. As your income rises, you enter higher brackets, which means you pay a higher tax rate only on the income within those brackets. For instance, if you earn more than a certain threshold, the income above that amount gets taxed at a higher rate. Comprehending these brackets helps you estimate tax liabilities and plan your finances effectively. How Do LLC Tax Brackets Work? LLC tax brackets depend on how your LLC is classified for tax purposes. If you’re a single-member LLC, you’ll report income on your personal tax return, subjecting it to individual tax brackets, ranging from 10% to 37% in 2025. Multi-member LLCs usually file as partnerships, and the income passes through to members’ returns. Furthermore, you might qualify for the Qualified Business Income deduction, potentially lowering your effective tax rate. State taxes could likewise apply. How Do You Calculate a Company’s Tax Rate? To calculate a company’s tax rate, you’ll first determine its taxable income by subtracting allowable deductions from total receipts. The corporate tax rate, currently 21% for C corporations in the U.S., then applies to this taxable income. Don’t forget to factor in state tax rates, which can vary widely. Furthermore, consider any special taxes, like the Base Erosion and Anti-abuse Tax, that may affect overall tax obligations. Proper adherence to IRS guidelines is essential. Conclusion In conclusion, comprehending company tax brackets is essential for effective corporate tax planning. C corporations face a flat federal tax rate of 21%, whereas state rates can vary, leading to an average combined rate of about 26%. Furthermore, factors like the Corporate Alternative Minimum Tax and Base Erosion and Anti-Abuse Tax can impact overall tax liability. By grasping these elements, businesses can better navigate their tax responsibilities and explore strategies to minimize their corporate tax burden. Image via Google Gemini This article, "What Are Company Tax Brackets and How Do They Work?" was first published on Small Business Trends View the full article
-
Warren Buffett is seldom wrong, especially regarding investment and innovation. As most of us know, the Oracle of Omaha offers wisdom that goes beyond industries, generations, and cultures. And that wisdom, even if it seems obvious (ever catch yourself saying, “Wait, I could’ve said that myself!”), is usually right on the mark. Like this piercing bit of truth-telling: If you get to my age in life and nobody thinks well of you, I don’t care how big your bank account is, your life is a disaster. That’s what Buffett once shared with a group of students at Georgia Tech when they asked him about his idea of success. He explained that success isn’t just about wealth, power, fame, or collecting lots of expensive toys before you pass away. Instead, he emphasized the importance of meaningful achievements and personal fulfillment. Buffett’s ultimate measure for success In the same quote mentioned above, which is included in the Buffett biography The Snowball: Warren Buffett and the Business of Life, Buffett also shared this piece of wisdom with the students (get ready to be amazed): Basically, when you get to my age, you’ll really measure your success in life by how many of the people you want to have love you actually do love you. I know many people who have a lot of money, and they get testimonial dinners and they get hospital wings named after them. But the truth is that nobody in the world loves them. That’s the ultimate test of how you have lived your life. The trouble with love is that you can’t buy it. You can buy sex. You can buy testimonial dinners. But the only way to get love is to be lovable. It’s very irritating if you have a lot of money. You’d like to think you could write a check: I’ll buy a million dollars’ worth of love. But it doesn’t work that way. The more you give love away, the more you get. Let me clarify: The key lesson and “the ultimate test” of a meaningful life are not about money but focus on the most powerful emotion humans experience: love. That’s what I’m talking about. Thank you, Warren. Closer to home, you have to ask: How can everyday workers, leaders, managers, and entrepreneurs with big ideas live out this principle of “the more love you give away, the more you get back”? In other words, what steps should you take to become so loved by others that, when you’re ready to retire or step back, they will shower you with praise, awards, admiration, and tell the world, “He loved well”? I suggest there are ways—although completely counterintuitive—to put this practical kind of love into action if you are daring and courageous. 1. Act selflessly, helping others without expecting anything in return The laws of love are mutual, but someone has to make the first move—why not it be you? When we choose to love someone first—whether it’s lifting up a colleague with encouragement, helping develop an employee under your guidance, or adding deep meaning and purpose to someone’s work—love returns in full force through respect, admiration, trust, loyalty, commitment, and voluntary effort. 2. Practice the “Platinum Rule” instead of the Golden Rule We all know the universal Golden Rule: “Treat others as you would like to be treated.” But the Platinum Rule elevates this idea to a new level of caring: “Treat others the way they want to be treated.” The Golden Rule, as great as it is, has its limitations because all people and situations are different. When you follow the Platinum Rule, however, you can be sure you’re actually doing what the other person wants and improve your chances of a better outcome. 3. Do what you love In closing, I return to Buffett for one last priceless insight: In the world of business, the people who are most successful are those who are doing what they love. Think about it. Does that thought ever cross your mind during your daily work? For most of us, we take our comfortable paycheck, health benefits, and job security for granted, even though we might dislike our jobs and wish we were doing something else—something we truly loved. Engaging in activities we truly enjoy can really uplift our spirits. What’s most important is to find out what truly sparks your passion. If you’re not quite sure yet, don’t worry; your first step is simply to start exploring and discovering what makes you feel alive. —Marcel Schwantes This article originally appeared on Fast Company’s sister website, Inc.com. Inc. is the voice of the American entrepreneur. We inspire, inform, and document the most fascinating people in business: the risk-takers, the innovators, and the ultra-driven go-getters that represent the most dynamic force in the American economy. View the full article
-
Federal authorities recently sentenced two individuals connected to a significant fraud ring that exploited government relief programs, a reminder for small business owners to remain vigilant against similar threats. Ikponmwosa Erhinmwinrose, 39, received a 17-year prison sentence after being convicted of multiple counts including wire fraud and aggravated identity theft. Co-defendant Nyerhovwo Presley Agbure, 34, was sentenced to 57 months in prison after pleading guilty to conspiring to commit money laundering. These two perpetrated a complex scheme that siphoned off more than $7.6 million from essential government support initiatives designed to aid businesses during the COVID-19 pandemic, including the Paycheck Protection Program (PPP) and the Economic Injury Disaster Loan (EIDL) program. Together, they applied for over $90 million in benefits using the stolen identities of over 1,000 innocent victims. “Driven by greed and selfishness, these criminals ran an aggressive fraud scheme which stole millions of dollars from American taxpayers and victimized more than a thousand innocent people,” said United States Attorney for the District of Colorado, Peter McNeilly. This case underscores the pressing issue of fraud that small business owners may face as they navigate national relief and stimulus programs. The implications for small businesses are significant. Fraudulent actions like these can undermine public trust in government assistance programs, potentially jeopardizing future funding opportunities. Small businesses that rely on programs like the PPP or EIDL may find themselves under increased scrutiny, leading to a more complex application process and stricter eligibility criteria. While nearly all small business owners seek to benefit from government support, they should also be aware of rising fraudulent activities. The elevated risk highlights the importance of diligence and ethical practices. Awareness is key; suspicious activities can include receiving communications that appear to solicit sensitive information or loans in your name that you did not apply for. Business owners should monitor their financial activities closely and educate their employees about the signs of fraud. Federal agencies, including the Small Business Administration (SBA) and the Department of Justice, are ramping up efforts to combat such fraudulent schemes. The National Fraud Enforcement Division actively coordinates investigations with various agencies and employs advanced tools to identify and prosecute fraudsters quickly. As McNeilly stated, the commitment to protecting taxpayer dollars remains a high priority among federal prosecutors. Moreover, as small business owners, it’s crucial to report any suspicious activity or potential fraud related to government assistance programs. The DOJ has established the National Center for Disaster Fraud hotline, allowing business owners to report any questionable instances related to COVID-19 aid. This avenue not only helps in holding perpetrators accountable but also serves the broader community of small business owners by ensuring the integrity of relief programs. However, as government agencies tighten scrutiny on applications to prevent fraud, small business owners may find that the requirements for receiving aid have become more stringent. This means that maintaining accurate financial records and following all application guidelines meticulously is more critical than ever. Proper documentation and proof of how funds are used can make a significant difference in securing the aid necessary for sustaining and growing a business during uncertain times. The case against Erhinmwinrose and Agbure stands as a cautionary tale for small business owners. Employing solid fraud prevention strategies and staying informed about potential threats can safeguard both individual business interests and the overarching economic landscape. As federal investigations continue to uncover fraudulent activities, the commitment to integrity within the small business community will be paramount. For further details about this case and ongoing efforts to combat fraud, you can refer to the original press release from the U.S. Department of Justice here. For continuous updates on fraudulent activities and investigative reports from the SBA, consider signing up for email updates from the SBA Office of Inspector General here. Image via Google Gemini This article, "Two Atlanta Men Sentenced for Multi-Million Dollar Fraud Scheme" was first published on Small Business Trends View the full article
-
When you buy a Samsung Galaxy phone, you're not just getting the standard, stock Android experience as far as software goes: You're also getting One UI, Samsung's own take on Android, complete with its own visual look, AI features, and other tweaks. One UI means you get access to settings on a Galaxy handset that aren't available on other Android phones—you can apply customizations and controls you won't find on a handset from Nothing or Google. Whether you're thinking of buying a Galaxy phone and want to know what the benefits are, or you already own a Samsung handset and want to make sure you're exploring everything it has to offer, here are some of my favorite settings exclusive to One UI: Adjust your Galaxy's color balanceSeveral other Android phones offer some basic tweaks for the color balance of the display, but Samsung goes above and beyond to give you more control. If you tap Display > Screen mode from Settings, you can adjust white balance with a slider, and switch between Vivid and Natural modes. Tap Advanced settings, and you can apply changes that are even more granular. You get separate sliders for the red, green, and blue color channels, and another slider to adjust the vividness of the screen. Keep your eyes on the preview pictures at the top to see the effects of your changes. Customize your Galaxy's side button Side button customization. Credit: Lifehacker The main side or power button on Galaxy phones can be remapped if you don't want to stick with the default configuration, which is a double press to launch the camera and a long press to launch Google Gemini. (Note you can't customize a single press, which will either lock or unlock your handset.) From Settings, choose Advanced features > Side button, then pick either Double press or Long press. You have a lot of options for a double press: everything from the flashlight and magnifier, to the Samsung Voice Recorder or any other app of your choice. For a long press, you can switch to a different digital assistant, or have a long press turn off the phone instead. By default, you need to press and hold both the side button and the volume down button to power off a Samsung Galaxy handset, so switching to a long press can be more convenient. Set up the Edge panel on your GalaxyThe Edge panel that's available on Samsung phones is a real superpower for One UI. It's a pop-up shortcut box that gives you quick access to apps, contacts, and features on your phone, and it can work as well as the Windows taskbar or the macOS dock. You can set up and customize the Edge panel from Settings by heading to Display > Edge panels. The options here let you change the appearance and position of the panel, and switch between the type of panel you want: Choose from Apps, People, Tasks, Weather, Tools, Clipboard, or Reminder. To customize the actual shortcuts on the Edge panel, open it with a swipe from the side of the screen, then tap the pen icon at the bottom. You can make sure your most-used apps and shortcuts are always readily available. Boost your Galaxy's available RAM RAM Plus settings. Credit: Lifehacker Samsung Galaxy phones come with a feature called RAM Plus that borrows part of your handset's storage and uses it as temporary RAM—which should mean launching and switching between apps happens more quickly. You can find the feature and change how much storage it uses by selecting Device care > Memory > RAM Plus from Settings. Use multi window mode on your GalaxyOne UI has a multi-window mode that turns Android into a more desktop-like operating system, and it can be helpful on phones with larger screens when you need to get a couple of apps up side by side. You can configure the feature by opening Settings and picking Advanced features > Multi window. To actually get apps up alongside each other, swipe up from the bottom of the screen into the center of the display to see your recently opened apps. Tap any of the app icons at the top of the carousel, then choose Open in split screen view. You then get to pick a second app to share the display with the first one. Automatically restart your Galaxy Auto restart options. Credit: Lifehacker If you open Settings and select Device care > Auto optimization, you'll see an option labeled Auto restart. If you enable this, your phone will restart when it's not being used to "keep it running in the best condition" (Samsung's words). You can opt to Restart when needed or Restart on a schedule. These regular restarts can help in clearing out the memory and temporary file cache on your phone, which can in turn optimize performance. As the information on screen tells you, restarts will only happen when the screen is off, you're not actively using your phone, the battery level is about 30 percent, and the SIM card lock feature is off. Apply 'Intelligent Wi-Fi' to your GalaxyOne UI on Galaxy phones doesn't just offer wifi—it offers "Intelligent Wi-Fi," which means it uses AI to optimize your connection as much as possible. Tasks where latency is crucial (such as video calls) get prioritized, and if the phone thinks you'll get better performance on a cellular connection, it will automatically switch to this instead. To find the options, open Settings and select Connections > Wi-Fi. Then you need to tap the three dots up in the top right corner, choose Intelligent Wi-Fi from the menu, and you're then able to switch on the features you want to make use of. There's also a secret wifi monitoring tool hidden away here. View the full article
-
According to Wells Fargo’s recent Money Study, 64% of parents with Gen Z children say their 18- to 28-year-old kids still rely on them for financial support—whether it’s for housing or other expenses. Of the 3,773 U.S. adults surveyed at the end of last year, more than half who are parents (56%) said the monetary support they’re extending to their adult children adds a strain on their own finances. “It’s not surprising that young adults are leaning on both family and nontraditional sources for support, but these dynamics are also putting pressure on parents,” Emily Irwin, Wells Fargo’s head of private wealth planning, said in a press release. “Open communication, clear expectations, and shared planning can help families navigate this stage together.” Nearly half of the study’s Gen Z respondents described their financial lives as “messy.” Considering the shrinking pool of entry-level jobs, mounting living costs, and high rates of career-related anxiety, “messy” might be a mild descriptor. On the one hand, parents lending a financial hand to young adults (if they have the means to do so) isn’t new. Many millennials received similar help as they struggled to find entry-level jobs while saddled with student debt during the Great Recession; in fact, many lived at home with their parents for years. With the rise of AI and a radically shifting professional landscape, Gen Zers are now struggling to launch their careers. Young adults still have a desire to make a future for themselves—they’re just approaching career-building through more nontraditional methods. A third of respondents in the Wells Fargo study said they took on side hustles and extra jobs to earn more income last year. A Harris Poll survey published in September revealed that more than half (57%) of Gen Z respondents had a side gig, compared to just 21% of baby boomers. Some young adults might prefer the freedom and flexibility that comes with having multiple gigs—but for many it’s not a way of life they necessarily want, but one they need to stay afloat. Meanwhile, the Wells Fargo study’s findings seem to be resonating with people of all ages. “As a Gen X mom of Gen Z kids, I watch them navigate a world where the basics cost more than the math ever adds up to,” one consulting professional wrote on LinkedIn. “As one such ‘Gen Z adult dependent,’ I could easily assure anyone that many of us in this situation are not doing so willingly, and would be happy to work at a steel mill or an entry-level job, if only they still paid for a life, rewarded loyalty, and actually hired,” one recent college grad commented. “To blame the young worker, or their suffering parents, is to ignore the greed that birthed the crisis in question.” “The system doesn’t work anymore. [Gen Z] can’t move away and live comfortably/normally like previous generations could,” a Reddit user said. “Just like in many other countries, intergenerational homes are going to become the new normal.” It’s not just Gen Z feeling the weight of economic turbulence and job insecurity, either. “I’m Gen X, married with a child, and my parents still help us out with big purchases,” a consulting professional wrote on LinkedIn. “Because as multiple layoffs, historic inflation, and an affordability crisis has battered my earning power, my parents’ wealth has grown.” View the full article
-
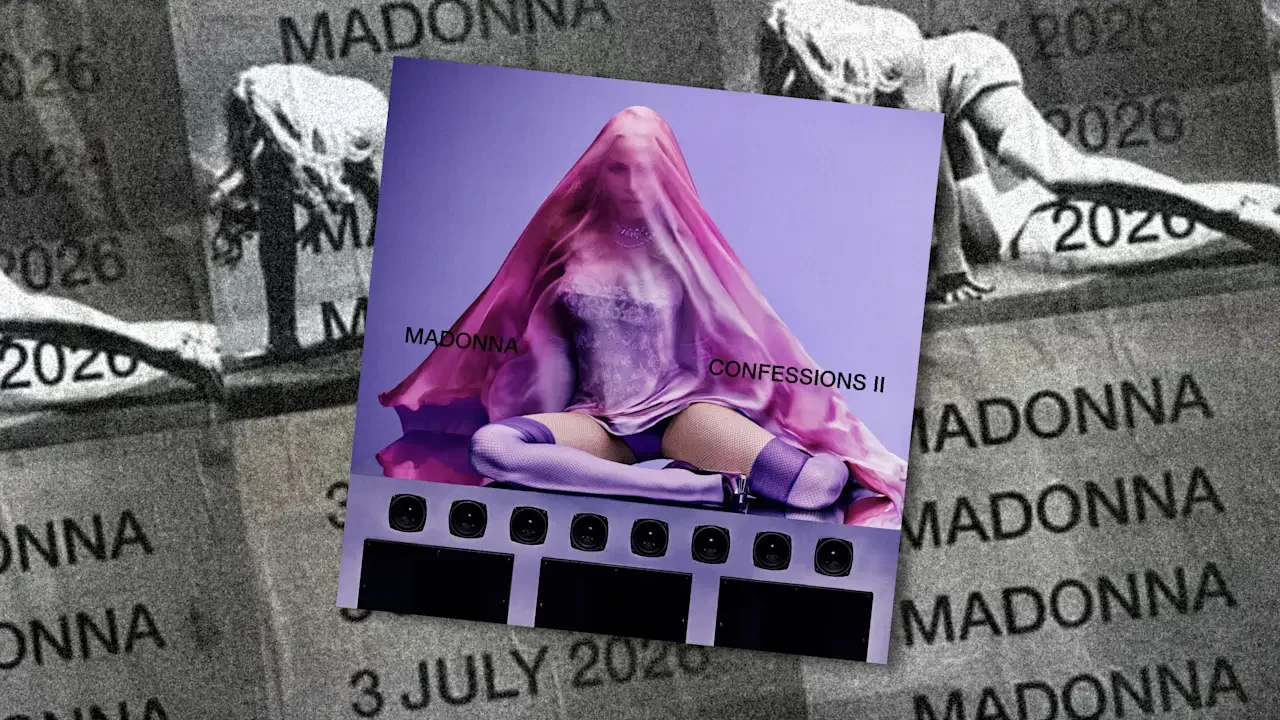
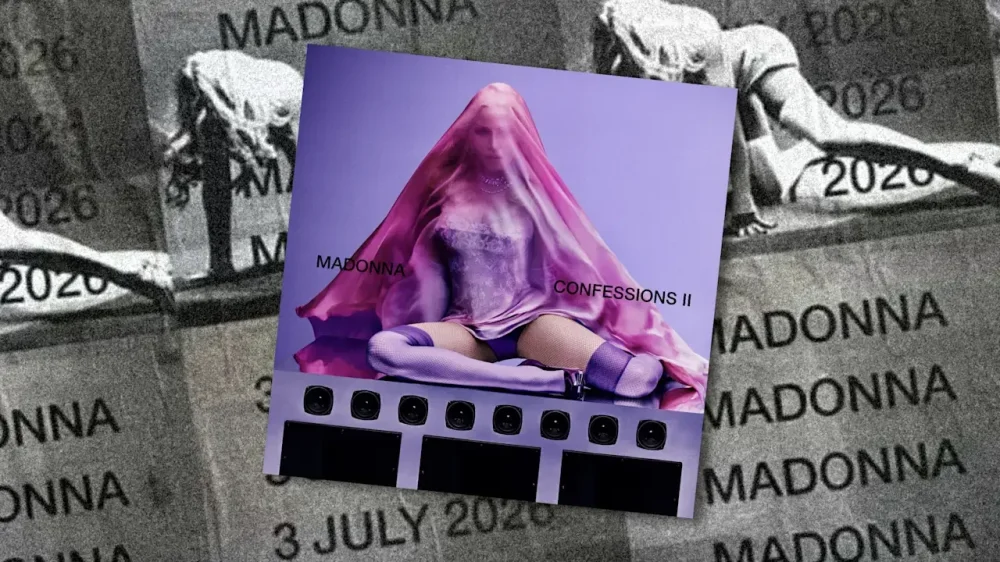
Madonna announced her new album Confessions on a Dance Floor II with sans-serif typography from the same creative agency behind Charli XCX’s brat. On wheat paste posters and short-form video posted to social media, Madonna teased her forthcoming album, out July 3, and its first song, “I Feel So Free,” in words. “Madonna Confessions II” is written on the album cover in Helvetica, a workhorse sans-serif font that’s one of the most popular fonts in the world because its minimalist form looks simple and perpetually modern. Typography was used throughout Madonna’s announcement to spell out “Confessions II,” “COADF 2,” and other promotional copy in all-caps, sans-serif typefaces, and some of the text is vertically stretched or outlined. The singer isn’t using a single font for this album launch; she’s using a whole font book. In an Instagram Stories video, text flashes and repeats vertically on screen, along with a strobe warning. It’s loud, fast, and eye-catching. A new, provocative M logo for the album shows the singer’s legs in high-heeled silver boots making the shape of the letter out from behind a speaker. For a sequel to Madonna’s beloved 2005 dance-pop album, Madonna reunited with producer Stuart Price who recorded, co-produced, and co-wrote the original Confessions on a Dance Floor. The snippet for the first track Madonna teased sounds squarely within the dance pop universe that the first album introduced. For the album’s graphic design, though, Madonna turned to a new creative partner that’s taking a type-first approach. Special Offer, Inc., had previously worked with artists like Haim and Miley Cyrus, but it was its art direction for 2024’s brat that put it on the map. Charli’s breakthrough album, known for its neon green color scheme and out-of-focus Arial Narrow font, won the Best Recording Package at the 2025 Grammys. After its launch, brat-style typography appeared just about everywhere: as murals, in an unofficial album cover generator, on merch (both official and unofficial), and on deluxe edition of the album. The brand also extended to flashing typography for Charli’s Sweat Tour with Troye Sivan and the video titles for her “360” and “Guess” music videos. Special Offer, Inc., which is credited for art direction for Madonna’s new album, did not respond to a request for comment. Madonna once promoted her music through platforms like MTV, but today it’s short-form video where music gets traction, and the strobing, type-first approach Special Offer, Inc., is taking works well on smartphones where short, bold, visually arresting text stops you mid-scroll. “The typography for an artist like Madonna is interesting,” says designer Nolan Strals, who’s made album artwork for artists including Titus Andronicus, Beach House, and John Legend and the Roots. “She’s always been played in clubs, but this feels like a bid at relevancy for a new generation… It’s typography not aimed to get the attention of her old fans, but to feel relevant to people who get their culture from TikTok.” The typography used for the original Confessions album included a Madonna logo that turned the O into a disco ball. The handwritten album title, track listing, and liner notes recalled the look of disco-era album art lettering from artists like Michael Jackson and Grace Jones. Photographer Steven Klein shot the artwork that showed Madonna in red hair, a pink leotard, and sparkling heels, and designer Giovanni Biano did the art direction and graphic design. The color scheme for the album, which spun off hits like the ABBA-sampling “Hung Up” and “Sorry,” was pink and purple while the lighting was dark and moody. A bright pink, red, and purple color scheme for the new album packs a Bratty, high-contrast visual punch, but echoes the colors of the original album art. Then there’s the photography for Confessions II, which this time around is more high fashion with a magazine-quality editorial look showing Madonna with fabric over her head wearing a floral pattern top and fishnet stockings. Her shoes this time aren’t sparkly, they’re all black. Using Helvetica on the album cover is a simple but smart play, because while the font is widely used, such as across New York City’s subway system and in logos like Target and Jeep, it also appears across art and fashion. Special Offer, Inc., has used the closely related font Arial in its work for Charli and Addison Rae, and before his death, Virgil Abloh used Helvetica to write words out on his designs. More than 20 years after the original album’s debut, the COADF visual identity has grown an extended universe that appeared on tour, a subsequent live CD-DVD, and an anniversary edition of the album. For the sequel, Madonna’s designers are building on what came before. The look of the new album is elevated, like Confessions on a Dance Floor all grown up. View the full article
-
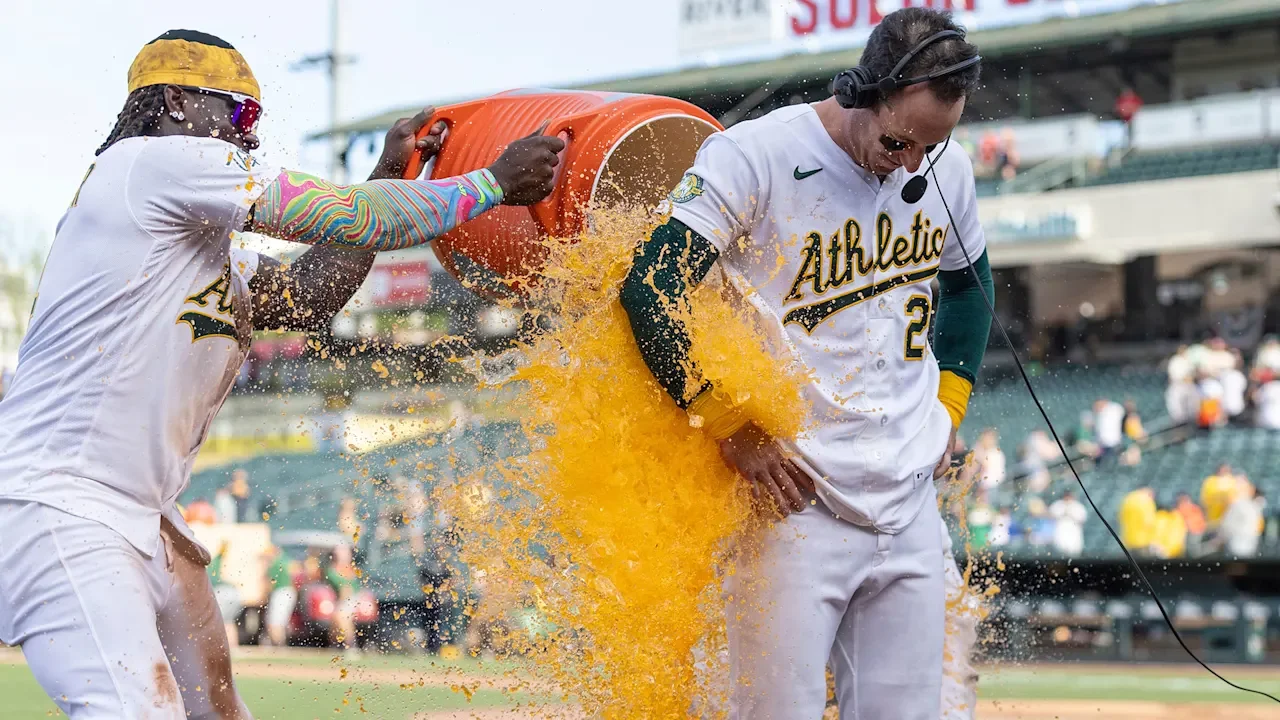
Sixty years after it invented sports drinks, Gatorade is making a surprising pivot: It’s no longer focusing primarily on athletes. PepsiCo, Gatorade’s parent company, said Thursday that the brand wants to broaden its reach to non-athletes who are looking for ways to hydrate, whether they’re on a long flight, going for a walk or nursing a hangover. New packaging highlights the specific ways Gatorade’s various drinks and powders work and the research behind them. The change reflects U.S. consumers’ booming interest in beverages with perceived health benefits. Jack Doggett, a food and drink analyst with the consulting firm Mintel, said his research indicates 60% of consumers who buy sports drinks aren’t athletes but want the functional ingredients those drinks provide, like electrolytes for hydration and carbohydrates for energy. “People are using these drinks more for wellness and daily maintenance,” Doggett said. “It’s easy to say that the wellness consumer is the young consumer, but older generations are also drinking these drinks for hydration.” Unit sales of sports drink mixes, like powders from Liquid I.V., Skratch Labs and Gatorade, rose nearly 20% in the year ending March 22, according to Circana, a market research company. Bottled water sales were flat in the same period. Crowded shelves Sensing that growth potential, new sports and hydration brands are crowding store shelves. Mike Del Pozzo, president of U.S. beverages at PepsiCo, said 150 new brands have entered the space in the last few years. “That puts a lot of risk on the category and pressure from a credibility perspective,” Del Pozzo said. “Some that are coming in are building on the science that we created. And we’re like, ‘Well, geez, we should be doing that. We should be talking more overtly about the science and the business and why we believe we’re future-forward.” Del Pozzo said Gatorade will now clearly label products that it says can hydrate better or faster than water. A new drink, Gatorade Longer Lasting, which will go on sale next year, blends glycerin and electrolytes to help the body stay hydrated for longer than water alone. PepsiCo’s approach with Gatorade echoes moves made by some of its rivals. Powerade, a sports drink owned by Coca-Cola Co., received brighter, clearer packaging in 2023 that promoted an increase in electrolytes. Last fall, Powerade began selling Power Water, a zero-sugar, electrolyte-enhanced drink aimed at non-athletes. Liquid I.V., which was founded as a sports drink mix in 2012, was acquired by Unilever in 2020 and has remade itself into a wellness and hydration brand. LMNT also had non-athletes in mind last fall when it introduced a smaller, 12-ounce version of its sparkling electrolyte drink. Sean Harapko, a beverage sector leader with Ernst & Young Americas, said consumers have so many beverage choices that companies must clearly define their products and explain why people should choose one over another. Americans are trying to live healthier lives, he said, but they’re collecting information from many different sources and defining for themselves what that looks like. Gatorade’s origins Gatorade was born in 1965, when the football coach at the University of Florida asked Dr. Robert Cade, a physician and professor at the school, why his players were losing so much weight during games but not urinating. Cade realized the players were sweating out electrolytes – another word for minerals like sodium, potassium and magnesium – and upsetting the body’s chemical balance. Cade came up with Gatorade, a drink containing salt to replace electrolytes, sugar to improve energy and lemon juice for flavor. Quaker Oats acquired Gatorade’s parent company in 1983 and established the Gatorade Sports Science Institute two years later. PepsiCo became Gatorade’s owner when it bought Quaker Oats in 2000. Del Pozzo said Gatorade will continue to meet athletes’ needs. Gatorade Thirst Quencher, for example, has 48 grams of sugar and 18% of the recommended daily amount of carbohydrates, which athletes need to maintain energy. But Del Pozzo notes that Gatorade Lower Sugar, which went on sale last month and has 75% less sugar, is one of the company’s biggest sellers in recent history. Del Pozzo said lower-sugar versions aimed at non-athletes, as well as the removal of artificial colors from Gatorade’s lineup, is bringing customers into the brand. “I think there were people that said, ‘I didn’t exercise or I’m not out in the heat or I am not sweating.’ The reality is, everybody is sweating and dehydrated from the moment they wake up and many just don’t know it,” he said. But Travis Masterson, an assistant professor at Pennsylvania State University’s College of Health and Human Development, said the average non-athlete gets the sodium they need from their diet. Athletes sometimes need a reminder to drink, he said, because their bodies are under stress. But for average people, the thirst signal is a good indicator. “Gatorade 100% has a place, but is it going to be necessary for everybody? Do you need to hydrate faster or longer?” he said. “The average person doesn’t need all the extra stuff.” —Dee-Ann Durbin, AP Business Writer View the full article
-
It seems that change and volatility are the only things that are certain when it comes to the labor market. Jobs and professions that once seemed ‘stable’ are not immune to the forces of artificial intelligence and other technological advancements. At the very least, AI is changing the nature of what jobs look like and will likely continue to do so at a fast rate. All of this can make it difficult to know what to do to foolproof your career. Liz Tran is a leadership coach to CEOs and founders and the author of AQ: A New Kind of Intelligence for a World That’s Always Changing. After two years of conversations with founders, CEOs, and leaders, Tran found that those who are most successful and fulfilled have one thing in common—they are comfortable adapting to change and uncertainty. This is what she calls the Agility Quotient (AQ), a type of intelligence that she believes will continue to be a key differentiator as AI and technology continue to change how we live and work. Part of increasing your AQ is improving your tolerance to risks and failure. Below are some of the habits and mindset shifts that can strengthen your resilience to both. 1. Assess your relationship with risk and failure The first step is to identify where you’re currently at. Are you someone that’s comfortable with risks and failure, or do the thought of both make you want to throw up? If you’re not sure, Tran has a framework that she sets out in her book. First, she says, “Bring to mind a stressful or intense situation that you’ve been in recently…and think about the way you’ve approached it.” If you find yourself avoiding the problem, distracting yourself, or telling yourself that it’s not going to be a big deal (without actually acknowledging the problem), that indicates a low level of AQ. This means that risk and failure aren’t something that you’re comfortable with. The middle level, Tran says, is when you acknowledge the change and “you do try to improve your situation in some way.” However, you’re still fighting the situation. “There’s a sense that you’re feeling like, ‘why is this happening to me?’ What did I do to deserve this? Why do I have to deal with this? There’s a resentment and maybe even an anger about what your situation is.” This indicates that while you have some level of tolerance to risk and failure, you’re still resistant to it when it happens. The top level is when you’ve decided to embrace whatever change comes your way, failure included. It doesn’t mean you like your circumstances, Tran says, “but it does mean that you’re seeing it as an opportunity...rather than just something you resent.” And when you have this mindset, Tran says, “not only are you setting yourself up to best tackle the change that is in front of you, but it also helps people from getting burnt out.” 2. Strive to be a ‘learn-it-all’ instead of a ‘know-it-all’ Improving your risk-taking muscle requires a change in mindset. Tran references Microsoft CEO Satya Nadella, who transformed Microsoft’s culture from being “know-it-alls” to “learn-it-alls.” IQ, Tran explains, is about being a “know-it-all,” about having the right information and knowing how to process it quickly. AI and technology have made that less important. The new world of work where everything is changing so quickly, Tran says, “rewards people who move fast.” That means letting go of your ego and being “willing to experiment, pivot, and reinvent yourself.” It also means accepting that sometimes, those experiments can lead to public failures. 3. Find an anchor that grounds you and gives you the stability to take risks While it might sound counterintuitive, Tran says that “agility requires stability.” She continues, “In order to feel psychologically grounded and stable enough to go out there and take risks, you actually need a cushion of comfort and security.” That anchor might be a strong relationship with family and friends, or habits and routines like healthy eating and exercise that make you feel good about yourself. It might also be a physical place that gives you a sense of peace, like your home, a park, or a place of worship. Tran says that anyone who wants to take risks should take the time to invest and build these anchors and routines if they don’t already have them in place. “If we push ourselves too far out of our comfort zones too quickly, then that can actually lead us to impaired cognitive functioning. You actually just want to hit that sweet spot where you’re pushing yourself out of your comfort zone, but it’s not so much that you’re tipping into fight or flight.” Creating a sense of security in areas of life that are in our control, she says, gives you the freedom to take risks in areas where the outcome is uncertain. 4. Practice discomfort on a daily basis Tran is also a believer in exposure therapy, and believes that regularly doing uncomfortable things in a low-risk environment can condition us to do the same in a high-risk environment. Tran likes to frame it as a ‘bet’ rather than a ‘risk’. A risk suggests that there’s a downside to it, whereas with a bet, you can frame it as taking action where you don’t know the outcome, while setting yourself up for the possibility of winning, she explains. This can look like something as small as trying out a new coffee shop or reaching out to someone who’s not in your network that you’d love to meet. “You start with risks that are tolerable, ” she says, and as you build resilience to taking those risks, you become more comfortable doing things that you might have once considered “anxiety-inducing.” 5. Work on improving your ‘recovery rate’ from failure For Tran, a practice that has served her well during periods of setbacks has been tracking “recovery rate” rather than outcomes. Say you set out to make seven “bets” during the week, and none of them worked out in the way that you wanted. If you focus on the outcome, you’re going to feel pretty bad, “even though that’s to be expected when you’re putting yourself out there for risk-taking and failure all the time.” “What you actually want to do is to track your recovery rate,” she says. Notice how quickly you bounced back from this, and how strong, resilient, or courageous you were in the process. Hopefully, the time it takes for you to bounce back becomes shorter and shorter, and that’s a good indication that you’re strengthening your risk and failure tolerance. 6. See failure and setbacks as open doors to new opportunities Tran continually stresses the importance of seeing AQ (and tolerance to risk and failure) as a skill to develop, no matter where your comfort level with change might currently be. If you find yourself resistant to change, for example, it’s probably because it’s something that you haven’t prioritized, or you’ve operated in an environment that doesn’t encourage it, she explains. High achievers, for example, can often struggle with risks because they’re used to doing something that they know will reward them in the end—like a pay rise or a promotion. But if we’re optimizing for outcomes all the time, Tran says, “we’re actually missing the broader target, which is to learn and become agile enough to succeed. “No matter how smart you are, we do not know what the future is going to bring for us, especially with the way that the world is operating now.” The key is to be open, Tran says, to new possibilities. It’s also reframing failure and risk-taking as a pathway to opportunities you didn’t know existed. This is something that Tran, whose own career has been full of pivots, has done personally. “In my career, I have failed so spectacularly,” she says. But looking back, she realizes that the setbacks ended up creating openings to the work that she is doing now. “What I had planned didn’t work out,” she says, “but actually, it helped open my eyes to a different path that I never would have mapped out for myself.” View the full article
-
Dark Matter's parent said the decision to promote its chief technology officer aligns the company to the direction of the market, with further changes to come. View the full article
-
Listing for world’s largest car glass repair group would boost Europe’s lagging market View the full article
-
It’s never been so expensive for Americans to buy a steak or hamburger, but cutting those costs requires ranchers like Stephanie Hatzenbuhler to raise more cattle — and that’s not an easy ask. For a host of reasons, Hatzenbuhler and other ranchers across the country are reluctant to grow the national herd — now its smallest in more than 75 years — and until they do so, demand will outweigh supply, and beef prices will likely remain high. Adding cattle makes sense for some ranchers, but others are struggling to stay afloat with the cattle they have, Hatzenbuhler said. “They’re good times, and they’re bad times,” she said. “It’s a combination of both.” Why is the beef herd so small? Hatzenbuhler will make her choices as cows give birth to about 700 calves this spring on her family’s Diamond J Angus ranch on more than 2,000 wind-swept acres near Mandan, North Dakota. Does she opt to increase her herd, or does she offset the new arrivals by selling an equal number of cattle to be slaughtered? The national herd size isn’t the only factor that determines what beef costs at the grocery store. Still, the dwindling number of cattle is a key reason the average price of all uncooked ground beef in the U.S. was $6.86 per pound in March, 3 cents off the record high set in February, according to federal statistics. That price in March is up nearly 48% from March 2021. The U.S. cattle herd reached a high of 132 million head in 1975, according to the U.S. Department of Agriculture, and that figure has gradually fallen to 86 million this year. Thanks to changes in cattle genetics and feeding techniques, ranchers now produce far more meat from each animal, so despite the much smaller herd, the country’s beef production hit a record 28.4 billion pounds in 2022, said Tim Petry, a North Dakota State University livestock marketing specialist. About 26 billion pounds of beef are expected in 2026. About 2.5 billion pounds of beef were exported to other countries in 2025, and the tight remaining supply, along with the high demand, has caused record prices. Ranchers acknowledge the higher prices, but they face plenty of challenges weighing against growing herds, especially from drought. Drought limits land for grazing Dry conditions have persisted across much of cattle country, with about 63% of the U.S. cattle herd in drought areas, according to the USDA. Some areas have also seen giant wildfires that left no grass for grazing. “You’ve got to have rain. You’ve got to have grass to keep cows on because they’re out on pastures for over half the year, and so that’s been the dilemma, is we had forced liquidation of cows,” Petry said. This time of year, as calves arrive, ranchers decide whether to retain young cows called heifers and calves for breeding herds, and a big factor is pasture conditions, said Bernt Nelson, an American Farm Bureau Federation economist. Feed is the highest cost for ranchers, and due to drought in spots like Texas and Oklahoma, they have had to truck in supplies from elsewhere. Those extra costs make it hard to increase a herd. “When these pasture conditions deteriorate, and water becomes an issue, some of these states have to go as far as to haul hay, haul water from other regions of the country that have grass and easy access to water, and that adds a significant cost to operations,” Nelson said. Even if ranchers opted to raise more cattle, it takes 15 to 24 months for a calf to mature before it can be slaughtered. Role of meat processors in beef prices Ranchers often blame the concentrated meat processing systems — primarily driven by four companies — for high beef prices, but the picture is complicated. In a statement and market updates, the Meat Institute, a meat processors trade group, noted that retailers and food service companies, not packers, set prices for consumers. And the organization said livestock producers were “earning record profits” while packers were losing money. The Meat Institute also argued that the concentration ratio hasn’t “changed appreciably” over the past 30 years. “Rhetoric about beef industry concentration implies that consolidation in the beef packing sector is ongoing and that market power is becoming increasingly concentrated. That is not the case,” the group said. John Robinson, a spokesman for the National Cattlemen’s Beef Association, said he sees many reasons for high prices, and in some cases, meat processors are responsible, but that “it’s far more complicated than most people will give it credit for.” A pest forces border closure Another driver of high prices is the closure of the U.S.-Mexico border to livestock imports to slow the spread of a flesh-eating parasite called the New World screwworm. The closures that began in late 2024 have stopped about 1 million cattle from being hauled from Mexico into the U.S., said Warren Rusche, an extension feedlot specialist at South Dakota State University. The border closure particularly affects cattle feedlots and ranchers who graze cattle in the southern plains. President Donald The President has called for increased beef imports from Argentina, but the country’s expanded quota would be only a tiny percentage of U.S. beef production, Rusche said. Are ranchers getting rich? Hatzenbuhler, the North Dakota rancher, isn’t getting rich, but for ranchers who own their land and equipment, she said it’s a good time to raise cattle. It’s not as good for people looking to break into the business, given the high cost of everything from equipment to fertilizer and the difficulty of finding workers. “If you’re a young guy and want to get in, it’s probably not the time to do it, but if you’re kind of established and been doing this for a while, you’re doing good,” she said. California rancher Mike Williams said he wouldn’t discourage someone from getting into ranching but would caution them, “don’t get too far upside down.” “I would say that we’re finally maybe getting a fair price,” Williams said. “I think people are starting to realize the value of beef, and they’re finding that they’re willing to pay maybe a little more than they have in the past for the quality of the product that they’re getting.” —Jack Dura, Associated Press View the full article
-
It was long assumed that boys were more likely to have attention-deficit/hyperactivity disorder (ADHD). But recent research suggests girls have been widely underdiagnosed—with sometimes devastating consequences. Now, many women who have long suffered from mental health conditions and everyday challenges are identifying ADHD as the underlying cause. “Women are much more likely to have what’s called ‘inattentive ADHD,’ versus ‘hyperactive ADHD,’” says Dr. Sarah Greenberg, a licensed psychotherapist and the vice president of expertise and strategic design for neurodivergence nonprofit Understood.org. “The hyperactivity is really visible to others in the room, whereas for inattentive ADHD that hyperactivity is internal. It might look like daydreaming or staring into space. But I can assure you, there’s a lot happening in the brain.” Dr. Greenberg says that undiagnosed ADHD can create challenges in childhood, from social to academic, leading to lots of self-doubt. Coupled with the over-thinking tendencies of those with inattentive ADHD, many are instead diagnosed with anxiety or depression. That misdiagnosis can have serious consequences, as untreated ADHD has been associated with everything from higher rates of substance abuse to divorce, car accidents, even suicide attempts. Women with ADHD are Often Misdiagnosed According to a study conducted by Understood.org, 72% of women with ADHD have at least two other mental health conditions, like anxiety or depression, and 44% were diagnosed with anxiety, depression or another mental health condition first. Furthermore, 89% say they originally attributed ADHD symptoms—like disorganization, overthinking and chronic lateness—to personal character flaws. “’Hysteria’ was a label given to women for a range of things, from insomnia to anxiety, and the theory rested on uterine imbalance,” explains Dr. Greenberg. “We don’t use that label anymore, but what has persisted is women are more likely to get diagnosed with an emotional disorder rather than ADHD, which is a brain difference.” According to a 2022 study conducted by the American Centers for Disease Control, boys are twice as likely to be diagnosed with ADHD. However, a 2022 study by medical research provider Epic Research found that women aged 23 to 49 were diagnosed twice as frequently as men that year compared to 2020. Males were also diagnosed with ADHD at 28% higher rates than females in 2022, down from 133% in 2010. In the Canadian province of Ontario, prescriptions for stimulant medications—often used to treat ADHD—were more prevalent among adult women aged 18 to 64 than men in 2023. “We’re getting closer to gender parity in adulthood, so that is very much a silver lining,” says Dr. Greenberg. “We’re also getting closer to gender parity in childhood. Whereas we used to see three boys diagnosed for every girl, we’re now seeing two, so that ratio is getting better.” Women with ADHD are Often Treating the Wrong Condition Misdiagnosis is common among women with ADHD, both because of longstanding misconceptions and because many of the diagnostic tools that test for ADHD are based on the hyperactive presentation more common in boys. As a result, women tend to suffer with ADHD well into adulthood before understanding the cause of some of their neurological differences, and the likely culprit behind other lifelong challenges. “It’s really important to get that ADHD diagnosis right, because while anxiety and depression are treatable and can be short term, ADHD is a lifelong difference,” says Dr. Greenberg. “Sometimes depression or anxiety speaks more to symptoms one has experienced, but it’s much more efficient to address ADHD as the primary condition.” There is yet to be a formal study into the relative effectiveness of anxiety and depression treatment on those with undiagnosed ADHD. However, a 2024 study of healthcare records in Wales found that women are more likely to be prescribed antidepressant medication prior to being diagnosed with ADHD, and are more likely to stop using the medication afterwards. “Anecdotally, it’s what we hear from patients all the time,” says Dr. Julia Schechter, a clinical psychologist at the Duke University School of Medicine and co-director of the Duke Center for Girls and Women with ADHD. “We hear that story so often.” “’For years, I was told I was anxious. For years, I was on medication that was not effective. Then I found out I had ADHD, and getting on ADHD medication really reduced the symptoms’.” The Dangers of Living with Untreated ADHD Research shows that those with untreated ADHD are more likely to struggle in school and to maintain employment, have financial challenges, get divorced, get into car accidents and struggle with substance abuse at higher rates. In women, untreated ADHD has also been linked to higher rates of unplanned pregnancy,eating disorders and suicide attempts. According to the Understood.org study, 23.5% of women diagnosed with ADHD report a history of suicide attempts, compared with 8.5% of men with ADHD. “We know that untreated ADHD is linked to so many negative outcomes for everyone,” says Dr. Schechter. “But for women and girls in particular, not treating this condition really can be a matter of life and death.” Awareness and Diagnoses Have Been Skyrocketing Since COVID Longstanding assumptions about ADHD primarily affecting young boys started to change during the pandemic, for many reasons. For one, those with undiagnosed ADHD often learn to cope with the disorder over time, such as by using timers, to-do lists and reminders, sticking to routines and by optimizing their workspace—much of which was disrupted by the pandemic. As a result, adults with undiagnosed ADHD felt the symptoms more acutely. “It was also becoming part of the conversation, and a big part of that was social media,” says Dr. Schechter. “People were turning to social media for medical questions and there was a lot of information out there around ADHD, especially ADHD in females.” Mothers Often Identify Symptoms in Their Children Many parents were also overseeing their children’s remote education, exposing some to signs and symptoms they might have otherwise missed. “They saw more of the challenges they had and started to look for reasons,” says Dr. Emma Climie, an associate professor at the school of applied psychology and director of The Strengths in ADHD Lab at the University of Calgary. “Parents were saying, ‘I’ve had similar challenges, what kind of support is there for my kids, and would that help me as an adult as well?” Dr. Climie explains that ADHD has “a strong hereditary component,” and during the pandemic, parents were more attuned to their children’s learning challenges, prompting more to seek diagnoses for their kids. As they learned more about the disorder, many parents—and especially mothers —identified similar symptoms in themselves. “ADHD apples don’t fall far from ADHD trees,” she says. As a result, the pandemic could go down as a turning point in our cultural perception of ADHD in women and girls, raising awareness of some of the common symptoms and helping those who have long suffered because of the disorder without understanding why. “There’s always been a smaller, vocal group saying, ‘what about women and girls with ADHD?’ but I don’t think they had really found their voice,” Dr. Climie says. “In the last few years, there’s been more people joining that conversation. We’re starting to develop new tools and assessments. And we’re starting to identify that ADHD looks a little bit different in girls and women.” View the full article
-
Investors Marc Andreessen and Ben Horowitz gave $25mn to pro-AI Super Pac in first quarter of yearView the full article
-
If you've had trouble accessing Bluesky this morning, you're not alone. The social media platform has been experiencing intermittent interruptions to service on Thursday. That's obvious from a glance at Downdetector, which shows thousands of user reports of issues with Bluesky starting at about 1:51 a.m. ET, and really kicking off at 2:21 a.m. ET. (Disclosure: Downdetector is owned by Lifehacker parent company Ziff Davis.) While my Bluesky feed does seem to be working at this time, there are still issues causing downtime for users and parts of the platform, including loading notifications. As of this article, Bluesky's status page reads "We are investigating an incident with service in one of our [regions]," and "We are experiencing further issues. We appreciate your continued patience." Bluesky had previously stated that the issue had been fixed, so the platform may be having trouble isolating the root cause of the problem. To that point, it isn't clear what exactly is causing this downtime across Bluesky. That said, this will likely be resolved in due time. Websites occasionally go down for one reason or another, and apart from an attack or catastrophic issue, the source is usually discovered relatively quickly, and a fix implemented shortly after. My guess is by some point today—perhaps by the time you read this article—Bluesky will be back up and running as usual. View the full article
-
When starting a business, comprehension vital registration requirements is critical. First, you’ll need to choose a business structure and file formation documents with the Texas Secretary of State. Next, check your desired business name for uniqueness and file a DBA if necessary. Tax registration with the Texas Comptroller may likewise be required. Compliance with local regulations and obtaining industry-specific licenses can’t be overlooked. Let’s explore these steps in detail to guarantee you’re set up for success. Key Takeaways Choose a suitable business structure, such as an LLC or corporation, to ensure limited liability protection and comply with formation requirements. Register your business name with the Texas Secretary of State and verify its availability through their database. File a DBA certificate with the county clerk if operating under a name different from your legal business name. Obtain necessary licenses and permits based on your industry, including local zoning and health permits where applicable. Apply for an Employer Identification Number (EIN) and register for relevant taxes, including the Texas Franchise Tax and Sales Tax Permit. Choosing the Right Business Structure When you’re deciding on the right business structure, it’s essential to understand the implications of each option available to you. In Texas, the choices include sole proprietorships, partnerships, LLCs, and corporations. A sole proprietorship is simple, requiring minimal paperwork, but you take on personal liability for debts. Partnerships can be general or limited, and you might need a DBA if your name doesn’t include all partners’ surnames. LLCs and corporations require filing a certificate of formation and offer limited liability protection. When considering a Los Angeles County business name search to verify your desired name is available. Familiarizing yourself with these business registration requirements will help you make informed decisions. Registering Your Business in Texas Registering your business in Texas involves several important steps to guarantee compliance with state regulations. First, you must register with the Texas Secretary of State by filing formation documents, such as the Certificate of Formation for LLCs or corporations, or the Partnership Registration for LLPs. Choose a unique business name and verify its availability using the Texas Secretary of State’s database. If you’ll operate under a different name, file a DBA (Doing Business As) Certificate with the county clerk where your business resides. Furthermore, registration with the Texas Comptroller of Public Accounts may be necessary for tax purposes, especially if you’re selling taxable goods or services. Obtaining Necessary Licenses and Permits Maneuvering the terrain of licenses and permits can feel overwhelming, but it’s vital for your Texas business to operate legally. Here’s what you need to take into account: Industry-Specific Licenses: Depending on your business type, you may need licenses like the Texas Sales Tax Permit for selling taxable goods or services. Professional Licenses: If you’re in a regulated field, such as healthcare or construction, make sure you obtain the necessary professional licenses to comply with state regulations. Local Permits: Check your municipality for local permits and zoning compliance, which can include health permits for food service operations. Failure to secure the right licenses can lead to fines and operational delays, so thorough research is important for compliance. Tax Requirements for Texas Start-Ups Understanding the tax requirements for your Texas start-up is crucial, especially since these obligations can significantly affect your business’s financial health. First, you’ll need an Employer Identification Number (EIN) if you hire employees or operate as an LLC or corporation. Most businesses, except sole proprietorships and certain partnerships, must pay the Texas Franchise Tax, which necessitates annual reporting based on revenue. If you sell taxable goods or services, registering for a Texas Sales and Use Tax Permit is required to collect and remit sales tax. Furthermore, you must withhold payroll taxes from employees’ wages. Consulting a business attorney or tax professional is fundamental for guaranteeing compliance with all relevant tax laws. Requirement Description Notes EIN Required for hiring and IRS operations Apply through the IRS Texas Franchise Tax Applies to most businesses, annual reporting needed Exemptions for sole proprietorships Sales and Use Tax Permit Needed for selling taxable goods/services Mandatory for tax collection Payroll Taxes Must be withheld and reported Compliance with state and federal Professional Consultation Crucial for managing tax obligations Helps guarantee compliance Business Banking and Financial Setup Setting up a solid financial foundation for your business in Texas is just as important as grasping your tax obligations. Opening a business bank account is crucial for managing your finances effectively. Here are three key steps to evaluate: Gather Required Documents: You’ll need your Employer Identification Number (EIN), business formation documents, and an operating agreement if you’re an LLC. Protect Personal Assets: Maintaining a separate business account safeguards your personal finances and simplifies tracking expenses and income. Build Business Credit: A dedicated account helps establish business credit, opening doors for future financing options. Many banks offer specialized services, such as merchant accounts and business credit cards, to support your growing business’s financial needs. Frequently Asked Questions What Is Typically Required When Registering a New Business? When you register a new business, you’ll typically need to file formation documents with the state, such as a Certificate of Formation for an LLC or corporation. You’ll likewise obtain an Employer Identification Number (EIN) from the IRS for tax purposes. If you’re using a different name, you must file an Assumed Name Certificate (DBA). Moreover, depending on your business type, you may need specific licenses or permits to operate legally. What Are the 5 SBA Requirements of a Small Business? To qualify as a small business under the SBA, you need to meet five key requirements. First, your business must operate for profit. Second, it must be independently owned and operated. Third, it should adhere to specific size standards, like having fewer than 500 employees or less than $7.5 million in receipts. Fourth, it must be legally organized in the U.S. Finally, your principal office should be located and primarily operate within the country. What Are the Three Essentials Needed to Operate a Business? To operate a business, you’ll need three fundamentals: a solid business plan, adequate funding, and a legal structure. A business plan outlines your objectives and strategies, guiding your operations. Securing adequate funding guarantees you can cover startup costs and sustain operations. Finally, choosing a legal structure—like an LLC or corporation—determines your liability and tax obligations. Each of these elements plays a vital role in establishing a successful and compliant business. Do I Need to Register My Small Business in California? Yes, you need to register your small business in California if you’re forming an LLC or corporation. If you plan to operate under a name different from your legal name, you’ll require a DBA (Doing Business As) certificate. Meanwhile, sole proprietorships don’t need formal registration; filing a DBA is necessary for a fictitious name. Furthermore, check for local business licenses and permits, as requirements vary by industry and location. Conclusion In conclusion, maneuvering the vital business registration requirements in Texas involves selecting the right structure, filing necessary documents, and obtaining relevant licenses and permits. Don’t overlook tax obligations, which may require registration with the Texas Comptroller. Establishing a solid banking and financial setup is additionally important for managing your business effectively. By following these steps, you’ll guarantee compliance and lay a strong foundation for your venture’s success. Taking these actions can help you operate legally and efficiently. Image via Google Gemini This article, "Essential Business Registration Requirements" was first published on Small Business Trends View the full article
-
Music lovers who have complained for years about Ticketmaster fees for concert tickets are surely reveling in a jury verdict Wednesday that found its parent company Live Nation has been running a harmful monopoly over large venues across the U.S. But they will have to wait to see if the verdict leads to changes that make concerts more affordable. Here are some things to know about the verdict in the closely-watched antitrust battle: No immediate relief for concertgoers The lawsuit, initially led by the U.S. government under former President Joe Biden, accused Live Nation of smothering competition and blocking venues from using multiple ticket sellers. Days into the trial, however, President Donald The President’s administration announced it would settle its claims against the concert giant. Some states joined the $280 million settlement, which still needs a judge’s approval, but more than 30 states pressed ahead with the trial. A federal jury in New York found that Ticketmaster had overcharged customers $1.72 per ticket in 22 states, which a judge could order the company to pay back. That could cost Live Nation hundreds of millions of dollars. “The jury’s verdict is not the last word on this matter,” Live Nation said in a statement Wednesday. The verdict brings no immediate relief for concertgoers. But the states view it as a step toward opening the market to other companies in a way that will enhance competition and could slightly lower prices. “There might be a few extra dollars that will come trickle down at consumers who bought tickets through Live Nation,” said Shubha Ghosh, a law professor at Syracuse University who focuses on technology and antitrust law. “Whether ticket prices will go down in the long run, I think it largely depends.” Verdict could cost company hundreds of millions The next step will be determining the penalties. Beyond the hundreds of millions that Live Nation could be ordered to pay, possible sanctions could force the company to sell off some of its venues. Live Nation owns, controls booking for or has equity in hundreds of venues, and its subsidiary Ticketmaster is the world’s largest ticket-seller for live events. Live Nation has continued to insist that it is not a monopoly. The company predicted that once the remedies phase of the case plays out and any appeals are resolved, the outcome likely won’t be much different from the deal it reached with the federal government. U.S. District Judge Arun Subramanian told attorneys to meet and deliver a joint letter by next week that proposes a schedule for next steps. Senators urge judge to scrutinize federal settlement A group of Democratic senators wrote to the judge Wednesday after the verdict, urging him to closely scrutinize the The President administration’s proposed settlement with Live Nation before he considers granting approval. The deal includes a cap on service fees at some amphitheaters and new ticket-selling options that could allow promoters and venues to also use Ticketmaster competitors, such as SeatGeek, Eventbrite or AXS. However, it does not separate Ticketmaster from Live Nation, which was an original goal of the Justice Department’s 2024 complaint. U.S. Sens. Amy Klobuchar, Elizabeth Warren, Cory Booker, Richard Blumenthal, Mazie Hirono and Peter Welch argue the deal was “negotiated under suspicious circumstances” and does not go far enough in restoring competition or protecting customers, artists and independent venues. The Justice Department has called the settlement a “win-win for everybody,” and Live Nation has said it is pleased with a deal that increases access for other promoters. Associated Press journalists Wyatte Grantham-Philips and David Martin contributed. —Hannah Schoenbaum, Associated Press View the full article
-
Social Security’s cost-of-living adjustment (COLA) could stay at 2.8% in 2027, the same as its rate for this year. That’s the latest prediction from The Senior Citizens League (TSCL) and mirrors 2026’s COLA. If enacted in October, it would increase the average benefits check from $2,024.77 to $2,081.46—a $56.69 increase. The TSCL finds the 2.8% increase concerning due to high costs of living, such as rents and mortgages. “The fact is that most senior households already get by on only about 58% as much income as their working-age counterparts, and you’d be hard-pressed to find a middle-class or working-class American who thinks the economy is doing well right now, especially as oil prices rise,” TSCL executive director Shannon Benton said in a statement. She added: “Reforming Social Security needs to follow a two-pronged approach, strengthening revenues and benefits at the same time to ensure prosperity for all Americans, of all ages.” How was the COLA prediction calculated? The nonpartisan senior group’s prediction uses a model incorporating the Consumer Price Index (CPI), the Federal Reserve interest rate, and the national unemployment rate. It releases a new figure monthly, but has maintained a predicted 2.8% COLA since February. The predicted COLA comes as Congress has proposed capping Social Security payments at $50,000 for one person and $100,000 for couples. The “Six Figure Limit” aims to prevent looming insolvency—something that is on track to occur in seven years. However, the TSCL claims most seniors aren’t in favor of the cap, instead in favor of getting rid of a $184,500 limit on income receiving Social Security tax. Notably, TSCL’s prediction is just one estimate floating around. For instance, independent Social Security and Medicare policy analyst Mary Johnson has predicted a COLA of 3.2%, CNBC reports. This figure is up from Johnson’s March prediction of 1.7%, a shift she attributes to rising gas prices. View the full article