Newsletter
Want to keep up to date with all our latest news and information?


ResidentialBusiness
Administrators
-
Joined
-
Last visited
Everything posted by ResidentialBusiness
-
Hay farming is an agricultural practice that has been around for centuries. It involves the growing and harvesting of hay, which is used primarily as feed for livestock. Hay is a critical component of the agricultural industry and plays a vital role in sustaining the livelihoods of farmers across the world. In this article, we will discuss what a hay farm is, the different types of hay that are commonly grown, and how to start a farm that produces hay. What is a Hay Farm? A hay farm is a type of agricultural operation that focuses primarily on the growing and harvesting of hay. Hay is a type of grass or legume that is cut and dried for use as animal feed. It is typically grown in large fields and harvested using specialized equipment, such as hay balers and mowers. Hay farms can be found all over the world, from small family-run operations to large commercial enterprises. How to Start a Hay Farm: Practical Steps to Follow Research and Plan Conduct thorough research on hay farming, focusing on different types of hay that thrive in your area. Decide on the type of hay you plan to grow based on the local climate, soil type, and market demand. Create a comprehensive business plan that outlines your farming objectives, identifies your target market, and provides financial forecasts. Selecting the Right Hay Varieties Choose hay varieties that are well-suited to your region’s climate and soil conditions. Consider the needs of your potential customers, whether they require alfalfa, timothy, clover, or Bermuda grass hay. Securing Suitable Land Look for land that has the right soil type for your chosen hay variety, ideally well-draining, with a pH between 6.0 and 7.5. Ensure the land has adequate sunlight and access to water sources for irrigation if needed. Understanding Soil Health and Fertility Test the soil to determine its nutrient levels and pH balance. Amend the soil based on test results to create the optimal growing conditions for your hay crop. Preparing the Land Till the land to create a smooth seedbed for planting. Remove any weeds or debris to minimize competition and pest risks. Planting the Hay Plant your selected hay variety according to the best practices for seeding rates and depths. Consider using a no-till drill or broadcast seeding method, depending on your land and equipment. Irrigation and Water Management Establish an effective irrigation system to guarantee that your hay farm receives adequate water, particularly during dry spells. Monitor moisture levels regularly to avoid over or under-watering. Pest and Disease Management Apply integrated pest management strategies to control pests and diseases. Regularly inspect your crop for signs of infestation or illness and take action as needed. Harvest Timing and Techniques Identify the best time to harvest your hay, which is typically during the early bloom stage for legumes and the late boot to early head stage for grasses. Use sharp, well-maintained harvesting equipment to ensure a clean cut and minimize losses. Post-Harvest Handling and Storage Bale the hay at the correct moisture level to prevent mold and spoilage. Store the hay bales in a dry, well-ventilated area, off the ground, to maintain their quality. Marketing and Selling Your Hay Develop a marketing strategy to sell your hay, targeting local farmers, livestock owners, and feed stores. Build relationships with your customers to encourage repeat business and referrals. Evaluating and Adjusting Your Practices After each growing season, evaluate the success of your hay farm by analyzing yields, customer feedback, and financial performance. Adjust your farming practices as necessary to improve efficiency, yield, and profitability. By following these steps, you can establish a successful hay farming operation that produces high-quality hay for your target market while managing resources efficiently and sustainably. The Business Side: Simple Steps to Start a Hay Farm Business Starting a hay farm business involves several steps to ensure success. Here are simple steps to help you establish and grow your hay farm business. Name and Brand Your Hay Farm Business Choosing a name and brand for your hay farm business is an important step. The name should be easy to remember, and it should accurately represent your business. You should also consider trademark and domain availability before finalizing your decision. Your brand should reflect your target audience and the values of your business. Form a Legal Entity and Register Your Hay Business To protect your personal assets and comply with legal requirements, you should register your hay farm business as an LLC or corporation. This also helps establish credibility and trust with potential customers and partners. You should also obtain any necessary licenses and permits for your business and make sure you have adequate insurance coverage. Sort Out Taxes, Licenses, Permits, and Insurance When starting a hay farm business, you need to familiarize yourself with tax requirements, obtain any necessary licenses and permits, and ensure you have adequate insurance coverage. This helps you comply with legal requirements, protect your business and assets, and avoid any potential fines or penalties. Create a Hay Farm Business Plan Creating a business plan is essential for any successful hay farm business. It defines your business objectives, target market, marketing strategies, and financial projections. Your business plan should also identify potential challenges and solutions and include a clear roadmap for the future growth of your business. Market Research Conducting market research is crucial to understanding your target market and competition. You need to identify market trends and potential customers and assess demand and pricing in your area. This helps you tailor your marketing strategies to effectively reach and engage with your target audience. Buy the Necessary Equipment for Baling Hay To operate a successful hay farm business, you need to invest in the necessary equipment, including tractors, mowers, balers, and storage facilities. You can purchase or lease equipment, depending on your budget and long-term goals. It’s important to research and compare options to ensure you get the best value for your investment. Open a Business Bank Account Opening a separate business bank account is important for managing your finances and keeping accurate records. It also helps you separate your personal and business finances, making it easier to track expenses, monitor cash flow, and prepare tax returns. You can also access financial services and benefits specifically designed for small businesses. Market the Business Developing a comprehensive marketing strategy is crucial to the success of your hay farm business. This should include a mix of online and offline tactics to reach and engage with your target audience. You can use social media, email marketing, content marketing, and advertising to increase brand awareness and drive sales. Choose Where to Sell Your Products Identifying potential buyers and sales channels is an important step in growing your hay farm business. This includes feed stores, horse stables, and livestock auctions, as well as offering delivery services to customers who need it. You should also consider building relationships with potential buyers to establish long-term partnerships. Expand Your Hay Farm Business Exploring opportunities to expand your hay farm business is key to sustained growth. This can include diversifying your product line, increasing production, or offering value-added services. You should also continuously monitor market trends and adapt your strategies to meet the evolving needs of your customers. What is Needed to Start a Hay Farm and How Much Does it Cost? Starting a hay farm requires suitable land, equipment, and baling machinery. The costs of starting a hay farm depend on factors such as land availability and equipment quality. A small hay farm can cost between $10,000 to $20,000, while a large one can easily cost hundreds of thousands. Suitable Land: Hay farming requires land that is suitable for growing hay. The ideal soil type should be well-draining and have a pH between 6.0 and 7.5. The land should also receive adequate sunlight and have access to water. The cost of purchasing or leasing suitable land varies depending on location and size. Equipment: Starting a hay farm requires a significant investment in equipment. This includes a tractor, mower, tedder hay rake, and baling equipment. The cost of equipment depends on the size and quality. Used equipment can be a cost-effective option for beginners. Tractor: A tractor is essential for every hay farm. It facilitates tasks such as plowing, tilling, planting, and harvesting. The price of a new tractor typically falls between $20,000 and $100,000, whereas a used tractor usually costs between $5,000 and $30,000. Mower: A mower is used to cut the hay before it is baled. The cost of a new mower can range from $2,000 to $10,000, while a used mower can cost between $500 to $5,000. Tedder & Hay Rake: Once the hay is cut, it must be dried before baling. A tedder helps to aerate the hay, ensuring it dries evenly. After that, a hay rake is employed to collect the dried hay into rows for baling. The price for a new tedder and hay rake typically ranges from $5,000 to $15,000, whereas used equipment can cost anywhere from $1,000 to $5,000. Baling Equipment: Baling equipment is used to compress the hay into bales for storage or transport. The cost of a new baler can range from $10,000 to $50,000, while a used baler can cost between $2,000 to $10,000. Other baling equipment includes wagons, trailers, and wrappers, which can add additional costs. The Hay Farm Industry in the United States The hay farming industry in the United States is a significant sector of the agriculture industry. Hay is an essential feed source for livestock, making it a crucial element for the country’s meat and dairy production. The United States is the world’s largest hay producer, with over 53 million acres of hay harvested annually. The top hay-producing states in the U.S. include California, Texas, South Dakota, Montana, and North Dakota. The industry has been growing steadily over the years, and advancements in technology and farming techniques have improved the efficiency and profitability of hay farming operations. The demand for hay continues to rise, and the industry is expected to remain an important contributor to the U.S. agriculture industry. Deciding What Type of Hay Farm to Run Choosing the right type of hay to grow on your hay farm is essential to your farm’s overall success. By considering your livestock’s nutritional needs, soil type and climate, market demand, and cost and labor, you can make an informed decision that will benefit both your farm and your livestock. Common Plants to Grow for Hay Production There are several different types of hay that are commonly grown on hay farms. These include: Timothy Hay: Timothy hay is a variety of grass hay commonly cultivated in North America. It is recognized for its rich nutritional value and is frequently used as feed for horses. Alfalfa Hay: Alfalfa hay is a legume hay that is high in protein and other essential nutrients. It is commonly used as feed for dairy cows and other livestock. Clover Hay: Clover hay is another type of legume hay that is commonly grown on hay farms. It is high in protein and is often used as feed for horses, sheep, and other livestock. Bermuda Grass Hay: Bermuda grass hay is a warm-season grass hay that is commonly grown in the southern United States. It is known for its high yields and is often used as feed for cattle and other livestock. Growing Hay for DIY on a Family Farm or Growing Hay to Sell You can either grow and let your livestock eat hay on your own farm, or you can grow hay to sell to other farmers and livestock owners. Consider factors such as soil type, climate, and market demand when choosing which type of hay to grow. How to Source Equipment to Grow Hay and For Harvesting Hay Sourcing equipment is essential to growing and harvesting hay. The process involves finding the right equipment that matches your needs, budget, and timeline. There are three main ways to source equipment: New: Buying new equipment is an option if you have a higher budget and want to invest in equipment that will last for years. Many farm equipment suppliers offer warranties on new equipment, and you can customize purchases to your specific needs. However, it’s more expensive than used or rented equipment. Used: Buying used farm equipment is a cost-effective option. However, it’s crucial to inspect the equipment carefully to ensure it’s in good condition. Look for reputable sellers, and research the equipment’s maintenance history before buying. Used equipment may have a shorter lifespan than new equipment. Rent: Renting equipment is an option if you don’t want to invest in equipment or only need it for a short period. Renting allows you to use high-quality equipment without the upfront costs of buying. However, it may be more expensive in the long run if you need equipment for extended periods. Renting is also subject to availability, so plan accordingly. The Steps in Making a Hay Crop Understanding the steps in making a hay crop can help farmers achieve maximum yield and quality. Let’s look at what the process involves… Preparing the Soil Soil preparation is essential for the success of the hay crop. This process includes tilling the soil to create a smooth seedbed, applying fertilizers and lime to adjust the soil pH, and clearing away any weeds or debris. Planting and Growing After the soil is prepared, the hay crop is planted and grown. The seed is spread evenly across the prepared seedbed and then covered with a layer of soil. The crop is then allowed to grow, and farmers must monitor it for weed growth and disease. Mowing Mowing is a crucial step in the hay crop process. Farmers must wait until the crop reaches the optimal height before mowing. This typically occurs when the crop is in the mid to late bud stage. Tedding Tedding involves fluffing and spreading the cut hay out to dry. This step helps to ensure the hay is dry and ready for raking. Raking Raking is the process of gathering the hay into rows to facilitate drying and baling. Farmers use specialized machinery, such as a rake or tedder, to move and shape the hay into neat rows. Stacking and Baling in Round Bales or Square Bales The final step in the hay crop process involves stacking and baling so there’s no loose hay. Farmers can choose to bale hay in either round or square bales, depending on their preference and the type of machinery they have. The farmer can then store hay so it’s ready for transport. StepDescription Preparing the SoilTilling, adding fertilizers, and correcting pH to create a suitable seedbed. Removing weeds. Planting and GrowingSpreading seed evenly, covering with soil, monitoring growth, and managing weed and disease. MowingCutting the hay crop at the optimal height, usually in the mid to late bud stage. TeddingFluffing and spreading cut hay to aid in drying and moisture evaporation. RakingGathering hay into neat rows to facilitate drying and baling using specialized machinery. Stacking and BalingCreating bales (round or square) from the dried hay. Stacking bales for storage or transport. Hay Farm: Downsides to Consider Despite its benefits, hay farming has downsides to consider. Weather conditions, such as drought or excessive rain, can reduce hay quality and yield. Hay storage can also be a challenge, and the cost of equipment and labor can be high. Hay Farming: A Sustainable Business Venture In conclusion, starting a hay farm represents a promising and sustainable business venture in the agricultural sector. With careful planning, appropriate land selection, and adherence to best farming practices, hay farming can yield significant returns while contributing to the agricultural community and supporting livestock nutrition. Achieving success in this area demands a commitment to soil health, effective crop management, and a thorough understanding of the market. However, for those who are prepared to invest the necessary time and resources, the rewards can be substantial. As the demand for quality animal feed continues, hay farming stands out as a valuable and enduring business idea. Whether you’re looking to support your own livestock or supply to local farmers and businesses, a well-managed hay farm can serve as a robust foundation for a thriving agricultural business. Hay Farm FAQs What is the Difference Between Hay and Straw? Hay is a forage crop harvested for livestock feed, while straw is a byproduct of harvested grains used primarily for bedding and other non-feed purposes. How Hard is Hay Farming? Hay farming can be physically demanding and time-consuming, requiring specialized equipment and knowledge. However, it can also be a rewarding and profitable industry. Can a Hay Farm be Profitable? Yes, a well-managed hay farm can be profitable. Factors such as crop yield, market demand, and operational efficiency can impact profitability. Is Hay Easy to Grow? Hay requires specific soil, moisture, and weather conditions for optimal growth. However, with proper preparation and care, hay can be successfully grown in many regions. How Much Hay Can 1 Acre Produce a Year? The amount of hay 1 acre can produce in a year varies depending on factors such as soil quality, crop variety, and weather conditions. On average, 1 acre can produce 1-4 tons of hay per year. Is it Worth it to Grow Hay? Whether growing hay is worth it depends on factors such as market demand, crop yield, and operational costs. With proper management, growing hay can be a profitable endeavor. How Should Hay Bales be Stacked to Reduce Waste? Hay bales should be stacked on a well-drained surface, preferably with a moisture barrier, and kept out of direct sunlight to prevent spoilage. Stacking bales in a crisscross pattern can also help reduce waste. Are Round Bales or Square Bales Better for Hay? The choice between a round bale and small square bales or large square bales depends on factors such as storage space, feeding method, and equipment availability. Round bales are generally better for outdoor storage, while square bales are easier to handle and stack. Image: Depositphotos This article, "How to Start a Hay Farm" was first published on Small Business Trends View the full article
-
Invoice financing, also known as accounts receivable financing, is a financial solution where businesses use their unpaid invoices as collateral to obtain immediate working capital from lenders or financing companies. Instead of waiting for customers to pay invoices, businesses can access a significant portion of the invoice value upfront, which helps improve cash flow and allows them to meet immediate financial obligations or invest in growth opportunities. What is Invoice Financing? Invoice financing is a form of short-term borrowing that enables businesses to unlock the value of their accounts receivable by selling unpaid invoices to a third-party financing company at a discount in exchange for immediate cash. https://youtube.com/watch?v=NdTBkvfCssg%3Fsi%3DjaPaug92KOJT-KEO How Invoice Financing Works Let’s say a small business provides goods or services to a client with invoice payment terms of net 30 days. However, the business needs immediate funds to cover operational expenses or invest in expansion. Instead of waiting for 30 days to receive payment, the business can choose to sell its unpaid invoice to an invoice financing company. The financing company may advance around 80-90% of the invoice value upfront, minus a fee (discount rate), and hold the remaining amount as a reserve. Once the client pays the invoice, the financing company releases the reserve amount to the business minus any fees or charges. The Role of Invoice Financing Companies Invoice financing companies are essential in the business landscape, as they provide vital liquidity to companies experiencing cash flow challenges caused by slow-paying customers. These firms serve as intermediaries, connecting businesses that require immediate cash with investors or lenders who are interested in purchasing invoices at a discounted rate. These companies assess the creditworthiness of the invoices and the businesses issuing them, determine the risk involved, and offer financing solutions tailored to the needs of different businesses. By offering timely access to working capital, invoice financing companies help businesses maintain operations, manage growth, seize opportunities, and avoid the pitfalls of late payments. Invoice Financing vs. factoring Here are the differences in two key categories: Ownership of Invoices: In invoice financing, the business retains ownership of the invoices, using them as collateral to secure a loan. In contrast, invoice factoring involves selling the invoices outright to a third-party factor. Responsibility for Collection: In invoice financing, the business usually handles the collection of payments from its customers. Conversely, in invoice factoring, the factor assumes the responsibility for collecting these payments. Invoice Factoring Invoice factoring is a financial arrangement in which a business sells its accounts receivable (invoices) to a third-party financial entity, referred to as a factor, at a discounted rate. The factor provides an upfront advance, usually covering about 70-90% of the invoice value, and proceeds to collect payments directly from the business’s customers. After the customers fulfill their payments on the invoices, the factor disburses the remaining balance to the business, deducting a fee or discount rate. The Role of Factoring Companies Invoice factoring companies provide a valuable service to businesses by offering immediate access to cash flow without taking on additional debt. They help businesses maintain stable cash flow, manage expenses, and seize growth opportunities by converting accounts receivable into immediate working capital. Additionally, invoice factoring companies often provide services such as credit checks on customers, collections management, and credit insurance, which can help mitigate the risk of non-payment and improve overall financial efficiency for businesses. By outsourcing accounts receivable management and providing flexible financing solutions, invoice factoring companies play a crucial role in supporting the growth and stability of businesses across various industries. FeatureInvoice FinancingInvoice Factoring DefinitionA way for businesses to borrow money against the amounts due from customers without selling the invoices.A financial transaction where a business sells its invoices to a third party at a discount to improve cash flow. Control of InvoicesThe business retains control over the collection of payments.The factor (third-party) takes control of the accounts receivable and the collection process. ConfidentialityUsually confidential, customers may not be aware that financing is being used.Often not confidential, customers are aware as they make payments directly to the factoring company. CostFees are based on the amount of financing and the time it takes for customers to pay.Fees include a factoring fee based on a percentage of the invoice, along with additional fees for the service provided. Speed of FundingFunds can be available quickly, often within 24-48 hours of approval.Similar to invoice financing, funds are typically available quickly after selling the invoices. CreditworthinessDepends more on the creditworthiness of the borrowing company.Depends on the creditworthiness of the customers (debtors) and the quality of the invoices. Risk and ResponsibilityThe business remains responsible for the collection of payments and any bad debts.The factor assumes the risk of non-payment (in non-recourse factoring), reducing the risk for the original business. Relationship with ClientDirect relationship with the client is maintained as the business continues to handle its accounts receivable.The factor may interact directly with clients, which could affect the business's relationship with its clients. FlexibilityMore flexible, as businesses can choose which invoices to finance.Less flexible, as factors often require a commitment to factor a minimum amount or all invoices from selected customers. PurposePrimarily used to improve cash flow without taking on new debt.Used to outsource sales ledger management and improve cash flow, while also potentially offloading credit risk. Benefits of Invoice Financing for Small Business Improved Cash Flow: Invoice financing offers businesses immediate access to cash, enabling them to fulfill financial obligations, pay employees and suppliers, and invest in growth initiatives without having to wait for customer payments on invoices. Flexible Financing: Unlike traditional loans, invoice financing does not require collateral beyond the invoices themselves, making it accessible to businesses with limited assets. It’s also typically easier and quicker to obtain compared to traditional financing options. Risk Mitigation: Invoice financing can help businesses mitigate the risk of late payments or non-payment by providing a steady stream of cash flow based on their accounts receivable. Opportunity for Growth: With improved cash flow, businesses can take advantage of growth opportunities, such as expanding operations, launching new products or services, or pursuing new markets. Eligibility Criteria for Invoice Financing Business Stability: Lenders typically prefer businesses with a history of operations and a proven track record of invoicing and collecting payments. Creditworthiness of Invoices: The invoices being financed should be from creditworthy customers to minimize the risk for the financing company. Minimum Invoice Value: Some lenders may have minimum requirements for the value of invoices eligible for financing. Absence of Legal Issues: Businesses should not have any pending legal issues or disputes related to the invoices being financed. Steps to Secure Invoice Financing Application: The business submits an application to the invoice financing company, providing details about their business, invoices to be financed, and financial history. Due Diligence: The financing company conducts due diligence to assess the creditworthiness of the invoices and the business, which may include credit checks on customers and a review of financial statements. Agreement: Once approved, the business and the financing company enter into an agreement outlining the terms and conditions of the financing arrangement. Submission of Invoices: The business submits the invoices to the financing company for verification. Funding: After verification, the financing company advances a percentage of the invoice value to the business. Payment Collection: The financing company may collect payments directly from customers or allow the business to collect payments, depending on the type of invoice financing. Invoice Financing Costs Discount Rate or Fee: Companies that offer invoice financing impose a fee or discount rate, usually calculated as a percentage of the invoice’s total value, for their financing services. Additional Charges: There may be additional charges, such as processing fees or administrative fees, associated with invoice financing. Interest: In some cases, invoice financing may involve interest charges, particularly if the financing arrangement extends beyond a certain period. Late Payment Penalties: Companies could face penalties or extra charges due to delayed payments or failure to pay invoices. Choosing the Right Invoice Financing Company or Invoice Factoring Company Here are some factors to consider when choosing an invoice financing or factoring company: Control Over Collections: If a business prefers to maintain control over collections and customer relationships, invoice financing might be more suitable. On the other hand, if the business wants to offload collections responsibilities and streamline cash flow, invoice factoring might be preferred. Cost Considerations: It is essential for businesses to evaluate the costs linked to invoice financing versus invoice factoring. This includes analyzing discount rates, fees, and any other charges to identify the most cost-effective choice. Customer Perception: Some businesses may be concerned about how their customers will perceive invoice financing or factoring. Invoice financing allows businesses to maintain direct relationships with customers, while invoice factoring involves customer notification of the financing arrangement. Common Misconceptions About Invoice Financing Only for Desperate Businesses: One common misconception is that invoice financing is only for struggling or desperate businesses. In reality, it’s a common and legitimate financing option used by businesses of all sizes to manage cash flow effectively. High Cost: Yes, there is an invoice financing cost. While there are costs associated with invoice financing, they can be offset by the benefits of improved cash flow and access to working capital, making it a cost-effective solution for many businesses. Complexity: Some businesses may perceive invoice financing as a complex or cumbersome process. However, with streamlined online platforms and efficient processes, invoice financing can be relatively straightforward and accessible. Invoice Discounting: An Alternative Approach Invoice discounting is a type of invoice financing where a business retains control over collections and customer relationships. Instead of selling invoices outright to a financing company, the business borrows against the value of its unpaid invoices, using them as collateral to secure a loan. The lender advances a percentage of the invoice value upfront, typically 70-90%, minus a discount or interest rate. The business retains responsibility for collecting payments from customers and repays the loan, along with any fees or interest, once the invoices are paid. Invoice Financing Explained Given the advantages of invoice financing, including improved cash flow, flexibility, and accessibility, it’s likely to remain a popular financing option for businesses in the future. As technology continues to advance and streamline financial processes, invoice financing may become even more accessible and efficient, further driving its adoption among businesses. FAQs: Invoice Financing How does accounts receivable financing help manage outstanding invoices? Accounts receivables financing helps manage outstanding invoices by providing immediate cash flow based on the value of unpaid invoices. By converting accounts receivable into cash, businesses can meet immediate financial obligations, invest in growth initiatives, and avoid the negative impacts of late payments or cash flow gaps. What’s the difference between accounts receivable financing and traditional loans? Collateral: Traditional loans often require tangible collateral, such as real estate or equipment, while accounts receivable financing uses invoices as collateral. Approval Process: Traditional loans may involve a lengthy approval process, including credit checks, financial assessments, and documentation requirements. Accounts receivable financing can be faster and more accessible, based primarily on the creditworthiness of invoices and customers. Repayment Structure: Traditional loans have fixed repayment terms, including principal and interest payments over a set period. Accounts receivable financing is more flexible, with repayment typically tied to the collection of invoices. Risk Sharing: Accounts receivable financing companies assume some of the risk associated with unpaid invoices, whereas traditional lenders may require businesses to bear the full risk of non-payment. Read More: What is an Invoice? How to Create an Invoice Image: Envato Elements This article, "What is Invoice Financing and How Does it Work?" was first published on Small Business Trends View the full article
-
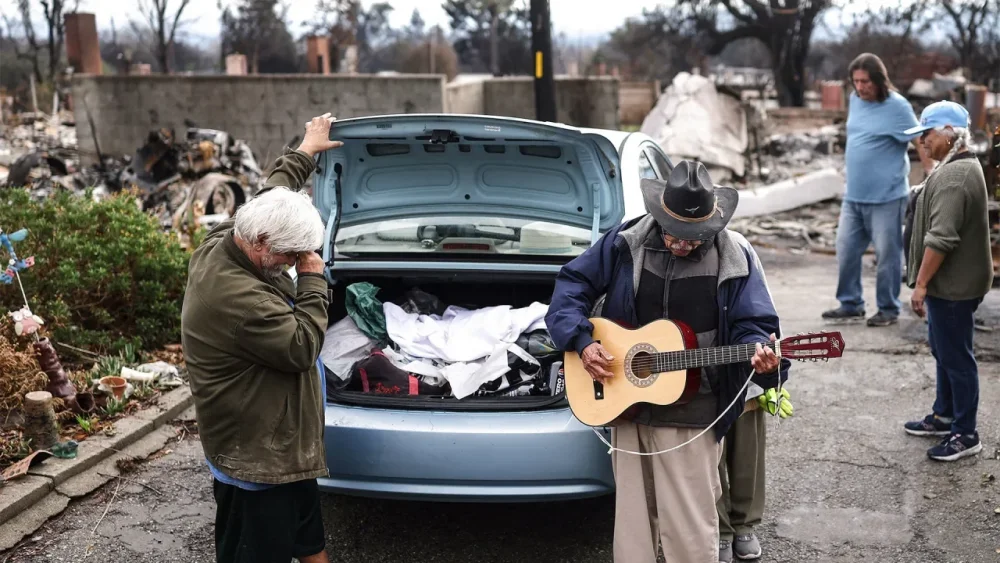
Rain-parched Southern California finally received some much-needed precipitation recently, offering some relief from the Los Angeles wildfires which displaced more than 150,000 people from their homes—and either razed or damaged some 15,000 structures. Of course, not everyone jumped to help. But amid the widespread devastation came what seems like, in our socially and politically fraught times, an unlikely ray of hope: A convergence of communities, of neighbors helping each other in whatever way possible and even heading out to assist complete strangers. The goodwill and altruism born from this calamity has been a boon to exhausted and overwhelmed firefighters and public resources. But why does it seem to take epic disasters to bring people together in the first place? Social behavior and trauma Psychological research provides fascinating insights into that very question. One particularly influential paper published in the American Journal of Orthopsychiatry in 2008 dubs this phenomenon of charity and communal support “altruism born of suffering.” “Research on altruism has focused on its positive roots, whereas research on the effects of victimization and suffering has focused on aggression and difficulties in functioning,” write the study authors. “However, anecdotal evidence, case studies, and some empirical research indicate that victimization and suffering can also lead people to care about and help others.” One of the paper’s authors, prominent psychologist and professor emeritus Ervin Staub at UMass Amherst, has expounded on his findings in the years since, noting the real-world evidence from studies of people’s social behavior following a traumatic event, such as the 2004’s devastating earthquake and tsunami in the Indian Ocean. “In one study, some participants reported that they have suffered because of abuse or violence against them in their families, because of harmful behavior against them as members of a group, or because of natural disasters,” Staub wrote in Psychology Today. “Months later they expressed more empathy with, and feelings of responsibility for helping people affected by the tsunami in Asia in 2004, and volunteered more to collect donations for them, than people who reported that they had not suffered. They also volunteered more for causes that involved helping people.” Tightening communities A trio of experts who spoke with Fast Company added further context to the social psychology of collective trauma events, group identity during times of disaster, and community cohesion after mass tragedies which helps explain this sudden impulse toward altruism and empathy. “There are place communities like we had in Altadena, and that’s very meaningful, and it’s not something that everyone has. But there are also these other kinds of communities of identity, you know, like people will say, I belong to the gay community, or I belong to the community around a particular organization,” says John Brekke, professor emeritus at the USC School of Social Work—and, incidentally, an Altadena resident whose own home was greatly damaged by the recent wildfires. “So, you know, it’s interesting when you see people who all of a sudden come together around this almost community of disaster, in a way, they feel themselves. They can be a part of something by participating in this community of helpers, really, either through giving money or lending time or actually taking people in, and that act of giving at the community level seems to be as meaningful as literally giving to someone that you’re right next to who needs some help.” There’s a neurobiological aspect to this, too, Brekke says, explaining that, “it not only feels good from a spiritual point of view, if people are being spiritual, but it also feels good from a psycho-biological perspective, because you get a rush of great stuff into your system when you are being empathic and when you are giving to others.” This includes biochemical releases of things like serotonin and oxytocin, which lead to feelings of contentment, well-being, and connection. Individualism and identity Unfortunately, whether that feeling of empathy and good will persists after a collective traumatic event like the wildfires is a more complicated question. Some of that has to do with American societal values. “American mainstream society is about rugged individualism,” says Jorja Leap, a professor of social welfare and executive director of the UCLA Social Justice Research Partnership. “Here you’re an individual, you’re taught. Whether it’s the frontier, whether it’s space travel, whether it’s running for office, we look at individual personality and individual strengths, and we tend to lift that up more than the idea of community, so people are expected to make it on their own.” So, while disasters such an earthquake or war may bring people together, there can be an ensuing cynicism, she adds. (Case in point: The ongoing battle over fire insurance and which communities’ houses will be rebuilt in Los Angeles.) “We may be incredibly altruistic and responsive and then incredibly cynical, and sometimes that cynicism is self-protective. I really believe that cynicism is just cover up for fear,” adds Leap. Another expert, Alison Holman, a professor at the UC Irvine School of Nursing and UCI’s School of Psychological Science, has extensive experience researching the effects of individual and collective traumas, including Southern California wildfires. Like USC’s Brekke, she believes identity is a key factor that drives empathy and altruism during crisis moments. “What may be happening is that people identify, to some extent, with the people, the victims,” she says. “We have found in our work that identifying with victims is really something that helps to encourage people to engage in pro-social behavior. So, when people identify with them, meaning, ‘Oh my God, I lived there, I lived in that area,’ or, ‘Oh my God, I’ve lost my home,’ or, ‘Oh my God, I know what it’s like to be threatened by that,’ it may just instigate in people that sense of identification that would make them want to help out.” That’s certainly a phenomenon playing out in Los Angeles at the moment. Whether it leads to lasting change in people and more community engagement after the blaze, and in an era where climate change is expected to lead to ever-cascading calamities, is a more open question. View the full article
-
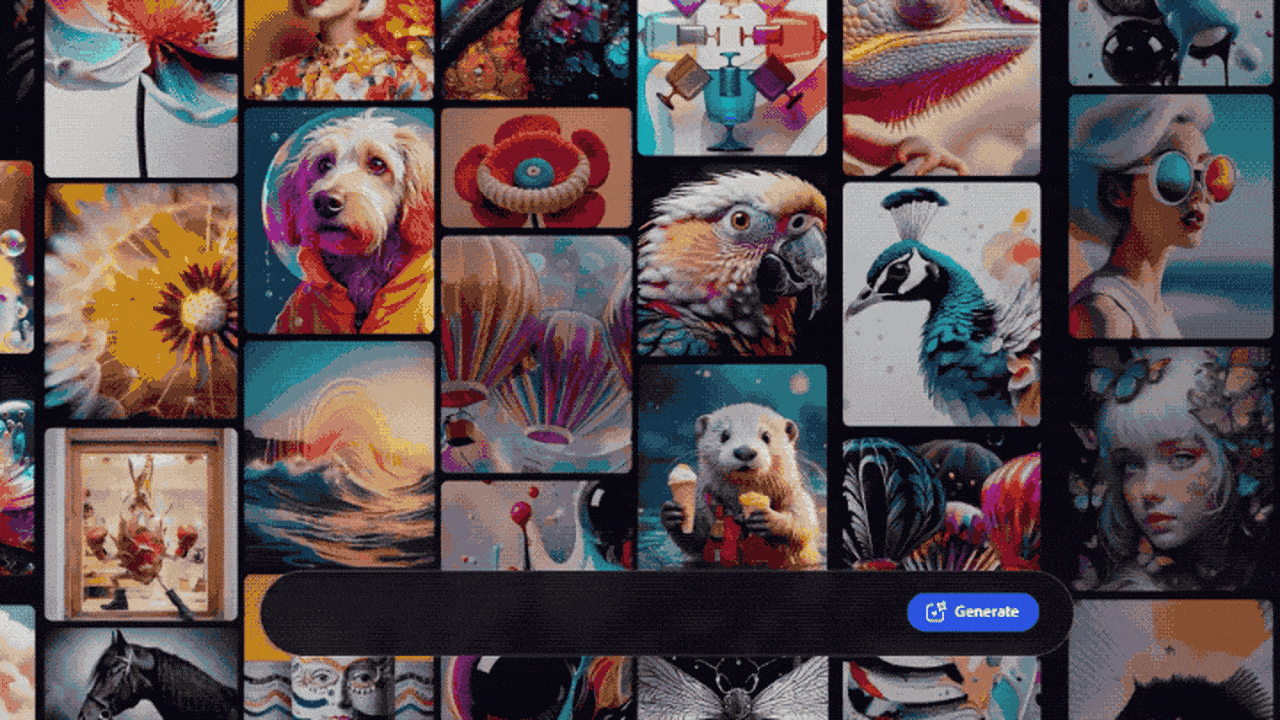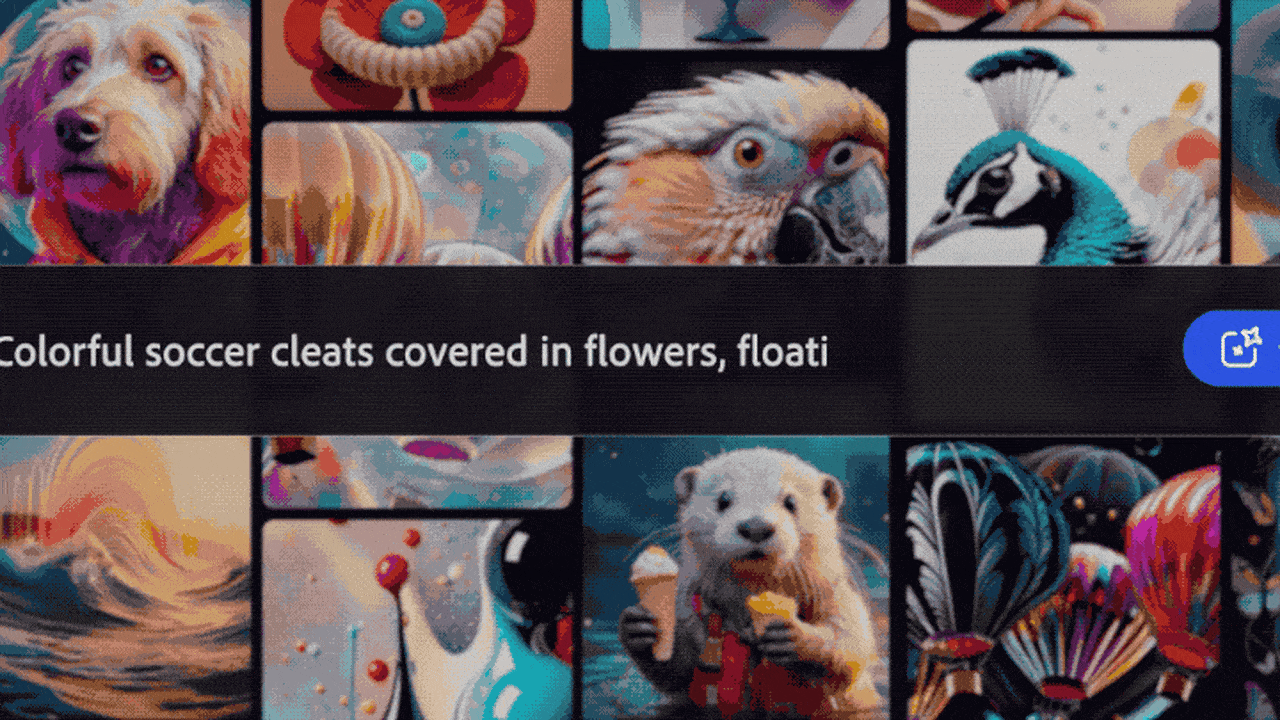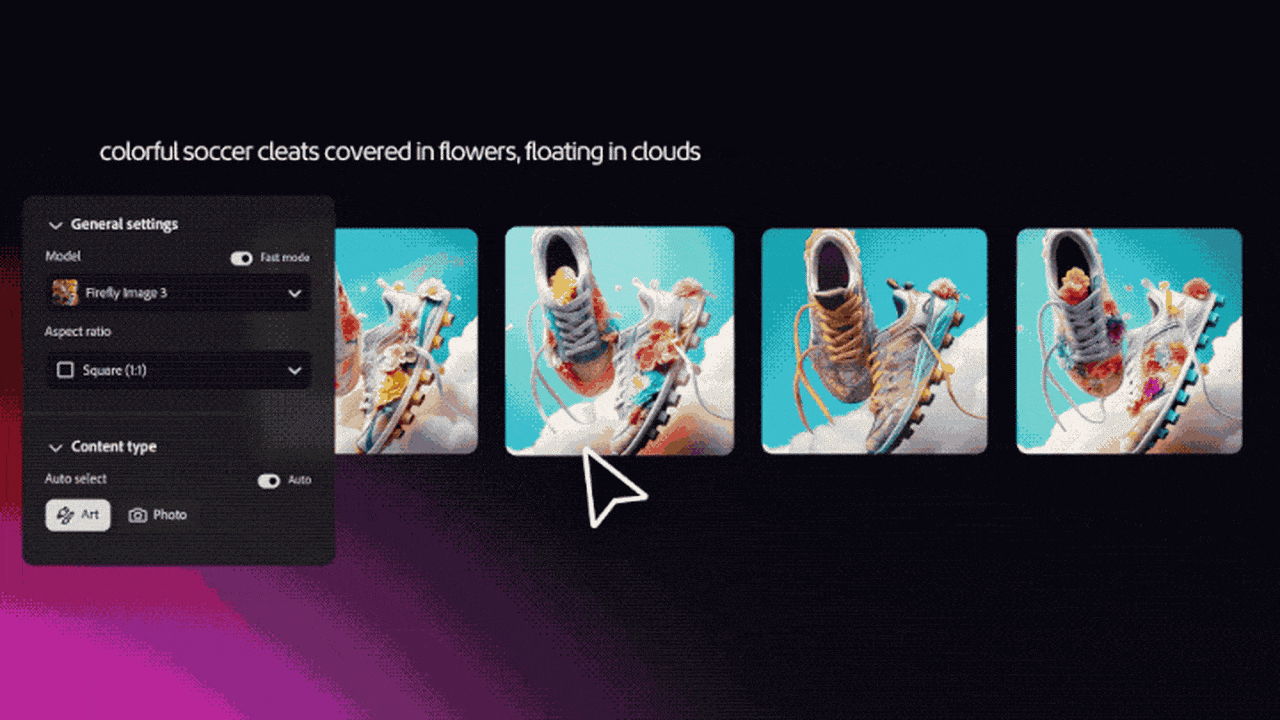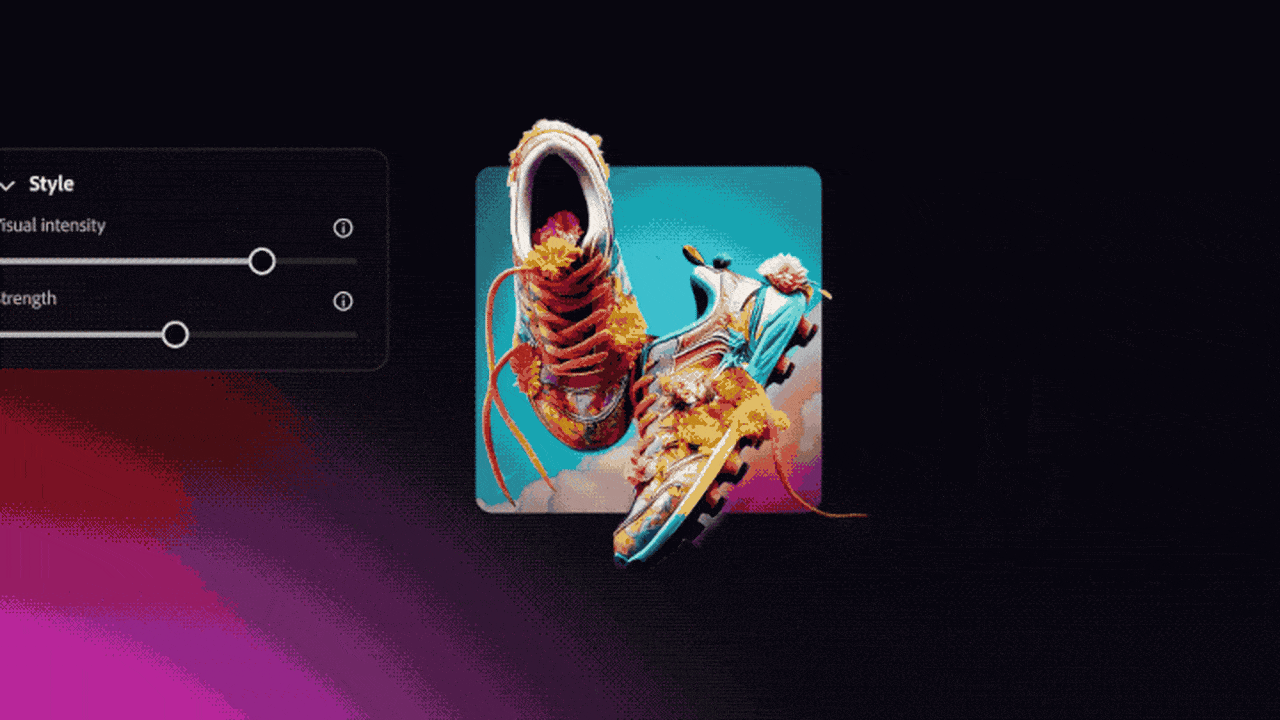
Nearly a year after Adobe first teased video AI features, the company is finally bringing its new video AI model to market. Today, the company is launching its Firefly Video Model in public beta. The model comes alongside a new Firefly web application, which essentially gathers all of Adobe’s AI tools, including existing features like Text to Image and Generative Fill, under one roof. Users can access Firefly’s web app through two subscription tiers—Firefly Standard and Firefly Pro—which retail for $9.99 and $29.99 per month, respectively. [Image: Adobe]What is Adobe’s new Firefly video model?Firefly Video Model is Adobe’s answer to existing video models like Open AI’s Sora and Meta’s new Movie Gen. Using the brand’s new suite of tools, creators can turn a written prompt into a video clip, convert an existing image into a video, and even translate audio and video into multiple different languages. Adobe’s video AI capabilities are late to market, but that’s par for the course for a brand that got into generative AI nearly a year after its main competitors back in 2022. In the past, Adobe has set itself apart in the AI space with stringent IP protections (it only trains Firefly on licensed content and bills its new video model as the industry’s “first commercially safe” video AI) and by making significant improvements to its new features over time. It remains to be seen whether Firefly Video Model will follow a similar upward trajectory. What can it do?[Image: Adobe]Text to VideoFirefly’s Text to Video feature is most comparable to OpenAI’s Sora. Users enter a specific prompt in a text box, which is then converted to a five-second video clip. The feature incorporates Adobe’s signature easy-to-follow UI with a drop-down menu that allows creatives to tweak aspects of its output like shot size, camera angle, and motion. Image to VideoAdobe is positioning its Image to Video feature as a kind of brainstorming tool for video editors. It’s similar to Text to Video, except the user can input an image alongside a written prompt to bring a specific frame to life. In a demo video shared by the company, an editor takes a still frame of an astronaut flipping a switch and asks Image to Video to create a shot of the astronaut unplugging a cord instead. It’s an example of a quick edit that could help an editor better convey their project’s intended mood to supervisors, she says. [Image: Adobe]Translate VideoTranslate Video—available in 20 different languages—is Adobe’s offering to help creators cut down on translation and dubbing services. Per a press release, “With voice, tone, cadence and acoustic match when translating video content into different languages, creators can [spend] less time on dubbing performance and audio mixing.” Right now, Firefly Video Model isn’t especially groundbreaking, but it will help plenty of Adobe creators streamline their production processes without turning to an outside video AI application, especially when just about every design platform wants to be creatives’ only platform. In an interview with Fast Company back in September, Adobe CTO Ely Greenfield noted that, for a generative AI tool that produces common stock images to make it into an Adobe product, the result should be acceptable 10/10 times. However, he added, for results with more specificity, “getting it right 1/10 times is still a huge savings. It can be a little frustrating in the moment, but if we can give people good content 1/10 times that saves them from going back to reshoot something on deadline; that’s incredibly valuable.” As Adobe continues to iterate on its Firefly Video Model, that success rate is only bound to go up. View the full article
-
We may earn a commission from links on this page. Deal pricing and availability subject to change after time of publication. A good video doorbell should do two things well: show you who’s at your door and make it easy to interact with them. The Arlo Video Doorbell 2K (2nd Gen) does both. Originally priced at $129.99, it's now $59.99, its lowest price ever, according to price trackers. Arlo Video Doorbell 2K $49.97 at Walmart $79.00 Save $29.03 Get Deal Get Deal $49.97 at Walmart $79.00 Save $29.03 That’s a serious drop for a doorbell that PCMag named Editor’s Choice and Best Video Doorbell of the Year 2024. With a crisp 2K resolution (1,944 x 1,944 pixels), a 180-degree field of view, and 12x digital zoom, this doorbell lets you see everything from a delivery driver’s face to the package at their feet. You can either hardwire it to an 8-24V transformer for continuous trickle charging or use it wirelessly with its built-in battery that lasts up to four months per charge via USB. It starts recording when motion is detected or when the doorbell button is pressed. When that happens, instead of just sending push notifications, this doorbell calls your phone which you can answer or decline like a regular call. If you pick up, you'll get a live video feed with two-way talk (or you can play a pre-recorded message if you’re not in the mood to chat). This PCMag review notes that daytime video has sharp details and vibrant colors, while night vision is clear in black-and-white up to 25 feet away. That said, it does not support color night vision—if you need that feature, the Ring Battery Doorbell Plus ($149.99) might be a better alternative. Also, there’s no local storage, meaning if you want access to recorded clips, you’ll need an Arlo Secure subscription. Plans start at $7.99/month for a single camera (or $17.99/month for unlimited cameras), giving you 60 days of cloud storage, smart alerts, and object detection. And, if you require 24/7 emergency response, you'll need to subscribe to the $24.99/month Premium plan. You can manage and control the Arlo Video Doorbell 2K using the Arlo Secure app, including accessing live streams, using two-way/muting audio, adjusting motion detection settings, enabling different modes, activating voicemail or the inbuilt siren, and more. View the full article
-
Figure bolsters case for Federal Reserve to proceed slowly with interest rate cutsView the full article
-
As an introvert, I dread large conferences. I get invited to a number throughout the year, and I usually scramble to find excuses for why I can’t attend. Since I have spent much of my career posing as an extrovert, some people are surprised to discover that I really don’t enjoy networking at large gatherings. I worry about feeling overwhelmed by the crowds, not remembering people’s names, having to sit alone for meals, drawing a blank and not being able to engage in small talk, and, of course, worried I won’t know anyone there. Just thinking through all of this is absolutely exhausting. Last year, I was invited to speak and attend Transform, a conference focused on driving innovation in the workplace. The same dread took over me as I committed to attend. And after spending a few days in Las Vegas with a few thousand attendees, I think I finally cracked the code for myself on how to approach large conferences as an introvert. So this year, as I prepare to attend again, I have a game plan to get the most out of this conference. Here’s my advice on how to navigate and network at large conferences. Plan your days in advance, including who you’ll talk to Now, I prepare for the conference weeks before I even arrive. If possible, I try to stay at the hotel where the conference is taking place. And if not, as close as possible. I take a look at when the conference begins and when it ends, and I study the agenda topics and list of sessions. I take a note of the speakers and who is attending and see if I see any familiar faces. If available, I use the conference app to keep track of the sessions I want to attend and message and connect with people before the conference. I also check if any colleagues or friends are attending the conference, what days, and coordinate travel and even share Ubers to and from the airport. Last year, I planned to meet a friend who was also attending in the lobby in the mornings and walked to sessions together, and when I was feeling anxious I texted her to grab a coffee or snack. We also walked out of the conference at the end of the day and grabbed a drink. I was happy to have a buddy I could rely on when I was feeling out of place or overwhelmed by the crowds. Find the super connectors While large conferences can be intimidating, I also want to push myself to meet new people. I set a goal of meeting at least three new people a day. This can be daunting if you feel uncomfortable walking up to a stranger or breaking into a circle of people and introducing yourself. My plan now is to find the super connectors and have them help me meet new people. I try not to apply expectations on what these introductions could lead to. Some of these new people I have a lovely interaction with and we don’t connect again. And some of these new people I hit it off with and we stay in touch post conference. My friend Dinah Alobeid, a communications executive, is a super connector who knows a variety of people across sectors and industries. She had me grab a coffee with her and then invited me to stand with her and her team at the Greenhouse booth in the exhibitor area. It was an easier way to meet people who came to their booth, as opposed to going around the large area alone and trying to force myself to stop and booth after booth after booth and make small talk (I did do that later, and of course brought my friend Sarah along.) My friend David Landman, an human resources executive, is also a super connector who seems to make friends wherever he goes. He plugged me into all the social events that were happening. He also found me the very first morning of the conference during a break and introduced me to people. He then got me invited to lunches, happy hours, and dinners so I didn’t have to worry about who to meet with and if I would be sitting alone. He even met me in the lobby so we could walk over to evening events together. I felt so much more at ease not having to enter rooms alone where I may not know anyone. Prioritize time to decompress Finally, I stopped putting pressure on myself to do every single thing at the conference. There’s so much happening at a large conference like Transform you can want to make the most of it and take advantage of everything being offered. The first year I went, I tried to do it all, and left feeling exhausted and depleted. Now, I don’t pressure myself to attend every single session. I take breaks, I grab a coffee and go and recharge for a few minutes alone. I usually have my journal with me to take notes. I also go back to my hotel room to freshen up or sit in the quiet and recharge before heading back downstairs. I give myself permission to leave when I want to. I also find by doing this, I am much more present and attentive when I am at the conference and one on one conversations. One evening, I wasn’t feeling great and couldn’t make it out to dinner plans. My friend Sally Wolf, a wellbeing advisor and keynote speaker, invited me to come to her hotel room, and join her and her friend Danielle Farage, a speaker on Generation Z corporate talent. I was hesitant at first to go, and then felt at ease as soon as I walked into their room. We nibbled on snacks and chatted for over an hour. It was great to connect with conference attendees in a more informal, casual setting. With preparation and pre-planning, with the help of super connectors, and prioritizing time to decompress, large conferences don’t have to be an introvert’s worst nightmare. In fact, now with my plan in place, I am excited to attend Transform and other large conferences this coming year. I am on a mission to learn and open my mind to topics, be present and share my expertise and knowledge, and hopefully make at least one or two new friends along the way. View the full article
-
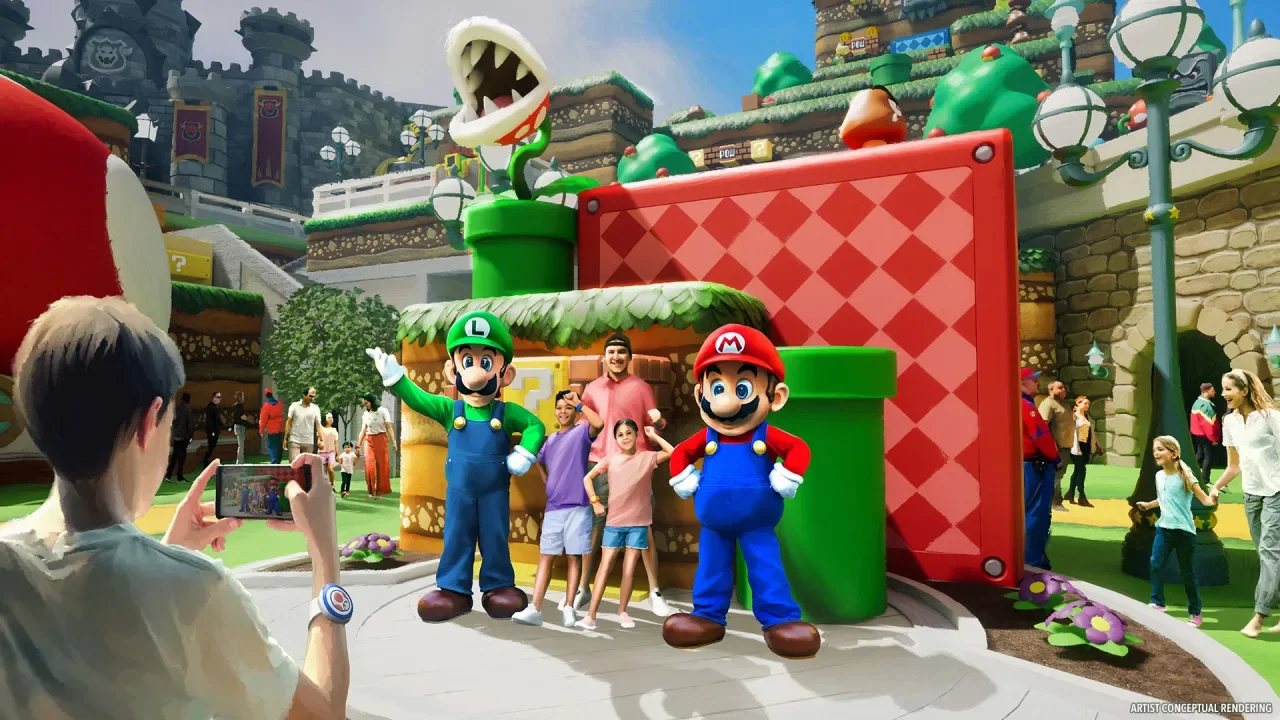
The theme park wars will shift into an even higher gear right before Memorial Day. On May 22, Universal Orlando is scheduled to open Epic Universe, it’s $6 billion expansion that’s meant to lure more visitors away from the Magic Kingdom and other assets of Walt Disney World and make the company’s theme-park hub a seven-day visit for tourists. Announced in 2019, Epic Universe will be the first new Central Florida theme park in more than 25 years. Divided into five lands, it’s a park that hopes to have something that appeals to all types of family members. And it’s a serious enough threat that Disney has announced a major upgrade to its Orlando parks, part of a 10-year, $60 billion investment in parks and experiences. For a park that’s so close to its opening day, there are still a lot of questions. Tickets went on sale last October, but unless you’re a hardcore theme-park junkie, you might not know what to expect from Epic Universe. Here’s what you can look forward to, if you’re planning (or thinking about planning) a vacation. Universal Epic Universe front gate [Rendering: Universal] Where is Epic Universe located? While it’s a part of Universal Orlando, the physical location of Epic Universe will be set about 2.5 miles southeast of Universal Studios and Islands of Adventure, as well as Universal Volcano Bay water park and Universal CityWalk. To transport visitors back and forth, Universal will run buses between the parks and will have a separate parking area for Epic Universe visitors. What are the five lands of Epic Universe? The park’s layout is designed to let visitors enter a “portal,” which takes them to five different lands. Celestial Park This is the entry into Universal Epic Universe, with dining, shopping, and three attractions: a carousel, a dual-launch coaster, and interactive dancing fountains. The Helios Grand Hotel (more details below) will also be located in this area. Celestial Park [Rendering: Universal] The Wizarding World of Harry Potter’s Ministry of Magic Universal has two other Harry Potter Wizarding Worlds: Daigon Alley at Universal Orlando and Hogsmeade at Islands of Adventure. Those are connected via the Hogwarts Express, but the Ministry of Magic will be a stand-alone park. The new park will include elements from both the Harry Potter and Fantastic Beasts franchises, and this area will let fans explore several international wizarding communities, from Paris in the 1920s to the U.K. in the 1990s. Food choices will include Café L’air De La Sirène and Le Goblet Noir. And yes, of course, you’ll be able to get a Butterbeer. Super Nintendo World Already a hit in Universal Studios’s California park, this interactive Nintendo-themed world is loaded with familiar characters from Mario to Bowser. It includes a big coaster (more on that below) and a live-action Mario Kart ride. It’s a larger park than its California cousin and has additional rides (such as Yoshi’s Adventure and Mine-Cart Madness) and interactive activities. Mario Kart: Bowser’s Challenge in Super Nintendo World [Rendering: Universal] Foodwise, Chef Toad is serving things up at the Toadstool Café—like the Mario Burger complete with a bun branded with Mario’s moustache and tiny red cap. There’s also the Bubbly Barrel in Donkey Kong Country. How to Train Your Dragon’s Isle of Berk On the Isle of Berk, you’ll be able to ride a dragon. You’ll also be able to explore the Viking village at the heart of the animated Dreamworks franchise. Dark Universe Universal embraces its monster-based roots, with reimagined classic creatures, including Frankenstein, the Wolfman, and Dracula. What will be the big rides? Epic Universe will have several big roller coasters, the standout of which will seemingly be Mine-Cart Madness in Super Nintendo World. This Donkey Kong-themed ride features an effect where the car will appear to jump over a gap in the tracks. The Wizarding World’s big draw will be Harry Potter and the Battle at the Ministry, which features the return of Imelda Staunton as Dolores Umbridge. Dark Universe’s big draw will be the animatronic-heavy Monsters Unchained: The Frankenstein Experiment, set under Frankenstein Manor. Harry Potter and the Battle at the Ministry [Rendering: Universal] At Isle of Berk, you can ride Hiccup’s Wing Gliders, a coaster that simulates a ride on a dragon’s back. And the Stardust Racers coaster will send visitors in Celestial Park zooming at 62 mph to heights of 133 feet. Will there be hotels? Three hotels are being built in the general area around Epic Universe, but the crown jewel will be the Grand Helios, which has a dedicated entrance to the park, along with a rooftop bar overlooking the park. Universal Helios Grand Hotel [Rendering: Universal] The others, Stella Nova and Terra Luna, are not within walking distance and will require some travel time to reach Epic Universe. How much will Epic Universe tickets cost? Right now, if you want to visit Epic Universe, you’ll need to buy either a three-, four- or five-day pass. And regardless of which one you choose, that will only get you into Epic Universe for a single day. The other days must be spent at the other Universal theme parks. For adults, those start at $117 per day. Kids are just a couple dollars less. If you’re already an annual passholder at Universal, you can buy one-day tickets, but those are already sold out for at least the first 17 days that Epic Universe will be open. Prices to add a ticket for the Epic Universe add-ons start at $122 a day. Individual tickets for Epic Universe will go on sale at a later date, which hasn’t been announced yet. View the full article
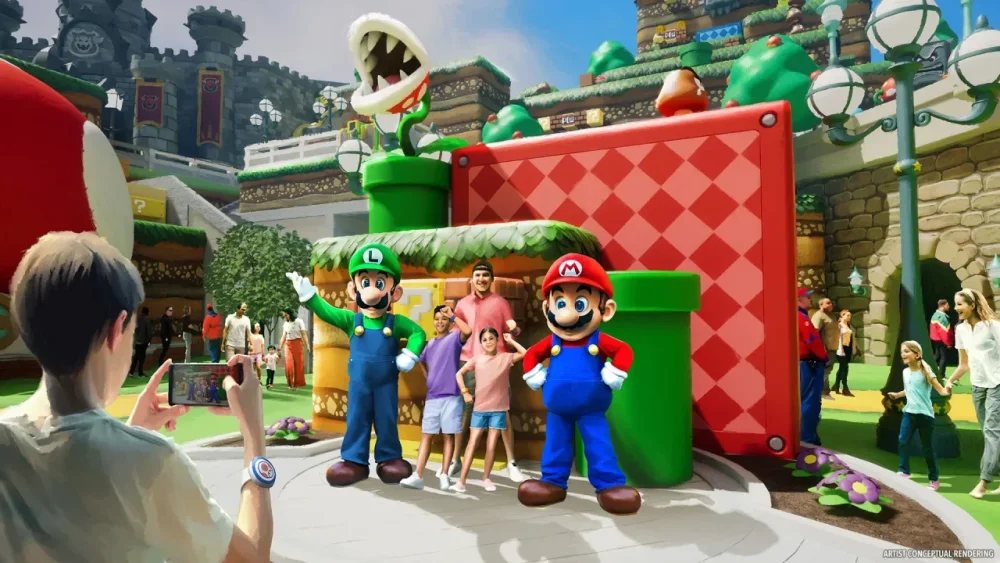
-
The United States Postal Service handles an average of 318 million pieces of mail every day, so there are going to be some mistakes. Carriers misread an addresses, letters shift around in the back of the truck, and people move without updating their addresses—all circumstances that could result in you receiving mail intended for someone else. Here’s what you should do if you get mail that doesn’t belong to you. What to do if mail is delivered to the wrong addressIf the mail you’ve received is not only for someone else, but for a different address than yours, you have two options to correct the mistake: Deliver it yourself. If the letter is clearly intended for a nearby neighbor, and you can physically open their mailbox, feel free to deliver the letter to the correct address yourself. It is not illegal to open someone’s mailbox (as long as it’s not locked), and it’s not illegal to personally forward mail to the correct address as long as the mail has proper postage. You could also knock on their door and hand it to them if you know them (or feel comfortable doing so). However, be aware that there are laws against placing other things—like flyers, notes, advertisements without postage, etc.—in mailboxes. Write a note and stick it in the outgoing. If the correct address is far away or you just don’t feel like dealing with delivering it yourself, write a note that says something to the effect of “wrong address” and attach it to the wrongly delivered piece of mail with a sticky note or a paperclip. A mail carrier will pick it up next time around and it will be delivered to the correct address in the next couple days. It’s best not to write your note directly on the envelope or article and risk defacing someone else’s mail. If you use a marker or Sharpie and it bleeds through, it could cause the intended recipient more grief than is necessary. So use a paperclip or a sticky note instead. What to do if you receive mail for a former residentIf you’re receiving someone else’s mail with your correct address, you need to inform the mail carrier and post office that they no longer live there. Again, you can do that with a paper clipped note placed on the letter. To return to sender, simply write "Not at this address, return to sender" on the note and attach it to the piece of mail. Stick the mail in the outgoing box in a way that makes the error clear to your mail carrier the next time they come around. This might take a few tries, and you may even have to contact the post office if it continues. Check that the mail doesn’t say “[other person’s name] or current resident”; That mail is technically addressed to you as long as you live in that residence, whether you want to receive it or not. (Junk mail companies love that trick.) If you keep telling the post office “person doesn’t live here” with “or current resident” mail, they might assume the residence is vacant and stop sending mail there entirely. When in doubt, a trip to the post office or a phone call can often clear things up. Is it illegal to open someone else's mail?You bet it is. It's also illegal to throw someone else's mail away on purpose. Both are considered tampering (and both are considered jerk-y.) When you get someone else's mail, do not open it and do not throw it away, since both are punishable offenses (and no one likes offending or punishment). Don't worry, if you were mindlessly tearing open your stack of mail and realized you'd received someone else's and opened in error, you won't be taken away in cuffs. The law is intended to protect against unsavory types looking to gather personal information. View the full article
-
You’ve likely heard about holiday pay in employee compensation. Employees receive extra pay when they take paid time off for holidays. Understanding this concept can be immensely important as you prepare your business for the holidays or begin hiring for the first time. In this article, we’ll break down what holiday pay entails and whether it should be on your list of employee benefits. What is Holiday Pay? Holiday pay is a part of employee compensation, typically extra wages given during holidays. In the U.S., it stems from both federal laws and industry norms. Federal guidelines set the foundation, while industries often add their own practices, ensuring workers are rewarded for their holiday hours. The Difference Between Paid Holidays and Holiday Pay It’s important to grasp the difference between a paid holiday and getting extra for working on one. A paid holiday means you get your usual pay for the day off, while holiday pay means extra earnings for putting in hours on a holiday. Paid Holidays: What Are They? In the U.S., we’re talking about the classic typical paid holidays like New Year’s Day, Independence Day, and Thanksgiving. These are days when folks typically take a breather, and employers often ensure their team gets this time without missing out on their regular pay. How Holiday Pay Works Holiday pay sweetens the deal. If you’re clocking in on a holiday, you’ll usually see a little extra in your paycheck. This could be a bump in your hourly rate or even a special bonus. It’s a way for employers to show appreciation for the effort of putting in work on a holiday, giving employees an extra nudge to be there when it counts. Eligibility and Requirements for Receiving Holiday Pay Let’s explore who typically qualifies for holiday pay. Eligibility is often determined by factors like your job type, industry, and the specifics of your employment agreement. While these criteria can differ, understanding them is essential. Who is Entitled to Receive Holiday Pay? Eligibility for holiday pay varies depending on your employment status. Typically, full-time employees receive more holiday pay benefits compared to part-time or contractual workers. Additionally, the details may be influenced by your employer’s policies and the specific nature of your work. Common Practices in Different Industries Different industries have their own take on holiday pay. In healthcare, it’s common to ensure staff working holidays receive extra compensation. In the hospitality industry, bonuses or higher hourly rates on holidays are common. Office jobs often follow standard holiday pay practices outlined in employment contracts or company policies. Finding a common standard and communicating it to employees so that they understand their compensation and what is expected of them is among the hardest parts of being a manager. How Much is Holiday Pay? Now, let’s talk dollars and cents when it comes to holiday pay. It’s not just a flat amount; it can vary based on several factors. Let’s break it down. Standard Rates vs. Overtime Pay Holiday pay can vary in its form. In some cases, it is paid at your standard hourly rate, while in others, it may be higher, such as overtime pay. The exact rate typically depends on your employer’s policies and agreements. Factors Influencing Holiday Pay Amounts Several things play into how much holiday pay you might get. Here’s a closer look at several factors: Job Role Different positions within a company might have varying pay scales. For example, managerial roles might receive a different holiday pay rate than entry-level positions. Some roles, especially those in essential services like healthcare or public safety, might get higher holiday pay due to the nature and demand of their jobs on holidays. Tenure with the Company Employees with longer tenure at the company may receive increased holiday pay as recognition for their loyalty and experience. Some businesses have a tiered system where holiday pay increases with each year of service. Size of the Employer Larger companies might have more established policies and budgets for holiday pay, potentially offering more generous rates. Smaller businesses, while they may have a tighter budget, sometimes offer competitive holiday pay to retain their staff. Company’s Financial Health A company that has had a successful financial year might decide to reward its employees with higher holiday bonuses or pay. Conversely, a business facing financial struggles might offer reduced holiday pay or none at all. Presence of a Union or Collective Bargaining Agreement In organizations with robust unions or collective bargaining agreements, holiday pay rates may be standardized and are often higher compared to non-unionized settings. Location and Cost of Living Businesses located in areas with a higher cost of living might offer more holiday pay to help offset living expenses. Regional laws and standards might also dictate minimum holiday pay rates. Policy on Holiday Pay Not all companies offer holiday pay. For those that do, the way they calculate it can vary—some might offer a fixed bonus, others might provide double-time pay, and some might give an extra percentage of the daily rate. The number of holidays recognized by a company can also influence overall holiday earnings. Employee Performance Some companies might offer performance-based bonuses during the holiday season, meaning an employee’s recent performance could influence their holiday pay. Industry Norms Some industries may typically provide more generous holiday pay because of competitive pressures or the specific requirements of the work. For example, the hospitality industry might offer higher holiday pay rates to incentivize working during peak holiday times. Understanding these variables is crucial for employees when negotiating contracts or for employers when establishing fair and competitive holiday pay policies. Types of Holidays and Implications for Pay Let’s break down the different holidays in the U.S. and what they mean for your pay. Each has its own set of implications, from federal holidays to religious observances. CriterionFederal HolidaysReligious HolidaysFloating Holidays DefinitionHolidays recognized by the federal government, often marking national events or historical figures.Important days in various religions; they may vary greatly among different religious groups.Personal days that an employee can take off at their choosing, sometimes offered by businesses in lieu of, or in addition to, fixed holidays. Examples- New Year’s Day- Christmas (Christian)Typically not fixed to any specific day. - Independence Day- Hanukkah (Jewish)Employee chooses the day based on personal or family needs. - Thanksgiving- Eid (Islamic) Mandatory OfferingIn the U.S., businesses are not required to close or offer time off for federal holidays, but many choose to do so.Not mandatory, but businesses may offer to accommodate employees' religious practices.At the discretion of the business. Some companies offer them, some don’t. Schedule ImpactFixed dates; businesses can plan ahead for closures or reduced staffing.May change every year, especially for lunar calendars. Can make scheduling more challenging.Can be unpredictable, as employees select dates based on personal needs. Might create short-staff situations if not managed. Diversity & InclusivityBroadly recognized, but doesn’t accommodate all cultural or religious observances.Accommodating religious holidays promotes inclusivity and respects diversity.Promotes inclusivity by allowing employees to choose days important to them, whether cultural, religious, or personal. Financial ImplicationIf businesses decide to offer additional pay (like double time), it's on fixed, predictable days.Offering additional pay might be less predictable due to varying observances among employees.If offering additional pay, cost is less predictable due to the personal nature of these holidays. Legal ConsiderationsWhile not mandated for private businesses, some regulations might apply to federal contractors or other sectors.Employers must reasonably accommodate religious practices, including observances, unless it creates undue hardship.Largely determined by company policy, but must be applied consistently to avoid discrimination. Employee Morale & SatisfactionSeen as standard in many industries, can affect morale if not offered.Recognizing and accommodating boosts morale among diverse employee groups.Highly valued for their flexibility, allowing employees to observe personal or cultural events. Federal Holidays vs. Religious Holidays Federal holidays like Independence Day often mean paid time off, while religious holidays may require accommodations or special pay arrangements. Understanding the distinctions helps employers navigate these situations effectively. Floating Holidays: A Flexible Option Floating holidays are gaining traction for their adaptability. They let employees choose when to take their day off, catering to diverse cultural or personal preferences. Offering this option shows consideration for individual needs and promotes a more inclusive work environment. Holiday Season and Pay Considerations Employers might offer additional incentives to keep their workforce engaged during busy holiday seasons, like the end of the year. Bonuses, extra pay, or even additional time off can be part of these seasonal considerations. It’s a way to say thanks for the extra effort during the holidays. Utilize work schedule apps or online calendars to schedule these extra breaks in a way that won’t harm your business. Holiday Pay Policy and Calculations When it comes to offering holiday pay, companies usually have a clear policy in place. This policy outlines who’s eligible for holiday pay, how much they’ll get, and when they’ll receive it. Companies consider factors like employment contracts, federal and state laws, and internal guidelines to create a solid holiday pay policy. How to Calculate Holiday Pay Calculating holiday pay might seem tricky, but it follows a straightforward formula. Start by figuring out how much the employee normally earns. Next, work out the average daily earnings over a certain period. Finally, multiply that average by the number of days they’re taking off. This way, you make sure they’re fairly paid for their holiday time. The Role of the Fair Labor Standards Act The FLSA plays a crucial role in holiday pay regulations. It sets the minimum wage, overtime rules, and standards for employee classifications. When it comes to holiday pay, the FLSA doesn’t mandate it, but it can affect how companies approach holiday compensation. Complying with FLSA guidelines ensures fair treatment and pay for employees during holidays. https://youtube.com/watch?v=Ovc16NUta94%3Fsi%3D85B6ynjTl7miiuym FAQs: Holiday Pay Are paid holidays the same as federally recognized holidays? Paid holidays and federally recognized holidays aren’t always identical. While federally recognized holidays like New Year’s Day and Independence Day are commonly paid, companies may offer additional paid holidays like Thanksgiving or Christmas. Check your company’s policy to see which holidays they provide paid leave for. How does working on religious holidays differ from a federal holiday? Working on religious holidays versus federal holidays varies. Federal holidays are recognized nationwide, and most businesses close or provide extra pay. Religious holidays depend on an employee’s faith and company policies. Accommodations may include time off, flexible hours, or swapped workdays. How should holiday pay be calculated for hourly employees? Calculating holiday pay for hourly employees follows a simple formula. Start by determining their regular hourly rate. Then, calculate their average daily earnings over a specific period, often the past few weeks. Finally, multiply that average by the number of holiday hours worked. What is the difference between holiday pay and paid holidays? Holiday pay refers to the additional compensation employees receive when they work on holidays. It’s an extra payment beyond their regular wages. Paid holidays, on the other hand, are days when employees receive their regular pay even though they’re not working, typically on federally recognized holidays or as per company policy. Creating a standard policy that can easily be communicated can simplify hiring and keep current employees happy. Image: Envato Elements This article, "What is Holiday Pay and Should You Offer It?" was first published on Small Business Trends View the full article
-
In another devastating blow to customers and employees of Joann Inc, the popular fabric and crafts retailer is moving to close a significant chunk of its brick-and-mortar locations as part of ongoing bankruptcy proceedings, according to a court filing on Wednesday. The company, which filed for Chapter 11 protection a second time last month, had initially said it would continue operating its approximately 800 stores as it restructured and sought a buyer. However, it told a court this week that it has now identified a number of underperforming locations during the bidding process that it wants to close as a way of cutting costs. “As the sale process progressed, and prospective bidders continued to conduct diligence and refine their potential bids, the Debtors and their advisors were able to identify a subset of underperforming stores that are unlikely to be considered or included in any going concern bid,” lawyers for the retailer said in the court filing. The filing lists hundreds of locations across more than 40 states, with big states like California, Florida, Illinois, and Michigan being hit the hardest. Joann says in the filing that it would like to begin store closing sales immediately. It warns that additional locations are likely to close as well. Reached for comment by Fast Company, Joann spokesperson Amanda Hayes confirmed the closings in a statement. “As part of the ongoing Chapter 11 process and our efforts to maximize the value of the business, JOANN has filed a motion seeking court authority to begin closing approximately 500 stores across the nation,” the statement read. “This was a very difficult decision to make, given the major impact we know it will have on our Team Members, our customers and all of the communities we serve. A careful analysis of store performance and future strategic fit for the Company determined which stores should remain operating as usual at this time. Right-sizing our store footprint is a critical part of our efforts to ensure the best path forward for JOANN.” A difficult needle to thread Founded in 1943, Joann has faced significant challenges in recent years, with factors such as the pandemic, inflation, and the broader shift to online retail hindering its operations. It was taken private last year when it filed for bankruptcy a first time, but it said at the time that it expected to continue operations once it emerged. A second bankruptcy came at the beginning of this year. Although Joann told customers that stores would remain open during the process, it warned that it could go out of business if it is unable to find a suitable buyer. Gordon Brothers, the restructuring firm that recently took control of embattled retailer Big Lots, has emerged as a “stalking horse” bidder for Joann. If it is successful, the firm is likely to liquidate and close all stores. This story is developing…. View the full article
-
Smashing Pumpkins' legendary frontman Bill Corgan and confrontational comedian Bill Burr look alike—both have shaved heads, stubbly beards, blue eyes, and similar facial structures. They look so much alike they could be brothers; so much alike that a lot of people think they are brothers. While it's possible, these people are probably wrong. Why people think Bill Corgan and Bill Burr are brothersThe rumor started with Corgan's appearance on Howie Mandel's podcast back in January. On the show, Corgan recounts the following conversation that he said happened a decade prior: My stepmother said to me, "Do you know who Bill Burr is?" Now at that point, I had never heard of Bill Burr … She said, "Well, he's this comedian…" And I think I even somehow called up a picture on the phone, and I kind of noticed right away, "Gee, he really looks like my father." Bill Burr looks more like my father than Bill Burr looks like me or I look like Bill Burr. So I said to my mother, "Why are you asking me this?"... She goes, "I think he might be one of your father's illegitimate children. Bill Burr might be one of the children that your father sired in his days being a traveling musician… My father did once tell me that I had a half-brother named Bill, who was born around the same time as me." A lot of people look like other people, so that doesn't mean much, and a single piece of family lore is anything but conclusive, but this evidence was apparently enough for Mandel to try to get to the bottom of it, in probably the worst way possible. Corgan and Burr: Worst. Family. Reunion. Ever.In a more recent episode of Howie Mandel Does Stuff, Mandel hosted Bill Burr and surprised the comedian with a special appearance from Corgan so the pair could compare notes on their fathers. Despite Mandel's assurance that he was "doing it out of love," the ambush did not go well. "You're an asshole," Burr tells Mandel. "He's just doing this for the fucking ratings," Burr adds. Corgan says he was told Burr was aware he was appearing on the show, but it seems Burr had no idea. Mandel eventually leaves the pair alone to talk things out. It's an uncomfortable, creepy conversation. Burr says his dad had multiple families. Corgan says his dad told him he was a musician where Burr's dad told him he was a dentist. Corgan points out that Bill Burr can't sing, and Billy Corgan isn't funny, so maybe they aren't related. It doesn't really reach any conclusion. Ultimately, the familial status of Corgan and Burr is inconclusiveThe bottom line is there isn't any solid reason to think that Bill and Billy have the same father. "They look alike" and "my mom said something once" isn't enough evidence to believe this rumor (even if Burr and Corgan believe it). Unless the results of a DNA test are made public, I'd file this under "probably not true." It's extremely unlikely for any person to become famous—there are a lot of singers and comedians out there—and it seems astronomically unlikely that two people would become famous at a Burr/Corgan level, but in two distinct fields. These aren't nepo babies we're talking about. The unique combination of talent, drive, personality, and luck that adds up to a career like either of these men is almost never seen. Two half-brothers developing all that independently is possible, but it would be a hell of a coincidence. The on-air results of the impromptu "family reunion" are inconclusive. Burr refers to "our dad" often on the podcast, and overall seems to accept the premise that they have the same father, but maybe he's playing along with the bit Mandel set up. Burr is a comedian so he knows how to run with a premise. He appeared on Mandel's show to promote an upcoming project, and seems to have succeeded wildly. I don't have any evidence one way or the other, and my gut says this is genuine, but I wouldn't exactly be surprised if this all turned out to be an elaborate set-up designed to get people talking and boost the careers of all three men; it wouldn't be the first time. Speaking of— Matthew McConaughey and Woody Harrelson are probably not brothers eitherMatthew McConaughey and Woody Harrelson look alike too. Unlike Corgan and Burr, the actors are pals, but there's a rumor that they're brothers too. Just as Corgan's mother brought up the possibility that he was related to Burr, McConaughey's mom brought up a possible family relationship with Harrelson. “We're all sitting around in Greece one night talking and my mom out of nowhere in a little pause goes, ‘Oh, I knew your dad, Woody...,’ ” McConaughey said in an interview. “And we all went, ‘What was the ellipsis about?' ...And she goes, ‘Just saying, we might have frequented the same place out in West Texas one time when he was on furlough.' ” The pair have mentioned doing DNA tests in the past, but, so far, haven't released any results. Again, I don't know if it was a publicity stunt for a movie, but I wouldn't be surprised. View the full article
-
UK Supreme Court on Wednesday quashed extradition of Joseph El-Khouri, curbing the reach of US prosecutorsView the full article
-
In this post, we’ll explore 15 different franchise financing options for small business owners. So whether you’re looking for a traditional loan or something more creative, there’s sure to be an option that’s perfect for you. Let’s get started! What Is Franchising? Franchising allows entrepreneurs to own and operate their own businesses with the support of a larger, more established company. Franchises offer brand recognition and a proven business model, which can be helpful for new business owners as they get started. Franchise business owners should have a business plan to guide them as they grow their businesses. READ MORE: See our Franchise Guide How Much Can Financing a Franchise Cost? Franchising offers an excellent opportunity to become your own boss and attain independence. However, it is crucial to comprehend the startup costs associated with it before making any commitments. Typically, the initial investment for most franchises falls between $75,000 and $500,000. The franchise fee will vary based on the specific franchise opportunity. Overall, the costs associated with owning a franchise can differ depending on the brand, the size of the business, and its location. Therefore, it is crucial to conduct thorough research to fully grasp all the expenses involved before embarking on your franchise journey. Should You Get Financial Assistance Paying for Your Franchise Business? Franchise loans are available from many different lenders, and they can be a great way to finance your franchise business. Here are five things to consider to help determine your financing needs: How much money do you need to borrow? If you need equipment financing to buy expensive items like ovens and coolers, a business loan may be your best bet. What are the terms of the loan? Be sure to understand the interest rate, repayment schedule, and any fees associated with the loan. What is the duration for repaying the loan? Understanding this will assist you in figuring out the amount of monthly payments you can manage. What is your credit score? Your credit score will affect the interest rate you qualify for, so it’s important to know what it is before you apply for a loan. What is the interest rate on the loan? The interest rate will affect your monthly payments, so be sure to compare rates from different lenders before choosing one. What Personal Assets Play a Role in Franchise Financing? When you seek a business loan to finance your franchise, the lender will probably require a personal guarantee. This indicates that you will be personally accountable for repaying the loan if your business cannot fulfill this obligation. Additionally, the lender may request collateral, which refers to an asset that can be used to back the loan. Savings and Investment Portfolios If you have money saved up in a savings account or investment portfolio, you may be able to use it as collateral for a business loan. Your investment portfolio or savings account can also be used to make a down payment on a franchise loan. Severance Package If you’re leaving your current job to start a franchise, you may be able to use your severance package as collateral for a loan. This can help you get the financing you need to get your business off the ground. Home Equity If you have equity in your home, you may be able to use it as collateral for a loan. Using your home equity as collateral can help you secure a lower interest rate and possible tax benefits such as the interest being tax-deductible. Retirement Funds If you have money saved in a retirement account, you may be able to use it as collateral for a business loan. You’ll likely be able to borrow a larger amount than you would without retirement funds as collateral, and the loan may have a lower interest rate. Choosing the Best Franchise Financing Options: Our Methodology When it comes to selecting the right financing options for your franchise, it’s crucial to consider various factors to ensure your small business’s success. We understand that every entrepreneur’s needs are unique, so we’ve developed a comprehensive set of criteria to guide you through this essential decision-making process. Each criterion will be rated on a scale of 1 to 5, with 5 being the most important, allowing you to prioritize according to your specific circumstances. Interest Rates (5/5): The interest rate on your franchise financing significantly impacts your overall costs. Lower interest rates can save you substantial money in the long run, making this a top priority. Loan Term (4/5): Consider the length of the loan term. Longer terms may come with lower monthly payments but potentially higher total interest costs. Loan Amount (4/5): Assess whether the financing option provides the necessary capital to meet your franchise’s specific needs. Adequate funding is crucial for a successful start. Repayment Flexibility (4/5): Evaluate whether the financing allows for flexibility in making repayments. Options like interest-only payments during the initial phase can ease financial strain. Credit Requirements (4/5): Understand the credit score and financial history necessary to qualify for the financing option. Your creditworthiness can affect your eligibility and interest rates. Collateral Requirements (3/5): Determine whether the financing requires collateral. Collateral may include personal assets or business assets, impacting your risk exposure. Origination Fees (3/5): Be aware of any initial fees related to the financing. Elevated origination fees can raise the total expense of borrowing. Approval Speed (3/5): Take into account how urgently you require funds and the usual approval timeline associated with the financing option. Quick approval can be vital for franchise financing in time-sensitive situations. Lender Reputation (5/5): Research the reputation of the lending institution. A reputable lender is more likely to provide transparent terms and excellent customer service. Prepayment Penalties (2/5): Determine whether there are penalties for paying off the loan early. Understanding prepayment terms can help you avoid unexpected costs. Additional Services (2/5): Some lenders offer value-added services, such as business coaching or networking opportunities. Consider whether these extras align with your needs. Customer Reviews (4/5): Seek out reviews and testimonials from other franchisees who have used the same financing option. Real experiences can provide valuable insights. CriteriaDescriptionImportance (1-5) Interest RatesThe rate at which you'll be borrowing funds. Lower rates can save you money in the long run.5 Loan TermThe length of the loan agreement. Longer terms may have lower monthly payments but higher overall costs.4 Loan AmountThe total funding available to meet your franchise's specific needs.4 Repayment FlexibilityFlexibility in making repayments, including options like interest-only payments during the initial phase.4 Credit RequirementsThe minimum credit score and financial history needed to qualify for the financing.4 Collateral RequirementsWhether the financing requires collateral, which can include personal or business assets.3 Origination FeesUpfront fees associated with the financing, which can impact the overall cost of borrowing.3 Approval SpeedThe typical approval timeline for the financing option, which can be crucial for time-sensitive opportunities.3 Lender ReputationThe reputation of the lending institution, as reputable lenders offer transparent terms and good customer service.5 Prepayment PenaltiesWhether there are penalties for paying off the loan early. Understanding prepayment terms can avoid unexpected costs.2 Available Franchise Loan Options Business loans are available through a variety of financial institutions. Let’s take a look at some of your financing options: SBA Loans The Small Business Administration offers various SBA loans to help small businesses get started. The SBA 7(a) loan program is the most popular option, and it offers loans up to $5 million. Other SBA loan programs include the 504 loan program, which offers loans up to $5 million for equipment and real estate, and the microloan program, which offers loans up to $50,000. Franchisor Financing Many franchisors offer financing to help franchisees get started. Franchisor financing can be in the form of loans, lines of credit, or royalty-based financing. If you’re considering franchisor financing, be sure to compare the terms and rates from different lenders before choosing one. Commercial Bank Loan Commercial banks provide various loan options for small businesses, such as business loans, lines of credit, and equipment financing. While loans from commercial banks generally feature lower interest rates compared to other loan types, qualifying for these loans can often be more challenging. Retirement Funds If you have a 401(k) or 403(b) retirement account, you can use Rollover As Business Startups (ROBS). With ROBS, you can roll over the funds from your retirement account into a new business without paying taxes or penalties. This can be a good option if you have a large amount of money saved in a retirement account. Personal Savings If you have money saved in a savings account or investment portfolio, you may be able to use it to finance your franchise. Using your savings can help you avoid taking on debt, but it will also tie up your assets in the business. Crowdfunding Crowdfunding is a way to raise money by soliciting donations from a large group of people. With crowdfunding, you can set up a profile on a website and solicit donations from friends, family, and strangers. Crowdfunding can be a good option if you don’t have access to traditional forms of financing. Term Loans A term loan is a type of business loan that offers a fixed amount of money for a set period of time. Term loans are typically repaid in monthly installments, and they can be used for a variety of purposes, such as funding equipment purchases or expanding your business. Small Business Credit Card A small business credit card can be a good option for financing your franchise. Small business credit cards typically have low interest rates and offer rewards, such as cashback or points, that can be used to offset the cost of your franchise. Equipment Financing If you need to purchase equipment for your franchise, you may be able to finance it through an equipment loan or lease. Equipment financing can be a good option if you don’t have the cash to purchase the equipment outright. Business Lines of Credit A business line of credit is a type of revolving credit that can be used for a variety of purposes, such as funding inventory or covering unexpected expenses. Business lines of credit typically have lower interest rates than other types of financing, such as credit cards. Credit Union Loans Credit unions provide a variety of loan products similar to those available at commercial banks. Unlike banks, credit unions are member-owned, which often allows them to offer lower interest rates and reduced fees. Home Equity Loan & HELOCs If you own a home, you may be able to use the equity you’ve built up to finance your franchise. Home equity loans and home equity lines of credit (HELOCs) are two common types of home equity financing. Home equity loans offer a fixed amount of money for a set period of time, while HELOCs offer a line of credit that can be used as needed. Severance Package If you’ve been laid off from your job, you may be able to use your severance package to finance your franchise. Severance packages typically include a lump sum of cash that can be used for a variety of purposes. Start a Partnership If you can’t afford the costs to open a franchise on your own, consider starting a partnership. With a partnership, you can pool your resources with another person or business to finance your franchise. Family & Friends If you have family or friends who are willing to invest in your franchise, you may be able to use their money to finance your business. However, you should be aware that taking money from friends or family can put a strain on your relationships. How Do You Qualify for Franchise Financing? When trying to get a business loan to meet your franchise financing needs, there are a few things that lenders will look at to determine if you qualify. Here are five things that may be considered: Personal credit score: Your score and personal credit history will be one of the first things a lender looks at when considering you for a loan. It’s important to know what your credit score is before you apply for a loan so you can be prepared. Business credit score: In addition to your personal credit score, the lender will also look at your business credit score. This is a score that’s based on the financial history of your business. Personal guarantee: A personal guarantee indicates that you are personally accountable for repaying the loan if your business cannot fulfill this obligation. Lenders may request a personal guarantee when evaluating your application for a loan. Collateral: collateral is an asset that can be used to secure the loan. The lender may ask for collateral in the form of a savings account, investment portfolio, or home equity. Ability to repay: The lender will also consider your ability to repay the loan. They’ll look at things like your income, debts, credit history, and other factors to determine if you can afford the loan payments. Can You Buy a Franchise with No Money? No matter how you slice it, you’re going to need some money to finance a franchise. Franchises typically cost at least tens of thousands of dollars. If you don’t have any money or the ability to borrow some, then buying a franchise will not be an option for you. Can You Get SBA Loan Financing for a Franchise? The SBA provides loan programs that business owners can utilize to finance a franchise. However, not every franchise will meet the eligibility criteria. The SBA has established specific guidelines that a franchise must adhere to in order to qualify for financing. Image: Envato Elements This article, "Top Funding Options for Aspiring Franchise Owners" was first published on Small Business Trends View the full article
-
Welcome to Pressing Questions, Fast Company’s work-life advice column. Every week, deputy editor Kathleen Davis, host of The New Way We Work podcast, will answer the biggest and most pressing workplace questions. Q: How can I get over decision paralysis? A: I feel this one. I think we all do. By most estimates, the average person makes around 35,000 decisions per day. Most of those are small choices like what to wear, what to have for lunch, what to post on social media. Hopefully you’re not paralyzed by those choices. But you also shouldn’t discount them completely. If you spend too much time mulling over the less consequential parts of life, you can end up with decision fatigue. Decision fatigue leaves your brain too tired to make the choices that really matter. It’s why some of the most successful people either automate or outsource those thousands of little choices (and why former President Obama always wore the same types of suits). After you cut down on the mental load of those thousands of small choices, you will hopefully have a bit more space to think about life’s big decisions: Should you leave your job? Should you get divorced? Should you have a child? Where should you go on vacation? Narrow your options That last example might not seem as high stakes, but it serves as a good example of one of the things that makes people feel stuck in decision-making: too many choices. When your options are unlimited, it’s easy to feel overwhelmed and want to give up. Here it might help to narrow it down by thinking about what time of year you are traveling, what type of trip you want, your budget, who is traveling with you, if you want to fly or drive, etc. Hone down those smaller choices and you’ll be left with far fewer options. Ask for impartial advice In the vacation example, you probably want to get the input of the other people you are travelling with. With other decisions that impact others in your life, like job change or moving, factoring in the needs and opinions of those impacted is certainly important. But, after you have that information, if the final choice is yours, you can still feel stuck. That’s when it might be good to ask someone who doesn’t have a stake in the outcome. Trying to decide on the best all inclusive resort for a spring break trip? Post the question in your local parenting group. Trying to decide which couch would look best in your living room? Post the pictures side by side and let people vote. Trying to decide if you should change careers? Talk to a friend who knows you well. Ask yourself the right questions I love a good pro/con list, and it’s a staple of decision-making. The problem is it weighs everything equally. When deciding to move, for example, the pro of having a bigger yard isn’t really comparable to the con of adding an hour to your commute or leaving your kid’s beloved school. That’s why asking yourself questions that probe a little deeper can help you arrive at a better decision. Try questions like: Does this take you closer to your goals? How do you think you’ll feel about this decision in five years? Is this something that you think you “should” do vs. something that you actually want to do? Check your gut (and your whole body) Another good piece of advice when it comes to decision-making? Pretend that you’ve made your choice and sit with it for a few hours or overnight (the classic “sleep on it” approach). If you imagine you’ve already told your boss that you quit and you feel lighter, it’s a pretty good indication of what you should do. When a decision is important, you can feel it physically. Leadership consultant Diana Chapman says the best decisions are accompanied by a “whole-body ‘yes‘”: When you’ve made the best decision you feel it in your whole body—head, heart, and gut. Still can’t decide? Here’s some more advice: 3 simple ways to become less anxious and more decisive Try these neuroscience-backed tactics to train your brain to make better decisions Your ultimate decision-making guide to help you make better choices faster 5 ways to prevent decision fatigue from ruining your productivity View the full article
-
After decades of fielding questions about travel points, loyalty programs, and rewards credit cards, you’d think that Brian Kelly—the founder of The Points Guy—would tire of the subject. Instead, he’s more energized than ever, a passion he channeled into his new book, How to Win at Travel. In 300-plus pages, Kelly delivers more than just strategies for maximizing credit cards and points. He’s created a travel bible of sorts, one that makes planning and logistics as rewarding as the trip itself. Brian Kelly [Photo: Brandon Launerts/courtesy Simon & Schuster] It’s a book built for every kind of traveler, from those working towards their first bucket-list trip to people trying to stretch points for a family of five. “Think of it as a choose-your-own-adventure book,” Kelly says. Here, he tackles some of the peskiest travel dilemmas: what to do when your flight goes sideways, when to cash in your points, how to stay on the right side of locals, and more. In your book, you note that we’re in the “platinum age” of travel, a departure from what people considered the Golden Age of travel. What do you mean by that? People are wistful for aviation in the 1960s, a time when people dressed up to fly. They were served meals on china with silver cutlery—we’ve all seen the pictures. But the truth is travel at that time was less convenient overall, and inaccessible except for the very rich. And everyone was smoking! Today, travel is safer, much less expensive, and we have tons of options. On top of that we have this points ecosystem, open to everyday people, that can unlock elite travel status. In your book, you write, “Loyalty is less about travel and more about personal finance and harnessing the power of your spending.” Can you explain? Points and travel can be an entry point into better finances, by paying your cards every month, bringing up your credit score, and so on. You’re starting with a reward that’s positive reinforcement for being smart about your financial health. What are three of your top tips for redeeming points and miles today? The first is to use technology to your advantage. The company Point.Me searches for flights based on your points across 33 loyalty programs on more than 150 airlines. [Brian Kelly is an investor in Point.Me.] Also, let the deals determine where you go. Even if you’re not flexible on your dates, you don’t have to travel where everyone else is going. In fact, it’s often better not to. Third, don’t hoard your points. They become less valuable over time. When you rack up these huge balances, you’re just losing money to inflation. When it comes to booking award travel with an airline, you know a lot of next-level tricks. Can you tell us about zone-based and distance-based airline rewards, and how you can use them to your advantage? These are the two types of rewards airlines use. For distance-based rewards, the math is pretty simple. The longer distance you fly, the more miles you pay, though distances are grouped together, so you can maximize these rewards when the price doesn’t exactly correlate to the distance of the flight. Zone-based rewards often have something that I call sweet spots. Turkish Airlines, for example, includes Hawaii in the same zone as the Continental U.S. So even though it’s much farther to, say, fly New York to Honolulu, so you can often fly there for the same number of miles as you would traveling a much shorter distance, like New York to Boston. What are “awards holds,” and when do you use them? Awards tickets can come and go in an instant, and it’s frustrating when you miss a deal. Some airlines, like Air France, American, and Lufthansa, allow you to hold your ticket for a certain number of days. It costs anywhere from $0 to $35. This permits you to make your other travel reservations and get your life in order before you book. In the past, we’ve seen credit cards offer travelers big points bonuses, which help you along the path to free travel. Are there ways to anticipate great offerings? In general, the industry is moving toward more personalized offers. So don’t ignore snail mail and promotional emails from credit card companies. Some might think it’s tedious to go through all that mail. I think of it as a treasure hunt. You also advise people to sign up for memberships to organizations that have travel benefits. What are some that people might not know about? AARP memberships, which start at $15 a year, offer great travel deals, and most people don’t know that you don’t need to be over 55 to join. I also love the American Bar Association, from $129 a year. It’s also open to a wider range of professions—like paralegals, law students, policymakers—than you might think, and the membership means steep discounts on loads of luxury hotels. When it comes to booking travel, you don’t love online travel agencies, like Expedia or Priceline, which are known as OTAs. Why not? How should travelers use them? OTAs revolutionized the travel industry 20 years ago, and I still use them to compare travel deals before I book. But when you book with an OTA, you are their customer. They own you. They don’t even pass your email along to airlines or hotels. So when things go wrong, you’ve inflicted a world of pain on yourself because you can’t go to the hotel or airline for help. You’ve agreed to the OTA’s terms, and often their customer service is lacking, if it exists at all. What are your top tips for what you call “turning off the friction of travel”? Book through the right travel channel—directly or with a travel agent that has deep relationships with the hotels you’re staying in and the destination you’re visiting. Also make sure your contacts are up to date, so your airline or hotel can contact you easily if something goes wrong. If you fly with certain airlines often, read their contract of carriage. Having a basic understanding of your rights can go a long way when you’re working with an agent in person or over the phone. What kinds of information can you find in the contract of carriage? There’s the flat tire rule—a grace period if you’re delayed or late for a flight—and airlines will book you free of charge on the next available flight. It’s also good to know which partner airlines are available to you, so you can search options from those airlines before speaking with a gate agent about rebooking. I always pull up specific flights and have all of the information ready before speaking with an agent. As of October of last year, the Department of Transportation also finally required airlines to automatically refund passengers if their flights are canceled. They’re still not required to compensate you, though. European and Canadian airlines are. For that reason, it’s worth flying on a European or Canadian airline when flying from the U.S. When flying back into the U.S., our airlines are beholden to European rules so compensation is on the table. Any advice for avoiding long lines at the airport? Definitely get Global Entry. Many rewards credit cards offer it as a travel perk, and now kids under 18 can get it for free. Clear can also be worth it, but not always. It depends on the airports you frequent. And if your flight plans go sideways, consider calling the foreign-language customer service line while waiting to speak to a gate agent. It’s the same service but often has a much shorter wait time. View the full article
-
Want more housing market stories from Lance Lambert’s ResiClub in your inbox? Subscribe to the ResiClub newsletter. When economic analysts talk about a cyclical change, they’re talking about short-term fluctuations driven by the business cycle. When those same analysts talk about a secular change, they’re talking about long-term, structural shifts in the economy. Sometimes a trend can be a little of both. One example: First-time homebuyers keep getting older. In 1991, the median age of first-time homebuyers in the U.S. was 28 years old. In 2024, it was 38 years old. In other words, the median first-time U.S. homebuyer in 2024 (age 38) has been out of high school for 20 years but is also only 24 years away from the earliest age at which they could receive Social Security benefits (age 62). Some of that increase is driven by how strained housing affordability has gotten over the past three years. And some of that increase is driven by secular changes, which are happening across the developed world, as younger generations are delaying life events compared to previous generations—attending school longer, marrying later, buying homes later, and having children later. It isn’t just first-time homebuyers. Repeat homebuyers are getting older, too. In 1991, the median age of repeat homebuyers in the U.S. was 42 years old. In 2024, it was 61 years old. While delayed life events and fewer homebuyers in their twenties and thirties are driving up the median age of repeat buyers, there are other factors. Part of the reason repeat buyers are older stems from the fact that the overall U.S. population is skewing older as the giant baby boomer generation ages and birth rates decline. Another factor is that older U.S. homeowners with substantial equity or even a paid-off primary residence are a little less sensitive to the recent mortgage rate shock. If they need to buy, some have taken the plunge over the past couple of years, avoiding 6% and 7% mortgage rates by simply paying all cash. View the full article
-
Currency jumps nearly 3% against US dollar on growing hopes of end to Ukraine warView the full article
-
Trade is wrongly blamed for the relative decline of the USView the full article
-
Onslaught points to growing frustration in Gulf state’s royal court with Israeli prime minister and war in GazaView the full article
-
IISS assessment lays bare challenges facing Europe should US cut back Ukraine military supportView the full article